>>> Up
* Chevron Raised to Buy at SocGen
* Covestro Raised to Buy at Jefferies; PT 40 euros
* Eli Lilly PT Raised to $360 from $335 at Cantor
* Glaston Raised to Buy at Inderes; PT 1.20 euros
* JDE Peet's Raised to Hold at Jefferies; PT 31 euros
* Kellogg Raised to Neutral at Piper Sandler; PT $74
* Lehto Group Raised to Reduce at Inderes; PT 35 euro cents
* Nurminen Logistics Raised to Accumulate at Inderes; PT 1 euro
>>> Down
* Assa Abloy Cut to Hold at Jefferies; PT 250 kronor
* BASF Cut to Hold at Jefferies; PT 47 euros
* Beiersdorf Cut to Hold at Deutsche Bank; PT 105 euros
* CapMan Cut to Accumulate at Inderes; PT 3.30 euros
* ConvaTec Cut to Neutral at BofA
* Hikma Cut to Equal-Weight at Barclays; PT 1,750 pence
* Just Eat Takeaway Cut to Sell at Numis; PT 15 euros
* Lanxess Cut to Neutral at Citi; PT 40 euros
* Legrand Cut to Hold at Jefferies; PT 79 euros
* Mediclinic Cut to Hold at Jefferies; PT 501 pence
* Next Cut to Neutral at Goldman; PT 7,600 pence
* Shop Apotheke Cut to Hold at Berenberg; PT 110 euros
>>> Initiation
* Marel HF Rated New Hold at Jefferies
>>> Call
* *BOFA STRATEGISTS CUT EUROPEAN STOCKS TO NEGATIVE FROM NEUTRAL
* Assa Abloy Cut at Jefferies as End Markets Start to Normalize
* Covestro Raised, BASF Cut as Jefferies Tweaks Chemicals Ratings
* JDE Peet’s Confounds Skepticism, Upgraded to Hold at Jefferies
* Lanxess Resumed Neutral at Citi on Cautious Near-Term Macro View
* Legrand Downgraded to Hold at Jefferies on Risks to US Growth
* Shop Apotheke Cut at Berenberg on Exected E-Prescription Delays
Stocks in Asia climbed along with US equity futures on Friday, helped by gains in technology shares, and oil snapped a slide as investor sentiment steadied after another turbulent week. An Asian equity index rose 0.8%, while S&P 500, Nasdaq 100 and European contracts posted modest gains. Taiwan recouped losses fueled by US House Speaker Nancy Pelosi’s visit, a jump that may have helped the wider mood. The 10-year Treasury yield was steady at about 2.68% and the dollar edged up. The inversion between two-year and 10-year yields remained near the deepest since 2000, indicating worries about a recession as monetary policy tightens. A global equity index is set for a third weekly advance and near a two-month peak in a recovery from bear-market lows, helped by resilient US company profits. The durability of the bounce remains in doubt as borrowing costs go up. Democrats agreed on a revised version of their tax and climate bill, adding a new 1% excise tax on stock buybacks. Investors are also monitoring the aftermath of Pelosi’s visit to Taiwan. China, which regards the self-ruled island as part of its territory, reportedly fired missiles over Taiwan during military drills -- a major escalation if confirmed. US After Hours Summary: Very busy earnings session; headliners: FUBO +25.4%, NET +21.2%, CVNA +14.7%, YELP +14.6%, DASH +13.7%, TEAM +10.2%, LYFT +9.1% on upside; DOCS -16.5%, CDNA -13.3%, MNTV -11.8%, WBD -11.4% on downside
Nikkei +0,86% Hang Seng -0,06% CSI +0,29% Shanghai +0,26% Shenzen +0,39%
Eur$ 1,0230 CNH 6,7509 CNY 6,7465 JPY 133,40 GBP 1,2139 CHF 0,9568 RUB 61,1261 TRY 17,9445 WTI$ 88,94 +0,50% Gold 1,791,04 -1,10% BTC 23,100 +3,2% ETH 1,653 +4%
S&P +0,23% Nasdaq +0,26% EuroStoxx +0,16% FTSE +0,15% Dax +0,18% SMI +0,16%
Macro :
- US Buyback Tax Could Be Friday’s S&P 500 Tail Risk
- Crypto Lender Voyager Receives Multiple Bids Above FTX Offer
- *BOFA STRATEGISTS CUT EUROPEAN STOCKS TO NEGATIVE FROM NEUTRAL
Keep an eye on :
- AED BB : Aedifica 1H EPRA EPS Beats Estimates
- AD NA : Ahold Delhaize to Postpone Amsterdam IPO of Bol.com
- AKTIA FH : Aktia Bank 2Q Adjusted EPS Misses Estimates
- ATUS US : Altice USA Eyes PE Infrastructure Funds for Suddenlink Sale:CNBC
- ALV GY : Allianz 2Q Operating Profit Beats Estimates
- ALV GY : Pimco Clients Pull Out $29 Billion as Allianz Sees Profit Rise
- AAL LN : Anglo Studies Chile Project Rejection With View to Seek Review
- AMGN US : Amgen 2Q Adjusted EPS Beats Estimates: Snapshot
- ATL IM : Atlantia FY Revenue Forecast Beats Estimates
- ATL IM : Atlantia Approves Mutually Agreed Exit of CEO Bertazzo
- ATCO US : Atlas Chairman, Fairfax Consortium Jointly Proposes to Buy Atlas
- NDA GY : Aurubis 9M Pretax Operating Profit EU448M Vs. EU268M Y/y
- BAVA DC : Monkeypox Declared a US Health Emergency, Freeing Up Funding
- BYND US : Beyond Meat Cuts Sales Forecast as Shoppers Trade Down
- BITTI FH : Bittium 2Q Operating Profit Beats Estimates
- BPE IM : BPER Banca 2Q Revenue EU903.2M Vs. EU840.7M Y/y
- BPOST BB : Bpost 2Q IFRS Net Beats Estimates
- BMW GY : European Lithium, BMW in Non-binding MOU on Lithium Hydroxide
- AFX GY : Carl Zeiss Meditec Sees FY Revenue at Least EU1.8B
- COR PL : Corticeira Amorim Buys Plot of Land From Novo Banco for EU22.3m
- CE IM : Credito Emiliano 2Q Net Income Beats Estimates
- DPW GY : Deutsche Post 2Q Ebit Beats Estimates
- DASH US : DoorDash Soars 11% After Results and Ebitda Forecast
- DBX US : Dropbox 2Q Adjusted EPS Beats Estimates
- EDF FP : EDF May Be Evaluating Sale of Italy’s Edison, MF Reports
- EXPE US : Expedia 2Q Adjusted EPS Beats Estimates
- GLPG NA : Galapagos Boosts FY Operating Cash Burn Forecast
- ILTY IM : Illimity 2Q Operating Income EU80.6M
- IPI US : Intrepid Potash 2Q Adjusted EPS Misses Estimates
- INGA NA : *ING GROUP FILES $20B MIXED-SECURITIES SHELF
- INW IM : Infrastrutture Wireless CEO Resigns as Sale of Shares Closes
- IPN FP : Ipsen Extends Expiration Date of Offer for Epizyme to Aug. 11
- ITA IM : ITA Airways Sale Won’t Be Left to Next Government: Draghi
- KKR US : KKR to Team Up With Loop Capital to Offer Equity Research, Firm Officials Say -- WSJ
- LGF/A US : Lions Gate Buyers Are Interested in Its Film Studio and Starz
- LSE LN :
- LHA GY : Lufthansa Seals Ground Crew Wage Deal to Avert Further Walkouts
- META US : Meta Makes Bond-Market Debut With $10 Billion Jumbo Deal
- MOBN SW : Mobimo 1H Ebit CHF81.4M Vs. CHF115.4M Y/y
- BMPS IM : Monte Paschi 2Q Net Income EU17.5M Vs. EU82.8M Y/y
- MNST US : Monster Beverage Shares Fall After 2Q Margins, EPS Miss
- NTGY SM :
- ORRON SS : Orron Eyes Possible Expansion Into Europe as Energy Demand Rises
- PIRC IM : Pirelli FY Revenue Forecast Beats Estimates; Raises FY Guidance
- RHM GY : Rheinmetall 1H Operating Profit EU206M Vs. EU191M Y/y
- ROTH FP : Rothschild & Co 1H EPS EU3.43 Vs. EU4.78 Y/y
- SAN FP : Innovent, Sanofi to Develop Cancer Medicines in China
- TWTR US : Musk Says Twitter Played ‘Hide-and-Seek’ as He Sought Info
- TWTR US : *TWITTER SAYS MUSK ACCUSING IT OF FRAUD IN MERGER COUNTERSUIT
- UBI FP : Ubisoft Surges on Possible Tencent Bigger Stake: Street Wrap
- UNI IM : Unipol 1H Consolidated Net EU574.9M Vs. EU536.7M Y/y
- US IM : UnipolSai 1H Consolidated Net EU401.5M Vs. EU525.8M Y/y
- VOW GY : Porsche Is Said to Court Gulf Sovereign Funds for Landmark IPO
- WPP LN : *WPP RAISES FY COMP SALES GUIDANCE ON `STRONG' 1H PERFORMANCE
- XIOR BB : Xior 1H Net Rental Income EU49.8M Vs. EU35.2M Y/y
- XPO US : XPO Logistics Boosts FY Adjusted EPS Forecast, Beats Estimates
- XPO US : XPO Logistics CEO Jacobs to Step Aside After Brokerage Spinoff
- YELP US : Yelp Boosts FY Adjusted Ebitda Forecast, Beats Estimates
- ZAL GY : Zalando Changes Track With Focus on Profitability: Handelsblatt
Scaling Ethereum: The Role Of Rollups
The growth of Decentralized Finance and more recently NFTs exposed Ethereum’s lack of scaling solutions for all to see. During the Bored Ape Yacht Club land sale only a few months ago, buyers paid over $10,000 in transaction fees per NFT, which surpassed the $6,000 or so price tag of the NFT itself. These transaction costs rear their ugly head every time the Ethereum network becomes congested - think times of extreme volatility like the Terra collapse or the Celsius crisis recently. Whatever your thoughts on Ether as an investment, the fact that the cost of using the network can exceed the price of the item being bought is a clear sign that the Ethereum blockchain isn’t fit for purpose in its current state.
This Deep Dive will take a look at the data behind Layer 2 rollups, Ethereum’s quickest solution for scaling the network in the short term.
There are two main ways to scale Ethereum:
- Improve the transaction capacity of the blockchain itself. The most effective way to upgrade the blockchain but also the most complicated. Sharding and other upgrades may not be seen for another year or more.
- Move to Layer 2. Instead of doing all the computational work on Layer 1 (Ethereum blockchain), a solution is to move the bulk of the work to Layer 2 - an off-chain network that reduces the computational strain on the Ethereum mainchain. The Layer 2 protocols responsible for achieving this scalability solution are called rollups. Layer 2 rollups are the fastest way to help Ethereum scale in the short term.
Blockchain Improvements
Improvements are being planned to the Ethereum network, most notably the Merge in September, which should see the energy consumption of the Ethereum blockchain reduced by about 99%. However, contrary to what some may think, the Merge itself won’t be a big factor in helping Ethereum solve its scalability issues. These fixes are due to come later in 2023 when the network begins the process of sharding. Sharding is beyond the scope of this deep dive but it essentially entails splitting the network into shards or seperate pieces in order to reduce congestion and improve transaction throughput. Transaction throughput is where Ethereum struggles compared to its ambitions to be the backbone of a new financial system. Currently, Ethereum can only handle about 15 transactions per second, compared to Visa’s 24,000 and Solana’s 50,000.
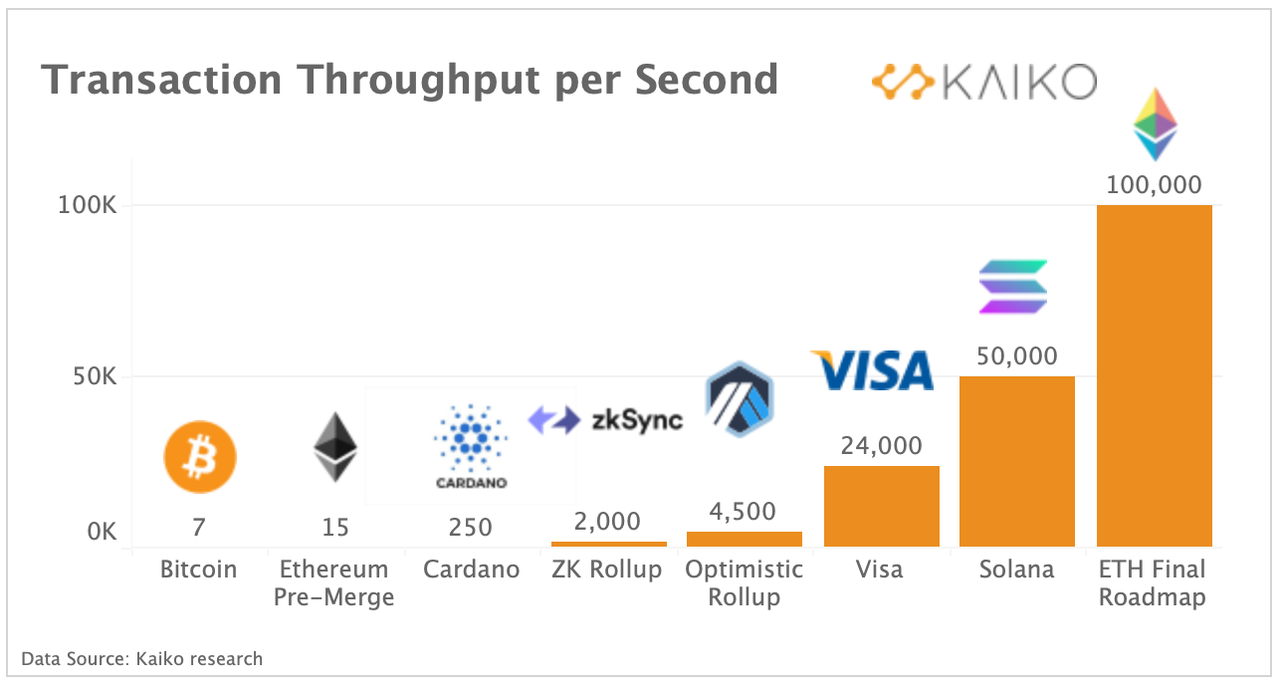
Only when Ethereum completes its roadmap of sharding and other updates to the blockchain will it reach the elusive 100,000 transactions per second. We can see that optimistic and zK rollups offer respectable throughput improvements and when we factor in that there are, and will be, multiple protocols offering capacity for transactions, that throughput number starts to approach Visa’s level. In the absence of widespread upgrades to the blockchain, rollups definitely serve a purpose for the Ethereum network in the near term - with lower fees comes more adoption.
Ethereum Fees
Transaction fees on the Ethereum network are currently at their lowest levels since December 2020.
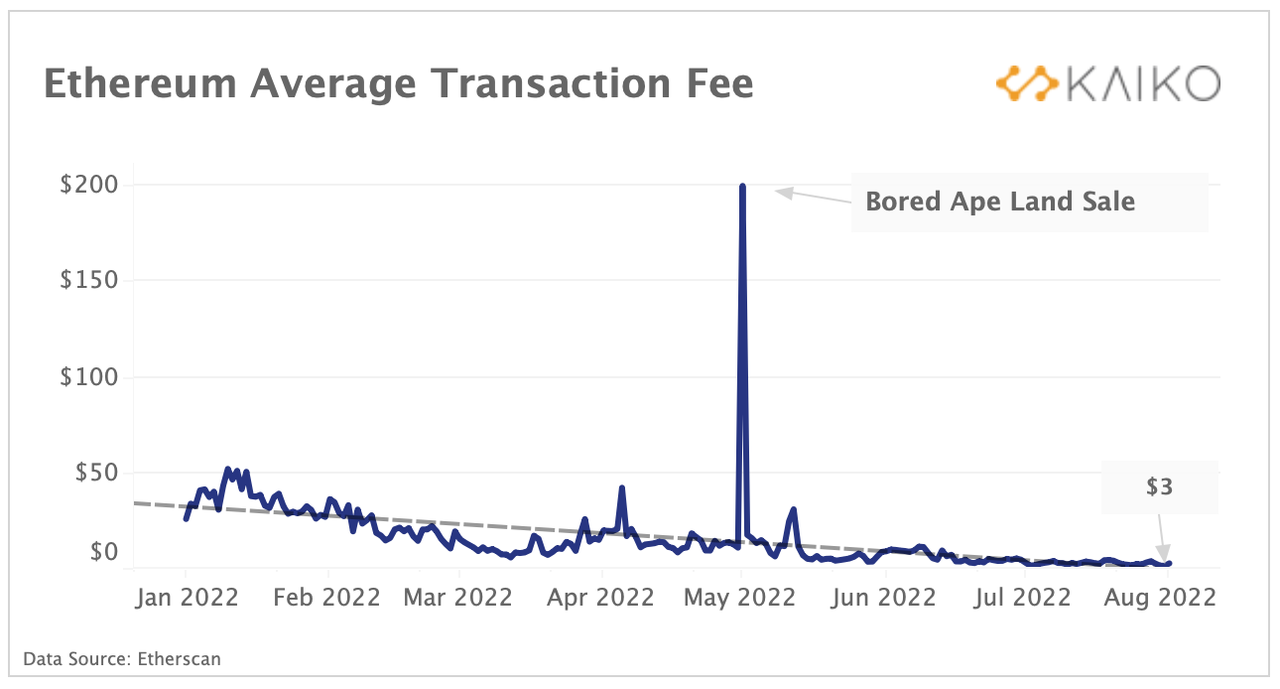
A falling transaction fee is exactly what Ethereum needs, however in this instance it's related to a lack of demand. TVL of DeFi projects has plummeted while NFTs are in their first ever bear market, all combining to bring blockspace demand to recent lows. However, the low fees do offer us a glimpse into how Ethereum users might interact with protocols in the future if the fees weren’t so prohibitive. As decentralized exchange volume decreases year to date, one would assume that this paints a sufficient picture of the activity on these platforms. However, an interesting trend to examine is trade count, which arguably shows the actual usage on an exchange. Trade size is also a useful barometer for whale vs. retail activity and for the purposes of this article, a smaller trade size is indicative of more retail usage.
Take Uniswap and Curve for example, Ethereum’s two largest decentralized exchanges by volume. Have users adjusted their behaviors in light of the lower fees?
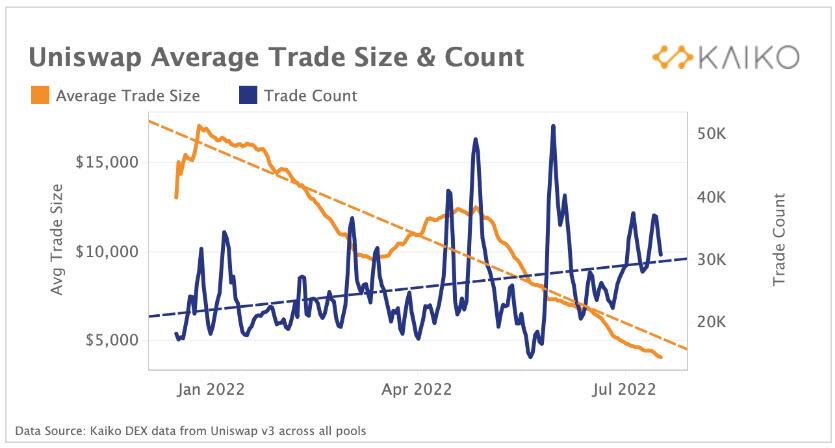
The answer is yes. The lowest transaction fees in nearly two years have seen trade sizes on the decentralized exchanges, such as Uniswap above, plummet while trade count actually rises. More trades are being placed by Uniswap users as transaction costs are low. Lower fees make DeFi more accessible to the average user and less geared towards whales, a nuance that is most definitely pivotal for the adoption of DeFi.
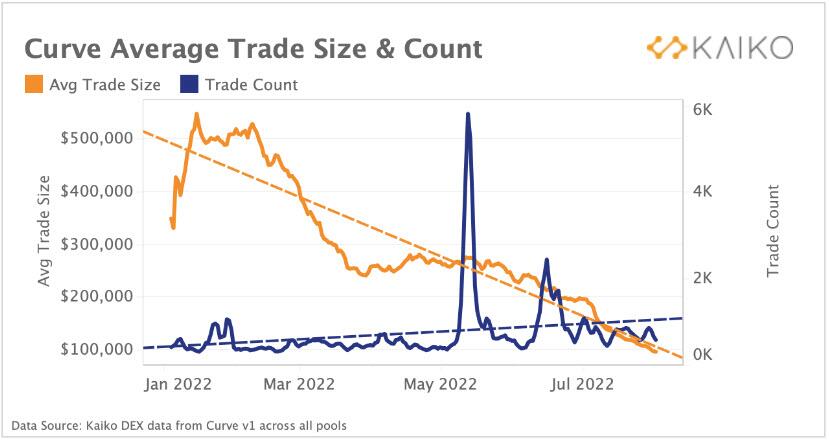
One decentralized exchange that is geared towards whales is Curve, an exchange specializing in stablecoin trading. We’ve observed a similar trend there where average trade size has fallen by over 80% while trade count rises.
In contrast, Coinbase volumes are hovering around yearly lows as average trade size and trade count are both moving lower.
In bear markets, volumes plummet on centralized exchanges as general interest among the public wanes. DeFi, however, still has plenty of use cases during a bear market (look at Curve’s role in the Terra collapse) and we can see that one factor of on-chain activity is Ethereum transaction fees, rather than general interest.
Reducing fees is priority number one for the Ethereum community in order to drive underlying adoption of the network. The quickest way to do that is via rollups.
State of Rollups
There are two main types of rollups, Optimistic and zK rollups, and their cost saving benefits have been clear to see already. Below are the fee comparisons between various Layer 2’s and Ethereum, according to l2fees.info.
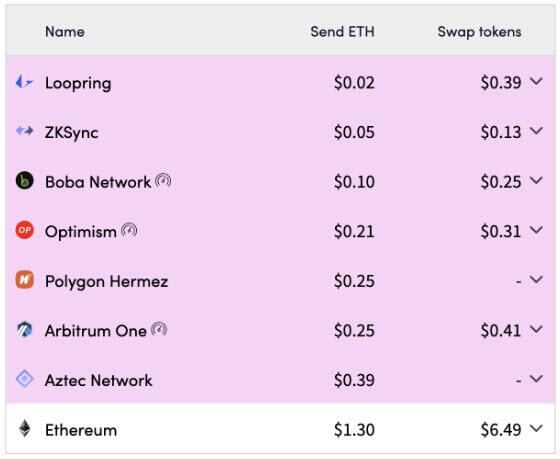
Optimistic and zK rollups mainly differ on their treatment of transaction veracity - how do we know the block being sent back to the Ethereum network does not contain fake transactions?
Optimistic Rollups
Optimistic rollups (ORs) presume transactions are valid when sending rolled up transactions back to the Ethereum blockchain, hence the name Optimistic. This assumption can be tested with a process called fraud proofs, where an onlooker can claim a transaction is fraudulent. The period for this usually spans 7 days, which is widely accepted as the biggest drawback of optimistic rollups. An exchange might logistically struggle to support immediate withdrawals if it was subject to a 7 day waiting period on transactions.
The two largest ORs are Arbitrum, which has yet to release a token, and Optimism, which launched a token on June 1st this year. There are other Layer 2 protocols with tokens that investors can get exposure to, such as Boba, a governance token for the Boba network, another optimistic rollup. Dydx is also a governance token, this time for the operation of the Layer 2 version of the decentralized exchange, which depends on zK rollups. IMX is a Layer 2 scaling solution for NFTs on Ethereum and differs slightly from the other governance tokens as it also can be used to pay transaction fees on the platform.
The market seemed to start arriving at the conclusion that optimistic rollups were just a band aid over a bigger issue as since the Optimism (OP) token launch, it underperformed not only ETH but also other Layer 2 protocols.
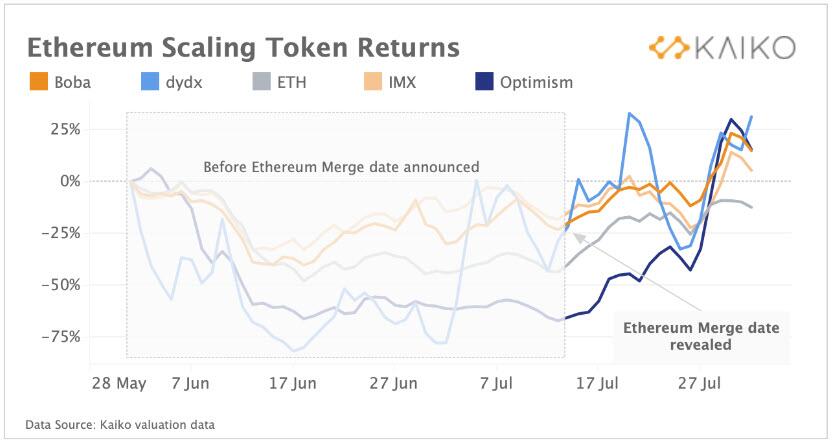
However, with the announcement of a final date for the Merge, the market became more bullish on the Ethereum blockchain as a whole and Optimism started to outperform. This bullish sentiment is also evident in the futures market for OP which has seen a large buildup of open interest while the funding rate has moved positive in the last week.

zK Rollups
While Optimistic rollups presume all transactions are valid and allow onlookers to submit fraud proofs, “Zero knowledge” (zK) rollups do the work of validating each transaction themselves by submitting a validity proof along with each bundle of transactions. This is why they are more computationally intensive and up until recently, not EVM compatible, but it is also why they are far faster at settlements and withdrawals - there is no need for a window for fraud proof. This near-instant settlement is extremely appealing to exchanges who need to be able to satisfy user withdrawals in a timely manner; exactly why dydx has already adopted a zK rollup on Layer 2.
Due to the computational intensity of zK rollups, OR’s were initially rolled out quickest while developers worked on what was deemed the ‘holy grail’ of rollups, a zK rollup that was EVM compatible. In the last couple of weeks we may have witnessed the beginning of the zK rollup era, as three teams, Polygon, Matter Labs and Scroll, all announced breakthroughs with EVM compatible zK rollups.
Layer 2s and DEXs
Looking specifically at Uniswap and Curve’s breakdown of TVL, we can see that only a small portion of their value sit on Layer 2 optimistic rollups (Optimism and Arbitrum): 1.9% on Uniswap and 1.8% on Curve. Uniswap currently has 97% of TVL sitting on the Ethereum mainchain, while Curve has 92%. It’s reasonable to expect that once a zK EVM compatible rollup is rolled out that this number will decrease and move towards Layer 2, allowing more DEX users to avail of the cheaper fees on offer.

Conclusion
Layer 2 rollups are an essential part of Ethereum’s short/mid-term scaling strategy and possibly even in the long term as the rollups will sit on top of the improved Ethereum network.
It looks as if zK rollups are beginning to arbitrage away the competitive advantages of optimistic rollups, and if the teams working on an EVM compatible zK rollup can successfully launch their products, I expect them to gain a large amount of market share, potentially with traffic directed from decentralized exchanges.
Vitalik Buterin: “my advice to teams like Optimism and Arbitrum is that I think they should start zK-ifying themselves fairly soon.”
Stock-based pay isn’t so nice in a down market
Coinbase and Robinhood both listed on public markets during last year’s bull run. Both rode the crypto and meme stock wave. And both stocks are now sitting with peak-to-trough declines of more than 85 per cent.
Things have been a bit less dire lately. Coinbase stock leapt 10 per cent yesterday after it inked a deal to offer crypto prime broker services to investors who use BlackRock’s popular risk-management software. Robinhood had a 15 per cent rally on Wednesday after laying off a fifth of its staff, which many took as a sign the company was duly focused on cost-cutting. All told, recent price performance hasn’t been half bad (though it still looks like a small upward blip on a longer-term chart):
This feels weird. Crypto trading volume is still down a lot, and falling. Coinbase is in a possibly existential dispute with the SEC over whether cryptocurrencies are securities. Robinhood is still lossmaking with a business model that doesn’t look as growthy as it once did. Why are some investors buying the dip?
Valuations are part of the story. The companies’ price-to-sales ratios, a typical valuation metric for immature tech businesses, have fallen hard. After its IPO in 2021, Robinhood’s P/S ratio (calculated as market cap divided by revenue) was about 25; now it’s closer to five. Coinbase’s has gone from 24 to two. Perhaps some investors figure the worst is over and want to snag a discount.
But Kenneth Worthington and Michael Cho, two analysts at JPMorgan, think investors could be overlooking a big threat to Coinbase and Robinhood’s share prices: dilution from stock-based compensation (SBC).
Here’s how that works. SBC is great when markets are bouncy and stinks when markets fall. You can think of it as creating hidden leverage, as Jamie Powell put it in an excellent FT Alphaville post back in February. To sum up the basic mechanics:
- Shares are often awarded through four-year vesting plans, where you get a chunk every year. These shares are called restricted stock units, or RSUs.
- Prices are set upfront. Say you earn $100,000 a year, half in stock. Maybe the stock trades at $50. So you get 1,000 RSUs worth $50,000 on paper.
- That $50,000 on paper is taxed as ordinary income right away, but you won’t be able to sell it all for four years. In the meantime, the share price will move around.
- If the stock goes up, you’re golden. You’ll pay some capital gains tax but ultimately you made more money than if all your pay had been in cash.
- If the stock goes down, you’re in trouble. You paid a lot of tax, but unless you want to wait for the stock to recover, you’re stuck with losses. Maybe you get mad and threaten to quit.
Worthington and Cho estimate in a recent note that Coinbase pays out 35 per cent of total compensation in stock. For Robinhood, that number is 50 per cent. In a down market, this is obviously bad news for employees. (A friend at a big San Francisco fintech says grumbling about the plunging value of stock compensation is commonplace.)
It could also be bad for outside shareholders. If Robinhood and Coinbase continue with current SBC levels — even after cutting staff — a swelling share count would destroy shareholder value. In an optimistic scenario assuming 3.5 per cent dilution per year for five years, Worthington and Cho calculate that value per share would be 16 per cent lower than if share count were kept constant. Nor are the companies’ other options much better. They write:
Pay employees less. Option one is to just pay employees less. Competition was fierce to win employee talent, but both Coinbase and Robinhood announced headcount reductions in 2Q22. Given the operating environment is challenging for both Coinbase and Robinhood, we can see the companies paying employees less, which would drive less stock-based compensation and lower RSUs granted. The downside is Coinbase and Robinhood could lose their better people and existing employees might be less productive.Award more cash, less stock. Option two might be to pay more cash and less stock. This reduces dilution, but puts more pressure on cash flow. With Coinbase debt trading at 0.65 at distressed levels, there are cash flow concerns by investors and paying more cash compensation could exacerbate cash flow concerns.Pay in out-of-the-money options. Using out-of-the-money options would reduce dilution, but disproportionately gives option holders [ie, employees] more of the upside in any stock price recovery.
In the extreme, you can imagine a death spiral scenario where worse pay creates a talent exodus, making the business worse, which lowers the stock price, and so on. It’s hard to know how likely this is, but the risk is probably lower for Coinbase than Robinhood, simply because Coinbase appears to have massively over-hired.
The punchline is that stocks which have fallen 60-90 per cent from the frothiest heights of the bull market can always keep on falling. Investors, it seems, are only now realising what they’ve bought.
Pelosi Says U.S. Won’t Allow China to Isolate Taiwan
Japan calls on China to end military exercises around Taiwan after five Chinese missiles landed in its exclusive economic zone
TOKYO—House Speaker Nancy Pelosi said Friday that the U.S. would continue engaging with Taiwan despite criticism from China, as Beijing encircled the island with rocket and ballistic-missile fire following her visit there.
“We will not allow them to isolate Taiwan,” Mrs. Pelosi said of Beijing.
Referring to China’s military drills, Mrs. Pelosi said that Beijing was “probably using our visit as an excuse.”
She rejected China’s criticism of her visit to Taiwan, saying: “They are not doing our travel schedule.” She called the visit a way to congratulate Taiwan for building a prosperous democracy.
“Taiwan is one of the freest countries in the world,” she said. Beijing claims the self-governing island as its own territory.
Mrs. Pelosi was speaking at a news conference in Tokyo after meeting Japanese Prime Minister Fumio Kishida for breakfast.
Mr. Kishida called on China to immediately halt its military exercises, after Japan’s Defense Ministry said five Chinese missiles had landed in its exclusive economic zone.
“The actions by the Chinese side will have serious consequences for the peace and stability of the region and the international community,” Mr. Kishida said. He said the U.S. and Japan should work closely together to respond to the Chinese drills.
China’s military exercises near Taiwan on Thursday tested the democratic island’s defenses with navy ships and war planes. The show of force disrupted commercial air and sea routes and raised concerns about further military escalation. Taiwan and the U.S. condemned China’s moves, with the White House announcing that the USS Ronald Reagan aircraft carrier and its accompanying ships would remain in the region “to monitor the situation.”
As part of the exercise, China fired a number of missiles around and over Taiwan. Five landed within Japan’s exclusive economic zone, the first time this has happened, Japan’s defense minister, Nobuo Kishi, said late Thursday.
“This is a grave problem affecting the safety of our people,” Mr. Kishi said. “I strongly protest.”
An exclusive economic zone is the area beyond a country’s territorial waters where the country claims special rights to explore for and use marine resources.
Meta: first bond sale sends message to equity investors
Company formerly known as Facebook should lock in long-dated maturities now
Meta is in a bind. The company formerly known as Facebook has staked its future (and its name) on virtual reality — a segment of the business that has lost close to $6bn this year. The Oculus headsets it sells, devices that will give users entry to the digital universe known as the metaverse, remain clunky and uncomfortable. More investment is required. Tapping credit markets is a good option. It also suggests more share buybacks are coming.
Like its Big Tech peer group, Meta is well cushioned. It has close to $40.5bn in cash, cash equivalents and marketable securities. It also has no debt. But the advertising business that comprises the majority of revenues and should be funding future plans has problems. Social media competitor TikTok is more popular with young users. Meanwhile, Apple’s decision to make it easier for internet users to opt out of ad tracking has made it more difficult to collect information needed for personalised adverts.
Meta has missed the era of ultra-low borrowing rates. Rising interest rates mean rising yields — a trend likely to continue in coming years. It should lock in long-dated maturities now. Earlier this week, Apple sold 30 and 40 year bonds. Meta is well placed to do the same. Novelty is prized by bond investors. It is likely to be in demand.
It can avoid convertible bonds too. A number of tech companies have spent the past few years issuing this, including Snap, Peloton and Beyond Meat. Investors were happy for tech companies to pay little or no interest — the appeal was the possibility of turning the debt into stock at a fixed price in the future. Since then, stock prices have fallen along with the value of the bonds. The cost of refinancing will be high.
Meta’s plans will not only interest bond investors. After Apple broke records with the biggest corporate bond sale in 2013, payouts to investors jumped. Meta’s share buybacks exceeded $5bn in the second quarter. If the sale of debt is successful expect that figure to keep rising.
Twitter calls Elon Musk’s case against $44bn deal ‘implausible’
Social media company and Tesla chief executive exchange salvos in bitter fight over takeover
Twitter has accused Elon Musk of creating a “new set of excuses” to avoid honouring his $44bn agreement to buy the social media company, calling his recently filed objections “implausible and contrary to fact”.
After Twitter sued Musk last month to force the deal through, Musk filed a countersuit last week trying to block the social media company’s effort, which is still under seal. A judge has ordered it to be released on Friday.
Twitter made public its rebuttals to the Tesla chief executive’s legal case on Thursday in a court filing shared by Bret Taylor, chair of the social media group’s board.
In his countersuit, Musk again claimed Twitter has breached the agreement by greatly underestimating the proportion of spam and bots on its platform. The billionaire’s own analysis estimated the number of bot or spam accounts to be at least 10 per cent of all users. Twitter has previously estimated bots make up less than 5 per cent of accounts.
Musk also claimed that Twitter has overstated how many of its users are monetisable, alleging the number of users who actually saw advertising on the service was “about 65mn lower” than the company represented in regulatory filings. Musk has claimed only about 16mn users were seeing the “majority” of advertising.
Twitter responded by calling Musk’s estimates “factually inaccurate, legally insufficient, and commercially irrelevant”.
It said the methodology behind Musk’s estimations was “untenable on its face” and was “not measuring the same thing as Twitter or even using the same data as Twitter”.
The company questioned the veracity of Musk’s data, claiming a tool purportedly used to analyse the data had labelled the billionaire’s own account as a “likely bot”.
Twitter concluded: “Musk’s counterclaims, based as they are on distortion, misrepresentation, and outright deception, change nothing.”
In addition to the filings, both parties are casting a wide net in seeking additional information regarding the formulation of the deal.
Musk has subpoenaed Goldman Sachs and JPMorgan Chase for details on how they advised Twitter, requesting any documents detailing financial performance, discussions with the company about the deal and any analysis of its valuation.
Twitter, meanwhile, has served information requests to the banks handling Musk’s financing of the deal, as well as co-investors and others in the billionaire’s orbit.
As the dispute with Twitter escalates, and heads for a fast-tracked October 17 court date, Musk is also contending with questions from Tesla fans and shareholders regarding his role as chief executive of the electric carmaker.
On Thursday, at Tesla’s annual meeting, Musk addressed several questions related to the Twitter dispute and said he had “a good sense of where to point the engineering team at Twitter to make it radically better”.
Asked what would happen to Tesla were he to leave or split his time, Musk said: “I think Tesla would continue to do very well even if I was kidnapped by aliens or went back to my home planet.”
Wildfires destroy almost all forest carbon offsets in 100-year reserve, study says
Carbon released by US forests burnt in recent blazes expected to wipe out most of the buffer in Californian trading system
Wildfires have depleted almost all of the carbon credits set aside in reserve by forestry projects in the US to protect against the risk of trees being damaged over 100 years, a new independent study has found.
As a result of fires, six forest projects in California’s carbon trading system had released between 5.7mn and 6.8mn tonnes of carbon since 2015, the non-profit research group CarbonPlan estimated. That was at least 95 per cent of the roughly 6mn offsets set aside to insure all forest projects against the risk of fire over a century-long period.
In principle, the offsets represent a tonne of carbon avoided or removed from the atmosphere. Offsetting projects, such as forestry schemes, contribute some of the credits to a so-called “buffer” pool that acts as an insurance mechanism, and are cancelled if the carbon absorbed by the trees is released, for example when they catch fire.
“In just 10 years, wildfires have exhausted protections designed to last for a century,” said Oriana Chegwidden, a co-author of the study. “It is incredibly unlikely that the program will be able to withstand the wildfires of the next 90 years.”
Companies across all industries are increasingly turning to carbon credits to compensate for their emissions.
Last year, a particularly fierce US fire season ripped through forest projects that had generated offsets bought by companies including BP and Microsoft.
In California, the Air Resources Board (CARB) allows certain offsets to be used in its official carbon trading system, under which polluters must buy permits to cover their emissions.
Under California’s rules, the carbon savings linked to the offsets must be guaranteed for at least 100 years. To guard against future risks, forest projects contribute between 10-20 per cent of all the credits they generate into the buffer pool, around a fifth of which relate to potential fires while others safeguard against hazards such as disease.
However, the researchers at CarbonPlan, which has previously conducted analysis with funding from Microsoft, said they were “unaware of any explicit analysis that justifies” the number of credits that went into the buffer pool. The risk analysis “may have been the product of educated guesswork”, they added.
After fires damaged two forest projects in 2015 and 2018, more than 1mn buffer pool credits were cancelled out of the roughly 6mn set aside to protect specifically against fires. Cancellations related to fires in 2020 and 2021 have not yet been processed, but CarbonPlan estimated that those blazes generated between 4.6mn-5.7mn tonnes of carbon, which would wipe out the remaining fire risk credits in the buffer pool.
At the start of 2022, there were a total of around 30mn credits in the buffer pool to cover all categories of risk, including fires and other perils such as disease, over a 100-year period.
The peer reviewed paper also estimated that an outbreak of sudden oak death, which has devastated forests on the US west coast, in projects with trees sensitive to the illness could also eliminate the buffer credits set aside for disease and insect risks.
The insurance mechanism was “severely undercapitalised”, the paper said. The system “makes no effort to account for the all but inevitable increase in fire risks as the earth continues to warm,” while the evidence needed to model drought risk “was not available” when the rules were developed, the researchers said.
The CARB said the fact that the forest buffer continued to grow, and had been used, was “evidence that it is a prudent part of our program.” The analysis underpinning the buffer pool contribution was based on “the best information available” at the time that the system was developed, and the CARB would assess “new information” at its next update, it said.