Closing Stock Market SummaryThe S&P 500 rallied 2.5% on Thursday, as earnings reactions helped instill confidence in dip-buying efforts. The Nasdaq Composite rose 3.1%, the Dow Jones Industrial Average rose 1.9%, and the Russell 2000 rose 1.8%.
After a shaky start in which the major indices, except the S&P 500, turned negative, the market kicked into higher gear in the afternoon. All 11 sectors in the S&P 500 closed higher with gains ranging from 1.1% (utilities) to 4.0% (information technology).
Meta Platforms (FB 205.73, +30.78, +17.6%) had sort of a halo effect on the mega-caps, as shares surged 17.6% following its better-than-feared earnings report. Apple (AAPL 163.64, +7.07, +4.5%) and Amazon.com (AMZN 2891.93, +128.59, +4.7%) posted strong gains in front of their earnings reports after the close.
Qualcomm's (QCOM 148.19, +13.09, +9.7%) results and guidance had a similar effect on the Philadelphia Semiconductor Index (+5.6%), while the 11% gain in PayPal (PYPL 92.09, +9.48, +11.5%) despite its downside guidance was viewed as a justification to buy other beaten-down growth stocks -- but not Teladoc (TDOC 33.51, -22.48, -40.2%), which cratered 40% on disappointing guidance.
McDonald's (MCD 254.19, +7.05, +2.9%) and Merck (MRK 88.58, +4.17, +4.9%) also pleased investors with their earnings reports. Fellow Dow components Caterpillar (CAT 212.44, -1.52, -0.7%) and Amgen (AMGN 238.13, -10.66, -4.3%), however, closed lower despite beating EPS estimates.
Of course, the notion that the market was simply due for a bounce from an oversold condition can't be understated. Encouragingly, too, the stock market did not appear fazed by the disappointing Advance Q1 GDP report that had marks of stagflation.
Briefly, real GDP decreased at an annual rate of 1.4% in the first quarter (consensus +1.1%) while the GDP Chain Deflator increased by a larger-than-expected 8.0% (consensus +7.3%).
The Treasury market, however, did react in such a way that maintained expectations for the Fed to prioritize tighter policy to keep inflation pressures in check. The 2-yr yield rose seven basis points to 2.64%, and the 10-yr yield rose five basis points to 2.86%. The U.S. Dollar Index (103.59, +0.64, +0.6%) hit a 20-year high. WTI crude settled above $105 per barrel ($105.31, +3.56, +3.5%).
Reviewing Thursday's economic data:
- Real GDP decreased at an annual rate of 1.4% in the first quarter (consensus +1.1%) while the GDP Chain Deflator shot up 8.0% ( consensus +7.3%). Real final sales of domestic product, which exclude the change in private inventories, were down 0.6%.
- The key takeaway from the report is that it will exacerbate concerns about the U.S. economy being at risk of slipping into an eventual recession at worst or at least entering a stagflation period that will necessitate tighter monetary policy to get inflation under control.
- Initial jobless claims for the week ending April 23 decreased by 5,000 to 180,000 (consensus 182,000). Continuing claims for the week ending April 16 decreased by 1,000 to 1.408 million, which is the lowest level since February 7, 1970.
- The key takeaway from this report remains the same: jobless claims are near historically low levels, which is indicative of a tight labor market. The tightness in the labor market, though, will continue to fuel concerns about wage-based inflation pressures that can feed into more persistent, and broader, price inflation.
Looking ahead, investors will receive Personal Income and Spending for March, PCE Prices for March, the Q1 Employment Cost Index, the Chicago PMI for April, and the final University of Michigan Index of Consumer Sentiment for April on Friday.
- Dow Jones Industrial Average -6.7% YTD
- S&P 500 -10.0% YTD
- Russell 2000 -14.6% YTD
- Nasdaq Composite -17.7% YTD
Twitter Misses Revenues, Admits "Over-Stating" Millions Of Users
Having disappointed on the top line ($1.20 billion vs $1.23 billion expected), seen advertising revenue below expectations, apparently slashed capex, and somewhat expectedly cut all previously provided outlooks and goals; Twitter's earnings' revelations offer a glimpse into why the Board flip-flopped so fast and grabbed Musk's 'apartheid-unleashing' offer so quickly.
However, buried deep in the filings was another little surprise for the billionaire who just bought the company.
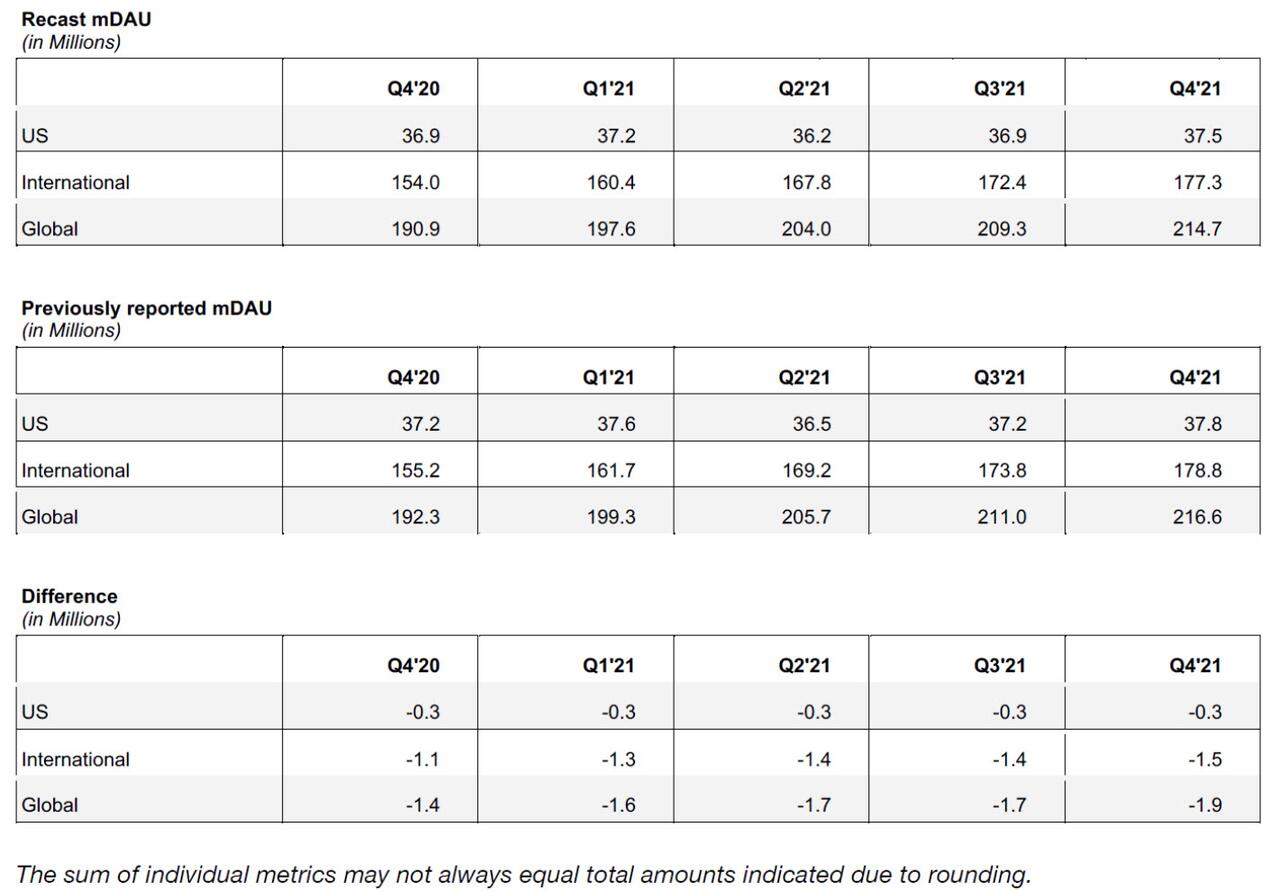
Since the start of 2019, Twitter has been over-estimating the number of users...
mDAU RecastIn March of 2019, we launched a feature that allowed people to link multiple separate accounts together in order to conveniently switch between accounts.An error was made at that time, such that actions taken via the primary account resulted in all linked accounts being counted as mDAU.This resulted in an overstatement of mDAU from Q1’19 through Q4’21.The table below provides updated values for mDAU from Q4’20 to Q4’21 alongside historical reported values for those same time periods. We are including one decimal place for both the absolute values and growth rates to give more detail around the magnitude of the changes. Note that recast data is not available prior to Q4’20 due to data retention policies, but our estimates suggest the prior period adjustments are not likely to be greater than those in Q4’20.
The adjustments are all one-way (lower) and are not de minimus... 1.9 million fewer users globally in Q4 2021 than they initially disclosed.
Is someone covering-their-ass ahead of Musk's deep-dive? And what other little surprises lurk below the surface of this leftist sanctuary?
The question many are asking now is - is this 'admission' material enough to warrant a price-adjustment for Musk?
Fashion’s ‘Reverse Inflation’ Has Costs Hikes Following Pricing Gains
After two years of disruption, the apparel and retail industry now has to adjust to the next new world with across-the-board cost increases.
Fashion is backing its way into the new world order.
Inflation usually starts with rising costs on raw materials and other essentials that eventually force companies to bring higher prices to consumers.
But this time through, the process has been operating out of sync. Many brands, particularly on the higher end of the spectrum, were able to hike their prices last year, supported by a strong consumer and a scarcity of merchandise given the COVID-19-induced supply chain backups.
That made for an industry filled with hot companies with better margins and led to more interest in the consumer sector (as evidenced by the string of fashion IPOs).
Now costs are going up in earnest with inflation at a 40-year high, with prices on all goods and services in the U.S. rising 8.5 percent over the past year, bringing the sector back down to earth.
Related Galleries
Kendall Jenner and Kim Kardashian
PARTIES
Inside the Revolve Festival at Coachella
Megan Thee Stallion
BEAUTY FEATURES
Beauty at the 2022 Grammy Awards
BMO analyst Simeon Siegel calls the progression “reverse inflation.”
It’s not just a novel situation, but a disorienting one for investors who fell in love with the peppier look retail had last year with sweeter margins and strong growth prospects.
“When costs go up, retailers and brands and investors are trained to believe there’s room to raise price,” Siegel said. “The problem is, everyone [already] did.”
Over the long run, he described it as “net neutral” for retailers, but acknowledged “it feels negative now.”
That is particularly true at Gap Inc., which last week cut its sales outlook and shook up leadership at the struggling Old Navy. The retailer said it has “taken a more aggressive approach to assortment balancing resulting in increased promotional levels primarily at Old Navy.”
That sounds a lot more like the familiar retail narrative defined by price promotions than the power-margin story the industry was settling into last year.
“People are asking, ‘Is Old Navy the beginning of the end?’” Siegel said.
That might depend on how other chief executive officers across the industry react to the growing pressures — on cotton costs, on freight, on labor and more.
Many, including John Idol, CEO at Capri Holdings, and Chip Bergh, CEO of Levi Strauss & Co., have been vocal about being willing to run more profitable, healthier businesses even if that means giving up some size or accepting slower sales growth.
But how many will be able to hold the line as pressures increase and Wall Street continues to seek growth?
“The question right now is, Who owns their destiny?” Siegel said. “CEOs are generally not hardwired to shrink. They’re hardwired to grow. The nature of that seat is to desire to do something special. Retail has been programmed toward growth, which is what got us in the [promotional] problem. It is a very hard thing for a human to internalize that less can be more.”
Already the last couple of years have been a study in corporate change, with companies racing first to survive the early lockdowns, pivoting on the fly toward the web and then enjoying a big boost as consumers reemerged.
Now leaders have to reposition again. And the CEOs having to deal with inflation also are ones who perhaps in their careers have never actually had to face the issue, at least in fashion. There was a time in the 2000s when the fear actually was the opposite — apparel prices were so stagnant and, in some cases declining, that the fear was the industry would enter deflation and would never be able to escape it. They’re learning on the fly not just how to set prices next season, but a year or even two ahead — all while costs throughout the supply chain spiral upward.
Elaine Hughes, CEO of executive search firm E.A. Hughes, a division of Solomon Page, said: “What CEOs can control is the way they run their company, how many people they have, how it is structured to make sure people have multiple skill sets so instead of being siloed doing one specific job, they can do multiple jobs, preferably within a department.”
But setting up the business to operate in inflationary times is just part of the ever-expanding job description for CEOs.
“It’s a very lonely job,” Hughes said. “Who do you talk to? Who do you trust? It’s very difficult. But what has compounded the CEO role today is that there are a million things going on. With the Black Lives Matter movement there has been a stronger emphasis on teams devoted to diversity and inclusion for the entire company population. Employees are becoming disgruntled, where they want to become unionized. There are women’s issues within these companies.
“There are too many of the social and political implications that have fallen on the shoulders of a CEO,” said Hughes.
Now, she said, rising costs are being piled on to the top of their list of responsibilities, forcing corporate chiefs to ask: “How is inflation going to run its course and how do we, as a company, address it without alienating our customers?”
These are questions that seem likely to become even more pressing as fashion starts to openly contend with the new dynamic.
Greg Portell, lead partner in Kearney’s global consumer practice, said the cost increases retailers have had to pay haven’t flown through to company’s profit statements yet.
But they’re coming.
“We’re expecting a very challenging second and third quarter as the cost increases start to hit the cost of goods and the revenue line gets harder to move,” Portell said.
After a period when companies were fighting scarcity given the supply chain troubles and paying up to get goods to the sales floor or the customer, that could be a major adjustment.
“We project it will take about 18 months for companies to really get their cost management strength back,” Portell said.
The market seems to be one that will, again, separate the inherently strong operators from the players still finding their footing.
“You’re going to start to see some of the sunshine darlings, the flowers that came out after the storm, start to wither” if they don’t have the supply chain management chops, he said.
The next turn of the wheel might also highlight just which companies evolved enough through the pandemic and which ones stopped too early.
“If you look back over the past six months, mostly the companies dropped [excess funds] to the bottom line or bought back shares, they didn’t put the money into innovation,” Portell said.
Ezra Greenberg, a partner at McKinsey & Co., said companies have “real work to do.”
“The only way to solve something like this is to have all hands on deck,” Greenberg said. “It has to be a rethink of the way in which we run the business and what we do on the supply chains and what we do on procurement so you’re not working at cross purposes.”
That means how people work is going to change, again, whether through new corporate structures or supported by automation or something else.
“There is one empirical fact that is true in the United States — it’s that nominal wages, regular dollar wages never fall, they just don’t,” Greenberg said. “If you went from $10 to $17 an hour or $25, you’re never getting that back. So what do you do? It’s definitely OK to pay people higher wages, if their value added per person is going up. This is about, ‘How do I raise productivity by increasing the top line versus cost cutting?’”
One way or another, retailers are going to have to learn to cope with cost increases.
But first, that realization might have to set in.
“Companies have taken price and markdowns are basically zero, they don’t exist, especially within apparel and softlines — historically a very competitive space,” said Ike Boruchow, an analyst at Wells Fargo. “Not just investors, but companies have forgotten that.
“The five-year period leading into COVID[-19], gross margins trended flat to down every year, very consistently,” Boruchow said. “All of a sudden, you looked at the group and we’re 300 to 400 basis points above COVID[-19] levels on gross margin.
“You’re starting to see little cracks,” he said, pointing to the Gap warning. “You can’t keep pricing stuff up. The consumer is still in a good spot, even the low-end consumer is still in a good spot. But you can’t just raise prices to the moon in a category that has historically been fairly deflationary. I’m pretty concerned.”
Boruchow is not alone.
Jean-Charles Naouri must find 50 million before Christmas for his Foncière Euris
In the annual reference document released this week, the auditor of Foncière Euris, holding company of the Casino group, warns that the company lacks cash to honor a large derivatives debt before Christmas. What weaken the control of the distribution group.
It is sometimes necessary to bring a magnifying glass to detect the financial setbacks of the CEO of the Casino group, Jean-Charles Naouri. In this case, you have to go to page 12 of Foncière Euris' annual financial report, published on Monday 25 April. As a reminder, the former director of Pierre Bérégovoy took control of Casino thanks to a series of holding companies. Foncière Euris, located under the holding companies Euris and Finatis, owns 57.9% of Rallye, which itself owns 52.3% of Casino.
However, on page 12 of the document, the statutory auditor explains: "The projected cash flow of Foncière Euris, as estimated to date, does not allow the derivative banks to be reimbursed at the maturity date of December 2022 (or June 2023 in some cases)". The news alerted scrupulous investors. Foncière Euris owes its creditors a total of 54 million euros: 50 million euros expiring in December 2022 and 4 million euros in June 2023. Because, unlike conventional loans, contracts in the form of derivatives are not "frozen" by the safeguard procedure for holdings in progress since May 2019. They must therefore be paid for.
The Societe Generale precedent
Societe Generale knows something about it. In 2019, when all of the group's holding companies were placed under safeguard proceedings, the bank had obtained through legal proceedings the benefit of Rallye shares as collateral for derivative contracts concluded in 2014 with the same Foncière Euris. She had thus found herself with 1.77 million Rallye shares, or 3.4% of the capital, which she had undoubtedly hastened to convert into cash.
Even today, if Foncière Euris could not honor its debts, the auditor reminds that the pledges on Rallye shares could result in a considerable loss of control of Casino's parent holding company. "The percentage of Foncière Euris in Rallye would drop from 57.9% to 39.8% in capital and from 71.8% to 55.6% in voting rights", details the document. What mortgage a little more the future of Jean-Charles Naouri at the head of Casino.
In the annual reference document released this week, the auditor of Foncière Euris, holding company of the Casino group, warns that the company lacks cash to honor a large derivatives debt before Christmas. What weaken the control of the distribution group.
It is sometimes necessary to bring a magnifying glass to detect the financial setbacks of the CEO of the Casino group, Jean-Charles Naouri. In this case, you have to go to page 12 of Foncière Euris' annual financial report, published on Monday 25 April. As a reminder, the former director of Pierre Bérégovoy took control of Casino thanks to a series of holding companies. Foncière Euris, located under the holding companies Euris and Finatis, owns 57.9% of Rallye, which itself owns 52.3% of Casino.
However, on page 12 of the document, the statutory auditor explains: "The projected cash flow of Foncière Euris, as estimated to date, does not allow the derivative banks to be reimbursed at the maturity date of December 2022 (or June 2023 in some cases)". The news alerted scrupulous investors. Foncière Euris owes its creditors a total of 54 million euros: 50 million euros expiring in December 2022 and 4 million euros in June 2023. Because, unlike conventional loans, contracts in the form of derivatives are not "frozen" by the safeguard procedure for holdings in progress since May 2019. They must therefore be paid for.
The Societe Generale precedent
Societe Generale knows something about it. In 2019, when all of the group's holding companies were placed under safeguard proceedings, the bank had obtained through legal proceedings the benefit of Rallye shares as collateral for derivative contracts concluded in 2014 with the same Foncière Euris. She had thus found herself with 1.77 million Rallye shares, or 3.4% of the capital, which she had undoubtedly hastened to convert into cash.
Even today, if Foncière Euris could not honor its debts, the auditor reminds that the pledges on Rallye shares could result in a considerable loss of control of Casino's parent holding company. "The percentage of Foncière Euris in Rallye would drop from 57.9% to 39.8% in capital and from 71.8% to 55.6% in voting rights", details the document. What mortgage a little more the future of Jean-Charles Naouri at the head of Casino.
Jean-Charles Naouri doit trouver 50 millions avant Noël pour sa Foncière Euris
Dans le document de référence annuel sorti cette semaine, le commissaire aux comptes de la Foncière Euris, holding du groupe Casino, alerte sur le fait que la société manque de trésorerie pour honorer une grosse dette de produits dérivés avant Noël. De quoi fragiliser le contrôle du groupe de distribution.
Le PDG du groupe Casino, Jean-Charles Naouri (photo de 2009). © Christophe Petit Tesson/MaxPPP
Il faut parfois se munir d'une loupe pour déceler les déboires financiers du PDG du groupe Casino, Jean-Charles Naouri. En l'occurrence, il faut se rendre en page 12 du rapport financier annuel de la Foncière Euris, publié ce lundi 25 avril. Pour rappel, l'ancien dircab' de Pierre Bérégovoy a pris le contrôle de Casino grâce à une cascade de holdings. La Foncière Euris, située sous les holdings de tête Euris et Finatis, détient 57,9 % de Rallye, qui elle-même possède 52,3 % de Casino.
Or, en page 12 du document, le commissaire aux comptes explique : "La trésorerie prévisionnelle de la Foncière Euris, telle qu'estimée à ce jour, ne permet pas de rembourser les banques dérivées à l'échéance de décembre 2022 (ou juin 2023 dans certains cas)". La nouvelle a alerté les investisseurs scrupuleux. La Foncière Euris doit en effet à ses créanciers un total de 54 millions d'euros : 50 millions d'euros à échéance de décembre 2022 et 4 millions d'euros à juin 2023. Car, contrairement aux prêts classiques, les contrats sous forme de produits dérivés ne sont pas "gelés" par la procédure de sauvegarde des holdings en cours depuis mai 2019. Ils doivent donc être payés.
Le précédent de la Société générale
La Société générale en sait quelque chose. En 2019, au moment de la mise sous procédure de sauvegarde de l'ensemble des holdings du groupe, la banque avait obtenu par voie de justice de bénéficier d'actions Rallye en garantie de contrats dérivés conclus en 2014 avec la même Foncière Euris. Elle s'était ainsi retrouvée avec 1,77 million d'actions Rallye, soit 3,4 % du capital, qu'elle s'était sans doute empressée de convertir en cash.
Aujourd'hui encore, si la Foncière Euris ne pouvait pas honorer ses dettes, le commissaire au compte rappelle que les nantissements sur titres Rallye pourraient aboutir à une considérable perte de contrôle de la holding mère de Casino. "Le pourcentage de la Foncière Euris dans Rallye passerait de 57,9 % à 39,8 % en capital et de 71,8 % à 55,6 % en droits de vote", détaille le document. De quoi hypothéquer un peu plus l'avenir de Jean-Charles Naouri à la tête de Casino.
The Trouble For Big Tech Stocks In Two Charts
This month (so far) has been the worst for the Nasdaq since the stock market was in the throes of the Great Financial Crisis back in 2008. And it shouldn’t be hard to understand what is plaguing the Big Tech stocks that make up the bulk of this index. In addition to capital flows, macro economic trends, risk appetites and insider activity, all of which warned of the current weakness in stock prices well ahead of time, there are two major bearish forces at work.
At the start of the month, the five largest components of the index (Microsoft, Amazon, Nvidia, Tesla and Apple, aka MANTA) traded at about 55-times their aggregate free-cash-flow (and nearly 70-times when you back out stock based compensation). Now that might not be totally obscene if it weren’t for the fact that free cash flow growth has recently turned negative. In that context, however, it’s hard to see how the most extreme valuation in the history of this group is at all sustainable.

Of course, this is only half of the story.
The other half is told by the Fed’s balance sheet to which Nasdaq valuations are highly correlated. We might infer from this relationship that money printing supports asset values and, when taken to an extreme, stokes “animal spirits” to the point at which a speculative mania is formed. And, truly, this is a story as old as central banking. The trouble for Big Tech is that raging inflation means the Fed will now have to put its money printer into reverse in an effort at reining in price pressures, not only in the real economy (where its tools are less effective) but also in the asset markets (where its tools are much more effective).

The bearish tandem of falling free cash flow and waning liquidity suggests extreme valuations could revert in a major way, depending on just how much and for how long free cash flow declines and by how much and for how long the Fed is committed to draining the markets of excess liquidity.
Considering the nature of the pandemic and the stimulus enacted as a result, it’s not unreasonable to think there was a significant pulling forward of demand for Big Tech products and services that will now leave a vacuum of demand for a prolonged period of time. In addition, because inflation is now a bigger problem for the Fed than any time in the last 40 years, it may be far more difficult for the central bank to once again pivot away from hawkish policies should the stock market continue its decline.
If these concerns prove valid, the recession already underway in both free cash flow and liquidity could be more significant than investors have become accustomed to enduring over the course of this long bull market. And, as such, the reversion in extreme valuations may have only just begun.
Research Calls
- Upgrades:
- Antero Midstream (AM) upgraded to Overweight from Equal Weight at Wells Fargo; tgt raised to $13
- Ares Capital (ARCC) upgraded to Outperform from Market Perform at Hovde Group
- Autohome (ATHM) upgraded to Buy from Neutral at Citigroup; tgt $30
- Fifth Third (FITB) upgraded to Overweight from Equal Weight at Wells Fargo; tgt $52
- Kinder Morgan (KMI) upgraded to Equal Weight from Underweight at Wells Fargo; tgt $21
- MaxLinear (MXL) upgraded to Overweight from Equal Weight at Wells Fargo; tgt $66
- MSCI (MSCI) upgraded to Outperform from Mkt Perform at Raymond James; tgt $515
- RPC (RES) upgraded to Accumulate from Hold at Johnson Rice; tgt $13
- Wabtec (WAB) upgraded to Peer Perform from Underperform at Wolfe Research
- Downgrades:
- Coca-Cola (KO) downgraded to Hold from Buy at DZ Bank; tgt $69
- Columbia Financial (CLBK) downgraded to Neutral from Buy at Compass Point; tgt lowered to $20
- FARO Techs (FARO) downgraded to Hold from Buy at Craig Hallum; tgt lowered to $40
- Greenhill (GHL) downgraded to Underperform from Mkt Perform at Keefe Bruyette; tgt lowered to $12
- LG Display (LPL) downgraded to Underweight from Neutral at JP Morgan
- Moelis (MC) downgraded to Neutral from Overweight at Piper Sandler; tgt lowered to $50
- Peoples Bancorp (PEBO) downgraded to Mkt Perform from Outperform at Raymond James
- Spotify (SPOT) downgraded to Hold from Buy at Pivotal Research Group; tgt lowered to $110
- Teladoc (TDOC) downgraded to Mkt Perform from Outperform at William Blair
- Teladoc (TDOC) downgraded to Neutral from Buy at Citigroup; tgt lowered to $43
- Teladoc (TDOC) downgraded to Neutral from Buy at Guggenheim
- Teladoc (TDOC) downgraded to Neutral from Outperform at Credit Suisse; tgt lowered to $35
- Vroom (VRM) downgraded to Mkt Perform from Outperform at William Blair
- Others:
- Allstate (ALL) resumed with an Outperform at Credit Suisse; tgt $188
- Archer Aviation (ACHR) initiated with an Overweight at JP Morgan; tgt $7
- Arvinas (ARVN) initiated with an Outperform at Credit Suisse; tgt $104
- AvidXchange (AVDX) initiated with an Equal-Weight at Morgan Stanley; tgt $9
- Babylon (BBLN) initiated with a Hold at Berenberg; tgt $5.50
- Beam Therapeutics (BEAM) initiated with a Neutral at Credit Suisse; tgt $62
- C4 Therapeutics (CCCC) initiated with an Underperform at Credit Suisse; tgt $10
- CRISPR Therapeutics (CRSP) initiated with a Neutral at Credit Suisse; tgt $78
- EVgo Inc. (EVGO) initiated with an Overweight at Cantor Fitzgerald; tgt $14
- Freshpet (FRPT) initiated with a Buy at The Benchmark Company; tgt $135
- Intellia Therapeutics (NTLA) initiated with an Outperform at Credit Suisse; tgt $100
- Joby Aviation (JOBY) initiated with a Neutral at JP Morgan; tgt $7
- Kemper (KMPR) initiated with an Underperform at Credit Suisse; tgt $44
- Kinetik (KNTK) initiated with a Buy at BofA Securities; tgt $80
- Kymera Therapeutics (KYMR) initiated with an Outperform at Credit Suisse; tgt $63
- Lilium GmbH (LILM) initiated with a Neutral at JP Morgan; tgt $5
- Monte Rosa Therapeutics (GLUE) initiated with a Neutral at Credit Suisse; tgt $19
- Progressive (PGR) initiated with a Neutral at Credit Suisse; tgt $124
- Sachem Capital (SACH) initiated with an Outperform at Oppenheimer; tgt $6
- Silicon Labs (SLAB) assumed with a Hold at The Benchmark Company
- Vascular Biogenics (VBLT) initiated with a Buy at Chardan Capital Markets; tgt $5
- Xeris Biopharma (XERS) initiated with a Buy at Craig Hallum; tgt $6.50
Gapping down
In reaction to earnings/guidance:
- TDOC -42.5%, ALGN -22.3%, BTU -11.7%, DPZ -7.5%, SWK -7.4%, ORLY -6.5% (also names new CFO), JKS -6.5%, LH -5.2%, AMGN -5.1% (also receives notice of deficiency from IRS), RLGY -5.1%, CAKE -5% (also dividend and buyback reinstated), AMSF -5%, COUR -4.9%, CACI -4.8%, CHD -4.5%, CLB -4.1%, OSTK -3.9%, TW -3.6%, NTGR -3.5%, UIS -3.3%, FARO -3.2%, GGG -3%, MC -2.5%, POR -2.4%, ALSN -2%, KBR -1.8%, SO -1.8%, KIM -1.7%, CAT -1.6%, HAYW -1.5%, HOLX -1.3%, STRA -1.3%, FTI -1.2%, TS -1.2%, EQIX -1.1%, LIN -1.1%, UCTT -1%
Other news:
- IKNA -6.8% (files for $300 mln mixed securities shelf offering)
- FHN -3% (files mixed securities shelf offering)
- ARKK -0.6% (down on TDOC earnings)
Analyst comments:
- GHL -8.7% (downgraded to Underperform from Mkt Perform at Keefe Bruyette)