Business Of Fashion : Luxury Seizes the Vacation Dressing Boom

Luxury Seizes the Vacation Dressing Boom
Camille Miceli’s Pucci debut on the island of Capri reflects the industry’s growing focus on resortwear — and resort retail — as consumers return to pre-pandemic lifestyles.
Camille Miceli's Pucci experience on the island of Capri shows how the industry's expansion into resortwear—and resort retail—is accelerating.

KEY INSIGHTS
  • Luxury players are betting big on vacation dressing this year as international travel looks set to rebound
  • Vacation lines target high net-worth clients, but they also provide an avenue to stay relevant with more aspirational, younger consumers
  • Retailers also see an opportunity to engage wealthy consumers while they travel, opening pop-ups and stores in resort hotspots like Capri and Saint Tropez

CAPRI — To mark her first collection for Italian luxury brand Pucci, creative director Camille Miceli axed the traditional runway show and took a different route: she organised a holiday.
The former Louis Vuitton accessories designer partnered with German e-tailer MyTheresa to stage a three-day experience on the idyllic island of Capri, bringing together a mix of industry figures, influencers and top clients to live la dolce vita — Pucci style. That meant zipping around on speed boats, seafood risotto and champagne cocktails on the beach, and serenades by a traditional folk band; starting the day with morning yoga and singing along to classic tunes like Volare into the night.
Meanwhile, the house’s kaleidoscopic prints could be spotted all around the isle: on table clothes at the local bar; adorning the interiors of speed boats at the harbour; on seats of the island’s funicular cable car. It was Instagram catnip that assured an online splash for a brand that previously struggled to gain traction on social media.
“You don’t relate to seasons, you don’t relate to fashion shows, you relate to a spirit of mind,” Miceli said. “I wanted to emphasise even more the lifestyle — the Pucci lifestyle. It’s about a smile that it gives you when you look at the clothes and you look at the collection.”

Miceli's collection focuses around six different prints from the Pucci archives. “They all have to work together. They all have to mix together,” she said. (Business of Fashion)
The trip exemplified Miceli and parent company LVMH’s vision to re-energise the house by leveraging its roots as a vacation label for fashionable jet-setters, just in time for a post-pandemic vacation surge expected this summer.
“We realised that Pucci was, first of all, a resort concept,” said Sidney Toledano, chief executive of LMVH Fashion Group. “The big names [like Dior] are also looking for the resort, for the beach concept. It’s a big opportunity.”
Pucci isn’t the only luxury player betting big on vacation dressing this season: Dior and Chanel are rolling out more beachside pop-ups in markets including Montenegro and Turkey. Matchesfashion is about to kick off what it calls a “Grand Tour of Italy,” staging activations in Florence, Naples and Ischia as part of a partnership with Pellicano Hotels Group.
The moves come as international travel appears ready to finally bounce back from the pandemic, with consumers in key regions like the US gearing up for their first mask-free summer vacations since 2019. Swimwear sales are set to surpass pre-pandemic levels to hit $22.1 billion in 2022, according to Euromonitor, suggesting shopping for vacation is ready to come back bigger than ever.
“Vacation dressing’s resurgence … is now at a fever pitch, with fewer restrictions around travel than has been allowed since pre-pandemic times,” said Kayla Marci, analyst at market intelligence firm Edited. “Both fashion and luxury retailers have adjusted their assortments to embrace a long-awaited return to normality.”
Resortwear was already becoming a key category for luxury retailers before the pandemic. Shoppers increasingly sought outfits to enhance their travel experience — and how it looked to social media followers back home — with each photo-op representing a bankable opportunity for brands.
For many companies, what started as seasonal marketing interventions quickly turned into a significant business. Just look at Loewe’s Paula’s Ibiza line: what began as a capsule collaboration between the Spanish luxury house and an iconic Balearic boutique back in 2017 has now flourished into a fully-fledged sub-label, spanning ready-to-wear, accessories, and even perfume. In 2019, Loewe acquired the Paula’s Ibiza trademark and archives, allowing creative director Jonathan Anderson to continue to build out the line as a brand within a brand.
Big names like Chanel and Dior bolstered their vacation offerings with dedicated capsule collections, while multi-brand retailers moved beyond bikinis and coverups to sell head-to-toe poolside ensembles. Today, holiday dressing assortments at the likes of Mytheresa and Matchesfashion include items like €280 Zimmermann beach towels, €450 raffia visors from Valentino and Gabriela Hearst, and €1,150 Saint Laurent beach bags.

“It’s really a very popular purchasing occasion,” said Paolo De Cesare, chief executive at Matchesfashion. “Going to a new place and meeting new people and going to new hotels — there’s nothing like this that sparks the idea of updating your wardrobe.”
Matchesfashion is about to kick off its “Grand Tour of Italy,” curated by Marie-Louise Scio and Robert Rabensteiner. (Matchesfashion)
It helps that vacation lines and beachwear items tend to be more accessibly priced than luxury houses’ usual handbags or ready-to-wear lines. A raffia basket bag from Chloé costs about €550, much less than the French house’s classic leather styles that command a price tag of nearly €2,000.
Luxury brands offer these items as a way for high net-worth clients to accessorise their holidays. But they also provide an avenue to stay relevant with more aspirational, younger consumers at a time when prices for their flagship bags are headed skyward.
Consumers see value in the way printed summer dresses and designer basket bags can easily translate from the beach to summer in the city. “[Shoppers] may be buying for the purpose of vacation, they still want to be sure they will use these items again once they return back to their everyday routine,” said NPD analyst Maria Rugolo.
For many consumers, summer 2022 has already started. At Net-a-Porter, the retailer says it is already seeing success selling wicker bags from Loewe, Saint Laurent and Chloé as well as straw hats from Gucci and Valentino. It’s betting hot new drops like Louisa Bellou’s “Sex Wax” swimsuit, Dior sunglasses and exclusive swim pieces from Alaïa will keep shoppers spending as summer rolls on.
Last month, MyTheresa added a special “vacation” shopping tab to its homepage. In April, sales of the women’s vacation category have tripled compared with 2019 levels, according to chief executive Michael Kliger.
“There’s pent up demand,” he said, noting that this is the first season since 2019 when many Americans were willing to venture to Europe again. Brands like Zimmermann, Loewe and Valentino are particularly popular, he said. “It is just much more than beach and swimwear. It’s the full accessorisation … And so we try to offer the basket, the sandals, the sunglasses.”
Brands also see an opportunity to engage wealthy consumers while they travel, marketing special beach collections to a captive audience of resort-goers who have plenty of time to browse — and buy.

Chanel's seasonal boutique in Saint-Tropez. (Marina Denisova)
Chanel just reopened its seasonal boutiques for its Coco Beach collection in Saint Tropez, Capri and Marbella. Dior, meanwhile, is expanding the reach of its Dioriviera beach collection, launching pop-ups in new locations like Bali, Montenegro, and New York’s Montauk.
This weekend in Capri, Pucci’s guests weren’t just posting their Chandon spritzes and beachside selfies online, they were buying too: Shoppers crammed into the brand’s boutique on Via Camerelle to purchase vibrant silk shirts, towering metallic wedges, and chunky pescare bangles inspired by the new brand logo, where two fishes intertwine to form a letter P.
“It’s perfect timing,” Mytheresa’s Kilger said of Pucci’s reboot, “because [after lockdowns] it is so much nowadays about going on vacation, having a party, enjoying life. And the DNA of the brand is very much joy.”

Business Of Fashion : For RTFKT and Nike, Sneaker NFTs Are Just the Start

For RTFKT and Nike, Sneaker NFTs Are Just the Start
RTFKT hasn’t slowed down since Nike acquired the company last year. Its founders have a bold vision for their brand’s future as they seek to bridge the digital and physical worlds.
The "Clones" of Chris Le, Benoit Pagotto and Steven Vasilev, with the RTFKT x Nike Dunk Genesis CryptoKicks. (RTFKT)

KEY INSIGHTS
  • RTFKT's goal is to build an expansive ecosystem of products that all link back to each other in a grand vision it's enlisting its community's help to build.
  • Its new virtual sneaker with Nike is just the first of many items it has planned with the company, including physical goods.
  • The NFT market broadly appears poised to shift away from collectables to items with more utility.

In 2019, Benoit Pagotto, Chris Le and Steven Vasilev were on the verge of launching RTFKT — their brand of virtual sneakers riffing largely on classic Nike silhouettes — when they learned Nike itself had been granted a patent for blockchain-linked shoes it called CryptoKicks.
The trio, who were travelling in Japan to get inspired, questioned whether to keep going but ultimately carried on, beginning to drop digital shoes like the “Cybersneaker” famously photoshopped onto Elon Musk. Over the next year or so, RTFKT — pronounced like “artefact” — built its brand, blending streetwear and gaming through items like NFT sneakers and collaborations.
During that period, Nike never released its CryptoKicks. Instead, it acquired RTFKT in December. When the sneaker giant did put out its first NFT footwear, the Nike Dunk Genesis CryptoKicks, it was with RTFKT, whose founders are now senior directors at the company.
In the time between the Japan trip and the launch of the Nike CryptoKicks, RTFKT became one of the biggest brands in the NFT market, which surged to $17.7 billion in sales in 2021, according to data from Nonfungible. Collectors have snatched up items like its sneakers with digital artist Fewocious and the “CloneX” avatars it created with Takashi Murakami for sums that routinely reach into the thousands or tens of thousands of dollars — and sometimes higher.

To those Clone owners, who form the foundation of the ecosystem it is building, it has “airdropped” freebies they can use with their Clones to start assembling a fictional world. What the company is really trying to do is construct the metaverse, step by step, by encouraging its audience to use its products as the building blocks.
The brand’s fans on Twitter and Discord anxiously await news of what’s to come. This year, they spent months eagerly solving puzzles trickled out by RTFKT to unlock one of those airdropped items, a mysterious cube RTFKT dubbed MNLTH. (The opening revealed RTFKT’s CryptoKicks with Nike, a “skin vial” to customise them and another MNLTH.)
“These buzzwords that we hear in retail and fashion and consumer culture of authenticity, experience and community, they live at the cross-section of them,” said Brian Trunzo, a fashion industry veteran who is now metaverse lead at Polygon Studios, the consulting arm of the Polygon blockchain.
An RTFKT x Nike hoodie. (RTFKT)
It arguably makes RTFKT a new kind of brand — one poised somewhere between the currents of fashion, crypto and gaming, and well-positioned to capitalise on the growing confluence of the three.
But it also has to contend with the challenges of the NFT market. Overall sales have slowed, and the market is rife with financial speculation. Many NFT projects appear to be cash grabs without much evident thought beyond a quick profit, tarnishing the image of the space. Not least of all, the space itself is entirely new, making its future far from clear.
RTFKT’s Vision for the Future
RTFKT’s founders met in 2018, when Pagotto, then head of marketing for the e-sports team Fnatic, was searching for someone to make gaming skins — add-ons that change the appearance of a character or item. He found Le, who had a business creating skins for “Counter-Strike.” Their paths then crossed with Vasilev, who ran a successful sneaker customisation studio in London, and together they produced a shoe for Fnatics’ “League of Legends” team.
If there’s one belief that unites them and drives RTFKT, it’s that the digital signifiers we use to broadcast our identities, tastes, social status and other traits are just as important as the physical ones — if not more so.

“The vision has always been that in the future all your digital possessions will be a lot more valuable to you than your physical possessions, and that means both economically and emotionally,” Pagotto said.
Virtual goods still have a long way to go before they surpass real-world stuff on a mainstream level — if that ever happens. But what’s clear is consumers who are online are spending more time there. RTFKT is designing for this future, devising identities, digital products and even homes. It sent “space pods” to the wallets of Clone holders that look like small futuristic apartments.
The point is to make all releases going forward interoperable, meaning they can be worn by a Clone, displayed in the space pod or used in some other way with previous RTFKT items. Vasilev said the next phase they’re moving into is “building full ecosystems and different units where everything will interlink.”
In doing so, RTFKT allows its fans to combine its products in different ways, involving them in building its mini-universe. Items like the Nike CryptoKicks are also AR-enabled, so parts of that universe can be overlaid on the real world.
The team is now introducing “evolution” mechanics. Owners of the CryptoKicks can use the “skin vials” RTFKT is releasing to change their look, which is derived from gaming aesthetics. But using a skin vial “burns” it, so as more are used the rarity of certain vials will increase.
The evolution of one pair of RTFKT x Nike Dunk Genesis CryptoKicks. (RTFKT)
Building With Nike
How, exactly, this vision sits within Nike’s business isn’t fully apparent, at least not yet. Pagotto described Nike and RTFKT as both being innovators, just in different worlds: Nike in sports, RTFKT in web3. While he was initially surprised Nike wanted to buy their company, he ultimately concluded it made sense. If Nike planned to enter this space, the smart approach, in Pagotto’s view, was to bring on a team that could build in it natively.
But while the RTFKT team advises Nike, it isn’t crafting the company’s NFT strategy, according to Pagotto. Its day-to-day focus is still RTFKT, over which it maintains autonomy. The companies do work closely though. Nike has an interest in protecting the legacies of products like the Dunk, a style that was instrumental in the birth of modern sneaker culture, and just the first of Nike’s classic styles RTFKT said it will modify.

“Especially with the art, we get a lot of insight from Nike’s team on keeping the traditional, classic look,” Le said. “As RTFKT, we tend to go a little crazy.”
RTFKT, meanwhile, gets to tap into Nike’s archive, draw on its brand-building expertise and get access to the machinery behind the largest sneaker company in the world. RTFKT was already a pioneer in what’s called “forging,” where an NFT product is turned into a tangible one.
“We’ve had nearly every resource opened to us and we have some really cool physical products coming out of the pipeline,” Vasilev said.
Their goal is to gradually bridge the digital and physical worlds.
Fighting “FUD” and the Road Ahead for NFTs
After soaring in 2021, the market for NFTs has recently cooled. Both the number of NFT sales and average prices have fallen, and sceptical analysts have raised doubts about its long-term outlook.
The crypto community generally retorts that NFTs are in their early stages, and their full uses still being worked out. They’ll evolve far beyond the jpeg collectables that have dominated the space, the argument goes.
“The trend is moving towards giving them utility, so that they can be used within metaversal virtual worlds or to unlock next-gen loyalty rewards from desirable brands,” Polygon’s Trunzo said. “If they don’t have utility — if they are just collectables — they will become akin to the stuff that you find in your junk drawer.”
RTFKT subscribes to this view, but it isn’t entirely insulated from what those in crypto call “FUD” — fear, uncertainty, doubt. When it first revealed its CryptoKicks with Nike, after months of making its fans solve riddles to unlock the MNLTH containing them, some posters in its Discord were not immediately impressed. The price of a MNLTH on the secondary market abruptly dropped.
It rebounded within minutes, though, as more detail about its contents and the CryptoKicks emerged. (Vasilev also pointed out that they gave out the MNLTH for free, so the fact that they were being traded for any substantial value was a testament to their success.)
MNLTH. (RTFKT)
“What we know for sure as a rule is there will always be people who complain,” Pagotto said. “There will always be people who try to take advantage of the situation.”
These are common issues in web3. Because creative projects double as financial assets, frequently with high price tags, they’re often measured by how much profit they might generate for those who buy in. The space is also brimming with scams.
The RTFKT team acknowledged these as challenges, and added that the user experience in web3 is complicated and cumbersome at this stage. But they and others in crypto see these as the normal problems that come with entering a new technological frontier.
For now, RTFKT’s interest lies in continuing to work on projects they believe in, with Nike and on their own. Maybe most important is gathering the help they need to fulfil their vision.
“You need to be able to build worlds,” Pagotto said, “and also mainly attract a community that’s going to build that world with you.”

TechCrunch : Why a bipartisan embrace of crypto might never touch Bitcoin

Why a bipartisan embrace of crypto might never touch Bitcoin
Image Credits: Getty Images
Hey everyone, and welcome back to Chain Reaction
In our Chain Reaction podcast this week, Anita and I chatted with Sequoia Capital’s Shaun Maguire on why gamers are skeptical of NFTs and where decentralization really matters. More details below.
Last week was our inaugural newsletter and we chatted at length about the changes Twitter could make to expand its crypto business. At that point, I — like many others — was operating under the assumption that a Musk Twitter deal was ultimately doomed, but low and behold we’ve got a deal. Everything has been approved at this point, but I can’t shake a feeling that something is going to kill this deal in the eleventh hour. If that happens, Twitter’s board or Musk will be on the hook for a $1 billion penalty for walking away from the deal, but I suppose we’ll see … This week, I’m looking at a controversial Bitcoin mining ban working its way through New York regulators and what bills like it could mean for the political reputation of crypto’s #1 coin.
To get this message in your inbox on Thursday mornings, you can subscribe on TechCrunch’s newsletter page. Follow me on Twitter while you’re at it!


Image Credits: Getty Images

the hottest take
Crypto’s biggest skeptics see plenty of reasons to criticize the industry, but generally at the heart of most complaints is a belief that crypto is contributing very little to society while burning massive amounts of energy.
While crypto’s believers could squabble over the former point until they’re blue in the face, the latter is a little harder to deny. Bitcoin uses an estimated 204.50 terawatt-hours (TWh) of electricity per year at current rates according to the oft-cited tracker built by Digiconomist, this number is equal to the power consumption of Thailand. Meanwhile Ethereum’s energy footprint is half the size but still comparable to the power consumption of Kazakhstan. In 2018 the United States reported its total consumption of electricity as 4,222.5 TWh.

For some legislators, those numbers are hard to swallow. This week, the New York State Assembly passed a bill that had team crypto up in arms. The bill blocks the formation of crypto mining firms in the state that rely on non-renewable power. It notably doesn’t apply to existing facilities. A corresponding bill is currently making its way through the Democrat-controlled state senate.
This is fascinating for a whole bunch of reasons.
For one, crypto is increasingly becoming a partisan topic. Republicans are typically wary of regulating unregulated industries and thus a number of major figures in the party have thrown their full support behind crypto with few concessions. This includes prospective future party leaders like the governors of Texas and Florida. Meanwhile, most of crypto’s most ardent critics appear to be Democrats, but that’s not to say it’s a party-line issue. President Biden’s recent cryptocurrency executive order was generally regarded as very friendly to the space by industry insiders. The energy usage seems to be the most salient sticking point for many regulators looking at sweeping bans.

The other reason that this is interesting is that this bill really only impacts a handful of major crypto networks, but that includes the two biggest ones — Bitcoin and Ethereum.
These networks use something called a proof-of-work mechanism to secure their networks. The work in this case is mining that involves computers working around the clock to essentially solve math problems that are protecting the integrity of the blockchain, making it extremely expensive and technically challenging for hackers to overwhelm the network to make unauthorized transactions and steal tokens. Crypto seems to be generally trending away from proof-of-work, most notably, Ethereum is deep in the process of transitioning its network toward a less energy-intensive consensus method. But Bitcoin seems unlikely to make its own transition, suggesting that regulatory maneuverings, like New York’s bills, are likely going to be increasingly antagonistic toward Bitcoin (and a few smaller networks) specifically.
This could lead to an interesting scenario where the crypto industry increasingly finds mainstream tolerance among its current critics but Bitcoin finds itself growing more and more politically isolated.
Bitcoin already broadcasts its libertarian bent a bit more prominently than other blockchains. At recent industry events, it’s becoming clearer that amid a burgeoning developer ecosystem for blockchains like Ethereum and Solana, the philosophy of the Bitcoin network’s infrastructure is increasingly its most harmonizing element. Bitcoin’s continuing resistance to criticism and calls for change may only embolden its supporters, but critiques around the power consumption of the network aren’t going anywhere and further adoption may only make this a more visible target for aggressive regulation.
Some politicians may grow to love crypto but hate Bitcoin all the same.

(ZH) Buyback Blackout Period Is Over, And 10 More Reasons Why Goldman Calls The

Buyback Blackout Period Is Over, And 10 More Reasons Why Goldman Calls The End Of The Market Carnage

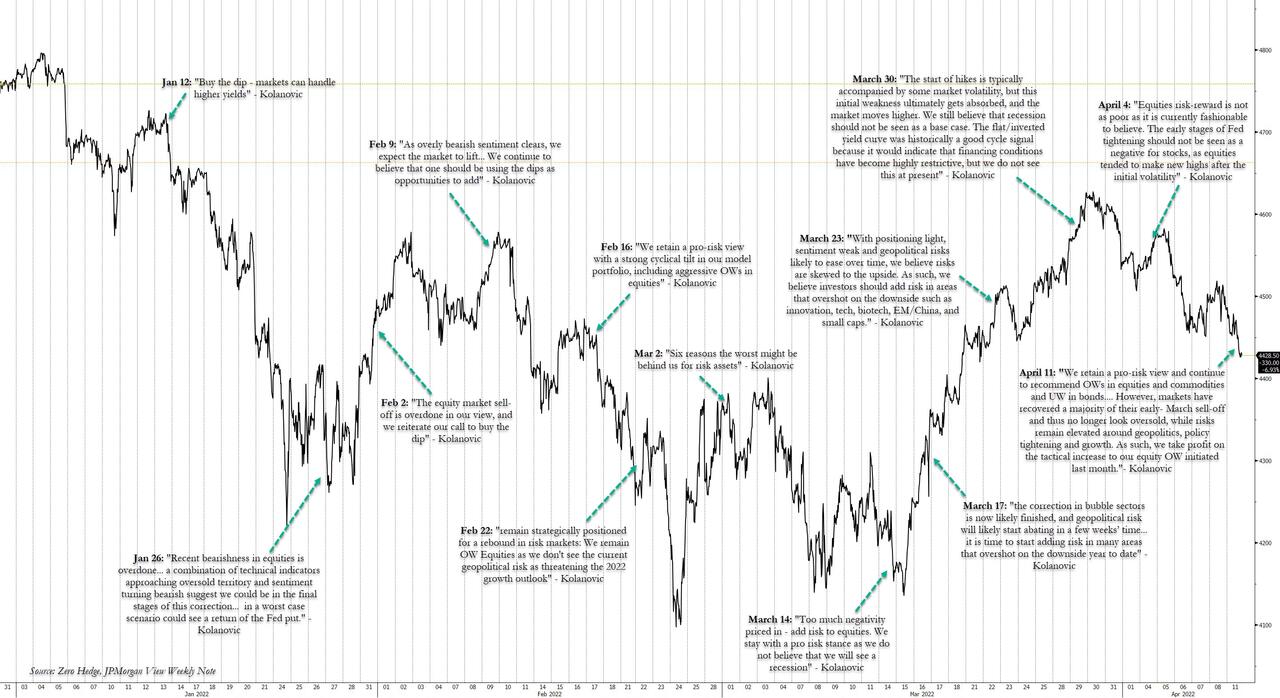
Two weeks ago, when looking at a recent matrix of market bull and bear cases, we asked if it was time to get bullish on stocks and concluded that the since fundamentals leaned in either direction, the answer was most likely “not yet” for one simple reason: JPM’s resident permabull, Marko Kolanovic, had just turned from modestly bearish – an extremely rare stance for him – to bullish again, urging his clients to reverse from taking profits (unclear on what exactly since he had been bullish all the way down from the market’s all time high)…
… to buying the dip again. Meanwhile, at roughly the same time, the far more accurate strategists at Goldman’s flow desk – in this case Tony Pasquariello - had just warned that the market was likely to be well lower in several weeks time, not higher. After last week’s furious rout in the market they were right.
Which is why we find it worth mentioning that after correctly calling the market’s downward inflection point in April, those same Goldman folks are once again leaning bullish, and in a Friday note from Goldman Scott Rubner (which is not for mass distribution to the bank’s entire client base and instead is reserved for a handful of the bank’s top client as it indicate what the bank’s traders actually do believe, it is also available to zero hedge professional subscribers), he says that the worst is behind us and gives 11 reasons why the late April rout may have been the market bottom for the time being.
Rubner’s argument in a nutshell: pointing to Thursday’s explosive move higher as testament of the market’s extremely negative sentiment and low positioning (which of course was followed by Friday’s rout), the Goldman trader thinks that global stocks will rally “significantly” in May as the flow-of-funds is set to improve starting on Monday (even though the closely watched 50bps rate hike FOMC meeting is due on May the 4th).
Below we lay out Rubner’s bullish 11-point checklist in greater detail.
  • 1. US Corporates return back to the open window on Monday with dry powder. Rubner calculates $5BN of demand per day, every day until mid-June. US corporates are the largest buyer of equities in 2022 and have authorized record YTD (AAPL = $90bn; GOOG = $70bn; MSFT = $60bn; FB = $50bn, etc).
  • 2. Pensions flipped to buy given the recent outperformance of bonds vs stock. This should carry over into next week.
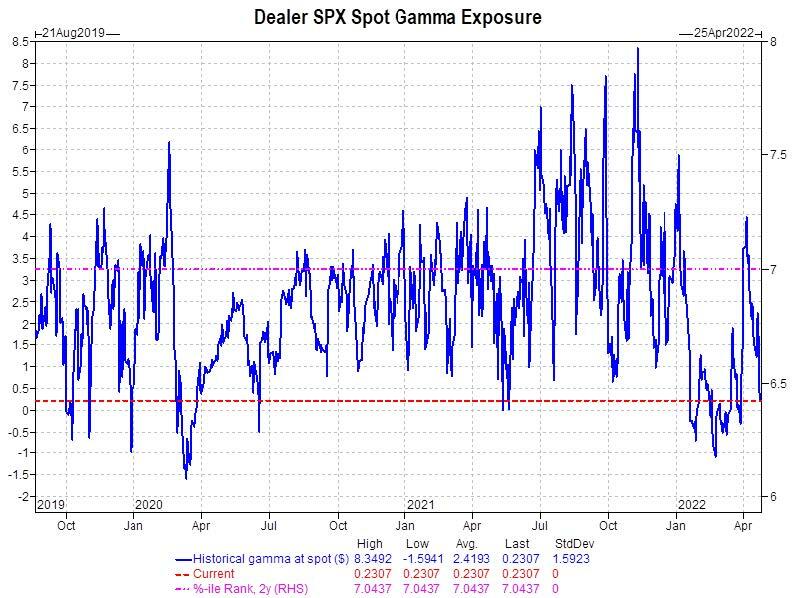
  • 3. S&P Index gamma turned negative on Thursday for the first time since March.
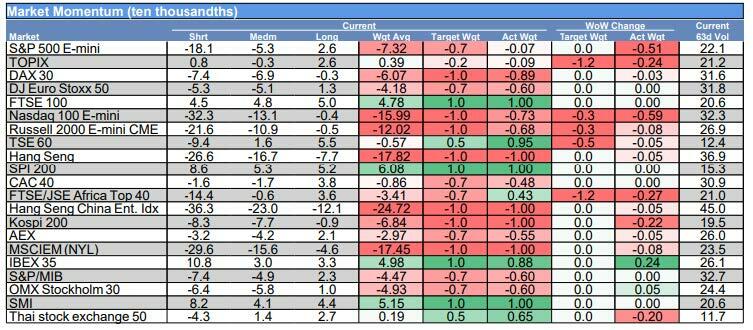
  • 4. Synthetic Short Gamma through CTA and Vol-Control strategies supply will fade over the next week (Thursday’s move will lower some of the supply expectations and Goldman’s estimates will dramatically change next week).
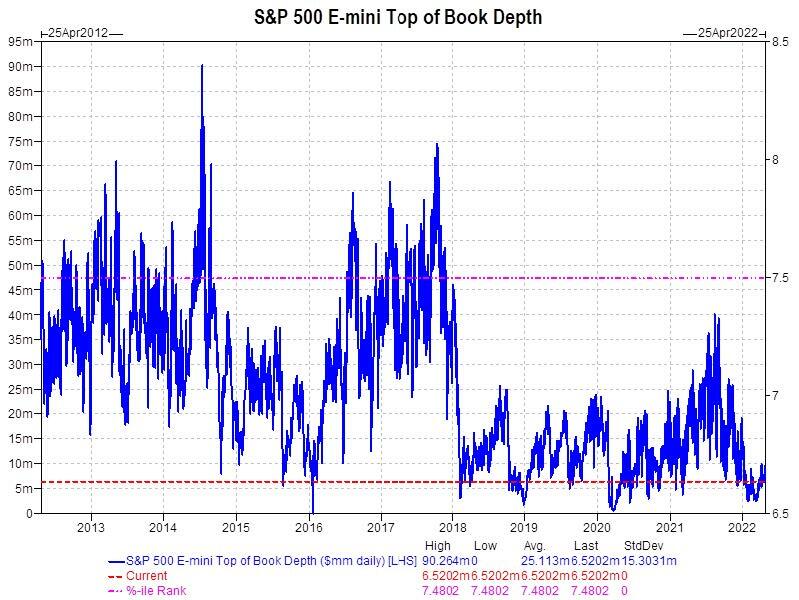
  • 5. Liquidity is simply not available to try to cover liquid macro. As we noted on several occasions last week [insert hyperlink to liquidity tweet], top book liquidity in the S&P 500 futures is $2.8M. This ranks in the 1st percentile in the last 10-years. This is as low as it gets.
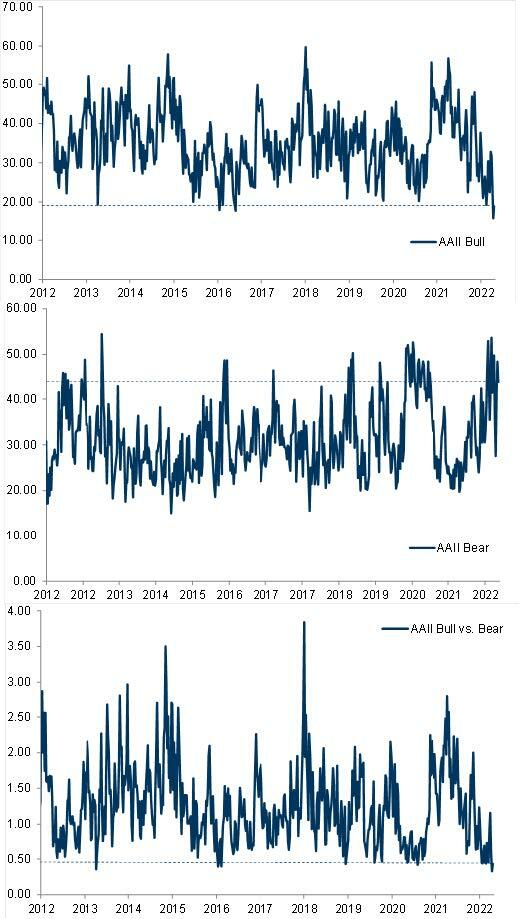
  • 6. Sentiment is the most bearish since the market crash lows in March 2009. Rubner says that he has done “more bearish zoom calls these past two weeks, than I can recall.” The bears (AAIIBEAR) published a reading of 59.40 today. This was the highest level since March 5th 2009 (70.27). S&P500 rallied 8.54% in March 2009 and 9.39% in April of 2009. That was the generational market bottom.
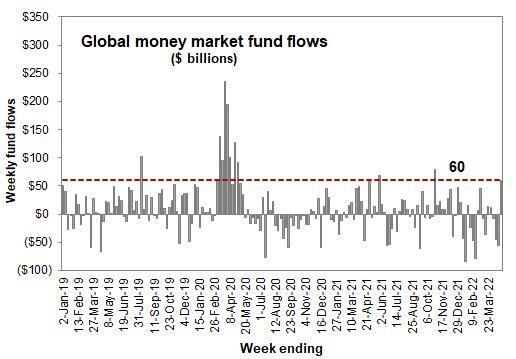
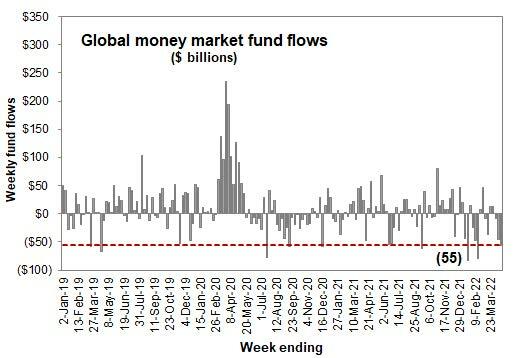
  • 7. Money Market Inflows Logged a massive +$60B inflows last week, which was the largest weekly inflow since Covid 2020 (and typically another fear gauge).
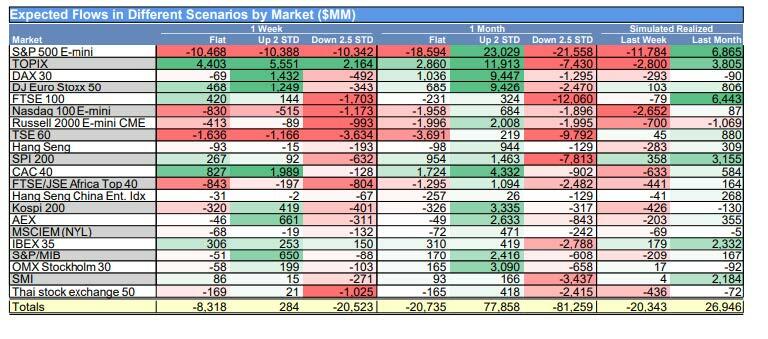
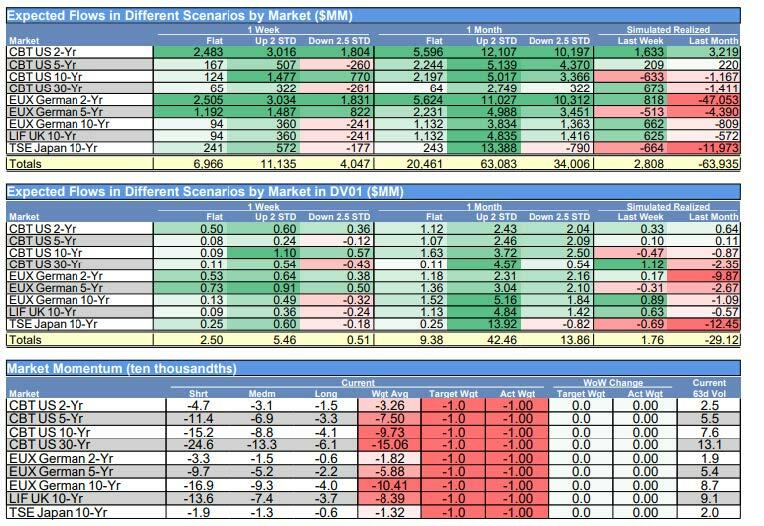
  • 8. For the fixed income watchers, Goldman’s CTA models show some impressive demand. Goldman has +$20B of bonds to buy in a flat tape, but +$117B of bonds to buy in an up tape, and $37B of bonds to buy in a down tape. This should ease some of the pressure on long duration equities and largest construction of market cap.
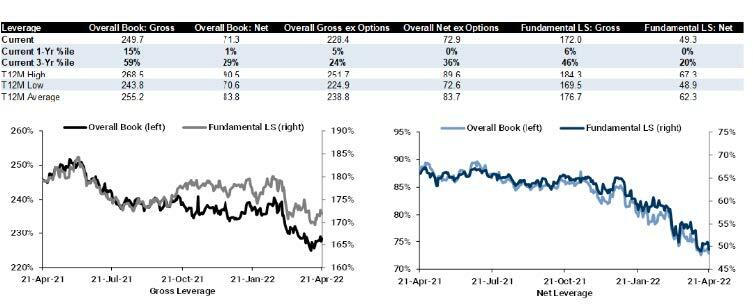
  • 9. Goldman’s Prime Desk notes that hedge funds exposure is dismal. Gross and Net Exposure are currently at 2-year lows. And vs the past 5 years, Gross ranks in the 21st and Net ranks in the 38th. US TMT Megacap L/S ratio declined by -48% in the past 1-month. (~right before earnings)
  • 10. Everyone is short: Short leverage (with options) ranks in the 98th percentile in the last 5 years.
  • 11. New month = New Inflows. There should be some decent inflows to start May per normal rebalancing cycle in retirement accounts.
* * *
Rubner then does a more detailed breakdown of what the latest flows indicate for markets. We excerpt from the main points below (professional subscribers have access to the full note).
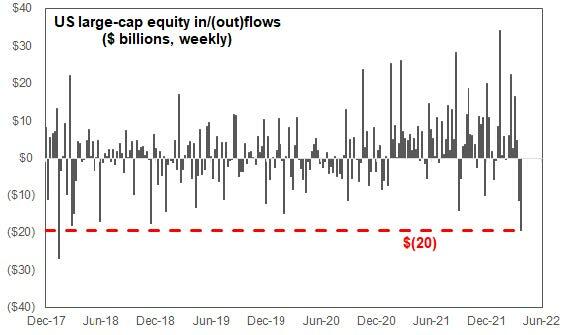
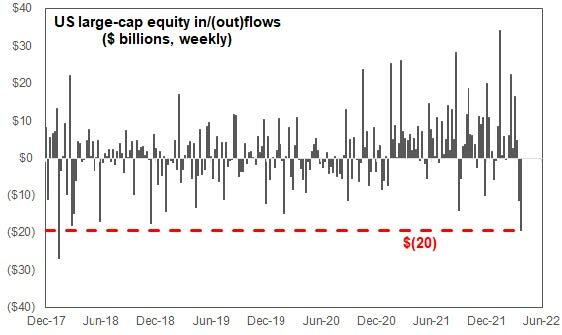
1. Passive USA Large Cap Outflows (and resulting MOC 3:50pm imbalances): = “you ask me for money and I sell”
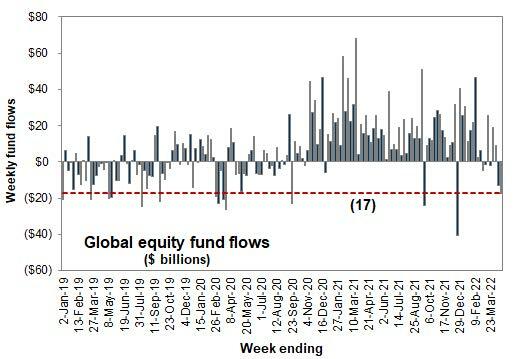
  • US Equity Funds registered their largest outflows of 2022.
  • b) US large cap Equity funds registered the largest outflows since 2018.
  • c) this is LIFO (last in, first out) behavior. This is where all of the new repatriated safe haven has flowed.
* * *
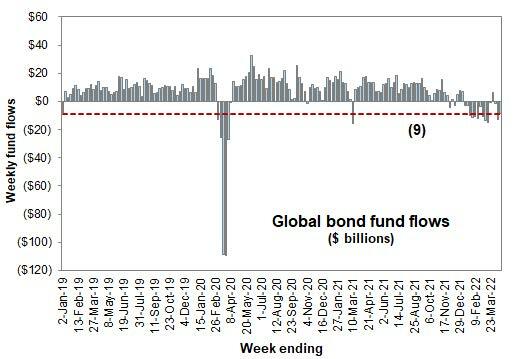
2. “Everything cross-asset outflow” - this is rare. Stocks, Bonds, and Cash all saw outflows this past week
  • You don't see this very often. This is what we call an everything outflow. No lines saw inflows, and its back to checking accounts.
* * *
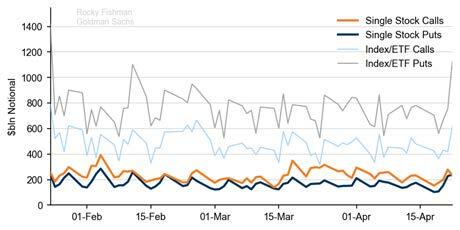
3. Retail Investors buyers of 0-1 DTE (days-to-expiry) puts are largest on record – does retail start buying calls again?
  • Friday's same-day SPX were the highest dollar-volume ever traded for a single expiry on a single day
  • $225bln of puts and $160bln notional of calls traded
    • Already in 12 figures on Friday’s SPX expiration - $105bln in just the the first hour. Keep an eye on DTEs
  • Daily option volume Notional volume ($bln) traded in listed US equity options
Final-day trading volume: Notional SPX option volume traded on the day of expiration, excluding Third Friday and end-of-month expirations
* * *
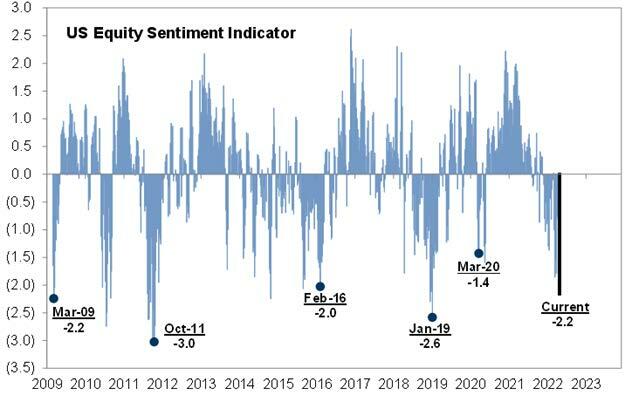
4. Both Professional and Retail Sentiment have reached new lows. Rules and Tools have historically marked a contrarian indicator.
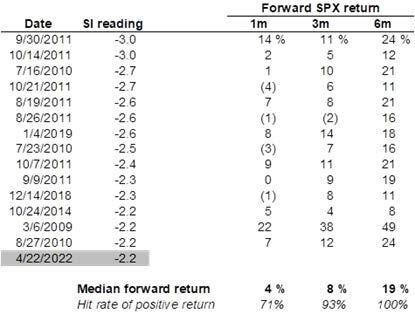
  • GS sentiment indicator (SI) current reading of -2.2 is a signal of extremely light positioning and typically acts as a solid contra indicator for the market. Out of 687 weekly readings (first recording: 2/27/09), there have only been 14 instances in which the sentiment indicator was more negative (below -2.2).
  • AAIIBULL (bullish investors) reached the 9th lowest reading since 1987 (1820) observations (zeroth percentile).
  • Market returns after such extremely negative readings have been uniformly bullish, and the hit rate six months after such a reading is 100% (14 of 14 occasions), leading to a median 19% return!
* * *
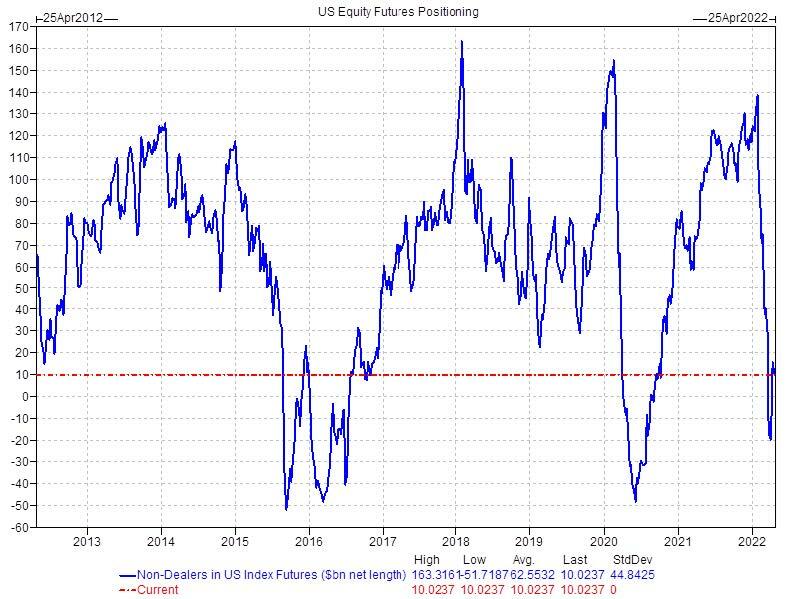
5. Futures Positioning has been unwound and ranks in the 15th percentile over the past 10 years.
  • For context, the high futures position for 2022 was +$138.4B (January 25th ) vs. +$10B currently.
* * *
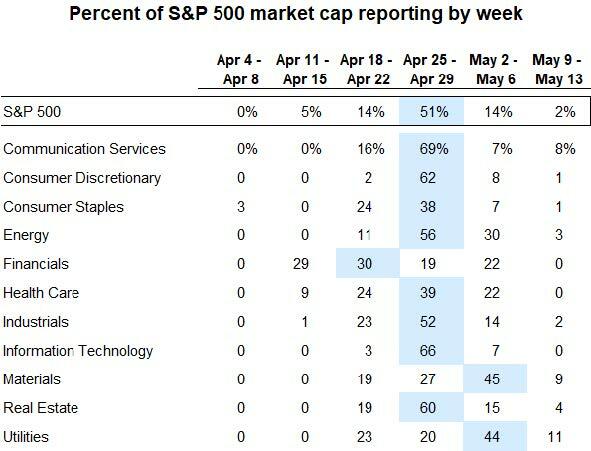
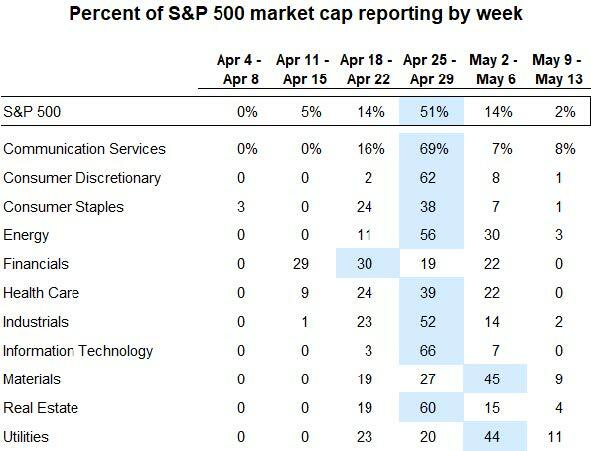
6. Peak Blackout is behind us. US Corporates return from the blackout window on May 2nd (Monday). The largest buyer of equities in 2022 has been out of the market for much of April and is now back.
  • 51% of the S&P 500 reported last week. This is the largest week for earnings in Q1. Corporates are slowing re-emerging from the blackout.
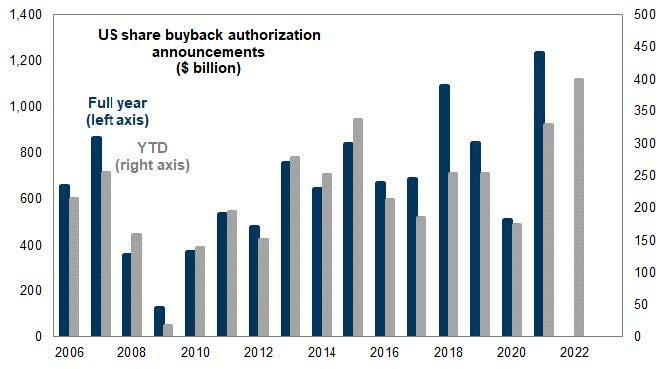
  • 2022 US corporate authorizations are off to the best year on record. Do they come back to buy stocks at these levels having already authorized? Do we hear about more big authorizations this week?
  • GS buyback activity last week was 2.4x the bank’s average 2021 levels - despite being in the earnings 'blackout window.’ the bank estimates ~59% of companies will emerge by this time next week
* * *
7. S&P Index Gamma (no longer long) given institutional “forced hedging” of May puts – do we see monetization of puts after the big FOMC event next week?
Dealer long gamma has been unwound, and works in both directions. This will exacerbate, not buffer moves in the same direction as the market.
* * *
8. Systematic Equity Supply is far smaller than some have feared given recent deleveraging.
  • Goldman calculates that CTA strategies have to sell $8B over the next 1 week and $21B to sell over the next month.
  • In an up tape, CTA strategies have up to buy $78B vs. down tape -$81B to sell. Said otherwise, they will continue to trade negative synthetic gamma in the same direction as the market
* * *
9. Synthetic fixed income short gamma (CTA strategies) have triggered flip levels. Does FI demand ease pressure on rate move and long duration equities?
  • Bond yields lower = SPX construction higher? This might be important chart for equity traders given the large cap tech weighting of the indices.
* * *
10. S&P 500 Top Book Liquidity “works in both directions”
  • Liquidity in the most liquid equity future in the world ranks in the 7th percentile in the past 10 years, and offers just $6M to trade on the screens.
* * *
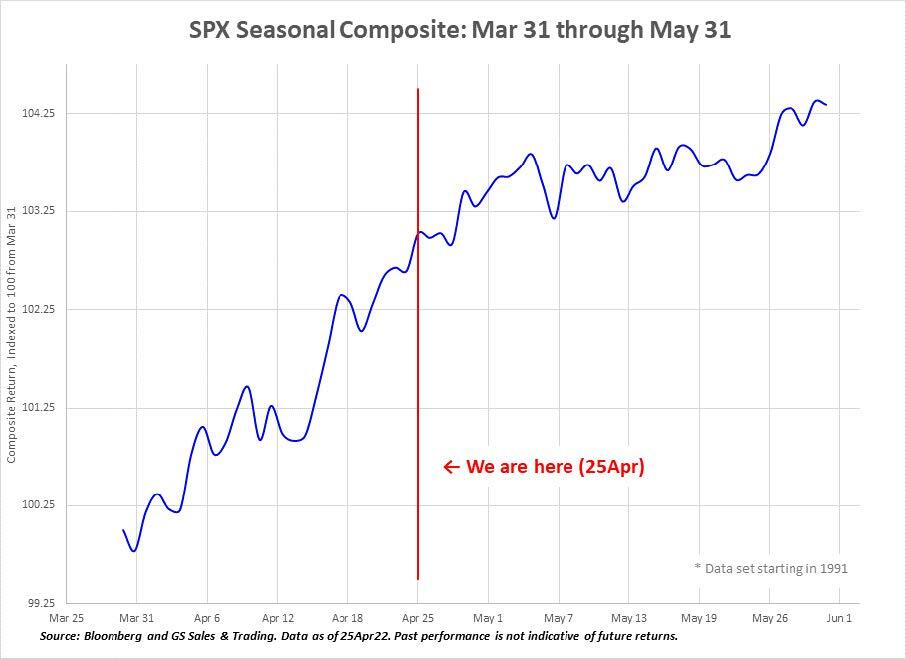
12. Seasonals – “Sell in May and Go Away” this year? Positioning is already too low to sell from here. (30-yr look back)
  • This chart will matter if and when May inflows come back.
* * *
13. HF Leverage Exposure remains at cycle lows, does May the 4th become another clearing event and quick adding back of exposure?
  • Overall book Gross leverage +1.0 pts to 228.4% (5th percentile one-year) and Net leverage -0.6 pts to 72.9% (lowest since May ‘20). Overall book L/S ratio -0.9% to 1.937 (lowest since May ‘20).
  • Fundamental L/S Gross leverage +1.3 pts to 172% (6th percentile one-year) and Fundamental L/S Net leverage -1.1 pts to 49.3%, near the lowest levels since Apr ‘20.
As Rubner concludes, “choppy and wide trading range continues but market technicals flip in favor of the bulls for may.” One thing is clear: the market can’t take much more pain without the Fed having to step in – we are talking the proverbial “flush” - no matter how much Biden berates Powell into standing to the side as stocks crash if it somehow means that inflation will shrink – and boost Biden’s approval rating - just because we enter a bear market. Incidentally, we wonder if Biden’s handlers have considered what will happen to the president’s approval rating if in additional to a stagflationary recession, the president were to also add a market crash to his list of achievements.
Finally, for those curious how to best trade the world as envision by the Goldman flow trader, details can be found in the full note available to professional subscribers.

FT : Bill Gates calls for global surveillance team to spot pandemic threats

Bill Gates calls for global surveillance team to spot pandemic threats
The philanthropist urges world leaders to increase spending to improve preparedness for health threats

A team of international experts ranging from epidemiologists to computer modellers should be created to quickly identify global health threats and improve co-ordination between countries, Bill Gates has said, warning that greater investment is needed to avoid another pandemic.

The Microsoft founder and philanthropist, who in 2015 first cautioned publicly that the world was not ready for the inevitable next pandemic, said his proposed Global Epidemic Response and Mobilization initiative should be managed by the World Health Organization.

As the war in Ukraine dominates the international agenda, Gates urged global leaders not to lose sight of the health crisis. He called for greater investment to prevent future pandemics. “It seems wild to me that we could fail to look at this tragedy and not, on behalf of the citizens of the world, make these investments,” Gates told the Financial Times.

More than 6.2mn worldwide are estimated to have died from Covid-19 since late January 2020, shortly before the WHO declared the outbreak a Public Health Emergency of International Concern.

He acknowledged there were questions over whether an international consensus could be reached to increase funding for WHO, which he believed was the only body that could build and manage the “top-notch” GERM team for which the running costs, he estimated, would be around $1bn a year.

“The amount of money involved is very small compared to the benefit and it will be a test: can global institutions take on new responsibilities in an excellent way, even in a time period where US-China [relations are] tough, US-Russia is extremely tough?” said Gates


Bill Gates © POOL/AFP via Getty Images
The WHO had “less than 10 full-time people” working on outbreak preparedness, said Gates, adding that “even those people are distracted with many other activities”.

“The current WHO funding is not at all serious about pandemics,” he said.

Gates, who argued that there was an urgent need for longer-lasting vaccines that blocked infection, stressed that the current pandemic still posed a threat.

“We’re still at risk of this pandemic generating a variant that would be even more transmissive and even more fatal,” he said. “It’s not likely, I don’t want to be a voice of doom and gloom, but it’s way above a 5 per cent risk that this pandemic, we haven’t even seen the worst of it.”

Gates, whose book How to Prevent the Next Pandemic is published on Tuesday, expressed his hope that the UK would not further reduce its contribution to foreign aid funding, suggesting this could lead to other nations engaging in their own retrenchment which could jeopardise key global public health programmes.

The UK’s decision last year to reduce its annual aid budget from 0.7 per cent, to 0.5 per cent, of gross national income was “a disappointment”. It meant areas such as polio and reproductive health had been cut.

“We’re down to the bare minimum, and if the UK cuts more, then others will do as well,” said Gates. “That would be tragic because . . . all that money saves lives for less than $1,000 per life saved.”

He said the UK remained a big donor to the vaccine alliance Gavi and the Global Fund to Fight AIDS, Tuberculosis and Malaria.

FT : Trucking shortage shifts from drivers to vehicles

Trucking shortage shifts from drivers to vehicles
Workers are back on the road but the industry is suffering from a lack of trailers and trucks

Haulage companies that spent last year battling to hire drivers now have a new problem: a shortage of trucks.

On both sides of the Atlantic, rising wages have helped lure workers back on the road after a lack of drivers strained the industry to breaking point, leaving shipping containers stranded at ports on the US west coast and petrol pumps running dry on British forecourts.

But a longstanding shortfall of equipment — due originally to coronavirus restrictions and chip shortages — is becoming more severe as Russia’s invasion of Ukraine shuts down the supply of key components and Chinese lockdowns threaten further turmoil in global supply chains.

“The driver has been the biggest constraint of the last two years . . . The bigger supply constraint now is the truck, and to some extent the trailer,” said Tim Denoyer, analyst at Indiana-based ACT Research.

Rico Luman, an economist at ING, said some European truckmakers were taking no more orders because their backlogs were already long, while others could not quote a price because they were unsure of the cost of raw materials for vehicles that might be delivered “far into” next year.

“Trucks one to two-years-old are almost the same price as new ones at the moment: there is no option B to get spare capacity,” Luman said.

We are struggling to keep the UK fleet on the road,” said Kieran Smith, chief executive of the recruitment agency Driver Require, who said vehicle availability at the operators with which he works had dropped noticeably because of a lack of spare parts.

Higher pay — wages across the industry rose about 25-30 per cent over the past year, according to Denoyer — and the easing of the Omicron coronavirus wave has alleviated worker shortages in the US.

The wave of new workers, meanwhile, has helped cap costs for companies transporting their goods by truck. US dry-van spot rates, excluding fuel, fell abruptly in March and are down more than a third since the start of the year.

The picture is similar in the UK, where industry associations say driver shortages have eased as pay has improved, testing for HGV licences resumed and large-scale government-backed training schemes got under way.

“A year ago we were bleeding drivers all over as a result of Covid,” said Rod McKenzie, head of policy at the Road Haulage Association. “Now things are really easing.” McKenzie estimated a shortfall of 100,000 drivers had dropped to about 65,000.

Luis Gomez, president of XPO Logistics Europe, said vacancies in the company’s UK business had fallen and wages had stabilised across the industry, with job applicants giving priority to shift patterns that offered a better work-life balance over large pay packets.

Paul Day, chief executive of Turners Soham, a Cambridgeshire based trucking and warehousing company, said the UK market was “close to equilibrium” between the number of drivers and the amount of work, with wages in his own business up about 15-20 per cent year on year.

But he and others believe the haulage industry is able to cope chiefly because rising prices for goods, combined with bottlenecks in manufacturing, have taken the edge off demand.

“We’ve avoided the worst because ironically the economy slowed down,” said Day, who said the volume of goods moved by supermarkets had tailed off, although demand in construction was still solid.

Ken Hoexter, an analyst at Bank of America, said shippers in the US were also reporting weaker demand as fuel prices soared and manufacturers had less work to do on rebuilding their inventories, which dropped to low levels during the pandemic.

However, the industry remains fragile. Although hauliers generally pass on changes in fuel prices, they face cost pressures for other raw materials. The price of Ad Blue, an anti-pollutant used in diesel engines, has quadrupled because its key ingredient is sourced from Russia, said Day. Small operators caught in drawn-out negotiations with customers could swiftly run into cash flow difficulties.

Though the driver shortage is less acute, the industry has not solved endemic problems with recruitment and retention of an ageing workforce.

“We’re in the slower part of [the] year . . . and we’re operating close to the edge,” Smith said, adding that conditions could worsen as demand picked up during the traditionally busier summer months. “It will be really tight . . . We’re not far away from another shortage.”