Nickel Halted Limit Up Again As Chinese Tycoon Begins Covering Giant Short, Sparking Fears Of Another Mega Squeeze
For the second day in a row, Nickel traded in London surged by the 15% exchange limit on the scandal-plagued London Metals Exchange, putting the spotlight back on bearish position holders just two weeks since the market was roiled by an historic short squeeze, and sparked speculation that a second, even more vicious short squeeze may be forming.
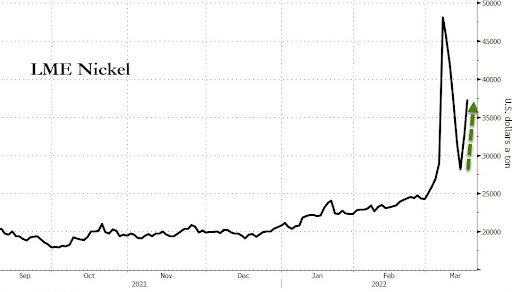
Nickel futures remained locked at the price limit by late morning on the London Metal Exchange, as the latest spike extends a period of unprecedented turmoil for the market. Prices soared over 250% over two trading sessions in early March during the short squeeze centered on China’s Tsingshan Holding Group Co., before the market was suspended to avoid bankrupting China's biggest stainless steel producer and potentially leading to billions in losses for its OTC counterparties, among which JPMorgan was the largest.
As we reported last week, Tsingshan struck a deal with its banks to avoid further margin calls, allowing the market to reopen last week, and said it would reduce its short position in the future. But the sharp two-day jump will be piling pressure on its banks and brokers who have to make margin calls of their own to cover short positions on the LME when prices rise.
Speaking to Bloomberg, Michael Widmer, head of metals research at Bank of America, said that “ultimately the short position is still out there, and they will have to close it out" adding that sharp daily price moves are likely to continue “at least until the short position is out of the market.”
And sure enough, in a separate report from Bloomberg today, we learn that Xiang "Big Shot" Guangda, the owner Tsingshan, bought some contracts on the London Metal Exchange to reduce his short bet as the nickel market briefly unfroze this week.
Tsingshan and its peers have covered tens of thousands of tons of their short positions, one of the people said. Xiang had short holdings of over 150,000 tons when the market was halted on March 8, and his business and trading partners held additional large short positions on top of that - Bloomberg
While the move modestly reduces the size of the potential pain for Xiang and his banks as nickel prices soar once again - prices on the LME are up more than 30% over the past two days - the risk is that now that markets know that the big short is covering, they may refuse to sell any metal at any price forcing yet another squeeze. Indeed, as Bloomberg first reported, the businessman and his allies have only reduced a portion of their total short position, and still hold large bets on falling prices.
On March 10, Bloomberg reported that Xiang told his banks that he didn’t want reduce his short position; that clear lie - which removed the possibility of a squeeze - helped send the nickel price sharply lower since then, falling as low as $26,675 a ton this week, compared with $48,078 a ton on March 7 -- the last price that the LME allowed to stand when it closed the market. Clearly, Xiang was lying, and has been quietly seeking to cover at least some of his short.
The LME reopened the nickel market last week after Tsingshan announced a deal with its banks to avoid further margin calls; in the meantime, and following an unprecedented trading suspension, the LME canceled billions of dollars of transactions sparking outrage among the industry and destroying overnight any positive reputation the exchange may have had.
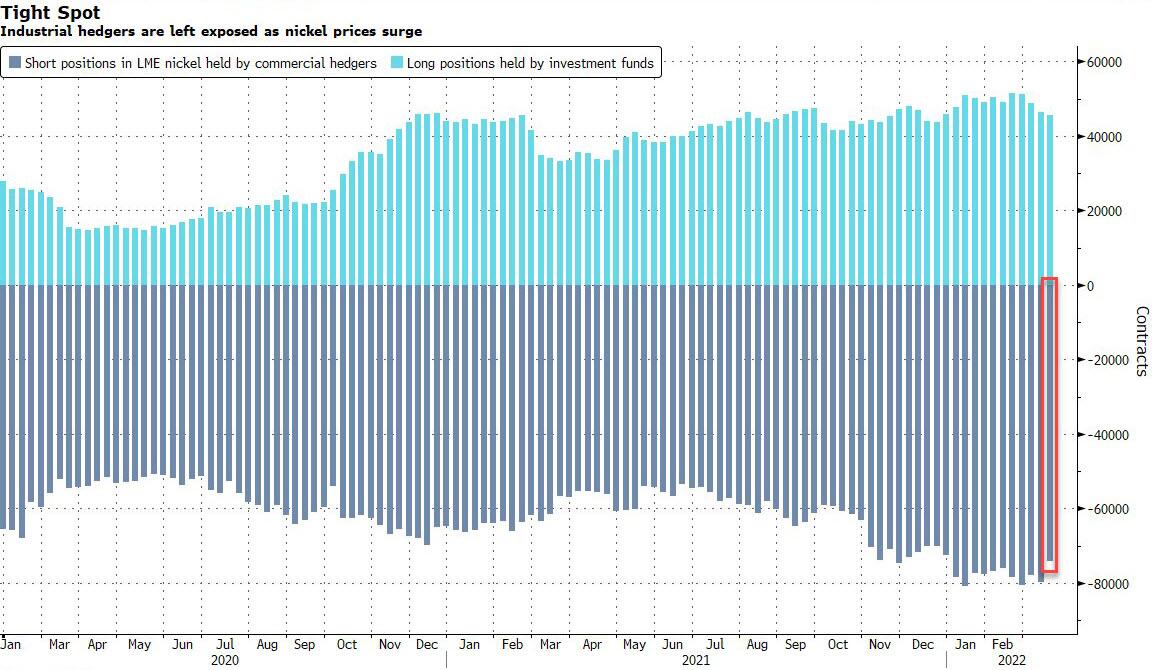
While Tsingshan holds an outsized short position on the LME, there are many other industrial users and physical traders who hold short positions to hedge their price risk, raising the threat of another squeeze if those parties need to buy their positions back, or brokers seek to close them out to avoid further margin calls.
Total short positions held by commercial parties stood at 74,166 contracts at the end of last week, according to data from the bourse. As Bloomberg correctly notes, they’ll need to turn to bullish hedge funds to liquidate their contracts: on a net basis investment funds are the largest holders of long positions in the LME nickel market.
That said, once the shorts come under renewed pressure - and now that Xiang is covering it's just a matter of time - the new daily price limits introduced by the LME should help prevent a repeat of the extreme price swings seen earlier this month. On the other hand, if the buying pressure is big enough, we may just end up with a locked market, one where every single day we see Nickel trade immediately limit up and stay there, only to repeat that again the next day.
Finally, and perhaps confirming that we are about to see another huge squeeze, overnight nickel also surged to the maximum daily limit on the Shanghai Futures Exchange earlier - tracking the overnight gain in London - despite a cloudy short-term demand outlook due to Covid-19 restrictions in China. It indicates that traders are looking for venues where to go balls to the wall long, knowing that they may not have much chance on the LME once it locks limit up for the foreseeable future.
Moscow Claims Roman Abramovich No Longer Involved In Ukraine Peace Talks
As Russian oligarch Roman Abramovich scrambles to find a buyer for Chelsea Football Club while moving two of his yachts to Turkey to avoid them being seized by European authorities, the Ukrainian government rode to the rescue yesterday by claiming that Abramovich was acting as a critical go-between during the ongoing peace talks between the Ukrainian government and Russia.

Abramovich's involvement in the talks was widely reported last month, but in spite of this, the west hasn't spared him from their sanctions against Russian oligarchs. Now, the US media is reporting that one of Abramovich's properties in Aspen, Colo. could be seized if Washington orders more sanctions against him (the US unveiled its latest round of sanctions against Russia). Fortunately for him, Abramovich wasn't included in the latest round of sanctions announced Thursday morning as President Biden met with his fellow leaders across NATO, the G-7 and EU.
But that doesn't mean he's in the clear.
Because on Thursday, the Kremlin said that while the sanctioned oligarch played an early role in peace talks between Russia and Ukraine, the process was now in the hands of the two sides' negotiating teams.
"He did take part at the initial stage," Kremlin spokesperson Dmitry Peskov told reporters. "Now the negotiations are between the two teams, the Russians and Ukrainians."
Abramovich, who is Jewish and has Israeli citizenship, was one of the most powerful businessmen who earned fabulous fortunes after the 1991 break-up of the Soviet Union. Forbes has estimated his net worth at $13.3 billion. He purportedly earned a fortune during the post-Soviet collapse during the looting and general insanity.
A commodity trader who thrived in the post-Soviet disorder of the 1990s under then-President Boris Yeltsin, Abramovich acquired stakes in the Sibneft oil company, Rusal aluminium producer and Aeroflot airline were also among the businesses he acquired.
He has repeatedly denied having ties to Putin or the Kremlin, although claims to the contrary have persisted in the Russian press.
Now that the Ukrainian government's claims that he is still essential to the peace process have been exposed as false, how much longer now until Abramovich's properties in the US are seized?
Lloyd’s of London: insurance market is well covered to deal with war risks
A state-orchestrated campaign of cyber attacks would leave insurers vulnerable to claims
The calm between the storms might be how 2021 is remembered by global insurers.
At the heart of the industry is Lloyd’s of London. The syndicated market reported its best year of the past six at annual results on Thursday. Profits of £2.3bn reflected a recovery from the pandemic and efforts to lower costs at the 300-year-old institution.
Lloyd’s also said it was expecting large losses from Russia’s continuing conflict in Ukraine. The size of those liabilities remains a big open question. Lloyd’s chief executive John Neal would only say the hit would be in the billions of dollars and that there is enough capital to cover it. More certain is that the plethora of claims from aviation, shipping, credit and trade policies will take years to resolve.
Precedent suggests that when states go toe-to-toe, the insurance industry is kept off the top of the casualty list. War coverage is usually specific and policies are subject to seven-day cancellation clauses. Insurers can implement these to mitigate large-scale losses. Reports suggest many of these had already been called by March 12. Dates will provide the subject of future legal debates as claims advance through the courts.
Even so, the inclusion of these clauses in aviation and marine policies has not prevented them from becoming a major source of angst for investors. About $10bn worth of aircraft are stranded in Russia. The country has passed laws allowing them to be seized by the state. But losses after reinsurance will be a fraction of that amount. The collapse in shipping activity at Black Sea ports is likely to reflect the risks and soaring costs of marine insurance incurred by those operating in the region.
Global insurance losses from man-made disasters have rarely exceeded $10bn annually since the September 11 attacks, according to reinsurance provider Swiss Re. Lloyd’s core capital of £6bn appears to leave it well enough protected. A bigger risk could be a state-orchestrated campaign of cyber attacks. Such an offensive would be difficult to pin on Russia. That would change matters, leaving insurers vulnerable to claims.
The hidden risks of rising rates and high house prices
Property market trouble could exacerbate other economic headwinds
Until recently, mortgage holders across advanced economies seemed safe in the knowledge that interest rates would stay put for some time. For the entirety of some of their lives as homeowners, there has barely been a hint of problematic inflation, let alone a suggestion that central banks would raise rates quickly to stop it. The worry was not unmanageable repayments, or falling prices, but finding enough money for a deposit to keep up with a market that showed no signs of slowing.
Many now find themselves revising these expectations. The Bank for International Settlements — the so-called central bankers’ central bank — has warned that rising interest rates could make existing debt burdens difficult to cope with and cause house prices to fall. Some have wondered whether housing debt represents the next “Minsky moment”: a term used to denote the point at which debt-fuelled asset bubbles unwind to cause economic collapse.
Much ink has been spilled in an effort to explain the long housing boom in advanced economies. The availability of cheap money with which to buy property has undoubtedly been a significant factor. Rates have been kept low in an effort to boost wages and growth. The side effect of these measures has been turbocharged demand for housing which ran head-on into supply constraints in many big cities.
If this boom is about to meet its own “Minsky moment”, an out-and-out crisis should be avoidable. While some banks could be overexposed to housing, regulators have not been ignorant to this risk. Stricter capital requirements should better insulate banks — unlike in 2008 — while some authorities have also been on the front foot, restricting the ability of households to become too highly leveraged.
Still, regulators cannot afford to be sanguine. Many mortgage borrowers who purchased over the course of the boom will be in significant debt — keeping up with house price inflation has been costly. While these high-leverage loans may not make up a large proportion of banks’ books, they are the kind that could go bad as borrowers struggle to keep up with higher rates, record increases in energy prices and other cost-of-living pressures.
Even if broader financial turbulence can be avoided, falling prices would not pass by without any impact. Economists have long speculated that households’ willingness to spend has some relationship to wealth as well as income. If house prices fall markedly, some decline in consumption is likely. Any shortfall in spending due to this so-called “wealth effect” may also be exacerbated by individuals devoting a greater proportion of their income to debt repayments as rates rise, and less to purchasing goods and services in the broader economy. Unwinding housing bubbles can also have deep ramifications in communities where defaults, or mortgage stress, may be more concentrated.
There are more benign possibilities. If inflation is brought under control, increases to long-term rates — which tend to inform mortgage rates — may be tempered. Many households could cope in this situation by using the buffer of savings they accrued during the pandemic. House prices may not fall as far as feared, or even at all.
That does not mean the risks are not real. Supporting growth and staving off economic crisis through years of “cheap money” was an understandable choice. As a new age of monetary tightening dawns, central banks and governments alike must hope that the housing debt built up in the previous era does not weigh too heavily on the prospects of the next.
Omega and Swatch’s surprise £207 MoonSwatch
Is it a cheap Speedmaster? A fancy Swatch? Or a brilliant mix of the two?
It takes quite a lot to pique the jaded appetites of the modern, hype-savvy, drop-sensitive consumer, but Swatch has pulled it off with a new range of candy-coloured Omega Speedmaster-inspired chronographs. The two brands, both part of Swatch Group, have come together to make MoonSwatch, a name which, like the watch itself, is a play on the famous Moonwatch.
Made from a topically tech/eco-sounding material named Bioceramic, apparently a mixture of ceramic and castor oil, it shows how far once “exotic” materials have improved in quality and come down in price. The colours – particularly the daffodil yellow of the Mission to the Sun version, the carmine of the Mission to Mars, and the (now inevitable) “Tiffany” blue of the Mission to Uranus – are fresh and bright.
But the greatest achievement of this range of 11 watches, one for each planet in our solar system, is that no one saw it coming. Even internally it was kept from all but a very few. Nobody really knows whether it is a cheap Speedmaster or a fancy Swatch. And that confusion is a good thing as it gets people talking. Some will see an icon traduced (one social media comment described it as the horological equivalent of Rolls-Royce partnering with Toyota). But I reckon that more people will see a bit of fun.
What is indisputable is that it (a) gets the collector community to focus on the Swatch brand and (b) massively extends the accessibility to the fabled Speedmaster. A Canopus white-gold Omega Speedmaster (with the new calibre 321) is currently £69,500 and before this announcement the entry price into the Moonwatch world was £5,420 (on strap). The Omega MoonSwatch is £207.
Under the leadership of the energetic Raynald Aeschlimann, Omega (and in particular its celebrated chronograph) has surfed the social-media-era watch boom with flair, exploiting minor cosmetic details once known only to hardcore collectors to create a broad range of collectibles for a generation of internet-educated instant experts.
The MoonSwatch rehearses the familiar tropes in a way that speaks to the philatelically minded collector: viz the “dot over 90” tachymeter bezel, the 42mm case diameter, and the recessed subdials. Moreover, every watch in the collection is different: for instance, the idiosyncratic “Alaska Project” subdial hands on the Mission to Mars. But it is preserved from pastiche by the fact that it is, of course, a quartz chronograph using a movement that dictates a specific 2-6-10 subdial configuration, the typical Swatch dial layout.
Importantly, it brings the Speedmaster into the market for design-led, entry-level quartz timepieces that have been issued by boutique (Furlan Marri) and big (Cartier) brands alike, but in a way that only Swatch Group could do. It is indisputably original. Omega is sometimes criticised for following what Rolex does, but whatever else you may think about it, this is not an accusation that can be levelled at the MoonSwatch.
This is not the first time that Swatch has riffed off Omega. In the past Swatch has taken advantage of Omega’s position as the official timepiece of 007 to release a boxed set of Bond-villain-inspired watches. But this unambiguous “tribute” to a specific and much-loved model raises the question of what further opportunities Swatch will espy in Omega and, for that matter, other brands in the group: maybe the time has come for a Blancpain x Swatch Fifty Fathoms, or even a Breguet x Swatch tourbillon?
MoonSwatch goes on sale this Saturday in 110 Swatch boutiques around the world. But even before the official release the watch has achieved its purpose of getting people talking about Swatch: sales, which will surely be significant, are a bonus.