After Hours Summary: Pretty quiet after hours; HNST -18.9%, SMRT -16.4% fall on earnings; RKLB -2.9% lowers Q1 rev guidance due to weather-related launch delayAfter Hours Gainers:
Companies trading higher in after hours in reaction to earnings/guidance: SGHT +3.9% (also announces treatment of first patient in TRIDENT trial), JOBY +1.9%, MCW +1.3%
Companies trading higher in after hours in reaction to news: TWI +2.5% (TWI and CNHI enter into long-term supply agreement), NVCR +0.9% (presents updated results from Phase 2 2-THE-TOP trial), KBR +0.2% (to collaborate with ExxonMobil on propane dehydrogenation technology), NFLX +0.2% (adds game development studio Boss Fight Entertainment to co)
After Hours Losers:
Companies trading lower in after hours in reaction to earnings/guidance: HNST -18.9%, SMRT -16.4% (also acquires SightPlan for $135 mln), ONL -8.8%, RKLB -2.9% (lowers Q1 rev guidance due to weather-related launch delay), MAXN -2.3%, AMPS -1.3%
Companies trading lower in after hours in reaction to news: MEIP -45.2% (MEIP and Kyowa Kirin provide regulatory update on zandelisib; FDA discourages filing based on Phase 2 TIDAL study data), PRPL -7.7% (announces $65 mln stock offering), GTES -4.5% (stock offering), SEIC -2.1% (HSBC Private Bank terminates one of its agreements), CHK -1.7% (stock offering), ASAN -1.2% (files mixed securities shelf offering), ABT -0.4% (awarded $1.02 bln Army contract)
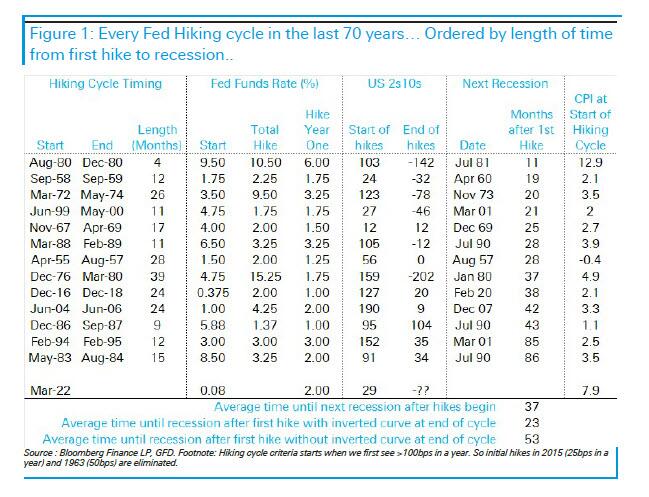
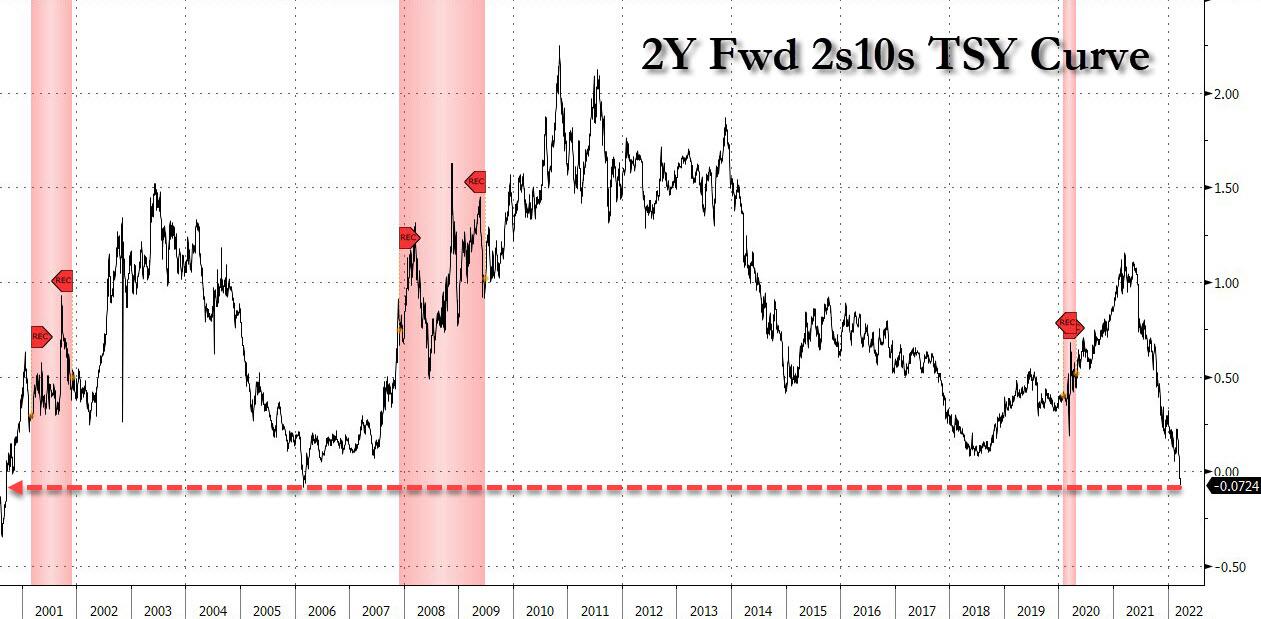
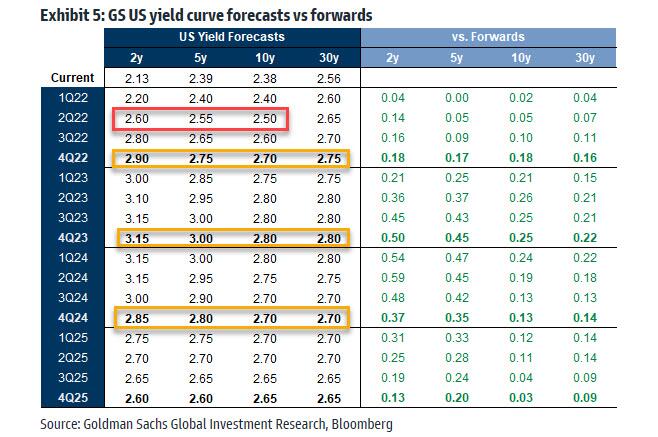
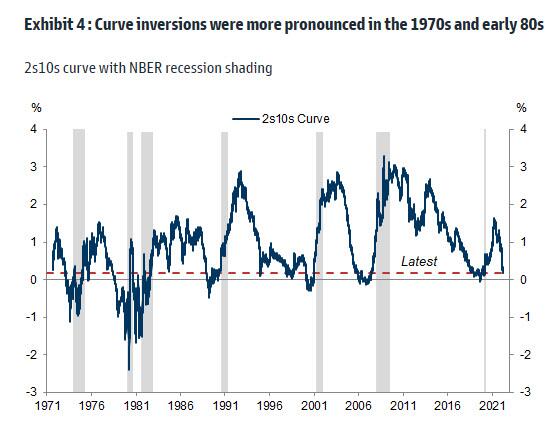
A notable aspect of our forecasts is that they feature a roughly 20bp inversion of the 2s10s UST curve as we progress through the year. Although this appears significant in the context of the business cycles since the late 1980s, where this curve has not inverted by more than 50bp ahead of a recession, inversions were significantly more pronounced in the 1970s and early 80s (Exhibit 4). We’ve argued in a previous report that earlier and/or deeper nominal curve inversions should not be that unusual in high inflation environments with significantly inverted inflation curves, requiring only modest flattening of the real yield curve flattening. As a result, in such periods we think modestly inverted nominal curves are a less definitive signal of recession probability than when using information about both the real and inflation curves.
Closing Market SummaryThe stock market ended Thursday on a firmly higher note with the Nasdaq (+1.9%) finishing ahead of the S&P 500 (+1.4%) and Dow (+1.0%).
Equities followed yesterday's weak finish with an opening advance and a daylong extension of the early gains. The S&P 500 clawed back above its 200-day moving average (4476), which has been in focus since Friday, while the Nasdaq continued this week's outperformance.
Nasdaq faced some pressure in early trade, but it took the lead in midday action with chipmakers fueling afternoon gains in the tech-heavy index. The PHLX Semiconductor Index jumped 5.1% with all but one of its component gaining at least 2.0% while NVIDIA (NVDA 281.50, +25.16, +9.8%) and Intel (INTC 51.62, +3.35, +6.9%) finished in the lead. NVIDIA rallied to its best level in ten weeks while Intel overtook its 50-day moving average (48.75), approaching its 200-day moving average (52.04).
The technology sector (+2.7%) was the only group with a gain of more than 2.0% while the materials sector (+2.0%) finished just behind after outperforming throughout the day. Steelmaker Nucor (NUE 153.52, +6.38, +4.3%) and fertilizer producers Mosaic (MOS 68.57, +0.64, +0.9%) and CF Industries (CF 106.40, +2.81, +2.7%) hit fresh 52-week highs as concerns about supply and rising prices persisted.
Crude oil, meanwhile, was a soft spot today, but not before it touched its best level in almost two weeks in overnight trade. It finished today's session with a loss of $4.02, or 3.5%, at $111.24/bbl. However, the energy sector (+0.1%) was able to eke out a slim gain, extending this week's advance to 5.0%.
The consumer discretionary sector (+0.7%) finished near the bottom of today's leaderboard as modest losses in influential components like Home Depot (HD 315.78, -1.27, -0.4%) and Lowe's (LOW 219.17, -1.75, -0.8%) overshadowed gains in most remaining components. HD and LOW retreated after KB Home (KBH 34.38, -1.65, -4.6%) missed Q1 expectations, but reaffirmed its guidance for FY22 revenue.
Elsewhere in the discretionary sector, travel names finished among the leaders with Booking.com (BKNG 2261.99, +102.24, +4.7%) ending in the top spot after Trip.com (TCOM 24.50, +0.48, +2.0%) beat Q4 expectations.
Treasuries slumped out of the gate but rebounded as the day went on. The 30-yr bond turned positive in the afternoon, sending its yield lower by a basis point to 2.51% while the 10-yr note finished with a modest loss, lifting its yield by two basis points to 2.34%.
On the international front, an Axios reporter tweeted that he has been told by the chief of staff to Ukraine's president that some progress has been made in cease-fire negotiations.
Reviewing today's economic data:
- Initial jobless claims for the week ending March 19 decreased by 28,000 to 187,000 (consensus 210,000), which is the lowest level since September 6, 1969. Continuing jobless claims for the week ending March 12 decreased by 67,000 to 1.350 million, which is the lowest level since January 3, 1970.
- The key takeaway from the report is that it is consistent with a tight labor market; however, the multi-decade low in initial and continuing claims is going to feed into concerns about a pickup in wage-based inflation pressures that might compel the Fed to take a more aggressive approach in removing its policy accommodation.
- Durable goods orders for February declined 2.2% month-over-month (consensus -0.5%) after increasing 1.6% in January. Excluding transportation, durable goods orders fell 0.6% month-over-month (consensus +0.5%) after increasing 0.8% in January.
- The key takeaway from the report is that the weakness follows on the heels of a solid January report despite the effects of the Omicron variant. The downturn likely reflects some natural slowing, meaning it is too early to tell if this is the start of a weaker trend.
- The IHS Markit Manufacturing PMI increased to 58.5 in the preliminary reading for March from February's final reading of 57.3.
- The IHS Markit Services PMI increased to 58.9 in the preliminary reading for March from February's final reading of 56.5.
- The Current Account deficit narrowed to $217.90 bln in Q4 from a revised deficit of $219.90 bln (from -$214.80 bln) in Q3.
February Pending Home Sales (consensus 1.2%; prior -5.7%) and the final reading of the Michigan Consumer Sentiment survey for March (consensus 59.7; prior 59.7) will be released tomorrow at 10:00 ET.
- Dow Jones Industrial Average -4.5% YTD
- S&P 500 -5.2% YTD
- Russell 2000 -7.6% YTD
- Nasdaq Composite -9.3% YTD


- Arizona
- Colorado
- Connecticut
- Georgia
- Hawaii
- Iowa
- Kentucky
- Maryland
- Mississippi
- Ohio
- Oklahoma
- Territory of Puerto Rico
- Utah
- iPhone 8 and later with iOS 15.4 required and Apple Watch Series 4 or later with watchOS 8.4 required
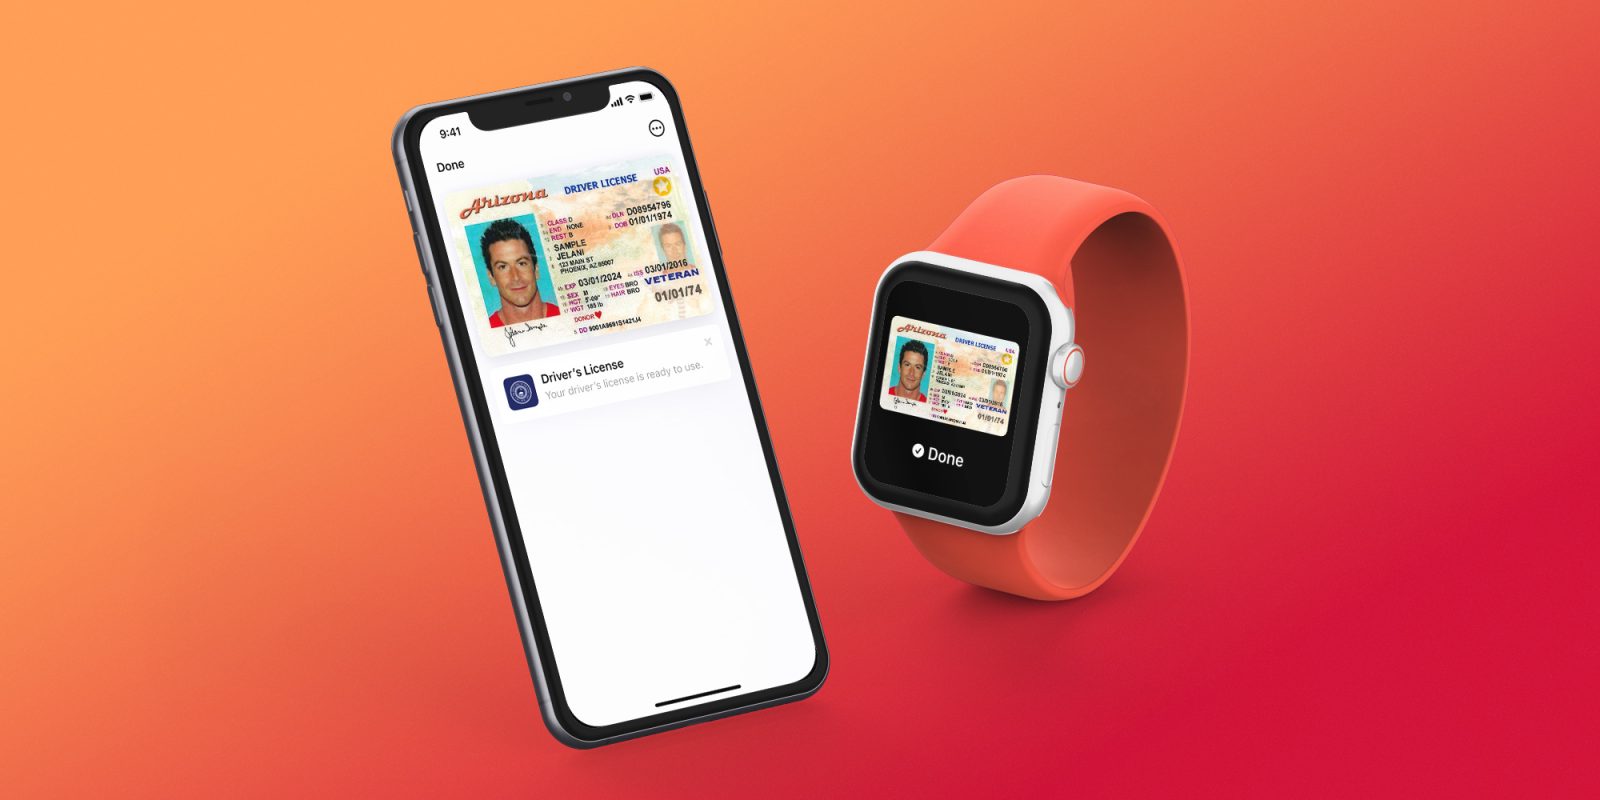
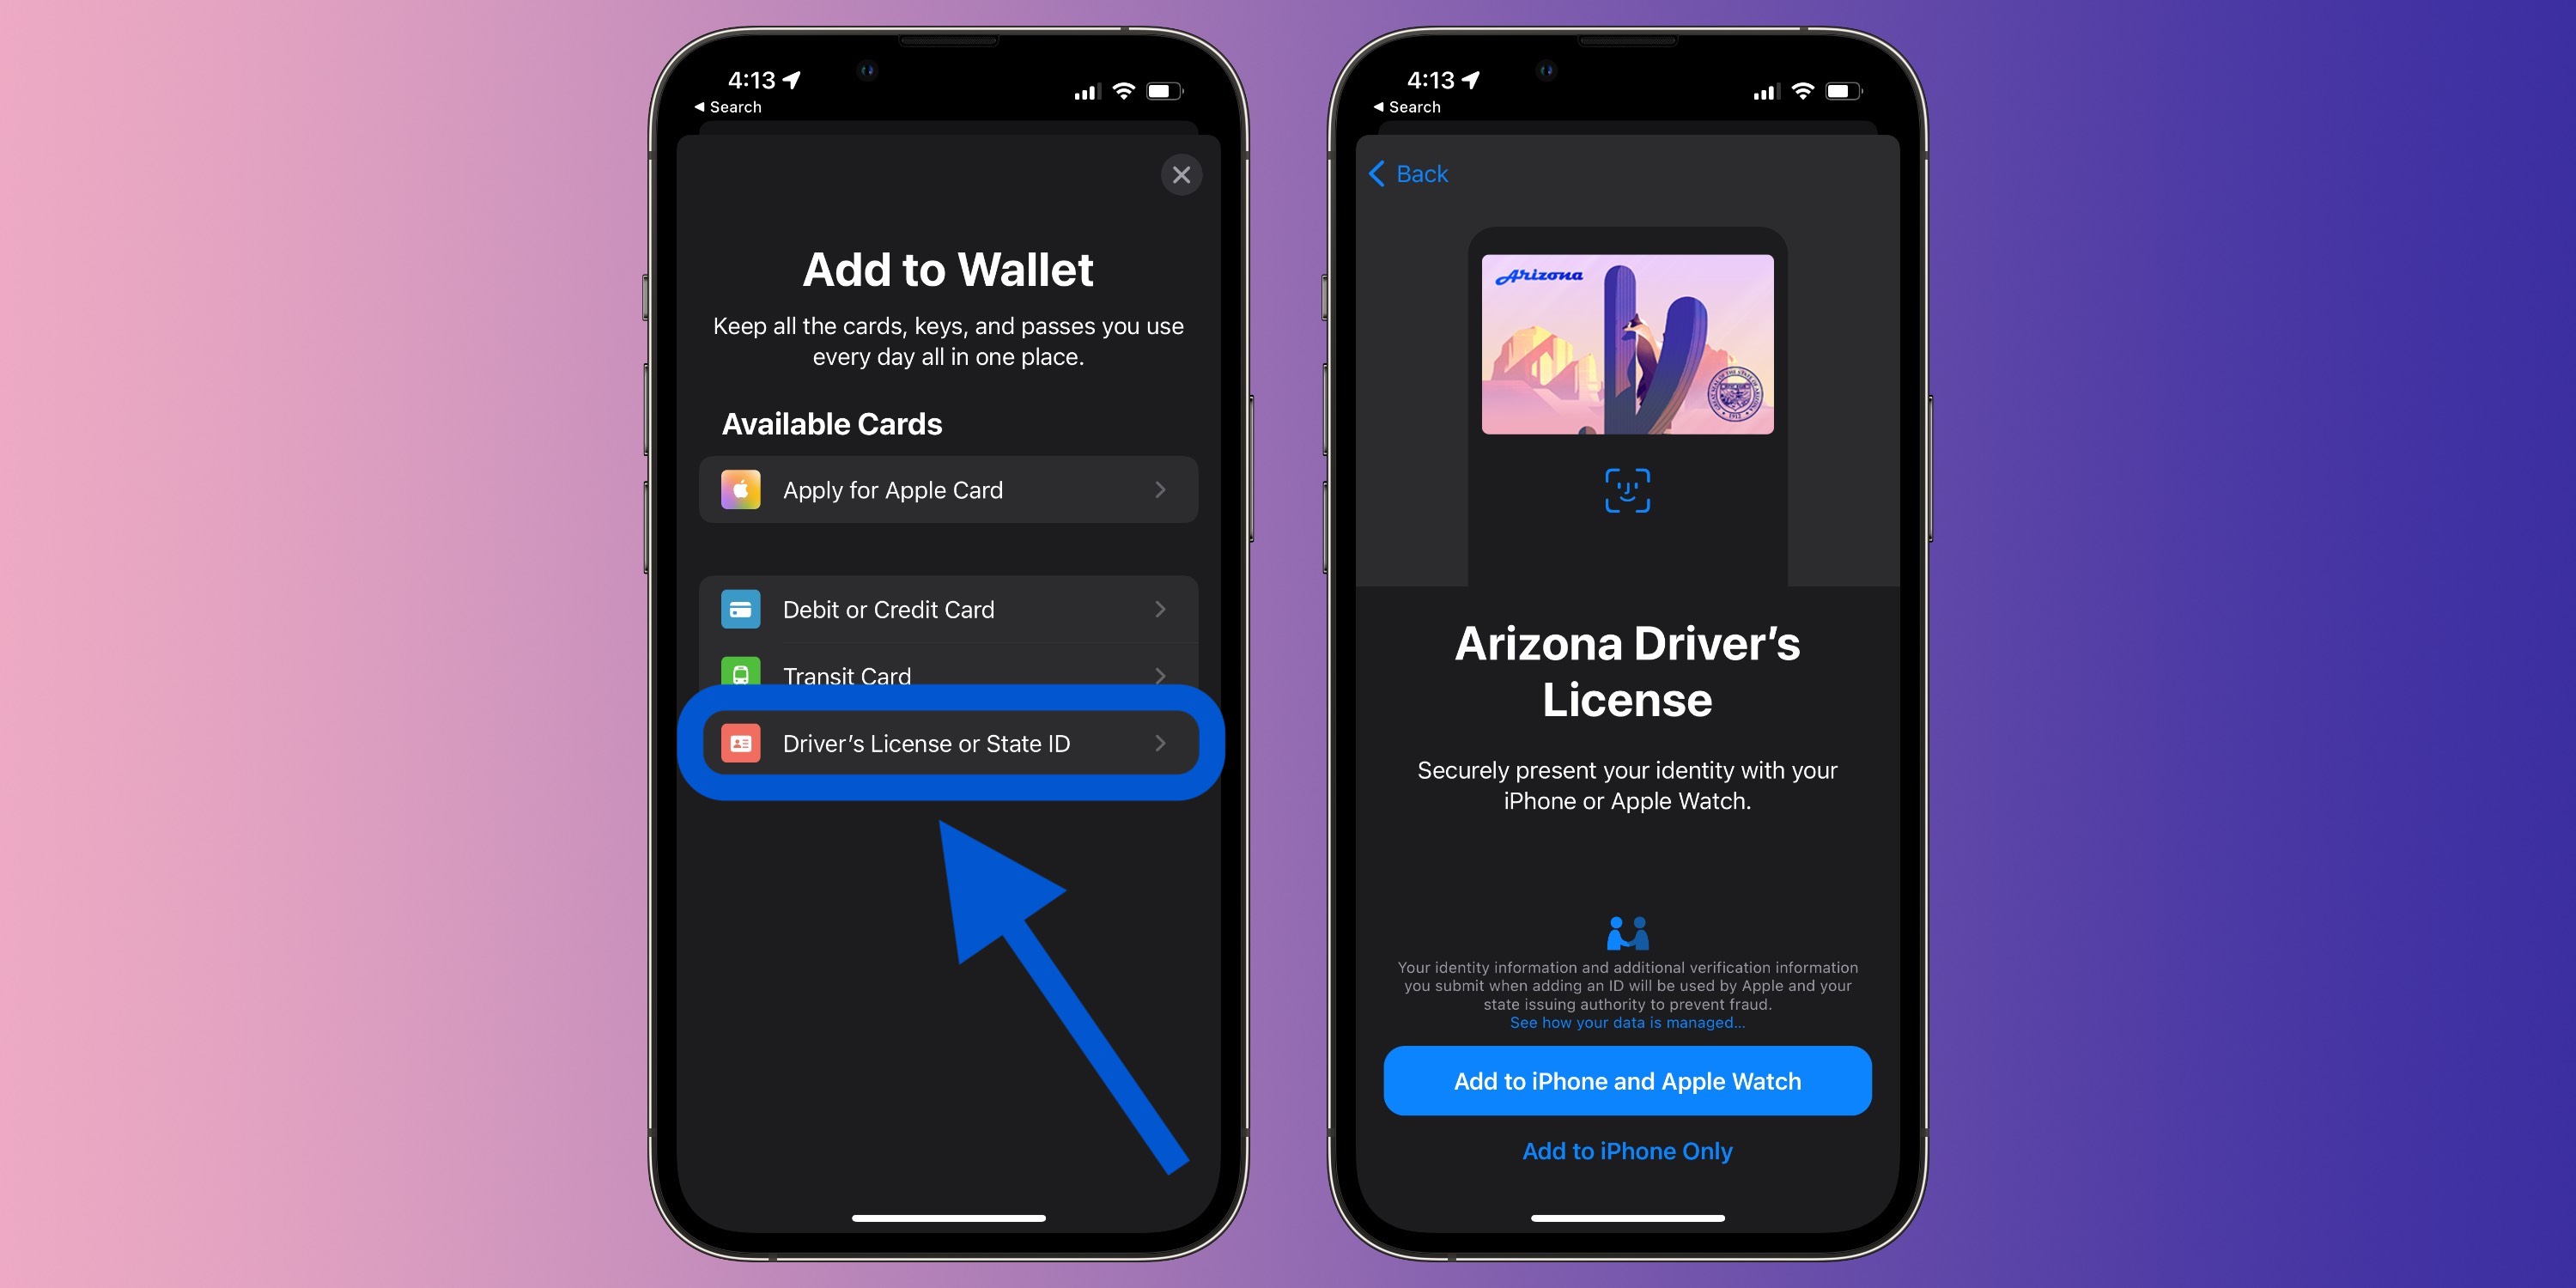
- Open the Wallet app on iPhone and tap the + icon in the top right corner
- Choose Driver’s License or State ID
- Currently only for Arizona residents – tap Add to iPhone and Apple Watch or Add to iPhone
- You may be required to log in to your state’s DMV/MVD website to authorize adding your ID to Apple Wallet

ID cards in Wallet are currently available for use in select states at select TSA checkpoints within Phoenix Sky Harbor International Airport (PHX). Travelers should refer to checkpoint signage to confirm availability.
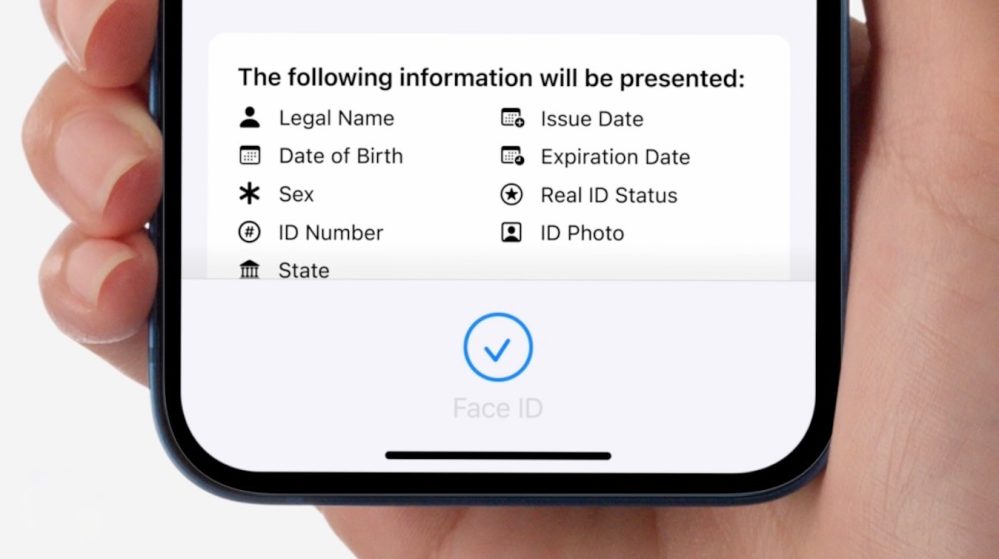
- Driver’s license and state ID in Wallet presents only the information needed for the interaction
- Users have the opportunity to review and authorize information being requested before it is shared
- Digital IDs are shared through encrypted communication directly between iPhone/Apple Watch and the identity reader (similar to Apple Pay)
- If a device is lost, Find My allows you to remotely lock or erase it
-
For supported TSA locations, users do not need to show or hand over their device, just scan it
- TSA will also capture a picture for verification purposes