FT : Omega and Swatch’s surprise £207 MoonSwatch

Omega and Swatch’s surprise £207 MoonSwatch
Is it a cheap Speedmaster? A fancy Swatch? Or a brilliant mix of the two?


It takes quite a lot to pique the jaded appetites of the modern, hype-savvy, drop-sensitive consumer, but Swatch has pulled it off with a new range of candy-coloured Omega Speedmaster-inspired chronographs. The two brands, both part of Swatch Group, have come together to make MoonSwatch, a name which, like the watch itself, is a play on the famous Moonwatch.

Made from a topically tech/eco-sounding material named Bioceramic, apparently a mixture of ceramic and castor oil, it shows how far once “exotic” materials have improved in quality and come down in price. The colours – particularly the daffodil yellow of the Mission to the Sun version, the carmine of the Mission to Mars, and the (now inevitable) “Tiffany” blue of the Mission to Uranus – are fresh and bright. 

But the greatest achievement of this range of 11 watches, one for each planet in our solar system, is that no one saw it coming. Even internally it was kept from all but a very few. Nobody really knows whether it is a cheap Speedmaster or a fancy Swatch. And that confusion is a good thing as it gets people talking. Some will see an icon traduced (one social media comment described it as the horological equivalent of Rolls-Royce partnering with Toyota). But I reckon that more people will see a bit of fun. 

What is indisputable is that it (a) gets the collector community to focus on the Swatch brand and (b) massively extends the accessibility to the fabled Speedmaster. A Canopus white-gold Omega Speedmaster (with the new calibre 321) is currently £69,500 and before this announcement the entry price into the Moonwatch world was £5,420 (on strap). The Omega MoonSwatch is £207. 


Under the leadership of the energetic Raynald Aeschlimann, Omega (and in particular its celebrated chronograph) has surfed the social-media-era watch boom with flair, exploiting minor cosmetic details once known only to hardcore collectors to create a broad range of collectibles for a generation of internet-educated instant experts.

The MoonSwatch rehearses the familiar tropes in a way that speaks to the philatelically minded collector: viz the “dot over 90” tachymeter bezel, the 42mm case diameter, and the recessed subdials. Moreover, every watch in the collection is different: for instance, the idiosyncratic “Alaska Project” subdial hands on the Mission to Mars. But it is preserved from pastiche by the fact that it is, of course, a quartz chronograph using a movement that dictates a specific 2-6-10 subdial configuration, the typical Swatch dial layout.

Importantly, it brings the Speedmaster into the market for design-led, entry-level quartz timepieces that have been issued by boutique (Furlan Marri) and big (Cartier) brands alike, but in a way that only Swatch Group could do. It is indisputably original. Omega is sometimes criticised for following what Rolex does, but whatever else you may think about it, this is not an accusation that can be levelled at the MoonSwatch.

This is not the first time that Swatch has riffed off Omega. In the past Swatch has taken advantage of Omega’s position as the official timepiece of 007 to release a boxed set of Bond-villain-inspired watches. But this unambiguous “tribute” to a specific and much-loved model raises the question of what further opportunities Swatch will espy in Omega and, for that matter, other brands in the group: maybe the time has come for a Blancpain x Swatch Fifty Fathoms, or even a Breguet x Swatch tourbillon?

MoonSwatch goes on sale this Saturday in 110 Swatch boutiques around the world. But even before the official release the watch has achieved its purpose of getting people talking about Swatch: sales, which will surely be significant, are a bonus.

(ZH) Forget "Retro-Fitted Narratives", Nomura Warns Equities Are Still A "Flows

Forget "Retro-Fitted Narratives", Nomura Warns Equities Are Still A "Flows & Positioning Story"

Equities are still a “flows and positioning” story, as opposed to what Nomura's Charlie McElligott says are a few silly macro narratives just being “retro-fitted” at this point.
Case in point, and an observation made by many in recent days:
...how did we go from the “inflation hawk” Fed pivot that created the past five month Equities zeitgeist of “higher interest rates / FCI tightening = destruction of high-multiple Stocks that are really just “long Duration” assets...
...to suddenly now over the past 2 weeks to the TINA argument of “higher interest rates benefit Stocks, because they act like TIPS but with pricing-power”
LOLOLOL
McElligott's “Pin your tail on the narrative”-rant aside, key flow themes in recent days include:
  • Systematic Strategy re-leveraging and again buying Stocks, after having slashed Equities exposure (Vol Control, Risk Parity) or gone outright “short” (CTA Trend) since 4Q21
  • Notable resumption of “peak Retail” lookalike behaviors in fits of “speculative frenzy” harkening back to periods of 2020 / 21: “meme stock” leadership on the rally, massive Call buying volume via YOLOing of short-dated, deep OTM upside options in Retail favorites
  • As opposed to these pockets of single-name upside grabbing noted above, Equities Index / ETF options greeks had been largely “flattish Delta” in recent days, where flows have been very mixed; however, yesterday was the first time that we saw SPX / SPY options with a clear “Positive Delta” bias all day via Call buying
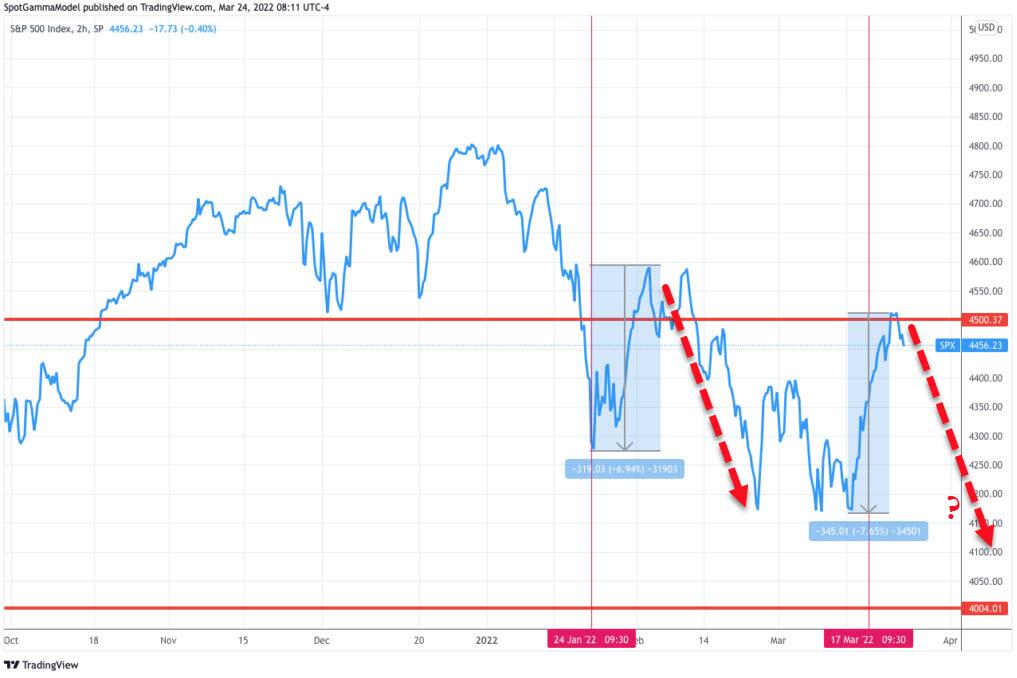
Notably, SpotGamma's January op-ex-linked analog continues to work...
And specifically looking at yesterday, McElligott notes that price-action certainly possessed characteristics of the “new” qtr / month end Pension Rebalancing flows.
I say “new,” bc estimates into the start of last week were for a “buy” of Equities, but that was before a 9% rally in S&P thereafter!—so instead, the flows have reversed, turning “buy Bonds, sell Equities” on the pension rebalancing.
Color from the UST desk: “We saw a pretty good amount of buying in the long end of the curve into the equity close for the second day in a row - this in addition to some pretty solid buying into and out of the 20yr auction. Flows were pretty supportive today"
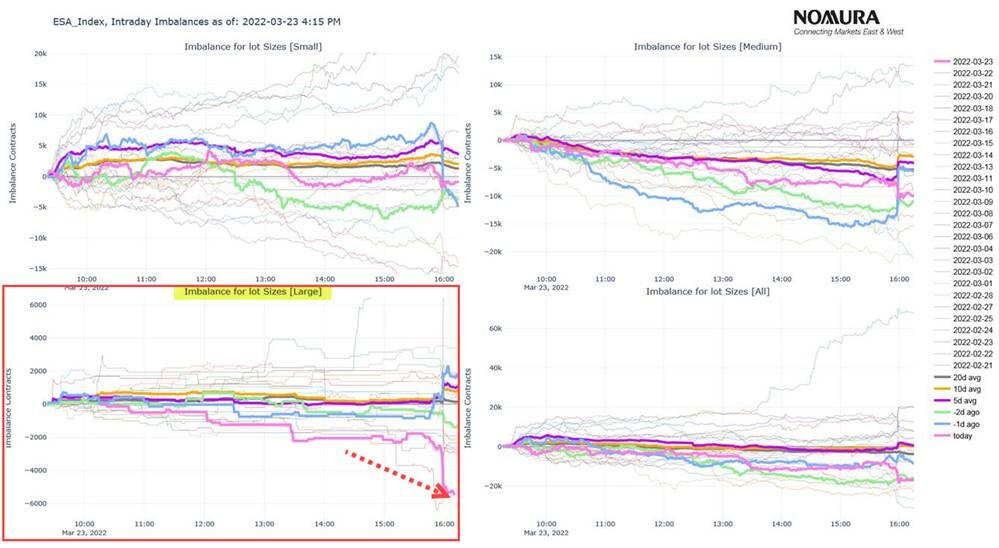
While we all saw the late-day Equities weakness, likely programmatic selling, as our S&P 500 future “imbalance” monitor showed the largest net “sell pressure” day in institutionally sized contract “large lots” experienced over the past 1m period (and that covers a LOT of “big down” days!)
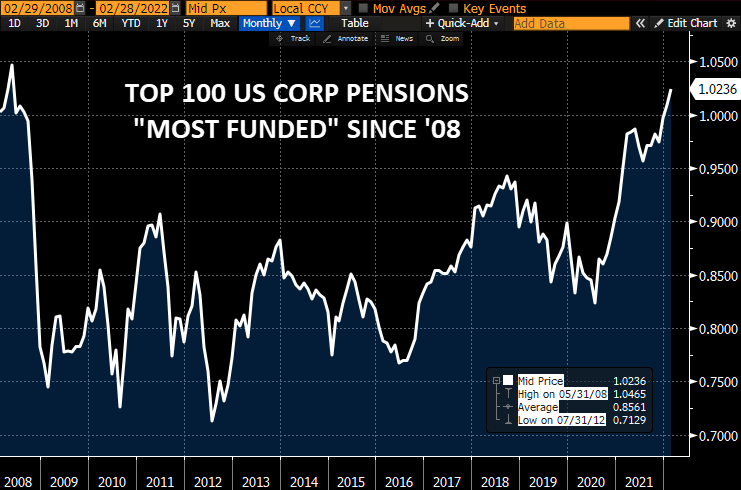
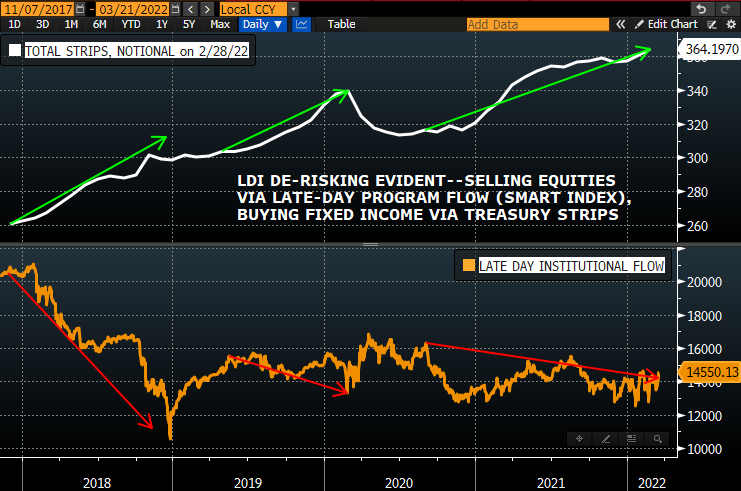
McElligott concludes by noting that this rebalancing is already coming off the back of a multi-year / long-term LDI “de-risking” trend, with the Milliman Pension Funding Ratio at 1.0236, the “most funded” that the top 100 US Corporate Pensions have been since 2008...
...hence, we have seen persistent “buy Duration, sell Stocks” flows as they gradually rebalance to match liabilities (note: let’s hope somebody is telling them about an “inflationary” regime and the impact it has )
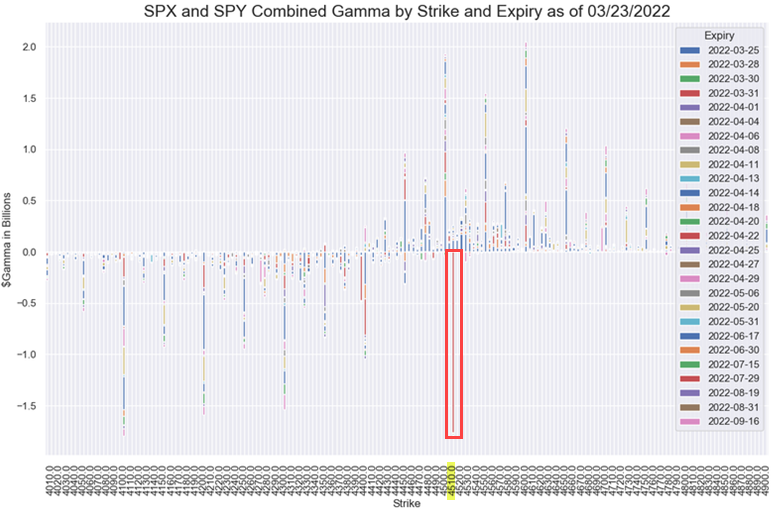
Finally, as SpotGamma details, there is lots of talk around the 4510 JPM put-strike, and its implications for current prices.
Our view on this is quite simple: by default the ~45k put contracts at 4510 here are decaying, and that will buoy/pin markets into 3/31. That, along with the other 450SPY/4500 area contracts supports the idea of looking for mean reversion back into 4500.
However if sellers emerge, possibly though some exogenous geopolitical catalyst, then those high gamma puts will add a lot of firepower to a move lower.
This is jump risk, and its material.

FT : Hedge funds search for bargains in Russian and Ukrainian bonds

Hedge funds search for bargains in Russian and Ukrainian bonds
Countries’ sovereign and corporate debt have dropped sharply since invasion last month

Hedge funds have been scooping up beaten-down Russian and Ukrainian bonds after the conflict between the two countries sent many traditional investors racing out of the markets.

Distressed debt specialists Aurelius, GoldenTree and Silver Point are among those that have been buying Russian corporate bonds, according to several people familiar with the matter.

The investments follow a rout in Russian assets that was sparked by President Vladimir Putin’s invasion of Ukraine and powerful sanctions that were put in place by western allies in response to the incursion.

Bonds issued by major companies such as Russian Railways are trading at prices that suggest many investors are not expecting to receive interest payments or even their initial investment back as groups are either unwilling or unable to service their debt.

One hedge fund manager said long-only investors — which hold assets with a view to their prices rising — had decided to “sell [Russian assets] at any price”, on concerns that capital controls implemented by Moscow would make it difficult for companies to service their dollar debt.

Many traditional asset managers have said they plan to divest their Russian assets, while others have sharply written down the value of their holdings. The country will also be removed next week from the JPMorgan emerging market bond indices that foreign investors use as a benchmark for their portfolios.

It was not immediately clear which corporate bonds Aurelius, GoldenTree and Silver Point had bought. All three declined to comment.


Analysts said it was likely other investors were also making bets that there is some value in Russian corporate debt, as well as bonds issued by Ukrainian companies, which has also been beaten down in recent weeks.

Bond trading data reported to industry watchdog Finra showed roughly $4.5bn of Russian and Ukrainian bonds changing hands since February 21, up substantially from $1.7bn in the earlier weeks of 2022, according to data compiled by MarketAxess.

Meanwhile, funds including Broad Reach and Gramercy have been buying Ukraine’s sovereign dollar-denominated debt. Prices of 10-year bonds issued by the country fell as low as 18 cents on the dollar in early March and have been trading between 20 and 40 cents in recent weeks, down from more than 80 cents before Moscow’s invasion on February 24.

“All but the unthinkable is in the price” of Ukraine’s dollar bonds, said Bradley Wickens, founder of London-based Broad Reach and former founding principal of Spinnaker Capital.

Wickens, whose main fund was up 15.5 per cent in 2021 and is up a further 1.5 per cent this year, bought a small “place holder” position in Ukraine’s bonds at about 19 cents recently and is considering buying more. He said he expected “some form of sovereign state of Ukraine” to exist in future, adding that it would take Russia permanently occupying the country and repudiating its debt for Ukraine’s bonds to lose all of their value.


Gramercy’s chief investment officer Robert Koenigsberger said: “We don’t know what’s going to happen with Ukraine — but I would expect it to be a massively western-supported entity.”

Gramercy has built a position in Ukraine’s sovereign debt at prices of about 20 to 30 cents on the dollar.

At the end of last month, Ukraine’s government commissioner for public debt management told investors that Ukraine’s treasury operations were “fully functioning” and it was not planning a debt restructuring.

One hedge fund manager, who did not want to be named, said they believed Russian president Vladimir Putin had made a “massive miscalculation” in underestimating Ukraine’s military. They also pointed to the Ukrainian debt management office’s determination to honour its debt.

Ukraine “survives under any scenario”, added the fund manager, who has also been picking up the country’s bonds in the weeks since the invasion.

FT : Holland & Barrett struggles to pay interest on €415mn loan

Holland & Barrett struggles to pay interest on €415mn loan
Owner LetterOne remains confident payment will be made despite difficulty processing

Holland & Barrett is struggling to make a scheduled interest payment to its lenders even though the UK healthcare retailer and its Russian oligarch-backed private equity owner are not under direct sanctions.

LetterOne, the London-based investment group that bought Holland & Barrett in 2017, has so far escaped UK and EU sanctions, even though its Russian owners such as Mikhail Fridman have been hit with asset freezes and travel bans.

But an interest payment the British retailer made on a €415mn loan on Wednesday has not yet reached lenders, according to three people familiar with the matter, because a bank is having issues processing the payment. In contrast, an interest payment on another £450mn loan at Holland & Barrett has flowed through to lenders without issue.

LetterOne confirmed to the Financial Times that “one of the paying agents is having difficulties processing euro payments”.

“We are working with them to rectify this,” the investment group added. “LetterOne is not sanctioned and has had confirmation of this from authorities in the UK and Luxembourg. We are confident the paying agent will make this payment swiftly.”

The delay in the interest payment is the latest example of the obstacles sanctions are creating for companies that have links to Russian oligarchs, even if they have not been directly targeted themselves.

Evraz, the London-listed steelmaker part-owned by sanctioned oligarch Roman Abramovich, said this week that it had been blocked from making an interest payment on one of its bonds, before announcing the following day that the situation appeared to have been resolved.

The FT reported earlier this month that banks had started to review their credit lines with LetterOne, in light of the escalating measures taken against the Russian billionaires that founded the private equity firm.

A group of Russian oligarchs led by Fridman and his business partner Petr Aven set up LetterOne almost a decade ago, to reinvest the $14bn windfall from the sale of their stake in oil group TNK-BP to Rosneft. As well as Fridman and Aven, other LetterOne backers such as German Khan have also been hit with sanctions this month.

In response to the measures taken against its owners, LetterOne has removed all of its Russian shareholders from the board and operations, with no ability to influence or benefit from its activities. All dividends will be used to support Ukrainian relief efforts.

As well as Holland & Barrett, LetterOne has funded the rollout of broadband in East Anglia, is majority owner of Spain’s Dia supermarket chain, as well as holding a stake in telecoms group Turkcell and a large minority position in German energy group Wintershall Dea.

UK retailer Holland & Barrett employs about 5,000 people across hundreds of stores in the UK.

>>> It's the beginning of the end of globalization, say BlackRock's Larry Fink a

It's the beginning of the end of globalization, say BlackRock's Larry Fink and Oaktree's Howard Marks

"The magnitude of Russia's actions will play out for decades to come and mark a turning point in the world order of geopolitics, macroeconomic trends, and capital markets."
That was Larry Fink, CEO of BlackRock (BLK), in his annual letter to shareholders that published Thursday. And in our call of the day, he closed the door on decades of global economies connecting.
"I remain a long-term believer in the benefits of globalization and the power of global capital markets," said the head of the world's biggest asset manager. "But the Russian invasion of Ukraine has put an end to the globalization we have experienced over the last three decades."
That disconnectivity between people, nations and companies got a head start from two years of the pandemic. "It has left many communities and people feeling isolated and looking inward. I believe this has exacerbated the polarization and extremist behavior we are seeing across society today," he said.
And now Russia's aggression against its neighbor and decoupling from the global economy will lead companies and governments worldwide to "re-evaluate their dependencies and reanalyze their manufacturing and assembly footprints -- something that COVID had already spurred many to start doing," he said.
While dependence on Russian energy is in the spotlight, we're also likely to see companies and governments bring operations either onshore or close to home, which could benefit Mexico, Brazil, the U.S. or Southeast Asia.
And that means higher costs and margin pressures are ahead. "While companies' and consumers' balance sheets are strong today, giving them more of a cushion to weather these difficulties, a large-scale reorientation of supply chains will inherently be inflationary," said Fink.
Also weighing in on globalization was Oaktree Capital Management founder Howard Marks, whose own letter to investors discussed the "pendulum" swinging back toward local sourcing. "Rather than the cheapest, easiest and greenest sources, there'll probably be more of a premium on the safest and surest," he said. That could impact investors as globalization has boosted worldwide GDP, but may also boost domestic manufacturing jobs.
Fink made a couple more points, such as the possibility of the war in Ukraine speeding up digital currencies as countries reconsider dependence on traditional ones. "A global digital payment system, thoughtfully designed, can enhance the settlement of international transactions while reducing the risk of money laundering and corruption," he said.
And while near-term progress toward net zero now faces a setback amid the tumult, the global shift to green energy may get a boost. "Higher energy prices will also meaningfully reduce the green premium for clean technologies and enable renewables," he said.

>>> US Research Calls

Research Calls

  • Upgrades:
    • Arcos Dorados (ARCO) upgraded to Buy from Neutral at BofA Securities; tgt raised to $10
    • British American Tobacco (BTI) upgraded to Overweight from Neutral at JP Morgan
    • Buenaventura SA (BVN) upgraded to Equal-Weight from Underweight at Morgan Stanley; tgt raised to $11.10
    • GDS Holdings (GDS) upgraded to Buy from Hold at Deutsche Bank; tgt $55
    • Johnson Controls (JCI) upgraded to Buy from Hold at Deutsche Bank; tgt lowered to $79
    • Liberty Global (LBTYA) upgraded to Outperform from Neutral at Credit Suisse
    • Ping Identity (PING) upgraded to Buy from Hold at Stifel; tgt raised to $30
    • Schnitzer Steel (SCHN) upgraded to Overweight from Sector Weight at KeyBanc Capital Markets; tgt $58
    • Transocean (RIG) upgraded to Hold from Sell at Pareto; tgt $5
    • Werner Enterprises (WERN) upgraded to Equal Weight from Underweight at Wells Fargo; tgt raised to $46
  • Downgrades:
    • Alcoa (AA) downgraded to Equal-Weight from Overweight at Morgan Stanley; tgt raised to $100
    • Atlantia SpA (ATASY) downgraded to Neutral from Buy at UBS
    • Bilibili (BILI) downgraded to Neutral from Outperform at KGI Securities; tgt $43
    • EOG Resources (EOG) downgraded to Hold from Buy at TD Securities; tgt $140
    • Intl Flavors (IFF) downgraded to Hold from Buy at Berenberg; tgt lowered to $144
    • Leidos (LDOS) downgraded to Equal Weight from Overweight at Wells Fargo; tgt raised to $113v
    • NetApp (NTAP) downgraded to Neutral from Buy at BofA Securities; tgt lowered to $96
    • PaySign (PAYS) downgraded to Neutral from Buy at Ladenburg Thalmann
    • Post (POST) downgraded to Hold from Buy at Truist; tgt lowered to $70
    • Southern Copper (SCCO) downgraded to Underweight from Equal-Weight at Morgan Stanley; tgt raised to $63
    • Traeger (COOK) downgraded to Hold from Buy at Jefferies; tgt lowered to $7
    • Traeger (COOK) downgraded to Hold from Buy at Stifel; tgt $7.50
    • Vale S.A. (VALE) downgraded to Equal-Weight from Overweight at Morgan Stanley; tgt raised to $22
  • Others:
    • Atlantica Yield (AY) initiated with a Neutral at JP Morgan; tgt $40
    • Capital One (COF) assumed with a Buy at Citigroup; tgt raised to $189
    • Ciena (CIEN) initiated with a Buy at Rosenblatt; tgt $80
    • Citizens Financial Group (CFG) assumed with a Buy at Citigroup
    • Comerica (CMA) assumed with a Buy at Citigroup
    • Fifth Third (FITB) assumed with a Neutral at Citigroup
    • Infinera (INFN) initiated with a Buy at Rosenblatt; tgt $12
    • KeyCorp (KEY) assumed with a Neutral at Citigroup
    • Li Auto (LI) initiated with a Buy at China Renaissance; tgt $37.20
    • M&T Bank (MTB) assumed with a Buy at Citigroup
    • NanoString Technologies (NSTG) initiated with a Buy at Canaccord Genuity; tgt $50
    • NeoPhotonics (NPTN) initiated with a Neutral at Rosenblatt; tgt $16
    • NIO (NIO) initiated with a Buy at China Renaissance; tgt $32.40
    • Regions Fincl (RF) assumed with a Buy at Citigroup
    • Reata Pharmaceuticals (RETA) assumed with a Buy at Goldman; tgt $91
    • S&P Global (SPGI) resumed with an Outperform at Credit Suisse; tgt $495
    • XPeng (XPEV) initiated with a Buy at China Renaissance; tgt $55.60

>>> US Gapping down

Gapping down
In reaction to earnings/guidance
:

  • COOK -19.1%, ENJY -10.7%, MOMO -8.7%, SCS -5.8%, KBH -3.8%, ASTL -1.9%, FSM -1.7%, EXAI -1.6%, DRI -1.5%, OLLI -1.2% (also launches a store remodel program)

Other news:

  • APLS -5.6% (announces pricing of public offering of common stock)
  • JD -4.1% (announces JD Logistics' proposed financing)
  • BXMT -2.4% (commenced offering of $300 million aggregate principal amount of convertible senior notes due 2027)
  • ASND -1.8% (announces $500 mln convertible notes offering)

Analyst comments:

  • AA -2.3% (downgraded to Equal-Weight from Overweight at Morgan Stanley)
  • LDOS -0.8% (downgraded to Equal Weight from Overweight at Wells Fargo)

>>> US Gapping up

Gapping up
In reaction to earnings/guidance
:

  • TCOM +7%, OXM +6.5% (also increases dividend), FUL +5.1%, TITN +4.8%, SOL +3.5%, AMRC +2.5%

Other news:

  • NKLA +18.2% (expects to deliver 300-500 BEV trucks largely in H2 of 2022; commercial truck production begun this week)
  • PLTK +5.1% (acquires JustPlay.LOL)
  • SPIR +3.9% (announced the expansion of their existing partnership with Slingshot Aerospace)
  • JBT +3.2% (provides financial targets at Investor Day)
  • STGW +3.1% (authorizes new $125 mln share repurchase program)
  • EGY +2.9% (signs contract to support subsea reconfiguration and FSO deployment at Etame Field)
  • MOLN +2.7% (Publication of Preclinical Data from CD40 Therapeutic Candidate MP0317 in Cancer Immunology Research)
  • WIX +2.6% (authorizes $500 mln securities repurchase program)
  • RIOT +2.5% (enters into a separation agreement with COO)
  • VNE +2% (reports planned date for closing of merger and future CEO)
  • MITK +1.9% (acquires HooYu for £98 mln in cash)
  • ALK +1.6% (to update long-term growth strategy at today's Investor Day; company also extends credit card agreement with Bank of America through 2030)
  • KBR +1.3% (secured a contract from a leading midstream company for a world-scale olefins production facility to be built on the U.S. Gulf Coast)
  • DDD +1.2% (enters partnership with Enhatch for personalized medical devices)

Analyst comments:

  • BTI +2.9% (upgraded to Overweight from Neutral at JP Morgan)
  • ARCO +2% (upgraded to Buy from Neutral at BofA Securities)
  • JCI +1.8% (upgraded to Buy from Hold at Deutsche Bank)
  • BVN +0.9% (upgraded to Equal-Weight from Underweight at Morgan Stanley)