Bye, Buybacks? No, but Signs Show Some Companies Shifting Focus Away From Them.
There are some signs that stock buybacks, which have been a popular capital-allocation strategy for many U.S. companies, are losing some steam after starting off the year strongly.
Jill Carey Hall, equity and quantitative strategist at BofA Securities, observed in an April 5 research note that the dollar amount of first-quarter S&P 500 company buyback announcements as a percentage of market capitalization were 50% below their five-year pre-Covid average—0.4% versus 0.8%.
“We see a greater case for dividends over buybacks in 2022, so we’re expecting a pretty negligible impact to S&P 500 [earnings per share] from net buybacks,” Hall tells Barron’s.
Hall’s note adds that “while buybacks typically slow at the end of each quarter ahead of earnings season, buybacks by corporate clients slowed to their lowest weekly level in 12 months.”
At the same time, there have been a few recent examples of companies de-emphasizing or suspending share repurchases, most notably Starbucks (ticker: SBUX). Howard Schultz, the company’s founder who returned as CEO on April 4, said as one of his first orders of business that Starbucks was suspending stock buybacks effective immediately to “allow us to invest more into our people and our stores.”
In its earnings release summarizing the 2021 fiscal year, which ended last October, Starbucks said it was committing $20 billion for share repurchases and dividends over the next three years. The company spent about $2.1 billion on dividends last year but didn’t repurchase any of its common stock—though on a net basis, including share issuance, it bought back about $1.4 billion of stock in fiscal 2020 and about $10 billion in fiscal 2019.
Elsewhere, the CEO of chip maker Qualcomm (QCOM), Cristiano Amon, told CNBC recently that the company is targeting dividend increases in the high single digits or low double digits. “We are going to continue to look at an opportunistic buyback, but we want to maintain strategic flexibility also for M&A,” he said, referring to mergers and acquisitions.
If a buyback slowdown does occur this year, backward-looking data doesn’t necessarily tell the story.
First-quarter S&P 500 dividends set a record, according Howard Silverblatt, senior index analyst at S&P Dow Jones Indices, adding that buybacks “still appear to be favored over dividends.”
BofA’s Hall, however, points to recent signs that share repurchases are slowing “based on our corporate client buyback activity, which provides a real time read and generally has been correlated with directional trends.”
For example, while the dollar amount of first-quarter BofA Securities’ corporate client buybacks was above those of other first quarters following the financial crisis of more than a decade ago, they were at their lowest level in five years when measured as a percentage of the S&P 500’s market capitalization.
Hall points to rising interest rates as another factor to consider in that they could cause a slowdown of companies using debt to buy back their shares. As a result, she says, “companies might prioritize balance sheet repair” or “business investment” over buybacks.
She adds there is nothing that would directly point to Russia/Ukraine specifically affecting buybacks.
For sure, buybacks, unlike dividends, give management teams more flexibility. A dividend, which is considered sacrosanct by many investors, is much harder to cut or suspend. Still, shares of Starbucks fell by 3.7% on April 4, the day of its buyout suspension announcement, and 4.5% the following day.
Meanwhile, Hall is looking for 13% dividend growth for the S&P 500 this year, partly due to “the high demand for dividend income.”
“When looking at buybacks versus dividends,” she says, “there’s more of a case to be made for dividend growth this year.”
Activists Find Lots of Targets and, in Private Equity, Flush Buyers
It’s shaping up to be a busy activist season, which is producing some new investor alliances.
Activist investors have increasingly been pulling pages out of the private-equity playbook, a trend likely to continue, given synergies between the two financial specialties.
Private-equity firms had nearly $2 trillion in dry powder looking for deals as of February, according to S&P Global. Meanwhile, after two years hampered by the pandemic, activists are having no trouble finding companies in need of shareholder prodding, in light of worries over inflation, supply chains, geopolitics, the Federal Reserve, and falling share prices.
Put another way, there’s no shortage of activist ideas or money to see them through.
“This provides activists with all they need to do what they do best, which is find holes in company strategies,” Jim Rossman, co-head of capital markets advisory at Lazard , told Barron’s.
There have been 73 activist campaigns launched in the first quarter of this year, well above the 55 campaigns in the year-ago quarter. And deal making appears to continue to be an impetus for activists to target a company—either by pushing for buyouts, spinoffs, or mergers.
Last month Nielsen Holdings (ticker: NLSN), which had been targeted by Elliott Investment Management, agreed to go private in a $16 billion deal also backed by Brookfield Asset Management (BAM). And CoreLogic was taken private by private equity’s Stone Point Capital and Insight Partners last year after initially being prodded by activist fund Senator Investment Group and holding company Cannae Holdings .
Carlyle Group’s CEO on Why the Deals Keep Coming
Amid a period of tectonic shifts in markets, the economy, and geopolitics, Kewsong Lee, chief executive of Carlyle Group , has reshaped the alternative-asset manager, diversifying beyond the company’s private-equity roots to capitalize on the explosive demand for private assets.
Lee had a long career as a deal maker at Warburg Pincus before making the jump to rival Carlyle (ticker: CG) in 2013. Since becoming co-CEO in 2018 and taking the reins solo in 2020, Lee has expanded the company beyond its roots in private-equity leveraged buyouts. He has shifted the focus from traditional performance fees to more-predictable fee-related earnings growth that analysts say drives shareholder returns.
“It’s a transformation where the numbers are clearly showing they are going in the right directions,” says Chris Kotowski, an analyst at Oppenheimer & Co. Carlyle reported record fee-related earnings in 2021 of $598 million, up 22% from the prior year’s total, and raised a record $51 billion in funds amid a banner year for the industry.
Kotowski thinks the company is still undervalued, given its progress, but Carlyle’s shares have begun to narrow the gap with peers over the past two years, returning almost 51%, compared with the group’s average of 53%. In its first years as a public company, the stock returned 14% from mid-2012 to 2018, lagging behind the S&P 500 index and its peer group’s average total return of 167.6%.
As the head of a global company with $301 billion in assets across sectors and industries, Lee has a bird’s-eye view of the issues that investors are grappling with. Barron’s spoke with him about Carlyle’s transformation, the outlook for private markets, and what the next iteration of globalization could look like. This is an edited version of the conversation.
Barron’s: How far along are you in the transformation you laid out in early 2021?
Kewsong Lee: Last year was a record year, and I’m confident this momentum is going to continue. Our strategy has been to accelerate the growth of the firm by building on the strengths of our core businesses, running them better than ever before, and forging into areas that will drive future growth, including infrastructure and renewables, insurance, and real estate credit. We will have a firm with greater diversification, more growth potential, and a recurring earnings stream that’s going to be very valuable to the market.
What do you think investors are missing?
No doubt Carlyle is great at the deal-doing business; we are great investors. But what’s not appreciated are intangible changes we have made to the mind-set and culture, enabling us to be great at the business of doing deals. For example, we are continuing to break down silos for more connectivity and collaboration among investment teams.
Carlyle has pushed further into credit, insurance, and other businesses. How much more do you want to diversify?
Last year, we raised $51 billion. Two-thirds was away from private equity. We are going to be focused on private markets. But private markets are expanding—well beyond private equity. Private credit is a fraction of its potential and could surpass the size of the PE market.
Real estate is huge. Infrastructure is just now starting to grow, and there is this huge business around portfolio solutions because the private market has grown so large that [chief investment officers] need help. The secular tailwinds for private markets will continue for many years to come.
What is driving that growth?
For companies, it is not just about access to capital anymore. The real edge is access to capital that comes with an ability to help them compete in an increasingly competitive world. Private capital can bring with it global networks of experts to help drive real, fundamental value. In a digital age where human capital is one of the most valuable competitive advantages, private markets are simply at an advantage to public markets.
What are your plans for the $2.5 billion on Carlyle’s balance sheet?
Witness recent credit acquisitions—CBAM and iStar—and the strategic advisory agreement with reinsurer Fortitude Re, each of which aligns with the growth areas we’ve been talking about. You will see more acquisition and investment activity in strategic areas to expand our presence, consolidate our position, and drive leadership in private markets.
What are the biggest concerns among the boards and chief executives you talk with?
CEOs and boards are wrestling with an environment with more volatility that’s projected to look quite different than it has over the past several decades. The confluence of rising rates, inflation, digital transformation and disruption, energy transition, geopolitical decoupling, and supply-chain vulnerability, among a host of other factors, will drive accelerated change. That change can create opportunities for those that can adapt quickly and pivot, so there is a lot of focus on trying to track where the puck is going.
Technology is a key consideration. Every deal is a tech deal, and it’s about how you use data and digital strategies to help drive growth.
What’s the outlook for mergers-and-acquisitions activity?
Volatility is going to create uncertainty, and CEOs are going to be cautious. While there may be a lag, eventually corporations need to figure out how to execute their plans and grow. A lot of CEOs have also learned after Covid that these are times to be bold and opportunistic—and really drive for acquisitions. Our pipelines are as busy as they have been in terms of deal flow, across all our asset classes and business lines.
Geopolitical tensions, an economic slowdown, and a drastic crackdown on technology companies in China has unnerved investors. Is that market still investible?
I know folks are saying we are decoupling. No doubt we are, but I view it less as a total decoupling and more of a new era of globalization. The challenge is how to manage that—and the risk in a decoupling and polarizing world. Any deal has to meet our ESG [environmental, social, and corporate governance] standards across the board.
Carlyle Group CEO Kewsong Lee.
Photograph by Benedict Evans
How can you invest with an ESG lens in China, given its authoritarian government and human-rights abuse allegations?
Look, this is a major region of the world and global economy. All of our clients, big and small, want to know how to invest in that part of the world. No doubt it’s very complicated, and there are issues. But that is why we have to be focused on adhering to our ESG standards that are uniform around the world.
How have the war in Ukraine and sanctions on Russia changed the face of globalization?
We are entering a new era where there is more thinking about regional ecosystems. That will create a shift from “just in time” to “just in case.”
Business leaders will have to think through implications to their supply chains, logistics, and the capital they need, including working capital, to enable a more resilient, “just in case” mentality instead. It’s early days, but clearly there are cost implications, [an impact on the] efficiency of capital usage, and huge supply, inventory, and working-capital implications.
Who benefits?
There are going to be lots of businesses that are advantaged—data companies to manage these supply chains better and new finance and payment solutions as we move toward this different ecosystem as it applies to the implications of “just in case.” There will be risks but also enormous opportunities for companies that can move quickly and adapt.
Are you worried that inflation and spiking commodity prices could pause the energy transition?
This is going to accelerate investing into alternative forms of energy, not slow it down. But it’s not an either/or. We have to do the hard work to improve companies and reduce their footprint and emissions. You can’t divest out of this problem. You have to invest your way out. We invest with an ESG lens that enables us to not just drive lower emissions, but also drive great returns.
Some see a reckoning ahead for ESG. What do you say to naysayers?
ESG is not a fad, concept, or a metric—it’s a mind-set that needs to be infused in your culture because it helps improve outcomes and drives our performance.
Where do you see froth in the market?
Liquidity driving higher and higher valuations—that game is over. There are certain aspects of the market, like momentum investing in certain sectors, which I think have come to an end. Eventually, all companies need to have a realistic path and timeline to profitability—that has become more apparent in an environment where rates are going up. When there is a tremendous amount of change, we look to invest in ways that will benefit from that change.
What investment trends will we be talking about in five years?
We have talked in the past about cybersecurity or energy security, but you are going to be hearing about food security. People are starting to realize how much wheat production and fertilizer run through the regions in conflict. The whole climate topic is going to continue to grow. Infrastructure is also going to become a huge topic. The private sector has amassed a lot of dollars to help fix problems and make critical investments in all aspects of our infrastructure.
Where Will The Food Riots Start?
Global food prices have never risen so fast and have never been so high, and as have detailed multiple times in recent months (as this is not simply a one-month, 'blame it on Putin' crisis), most recently here, the pieces are in place for some serious tears to form in the social fabric of many nations.
While food prices may be generally seen as an emerging market problem, they will have an effect on developed markets too, something we will see in the upcoming French election.
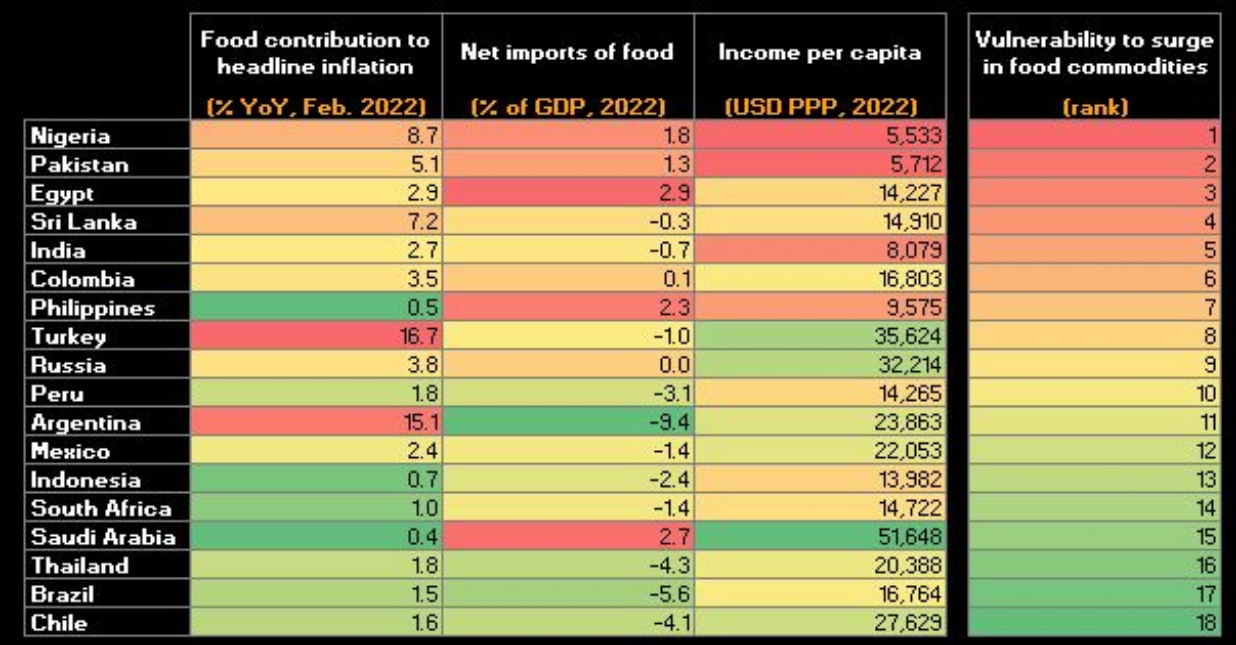
And as the following table from Bloomberg Economics shows, while Pakistan is already in the midst of a political crisis and Egypt is already coming under financial pressure (along with Peru and Sri Lanka), the surge in food prices is also adding to problems in the developed world.
Nigeria, India, Colombia, Philippines, and Turkey all bear watching, along with Russia...
In fact, as PeakProsperity's Chris Martenson details below, the inflation riots have begun. Peru and Sri Lanka both are experiencing violence as inflation spirals the prices of basic necessities higher and higher.
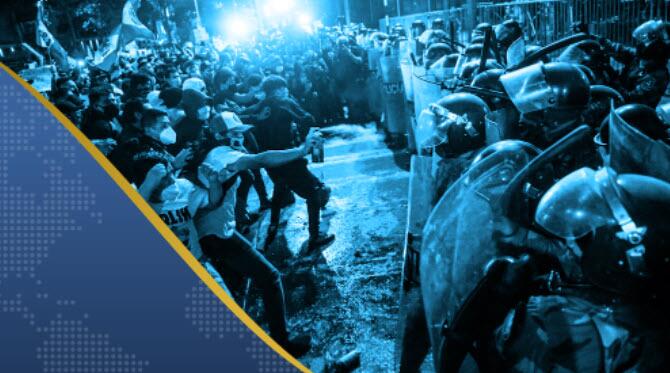
We’ve been here before, and recently.
The Arab Spring was a period of social unrest and riots in 2010 and 2011 that was triggered, in part, by spiking food costs.
As Alfred Henry Lewis said in 1906, “There are only nine meals between mankind and anarchy.”
But before pure anarchy comes, society experiences increasing unrest and the erosion of social bonds and niceties. That’s where we are now.
Food prices today are higher than they were in 2010, so the protests are not at all surprising. We can and should expect more of them.
Worse than that, however, is the prospect of actual famine and food shortages.
I expect true famine to emerge by the end of this year, after the northern harvest fails to cover the basic needs of 8+ billion people.
This is yet another reason why you should plant a garden. As if you needed one more, right?
The reason for the glum outlook is not just the loss of Ukraine exports, and probable loss of the planting season for quite a large portion of the Ukraine, but because of the desperate global shortages of fertilizers which have become utterly essential to today’s crop yields.
In this lesson, we learn that converting biologically active and supportive soil into barren dirt was a terrible idea.
By 2030, it is projected that phosphate will reach peak output and then begin its long slow decline. What’s the world plan for this? There isn’t one. Again, this is why local, regenerative farming is so critical to undertake at this time.
Course of post COVID-19 disease symptoms over time in the ComPaRe long COVID prospective e-cohort
Nature Communications volume 13, Article number: 1812 (2022)
Abstract
About 10% of people infected by severe acute respiratory syndrome coronavirus 2 experience post COVID-19 disease. We analysed data from 968 adult patients (5350 person-months) with a confirmed infection enroled in the ComPaRe long COVID cohort, a disease prevalent prospective e-cohort of such patients in France. Day-by-day prevalence of post COVID-19 symptoms was determined from patients’ responses to the Long COVID Symptom Tool, a validated self-reported questionnaire assessing 53 symptoms. Among patients symptomatic after 2 months, 85% still reported symptoms one year after their symptom onset. Evolution of symptoms showed a decreasing prevalence over time for 27/53 symptoms (e.g., loss of taste/smell); a stable prevalence over time for 18/53 symptoms (e.g., dyspnoea), and an increasing prevalence over time for 8/53 symptoms (e.g., paraesthesia). The disease impact on patients’ lives began increasing 6 months after onset. Our results are of importance to understand the natural history of post COVID-19 disease.
Introduction
As of March 2022, about 437 million people worldwide had been infected by the severe acute respiratory syndrome coronavirus 2 (SARS-CoV-2), the pathogen responsible for coronavirus disease 2019 (COVID-19)1,2. According to the United Kingdom Office for National Statistics, about 10% of them will experience post COVID-19 disease or “long COVID”, that is, the persistence of symptoms such as fatigue, dyspnoea, chest pain, cognitive disturbances, or arthralgia, for several weeks to months after their initial SARS-CoV-2 infection2,3. Research has mainly focused on the occurrence of specific long-term complications among hospitalised and non-hospitalised patients recruited during their acute COVID-19 infection4,5,6,7,8,9,10,11. To our knowledge, only a handful of studies have investigated the longitudinal evolution of symptoms among patients with persisting symptoms (i.e., with post COVID-19), but they have generally been small, retrospective or limited to single centres12,13,14. In this study, we used data from a large nationwide cohort of patients to reconstruct the day-by-day course of their symptoms from onset to 1 year after the acute phase of the infection.
Results
Participants
The ComPaRe long COVID cohort is an ongoing nationwide e-cohort of patients with post COVID-19 disease in France, nested in the ComPaRe research programme (www.compare.aphp.fr), an umbrella e-cohort of patients with chronic conditions15. The cohort started in December 2020, and recruitment is ongoing. Among the 1859 patients included in the ComPaRe long COVID cohort on October 15, 2021, we analysed the data from the 968 patients reporting: (1) a laboratory-confirmed COVID-19 infection with a positive test for SARS-CoV2 by PCR swab and/or serologic assay; (2) symptoms persisting for at least 2 months after their onset; and (3) enrolment in the cohort by August 1, 2021, and thus at least 2 months of follow-up in this analysis (Fig. 1). To improve the representativeness of results, we weighted observations by calibration on margins, so that the weighted distribution of age (<24, 25–34, 35–49, 50–69, and ≥70 years), gender, and hospitalisation during the acute phase of the disease (Yes/No) matched the data from the UK Office of National Statistics Covid Infection Survey (2 September 2021 data)16,17. Raw and weighted patients’ characteristics are presented in the Table 1. Hereafter, results presented always come from the weighted dataset. Raw results are available in the Supplementary Materials.
Fig. 1: Study flow chart.
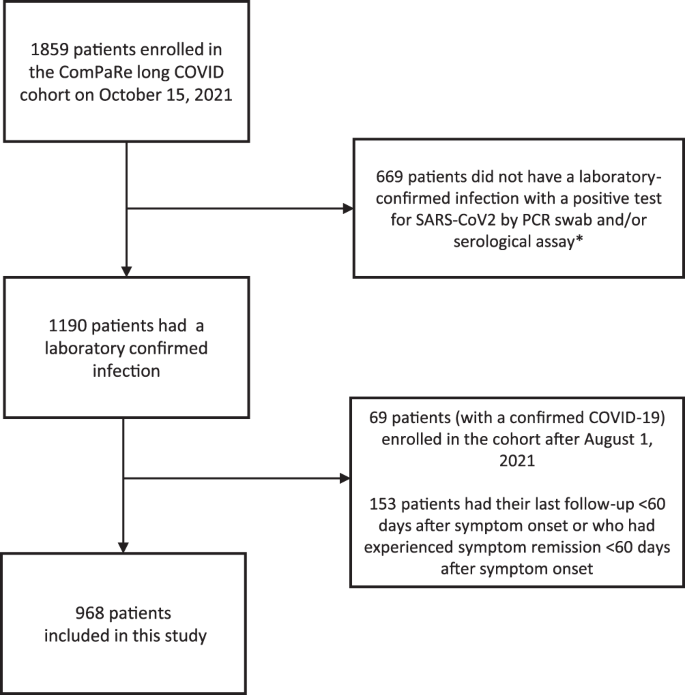
*The high number of patients without a confirmed infection is due to the limited availability of testing during the first wave of COVID-19 in March 2020, in France.
Table 1 Patients’ characteristics (n = 968).
In the weighted data, patients’ median age was 48 years (interquartile range 32–56) with 57.7% (559/968) men. In all, 35.1% (340/968) reported comorbidities, 6.3% (61/968) had chronic lung diseases, and 4.2% (41/968) high blood pressure. The median time between symptom onset and the last follow-up was 174 days (IQR 97 to 284 days). Among participants, 75 (7.7%) had been hospitalised during their acute disease and 34 (3.5%) had been admitted to an intensive care unit (ICU).
Probability of symptom persistence at 12 months
Participants were followed up every 60 days with online questionnaires available on computer or smartphone. At each observation point, patients were first asked if they still had symptoms related to COVID-19. Those reporting the persistence of symptoms completed the long COVID symptom tool (ST) and impact tool (IT), a pair of validated patient-reported instruments assessing respectively 53 symptoms and 6 dimensions of patients’ lives that can be affected by the disease18. Those reporting that they no longer had any symptoms were asked to report the date when they first noticed the absence of symptoms. Overall, our data covered 5350 person-months, with a median follow-up since cohort enrolment of 181 days (interquartile range 118 to 240 days). The proportion of patients lost to follow-up was <20% at every follow-up (Supplementary Material 1).
Remission of symptoms (i.e., disappearance of all symptoms) was observed during follow-up for 150 patients. Among those who reported full symptom remission, 50/150 (33.3%) subsequently described a relapse for at least one symptom. At 12 months, the probability of symptom persistence (including patients in remission who relapsed) was 84.9% (95% CI 79.8–90.4%) (Fig. 2).
Fig. 2: Cumulative event curve for remission of post COVID-19 symptoms.
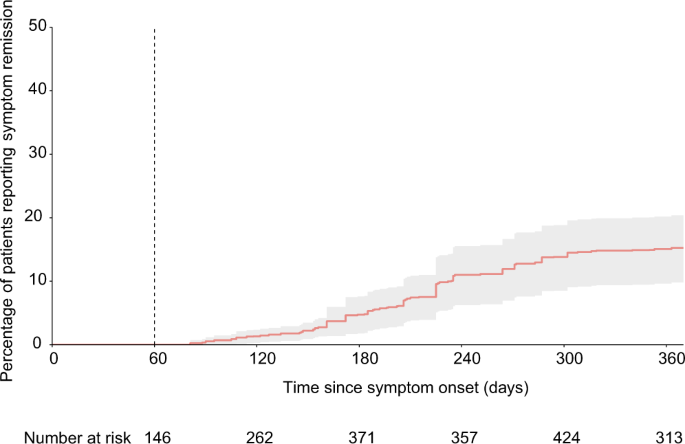
Time of remission was defined as the first time that patients reported no longer experiencing any symptoms of post COVID-19 disease. The time at risk started at entry in the cohort and ended on October 10, 2021. Follow-up data were censored at the participants’ latest observation point. Error bands represent 95% confidence intervals. Source data are provided as a Source Data file.
Day-to-day prevalence of post COVID-19 disease symptoms
We used multistate models taking both left and right censoring into account to estimate the longitudinal evolution of symptoms. In the models, each patient contributed to the data during his/her follow-up period. Because our cohort included patients enroled at different times after their initial infection, we were able to reconstruct the prevalence of each symptom, day-by-day, in the study population (Fig. 3A and Supplementary Material 2). First, 27 (51%) symptoms showed a progressive decrease in prevalence over time. Among them, loss of appetite, change/loss of taste, and cough changed most (>20% decrease). Second, 18 (34%) symptoms showed no specific change in prevalence over time. Among them, word finding problems and dyspnoea were the most prevalent. At 360 days, they affected respectively 48% and 44.5% of the population. Finally, eight symptoms showed an increase in prevalence over time. Among them, neck, back, and low back pain and paraesthesia changed most markedly (>10% increase) (Supplementary Material 3). The evolution of symptoms over time in subgroups by age, sex, and presence of comorbidities is presented in Supplementary Materials 4–6.
Fig. 3: Day-by-day trends in the prevalence of post COVID-19 disease symptoms (A) and of their impact on patients’ lives (B).
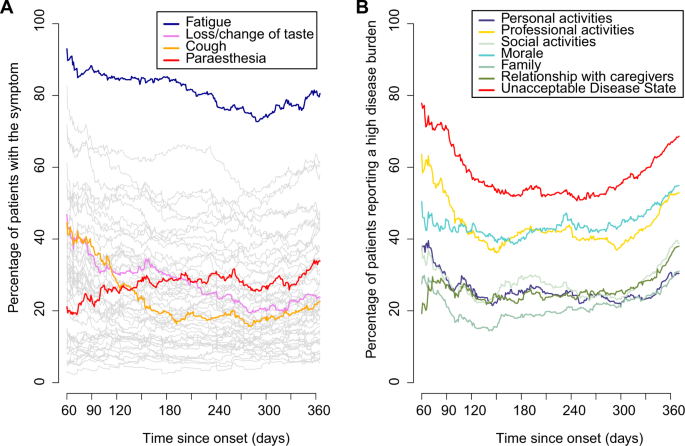
A The figure presents the day-by-day prevalence of each of the 53 symptoms assessed by the Long COVID ST (grey lines). Examples of specific symptoms have been highlighted (coloured lines). For each symptom and at each observation point, we assumed that patients could either be “experiencing” or “not experiencing” the symptom. We assumed that their state at an arbitrary time was the same as the state at their previous observation point and that their states before their first observation and after their last observation are unknown. B The figure presents the day-by-day evolution of the six domains of patients’ lives that can be affected by post COVID-19 disease and are assessed by the Long COVID IT. For each item and at each observation point, we modelled patients answers as either “reporting” a significant impact of the disease on this domain” (i.e., item score >7) or “not reporting” this impact (i.e., item score <8). We assumed that their state at an arbitrary time was the same as the state at their previous observation point and that their states before their first observation and after their last observation are unknown. The red lines represent a similar model for the Patient Acceptable Symptomatic State (PASS) of the long COVID IT, which is the long COVID IT score below which 75% of patients find that their disease state is acceptable. Source data are provided as a Source Data file.
Post COVID-19 disease is a relapsing-remitting disease. Sixty days after symptom onset, most of patients reported permanent, daily or weekly symptoms. Over time, relapses became less frequent, with a decrease in the proportion of patients reporting weekly or more frequent symptoms (including those reporting permanent symptoms) and a parallel increase in the proportion reporting relapses less than weekly (Supplementary Material 7).
Evolution over time of the impact of post COVID-19 disease on patients’ lives
Figure 3B illustrates patients’ perceptions of the impact of the disease on their lives, measured by the long COVID IT. In particular, we present the proportion of patients reporting an unacceptable disease state, defined as a score on the long COVID IT above the value at which >75% of patients consider that they could not cope with a similar level of lifelong symptoms18. This analysis revealed two distinct phases of the disease. In a first phase, from 60 to 180 days, the burden of disease progressively decreased as several symptoms disappeared, while the number of patients reporting an unacceptable symptom state diminished slowly to 50%. After 6 months, the proportion of patients reporting an unacceptable disease state increased more rapidly, with 60–70% of patients considering their disease unacceptable at that time. This secondary increase may correspond to patients’ realisation that they had a chronic disease. This U-shaped trend in the evolution of the perception of the impact of the disease on patients’ lives over time was found in subgroups defined by age and sex. (Supplementary Material 8 and 9).
Discussion
This study reports how the symptoms and impact of post COVID-19 evolve after the acute phase of the disease, in a large prospective cohort of patients with a laboratory-confirmed infection. Among patients with post COVID-19 disease, 85% still reported symptoms 1 year after symptom onset. This finding is consistent with observations in a single-centre study in Germany, where 20% of patients were free from all 14 symptoms under study at 12 months12.
The course of symptoms over time highlighted three distinct patterns that offer insight into the aetiologies and mechanisms underlying this disease. First, we observed a decrease in prevalence over time for symptoms such as loss of taste or smell, coughing, or diarrhoea. For example, the prevalence of coughing decreased from 50 to 20% of participants within the first 6 months after symptom onset before reaching a plateau. This was similar for loss of smell, with a plateau reached after 8 months. This evolution, indicating recovery from the acute phase, is slower than expected. Indeed, most guidelines still consider a cut-off of 12 weeks to distinguish ongoing symptomatic COVID-19 (i.e., signs and symptoms of COVID-19 from 4 to 12 weeks) from post COVID-19 syndrome19. For other symptoms, we showed that their prevalence increased over time. For example, the prevalence of hair loss increased over time with 8% and 15% of participants reporting it at 2 months and 1 year after onset respectively. Late symptom appearance, especially alopecia, has been reported in other studies and should be further investigated20. Finally, symptoms showing no change of prevalence over time may be caused by mechanisms that do not change rapidly over time, such as deconditioning or post-traumatic stress disorder, or due to a mixture of recovery from acute disease and late-onset symptoms appearing as a consequence of COVID-1921.
We found some differences in the evolution of symptoms between men and women; and in age groups. We hypothesise that differences may be due either to different underlying causes of the persistent symptoms or to specific factors directly affecting symptoms. For example, several studies have highlighted differences between the sexes in immune responses (in terms of levels of innate immune cytokines such as IL-8 and IL-18, induction of non-classical monocytes, and T cell activation)22 and in response to a traumatic event23.
Our results demonstrate the substantial impact of post COVID-19 disease on patients’ lives. Specifically, the course of patients’ perceptions of the impact of the disease changed similarly over time across all subgroups, with an aggravation 6 months after onset. We hypothesise that this corresponds to patients’ realisation that this novel and previously unknown disease is chronic rather than acute. This trend seemed more pronounced among younger patients, for whom post COVID-19 is more likely to be both their first contact with a chronic disease and a biographical disruption of their lives24.
Strengths of this study lie in the prospective follow-up of a large population of patients with a confirmed COVID-19 infection and their regular assessment of their symptoms using validated patient-reported outcome measures, developed from patients’ lived experience, with excellent reproducibility (intraclass correlation coefficient 0.83, 95% confidence interval 0.80–0.86)18. The use of online questionnaires reduced social desirability bias and may provide better estimates of the prevalence of sensitive symptoms such as genitourinary or cognitive disorders25.
This study has several limitations. The recruitment of volunteers in the ComPaRe long COVID cohort may have selected patients who had overall more symptoms, and our recruitment strategy included a social media and general media campaign that may have selected younger and better educated patients. Second, our sample included a majority of women. Persistent symptoms after COVID-19 are more frequent among women; for example, the odds of persistent fatigue at 1 year among women compared with men was 1.43 [1.04–1.96]26. To minimise these issues, we used a weighted dataset with weights derived from the September 2021 data from the Office of National Statistics in the United Kingdom16. Yet, because our original dataset included fewer men, results in this subgroup may lack precision. More generally, the subgroup analyses were post-hoc, and should be considered as exploratory. Third, in this study we included patients with a history of confirmed SARS-CoV-2 infection who had symptoms for at least 2 months, in accordance with the WHO’s recent consensus definition of post COVID-19 disease27. However, our data prevented us from ascertaining whether an alternative diagnosis might explain the symptoms. Fourth, as patients could enrol in the cohort at any time point after their initial infection (with an interval between symptom onset and enrolment exceeding 300 days for 25% of participants), we chose to minimise memory bias by not asking retrospectively for symptoms experienced during the infection’s acute phase. This limits our ability to describe how symptoms change immediately after the acute phase of the disease. Fifth, disease remission was defined as having no symptoms among 53. As the likelihood of having at least one symptom, at any time point, is expected to be high even in the general population, our analyses may overestimate the number of patients who still report symptoms 1 year after their symptom onset. Sixth, this study did not use a control group. Because several symptoms of post COVID-19 disease are non-specific, we cannot ascertain that the observed symptoms are different from or in addition to what might be due to intercurrent illnesses, comorbidities, ageing, or social effects of living through the pandemic. Finally, in view of the limited number of patients who were hospitalised in ICUs in our study, our results cannot be generalised to this specific population.
In conclusion, our study shows that most patients with post COVID-19 disease have symptoms evolving in different patterns but persisting through 1 year. Recovery from the acute infection is a slow process, and the prevalence for most symptoms decreased over time before plateauing 6–8 months after onset. Our results are of importance to understand the natural history of this disease, and should help physicians to inform their patients about the potential course of this disease.
Closing Stock Market SummaryThe S&P 500 declined 0.3% on Friday in a mixed session in which value stocks outperformed at the expense of growth stocks. The growth/value divide was evident in the disparity between the Nasdaq Composite (-1.3%) and Dow Jones Industrial Average (+0.4%). The Russell 2000 lost 0.8%.
Growth stocks remained pressured by valuation concerns as long-term interest rates continued to creep higher: the 10-yr yield rose five basis points to 2.71% (+34 bps for the week). Shorter-dated rates also pushed higher, with the 2-yr yield increasing five basis points to 2.52% (+10 bps for the week).
The mega-caps within the S&P 500 information technology (-1.4%), consumer discretionary (-1.0%), and communication services (-0.7%) sectors were among the heaviest weights on the market. The Vanguard Mega Cap Growth ETF (MGK 227.74, -2.78) fell 1.2%.
Transportation stocks also struggled amid underlying growth concerns and negative-minded analyst recommendations. BofA Securities downgraded both Union Pacific (UNP 241.98, -2.88, -1.2%) and UPS (UPS 191.02, -1.68, -0.9%) to Neutral from Buy. The Dow Jones Transportation Average fell 0.9%.
Conversely, the financials (+1.0%) and energy (+2.8%) sectors were the strongest performers amid the higher rates and higher oil prices ($98.18/bbl, +1.88, +2.0%). The defensive-oriented health care (+0.6%), consumer staples (+0.4%), utilities (+0.3%), and real estate (+0.3%) sectors added to their weekly gains.
Blue-chips like UnitedHealth (UNH 545.96, +9.01, +1.7%), Walmart (WMT 157.41, +0.87, +0.6%), and Coca-Cola (KO 63.83, +0.39, +0.6%) set all-time highs, contributing to the outperformance of the Dow, on no specific news. Note, UNH will be among the first batch of companies to report Q1 earnings next week.
Separately, the S&P 500 wavered around its 200-day moving average (4493) the entire session, ultimately closing below the key technical level amid some slippage activity into the close.
The U.S. Dollar Index (99.84, +0.09, +0.1%), meanwhile, rose for the seventh straight session and briefly topped the 100.00 level.
Friday's economic data was limited to Wholesale Inventories, which increased 2.5% m/m in February (consensus 2.1%) following a revised 1.1% increase (from 0.8% increase) in January. There is no data of note scheduled for Monday.
- Dow Jones Industrial Average -4.5% YTD
- S&P 500 -5.8% YTD
- Russell 2000 -11.2% YTD
- Nasdaq Composite -12.4% YTD
Weekly Market Update: Ukraine war and Fed policy minutes keep markets under pressure
Markets opened the week unsettled amid ongoing consternation surrounding the Ukraine war as well as US Federal Reserve policy. Crude oil prices rose in the early part of the week as another round of Western sanctions on Russia was being contemplated following the unearthing of atrocities committed by Russian forces in Bucha. Europeans openly discussed a mandatory phase out of imported coal to go along with additional measures to strength energy sanctions. Western officials also stepped up their rhetoric surrounding President Putin reiterating their belief that war crimes, and potential genocide is being committed by Russia. The pressure seemed to have little baring on the ground though. By Friday, reports circulated that dozens has been killed in Russia missile attack on Ukraine railway station in Kramatorsk which was being used as an evacuation center.
US Treasury yields were jolted higher on Tuesday when Vice Chair nominee Brainard’s hawkish commentary caught investors’ attention, presaging the March FOMC minutes. Wednesday’s minutes essentially supported what we have heard from a full throated chorus of Fed officials of late. Namely, a 50 bps cut remains firmly on the table and is possible in May when the Fed is likely to begin cutting back on the balance sheet as well. According to the minutes, the monthly cap on drawdowns will likely rise to $95B by this summer, but to date officials have not decided the target size for the balance sheet at the end of the process. Increasingly aggressive calls by both Fed officials and forecasters on rates continued to push yields higher as the week progressed. By Friday, US 10-year Treasury yield rose for a sixth consecutive day, notching a new three-year high above 2.7% which resulted in an unwind in the recent curve inversion for the benchmark 2/10 year spread. Oil prices ended the week only modestly higher, with WTI below $100/bbl. For the week, the S&P fell 1.3%, the DJIA slipped 0.3%, and the Nasdaq was dove 3.9%.
In corporate news this week, newly reinstated Starbucks CEO Howard Schultz announced he would halt stock buybacks in order to invest in employees and stores, as unionization efforts accelerate at some of its locations. Costco shares hit a new 52-week high after the store chain announced double digit growth in March same store sales. Twitter added Elon Musk to its board of directors after the Tesla CEO disclosed a large position earlier in the week, though Musk will be limited to taking a 14.9% stake while he serves on the social media giant’s board. Spirit Airlines confirmed receipt of an unsolicited $33/share all-cash takeover offer from JetBlue Airways, throwing a wrench in its planned merger with Frontier Airlines.
SUN 4/3
(EU) Latvia, Estonia and Lithuania stopped imports of Russian gas from Apr 1st - press
(RU) Russian Pres Putin said to be under pressure to achieve victory in eastern Ukraine by Russian holiday Victory Day on May 9th - CNN
(RU) Russia govt spokesman Peskov: Russia will demand Rouble (RUB) payments for other goods; Russia does not want to make life difficult for Western purchasers of Russian gas
MON 4/4
(UK) FCA: To review LME approach on suspension and resumption in Nickel Trading; sees exchange remaining vigilant until situation resolved
SBUX Founder and incoming CEO Howard Schultz decides to suspend stock repurchasing program, effectively immediately
TWTR Tesla CEO Musk reports 9.2% passive stake - 13G filing
(US) US to seek Russia's suspension from UN Human Rights Council - press
(UK) Chancellor of the Exchequer (Fin Min) Sunak: It is my ambition to make the UK a global hub for cryptoasset technology
CCL Reports one-week period of March 28-April 3 was its busiest booking week in the company's history (double-digit increase from the previous record 7-day booking total)
TUES 4/5
(PE) Peru President Castillo declares state of emergency in Lima and Callao; to enforce curfew on Apr 6th due to inflation protests
(EU) EU's Dombrovskis: Sanction discussions on Russia to include energy sector with oil, coal sanctions as an option
(UR) EU's Foreign Policy Chief Borrell and EU Commission President Von der Leyen to travel to Kyiv this week - press
(RU) EU reportedly to ban Russian trucks and vessels from entering the EU; To block all transactions with VTB bank and other three Russian banks already excluded from SWIFT messaging system - press
(DE) Germany Finance Min Lindner: EU did Not find deal on corporate tax today; Poland vetoed 15% min tax implementation by 2023
(CN) Reportedly China urges Shanghai to ensure port, shipping operations - press
(UR) Czech Republic reportedly sent several T-72 tanks and BVP-1 infantry fighting vehicles to Ukraine - Czech TV
TWTR Adds Elon Musk to board of directors; To limit Musk stake to 14.9% while he serves on Board (currently 9.2% stake)
*(US) MAR ISM SERVICES INDEX: 58.3 V 58.5E
(US) Fed’s Brainard (vice chair nominee): Expects balance sheet to shrink considerably more rapidly than prior recovery; Fed ready to take stronger action if inflation and inflation expectations indicators suggest need for such action
(US) Fed's George (FOMC voter, hawk): A 50bps hike will be an option we have to consider; Fed may have to go above neutral to bring inflation down - TV interview
(NZ) Fonterra Global Dairy Trade Auction Dairy Trade price index: -1.0% v -0.9% prior
(US) Atlanta Fed GDPNow: Cuts Q1 GDP forecast to 0.9% from 1.5%
SAVE Confirms receipt of unsolicited $33/shr all-cash proposal from JetBlue Airways
*(CN) CHINA MAR CAIXIN PMI SERVICES: 42.0 V 49.7E (1st contraction in 7 months and lowest level in two years)
WEDS 4/6
(RU) Russia govt spokesman Peskov: If there is to be a successful negotiation between the Russian and Ukrainian delegations, there will have to be a meeting between Putin and Zelensky at the highest level - French tv interview
(RU) Russia Finance Min Siluanov: Had to pay Roubles (RUB) to holders of 2022 and 2042 eurobonds as foreign bank rejected to process FX payment in amount of $649.2M
(CN) China oil firms Sinopec, CNOOC and Petrochina reportedly stay away from trading new Russian cargoes for May loadings; Some independent refiners continue ESPO** crude imports - press
(CN) China vows use of monetary policy tools to aid domestic economy at the proper time and in a flexible way - Chinese media
(DE) German Chancellor Scholz: Confidentially discussing possible security guarantees with Ukraine; Not making any preparations to postpone exit from nuclear power - speaking in Berlin
(RU) UN to vote on suspending Russia from United Nations Human Rights council - press
Reportedly US banks, including Wells Fargo and Bank of America debating a plan to use Zelle to challenge Visa and Mastercard; Plan to expand Zelle to merchant payments - press
TM North America sales exec: See US sales of 15.5M units in 2022 vs 16.5M y/y, citing supply chain headwinds
(US) Association of American Railroads weekly rail traffic report for week ending Apr 2nd: 502.2K total units, -2.7% y/y
(US) USPS raises price of First-Class Mail Forever stamp by 6.5% from 58 cents to 60 cents, effective July 10th
*(US) FOMC MAR MINUTES: OFFICIALS GENERALLY EYED MONTHLY $60B CAP FOR TREASURY DRAWDOWN AND $35B FOR MBS DRAWDOWN; MANY ON FED WOULD HAVE SOUGHT 50BPS MARCH HIKE IF NOT FOR UKRAINE WAR
COST Reports Mar total SSS +12.2% (ex-gas and FX)
005930.KR Reports Prelim Q1 (KRW) Op 14.1T v 13.4Te (highest Q1 Op since 2018); Rev 77.0T v 75.0Te (Rev record high)
HPQ Berkshire Hathaway files Form 3, reports purchase of ~121M shares in the co.[~11.4% stake]
(US) Reportedly House speaker Pelosi in talks to visit Taiwan [would be the first US House Speaker to visit Taiwan in 25 years] - press
THURS 4/7
066570.KR Reports Q1 (KRW) Op 1.88T v 1.52T y/y; Rev 21.1T v 18.81T y/y
(CN) China Foreign Min spokesperson Zhao Lijian: US House Speaker Pelosi should immediately cancel her trip plan to Taiwan
(RU) Russia Foreign Min Lavrov: Ukraine presented new proposals and new draft agreement on Apr 6th, different from Istanbul ones; Ukraine proposes to discuss Crimea, Donbas status which is unacceptable
STZ Reports Q4 $2.37 adj v $2.15e, Rev $2.10B v $2.02Be; Plans $500M share repurchases in Q1
CAG Reports Q3 $0.58 v $0.57e, Rev $2.90B v $2.84Be; Guides Q4 gross inflation* 16%
*(US) INITIAL JOBLESS CLAIMS: 166K V 200KE (lowest since 1968); CONTINUING CLAIMS: 1.523M V 1.302ME
(US) Speaker Pelosi tests positive for COVID-19, trip to Asia postponed to a later date
(RU) Russia govt spokesperson Peskov: We have had significant losses of troops in Ukraine, its a tragedy - TV interview
(US) Senate confirms Biden nominee Ketanji Brown Jackson to Supreme Court by 53-47 vote (as expected)
(EU) EU reportedly to support Russian coal embargo in fifth round of sanctions - press
*(US) FEB CONSUMER CREDIT: $41.8B V $18.1BE (record level)
TSLA CEO Musk: Trailing 12-month deliveries >1.0M; Tesla seeking to produce 500K Model Y at Texas factory, to start Cybertruck production next year
AAPL Reportedly orders for the 5G iPhone SE and AirPods are stable - Digitimes
FRI 4/8
(DE) German Chancellor Scholz reportedly delaying a final decision over whether to give Ukraine high-end tanks for its battle against Russia. initially expected this week - Politico
MAERSKB.DK Launches Maersk Air Cargo unit; Expected to be fully operational as of H2 2022
*(RU) RUSSIA CENTRAL BANK (CBR) CUTS KEY 1-WEEK AUCTION RATE BY 300BPS TO 17.00% (INTRA-POLICY MOVE); Says further rate cuts possible during upcoming meetings
(EU) EU adopts 5th round of sanctions against Russia, including ban on Russian coal import from Aug 2022 and banning Russian vessels from EU ports
(EU) Reportedly EU has already started working on the 6th package of sanctions against Russia; Next objectives could be uranium and/or oil sanctions via monthly reductions, tariffs or escrow accounts, or a combination - press
(UR) Slovakia PM: Delivered its sole S-300 air defence system to Ukraine
*(CA) CANADA MAR NET CHANGE IN EMPLOYMENT: +72.5K V +79.9KE; UNEMPLOYMENT RATE: 5.3% V 5.4%