Goldman Sachs offers former partners exclusive access to ‘1869 fund’
Vehicle for ex-members of elite group has raised $1bn and invests in alternative assets
Goldman Sachs is offering its network of former partners, who range from tech executives to prime ministers, exclusive access to a new investment vehicle that will put money into the Wall Street firm’s private market funds.
The so-called 1869 fund, which takes its name from the year Goldman was founded, invests across multiple private funds managed by the firm’s asset management division, according to five people familiar with the matter.
Former partners who invest in the fund of funds receive discounted management and performance fees, with the total amount an individual can put in capped at $5mn, the people said.
They have previously had access to private funds through Goldman’s wealth management platform and paid the same fees as other clients.
The 1869 fund invests in Goldman Sachs Asset Management’s private funds, which are focused on alternative investments including private equity and real estate opportunities.
It has so far raised about $1bn, two of the people added, although it is unclear how much capital has been deployed.
Ex-partners see the vehicle as an attempt by Goldman to retain an attachment to former top bankers who have left to pursue other opportunities as well as those who might feel disgruntled after being pushed out.
“You helped create our 152-year history of excellence in the industry, and with this offering, we hope to show our gratitude for your support, leadership and friendship over the years,” the bank wrote to former partners last year in a note announcing the new vehicle, which was seen by the Financial Times.
Goldman declined to comment.
Becoming a partner at Goldman Sachs, a title that brings with it multiple perks including a guaranteed salary of $1mn a year, has historically been one of the most prestigious positions on Wall Street.
Goldman names new partners every two years, but by 2020 the group’s ranks had swollen to the point where David Solomon, chief executive, decided to elevate fewer bankers to cut costs and ensure the title retained its exclusivity.
Former Goldman partners include Gary Gensler, the chair of the Securities and Exchange Commission, and Anthony Noto, the CEO of fintech company SoFi who was formerly chief operating officer at Twitter.
Steven Mnuchin, who worked as US Treasury secretary in the Trump administration, is also a former partner, as is Malcolm Turnbull, Australia’s former prime minister. It is unclear which former partners have invested in the 1869 fund.
Alternative asset management is one of the areas Solomon has targeted to help diversify the bank away from investment banking and trading.
Solomon has set the bank’s asset management division a goal of raising $225bn to invest in alternative assets between 2020 and 2024.
Goldman Warns Of Higher Oil Prices & Volatility Due To "Self-Sustaining" Physical & Financial Deficit Doom-Loop
On the same day as oil prices slip to their lowest since Putin's invasion of Ukraine - and reports of Russia selling oil to China for Yuan - Goldman Sachs doubled-down on their Poszar-esque commodity-currency-linked warnings about the regime-change under way in the energy complex.
As Goldman's Jeff Currie recently warned, commodities are entering a volatility trap.
Crucially, as we detail below, this self-sustaining regime-shift driven by both physical and financial factors, is likely to last years rather than weeks.
'Physically'
Inventories are already at historical lows in terms of 'days of demand' following 20 consecutive months of deficit...

...and Goldman notes that the unavailability of the usual system buffers of inventory and spare capacity...

...has required an evolution in the pricing regime towards the more abrupt mechanism of demand destruction, amplifying the price and volatility impact of the continued pandemic shocks and, currently, the Russia-Ukraine war.
Remember, the 'physical' markets have suddenly become significantly more complicated (and delivery anything but guaranteed) as we recently noted 'oil is no longer fungible' to some extent, for some buyers... "Russian oil bidless, non-Russian oil offerless"...

'Financially'
Volatility is both curbing liquidity and restricting access to the very credit required to maintain orderly financial and physical trading of commodities.
In addition, it is also exacerbating the medium- to long-term capital shortages that have built up after an era of low returns and ample supply, reinforced by political and investor ESG concerns.
This can be visualized in the following vicious doom-loop of volatility creating more illiquidity and lowering capital, leading to more volatility and so on...
As oil becomes more volatile...

...the range of possible outcomes becomes wider, with a greater potential for loss...

...that shifting distribution drives up the Vale-at-Risk (VaR)...

...which drives down the hedgeable amount of commodities, for any given amount of risk capital...

And a lack of risk capital lowers market participation, driving down liquidity and exacerbating volatility, and further discouraging potential lenders and investors, reinforcing lower participation and higher volatility.
This volatility trap is a direct consequence of the "Revenge of the Old Economy".
As commodity producers under-invest in new supply, commodity inventories deplete, raising volatility as the market loses its balancing buffer between small supply and demand shocks. This volatility in turn keeps commodity producer assets unattractive - it raises the uncertainty surrounding the investment's true value, lowering its appeal to investors. Capital continues to stay away from the sector, keeping new supply capacity - and hence inventories - low.
And as we saw in the 1970s, such a volatility trap can create persistently higher commodity inflation and a supply constrained market.
- In the 1970s, the markets turned to long-term fixed price contracts and built large conglomerates to deepen the balance sheets required to deal with these funding stresses.
- In the 2000s (pre GFC) they used financial markets, and a higher degree of bank leverage, to share the risks. Neither avenue is fully available in today’s regulatory environment.
But, it's different this time.
Given there is unlikely to be a widespread lift of sanctions on Russia, regardless of the outcome of the war, as has historically been the case with such regulatory impositions, Goldman expects this new, more volatile pricing regime to persist for the foreseeable future.
All of which reinforces Goldman's forecast for $125/bbl Brent crude in 2H22 and reinforces Poszar's warnings that you can print money but not print oil, iron, or wheat, or VLCCs or other ships to guarantee delivery of the critical commodities. Thus, as Poszar concludes rather ominously, commodity reserves will be an essential part of Bretton Woods III, and historically wars are won by those who have more food and energy supplies. And as Goldman's price forecast suggests, the current 'lull' in the stagflationary storm (as oil prices slide to post-invasion lows) is perhaps just the eye of a very much larger and longer storm.
However, while many have been predicting the birth of a new monetary system in the past decade, it is the nuances of Zoltan's vision of the monetary future that is especially troubling: as he puts it "we are witnessing the birth of Bretton Woods III - a new world (monetary) order centered around commodity-based currencies in the East that will likely weaken the Eurodollar system and also contribute to inflationary forces in the West."
"This Is Shocking": Quant Guru Calculates Fed Can Only Hike To 1% Before It Must Halt The Cycle
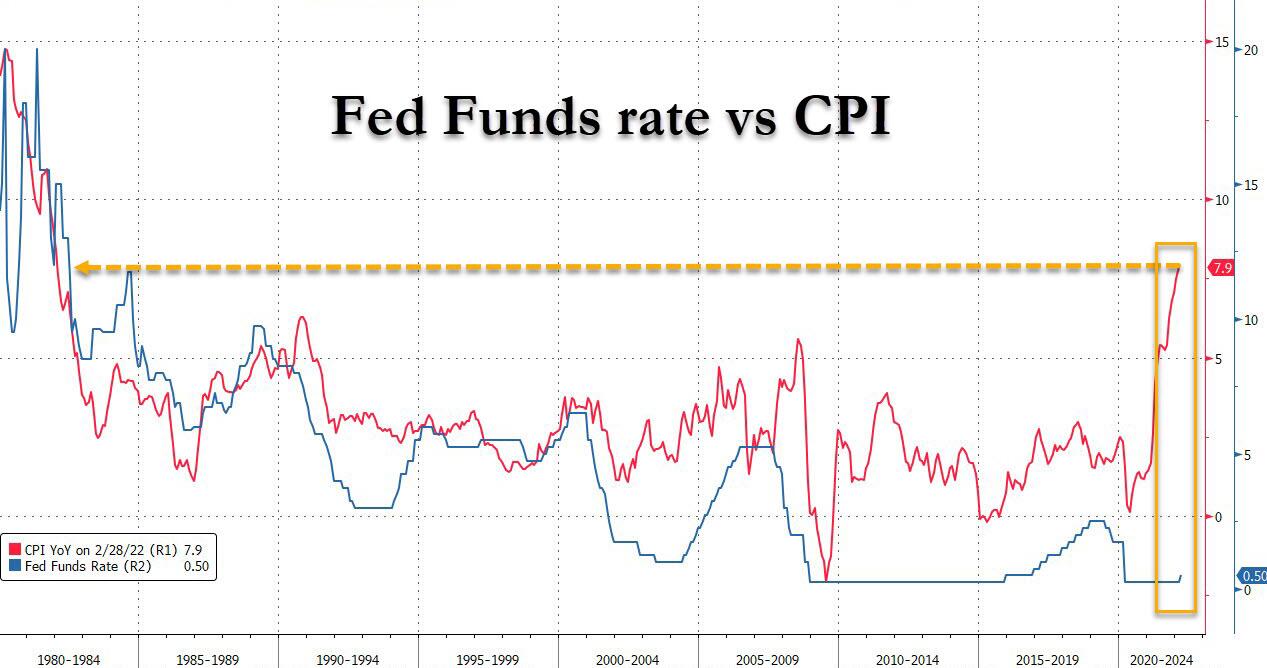
Earlier today, futures slumped to session lows (before an algo driven meltup sent stocks soaring to session highs) when the Fed's resident uberhawk and FOMC dissenter, James Bullard, poured more overpriced gasoline on the tightening fire when he said that “the current policy rate is too low by about 300 basis points" according to a version of the Taylor rule which showed that the Fed has a long way to go to catch up to where it should be if, somewhere around 3.5%, it has any hopes of denting runaway inflation around 8%, which as shown below sounds about right considering the last time inflation was here, the fed funds rate was 12%.
While Bullard's comments were not surprising - we already knew that he had dissented in favor of a 50bps rate hikes in March - comments by Lael Brainard, regarded as the most dovish of all Fed Governors, shocked the markets on Tuesday when she highlighted the likelihood the Fed will undertake a more rapid shrinkage of its balance sheet than markets were expecting.
Here, one obvious question is whether the Fed can hike anywhere close to 12% - or even 3.5% - without crashing the entire financial system. Another question is whether the Taylor rule is applicable in such a unique situation where not only are rates still at rock bottom but the Fed has some $9 trillion in securities on its balance sheet. Indeed, while the prevailing hawkishness across the FOMC means monetary policy will be tightened faster than expected, a third question is how much faster, or in other words, "what is the trade-off between QT and higher Fed Funds? Surely the faster the balance sheet is shrunk, the fewer rises will be needed in Fed Funds."
According to at least one Wall Street strategist, the answer to these questions is also the reason why the Fed Funds rate won't climb beyond 1.0%!
We refer to SocGen's resident permaskeptic, Albert Edwards, who today writes that "the prospect of the Fed engaging in rapid balance sheet shrinkage (QT) has spooked the markets." But, as we muse above, how does one combine the concurrent impact of QT with the Fed Fund hikes to get a handle on where Fed Funds might peak?
Well, Edwards believes he may have the answer, or rather he says that his "learned colleague", SocGen's in house quant guru Solomon Tadesse has an answer. While few in the mainstream have ever heard of Solomon, back in mid-2018, not long before the Fed's rate hike plans blew up spectacularly, the SocGen quant made waves on Wall Street trading desks when he went against the consensus view, and in May 2018 pinpointed the peak in Fed Funds at a lowly 2½%. He was absolutely spot on.
The problem: his latest analysis for this cycle puts the peak of the Fed Funds at just below 1.0%, or less than 3 more rate hikes before the Fed is forced to reverse! That, as Edwards notes, "is so far away from the current consensus that it deserves some serious analysis."
* * *
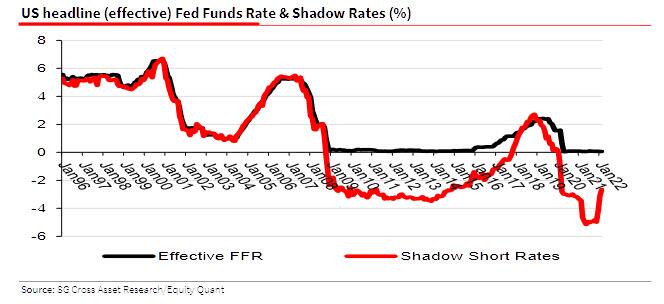
First, for those curious about the details some background: Solomon’s explanation of the first generation Shadow FFR based on Wu and Xia (2016) and his second generation estimate from De Rezende and Ristiniemi (2020) are in this note here. For those pressed for time, what the analysis says is that the pace of QE or QT can be combined with the headline Fed Funds rate to calculate a Shadow FFR.
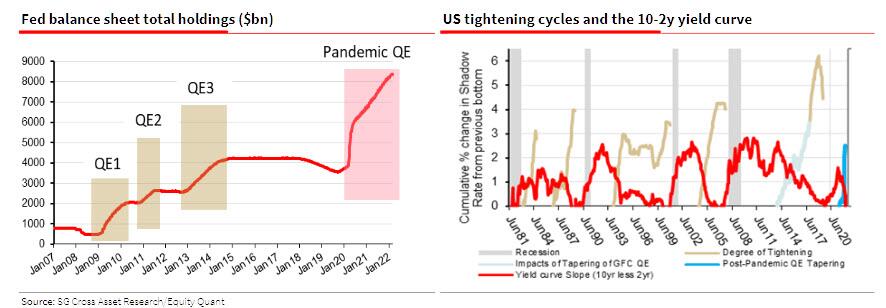
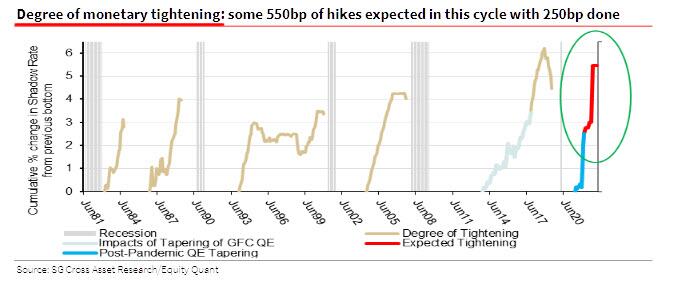
So combining the expansion of the Fed’s balance sheet from sub-$4 trillion at end 2018 to almost $9 trillion was the equivalent of the FFR falling to minus 5% (charts below)! But now that the Fed has reveresed, ending QE combined with just one ¼% hike in the headline FFR means the Shadow FFR has already jumped from minus 5% to minus 2.5% – a 250bp hike (blue line below).
We now take a brief tour down memory lane to remind readers how when Solomon made his mid-May 2018 call that the FFR would peak at 2½%, the market was looking at something nearer 3% (see chart below). Not much difference you might think, but as the Fed enacted its final hike to 2½% in Dec 2018, expectations of easing were rapidly taking hold as investors realized that the Fed had clearly overdone the tightening cycle (as we had said previously, the Ghost of 1937 has emerged right on schedule and the Fed has overtightened) even though just back in October 2018, Powell said that "we are a long way from neutral."
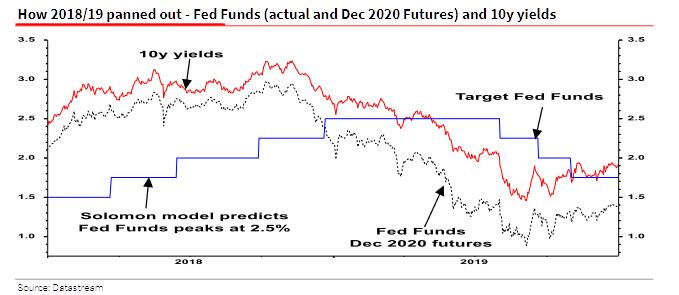
Meanwhile, as Edwards reminds us, the US bond rally from mid-Nov 2018 onwards was typical of the situation when yields tend to peak before the last rate hike. By comparison, currently the market expects the Fed to tighten rates rapidly and the peak in the FFR to be close to 3½% by March 2023.
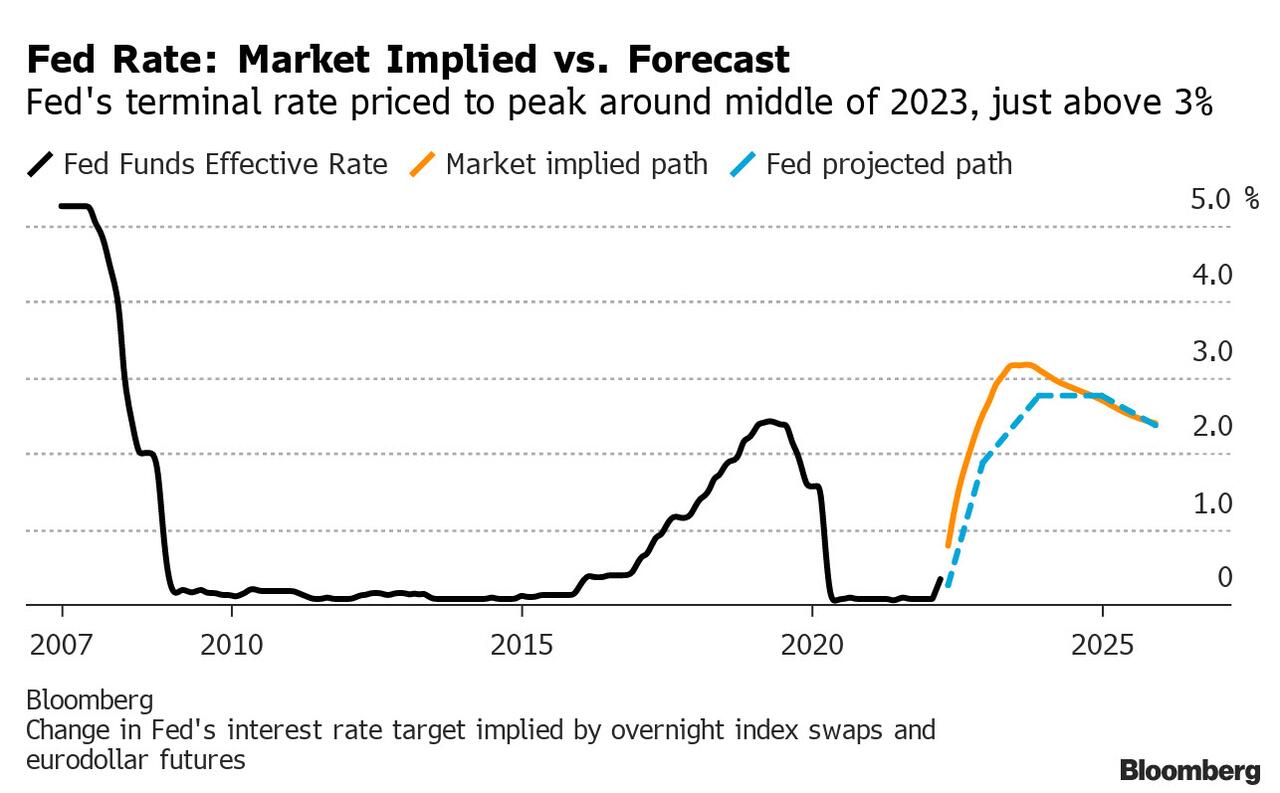
On that basis, you should wait until the back end of this year before dipping your toe into the bond market. But with inflation considered rampant, many investors believe the headline FFR will peak nearer 4%, despite recession fears mounting, and earlier this week, Deutsche Bank became the first large broker to forecast a US recession.
Needless to say with market consensus expecting rates to rise as high as 3% before the Fed starts cutting around the next recession, if Solomon is right that the Fed will struggle to raise FFR to 1% or above, this is a huge divergence with consensus. One can see clearly in Solomon’s chart below how the recent 250bp Shadow FFR hike compares to the cumulative easing and tightening in previous Fed cycles:
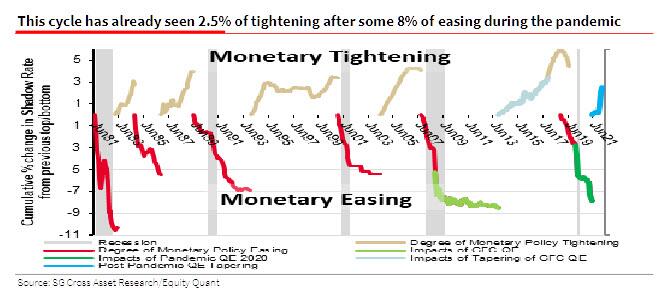
As depicted in the chart above, Solomon constructs a Monetary Tightening to Easing ratio (MTE, the ratio of the degree of tightening to the degree of easing in the preceding cycle). The charts below show how the MTE ratio declined in the 1980s as disinflation became the dominant theme. Hence since the mid-1980s the tightening cycle has topped out at around 70% of the previous easing cycle. But shouldn’t this ratio now return to 1.5x given CPI inflation has comprehensively overshot, Edwards asks and answers: Maybe...
You see, the main reason why Solomon’s MTE ratio has been consistently lower (at 70%) recently is that tightening cycles have been halted because financial market bubbles, created by excessive Fed easing, then blow up and prevent the Fed from further tightening. Another way of visualizing this is the infamous chart showing that every Fed tightening cycle ends in crisis (and this one will be no different);
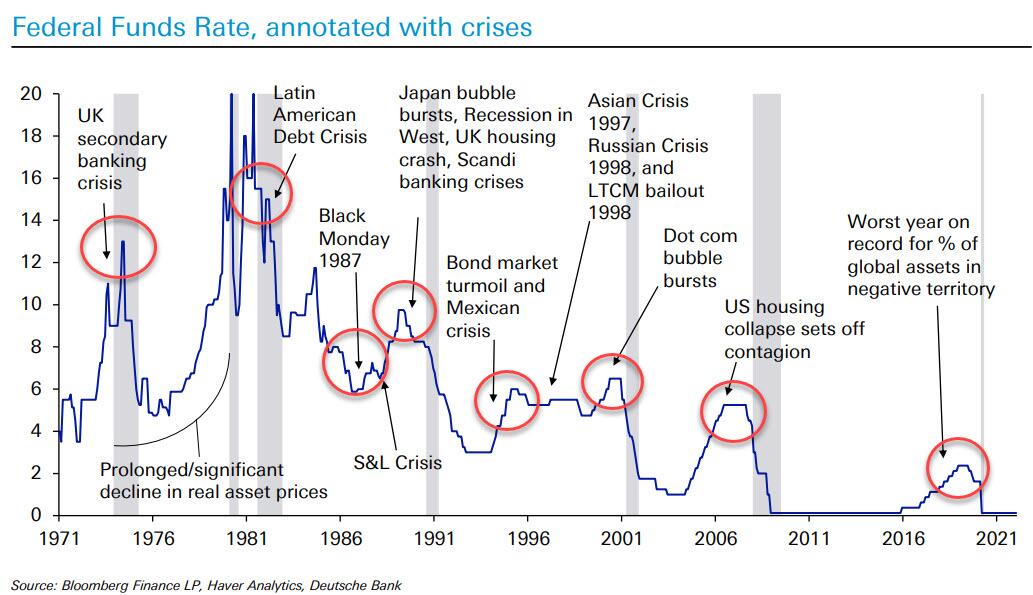
So putting it all together, if we take the 70% MTE ratio above, Solomon calculates that the Shadow FFR will likely top out with 550bp of tightening (70% of the 800bp easing), and even though the Fed will fail to tame inflation the crash in markets and the recession (or depression) that will hit the hyperfinancialized US economy, with its 6.3x financial assets to GDP...
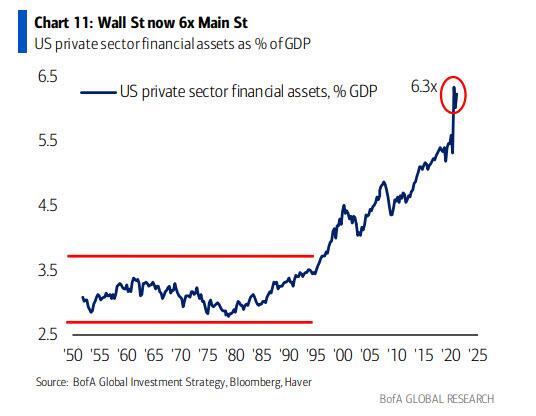
... will force the Fed to not only end tightening early but to rush into an easing cycle
The final point: prior to Lael Brainard’s comments, the remaining 300bp hike in the Shadow FFR was split between a headline FFR rise to only 1½% with the remainder being QT. But now that the Fed minutes confirmed that the pace of QT will accelerate accelerate to $95BN (or more) per month, Edwards concludes that "the actual FFR will struggle to get to 1% before the Fed needs to halt the tightening cycle. That is shocking."
The full notes, both Edwards and Solomon's are available to pro subs in the usual place.
As Bitcoin Market Expands, Demand for Regulatory Guidance Grows
Without clear regulatory standards, how crypto firms determine and manage their compliance risks and processes are a key business strategy, panelists said at the Bitcoin 2022 conference
MIAMI BEACH, Fla.—Increased regulatory guidance is crucial to the continuing growth of the cryptocurrency sector in the U.S., said panelists Thursday at one of the largest bitcoin conferences of the year.
But uncertainty about how the U.S. will write its cryptocurrency regulation remains one of the top barriers for both crypto firms looking to enter the U.S. market and for digital assets seeking to attract institutional investors, according to Compliance & Regulation panelists at the Bitcoin 2022 conference in Miami Beach, Fla.
Without clear regulatory standards, the ways that crypto firms navigate their compliance risks and processes become a key business strategy, they said.
Blockchain analytics provider Elliptic Enterprises Ltd., which provides information that helps identify crypto-related criminal activity, has seen growing interest in its services and data from both crypto firms and traditional financial institutions, John Melican, the company’s chief of external affairs, said Thursday.
“That’s what we’re seeing and that’s what we’re building is the capacity to serve crypto at scale. And we’re building this capacity to bring in assets as quickly as they’re demanded because it’s an ever-changing environment,” Mr. Melican said.
Regulatory uncertainty in the U.S. has been the primary obstacle to greater acceptance of digital assets by institutional investors, according to Jeffrey Howard, head of North America business development and institutional sales at brokerage firm OSL.
President Biden last month signed an executive order that directed federal agencies to report on digital currencies and consider new regulations. Many in the crypto world see it as a change to a more neutral attitude toward cryptocurrency.
“I think the executive order was a step in the right direction,” Mr. Howard said. “I think they’re trying to do it the right way and I think over time they will…As painful as it is, I think over time if they get it right, it’ll be a good thing for the industry.”
Crypto companies are dealing with various federal and state regulators that often compete with each other to rein in the digital-asset market, said Hailey Lennon, a partner at law firm Anderson Kill PC who specializes in regulatory compliance. She said the various hoops crypto firms need to jump through from both state and federal regulators can sometimes discourage crypto firms from entering the U.S. market.
“I think we’re going to see that regulators become a lot more active in this space because even [Senator Elizabeth] Warren and individuals in the government have said, ‘Hey, you don’t need to wait ‘til there’s collaboration among all these different regulators. Your purpose is to protect consumers, and you all receive a lot of complaints about bitcoin and crypto, go do something,’” Ms. Lennon said.
Lacking guidance, each crypto firm has had to determine its own risk appetite, according to Simon Douyer, the chief operating officer of cryptocurrency trading service firm SheeldMarket. These include direct risks, such as determining if a crypto transaction is connected to addresses under sanctions or derived from illegal activities, and indirect risks that may derive from business clients, he said.
“The issue really is about the threshold,” he said. “Where do you put your risk threshold?”
“And this gray area here is really, it’s everyone’s secret sauce,” Mr. Douyer said. “You just know where you put your risk threshold and right away just decide to say, ‘Okay. I’m going to accept these funds.’”
These comments came as Treasury Secretary Janet Yellen on Thursday provided insight into how the federal government views digital assets, saying that the design and development of a digital dollar would likely take years if the U.S. chose to create one. She also outlined the various questions the Biden administration is weighing as it considers ways to make payments faster in the U.S.
Peter Thiel claims ‘finance gerontocracy’ is holding back bitcoin
PayPal founder attacks Warren Buffett as he touts crypto’s ‘revolutionary youth movement’ in Miami
Peter Thiel, the libertarian tech investor, challenged some of the most powerful US financial figures on Thursday over their criticism of bitcoin, accusing them of trying to suppress what has become a powerful political movement.
Thiel, who made his name as an outspoken contrarian and early investor in Facebook, dismissed revered investor Warren Buffett as a “sociopathic grandpa from Omaha”. He also cast Jamie Dimon, chief executive of JPMorgan Chase, and Larry Fink, head of BlackRock, as part of a “finance gerontocracy” that was looking to lock cryptocurrencies out of the mainstream.
His outburst came in front of a cheering crowd at the Bitcoin 2022 conference in Miami, where he described the cryptocurrency as part of a “revolutionary youth movement” that was out to overturn traditional finance, threatening the power and wealth of the establishment.
Thiel, one of the founders of PayPal, has long argued that digital currencies could supplant the current financial system. PayPal gave up on its own digital currency ambitions early in its existence to fit into the existing payments world. While it is now worth $130bn, Thiel described the online payments company as a disappointment compared with what it could have become.
By contrast, he claimed bitcoin, worth $830bn, had the potential to rival all the world’s gold, worth $13tn. With inflation rising and confidence in paper currencies declining, he also claimed that the value of bitcoin could match that of all public equities, which are currently worth $115tn, just as gold had matched equities at the end of the 1970s.
In an incendiary attack, he claimed that financial leaders had deliberately sought to suppress bitcoin to protect their own power. “It’s a movement, and it’s a political question whether this movement is going to succeed, or whether the enemies of the movement are going to succeed in stopping us,” he said. Buffett, he added, was “enemy number one”.
Thiel became the tech world’s most famous rightwing figure in 2016 when he backed Donald Trump’s presidential run and spoke at the Republican convention that year.
On Thursday, he lashed out at the fashion for environmental, social and governance investing, depicting it as a core part of the system the financial establishment uses to squash anything that threatens its power.
ESG has become a “hate factory for naming enemies”, he claimed, comparing the focus on social and governance issues to the way the Chinese Communist party operates. He also dismissed environmental investing as “sort of fake”.
In a sideswipe at companies that responded to pressure from politicians or employees over political issues, he added: “Woke companies are quasi-controlled by the government in a way that bitcoin never will be.”
Porsche’s IPO shows old ties are loosening in corporate Germany
Until now, excluding Deutsche Bank from a leading role in a blockbuster listing had been unthinkable
Germany doesn’t do glitzy initial public offerings. List on the Frankfurt Stock Exchange and you will get shots of executives posing awkwardly next to the city’s own bronze bull statue, but no fashion models and none of the over the top TV coverage enjoyed by New York market debutants.
Enter Porsche. Germany’s most coveted and profitable auto brand is — after much cajoling — being let loose on the market by its owner Volkswagen, with a partial flotation planned for the end of the year, the war in Ukraine permitting. The IPO will probably eclipse Deutsche Telekom’s record-breaking 1996 offering in terms of cash raised and any other German IPO in terms of media excitement.
Yet when a row of 911s parade through Germany’s financial capital ahead of the bell-ringing ceremony, bankers at the country’s largest lender will be looking on wistfully from their Frankfurt skyscraper. Neither Deutsche Bank, nor its European rivals Barclays and BNP Paribas, are taking a leading role in the IPO.
Instead, in what one industry observer described as a “slap in the face” for European investment banks, VW chose a US-only quartet of Goldman Sachs, Bank of America, JPMorgan and Citi to act as global co-ordinators.
There is of course nothing new about US banks encroaching on European territory. JPMorgan has acted as a bookrunner on 223 European IPOs with a combined deal value of more than $45bn since the 2008 financial crisis, according to data from Dealogic, while Deutsche Bank had 131 deals worth $28bn in its home region during the same period. But until now, excluding Deutsche Bank from a leading role in a blockbuster IPO had been unthinkable under corporate Germany’s omertà-like code of loyalty.
VW insists that the Americans simply did better in a meritocratic selection process, which involved bank bosses such as Deutsche Bank’s Christian Sewing recording video paeans to Porsche in an attempt to win the work.
Not all US pitches were successful either. Morgan Stanley, which refused to extend further credit to VW in the wake of the diesel emissions scandal, was among the banks that failed to win a top spot.
Plus, Deutsche Bank’s recent record in the auto sector is hardly stellar, having presided over the flotation of VW truck unit Traton in 2019, which languishes well below its listing price, and the IPO of Aston Martin, which remains a masterclass in value destruction.
Though VW’s complex ownership structure forces it to list Porsche in Frankfurt rather than the US, it has also been doing its best to convince investors that it is first and foremost a global — rather than a German — company and that it ought to attract US-style sticker prices as a result. One VW manager recently lamented that Rivian, which had not sold a single electric vehicle when it achieved a $66bn valuation last year, was deemed to be worth as much as two-thirds of VW, which sold 450,000 electric vehicles in 2021.
Still, the exclusion of Deutsche Bank, which has a former VW executive on its supervisory board, shows old ties count for less than they used to as European businesses race to tap the biggest capital market in the world.
“The US banks are just not standing still, while the Europeans are slow to move,” says Eriola Shehu Beetz, a partner at BCG who advises the industry. The lack of auxiliary services such as equities trading, which Deutsche Bank axed, had made European banks less attractive, she added. They also struggle to compete with their richer US rivals for the best staff.
Porsche has long said it would not build a factory in China, arguing that its customers were happy to pay for the “Made in Germany” tag. The same cannot be said for the country’s biggest investment bank.
European credit funds hit by outflows of almost €14bn in first quarter
Surging inflation stoked by the war in Ukraine has hurt the region’s corporate bond
Investors withdrew close to €14bn from European corporate debt funds in the first three months of the year, the worst quarter since the start of the pandemic, as the war in Ukraine fired up already rapid inflation and stirred market volatility.
So-called investment grade debt — at the safer end of the spectrum — lost 5.4 per cent for investors at the start of 2022; again, the worst since the darkest days of the Covid markets shock, while high-yield bonds lost 4.3 per cent. By contrast, US corporate debt markets are relatively serene.
The gap shows investors are braced for sanctions on Russia, particularly in energy, to hurt corporate Europe, with the added chance that a more restrictive stance from the region’s central bank could exacerbate recession risks.
“If there’s a place we don’t want to be right now, it’s [eurozone] credit,” said Florian Ielpo, multi-asset portfolio manager at Lombard Odier Investment Managers. Higher costs for companies and the possibility of rising interest rates are a troubling combination for the asset class, he said.
Russian president Vladimir Putin’s invasion of Ukraine has raised prices for food and fuel, sending annual consumer price inflation in the eurozone as high as 7.5 per cent. Economic growth forecasts have dropped, creating a dilemma for the European Central Bank, which is under pressure to pull back its ultra-loose monetary policy to dampen prices.
US corporate debt markets — which are less exposed than those in Europe to the war in Ukraine — have held up better, with the spread between the yield on high-yield bonds and US Treasuries well below any signal of distress.
But after a bumper 2021, “Europe has underperformed”, said Mike Scott, lead portfolio manager at Man GLG. “Cyclicals, industry, as well as single B credit and below . . . these are the areas of the market that have seen the greatest amount of pressure.”
In addition, market volatility has more or less stopped the flow of new risky corporate bonds in Europe. Markets had effectively closed to speculative issuers for almost five weeks because of the geopolitical turmoil.
Yet despite the outflows from funds and the slowdown in issuance — debt issuance by companies excluding banks stood at around half its 2021 level between January and mid-March this year — analysts say European companies are relatively well-positioned to cope with rising borrowing costs.
Companies spent much of the pandemic loading up on cheap debt and locking in longer-term repayment schedules, meaning rising interest rates are unlikely to be as damaging today as they have been in the past. “Near term speculative [refinancing] risk is limited,” said S&P Global, which notes that around 90 per cent of debt maturing through 2023 is investment-grade.
European high-yield default rates ticked up in March to end a run of 10 consecutive monthly declines. JPMorgan, for one, appears unfazed. Although investors are “concerned about macro risks to credit arising from monetary policy and geopolitics, they are also struggling to identify potential default candidates,” the bank said in a note.
Some higher-risk companies are slowly coming back to the market. German drug and agrochemical conglomerate Bayer late last month raised €1.3bn, with Italian bank Intesa Sanpaolo issuing €1bn of debt and Finnish nuclear power company Teollisuuden Voima raising €600mn.
The war in Europe and its effects on inflation and central bank policy have been largely priced in by investors, said Man GLG’s Scott. “I believe there is a window of opportunity for deals to start coming to the market,” he added. “But is the market ready? Unlikely.”
After Hours Summary: WDFC +10.6% up big on earnings; BIIB -1.7% as Medicare releases national policy on aducanumabAfter Hours Gainers:
Companies trading higher in after hours in reaction to earnings/guidance: WDFC +10.6%, NRIX +4.8% (also provides corporate update), PSFE +4.2% (reaffirms guidance for Q1 and FY22; also names new CEO), PSMT +2.3%, QDEL +0.3%
Companies trading higher in after hours in reaction to news: WOW +3.6% (co is exploring options including a sale, according to Bloomberg), GATO +2.9% (names new CEO; also announces record quarterly production), CRWD +2.8% (secures Provisional Authorization to Operate at Impact Level 4), BTAI +2.6% (enters into commercial supply agreement with Arx), DOMA +0.5% (CFO to depart), IIPR +0.1% (announces quarterly operating activity)
After Hours Losers:
Companies trading lower in after hours in reaction to earnings/guidance: None
Companies trading lower in after hours in reaction to news: HARP -11.6% (CMO departs), CWT -2.3% (to acquire Stroh's Water Company), CPT -1.8% (stock offering), BIIB -1.7% (Medicare releases national policy that limits coverage for aducanumab), NDAQ -0.5% (reports March 2022 metrics), LMT -0.1% (awarded $260 mln Navy contract)