FT : Italy lines up gas deal with Algeria in effort to cut dependence on Russia

Italy lines up gas deal with Algeria in effort to cut dependence on Russia
Mario Draghi aims to sign agreement to boost volumes on visit next week

Italian prime minister Mario Draghi will visit Algeria on Monday to sign a new gas supply deal, as Rome strives to reduce its dependence on Russian fuel following the invasion of Ukraine.

It is the latest in a series of moves made by European countries to secure alternative fuel sources as they seek to cut Russia off from the global economy in punishment for the war.

Italy buys about 30bn cubic meters of gas a year from Russia, 40 per cent of its total consumption. Algeria is Italy’s second-largest supplier, providing 21bn cubic metres a year — about 31 per cent of annual consumption.

An Italian government official said the Trans-Mediterranean pipeline — which carries gas from Algeria to Italy via Tunisia — is only operating at two-thirds of its capacity of 33bn cubic meters per year, giving Italy the scope to rapidly step up its purchases from Algeria.

“This can have an immediate impact — you don’t need to build more pipelines or other new infrastructure,” the official said.

A third of the Russian gas supplied to Italy each year could be replaced by quickly increasing imports from Algeria, the Italian official said.

Since the invasion of Ukraine, Draghi has stressed the need for Italy to urgently diversify its energy supplies, especially given the risk that Russia could retaliate against EU sanctions by shutting off the flow of gas to Europe.

“Diversification of our energy supplies is something to aim for regardless of what happens with Russian gas supplies in the immediate future,” Draghi told lawmakers last month. “We cannot be so dependent on the decisions of just one country, as this jeopardises our freedom, not just our prosperity.”

Last week, Lithuania became the first EU country to cut off Russian gas supplies completely, with the two other Baltic states also temporarily stopping its flow.

Recommended
War in Ukraine: free to read
‘There is nothing else out there’: why Europe is hooked on Russian gas

Germany has said it aims to be “virtually independent” from Russian oil by the end of this year and from gas by mid-2024. Berlin recently signed a long-term agreement with Qatar for the supply of liquefied natural gas (LNG), which Robert Habeck, economy minister, said would reduce its reliance on Russian supplies.

EU leaders last month decided to bulk buy natural gas jointly from other sources.

The Italian delegation led by Draghi on Monday will include foreign minister Luigi Di Maio and Roberto Cingolani, the minister for ecological transition, as well as the head of Eni, the Italian energy company, which has strong ties with Algerian energy company Sonatrach.

The Italian official said the deal would not only pave the way for increased purchases of Algerian gas but would also include an agreement on greater Italian investment in renewable energy in the north African country, which could help it cut down its own gas consumption, freeing up more for export.

Di Maio has visited several energy-producing nations in recent weeks and Cingolani has been working on how to speed up the development of renewable energy sources.

FT : Contrarian fund manager cautions against writing off Russia assets

Contrarian fund manager cautions against writing off Russia assets
Kopernik’s Dave Iben says Gazprom and Sberbank ‘still have a lot of value’

In the weeks after the invasion of Ukraine, most big asset managers rushed to write the value of their Russian holdings down to zero. With the stock market closed and sanctions imposed, investors were told to assume that billions of dollars in Russian assets had become essentially worthless.

Dave Iben, chief investment officer of Kopernik Global Investors, calls that caution a “marketing ploy” that understates Russia’s potential and penalises current investors in hope of juicing future returns.

Kopernik’s $7bn global value-oriented funds had roughly 14 per cent of their holdings in Russian companies before the invasion. Iben’s team has cut their valuation of stocks such as Gazprom, Sberbank and Polyus by an average of 70 per cent, rather than all the way to zero.

“Marking them to zero is unfair because it is likely these companies still have a lot of value,” he said. “If you mark it to zero, new people coming in to a fund get a bargain. Anybody leaving the fund is getting zero for something that probably is worth something,” he said.

His view stands in contrast to the practice at most big asset managers, who have opted to give investors all the potential bad news up front. Morgan Stanley, Goldman Sachs, BlackRock and Franklin Templeton all marked Gazprom shares down from above $4 to less than 10 cents, according to data from FactSet on the pricing of exchange traded funds. Sberbank shares have similarly been written down from $3.60 to no more than 2 cents.

Iben admitted there is a “real possibility” that sanctions or other government action will make it impossible for his investors to realise the value of their Russian equities. But he added: “It’s also highly possible that they’re not permanently lost.”

If the expected value was positive, it was not fair to price it below the expected price, he said. “Maybe it's a good marketing ploy, but it doesn’t seem fair to us,” he said.

Kopernik calculated that the invasion wiped about $700mn off the value of its Russian assets but funds have more than made up the losses through gains on its energy holdings elsewhere.

Challenging the crowd comes naturally to Iben and Kopernik. The fund is named after the Renaissance Polish astronomer better known as Copernicus, who punctured the orthodoxy that the sun orbited the earth.

Florida-based Kopernik looks for companies around the world that it believes are undervalued even after discounts are applied for political and economic instability. Before the invasion of Ukraine, its models applied a 50 per cent discount to Russian corporates and that may increase depending on the conditions under which the country rejoins the global financial system.

Roughly 30 per cent of the funds’ holdings are Canadian and just 4 per cent are American, Iben said. By comparison, its benchmark, MSCI All-World, is 61 per cent US.

“Everybody likes the really good franchises that have oligopolies and sell things people need. You pay a fortune for that in the US, but if you’re willing to own companies in Korea and Brazil, and of course Russia, China, Japan, places like that, you can get these really good companies for bargains.”

While many investors are pressing companies to pull out of Russia on moral grounds, Iben was as impatient with that argument as he is with calls to shun fossil fuels to speed the energy transition.

“Selling Gazprom would not hurt Russia in any way,” he said. “We all want less pollution and we all want peace in the world. Selling stocks mindlessly down 90 per cent is not a way to achieve those goals.”

FT : London house prices rise at fastest rate since 2016

London house prices rise at fastest rate since 2016
Property market bounces back as people return to the city for work and entertainment

The rise in London property prices has accelerated, driven by a shortage of supply and increased demand as people flocked back to offices and the social attractions of the capital.

The Covid pandemic has led to a housing boom across the country, but in London demand has been relatively muted due to reduced migration as home buyers looked for more space outside the city.

However, in the first quarter of this year, London house prices grew at an annual rate of 7.4 per cent, up from 4.8 per cent in the same period last year and the fastest rate since 2016, according to the mortgage provider Nationwide.

While the rate was still below the national average of 12.6 per cent, similar upward trends were reported in house prices compiled by Academetrics, Knight Frank and Halifax.


“The past two years have resulted in a loss of love for city centres such as London,” said Emma Cox, managing director of real estate at Shawbrook Bank.

“But as we see the city centre open their doors to businesses and hospitality . . . [these] hotspots once again are fast becoming an attractive place to be,” she added.

“Over the last few months, London has come back on the radar of buyers as the economy reopened,” said Tom Bill, head of UK residential research at Knight Frank.

The trend is echoed by other economic indicators. The average asking price of a London property up by an annual rate of more than 6 per cent, a reversal of the contraction that began in early 2021, according to the property website Rightmove.

The proportion of surveyors who expect house prices to rise in the capital was its highest since 2014, and greater than the national average for the first time since the crisis began, according to the Royal Institution of Chartered Surveyors, a professional body.


Rising demand has bumped against a shortage of London properties for sale. “The acute supply and demand imbalance across London has driven pricing and competitive bidding on properties,” said Angus Dixon, director of private clients at the property consultants INHOUS.

Activity is strongest among the most expensive properties where “buyers are less exposed to increased costs of living and costs of debt”, said Alec Harragin, a director at the London surveyor company Savills.

While John King, surveyor at Andrew Scott Robertson, confirmed that demand for houses in the £1mn-£2mn range “was the most active sector”.

Despite the pick-up, the London property market has been underperforming the national average since 2016 and still lags behind other regions in the UK.

A lack of foreign buyers still weighs on the capital’s housing market, according to Bill from Knight Frank, despite some improvements, adding that he expected it to underperform the national average in the months ahead.

Many experts warned that affordability was a longer lasting problem in the capital. Like the rest of the country, “concerns about interest rates, the economy and the war in Ukraine will be factors that could well dampen the market”, said Allan Fuller, of Allan Fuller Estate Agents in London.

FT : London house prices rise at fastest rate since 2016

London house prices rise at fastest rate since 2016
Property market bounces back as people return to the city for work and entertainment

The rise in London property prices has accelerated, driven by a shortage of supply and increased demand as people flocked back to offices and the social attractions of the capital.

The Covid pandemic has led to a housing boom across the country, but in London demand has been relatively muted due to reduced migration as home buyers looked for more space outside the city.

However, in the first quarter of this year, London house prices grew at an annual rate of 7.4 per cent, up from 4.8 per cent in the same period last year and the fastest rate since 2016, according to the mortgage provider Nationwide.

While the rate was still below the national average of 12.6 per cent, similar upward trends were reported in house prices compiled by Academetrics, Knight Frank and Halifax.


“The past two years have resulted in a loss of love for city centres such as London,” said Emma Cox, managing director of real estate at Shawbrook Bank.

“But as we see the city centre open their doors to businesses and hospitality . . . [these] hotspots once again are fast becoming an attractive place to be,” she added.

“Over the last few months, London has come back on the radar of buyers as the economy reopened,” said Tom Bill, head of UK residential research at Knight Frank.

The trend is echoed by other economic indicators. The average asking price of a London property up by an annual rate of more than 6 per cent, a reversal of the contraction that began in early 2021, according to the property website Rightmove.

The proportion of surveyors who expect house prices to rise in the capital was its highest since 2014, and greater than the national average for the first time since the crisis began, according to the Royal Institution of Chartered Surveyors, a professional body.


Rising demand has bumped against a shortage of London properties for sale. “The acute supply and demand imbalance across London has driven pricing and competitive bidding on properties,” said Angus Dixon, director of private clients at the property consultants INHOUS.

Activity is strongest among the most expensive properties where “buyers are less exposed to increased costs of living and costs of debt”, said Alec Harragin, a director at the London surveyor company Savills.

While John King, surveyor at Andrew Scott Robertson, confirmed that demand for houses in the £1mn-£2mn range “was the most active sector”.

Despite the pick-up, the London property market has been underperforming the national average since 2016 and still lags behind other regions in the UK.

A lack of foreign buyers still weighs on the capital’s housing market, according to Bill from Knight Frank, despite some improvements, adding that he expected it to underperform the national average in the months ahead.

Many experts warned that affordability was a longer lasting problem in the capital. Like the rest of the country, “concerns about interest rates, the economy and the war in Ukraine will be factors that could well dampen the market”, said Allan Fuller, of Allan Fuller Estate Agents in London.

TechCrunch : Inside Mercedes’ plan to deliver hands-free driving to the masses

Inside Mercedes’ plan to deliver hands-free driving to the masses
When it arrives in 2023, it will be limited.
Image Credits: Mercedes-Benz
I’m sitting in the passenger seat of a special Mercedes Benz S-Class on a blindingly bright California spring day, casually watching an autonomous delivery robot roll through a crosswalk on its way to deliver someone’s takeout meal in Santa Monica. The test driver next to me chuckles as we’re about to merge onto the highway for a demonstration of Mercedes’ Drive Pilot system, a conditional Level 3 automated driving system that consumers may be able to order by the end of this year.
Mercedes is aiming to be the first automaker to bring legal Level 3 automated driving off the test track to the masses in its full-size, luxury S-Class vehicles. The question is whether it should, especially considering the Everest-sized challenges that lay ahead — even if the economic opportunities include cornering a piece of the estimated $220.4 billion autonomous driving market.
The stakes are high, too. The Mercedes Level 3 system has to handle multiple tasks all at once, including recording and exchanging vast amounts of data and giving ample time and warnings for the human driver to take back control when something goes sideways. There are the legal risks that Mercedes has pledged it will take on when the system is engaged, and there are even geopolitical ones: Mercedes uses the Russian GLONASS system for its global positioning information in Germany, for instance.

And yet, Mercedes is plowing ahead despite the risks, because the opportunity is just too vast to ignore. While other manufacturers like Tesla claim to have fully autonomous driving systems, Mercedes is the first to pass the required legal hurdles in the U.S. and in Germany to offer the conditional system to consumers. While the timeline is a bit fuzzy because Mercedes is still working through those legal requirements, the system could be in consumers’ hands and their driveways as soon as mid-2023.
The technology

Image Credits: Abigail Bassett

In the trunk of one of the four development vehicles parked in the garage of the Proper Hotel in Santa Monica, sits a huge chassis of computer components. When we arrive, the trunk is open to let the components breathe, according to the test driver. There’s no room for your coveted golf bags or luggage here.
These components register, record, manage and upload as much as 2.87 GB of data per minute when the car is in regular operation. If an incident occurs while the vehicle is underway, say, for example, someone cuts off the development vehicle in traffic and forces a panic stop, the system takes in as much as 33.73 gigabytes of data so that engineers can take a closer look at what happened and improve the system.

Customers who own the S-Class vehicles equipped with the Drive Pilot system will not have to contend with computer components hogging up the trunk space. Instead, the vehicle will still b they will still be present in the cars so that the Level 3 system will work and be able to process and store large amounts of data. Some of that data will be kept on board, while much of it will be uploaded to a secure cloud system.
That data all comes from a variety of sensors around the vehicle, a few of which will be new to future S-Class vehicles that have been ordered with the new Drive Pilot system. While the company wouldn’t disclose specific costs of the system, representatives did say that it will cost as much as their top-of-the-line Burmester audio system. That audio system on the S-Class is a $6,700 option alone, yet requires the addition of a separate $3,800 package, bringing the rough total to around $10,500. That’s getting close to the cost of Tesla’s “Full-Self Driving” system, which currently is a $12,000 option.
The conditional Level 3 Drive Pilot system builds on the hardware and software used by Mercedes’ Level 2 ADAS system known as Distronic. It adds a handful of additional advanced sensors as well as software to support the features. Key hardware systems that will be added to future S-Class vehicles configured with the Drive Pilot upgrade include an advanced LiDAR system developed by Valeo SA, a wetness sensor in the wheel well to determine moisture on the road, rear-facing cameras and microphones to detect emergency vehicles, and a special antenna array located at the rear of the sunroof to help with precise GPS location.
The Valeo LiDAR system is more advanced than what is on the current generation of S-Class, in that it scans at a rate of 25 times per second at a range of 200 meters (approximately 650-plus feet). This is the second generation of the system, according to the Valeo spokesperson at the event. The system sends out lasers which then create points in space to help the AI classify the type of object in and around the path of the vehicle, whether its human, animal, vehicle, tree, or building. From there, the AI uses data from the other sensors around the car, to determine more than 400 different projected paths for both itself and the potential paths for the vehicles, pedestrians, and motorcyclists around it, and choose the safest route through.
The wetness sensor is a small round audio sensor positioned at the rear of the front driver wheel well and it determines how damp the road surface is. When the road is wet, droplets are thrown up against it creating an audible patter. When the system “hears” that patter, Drive Pilot will be disabled and the human in the driver seat will need to take over.
The antenna array on the roof of the S-Class uses a variety of different satellites to pinpoint the exact location of the vehicle within a few centimeters. It is precise enough to recognize which lane the vehicle is in on the highway. Mercedes says it relies on Galileo, and GPS in the U.S., and the Russian GLONASS system for this positioning information in Germany. These precise GPS points are integrated into an HD map which then helps the system navigate the real world.
These sensors are added to those already present in the Distronic system, which includes interior cameras to ensure that the driver is paying attention, as well as radar, ultrasonic, and 3D cameras outside. The added hardware is there to ensure that each system has redundancy and provides a more accurate view of both the interior and exterior of the vehicle as the system navigates the environment and, unlike the Tesla system, ensures that the driver is actually paying attention and not sleeping or watching a movie while operating the system.
There ‘s a reason for all of this precise and specialized equipment. Mercedes-Benz has taken on the responsibility, including the liability, for the safe operation of the system. The legal ramifications could be immense should something go wrong and a crash occur while the system is in use by a consumer.
New rules for Level 3 operation
Mercedes has used vehicles just like this one to test its Drive Pilot on more than 50,000 miles of roads in California and Nevada, where the company currently has conditional licenses to run the system.
Once the legal hurdles are passed, which Mercedes says it expects to happen by the end of the year, the systems will be available on properly equipped S-Class vehicles, when driven in specific conditions. However, it will still be limited.
The system will only be available in states where it’s legal (California, Nevada, and Florida currently). Cross the border into say, Arizona or Utah with an S-Class equipped with Drive Pilot, and the system will not be available. It’s geo-fenced.
In addition to the state location, the system won’t engage unless the vehicle is on clearly marked, divided highways, freeways, or interstates driving in a traveling lane, not in an exit lane. While out on our drive, the test driver moved over to take an exit, and the system turned off and requested that he take over as soon as he indicated that he was changing lanes.
And even when all of these requirements are met, the system is only available up to speeds of 40 mph (60 kmh).
The ride

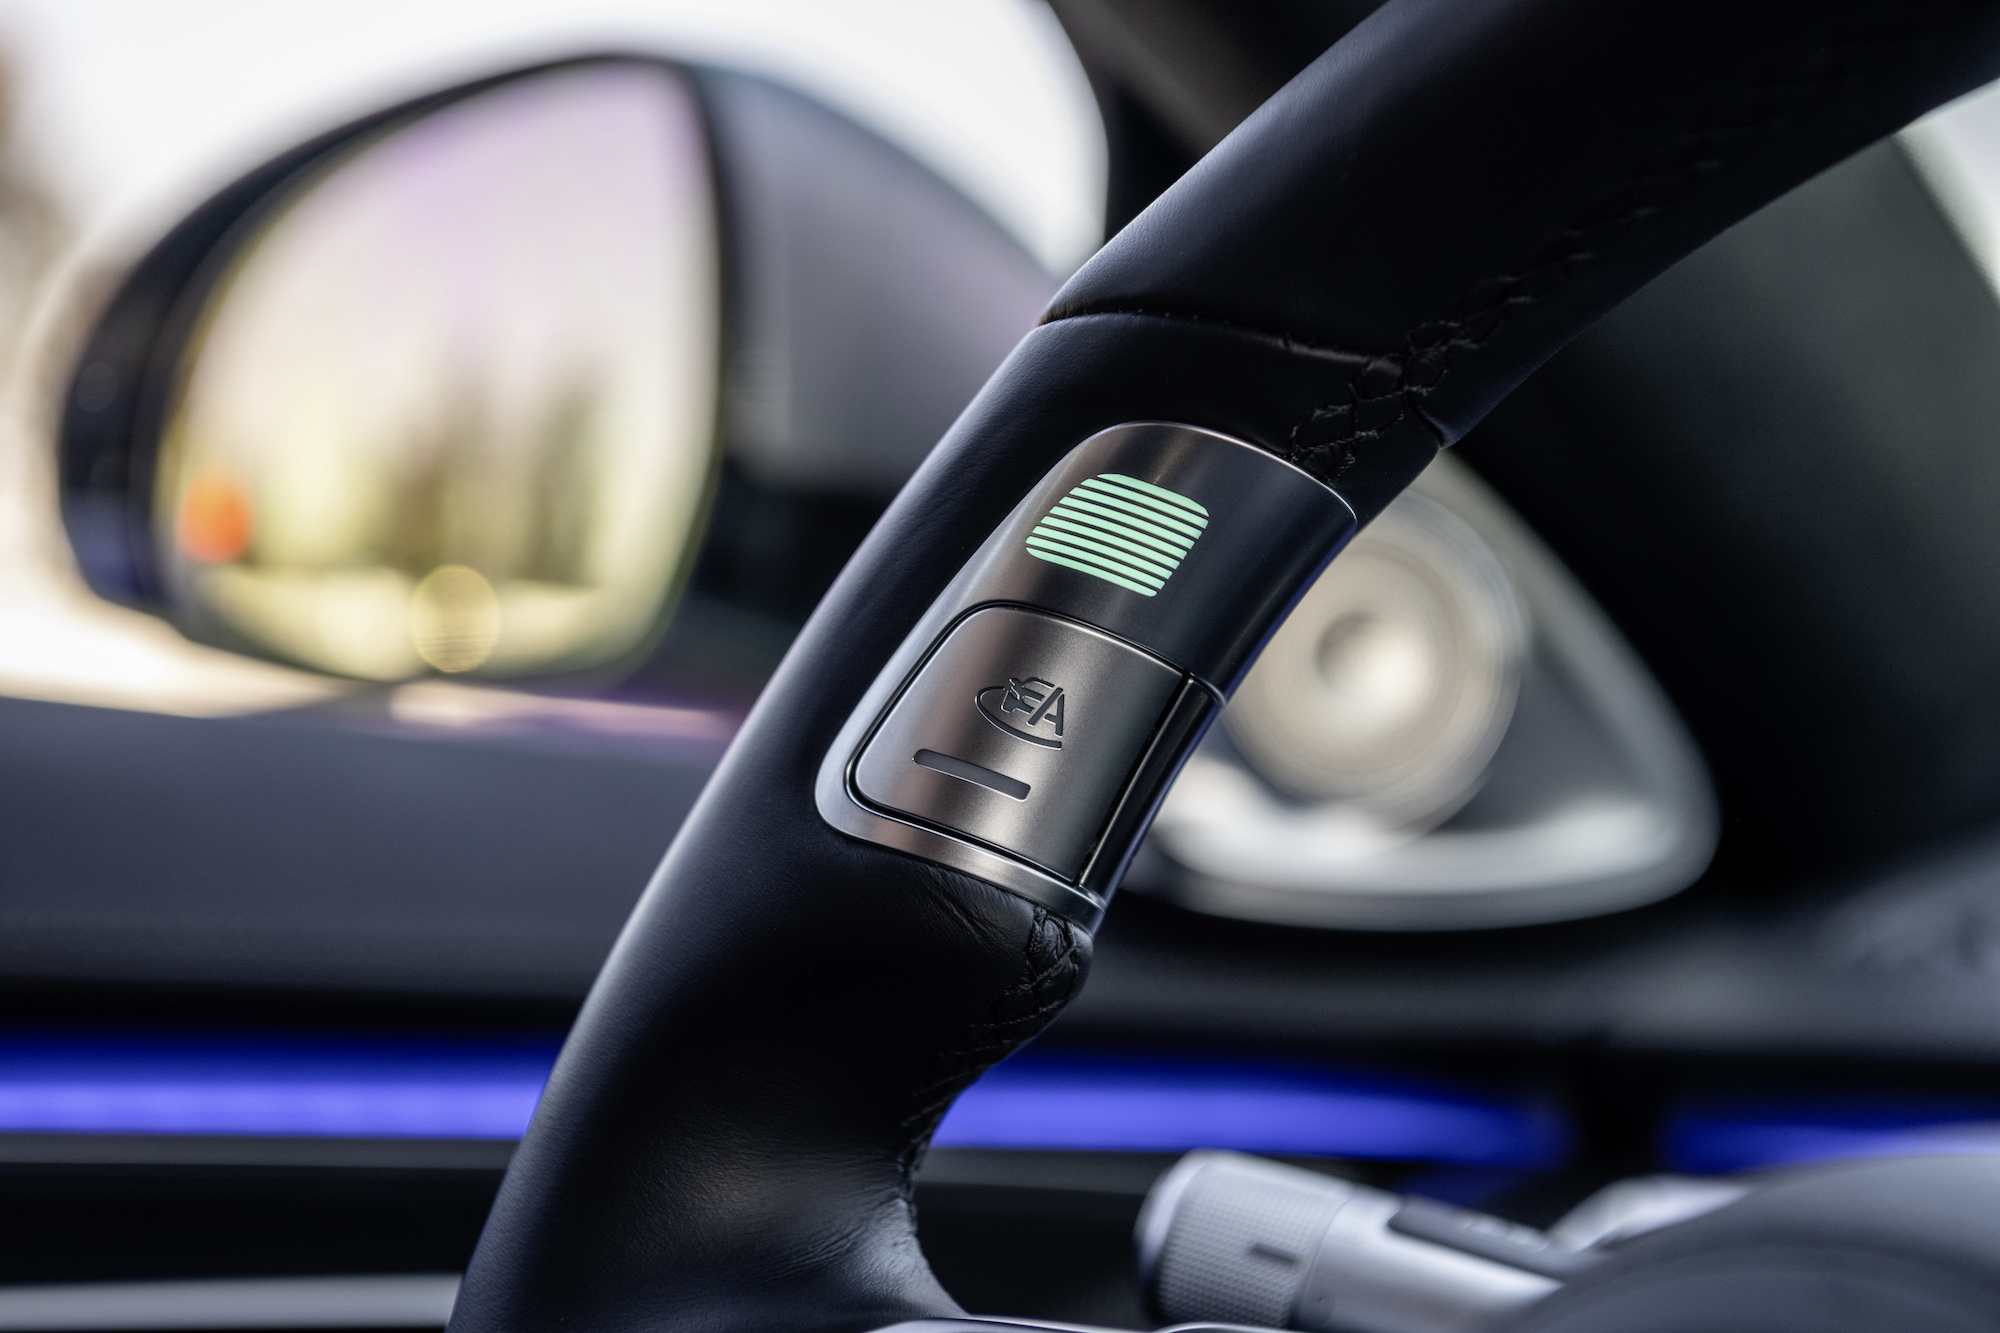
When DRIVE PILOT is activated, the controls in the steering wheel glow turquoise. Image: Mercedes-Benz

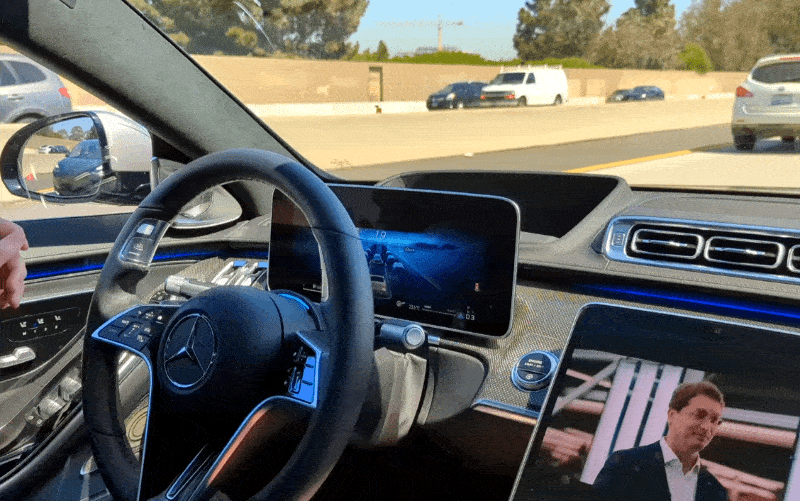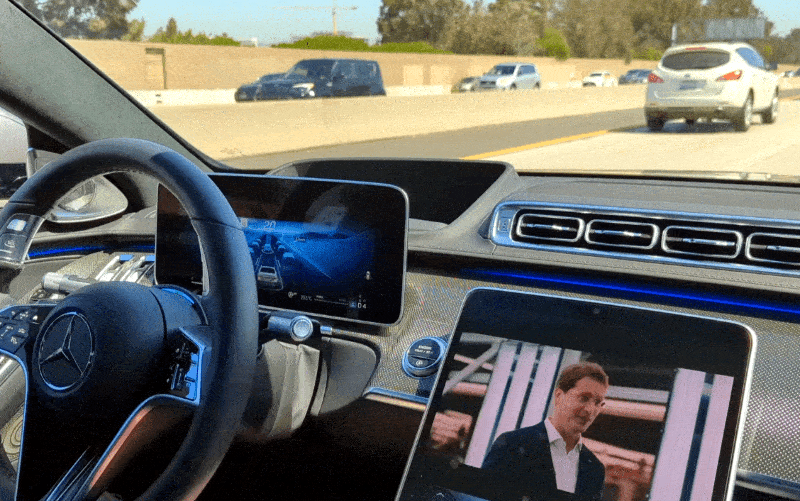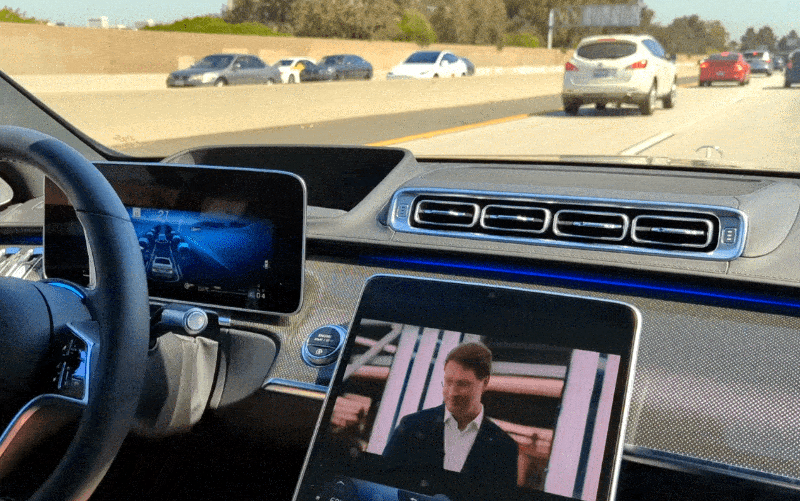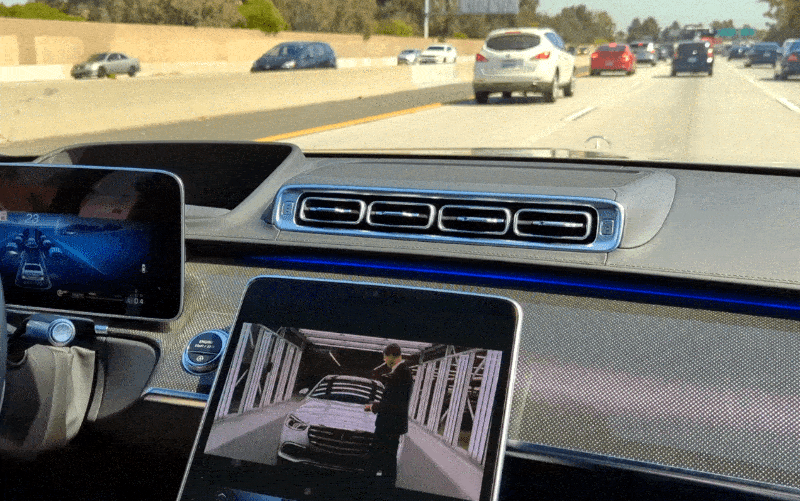
Inside, the vehicle looks almost identical to an S-Class with one key difference: On the steering wheel sits a pair of buttons that fall directly under the driver’s thumbs. These buttons, engraved with the image of the front of a car with the letter ‘A’ over the top, are used to initiate the Level 3 system when the external conditions are met. Lighting around the buttons and on the steering column turns white when the system is available, and green-blue when it is engaged.
Our short ride took us down the 10 freeway in Los Angeles towards downtown LA and back to Santa Monica. Traffic was heavy stop-and-go, and there were plenty of opportunities for the system to fail. Within the first few minutes on the freeway, we encountered various road obstacles like plastic bags, cardboard boxes and more than one oblivious Angeleno making panic stops and randomly cutting into our lane of travel.
In the short periods where the system was available when all conditions were met, its operating appeared to be seamless. The handover was smooth and almost unnoticeable. The driver engaged the system, took his hands and feet off the controls, and let the car drive itself, all while keeping his attention on the road ahead.
The system uses maximum following distance when it’s engaged, so the gap was quite large between the S-class and the car ahead. Surprisingly, and sadly, no one decided to jump into that gap while the system was engaged, so we didn’t get to experience what might happen if a human made a sudden lane change in front of the car while operating the conditional Level 3 system. When the system lost the needed information, say when the lane markers (known sometimes as oreos), became faint, an audible tone would sound, and a message would appear for the driver to take over. At that point, the test driver would take control of the vehicle.
All in, the system was only engaged for maybe 10 minutes in total over our 30-minute ride. Each engagement was relatively short as traffic sped up to over 40 mph, or the system lost the required information to manage the driving. The very short ride along didn’t give us enough time to evaluate the system, but it did offer a glimpse of just how Level 3 autonomy may work in the very near future. The real question, however, is how the system will behave in customers’ hands, and whether or not, even the very well-off, will purchase the technology.

>>> Objects Of Desire: Record-Breaking Auction Sales In 2021

Objects Of Desire: Record-Breaking Auction Sales In 2021

2021 may have been the year of the NFT, but, as Visual Capitalist's Marcus Lu and Rosey Eason detail below, wealthy collectors still dropped plenty of cash on physical objects. This included the usual items like paintings and cars, as well as some more obscure ones like meteorites.
To gain insight into the world of rare collectibles, this infographic summarizes the biggest auction sales of 2021, spread across 12 different item categories.
The Numbers
The key details of these sales are listed below in tabular format. Some broke all-time records, while others set the record for 2021 specifically.
The Details
Here are some interesting facts and details about these rare collectibles, starting with:
Pablo Picasso’s Femme assise près d’une fenêtre (Marie-Thérèse)
This 1932 painting is a depiction of Picasso’s lover, Marie-Thérèse Walter (1909-1977). Walter is believed to have had a significant impact on Picasso’s work, and the pair had a child out-of-wedlock in 1935.
He loved the blondeness of her hair, her luminous complexion, her sculptural body.
– BRASSAÏ
Sold by Christie’s in New York, this was the first painting to auction for over $100 million in nearly two years. The all-time record holder is Leonardo da Vinci’s Salvator Mundi, which sold for $450 million in 2016 to Mohammed Bin Salman, the Crown Prince of Saudi Arabia.
1995 McLaren F1
Produced between 1992 and 1998, the McLaren F1 is widely regarded as one of the most desirable supercars in the world. It features many innovations that are still rare in modern road cars, including a carbon fiber monocoque (the main structure of the car), active aerodynamics on the underbody, and a centered driving position.
The F1’s legacy is cemented by the fact that only 106 were ever produced, many of which have been owned by celebrities. That includes Elon Musk, who famously crashed his F1 in 2000 without insurance.
The specific car highlighted above was sold by Gooding & Company, a classic car auction company. It has just 242 miles (390 km) on the clock, which translates to an average of 9.3 miles (15 km) being driven on the road per year.
1933 Double Eagle Coin
The 1933 Double Eagle is one of the last $20 gold coins ever produced in the United States. It dates back to an era when the U.S. dollar’s value was tied to gold, which is a system known as the gold standard. The coins were melted down when the U.S. transitioned to fiat money, and only 13 examples are known to exist today.
After selling for $18.9 million, this Double Eagle holds the title as the most valuable rare coin in the world.
The Revolver Used to Kill Billy the Kid
The Colt single-action revolver that was used to kill Billy the Kid is now the most expensive firearm ever sold at an auction. It belonged to Sheriff Pat Garrett, who killed Billy in 1881.
Billy is one of the most notorious figures from America’s wild west era and was responsible for the deaths of eight men, including two sheriff’s deputies during an escape from jail.
Because of Billy’s legacy, this revolver is lauded as one of the most desirable Western firearms in existence. Surprisingly, it was the gun’s first appearance in a public auction.
Final Text of the United States Constitution
This first-edition copy of the U.S. constitution is an incredibly rare and historically significant artifact. The story of how it sold is equally as impressive.
Bidding came down to two parties, one of which was Ken Griffin, billionaire CEO of Citadel. If you’re an investor, that name may sound familiar—Citadel was a hedge fund involved in the r/wallstreetbets saga of 2021.
The other party was ConstitutionDAO, a group of 17,000+ crypto investors who pooled together $47 million worth of Ethereum. The term “DAO” refers to a decentralized autonomous organization, which is an online entity that’s collectively owned by its members without centralized leadership—and that takes action based on transparent rules set on a public blockchain.
In the end, the copy was sold to Griffin for a total of $43.2 million. Organizers of ConstitutionDAO could not place a higher bid because they wouldn’t have had enough money to insure, store, and transport the document.
About Those NFTs…
NFTs only exist in the digital realm, but they’ve quickly become some of the world’s most valuable collectibles. How valuable, you may ask?
For starters, consider the $7.6 million sale of CryptoPunk #3100, a profile picture (PFP) NFT that depicts a blue zombie. Then there’s The Merge, a digital artwork comprised of 312,686 pieces. In December 2021, it was sold to a collective of 28,983 buyers who, altogether, paid $91.8 million.
All of this hype has led some of the world’s oldest auction houses to begin selling NFTs through online events. This includes Christie’s (founded in 1766), which surpassed $100 million in NFT auction sales in less than a year.
Whether this momentum can carry forward is questionable. Interest in NFTs has plummeted, and crypto markets remain incredibly volatile.

(ZH) The Commodity-Currency Revolution Begins...

The Commodity-Currency Revolution Begins...

We will look back at current events and realise that they marked the change from a dollar-based global economy underwritten by financial assets to commodity-backed currencies. We face a change from collateral being purely financial in nature to becoming commodity based. It is collateral that underwrites the whole financial system.
The ending of the financially based system is being hastened by geopolitical developments. The West is desperately trying to sanction Russia into economic submission, but is only succeeding in driving up energy, commodity, and food prices against itself. Central banks will have no option but to inflate their currencies to pay for it all. Russia is linking the rouble to commodity prices through a moving gold peg instead, and China has already demonstrated an understanding of the West’s inflationary game by having stockpiled commodities and essential grains for the last two years and allowed her currency to rise against the dollar.
China and Russia are not going down the path of the West’s inflating currencies. Instead, they are moving towards a sounder money strategy with the prospect of stable interest rates and prices while the West accelerates in the opposite direction.
The Credit Suisse analyst, Zoltan Pozsar, calls it Bretton Woods III. This article looks at how it is likely to play out, concluding that the dollar and Western currencies, not the rouble, will have the greatest difficulty dealing with the end of fifty years of economic financialisation.
Pure finance is being replaced with commodity finance
It hasn’t hit the main-stream media yet, which is still reporting yesterday’s battle. But in March, the US Administration passed a death sentence on its own hegemony in a last desperate throw of the dollar dice. Not only did it misread the Russian situation with respect to its economy, but America mistakenly believed in its own power by sanctioning Russia and Putin’s oligarchs.
It may have achieved a partial blockade on Russia’s export volumes, but compensation has come from higher unit prices, benefiting Russia, and costing the Western alliance.
The consequence is a final battle in the financial war which has been brewing for decades. You do not sanction the world’s most important source of energy exports and the marginal supplier of a wide range of commodities and raw materials, including grains and fertilisers, without damaging everyone but the intended target. Worse still, the intended target has in China an extremely powerful friend, with which Russia is a partner in the world’s largest economic bloc — the Shanghai Cooperation Organisation — commanding a developing market of over 40% of the world’s population. That is the future, not the past: the past is Western wokery, punitive taxation, economies dominated by the state and its bureaucracy, anti-capitalistic socialism, and magic money trees to help pay for it all.
Despite this enormous hole in the sanctions net, the West has given itself no political option but to attempt to tighten sanctions even more. But Russia’s response is devastating for the western financial system. In two simple announcements, tying the rouble to gold for domestic credit institutions and insisting that payments for energy will only be accepted in roubles, it is calling an end to the fiat dollar era that has ruled the world from the suspension of Bretton Woods in 1971 to today.
Just over five decades ago, the dollar took over the role for itself as the global reserve asset from gold. After the seventies, which was a decade of currency, interest rate, and financial asset volatility, we all settled down into a world of increasing financialisation. London’s big bang in the early 1980s paved the way for regulated derivatives and the 1990s saw the rise of hedge funds and dotcoms. That was followed by an explosion in over-the-counter unregulated derivatives into the hundreds of trillions and securitisations which hit the speed-bump of the Lehman failure. Since then, the expansion of global credit for purely financial activities has been remarkable creating a financial asset bubble to rival anything seen in the history of financial excesses. And together with statistical suppression of the effect on consumer prices the switch of economic resources from Main Street to Wall Street has hidden the inflationary evidence of credit expansion from the public’s gaze.
All that is coming to an end with a new commoditisation — what respected flows analyst Zoltan Pozsar at Credit Suisse calls Bretton Woods III. In his enumeration the first was suspended by President Nixon in 1971, and the second ran from then until now when the dollar has ruled indisputably. That brings us to Bretton Woods III.
Russia’s insistence that importers of its energy pay in roubles and not in dollars or euros is a significant development, a direct challenge to the dollar’s role. There are no options for Russia’s “unfriendlies”, Russia’s description for the alliance united against it. The EU, which is the largest importer of Russian natural gas, either bites the bullet or scrambles for insufficient alternatives. The option is to buy natural gas and oil at reasonable rouble prices or drive prices up in euros and still not get enough to keep their economies going and the citizens warm and mobile. Either way, it seems Russia wins, and one way the EU loses.
As to Pozsar’s belief that we are on the verge of Bretton Woods III, one can see the logic of his argument. The highly inflated financial bubble marks the end of an era, fifty years in the making. Negative interest rates in the EU and Japan are not just an anomaly, but the last throw of the dice for the yen and the euro. The ECB and the Bank of Japan have bond portfolios which have wiped out their equity, and then some. All Western central banks which have indulged in QE have the same problem. Contrastingly, the Russian central bank and the Peoples Bank of China have not conducted any QE and have clean balance sheets. Rising interest rates in Western currencies are made more certain and their height even greater by Russia’s aggressive response to Western sanctions. It hastens the bankruptcy of the entire Western banking system and by bursting the highly inflated financial bubble will leave little more than hollowed-out economies.
Putin has taken as his model the 1973 Nixon/Kissinger agreement with the Saudis to only accept US dollars in payment for oil, and to use its dominant role in OPEC to force other members to follow suit. As the World’s largest energy exporter Russia now says she will only accept roubles, repeating for the rouble the petrodollar strategy. And even Saudi Arabia is now bending with the wind and accepting China’s renminbi for its oil, calling symbolic time on the Nixon/Kissinger petrodollar agreement.
The West, by which we mean America, the EU, Britain, Japan, South Korea, and a few others have set themselves up to be the fall guys. That statement barely describes the strategic stupidity — an Ignoble Award is closer to the truth. By phasing out fossil fuels before they could be replaced entirely with green energy sources, an enormous shortfall in energy supplies has arisen. With an almost religious zeal, Germany has been cutting out nuclear generation. And even as recently as last month it still ruled out extending the lifespan of its nuclear facilities. The entire G7 membership were not only unprepared for Russia turning the tables on its members, but so far, they have yet to come up with an adequate response.
Russia has effectively commoditised its currency, particularly for energy, gold, and food. It is following China down a similar path. In doing so it has undermined the dollar’s hegemony, perhaps fatally. As the driving force behind currency values, commodities will be the collateral replacing financial assets. It is interesting to observe the strength in the Mexican peso against the dollar (up 9.7% since November 2021) and the Brazilian real (up 21% over a year) And even the South African rand has risen by 11% in the last five months. That these flaky currencies are rising tells us that resource backing for currencies has its attractions beyond the rouble and renminbi.
But having turned their backs on gold, the Americans and their Western epigones lack an adequate response. If anything, they are likely to continue the fight for dollar hegemony rather than accept reality. And the more America struggles to assert its authority, the greater the likelihood of a split in the Western partnership. Europe needs Russian energy desperately, and America does not. Europe cannot afford to support American policy unconditionally.
That, of course, is Russia’s bet.
Russia’s point of view
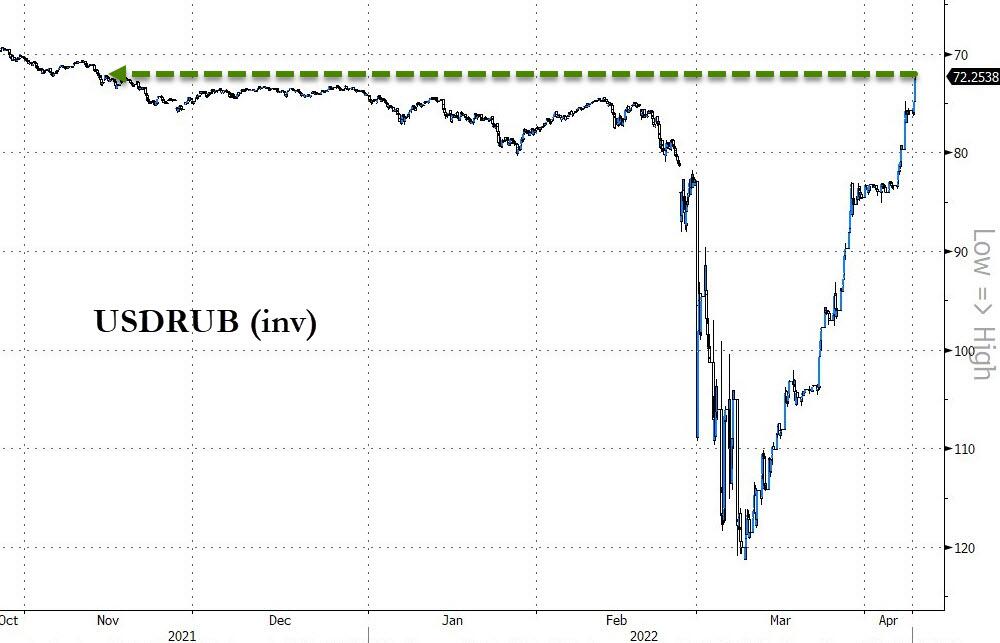
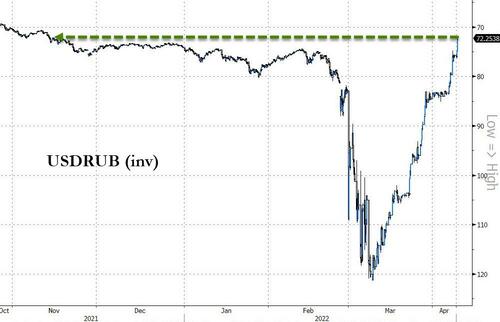
For the second time in eight years, Russia has seen its currency undermined by Western action over Ukraine. Having experienced it in 2014, this time the Russian central bank was better prepared. It had diversified out of dollars adding official gold reserves. The commercial banking system was overhauled, and the Governor of the RCB, Elvira Nabiullina, by following classical monetary policies instead of the Keynesianism of her Western contempories, has contained the fall-out from the war in Ukraine. As Figure 1 shows, the rouble halved against the dollar in a knee-jerk reaction before recovering to pre-war levels.
The link to commodities is gold, and the RCB announced that until end-June it stands ready to buy gold from Russian banks at 5,000 roubles per gramme. The stated purpose was to allow banks to lend against mine production, given that Russian-sourced gold is included in the sanctions. But the move has encouraged speculation that the rouble is going on a quasi- gold standard; never mind that a gold standard works the other way round with users of the currency able to exchange it for gold.
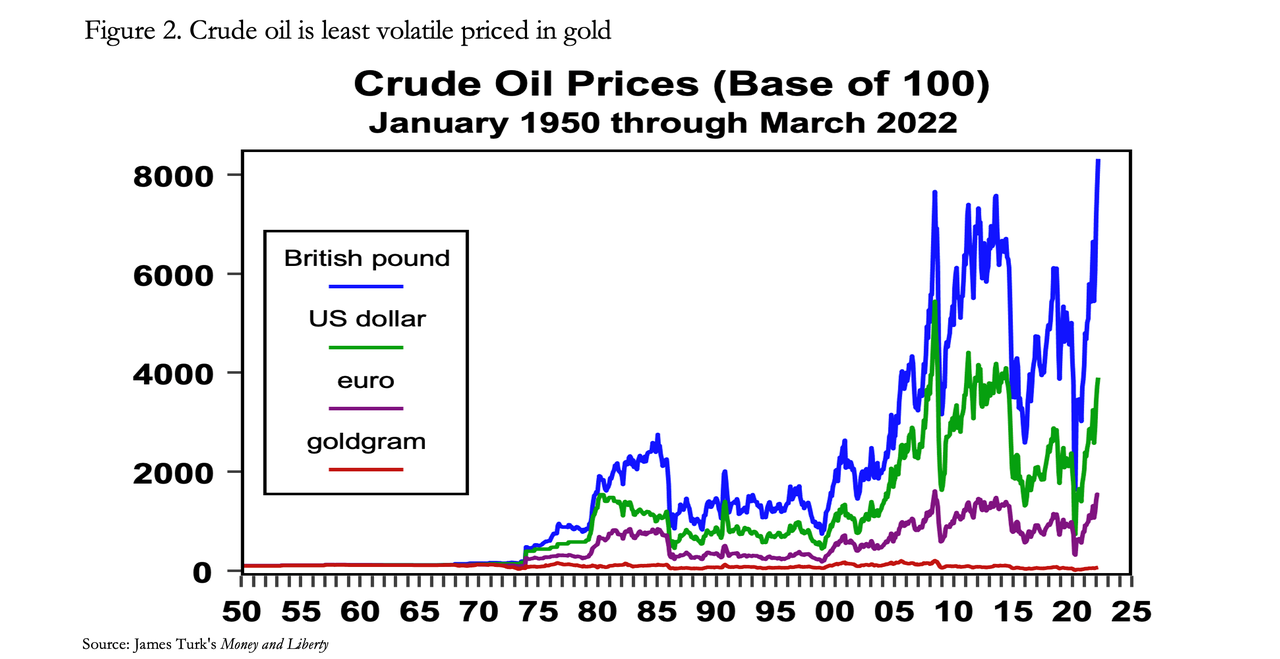
Besides being with silver the international legal definition of money (the rest being currency and credit), gold is a good proxy for commodities, as shown in Figure 2 below. Priced in goldgrams, crude oil today is 30% below where it was in the 1950, long before Nixon suspended the Bretton Woods Agreement. Meanwhile, measured in depreciating fiat currencies the price has soared and been extremely volatile along the way.
It is a similar story for other commodity prices, whereby maximum stability is to be found in prices measured in goldgrams. Taking up Pozsar’s point about currencies being increasingly linked to commodities in Bretton Woods III, it appears that Russia intends to use gold as proxy for commodities to stabilise the rouble. Instead of a fixed gold exchange rate, the RCB has wisely left itself the option to periodically revise the price it will pay for gold after 1 July.
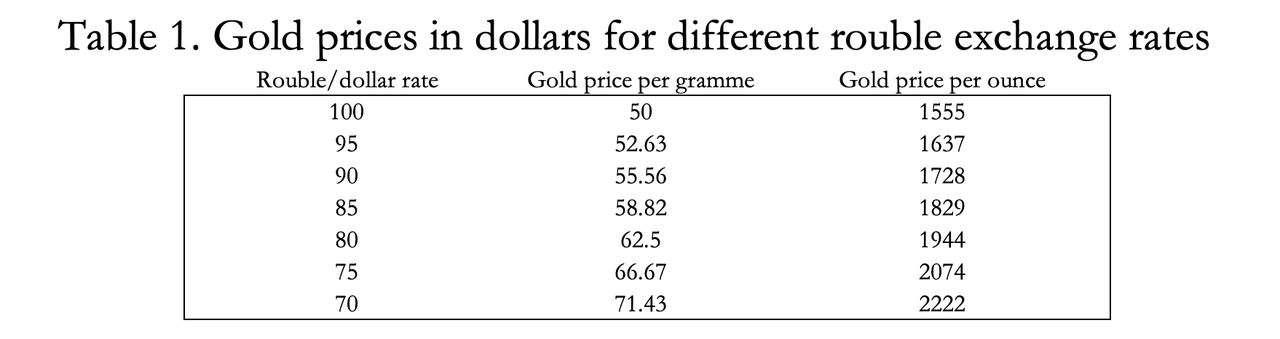
Table 1 shows how the RCB’s current fixed rouble gold exchange rate translates into US dollars.
While non-Russian credit institutions do not have access to the facility, it appears that there is nothing to stop a Russian bank buying gold in another centre, such as Dubai, to sell to the Russian central bank for roubles. All that is needed is for the dollar/rouble rate to be favourable for the arbitrage and the ability to settle in a non-sanctioned currency, such as renminbi, or to have access to Eurodollars which it can exchange for Euroroubles (see below) from a bank outside the “unfriendlies” jurisdictions.
The dollar/rouble rate can now easily be controlled by the RCB, because how demand for roubles in short supply is handled becomes a matter of policy. Gazprom’s payment arm (Gazprombank) is currently excused the West’s sanctions and EU gas and oil payments will be channelled through it.
Broadly, there are four ways in which a Western consumer can acquire roubles:
  • By buying roubles on the foreign exchanges.
  • By depositing euros, dollars, or sterling with Gazprombank and have them do the conversion as agents.
  • By Gazprombank increasing its balance sheet to provide credit, but collateral which is not sanctioned would be required.
  • By foreign banks creating rouble credits which can be paid to Gazprombank against delivery of energy supplies.
The last of these four is certainly possible, because that is the basis of Eurodollars, which circulate outside New York’s monetary system and have become central to international liquidity. To understand the creation of Eurodollars, and therefore the possibility of a developing Eurorouble market we must delve into the world of credit creation.
There are two ways in which foreigners can hold dollar balances. The way commonly understood is through the correspondent banking system. Your bank, say in Europe, will run deposit accounts with their correspondent banks in New York (JPMorgan, Citi etc.). So, if you make a deposit in dollars, the credit to your account will reconcile with the change in your bank’s correspondent account in New York.
Now let us assume that you approach your European bank for a dollar loan. If the loan is agreed, it appears as a dollar asset on your bank’s balance sheet, which through double-entry bookkeeping is matched by a dollar liability in favour of you, the borrower. It cannot be otherwise and is the basis of all bank credit creation. But note that in the creation of these balances the American banking system is not involved in any way, which is how and why Eurodollars circulate, being fungible with but separate in origin from dollars in the US.
By the same method, we could see the birth and rapid expansion of a Eurorouble market. All that’s required is for a bank to create a loan in roubles, matched under double-entry bookkeeping with a deposit which can be used for payments. It doesn’t matter which currency the bank runs its balance sheet in, only that it has balance sheet space, access to rouble liquidity and is a credible counterparty.
This suggests that Eurozone and Japanese banks can only have limited participation because they are already very highly leveraged. The banks best able to run Eurorouble balances are the Americans and Chinese because they have more conservative asset to equity ratios. Furthermore, the large Chinese banks are majority state-owned, and already have business and currency interests with Russia giving them a head start with respect to rouble liquidity.
We have noticed that the large American banks are not shy of dealing with the Chinese despite the politics, so presumably would like the opportunity to participate in Euroroubles. But only this week, the US Government prohibited them from paying holders of Russia’s sovereign debt more than $600 million. So, we should assume the US banks cannot participate which leaves the field open to the Chinese mega-banks. And any attempt to increase sanctions on Russia, perhaps by adding Gazprombank to the sanctioned list, achieves nothing, definitely cuts out American banks from the action, and enhances the financial integration between Russia and China. The gulf between commodity-backed currencies and yesteryear’s financial fiat simply widens.
For now, further sanctions are a matter for speculation. But Gazprombank with the assistance of the Russian central bank will have a key role in providing the international market for roubles with wholesale liquidity, at least until the market acquires depth in liquidity. In return, Gazprombank can act as a recycler of dollars and euros gained through trade surpluses without them entering the official reserves. Dollars, euros yen and sterling are the unfriendlies’ currencies, so the only retentions are likely to be renminbi and gold.
In this manner we might expect roubles, gold and commodities to tend to rise in tandem. We can see the process by which, as Zoltan Pozsar put it, Bretton Woods III, a global currency regime based on commodities, can take over from Bretton Woods II, which has been characterised by the financialisation of currencies. And it’s not just Russia and her roubles. It’s a direction of travel shared by China.
The economic effects of a strong currency backed by commodities defy monetary and economic beliefs prevalent in the West. But the consequences that flow from a stronger currency are desirable: falling interest rates, wealth remaining in the private sector and an escape route from the inevitable failure of Western currencies and their capital markets. The arguments in favour of decoupling from the dollar-dominated monetary system have suddenly become compelling.
The consequences for the West
Most Western commentary is gung-ho for further sanctions against Russia. Relatively few independent commentators have pointed out that by sanctioning Russia and freezing her foreign exchange reserves, America is destroying her own hegemony. The benefits of gold reserves have also been pointedly made to those that have them. Furthermore, central banks leaving their gold reserves vaulted at Western central banks exposes them to sanctions, should a nation fall foul of America. Doubtless, the issue is being discussed around the world and some requests for repatriation of bullion are bound to follow.
There is also the problem of gold leases and swaps, vital for providing liquidity in bullion markets, but leads to false counting of reserves. This is because under the IMF’s accounting procedures, leased and swapped gold balances are recorded as if they were still under a central bank’s ownership and control, despite bullion being transferred to another party in unallocated accounts.
No one knows the extent of swaps and leases, but it is likely to be significant, given the evidence of gold price interventions over the last fifty years. Countries which have been happy to earn fees and interest to cover storage costs and turn gold bullion storage into a profitable activity (measured in fiat) are at the margin now likely to not renew swap and lease agreements and demand reallocation of bullion into earmarked accounts, which would drain liquidity from bullion markets. A rising gold price will then be bound to ensue.
Ever since the suspension of Bretton Woods in 1971, the US Government has tried to suppress gold relative to the dollar, encouraging the growth of gold derivatives to absorb demand. That gold has moved from $35 to $1920 today demonstrates the futility of these policies. But emotionally at least, the US establishment is still virulently anti-gold.
As Figure 2 above clearly shows, the link between commodity prices and gold has endured through it all. It is this factor that completely escapes popular analysis with every commodity analyst assuming in their calculations a constant objective value for the dollar and other currencies, with price subjectivity confined to the commodity alone. The use of charts and other methods of forecasting commodity prices assume as an iron rule that price changes in transactions come only from fluctuations in commodity values.
The truth behind prices measured in unbacked currencies is demonstrated by the cost of oil priced in gold having declined about 30% since the 1960s. That is reasonable given new extraction technologies and is consistent with prices tending to ease over time under a gold standard. It is only in fiat currencies that prices have soared. Clearly, gold is considerably more objective for transaction purposes than fiat currencies, which are definitely not.
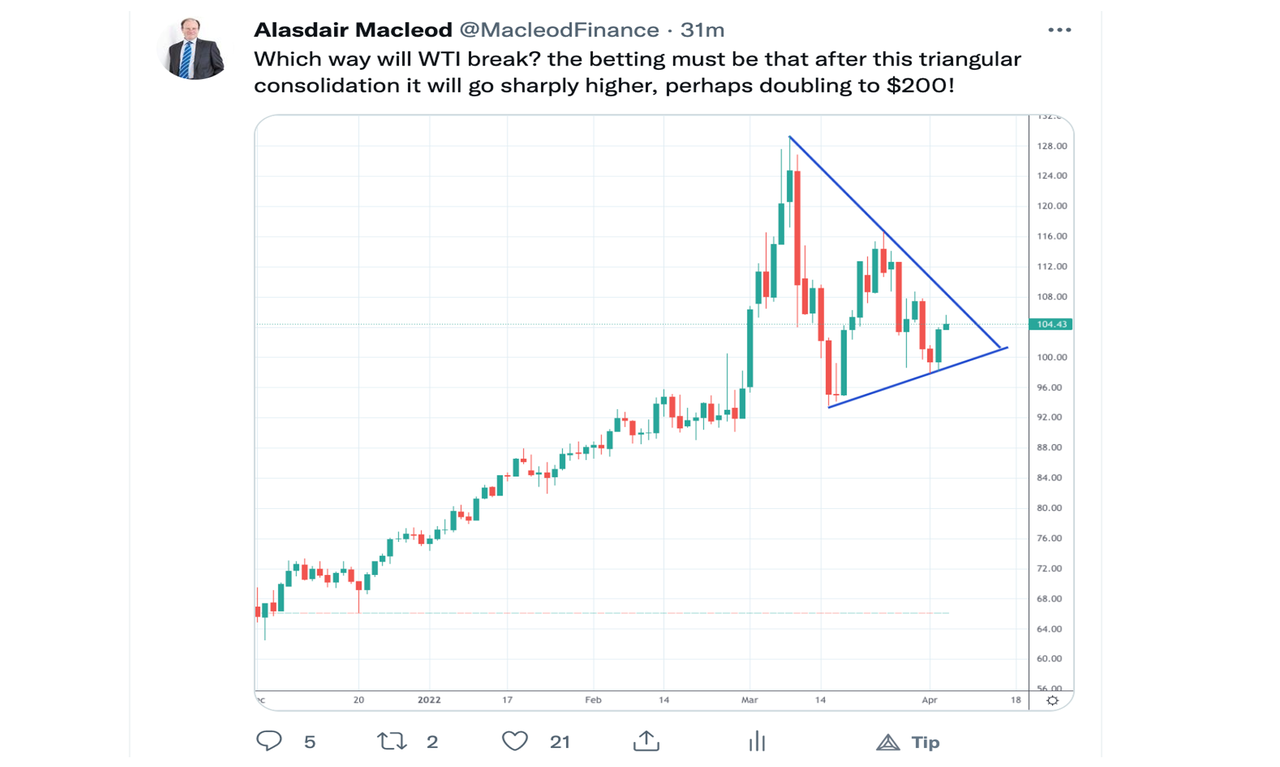
Therefore, if, as the chart in the tweet below suggests, the dollar price of oil doubles from here, it will only be because at the margin people prefer oil to dollars — not because they want oil beyond their immediate needs, but because they want dollars less.
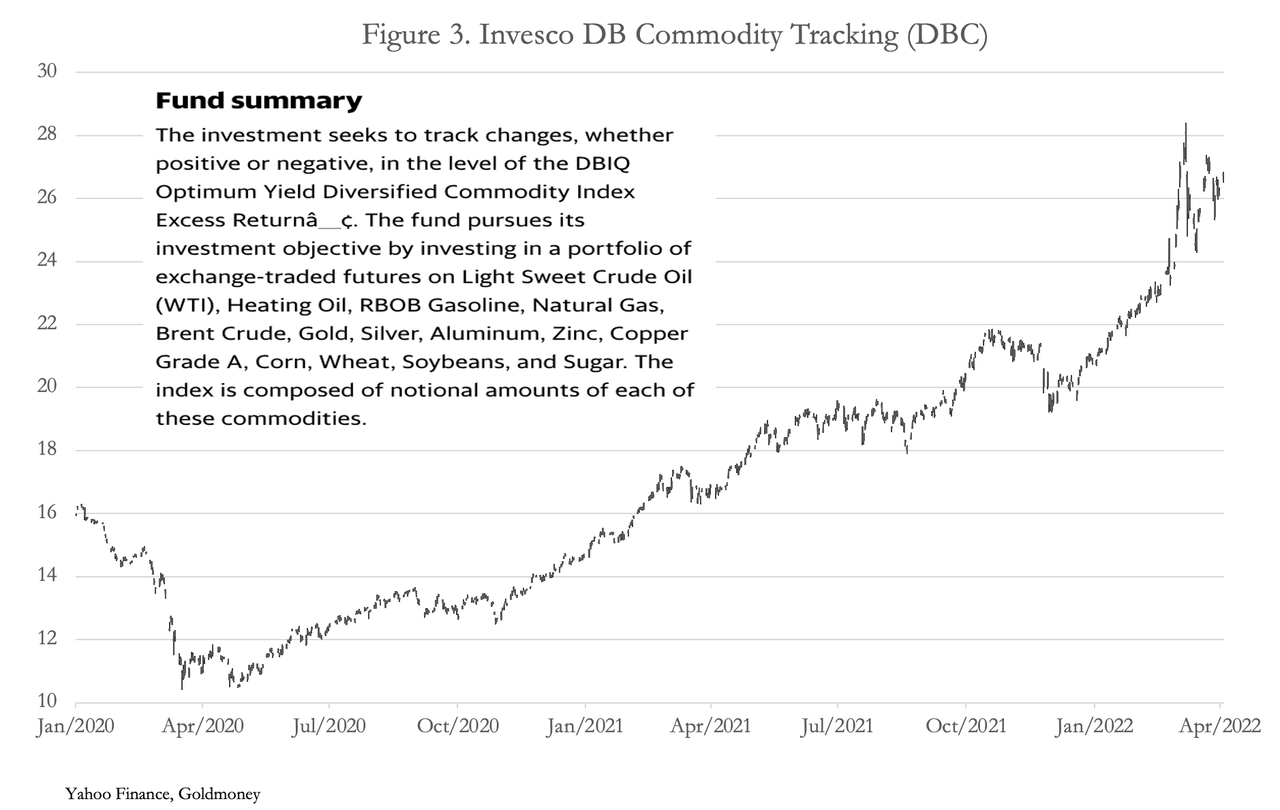
China recognised these dynamics following the Fed’s monetary policies of March 2020, when it reduced its funds rate to the zero bound and instituted QE at $120bn every month. The signal concerning the dollar’s future debasement was clear, and China began to stockpile oil, commodities, and food — just to get rid of dollars. This contributed to the rise in dollar commodity prices, which commenced from that moment, despite falling demand due to covid and supply chain problems. The effect of dollar debasement is reflected in Figure 3, which is of a popular commodity tracking ETF.
A better understanding would be to regard the increase in the value of this commodity basket not as a near doubling since March 2020, but as a near halving of the dollar’s purchasing power with respect to it.
Furthermore, the Chinese have been prescient enough to accumulate stocks of grains. The result is that 20% of the world’s population has access to 70% of the word’s maize stocks, 60% of rice, 50% of wheat and 35% of soybeans. The other 80% of the world’s population will almost certainly face acute shortages this year as exports of grain and fertiliser from Ukraine/Russia effectively cease.
China’s actions show that she has to a degree already tied her currency to commodities, recognising the dollar would lose purchasing power. And this is partially reflected in the yuan’s exchange rate against the US dollar, which since May 2020 has gained over 11%.
Implications for the dollar, euro and yen
In this article the close relationship between gold, oil, and wider commodities has been shown. It appears that Russia has found a way of tying her currency not to the dollar, but to commodities through gold, and that China has effectively been doing the same thing for two years without the gold link. The logic is to escape the consequences of currency and credit expansion for the dollar and other Western currencies as their purchasing power is undermined. And the use of a gold peg is an interesting development in this context.
We should bear in mind that according to the US Treasury TIC system foreigners own $33.24 trillion of financial securities and short-term assets including bank deposits. That is in addition to a few trillion, perhaps, in Eurodollars not recorded in the TIC statistics. These funds are only there in such quantities because of the financialisation of Western currencies, a situation we now expect to end. A change in the world’s currency order towards Pozsar’s Bretton Woods III can be expected to a substantial impact on these funds.
To prevent foreign selling of the $6.97 trillion of short-term securities and cash, interest rates would have to be raised not just to tackle rising consumer prices (a Keynesian misunderstanding about the economic role of interest rates, disproved by Gibson’s paradox) but to protect the currency on the foreign exchanges, particularly relative to the rouble and the yuan. Unfortunately, sufficiently high interest rates to encourage short-term money and deposits to stay would destabilise the values of the foreign owned $26.27 trillion in long-term securities — bonds and equities.
As the manager of US dollar interest rates, the dilemma for the Fed is made more acute by sanctions against Russia exposing the weakness of the dollar’s position. The fall in its purchasing power is magnified by soaring dollar prices for commodities, and the rise in consumer prices will be greater and sooner as a result. It is becoming possible to argue convincingly that interest rates for one-year dollar deposits should soon be in double figures, rather than the three per cent or so argued by monetary policy hawks. Whatever the numbers turn out to be, the consequences are bound to be catastrophic for financial assets and for the future of financially oriented currencies where financial assets are the principal form of collateral.
It appears that Bretton Woods II is indeed over. That being the case, America will find it virtually impossible to retain the international capital flows which have allowed it to finance the twin deficits — the budget and trade gaps. And as securities’ values fall with rising interest rates, unless the US Government takes a very sharp knife to its spending at a time of stagnating or falling economic activity, the Fed will have to step up with enhanced QE.
The excuse that QE stimulates the economy will have been worn out and exposed for what it is: the debasement of the currency as a means of hidden taxation. And the foreign capital that manages to escape from a dollar crisis is likely to seek a home elsewhere. But the other two major currencies in the dollar’s camp, the euro and yen, start from an even worse position. These are shown in Figure 4. With their purchasing power visibly collapsing the ECB and the Bank of Japan still have negative interest rates, seemingly trapped under the zero bound. Policy makers find themselves torn between the Scylla of consumer price inflation and the Charybdis of declining economic activity. A further problem is that these central banks have become substantial investors in government and other bonds (the BOJ even has equity ETFs on board) and rising bond yields are playing havoc with their balance sheets, wiping out their equity requiring a systemic recapitalisation.
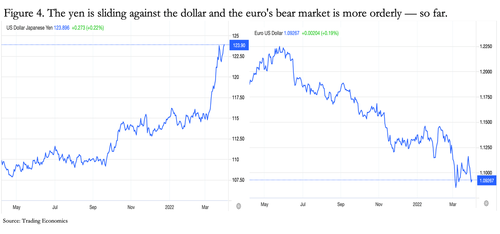
Not only are the ECB and BOJ technically bankrupt without massive capital injections, but their commercial banking networks are hugely overleveraged with their global systemically important banks — their G-SIBs — having assets relative to equity averaging over twenty times. And unlike the Brazilian real, the Mexican peso and even the South African rand, the yen and the euro are sliding against the dollar.
The response from the BOJ is one of desperately hanging on to current policies. It is rigging the market by capping the yield on the 10-year JGB at 0.25%, which is where it is now.
These currency developments are indicative of great upheavals and an approaching crisis. Financial bubbles are undoubtedly about to burst sinking fiat financial values and all that sail with them. Government bonds will be yesterday’s story because neither China nor Russia, whose currencies can be expected to survive the transition from financial to commodity orientation, run large budget deficits. That, indeed, will be part of their strength.
The financial war, so long predicted and described in my essays for Goldmoney, appears to be reaching its climax. At the end it has boiled down to who understands money and currencies best. Led by America, the West has ignored the legal definition of money, substituting fiat dollars for it instead. Monetary policy lost its anchor in realism, drifting on a sea of crackpot inflationary beliefs instead.
But Russia and China have not made the same mistake. China played along with the Keynesian game while it suited them. Consequently, while Russia may be struggling militarily, unless a miracle occurs the West seems bound to lose the financial war and we are, indeed, transiting into Pozsar’s Bretton Woods III.

FT : Market turmoil splits hedge funds into macro winners and tech losers

Market turmoil splits hedge funds into macro winners and tech losers
War and rising inflation widen the gap between best and worst performers

Market turmoil driven by Russia’s invasion of Ukraine and rising inflation has sharply divided the hedge fund industry, with macro hedge funds celebrating one of their best-ever starts to a year while technology and growth funds rack up double-digit losses.

The top 10 per cent of hedge funds gained an average of 24.3 per cent in the first quarter, while the bottom decile dropped by 15.4 per cent, according to HFR, which tracks the sector. The dispersion is one of the widest since the financial crisis.

The industry as a whole suffered losses of 0.3 per cent for the first quarter, as measured by the HFRI fund-weighted index, and larger funds tended to do better than small ones.

“I struggle to think of a quarter with more dispersion in quite a long time,” said Michael Edwards, deputy chief investment officer of Weiss Multi-Strategy Advisers.

Recommended
ExplainerFederal Reserve
Can the Fed shrink its $9tn balance sheet without causing market mayhem?

Many long-short equity hedge funds cut their exposure to US stocks and reduced leverage as the market sold off in January and February, nervous that there was further room for stocks to fall. They remained on the sidelines and pared positions further when the market finally found its footing, according to the prime brokerage arm of Goldman Sachs.

It meant that some funds missed out on a 9 per cent rally in the S&P 500 from its February lows, including in many of the technology stocks that had been badly hit at the year’s start. That drove the HFRI index for equity funds down 4 per cent.

Tiger Global was among the hardest hit: it is down 34 per cent for the quarter. Melvin Capital, Whale Rock and RiverPark’s Long/Short fund all saw drops of more than 20 per cent in the quarter, as consumer, technology and growth stocks more generally struggled. The troubles with tech were not confined to the US. Accendo Capital lost 17.8 per cent, as one of its biggest holdings, Swedish telecoms manufacturer Hexatronic, gave back some of last year’s gains.

By contrast, computer-driven and macro funds rallied strongly: HFRI’s macro index rose more than 8 per cent in the quarter.

Those gains, Edwards added, were due in part to the fact macro quant funds traded systematically. Without human sensibilities to be affected by the war in Ukraine, surge in Treasury yields and sell-off in markets, computer-driven funds were quicker to re-enter the fray compared to some flesh-and-bone hedge fund managers.

“Machines are not subject to the same Fomo [fear of missing out] and wound-licking tendencies that discretionary managers are,” he said.

Among the biggest winners this year have been the BH-DG Systematic Trading fund, run by a joint venture between hedge fund firm Brevan Howard and former Chase Manhattan trader David Gorton. The fund gained 23 per cent to late March, according to numbers sent to investors.

Meanwhile, Leda Braga’s Systematica was up nearly 18 per cent, helped by bets on commodities and bonds, and Aspect Capital is up 21.5 per cent in its Diversified fund.

Bridgewater, the world’s biggest hedge fund with about $150bn under management, gained 16.3 per cent. It told investors that its top performances came in commodities, short rates and nominal bonds.

Many of the winning funds use algorithms to predict and bet on trends and patterns in futures and other financial markets. They have profited from a huge sell-off in government bond markets this year, with yields on 2-year US Treasuries rocketing from 0.7 per cent to 2.4 per cent and 10-year yields jumping from 1.5 per cent to 2.5 per cent, as the Federal Reserve moves to tighten monetary policy.

“So far this year [performance] is spectacular,” said Philippe Jordan, president at Paris-based CFM, which manages around $9bn, and is up around 17 per cent in its Discus strategy and 7 per cent in its flagship Stratus fund. “The macro backdrop for [quant] futures trading is better than it’s been in the past 10 years.” 

The HFRI commodity funds index soared nearly 25 per cent, powered by a one-third rise in the price of crude oil and a jump for natural gas of almost two-thirds. Makuria Investment Management, which invests in commodities and companies involved in the energy transition, gained 31 per cent. “The tragic events in Ukraine merely accelerated already existing structural trends across commodity markets . . . by further increasing market tightness,” founder Mans Larsson wrote.

Other traders have also profited from the huge market moves in bonds and currencies. Odey Asset Management’s European fund gained nearly 61 per cent to mid-March, helped by bets on long-dated bond yields rising. He believes they have further to go. “There’s nothing holding down yields from here,” said founder Crispin Odey.

Equity hedge funds had a much tougher time. Funds that were positioned for rising prices suffered losses as equity markets were affected by the Ukraine war and the prospect of higher borrowing costs, and bond markets sold off rapidly.

“Extreme volatility in the rates market and the Ukraine situation delivered a difficult risk environment for all asset classes,” said Kevin Russell, chief investment officer at the UBS hedge fund unit O’Connor, which manages more than $11.2bn in assets.