FT : Electric vehicle targets ‘impossible’ without changes to lithium pipeline

Electric vehicle targets ‘impossible’ without changes to lithium pipeline
West has been ‘remarkably slow’ to develop robust supply chains, says Australian producer

Battery manufacturers are confronting a severe lithium shortage, highlighting the need to challenge China’s dominance of raw material supply chains, an Australian lithium producer has warned.

Stuart Crow, chair of Lake Resources, said western companies and governments had failed to build adequate supply chains for lithium, making the sudden boom in electric vehicle manufacturing unsustainable.

“There simply isn’t going to be enough lithium on the face of the planet, regardless of who expands and who delivers, it just won’t be there,” he said. “The carmakers are starting to sense that maybe the battery makers aren’t going to be able to deliver.”

Lithium-ion batteries play a critical role for governments hoping to decarbonise their economies, and the west is working to loosen China’s grip on the lithium supply chain and processing capacity in particular. Disruption from the war in Ukraine and subsequent sanctions imposed on Russia have also underlined the importance of supply security.

Lake Resources’ share price more than doubled in March, giving it a market capitalisation of A$2.5bn (US$1.9bn), after it signed a memorandum of understanding with the Japanese import-export group Hanwa to deliver 25,000 tonnes of lithium carbonate a year. On Monday, the company announced it had signed another non-binding offtake deal with US carmaker Ford.

“Right now China owns basically 70-80 per cent of the entire supply chain for electric vehicles and lithium-ion batteries, and therefore energy storage,” Crow said. “The west has been remarkably slow to adopt a strategy to try and assist and secure a supply chain.”

Daniel Morgan, a mining analyst at investment bank Barrenjoey, said it was “impossible for the [EV production] targets being made by either carmakers or governments to be met”. He added: “There’s a great love of throwing out lofty targets, but where the rubber hits the road it’s not going to happen.”

Lake Resources, which is listed on the Australian Securities Exchange, is developing a lithium production plant in Argentina. There it will use technology developed by US company Lilac Solutions, backed by Bill Gates, to extract lithium directly from brine, rather than via the more common evaporation method.

It plans to produce 50,000 tonnes of lithium carbonate a year by 2025 and is focused on building supply chains that bypass China.

Lake Resources’ plant in Argentina has by itself yet to produce any lithium carbonate, despite having been set up in 2015. Crow said that was a result of the time it takes to develop lithium projects, which carmakers had not adequately factored in when setting their EV production targets.

“The forecasts for the [lithium] deficit this year vary from 50,000 tonnes per annum out to 400,000 tonnes, on a market that looks potentially to produce 450,000 tonnes a year,” he said. “Anecdotally, we’re hearing stories of two very large battery makers in the market trying to source 150,000 tonnes [each] of lithium hydroxide this year. And with 450,000 tonnes of supply, it’s not going to happen.”

While the US wants half of all car sales to be EVs by 2030, the EU has proposed banning internal combustion engine car sales altogether by 2035. Major marques including Volkswagen, Ford, Stellantis, General Motors and Toyota have all announced ambitious targets to ramp up EV production and phase out petrol cars.

The International Energy Agency estimates global EV sales must reach 47mn a year by 2030 to ensure transport emissions are consistent with its “sustainable development scenario”, which would keep global warming “well below” 2C in line with the Paris climate accord.

Mining group Rio Tinto predicts demand for lithium will rise by 25-35 per cent a year over the next decade.

Barrenjoey’s Morgan said 28mn EV sales by 2030 was a more realistic projection, but even that would not be possible with current announced lithium projects. Indeed, it would require lithium production to increase six-fold between now and 2030.

“There’s eight years until 2030. We need to start hearing about new projects now,” he said, adding that it was a “great time to be a miner”.

>>> Europe : Brokers Upgrades & Downgrades - 11th of April 2022 V2(+)

>>> Up
* Adevinta Raised to Buy at Goldman; PT 118.50 kroner
* Aixtron Up to Outperform at Exane BNP on MicroLED Opportunity
* Ediliziacrobatica Raised to Buy at Intesa Sanpaolo (+)
* Nexans Raised to Add at AlphaValue/Baader
* Schibsted Raised to Buy at Goldman; PT 326.90 kroner
* Schlumberger NV Raised to Overweight at Piper Sandler; PT $55
* TGS Raised to Buy at SEB Equities; PT 175 kroner

>>> Down
* AMS cut to Neutral from Outperfotm at Exane (+)
* Encavis Cut to Equal-Weight at Barclays; PT 19 euros
* Metro Bank Cut to Hold at Investec; PT 105 pence (+)
* Nvidia Cut to Neutral at Baird; PT $225 (+)
* Polytec Holding Cut to Hold at M.M. Warburg; PT 7.50 euros (+)
* ProSieben Cut to Neutral at Goldman; PT 13.10 euros
* RTL Cut to Neutral at Goldman; PT 60.74 euros
* Stroeer Cut to Sell at Goldman; PT 62.10 euros
* WPP Cut to Neutral at Goldman; PT 1,235 pence

>>> Initiation
* Kraft Bank Rated New Buy at SpareBank; PT 13 kroner
* Medartis Resumed Market Perform at ZKB (+)
* Patrizia Rated New Buy at Bankhaus Metzler; PT 21.10 euros (+)
* Richemont Started at Buy by Jefferies, Target Started at CHF140 by Jefferies
* Tinybuild Rated New Add at Numis; PT 210 pence

>>> Call
* AG Barr Raised at Berenberg on ‘Underappreciated Transformation’
* Airbus 1Q Deliveries in Line, Orders ‘Solid,’ Jefferies Says (+)
* Aixtron Up to Outperform at Exane BNP on MicroLED Opportunity
* Goldman Strategists See Risks to European Margins, Revenues
* Omer-Decugis Rated New Buy at Stifel; PT 10.50 euros (+)
* Richemont a New Buy at Jefferies With Cartier Still the Standout
* Sainsbury Up to Buy on Resilient U.K. Consumers, Jefferies Says
* Citi Stays Cautious on Fintech, Sees Near-Term Risks at Temenos
* Wood Raised to Hold at Jefferies on Upcoming Major Catalysts

>>> Monday Morning Papers

Monday Morning Papers Summary

LA REPUBBLICA
-The first polls and analyses of electoral flows are favorable to Marine Le Pen, who has reached the runoff ballot for the second time in 5 years. But compared to 2017 everything is differentMarine Le Pen’s performance allows her to aim for the presidency well beyond the results of the first round of the presidential elections in France, which saw Emmanuel Macron take a small lead over Rassemblement National candidate by more than three points. With the polls closed, a large part of defeated candidates have immediately endorsed the incumbent president.
-The Italian prime minister Mario Draghi, who will be in Algeria today to negotiate gas import deals, is convinced that the Lega and M5S parties will try to make the government unmanageable in the wake of Marine Le Pen’s success, which will keep the pro-European Union and NATO leaders on alert.

FRANKFURTER ALLGEMEINE ZEITUNG
-French Presidential candidate Marine Le Pen has improved on her result from five years ago and, gaining a solid 23% of the vote. She has become a serious threat to Macron's re-election. On the evening of the election, she appealed to all voters who had not voted for Macron to join her. It was "a civilizational decision," she said.
-The World Bank has revised its economic forecast for Ukraine significantly downwards as the Russian war of aggression progresses. Economists predicted on Sunday that Ukraine's gross domestic product would fall by 45.1% this year – instead of the expected drop of between 10 and 35% a month ago. Grain exports and other economic activities have "become impossible in large parts of the country due to severe damage to infrastructure," Bjerde explained. This has global consequences: Because of the war, world market prices for grain and energy, where Ukraine and Russia are among the most important exporters, have shot up significantly. The economy of Russia, which is subject to international sanctions, will shrink by 11.2%.

HANDELSBLATT
-Acute staff shortages, frequent job changes and rapidly growing inflation rates are fueling a salary bubble among skilled workers in Germany. This is shown by a study by the management consultancy Willis Towers Watson (WTW), which is available exclusively to the Handelsblatt. The analysis focused on jobs that required specialized knowledge. According to this, since the outbreak of the corona crisis, the salaries of IT system architects have increased by almost a quarter on average. Salespeople in key account areas have also earned an average of 15% more since the pandemic. The situation is similar in controlling, marketing and financial analysis.
-Russia's war against the Ukraine is hitting German medium- sized companies hard. This is the result of a representative survey by DZ Bank, which was previously available to the Handelsblatt. For this purpose, more than 1000 managing directors and decision-makers of medium-sized companies were surveyed in the period from the end of February to the end of March. This makes it the first survey to show the effects of the war.

IL SOLE 24 ORE
-More than 600 multinationals have decided and announced total or partial exits from Russia since February. In the most diverse sectors, from oil and burgers to tech and media, from banks to accounting services. From Exxon Mobil and BP to McDonald's, from Citigroup to the kings of credit cards, from McKinsey and Bain to Apple and Disney.
-An Italian delegation led by Prime Minister Mario Draghi, the Ecological Transition Ministers Roberto Cingolani and Foreign Affairs Luigi Di Maio is heading to Algeria to strengthen energy cooperation between the two countries (as follow up to a previous diplomatic visit on February 28) accompanied by Eni CEO Claudio Descalzi. The plan is to double the amount of gas that Italy imports from Algeria, adding about 9B m3/year to the 10B m3 already supplied to Italy by Eni through the Transmed gas pipeline and in order to diversify sources and gradually free up the Italy from the Russian energy yoke. Algeria is currently Italy’s largest supplier after Russia (from which Rome imports some 29B m3/year). Draghi is also expected to sign a pact for joint investments in renewables, which have great development potential in Algeria and North Africa.

LES ECHOS
-As in 2017, Emmanuel Macron and Marine Le Pen have qualified for the second round. The outgoing president came out ahead in the first round with 27.9% of the vote, according to OpinionWay estimates. It is doing better than five years ago (24%). Le Pen of the RN Party was second with around 23.3% of the vote, according to estimates. If she achieves the best score in the history of her political family in the first round of the presidential election, this may be less than she had hoped. The other big player of the first round of the election was absenteeism as 27.4% of voters shunned the ballot boxes according to estimates from Opinionway on Sunday evening.
-The big loser of the first round of the French presidential election is Valérie Pécresse. She claimed that the campaign was “the fight of a lifetime.” She actually gave everything, but her fight turned into an ordeal. For the second consecutive time, the Republican right is absent from the second round of the presidential election. The leaders of LR have not had access to power for ten years and for this political family which founded the Fifth Republic, it is more than a trauma, it is reason to question its raison d'être.

ABC
The war in Ukraine and the consequent sanctions imposed on Vladimir Putin 's Russia by the United States and the European Union (the latest version of which was approved last week) have secondary effects on the EU economies and, particularly, on an agricultural exporting power such as Spain (eighth exporter in the world and fourth at European level). Last year alone, agro-food products were sold abroad worth EUR60,118M, 11% more than in 2020. Especially fruit (EUR10,162M), meat products (EUR8,819M) and vegetables (EUR7,461M). Specifically, due to the cancellation of the Swift payment system and the strong depreciation of the ruble, countries such as Morocco, Egypt, Turkey or Israel , which had taken the place left in the Russian market by European nations such as Spain - following Russia's takeover of Crimea in 2014, are beginning to divert part of these exports to Europe.

>>> Stoxx 600 Pre-Market Indications

  • Voestalpine (VAS TH) +3%
    • Watch Europe Miners as Iron Ore Drops Over China Virus Outbreak
  • Norsk Hydro (NOH1 TH) +2.6%
  • Rolls-Royce (RRU TH) +2.3%
  • Orsted (D2G TH) +1.6%
  • M&G (7MP TH) +1.6%
  • Tomra (TMR TH) +1.4%
  • Alstom (AOMD TH) +1.1%
  • SocGen (SGE TH) +1.1%
    • SocGen Agrees to Sell Rosbank to Interros Capital
  • Vestas (VWSB TH) +1%
  • Equinor (DNQ TH) +1%
    • Watch Europe Oil Stocks as Crude Falls on China’s Virus Outbreak
  • BAE (BSP TH) -1.4%
  • GSK (GS7 TH) -1.6%
  • Continental (CON TH) -1.6%
  • Linde (LIN TH) -1.6%
  • Orange (FTE TH) -1.8%
  • Repsol (REP TH) -2.1%
    • Watch Europe Oil Stocks as Crude Falls on China’s Virus Outbreak
  • EDP (EDP TH) -2.1%
    • EDPR Gets Purchase Agreement to Sell Power From Texas Solar Park
  • Aurubis (NDA TH) -2.3%
  • Nokian Renkaat (NRE TH) -2.5%
    • Nokian Renkaat Says Sanctions’ Impact on Tire Sales Significant
  • Prosus (1TY TH) -2.7%

>>> TradeGate Pre-Market Indications

DAX:
  • Mercedes (MBG TH) -1.2%
  • Fresenius SE (FRE TH) -1.2%
  • Adidas (ADS TH) -1.2%
  • BMW (BMW TH) -1.2%
    • BMW Sees Chip Shortage Lasting Into 2023: Neue Zuercher Zeitung
  • Linde (LIN TH) -1.3%
MDAX:
  • Aixtron (AIXA TH) +2.5%
    • Aixtron Up to Outperform at Exane BNP on MicroLED Opportunity
  • Rheinmetall (RHM TH) +1.4%
  • Siltronic (WAF TH) +1.2%
    • Watch Tech, Yield-Sensitive Sectors as Treasury Yields Climb
  • Aroundtown (AT1 TH) +1.1%
  • K+S (SDF TH) +1%
  • ProSieben (PSM TH) -1.4%
    • ProSieben Cut to Neutral at Goldman; PT 13.10 euros
  • Stroeer (SAX TH) -1.9%
    • Stroeer Cut to Sell at Goldman; PT 62.10 euros
  • Aurubis (NDA TH) -2.3%
SDAX:
  • Takkt (TTK TH) +2.6%
  • LPKF (LPK TH) +2.2%
  • Schaeffler (SHA TH) +1.1%
  • Metro (B4B TH) -1.3%
  • Encavis (ECV TH) -1.8%

>>> What to look at today - 11th of April 2022

Treasuries, stocks and U.S. equity futures slid Monday amid heightened worries about inflation risks and tightening financial conditions. A gauge of the dollar climbed. The 10-year Treasury yield touched 2.77%, exceeding the equivalent rate on Chinese debt for the first time since 2010. Real U.S. yields are getting closer to turning positive, a development that could be an impediment for risk assets.  An Asia-Pacific equity index shed more than 1%, dropping to the lowest since mid-March. China and Hong Kong were in the red, weighed down by the mainland’s Covid outbreak, elevated Chinese factory-gate prices and regulatory concerns in the technology sector. U.S. and European futures also declined, pointing to more challenges for global shares after the Federal Reserve last week signaled sharp interest-rate hikes and balance-sheet reduction to curb price pressures. Oil retreated on risks to demand from China’s Covid lockdowns, including extensive curbs in Shanghai. Market sentiment continues to be shaped by a hawkish Fed, commodity-market disruptions caused by Russia’s invasion of Ukraine and the prospect of an economic slowdown. China’s Covid curbs threaten to exacerbate supply-chain snarls, further stoking inflation risks. The nation’s factory gate prices increased more than expected in March.

Nikkei -0,83% Hang Seng -2,75% CSI -2,72% Shanghai -2,12% Shenzen -2,76%

Eur$ 1,0889 CNH 6,3816 CNY 6,§3720 JPY 125 GBP 1,3015 CHF 0,9353 RUB 81,45 TRY 14,7404 WTI$ 96,45 Gold 1943 BTC 4,280 -2% ETH 3180 -2,5%

S&P -0,48% Nasdaq -0,51% EuroStoxx -0,45% Dax -0,64% SMI -0,08%

Macro :
- Macron Set to Face Le Pen in French Presidential-Election Runoff
- Goldman Strategists See Risks to European Margins, Revenues
- Former Citi Executives Seek $100 Million for Crypto Hedge Funds
- Dollar Jumps on Soaring Yields; China Stocks Slump: Macro Squawk

Keep an eye on :
- AIR FP : Airbus Books 104 Gross Orders in March
- AF FP : Dutch Watchdog Rules KLM’s ‘Carbon Zero’ Ad Is Misleading
- AKERBP NO : Aker BP, Pandion Start Production From Hod B in North Sea
- ASCL LN : Ascential Weighs U.S. Spin Off of Digital Operations, Sky Says
- ATL IM : GIP, Brookfield Not Planning Hostile Move on Atlantia: Rtrs
- SPR SW : Axel Springer Pledges Focus on Culture as It Overhauls Board
_ BMW GY : BMW Sees Chip Shortage Lasting Into 2023: Neue Zuercher Zeitung
- BOSN SW : Bossard 1Q Sales CHF291.6M Vs. CHF244.8M Y/y
- BSGR NA : B&S to Buy 70% of Undisclosed French Beauty Company; No Terms
- Channal 4 IPO : U.K. Mulls Listing of Channel 4 If No Bids Are Made, Times Says
- DHER GY : Delivery Hero Completes EU1.4B-Equiv Debt Financing Syndication
- EOAN GY : E.ON Rules Out German Nuclear Power Plant Extension: FT
- FORTUM FH : Finnish Premier Signals Fortum Will Have to Exit Russia Soon
- G IM : Generali Investors Should Back Board’s Slate, Proxy Firms Say
- HEIJM NA : Heijmans Doesn’t Need to Pay Advance Compensation on Wintrack II
- LHA GY : Lufthansa Debt Climbed by $11 Billion Due to Pandemic: CEO Spohr
- TYRES FH : Nokian Renkaat Says Sanctions’ Impact on Tire Sales Significant
- NVDA US : Nvidia Seeks Holder Approval to Boost Authorized Common Shares
- ORSTED DC : Orsted to Build Coal Stockpile Due to Ukraine War Situation: FT
- RIO LN : Rusal Doesn’t Agree With Rio Taking Control of Alumina Plant
- TIT IM : Telecom Italia’s Single Network Plan Open to KKR, CEO Tells Sole
- UCG IM : UniCredit Delays Meeting for More Time to Manage Russia Exposure
- VOD LN : *VODAFONE SPAIN MULLS SALE OF FIXED BROADBAND NETWORK: EXPANSION
- VOE AV : Voestalpine to Sell Stake in Texas Steel Plant, Standard Says
- WKP LN : Workspace Says Like-For-Like Occupancy Grew in Jan.-March

>>> Europe : Brokers Upgrades & Downgrades - 11th of April 2022

>>> Up
* Adevinta Raised to Buy at Goldman; PT 118.50 kroner
* Aixtron Up to Outperform at Exane BNP on MicroLED Opportunity
* Nexans Raised to Add at AlphaValue/Baader
* Schibsted Raised to Buy at Goldman; PT 326.90 kroner
* Schlumberger NV Raised to Overweight at Piper Sandler; PT $55
* TGS Raised to Buy at SEB Equities; PT 175 kroner

>>> Down
* Encavis Cut to Equal-Weight at Barclays; PT 19 euros
* ProSieben Cut to Neutral at Goldman; PT 13.10 euros
* RTL Cut to Neutral at Goldman; PT 60.74 euros
* Stroeer Cut to Sell at Goldman; PT 62.10 euros
* WPP Cut to Neutral at Goldman; PT 1,235 pence

>>> Initiation
* Kraft Bank Rated New Buy at SpareBank; PT 13 kroner
* Richemont Started at Buy by Jefferies, Target Started at CHF140 by Jefferies
* Tinybuild Rated New Add at Numis; PT 210 pence

>>> Call
* AG Barr Raised at Berenberg on ‘Underappreciated Transformation’
* Aixtron Up to Outperform at Exane BNP on MicroLED Opportunity
* Goldman Strategists See Risks to European Margins, Revenues
* Richemont a New Buy at Jefferies With Cartier Still the Standout
* Sainsbury Up to Buy on Resilient U.K. Consumers, Jefferies Says
* Citi Stays Cautious on Fintech, Sees Near-Term Risks at Temenos
* Wood Raised to Hold at Jefferies on Upcoming Major Catalysts

(ZH) Goldman: "Is The Recession Signal Once Again Hiding In Plain Sight?"

Goldman: "Is The Recession Signal Once Again Hiding In Plain Sight?"

Two weeks ago, Goldman's head of hedge funds sales Tony Pasquariello unexpectedly took a contrarian position to the conventionally bullish house view, warning that over the next few weeks, "he called the market lower." So far he has been spot on, and stocks indeed are now lower than they were at the end of March as the retail driven melt up that started in mid-March has once again collapsed.
So what happens next? Well, it depends on whom one listens to: Goldman or Goldman, because while the bank's traditionally permabullish chief equity strategist (for common consumption) David Kostin continues to push the bank's retail clients to buy whatever Goldman has to sell, and as we noted on Friday, Goldman has been selling a lot...
... Pasquariello still refuses to jump on the bullish bandwagon, and instead in his latest Markets and Macro note says that while he is not yet ready to fully subscribe to the recession narrative, he is very close and adds that when all is said and done, "bulls are fighting uphill."
. Below we excerpt from the note which is traditionally reserved for Goldman's most lucrative institutional clients, and which presents a far less optimistic view than that one would glean from reading Goldman's generic (and generally worthless) "house" research.
From Pasquariello's latest "Markets and Macro: From QE to QT":
Let me summarize 23 points in just two lines:
  • the tectonic plates underlying the global investing ecosystem are on the move.
  • that is neither “all good” nor “all bad” for market participants, but the game is getting a lot more complicated.
here’s the run of it ... as always, a taker of feedback and good ideas:
1. Recent price action in spaces like homebuilders (see S15HOME) and transports (see GSSITRUC) has been dreadful, and cause for some contemplation. If you lived through 2006-08, when you observe these charts today, it’s hard not to wonder if the recession signal is once again hiding in plain sight. What I’m getting at here: there’s a message coming from the underbelly of the market that -- rightly or wrongly -- points, with increasing force, in the direction of a growth scare.
2. This stress in the deep cyclicals is consistent with a recent poll of our institutional client base, where over half of the respondents expect a US recession between now and the end of next year. alongside the ongoing heaviness of high yield, this also foots with the interest strip, where Eurodollars are seemingly discounting that the Fed will need to reverse course come 2024. Even though I would argue that geopolitical risk premium has been tamping down over recent weeks -- look no further than the VIX or EM currencies -- other parts of the macro complex are simultaneously dialing up warning signs around the trajectory of growth.
3. To be clear, the GFC was principally a function of the US building far too many homes, while the broader private sector built up far too much leverage. this time around, the setup is fundamentally very different: the US currently has a serious national shortage of housing ... and, the private sector financial balance is far healthier. Furthermore, despite how poorly certain parts of the market trade, also note how well some of traditional mega caps have performed: WMT, KO, JNJ, LLY and COST all marked an ATH this week (reflective of a sensible up-in-quality bias).
4. Where this leaves me: respectful of the flickering red lights on the macro dashboard, while not yet ready to fully subscribe to the recession narrative (see point 10 below). That tension supports my ongoing instinct that S&P will remain in a turbulent range trade -- sell rips over 4500, buy dips below 4200 -- with an overall portfolio bias towards commodities and quality. I also continue to believe that gap risk is more likely to be to the downside and not to the upside.
5. The upcoming barrage of Q1 earnings is apt to be fascinating given the macro cross-currents. As mentioned last week, the bar for Q1 isn’t particularly demanding: 0% expected y/y growth ex-energy, which seems low given the nominal GDP world we live in. The challenge, rather, will be H2’22 expectations of double-digit y/y growth … how guidance around that shakes out will be the key part of the story. As GMD colleague Bobby Molavi put it: “in certain cases it will be the starter gun for broad stroke sell side downward revisions.”
6. I’d argue the biggest development of the week -- a more forceful discussion of Fed balance sheet runoff -- supports a view that the bulls are fighting uphill. I’m inclined to think this is a big deal, and one which will intimidate stock operators on occasion, given what we learned way back in QE2: if you want to adjust financial conditions, the balance sheet is a much more powerful tool than the Fed Funds rate. I had actually pecked out that point before Bill Dudley took off the gloves: “if stocks don’t fall, the Fed needs to force them. In contrast to many other countries, the U.S. economy doesn’t respond directly to the level of short-term interest rates ... financial conditions need to tighten. If this doesn’t happen on its own (which seems unlikely), the Fed will have to shock markets to achieve the desired response.”
7. With respect to positioning, the disjunction between professionals and households persists: our Prime Brokerage franchise has seen selling from hedge funds for five of the past six weeks; over that same period, there’s been $46bn of inflows to equity mutual funds / ETF’s (entirely to the US; credit GMD client Scott Rubner). I suspect the collective flow-of-funds picture skews towards the negative side over the next few weeks, given the buyback blackout window and market talk of a > $300bn capital gains tax bill -- while also noting that retail is the heavy, and if they don’t back down, underlying sponsorship will remain intact.
8. While it’s a guarantee of nothing on the forward, I suspect a significant part of ongoing retail demand for equities begins and ends with a severe lack of good alternatives. Witness this check-down: the real returns on cash are terrible (consider the compounding of inflation over a five or ten-year period, it’s sobering). The nominal bonds you hold -- Treasuries, munis -- just keep selling off. the risk/reward profile of corporate bonds is not at all appealing. Crypto continues to hang in there, but it carries a very low weighting for most actors, and as much as you should love commodities, the volatility is not for anyone.
9. A non sequitur: through the end of 2021, the total return of S&P was positive in 17 of the past 19 years, and the average annual return over the prior three years was +26%. This provokes a few big picture reactions:
  • (1) while those stats belie how hugely difficult the path of risk management was along the way, for strategic holders of risky assets, the getting was so exceptionally good;
  • (2) despite an ongoing boom in genuine corporate innovation, I do worry that some of the underlying drivers that supported profit growth -- the compounding of immense Chinese GDP growth, structurally lower global inflation, low US corporate taxes and an ever lower cost of capital -- could all be in some form of retreat.
10. This is the most interesting point I read all week, credit to Jan Hatzius in GIR: “There has never been an increase in the [US] unemployment rate of more than 0.35pp (on a 3-month average basis) that wasn’t associated with a recession. The broader point is that once the labor market has overshot full employment, the path to a soft landing becomes narrow ... nevertheless, we think a recession is far from inevitable. First, the US recession sample underlying our labor market rules of thumb is small -- 12 in the entire postwar period and just 4 since 1982 -- and there are quite a few instances in other G10 economies in which moderate labor market deterioration did not result in recession. Second, in previous US labor market overheating episodes there was no source of incremental labor supply comparable to the 1-1.5 million prime-age workers that may now be poised to return to the workforce. Third, few of the financial imbalances that made the US economy vulnerable to self-feeding recessionary forces in the run up to the 2001 and 2007-2009 recessions -- especially the giant private sector deficits in the household and/or corporate sector -- are visible now."
11. quick points:
  • i. while acknowledging how volatile local price action has been, Jeff Currie’s mark-to-market on the commodities bull market is worth a glance. The punch line is vividly clear: this is a policy-driven volatility trap ... oil to $125 by year-end and GSCI +28% NTM ... “our conviction in a multi-year super cycle has risen substantially."
  • ii. speaking of commodities and inflation, next Tuesday brings a biggee: CPI. while this print could well mark the cycle high -- consensus on headline is +8.4% y/y -- I suspect the move from peak back towards trend will keep macro traders on their feet a good while longer.
  • iii. do you know when globalization peaked? if defined by global trade as a % of GDP, the peak in globalization was not in 2016 ... it was not in 2019 ... it was actually back in 2008.
  • iv. a reminder: Chinese industrial data peaked in November of 2020. in this spirit, I re-learned something else this week: Chinese debt/GDP is now running around 280%.
  • v. Brazil has enjoyed a remarkable, if surprising trading rally to start the year. For a (cautious) take on where we go from here: link.
  • vi. on the technicals of the all-important US bond market: “The past 24 hours have seen some significant developments transpire in the US rates markets. the most notable is the 1yr1yr Libor Swap ending its secular downtrend with the break above its 2018 high at 3.330%. To our knowledge this is the first US rates market to end its long term bull trend”.
  • vii. in the spirit of April Fool’s -- and, my unabashed fondness for Taco Bell -- this warrants mention: “the Taco Liberty Bell was an April Fool's Day joke played by fast food restaurant chain Taco Bell. On April 1, 1996, Taco Bell took out a full-page advertisement in seven leading U.S. newspapers announcing that the company had purchased the Liberty Bell to ‘reduce the country's debt’ and renamed it the ‘Taco Liberty Bell’”.
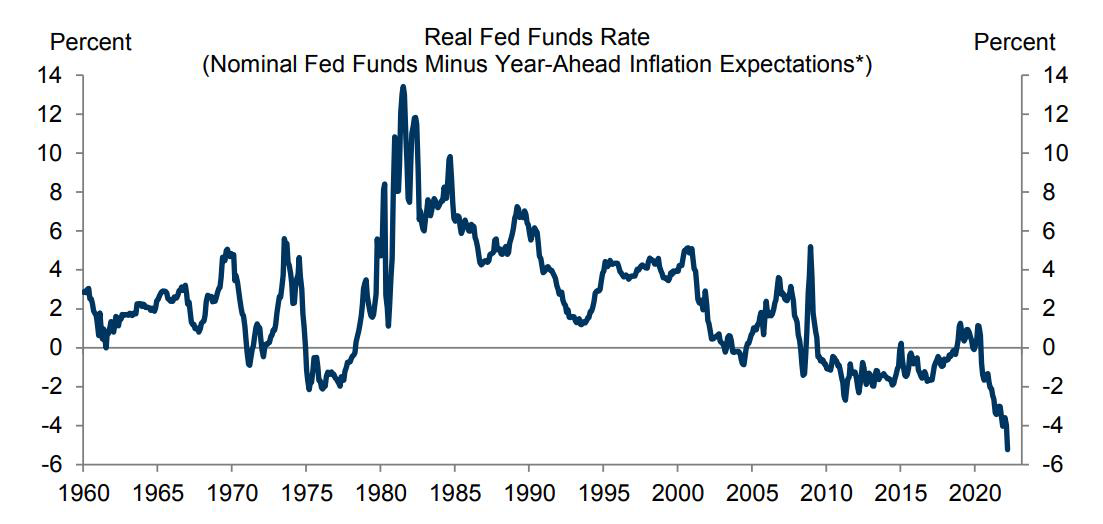
12. This plots the real Fed Funds rate, with the inflation adjustment coming from market-based expectations. It levels sets just how crazy easy the starting point is for this tightening cycle -- perhaps part of the reason stocks have held up decently of late -- while also inviting the question of “how could this possibly get any better from here”:
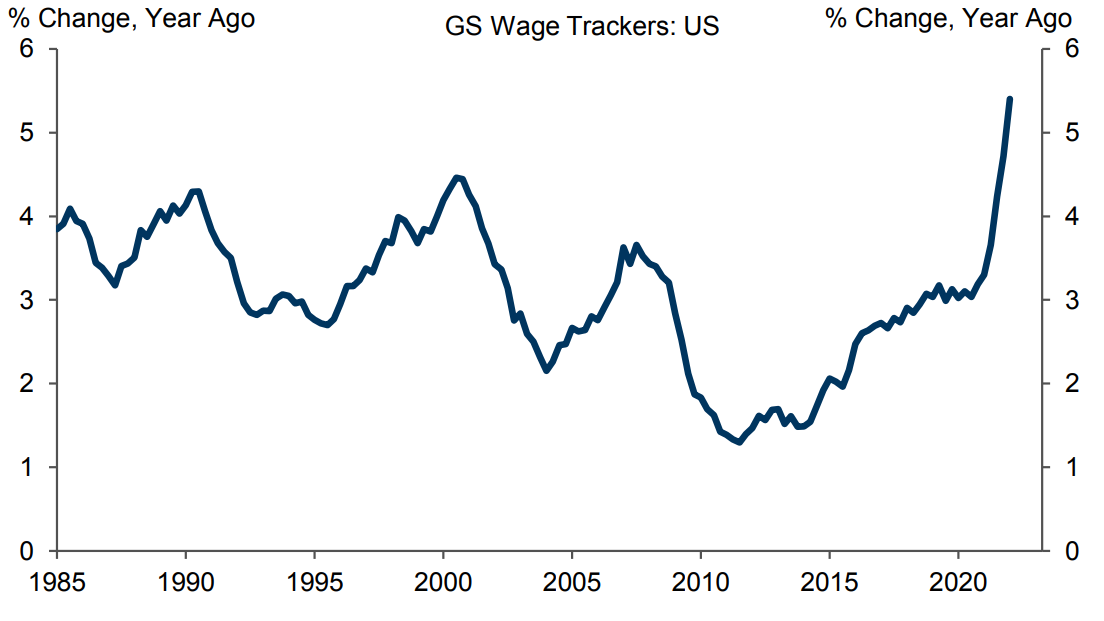
13. Then there’s this show stopper -- also subject to your interpretation -- the GS wage tracker. My view: while it’s hard to think the gradient of this slope can be sustained forever, I also don’t see it turning meaningfully lower anytime soon:
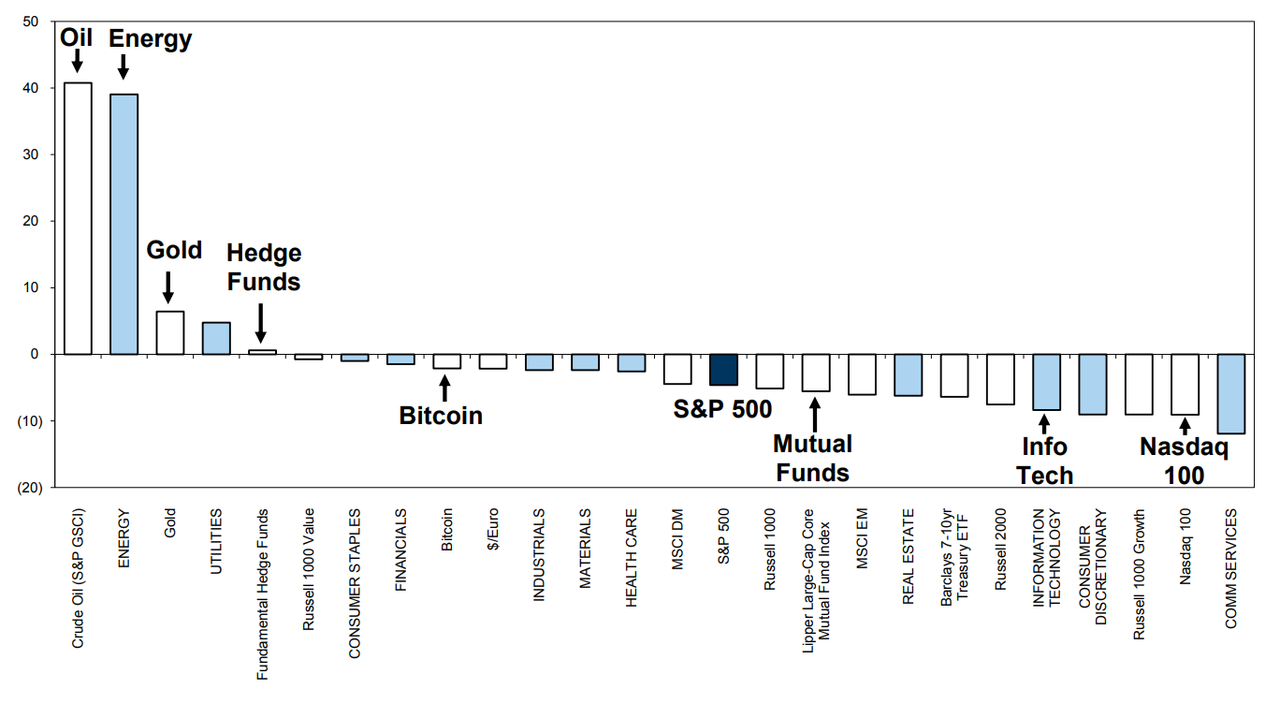
14. A chart that (actually) tells you everything you need to know about Q1:
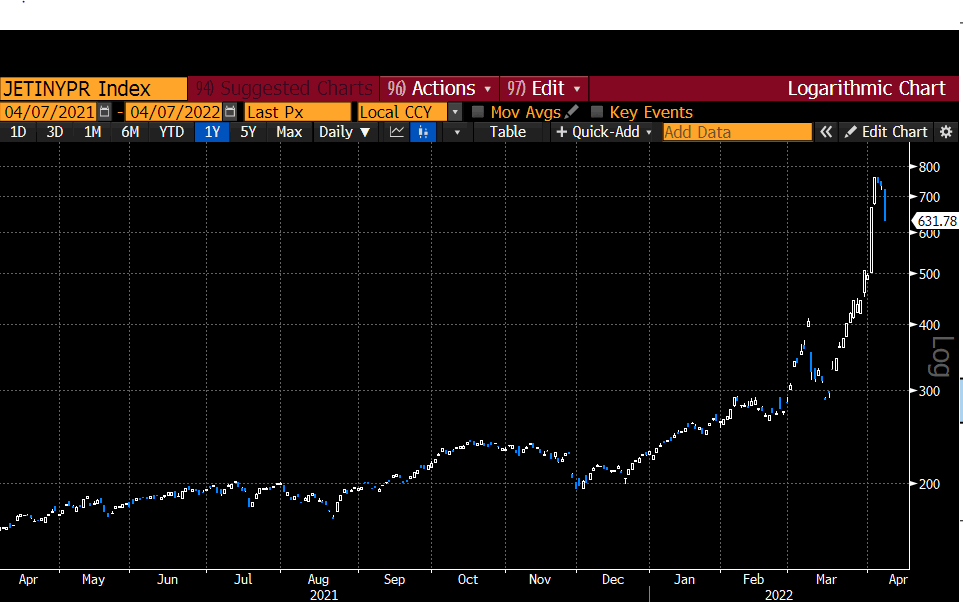
15. Speaking of energy prices ... this is what the cost of jet fuel looks like. From Callum Bruce in GIR: “ultimately, it’s a specific locational issue that is not significant to broader balances, but is nevertheless symptomatic of tight market and shows the binding, physical nature of commodity shortages and their large upside convexity at low storage levels. more of these events are in store.”
16. The more I travel around, the more I think the primary destination for capital is the US for now. In a similar vein, the market is very clearly rewarding companies with leverage to the US vs those with leverage to offshore revenues:
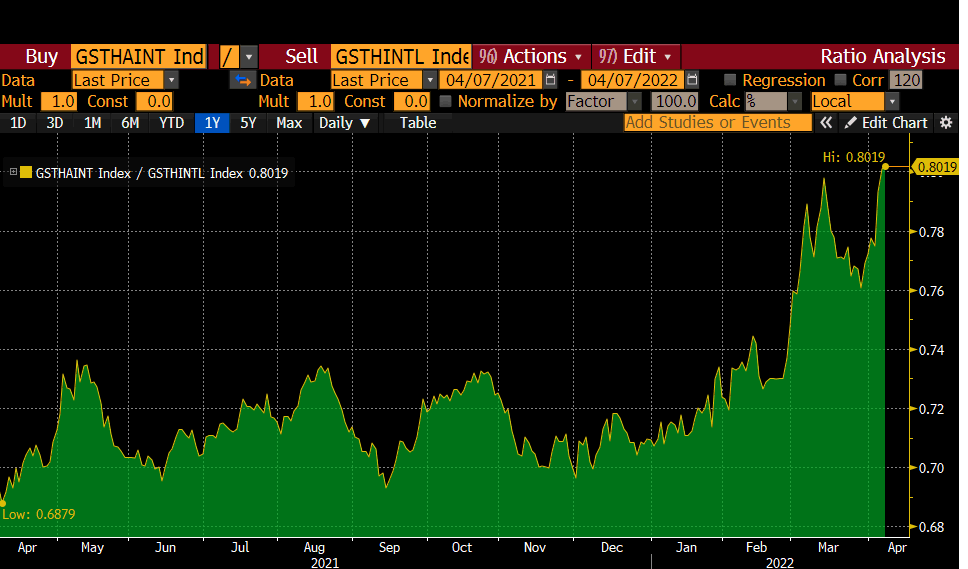
17. Scott Feiler, GMD: “at the idea dinners I attended in November/December, shorting the low-income consumer was the most popular idea. that was just due to compares, lack of stimulus, lack of child tax credit etc. that had not even contemplated higher gas prices. here we are though at the end of 1Q and our GS low-income basket outperformed the high-income basket by 500 bps. many of the low-income stocks have heavy consumables exposure and have simply outperformed. Our conversations have shifted dramatically the last 3 weeks, with investors looking to more middle-income type names that are heavily discretionary and have chunky dollar purchases that a consumer might forgo ... our baskets team put a basket together last week that they think addresses this theme, with the title being the ‘middle income discretionary basket’ (ticker GSCNSMDI Index).” note the ratio of this basket vs S&P.

CruncBase : The Week’s 10 Biggest Funding Rounds: Remote Brings Home $300M, Gran

The Week’s 10 Biggest Funding Rounds: Remote Brings Home $300M, Grand Ole Opry Raises $293M

Some weeks are heavy on fintech, others are big on biotech. This week, however, was all over the board. From HR solutions that help hire workers overseas to a legendary music landmark to crypto, investors spread their money far and wide. They also spread a lot of it around. Six rounds that went to U.S.-based companies were of $200 million or more.
1. Remote, $300M, human resources: Companies are finding it harder to find good employees and are having to cast a wider net. That is where San Francisco-based Remote can help. The company calls itself an “employer of record service”—allowing companies to make hires and handle payroll and compliance in countries where they don’t have existing operations. It also can help businesses manage independent contractors worldwide. That business model is attractive right now, and less than a year after closing a $150 million Series B at a valuation of more than $1 billion, Remote raised a $300 million Series C led by SoftBank Vision Fund 2.
2. Opry Entertainment Group, $293M, media: Yes, even Nashville, Tennessee’s famed Ryman Auditorium is receiving funding. Atairos and NBCUniversal took a 30 percent stake in the Opry Entertainment Group, which consists of the “Grand Ole Opry” stage show and media rights, the Ryman Auditorium, a radio station and the “Grand Ole Opry” streaming channel. The deal comes to a $293 million investment, with Atairos agreeing to invest another $30 million if certain performance targets are met. The deal values the media and entertainment company at $1.4 billion—which surely would stop even the legendary Hank Williams from “Moanin’ the Blues.”
3. (tied) Fetch Rewards, $240M, e-commerce: Everybody loves to be rewarded when they shop. Investors are hoping to be rewarded for their new deal with Madison, Wisconsin-based Fetch Rewards. Fetch, a consumer-rewards app, locked up a $240 million equity and debt round led by Hamilton Lane on behalf of clients that raised the company’s valuation to $2.5 billion. The company—whose digital loyalty and marketing platform has more than 13 million active users—has now raised more than $500 million.
4. (tied) Grafana Labs, $240M, analytics: People must really love to be able to visualize analytics. Just seven months after closing a $220 million Series C, New York-based Grafana Labs locked up a $240 million Series D led by GIC, with participation from new investor JP Morgan. The company’s open-source software platform helps monitor and visualize data. Founded in 2014, the company has now raised more than $535 million, according to Crunchbase data.
5. Binance.US, $200M-plus, crypto: San Francisco-based crypto exchange platform Binance.US—the American franchise of Binance—closed a seed round of more than $200 million at a pre-money valuation of $4.5 billion. The deal included investment by RRE Ventures, Foundation Capital, Original Capital, VanEck, Circle Ventures and others. The round is yet another signal of investors’ appetite for all things crypto—especially in this case where they are investing in the U.S. franchise of the world’s largest crypto exchange.
6. Neiman Marcus Group, $200M, retail: Dallas-based apparel retailer Neiman Marcus Group received a $200 million minority equity investment from online luxury fashion platform Farfetch.
7. LogicSource, $180M, enterprise software: Norwalk, Connecticut-based procurement platform LogicSource raised $180 million from FTV Capital. The company has now raised a total of nearly $230 million, according to Crunchbase data.
8. Clarify Health, $150M, health care: San Francisco-based Clarify Health, a cloud analytics and platform for better health care, secured a $150 million Series D financing led by SoftBank Vision Fund 2.
9. BostonGene, $150M, health care: Waltham, Massachusetts-based biomedical software developer BostonGene closed a $150 million Series B led by NEC Corp.
10. IntelyCare, $115M, health care: Quincy, Massachusetts-based IntelyCare, a tech-enabled nurse staffing platform, raised a $115 million Series C led by Janus Henderson Investors at a $1.1 billion valuation.
Big global deals
The three top deals were done outside the U.S. this week, including a raise by a retailer at a whopping $100 billion valuation—a centa-corn?

TechCrunch : The US needs a tech doctrine

The US needs a tech doctrine

The TechCrunch Global Affairs Project started with a simple premise: that technology is increasingly intertwined with global affairs and that we ought to examine what that means for both. From crypto to climate, international development to defense procurement, I hope we’ve done just that.

Reflecting on the nearly 40 pieces we’ve published over the last few months, I can’t help but see a few common threads emerge: Tech industrial policy is increasingly in favor. Emerging tech is top of mind. And where China isn’t setting the pace, it isn’t far behind.

While the U.S. has made remarkable strides in meeting these challenges (see my piece on the State Department’s new cyber bureau), it still lags on perhaps the most important one: navigating the increasing fusion of geopolitics and technology. If the U.S. is to succeed in the contest for the 21st century, it needs more than new agencies or investments in infrastructure (however large they may be). Even an industrial strategy is insufficient.

What America needs is a geopolitical technology doctrine.

What do I mean by a doctrine? Well for the most part, technology policy can be seen in two ways. The first is as a new security domain. The public and private sectors have spent billions of dollars improving our cyber capabilities to both protect our civil and military networks and acquire the ability to strike our adversaries. While many of our networks are still woefully vulnerable, we generally know the challenges and are making strides to shore up our defenses.

The second follows the thesis that the future will be won by whichever country controls (and integrates into its economy) the most advanced technologies. Thus tech policy becomes a function of broader economic competition. This is the ground on which much of our current debate is held — are we on the right track on emerging tech like 5G, quantum or artificial intelligence? Are our supply chains secure? What regulatory edge can we give American tech companies? How can we work with allies to jump-start those efforts?

These two facets of technology policy are incredibly important — and well worth the attention paid to them in this series and elsewhere. Look only to Russia, which has found itself cut off from Western tech supply chains and software updates as a result of its invasion of Ukraine.


But they shortchange a significant element of tech’s role in geopolitics that I hope we’ve raised here as well. That yes, tech is an asset. But like other economic resources (ahem, the U.S. dollar), tech can also be a leverage point that gives policymakers clever ways to further broader foreign policy interests. Yet for the most part, we have not thought systematically about how to wield this power — or protect it.

Our rivals aren’t so diffident. As with many asymmetric capabilities, it’s the authoritarian regimes, unconcerned by scruples over such things as human rights or the rule of law, that have pioneered creative and effective — if odious and unethical — geopolitical tech strategies.

Early in our series, Scott Carpenter warned about the baleful trend of dictators simply shutting down the internet to deprive their citizens of information. Matthew Hedges and Ali Al-Ahmed wrote about how regimes have deployed spyware to hunt down dissidents — and how countries like Israel have exported this technology to lubricate their own diplomacy. Jessica Brandt explored how Russia and China use social media to spread disinformation that discredits the West. And Samantha Hoffman wrote about how China uses data its firms collect to acquire intelligence around the world.

Obviously these are not practices democracies should emulate, and even if they wanted to, law, custom and democratic accountability would mostly preclude it. And the U.S. and its allies can’t make tech companies arms of the state. But they do raise important questions about where technology fits in American statecraft.

For the last two decades, American tech companies have dominated the landscape with a simple strategy: growth at all costs. And the U.S. government, equating tech’s success with America’s, has let tech — especially Big Tech — do just that, essentially ceding the regulatory space until quite recently.

But the world is too sophisticated, and “growth” too blunt a tool, for that to remain the goal moving forward. Should tech supremacy be pursued for its own sake as an expression of American soft power? For economic position? As a means to best our rivals? Or because it is something that can be weaponized?

The answer can’t just be “yes” and “more.” We need a new framework that reconciles what tech can do with what it should do — and with what we as a nation need it to do.

Even if we can agree that U.S. interests are served by technological dominance, that still leaves a crucial question unanswered: How should tech be wielded geopolitically?

Western technology export controls on Russia in response to its invasion of Ukraine are an encouraging use of geotechnological hard power. But Washington can be even more creative; it might use an emerging technology like crypto to bolster U.S. dollar dominance, like Connor Spelliscy suggested or deploy technology to enforce treaties we value, as Thomas McInerney described.

But America is most effective when it plays to its strengths, building upon alliances, networks and the rule of law. That might entail using technology as a tool to expand democracy, per Vera Zakem; stepping in, as Australia did, to build a cable to Pacific islands in lieu of China; or working with Apple and Google to protect dissidents. The U.S. should also take lessons from Ukraine’s creative information campaign against Russia to deploy in future conflicts.

Rather than fruitlessly trying to dictate outcomes, a better strategy would be to encode liberal values in emerging technologies. China has recognized that growing its tech sector is not enough if it doesn’t also set the rules of the road. That’s why it has become very successful at dominating the global fora that set new technology standards. And it’s not just a question of writing rules that benefit Chinese companies (i.e., Huawei in 5G); if authoritarian regimes are able to encode their repressive values in the rules and norms around critical emerging technology like AI, autonomous weapons or biotechnology, it could pose a serious threat to freedom and human rights everywhere. The U.S. and its allies must do the hard work to push back by attending to the patient, technical diplomacy that they have too often overlooked.

Above all, a proper geopolitical tech doctrine would, like all good strategic concepts, recognize limits. The U.S. is no longer Colossus bestriding the world, and it would be folly to think it can impose its will, even on its allies. Americans can’t achieve internet freedom just by wishing it so — and should accept that not every country’s internet needs to be identical for a free and open internet to succeed. If Apple, with a single policy decision, can cut Facebook’s market capitalization by a quarter, there’s no reason why (democratic) governments shouldn’t be able to have reasonably different regulatory regimes in their own jurisdictions.

Americans (and American tech companies) have grown used to having it all. But as technological supremacy becomes increasingly central to geopolitics, tech policy will no longer be made in a vacuum. Politics is the art of making choices, and Silicon Valley doesn’t have to like all of Washington’s. Perhaps, from Washington’s point of view, the global ambitions of American tech firms are no longer tenable if they clash with our values and interests.

What might that mean? Western tech firms have just shown that they can choose sides, voluntarily leaving Russia to either show solidarity with Ukraine or to not violate their principles by censoring their content. Meta and Elon Musk are now heroes in Ukraine; the former for permitting users to call for the death of Putin and Russians; the latter for deploying his StarLink platform to ensure Ukraine stays online.

But harder trade-offs beckon: Should Apple and Tesla give up their Chinese factories? Should America force Chinese tech firms like TikTok from its shores? Having set the precedent in Russia, these are realistic scenarios that Washington might consider — and that Silicon Valley must plan for.

Zooming out, what happens when American tech priorities conflict with broader diplomatic agendas? Should the U.S. government ally with Brussels on antitrust, or stand up on behalf of U.S. tech companies? What happens when the interests of the tech sector conflict with stability in Taiwan or progress on climate change? These are essential questions that are as yet unanswered.

Meanwhile, national security planners must consider that we are once again in an era of great power war. The Ukraine conflict has surprised many with its conventionality — but it has also proven a testing ground for new tech like drones. We are also seeing a war play out in a fully online society for the first time — don’t discount the immense soft power Ukraine has yielded through social media. Would Western support be so strong without Kiev’s polished online presence (or propaganda, as one might call it)?

A year ago, I asked how tech factored into U.S. foreign policy. America is surely in a better place than it was then. Technology is rightly taking center stage in its foreign affairs and national security agendas.

But if the U.S. is to maintain its leading global role – much less avoid falling behind its rivals — it must do more than foster innovation and develop new capabilities with little more justification than “for innovation’s sake.” It must develop a doctrine that comprehensively considers how all aspects of technological statecraft — cyber, antitrust, regulatory, supply chains, basic science, standards, not to mention the role of tech companies themselves — can best serve U.S. foreign policy objectives. Failing to do so doesn’t just risk strategic muddle, but wasting perhaps America’s greatest assets: its entrepreneurial and scientific excellence. Nothing less than American power, prestige and prosperity are at stake.