FT : City bosses warn of UK recession this year

City bosses warn of UK recession this year
FT executive network members raise concerns that managers lack experience in handling economic shocks

City of London bosses have warned that the UK faces a damaging recession later this year and raised fears that managers lacked experience in dealing with severe economic shocks.

The FT’s City Network, a forum of more than 50 senior executives from finance, business and policymaking, said that policymakers faced difficult decisions on how to mitigate the worst effects of an economic downturn.

“It’s not pretty,” said Amanda Blanc, chief executive of Aviva, the insurer. “The risk of a recession looks real . . . Even if we miss a technical recession, we see a weak outlook for growth. Stagnation is a clear possibility.”

Anne Richards, chief executive of Fidelity International, said the key risk to economic stability was “stubbornly high inflation, even as demand slows, which forces the central bank to keep hiking into a sustained and deep recession”. 

Economists have said it is increasingly likely that the UK will sink into recession this year. The Paris-based OECD last week cut its UK growth forecast for 2023 to zero, the lowest in the G20. The Bank of England raised interest rates to 1.25 per cent last week to tackle fast rising inflation, which is expected to reach 11 per cent by October.

Paul Drechsler, former president of the CBI and chair of lobby group London First, warned that recession was likely to hit many major economies — the “key questions are how deep and how long”, he added.

Sir Win Bischoff, a senior banker and former chair of Lloyds Banking Group, added that policymakers needed to decide whether to pursue “a short, sharp shock or a slow but ultimately more painful reduction in GDP”.

“Central bank orthodoxy almost universally would suggest the former but political sensitivities incline towards the latter. Even without any drastic action by the central bank, it is possible that the UK could face a recession.”

Low unemployment and high consumer spending offered positive signs, according to Ann Cairns, vice chair of Mastercard.

But she added: “Despite this consumer spend, we may be at the start of a recession. One where business leaders, policymakers and central bankers might see themselves as wartime leaders. Not just because of war in Ukraine but because of all the supply side shocks we are living through coming out of Covid.”

With inflation set to rise in the autumn to as high as 11 per cent according to the Bank of England, alongside continued energy cost hikes and disruption because of war in Ukraine, many City bosses identified the threat of sustained economic pressure.

Mervyn Davies, a senior banker and former Labour minister, said that it felt “as if the world has changed for the worse in a very fundamental way during the past few months”.

“It will not return to the previous normal in the foreseeable future,” he said. “Energy cost disruption, supply chain dislocation, vicious cost of living increases, shortage of key materials are just a few of the huge pressure points.”

Even with the cost of living crisis dominating the headlines, Andreas Utermann, chair of Swiss investment group Vontobel and former chief of Allianz Global Investors, said that “almost everyone is underestimating the inflation risk”.

The sort of downturn triggered by supply side shocks was not something that had been seen by most managers and investors, according to City leaders.

“The natural inclination of company boards, embedded over their experience of the last several decades, may well be to make short-term decisions based on the environment we are leaving behind rather than the one we now face, and as a consequence pivot too late,” said Richards.

The experience of dealing with a recession “lies far in the past in the minds of by now retired managers and mistakes are bound to be made by their successors”, Bischoff also warned.

Sustained stagflation — the combination of high inflation and low growth — appeared to several of the City Network to be less of a risk.

James Bardrick, head of Citi in the UK, said the Queen’s platinum jubilee celebrations seemed to have helped the economy avoid the hard “headline” of technical recession.

He added that the UK was on course to suffer two negative, nonsequential quarters of GDP growth in the second and fourth quarters — but the “ghastly stagflation of the type that I experienced as a youngster in the 1970s” was less likely.

Many also raised concerns about government policy, including the destabilising impact of the threat of a trade war with the EU over Northern Ireland.

Most argued that the government needed to work more closely with business to weather the period of economic disruption.

Cairns said that business and government leaders needed “to keep an eye on the longer term, as short-term cuts and short-sighted decisions can be very harmful”, pointing to the need for continued investment in net zero carbon emission strategies.

“Clear and consistent policy direction stimulates the confidence and certainty businesses need to continue investing in the UK,” said Blanc.

Former BT and KPMG chair Mike Rake worried that the government did not appear to have a clear or coherent strategy for handling the downturn, however.

“It seems to be distracted by divisions within its own party and short-term politics seemingly aimed to divide rather than unite the UK whilst damaging our reputation and influence internationally.”

Davies noted that there was a wider societal impact to consider. “Today we all face a very uncertain future . . . my worry is whether the global political elite can handle this and ensure the divides in society do not widen.”

But Guy Hands, boss of private equity group Terra Firma, said that he was “not sure if there is any way to protect wealth in a situation closer to the late 20s and early 30s than the 70s.”

“We might actually see the top 25 per cent of society getting closer in wealth to the bottom 25 per cent but not through a levelling up,” he added.
FT : EU plans sanctions if partner countries breach labour and sustainability ru

EU plans sanctions if partner countries breach labour and sustainability rules
Talks with India will present first challenge as EU increasingly uses economic muscle to change policies elsewhere

The EU will propose new rules this week that would allow it to impose trade sanctions against countries that breached conditions on labour rights and climate change in bilateral deals with the bloc.

Valdis Dombrovskis, EU trade commissioner, said in an interview he wanted to put “sustainability at the heart of trade policy” by improving enforcement of the trade and sustainable development (TSD) clauses in the deals.

The move comes days after the World Trade Organization clinched its first agreement on sustainability and trade, limiting subsidies for vessels fishing in unregulated international waters and for overfished stocks.

Dombrovskis said the fishing deal marked “a real turning point” after 21 years of talks. “Sustainability has gone from a side show to being centre stage when it comes to global trade. It shows there is now greater willingness by the global community to address these issues.”

The EU has included TSDs in all trade deals since 2009 but has rarely used them to force trading partners to change domestic policies. “We will be outlining our new approach on sustainable development chapters in our bilateral trade deals, including by stepping up enforcement and implementation of sustainability commitments,” Dombrovskis said.

The new rules, to be formally agreed by the European Commission on Wednesday, are likely to win broad acceptance among member states and in the European Parliament, which must approve them.

They will include tighter enforcement of TSDs in new trade deals and the ability to impose sanctions such as tariffs if countries breach “core provisions”, according to people briefed on the plan. Those core provisions meet the standards of the International Labour Organization and the Paris agreement to cut carbon emissions, the people said.

The EU has found it increasingly hard to ratify trade deals in all 27 member states without addressing concerns that they will cause environmental destruction or labour abuses as partners increase production to meet EU demand.

Brussels has negotiated a deal with South American trading bloc Mercosur, which includes Brazil and Argentina, but several EU countries have refused to ratify it until Brazil signs a side letter promising to protect the Amazon rainforest.

“If we want to get more bilateral trade deals done . . . we have to reinforce sustainability commitments”, Dombrovskis said.

However, both parties to any trade deal would have to agree with the EU conditions. The first big challenge could come in talks with India, known as a tough negotiator, which restarted on Friday after a decade.

At last week’s WTO gathering, Piyush Goyal, India’s commerce minister, refused to cut most fishing subsidies in domestic waters, saying developed nations had “allowed their gigantic industrial fleets to exploit and plunder the ocean’s wealth over the past several decades”.

A proposed deal with New Zealand is largely finished and would not be affected.

Dombrovskis said the WTO’s ministerial conference in Geneva last week had put “multilateralism back on track”. 

As well as a plan to make it easier for poorer countries to make cheap copies of Covid vaccines, trade ministers agreed to limit food export restrictions to tackle global food shortages. They also temporarily extended duty-free trade in digital products such as films, computer software and data,

“When the globe is facing a multitude of acute challenges, stronger and better global rules are more important than ever,“ the trade commissioner said.

The EU is increasingly using its muscle as the world’s largest trader to change policies in developing countries. Earlier this year it proposed imposing tariffs on countries that block the return of deported migrants.

But the EU’s use of trade to export its values globally has previously faced resistance. Jair Bolsonaro, Brazil’s populist president, in 2019 told Berlin to “reforest Germany” when it said he was failing to protect the Amazon.

FT : Talent war in the funds industry is driving a ‘great negotiation’

Talent war in the funds industry is driving a ‘great negotiation’
Employees have more options and fund firms are having to work to keep staff, says JPMorgan Asset Management chief George Gatch

A fierce and broad talent war in the asset management industry is driving a “great negotiation” as employers fight to retain and attract staff, according to the chief executive of JPMorgan Asset Management.

“We have to work more closely to keep people on board” because “people have more options,” said George Gatch in an interview. “I don’t call it the great resignation. I call it the great negotiation,” he added, referring to the elevated rate at which workers quit their jobs during the pandemic.

The breadth of competition for talent has widened beyond the mainstream asset management industry. As well as their traditional rivals, groups such as JPMorgan Asset Management, an active-management house that mostly sells to retail investors, are now competing with alternatives firms that are expanding their footprint in the retail market and are also going head to head with tech companies in the battle to lure engineers.

Gatch, who joined JPMorgan in 1986, said the firm was “working really hard” to appeal to “younger people and particularly tech savvy people”. JPMorgan Asset Management employs 1,500 technologists globally and spends $500mn on technology each year. Overall it has $2.5tn in assets under management.

“It’s about competitive compensation, but as important are the other things as well,” he added, pointing to factors such as a company’s culture, environment, people and opportunities on offer.

In the war for talent, Gatch said the asset management industry needs to do a better job of “conveying the purpose and the fulfilment that could come out of building products and services that are pretty fundamental to people’s lives. Helping people save for college, pay for your child’s wedding, your parents retirement, your own retirement.”

Last year JPMorgan Asset Management bought Campbell Global, an investment manager focused on timberland, to expand its position in alternatives. The previous year it acquired 55ip, a fintech company that allows financial advisers to deliver tax-smart investment strategies at scale.

Now the focus is on organic growth rather than deals. “I don’t really see a gap in our offering or any urgent strategic priorities,” said Gatch. “The hurdle is very high for us to do something. It’s very difficult to be successful integrating strong cultures and integrating two asset management firms. So where we have done acquisitions, we’ve been focused on incremental capabilities.”

Gatch said that while the wider asset management industry is still highly fragmented and scale has become increasingly important, he thinks that large, transformational deals are “less likely” in the current environment of tougher markets. He sees areas such as environmental, social and governance strategies, alternatives and exchange traded funds as the most likely target areas for industry deals, as firms look to tap into strong investor demand for these areas.

Market volatility, Gatch believes, means that “active [management] is back.” He said: “Fundamentals have been reset. And I think that is key for the role that active can play over the next cycle.”

Back in 2014 JPMorgan Asset Management launched its first actively managed ETF business, a type of investment that combines stockpicking normally associated with mutual funds with the convenience and tax benefits of ETFs. It has subsequently grown to almost $90bn in assets.

Gatch predicts that in the long term “ETFs will overtake mutual funds”. Increasingly, he believes, investors are seeing the ETF structure as superior to the mutual fund because of its tax efficiency, lower transaction costs and ease of use. “I think the active ETF industry is at a tipping point in the US and will grow rapidly.”

(ZH) History Is Not On The Side Of Crypto's Grave-Dancers

History Is Not On The Side Of Crypto's Grave-Dancers

On June 12, 1817 in the city of Mannheim, Germany, a local inventor by the name of Karl von Drais unveiled a brand new, futuristic invention he had just developed.
It was called a laufmaschine, or “running machine” in German. And it was essentially the world’s first bicycle.
There were no pedals, no seat, and no chain to connect the wheels; the rider basically had to propel the laufmaschine with his feet, then balance on it once achieving sufficient momentum.
It was crude, but it worked.
And von Drais showed off his machine to the world that summer day by riding 7 kilometers in roughly one hour.
The reaction was instantly divisive.
Some people thought the laufmachine was as significant as cave men inventing the wheel, and they envisioned a future world in which bicycles dominated transportation.
Others thought it was a silly, unnecessary, dangerous invention. And many in the press derided von Drais’s invention, pejoratively calling it a “dandy horse”.
Plus several governments, including in the United Kingdom, the US, and even Germany, banned its use for posing too much risk to pedestrians.
Nevertheless, the development of the bicycle persisted over the next several decades, and public interests grew.
By the early 1880s, cycling had become incredibly popular. Even the Queen of England owned a bicycle, making it highly fashionable among Britain’s elite.
The most advanced bicycle design in the world at that time was called the ‘penny-farthing,’ which is the one you’ve probably seen in old photos. It had one ridiculously large wheel, and one tiny wheel.
The penny-farthing was fast… but incredibly unstable. Cyclists cruising at high speed would often flip over the handlebars after hitting one of London’s many potholes– which they referred to as “taking a header”.
The rapidly growing popularity of bicycles prompted inventors and engineers across Europe to work feverishly on new, safer designs and innovations; there was so much brainpower devoted to cycling that, by 1896, a full 15% of British patents were issued for bicycle designs.
The entire industry exploded. Bicycle factories, tire factories, repair shops, and sales shops were everywhere.
In the city of Birmingham alone, the number of bicycle manufacturers grew from almost nothing in the early 1880s, to 177 by the mid 1890s.
‘Bicycle mania’ was in full swing. So naturally it didn’t take long for the bankers to get involved.
In 1895, 70 bicycle-related companies went public on stock exchanges in the United Kingdom. In 1896, that number swelled to 363. And just in the first six months of 1897, another 238 were listed.
Most of these companies were totally hollow; they had no useful intellectual property, no plan to generate revenue, no professional management or engineering talent, and no hope to generate profit.
They simply went to the market and said, “I’m in the bicycle business,” and their stock prices soared.
Bicycle stocks became so popular, and rose so quickly, that the Financial Times devoted a section of its daily newspaper to the industry. And Cycling magazine had a financial section discussing stock prices in the industry.
The air finally came out of the cycling sector in the middle of 1897, with the ‘Bicycle Index’ falling more than 70% from its peak by the end of 1898. By 1900, roughly HALF of the bicycle companies that had gone public were no longer in business.
Along the way, there were plenty of skeptics in the media who thought bicycle mania was a ‘scam’, or who thought the technology was a bunch of hooey.
After the bust in the late 1890s, these same skeptics predictably began dancing on the graves of the fallen companies, convinced that they had been proven correct.
Except the skeptics weren’t correct.
When the bicycle bubble burst, the poor quality companies and idiotic designs all got washed away. But the great business and the great designs survived.
Dunlop Tires is a great example; it’s still one of the biggest tire brands in the world today, and it got its start during Bicycle Mania in 1890.
More importantly, the fundamental technology has proven to be extremely sound. Bicycles have become ubiquitous around the world. Plus they directly influenced the development of the automobile.
This is similar to many financial bubbles throughout history, especially those that are sparked by new trends and technologies.
There were plenty of idiotic ideas and useless companies that went public in the 1990s during the dot-com boom. And when the bubble burst, many of them were washed away forever.
But there are plenty of successful businesses which still dominate today, including Amazon, Google, and Nvidia, that were founded during the mania of the 1990s.
More importantly, the bursting of the dot-com bubble did not invalidate the potential of the Internet and how much it would change our lives.
And that leads me to where we are today. Cryptocurrency is the latest technology to go through this boom/bust cycle.
Crypto has actually gone through multiple boom/bust cycles in its relatively short existence; in the last cycle the price of Bitcoin fell 85% from its peak, before rising ~20x in the next cycle.
All along the way there have been skeptics calling cryptocurrency a ‘scam’ and ‘dangerous’.
(Remember, there was a time in the early 1800s when multiple governments even outlawed bicycles because they also considered that technology ‘dangerous’.)
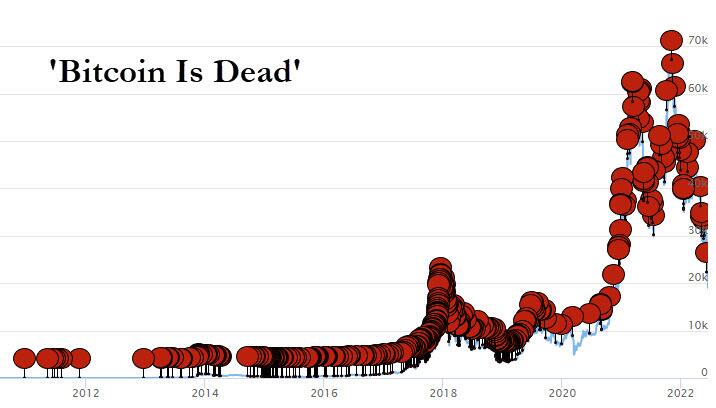
The price of Bitcoin is now down ~70% from its most recent peak. And, almost on cue, the crypto grave-dancers (like Bill Gates) are now insisting that they were right for predicting its demise.
[ZH: As 99Bitcoins.com tracks, there have been (at least) 453 declarations of the death of Bitcoin since 2010...]
If history is any guide, this is pretty foolish.
The fact that a technology attracts manic boom/bust capital is no reflection on the technology itself. It is a reflection on the market’s tendency towards irrationality.
This was the case with bicycles and the Internet. And it will most likely be the case with crypto.
There will be plenty of crypto businesses, and many tokens themselves, that will (and should) go bust.
But there are still plenty of great projects and great ideas out there– most notably, the fundamental idea of having a decentralized financial system.
Our traditional financial system, dominated by clueless politicians and out of touch central bankers, has been a total disaster. It is responsible for the record-high debt and record-high inflation which are disrupting the lives of literally billions of people.
Given these conditions, the decentralized financial system that cryptocurrency represents makes more sense than ever. And the fact that Bitcoin is going through another ‘down phase’ in the market cycle bears absolutely no relevance to its value whatsoever.
History is almost invariably on the side of innovation. And there’s still an abundance of innovation in crypto.

FT : US economy will slow but recession not inevitable, says Janet Yellen

US economy will slow but recession not inevitable, says Janet Yellen
Treasury secretary tries to ease investor fears over stubbornly high prices and rising interest rates

US Treasury secretary Janet Yellen said on Sunday that she expected the economy to slow but that a recession was not “inevitable”.

“I expect the economy to slow, it’s been growing at a very rapid rate as the labour market has recovered and we’ve reached full employment,” Yellen said on ABC’s This Week. “We expect a transition to steady and stable growth but I don’t think a recession is at all inevitable.”

She said US president Joe Biden’s top priority is to bring inflation down, which she reiterated was “unacceptably high”.

The US Federal Reserve kicked up its response this week, raising its main interest rate by a historic 0.75 percentage points, the first time it has done so since 1994.

The Fed has also set the stage for much tighter monetary policy in the near term, with officials projecting rates to rise to 3.8 per cent in 2023 and most of those increases scheduled for this year. They now hover between 1.50 per cent and 1.75 per cent.

On Saturday, Fed governor Christopher Waller said he would support another 0.75 percentage point interest rate rise at the central bank’s next meeting in July if, as expected, data showed that inflation had not moderated sufficiently.

Fed chair Jay Powell has said his goal is to bring inflation down while maintaining a strong labour market.

“That’s going to take skill and luck, but I believe it’s possible,” Yellen said.

Other senior officials on Sunday repeated the line that recession was not inevitable, even as recent surveys show economists and business leaders expect one next year.

“Where we are in the economy right now is a transition and I’ve spoken to CEOs over the past week from sectors across the economy and they’re figuring out how to navigate the transition,” said Brian Deese, director of the US National Economic Council.

Loretta Mester, president of the Federal Reserve Bank of Cleveland, said she was not predicting a recession, but acknowledged “the recession risks are going up”.

“I’m not predicting a recession,” she said. “We do have growth slowing . . . and that’s OK, we want to see some slowing of demand to get in better line with supply.”

Mester predicted that it would take two years to get inflation to meet the Fed’s 2 per cent goal because, while monetary policy can target the excessive demand in the economy, it will take time to get the supply side “to come back into better balance”.

“It isn’t going to be immediate that we see 2 per cent inflation, it will take a couple of years, but it will be moving down,” she said.

Yellen said that while there was month-to-month volatility in consumer spending, overall it remained strong and she did not expect a drop off in spending would cause a recession.

“It’s clear that most consumers, even lower-income households, continue to have buffer stocks of savings that will enable them to maintain spending,” the Treasury secretary said. “I don’t see a drop off in consumer spending is a likely cause of the recession in the months ahead.”

The labour market also remained strong, she said, with two job openings for every unemployed worker.

Yellen reiterated the Biden administration’s argument that Russia’s war on Ukraine was partly to blame for high inflation because it boosts global food and energy prices. Supply chain snarls from lockdowns in China are also contributing, she said. Though these factors will not change immediately she said she expected inflation to go down.

“I do expect in the months ahead that the pace of inflation is likely to come down, although, remember there are so many uncertainties relating to global developments,” she said.

Deese said Biden was working with Congress on legislation to lower costs for things such as prescription drugs and utilities. “The single most impactful thing we can do right now is to work with Congress to pass legislation that would lower the costs of things that families are facing right now,” he said.

The White House also wants the package to include tax reforms that would lower the deficit and is working with top Senate Democrat Chuck Schumer to get measures in place in the coming weeks, Deese said.

Biden is also looking to reduce gas prices, and senior administration officials said on Sunday that the US was weighing a temporary pause on the federal gas tax.

Yellen said it was “an idea certainly worth considering” and that Biden was looking to work with Congress to try to bring gas prices down.

Energy secretary Jennifer Granholm said on CNN that the Biden administration was evaluating a proposal for a gas tax holiday.

FT : Germany fires up coal plants to avert gas shortage as Russia cuts supply

Germany fires up coal plants to avert gas shortage as Russia cuts supply
Emergency move is ‘bitter but essential’ to ease threat of energy shortage, economic minister Robert Habeck says

Germany will significantly increase its use of highly polluting coal to preserve energy supplies ahead of the winter as Russian cuts to gas exports threaten shortfalls in Europe’s largest economy.

The German government said on Sunday it would pass emergency laws to reopen mothballed coal plants for electricity generation and auction gas supplies to industry to incentivise businesses to curb consumption. The move illustrated the depth of concern in Berlin over possible gas shortages in the winter months.

“This is bitter but in this situation essential to lower the use of gas,” said German economic minister Robert Habeck, a member of the Green party.

Russia cut capacity on the main gas export pipeline to Germany this week by 60 per cent, sending ripples across the continent as western officials became convinced that Moscow is weaponising its gas exports in response to EU sanctions following the full-scale invasion of Ukraine.

Italy, which has also seen gas supplies from Russia fall, is expected to announce emergency measures in the coming days if supplies are not restored.

Habeck said Berlin was working on a new law to temporarily bring back up to 10 gigawatts of idle coal-fired power plants for up to two years; that would increase Germany’s dependence on coal for electricity generation by up to a third.

“The situation is serious,” said Habeck. “It is obviously Putin’s strategy to upset us, to drive prices upwards, and to divide us . . . We won’t allow this to happen.”

The plan is at odds with Germany’s climate policy; it aims to phase out coal by 2030 as it is much more carbon-intensive than gas.

Germany’s three remaining active nuclear power plants have a capacity of 4 gigawatts and are scheduled to go off the grid by the end of this year. Their lifespan will not be extended as the government has concluded the technical and safety hurdles are too high.

Prior to Russia’s invasion in February, Germany imported 55 per cent of its gas from Russia.

In recent days, Russia’s state-controlled gas exporter Gazprom has reduced supply volumes through the Nord Stream 1 (NS1) pipeline that runs through the Baltic Sea to Germany, blaming Canadian sanctions that left pumping equipment maintained by Siemens Energy stranded in Montreal.

Germany and its allies in Europe have rejected Gazprom’s claims, arguing any technical issue was a pretext for Moscow’s retaliation against EU sanctions. Gazprom has not utilised alternative pipeline routes to make up for the supply shortfall through NS1.

European gas prices, already running close to record levels, soared further last week in response to the latest supply cuts.

Rising energy prices are stoking inflation and a cost of living crisis across Europe, which central banks are struggling to address without tipping the region’s economy into recession.

German chancellor Olaf Scholz called the country’s dependence on Russian energy “a mistake of Germany’s economic policy” and told newswire DPA that previous governments missed out on creating alternative gas supply routes.

Germany plans to install four floating liquefied natural gas (LNG) terminals and has prioritised refilling gas storage tanks that can be used in winter. Currently they are 56 per cent full, and Habeck wants to reach 90 per cent by December.

“We need and we will to do everything to store as much gas as possible,” said Habeck, calling it the “highest priority” and adding that “it would really be a tight squeeze in winter otherwise”.

Germany aims to reduce normal consumption by about a fifth without resorting to rationing, while increasing Norwegian pipeline supplies and LNG imports.

However this could still leave supplies dangerously tight, especially if it is a particularly cold winter. Average temperatures in Germany are 6C or below from November to April, according to the German gas regulator. 

Analysts say German storage, if filled to 90 per cent, would only be able to cover two or three months of normal winter consumption if Russian supplies are completely cut off. 

Germany will also introduce an auction mechanism for industrial gas users, Habeck said. Companies that cut consumption will be compensated, a person familiar with the government’s plans told the Financial Times, but the details are still being finalised.

Last year gas-fired power plants accounted for 15 per cent of German electricity generation. By the end of May, Germany had 31.4 gigawatts of coal-fired plants and 27.9 gigawatt of gas-fired plants on the grid, according to regulatory data.

The 10gw of mothballed coal capacity which will be put back on the grid account for just under 5 per cent of total German production capacity.

FT : Fear of recession will not stop deals, says Centerview’s Blair Effron

Fear of recession will not stop deals, says Centerview’s Blair Effron
Co-founder of boutique investment bank says pressure from new technologies has made M&A ‘less cyclical’

Companies will be forced to keep making acquisitions despite the threat of a global recession due to the relentless pressure from new technologies, according to one of Wall Street’s top investment bankers.

Soaring inflation, rising interest rates, geopolitical tensions and the continuing Covid-19 pandemic mean many on Wall Street fear that corporate management teams will be more reluctant to make big bets through mergers and acquisitions.

However, Blair Effron, co-founder and partner at Centerview Partners, one of the largest boutique investment banks, said a need for companies to keep pace with innovation and add new products and services has made the M&A industry “less cyclical”.

“Disruption in any industry, the idea that companies have gotten better about thinking about acquisitions generally, they think about how to build capabilities, not just new products, they think about every company considering itself in some ways a technology company,” Effron said in an interview with the Financial Times.

“There’s a reason the last year [had] $5tn [in M&A] activity globally. The average before that for the past five years was $4tn. My bet is you end up, whether it’s between $3.8tn or $4tn, that’s where we end up again in 2022,” added Effron, who founded Centerview with Robert Pruzan in 2006.

Last year was a record year for investment banking fees for companies such as Centerview, which earns fees on transactions being completed. Centerview, which as a private company is not required to disclose earnings, earned more than $1.5bn in revenue last year, a record for the bank, according to people familiar with the matter.

In the first five months of 2022, global M&A volumes of pending and completed deals totalled $1.88tn, down from $2.92tn in 2021 but still ahead of the $1.57tn at that point in 2019, according to Refinitiv data.* Part of that activity, though, is coming from the completion of transactions which were announced last year.

“If we remain in an uncertain environment, and we’re deep into the [autumn], it will absolutely have an impact on 2023,” Effron said.

In addition to the uncertain economic backdrop, investment banks like Centerview are also grappling with how to get its workforce back to the office on a more regular basis following two years of largely remote work during the pandemic.

Effron said the bank wants “our people to be less efficient and less productive” as a result of the time spent commuting into the office, but believes being in the office will help employees be “more creative, more collaborative”.

“We encourage that you’re in the office four days a week. But we don’t mandate and we assume we’re doing our jobs well and making the office attractive and making it a campus,” he said.

“Without a lot of pushback, most people are in the office. And if you’re not then obviously you’re probably travelling for clients or doing something else. You’re not sitting on a Wednesday at home.”

FT : US lawmakers push for more money to counter China in Indo-Pacific

US lawmakers push for more money to counter China in Indo-Pacific
Joe Biden’s claim to refocus foreign policy on Asia is not matched by resources, critics say

Democratic and Republican lawmakers will next week introduce legislation to spur the White House to funnel more money to the Indo-Pacific region to help counter China.

Ami Bera, the Democratic chair of the House foreign affairs Asia subcommittee, and Steve Chabot, the top Republican on the panel, hope their “Indo-Pacific Engagement Act” will narrow the gap between the rhetoric about Asia being the priority region and funding levels.

President Joe Biden came to office pledging that he would focus his foreign policy on China. But some experts worry that the US is still not matching its words with resources — a concern over multiple administrations that has been amplified this year as the US has given Ukraine billions of dollars.

“Going back to the Obama administration, we’ve been trying to do this pivot to the Indo-Pacific. We’re getting there, but we’re getting there awfully slowly,” Bera told the Financial Times. “We want to make sure we’re not losing focus on the strategic competition of the 21st century — competition with China.”

The bill will require the state department’s East Asian and Pacific Affairs bureau — in co-ordination with the South and Central Asian Affairs bureau and the Asia bureau at the US Agency for International Development — to submit a report to Congress each year outlining the resources needed to meet the goals in the US Indo-Pacific strategy and upcoming National Security Strategy. It is designed to give Asia officials a louder voice in the debate about the appropriate level of funding for each geographic region.

“If we truly believe China is the priority and the Indo-Pacific is where the future of the 21st century will be written, we need to match our rhetoric with our budgets. It’s that simple,” said Chabot, who added that it was “unconscionable” that administration foreign aid and diplomacy budgets routinely treat Asia as “one of the least important” regions.

The proportion of the foreign operations budget allocated to the East Asia bureau, for example, has hovered between 3 and 5 per cent over the past decade, according to the Congressional Research Service. By comparison, budgets for Europe and Eurasia have risen 65 per cent over that period.

The bill echoes the Pacific Deterrence Initiative, which was passed in 2020 to give the head of US Indo-Pacific Command, who oversees American military forces in Asia, a bigger say in the Pentagon budget process.

Eric Sayers, an Asia expert at the American Enterprise Institute, said PDI had started a “healthy debate” about defence priorities but the US had to bolster its diplomacy and security assistance. “Too often we have allowed other priorities in Europe or the Middle East to take precedence. This Asia-second default tendency needs to give way to a new framework for a comprehensive strategy to resource the Indo-Pacific as the priority theatre.”

Kurt Campbell, the top White House Indo-Pacific official, this week conceded that it was a “valid criticism” to say that the US had not matched its rhetoric with dollars. He said the Biden administration was moving in the right direction, and cited examples including a move to open more embassies in the Pacific and money to finance coastguard initiatives.

“We’ve been to this rodeo before. We understand how things can be diverted,” Campbell said at an event at CNAS, a think-tank. “We’ll have to make the argument that . . . the lion’s share of the history is going to be playing out in the Indo-Pacific, and we have to really take the necessary budgetary steps to reflect that in our activities.”

The White House in May said it would invest $150mn in south-east Asia to fund areas such as climate change to infrastructure. Critics said the sum was relatively small compared to the funds China ploughs into the region. At the CNAS event, US national security adviser Jake Sullivan dismissed the idea that the US was not doing enough.

“We’re really trying to stimulate a long-term economic relationship rooted in private sector investment, not in massive cash transfers from the American Treasury to these countries. And that means taking relatively smaller amounts of money and leveraging significant private sector investment to add up to billions and ultimately tens of billions of dollars,” Sullivan said.

Charles Edel, an Indo-Pacific expert at CSIS, a think-tank, said the new bill would help address the fact that America US “has chronically under-resourced our diplomacy in the Indo-Pacific region while Beijing has poured time, money and attention into its efforts over the past decade”.

Lisa Curtis, an Indo-Pacific expert at CNAS, said the US was starting to make a shift towards prioritising the Indo-Pacific in terms of military, economic, and diplomatic budgets, but said it also needed to be smart in its approach. “When it comes to things like increasing financing for infrastructure needs in the region, the US will never match China dollar for dollar, but the US can leverage its private sector and offer things like technical assistance and training which countries in the region value.”

One state department official welcomed the push for more Indo-Pacific resources and the bipartisan congressional interest. But she said that unless lawmakers approved a bigger overall budget, the effort to focus on the Indo-Pacific in the legislation risked ending up more just an exercise.

But Bera stressed that the bill would intensify the focus on the need to combat China. “If we can shine a spotlight on this and keep sustained pressure and focus on the Indo-Pacific, that will signal to the administration the urgency Congress sees.”