Weekend Papers Summary
NEW YORK TIMES
-Pennsylvania has hosted crucial victories and devastating defeats for both Republicans and Democrats, and it is now the ultimate battleground as peak campaign season arrives. Its races could determine the future of abortion rights and fair elections in the state, control of the Senate and whether the Trump era can hold.
-Divergent realities challenge Biden’s defense of democracy. President Biden seeks to confront threats to American institutions, but Americans are deeply divided on who is imperiling them.
-Former Attorney General William Barr dismisses Trump’s request for a special master. Former Attorney General William Barr said the Justice Department was justified in investigating former President Trump’s handling of government materials.
-With midterms looming, McConnell’s woes pile up. Senator Mitch McConnell, the minority leader, has allowed Democrats to claim policy victories as Republicans’ hopes of reclaiming the Senate dim.
-The FBI found 48 empty folders that had contained classified documents at former President Trump’s Florida home.
-The UN will keep two experts at embattled nuclear plant: Russia and Ukraine have blamed each other for shelling at the Zaporizhzhia station, where some inspectors have been assessing damage and risks.
-In a surprise, Russia says the gas pipeline to Germany will remain closed. The pipeline won’t reopen Saturday as expected, heightening fears Russia will step up its use of energy to pressure Europe on its support of Ukraine.
-Investigators, citing looting, have seized 27 antiquities from the Met
The museum said it was cooperating with the Manhattan district attorney’s office, which has executed several search warrants at the institution.
-Eight migrants drown as dozens are swept down Rio Grande. A large group attempting to cross into Texas was overcome by a fast-moving current, the authorities said.
-College football playoff will expand to 12 teams. The change, intended to capitalize on America’s appetite for the sport, could take effect as soon as the 2024 season. It is expected no later than 2026.
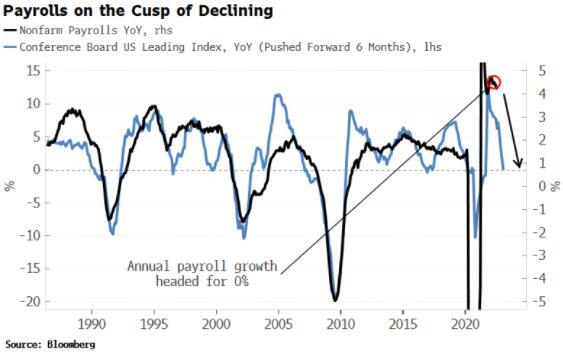
-US Job market cooled but was still strong in August. Employers added 315,000 jobs last month, a sign that the labor market remained resilient in the face of higher interest rates and fears of recession.
-Argentina reels from assassination attempt on its powerful Vice President
The man accused of trying to shoot Vice President Cristina Fernández de Kirchner seemed interested in fringe ideologies, according to his social media.
-Pete Buttigieg is trying to fix air travel with a ‘dashboard.’ The Transportation Department says a new tool compels airlines to commit to compensating passengers after cancellations or delays.
THE FINANCIAL TIMES
-State-owned Gazprom, which was meant to restore operations on the Baltic Sea pipeline on Saturday after three days of maintenance, said the suspension was due to a technical fault. The move came hours after the G7 countries said they were pushing ahead with a plan to try to impose a price cap on Russia’s oil exports as part of an attempt to lower revenues flowing to Moscow that can be used to fund its invasion of Ukraine.
-The US Securities and Exchange Commission — in an early flashpoint of an investigation that has spread across Wall Street — found that JPMorgan failed to track more than 21,000 texts and emails, sent and received on personal phones or through unapproved apps, related to the co-working company, according to people familiar with the matter. The investigation, which became public last year, has ensnared a growing number of banks, which are preparing to pay more than $1B in fines to the SEC and Commodity Futures Trading Commission, dwarfing earlier penalties for record-keeping breaches.
-ESG has an existential defect. Fix this and ESG can thrive. The flaw is that ESG has carried two meanings from birth. Regulators have never bothered disentangling them, so the whole industry speaks and behaves at cross purposes.
-FBI agents retrieved just over 100 classified or secret files from Donald Trump’s Florida resort when they raided it last month, as well as 43 empty folders marked “classified”, according to documents released on Friday.
-Hedge funds snapped up Berkshire Hathaway stock in the second quarter, with DE Shaw, Renaissance Technologies and Bridgewater Associates buying millions of shares in Warren Buffett’s conglomerate.
-Cinema operators have spent years pushing back against the streaming revolution, but the US trade group that represents the industry is now looking to Netflix, Apple and Amazon to help revive the struggling business.
John Fithian, head of the National Association of Theatre Owners, told the Financial Times that discussions are under way with Apple, Amazon and Netflix about wider theatrical releases of their films and there is “some optimism” about an agreement.
-President Putin paid his respects on Thursday as Mikhail Gorbachev lay in state at Moscow’s Central Clinical Hospital, but he will not attend the former leader’s funeral on Saturday due to a scheduling conflict, the Kremlin has said. Nor will the funeral be a full state affair, while Russia’s international pariah status due to its war of aggression in Ukraine and the difficulty of travelling to Moscow mean no foreign dignities have pledged to make the trip.
NY POST
-John Harwood, the veteran White House correspondent for CNN, announced he is leaving the embattled cable network on Friday — the latest high-profile departure under new boss Chris Licht. Harwood tweeted “personal news,” announcing “today’s my last day at CNN.” The 65-year-old former editor-at-large for CNBC — whose resume includes stints as a reporter for the New York Times and the Wall Street Journal — tweeted he was “proud of the work” and that he was “lucky to serve the best in American media.”
-Ex-Treasury Secretary Larry Summers dismissed optimism sparked by a solid August jobs report, warning that a stronger labor market could actually make inflation worse. Summers delivered his latest dire outlook for the US economy after federal data showed US employers added a robust 315,000 jobs last month. The report included a higher-than-expected 62.4% labor force participation rate, stoking optimism that tight labor conditions that contributed to inflation are easing.
-New York City is suing Starbucks over the “wrongful termination” of a barista who worked at an Astoria store that had just voted to unionize, the Department of Consumer and Worker Protection said Friday. Austin Locke, who had worked for Starbucks for the past six years, was canned on July 5 — a month after employees at the store voted in favor of a union.