Closing Stock Market SummaryThe major indices registered some decent gains at their highs for the session, but closed a good bit off their best levels of the day; however, a rally effort in the last 10 minutes saved them from a negative finish. The market was a little choppy early on due to some uneven performances in the mega cap space, but the main indices settled into a narrow range with sizable gains until the release of the FOMC Minutes for the December 13-14 meeting at 2:00 p.m. ET.
There wasn't anything too surprising in the release, but the market did experience some post-Minutes volatility with participants seemingly reacting to the following: "No participants anticipated that it would be appropriate to begin reducing the federal funds rate target in 2023."
Despite the major indices closing off their highs, market internals reflected a decent positive bias. Advancers led decliners by a 4-to-1 margin at the NYSE and a greater than 2-to-1 margin at the Nasdaq. The Invesco S&P 500 Equal Weight ETF (RSP) was up 1.6% versus a 0.5% gain in the Vanguard Mega Cap Growth ETF (MGK) and a 0.8% gain in the S&P 500.
Ultimately, the S&P 500 was able to settle just a whisker above the 3,850 level, which has been a resistance point since mid-December. Additionally, it logged a net gain for the Santa Claus rally period (the last five trading sessions of the year and the first two trading sessions of the new year), which, historically has been regarded as a positive sign for the start of the new year.
Microsoft (MSFT 229.10, -10.48, -4.4%), which was downgraded to Neutral from Buy at UBS on concerns about weaker growth for the Azure and Office 365 businesses, Alphabet (GOOG 88.71, -0.99, -1.1%), and Amazon.com (AMZN 85.14, -0.68, -0.8%) were among the more influential drags on the market while Apple (AAPL 126.36, +1.29, +1.0%), Tesla (TSLA 113.64, +5.54, +5.1%), and Meta Platforms (META 127.37, +2.63, +2.1%) helped out the rebound effort.
Dow component Salesforce (CRM 139.59, +4.81, +3.6%) was another notable winner today following reports that it will be pursuing a restructuring effort that will include the elimination of roughly 10% of its staff and select real estate exits and and office space reductions.
All 11 S&P 500 sectors were able to register a gain with real estate (+2.3%) and materials (+1.7%) leading the outperformers. Meanwhile, the energy (+0.1%), health care (+0.3%), and information technology (+0.3%) sectors fell to the bottom of the pack.
The 2-yr Treasury note yield settled the session unchanged at 4.37% while the 10-yr note yield fell seven basis points to 3.71%.
- Dow Jones Industrial Average: 0.2% YTD
- S&P Midcap 400: +0.8% YTD
- S&P 500: +0.2% YTD
- Russell 2000: +0.7% YTD
- Nasdaq Composite: -0.4% YTD
Reviewing today's economic data:
- The MBA Mortgage Applications Index for the week ending December 31 fell 13.2% from two weeks earlier with purchase applications declining 12.2% and refinancing applications falling 16.3%.
- The December ISM Manufacturing Index dropped to 48.4% ( consensus 48.5%) from 49.0% in October. The dividing line between expansion and contraction is 50.0%, so the sub-50.0% reading for December reflects a general contraction in manufacturing activity. The ISM for December hit its lowest level since May 2020, and marks the second straight month with a sub-50.0% reading.
- The key takeaway from the report is that manufacturing activity contracted in December for the second straight month, demonstrating that the cumulative effect of rate hikes around the globe is adversely impacting demand while at the same time curtailing inflation pressures.
- JOLTS - Job Openings increased to 10.458 million in November from a revised total of 10.512 million in October (from 10.334 million).
Looking ahead to Thursday, market participants will receive the following economic data:
- 08:15 ET: December ADP Employment Change Report ( consensus 148K; Prior 127K)
- 08:30 ET: Initial Jobless Claims for week ending Dec. 31 ( consensus 225K; Prior 225K) and Continuing Jobless Claims for week ending Dec. 24 (Prior 1710K)
- 08:30 ET: November Trade Balance ( consensus -$76.4B; Prior -$78.2B)
- 09:45 ET: December Final IHS Markit Services PMI (Prior 44.4)
- 10:30 ET: EIA Natural Gas Inventories (Prior -213 bcf)
- 11:00 ET: EIA Crude Oil Inventories (Prior 0.718M)
Hong Kong’s Retail Sales Post Surprise Drop in November
Hong Kong’s retail sales unexpectedly dropped in November by the most in eight months as the city struggled to shake off the lingering effects of its pandemic-era controls and a slowing global economy.
Retail sales value fell 4.2 percent from a year ago, the Census and Statistics Department said Wednesday. That was far worse than the forecast for a 4.8 percent rise in a survey of economists, and also lower than the 4 percent increase in October. It was the worst performance since March, when sales plunged 13.8 percent.
Sales volume decreased 5.3 percent, compared with economists’ expectations of a 3.3 percent rise, with a government spokesman saying in a statement that the retail business had “softened” in November.
The drop that month may be due to Hong Kong’s reopening of its international border, according to Samuel Tse, an economist at DBS Bank Ltd.
“Everyone rushed out for outbound travel. That explains why retail sales are really bad,” he said. “Foreigners weren’t traveling to Hong Kong when Covid curbs still remained, while Hong Kong residents were rushing out.”
The retail data covers consumer spending on goods but not on services such as catering, medical care and entertainment. Those services account for over 50 percent of total consumer spending.
The sector struggled throughout 2022 as the city was hit by a brutal Covid wave that killed thousands and led to more social distancing rules and business closures. That was followed by the slow reversal of travel restrictions, but only at the end of December did Hong Kong eliminate the last of its major Covid rules, including a requirement that inbound travellers take a PCR test.
The city has handed out spending vouchers to support retailers, though the government has said in the past that “tightened financial conditions” would offset the effects of that aid. Global headwinds including rising interest rates and a worldwide drop-off in demand have weighed heavily on the economy.
In Wednesday’s statement, the government spokesman again cited tighter conditions as likely to weigh on local demand, though said that the further relaxation of social distancing measures and an improving labor market will provide some support. The spokesman also said that an expected increase in visitor arrivals should help the sector.
A long-awaited reopening of Hong Kong’s border with mainland China is likely to boost the economy and lift retail sales in the coming months. City leaders have said they intend to start that reopening by the middle of this month.
Before the pandemic, 80 percent of Hong Kong’s visitors were from mainland China, noted Tse of DBS.
“As long as the border remains close, even if you open to the rest of the world at most you can get 20 percent of tourism,” he said, adding that January data should see a “sharp jump” with an even more material one after the Lunar New Year holiday period.
Financial Secretary Paul Chan has said he’s optimistic about the city’s prospects and expects the economy to rebound as the border reopens. Economists at Goldman Sachs Group Inc. last month predicted the Asian hub could see an estimated 7.6 percent boost to gross domestic product as exports and tourism income climb.
Fed wants ‘more evidence’ of easing inflation and backs fresh rate rises
Minutes from December meeting show US central bank officials intend to keep squeezing economy
Federal Reserve officials warned they would need to see “substantially more evidence” of easing inflation before they are convinced that price pressures are under control as they backed fresh rate rises this year, according to an account of their most recent meeting.
Minutes from the December gathering, when the US central bank raised its benchmark rate by half a percentage point, showed the Fed intends to continue squeezing the economy to try to tackle price pressures, which they warned could “prove to be more persistent than anticipated”.
The half-point rise ended a months-long string of 0.75 percentage point increases and lifted the target range of the federal funds rate to between 4.25 per cent and 4.5 per cent.
The decision in December followed fresh evidence that inflation appeared to have peaked as energy prices and those tied to the goods sector have retreated, developments which participants described as “welcome”.
“Participants generally observed that a restrictive policy stance would need to be maintained until the incoming data provided confidence that inflation was on a sustained downward path to 2 per cent, which was likely to take some time,” the minutes, released on Wednesday, said, referring to the Fed’s inflation target.
The minutes also indicated that officials are attuned to how their policy communications are being digested by investors and others across Wall Street. In the weeks leading up to the December meeting, financial conditions had loosened as traders in fed funds futures wagered the Fed would back off its tightening campaign sooner than officials have signalled.
A slower pace of rate rises “was not an indication of any weakening of the committee’s resolve to achieve its price-stability goal or a judgment that inflation was already on a persistent downward path”, a number of participants said was important to make clear, according to the minutes.
Officials also warned an “unwarranted easing in financial conditions, especially if driven by a misperception by the public of the committee’s reaction function, would complicate the committee’s effort to restore price stability”.
According to the “dot plot” of policymakers’ interest rate projections published after the meeting, most officials now see the federal funds rate peaking between 5 per cent and 5.25 per cent, with a large cohort of the view that it may need to go even higher. That suggests a total of at least 0.75 percentage points’ worth of rate rises to come.
At the press conference that followed last month’s rate decision, Jay Powell, Fed chair, warned that he could not “confidently” say the central bank would not raise its estimates again as he sought to push back against speculation that it would soon abandon its tightening plans.
“We’ve covered a lot of ground and the full effects of our rapid tightening so far are yet to be felt. We have more work to do,” he told reporters.
The dot plot showed that rate cuts are not expected until 2024, when the benchmark rate is projected to fall to 4.1 per cent, before dropping to 3.1 per cent in 2025. Growth is set to slow considerably as borrowing costs are kept high for an extended period, with most officials projecting an expansion of just 0.5 per cent this year before a 1.6 per cent rebound in 2024.
The unemployment rate is likely to increase by nearly a full percentage point from its current level to 4.6 per cent, the estimates show.
The minutes also indicated that officials are still chiefly concerned about “upside risks to the inflation outlook” and doing too little in terms of tightening. But there are also fears that the Fed will have raised rates excessively and to a degree that will lead to an “unnecessary reduction in economic activity”.
While the weakening economy is set to put downward pressure on prices, it is expected to take some time for inflation to fall to the Fed’s longstanding 2 per cent target. The central bank’s preferred inflation gauge — the core personal consumption expenditures price index — is projected to decline to 3.5 per cent by the end of 2023 and 2.5 per cent in 2024. As of November, it hovered at 4.7 per cent.
So far, the Fed’s tightening has been felt most in interest-rate sensitive sectors such as housing, where prices have declined dramatically from their coronavirus pandemic peaks. However, labour demand remains high as consumers continue to spend, helping to further entrench inflationary pressures that have taken hold across the services sector. Economists warn that rooting those out will require a recession and job losses.
Powell and his colleagues, as well as White House officials, maintain a recession can be avoided even as the unemployment rate ticks up.
Funeral provider Dignity in talks with consortium over £262mn takeover
Cash offer represents a 23% premium to Tuesday’s closing share price
Dignity, one of the UK’s largest funeral providers, is set to be taken over by a consortium of financiers led by Sir Peter Wood, the founder of insurer Direct Line.
The company said it would be “minded to recommend” a cash offer that values the company at £262mn, or 525p a share, and represents a 23 per cent premium to Tuesday’s closing share price.
The consortium, which is also fronted by City fund manager and former Dignity executive Gary Channon, has already acquired 29 per cent of Dignity’s share capital.
Dignity’s shareholders would have the option to remain partially invested in the company through an unlisted holding company or through Castelnau, a London-listed investment vehicle that is part of the consortium.
Both parties said that discussions had begun in mid-October with an opening shot of 475p a share. At the time, that represented a 37 per cent premium to the prevailing share price. The fourth offer of 525p was tabled in mid-November, Dignity added.
In a statement, the consortium said its proposal was “a compelling opportunity” at a time when the company “faces substantial operational challenges”.
It added that Dignity’s growth prospects “can only be realised over a longtime horizon” and “require significant additional near-term capital”.
“Dealing with that in the public markets will be difficult and potentially damaging to the delivery of the core strategy and the brand reputation,” it concluded.
Channon, the co-founder of Phoenix Asset Management, briefly served as executive chair and chief executive of Dignity. His involvement in the bid is the latest chapter in a storied recent history. He was installed as executive chair of Dignity at an extraordinary meeting of shareholders in April 2021 and later moved to the chief executive position before making way for Kate Davidson, the current chief executive, in June last year.
Sir Peter said: “Dignity has long-term growth potential — the signs are clear to me. But the changes and significant development work and investment needed to enable this growth mean the best way forward for Dignity is as a private company”.
The wider funeral sector has been beset by difficulties in recent years. Although the coronavirus pandemic increased the UK’s death rate, it also resulted in significant additional operating costs.
At the same time, the government required simpler and smaller funerals — which were less profitable for providers such as Dignity and Cooperative Funeralcare — in order to enforce social distancing.
More recently, the sector has been hard hit by increased energy prices which have raised the cost of cremations, and staff shortages.
It has also been the subject of two regulatory probes, one into the cost of funerals themselves and the other into the promotion of pre-paid funeral plans.
Dignity has made a pre-tax loss, before exceptional items, in each of its past four financial years and its share price has fallen sharply from the peaks of over £20 reached in 2016 and 2017 to £4.35 immediately before the bid talks were revealed on Wednesday.
The stock closed at £5.35, up 25 per cent on the day.
Business Wire
NEW YORK -- January 4, 2023
Byron R. Wien, Vice Chairman together with Joe Zidle, Chief Investment Strategist in the Private Wealth Solutions group at Blackstone, today issued their list of the Ten Surprises of 2023. This is the 38th year Byron has given his views on a number of economic, financial market and political surprises for the coming year. Byron defines a “surprise” as an event that the average investor would only assign a one out of three chance of taking place but which Byron believes is “probable,” having a better than 50% likelihood of happening. Byron started the tradition in 1986 when he was the Chief U.S. Investment Strategist at Morgan Stanley. Byron joined Blackstone in September 2009 as a senior advisor to both the firm and its clients in analyzing economic, political, market and social trends. In 2018, Joe Zidle joined Byron Wien in the development of the Ten Surprises.
Byron and Joe’s Ten Surprises of 2023 are as follows:
- Multiple candidates on both sides of the aisle organize campaigns to secure their party’s presidential nomination. There are new headliner names on the respective tickets for 2024.
- The Federal Reserve remains in a tug-of-war with inflation, so it puts the word “pivot” on the shelf alongside the word “transitory.” The fed funds rate moves above the Personal Consumption Expenditures price index and real interest rates turn positive, a rare phenomenon relative to the last decade.
- While the Fed is successful in dampening inflation, it over-stays its time in restrictive territory. Margins are squeezed in a mild recession.
- Despite Fed tightening, the market reaches a bottom by mid-year and begins a recovery comparable to 2009.
- Every significant correction in the market has in the past been accompanied by a financial “accident.” Cryptocurrencies had a major correction and that proved not to be a systemic event. This time, Modern Monetary Theory is fully discredited because deficits have proven to be inflationary.
- The Fed remains more hawkish than other central banks, and the US dollar stays strong against major currency pairs, including the yen and euro. This creates a generational opportunity for dollar-based investors to invest in Japanese and European assets.
- China edges toward its growth objective of 5.5% and works aggressively to re-establish strong trade relationships with the West, with positive implications for real assets and commodities.
- The US becomes not only the largest producer of oil, but also the friendliest supplier. The price of oil drops primarily as a result of a global recession, but also because of increased hydraulic fracking and greater production from the Middle East and Venezuela. The price of West Texas Intermediate crude touches $50 this year, but there’s a $100 tick out there sometime beyond 2023 as the world recovers.
- The bombardment, destruction and casualties in Ukraine continue for the first half of 2023. In the second half, the combination of suffering and cost on both sides necessitates a ceasefire and negotiations on a territorial split begin.
- In spite of the reluctance of advertisers to continue to support the site and the skepticism of creditors about the quality of the firm’s debt, Elon Musk gets Twitter back on the path to recovery by the end of the year.
The “Also Rans” of 2023
Every year there are always a few Surprises that do not make the Ten, because we either do not think they are as relevant as those on the basic list or we are not comfortable with the idea that they are “probable.”
- Because of meical breakthroughs across the board, many people decide on a cryogenic burial, expecting to be defrosted when a cure for the disease that caused their demise is discovered. Funeral homes across the country advertise that “It’s Nice to Be On Ice.”
- A technology breakthrough in reducing the carbon emissions of coal-fired plants takes the edge off the climate / global warming scare. This lowers the political pressure on emerging markets to make a rapid transition to renewable energy sources.
- India begins to compete seriously to win/retain the manufacturing base that started looking for a new home after becoming increasingly uneasy with the uncertainty that has continuously surrounded US–China policies. The country initiates a campaign to attract global multinationals, focusing on its young population, relatively low income and growing consumer market, and prioritizing policies that incentivize investment in the auto, energy, pharma and tech sectors. Apple and Samsung are a proof of concept after successfully producing their respective flagship phones for global markets.
Adidas and Thom Browne Face Off in Court Over Use of Stripes

The German sports brand is seeking just under $8 million in damages and profits from the luxury label.
NEW YORK — The ongoing battle between Adidas and Thom Browne over the use of stripes on apparel and footwear kicked into high gear in the new year as the two brands faced off in Manhattan’s Southern District Court Tuesday in a trademark dispute case.
The trial in front of Judge Jed Rakoff began with attorneys on each side laying out their arguments to a jury, which will decide if the luxury designer infringed on Adidas’ trademark for three parallel stripes that have been a staple of the brand since the 1940s.
Adidas is seeking damages in the amount of $867,225 — the amount that it says the company would have received in licensing fees from Thom Browne Inc., if the two had worked together — as well as the $7 million in profits it alleges the American fashion brand made selling apparel and footwear with stripes, according to R. Charles Henn Jr. of Kilpatrick Townsend & Stockton LLP, who represents Adidas.
In his opening argument, Henn told the jurors that the trademarked three-stripe mark has been used in the U.S. since 1952 and Adidas spends some $300 million a year in advertising and brings in $3.1 billion in the sale of footwear and apparel bearing the motif. He showed examples of the logo being used vertically and horizontally in a range of colors on a variety of products including track pants, T-shirts, jackets and sneakers.
When Thom Browne started his brand, he used three stripes on some items such as sweaters to reference the varsity and collegiate sports uniforms that he has since become known for, as well as a red, white and blue grosgrain that is now a signature of the collection.
Henn argued that when Adidas discovered the use of the stripes, it approached Browne’s then chief executive officer and the designer agreed to change to a four-stripe detail. Even so, consumers still see it as three stripes, Henn said, citing a recent survey that was conducted where 2,400 consumers were shown images of Thom Browne striped product and 26.9 percent thought the product was made by Adidas.
The problem was exacerbated as the Thom Browne brand grew and expanded beyond its core of tailored clothing for men into a variety of sports-related products for men, women and children, including compression running gear, golf shirts, T-shirts, hoodies and other casual product, Henn said, in a “targeted attempt to grow its sportswear business.”
An Adidas shoe with the three stripes that it has trademarked.
Thom Browne also inked deals to dress FC Barcelona and its star athlete at the time, Lionel Messi, who had been an Adidas-sponsored ambassador for 15 years, as well as the Cleveland Cavaliers of the NBA where Adidas has had a “long relationship,” he said. The FC Barcelona deal was for off-the-field apparel, however, and the designer created custom tailored looks for the Cavaliers during the NBA Playoffs in 2018 that they wore in the tunnel as they arrived at the arena.
Although Henn said it is not likely that any consumer would purchase a high-end Thom Browne product thinking it was Adidas — a track pant from Adidas retails for around $55 while a Thom Browne version is more than $1,000 — it still led to confusion among shoppers.
In his rebuttal, Thom Browne’s attorney, Robert T. Maldonado of Wolf, Greenfield & Sacks P.C., said while the designer is not questioning Adidas’s trademark rights to the three stripes, it had agreed to change its motif to four stripes in 2007 so as not to get into an extended legal battle with the German-based “powerhouse” sports brand.
But the fact that Adidas did not object to Browne’s use of four stripes from 2008, when it made its debut during a fashion show, until 2018, when Adidas approached the Thom Browne team to negotiate a settlement, is the crux of the brand’s argument. “Thom Browne doesn’t agree that a decadelong delay is acceptable,” Maldonado said.
In addition, the attorney said Thom Browne does not believe consumers are confused by any similarities between the brands or that Adidas was harmed by the brand’s use of stripes.
Maldonado went on to introduce the designer, who was seated in the front of the courtroom in shorts and shrunken jacket, to the jury, saying that his outfit was not for their benefit, but is the “uniform” that he and his staff wear every day. He said the brand has now become known for the four parallel bars on the sleeves or pant legs as well as its grosgrain tag on the garments, which have been “branding elements” for the past decade or more.
He said Browne has been designing casual clothes such as cardigan sweaters and shorts for more than 15 years and introduced jersey sweatpants in 2009, drawing inspiration from varsity sports, not Adidas.
“Thom Browne does not compete with Adidas,” he said. “Thom Browne is a luxury designer and Adidas is a sports brand.”
Over the course of the trial, he said the brand will talk about the use of stripes in fashion and sports dating back “centuries,” and will also show that Adidas has no trademark for anything other than the three stripes that are almost always used vertically on its apparel and footwear while Browne’s are used horizontally.
He said that if the designer is forced to stop using the four bars or the grosgrain tags, it will have a significant impact on the business that has grown to 69 million euros in the third quarter of this year. Browne sold a majority stake in the brand to Ermenegildo Zegna in 2018.
“Three stripes are not the same as four horizontal bars,” Maldonado argued, adding that Adidas should have known years earlier that Browne was using stripes in his collection. “They fell asleep at the wheel and woke up too late,” he said.
The trial is expected to last about two weeks and Browne as well as the company’s CEO Rodrigo Bazan are both expected to testify.
What to Watch: Clienteling Is the New Black for Europe’s Luxury Giants


Existing, wealthy clients are seen as a buffer amid a darkening economic picture.
With dark economic clouds gathering, Europe’s luxury brands would be wise to lean further into clienteling, an arsenal of tactics that were sharpened during the pandemic and have been lifting a vibrant sector even higher.
Most were applied to high-spending clients, who will be key to minimizing volatility in the near term.
“We are about to go through a tough six to nine months in terms of demand and the parts that will hurt most are the entry-level price points that are essentially driven by lower-means, first-time purchasers who, given the current uncertainties, will likely postpone purchases,” said Erwan Rambourg, global head of consumer and retail research at HSBC in New York.
As macro headwinds weigh, it will be tougher for Europe’s marquee luxury brands to bring in first-time purchasers, he argued.
Rambourg is bullish long-term on the luxury sector based on a phenomenal reserve of first-time purchasers that can be recruited. However, he allows that a consumer’s first branded watch or designer handbag “is generally coming at the expense of other areas of spending and will take a hit as aspirational consumers postpone purchases right now.”
“The short term should be driven more by existing, wealthier cohorts,” he stressed.
Luckily, many European brands are becoming extremely adept at extracting a large proportion of sales from small numbers of active, affluent consumers.
According to Delphine Vitry, founding partner of Paris-based luxury consultancy MAD, it comes down to conversion rates, which range from 10 to 30 percent for walk-ins at luxury boutiques, depending on traffic levels, but reach 60 to 70 percent for clients who shop by appointment.
While declining to specify the brands, she said “best-in-class” jewelers garner 40 percent of revenues from sales by appointment, and best-in-class fashion brands as much as 30 percent.
“The more you will do on appointment, the more you will sell,” she explained in an interview. “It’s not only about business, it’s about creating a bond, a relationship with the customer.…When you book an appointment, you’re definitely much more engaged.”
VIP clients have become such an important revenue stream that marquee brands like Chanel, Dior and Louis Vuitton have all created expansive spaces for these high-spenders at SKP in Beijing, one of the most productive luxury department stores in China.
Innovative and immersive store concepts — such as Dior’s multifaceted Avenue Montaigne flagship in Paris, and Gentle Monster’s otherworldly mechanized merchandising wizardry — plus grandiose pop-ups and activations are also part of the modern client experience.
Couture brands like Christian Dior have an edge in clienteling because when they were founded, all commerce was done by appointment.
“The way to take care of your client by appointment is to optimize, anticipate and prepare the moment when you’re going to receive the person,” Vitry said, noting that this comprises thousands of small details, from serving Champagne to wearing white gloves during the selling ceremony of jewelry or precious leather goods. “Cherishing the customer and his or her lifetime value is definitely what all luxury brands are trying to do, with more or less success.”
Last month, MAD released a white paper about what it takes to construct a well-managed luxury experience that allows the client to “concentrate on the dream that they have come to experience.” One of the key challenges for brands is to define an “experiential signature” that reinforces key memories across every channel.
The VIP salon at Montblanc’s Paris flagship on the Avenue des Champs-Élysées .
DAVIDE LEGGIO
For example, a brand may seek to make their clients feel glamorous, powerful, fashionable or edgy.
According to MAD’s tabulations, two out of three luxury clients are capable of turning their backs on a brand after encountering a poorly executed omnichannel experience, while brands with advanced omnichannel approaches can expect their multichannel clients to have a lifetime client value up to three times higher than that of single-channel clients.
Vitry said the most advanced brands employ a one-stock model and create omnichannel client journeys; empower sales associates with sophisticated clienteling apps, and motivate them with new renumeration models.
Step number one for brands to excel at clienteling is having the right company culture. Vitry noted that “technology has never been a driver for luxury” and that “creation has been at the center of luxury historically, not clients.”
Yet successful clienteling requires investments in new processes, talents, training, IT solutions and more in order to “master all touch points and interactions,” Vitry stressed.
“There’s no ambiguity — increase the conversion rate, reach VIP targets, increase the customer lifetime value, and invest massively to equip your company with top management, omnichannel devices, etc.,” she said.
She noted that most luxury brands focus on key performance indicators linked to the product, not the customer, which she characterized as a “huge shift” in mindset.
While queues in front of luxury stores might be seen as a signal of brand vitality by some, especially in cities with high tourist flows, Vitry noted they’re a concern for many brands, as queues can contain VIPs who might not have anticipated a line, or customers seeking after-sale service, for example.
“We are working with all the brands to manage these queues, to avoid these queues,” she said.
Indeed, Vitry said brands neglect or inconvenience new clients at their peril, since some could blossom into VIPs in the future. Jewelry houses should take great care with engagement-ring buyers, for example, since that’s often the first time people push the door on a luxury retailer.
“It’s a skill to identify the potential of a customer, not a science,” she said.
The coronavirus pandemic, which shuttered luxury stores in most international markets for long periods and halted waves of Chinese tourists, compelled brands to pay loads more attention to European clients in its main capitals.
According to Rambourg, “This has been instrumental in growth and carries the silver lining of luxury not being just a play on a specific market of wealth but one on global, very diversified, clienteles.
“Ironically being separated by COVID[-19] has made us become closer to end-consumer needs,” he added, citing selling over Zoom, at people’s homes, privatizing stores or other spaces as only a few of the new tactics that emerged.
“Hermès and Louis Vuitton have been really best in class in my view,” Rambourg said, also calling out Moncler’s top-notch CRM system known as “Monclient,” which has “proven to be an incredibly powerful tool.”
Vitry warned that staffing luxury boutiques looms as a future challenge, describing a “war” for the most gifted sales associates, and difficulties luring new employees who got a taste of home working and might balk at the 24/7 demands of enriching VIP client experiences.
Rambourg said he’s “still convinced that once we get past the current turmoil, luxury will be predominantly driven, as often, by recruitment rather than repeat consumers once more.”
“Just don’t forget who feeds you in good times and keep access to the entry level,” he said, advising that brands should not increase prices too much “as you risk alienating the local consumer.”
Beyond clienteling, the luxury analyst predicts that Europe’s big luxury players will continue to diversify into categories like hospitality, furniture and fine jewelry; address new markets in Africa and also smaller cities in the U.S.; focus on in-person events to create “emotional memories,” and strategize how to best capitalize on the eventual return of Chinese tourists.
Three Paths For 2023
As we anticipate what 2023 might have in store for investors, we must first consider what the Fed may or may not do. We think there are three potential paths the Fed might follow in 2023. The three paths determine the level of overnight interest rates and, more importantly, liquidity for the financial markets. Liquidity has a heavy influence on stock returns.
Let’s examine the three paths and consider what they might mean for stock prices.
The Road Map for 2023
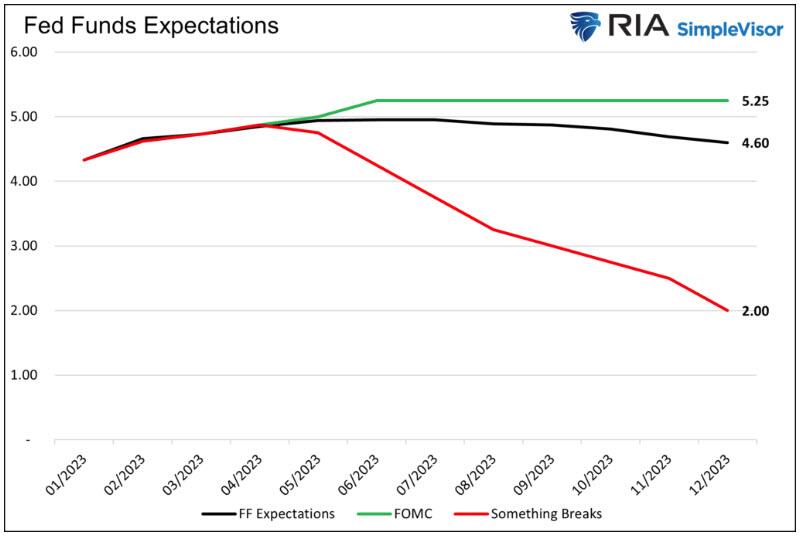
The graph below compares the three most probable paths for Fed Funds in 2023. The green line tracks the Federal Reserve’s guidance for the Fed Funds rate. The black line charts investor projections as implied by Fed Funds futures. Lastly, the “something breaks” alternative in red is based on prior easing cycles.
Scenario 1 The Fed’s Expectations
To provide investors transparency into Fed members’ economic and policy outlooks, the Fed publishes a summary of each voting member’s economic and Fed Funds expectations for the next few years. The latest quarterly guidance on the Fed Funds rate, as shown below, is from December 14, 2022 (LINK).

The dots represent where each member expects the Fed Funds rate to be in the future.
The range of Fed Funds expectations for 2023 is between 4.875% and 5.625%. Most FOMC members expect Fed Funds to end the year somewhere between 5.125% to 5.375%. Based on comments from Jerome Powell, the Fed seems to think Fed Funds will increase in 25bps increments to 5.25%.
While investors place a lot of weight on the Fed projections, it’s worth reminding you they do not have a crystal ball. For evidence, we only need to look back a year ago to its 2022 projections from December 2021.
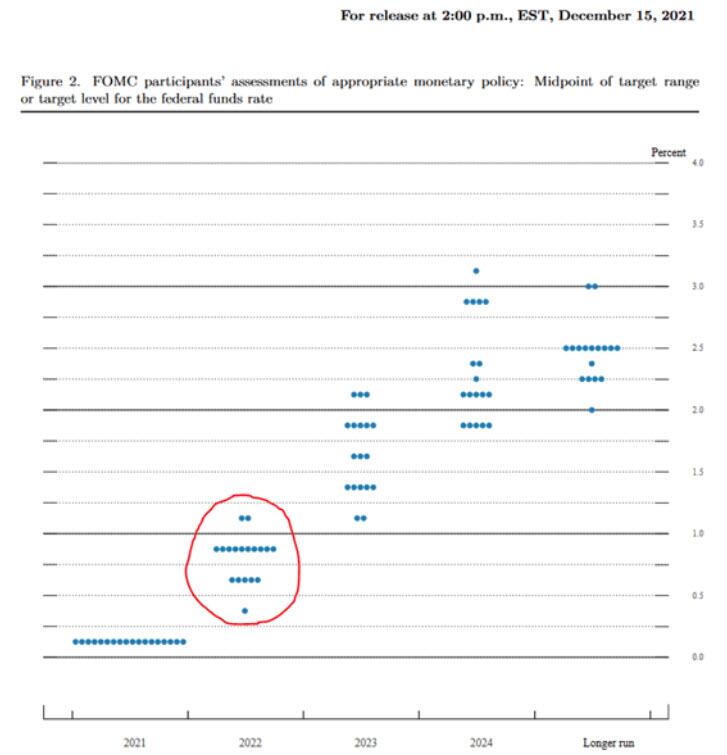
Their misguided transitory inflation forecast grossly underestimated inflation’s lasting power and how much they would have to raise rates. The point of sharing the graph is not to belittle the Fed but to highlight its poor ability to predict the future.
Scenario 2 Implied Market Expectations
Fed Funds futures are monthly contracts traded on the CME. Each contract price denotes what the collective market implies the daily Fed Funds rate will average each month. For example, when writing the article, the June 2023 contract traded at 95.05. 100 less 95.05 produces an implied rate of 4.95%. We can arrive at an implied path for Fed Funds by stringing the monthly implied rates together.
The market thinks the Fed will raise rates to just shy of 5% in May and hold them there through July. After that, the market implies increasing odds of a Fed pivot. By December, the market believes the Fed will have cut interest rates by about 40bps.
Like the Fed, the Fed Funds market can also be a poor predictor of Fed Funds.
In late 2019 we wrote an article studying how well the Fed Funds futures market predicts Fed rate hikes and cuts. Per Investors are Grossly Underestimating the Fed:
As shown in the graphs, the market underestimated the Fed’s intent to raise and lower rates every time it changed monetary policy meaningfully. The dotted lines highlight that the market has underestimated rate cuts by 1% on average, but at times during the last three rate-cutting cycles, market expectations were short by over 2%.
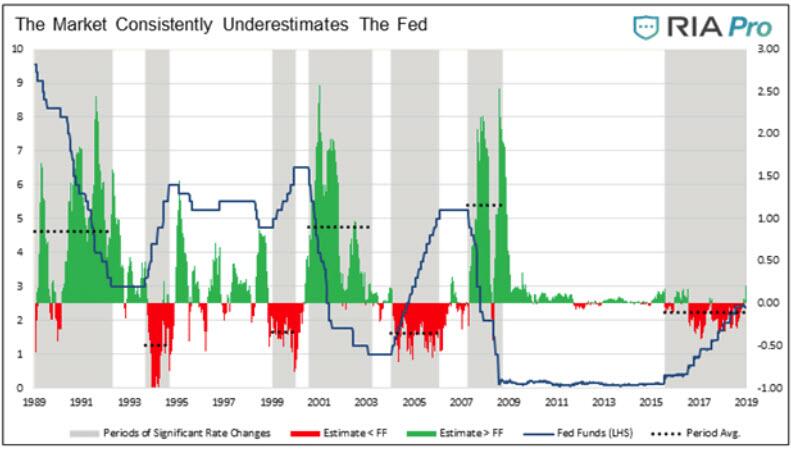
During the last three recessions, excluding the brief downturn in 2020, the Fed Funds market misjudged how far Fed Funds would fall by roughly 2.5%. Implied Fed Funds of 4.6% today may be 2% by December if the market similarly underestimates the Fed and the economic and financial environment.
Scenario 3 Something Breaks
The first two alternatives assume the Fed will tread lightly, be it raising rates a little more or a slight pivot in 2023. The third path is the outlier “something breaks” forecast.
There is a significant lag between when the Fed raises rates and when the effect is fully felt. Economists believe the lag can take between nine months and, at times, over a year. In March 2022, the Fed raised rates by 25bps from zero percent. Since then, they have increased rates by an additional 4%. If the lag is a year, the first interest rate hike will not be fully absorbed into the economy until March 2023.
The third path, in which the Fed aggressively lowers rates, would be a response to a significantly weakening economy, inflation falling much more rapidly than expected, or financial instability. It could also be a combination of any or all three factors.
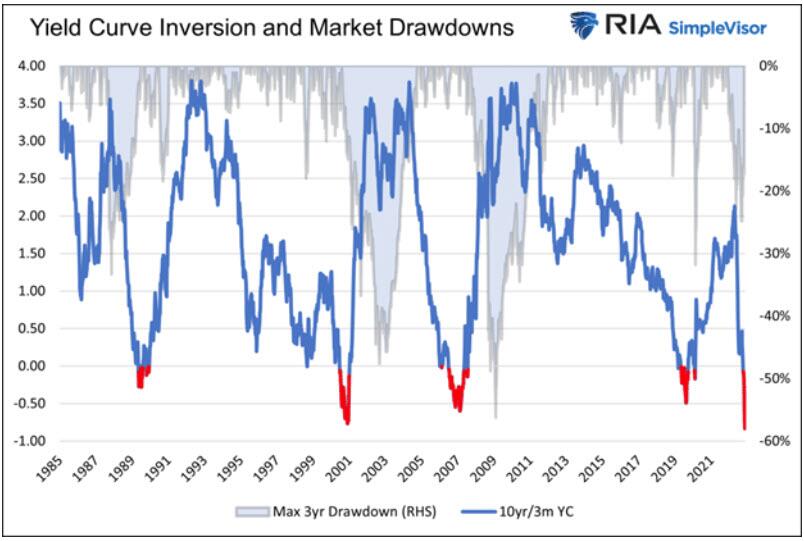
In The Foghorn is Blowing, we discuss how an inverted Treasury yield curve that un-inverts has been a great predictor of recessions, stock market drawdowns, and corporate earnings declines. The re-steepening of the yield curve is almost always the result of the Fed lowering interest rates.
The yield curve is currently inverted to a level not seen in over 40 years. It will un-invert; the only question is when and how quickly. As we wrote:
The financial foghorn is blowing. Historical odds greatly favor a recession, stock market drawdown, and a much lower Fed Funds rate.
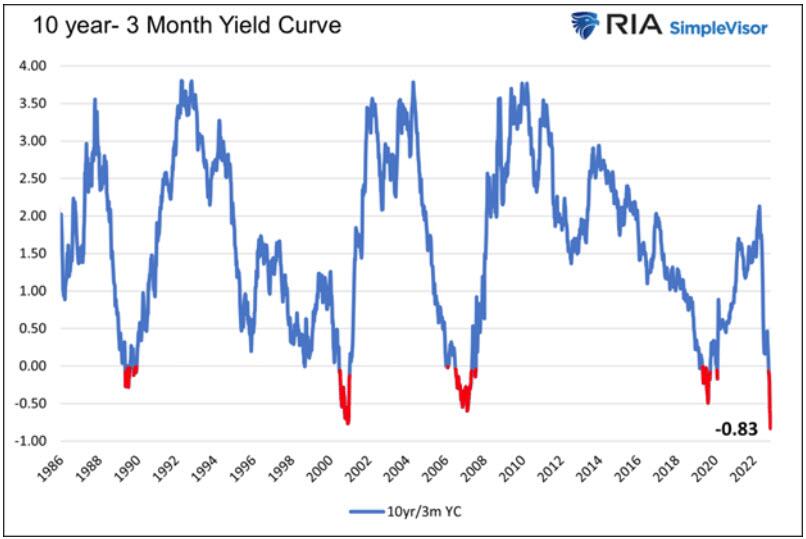
If it un-inverts as violently as it has in the past, the 2% Fed Funds for the year-end scenario may prove too high!
Asset Performance in The Three Paths
Stock investors expect the second path with a slight pivot during the summer. Currently, corporate earnings are expected to grow by 8% in 2023. Such implies economic growth. Therefore, it also intones the Fed will not over-tighten and cause a recession. This goldilocks scenario may provide investors with a positive return.
The first alternative, the FOMC’s expected path, may entail more pain for stock investors as it implies rates will rise higher than market expectations with no pivot in sight.
The third “something breaks” scenario is the potential nightmare scenario. While investors will receive the pivot they have been desperately seeking, they will not like it. Historically, rapidly declining economic activity and financial instability do not bode well for stocks, even if the Fed adopts a more accommodative policy stance.
The graph below shows that the yield curve steepens well before the market bottoms. Likely, the steepening will result from the Fed quickly slashing interest rates in response to “something breaking.”
Don’t Forget About QT
Another Fed policy facet to consider is QT. The Fed is removing liquidity at a sizeable clip. Like interest rates, QT has a lag effect. In time, economic and financial market liquidity diminishes with QT.
Leveraged investors must often reduce exposure as liquidity becomes harder to obtain and more expensive. Usually, the deleveraging process starts slowly with fringe assets and overly leveraged investors feeling pain. However, deleveraging can spread quickly to the well-followed broader markets. The U.K. pension fund bailouts and failing crypto exchanges like FTX are likely signs of liquidity exiting the system.
Even if the Fed stops raising rates or marginally lowers them, QT will present headwinds for stock prices.
Summary
The unprecedented influx of liquidity that drove asset prices higher in 2020 and 2021 is quickly leaving the market. The lag effect of higher interest rates and fading liquidity will likely play a prominent role in determining stock prices in 2023.
Based on the Fed’s determination to quash inflation via higher interest rates and QT, we think the “something breaks” scenario is the likely path ahead.
World renown investor Stanley Druckenmiller seems to agree with us per a recent quote- “I would be stunned if we didn’t have a recession in 2023.”
Given the dynamic nature of economic and financial market activity and the difficulty of predicting the economic future, the Fed’s projections and the other two paths we discuss should be monitored closely throughout the year.
Expect the unexpected in 2023 and keep the Fed’s path top of mind.
A Big Short-Squeeze Is Taking Place In Europe
By Michael Msika, Bloomberg Markets Live reporter and commentator
It might be very early days, but it seems investors don’t want to start the year being heavily short on European stocks, especially not when it comes to the worst laggards of 2022.
The biggest losing stocks of last year are looking to put their awful performance behind them, starting 2023 in the best way possible. A basket of the 20 biggest stragglers of 2022 is up about 6% this week, more than three times the performance of the Stoxx 600.
“We are seeing strong evidence of the January effect,” says Cowen head of EMEA trading Carl Dooley, noting that the last time European stocks had a similarly poor year — in 2018 — underperformers “rallied hard” in the first month of the next year. This time round, he pointed to Faurecia, HelloFresh, SBB, Kion, Just Eat Takeaway, Zalando, GN Store Nord, Aroundtown and AMS as among those off the list of unloved 2022 names enjoying the brightest start.

There’s another common theme linking some of these stocks: a high quantity of shares out on loan, an indication of short-selling interest. Take Swedish real estate company SBB for example, with almost 23% of the free float available to borrow, according to S&P Global data. It’s up 10% this year, extending a rally since Dec. 20 to about 25%. Elsewhere, Zalando, Ocado, Aroundtown and HelloFresh all have more than 9% of their free float out on loan.

A similar picture of losers turning winners is evident in European sectors. Autos, real estate and retail are among the pace-setting industry groups, after they all severely underperformed in 2022. Banks look like the exception in the top six performing groups so far. Real estate was the second most-shorted sector after food retail by mid-December, according to S&P Global data.

“I think investors should be on really high alert for a short squeeze before we see another leg lower in equities,” says Vanda Research global macro strategist Viraj Patel. “Part of the reason for that is that we’ve got bond markets trading on recession fears, while equity markets are in this pessimistic, bearish sentiment state.”
Patel sees a possibility of a “Goldilocks state environment,” where inflation moves lower and economic activity holds up somewhat. “Could that be the template for the next couple of months? That’s certainly not priced in at the moment,” he said in a Bloomberg Television interview.
The short-covering trend shows up in the futures market too. For example, net futures positioning from asset managers and leveraged funds turned positive on the S&P 500 at the end of December, rising from a multi-year low. Meanwhile, European futures positioning has been relatively stable over the past two weeks, with investors marginally net long Euro Stoxx, while positioning in the FTSE 100 and DAX is moderatey net short and rising, according to Citigroup strategists.

“Investors have returned to their trading desks with some confidence about this new year,” says Pierre Veyret, technical analyst at ActivTrades. “It is, however, still hard to say if the current price action is being driven by real directional motivations from portfolio managers or if it is just a liquidity bull trap, covering some of last year’s short positions.”
Veyret cautions that a combination of high volatility and lower market liquidity is often treated as a dangerous indicator for stock traders.
Pee is the magic number, as Withings puts a urine analysis lab in your toilet
Withings, best known for its smart scales, watches, and other health-focused consumer tech, released a new gadget at CES in Las Vegas today. Making a splash in an underserved market, U-Scan aims to help customers track what’s going on in their urine, without having to worry about catching their wastewater in a cup or messing about with test strips. The device syncs to the company’s ever-expanding Health Mate app and promises to give actionable insights.
The U-scan is designed to be installed in the toilet bowl, which gives users hands-free access to urine analysis. While routine in medical settings, Urine is a rarely-tapped opportunity for at-home health monitoring. That may change quite a bit over the next few years if Withings has its way. The company points out that urine has more than 3,000 metabolites, giving an immediate snapshot of the body’s balance and health.
“The ability of U-Scan to perform daily urine analysis from home will allow Withings to take its mission to help consumers fully utilize urine data to an entirely new level,” said Mathieu Letombe, Withings CEO at a press conference. “It’s one of the most exciting and complex products we have ever announced. We begin this journey with U-Scan Cycle Sync and Nutri Balance and look forward to announcing more cartridges on an ongoing basis as well as medical applications of the technology.”
The rechargeable U-Scan reader knows the difference between flush water and urine and ensures it collects only the samples it needs. When in use, urine flows efficiently to a collection inlet, activating a pump when a thermal sensor detects the presence of urine. The sample is guided through a microfluidic circuit and injected into a test pod. Here, the reaction is read by an optical sensor and reported back to the app. Every subsequent flush of the toilet cleans the system, resetting it for the next sample collection.
In Europe, the U-Scan Nutri Balance app shows an analysis of specific gravity, pH, vitamin C and ketone levels. The combination of these measurements helps people monitor their metabolic intake to optimize their daily hydration and nutrients. The ‘actionable’ part of that is that the system can recommend workouts, offer dietary suggestions, and recipes, all to help health-conscious users achieve their goals. The company points out that US functionality of Nutri Balance may vary, depending on what the FDA has to say about the matter.
The product will make its debut in Europe with dwo different health cartridges aimed at consumers. Medically focused cartridges will follow in the not-too-distant future. The price tag is €499.95, and includes one U-Scan reader and a cartridge providing 3 months of testing. The first two cartridges that are becoming available are Cycle Sync, which will help people who have monthly cycles track them, and a Nutri Balance cartridge, which will gives a detailed metabolic guide for nutrition and hydration. The company isn’t sure when the device will be made available in the US, as its launch will be depending on FDA clearance.
Incredibly, U-Scan can tell the difference between various users (and therefore assigning the results to the correct person using the device), through it’s amazingly named Stream ID feature. Low-energy radar sensors embedded within the reader measure multiple variables to identify an individual’s “urine stream signature”, by detecting the movement and distance of the stream. Stream ID information can be affirmed in the app.
In addition to the consumer-focused product, Withings Health Solutions, the company’s business-to-business division serving the healthcare provider market, is making the technology available to partners for research purposes.
The company told TechCrunch it is planning to make the cartridges available on a subscription basis, or on an individual basis.