FT : Government forced to pay Atos £24mn over Met Office supercomputer procureme

Government forced to pay Atos £24mn over Met Office supercomputer procurement
French group claimed its bid was unfairly rejected

The UK government was forced to pay out £24mn to Atos in an out-of-court settlement after the French IT group challenged the award of an £850mn contract to develop a supercomputer for forecasting weather and climate change to US rival Microsoft.

The French company, which was the only other shortlisted bidder, filed a lawsuit in May last year alleging breaches in the government’s obligations under the public procurement regulations but it was settled before it went to court.

The new supercomputer, which will be managed by the Met Office, is expected to be one of the most advanced in the world for weather prediction and climate change analysis. The cost of the overall project is put at £1.2bn.

The terms of the settlement were not disclosed at the time but the latest annual report of the Department for Business, Energy, and Industrial Strategy reveals there was a payout of £24mn to Atos without an admission of liability.

The opposition Labour party accused the government of wasting taxpayers’ money. “This is yet another example of the Conservatives failing to take care of public money. While families are counting every penny, the Tories are shelling out taxpayers’ cash to pay for their own mistakes,” said Angela Rayner, Labour’s deputy leader.

The government said: “The proceedings regarding supercomputer procurement have been resolved with no admission of liability from any party. This settlement is in the best interest of taxpayers.” 

It added that an “independent review has assured that all procurement processes were followed and there were no failures associated with governance or lack of controls”.

In its lawsuit, Atos alleged the procurement process was not managed properly after its tender was non-compliant with technical specifications. The dispute centred on requirements to supply two test supercomputers and a development supercomputer in addition to the main supercomputer system, where the systems were all required to be “architecturally equivalent”.

Atos alleged that the government rejected its bid as “non compliant” on the basis that its proposal for a smaller development computer system used different processors in the main supercomputer, according to court documents.

The company claimed that the government made “obvious errors in the evaluation” of the bid and that the “Met Office has chosen a final tender which scored lower in quality, transferred more commercial risk to the Met Office and is more expensive”.

The Met Office and BEIS denied the allegations, and alleged that Atos proposed a non-compliant solution and that its offer was not “the most economically advantageous”.

Atos said in a statement that it was “pleased to have resolved this matter”.

The new computer is expected to be in the top 25 supercomputers in the world and will be used to more accurately predict storms as well as help select the most suitable locations for flood defences and predict changes to the global climate.

The new supercomputer will also provide detailed information for the energy sector to help it take action against potential blackouts and power surges.

CrunchBase : Our Top 7 Predictions For What 2023 Has In Store For The Startup Wo

Our Top 7 Predictions For What 2023 Has In Store For The Startup World
Coming off a record-breaking 2021 for startup investment, this year has marked a hard reset to more normal times. As we head into 2023 with recession fears top of mind, here are a few of Crunchbase News’ top predictions for what the new year has in store, based on our reporting.

1) IPO markets will remain sluggish, but if anybody is going public it could be these companies. While market conditions remain crummy, there’s also a huge backlog of late-stage startups that have to find an exit at some point. With that in mind, we offered up ideas for 15 companies — ranging from logistics unicorn Flexport to grocery delivery app Instacart — that could be public-market candidates if and when the IPO markets open back up.

2) Expect more M&A as companies go bargain shopping: Speaking of exits, we could see more mergers and acquisitions in 2023, dealmakers predict. Although rising interest rates make capital more expensive, there are plenty of deep-pocketed buyers who already have money to spend and could go bargain-hunting as startup valuations drop, sources told Senior Reporter Chris Metinko.

3) Cybersecurity valuations will come back to Earth: Even the well-funded cybersecurity sector isn’t protected from valuation drops. Industry experts who spoke with Chris about the outlook for cyber startups in 2023 say they expect fundraising and valuations will continue to soften. That’s despite 2022 easily being the second-best on record for VC funding to cyber companies.
4) Fintech will remain hot, despite the crypto crash: Fintech was the largest recipient of venture dollars in 2022, despite an overall drop in VC funding this year and despite high-profile crypto companies going bust. Next year will likely see continued investment in fintech companies, particularly in the B2B payments and business services space, though we should expect to see a pullback in crypto funding in the wake of FTX’s collapse, Senior Data Editor Gené Teare reports.

5) Investors may be losing their appetite for plant-based meat: Investment into plant-based meat startups has come to a standstill, Keerthi Vedantam reports, noting that funding into the sector fell from almost $2 billion in 2021 to around $800 million this year. The challenges are likely to continue next year as startups try to find a way to deliver plant-based meat products at a reasonable price to consumers, who mostly are not vegan or vegetarian. Still, the alternative meat industry did end the year on a good note, with the FDA in November approving California-based Upside Foods’ lab-grown chicken as safe for human consumption.

6) Biotech offers a rare bright spot: One area that could see continued investment even during a downturn? Biotech, specifically those companies involved with the so-called “omics” — think genomics, transcriptomics, metabolomics and proteomics. That’s because, as Keerthi notes, “many of these startups can turn a profit long before they actually make and sell a drug, simply by licensing out their platform to other biotech companies and employing a fee-for-service model.”

7) Novelty is in, copycats are out: Expect to see fewer startups position themselves as the “Uber of X” or the “Shopify of Y” next year, contributing reporter Joanna Glasner writes. While during times of easy money, VCs tended to glom on to follow-on startups riding a hot trend, that era is likely now over. Instead, “startup investors will be looking for novelty in the companies they back,” Joanna predicts. “Out with the me-too business plans. In with those quirky or differentiated enough to stand on their own.” And what are some of those startups? She offers a few picks, from bee startups to a defense tech unicorn.

CrunchBase : The Week’s 10 Biggest Funding Rounds: SpaceX Takes Off In New Year

The Week’s 10 Biggest Funding Rounds: SpaceX Takes Off In New Year; Netskope Secures $401M
Despite last year’s decline in venture capital investment, the first week of the new year saw some sizable deals. Three were more than a quarter-billion dollars, and the top seven made it into the nine-figure realm. This week may be more of an outlier than a harbinger of things to come in light of recent headlines of layoffs and a looming recession, but it still is a big kickoff to the new venture year.

1. SpaceX, $750M, space: Elon Musk’s rocket and satellite company raised a lot of cash in 2022, and this year may be more of the same. SpaceX is looking to raise a fresh $750 million round at a $137 billion valuation, CNBC reported. The report also said an email revealed a16z will likely lead the new funding round — the same VC firm also helped Musk in his $44 billion Twitter buyout. The Hawthorne, California-based startup raised $1.68 billion in June 2022 that valued it at more than $125 billion. The space startup quickly added another $250 million in July. It has raised a total of nearly $10 billion, according to Crunchbase data. Previous investors in the company include NASA, Stack Capital, Bracket Capital and the United States Space Force, among others.

2. Netskope, $401M,cybersecurity: There must be something about cybersecurity startups and $401 million in convertible notes. In October, Eden Prairie, Minnesota-based Arctic Wolf raised $401 million in convertible notes led by existing investor Owl Rock. This week another startup, Santa Clara, California-based Netskope received a $401 million convertible note investment led by Morgan Stanley Tactical Value. Both Netskope and Arctic Wolf are companies that have been rumored to be IPO candidates for the past few years, so such financings make sense with the path to the public market blocked. Convertible notes work like a short-term loan, but are repaid to the investor at a later point in equity — i.e. after an IPO — typically at a discount and can also include an interest rate. Founded in 2012, Netskope has now raised $1.4 billion, per Crunchbase.

3. Silicon Ranch Corp., $375M, renewable energy: Silicon Ranch Corp. actually announced a $600 million raise this week, but only the initial funding of $375 million has closed, with the additional $225 million expected to fund in early 2023. Founded in 2011, Silicon Ranch provides customized renewable energy, carbon and battery storage solutions for a variety of partners across North America. Last year, the company installed 11 new solar facilities that produce nearly 700 megawatts of new generating capacity. Silicon Ranch is no stranger to large raises; it raised $775 million early last year. The company has now raised about $1.6 billion, per Crunchbase.

4. Asimov, $175M, biotech: Biotech was big in a slow week, and Boston-based Asimov led the way with a $175 million Series B led by Canada Pension Plan Investment Board. The startup is developing a synthetic biology platform to design and manufacture next-generation therapeutics, including biologics, cell and gene therapies, and RNA. It currently partners with more than 25 companies that include pharmaceutical companies, biotechs and manufacturing organizations. Founded in 2017, Asimov has raised more than $200 million, per the company.

5. (tied) Chronosphere, $100M, analytics: New York-based Chronosphere, which helps companies monitor their cloud-based applications, raised $100 million from GV, per a report in The Information. Founded in 2019, the startup has now raised more than $350 million, according to Crunchbase.

5. (tied) Metagenomi, $100M, biotech: Metagenomi apparently was in no rush to close its Series B. Almost a year after announcing it had raised $175 million, the biotech company decided to add another $100 million in a Series B extension financing, co-led by Novo Holdings A/S, Catalio Capital Management and Symbiosis. The Emeryville, California-based genetic medicines company has raised more than $450 million, according to Crunchbase data. The startup uses metagenomics and machine learning to discover genome editing systems for therapeutics.

5. (tied) Synthekine, $100M, biotech: Menlo Park, California-based biotherapeutics startup Synthekine closed a $100 million Series C led by The Column Group. Founded in 2018, the company has raised nearly $290 million, per Crunchbase.

8. Ensoma, $85M, biotech: Boston-based genomic medicines company Ensoma closed an $85 million financing co-led by Arix Bioscience and 5AM Ventures. Founded in 2019, the startup has raised $155 million, per Crunchbase.

9. Perceive Biotherapeutics,$78M, biotech: South San Francisco, California-based Perceive Biotherapeutics raised a $78 million Series B led by Johnson & Johnson Innovation. It is the company’s first announced round, according to Crunchbase data.

10. (tied) Belharra Therapeutics,$50M, biotech: San Diego-based Belharra Therapeutics came out of stealth this week in a big way — securing $130 million. First, the startup — which has developed a chemoproteomic-based drug discovery engine — locked up a $50 million Series A from founding investor Versant Ventures. It also announced a multiyear collaboration with Genentech that will provide the startup with $80 million in upfront capital.

10. (tied) Nano-C, $50M, advanced materials: Boston-based Nano-C, a chemical company involved in energy and electronics applications, received $50 million from COTE Capital. Founded in 2001, the company has raised more than $67 million, according to Crunchbase.

Big global deals
With so many big rounds in the U.S. this week, only one from abroad cracked the top five.
  • U.K.-based Upstream Health, which provides technologies for health and social care teams, raised a $140 million Series B.

(ZH) Americans Extremely Pessimistic About US Prospects in 2023: Gallup

Americans Extremely Pessimistic About US Prospects in 2023: Gallup

Coming off several challenging years, Americans enter 2023 with a mostly gloomy outlook for the U.S. as majorities predict negative conditions in 12 of 13 economic, political, societal and international arenas.
When offered opposing outcomes on each issue, about eight in 10 U.S. adults think 2023 will be a year of economic difficulty with higher rather than lower taxes and a growing rather than shrinking budget deficit. More than six in 10 think prices will rise at a high rate and the stock market will fall in the year ahead, both of which happened in 2022. In addition, just over half of Americans predict that unemployment will increase in 2023, an economic problem the U.S. was spared in 2022.
On the domestic front, 90% of Americans expect 2023 will be a year of political conflict in the U.S., 72% think the crime rate will rise, and 56% predict there will be many strikes by labor unions.
Regarding world affairs, 85% of U.S. adults predict the year ahead will be fraught with international discord rather than peaceful. And while 64% think the United States’ power in the world will decline, 73% think China’s power will increase. However, 64% of Americans expect Russia’s power in the world will decrease in 2023, likely a reflection of that country’s recent setbacks in its war against Ukraine.
These findings are from a Dec. 5-19 nationally representative web survey of U.S. adults who are members of Gallup’s probability-based panel.
Gallup has asked Americans for their predictions for the coming year intermittently over the years starting in 1960. The prior surveys were conducted by in-person or telephone interviews, and the results are not directly comparable to the current data collected by self-administered web survey.
However, historical data have generally shown that Americans’ forecasts for the coming year are largely dependent on their views of the domestic and international climates at the time. Likewise, recent Gallup polling underscores the public’s gloomy outlook in their 2023 predictions on domestic issues.
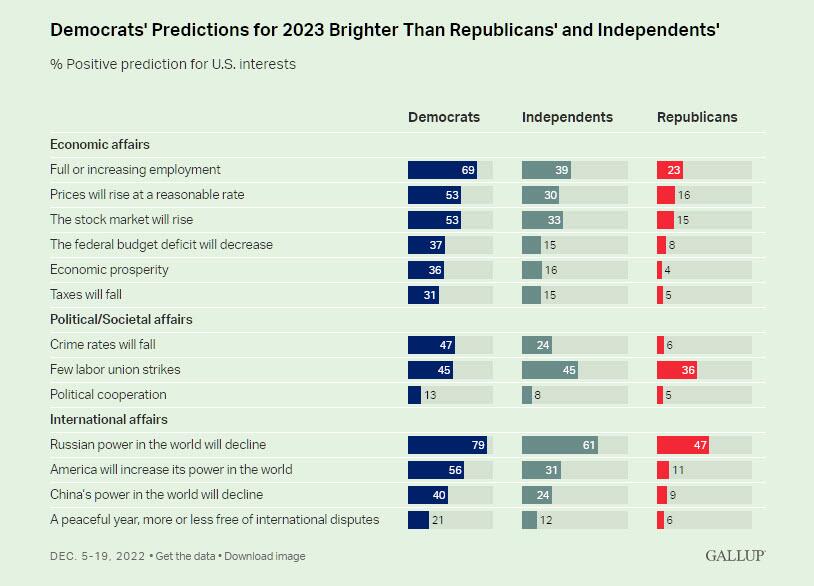
Democrats More Hopeful About 2023 Than Republicans, Independents
Party identification is the greatest demographic differentiator in predictions for 2023, with Democrats more likely than Republicans to offer positive predictions for all of the dimensions. This is a typical phenomenon whereby Americas who identify with the sitting president’s party are more positive in general in their outlook for the year ahead.
Majorities of Democrats foresee five positive developments in 2023. These include full or increasing employment (69%), a reasonable rise in prices (53%), a rising stock market (53%), an increase in U.S. power (56%) and a decrease in Russian power (79%). Democrats are least likely to predict political cooperation (13%) and a peaceful year mostly free of international disputes (21%).
Meanwhile, 61% of independents and 47% of Republicans expect Russian power in the world will decrease. Aside from the 36% of Republicans who expect few labor union strikes in the year ahead, no more than 23% of Republicans expect a positive outcome for any of the other 11 dimensions.
Bottom Line
Americans are greeting 2023 with great skepticism and little expectation that the economic struggles that closed out 2022 will abate. Few U.S. adults also predict the partisan politics that plague the nation will improve, not an unreasonable expectation given that there will be divided government in 2023 after Republicans won control of the U.S. House of Representatives. The public’s predictions for international affairs are similarly pessimistic. However, with their party controlling the White House, Democrats are more hopeful about the year ahead.

FT : Boss of South African power producer Eskom survived poisoning attempt in De

Boss of South African power producer Eskom survived poisoning attempt in December
André de Ruyter, who resigned after trying to overhaul the troubled utility, claims he was given cyanide-laced coffee

The chief executive of South Africa’s troubled Eskom state power monopoly survived an alleged attempt to kill him with cyanide-laced coffee last month, shortly after submitting his resignation.

The alleged attempt to poison André de Ruyter took place before it was widely known he had resigned, according to people familiar with the details. De Ruyter drank a cup of coffee laced with cyanide on December 12, the people said.

Pravin Gordhan, the minister overseeing Eskom and other state companies, on Saturday confirmed that de Ruyter had informed him of the alleged attempt to poison him. “This attempt on his life will be thoroughly investigated and those responsible must be charged,” Gordhan said.

Eskom said that it “cannot comment further on the poisoning incident involving the chief executive, which occurred during December 2022, as the matter is subject to police investigation”.

De Ruyter, who will stay as Eskom chief executive until the end of March while a replacement is found, did not respond to a request for comment.

The timing of the incident indicates that those allegedly seeking to warn de Ruyter or kill him may not have known he had already quit. The coffee machine at Eskom’s Johannesburg headquarters was out of service, according to people briefed on the incident, but he was served the drink from a different source using his usual mug. He immediately felt nauseous and confused, forgetting familiar words.

De Ruyter had sought to turn round Eskom by taking on alleged criminal syndicates that have been draining the state utility through corrupt coal and other contracts. He has blamed a lack of support from President Cyril Ramaphosa’s government for his resignation, amid a battle to stem the worst-ever blackouts in Africa’s most industrialised nation and tackle rampant graft within the company.

The alleged poisoning underscores the threat to the government’s campaign to root out corruption from South Africa’s state-owned companies. Ramaphosa strengthened his grip on the ruling African National Congress in December with his re-election as leader despite a damaging scandal over a theft at his private game farm.

The main opposition Democratic Alliance said on Sunday that “not only has de Ruyter been left out to dry amid ANC shenanigans but now criminal syndicates within Eskom are palpably hell-bent on cementing their stranglehold on Eskom that is destroying the economy . . . firm and decisive action needs to be taken now”.

South Africa’s EE Business Intelligence first reported on Saturday that de Ruyter had fallen violently ill after drinking coffee at Eskom’s headquarters and been rushed to medical facilities where doctors found he had high levels of cyanide in his blood. De Ruyter told the publication: “I have reported the matter to [the South African police] on January 5 2023, and the case can be assumed to be under investigation.”

Eskom’s crisis is seen as the single-biggest threat to the South African economy and to the ANC’s decades-long grip on power ahead of national elections next year.

In 2022 South Africans endured twice as many power outages as the year before as breakdowns increased at Eskom’s fleet of ageing coal power stations. Newer coal-fired plants also constantly malfunction. The power cuts continued throughout South Africa’s holiday season and into the new year.

De Ruyter made many enemies after his appointment in late 2019, as he launched investigations into alleged criminal syndicates that he accused of worsening the blackouts by pilfering supplies from coal power stations and sabotaging attempts to fix problems. He is protected at all times by a bodyguard, as are other executives and some power station operators at the company.

“Make no mistake Mpumalanga is a gangster province,” de Ruyter told the FT in October, referring to the coal-producing region where many of Eskom’s power stations are located. “We’ve had contractors shot in their cars on the way to site because they didn’t give jobs to the right people.”

The alleged attempt to murder or frighten de Ruyter “shows the intense battle between those who want South Africa to work and thrive; and those who want to corruptly enrich themselves”, Gordhan said.

A plan to split heavily indebted Eskom into separate generation, transmission and distribution units has been opposed by some members of the ANC who see it as a way of reducing state control and privatising the energy sector.

In delayed annual statements released last month, Eskom’s auditors warned of “significant control deficiencies” in the supply of coal, fuel and parts to power stations. In one incident, the auditors added, key documents that they had requested “were purposefully destroyed in a fire”.

South Africa has experienced a marked increase in politically linked killings in recent years, from ANC politicians to state officials and anti-graft whistleblowers. Activists have warned of the spread of assassinations as reprisals for probes into corruption and threats to patronage networks.

FT : US regulatory action on the tech sector may come too late — or not at all

US regulatory action on the tech sector may come too late — or not at all
New EU laws could set an example to Washington in reining in social media platforms, AI and crypto

Between the meltdown of cryptocurrency exchange FTX, Elon Musk’s adolescent toying with Twitter, and the appearance of the disruptive chatbot ChatGPT, 2022 was a confrontational year for tech companies. It left society reeling. Now crashing stock prices have finally delivered a moment of reckoning, bursting the bubble of those who peddled a narrative of unregulated, “permissionless” innovation and its inexorable success.

Although FTX and Twitter must deal with their own leadership problems, and OpenAI’s breakthrough will be seen by many as progress rather than a threat, these disparate examples tell a common story: sooner or later the lack of guardrails produce the potential for damage to society. So can we expect decisive regulatory action this year?

The answer unfortunately, at least in the US, is “no”. Washington’s lawmakers are laughed at in Silicon Valley, where companies are confident that their lobbying spend of about $100mn over the past two years will continue to steer proposed laws away from damaging their bottom line.

In Congress, hopes of finding a majority to rein in crypto brokers and social media giants, or to establish firm regulations of artificial intelligence, seem a mission impossible. Political divides are wider than ever, and the House of Representatives is at a historic moment of dysfunction after struggling to find the next Speaker. In 2022, initiatives towards greater antitrust regulation, data protection and even child protections online never managed to be brought to a vote or win over the majority. Given the speed of democratic decision-making, chances are that the US legal landscape in which billionaire tech bros operate will be remarkably similar at the end of 2023.

For Europeans, the answer on regulatory action is “yes, but”. A whole host of new laws are already in the works and will trim the sails of the Sam Bankman-Frieds and Elon Musks of this world, as well as those of Sam Altman of OpenAI. First, markets in crypto assets will be regulated. A new EU law seeks greater transparency regarding risks to consumers, better financial disclosure and oversight of company reserves and environmental harms. We now have to wait for the new law to come in to force this year.

For platforms such as Twitter, business as usual is over in the EU. The two-pronged legislation, the Digital Services Act and the Digital Markets Act, spell out new responsibilities for companies on moderating content, and clarify antitrust rules for gatekeeper companies. That means Musk will not enjoy limitless personal power over what content to allow on Twitter. There will also be greater transparency on algorithms. And here’s a date to mark in your calendar: February 17, a deadline for platforms to report the number of their active users.

On top of these new constraints, the EU’s AI Act, to be finalised this year, will be a world-leading law that takes a risk-based approach. Some very risky applications such as social credit scoring will be banned while the use of AI in chatbots would be identified as low risk. For generative AI (the technology used to power ChatGPT) the question is whether that label does justice to risks of bias in the underlying data sets that large AI models are trained on. Or would the application be considered risky if it comes up with misguided health solutions?

The political agreement within the EU means important work has already been done. Yet the power of the new rules to have an impact on crypto assets, social media platforms and artificial intelligence also depends on successful enforcement. That is a space to watch with a critical eye.

Once EU rules prove their promise in practice, American internet users and lawmakers can observe from the other side of the Atlantic that US technology companies are perfectly capable of complying with laws that ensure a fairer economy, respect for civil rights and the protection of consumers and investors. And they can already see the challenges of unregulated technologies all around us. “No industry did more harm than tech,” the investor Roger McNamee said last week.

Last year offered plenty of reminders that the marketing and lobbying narratives of tech companies are not matched by the level of societal value they create. Yes, crypto assets, social media platforms and AI companies are all different, and the companies in those sectors face distinct challenges. But to wait for the next disaster resulting from a lack of regulation and oversight would be a mistake. Here’s to making 2023 a turning point.

>>> Weekend Papers Summary

Weekend Papers Summary

NEW YORK TIMES
-On 15th vote, McCarthy is elected House Speaker. Kevin McCarthy won over a bloc of right-wing holdouts and finally clinched the speakership after four days of voting. The result came after a dramatic, late-night roll call that hinged on a single vote, ending the longest speaker election since 1859.
-As the Republican leader Kevin McCarthy has made concessions to the far right, he has effectively agreed to give them carte blanche to disrupt the workings of the House — and to hold him hostage to their demands.
-After dramatic 14th vote, Trump calls holdouts who refused to back McCarthy. The former president made crucially timed calls to Representative Matt Gaetz and others who sunk McCarthy’s 14th effort to be elected House speaker.
-Biden honors ‘extraordinary Americans’ who defended democracy on Jan. 6. President Biden marked the second anniversary of the Jan. 6 attack by awarding the Presidential Citizens Medal to 14 people.
-Attacks continue in Ukraine despite Russia’s supposed ceasefire
Ukraine never accepted Russia’s unilateral Christmas truce, dismissing it as a ploy, and Russian shelling was as intense as ever in a hotly contested city.
-Ant group says its founder, Jack Ma, will relinquish control. Ant Group, the fintech sister company of the e-commerce behemoth Alibaba, is one of China’s most influential companies.
-A 6-year-old has shot a teacher at a Virginia elementary school. The teacher at Richneck Elementary School in Newport News has “life-threatening injuries” after being shot by one of her students, the authorities said.
-Widening highways doesn’t fix traffic. So why can’t we stop? With billions available to improve transportation infrastructure, states can try new ways to address congestion. But some habits are hard to break.
-Here are the people Iran sentenced to death in its protest crackdown.
An updated look at the Iranians marked for execution in the government’s attempt to curb a months-long uprising.
-A judge declined to dismiss the suit by Letitia James, New York’s attorney general, against former President Trump, calling his lawyers’ filing frivolous.
-After troops arrested a son of the notorious drug lord known as El Chapo, cartel gunmen tried to free him, resulting in a series of gun battles and thousands of troops called into the fight.

THE FINANCIAL TIMES
-Kevin McCarthy has been elected as Speaker of the House of Representatives, ending a tortuous week of wheeling and dealing on Capitol Hill that exposed sharp divisions in the Republican Party and raised fresh questions about whether Congress can govern effectively in the years to come.
-Elon Musk’s Twitter takeover did not go down well on Wall Street, which feared the chaos and political polarization it unleashed would tarnish the automaker’s brand and distract him at a critical time. A Tesla stock price slide that began in the autumn turned into an avalanche; shares are now 73% below their peak of a little more than a year ago. Musk himself is $200B poorer.
-Chinese billionaire Jack Ma is to relinquish control of Ant Group, the fintech company revealed on Saturday, as its founder continues his withdrawal from his online businesses following Beijing’s tech crackdown.
Ma will see his voting rights shrink from above 50% to 6.2%, according to calculations based on a statement from the online payments and loans provider. The planned change of control, first reported last July, would help release the company from the limbo it has experienced since an intended IPO was pulled at the last minute in November 2020.
-Rising economic optimism buoyed stock markets on both sides of the Atlantic on Friday, after Eurozone inflation figures and US jobs data boosted hopes of a soft landing this year. But economists warned that while a recent big fall in energy prices has bolstered prospects for 2023, underlying inflation would maintain pressure on central banks to raise interest rates further to keep price rises under control.
-Russia is trying to block the reappointment of the Danish head of the UN’s leading environmental agency, following a highly critical report about the impact of the war on Ukraine, according to people familiar with the matter.
-Rival members of Qatar’s royal family are battling for control of the world’s largest cut blue diamond in London’s High Court, with one side trying to force a $10M sale of the opulent 70 carat “Idol’s Eye” gemstone. The storied Indian diamond, whose past owners include a Sultan of the Ottoman Empire, is at the centre of a lawsuit filed by Qipco, a conglomerate run by Qatar’s big-spending art collector Sheikh Hamad bin Abdullah al-Thani.
-Data show UK public support for leading members of the royal family holding firm in the face of criticism from Prince Harry and his wife, Meghan, Duchess of Sussex. The latter prince’s own personal popularity, however, has been on the slide since he embarked on a series of media appearances and interviews last year.
-Since early 2020, the Chinese, the world’s largest tourism population, have been cut off from the world by China’s apparatus of zero-Covid restrictions that included mass-testing, lockdowns and quarantine for arrivals.
Some countries are imposing border controls and compulsory testing on visitors from China. This weekend, as Beijing finally dismantles the last of those measures, that is set to change. Around the world, airlines, hotels and luxury businesses are bracing for the return of tens of millions of tourists and their hundreds of billions of dollars — though experts suggested the revival could take months to fully gather pace.
-Launches of hedge funds have dropped to their lowest level since the 2008 financial crisis, as some managers struggle to make money in falling markets and huge firms such as Millennium and Citadel hoover up traders who once might have branched out on their own.
-Rival teams leading FTX bankruptcy proceedings in the US and the Bahamas, which have clashed over the insolvency proceedings for the cryptocurrency exchange, struck a co-operation agreement on Friday following weeks of public feuding.
Under the agreement, “the parties commence work together to share information, secure and return property to their estates, co-ordinate litigation against third parties and explore strategic alternatives for maximizing stakeholder recoveries”, the two bankruptcy teams said in a statement on Friday.
-Mali has pardoned 49 Ivorian soldiers arrested in July and sentenced last week by a court to 20 years in prison, the military junta said on Friday. The gesture, amid diplomatic efforts to free the captives, ends a dispute that had raised tensions between the neighboring countries and sparked threats of sanctions being imposed on the Malian regime by the ECOWAS regional bloc.
-US jobs growth slowed for a fifth consecutive month in December after the Federal Reserve’s aggressive interest rate rises squeezed economic activity even as the US labor market remained historically tight. The world’s largest economy added 223,000 jobs in the final month of 2022, lower than the downwardly-revised 256,000 increase registered in November and well below last year’s peak of 714,000 in February. Most economists had expected a 200,000 increase.
-As commissioner of the US National Football League, Roger Goodell has presided over the expansion of the NFL, the world’s most valuable professional sports league. But his tenure has been marked by controversies from player protests to legal settlements over concussions.
On Monday, Goodell and the league were thrust into a new crisis after Buffalo Bills player Damar Hamlin suffered a cardiac arrest on the field, causing the suspension of a nationally televised primetime game with ramifications for the postseason games leading up to the Super Bowl next month.

NY POST
-Former President Donald Trump added to Friday night’s drama on the House floor by calling two Republican lawmakers who were refusing to back eventual House Speaker Rep. Kevin McCarthy during the 14th round of voting, according to reports. Trump phoned Reps. Matt Gaetz (R-Fla.) and Andy Biggs (R-Ariz.) — former supporters of the 45th president — to urge them to back McCarthy for the gavel after four days of grueling negotiations, Politico reported.
During the 14th ballot, Gaetz ultimately voted “present,” which, in part, derailed McCarthy’s speakership bid that round. Biggs voted for Rep. Jim Jordan in the 14th round. The former president also apparently called conservative firebrand Rep. Marjorie Taylor Green, (R-Ga.), who is supporting McCarthy.
-Amazon employees openly welcomed a potential comeback by Jeff Bezos to run the struggling e-retail giant after current CEO Andy Jassy announced a larger-than-expected wave of layoffs, according to a report Friday. Speculation that Bezos could seek to supplant Jassy as CEO has increased during a sustained downturn in Amazon’s stock price. In a recent blog post, Michael Batnick, a managing partner of Ritholtz Wealth Management, suggested Bezos could “pull a Bob Iger” this year and return to stabilize the company he founded.
-Burger chain McDonald’s said Friday that it will review corporate staffing levels and aim to build more restaurants as part of an updated business strategy. The new plan, announced in a letter from Chief Executive Officer Chris Kempczinski to global employees and seen by Reuters, calls for the Chicago-based company to cancel or “de-prioritize” some initiatives while also accelerating development. That could lead to layoffs in some areas and expansion in others, the company said. “We will look to our strategy and our values to guide how we reach those decisions and support every impacted member of the company,” the letter said, adding that McDonald’s will begin announcing key decisions by April 3.

>>> Barron’s Weekend Summary

Barron’s Weekend Summary: The tech-stock declines—the Nasdaq Composite just finished its worst year since 2008

Cover Story:
-The tech-stock declines—the Nasdaq Composite just finished its worst year since 2008—are a continuing unwinding of rapid changes that took place early in the pandemic, when homebound consumers spent lavishly on technology products, digital services, and physical goods. Along the way, venture capitalists urged start-ups in their portfolios to boost spending in order to capture trends and increase growth. And they gave them the funds to get that done. All that spending was fueled by a flood of money from government stimulus and interest-rate cuts, making it easier to borrow. But extrapolating growth turned out to be a bad assumption. As economies reopened, spending shifted back to real-world experiences and away from technology.

Interview:
-Dave Bujnowski, who co-manages Baillie Gifford’s US equity growth portfolio. While Bujnowski says last year’s experience forced him to challenge his assumptions—the U.S. fund fell more than 50% last year, after returning an average of 43% annually in the prior three years—he is unflinching in his view that Baillie has the right approach in making long-term bets on the power of change. Bujnowski spoke with Barron’s about why he remains a true believer in the power of change-driven growth, why he still likes cloud stocks, and why he remains a bull on Tesla.

Tech Trader:
-This year, organizers at the Consumers Electronics Show (CES) were targeting 100,000 attendees. It felt busier. The halls were bustling, taxi lines were long, and restaurants were packed. At last year’s show, almost everyone was masked; this year, almost no one was. Abbott Labs was handing out free two-packs of Binax Now Covid test kits, but there was no testing requirement, and no one asked for my vax card. The show felt giddy, a throwback to the days before most people had heard of the coronavirus. The talk from the stage was optimistic about the future, particularly around the power of artificial intelligence. But it became clear that the industry faces tough months ahead. In 2022, tech stocks cratered in the face of soaring interest rates, rising inflation, and a potential recession. In 2023, things seem likely to get worse before they get better.

The Trader:
-The Fourth Quarter reporting season is about to begin. Some major companies— JPMorgan Chase, Bank of America, UnitedHealth Group and Delta Air Lines will be among those kicking off the festivities. The vast majority of the S&P 500 will report over the following month and a half. Few are expecting a good fourth quarter. In aggregate, S&P 500 companies are expected to report their first losing quarter since 2020. Earnings per share are forecast to decline by 2.2% year over year, to $53.87, after roughly 4.4% growth in the third quarter and 8.4% in the second quarter, per IBES data from Refinitiv. The consensus fourth-quarter outlook became much gloomier as 2022 proceeded—at the start of last year, analysts had penciled in 14.1% year-over-year earnings growth for the period.
-Schwab finished last year off 1%. But there was a lot more action than that minuscule loss implies. The stock tumbled 29% through June 17, as investors fretted about higher rates pushing money out of Schwab’s deposit accounts and into higher-yielding money-market funds, before bouncing 38% over the rest of the year to finish roughly flat. This year has gotten off to a better start, with Schwab gaining 1.5%, to $84.54, during the first week of trading—and there’s a good chance those gains continue. Goldman Sachs analyst Alexander Blostein upgraded the stock to Buy from Neutral this past week. In all, Schwab should be able to grow earnings at 15% in 2023 and by 32% in 2024. Blostein has a 12-month price target of $98 on Schwab, up 16% from Friday’s close.

Features:
-Michael Kops, a vice president and partner at Heartland Advisors, recommends value investing, He says that for today’s investors wondering if it’s too late to embrace value, that experience should offer an important clue. Growth and value tend to take turns leading the market, but the cycles often last years, not days. More importantly: Value investing and “buying on the dips” are not the same thing. Just because popular growth stocks that were once the market’s darlings are down considerably from their peak doesn’t mean they’re cheap. Or cheap enough to make them worth buying. They may well have more room to fall. Looking back at 2000, investors who bought beaten-down growth stocks on the dips were not thinking like true bargain hunters. As Graham noted, the intelligent investor focuses on the fundamentals and is always conscious of building in a margin of safety to their strategy.
-Airlines enjoyed a strong second half of 2022 as robust demand and industrywide capacity constraints led to higher airfares and bumper revenue. For US carriers, the year ended on a bit of a sour note as a brutal winter storm left passengers stranded at airports across the country. Aside from Southwest Airlines, the worst affected carrier by some distance, the disruption is unlikely to have a major impact on US airlines’ fourth quarter earnings. The large carriers are better placed than their low-cost counterparts to weather those cost pressures. The bigger airlines are also more likely to benefit from three trends–and potential positive catalysts–emerging in 2023. Raymond James analysts expect United Airlines to have the greatest upside from the reopening of the Pacific region to travel. In Europe, Ryanair, with its robust balance sheet and ultralow cost base, could be one to watch. But, the European long-haul sector isn’t the same as it was prepandemic. Two major players, Norwegian Air and Thomas Cook have exited that market and British Airways owner International Consolidated Airlines is likely to benefit from their market shift.

European Trader:
-Investors hoping to play defense might look for companies that use inflation to their advantage. That’s where a stock like Bunzl can be attractive. The British company is a worldwide distributor of equipment for food-service providers and other companies. Its logo can be found on disposable cutlery in fast-food restaurants and on the sides of trucks delivering cleaning and safety products. Bunzl operates in 31 countries (in the Americas, Europe, and Asia Pacific) and enjoyed a decent 2022. It benefited from the pickup in activity as most of the world emerged from the pandemic—and was able to raise prices along the way. Bunzl had a “strong 2022, benefiting from the highest levels of product inflation in decades, plus continued post-lockdown rebounds,” says Karl Green, an analyst at RBC Capital Markets, who rates the stock a Hold.

Emerging Markets:
-Investors brimmed with optimism when Luiz Inácio Lula da Silva was elected Brazil’s president on Oct. 30, returning to power after two prior terms in 2003 to 2011. It didn’t last. The iShares MSCI Brazil exchange-traded fund dropped 17% since then. Brazilian bonds could be more attractive than equities nonetheless, says Thierry Larose, portfolio manager for emerging markets local debt at Vontobel Asset Management. Yields on 10-year sovereign Brazilian bonds have risen 1.5 percentage points since Lula’s election, to more than 13%, while inflation keeps declining, to less than 6% annually. “Brazil’s real rates are the highest in the world,” Larose says. “My long-term opinion is cautiously optimistic. Some Brazilian stocks could become attractive depending on how the early dust settles. Continued decline in the real could boost exporters like meat giant JBS or aircraft giant Embraer, says Steven Schoenfeld, CEO of MarketVector Indexes. A Lula tilt to pragmatism, and a stable environment to follow, would boost the leading private banks, Itaú Unibanco Holding and Banco Bradesco.

Commodities:
-Last year, global oil companies boomed. BP and Shell, both based in London, saw share prices rise some 40% in 2022 and trade at five times forward earnings. US-based Exxon Mobil soared nearly 80% and trades at almost 10 times earnings, while Chevron rose 50% and trades at 11 times. Why that gap? Many blame windfall-profit taxes. All of the oil giants feasted on rising oil prices after Russia invaded Ukraine. While prices have fallen, they’re still at levels that produce sizable profits. However, European governments are clawing back some of those gains by taxing oil producers to subsidize high energy costs for consumers.

Streetwise:
-Jack Hough likes biotech. He says that he just needs to figure out what the stocks will do. Last year, Respira Technologies became Qnovia. It’s run by a former tobacco executive with vape experience, and it’s developing an inhaled nicotine platform for quitting smoking. On one hand, Hough says he found years ago that a pretty good platform for that is just to not inhale any more nicotine. But on the other hand, going from Q straight to N in a company name sounds clinically promising. A biotech once called CytRx fell from over $4 a share in 2021 to 10 cents last September, before changing its name to LadRx. Still 10 cents. Bone Therapeutics is now BioSenic and still into bone therapeutics. The industry blog FiercePharma calls this and many other examples a “biopharma name-changing craze.” The biotech industry could use a fresh look. The SPDR S&P Biotech XBI exchange-traded fund gained 32% in 2019, and then 48% in 2020, before sliding 20% in 2021, and another 26% last year. Now it’s back to a price it hit in 2015. There was a rush of companies going public when shares were riding high. Many weren’t only prerevenue, but also not yet testing in humans. With interest rates rising, investors have favored pharma stalwarts instead. Geoff Meacham, who covers drugs for BofA Securities, says to favor quality companies with good growth prospects. This past week, he downgraded Pfizer PFE to Neutral from Buy, and did just the opposite with Merck, raising it to Buy.