Fed’s Barkin Says Economy May Be Shifting to Higher Inflation Regime
Richmond Fed president says the central bank may need to tighten monetary policy more often
The Federal Reserve may be facing more persistent inflation pressures that could mean interest rates will be higher than in recent years, Federal Reserve Bank of Richmond President Thomas Barkin said Tuesday.
“There are a few reasons to think we may face more headwinds when it comes to containing inflation going forward,” Mr. Barkin said in a speech text.
“We may need to navigate in the context of more medium-term inflationary pressure than we have experienced during the Great Moderation,” he added, referring to cooling levels of inflation in recent decades.
Mr. Barkin, who is not currently a voting member of the rate setting Federal Open Market Committee, said this potential regime shift could affect monetary policy, though the Fed’s 2% inflation target would remain in place and the central bank would still have the ability to meet that goal.
In the face of more persistent inflation pressures, the Fed’s “efforts to stabilize inflation expectations could require periods where we tighten monetary policy more than has been our recent pattern,” Mr. Barkin said.
“Inflationary pressure puts constantly on the table the potential for a trade-off between employment and inflation, our dual mandate goals,” he added, suggesting the effort to cool inflation could push up unemployment.
Higher longer term inflation could come from different factors, among them a retreat from globalized supply chains, changing demographics reducing the number of available workers, geopolitical events and headwinds related to government spending, Mr. Barkin said.
In the near term, he offered support for the Fed’s effort to bring inflation down with interest rate increases.
“With inflation persisting and broadening, we see clearly that it is time to normalize our monetary policy stance,” Mr. Barkin said. “How far we will need to raise rates in fact won’t be clear until we get closer to our destination, but rest assured we will do what we must to address this recent bout of above-target inflation. And this commitment does not necessarily require a hard landing.”
Mr. Barkin said he was upbeat about the current state of the U.S. economy, citing a strong job market and solid levels of demand.
After Hours Summary: NSTG -30.2% falls on weak guidance; PYPL -1.6% CFO to become Walmart CFO; AFMD +5.3% trades higherAfter Hours Gainers:
Companies trading higher in after hours in reaction to earnings/guidance: MXCT +1.9% (also CFO departs), ASH +1.3% (provides upbeat preliminary MarQ results; reiterates FY22 outlook)
Companies trading higher in after hours in reaction to news: AFMD +5.3% (stock offering), GRTS +5.1% (presentations at AACR support expertise in neoantigen vaccine), ORIC +4.3% (presents promising preclinical data on three programs), SB +2.2% (to acqurie vessel for $30 mln), BCTX +1.9% (presents development details of Bria-OTS Platform technology), SLGC +1% (announces journal publication of landmark proteomics study), ANGI +0.7% (reports monthly metrics for March), HONE +0.6% (authorizes new share repurchase program equating to 5% of shares outstanding), PSX +0.6% (names new CEO), AMC +0.5% (finalizes deal with Bow Tie Cinemas to purchase and operate seven locations), PG +0.4% (increases dividend), CABO +0.1% (names new CFO)
After Hours Losers:
Companies trading lower in after hours in reaction to earnings/guidance: NSTG -30.2% (lowers Q1 product and service revenue guidance), NTNX -0.2% (reaffirms AprQ and FY22 guidance; also names new CFO)
Companies trading lower in after hours in reaction to news: LQDA -12% (stock offering), HLMN -8.1% (commences 10 mln share offering by selling stockholders; also guides Q1 revenue above consensus), TPTX -3.2% (announces positive topline data for Repotrectinib), SQSP -2% (CFO to resign), PYPL -1.6% (PayPal CFO John Rainey to become Walmart CFO), OR -0.9% (provides preliminary deliveries update for Q1), CTS -0.1% (to acquire Ferroperm Piezoceramics for Danish Krone 525 mln in cash), NE -0.1% (provides update on ongoing merger control process)
Closing Stock Market SummaryThe S&P 500 declined 0.3% on Tuesday, fading an early 1.3% gain that was rooted in hopes that inflation rates could be peaking. The Nasdaq Composite (-0.3%) and Dow Jones Industrial Average (-0.3%) followed similar price action, while the Russell 2000 (+0.3%) eked out a gain.
Seven of the 11 S&P 500 sectors closed lower after each spent time in positive territory during the day. The financials (-1.1%) and health care (-1.0%) sectors declined at least 1.0%, while the energy (+1.7%), utilities (+0.4%), and consumer discretionary (+0.2%) sectors closed higher.
Early in the day, the Consumer Price Index (CPI) report for March was being construed as a sign of peak inflation and a corresponding excuse to rally. Total CPI rose 1.2% m/m, as expected, while core CPI, which excludes food and energy, increased by just 0.3% (Briefing.com consensus 0.5%).
The fast start for the market was further supported by technical factors as the S&P 500 temporarily reclaimed its 50-day moving average (4424) and short-covering activity among investors caught off guard by the market's positive reaction to the CPI data.
The rally excuse also pertained to the Treasury market, where the 2-yr yield subsequently dropped 11 basis points to 2.39% and the 10-yr yield dropped six basis points to 2.73%. The U.S. Dollar Index topped the 100.00 level (100.31, +0.37, +0.4%) for its ninth-straight advance.
Unfortunately, the stock market proceeded to drift lower the rest of the day amid a lack follow-through buying interest and a violation of the S&P 500's 50-day moving average. The benchmark index closed below the key technical level.
The nervous price action was presumably tied to a recognition that the Fed is poised to hike rates by 50 basis points next month, underlying growth concerns, uncertainty regarding corporate guidance this earnings season, and disappointing earnings reactions in CarMax (KMX 93.33, -9.84, -9.5%) and Albertsons (ACI 31.97, -2.81, -8.1%).
Oil prices reclaimed $100.00 per barrel ($100.69, +6.53, +6.9%), which was cited as an additional drag on sentiment, although the rebound corresponded with the good news that Shanghai started to relax some COVID-19 restrictions.
American Airlines (AAL 17.13, +0.16, +0.9%), meanwhile, provided a lift for the airline industry after raising its Q1 revenue guidance. As a reminder, JPMorgan Chase (JPM 131.54, -1.46, -1.1%) will report earnings prior to Wednesday's open.
Reviewing Tuesday's economic data:
- Total CPI increased 1.2% month-over-month in March, as expected, while core CPI, which excludes food and energy, increased a smaller-than-expected 0.3% (consensus 0.5%). That left total CPI up 8.5% year-over-year, the highest 12-month increase since December 1981, and core CPI up 6.5% year-over-year, the highest 12-month increase since August 1982.
- The key takeaway from the report is that it is subject to widening interpretations. The popular narrative is that it's hard to believe things will get any worse; therefore, this report is "good" because it must mark peak inflation. The less popular, but practical, narrative is that this report reveals a broadening in inflation pressures that will push the Fed to raise rates by 50 basis points at the next FOMC meeting.
- The Treasury Budget showed a $192.7 bln deficit in March versus a $659.6 bln deficit in the same period a year ago. The budget data is not seasonally adjusted, so the March deficit cannot be compared to the February deficit of $216.6 bln.
- The budget deficit over the last 12 months is $1.74 trln versus a deficit of $2.20 trln in February.
- The NFIB Small Business Optimism Index for March decreased to 93.2 from 95.7 in February.
Looking ahead, investors will receive the Producer Price Index for March and the weekly MBA Mortgage Applications Index on Wednesday.
- Dow Jones Industrial Average -5.8% YTD
- S&P 500 -7.7% YTD
- Russell 2000 -11.5% YTD
- Nasdaq Composite -14.5% YTD
Research Calls
- Upgrades:
- Aptiv (APTV) upgraded to Equal Weight from Underweight at Wells Fargo; tgt raised to $112
- Brighthouse Financial (BHF) upgraded to Equal Weight from Underweight at Wells Fargo; tgt raised to $54
- Cardinal Health (CAH) upgraded to Overweight from Equal-Weight at Morgan Stanley; tgt $74
- Charles Schwab (SCHW) upgraded to Buy from Neutral at Compass Point; tgt $98
- CrowdStrike (CRWD) upgraded to Buy from Neutral at Goldman; tgt raised to $285
- Domino's Pizza (DPZ) upgraded to Buy from Neutral at Citigroup; tgt raised to $487
- Ferrari (RACE) upgraded to Outperform from Neutral at Exane BNP Paribas
- Finmeccanica SpA (FINMY) upgraded to Buy from Hold at Deutsche Bank
- First Financial (THFF) upgraded to Outperform from Mkt Perform at Raymond James; tgt $49
- Fox Corporation (FOXA) upgraded to Positive from Mixed at Vertical Group
- ICON plc (ICLR) upgraded to Buy from Hold at Deutsche Bank; tgt raised to $310
- Juniper Networks (JNPR) upgraded to Neutral from Sell at Citigroup; tgt raised to $36
- Louisiana-Pacific (LPX) upgraded to Buy from Hold at TD Securities; tgt $75
- Novo Nordisk A/S (NVO) upgraded to Equal-Weight from Underweight at Morgan Stanley
- Ryanair Hldgs (RYAAY) upgraded to Buy from Neutral at UBS
- Downgrades:
- AmerisourceBergen (ABC) downgraded to Equal-Weight from Overweight at Morgan Stanley; tgt $178
- Bancolombia S.A. (CIB) downgraded to Neutral from Overweight at JP Morgan; tgt $46
- Chegg (CHGG) downgraded to Sector Weight from Overweight at KeyBanc Capital Markets
- Cisco (CSCO) downgraded to Sell from Neutral at Citigroup; tgt lowered to $45
- Cohu (COHU) downgraded to Neutral from Buy at B. Riley Securities; tgt lowered to $30
- Dana Inc (DAN) downgraded to Equal Weight from Overweight at Wells Fargo; tgt lowered to $17
- Enjoy Technology (ENJY) downgraded to Market Perform from Outperform at Telsey Advisory Group; tgt lowered to $4
- F5 Networks (FFIV) downgraded to Equal-Weight from Overweight at Morgan Stanley; tgt lowered to $250 and removed as Top Pick
- Federated Hermes (FHI) downgraded to Sell from Neutral at Citigroup; tgt lowered to $28.50
- Fiserv (FISV) downgraded to Market Perform from Outperform at Cowen; tgt lowered to $126
- Franklin Resources (BEN) downgraded to Mkt Perform from Outperform at Keefe Bruyette; tgt $30
- Franklin Resources (BEN) downgraded to Neutral from Buy at Citigroup; tgt lowered to $28
- Hewlett Packard Enterprise (HPE) downgraded to Underweight from Equal-Weight at Morgan Stanley; tgt lowered to $15
- Ingredion (INGR) downgraded to Neutral from Outperform at Credit Suisse; tgt lowered to $94
- Invesco (IVZ) downgraded to Mkt Perform from Outperform at Keefe Bruyette; tgt $25
- JetBlue Airways (JBLU) downgraded to Underperform from Peer Perform at Wolfe Research
- Krispy Kreme, Inc. (DNUT) downgraded to Neutral from Buy at Citigroup; tgt lowered to $16
- Kulicke & Soffa (KLIC) downgraded to Neutral from Buy at B. Riley Securities; tgt lowered to $59 *
- Landos Biopharma (LABP) downgraded to Hold from Buy at Jefferies; tgt lowered to $1.40
- Mytheresa (MYTE) downgraded to Equal-Weight from Overweight at Morgan Stanley; tgt $14
- NetApp (NTAP) downgraded to Equal-Weight from Overweight at Morgan Stanley; tgt lowered to $91
- PACCAR (PCAR) downgraded to Neutral from Buy at Citigroup; tgt $90
- Rapid7 (RPD) downgraded to Neutral from Buy at Goldman; tgt $130
- Repare Therapeutics (RPTX) downgraded to Hold from Buy at Stifel; tgt $11
- Restaurant Brands Int'l (QSR) downgraded to Neutral from Buy at Citigroup; tgt lowered to $64
- Rolls Royce PLC (RYCEY) downgraded to Underweight from Neutral at JP Morgan
- Starbucks (SBUX) downgraded to Neutral from Buy at Citigroup; tgt lowered to $91
- STMicroelectronics (STM) downgraded to Equal Weight from Overweight at Barclays
- Skyworks (SWKS) downgraded to Neutral from Buy at B. Riley Securities; tgt lowered to $138
- Utz Brands (UTZ) downgraded to Neutral from Outperform at Credit Suisse; tgt lowered to $16.50
- Verint Systems (VRNT) downgraded to Neutral from Buy at Goldman; tgt $57
- Waste Mgmt (WM) downgraded to Market Perform from Outperform at BMO Capital Markets; tgt $174
- Others:
- ADTRAN (ADTN) initiated with a Buy at Rosenblatt; tgt $25
- Align Tech (ALGN) added to Tactical Underperform List at Evercore ISI
- BJ Restaurants (BJRI) initiated with a Neutral at Citigroup; tgt $29
- Bloomin' Brands (BLMN) initiated with a Neutral at Citigroup; tgt $24
- Brinker (EAT) initiated with a Neutral at Citigroup; tgt $38
- Calian Group (CLNFF) initiated with an Outperform at BMO Capital Markets
- Calix Networks (CALX) initiated with a Buy at Rosenblatt; tgt $60
- Cheesecake Factory (CAKE) initiated with a Buy at Citigroup; tgt $52
- Chipotle Mexican Grill (CMG) initiated with a Buy at Citigroup; tgt $1900
- Cracker Barrel (CBRL) initiated with a Sell at Citigroup; tgt $97
- Darden Restaurants (DRI) initiated with a Buy at Citigroup; tgt $162
- Denny's (DENN) initiated with a Neutral at Citigroup; tgt $15
- First Bancorp (FBP) assumed with an Outperform at Keefe Bruyette; tgt $17.50
- First Watch Restaurant Group (FWRG) assumed with a Buy at Citigroup; tgt lowered to $17
- HashiCorp (HCP) initiated with a Neutral at Piper Sandler; tgt $59
- Helmerich & Payne (HP) initiated with a Buy at The Benchmark Company; tgt $53
- Jack In The Box (JACK) initiated with a Neutral at Citigroup; tgt $104
- Mondelez Int'l (MDLZ) resumed with an Outperform at Credit Suisse; tgt $70
- McDonald's (MCD) assumed with a Neutral at Citigroup; tgt raised to $270
- OFG Bancorp (OFG) assumed with an Outperform at Keefe Bruyette; tgt $35
- Patrick Industries (PATK) initiated with a Buy at Truist; tgt $75
- Ping Identity (PING) initiated with a Buy at DA Davidson
- Pool (POOL) initiated with a Hold at Edward Jones
- Popular (BPOP) assumed with an Outperform at Keefe Bruyette; tgt $115
- Pyxis Tankers (PXS) initiated with a Buy at H.C. Wainwright; tgt $1.50
- QuantumScape Corporation (QS) initiated with a Hold at Deutsche Bank; tgt $20
- Sculptor Capital (SCU) added to 90-day Positive Catalyst Watch at Citigroup
- SelectQuote (SLQT) added to Tactical Underperform List at Evercore IS
- Sweetgreen (SG) initiated with a Neutral at Citigroup; tgt $32
- Syneos Health (SYNH) initiated with a Buy at Deutsche Bank; tgt $102
- T. Rowe Price (TROW) added to 30-day Negative Catalyst Watch at Citigroup
- Tenable (TENB) initiated with a Buy at DA Davidson; tgt $75
- Texas Roadhouse (TXRH) initiated with a Buy at Citigroup; tgt $105
- TORM plc (TRMD) initiated with a Buy at H.C. Wainwright; tgt $14
- Upstart (UPST) initiated with an Outperform at FBN Securities; tgt $150
- Veritone (VERI) initiated with a Neutral at UBS; tgt $18
- Wendy's (WEN) initiated with a Neutral at Citigroup; tgt $23
- Wingstop (WING) initiated with a Buy at Citigroup; tgt $160
- Xometry (XMTR) initiated with a Buy at Loop Capital; tgt $50
- Yum! Brands (YUM) initiated with a Buy at Citigroup; tgt $156
"Extraordinary" - US Consumer Prices Soar At Fastest In Over 40 Years
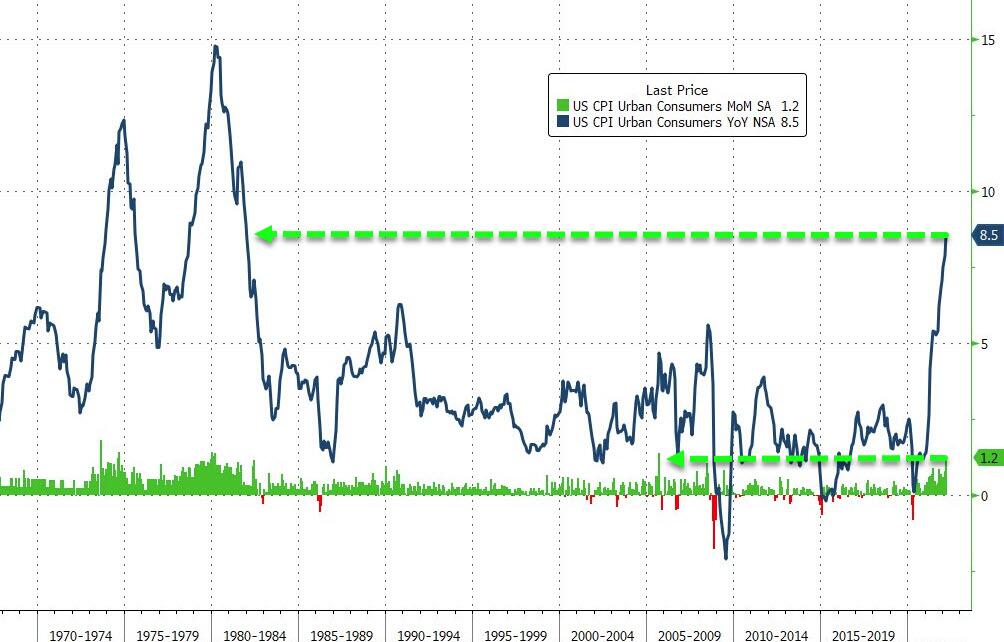
Having warned the world to expect "extraordinarily elevated" levels of inflation due to "Putin's Price Hike", The White House is likely in shock this morning as headline CPI rose 1.2% in March (vs +1.2% MoM) which sent the headline CPI up a shocking 8.5% YoY (vs +8.4% YoY exp and +7.9% prior) - the highest since 1981.
Source: Bloomberg
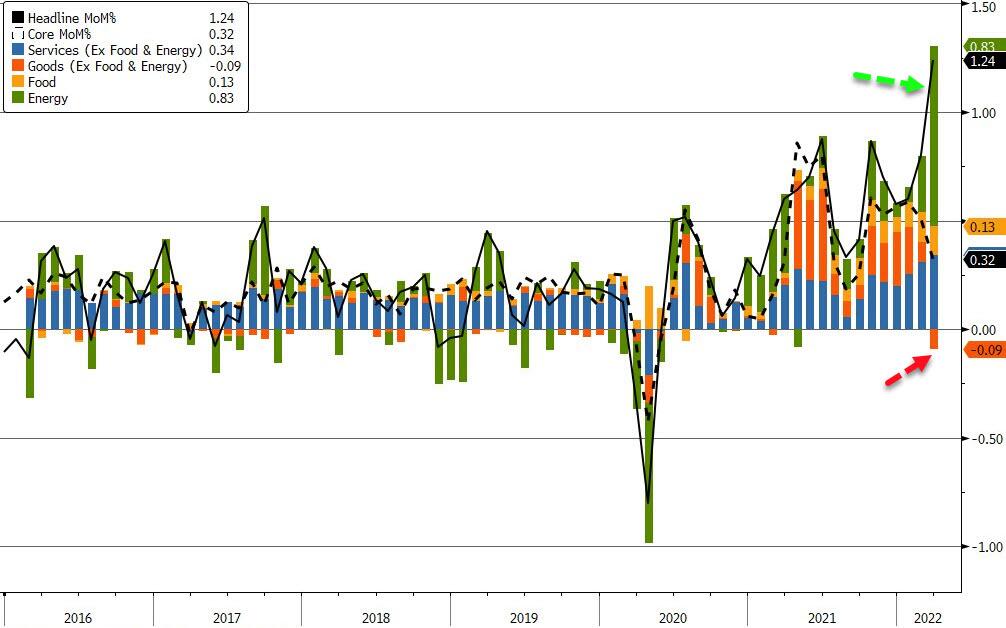
The 1.2% MoM rise is the biggest since Sept 2005 and CPI has risen for 22 straight months, but we note that goods inflation actually fell on a MoM basis (while energy soared)...
Source: Bloomberg
However, Core CPI (ex food and energy) rose just 0.3% MoM (below the +0.5% expected) and was up 6.5% YoY (above Feb's 6.4% but below the +6.6% exp).
The shelter index was by far the biggest factor in the increase, with a broad set of other indexes also contributing, including those for airline fares, household furnishings and operations, medical care, and motor vehicle insurance.
In contrast, the index for used cars and trucks fell 3.8 percent over the month.
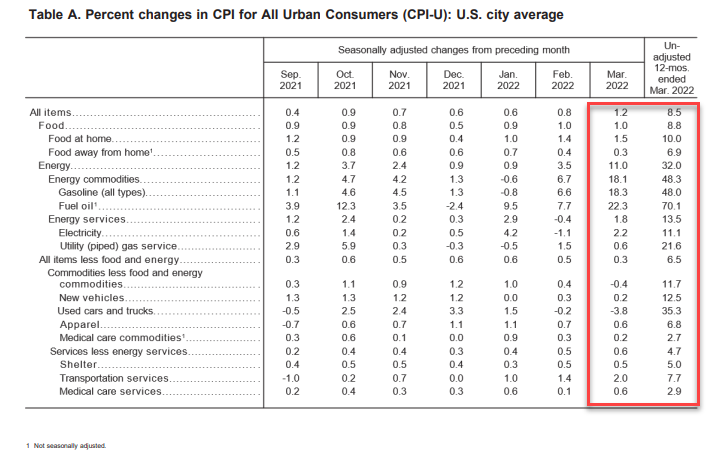
The rise in prices was dominated by Energy and goods on a year-over-year basis

Source: Bloomberg
The cost of putting a roof over your head (unless you're homeless in LA) continues to soar...
- March Shelter inflation 5.0% Y/Y, up from 4.7% in Feb, and the highest since May 1991
- March Rent inflation 4.44% Y/Y, up from 4.17% in Feb, and the highest since May 2007

Bear in mind that after this March report, inflation expectations start to step down, with second-quarter CPI seen at 7.6% and 5.7% by year-end, according to a Bloomberg survey. According to at least 6 Wall Street banks, this was the peak of the inflation wave.
And finally, and perhaps most importantly for the average American who actually has to pay for 'stuff' every day with his (or her or zher) own money, real average hourly earnings fell for the 12th straight month...

Source: Bloomberg
This confirms NBC News recent poll that showed 62% of Americans saying their incomes cannot keep up with the rising cost of living.
Still, the good news is, we all know who to blame for this right?
The bottom line: No inter-meeting or 75bps rate hike as the CPI data isn't as bad as it could have been.
If Crypto Can’t Be Used to Evade Russian Sanctions, What Is the Point?
Only small sums of money seem to have left Russia via digital currencies, which suggests their chances of ever replacing today’s government-run monetary system are low
If cryptocurrencies can’t have their moment in the sun when the entire Western monetary system is called into question, it may be time to call it quits.
As new sanctions hit Russia, the price of bitcoin keeps falling and is already 13% below where it was at the start of the year. Other digital currencies like ether and dogecoin have dropped in lockstep as stocks have stumbled, confirming once again that crypto gyrations mostly depend on broader speculative appetite.
But with U.S. lawmakers warning that cryptocurrencies could be used to bypass sanctions and many nations now aware of the perils of depending on currencies weaponized by Western governments, it is remarkable that prices aren’t reflecting the possibility of higher crypto adoption.
The likely explanation is that there isn’t much of any.
After Russia invaded Ukraine, ruble trading in bitcoin and tether hit 6.6 billion rubles on March 7, according to data firm Kaiko, compared with less than one billion before. But volumes quickly plummeted back to preinvasion levels due to U.S. card networks Visa and Mastercard suspending their Russian operations.
This suggests that crypto may have helped some people circumvent capital controls and shield their savings against a depreciating ruble, but that they were few and financially unsophisticated. Households would ideally use it to send the money to a foreign bank account, but most don’t have that ability. Crucially, the crypto market isn’t deep enough to absorb inflows of macroeconomic significance and, if it were, Moscow could ape China and force domestic banks to crack down on exchanges of rubles for crypto.
Whatever financial backdoor crypto offers, it doesn’t even seem to be big enough for expert sanction evaders.
For one, big, regulated exchanges like Binance must restrict accounts linked to sanctioned people. To be sure, there is still likely illegal activity in Russian crypto: There is evidence of new bank-deposit addresses being used on small exchanges tied to money laundering, according to Chainalysis, a firm that tracks illicit crypto transactions. But the sums liquidated are in the range of tens of millions of dollars, which is minuscule relative to the wealth of the hundreds of sanctioned individuals and entities.
Officials aren’t sitting idle either: Last week, the U.S. Treasury sanctioned Russia’s Garantex and Hydra for aiding cybercrime.
Analysts have long linked digital currencies’ value to the black market. This may be true when crypto stays within a circuit of companies with low “know your customer” controls in the niche digital economy—someone earning bitcoin from mining or ransomware can use it to buy virtual private networks or cloud hosting, for example—but the range of services on offer is small. Usually, crypto holders need to turn it into hard money by interacting with banks, and the traceability of blockchain technology becomes problematic. The idea that crypto anonymity can replace the traditional, meticulously built network of shell companies is wrong.
As Chainalysis’ director of research Kim Grauer puts it: “That’s just not how money laundering works.”
Of course, many crypto proponents prefer to dissociate it with crime and focus on how it has helped a war-torn Ukraine move money and receive $100 million in donations. Yet much of that activity is in tether, a digital currency pegged to the dollar.
The hard truth is that the only feature of cryptocurrencies that can’t be replicated by banks is the promise to sidestep government oversight. As far back as the 1905 writings of Georg Friedrich Knapp, economists have distinguished between the “chartalist” theory by which money is granted value by the power of the State and the “metalist” view that money only has true value if made up of a scarce commodity.
Crypto investors need the latter to be true, but the situation in Russia is piling up ever more evidence in favor of the former.
Ukraine War Drives Shortage in Pig Iron, Pushing Steel Prices Higher
Russia, Ukraine were top suppliers of pig iron used to make steel in the U.S.; steel companies look to Brazil, India
Pig-iron prices are surging, helping reverse a recent decline in the U.S. steel market.
Pig iron, a raw form of the metal used in the production of steel, has grown scarce in the weeks following Russia’s invasion of Ukraine, industry executives said. Two-thirds of the 6 million metric tons of pig iron imported by the U.S. last year came from those two countries, according to the U.S. Census Bureau, but the fighting brought Ukrainian shipments to a halt and importers have stopped ordering from Russia, steel executives said.
The crunch has steelmakers seeking out new suppliers in Brazil, India and elsewhere, in the midst of tightening U.S. supplies of scrap steel. Meanwhile, prices for pig iron have nearly doubled.
“There is really a concern about the availability of materials,” said Parth Jindal, director of JSW USA, a unit of India’s JSW Steel Ltd. 500228 -1.50% “The lack of pig iron and the lack of scrap in the U.S. has really pushed up prices.”
Pig iron—ore reduced to molten iron that is cast into briquettes—is mixed with scrap in electric furnaces and melted into new steel. About 70% of steel produced in the U.S. is made in electric furnaces, making the U.S. particularly reliant on scrap steel and pig iron. U.S. pig iron imports last year were 20% higher than in 2019.
Russia and Ukraine are the world’s largest sellers of pig iron, and in most years, the U.S. steel industry is the world’s biggest buyer. Since January, the price of pig iron in the U.S. has increased by 74% to $940 a metric ton, according to S&P Global Commodity Insights.
To offset more expensive pig iron, steelmakers said they are relying more on scrap steel from manufacturing waste, shredded cars and other debris. That demand has driven the price of high-quality scrap 51% higher since February, and set off a new round of price increases for finished steel, reversing months of declines. The spot-market price for the industry benchmark hot-rolled coiled sheet steel is up 48% since the beginning of March to $1,480 a ton, according to S&P Global price surveys.
“The rise in steel prices is related directly to the Russia and Ukraine war,” said Philipp Englin, chief executive of World Steel Dynamics, a market consulting firm in New Jersey.
Indiana-based steelmaker Steel Dynamics Inc. in late February was tracking what would be its last shipload of pig iron from Russia when the country invaded Ukraine. That shipment arrived March 3, but the company’s contract for additional shipments from Russia has been canceled because of the war, said Chief Executive Mark Millett.
Mr. Millett said that Steel Dynamics switched its pig iron purchases to Brazil, and the company has been able to reduce its overall usage of the commodity by improving its scrap-processing operations. By doing a more thorough job of removing copper, stainless steel and other metal that contaminates steel scrap, he said, Steel Dynamics can upgrade lower-quality scrap.
Pig iron accounts for about 10% to 20% of the raw material used to make steel in an electric furnace. Mr. Millett said that Steel Dynamics’ pig-iron usage has dropped to the lower end of that range by improving the processing of the company’s scrap.
“We have an adequate supply,” he said. “We have modified our operation to use a little less pig iron. ”
Most pig iron is produced in blast furnaces that are heated with coking coal, a type of processed coal that burns hotter and more efficiently than regular coal. Pig iron’s unusual name dates to the earliest days of steel mills, when liquid iron was poured into troughs and molds dug into the dirt floors of mills. The configurations resembled a sow with suckling piglets, and the name “pig iron” stuck.
JSW’s Mingo Junction, Ohio, mill gets its pig iron from its parent company in India. Mr. Jindal said JSW typically hasn’t sold pig iron outside of India, but the global shortages are changing that. The steelmaker’s operations in India can produce about 1 million metric tons a year of surplus pig iron for the export market, he said, and JSW recently sold a couple of shiploads of pig iron for United States Steel Corp.’s X -0.78% , Big River Steel mill in Arkansas.
Nucor Corp. , the largest steelmaker in the U.S. and a purchaser of 2.5 million metric tons of pig iron annually, said mills in China, Japan, the United Arab Emirates and Canada also have started offering pig iron.
“It’s more of a cost issue than an availability issue,” said Doug Jellison, Nucor’s executive vice president of raw materials.
American steel companies using blast furnaces typically use their molten iron to make finished steel, rather than sell pig iron to competitors. U.S. Steel recently said that it intends to devote one of the blast furnaces at its Gary, Ind., mill to produce pig iron for its Big River mill. U.S. Steel plans to double the annual steel production capacity at that mill to 6.3 million tons in 2024.
The mill’s expansion is part of the 10 million tons of additional production capacity for flat-rolled steel that is scheduled to enter service in the U.S. over the next two years. The build-out will likely keep prices for pig iron and scrap elevated for U.S. steelmakers, industry executives said.
“They need the material,” said Mark Kaplan, president of Consolidated Mill Supply Inc., an Illinois distributor of pig iron. “But companies either can’t afford it or they can’t find it.”