FT : External money managers now running $2.5tn of assets worldwide

External money managers now running $2.5tn of assets worldwide
Demand for expertise drives growth of investment outsourcing industry but conflict of interest concerns remain

The industry for outsourcing investment mandates is booming, offering large prizes for asset managers as challenging markets, a deluge of compliance and governance requirements and rising costs push big asset owners to seek their help.

The industry has more than doubled in size since 2016, growing to $2.46tn in assets under management worldwide.

The pace looks unlikely to let up with a flurry of recent chunky deals. In March BlackRock was appointed by insurer AIG to manage up to $150bn in fixed income and private assets. Last year, British Airways transferred £21.5bn in its two main pension schemes to the US manager. In April UK fund house Schroders announced a new £10bn mandate managing energy provider Centrica’s pension schemes.

New research from Chestnut Advisory Group estimates the industry will grow to more than $4tn in assets by 2026, as more flexible mandates open the industry to a wider range of clients than the smaller pension schemes who initially sought out external help managing their investments.

While the US has led the way in what are dubbed outsourced chief investment officer (OCIO) deals, accounting for more than two-thirds of assets, growth in Europe has also been notable.

“More than half of our growth over the past three years in Europe has been in the non-pension segments — so insurance, endowments, family offices, foundations,” said Jo Holden, global head of investment research at Mercer, one of the largest OCIO providers globally with $388bn in assets under delegated management. “We’ve had a phenomenally busy time in terms of tenders and new mandates coming in,” she added.

Outsourcing agreements vary in the level of control that is delegated and the amount of flexibility has increased significantly over time.

Some clients want the external investment manager to handle everything: asset allocation, selection of individual funds and managers and finally all risk management and back-office functions. Others want to maintain a veto over key decisions, or only outsource funds earmarked for a particular type of asset, as with the AIG-BlackRock deal, which involves fixed income and private placement assets.

In order to secure the Centrica mandate, as well as a partnership to manage funds on a new platform with insurance marketplace Lloyd’s of London, Schroders “worked with both of those organisations for a long time, establishing that we have a common culture, a common set of beliefs,” said James Barham, executive chair at Schroders Solutions, which has £234.5bn in assets managed under OCIO deals. “The trustees are not just passing over a very well recognised and regarded team of individuals, but also the assets of three schemes, and all of their employees. It’s not a decision which is taken lightly,” he said.

BlackRock had struck outsourcing deals with more than 120 institutional clients to manage more than $200bn at the end of last year. The world’s largest asset manager also provides similar “whole portfolio” services to wealth management clients covering another $230bn in assets. Last year this whole portfolio business grew 16 per cent, compared to a 7 per cent average for the industry, BlackRock said.

For the full service, BlackRock provides a wider range of hand-holding options, including helping top executives report to their boards of trustees on key issues and respond to questions.

“You’ve got to imagine you are down the hallway from the CEO or the president of the university and what might send them down the hallway. You have to serve that stakeholder,” said Ryan Marshall, BlackRock’s co-head of multi-asset strategies and solutions.

“Every pension fund has to support not only the front office [investment choices] but also technology and back office,” he added. “People want something that is bespoke to them with the advantages of scale that BlackRock can provide.”

OCIO deals initially took off among relatively small clients — usually pension schemes with $100mn to $1bn, if not even less — who were looking to cut costs and benefit from economies of scale and technology investments.

But much larger plans have shown interest in the last couple of years. So have mature pension schemes that are closed to new money and do not wish to hire people in-house to run them.

Interest has also spread from European defined benefit plans, who were early adopters, to the US and more recently Asia. Endowments, insurers and family offices are also picking up on the services.

Increased regulatory and compliance scrutiny, and especially the explosion of environment, social and governance investing in the past few years, has also pushed up demand.

“Sustainable investing is a very important driver especially in the UK and Europe because of the reporting requirements. Non-profit and endowments are [also] especially focused on this in the US,” said Greg Calnon, global head of multi-asset solutions at Goldman Sachs, which has $220bn under management in its OCIO business.

But while their popularity has exploded, there is scant evidence to demonstrate how outsourced investment mandates perform compared to their in-house peers.

OCIO fees are highly bespoke and rarely made public, and they come on top of fees paid to the managers of the actual investments.

That means potential conflicts of interest between the investor and the external manager can arise around investment allocation, and need to be managed.

“You need to have a governance structure in place to make sure that investments made in-house are being made for the right reasons,” said Rikhav Shah, director at consultancy EY.

Crucially, critics question the ability to make money from an outsourced CIO mandate unless the fund manager deliberately steers investment to its own funds.

“We looked at it and could not make it work,” said the chief executive of a very large asset manager. “My view is there is a direct conflict of interest. The firm will say ‘I’m going to charge you close to zero for OCIO service but by the way 50 per cent of the money is going to my funds.’”

Seth Bernstein, chief executive of $779bn asset manager AllianceBernstein, said: “It’s hard to do outsourced CIO well if you’re a proprietary shop because your preference will always be for your own funds, and clients will have issues with that.”

“For the OCIO provider, it’s a concept looking for commercial validation as it is hard to scale and retain quality service and performance,” he added. “For the OCIO user the returns are not compelling. The reason to do it is risk mitigation rather than returns, because you don’t have the time or resources to do it yourself.”

FT : Defence companies face supply snags as demand for US weapons rises

Defence companies face supply snags as demand for US weapons rises
American aerospace groups could struggle to scale up production in the wake of the Ukraine war

Northrop Grumman chief executive Kathy Warden delivered good news and bad news: the aerospace group expects more demand for its weapons systems, but supply chain issues could hinder efforts to expand production.

“Right now, it’s a question of how do we scale production to backfill stockpiles?” Warden said at the Economic Club of Washington, DC on Wednesday. She has also acknowledged labour shortages.

The largest US aerospace defence contractors are due for a windfall as western governments recalibrate their security strategies and increase defence spending following the Russian invasion of Ukraine.

The chief executives of Lockheed Martin, Raytheon Technologies, Boeing, Northrop Grumman and General Dynamics — prime contractors for the US Department of Defense — acknowledged in April earnings calls that they will profit from increased defence spending. Stock prices for Lockheed, Northrop Grumman and General Dynamics are up 12 to 15 per cent since the start of the war.


Contractors are now expected to ramp up production to meet demand from both the US and European governments, which have renewed commitments to defence spending due to the war.

But the companies have supply chain issues, labour constraints and inflationary pressures that could hold back efforts to scale up production.

Raytheon chief executive Greg Hayes told analysts that finding new, non-Russian sources of titanium has proved difficult, and that the Stinger will need an electronic redesign since “some of the components are no longer commercially available”.

Stingers and Javelins, both shoulder-fired missiles, have become the emblematic weapons of the Ukraine conflict as the country’s soldiers employ them to beat back Russian forces. US president Joe Biden travelled to a Lockheed plant in Alabama on Tuesday to tout the Javelin. The US has committed over 5,500 Javelins to Ukraine.

An estimated quarter of the US’s Stinger stockpile has gone to Ukraine, according to Mark Cancian, a former Pentagon official now at the Center for Strategic and International Studies, a think-tank.

But the Stinger is produced at negligible levels — there is only one active international customer and the US has not bought one for 18 years. Hayes said large orders are not expected until 2023 or 2024 as “we have a very limited stock of material for Stinger production”.

A similar timeline is expected for Javelin orders, added Hayes. It could take two years to get Javelin production up to its maximum of 6,000 per year, said Cancian. Raytheon and Lockheed produced 866 Javelins for $207.2mn for the US in 2021; the Pentagon wants 586 for $189.3mn in 2023.

Long-range systems will take over from medium-range Javelins in the current phase of the Ukraine war as it shifts to a “more conventional conflict in the east” of the country, said Greg Sanders, deputy director of CSIS’s Defense-Industrial Initiatives Group, meaning those weapons could top procurement lists.

“Globally, there’s an ongoing paradigm shift regarding national security, and several allies have pledged to increase defence spending as a result,” Warden told analysts during Northrop Grumman’s first-quarter earnings call. This “will enable us to accelerate our revenue growth rate in 2023”, she added. The contractor expects 2022 sales to range from $36.2bn to $36.6bn, compared to $35.7bn in 2021.

German chancellor Olaf Scholz upended his country’s decades-long defence policy by announcing a €100bn military fund and a commitment to take spending to 2 per cent of gross domestic product. Meanwhile, there is growing interest in Sweden and Finland for the countries to join Nato.

“The depressing reality is that the last 30 years of [relative peacetime] might just be an aberration,” said Richard Aboulafia, an aerospace consultant at AeroDynamic Advisory.

“[People thought:] ‘We won the cold war. Now, that’s the end of naked human aggression — excellent — let’s go start a unicorn petting zoo and everything will be fine.’ And it didn’t work.”


The defence companies have said it is too early to predict sales and revenue boosts. But Morningstar analyst Burkett Huey has updated his sales estimates across a range of products by 1.5 to 3 per cent in the latter years of his 2022 to 2026 forecast.

The Biden administration’s proposed $773bn 2023 defence budget is widely expected to increase further before final congressional approval, potentially by tens of billions of dollars, as the range of potential security threats widens and becomes more complex. As the largest military spender, the US made up 38 per cent of global defence spending in 2021, which topped $2tn for the first time, according to the Stockholm International Peace Research Institute.

While Russia is an acute threat, the Pentagon has made clear that the Indo-Pacific region remains its priority theatre. In its budget, the department “prioritised investments in foundational capabilities that address our challenges from both China and Russia”, under-secretary of defence Michael McCord recently told Congress, indicating the need for acquiring nimble systems that can carry out bifurcated strategies.

“We were heading for this pivot to Asia, which meant de-prioritising land systems and the benefit going to air and naval,” said Aboulafia. Now that the US is “being dragged over to Europe . . . it really becomes a struggle between land systems and naval systems for resources”. Air systems are the most flexible.

After the cold war, the defence industry began consolidating at a rapid rate: since the 1990s, 51 prime Pentagon defence contractors have shrunk to five highly diversified companies, meaning each of the Big Five will get large pieces of the pie.

In 2020, defence contracts accounted for 58 per cent of Pentagon spending, the highest level in 20 years, according to CSIS. Of the $421bn doled out that year, 36 per cent went to the Big Five contractors, up from 19 per cent in 1990.

European companies collectively produce a wide range of weaponry, but there is not enough industrial capacity to ramp up to the production level necessary to meet demand, industry experts said. This will send European governments to US companies. Some US-made weapons will also tailor better to certain governments’ needs.

Eastern European nations will be inclined to buy American not just for the technological aspects, but for the nominal connection to the US, because “with US companies embedded in their military forces, that just gives them a little better feeling”, said Cancian.

(ZH) Morgan Stanley: "We Live In The Most Chaotic, Hard-To-Predict Macroeconomic

Morgan Stanley: "We Live In The Most Chaotic, Hard-To-Predict Macroeconomic Times In Decades"

By Seth Carpenter, Global Chief Economist of Morgan Stanley
How Close To The Edge
Fears of a global recession abound, and in the past three months we have revised our global growth forecast down 170bp while inflationary pressures have risen.
We live in the most chaotic, hard-to-predict macroeconomic times in decades. The ingredients for a global recession are on the table. My colleague Mike Wilson is calling for a substantial further selloff in US equities, even in the base case of no recession. Consider that the recovery from Covid means companies that have over-earned – especially those producing consumer goods whose demand has soared – will face a reversal of fortune. What's more, higher rates and falling growth are never good for valuations. Avoiding a recession is our base case, but markets will have to confront the rising probability of one regardless.
China’s sharp slowdown is clear. Last year, the Chinese government embarked on a regulatory reset that caused a marked downshift in the economy. Then successive waves of Covid buffeted the country. The Covid-zero policy has throttled household spending and has not left the productive side of the economy unscathed. Critically large cities like Shanghai and Shenzhen have been locked down, and cases in other major cities have been rising. The risk of an extended contraction is plain to see.
For Europe, the slowdown is more prospective because recent PMIs and confidence surveys suggest continued momentum. But since Russia’s invasion of Ukraine started, downside macroeconomic risks have risen. The sharp spike in energy and food prices will impose a tax on the European consumer. And as the Russian invasion of Ukraine continues, the prospect of an embargo on oil imports from Russia is becoming more certain. The second half of the year looks decidedly worse for euro area growth than the first half. Accompanying these headwinds, high inflation has spurred the ECB to normalize policy. While ending QE and bringing the depo rate to zero are highly unlikely to pitch Europe into recession, markets are forward looking, and the selloff in euro area sovereigns is likely just the start of tightening financial conditions.
In the US, GDP contracted in 1Q. To be sure, domestic final spending was solid, and the culprits were inventories and exports. Weak exports, however, warn of softening global growth. Nonfarm payrolls for April rose by 428k, extending a string of very strong job gains. But just as in Europe, we have yet to see the hit to consumer spending from the surge in food and energy prices, and our recent work shows that the drag can be noticeable (see Slower Growth Ahead). Moreover, mortgage rates have gone above 5% for the first time in 12 years, and with a shortage of new homes driving prices higher and higher, home affordability is the worst in decades. And of course, the Fed has signaled a fairly aggressive set of rate hikes that we see taking the federal funds rate past 2.5% this year as the balance sheet starts to shrink. The direction of travel for the US economy is clear, though for now it remains strong.
So why not call for a global recession? For now, even if Chinese GDP sees a modest sequential contraction in 2Q, mounting fiscal policy and receding Covid should allow for a subsequent rebound. A European embargo on Russian oil is likely to be manageable, while for a recession, we would need a scenario where all energy imports from Russia including natural gas are cut off abruptly. And the Fed is feeling its way with policy, trying to slow the economy to rein in inflation but willing to reverse course at the first sign of doing too much. We would need a European contraction to hit the US economy after enough front-loaded policy tightening is in train to trigger a recession. The alignment of those unlucky stars is possible, hence the rising risk, but it is not something I would count on.

(ZH) Hedge Funds Are Flooding Into Energy Stocks At The Fastest Pace In Years

Hedge Funds Are Flooding Into Energy Stocks At The Fastest Pace In Years

It didn't take long for hedge funds to completely reverse their aversion towards energy.
Recall back in the middle of March, when not long after oil briefly soared to the highest level in 14 years, hedge funds just couldn't sell oil fast enough - contrary to traders of physical oil who were buying up every last drop, be it real or synthetic - they could find. It's also one of the primary reasons why despite dismal fundamentals which scream oil in the mid to upper-$100 range, the black gold would get slammed down every time it tried to make a break for it.
So fast forward to today, when oil is now well back over the price hit when Biden announced his SPR release, and energy stocks - in the words of Goldman's head of hedge fund sales Tony Pasquariello - remain the only place to hide from the market's vicious selloff. A big reason for that is that hedge funds have finally capitulated on dumping and shorting energy, and have turned full-bore oil bulls.
According to the latest weekly report by Goldman's Prime Brokerage group (full note available to professional subscribers), amid rising crude oil prices, Energy was the only US sector that saw positive price returns this week, outperforming the S&P 500 index by +7.7% (largest spread in 8 weeks). More importantly, it was also among the most $ net bought US sectors on the GS Prime book.
Remarkably, hedge funds bought US Energy stocks at the fastest pace since Mar ’20 amid continued sector outperformance.
According to GS Prime, "this week’s net buying in US Energy was the largest since Mar 2020 (1-Yr Z score +1.8), driven by long buys outpacing short sales nearly 4 to 1; Integrated Oil & Gas, E&P, and Oil & Gas Equip & Services were among the most net bought subindustries, while Storage & Transportation and Oil & Gas Drilling were among the most net sold."
Some more details on the recent buying flurry: hedge funds were net buyers of US Energy stocks in 4 of the past 5 weeks, driven by long buys outpacing short sales 3 to 1. More notably, the uptick in $ gross trading flow in US Energy over the past month was the largest over any 4-week period since Mar ’20.
Still, before we get calls of "hedge funds are rotating in so dump it all", here is some context: energy now makes up a paltry 4.4% of overall US Net exposure (vs. an even paltrier 2.1% at the start of 2022), and while this is the highest level since Aug ’19, it is just in the 37th %ile vs. the past five/ten years.
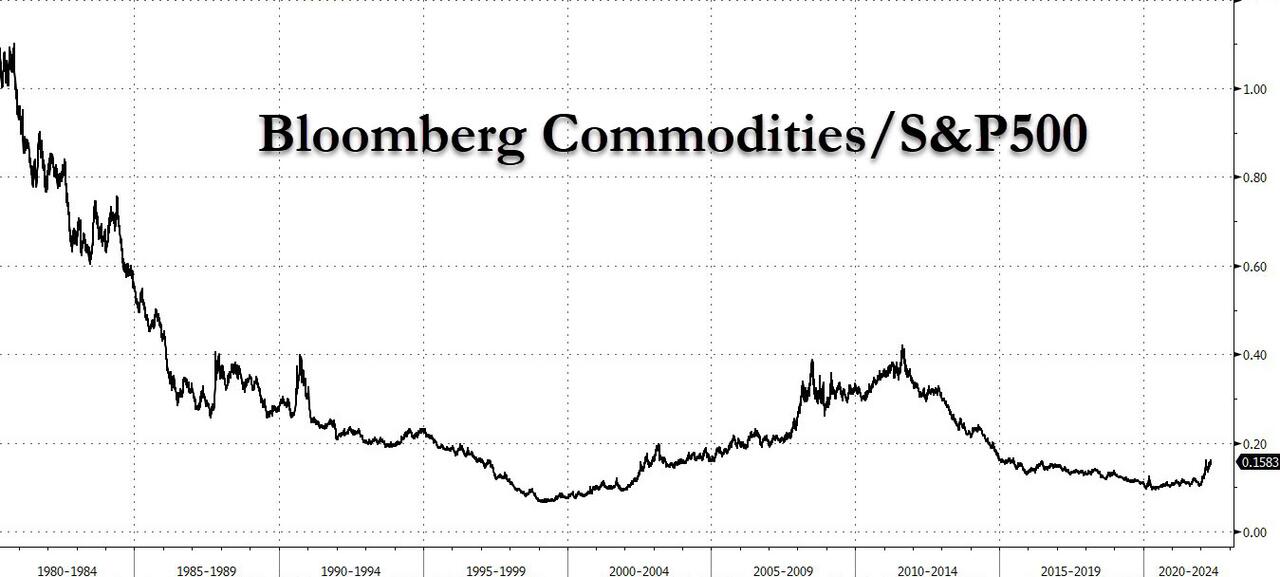
How much more can the rotation into energy be in the coming weeks and months? Well, if we are about to experience a reversion to the mean, it could be a lot because while the Bloomberg commodity spot index is clearly trading at all time highs...
... when put in the context of equities, well... see for yourselves:

Business Of Fashion : Can Meta Make Wearable Technology Happen?

Can Meta Make Wearable Technology Happen?
This week, everyone will be talking about Meta’s new store and its Ray-Ban smart glasses, plus the selloff in tech stocks that has hurt the prospects of fashion’s unicorns.

Very Meta
  • Facebook parent Meta is opening its first physical store near San Francisco on May 9
  • The store will feature Meta products, including wearables such as AR glasses
  • Last week, Mark Zuckerberg met with executives from Italian fashion brands, including Salvatore Ferragamo and Moncler

Wearable technology that consumers find both useful and fashionable has frustrated even the biggest technology and fashion companies. The market is littered with failed attempts at true augmented reality via spectacles or headsets. The most notable success, the Apple Watch, is a hit. But the ability to transfer some iPhone capabilities to users’ wrists is hardly the virtual utopia fashion futurists dream of.

Some of Silicon Valley’s biggest players are giving it another go, though. Last week Snap demoed augmented reality shopping tools, including a realistic virtual try-on service, exactly the sort of consumer-friendly application that could convince some to take the leap into wearing the company’s Spectacles. And Meta’s Ray-Ban smart glasses appear to be one of the flagship products at the company’s first store, which opens Monday. The glasses, which allow the wearer to take photos, shoot videos, stream music and send texts, have been on the market since September. They remain a niche product, but Meta clearly has big ambitions in the category. Last week, Mark Zuckerberg was spotted in Italy meeting with fashion executives, including the CEO of Ray-Ban owner EssilorLuxottica, but also the leadership of a slew of big luxury brands. Zuckerberg teased a new wearable product, which he described as a “neural interface EMG wristband that will eventually let you control your glasses and other devices.”

The Bottom Line: Snap and Meta have avoided the biggest misstep of past generations of wearables by creating products that, to the casual observer, look like appealing analog products already on the market. Now, they must roll out features that are fun and useful enough to convince consumers that they need to wear a camera on their head in addition to a smartphone on their wrist.

BReakingViews : Big Tech valuations are re-entering the real world

Big Tech valuations are re-entering the real world

Punching virtual timecards

U.S. stock markets sold off sharply on Thursday. Meanwhile, looking past day-to-day volatility, technology company valuations are re-entering the real world. Tech sector price-to-earnings multiples for names like Amazon.com and Apple are converging with industrial companies like Caterpillar and United Parcel Service. That makes sense: Minus recent euphoria, they’re just tools for everyone else’s business.

A basket of nine tech giants, also including Nvidia, Baidu,and Facebook parent Meta Platforms, boasts an average price-to-earnings ratio of around 27 times. That’s still noticeably higher than the average of nine industrial companies, including General Electric, Honeywell International, and Siemens, of around 17 times. But that spread has come down considerably. Five years ago, the ratios were 42 and 19 times respectively.

Before investors started losing their optimism, the Silicon Valley giants and their peers could do little wrong. The companies transformed how people buy things, store data, and entertain themselves, and they were rewarded for their fast-growing, scalable businesses. But above-market growth, boosted by stay-at-home Covid-19 habits, can’t last forever.

Last month, Netflix architect Reed Hastings blamed competition, in part, for slowing subscriber growth. Amazon finance chief Brian Olsavsky said that the cost to ship goods overseas doubled compared to pre-pandemic rates. Microsoft and Google owner Alphabet are hiring rapidly in a fiercely competitive environment for employees. Tech-sector companies in the S&P 500 Index have so far reported revenue growth of 13% in this year’s first quarter from a year earlier, while industrial firms’ top lines are up 40%, according to Refinitiv data.

That sounds an awful lot like the issues hitting companies that have been around for ages. Illinois-based Caterpillar boss James Umpleby said that margins are under pressure as a result of inflationary impacts on manufacturing costs. Supply chain challenges are a drag on Minnesota-based 3M’s businesses, just as on Apple’s. UPS is dealing with labor cost increases.

The technology powerhouses may achieve faster growth than old-line groups. But as they mature their services are no longer new and disruptive. The endgame is that they become part of the portfolio of businesses that support an economy, and the pace of their growth aligns with that. Investors are more likely to see that in their crystal balls when they’ve been brought down to earth.

BReakingViews : Stars align for UAE to become a global crypto hub

Cryptic puzzle

Dubai and Abu Dhabi are making a play for the cryptocurrency crown. Big crypto exchanges like FTX, last valued at $32 billion, are setting up shop in Dubai. There are a number of reasons why it might be to their taste.

Crypto is growing fast: total transactions volumes grew over 500% to $15.8 trillion in 2021, according to Chainalysis. Yet plenty of Western regulators seem to hate it. European Central Bank board member Fabio Panetta and the U.S. Securities and Exchange Commission’s boss Gary Gensler have both compared the asset class to the “Wild West”. Perhaps as a result, even the two largest cryptocurrencies, bitcoin and ether, are yet to have a dedicated supervisory body in the United States and the UK. Singapore has imposed stricter regulation, despite expressing interest in the market.

That leaves a gap for an ambitious locale willing to build its regulatory architecture around crypto, rather than vice versa. Step forward Dubai and Abu Dhabi. In the last few months, the pair have handed out more than 30 licences and passed new laws for crypto exchanges to operate in the cities. The exchanges have responded. Binance is recruiting for over 100 positions in the Gulf, while boss Changpeng Zhao has moved from Singapore to Dubai and bought a home there. FTX and Kraken are heading Gulf-wards, too.

The mutual love-in has a certain logic. Total private wealth held in the United Arab Emirates rose by $46 billion between 2019 and 2021 as some 5,600 millionaires moved to the country, according to the Global Citizens Report, and an influx of Russian oligarchs should amplify the trend. Around 25% of Middle East millionaires already invest in some kind of crypto, data from consultant Knight Frank shows. Meanwhile, local businesses like grocery delivery service YallaMarket and property firms are accepting payments in crypto, and the former has floated the idea of paying salaries in the currency. A global YouGov survey found that trust in cryptocurrencies was highest among adults in the UAE.

A Gulf crypto hub also carries obvious risks. The Financial Action Task Force recently said the UAE wasn’t doing enough to counter money-laundering risks, and crypto’s popularity with criminal elements raises the risk that a crypto-fuelled scandal could dilute the UAE’s good name instead of enhance it. On the other hand, if these elements can be managed and regulated then it could equally give the region what it could really use: a leading position in a major financial growth sector.

NY Times : Seizing an Oligarch’s Assets Is One Thing. Giving Them to Ukraine Is

Seizing an Oligarch’s Assets Is One Thing. Giving Them to Ukraine Is Another.
It could take years for Russian assets seized by the United States to be permanently confiscated and sold to benefit the Ukrainian people. The Biden administration wants to speed up the process.

The U.S. government was so pleased with its swift seizure of a Russian oligarch’s 255-foot yacht on the Mediterranean island of Majorca last month that it posted a video on YouTube of the moment F.B.I. agents and Spanish authorities clambered up the gangplank. The $90 million yacht owned by Viktor Vekselberg, called the Tango, was the government’s first big prize in a campaign against billionaires with close ties to the Kremlin.

The Tango is just a sliver of the $1 billion in yachts, planes and artwork — not to mention hundreds of millions in cash — that the United States has identified as belonging to wealthy allies of Russia’s president, Vladimir V. Putin, since the invasion of Ukraine. U.S. Magistrate Judge Zia M. Faruqui, who approved the seizure, called the pursuit of the yacht by a new Justice Department team called task force kleptocapture “just the beginning of the reckoning that awaits those who would facilitate Putin’s atrocities.”

The reckoning may take a while.

Seizing assets, whether a yacht or a bank account, is the easy part. To permanently confiscate them, the government must usually navigate a potentially cumbersome process known as civil forfeiture, which requires proving to a judge that the assets were obtained from the proceeds of a crime or through money laundering. Only then does the government actually own the assets, and have the power to liquidate them.

All that can take years, especially if the former owner is inclined to fight the forfeiture action in court.

Hoping to speed things up — and quickly get the proceeds from seized assets turned over to the Ukrainian government — the White House announced a plan last week that would make it easier for U.S. authorities to go after some oligarch assets through an administrative procedure led by the Treasury Department. Although it has not provided details of its plan, administration officials said the new procedure will provide adequate due process and allow for an “expedited” review by a federal court.

The White House proposal would significantly change the way the government handles high-dollar asset seizures. Generally, administrative forfeiture is used in lower-profile cases, intended for assets worth $500,000 or less. Such efforts are not really designed for luxury homes or massive yachts, let alone the huge sums of money that wealthy Russians are believed to have stashed away in U.S. bank accounts or invested with hedge funds and private equity firms.

“The idea of a yacht or jet valued in the hundreds of millions seized and liquidated administratively is new territory,” said Franklin Monsour Jr., a former federal prosecutor and a white collar defense lawyer with Orrick in New York.

Mr. Monsour said the administration and Congress may be banking that many Russian oligarchs will not muster a legal challenge to a new, expedited process because that would risk subjecting themselves to U.S. jurisdiction.

“It will likely be without challenge,” he said. “And the government knows that.”

Even if prosecutors are forced to proceed in some cases through the more typical civil forfeiture process, the litigation might go faster than normal for that same reason, Mr. Monsour said.

There are indications the pace of seizures is picking up. On Thursday, prosecutors said that authorities in Fiji working with the task force seized a $300 million mega yacht belonging to Suleiman Kerimov, a Russian gold magnate. But in a sign the task force may be unwilling in some cases to expose its tradecraft in tracking down assets, the 24-page affidavit presented to a federal judge in support of the seizure was heavily redacted.

The more pricey assets the government seizes, the more reason it has to speed up the forfeiture process: Luxury property must be properly maintained, otherwise their value will drop before they can be sold off to someone else in the small pool of people who can afford them.

“For yachts that are languishing in ports, there will be assets spent to maintain the vehicles,” said Daniel Tannebaum, an expert on financial crimes at the consulting firm Oliver Wyman and former Treasury official. “Some of these assets can sit for an extremely long time.”

But authorities in the U.S. are looking to do more than just strip oligarchs of their prized possessions. Elizabeth Rosenberg, assistant secretary for terrorist financing and financial crimes at Treasury, said one goal is to “undermine the financial architecture that Russia uses to move money.”

Over the years, Russia and its oligarchs have become skilled at using a parade of shell companies in places like the British Virgin Islands to move money from Cyprus to the Cayman Islands to Jersey, in the Channel Islands, all places with a history of being seen by investors as tax havens. The task force will be looking for evidence of oligarchs taking steps to illegally evade sanctions by surreptitiously transferring money and property to an unsanctioned person or business entity.

Just last month, federal prosecutors in Manhattan filed criminal charges against Konstantin Malofeyev for illegally transferring $10 million from a U.S. bank to a business associate in Greece. Mr. Malofeyev, who recently described Russia’s invasion of Ukraine as a “holy war,” was the subject of a sanctions order by the Treasury Department in 2014 after Russia’s invasion of Crimea, a part of Ukraine that it ultimately annexed.

In October, federal agents raided a mansion belonging to Russian billionaire Oleg Deripaska in Washington and seized a wide array of assets including a Diego Rivera painting. Authorities took action in response to suspicions that Mr. Deripaska had been trying to evade sanctions by moving some of his money around, Bloomberg reported last month.

U.S. authorities have pursued assets belonging to Mr. Deripaska, an industrialist with close ties to Mr. Putin, since a sanction order in 2018 that was partly in response to Russia’s meddling in the 2016 presidential election. A year later, Mr. Deripaska sued the U.S. government, claiming that the sanctions designation was based on rumor and had rendered him “radioactive” in the business community. Six weeks ago, a federal appellate court rejected his claims.

Since Russian forces invaded Ukraine in February, the Treasury Department has imposed sanctions on more than 530 well-connected Russians. Andrew Adams, the federal prosecutor directing the new kleptocapture task force, said much of his team’s early work has involved “unprecedented” sharing of information about those individuals with U.S. financial firms, Treasury officials and overseas law enforcement groups.

Even without taking possession of an asset, the task force can make it difficult for the owner to make use of it, said Mr. Adams, a veteran federal prosecutor in Manhattan who has focused on money laundering and asset forfeiture cases.

“In the past, I would consider a win to be getting a conviction,” Mr. Adams said. “Now it could be getting an insurance company to cancel policy coverage for an oligarch’s yacht.”

Although it’s possible for the government to seize assets as part of a criminal case, Mr. Adams said, the government was unlikely to take that route. Doing so would require the arrest and conviction of their owners — an even more daunting process than the civil process or the expedited administrative procedure that the White House is considering.

But even the civil forfeiture process requires the government to show evidence of criminal conduct.

In approving the seizure of the Tango, Judge Faruqui said federal authorities had shown probable cause that Mr. Vekselberg had purchased the yacht — held through a series of shell companies — with “illicit proceeds and laundered funds.” Permanent confiscation will require prosecutors to establish that Mr. Vekselberg actually committed bank fraud, money laundering or some other crime.

Although the United States imposed sanctions on wealthy Russians soon after the invasion, global efforts to seize their assets have mostly played out in Europe and the Caribbean.

The European Union has frozen about $30 billion assets traced to Russian oligarchs since February. A few weeks ago, British officials said they had frozen some $13 billion in assets tied to just one of them: Roman Abramovich. Mr. Abramovich, one of Russia’s wealthiest men and the longtime owner of London’s Chelsea Football Club, has faced significant pressure from British officials. He agreed to part with the team in March as officials were moving to impose sanctions, and the club said on Friday that it had accepted a $3 billion bid from a consortium of buyers. The proceeds from the sale — the highest price in history for a sports team — will be placed in a frozen British bank account.

Mr. Abramovich, who has invested billions of dollars with offshore funds managed by U.S. firms and has an interest in several steel mills in the United States, has not been sanctioned by American officials, in part because he has served as an intermediary in negotiations between Ukraine and Russia. Mr. Adams, the leader of the kleptocapture task force, declined to discuss the matter.

But he did offer an explanation for why the Russian oligarchs his team is focused on seem to have fewer assets in the United States than in other countries: The sanctions that Treasury imposed following Russia’s invasion of Crimea seven years ago scared some away.

“We have had sanctions in place since 2014,” said Mr. Adams. “We have not been a friendly country to park your money in.”

NY Times : Inside Elon Musk’s Big Plans for Twitter

Inside Elon Musk’s Big Plans for Twitter
Here’s what Mr. Musk is projecting for Twitter’s finances over the next few years, according to a pitch deck he presented to investors.

Elon Musk has in recent days distributed a pitch deck to investors outlining his grand plans for Twitter.Credit...Joe Skipper/Reuters

<button>
  • May 6, 2022

Elon Musk has never been accused of dreaming small. He has reinvented at least two industries with Tesla, his electronic vehicle company, and SpaceX, the rocket company — and now his ambitions are carrying over to his $44 billion acquisition of Twitter.
Mr. Musk, the world’s richest man, has presented a pitch deck to investors in recent days outlining his grand — some might say incredible — plans for Twitter and its financial targets. The New York Times obtained the presentation. Here’s a peek into what Mr. Musk sees for the social media service in the years ahead.
Quintuple revenue to $26.4 billion by 2028.
In his pitch deck, Mr. Musk claimed he would increase Twitter’s annual revenue to $26.4 billion by 2028, up from $5 billion last year.
Cut Twitter’s reliance on advertising to less than 50 percent of revenue.
Under Mr. Musk, advertising would fall to 45 percent of total revenue, down from around 90 percent in 2020. In 2028, advertising would generate $12 billion in revenue and subscriptions nearly $10 billion, according to the document. Other revenue would come from businesses such as data licensing.

Produce $15 million in revenue from a payments business.
Twitter would bring in $15 million from a payments business in 2023, according to the document, which would grow to about $1.3 billion by 2028. The company’s payments business today, which includes tipping and shopping, is negligible. There has been speculation that Mr. Musk may introduce payment abilities to Twitter given that he helped popularize PayPal, the digital payments service.
From Opinion: Elon Musk’s Twitter
Commentary by Times Opinion writers and columnists on the billionaire's $44 billion deal to buy Twitter.
Increase average revenue per user by $5.39.
With all of these changes, Mr. Musk anticipates he can lift Twitter’s average revenue per user — a key metric for social media companies — to $30.22 in 2028 from $24.83 last year, according to the document.
Reach 931 million users by 2028.
Mr. Musk anticipates Twitter’s total number of users will grow from 217 million at the end of last year to nearly 600 million in 2025 and 931 million six years from now. Most of that growth will come from Twitter’s ad-supported business, including Twitter Blue, for which users pay $3 a month to customize their experience on the app. According to the pitch deck, Mr. Musk expects 69 million users of Twitter Blue by 2025 and 159 million in 2028.
Have 104 million subscribers for a mysterious X by 2028.
Included in Mr. Musk’s total user estimates are what appear to be subscribers to a new product called X, which would have 104 million users in 2028, according to the document. The document did not detail what X Subscribers was, but Mr. Musk has hinted at introducing an ad-free experience on Twitter. The X Subscribers product shows up on the pitch deck in 2023, with nine million users expected in its first year.
Hire 3,600 employees — after shedding hundreds.
By 2025, Mr. Musk anticipates Twitter will have 11,072 employees, according to the document. That would be up from around 7,500 today.

But in between, Mr. Musk expects the number to fluctuate, rising to 9,225 employees in 2022, then declining to 8,332 in 2023 before increasing again. Mr. Musk is likely to shed workers as part of his takeover, before bringing on new talent in engineering, a person with knowledge of the situation said. Stock-based compensation costs are also expected to rise to just over $3 billion by 2028, from $914 million in 2022.
Raise free cash flow to $9.4 billion.
Twitter will add about $13 billion of debt as part of Mr. Musk’s buyout plan. But he expects to pay that debt down as free cash flow — a measure of how much money a company has to service its debt — is set to grow to $3.2 billion in 2025 and $9.4 billion in 2028, according to the pitch deck. Free cash flow would rise even as operating expenses and costs also rose, according to the document.

>>> The Dangerous American Game of Helping Kill Russian Generals

The Dangerous American Game of Helping Kill Russian Generals
The U.S. establishment need to ask themselves just one question: If the position were reversed, how would the United States react to a third country deliberately helping to kill U.S. commanders?

A New York Times report that the United States has been providing real time intelligence to the Ukrainian army with the specific purpose of killing Russian generals brings America a long step closer to actual war with Russia.

This also means a risk of nuclear war that is now greater than it has ever been, even perhaps during the Cuban Missile Crisis. The Biden administration and the U.S. establishment need to ask themselves just one question: If the position were reversed, how would the United States react to a third country deliberately helping to kill U.S. commanders?

If Russia were winning in Ukraine, the Kremlin might be able to ignore this kind of U.S. help to Ukraine. But the Russian invasion of northern Ukraine was defeated and abandoned, and Russian forces are now making only glacial progress in eastern Ukraine. Reportedly, Russian casualties have been enormous, due in large part to NATO weaponry provided to Ukraine. These casualties have included 12 generals killed — as it now appears with direct American help.

The Times story contains the following passage:

“Some European officials believe, despite Mr. Putin’s rhetoric that Russia is battling NATO and the West, he has so far been deterred from starting a wider war. American officials are less certain, and have been debating for weeks why Mr. Putin has not done more to escalate the conflict.”

As this indicates, there are in fact many ways that Russia can abandon its restraint so far and retaliate for the killing of its generals: cyber attacks on key Western infrastructure (widely predicted, but so far non-existent); the targeting with missiles and drones of U.S. offices and personnel in Kiev; the assassination of U.S. diplomats, military personnel, and intelligence officers in other countries; and warning shots aimed at NATO supply lines in Poland.

Any of these actions would create a fierce reaction in the United States, and no-doubt renewed calls for a no-fly zone, enforced by fighters flown out of NATO bases in Poland. These bases would then be subject to missile attack by Russia, even as U.S. planes over Ukraine were being shot down by missiles based in Russia itself. Russia would also very likely declare its own no-fly zone over much of the Baltic Sea. Two things would then probably happen: the United States and the West would lurch towards mutual nuclear annihilation; and seeing this, France, Germany, and other NATO members would break ranks with Washington and seek a peace agreement.

To ward off this threat, the Biden administration must move immediately to assure Russia that U.S. strategy is to help defend Ukraine, but not to impose a complete defeat on Russia and use this to weaken or destroy the Russian state.

The first step should be for Washington to declare publicly that it supports a diplomatic solution to the issues of the status of Crimea and the Donbas, and that if Russia will cease its offensive in Ukraine and agree to a ceasefire, the United States will respect that ceasefire. This should not of course imply U.S. recognition of Russian claims to these territories. It would simply involve the Biden administration giving its public support to the previous statement by the Ukrainian government that it is willing in principle to “compartmentalize” the territorial issues and leave them for future negotiation.

Such a move by the Biden administration would be met with the usual parrot-hawk cries of “appeasement.” But these critics need to ask themselves the following: Were Eisenhower, Kennedy, Nixon, Reagan, and other U.S. Cold War presidents “appeasers”? The suggestion is absurd. Yet all of these men, while acting with great firmness against Soviet aggression and expansionism, took great care to shape the U.S. response to minimize the risk of nuclear war. They did so not because of any sympathy or weakness towards the Soviet Union, but because they had sworn an oath to preserve and defend the United States.

UPDATE, 5/5, 5 p.m. EST: The Pentagon has denied the report that the U.S. is providing info to Ukraine to help kill Russian generals. During Thursday’s briefing, DoD spokesman John Kirby said the following:

“We do not provide intelligence on the location of senior military leaders on the battlefield or participate in the targeting decisions of the Ukrainian military…

“Ukraine combines information that we and other partners provide with the intelligence that they themselves are gathering, and then they make their own decisions and they take their own actions.”

When asked if the NYT report was inaccurate, he declined to comment, saying, “I am not going to talk about intelligence sharing from this podium.”

© 2021 Responsible Statecraft

ANATOL LIEVEN

Anatol Lieven is a Professor at Georgetown University School of Foreign Service, Qatar, visiting professor in the War Studies Department of King’s College London, and a senior fellow of the New America Foundation in Washington DC. He is the author of ­
Pakistan: A Hard Country.
 Anatol spent the first part of his career as a journalist in Afghanistan, Pakistan and the former USSR.