>>> These Are The Most-Downloaded Apps So Far In 2022

These Are The Most-Downloaded Apps So Far In 2022

Whether they’re providing a service like ride-sharing or acting as a mere source of entertainment, mobile apps have become an integral part of many peoples’ day-to-day lives.
But which apps are most popular among users?
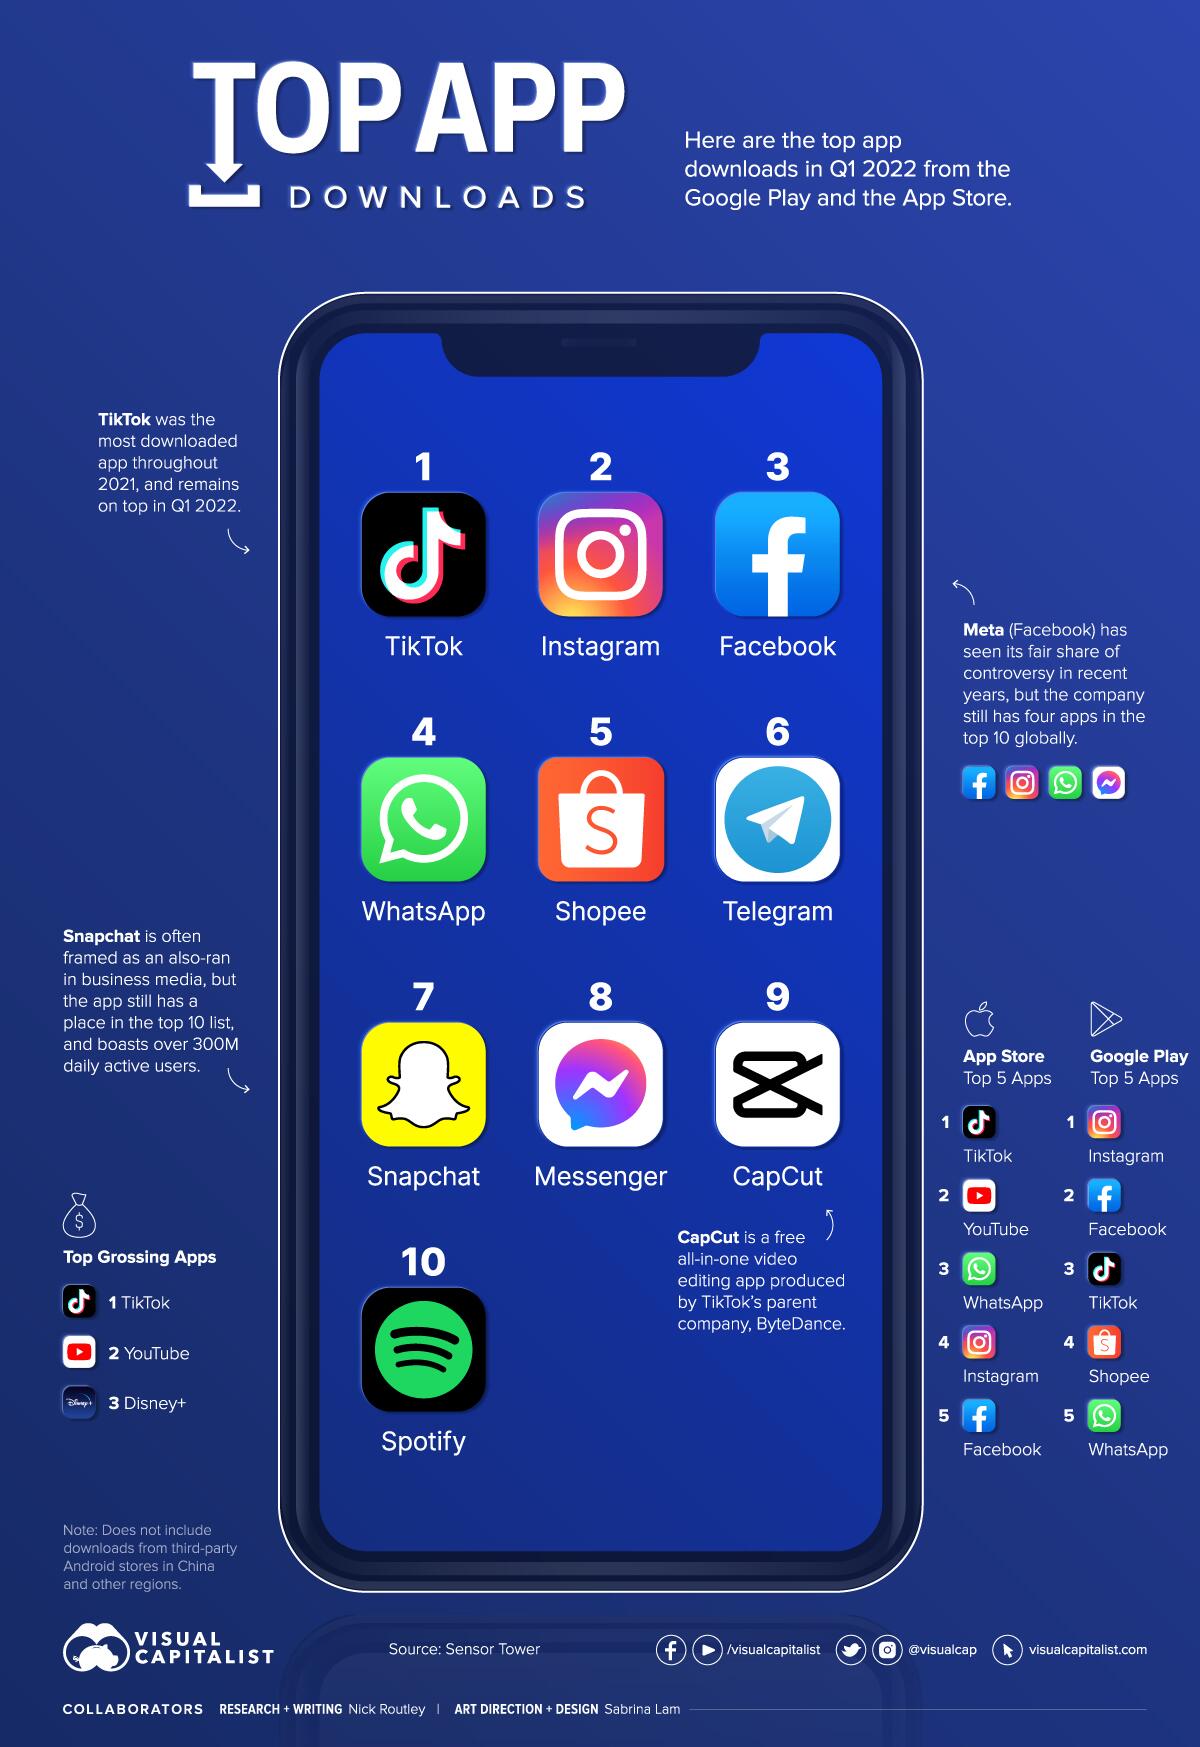
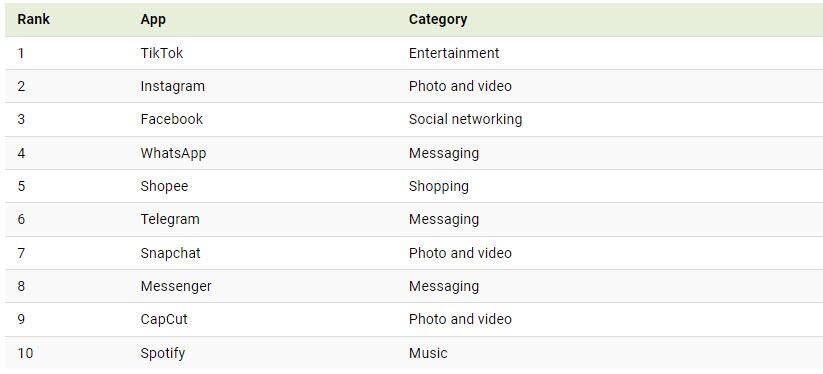
In the graphic below, Visual Capitalist's Carmen Ang uses data from a recent report by Sensor Tower to show the top 10 most downloaded apps around the world in Q1 2022 from the Google Play and Apple App Store.
Social Reigns Supreme
According to the report, total app downloads reached 36.9 billion in Q1 2022, a 1.4% increase compared to Q1 2021.
A majority of the top 10 most downloaded apps were social media platforms, with Meta and ByteDance owning six of the top 10.

Meta’s four platforms on the list are Instagram, Facebook, WhatsApp, and Messenger, while ByteDance owns TikTok and video-editing platform CapCut.

Just outside the top 10 are Zoom and WhatsApp Business (yet another Meta-owned app).
TikTok’s Winding Road to the Top
In Q1 2021, TikTok exceeded 3.5 billion all-time downloads, becoming the fifth app (and the first non-Meta app) to reach this milestone. This is impressive considering the app has been banned in India as of June 2020. Prior to the ban, India accounted for 30% of TikTok’s downloads.
India’s not the only country that’s banned the use of TikTok. Pakistan has blocked TikTok multiple times because of concerns over “inappropriate” content. However, it’s worth noting that the bans in Pakistan only lasted a few days before being lifted, and currently, Pakistanis are able to access the platform.
Top 10 Highest Grossing Apps
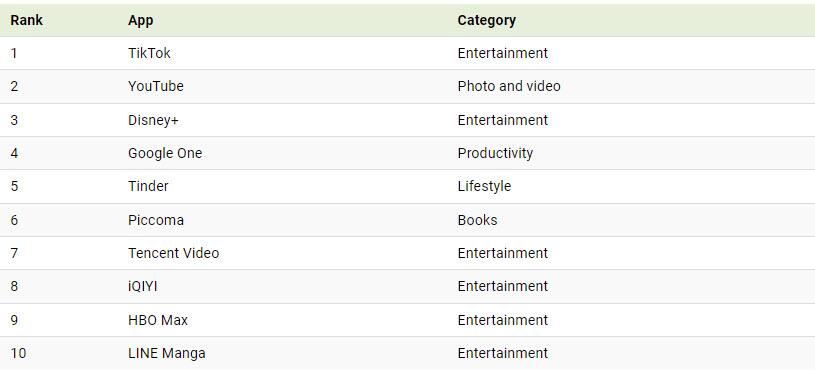
TikTok isn’t just the most downloaded app in the world—it’s also the highest-grossing non-game app, based on Q1 2022 revenue from the App Store and Google Play:

TikTok generated an impressive $821 million in consumer spending in the last quarter. The video-sharing platform was the top-grossing app on the App Store, and the second-highest-grossing on Google Play, coming just after Google One.

While none of Meta’s platforms made it onto the top 10 list for gross revenue, these platforms make a ton of money that doesn’t necessarily flow through app stores. In 2021, Meta generated more than $117.9 billion in revenue, with over 97% of that coming from ads.

Growth’s on the Horizon
The pandemic had a massive impact on the app market.
In 2020, app spending on things like premium access, in-app purchases, and subscriptions surged by 30% year-over-year to reach $111 billion.
And while COVID-19 restrictions are easing in most places around the world, app spending isn’t likely to taper off anytime soon. By 2025, spending is expected to grow to $270 billion.

WWD : Gucci Is Still Italy’s Most Valuable Brand, According to BrandZ

Gucci Is Still Italy’s Most Valuable Brand, According to BrandZ
Prada is the second-most valuable brand among fashion and luxury players, followed by Fendi, which reported the greatest growth, also thanks to the Fendace collection.

MILAN — Gucci has confirmed its top position in the BrandZ 2022 Top 30 Most Valuable Italian Brands ranking by Kantar, which measures the value of brands by combining financial data with brand equity research.

The fashion house leads the list for the fourth year with a brand value that increased 12 percent to $37.9 billion compared to 2021.

Gucci’s brand value is nearly one third of the total value of all Italian brands in the ranking, which were up 12 percent to $128.7 billion compared to last year. The Florentine fashion house also reported more than three times the value of second-tier utilities company Enel.

Prada is the second-most valuable brand among fashion and luxury players with a value of more than $5.6 billion, which secured the house the sixth position on the list, behind automotive company Ferrari.

Fendi ranked seventh but reported the greatest growth, as its brand value jumped 47 percent to $4.7 billion. The Fendace collection, with its swap formula and media resonance, played a key role in this performance, benefiting also Versace, which was the only newcomer of the luxury segment in this year’s ranking.

Overall, Italian luxury brands continued to contribute the most to the top 30, accounting for 44 percent of the total brand value. According to the list, the top 10 luxury brands included Bulgari — among the overall top five risers along with Fendi and Prada — Giorgio Armani, Bottega Veneta, Salvatore Ferragamo, Valentino and Dolce & Gabbana.

Another 11 categories were represented in the overall ranking, too, with telecommunication companies, energy, insurance, food and automotive players also appearing in the first 10 positions. In particular, the second-most valuable Italian brand Enel reported $12.6 billion in brand value, followed by Kinder, Tim and Ferrari, valued at $9.8 billion, $8.9 billion and $8.3 billion, respectively.

The report spotlighted the positive momentum experienced by the country’s brands, showing that in the last four years they have grown in value by 51 percent.

Even if highlighting that the “Made in Italy” stamp of quality still bolsters the international growth of local brands, Kantar urged local companies to implement stronger and most effective communication to further build brand equity.

“Excelling with innovative products and a superb brand experience is no longer sufficient to guarantee success. Brands must address new values of consumers who want the brands they buy to align with their own beliefs. They no longer think only about how things are made, but by whom, under what conditions, and whether their materials are ethically sourced,” said Federico Capeci, managing director Italy, Greece & Israel — insights division, Kantar.

“Leading brand Gucci, for example, has tackled this challenge head on. It trades not just in fabrics, leather goods and gemstones, but commitment, authenticity, and conviction,” he added.

Capeci continued emphasizing the increasing importance of exposure as a business lever, especially because “as the value that Italy and its brands derive from exports overseas risks being impacted by instability, inflation and rising material costs, there is a greater need to focus on ensuring that consumers properly understand that brands are worth their value.”

The BrandZ Italian list is compiled by combining financial analysis of each label for the most recent fiscal year with surveys distributed to almost 70,000 Italian consumers. A Top 100 Most Valuable Global Brands list is also issued annually, combining market data with opinions of more than 4 million consumers worldwide.

WWD : Augustinus Bader Is Building a Supersonic Skin Care Business

Augustinus Bader Is Building a Supersonic Skin Care Business
Charles Rosier talked brand strategy and the future of beauty.

Augustinus Bader is a case study of how to build a supersonic skin care business.

Charles Rosier had a career in finance when a mutual friend who knew of his interest in biotech and medicine introduced him to the doctor Augustinus Bader. The friend called Bader “the best stem cell researcher in the world today.”

In his own words, Bader described his stem cell technology in a video shown at the Summit. “It is a different approach to medicine,” he said. “If there is an auto-regenerative mechanism only in terms of neuro-degenerative diseases, auto-immune diseases and any skin disorders, we can now target the area and induce and unfold the auto-regenerative process with the [aim] to create healing where it was not possible before. We are facing a shift of paradigm.”

Rosier had heard of Bader’s research in wound healing, and was interested in helping to finance it. Although launching a beauty business had not occurred to him, he had an epiphany and envisaged potential applications for Bader’s work that extended it beyond the medical realm.

“Augustinus’ discovery is really a communication mechanism [to awaken stem cells],” explained Rosier. “I was just mesmerized by that technology.”

Augustinus Bader — the brand, which launched in March 2018 — is among beauty’s fastest-growing today. In 2020, its annual sales tripled to $70 million, and The Cream and Rich Cream were voted the top skin care product in a poll of more than 300 beauty industry insiders conducted by Beauty Inc in 2021.

Rosier outlined a few pillars of growth for Augustinus Bader. Number one is having products that deliver. “That was the foundation of our brand,” he said.

Then there was also the support of celebrities and journalists who praised its efficacy.

When Augustinus Bader launched on Violet Grey, the platform’s total business was $5 million. “It’s a symbiotic relationship, because we broke the record of anyone there the first year we launched, and then we tripled our size — and probably doubled the size of Violet Grey’s business as a whole,” Rosier said.

“What is the future for us?” he mused. It’ll surely be based on technology.

“We’re very excited about the hair care category,” said Rosier, referring to a segment the brand entered with a big-bang launch last year — to sell-out effect.

He explained Augustinus Bader isn’t focused on hair care because it’s a surging category at present. “We want to be a problem-solver,” Rosier said. “So we need to be driven by creating solutions.”

Consumers inform the brand’s direction. It asked them what they wanted in a body cream, and the answer was solutions to stretch marks and cellulite. Those therefore became focal points.

The future will be robust with scientific studies into people’s individual biological age and longevity, Rosier said. And findings stemming from those could be applied to cosmetics.

“The focus is really on the convergence of beauty, health and longevity,” he said.

Business Of Fashion : Can Farfetch Change the Narrative Around Fashion Tech?

Can Farfetch Change the Narrative Around Fashion Tech?
This week, everyone will be talking about earnings from Farfetch and Gap Inc., plus the amfAR Gala.

Running Out of Moves
  • Farfetch reports first-quarter results on May 26
  • The company’s stock is down more than 80 percent over the last year, mirroring declines seen across the tech sector
  • Investors are concerned about online brands’ and retailers’ ability to grow and achieve profitability as consumers return to brick-and-mortar stores

Farfetch is a master at reinventing itself to ride the latest trends in online retail. But it’s having a tough time convincing investors it’s not just another pandemic stock. Like most other e-commerce companies, the luxury marketplace benefitted hugely from the boom in online retail in 2020 and 2021. Now, with consumers reverting to their pre-Covid shopping habits, Farfetch must make the case that it has a plan B.

Earlier this year, Farfetch made a high-profile push into beauty, though adding a new category doesn’t solve e-commerce’s post-pandemic problems. A $200 million investment in Neiman Marcus Group marks a major expansion of the marketplace’s ambitions to provide e-commerce services to less-wired retailers. That’s potentially a lucrative market, though the rapid decline in Shopify’s fortunes indicates running the back end of online retail is not as dynamic a business as it might have looked a year or two ago.

The Bottom Line: The real game-changer for Farfetch would be a partnership with Richemont that includes a minority investment in Yoox Net-a-Porter. Such a deal would neutralise a major competitor and open up new relationships with luxury brands. But the parties have said little about the deal since it was announced late last year. Last week, Richemont’s stock plunged after the company failed to indicate progress toward an agreement.

Business Of Fashion : Is This the Beginning of the End for Free Returns?

Is This the Beginning of the End for Free Returns?
For much of the last two decades, online retailers have competed to offer cheaper, more convenient shopping experiences. What happens when one of the world’s biggest apparel sellers bucks the trend?

This week, the BBC reported that Zara had earlier this month begun charging UK customers £1.95 ($2.44) to return online purchases by mail. The policy — already in place in 37 other countries — doesn’t apply to online orders returned in stores.

Outraged shoppers took to social media to complain. Some told horror stories about long queues and slow service when they attempted to bring items back to Zara’s stores. Others argued that Zara should improve its sizing and fits if they were going to charge for returns. A few applauded the new policy, saying it would nudge consumers toward more mindful consumption habits (the retailer said that it had begun charging for some returns in an effort to reduce its carbon footprint).

The environmental case for Zara’s switch is iffy — a delivery van picking up multiple returns will likely generate fewer emissions than individual customers driving to stores to avoid the fee, Deutsche Bank analysts wrote in a research note this week.

The economic case is clearer.

Online shopping, which boomed over the pandemic, has a much higher rate of customer returns than in-store purchases. Shipping and processing returned items create mounting logistical costs, as well as carbon emissions. Still, retailers fear turning back the clock now that many shoppers have become accustomed to free and easy returns: in a 2021 survey by the payments firm Klarna, 57 percent of respondents said they would never buy from a retailer that charged for returns.

But some companies are looking to dial back these expensive perks that attracted shoppers during the pandemic. In October and November 2021, just under 40 percent of retailers said they charge for mailed returns, while about 2 percent planned to incur charges over the holiday period and 19 percent were undecided on what measures they would take, according to a survey by Appriss Retail and the US National Retail Federation.

Online returns “have been abused, and are more costly [not only] in terms of the logistical cost, but in terms of the environment as well,” said Joaquin Villalba, chief executive of retail analytics firm Nextail Labs, which counts River Island and Guess among its clients. He is also a former head of Zara-owner Inditex’s European logistics operations.

Zara is by no means the first retailer to charge for returns — in the UK, Uniqlo and Next charge customers for returning products via parcel shops or home collection. Retail experts suspect it will not be the last, especially if consumers prove more willing to pay the fee than they have indicated in surveys.

The Burden of Returns

E-commerce returns have always posed a logistical headache to retailers, but the costs have risen significantly in the past two years, as online sales overall rose dramatically and parcel carriers raised their rates to deal with surging volumes. In January, UPS said it would handle a record 60 million returns following on from the holiday season, 10 percent higher than the year prior. At the beginning of the year, shipping company Fedex increased average prices by 5.9 percent.

As consumers buy fewer stretchy sweatpants and more party dresses, those costs will only continue to rise. At Revolve, 54 percent of orders were returned, the highest rate in at least two years, according to Cowen. In its full-year results reported earlier this month, Boohoo recorded a return rate of 33.7 percent in its core UK market, up nearly 10 percentage points from the year prior.

“Returns are a big mess, especially in the fashion space … [and] always a profitability drain for brands,” said Balaji Santhanam, associate partner covering consumer goods, retail and logistics at consultancy Infosys.

Online shopping bears a prodigious environmental cost as well, from packaging to the millions of home deliveries. The bulk of the fashion industry’s environmental impact takes place in manufacturing, however. Carbon emissions associated with returns are minimal in comparison.

Cutting overproduction, or the volume of clothes discounted at end of season, from 40 percent to 30 percent every year could save 158 million tonnes of carbon emissions, according to a 2020 report by McKinsey and Global Fashion Agenda. Reducing an e-commerce return rate from 35 percent to 15 percent, meanwhile, could save 12 million tonnes of greenhouse gas emissions per year, the report found.

Formulating the Best Policy

Whatever the motivation, charging for online returns will no doubt reduce the number of orders sent back. Incentivising in-store returns, which immediately puts products back in circulation, can also prevent waste, said Santhanam.

Other tactics include improving product pages and virtual sizing technology, or letting customers know about fit and styling advice if they start to add multiple sizes of the same item to their online cart. Some retailers offer repair and alteration services, hoping some minor adjustments to fit will ward off some returns. Ganni, for example, partnered with London-based tailoring app Sojo in November last year to offer on-demand alterations (this service isn’t limited to brands selling $400 dresses; Uniqlo also offers in-store tailoring).

Consumer psychologist Kate Nightingale also argues that, counterintuitive as it may seem, brands could benefit from adding a little more friction to the customer’s online shopping journey. Instead of constantly pushing new product, they could provide personalised styling tips for customers’ older purchases, thereby reducing the number of impulse buys that ultimately get returned.

“It’s more about a long-term mentality change,” she said. “It’s a big ask, because it [involves] a lot of permutations, but imagine the savings in returns that could make, without charging the customer.”

WSJ : More Subprime Borrowers Are Missing Loan Payments

More Subprime Borrowers Are Missing Loan Payments
Borrowers with limited or troubled credit histories are defaulting on credit cards, car loans and personal loans

Consumers with low credit scores are falling behind on payments for car loans, personal loans and credit cards, a sign that the healthiest consumer lending environment on record in the U.S. is coming to an end.

The share of subprime credit cards and personal loans that are at least 60 days late is rising faster than normal, according to credit-reporting firm Equifax Inc. In March, those delinquencies rose month over month for the eighth time in a row, nearing their prepandemic levels.

Rising delinquencies were inevitable following their decline during the pandemic, many lenders and analysts said. Even so, the increase is getting attention from investors partly because the Federal Reserve, facing the highest inflation since the early 1980s, is embarking on what is expected to be the sharpest series of interest-rate rises in years. Higher loan delinquency figures can indicate stress on the part of consumers whose spending is a significant driver of economic activity.

Fears that rising rates will throw the economy into recession have fueled the worst start of the year for stocks in decades. A poor earnings season for major U.S. retail chains has intensified those concerns this week, prompting large declines in major retail shares and sending the Dow Jones Industrial Average to its steepest drop of the year Wednesday.

Delinquencies on subprime car loans and leases hit an all-time high in February, based on Equifax’s tracking that goes back to 2007.

Many people, including those with less-than-perfect credit, paid off debts and built up savings during the pandemic, a surprising outcome considering that lenders at first thought borrowers would default en masse when Covid-19 hit. The government’s response, including stimulus payments and child tax credits, boosted many families’ financial health.

But now many of those benefits have run out. Subprime borrowers, who sometimes have lower incomes or less savings, are being hit hard. Inflation, running near its highest point in four decades, is also forcing many households to choose between paying for essentials and paying their monthly loans.

There is also a broader concern among some lenders about the ability of consumers overall to keep up with payments when some of their financial benefits, including excess savings that they accrued during the early stages of the pandemic, taper off.

Wells Fargo & Co. Chief Executive Charlie Scharf said Tuesday that higher prices for food and gasoline will constrain U.S. households. “We are still in the best credit environment we have ever seen in our lives,” Mr. Scharf said at The Wall Street Journal’s Future of Everything Festival. But, he added, “There will be deterioration in people’s ability to pay.”

The jump in subprime delinquencies could reduce lenders’ willingness to make loans to riskier borrowers.

Lenders have kept their standards for mortgage loans relatively strict. A red-hot housing market and a flood of mortgage applications meant lenders could be picky with their offerings and the type of borrowers they approved.

But last year, many lenders embraced subprime customers for other types of loans, comforted by low unemployment and fueled by an eagerness to rebuild loan balances that took a hit early in the pandemic. Subprime lending hit records last year when measured by the total dollar amount of personal loans originated and spending limits on new general-purpose credit cards, according to Equifax.

Some 11% of general-purpose credit cards held by consumers with credit scores below 620 were at least 60 days behind on payment in March compared with 9.8% a year prior, according to the latest data available from Equifax. Personal loans and lines of credit delinquencies came in at 11.3%, up from 10.4% a year prior. Both categories hit Covid-19-era lows of 7.5% and 8.3%, respectively, in July.

Car loan and lease delinquencies hit a record in February, based on Equifax’s tracking, with 8.8% of subprime accounts behind on payment by at least 60 days. That edged down to 8.5% in March but was still the second highest level on record.

Fewer people are in subprime credit-score brackets than when the pandemic began. Some 18.6% of U.S. adults with credit scores had a score lower than 600 in 2020, compared with 15.5% last year, according to Fair Isaac Corp. , creator of FICO scores.

Lenders say that delinquencies are going up from artificially low levels and that their credit portfolios overall remain strong. Many refer to what is happening as a normalization, where delinquency rates return to levels more in line with prepandemic times. Some say their delinquencies remain below their first-quarter 2020 levels.

Capital One Financial Corp. recorded a higher U.S. credit-card 30-day-or-more delinquency rate in the first quarter from a year prior. Lender Bread Financial Holdings Inc. also reported a higher delinquency rate for its cards and other loans for the quarter. Both lenders issue credit cards to subprime borrowers. Other large card lenders didn’t record this increase for the year-over-year period, said Michael Taiano, senior director at Fitch Ratings’s U.S. banks group.

“It would be an unnatural thing for credit to stay where it is,” Capital One Chief Executive Richard Fairbank said on the bank’s last earnings call. “We would expect this is an across-the-board kind of return toward normal over time.”

Upstart Holdings Inc., Oportun Financial Corp. and OneMain Holdings Inc., which facilitate or extend personal loans to people with limited credit histories or low credit scores, also reported increased delinquencies for the first quarter.

Upstart said on its earnings call last week that government stimulus led to a temporary overperformance of consumers. It recently reintroduced loan modifications for borrowers who are struggling to keep up with payments.

Consumers are dealing with a mixed bag of rising gasoline prices and rent, while employment and wage growth remain strong, Raul Vazquez, Oportun’s chief executive, said in an interview. “How that all mixes out we are all going to see in the next few months.”

WSJ : China Spends Far More Than Others to Help Favored Industries, Report Finds

China Spends Far More Than Others to Help Favored Industries, Report Finds
State-directed funds, cheap loans and incentives surpass those of other major economies

China spends much more in helping favored industries with state-directed funds, cheap loans and other government incentives than other major economies, according to a new study expected to intensify the debate in Washington and elsewhere over Beijing’s use of industrial policy.

The study, to be published by the Center for Strategic and International Studies on Monday, finds that China’s backing of its companies amounted to at least 1.73% of its gross domestic product in 2019—the most recent year for which comprehensive data is available—and the trend is continuing.

In dollar terms, that is more than $248 billion based on market exchange rates—exceeding estimated Chinese military spending—or $407 billion based on exchange rates that adjust for differing costs across countries.

China’s spending, both as a share of GDP and in dollar terms, is significantly higher than that of seven other economies analyzed in the report, including South Korea, France, Germany, Japan, Taiwan, the U.S. and Brazil. By comparison, according to the study, the U.S. spends 0.39% of its GDP on industrial support, while South Korea, the No. 2 spender, devotes 0.67% of its output.

“China is a large outlier,” said Scott Kennedy, an expert on China’s economy at the Washington-based think tank and an author of the report. “It spends an enormous amount on industrial policy and also uses more tools for such spending than anybody else.”


Beijing’s disclosure of subsidies is murky at best, China analysts say, and its use of industrial policy is one of the most contentious issues involving the country’s statist economic model. The CSIS study is the first trying to put a total tally on China’s overall manufacturing support and to assess how it stacks up against other economies that have directed resources to help manufacturers rather than leaving their development to market forces.

Since late last year, the Biden administration has been looking for ways to confront Beijing with its use of industrial subsidies that give Chinese companies an edge over their foreign rivals.

The new study, which has been months in the works and already generated some buzz in Washington, could offer administration officials a grasp of the scale of the Chinese support as they are considering whether to launch a new investigation into Chinese subsidies, potentially using Section 301 of the Trade Act, which allows the U.S. to take punitive action against certain practices of a trading partner.

The report also comes as industrial policy is coming back in vogue in the U.S. and among its allies in both Europe and Asia, fueled by pandemic-driven disruptions to supply chains as well as the competition with China.

From Washington and Brussels to Seoul and Tokyo, officials have been rushing out government subsidies to promote industries they deem strategic, including semiconductors, electric-car batteries and pharmaceuticals.

The renewed interest in the use of interventionist measures by developed economists has prompted Chinese officials to argue that Beijing’s industrial support isn’t all that different and countries like the U.S. are simply trying to thwart China’s rise by targeting its policies.

A purpose of the report, say the authors, who also include CSIS analysts Gerard DiPippo and Ilaria Mazzocco, is to spark more substantive discussions among policy makers, business leaders and academics about the impact of China’s industrial spending on the rest of the world.

Many economists and Western officials once assumed that Beijing would gradually reduce the state’s role in directing credit and other resources as the economy matured. However, government interventions have increased in China over the years, especially under President Xi Jinping, who sees industrial policy as vital to reducing China’s economic dependence on other countries while increasing their dependence on China.

The study points out that Beijing’s industrial initiatives have become more ambitious in recent years, with their focus shifting from “catching up” to the West technologically to targeting industries at the frontier of innovation, such as electric vehicles and artificial intelligence.

To quantify Chinese spending, the analysts made estimates based on data such as direct government subsidies, tax incentives, below-market credit and state investment funds. To avoid overestimating or double-counting, the study excludes tools that are hard to quantify, including restrictions on foreign firms’ market access in China and government purchases, which often include incentives for domestic suppliers.

Mr. DiPippo noted that government-guided funds are one unique instrument China has used for industrial policy. “China’s state ownership of much of its financial sector gives Beijing enormous capabilities to direct financial resources in a way that other economies can’t,” he said.

These funds are intended to be more commercially oriented vehicles with funding from both the government and the private sector. In practice, however, the state still maintains a heavy hand in running them. “They end up crowding out private capital and distorting the market,” Mr. DiPippo said.

By the end of 2020, some 1,851 government-guided funds had been established in China, with a total designated funding target of $1.7 trillion, according to research firm Zero2IPO. The actual funds raised were around $820 billion. One of them is the semiconductor-focused National Integrated Circuit Industry Investment Fund, dubbed the “Big Fund,” which has raised more than $29 billion.

The value of funding raised by these state funds from 2015 to 2020 was equal to roughly two-thirds of the total venture-capital and private-equity investments made in China during those years, according to the report.

The study also expands on some of the existing sector-based research on Chinese subsidies, such as those involving chip-making, aluminum and electric vehicles.

For instance, China provided an estimated $58 billion to its EV makers between 2009 and 2017, the report shows. Beijing’s largess has in part fostered overcapacity and a fragmented industry, with the government now calling for consolidation.
FT : Lukoil’s ex-chief warns against EU ban on ‘irreplaceable’ Russian oil

Lukoil’s ex-chief warns against EU ban on ‘irreplaceable’ Russian oil
Vagit Alekperov says tightened sanctions would be worst outcome for Europe as well as Moscow

The former head of Russia’s second-biggest oil group has warned that a European ban on the country’s “impossible to replace” crude would be “the most negative scenario” for all parties as EU discussions on an embargo intensify.

Vagit Alekperov, who stepped down as chief executive of Lukoil last month after he was hit by western sanctions, told the Financial Times that any EU move to cut off Russian oil imports would be “a shock for everyone”. 

“By imposing sanctions, western countries gave a clear signal and declared their position. There is no need to further tighten them,” the billionaire said in his first press interview since stepping down.

Alekperov’s comments come amid fierce debate in the EU — which relies on Russia for a quarter of its oil imports — on whether to instigate an oil ban that would ratchet up the pressure on Moscow but exacerbate Europe’s energy crisis.

European Commission president Ursula von der Leyen wants the EU to stand alongside G7 partners including the US, which imposed oil sanctions in March. But a push to include an oil ban in the EU’s sixth package of measures against Russia has run into opposition from Hungary, which says it cannot afford to find alternative fuels.

Alekperov acknowledged that an oil import ban would mean “Russia will have to reduce production, freeze wells, as we did at the beginning of the pandemic in 2020, because it is impossible to redirect all European volumes to other markets overnight”.

But he warned that for the EU, “it is impossible to replace such a major energy exporter as Russia, even in the medium term”.

Building new infrastructure to redirect Russian crude currently flowing to Europe would take years, Alekperov said, particularly in an environment where the global industry had already lost “hundreds of billions, trillions of dollars” of investment in recent crises.

“Military conflicts can end quickly, while the energy configuration of the world has been set by decades of investment and hard work of many generations of professionals,” he added. “There is no need to undermine or destroy it.”

Referring to declining energy security and rising prices in the wake of Russia’s invasion of Ukraine, he said: “This is not a natural process, such as decarbonisation, and not a short-term consumption crisis as in the coronavirus pandemic. This is a very severe energy crisis with negative long-term consequences for all market participants.”

The commission has offered €2bn in loans to Hungary and other central European states to adapt their infrastructure as part of its €210bn RepowerEU plan to attain energy independence from Moscow.

Alekperov was one of the longest-serving oil executives in Russia until UK and Australian sanctions against him prompted him to step down from Lukoil after 30 years at the helm.

Hailing from Azerbaijan, where he worked as an oilman before moving to manage oilfields in Siberia and then to the Soviet oil and gas ministry, Alekperov founded Lukoil by uniting three of the largest Soviet oilfields in 1991. The company was in the top three global oil producers in 1992.

Alekperov saw it through its 1993 privatisation, a London listing and the transition to international reporting standards. The LSE suspended trading in Lukoil shares in March.

He retains an 8.5 per cent stake directly or via family trusts or investment funds. Forbes estimated his wealth in May at $22bn, down from almost $25bn last year.

Like other Russian businesses, Lukoil has been hit by various western measures targeting Russia’s economy. The company warned last month it may need to shut refineries because of its reduced ability to sell oil products abroad or store them domestically.

Alekperov was targeted with sanctions for what the UK government described as benefiting from or continuing to support the Russian government. But he insisted Lukoil and its management had no influence over political decisions or processes.

His decision to step down “was made for the sake of the company, although I won’t hide it, it was a sad one for me”, he said.

“We see that sanctions are often of chaotic, emotional nature,” he said. “They affect people who make no political decisions, have no political influence. Let alone the factual mistakes in them, in last names, titles, or reasons for being sanctioned. It doesn’t look serious from the legal standpoint at the very least and negates the importance of these measures in the eyes of the public.”

FT : ABB and Siemens back Norwegian battery start-up

ABB and Siemens back Norwegian battery start-up
European industrial heavyweights lead €100mn funding round in Morrow Batteries

ABB and Siemens are leading a €100mn fundraising round by Morrow Batteries, a start-up that aims to start producing in its home country of Norway by the end of next year.

Boosting investment in battery production has become an urgent strategic goal for Europe as it races to address the energy crisis and the shortage created by declining Russian gas supplies. 

The region’s biggest battery makers include Sweden’s Northvolt, which raised $2.75bn last year and started production in December, and Norway’s Freyr, which went public last year through a merger with a listed company.

Morrow said it would use its funding to build a 1.2GW pilot factory by the end of next year, which will produce batteries used in energy storage systems such as those used for rooftop solar panels. 

Chief executive Terje Andersen said this initial production would allow the company to obtain certification for producing electric vehicle batteries, which would ultimately become its main market.

“The market is huge,” he said, acknowledging that Morrow was two or three years behind larger rivals such as Northvolt. He estimates Morrow is in the top third of European battery groups. “We are not in the front, and we are not in the back,” said Andersen.

At present China is the world’s biggest battery manufacturer. However, new European trade rules will make it extremely expensive to import batteries from Asia from 2027, creating an opening for Europe’s homegrown battery makers.

Morrow’s €100mn fundraising is being led by Siemens Financial Services, a subsidiary of the German industrial group, and ABB, the Swedish-Swiss power conglomerate. Additional investors include the Norwegian state’s Nysnø Climate Investments and Arendals Fossekompani, a hydropower company and green investment fund.

Morrow previously raised €32mn from investors including Danish pension fund PKA and Agder Energi Venture, which both participated in the second round.

At present Morrow’s battery development line is in South Korea, and the company said it would relocate the production to the new factory in Arendal on Norway’s southern coast.

Global shortages of cobalt and nickel are threatening to push up the price of electric vehicle batteries, prompting some manufacturers to invest in technologies that use less of these materials.

Andersen said the company was planning a battery that had no cobalt and used significantly less nickel. “We will replace nickel and cobalt with manganese. This is what the EV producers are keen to discuss with us.”

FT : Saudi Arabia signals commitment to Russia as Opec+ partner

Saudi Arabia signals commitment to Russia as Opec+ partner
Oil alliance’s production quotas set to expire in three months and Russian output is falling

Saudi Arabia has signalled it will stand by Russia as a member of the Opec+ group of oil producers despite tightening western sanctions on Moscow and a potential EU ban on Russian oil imports.

Prince Abdulaziz bin Salman, the energy minister, told the Financial Times that Riyadh was hoping “to work out an agreement with Opec+ . . . which includes Russia”, insisting the “world should appreciate the value” of the alliance of producers.

His comments are an important sign of support for Russia from a traditional US ally as the west tries to isolate the country and its oil production falls, raising questions about its place in the Opec+ group.

As energy consumers grapple with oil prices that are at their highest levels in a decade, a set of Opec+ production quotas put in place in April 2020 is set to expire in three months.

Riyadh has been resisting western pressure to raise crude output to help bring down prices in the wake of Russia’s invasion of Ukraine, insisting there is not a lack of supply.

Prince Abdulaziz said it was too early to say what a new agreement might look like given the uncertainties in the market, but added that Opec+ would increase production “if the demand is there”.

“With the havoc you see now it’s too premature to try to pinpoint [an agreement],” Prince Abdulaziz said in an interview. “But what we know is what we have succeeded to deliver is sufficient for people to say so far there is a merit, there is a value of being there, working together.”

Opec+ has stuck to its 2020 agreement, under which the alliance members raise total production each month by the modest amount of 430,000 barrels a day.

But Russia’s output has dropped since the start of the Ukraine war, falling from about 11mn b/d in March to an average of 10mn b/d in April, according to data provider OilX.

The International Energy Agency predicts it could fall further, declining by as much as 3mn b/d if western powers impose tougher sanctions to reduce Europe’s dependence on Russian energy, including a possible EU ban on oil imports. India, however, has increased Russian oil imports since the war began. 

Brent crude, the international benchmark, was trading at about $112 a barrel last week.

Saudi Arabia, the de facto leader of Opec and the world’s top oil exporter, has co-ordinated oil production quotas with Russia, since 2016, through Opec+.

The kingdom has sought to navigate a neutral path since Russia invaded Ukraine. Crown Prince Mohammed bin Salman has spoken twice to Putin since the invasion and this month he and King Salman congratulated the Russian leader on the day the country marks the Soviet victory over Nazi Germany.

Prince Abdulaziz blamed soaring prices at petrol pumps on a lack of global refining capacity and taxes.

“The determinant of the market is refinery capacity, and how do you unlock it,” he said. “At least for the last three years, the whole world lost around 4mn barrels of refining capacity, 2.7mn of them just from the beginning of Covid.”

Some members of Opec+ have also consistently failed to meet their production quotas, and Saudi Arabia and the United Arab Emirates are the only producers who have the capacity to significantly increase output.

After Russia launched its invasion in February, the west initially avoided imposing sanctions on Russian energy assets because of Europe’s heavy dependence on the country’s gas and oil exports.

The US and UK banned oil imports from Russia in March. But EU states remain divided on measures to phase out Russian oil supplies, and this month dropped a proposal to ban the EU shipping industry from carrying Russian crude.

Prince Abdulaziz said politics should be kept out of Opec+, adding the alliance would be needed to bring about “orderly adjustments” in the future amid uncertainty about coronavirus lockdowns in China, global growth and supply chains.

He said that to ease bottlenecks in production and refinery capacity governments had to encourage the industry to invest in hydrocarbons even as nations switch to cleaner energy sources.

“This situation needs people to sit together, focus, take out the masquerade and the so-called political correctness . . . it’s about trying to relate to existing reality and find remedies to it.”