Gapping down
In reaction to earnings/guidance:
- NTNX -37.4%, SNOW -12.4%, ZUO -9.4%, VSAT -6.3%, NVDA -4.7% (also increases and extends share repurchase program to $15 bln), MDT -3.4%, DXC -2.9%, ZTO -2.4%, BOX -1.8%, LU -1.5% (also also CFO to retire)
Other news:
- AVDL -15.7% (received a proposed final label and medication guide for FT218 from the FDA)
- BBIG -10.6% (delays distribution date for Cryptyde spin-off)
- DDOG -4.8% (in sympathy with SNOW earnings)
- MIRM -4.7% (stock offering)
- HQI -3.8% (files for $100 mln mixed securities shelf offering)
- ADC -3.7% (prices offering of 5.0 mln shares of common stock at $68.65 per share)
- NRIX -2.1% (announces positive dose finding data in chronic lymphocytic leukemia and advances NX-2127 to next phase of clinical development)
- AMD -1.2% (in sympathy with NVDA earnings)
- AVGO -1% (acquires VMW; also reported earnings)
Analyst comments:
- ASGN -4.2% (downgraded to Market Perform from Outperform at BMO Capital Markets)
- PUMP -2.3% (downgraded to Underweight from Overweight at JP Morgan)
- TBI -1.7% (downgraded to Market Perform from Outperform at BMO Capital Markets)
- CAH -1.6% (downgraded to Equal Weight from Overweight at Barclays )
- CMCO -1.3% (downgraded to Neutral from Overweight at JP Morgan)
- CNC -1.2% (downgraded to Neutral from Buy at BofA Securities)
Gapping up
In reaction to earnings/guidance:
- M +13.2%, DLTR +12.7%, DG +11.1%, WSM +8.4%, MOD +8%, BKE +7.2%, SPLK +6.7%, BIDU +5.6%, TITN +5.6%, BABA +4.2%, ELF +3.8%, MANU +3.5%, GES +3.4%, ENS +3.1%, BRC +2.5%, JBLU +2% (guidance), LUV +1.5% (guidance), BZUN +1.4%, CHNG +1.1%, CM +0.9%
Other news:
- AKTS +6.1% (suspended sales under its previously-announced "at the market" equity offering program in light of current market conditions)
- RETA +6% (announces FDA filing acceptance and Priority Review Designation for the NDA for omaveloxolone for the treatment of patients with Friedreich's ataxia; PDUFA date November 30 2022)
- TWTR +5.6% (Elon Musk increases commitment in takeover bid to $33.5 bln; also reaches settlement with DOJ and FTC to pay $150 mln in civil penalties for alleged data privacy violations)
- RH +4.2% (in sympathy with WSM earnings)
- W +3.4% (in sympathy with WSM earnings)
- LEGN +3.4% (receives conditional approval for CARVYKTI by the EC)
- BBBY +2.8% (in sympathy with WSM earnings)
- TSLA +1.7% (Elon Musk increases commitment in takeover bid of TWTR to $33.5 bln)
- VMW +1.5% (Broadcom (AVGO) to acquire VMware for ~$61 billion in cash and stock)
- HYLN +1.3% (receives Hypertruck ERX order from Holcim)
- HMN +1% (authorizes new $50 mln share repurchase program)
Analyst comments:
- ALHC +3.8% (upgraded to Buy from Neutral at BofA Securities)
- CI +1.7% (upgraded to Neutral from Underperform at BofA Securities)
WeWork co-founder Adam Neumann’s new crypto project sounds like a scam within a scam
Turning carbon credits into crypto won’t fix climate change.
Adam Neumann is back. The cofounder and former CEO of WeWork and subsequent subject of the podcast-turned-TV-series WeCrashed now says he wants to fix climate change — with crypto.
Specifically, Neumann wants to put carbon credits on the blockchain. But making carbon credits easier to buy and sell does nothing to solve the real problem with carbon credits and offsets, which is that they’re broken. More easily trading a broken product doesn’t make it any less broken.
Neumann’s new company is called Flowcarbon, and it has big ambitions, which will be backed by $70 million from the crypto arm of the venture capital firm a16z. On its website, Flowcarbon says that the current system of buying and selling carbon credits is built on an “opaque and fractured market infrastructure” and that the carbon credits themselves have “little liquidity, accessibility, and price transparency.” In other words, the problem is the carbon credit market, and the way to fix it is by making it easier to trade carbon credits.
This is a classic argument for a crypto company, by the way. The answer for everything in the crypto world seems to be greater commodification. But when it comes to saving the planet (as with most things in life), that’s not necessarily true.
Carbon credits and offsets are two sides of the same coin, and the terms are often used interchangeably. A carbon offset refers to a project that reduces carbon dioxide emissions (preserving forests is a popular one), and carbon offsets generate carbon credits. And both trade in units that represent one metric ton of carbon dioxide. Flowcarbon is supposed to work through the creation of a new crypto token, called the Goddess Nature Token, or GNT. Those tokens would represent carbon credits, and Flowcarbon users looking to trade carbon credits would do so by buying and selling those tokens.
That second part has the potential to be problematic: Unlike stocks or cryptocurrencies, carbon offsets ultimately need to be taken off the market in order for them to have any lasting, traceable impact on a company or individual’s carbon footprint. Google, for example, “retires” any carbon offsets it buys, putting a stop to the trading so nobody else can claim their climate benefits. (How effective those offsets ever were is debatable.) Flowcarbon users have the option to retire their tokens, redeem them for classic carbon credits off the blockchain, or keep trading them. If a Flowcarbon user were to keep the carbon, well, flowing by trading away their carbon credits, they can’t claim to have offset any of their own emissions.
“I think they’re trying to solve something that’s not a problem,” Robert Mendelsohn, a professor of forest policy and economics at Yale, told Recode. “The kinds of things that blockchains are good at, which is sort of just making sure nothing gets lost, isn’t really a problem with the current market. That’s not where they’re broken. Where they’re broken is the credits themselves may not actually be causing any reduction in carbon.”
As my colleague Umair Irfan wrote in 2020, one of the key principles for making a good carbon credit is “additionality,” or ensuring that a carbon offset project will actually lead to a reduction of emissions that wouldn’t have happened otherwise. This is trickier than it sounds: A 2020 Bloomberg investigation found that carbon offsets sold by the Nature Conservancy, one of the largest environmental nonprofits in the world, were based on forested properties that likely would have been preserved even without extra funding. In other words, the emissions reductions from those trees would have happened anyway, making them invalid as carbon offsets.
That’s just one example. Carbon credits and offsets frequently miss the mark, and in some cases can even cause additional harm to forests. Carbon offsets that don’t provide any additional emissions reductions allow companies who buy them to claim they’ve made a difference to their carbon footprint without having any real impact. “They haven’t offset anything,” Mendelsohn explained. “They’ve just got this worthless piece of paper saying they got a credit. You could put that credit onto the blockchain, and it would be just as worthless.”
It’s not exactly clear how Flowcarbon would actually make carbon offsets more useful or trustworthy. Nicole Shore, a Flowcarbon spokesperson, said in an email that the credits backing the GNT “follow the criteria of the global carbon market” and come from one of four large carbon credit registries. The company also says the carbon credits behind its token have been “certified,” but it doesn’t detail how that certification process happens, or if it has a verification system that’s any different from the current carbon credit market.
The difficulty of verifying carbon credits means it can take a while for more of them to come on the market. As more companies become interested in purchasing credits to offset their emissions, that can create a bottleneck.
“The problem with the current markets is nothing to do with how we can trade these more effectively,” said Anil Madhavapeddy, who is an associate professor of computer science and technology at Cambridge University and the director of the Cambridge Center for Carbon Credits. “We just do not have enough supply.”
Madhavapeddy, like Flowcarbon, is working on building a blockchain-based solution for carbon credits. But unlike Flowcarbon, he isn’t interested in building a marketplace for those credits. Instead, he’s focused on verifying they’re real by using satellite imagery and remote sensing technology to monitor carbon offset projects around the world and recording the results on the blockchain. Madhavapeddy hopes that technology will make it easier to get more carbon credits on the market more quickly.
Instead of building a whole new marketplace for carbon credits, for now, Madhavapeddy just wants to help ensure that those credits are based on something that will have a real impact. “Because the supply is so constrained, you don’t need to tokenize all these things,” Madhavapeddy told Recode. “It takes years for new (carbon offset) projects to kick off, so every marketplace constructed right now is just shuffling the same old pieces around.”
Crypto’s climate credit gold rush isn’t going unnoticed by the traditional players in the market, either. Verra, the world’s largest carbon-offset registry, announced this week that it will no longer allow its credits to be used as the basis for crypto tokens. Active crypto markets for carbon credits, Verra said, create too much confusion over who should get final credit for carbon reductions.
Once carbon credits become more readily available — and verifiably trustworthy — it’s possible companies like Flowcarbon could be key to making carbon credits and offsets more easily accessible to regular folks who are interested in offsetting their carbon emissions. But let’s not forget what happened last time Adam Neumann promised big things when founding a company with a questionable business model. WeWork speculated on how flexible our relationship with our built environment could be, and while it remains to be seen if Flowcarbon is any different, we can’t afford to leave our relationship with the natural world open to similar speculation.
Commodifying nature is part of what led us to our climate mess in the first place. Perhaps it’s time to learn from our mistakes.
Early premarket gappers
- Gapping up:
- WSM +8.7%, TWTR +5.7%, HYLN +5.2%, BIDU +4.7%, SPLK +4.5%, ELF +3.8%, MOD +3.7%, RH +3.1%, ENS +3.1%, CHNG +2.4%, LEGN +2.1%, ACAD +1.9%, GES +1.6%, W +1.4%, BBBY +1.3%, HMN +1.2%, BZUN +1%, ENLC +0.7%, TSLA +0.5%, INTC +0.5%, LZB +0.5%
- Gapping down:
- NTNX -35.1%, SNOW -14.4%, BBIG -8.9%, VSAT -6.3%, DDOG -5.6%, NVDA -5.4%, MIRM -4.7%, ZUO -4.6%, HQI -3.8%, ADC -3.7%, BOX -2.2%, AMD -1.9%, SB -1.5%, CM -1.3%, MRVL -1.2%, DXC -1.2%, CNK -1.1%, MU -1%, HPQ -0.5%, ENOB -0.5%
FirstGroup evaluates PE offer valuing shares at up to £1.23bn
Aberdeen-based bus and train operator’s stock rises 8% after unsolicited bid from I Squared Capital
FirstGroup is evaluating a bid valuing its shares at up to £1.23bn after “a series of unsolicited, conditional proposals” from private equity group I Squared Capital.
The UK bus and train operator said on Thursday the offer consisted of a cash component of 118p per share and a “contingent right” of “up to a further 45.6p per share” based on the outcome of payouts due to the company following the sale last year of its US transit business and on the net assets of the Greyhound bus business, which was also sold last year.
The full 163.6p-per-share offer would value FirstGroup’s equity at £1.23bn.
FirstGroup said it was “currently evaluating” the latest offer, noting that “the previous approaches were all unanimously rejected by the board”.
Like other bus and train operators, FirstGroup has been grappling with the sudden decline in bus and rail traffic during the coronavirus pandemic and the subsequent slow recovery of demand.
The company last year fought a prolonged battle with activist investors who forced out chief executive Matthew Gregory in July last year.
The activists — led by New York-based Coast Capital Management — were unhappy at the £3.3bn the company received for its First Transit and First Student transit and school bus operations in the US.
The sale of the Greyhound operations in a complex deal for which the company received $172mn cash was announced in October.
Aberdeen-based FirstGroup, the UK’s biggest train operator, is the main shareholder in four UK rail franchises: Great Western Railway, South Western Railway, TransPennine Express and Avanti West Coast.
It also runs Hull Trains and Lumo, two “open access” operations that operate trains on a commercial basis without franchises. In addition, it is the second-biggest operator of regional buses, providing services in Glasgow, Bristol and Leeds.
The company’s shares were up more than 8 per cent at 129.5p in morning trading in London.
Nikkei Asia reported this week that Apple and its suppliers are struggling with iPhone 14 production due to COVID-19 lockdowns in China. Now analyst Jeff Pu of Haitong International Securities has brought more detail to this story by saying that iPhone 14 Max production is delayed by three weeks.
According to Nikkei Asia, Apple has asked suppliers to speed up production of the new iPhone models, which are expected to be released later this year. This is because multiple Apple suppliers have suspended their operations in China as a result of COVID-19 lockdowns.
Yesterday’s report revealed that a specific iPhone 14 model was affected by delays in the engineering verification test (EVT), when suppliers finalize all parts and processes before starting mass production. Analyst Jeff Pu believes that the affected model is the long-rumored iPhone 14 Max (not the Pro Max).
To mitigate the impact of the delays, Apple has been planning to start mass production of the new iPhones earlier than expected. However, the iPhone 14 Max production, which will be primarily assembled by Pegatron, is expected to begin in late August – just a few weeks before the announcement of the new models.
Jeff Pu predicts that Apple will build 91 million iPhone 14 units by the end of the year despite production delays for the 14 Max model, which is more than the 84 million iPhone 13 units Apple shipped in 2021. However, it’s unclear whether production delays will push Apple to hold off on the official announcement of the iPhone 14.
iPhone 14 rumors
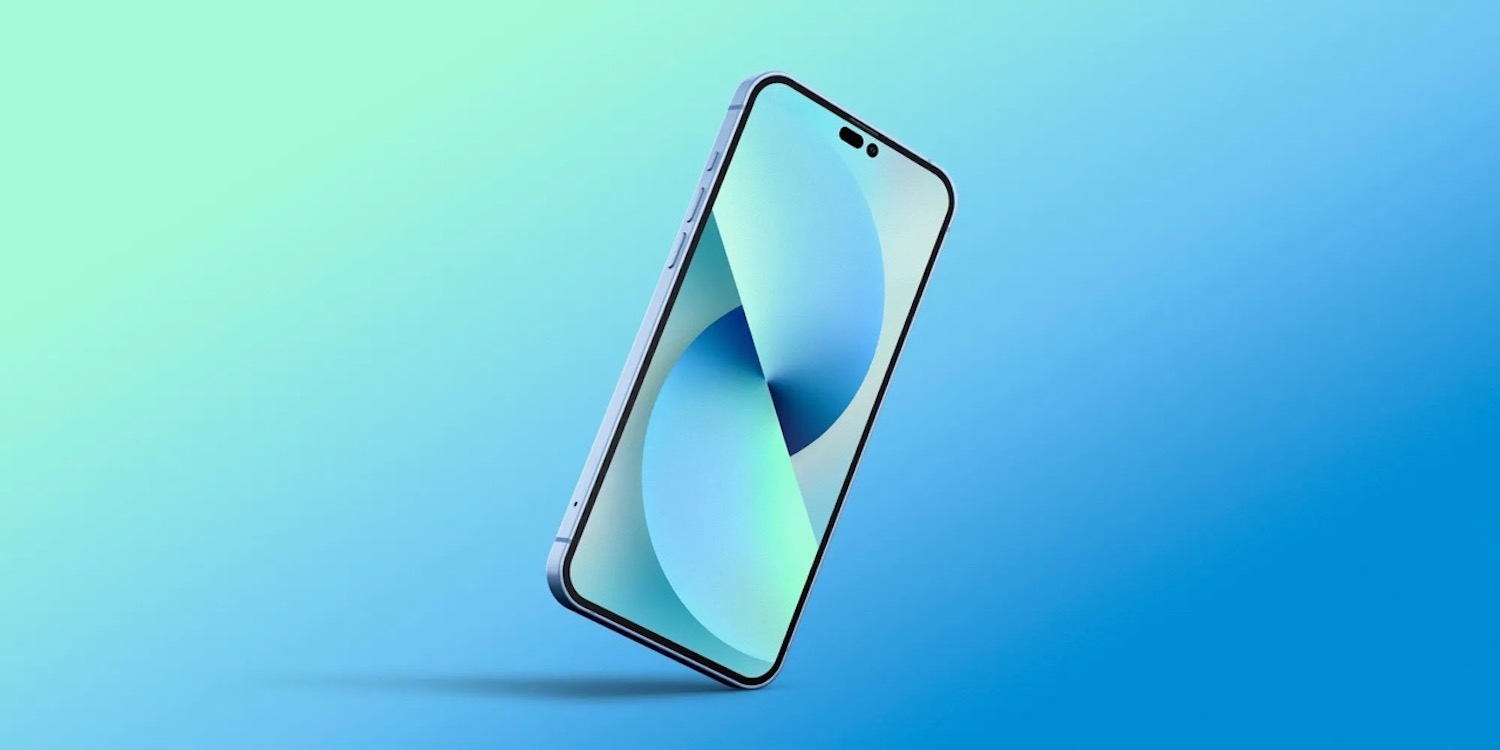
iPhone 14 is expected to be available in four different models. A 6.1-inch iPhone 14, a brand new 6.7-inch iPhone 14 Max, a 6.1-inch iPhone 14 Pro, and a 6.7-inch iPhone 14 Pro Max. As you can see, there won’t be a new “mini” model in the iPhone 14 lineup.
Other rumors include a refreshed design for the 14 Pro models with a new “pill-shaped” notch, thinner bezels, and larger camera sensors with a 48-megapixel wide lens. Unfortunately, the regular iPhone 14 models aren’t expected to have significant changes in terms of design and hardware.
9to5Mac independent sources and analyst Ming-Chi Kuo say Apple might break from tradition this year by releasing some iPhone 14 models with the same A15 chip as the iPhone 13.
>>> Up
* Datagroup Raised to Reduce at Baader Helvea; PT 69 euros
* Datagroup Raised to Reduce at Baader Helvea; PT 69 euros
* Electrolux Raised to Neutral at Goldman; PT 142 kronor (+)
* Freenet Raised to Buy at Goldman; PT 30 euros (+)
* Galp Raised to Outperform at RBC; PT 16 euros
* Lululemon Raised to Overweight at Morgan Stanley; PT $303
* MFE Raised to Buy at Banca Akros (ESN) (+)
* Pagegroup Raised to Buy at Citi
* Saipem Raised to Add at AlphaValue/Baader
* Serco PT Raised to 200 pence from 180 pence at Liberum (+)
* Whitbread Raised to Buy at Panmure Gordon; PT 3,500 pence
>>> Down
>>> Down
* Aareal Bank Cut to Sell at AlphaValue/Baader
* Nordex Cut to Reduce at AlphaValue/Baader
* Tesla PT Cut to $1,050 from $1,250 at Jefferies
>>> Initiation
* Tesla PT Cut to $1,050 from $1,250 at Jefferies
>>> Initiation
* Ashtead Assumed Buy at Jefferies; PT 5,000 pence
* BRSA LN Rated New Corporate at Edison Investment Research
>>> Call
* BRSA LN Rated New Corporate at Edison Investment Research
>>> Call
* Citi Strategists Recommend Buying the Dip, Especially in Europe (+)
* FirstGroup a ‘Classic Value Gem,’ Initiated Buy at Berenberg
* Freenet Double Upgraded to Buy at Goldman on Structural Quality (+)
* IntegraFin’s Key Metrics ‘Developing as Expected’: Peel Hunt (+)
* PageGroup Valuation Outweights Near-Term Earnings, Citi Upgrades
* Verbund Upgraded at Deutsche Bank on Reduced Windfall Tax Risk (+)
>>> Up
* Datagroup Raised to Reduce at Baader Helvea; PT 69 euros
* Datagroup Raised to Reduce at Baader Helvea; PT 69 euros
* Freenet Raised to Buy at Goldman; PT 30 euros (+)
* Galp Raised to Outperform at RBC; PT 16 euros
* Lululemon Raised to Overweight at Morgan Stanley; PT $303
* Pagegroup Raised to Buy at Citi
* Saipem Raised to Add at AlphaValue/Baader
* Whitbread Raised to Buy at Panmure Gordon; PT 3,500 pence
>>> Down
>>> Down
* Aareal Bank Cut to Sell at AlphaValue/Baader
* Nordex Cut to Reduce at AlphaValue/Baader
* Tesla PT Cut to $1,050 from $1,250 at Jefferies
>>> Initiation
* Tesla PT Cut to $1,050 from $1,250 at Jefferies
>>> Initiation
* Ashtead Assumed Buy at Jefferies; PT 5,000 pence
* BRSA LN Rated New Corporate at Edison Investment Research
>>> Call
* BRSA LN Rated New Corporate at Edison Investment Research
>>> Call
* Citi Strategists Recommend Buying the Dip, Especially in Europe (+)
* FirstGroup a ‘Classic Value Gem,’ Initiated Buy at Berenberg
* PageGroup Valuation Outweights Near-Term Earnings, Citi Upgrades
* Verbund Upgraded at Deutsche Bank on Reduced Windfall Tax Risk (+)