A Bored Ape Lawsuit Won’t Set the NFT Precedent Seth Green Wants
After the actor’s NFT and licensing agreement were stolen, he suggested going to court to win back intellectual property rights. Not so fast.
THE FIRST THING you should probably do if you find yourself in Seth Green’s position is not tweet about how much you’re “looking forward to precedent setting debates on IP ownership & exploitation.”
Green, an actor best known for his pouty portrayal of archvillain Dr. Evil’s disappointing son in the Austin Powers franchise, has become the butt of crypto’s latest bad joke. Earlier this month, Green lost his prized Bored Ape when he fell for a scam and made himself vulnerable to thieves by interacting with a clone of another NFT project’s website. Clone sites can be virtually indistinguishable from the originals, often with only a letter or two missing from their domain names. Green is not the first to lose an NFT this way, and he won’t be the last. Hacking and old-fashioned con artistry are endemic in the magical world of Gutter Cats and Happy Hippos.
What makes Green unique is that he had a lot more riding on his Ape than most members of the Yacht Club. Unlike many NFTs, Bored Apes come with a license to make personal or commercial use of your new primate pal. When you purchase an Ape, you are granted the right to reproduce its image and create derivative works. Green had planned to do just that. For months, he has been developing a series called White Horse Tavern, which combines live action and animation and stars an Ape with a halo and endearing intimacy issues as the titular watering hole’s bartender.
But with the star missing, the show likely can’t go on. According to the Bored Ape Yacht Club (BAYC) terms and conditions, the right to exploit an Ape’s image follows the NFT. After a BuzzFeed article got the internet talking about how White Horse Tavern is now doomed, Green tweeted in response, “Not true since the art was stolen. A buyer who purchased stolen art with real money and refuses to return it is not legally entitled to exploitation usage of the underlying IP.”
Incorrect. This latest Ape affair illustrates the limits of the free, frictionless world promised by crypto—and its many misunderstandings around ownership.
Green’s claim about stolen art would be true if the stolen work of art in question was, say, Jeff Koons’ Rabbit. Whether a buyer purchased the stolen sculpture with “real” or unreal money, Koons would still have the exclusive right to, God forbid, make a life-affirming romantic dramedy starring the quicksilver critter. The default—which applies to both traditional art objects and crypto art—is that the author holds the copyright regardless of what happens to the artwork. But by tying the rights to the NFT, the Apes’ licensing scheme makes them different animals.
It’s not that anyone who goes around stealing simians has carte blanche to launch their own BAYC restaurant. If Green’s Ape were still in the thief’s wallet, Green would still be legally regarded as the “true owner,” with his right to exploit the underlying intellectual property left undisturbed. Unfortunately for Green, the Ape was quickly flipped to a user known as DarkWing84 for $200,000 and the law protects buyers who inadvertently shell out for fraudulently procured property. Assuming DarkWing84 wasn’t in on the scheme, they now own the Ape and the right to make him the star of a TV show about life and love in the big city. While Apes have gone for six figures, $200,000 was probably not a low enough price to put someone on notice that this particular Ape had a sordid past.
Because there is so little law on the books about NFTs and the transfer of intellectual property rights via smart contract, it’s true that a lawsuit over Green’s Ape could set a meaningful precedent. But it wouldn’t be the kind Green seems to expect. If DarkWing84 took Green to court to prevent him from moving forward with White Horse Tavern, they would likely prevail. Green’s only real hope is to steer clear of litigation all together and settle this quietly. Announcing to the world that he has been robbed and crowing about going down in legal history is making such a possibility increasingly remote. Next time you think you’ve got the trial of the century on your hands, please talk to your attorney before you talk to Twitter.
Green’s outspokenness also makes him a highly visible target for future scams. Last week at the NFT conference VeeCon, Green said he had found it “encouraging” to see “how many people approached me and said, ‘We’ve got to do something about this,’” when he went public about the theft. There’s a good chance that many of those concerned souls were fraudsters themselves. Once the cryptoverse knows you’ve been fooled once, you’re likely to be besieged by bad actors hoping they can fool you twice, offering to help you recover your NFT for a fee.
While the possibilities of crypto art continue to inspire artists working in a range of media, tethering rights with off-chain value to on-chain assets continues to be a risky proposition.
Crypto’s Future Is Even More Exciting, and Maybe More Volatile, Than Its Present
Few areas in the tech world are quaking like crypto. BitcoinBTCUSD +0.31% and other cryptocurrencies have lost $1.6 trillion of value since the market peaked last November. Tighter monetary policy and fears of a recession are weighing not only on stocks but also, in the case of crypto, on an asset whose hype has long exceeded its real-world uses. The recent collapse of a major “stablecoin,” which wiped out $40 billion in a few weeks, isn’t instilling confidence in the crypto ecosystem, either.
Still, Bitcoin, the most recognizable cryptocurrency, is up fivefold from its prepandemic days, and the industry has expanded to legions of other blockchains, tokens, and apps. The crypto market, worth $1.2 trillion, now encompasses decentralized finance, or DeFi, platforms for trading and lending; nonfungible tokens, or NFTs, that grant owners some property rights for things like art or video; and stablecoins, which are supposed to act like crypto dollars, holding a peg to a U.S. dollar with the backing of reserve assets.
Yet despite its vast technological and financial potential, the crypto industry is finding it tough to break into the mainstream, as investors retrench into safer assets while regulators bear down with more rules.
Is crypto facing an existential crisis? Or, as the bulls argue, is this a cyclical blip for a technology that will revolutionize markets, transform global commerce, and even form the basis for a new version of the internet called Web3? We asked a panel of industry experts to weigh in at our first-ever crypto roundtable.
Our panelists included Dan Morehead, founder and CEO of Pantera Capital, a crypto hedge fund firm; Eswar Prasad, an economist at Cornell University and author of the book The Future of Money; Alkesh Shah, head of digital asset strategy at Bank of America; and Lisa Shalett, chief investment officer at Morgan Stanley Wealth Management. The roundtable took place in mid-May. An edited version of the discussion follows.
Barron’s: Bitcoin is down 60% from peak prices, and it’s looking like another “crypto winter.” In the prior one, Bitcoin lost 82% of its value and took three years to return to its previous high. Is this cold stretch comparable?
Alkesh Shah: This asset class is correlated with risk assets like technology, and that sector has corrected due to factors like rising interest rates and inflation. For us to see a crypto winter, we would need to see people leaving the ecosystem—less institutional and corporate engagement, less developer activity. Instead, we’re seeing the opposite, with more institutional, corporate, and developer activity. Our view is, it’s not a crypto winter. It’s a consolidation period for a risk asset.
Eswar Prasad: It’s not acting like a unique asset class. The factors that seem to be driving other risky assets, including the path of inflation, interest rates, and liquidity conditions, all seem to be driving crypto. And there aren’t any fundamental valuation models to underpin crypto, especially currencies like Bitcoin with no intrinsic value. The Nasdaq CompositeCOMP +3.33% is down about 30% from its high, and crypto is off 60%. That indicates crypto is going to be much more volatile, with a lot more upside and downside risk.
Lisa Shalett: I wouldn’t say that the asset class is in a “winter.” But it’s in a severe bear market, and questions will have to be answered for it to revisit previous highs. The vulnerability around use cases is increasingly fraught. We’ve seen huge problems with stablecoins—one of the fundamental use cases for crypto. The lack of regulation and true collateralization has been unveiled, and it has exposed risks, not only to regulators but also to participants.
Dan Morehead: We’ve been doing this for 10 years and have seen six big cycles. The weighted average bear-market loss has been 61%, and we hit 62%. It has been going on for 110 days, which is about average for a bear market. This is the first bear market in Bitcoin history in which it has given back more than 100% of the previous bull market, and the first time we’ve had a new low after a bear market. All of those things make me think we’re closer to the end than the beginning.
One of the largest stablecoins, an “algorithmic” coin called TerraUSDUSTUSD –5.95% , recently collapsed, wiping out an estimated $40 billion in the token and a related crypto called LUNALUNAUSD –6.85% . The largest stablecoin, TetherUSDTUSD –0.01% , has been trading slightly under $1. Does this call into question the use for stablecoins as assets that can be relied on to hold their full value?
Shah: There are strong use cases for stablecoins. The economies of a “metaverse” will probably be powered by stablecoins. A retailer might have a digital catalog on a platform powered by a Meta or Microsoft , and could be paid in a stablecoin, with the transaction settled across borders in real time. If you use fiat currency today, it may settle in two to five days. If you have a view that the metaverse is in the first innings, you have to believe in stablecoins.
Prasad: There is a rich irony embedded in fiat-currency-backed stablecoins. The whole point of Bitcoin was to get away from trusting intermediaries such as central banks, commercial banks, or credit-card providers. But to work as reliable mediums of exchange, stablecoins need a centralized validation mechanism. They need to be backed by exactly what Bitcoin was trying to get away from—fiat currencies.
Ultimately, stablecoins meet some important demands of payment systems, domestically and across borders, and when we think about a metaverse. But I worry about whether stablecoins can be trusted to hold their value. Yes, they are collateralized, but who knows what the quality of that collateral is. We had problems with money-market funds, which were supposed to be safe, during the global financial crisis. It’s worrying if an entire financial ecosystem gets built on stablecoins.
Shah: The Terra failure will probably accelerate regulation. Eswar is right: It’s not what Bitcoin’s developers envisioned, but it is programmable money, and you could do all sorts of things with it. PayPal Holdings [ticker: PYPL] and Silvergate Capital [SI] are considering the launch of their own stablecoins, but we need a regulatory framework.
Morehead: The stablecoins that we work with are backed and audited, like USD Coin, or USDC. It would be better if stablecoins were regulated, and I think that will be the model in the future. But the demise of Terra doesn’t say anything about the broader promise of stablecoins or blockchains. Pets.com’s failure didn’t mean that the internet was stupid. It meant that one business model didn’t work.
A migrant who wants to send money across the border doesn’t want to speculate on the price of Bitcoin. They just want to send a payment instantaneously to someone with a smartphone. Banks and money-transfer businesses charge high fees and profit from exchange rates for a cross-border transfer. Stablecoins are incredibly advantaged over money-movement systems like Swift, which are antiquated, slow, and expensive. So, there is a use case for nonvolatile money, like a USDC stablecoin.
But stablecoins are backed by fiat money that is being debased. Inflation is around 8%. That is going to prompt a lot of people to want to save in things other than a fiat currency. Bitcoin and volatile currencies will have different uses than stablecoins.
Processing Bitcoin transactions, or mining, consumes a huge amount of electricity—equal to the amount consumed by countries like Norway in a year—because of the laborious “proof of work” system. More mining is now done with renewable fuels, but a large chunk still relies on fossil fuels, making Bitcoin environmentally controversial. What’s the outlook?
Prasad: My Cornell colleague Ari Juels, who devised proof of work in a 1999 paper, rues its use with Bitcoin. It’s incredibly clever, but it is inefficient and environmentally destructive.
This notion that proof-of-work mining creates jobs, especially with renewable energy, is a mirage if you think about the opportunity cost of energy, which can be put to better use. Blockchain protocols like ‘”proof of stake” are much more energy-efficient for processing transactions and securing a network. But with Bitcoin, I don’t see any incentives for the network to shift.
Shah: Outside of Bitcoin, most other blockchains are acting as operating systems with applications on top, and they are moving away from proof of work. Mining can help spur renewable-energy investment. With renewables, there are periods of time when you have significant excess energy. If you can monetize that excess energy and use that to fund further investment, you will actually do more renewable projects.
Since mining can be turned on and off in under 60 seconds, and the profit margin for mining is around 70%, even at today’s prices, it is a hugely profitable business for a utility. There is a scenario in which every utility that wants to do renewables has a mining arm, because it is something that will help balance the grid and not waste as much energy.
Prasad: The evidence doesn’t support the idea that Bitcoin mining will lead to more renewable-energy production. Yes, mining operations can be switched off in under 60 seconds, but given the huge investments that miners undertake in their equipment, they are on full-blast, 24/7, to be economically viable and maximize profits. Even miners who are ostensibly relying largely on renewables are using renewable resources for much less than half of their energy needs because the mining devices are run nonstop and need a steady supply of electricity.
Morehead: Bitcoin mining consumes an estimated 0.5% of the world’s energy. You can argue about whether that’s too much. But everything has a cost. ESG [environmental, social, and governance] has three letters in it. Definitely, the environment is one of the letters. But then there’s an S and a G. Bitcoin and other blockchains are delivering value in social and governance to literally billions of people. You have to weigh that against the environmental costs.
It’s way too easy to say, oh, Bitcoin’s an ESG killer, when people have all kinds of other things in their portfolios. Aluminum production takes 3% of all the world’s electricity. And old-school gold is the ultimate trifecta in ESG horribleness. It’s strip-mined in the world’s worst kleptocracies, using cyanide leaching production techniques. Unless a company has divested itself from gold, it’s super hard to say that Bitcoin is in the negative.
Are all the resources devoted to Bitcoin supporting something without intrinsic value?
Morehead: Gold doesn’t have much intrinsic value, either. It is used for dental fillings and some welding in satellites, or whatever. But the main use of gold is just to own it. It has been working for 5,000 years. People trust it, and it’s not that volatile. I think digital gold, Bitcoin, will be similar to that. It’s going to take decades to get it there. But the fact that gold doesn’t have any kind of physical property that makes it do anything doesn’t make it bad, either.
Prasad: Dan makes a good point that blockchain technology can have tremendous benefits in terms of improving the S and G in the ESG model. But there is no reason why you need to have proof-of-work mining for blockchain technology. It is not the most efficient way to do it. Just because gold has terrible environmental consequences, that doesn’t translate into a case for digital gold.
Shalett: I want to come back to this idea that Bitcoin, as a pure financial commodity, is going to face growing demand. I want to push back on that. This idea that Fidelity has advanced—that Bitcoin is a viable asset class for 401(k) participants—is going to face extraordinary regulatory pushback. There is no way that the [Department of Labor] is going to permit Fidelity to push this agenda. There are going to be a lot of people on the other side of that discussion. [The DOL has cautioned companies, including Fidelity, against including Bitcoin in 401(k) plans.] Erisa, the law overseeing 401(k)s, restricts clients’ access to wealth-creating asset classes that have very high levels of stability in the alternatives world. So, why accept this kind of asset class that has no intrinsic value, no real use case, and a volatility that is four to five times that of equities?
The second-largest blockchain, Ethereum, is planning a network upgrade in August, aiming to make it much faster, less costly, and more scalable as it switches to a proof-of-stake system. Will that be a game changer for the crypto ecosystem?
Shah: What’s attractive about Ethereum is the actual cash flows. Last year, $10 billion of fees were paid to network operators for processing transactions on the Ethereum blockchain. There’s cash flow here, even if we don’t yet have a model for figuring out the intrinsic value.
Think about Ethereum like an operating system for applications, projects, stablecoins, NFTs. In the past, when you had an operating system like Windows, a company owned it and collected royalties from PC makers. With Ethereum, 70% of the transaction fees will be used to burn tokens, kind of like share buybacks, and 30% will go to stakers—people who own the tokens and use them to help secure the network.
At some point, we will be able to forecast transaction fees for applications and projects on the network. Does this upgrade change everything for Ethereum and the applications on top of it? It makes it more attractive. But there is probably room for other blockchains optimized for other things, like Avalanche or Solana. There probably isn’t room for the 35 to 40 “layer 1” networks that exist today. But there’s room for three to five.
Prasad: Proof of stake is going to be a game changer for the blockchain-based financial ecosystems. Not only will it substantially reduce the transaction fees by increasing the throughput of transactions, but it also is much more scalable. It’s much more efficient in terms of processing times, and that is going to undergird significant changes in blockchain architecture.
But the governance issues for these decentralized architectures are going to be equally important. When you think about the governance of something like Ethereum, whether we might actually have centralization rather than decentralization is an important issue.
If you think about many blockchains proliferating, ultimately some of them will end up winning the race. Regulation might be necessary to prevent these decentralized architectures from leading to more concentration, rather than more decentralization and competition.
Morehead: There’s not going to be one blockchain. There’s not going to be 50. There’s going to be half a dozen, each with different features. That’s why we think there’s a place for something as powerful as Ethereum, but also Ripple for transactions and Bitcoin as digital gold. The web is not one company. There’s a dozen important web companies. The new blockchains are much more scalable—Polkadot and Solana are two that are built to be very scalable. While it’s frustrating that it is so expensive to do a Bitcoin transaction, I don’t think that in a few years’ time there will still be a problem.
If you’re going to invest in crypto, what’s the best way to do it? And does it have a place in a portfolio as an alternative asset when it appears so highly correlated to tech?
Morehead: Using Bitcoin as a proxy for our industry, it has grown at an 11-year rate of 2.5 times a year. We are in a short-term bear market here. But anyone who has owned Bitcoin for three years has made money. The internet itself is 50 years old. We have decades more to go. And it has historically had a low correlation with the S&P 500 index.
We will come to a place where investors decide to invest in things that aren’t interest-rate sensitive—like commodities, gold, oil, agricultural commodities, and things like blockchain assets. Obviously, it hasn’t happened for digital assets in the past three or four months. But I think that’s what will happen.
Shalett: We’re huge advocates of the crypto ecosystem. We think blockchain technology will be transformative and ultimately add value to a portfolio. So, we advocate exposure. But you probably want to do it in a highly diversified way, across the asset-class spectrum, from folks who are in mining, exchanges, custodial services, and such. A way we do that is through hedge funds or private investment vehicles for accredited investors. Crypto probably has a place in portfolios to a maximum of 5% for clients who understand exactly what they own.
Prasad: It’s hard to make the case against holding, say, 2% to 3% of your portfolio in crypto, because even if the value of those assets goes to zero, you’re not out very much. But the upside could be enormous. My worry is about many investors who are latching on largely because of bandwagon effects and the fear of missing out. I worry about many people who seem to be putting their life savings or a large part of it in crypto assets without fully understanding the risks.
Shah: There are so many choices as the sector matures; you don’t have to just buy the sector. There’s a handful of public companies today, but that’s only because we’re beginning this tech cycle. Look at the amount of venture-capital money flowing in—$25 billion last year, up from $3 billion in 2020, on track for $30 to $40 billion this year. There are 278 private companies valued above $100 million, 118 above $500 million. As you think about those companies going public, you’ll probably have, within three years, a $1 trillion sector.
Morehead: The four major blockchains that we’re excited about are Ethereum, Polkadot, Solana, and NEAR. The important point is that the vast majority of interesting tokens out there aren’t cryptocurrencies—they’re like crypto companies that are replacing traditional companies. There are more than 4,000 publicly traded companies in the U.S. We could easily have more than 4,000 tokens.
The Securities and Exchange Commission has approved Bitcoin futures exchange-traded funds. What is the prospect for approval of a Bitcoin ETF that owns the coin directly rather than through futures contracts?
Prasad: It’s going to take a lot to convince the SEC to move forward on a Bitcoin ETF under Chairman Gary Gensler. One issue from the regulatory perspective is that even if the risks are made clear, the fact that products are approved by regulators gives them some legitimacy, which convinces retail investors to believe these markets are overseen in a way that the risks can be contained. There is a compendium of issues that will make regulators take a long, deep breath before they move forward on this.
Morehead: The SEC has been using an extreme standard for Bitcoin relative to other crazy ETFs that exist. SEC Commissioner Hester Peirce makes the argument that the SEC has approved commodity ETFs, like one for palladium, that are based on unregulated spot markets. Bitcoin trades $70 billion a day on hundreds of exchanges in dozens of countries. It is way too big to be manipulated.
Even if there are some issues with data feeds or market manipulation, they are orders of magnitude smaller than the wealth destruction that has been caused by the Grayscale Bitcoin Trust [GBTC]. Retail investors were buying that at an 83% premium, and now it’s at a 37% discount. I can’t see how it serves the public good to allow that and not have a Bitcoin ETF.
Shalett: Part of me worries that when an ETF vehicle is made available, it will just be one more avenue that allows investors who don’t have the knowledge and sophistication to speculate. I worry that it would make the asset class even more volatile, not more efficient.
One positive for Bitcoin is that we’re at the trough of a demandsupply phenomenon. The developers of Bitcoin agreed to a fixed rate of supply, and every four years the amount of supply that will be added to circulation is halved. In the next 18 to 24 months, there are going to be fundamentals around scarcity that are more advantageous. But investors and regulators are getting more knowledge of the risks in the ecosystem, and that is going to affect valuations.
What are your thoughts on Web3—the idea that we could have new networks and apps based on decentralized blockchains and tokens?
Shah: Web3 is a concept, just like software, that isn’t going away. Blockchains will act as operating systems for new apps and services. Stablecoins will transfer value across borders. NFTs will potentially provide ownership of real goods in the metaverse, which will be powered by Web3.
Morehead: The whole concept of Web3 is about replacing companies like Spotify Technology [SPOT] or Airbnb [ABNB] with decentralized versions. We’re excited about a range of projects that are competing with the data monopolies. An example would be Audius, which is a sharing protocol that helps recording artists get more money. The users get paid for contributions they’re bringing by uploading songs. Audius already has six million monthly active users. We invest in about 80 different protocols that are doing these different business models.
We’re used to massive data monopolies, like Facebook [ Meta Platform ; FB] and Airbnb, sucking an enormous amount of value in their verticals. Those can be decentralized. Social media, like Facebook, will probably take a decade. But ultimately, we’re going to have a cooperatively owned and cooperatively governed version of the data monopolies like Facebook.
It’s going to be a wonderful world, way better for everybody, because these current owners can be pretty toxic. With decentralized governance, better decisions will be made, democracy won’t be destabilized, and false information about vaccines won’t be sold. It’s going to take a while, but that’s where we’re heading. It is one of the most obvious trends I’ve seen in my 35-year career.
Prasad: I worry that this decentralization and extensive fragmentation is not necessarily going to lead to better economic or social cohesion. I can imagine many of these technologies being co-opted by authoritarian, ostensibly benevolent governments, or large corporations, to accrue even more economic power. While these technologies do provide a pathway to desirable objectives, such as more democratization of finance, I worry that without guardrails in place, it will not lead us to some sort of nirvana. That outcome might be subverted toward a much darker place.
Shah: There is an automatic gravitation towards centralization. And we want that. Regulators want that centralization because they want governance and want to hold somebody accountable. The next step for the web is going to be semi-decentralized. And hopefully, Web4, Web5, Web27 will move to a world where it’s more decentralized. But it’s going to take a long time. The beauty of these tools is, they help decentralize the current internet a little bit more.
What is the outlook for crypto regulation, and do you expect governments worldwide to crack down on this technology and trading?
Shah: It’s not going to be a global regulatory framework because countries can’t agree on almost anything. Hopefully, there will be certain frameworks and countries adopt them. Our long-term view is that a regulatory framework that encompasses this ecosystem, the product, software, or services, is going to be hugely beneficial.
Prasad: The moment DeFi starts touching the regulated financial institutions, the regulators will become especially concerned. Stablecoins are going to face serious regulatory oversight. And if you have a central bank digital currency, or CBDC, it’s not clear what the use is for a stablecoin. We may get to a world where highly regulated stablecoins coexist with CBDCs. But if we move to a world where CBDCs become easily accessible within countries and for cross-border transactions, the use case for many stablecoins could be significantly undercut.
Shalett: I think we’re going to hear a lot of noise around Erisa. Given the volatility of the crypto asset class, to think that an Erisa fiduciary is going to suggest that Bitcoin should be an option in a 401(k) menu is a bridge too far. Most 401(k) menu designs do not include things that you and I might think are mainstream—like gold or energy infrastructure assets or real estate investment trusts. To this day, there are 401(k) plans that are debating whether emerging markets should be a choice on their platform.
Investors don’t really know what they’re buying?
Shalett: A lot of investors don’t even comprehend the elements of a Bitcoin transaction. If you’re buying on an exchange, what type of an exchange is it? Where is it going to be custodied? Who’s going to have access to it? Who are you actually trading against?
The vast majority of people transacting on these exchanges today couldn’t answer a single one of those questions. There’s no definition of “best execution.” In many cases, people don’t know where their assets are custodied. There are still a huge amount of questions around buying and securing a cryptocurrency asset.
We’ll need another roundtable to discuss all of that. Thanks, everyone.
Write to Daren Fonda at daren.fonda@barrons.com
VMware Should Not Expect a White Knight; Wish Sidelined as Dollar Stores Rally
Broadcom made official its plan to acquire VMware in a cash-and-stock deal worth around $61 billion. The deal underscores the degree to which CEO Hock Tan has transformed Broadcom from a maker of networking chips into a formidable player in enterprise software.
The agreement includes a “go-shop” provision allowing VMware to solicit bids from other companies until July 5. But Broadcom is paying a rich premium, which may dissuade other bidders. The deal works out to about $138 per VMware share, about 44% above where VMware was trading before word of the deal leaked last weekend. And VMware was starting from a relatively higher base: Its shares were down 18% this year through last Friday, compared with a 28% decline for the Nasdaq.
Broadcom is likely expecting to make the deal pay off in part by cutting costs at VMware, as it has done with past acquisitions. David Bicknell, principal analyst at GlobalData, said head count at CA Technologies fell 40% after Broadcom bought the software company in 2018, “and employee termination costs were also high at Symantec,” a maker of security software that Broadcom bought the following year.
But don’t cash those checks just yet. As we reported earlier this week, the deal could face an antitrust challenge from U.S. regulators. The Federal Trade Commission is already investigating Broadcom for allegedly forcing customers into exclusive agreements, making it difficult for them to shop around, less than a year after the company settled an FTC case involving similar allegations of anticompetitive conduct regarding its customers.
Wish for Something Better
Could Wish parent ContextLogic get a recessionary lift? The operator of the Wish app, which features cheaply made items displayed in an Instagram-like feed, has often been described as the dollar store of the internet. Brick-and-mortar retailers like Dollar Tree and Dollar General have thrived in past downturns, particularly 2007–08, as cost-conscious middle-income consumers have sought out deals. For that reason, their stocks have proved particular favorites for investors when the economic outlook darkens. That seems to be the case again.
Dollar Tree on Thursday reported that its net income increased 43% to $536 million for the quarter ended April 30—even after lifting prices on most items past a dollar (to $1.25!)—and it raised its sales outlook for the year. Dollar General’s performance was weaker: Profit slipped 18% to $553 million. But it also hiked its sales outlook for the year. Stocks for both rallied more than 13% Thursday.
Wish shares, however, caught only a tiny bit of that tailwind, rising 1% to $1.63. (Its market cap of $1 billion is now just a tenth of its highest private-market value.) It’s not hard to see why investors have viewed Wish with more skepticism than they have physical retailers, even though those chains are also struggling with labor shortages and rising wages.
Even before talk of an inflation-driven recession heated up this year, Wish’s revenue had spiraled lower, as the end of pandemic shutdowns and reduced spending on marketing caused some customers to flee. Revenue fell 18% last year and it booked a $361 million loss. Its first-quarter results did not improve the picture much: In early May it announced negative free cash flow of $148 million as revenue sank 76%.
Wish’s CEO, Vijay Talwar, appointed after founder Piotr Szulczewski stepped down as CEO late last year, is now heading up a turnaround that involves paring down to a much smaller workforce and employing new strategies to keep its users from bolting. In theory, a recession should be good for a consumer seller like Wish. In reality, its problems may be recession-proof.—Laura Mandaro
Alibaba’s Feint
Don’t get too excited about a recovery in Chinese tech based on Alibaba’s results. The Chinese e-commerce giant said revenue for the quarter through March rose 9%, helping drive a 13% rally in shares in New York. But the results largely predate China’s severe Covid-19 lockdown in Shanghai starting in late March, which has hit supply chains for manufacturers and retailers. A bad sign: Alibaba didn’t provide an annual revenue forecast for the fiscal year ending in March 2023.—Shai Oster
In Other News…
Instagram plans to slow the pace of hiring in the second half of the year, Bloomberg reported.
The U.K.’s Competition and Markets Authority has opened a new investigation into Google’s ad business.
Dell said its quarterly revenue rose 16% to $26.1 billion, boosted by sales of business PCs.
New From Our Reporters
A Top China VC Firm Struggles to Raise Funds After 10% Return, U.S. Investor Fears
To Combat Declining Staff Morale, FTC Chair Khan Lifts Public Speaking Ban as Deputy Issues Apology
Creator Economy Winter, TikTok’s Rivals and NFTs: Highlights From the Creator Economy Summit
What We’re Reading
A Profile of Stripe’s Founders
Q&A With Epic CEO Tim Sweeney
Car-Insurance Bills Are Rising, With More Increases to Come
Rates up as much as 20% as insurers struggle with inflation
Car owners need to buckle up: Higher premiums are starting to arrive as insurers get state approval for rate increases to offset inflation and an increase in serious crashes.
Rates are rising as much as 20% in some locations, as insurers seek increases to compensate for what they believe will be more sustained inflation. Consumers are starting to see the impact when their policies, which typically run for six months, come up for renewal.
Some state insurance departments, including California’s, are pushing back or going slow on approving the increases.
“These cost increases are going to be here for a while,” said Allstate Corp. ALL 2.39% Chief Executive Tom Wilson, speaking about inflation in repairing and replacing vehicles. “So we’ve been raising prices pretty aggressively, as well as reducing our expenses.”
Car insurers have struggled as driving and accidents have rebounded from pandemic lows. Car repairs and replacement vehicles are more expensive. Insurers are paying for longer rental periods than they used to, amid shortages of body-shop technicians and delays in getting repair parts, among other cost pressures. In addition, traffic fatalities surged in 2021 to a 16-year high.
During the first quarter, Allstate increased rates in 28 states an average of 9.3% for its Allstate car-insurance brand. An Allstate senior executive told analysts in an earnings call in early May that, “given the ongoing inflationary pressure, we have increased the magnitude of rate increases we expect to take in the rest of 2022.” Allstate’s underwriting income for its car- and home-insurance unit fell 83% to $280 million in the quarter.
From the middle of last year when some insurers began raising rates aggressively, the industry through early May obtained increases on about 61% of its base of personal-auto premiums, said Elyse Greenspan, an analyst with Wells Fargo Securities. For now, the rate increases are “not enough to offset the elevated loss trend.”
The increases vary by state, with larger rate hikes by big carriers ranging from 7% to 20% as of March, according to filings reviewed by S&P Global Market Intelligence. The average U.S. car-insurance rate was $1,529 last year, according to Zebra, a price-comparison website.
So far, regulators in California, the nation’s most populous state, haven’t approved any recent rate-increase requests. The regulators are concerned partly that Covid-19 premium-relief programs offered by car insurers in general were inadequate, said Deputy Commissioner Michael Soller.
Nationally, those programs spared consumers about $14 billion in payments during early months of the pandemic in 2020 when driving plummeted and insurers enjoyed outsize profits.
The California department is reviewing data from Allstate and other carriers deemed to have the largest gaps between what the state believes they owe consumers and what has been refunded “to determine how best to close the gap,” Mr. Soller said.
Allstate provided average 15% premium reductions to personal auto-insurance customers for three months in 2020, allowed payment delays and took other steps to help policyholders. “From our standpoint, we gave our shareholders $1 billion back, and we were not in any way, shape or form required to do that,” Mr. Wilson said. “We did it because we thought it was the right thing to do.”
Mr. Wilson said that insurers don’t sell policies “to give their money away,” and that most regulators “understand and are supporting price increases.”
As they seek higher rates, “some insurance companies have slowed new-business growth and tightened underwriting standards,” most notably in California, said Matthew Carletti, an analyst with JMP Securities.
The U.S. personal car-insurance industry has turned an underwriting profit in just three of the past 10 years, according to Moody’s Investors Service. That means some insurers over much of the past decade annually sent more money out the door in claims and other expenses than they collected in premiums, before accounting for income earned by investing premiums, though results vary widely across companies.
Many carriers also have other lines of business and operations that have helped them generate profits overall.
When regulators deny or delay approvals for justified increases in the name of consumer protection, it “will have the exact opposite effect on policyholders by threatening the availability of coverage and the solvency of companies providing it,” said Neil Alldredge, president of the National Association of Mutual Insurance Companies.
Consumer activists see it differently. Birny Birnbaum, executive director of the Center for Economic Justice, said that some “regulators seem to uncritically approve rate increases.”
One noticeable element of the push for higher premiums may be a decline in advertising for car insurance. Insurers don’t want to attract too many new customers at rates they consider insufficient, and cutting marketing expenses can reduce costs to boost results.
Progressive Corp. PGR 3.02% Chief Executive Tricia Griffith said in the company’s first-quarter call in May that once rate increases are approved, the company will boost marketing to spur growth.
“We want to be open for Californians and we’ll work closely with the regulators to make that happen,” she said. Progressive said it provided more than $1 billion in premium credits in 2020, among other actions aiding policyholders.
With Elon Musk’s Twitter Bid in Flux, Some Tesla Fans Say Enough Already
Electric-car maker’s stock has tumbled around 30% since billionaire disclosed his stake in social-media company
Elon Musk’s Twitter Inc. TWTR 1.64% takeover comments haven’t just riled the social-media company’s executives and staff. They have also frustrated some of the billionaire’s loyal Tesla Inc. TSLA 7.33% backers.
The electric-vehicle maker has lost roughly 30% of its value since April 1, as the will-he-or-won’t-he drama around Mr. Musk’s investment in Twitter—and eventual $44 billion deal to take over the social-media company—has played out. The tech-heavy Nasdaq Composite fell around 15% in that time.
The episode has sparked concerns even among some fans of the Tesla chief executive that he might risk stretching himself too thin. Mr. Musk also runs rocket company SpaceX and helped start a tunneling enterprise and a neuroscience startup working on brain-implant technologies. Now with Twitter, some Tesla supporters are concerned that he could lose focus.
“I wish he would walk away,” said Gary Black, managing partner of the Future Fund LLC, which owns roughly $50 million worth of Tesla, according to FactSet. Mr. Black, a Tesla booster, said he views Twitter as a distraction that is likely to demand more of Mr. Musk’s time than the billionaire expects.
A close follower of Tesla recently tweeted at Mr. Musk and the Twitter CEO: “Elon, Twitter is an unnecessary distraction. Just focus on Tesla.”
Mr. Musk has sought to quell such anxiety. “To be clear, I’m spending <5% (but actually) of my time on the Twitter acquisition. It ain’t rocket science!” he tweeted last week. “Tesla is on my mind 24/7.”
Tesla didn’t respond to a request for comment.
Concerns Mr. Musk may have taken on too much aren’t new, and he has been able to build Tesla into the world’s most valuable auto maker while also running Space Exploration Technologies Corp., as SpaceX is formally known.
Tesla investors have digested Mr. Musk’s Twitter takeover effort in waves. The company’s stock fell around 8% from April 1—the last trading day before Mr. Musk disclosed that he had taken a large stake in Twitter—through April 25, when Twitter accepted his bid to take over the company. The Nasdaq Composite slid roughly 9% in that time.
Tesla’s tumble continued from there. First, Mr. Musk sold roughly 9.6 million Tesla shares, worth around $8.5 billion, in the days after striking the Twitter deal. Then, facing the continued erosion of Tesla’s stock price, he injected fresh doubt into the Twitter deal, saying that the planned acquisition was “temporarily on hold” citing concerns about fake accounts, though he added at the time that he remained committed to the acquisition.
Twitter has said it is proceeding with the transaction as agreed.
Mr. Musk, whose fortune is made up largely of Tesla stock, disclosed on Wednesday that he no longer plans to rely on a margin loan backed by Tesla shares to finance the Twitter deal. He committed additional equity instead, saying he was seeking additional outside financial backing.
The recent slide in Tesla’s stock price has prompted some, including Mr. Black, to press Tesla to repurchase its own shares. Buybacks can project confidence to investors and support stock prices by reducing a company’s share count. Tesla was sitting on roughly $17.5 billion in cash as of the first quarter.
Tesla didn’t respond to a request for comment about whether it was considering buybacks. Asked in April about what Tesla plans to do with its cash long-term, Chief Financial Officer Zachary Kirkhorn said the company was investing in its new factories and products.
It couldn’t be learned whether the comments of some Tesla loyalists are affecting Mr. Musk’s thinking, or if they reflect the views of larger shareholders.
Earl Banning, a Dayton, Ohio, psychologist and Tesla investor, described himself as hesitant about Mr. Musk’s pursuit of Twitter.
“He’s already a lightning rod, and it makes him more of a lightning rod,” said Dr. Banning, a Tesla enthusiast whom Mr. Musk interacts with regularly on Twitter. That hasn’t spurred Dr. Banning to sell Tesla stock, though.
“Elon’s going to continue being Elon,” Dr. Banning said. “I feel that as a long-term shareholder, it will come back to where it should be because they’re executing. They are selling cars, and they’re profitable.”
Tesla reported a record $3.3 billion quarterly profit in the three months ended in March.
Twitter hasn’t been the only issue for Tesla investors to digest. Supply-chain bottlenecks and Covid-19 lockdowns in China have constrained the electric-car company’s sales. Tesla in April sold just 1,512 vehicles made at its Shanghai plant, down 94% from a year earlier.
Analysts surveyed by FactSet expect the company to deliver roughly 292,000 vehicles globally in the three months ending in June, down from 310,048 vehicles in the first quarter. That would mark Tesla’s first quarter-over-quarter decline in deliveries in more than two years.
Meanwhile, Mr. Musk has waded further into politics, saying that he expected partisan attacks against him and that he plans to vote Republican moving forward.
“Unless it is stopped, the woke mind virus will destroy civilization and humanity will never reached Mars,” Mr. Musk tweeted last week.
Last week, news publication Insider reported that SpaceX paid an unidentified flight attendant $250,000 in 2018 to settle a sexual misconduct claim against Mr. Musk, the company’s chief executive. Mr. Musk responded on Twitter, calling the accusations “utterly untrue.”
SpaceX President Gwynne Shotwell told company staff in a subsequent email that she personally believed that allegations made against Mr. Musk were false. Neither she nor Mr. Musk addressed whether a settlement was paid. Ms. Shotwell said in the email that SpaceX doesn’t tolerate harassment of any kind.
Some Tesla devotees see opportunity in the share-price decline. John Stringer, who runs a Tesla owners club in Silicon Valley, said he has increased his Tesla holdings in recent weeks.
“This is kind of what comes with the territory,” Mr. Stringer said of Mr. Musk’s unpredictable tweeting and his corporate juggling act.
Lidar exposes the remnants of an overgrown ancient civilization in the Amazon
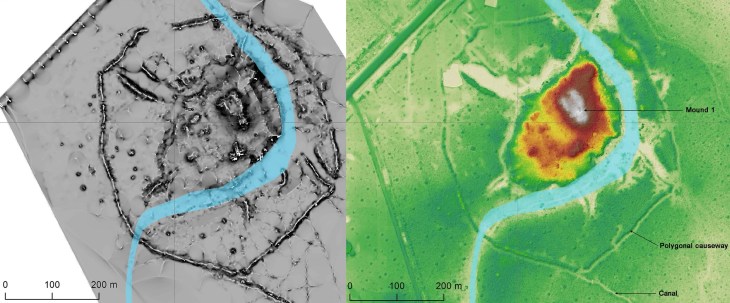
Image Credits: Prümers et al.
It’s Friday and the world is falling apart, so let’s just take a short mental health break with some interesting news out of the field of archaeology, where tech is enabling some fascinating new discoveries. A new lidar-powered analysis of land in the Amazon basin has provided evidence of a previously unknown urban center of “mind blowing” complexity.
To be clear, that doesn’t mean ancient aliens or long-lost technology, just that it far exceeds the expected levels of organization and population that scholars considered possible for Amazonians of 1,500 years ago.
“Nobody expected that kind of society in that region … pyramids 20 meters high,” said Heiko Prümers, of the German Archaeological Institute, in a video produced by Nature. “The whole region has been so densely habitated during the pre-hispanic time, that’s incredible to believe. There is a new civilization, new culture, waiting for us to study them.”
Until recently it was thought that the Amazon had nothing but smaller tribes until the arrival of Spanish and Portuguese explorers — a typically Eurocentric view increasingly challenged by new scholarship. In this case Prümers was intrigued by mounds called lomas, hidden beneath the vegetation but hinting at something greater. Excavations showed that these were not rubbish dumps (as some thought) but organized areas for graves, rites and other things indicative of a complex, hierarchical society.
But finding bumps on the ground under the canopy of a rainforest is far from easy, so in 2019 they set out to scan the area by helicopter, using lidar to reconstruct the contours of the surface below the trees. This technique has proved highly fruitful recently, with whole Mayan cities and even a kilometer-long artificial earthwork uncovered that way.
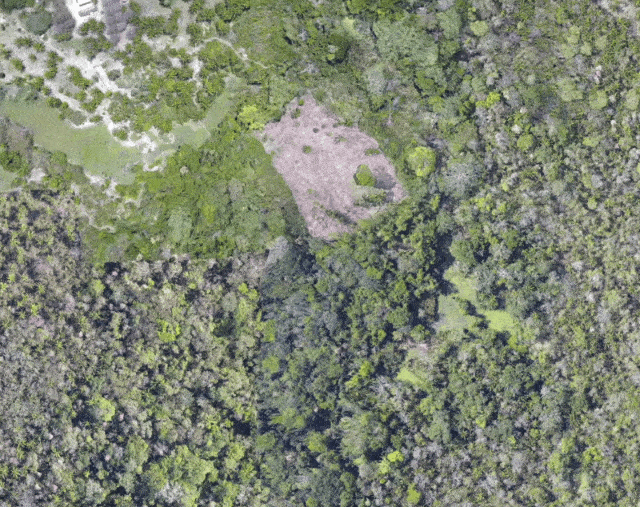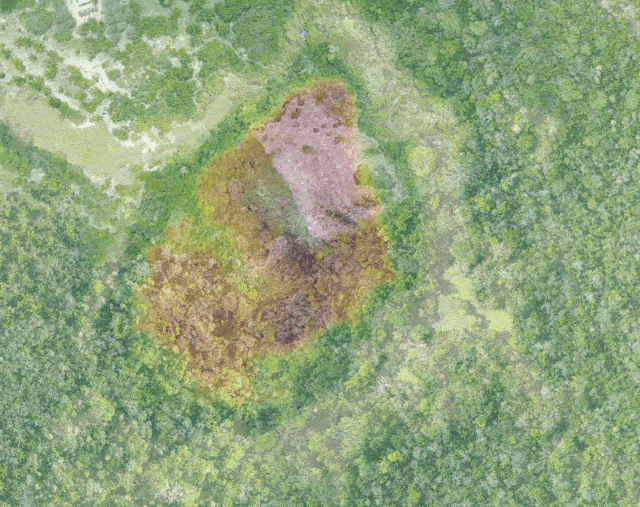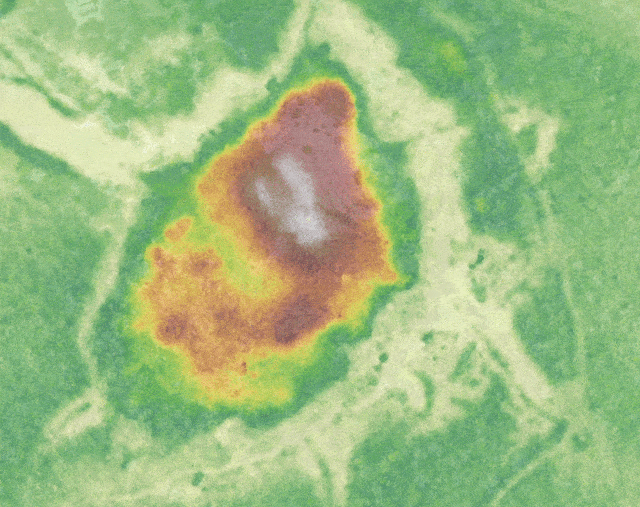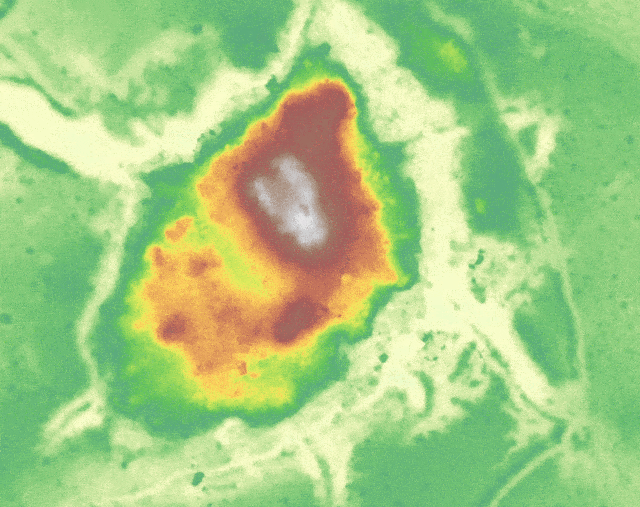
Image Credits: Prümers et al.
Lidar beams pass between the leaves and branches, bouncing back to provide a surprisingly detailed look at the height of the ground beneath. And more than ever this data can be quickly collected and analyzed to produce a 3D point cloud easily inspected for hidden structures.
What the team found was more than a few new lomas: platforms, huge pyramids, defensive structures, reservoirs and canals and more connecting what appeared to be hundreds of settlements of various sizes. This flies in the face of assumptions that local peoples were nomadic or foraging cultures, not sedentary and agricultural ones.
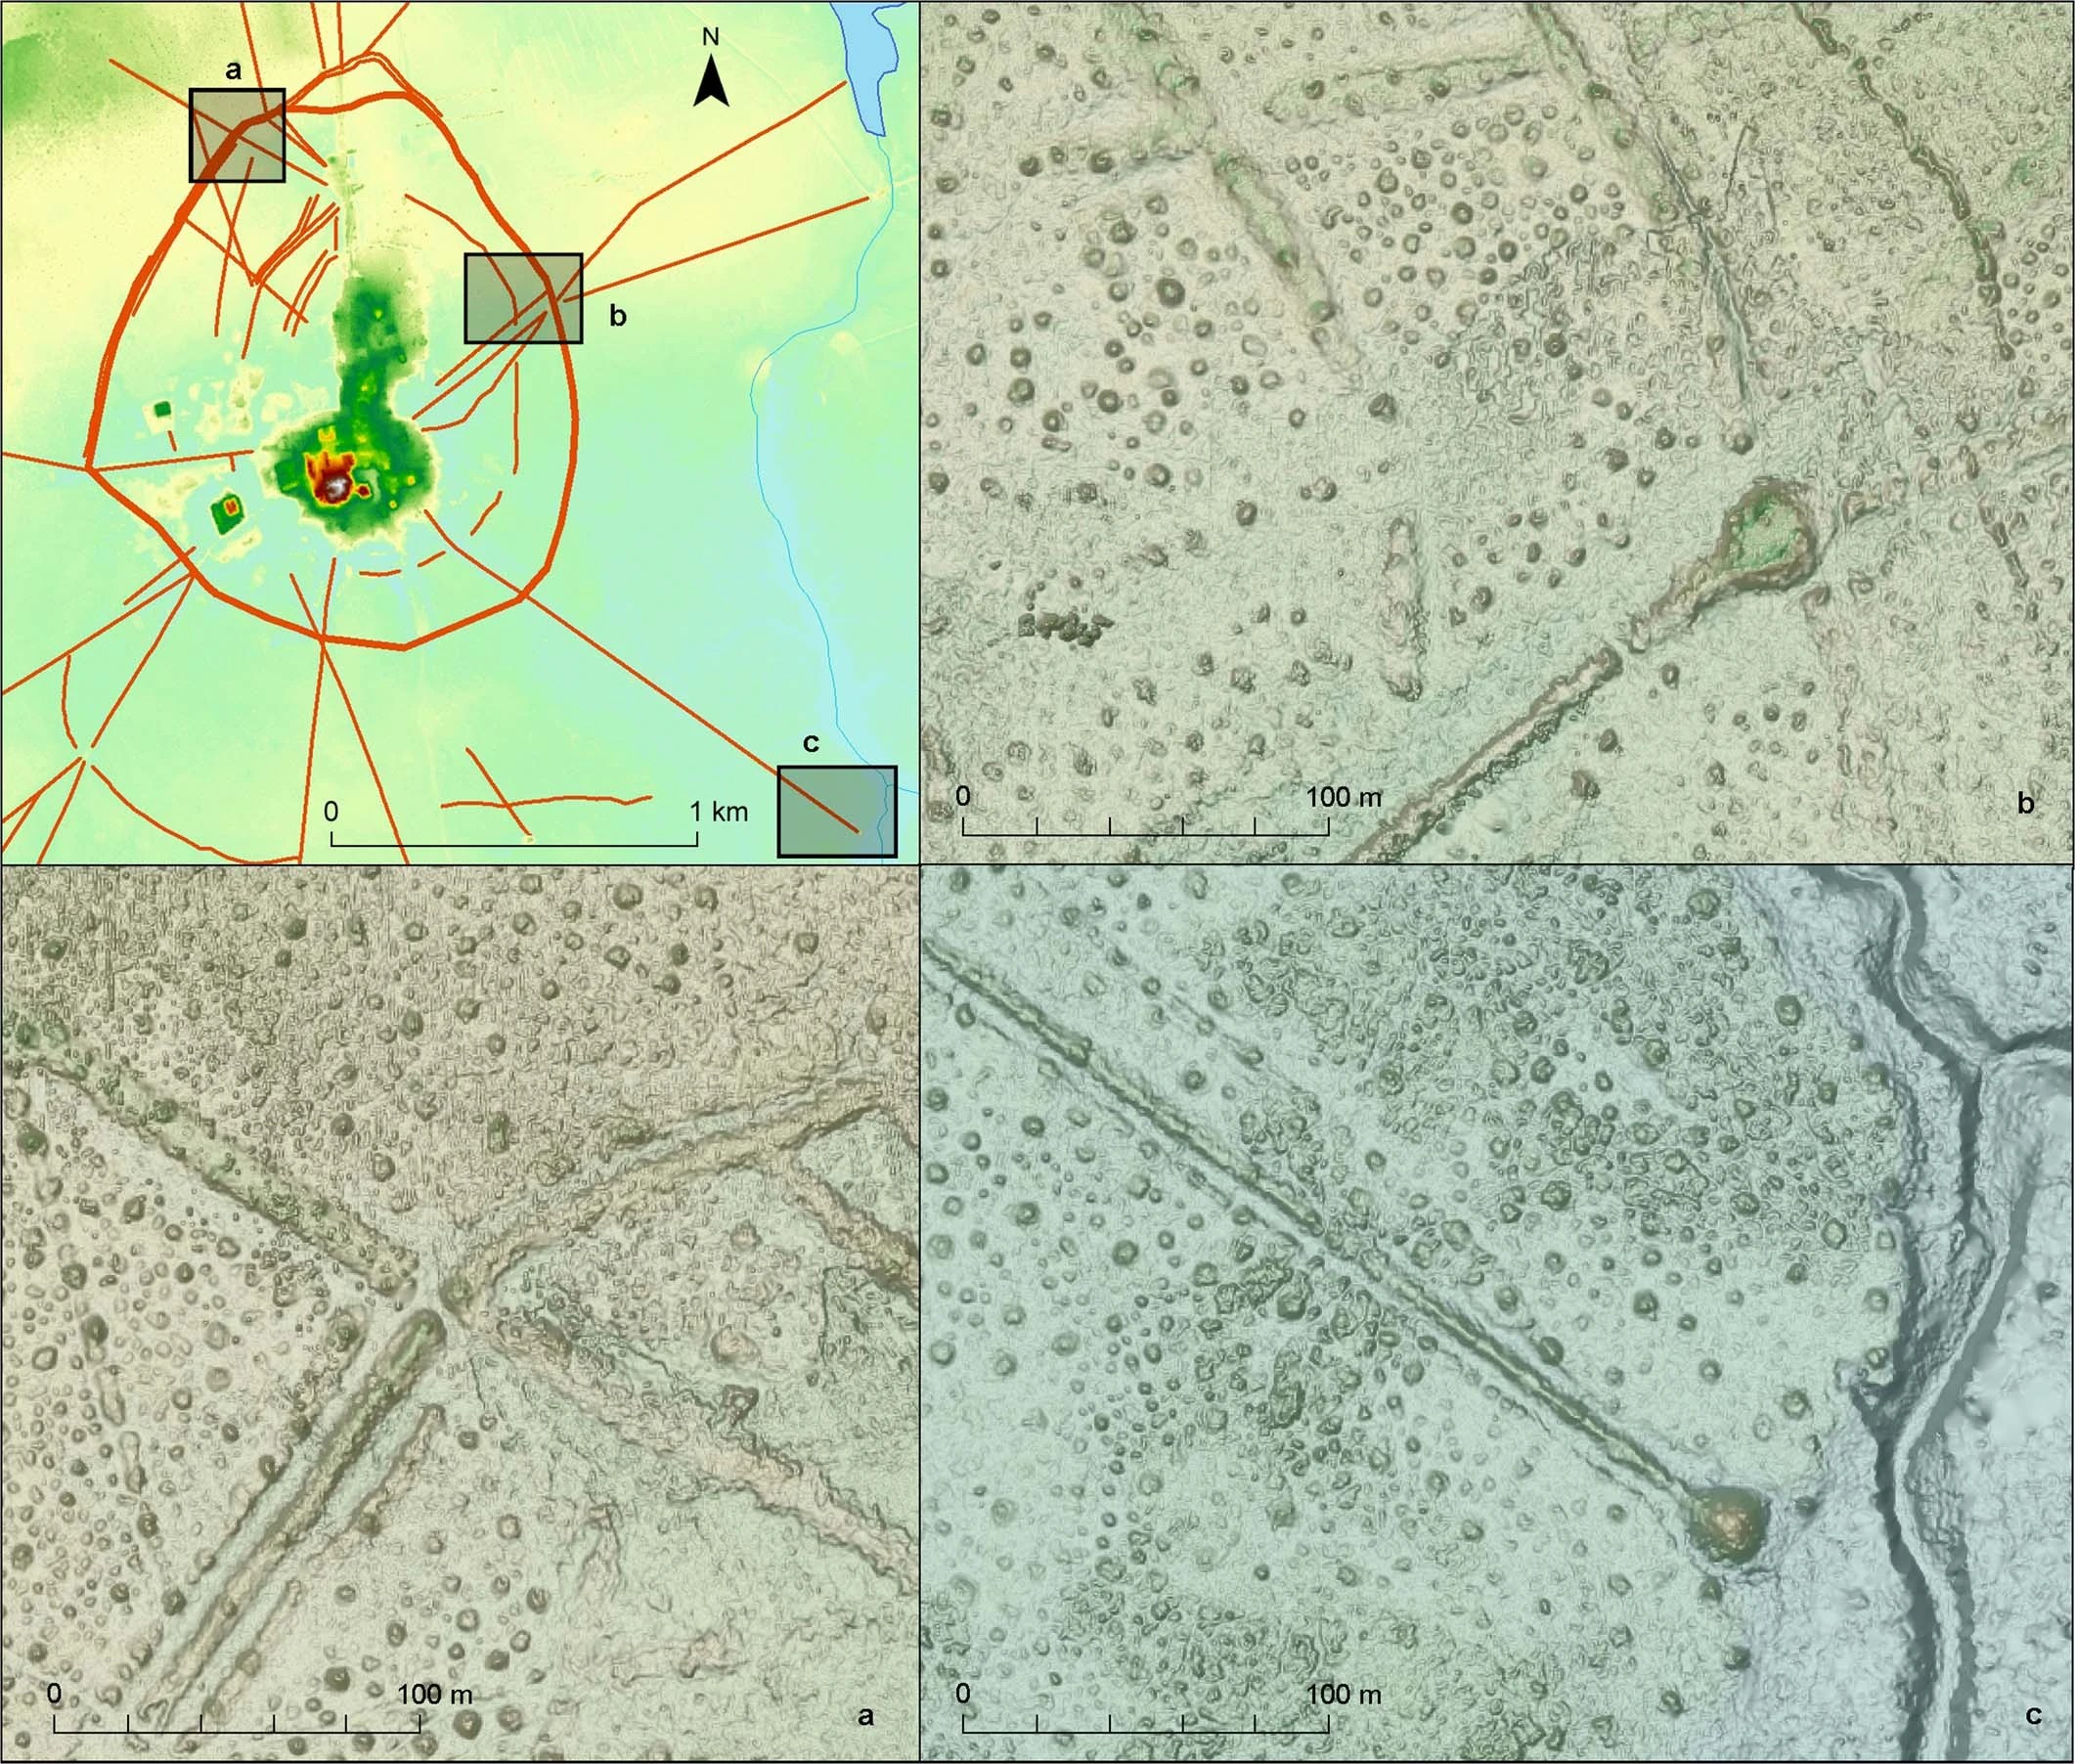
Lidar imagery of features discovered in the Casarabe city using lidar. Image Credits: Prümers et al.
The Casarabe culture, as it has been named following its discovery, remain mostly a mystery. After all, its existence was only recently confirmed — but this provides a starting point for further investigation.
“We need to be patient and wait for further excavations in those sites to be able to explain something of what we are seeing right now,” said Prümers — though it’s work of a scale and duration that may require him to bequeath it to his students. “For me, who has worked over these last 20, 25 years in that region, it’s sort of a dream coming true! To say at the end of my career that, yeah, we have a new culture? That’s nice, I admit that.”
As in so many domains, tech is an enabler (Prümers estimated it might have taken 400 years of digs to unearth all the things they found using lidar) but can never replace the hard work and expertise that humans bring to the equation. You can read the full paper (it’s open access) in Nature.
Link to Video : https://bit.ly/38ZrSBM
The Week’s 10 Biggest Funding Rounds: Clearway Energy Group Powers Up With $1.6B, SpaceX Receives Galactic-Sized Raise
Companies in the energy sector seem like the big winners this week. But startups in and around the enterprise software space also made a big splash with investors. Despite that, the chatter this week mostly focused on the large SpaceX raise because, well, it involves both space and Elon Musk.
1. Clearway Energy Group, $1.6B, renewable energy: The biggest round this week was a large corporate one involving San Francisco-based renewable energy developer Clearway Energy Group. France-based TotalEnergies SE bought half of Global Infrastructure Partners’ stake in the firm for a cool $1.6 billion investment. Clearway is one of the largest developers and operators of clean energy in the U.S. The company has more than 5 gigawatts of wind, solar and energy storage in operation currently. The move is another illustration of energy companies looking to diversify into newer green energy assets as carbon emissions become a top concern globally. The agreement represents TotalEnergies’ largest investment in U.S. renewables to date. In 2011, TotalEnergies bought a controlling stake in San Jose, California-based solar power company SunPower.
2. SpaceX, $1.5B, space travel: Remember when Elon Musk wasn’t in the news every day? Neither do we. This week, along with the neverending Twitter purchase, his SpaceX company made headlines after it was reported the company was raising at least $1.5 billion, according to The Wall Street Journal. The Hawthorne, California-based company did not confirm the new round nor the new valuation of around $125 billion. SpaceX raised $1.9 billion in funding in April and has raised a total of $7.8 billion in funding, according to Crunchbase data. Previous investors in the company include NASA, Stack Capital, Bracket Capital and the United States Space Force, among others.
3. Semperis, $200M, cybersecurity: Private equity loves cybersecurity—just look at Thoma Bravo’s deal last summer for email security firm Proofpoint. This week, Hoboken, New Jersey-based Semperis saw some of that love, scooping up a $200 million Series C led by PE giant KKR. Semperis allows companies to secure their active directory both on-premise and in the cloud, as well as offering response tools for identity-focused incidents. Despite the downturn in both the private and public markets, cybersecurity has held strong with growing fears of ransomware and other attacks. Founded in 2014, Semperis has now raised $240 million, according to Crunchbase.
4. Clear Street, $165M, fintech: Now may not be the best of times for the market, but that doesn’t mean people don’t want better access to it. New York-based Clear Street is attempting to offer that after raising a $165 million Series B led by Prysm Capital at a valuation of $1.7 billion. Launched in 2018, Clear Street started with a prime brokerage platform for institutional investors and now will use the new funding to expand to serve fintechs, market makers and other professional traders. In a release, the company said its architecture processes more than $3 billion in daily trading volume. Clear Street has now raised nearly $460 million, according to Crunchbase.
That brings us to an odd four-way tie for the fifth-largest round of the week—with all raising $150 million.
5. (tied) Cribl, $150M, big data: Data observability was big this week with investors. San Francisco-based Cribl raised $150 million in Series D funding led by Tiger Global Management. Cribl’s platform allows users to understand the health of their data and control it. The new round comes less than a year after the company’s nearly $210 million Series C last summer and brings its total funding to $400 million, according to the company.
5. (tied) Firework, $150M, e-commerce: San Mateo, California-based livestreaming commerce and digital platform Firework closed a $150 million Series B led by the SoftBank Vision Fund 2. Founded in 2017, the company has now raised nearly $270 million, according to Crunchbase.
5. (tied) Mainspring Energy, $150M, energy: Menlo Park, California-based onsite power generation provider Mainspring Energy closed $150 million in the first stage of its Series E fundraise led by global growth equity investor Lightrock. Founded in 2010, according to Crunchbase data, the company has now raised nearly $330 million.
5. (tied) Motive, $150M, logistics: San Francisco-based Motive raised a $150 million Series E co-led by Insight Partners and Kleiner Perkins that values the automated operations platform developer at $2.85 million. Motive, formerly KeepTruckin, offers an AI-powered platform that helps improve driver safety and track fleet spending. The platform also offers other logistics and management tools. Founded in 2013, the company has now raised a total of nearly $570 million, according to Crunchbase data.
9. Monte Carlo, $135M, enterprise software: Another company in the data observability space to make the list this week is San Francisco-based Monte Carlo. The company, which tracks data reliability, closed a $135 million Series D led by IVP, valuing the company at $1.6 billion. Founded in 2019, the company has now raised more than $235 million, according to Crunchbase.
10. Booster, $125M, energy: San Mateo, California-based mobile energy delivery firm Booster raised more than $125 million in a Series D led by Rose Park Advisors. Founded in 2015, the company has now raised nearly $214 million, according to Crunchbase.
Big global deals
With the monster rounds raised by Clearway and SpaceX, only one round outside the U.S. broke into the top five rounds globally.
- London-based Bloom Financial, which helps finance internet brands, closed a Series A worth nearly $380 million.