(ZH) Crackhead MILF And Incest Porn: Hunter Biden Search History Revealed; Texte


Crackhead MILF And Incest Porn: Hunter Biden Search History Revealed; Texted Pornhub Link To 'Dad'

Hunter Biden, who dated his late brother's wife Hallie, had an obsession with 'MILF crack cocaine porn,' lonely widows, and incest fantasies, according to his internet search history covering just six days before his laptop broke in March 2019.
According to the Daily Mail, Hunter also loved filming himself banging prostitutes and then uploading them to his own Pornhub account, "RHEast," none of which showed Hunter's face.
In one instance, Hunter texted a Pornhub page to a phone number saved in his contacts as "Dad" on Oct. 22, 2018 - however the Mail points out that Hunter and Joe Biden used each other's phone numbers at various times - so it's unclear if Joe was the intended recipient.
Then we get to widow porn...
Hunter, who had a controversial relationship with his brother's widow, also repeatedly searched Pornhub for videos involving widows, including 'Homemade widow porn', 'Homemade lonely widow porn' and 'Lonely widow porn'.
The Biden son, who was 49 at the time, searched for porn videos involving teenagers according to his browsing history.
Videos he visited included '18 Yrs old and really Good at Riding D***', 'TEENFIDELITY Country Girl Raylin Ann C****pie' and 'Lucky Foreign Student Stripped & F***ed by Horny Teen Pals'. -Daily Mail
And Hunter's seven searches for "Washington DC Milf Crack Cocaine" right before he dropped the laptop off for repair.

Hunter's Pornhub stats show he's watched 3,361 videos, had 24 subscribers and 66 'friends' on the site. He went under the name "Harper," a 45-year-old single, heterosexual male living in Paris.
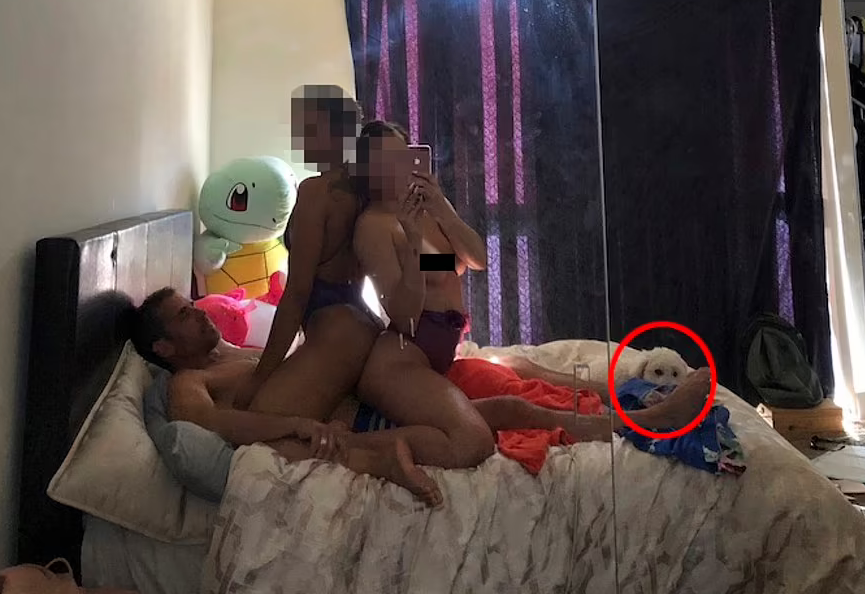
The profile picture for his account is a photo of two women (pictured) sitting on him on a bed in a messy room, with a small white dog also perched on the bed in the background
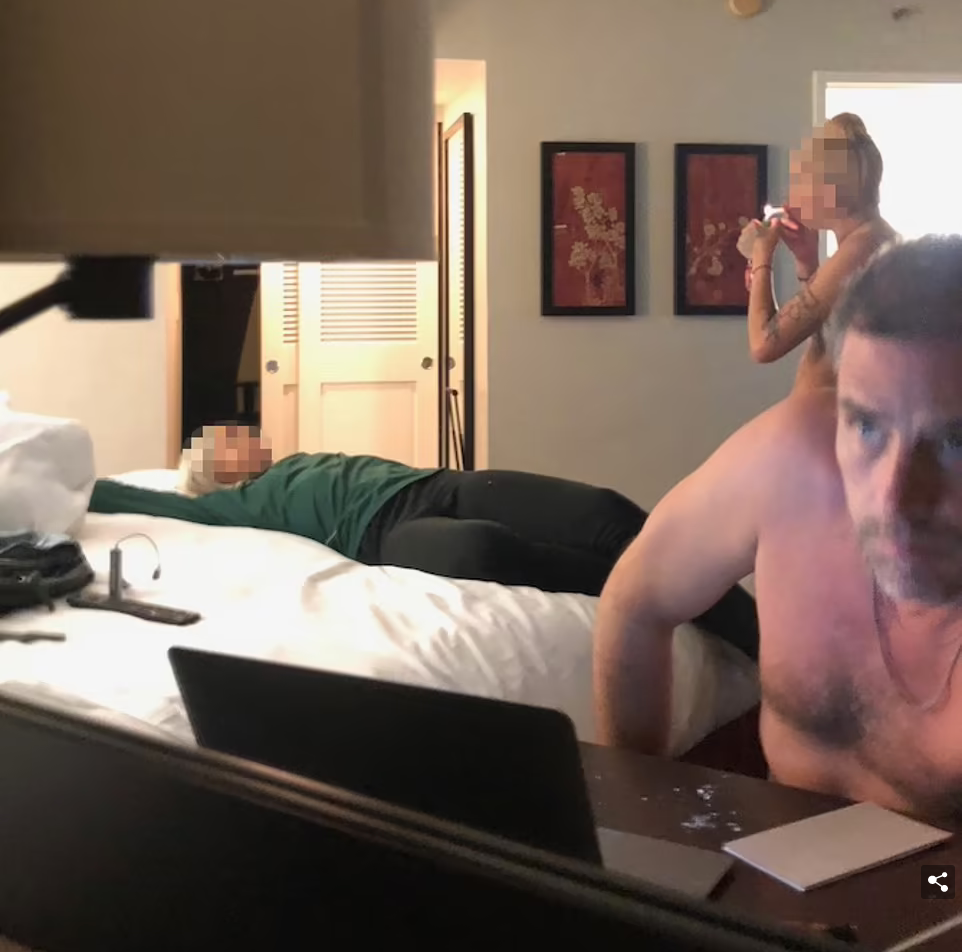
Texts, photos and video footage on the laptop show the president's son ordering prostitutes and filming porn videos with them which he then posted online on his Pornhub account (via the Daily Mail)
According to the report, Hunter may have also been spying on his lover Hallie - accusing her at one point of sleeping with a family friend. Hunter kept spreadsheets full of text messages from Hallie's phone, along with call logs.
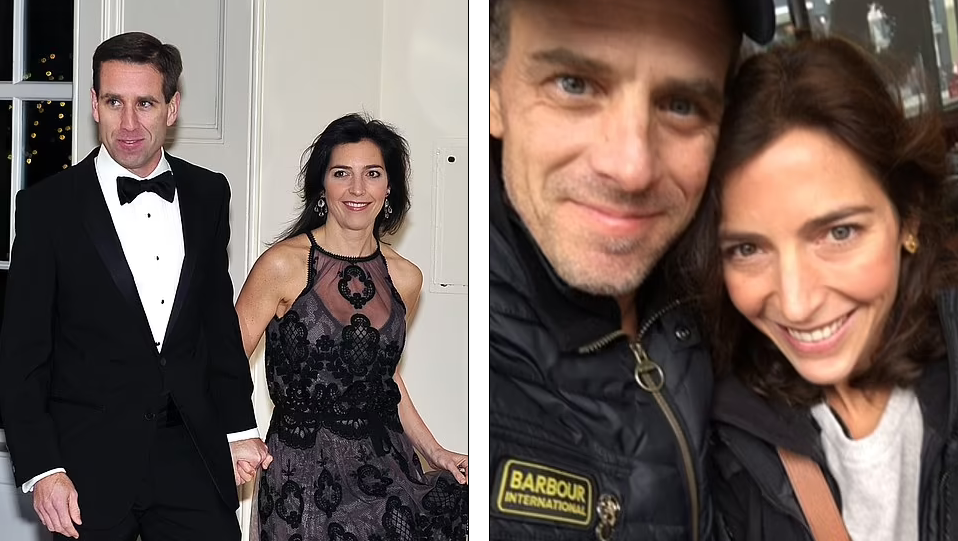
Hunter infamously dated his late brother Beau's (left) widow, Hallie Biden, after his passing in 2015. Files on his laptop suggest that he may have been spying on her (via the Daily Mail)
In one testy exchange on February 6, 2017, Hunter texted Hallie and a family friend what appears to be a transcript of private texts between the man and Hallie.
'If you can possibly explain this as something innocent and - [the man] is just such a food friend then I will apologize,' Hunter wrote to them.
Hunter wrote to the family friend '...if I sent this to your girlfriend when you were away (I went to CA for Rehab) AND 87 other texts just in march would you be OK with that?'
In the text transcript, [the man] texts Hallie on March 3, 2016: 'Come pls. Need you here. One drink and I'll fill you in when you get here. For real. I need you.'
Hallie replies: 'Feel free to stay here I'm in bed' and [the friend] responds 'I probably will'.
After Hunter sent them the transcript, [the friend] responded angrily denying any romantic involvement with Hallie.
'I've blocked all of you on my phone. The idea that I lied to you about Hallie is so f***ing laughable,' he wrote.
'I will never talk to Hallie ever again until she tells you I never gave her any idea that I was interested in her. It's f***ing so pathetic. -Daily Mail
Hunter was also a huge fan of sex cam sites according to his search history, including the site Glasscams.com. Recordings of interactions between a naked Hunter and camgirls were also found.
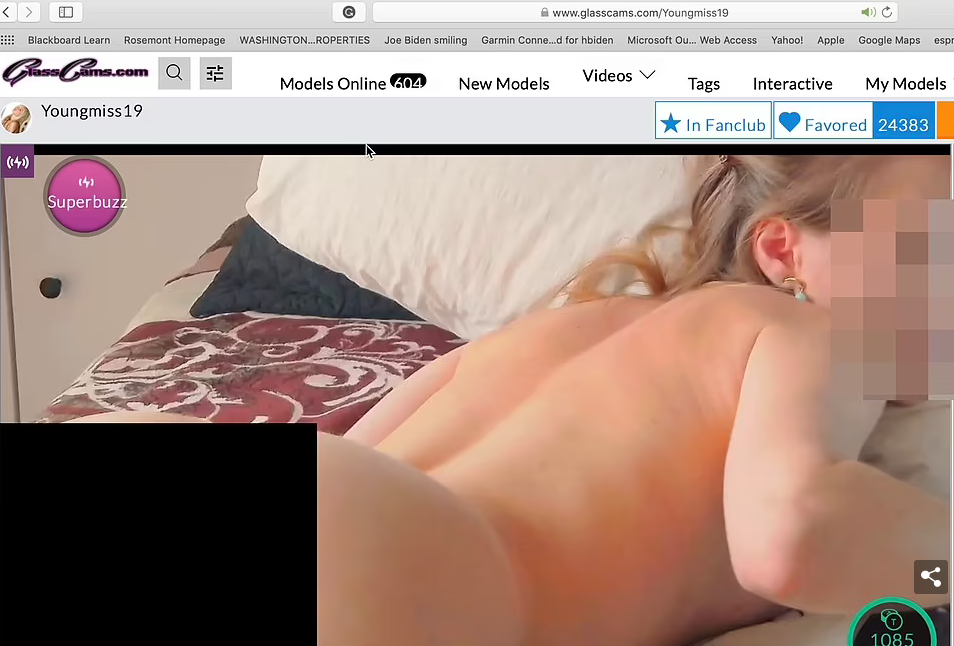
Above is a grab from a screen recording he took of his live web cam interactions with cam girls

The aristocrats!

FT : Forced sovereign debt defaults

Forced sovereign debt defaults
The US Treasury might have made a mistake in its eagerness to trigger a Russian default

Some countries are unable to pay their debts because they don’t have the dough. Others have the money but are just unwilling to pay. To this taxonomy we can now add a third category — a solvent sovereign ready, indeed eager, to pay creditors but that cannot do so because it is prevented from sending the money through the international payments system.

As a result of a decision announced by the US Treasury on May 24, the Russian Federation finds itself in this third category. Under a prior policy that expired on May 25, US holders of Russian sovereign bonds were permitted to receive debt payments on those securities as long as the source of the money was an account that was not frozen by the sanctions imposed after Russia’s invasion of Ukraine. The US Treasury has now allowed that permission to expire.

The result? Russia may effectively be forced to default on its international bonds, not because it is unwilling or financially unable to pay the debt service due on the instruments, but rather because the payments would be blocked by the financial intermediaries through which they must pass in order to reach the accounts of the bondholders.

On its face, this new policy seems counterintuitive. It simultaneously enriches Vladimir Putin’s regime (because it allows him to conserve his remaining foreign exchange), impoverishes western bondholders who were expecting to receive those payments, and perversely may give Russia a legal defence in an English or US court in any lawsuit brought by a bondholder to enforce the instruments.

In contrast, a continuation of the prior policy (which allowed Russia to pay by debiting unfrozen accounts) would have amplified the effect of the sanctions by draining off some of Russia’s remaining foreign currency reserves.

The motivation for this change of policy is opaque. We can think of four possible explanations.

One interpretation holds that once Russia demonstrated its eagerness to continue full servicing of its external debt, the US Treasury smelled a rat and took steps to thwart those payments. If so, Putin may have just pulled off the most successful Br’er Rabbit “don’t throw me into that briar patch” strategy in history. By showing himself eager to pay, he induced the Treasury to stop him from paying, thereby saving himself some money and giving him something that he otherwise would have lacked — a legal defence in court.

An alternative explanation is that by preventing US holders of Russian bonds from receiving payments, the US Treasury will assert control over any future debt management activities that Russia may pursue. Those holders could not, for example, participate in a restructuring of the instruments without a US Treasury license. Holders of Venezuelan public sector bonds have been in precisely this situation since the US imposed sanctions on the Maduro regime in Venezuela in 2019.

But it isn’t at all clear to us that Russia will want or need a debt restructuring when this situation ends. The amount of the country’s external debt is manageable and Russia may attempt to simply to pay any arrears caused by the sanctions when the smoke clears, literally and figuratively.

Perhaps the Treasury is betting that a Russian bond default — even one engineered through sanctions policy — will indelibly stain Russia’s credit reputation and inflict long term damage to the country in the form of constrained market access and higher interest rates?

We offer two observations. First, the market’s memory of this situation is likely to be that the default was forced on Russia despite its best efforts to pay. From a creditor perspective, that might actually be reputation-enhancing. Indeed the Russians have already tagged this as an “artificial” or “technical” default.

Second, it isn’t the bond default that financial markets are likely to remember and punish; it is rather the memory of a brutal and unprovoked invasion of a neighbour that will have that effect.

A final explanation may lie in a desire of the US Treasury to conscript the commercial investor community into applying pressure on Russia to cease its aggression in Ukraine.

If Russia’s bonds do slip into default the bondholders may have an unusually short period of time — a mere 36 months — in which to bring their claims to court or lose their claim altogether. The bonds contain an oddly-worded “prescription” clause saying that claims become void after three-years unless “made”.
Treasury’s decision to refrain from renewing the license that permitted US bondholders to receive payments sourced from unfrozen Russian assets may thus be motivated by a desire to force Russia into confronting multiple lawsuits brought by the holders of those instruments.

This would not be the first time the US Treasury has attempted this manoeuvre in the context of sanctions.

At 8:15am EST on November 14, 1979, the Treasury froze Iranian deposits in US banks in retaliation for the taking of hostages at the American embassy in Tehran. With its US dollar deposits unreachable, Iran was unable to make payments on its US dollar-denominated bank loans. Some of those loans were quickly accelerated by the American syndicate agents. Set-offs, litigation and seizure of Iranian assets soon followed.

It was a remarkably effective use by the US sanctions authorities of their power over the US financial system in order to force a foreign sovereign into defaulting on its commercial debt instruments. The result was a conscription of private sector lenders into applying additional pressure on the errant sovereign.

But if this is the US Treasury’s motivation for forcing a Russian default, it may have a flaw.

By preventing Russia from making payments through the contractually-mandated payment procedures in the bonds, the US Treasury may have unwittingly given the Russian Federation a legal defence in any bondholder enforcement action.

Both UK and US law recognise as a defence a situation in which it has become impossible or illegal to perform the contract. It is hard to predict whether courts would recognise the Russian situation as a genuine case of impossibility. The general rule is that the party claiming the defence cannot itself have been the cause of the difficulty.

In this case, is the inability to pay the bonds a result of the sanctions or is it rather a result of Russia’s illegal invasion that caused the sanctions?

FT : Hedge funds turn more bearish on stocks even after rough start to 2022

Hedge funds turn more bearish on stocks even after rough start to 2022
Crispin Odey wagers ‘life is going to be much more difficult for investors’

Hedge funds are growing increasingly pessimistic about the outlook for global equities, even though markets have already sold off sharply since the start of 2022.

Top-performing managers including Lansdowne Partners’ Peter Davies and BlackRock’s Alister Hibbert have become more bearish on the prospects for parts of the market or on stocks overall, with high-growth technology shares a particular area of concern.

“Life is going to be much more difficult for investors”, wrote Crispin Odey, founder of London-based Odey Asset Management, in a note to clients seen by the Financial Times. “Outages, shortages, strikes and war will come along.”

The manager has sharply increased cash positions in his Opus fund, which typically places bets on companies’ share prices rising and is up around 7 per cent this year, the document shows. His European fund, which is able to bet on prices rising and falling, is up by about 87 per cent this year, according to numbers sent to investors.

Meanwhile, Hibbert, who runs BlackRock’s $9bn Strategic Equity hedge fund and has one of the strongest long-term track records in the sector, has recently shifted his portfolio so that bets on falling stock prices exceed bets on rising prices, said people familiar with the fund.

Such a move is unusual for hedge funds, which tend to retain a bias to rising prices because stocks are expected to rise over the long term. BlackRock and Odey declined to comment.

Other managers have also become more cautious. Hedge funds have significantly reduced the overall size of their bets recently, according to a client note from Morgan Stanley’s prime brokerage team, seen by the FT.

And in the US, the difference in size between funds’ bets on rising prices and their bets on falling prices is now close to its lowest level since 2010, in a sign of how wary managers have become, the note showed.

Such bearishness among hedge fund managers comes as the Federal Reserve and other central banks have started to raise interest rates aggressively to curb inflation. That tightening of monetary policy has knocked the shares of speculative companies whose valuations are flattered by ultra-low borrowing costs. The technology-heavy Nasdaq Composite share gauge is down more than a fifth this year.

Minutes of the Fed’s early May rate-setting committee meeting showed that officials thought a “restrictive” monetary policy, with faster rate hikes, a longer tightening cycle, or both, “may well become appropriate”.

However, stocks last week snapped their longest losing streak since 2001 on hopes that inflation may have peaked.

“We’re in the early stages of money coming out of it [technology stocks],” said Davies, partner at Lansdowne and one of Europe’s most influential investors. “I don’t get the impression many people have sold out of tech.”

He pointed to the amount of money that very big tech companies had to spend to compete with rivals, which he said detracted from cash returned to shareholders.

“I’d be very reluctant to get engaged there [at current prices],” he said.

Meanwhile, Sir Michael Hintze, founder of $19bn-in-assets London-based hedge fund firm CQS, has been positioning for a sell-off in growth stocks. A wager on the Nasdaq falling relative to the Euro Stoxx index has, in turn, paid off for him, according to investor documentation seen by the FT.

Hintze said in the documents that he was expecting “ongoing market volatility and dislocations”.

CQS declined to comment.

>>> US Close Dow -0,54% S&P -0,75% Nasdaq -0,72% Russell -0,49%

Closing Market Summary

The stock market ended Wednesday on a weak note with the major averages finishing near yesterday's lows. The S&P 500 lost 0.8% while the Russell 2000 (-0.5%) finished a bit ahead despite lagging in morning trade.

Early action saw a continuation of yesterday's selling with some recent top performers fueling the retreat. The financials sector (-1.7%) underperformed throughout the day after rallying off a 13-month low at the end of May. Today, the sector was pressured by comments from JPMorgan Chase (JPM 129.91, -2.32, -1.8%) CEO Dimon, who warned about an approaching "economic hurricane." Shares of JPM surrendered yesterday's gain but finished above their low after bouncing off their 50-day moving average (128.34).

The broader market enjoyed an afternoon recovery that returned the S&P 500 to its unchanged level, but renewed selling pressure appeared in the afternoon.

Elsewhere among cyclical sectors, industrials (-0.6%) and the consumer discretionary space (-0.8%) finished near the S&P 500 while the technology sector (-0.3%) ended just below its flat line after reclaiming a chunk of its opening loss. The sector owed its outperformance to relative strength in top components Apple (AAPL 148.71, -0.13, -0.1%) and Microsoft (MSFT 272.42, +0.55, +0.2%), but they too faced some late pressure. Salesforce (CRM 176.07, +15.83, +9.9%) and HP (HPQ 40.34, +1.50, +3.9%) represented pockets of relative strength throughout the day after both companies reported better than expected quarterly results. Chipmakers failed to keep pace with the sector, sending the PHLX Semiconductor Index lower by 1.6%.

Health care (-1.4%) and consumer staples (-1.3%) finished near the bottom of the leaderboard due to broad-based losses. Archer-Daniels (ADM 86.67, -4.15, -4.6%) was the worst performer among staple stocks, falling from its best level in nearly four weeks back below its 50-day moving average (90.25).

On the upside, energy (+1.8%) spent the day in the green, building on its gain as the session went on. The sector's continued strength was supported by another uptick in crude oil, which climbed $0.40, or 0.4% to $115.33/bbl. Baker Hughes (BKR 37.41, +1.43, +4.0%) was the top performer in the sector, reclaiming yesterday's entire loss.

Treasuries added to their losses from yesterday with shorter tenors leading the retreat. The 2-yr yield rose 11 bps to 2.65% while the 10-yr yield rose nine basis points to 2.93%.

The Fed released its Beige Book for June, which noted that all Districts reported continued growth with most reporting slight or modest growth while four reported a slowdown. There was some softening in the retail sector and residential real estate due to high prices and high interest rates. Employment expanded modestly or moderately while one District saw a slowdown. Prices continued rising at a strong or robust pace with manufacturers maintaining the bulk of their pricing power.

Reviewing today's economic data:

  • The May ISM Manufacturing Index increased to 56.1% ( consensus 54.9%) from 55.4% in April. A number above 50.0% is indicative of expansion. May marked the 24th consecutive month of expansion in the manufacturing sector, although the May reading was the second lowest since September 2020.
    • The key takeaway from the report is that manufacturing activity picked up in May despite ongoing supply chain problems and pricing pressures. Still, sentiment regarding demand remained strongly optimistic.
  • Total construction spending increased 0.2% month-over-month in April (consensus 0.6%) following an upwardly revised 0.3% increase (from 0.1%) in March. Total private construction increased 0.5% month-over-month while total public construction decreased 0.7%. On a year-over-year basis, total construction spending was up 12.3%.
    • The key takeaway from the report is that, other than residential spending, there wasn't much strength in spending activity in either the private or public sectors.
  • Job openings decreased to 11.400 mln in April from a revised 11.855 mln (from 11.549 mln) in March.
  • The IHS Markit Manufacturing PMI fell to 57.0 in the final reading for May from 57.5 in the preliminary reading.
  • The weekly MBA Mortgage Index fell 2.3% after falling 1.2% during the previous week.

The ADP Employment Change for May (Briefing.com consensus 295,000; prior 247,000) will be reported tomorrow at 8:15 ET, followed by weekly Initial Claims (consensus 210,000; prior 210,000), Continuing Claims (prior 1.346 mln), revised Q1 Productivity (Briefing.com consensus -7.5%; prior -7.5%), and revised Q1 Unit Labor Costs ( consensus 11.6%; prior 11.6%) at 8:30 ET, and April Factory Orders (Briefing.com consensus 0.7%; prior 2.2%) at 10:00 ET.

  • Dow Jones Industrial Average -9.7% YTD
  • S&P 400 -12.1% YTD
  • S&P 500 -14.0% YTD
  • Russell 2000 -17.4% YTD
  • Nasdaq Composite -23.3% YTD

>>> After Hours Summary: CHWY +20.9%, MDB +5.8%, PVH +4.3%, VEEV +3.5%, NTAP +3.

After Hours Summary: CHWY +20.9%, MDB +5.8%, PVH +4.3%, VEEV +3.5%, NTAP +3.4% higher on earnings; AI -19.5%, HPE -6.6% fall on earnings

After Hours Gainers:

Companies trading higher in after hours in reaction to earnings/guidance: CHWY +20.9%, CRDO +9.8%, PSTG +9.7%, PATH +6.5%, MDB +5.8%, PVH +4.3% (also increases planned 2022 share repurchases to $400 mln), VEEV +3.5%, NTAP +3.4%, NCNO +1.8%, ESTC +1.5%, GME +1.4%, DSGX +0.9%, SMTC +0.2%

Companies trading higher in after hours in reaction to news: RPTX +16.6% (announces worldwide license and collaboration agreement with Roche for camonsertib), APRN +12% (launches new meal kit offering on Walmart.com), KIND +8.1% (authorizes new $100 mln share repurchase program), IGT +2.6% (signs ten year contract extension with Kansas lottery), GSM +2.5% (names new COO), SANA +0.6% (to develop manufacturing facility in Bothell), SAIL +0.4% (receives HSR clearance for pending merger with Thoma Bravo), CERN +0.3% (ORCL obtains approvals for proposed acquisition of CERN), DHX +0.2% (US PTO issues patent related to taxonomy), VAL +0.2% (receives contract termination notice for drillship VALARIS DS-11), BYD +0.1% (authorizes $500 mln increase to share repurchase program), BA +0.1% (DAL still trying to reach an aircraft deal with BA, according to Reuters)

After Hours Losers:

Companies trading lower in after hours in reaction to earnings/guidance: AI -19.5%, HPE -6.6%, S -3.1%

Companies trading lower in after hours in reaction to news: RDUS -6.3% (provides update on abaloparatide transdermal system; to cease all work on abalo-TDS), OWL -2.2% (stock offering by selling shareholder), ITI -1.1% (authorizes new $10 mln share repurchase program), MGY -1.1% (announces proposed block trade of 7.5 mln Class A shares by selling shareholders; intends to purchase 2 mln Class B shares), ANIP -1% (receives FDA approval for ANDA for Fludrocortisone Acetate Tablets), VCSA -0.5% (stock offering by selling shareholders), RIOT -0.3% (names new CFO), DAL -0.2% (DAL still trying to reach an aircraft deal with BA, according to Reuters), RYI -0.1% (acquires tool steel processor Ford Tool Steels), ABC -0.1% (provides long-term goals at Investor Day), TMX -0.1% (satisfies key closing condition for Rentokil merger), BRO -0.1% (acquires the assets of Dealer Specialties)