>>> What to look at today - 5th of July 2022

Asian stocks and US equity futures pared gains Tuesday amid a jump in Treasury yields and as an earlier lift to investor sentiment from a potential improvement in US-China ties ebbed. An Asian share index came off session highs, in part as China turned lower. S&P 500 and Nasdaq 100 contracts made modest gains from Friday’s close. US markets were shut Monday for the Independence Day holiday. The US may announce the rollback of some China levies as soon as this week to counter high inflation. Officials could also unveil a probe into industrial subsidies, which might lead to more duties in strategic areas like technology. Chinese Vice Premier Liu He held a video talk with US Treasury Secretary Janet Yellen Tuesday morning on tariffs and supply chains. The drop in Treasuries was led by shorter maturities, including a surge of as much as 13 basis points in the two-year yield. That extended a global bond retreat that began in Europe on Monday. Speculation has intensified that President Joe Biden may reduce some Trump-era tariffs on $300 billion in Chinese imports. Policy makers are under pressure to tackle inflation, which has forced interest-rates higher, sapped economic expansion and contributed to steep equity and bond losses this year. Brent crude hovered at $113 around barrel. Bitcoin retook the $20,000 level. 

Nikkei +1.02% Hang Seng +0.23% CSI -0.71% Shanghai -0.46% Shenzen -1.27%

Eur$ 1.0447 CNH 6.6913 CNY 6.6926 JPY 136.26 GBP 1.2114 CHF 0.9602 RUB 56.0979 TRY 16.8338 WTI$110.11 +1.555 Gold 1,810.65 -0.32% BTC 20,320 +2.85% ETH 1,160 +3.5%

S&P +0.40% Nasdaq +0.52% EuroStoxx +0.49% FTSE +0.28% Dax +0.52% SMI +0.17%

Macro :
- EU Set to Ease IPO Rules to Lure $47 Billion Deep Tech Funding
- UK Starts Consultation on Tax-Treatment of Sovereign Investors
- UK’s Johnson Says ‘We Are Going to Need a Lot More OPEC+ Oil’
- Germany Seeks Subsidies for Firms With High Energy Usage: FAZ

Keep an eye on :
- AT/ LN : Ashtead Technology Holder BP Inv2 Newco Offers ~10m Shares
- BAKKA NO : Bakkafrost Prelim 2Q Total Harvest 19,700 Metric Tons
- CABK SM : *CAIXABANK WANTS TO SPEED UP REAL ESTATE ASSETS SALE: EXPANSION
- COFB BB : Forever Care-Ion Cuts Cofinimmo Holding to 4.97% as of June 28
- CSGN SW : Credit Suisse Switzerland Names Roger Suter Head Private Banking
- DTE GY : KKR Is Said to Lead Bidding for $20 Billion Deutsche Telekom Arm
- ECV GY : Encavis CEO Dierk Paskert Will Resign, Leave Company
- ERG IM : ERG in Exclusive Talks for Some EDP Renewables Wind Assets: MF
- GLJ GY : Grenke 1H New Business in the Leasing Segment +42.2%
- LHA GY : MSC-Lufthansa, Certares May Lower ITA Valuation: Corriere
- RWE GY Hellenic Petroleum, RWE to Develop Greek Offshore Wind Parks
- SAS SS : Danish Government Won’t Interview in SAS Strike, JP Reports
- SAE GY : Shop Apotheke Maintains FY Adj. Ebitda Margin Forecast
- UBSG SW : UBS to Sublet Two Floors in London Office Amid Flexible Work: FT
- UN01 GY : Germany’s Uniper in Bailout Talks to Plug $9.4 Billion Hole
- VALN SW : Femsa to Buy Valora for CHF260/Shr: M&A Snapshot
- VALN SW : Valora Sees 1H External Sales About 20% Above Prior Year

>>> Europe : Brokers Upgrades & Downgrades - 5th of July 2022

>>> Up
* AB InBev Raised to Buy at Citi; PT 62 euros
* Aker Solutions Raised to Buy at Arctic Securities; PT 35 kroner
* Ascential Raised to Buy at Citi
* BNP Paribas Raised to Buy at Deutsche Bank; PT 66 euros
* DBV Tech Raised to Buy at Kempen & Co; PT 5.50 euros
* Dechra Pharma Raised to Outperform at RBC; PT 4,200 pence
* Genfit Raised to Buy at Kempen & Co
* Moneysupermarket Raised to Buy at Liberum
* Moncler Raised to Sector Perform at RBC; PT 47 euros
* Proximus Raised to Neutral at Citi; PT 14 euros
* Remy Cointreau Raised to Buy at Jefferies; PT 200 euros
* Scout24 SE Raised to Buy at Goldman; PT 64.30 euros
* Sparebanken Vest Raised to Buy at Nordea; PT 99 kroner
* TietoEVRY Raised to Buy at Handelsbanken
* Wolters Kluwer Raised to Buy at Goldman; PT 113 euros

>>> Down
* Credit Agricole Cut to Hold at Deutsche Bank; PT 12 euros
* ProSieben Cut to Sell at Goldman; PT 9 euros
* Publicis Cut to Neutral at Goldman; PT 53.10 euros
* Standard Chartered Cut to Market Perform at KBW; PT 700 pence

>>> Initiation
* About You Rated New Underperform at Exane; PT 5.20 euros
* Diageo Reinstated Buy at Stifel; PT 4,530 pence
* Dredging Environmental & Marine Engineering Rated New Buy at ING
* Global Fashion Group Rated New Underperform at Exane; PT 1 euro
* Oncopeptides Reinstated Buy at Kempen & Co; PT 35 kronor
* Pernod Ricard Reinstated Hold at Stifel; PT 192 euros
* RS Group Rated New Neutral at Citi; PT 900 pence

>>> Call
* Morgan Stanley’s Wilson Says Slowdown Is ‘Worse Than Expected’
* Ascential Re-Rating Likely, Citi Raises and Opens Catalyst Watch
* Lonza Raised to Buy at Citi on Strong Trends in Biologics
* Proximus Upgraded to Neutral at Citi, Downside Now Priced In
* Remy Gets Buy for First Time at Jefferies on China Tailwind
* SAP an Evolving ‘Software Powerhouse,’ Berenberg Initiates Buy

FT : Who pays for climate change? The Peruvian suing a German utility

Who pays for climate change? The Peruvian suing a German utility
A farmer’s case against energy company RWE could shatter precedent on climate-related litigation

For several days at the end of May, an unusual collection of scientists, lawyers and judges from Europe could be found in the Peruvian Andes almost 5,000 metres above sea level, watching as a drone flew up to a huge, but shrinking, glacier.

The setting was spectacular: the bright blue Lake Palcacocha sparkled in the sun in front of a huge wall of rock and ice hundreds of metres tall, the facade of a glacier that extends backwards over the snowy peaks. The beauty of the scene belied its instability; if an avalanche were to crash into the lake, experts warn floodwater could rush down into the city of Huaraz below.

The unlikely group was deep in the mountains to gather evidence in a high-stakes lawsuit brought by a Peruvian farmer, Saúl Luciano Lliuya, against RWE, Germany’s largest utility company.

Since the emissions produced by RWE globally over its 124-year history contributed to the warming that is shrinking the glacier, the farmer argues, the company should help pay for defences to protect Huaraz, his hometown.

RWE has never had any operations in Peru. But it is one of Europe’s 10 biggest polluters, according to an influential 2014 study, accounting for 0.47 per cent of the cumulative global industrial emissions of carbon and methane between 1751 and 2010 — the effects of which do not respect national borders.


Accordingly, in a suit filed in Germany in 2015, Luciano Lliuya said the company should pay for 0.47 per cent of the costs of protecting Huaraz — around €20,000. RWE says the claim has no basis in German law, and that it is judicially impossible to attribute specific local consequences of climate change to an individual company.

Luciano Lliuya’s action, which has been funded entirely by donations, is about much more than compensation. The dispute, now nearing its final stages, is a landmark case — seen by many academics, campaigners and litigators around the world as a potential watershed moment that could usher in a wave of compensation claims for climate-related destruction.

“If this case is successful I have no doubt that there will be a number, probably a big number, of additional court cases,” says Christoph Bals, policy director of the non-profit Germanwatch, which is supporting Luciano Lliuya.

It is just one of the ballooning number of climate-related lawsuits that have been filed in the six years since the Paris Agreement was signed. The Agreement — in which more than 190 countries agreed to limit global warming to well below 2C — has provided new legal ammunition to activists and environmentalists, as domestic courts are being asked to interpret what the treaty obliges individual countries to do.

Recent wins — such as a French court’s 2021 ruling that the government must do more to cut emissions — have emboldened activists, and funding for climate cases is increasingly available. There is also broadening acceptance in many jurisdictions of the need to curb warming: in a 2021 decision, a court in the Netherlands ruled that oil major Royal Dutch Shell had a duty of care to Dutch citizens and must make steeper emissions cuts.

While the sum Luciano Lliuya is seeking amounts to little more than a rounding error for a company like RWE, which had a turnover of €24.5bn in 2021, a precedent-setting victory would expose other polluters to the risk of similar claims from around the world, potentially for much larger sums.

The judges’ decision will “influence the thinking” of judges elsewhere, who are “seeing climate cases come into their courtrooms and [are] looking for guidance,” says Michael Burger, executive director at the Sabin Center for Climate Change Law at Columbia University, New York.

Even if Luciano Lliuya’s challenge fails, the architecture of the case will exist for others to learn from, at a time when demands from poor nations for climate-related financial support are growing louder. The RWE case is the first transnational lawsuit of its kind to have got as far as it has, and is thought to be the first time a resident of one country has sought compensation from a polluter based elsewhere.

“Eventually there will be a brave court that will order compensation,” says Sophie Marjanac, a lawyer at environmental law charity ClientEarth. It could be “impossible to estimate or put a limit on that liability . . . That’s why [companies are] resisting it incredibly hard.”

The fight reflects a stark reality: those who are most affected by climate change have often done little to cause it, and feel abandoned by big polluters that they say are not doing enough to help them cope with its effects.

“When we took this case in 2015 everybody said we were crazy,” says Luciano Lliuya’s German lawyer, Roda Verheyen. “Science is only working to our advantage . . . I don't think I’ve ever been this optimistic.” Even if the farmer loses, she adds, the issue of who is responsible for the damage caused by climate change is not “going to go away”. 

The case for the plaintiff
To have a chance of winning, Luciano Lliuya’s legal team must first show that the threat to his property is significant and imminent. That is what the scientific experts appointed by the regional court of Hamm, Germany were gathering evidence about during the week-long visit in May, watched over by the German judges set to rule on the case.

The scientists took soil samples and noted down measurements. A drone flew up to the ice wall — which was theoretically accessible by boat, but “much too dangerous” to get close to due to the risk of falling ice, says Martin Mergili, a geomorphology expert who has supported Luciano Lliuya’s team.

They worked to the sound of occasional cracking. “It’s not a constant noise, but from time to time . . . small ice avalanches come down,” says Mergili. Sometimes the sound is “shocking”.

According to people familiar with the case, RWE has questioned and tried to discredit the climate science presented to the German court by Luciano Lliuya’s team over the course of the case, much of which is being fought behind closed doors.

In a statement to the FT, the company says it “must be allowed to argue about studies and whether or not they are of relevance for the case . . . We do not deny climate change and that man has been and still is influential on it.”

In addition to proving the threat to his home, the farmer’s team must show that RWE is partly to blame for the risk because of its historic emissions. That is more of a challenge, and something that until recently would have been difficult to prove.

Enter “attribution science”, a rapidly evolving field of research about the extent to which climate change made a natural disaster more likely or severe, and who emitted the pollution that caused warming.

Once a niche specialism, this area of study has advanced rapidly in the 20 years it has been around and scientists are getting better at drawing causal links. Without these advances, proving liability for climate-related destruction would have been much harder, says Delta Merner, who leads the Science Hub for Climate Litigation at the US non-profit Union of Concerned Scientists. The RWE case “would not have been possible 10-15 years ago,” she adds. 

For Luciano Lliuya and his supporters, winning is about “climate justice” — or redressing the balance between big polluters and the communities that have done little to contribute to climate change, but will be worst hit by its effects.

A wave of legislation
Vulnerable countries are also seeking climate justice, which some of their leaders say should include compensation for the effects of warming — something long resisted by rich countries. Compensation cases are “the holy grail of climate change litigation”, says Marjanac. “There’s no way that the rich countries of this world will voluntarily agree to pay compensation to the global south.”

The issue proved a sticking point at last year’s COP26 UN climate summit, at which rich countries refused to back a proposal by poorer ones for a new financing facility for “loss and damage”, or money to help those most at risk cope with the devastation wrought by rising sea levels, hurricanes and wildfires. Loss and damage is expected to be a major theme at this year’s COP27 meeting in Egypt.

Lee White, Gabon’s minister of water, forests, the sea and the environment, says if he were representing a country at high risk from climate hazards, “I’d be very tempted to take [legal] action . . . even though I know that it would be extremely complex and difficult to prove.”

Some island nations are considering doing just that: last year, Antigua and Barbuda and Tuvalu established a group to discuss the prospect of suing countries for the effects of their emissions, among other things. The Commission of Small Island States on Climate Change and International Law plans to seek legal opinions from international courts and tribunals about whether they could bring such cases.

In the US, meanwhile, more than 20 cases are making their way through courts in states across the country, seeking damages for climate-related destruction. Unlike the RWE case, they are rooted in the idea of deception as the source of liability — that big polluters misled people about the effects of their carbon intensive products.

“As science comes to play an increasingly prominent role in [legal] cases, it’s very likely that fights over the science, and questions over whose science courts should believe, will increasingly become more prominent,” says Rupert Stuart-Smith, a University of Oxford researcher who has studied the glacier at the centre of the case, but is not affiliated with the suit.

Not everyone agrees that litigation is the best way to hold major corporate polluters to account. Some experts say governments and regulators should set out what they expect of companies, rather than allow specific polluters to be targeted for past emissions.

“Companies need to know what their responsibilities are, since they cannot be limitless,” wrote David Pitt-Watson, former chair of the UN Environment Finance Initiative, in 2020.

“If we don’t resolve this, we end up with potentially a very chaotic commercial world in 20 years’ time,” he tells the FT. The rules about a company’s obligations should be set by regulators, and businesses should be sure that if they follow them “in good faith, there is safe harbour and they won’t be sued”, he says.

The growing risk to the corporate world has not escaped the notice of authorities: in May, the Bank of England warned that litigation could affect “the cost and availability” of directors’ liability insurance. “If real-world cases led to payouts, the possible financial costs that could be borne by businesses or insurers are large,” the Bank said.

Thom Wetzer, director of the Oxford Sustainable Law Programme, says part of the reason for the uptick in litigation is the climate “governance gap”. The Paris Agreement lacks an enforcement mechanism to ensure that “countries do what they’ve signed up for . . . As long as these governance gaps persist, we will see more and more litigation to try and plug those gaps.”

There is also no net zero legislation governing what companies can or must do in most parts of the world, he adds.

‘It shouldn’t be necessary’
Despite what’s at stake, and the presence of two opposing sides, those who visited the glacier in May say the atmosphere was amicable and supportive.

“It was very friendly,” with “people sitting around on stones eating their sandwiches and energy bars,” says Verheyen, the lawyer for Luciano Lliuya. “Nobody got sick, at least not very seriously, even though that is a very unusual altitude to be working on.”

The German court must now come to a decision about the risk facing the farmer’s house, before moving on to the second question — whether RWE bears some responsibility and can be held legally liable. A final decision in the case is unlikely to come this year.

All the while, and for the seven long years since the case was filed, the possibility of disaster hangs over Huaraz. “The situation is hazardous, it’s not something which is purely theoretical,” says Mergili.

In 1941, when Lake Palcacocha was much smaller, it brimmed over and the city was hit by flooding that killed over 1,000 people. Serious ice and rock avalanches also occurred in the Peruvian Andes in 2010 and 2020, and large mass movements in high mountain areas have become more common.

Luciano Lliuya and the local community want additional protection measures, such as a new drainage system. The authorities have already placed hoses in the lake to lower the level of the water, which is used by the local population, and the city has a well-signposted evacuation route.

But like the Pacific Island nations threatened by rising sea levels, Luciano Lliuya also wants to raise the profile of those at risk and find an answer to the climate justice question. “I’m very happy that I’ve been able to show people what’s happening,” he said at a press conference at the end of the site visit in May.

Some countries are “far more responsible for the pollution, and others far more affected by the consequences”, says Payam Akhavan, legal counsel to the Commission of Small Island States on Climate Change and International Law.

“The idea is not to litigate all of these issues, but pressure states to start addressing loss and damage in the [UN climate] negotiations,” he says. “But if necessary, yes there could ultimately be litigation against specific states.” 

If RWE loses the case, “they’d have to pay this very small, symbolic amount of money” towards the cost of defending Huaraz, says Noah Walker-Crawford, an external consultant on climate litigation for Germanwatch.

“But of course it’s about much more than that,” he continues. “The whole point of bringing these kinds of cases is that not enough has happened on a political level. Really, it shouldn't be necessary.”
FT : Crypto collapse reverberates widely among black American investors

Crypto collapse reverberates widely among black American investors
Higher exposure to digital assets leaves owners vulnerable to downturn

The widespread losses caused by the cryptocurrency crash are even broader among black investors.

A quarter of black Americans own cryptocurrencies, compared with only 15 per cent of white investors, according to a survey by Ariel Investments and Charles Schwab. Black Americans have been more than twice as likely to purchase cryptocurrency as their first investment.

The value of those investments has imploded. The total market capitalisation of cryptocurrencies has plunged below $1tn from more than $3.2tn last year. The fall in digital assets comes alongside a bear market in US stocks.

Black Americans’ higher exposure to cryptocurrencies has left them more vulnerable to the financial downturn, even as their households on average hold less wealth.

The attraction of building wealth, amplified by marketing, drew many black investors into cryptocurrencies. The dollar price of bitcoin rose by 9,300 per cent in the five years to its peak in November.

Jefferson Noel, 27, said he gained his first exposure to crypto in January 2019 when he accidentally invested $5 in bitcoin while using Cash App, a payment service.

“I had no idea what it was, and I don’t even remember doing it,” he said.

By last May his unintentional investment was worth $70. The astronomical gain inspired him to take a friend’s advice to plough $20,000 of his savings into other cryptocurrencies, such as dogecoin, over more traditional investments such as index funds.

“[Black Americans] do not want to be left behind again,” Noel said. “As far as I can tell, the black community sees crypto as a way to even the playing field and get in the game before the gatekeepers prevent others from participating.”

But he is now rethinking that decision. Persistent losses have wiped more than 20 per cent from his crypto investment. He is researching mutual funds on the advice of his uncle, but still buying more crypto.

Historically, black investors have tended to be conservative, investing more of their money into low-risk assets such as insurance and savings bonds. Black Americans are less trusting of the stock market and financial institutions than white Americans, according to the Ariel-Schwab survey. Further research has tied their apprehension to decades of discrimination in the financial system.

Jatali Bellanton, the author of a personal-finance curriculum geared towards young black Americans called Kids Who Bank, sees cryptocurrencies as a way to make up for wealth-building opportunities that were historically unavailable in housing and stock markets.

“We do not like to get left behind when it comes to new technology,” she said.

The promise of cryptocurrencies as a wealth builder has been supercharged by celebrity endorsements, sponsorships and advertising.

Prominent black Americans including the musicians Jay-Z and Snoop Dogg, the boxer Floyd Mayweather, the actor Jamie Foxx and the film-maker Spike Lee have promoted crypto to their communities.

Lee appeared in commercials for crypto ATM operator Coin Cloud last year, saying that “old money is not going to pick us up; it pushes us down” and “systematically oppresses”, whereas digital assets are “positive, inclusive”. 

Last month, Jay-Z announced a partnership with former Twitter chief executive Jack Dorsey to launch a “Bitcoin Academy” literacy programme in the Brooklyn public housing complex where he grew up.

Such celebrity endorsers have faced heavy criticism for getting paid to sell high-risk investments to people who may not have the resources to weather crypto’s volatility.

“Ninety-eight per cent of these cryptocurrencies were not designed to do anything other than extract money from people’s bank accounts,” said Najah Roberts, a former financial adviser and the founder of cryptocurrency education centre Crypto Blockchain Plug.

“This is not ‘get rich quick’,’’ Roberts added. “There are massive targeting ads that are targeting our community.” 

Bellanton said it is not adverts but the prospect of financial freedom, a lack of the investment minimums common for mutual funds, and a feeling that the blockchain distributed ledger is more transparent than big banks that draws in first-time investors.

“The reason that minorities at a higher rate than others are adopting crypto is precisely because if you’re not already rich, it’s way cheaper to send [USD Coin, a stablecoin asset] than to send a wire,” said Brian Brooks, chief executive of blockchain company Bitfury, at the Aspen Ideas Festival last month. “It’s just cheaper. The entire system is cheaper and faster. It doesn’t have all these entry barriers where you can only get it if you’re already rich.” 

Despite the risk of losses, many black investors are staying invested in the market. Dennis McKinley, 41, has been buying the dip against the advice of his financial adviser. He said his crypto coins now constitute roughly 30 per cent of his overall portfolio, held alongside equities.

“Young black America is just now getting to a point where we have the amount of freedom to have the opportunity to invest in alternative strategies besides just real estate,” said McKinley, a small-business owner in Atlanta. “I think that it’s important to learn and get out there.”

FT : How a £15bn KKR deal blew up


The company that was so inflation-resistant, it shattered a mega-deal
KKR was two days away from bagging a bargain.

Alongside Australia’s Macquarie Group, the private equity giant was preparing to buy Britain’s largest electricity distributor, UK Power Networks, for £15bn.

For a buyouts industry that has been pushing into infrastructure funds, through which it can hold a company for a decade or more — and benefit from all of the associated fees and dividends in that time — it was a dream deal.

UKPN is not a glamorous, high-growth proposition. It gets its revenue from residents of south-east England paying their electricity bills — the kind of steady, sticky revenue you can comfortably borrow against to fund payouts to investors.

Better still, it stands to be a winner in an inflationary world, at least relatively. Like other privatised parts of the UK’s infrastructure, its returns are set by a regulator and are linked to a price index — meaning they rise with inflation. And because the business is not labour-intensive, that advantage typically outweighs the extra costs that inflation brings.

On top of that, a chunk of regulated utilities’ debt has interest payable in nominal terms, as Lex points out. That means payments on those bonds will not rise, further enhancing the returns from inflation-pumped revenues.

The company was so inflation-resistant, it turns out, that it ultimately crashed the deal.

As talks entered their later stages last month, UK inflation hit 9.1 per cent. That led the electricity distributor’s owner, billionaire tycoon Li Ka-shing’s CK Infrastructure Holdings, to increase the price just as a deal was about to be inked, the FT’s Gill Plimmer revealed.

KKR, Macquarie and the other bidders in their consortium decided the asking price was too high, and walked away.

DD reckons the buyers’ advisers Rothschild, Citigroup and Nomura were less than thrilled: due diligence had been going on for a year, one person close to the bidders said.

It’s easy to see why CK wanted a higher price.

But it must have been a significant mark-up to make the buyers back out at the eleventh hour — the person close to the bidders described the increase as “massive”.

Nature : What polio’s UK presence means for global health

What polio’s UK presence means for global health
A form of polio derived from the vaccine is probably circulating in the United Kingdom, highlighting the ongoing need for polio vaccination worldwide.

UK health officials are urging people to make sure they are vaccinated against polio, after several sewage samples in London tested positive for the poliovirus towards the end of June.

The UK Health Security Agency (UKHSA), a public-health body, said a poliovirus strain was detected during routine surveillance of waste water in February. A mutated version of the same strain was picked up again in the following months, the agency added, suggesting the virus has spread between individuals, allowing it to evolve.

This virus is called vaccine-derived poliovirus. It is a strain of (weakened) poliovirus that would have originally been found in oral polio vaccines, but has changed over time to behave more like a wild type, or naturally occurring, poliovirus. Vaccine-derived poliovirus can spread through faeces or respiratory secretions. On rare occasions, it can infect the nervous system, causing paralysis and breathing problems in unvaccinated people.

No people with symptoms of polio — including paralysis — have been reported so far, but health authorities are asking doctors to look out for, and report, any symptoms of the disease.

The last case of wild polio contracted in the United Kingdom was in 1984, and the country was declared polio-free in 2003, but the virus still circulates in some parts of the world. Nature explores what the resurgence of polio in the country means.

Why is there polio circulating in London sewers?
Traces of unrelated vaccine-like polioviruses are found every year in UK sewage samples. These detections typically occur when people vaccinated in other countries with a weakened form of the poliovirus return or travel to the country and shed the weakened live virus in their stool for a few weeks.

However, the viruses detected since February are different. They were related to one another and contained mutations suggesting that the virus was spreading from person to person — probably through poor hand hygiene.

According to the UKHSA, there might have been some spread between “closely linked individuals” who are now shedding the poliovirus strain in their faeces. “Investigations will aim to establish if any community transmission is occurring,” the agency said in a press release.

Should people be alarmed?
Scientists say that, at the moment, there’s no reason to panic. The form of virus that was detected in waste water poses a low risk to health: vaccination easily prevents the disease it causes.

Children are routinely vaccinated against polio. According to the World Health Organization (WHO) Global Polio Eradication Initiative (GPEI), 86% of people in London are vaccinated against polio. However, a drop in vaccination uptake during the COVID-19 pandemic could allow the virus to keep circulating. A report this year by the UKHSA found that, in parts of west London, only 35% of teenagers had received their polio booster in 2020–21.

The COVID-19 pandemic has hindered routine vaccinations, which include polio immunization, says Kathleen O’Reilly, an epidemiologist at the London School of Hygiene & Tropical Medicine. The primary course of immunization against polio is combined with vaccinations against other diseases, such as tetanus and whooping cough, so children who missed their polio vaccination are probably vulnerable to other infectious diseases, O’Reilly says. “In some communities, [children] might have also missed the measles vaccine, so this is an early warning of other vaccine-preventable diseases potentially being a problem.”

The detection of vaccine-derived poliovirus in London, she adds, emphasizes the need to invest in vaccination efforts and the importance of wastewater surveillance.

Is polio on the rise globally?
Although wild polio is declining, with only Afghanistan and Pakistan still reporting cases, there have been several outbreaks of the vaccine-derived form of the virus in recent years — with a peak in 2020, when more than 1,100 cases of vaccine-derived polio were reported.

At the beginning of the COVID-19 pandemic, the GPEI paused its polio-eradication activities for a few months, says Michel Zaffran, who retired as head of the GPEI last year. “During that time, the viruses were able to circulate undetected,” he says.

Since 2021, however, the number of vaccine-derived polio cases has been declining. In the past year, 18 countries have reported at least one case of vaccine-derived polio. Regions including south central Somalia and northern Nigeria are outbreak hotspots, says Oliver Rosenbauer, communications officer at the GPEI. “That’s also where you have the highest proportion of children who have never been immunized,” he says.

Because outbreaks can be brought under control with immunization, countries should continue to vaccinate as many people as possible, Rosenbauer says.

How can polio be wiped out worldwide?
The world has spent more than US$17 billion over three decades in an effort to eradicate the virus through vaccination campaigns. In late 2020, the WHO granted emergency approval to a modified vaccine, called nOPV2, to stop outbreaks of circulating vaccine-derived poliovirus in African and East Mediterranean countries. The virus in that vaccine has been genetically engineered to prevent it from becoming harmful.

According to the GPEI, more than 300 million doses of nOPV2 have been administered in 15 countries since March 2021. The vaccine “is a tool that we are all very excited about”, says Ananda Bandyopadhyay, a public-health epidemiologist who conducts polio research at the Bill & Melinda Gates Foundation in Seattle, Washington.

The new vaccine successfully ended a polio outbreak that left 34 children paralysed in Tajikistan. But “a vaccine is of no use if it is sitting in a vial”, says Bandyopadhyay, who co-leads the nOPV2 working group at the GPEI. “What really makes a difference is vaccination coverage.”

Global polio-eradication campaigns face challenges including vaccine hesitancy, political unrest and a lack of adequate health infrastructure. To end polio, Bandyopadhyay says, the global community should provide support for low-income countries to buy vaccines, enhance surveillance and enable front-line health workers to deliver vaccines to every child.

Until polio is wiped out worldwide, all countries are at risk of a resurgence, he says. “Polio can be a plane ride away, if it is out there somewhere.”

FT : Germany draws up law to take stakes in struggling gas importers

Germany draws up law to take stakes in struggling gas importers
Berlin moves to tackle fallout from surging energy prices in wake of Russia’s invasion of Ukraine

The German government has drafted a law that allows it to take stakes in companies crippled by the soaring cost of imported gas as tensions with Russia threaten to plunge the country’s power sector into crisis.

The law, which could be passed by the German parliament as early as this week, would clear a path for the government to bail out Uniper, the largest importer of Russian gas into Germany.

The amended energy law would also allow importers to pass on the higher costs of the gas they are procuring on spot markets to all their customers, and so avoid insolvency.

“Gas has become a scarce commodity and in the current situation we have to make all options available in case of an emergency, and to once again expand our toolbox,” an official said, explaining the measures.

The aim, officials say, is to avoid a repeat of 2008 when the collapse of Lehman Brothers cascaded through the whole financial market, helping to trigger a global crisis.

Germany’s energy sector has been in turmoil since mid-June when Russia’s state-controlled gas exporter Gazprom reduced flows of gas through the Nord Stream 1 pipeline under the Baltic Sea by 60 per cent.

NS1 will undergo scheduled maintenance between July 11 and July 21, and many in the government fear that gas flows might not resume after the repairs are completed as the economic war between Russia and Germany escalates.

Officials have already warned that gas might have to be rationed to industrial customers this winter if Germany fails to fill gas storage facilities quickly enough ahead of the cold season.

Deprived of Gazprom supplies, importers have been forced to procure gas on the spot market at much higher prices. However, they have been unable to pass on these higher costs to their customers, most of whom receive their gas under long-term contracts that are not open to renegotiation.

“If energy companies can’t pay the high prices or fulfil their contracts, they face financial difficulties up to and including insolvency,” the official said. “But if [they] collapse, that could trigger a serious breakdown of the whole market, right along the supply chain to the end consumer.”

Uniper, which issued a profit warning last week and said it was in talks with the government about a bailout, is so far the highest-profile casualty of the crisis.

It said the talks concerned “stabilisation measures” which could include guarantees, an increase in the current credit facility it was granted at the start of the year by the state-owned bank KfW, or the state taking a stake in the company.

Most analysts believe Berlin will bail out Uniper, with a package expected to amount to around €9bn. The rescue deal could be modelled on the relief provided to airline Lufthansa during the pandemic.

Under the proposed amendments to the energy law, the German state would be able to take stakes in troubled companies “of critical infrastructure in the energy sector”, just as it did in banks affected by the global financial crisis and during the Covid-19 pandemic. As part of the Lufthansa bailout the state took a 20 per cent stake in the airline.

The amended law also includes a new “price adjustment” mechanism designed to “maintain supply chains as long as possible and prevent cascade effects”, the official said. It would essentially allow companies to pass on the additional costs of procuring gas on spot markets by imposing a levy on all their gas customers.

MisesInstitute : Here We Go Again: The Fed Is Causing Another Recession

Here We Go Again: The Fed Is Causing Another Recession

07/02/2022Jon Wolfenbarger
Cause of the Boom-Bust Business Cycle
The primary cause of the recurring “boom and bust” business cycle is central banks like the Federal Reserve creating money out of thin air. This was first explained by Austrian economist Ludwig von Mises over a century ago. His student F.A. Hayek won the 1974 Nobel Prize in economics for his work on this theory, which is now known as Austrian business cycle theory.
The basic outline of Austrian business cycle theory is as follows:
  1. the government “central bank” (in the US, it is the Federal Reserve or “Fed”) creates money out of thin air (they effectively “print it,” although typically in the form of digital entries now), usually by buying Treasury bills or bonds from commercial banks, which then …
  2. is deposited in commercial banks which, through the process of fractional reserve banking (where banks are legally allowed to keep only a fraction, such as 10 percent, of their deposits in cash reserves), create even more money out of thin air to lend to their customers, which then …
  3. leads to lower interest rates than would prevail in a free market without a central bank and fractional reserve banks legally creating money out of thin air, which then …
  4. causes businesses and consumers to borrow the newly created money to invest in long-term projects such as mines, factories, houses, etc., since the profitability of those investments appears higher now with a lower cost of capital, which then …
  5. leads to the unsustainable “boom” phase of the business cycle where scarce capital is misallocated to unsustainable investments since the real resources of raw materials, equipment and labor needed to finish these long-term projects are not physically available; while paper money may literally grow on trees, the actual scarce resources needed to create goods and services do not (printing money does not create the goods needed for profitable investment—if it did, Zimbabwe would be the wealthiest country in the world and we could all stop working, saving and investing); then …
  6. the higher money supply leads to higher price inflation, which raises production costs and usually causes the central bank to slow the growth rate of money supply and raise interest rates to try to lower inflation (if they do not, it will eventually lead to hyperinflation, which effectively destroys a functioning currency and economy), which then …
  7. leads to the “bust” phase of the business cycle, where the unsustainable investments are proven to be unprofitable and must be liquidated to allocate capital to the most productive uses that meet consumer desires.
As this theory shows, the dreaded boom and bust business cycle is not inherent in a free market economy. It is caused by the legal privilege granted to central and fractional reserve commercial banks to create money out of thin air. As Mises summarized:
True, governments can reduce the rate of interest in the short run. They can issue additional paper money. They can open the way to credit expansion by the banks. They can thus create an artificial boom and the appearance of prosperity. But such a boom is bound to collapse soon or late and to bring about a depression.
Fed Panicked Over Covid
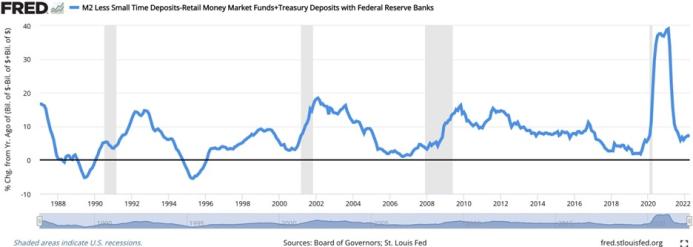
As a result of the stock market crash and global economic collapse caused by government covid policies in early 2020, the Fed panicked and aggressively increased the money supply by 40 percent, more than double the increase in the money supply in prior recessions, as shown below (which is the “Austrian money supply,” calculated as M2 less small time deposits and retail money market funds plus Treasury deposits at the Fed).
This massive money creation resulted in the highest inflation rates in over forty years, with the latest CPI report showing inflation at 8.6 percent, well above the Fed’s 2 percent target. And now that money supply growth has slowed substantially to only 7 percent —and the Fed-controlled monetary base (currency plus bank reserves at the Fed) is now declining 2.6 percent year over year — the economy is starting to slow.
Recession Signs Are Mounting…
Economic growth has already weakened substantially. US gross domestic product fell 1.4 percent in the first quarter of 2022 and the Atlanta Fed is now estimating 0.0 percent GDP growth in the second quarter.
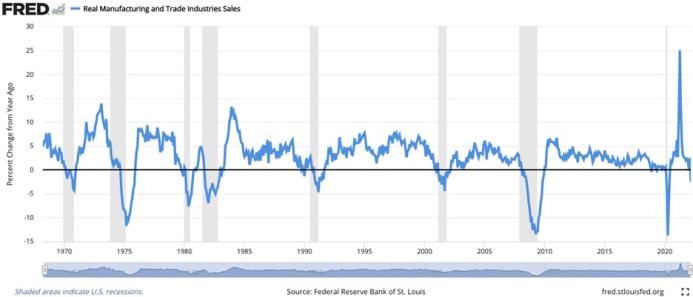
Real personal income is down 3.5 percent year over year, and was down 17 percent in March, the biggest decline in over sixty years. Real manufacturing and trade sales are now down 2.5 percent year over year. This broad sales measure only declines in recessionary periods, as shown below (recessionary periods are shaded gray).
Interest rates have been skyrocketing due to high inflation and slower money supply growth. The ten-year Treasury yield increased from 1.19 percent last summer to 3.25 percent now, while the two-year Treasury yield increased from 0.13 percent last summer to 3.17 percent now. The thirty-year fixed mortgage rate has risen from 2.77 percent last summer to 5.78 percent now, which is causing a collapse in mortgage applications and homebuilder sentiment.
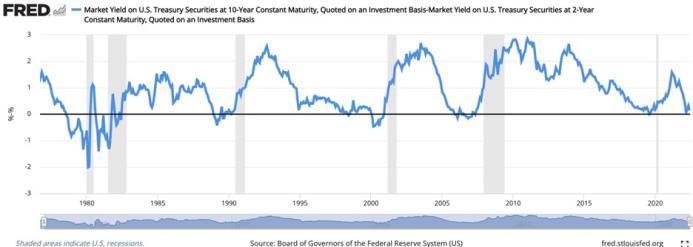
The “yield curve” spread between the ten-year and two-year Treasury yields has now flattened to only 0.08 percent. This spread “inverted” briefly a couple of months ago when the two-year yield rose above the ten-year yield. It could easily invert again soon. As shown below, a flattish or inverted yield curve spread between the ten-year and two-year Treasury yields has occurred before every recession in recent decades.
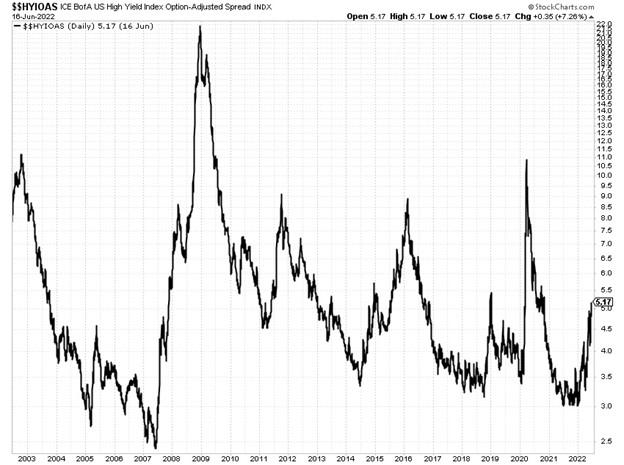
The spread between high-yield “junk” corporate bonds and Treasury yields has risen to the highest levels since the covid panic of 2020, as junk bond investors start to price in the risk of a recession, as shown below.
Copper is known as “Dr. Copper” for its ability to predict recessions due to its sensitivity to the economy. Copper prices have fallen 20 percent in the past three months.
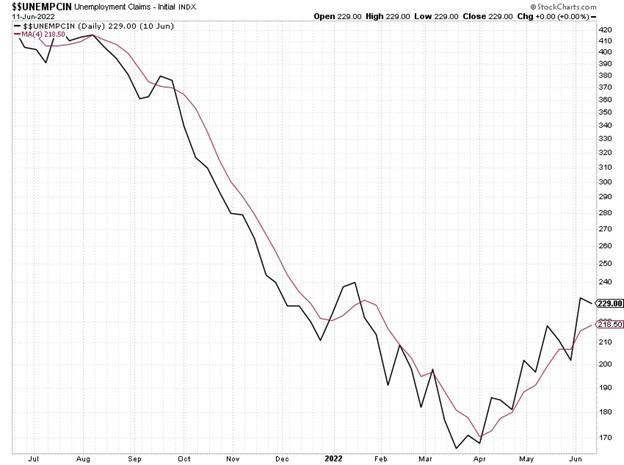
Initial unemployment claims are the best leading indicator of employment. They have been rising steadily for the past three months, as shown below (weekly claims are the black line and the four-week moving average is the red line).
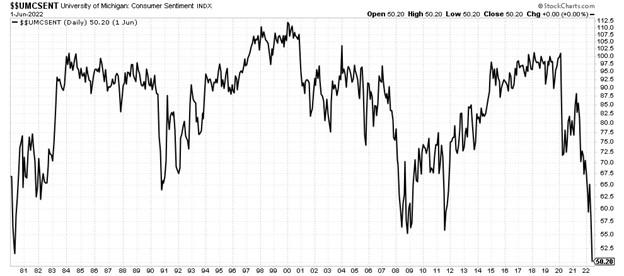
The University of Michigan Consumer Sentiment survey has fallen to the lowest levels in over forty years, as shown below.
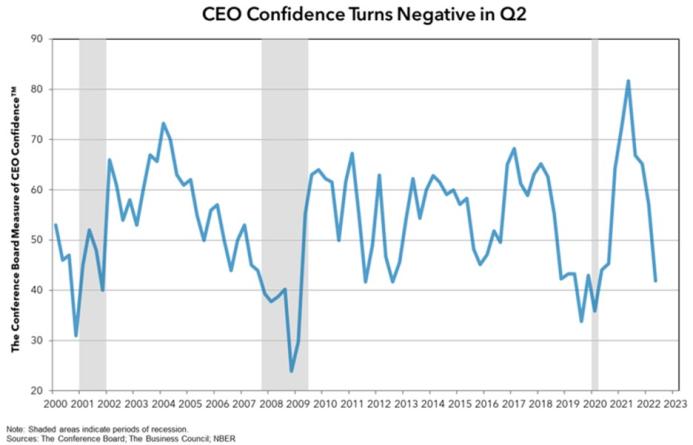
Similarly, The Conference Board CEO Confidence survey has fallen to recessionary levels, as shown below.
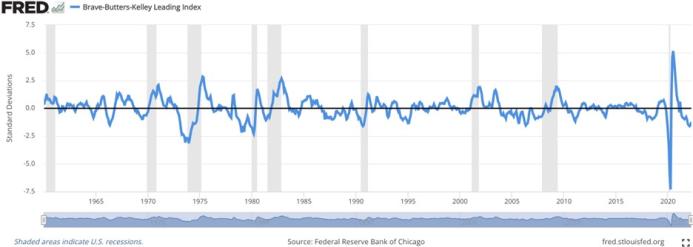
Proven leading economic indices have weakened to recessionary levels. The Economic Cycle Research Institute’s Weekly Leading Index, which leads the US economy by at least six months, has declined from a high of around +28 percent last year to –6.3 percent now. This highly regarded economic forecasting firm has recently gone public with their forecast for a coming recession.
The Brave-Butters-Kelley Leading Index has fallen well below the –1 threshold that signals with 86 percent accuracy that a recession is likely to start within eight months, as shown below.
Now the Fed Is Trying to Crash Financial Markets and Cause a Recession
Normally, the Fed would be slashing interest rates and printing money to try to prevent a recession and stock bear market at this point, which they tried and failed to do in the early 2000s Tech Bust and 2008–09 Great Recession.
But instead, the Fed is being forced to hike rates aggressively to try to bring inflation down. They already hiked the Fed Funds rate to 1.50 percent to 1.75 percent and will need to hike at least 1.50 percent more to catch up to the two-year Treasury yield.
The Fed is explicitly saying they want to lower bond, stock and housing prices and raise unemployment. They say they can do all of that without causing a recession. That is clearly a fantasy.
As Bill Dudley, former president of the New York Fed and vice chairman of the Fed’s Federal Open Market Committee, has said in recent months:
The Fed’s application of its framework has left it behind the curve in controlling inflation. This, in turn, has made a hard landing virtually inevitable…. To create sufficient economic slack to restrain inflation, the Fed will have to tighten enough to push the unemployment rate higher…. Getting inflation down will be costly, in terms of jobs and economic growth…. Investors should pay closer attention to what Powell has said: Financial conditions need to tighten. If this doesn’t happen on its own (which seems unlikely), the Fed will have to shock markets to achieve the desired response. This would mean hiking the federal funds rate considerably higher than currently anticipated. One way or another, to get inflation under control, the Fed will need to push bond yields higher and stock prices lower…. So far, financial conditions really haven’t tightened very much…. The Fed has to push up the unemployment rate, when the Fed has done that in the past, it has always resulted in a recession…. It is very unlikely that a year from now we will be at this level of bond yields this low and this level of stock prices this high.
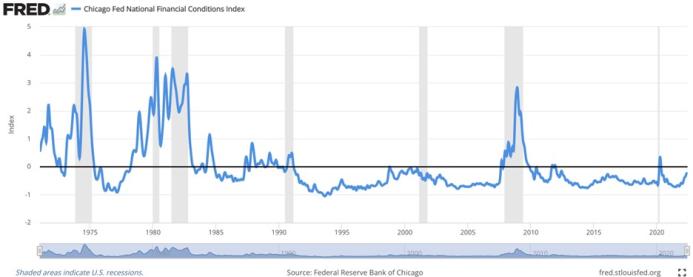
As shown below, despite the stock and bond bear markets, financial conditions remain very easy, according to the Chicago Fed National Financial Conditions Index.
Conclusion
If the Fed succeeds in tightening financial conditions enough to try to maintain their reputation as an “inflation fighter” (i.e., trying to lower the inflation they created in the first place), this will likely be the biggest government-caused economic catastrophe since the Great Depression, as we predicted here last year.

>>> American Pride Hits New Low

American Pride Hits New Low

Americans’ pride in their country has steadily fallen since Gallup started conducting a survey on the subject in 2001.
You will find more infographics at Statista
Now, as Statista's Katharian Buchholz reports, national pride in the U.S. has plummeted to an all-time low, as the fewest respondents in the history of the poll said they were extremely proud to be an American. The measure dropped to just 38 percent upon Gallup's latest survey in June 2022.
Adding up those Americans who felt extremely or just very proud of their country, the measure fell from 69 percent in 2021 to 65 percent in 2022. This is still 2 percentage point above an all-time low of 63 percent in 2020.
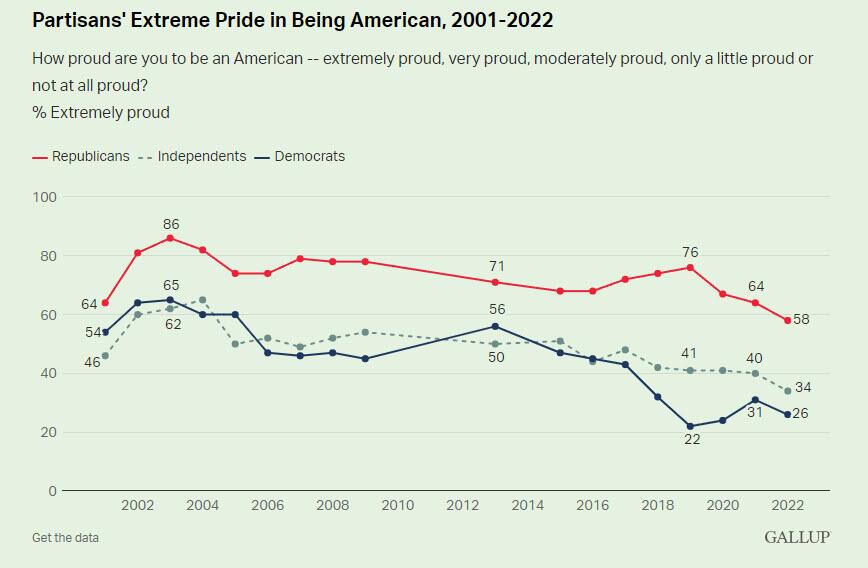
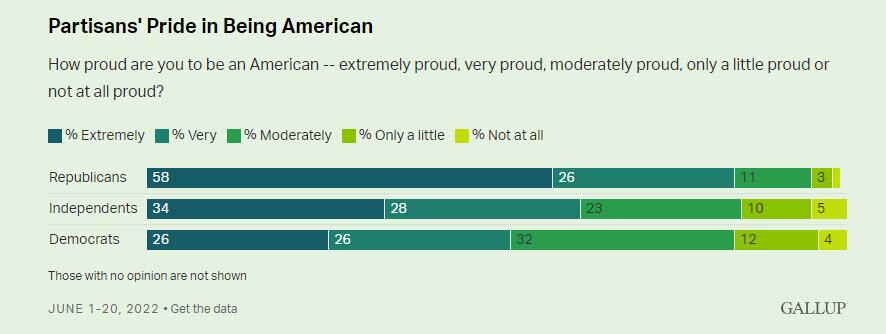
In terms of partisanship, Democrats have predictably seen the largest drop in national pride. Only 26 percent of Democrats responded that they were extremely proud of their country in 2022 – down five points from 2021 and 30 points since 2013. But Republicans were also affected, losing 18 percentage points since a recent high of 76 percent extremely proud respondents in 2019, landing at 58 percent saying they were extremely proud of America in 2022.
National pride, like many other topics in the U.S., has become intertwined in political polarization, having culminated in a record 54-point gap in feelings of extreme pride between Republicans and Democrats in 2019.
The survey also shows that older Americans are more likely to have extreme pride in the U.S. when compared with younger ones, while men are also much more likely than women to show extreme national pride.