China June FX Outflows Are The 2nd Highest Since The Covid Crash
With China's economy slowing to levels not seen this century...
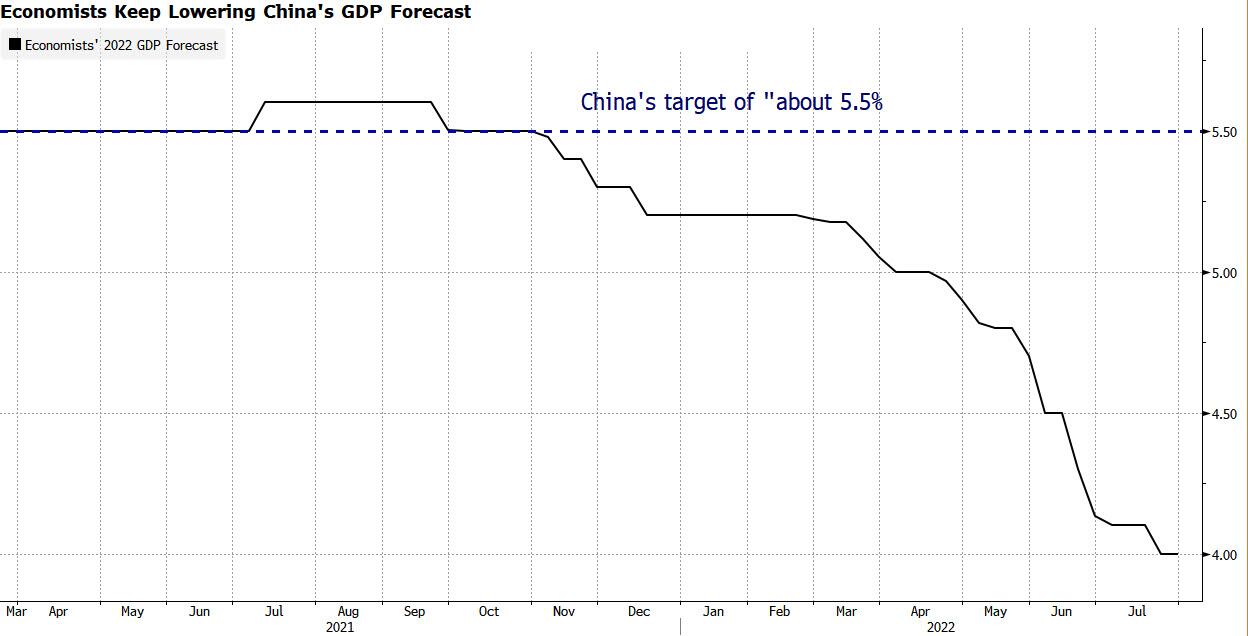
... and its financial system in danger of disintegration should the housing crash escalate further (which is why in a sharp reversal to months of non-action, overnight Beijing launched a multi-billion fund to support struggling developers), many have been wondering how long will local oligarchs wait before (quietly) pulling their money out of the country.
Well, according to the most accurate gauge of FX flows, June saw another month of net outflows of around US$9BN, in comparison to inflows of US$2bn in May, the biggest outflow since February and the second biggest outflow in two years going back to the Covid crash.
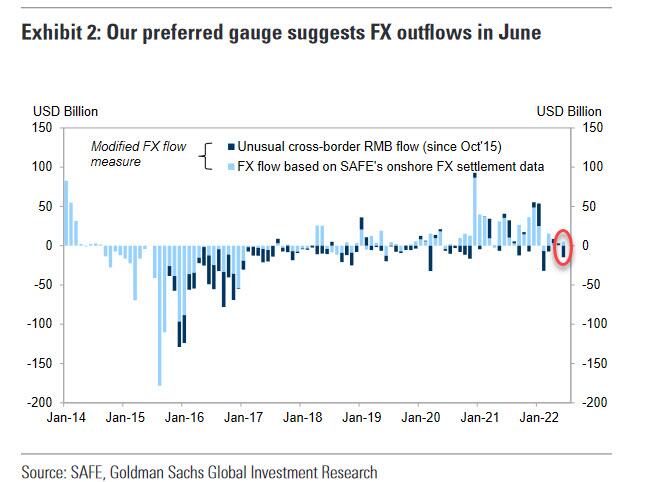
Cross-border RMB flows suggest net payments of RMB from onshore to offshore, which was consistent with the continued bond outflows.

Here are the main highlights:
1. In June, there were US $4BN in net inflows via onshore outright spot transactions, and US $2BN inflow via freshly entered and canceled forward transactions. Another SAFE dataset on “cross-border RMB flows” shows that domestic banks made net RMB payments of $15BN from onshore to offshore. A preferred FX flow measure therefore suggests in total $9BN outflows in June, in comparison with $2BN inflows in May.
2. Current account saw small net inflows: Goods trade surplus translated into $25BN inflows in June, vs $8BN in May. Here Goldman notes that while goods trade surplus rose to a record-high level of $98BN in June, the conversion ratio of goods trade surplus remained low at 26%, vs an average of 39% in the prior six months. Previous analyses suggested the conversion rate tends to decline when CNY weakens and interest rate spreads narrow. According to SAFE, corporates' FX hedging ratio increased to 26% in 1H 2022, 4% higher than the same period last year. Services trade deficit remained muted at $6BN. Income and transfers account showed an outflow of $16BN in June, partially on seasonality.
3. Portfolio investment showed outflows in June. Stock Connect data suggests more northbound buying of equities (relative to southbound buying) in the month, and thus on a net basis, translates into around $4BN inflows through Stock Connect in June. China Central Depository & Clearing and Shanghai Clearing House data suggest foreigners continued to reduce their holding of RMB bonds by US$13.9bn in June, vs US$16.3bn outflows in May.
4. Official FX reserves (released earlier in the month) fell to US$3,071bn in June from US$3,128bn in May. Estimating for FX valuation effects would have lowered FX reserves by $34BN in June, so after adjusting for FX valuation effects, FX reserves declined by US$23bn in June. Note that decline in bond and equity prices might have also contributed to the overall decline in reported FX reserves through asset price valuation effect, although SAFE does not release the exact decomposition of China’s FX reserves.
Borrowing Among Junk-Rated Firms Slows to a Trickle
A combination of higher funding costs and ratings upgrades trims the supply of high-yield bonds
Companies with speculative-grade credit ratings have slowed their pace of borrowing, illustrating how rising interest rates have upended the pandemic-driven boom.
Junk-rated companies have raised roughly $74 billion so far this year, just a quarter of the nearly $300 billion from the same period last year, according to Refinitiv.
That has led to an $80 billion drop in the net supply of high-yield bonds, a figure that is expected to grow to $130 billion by the end of the year, according to Goldman Sachs Group Inc. GS 0.06%▲ Such a fall would mark the biggest annual decline on record.
Yet the market isn’t ringing alarm bells.
The extra yield investors demand to hold junk bonds over U.S. Treasurys has risen to 5 percentage points from 3.1 points in January. That is well below the recent high of 11 points in March 2020.
Historically, the spread averages between 3.75 and 4.5 points, according to Seth Meyer, portfolio manager at Janus Henderson Investors.
“The market is implying some level of stress, but no reason to panic,” he said.
High-yield bonds trading in the secondary market still total a lofty $1.4 trillion, fueled by the nearly $900 billion in new junk bonds that came to the market in 2020 and 2021. Back then, easy monetary conditions during the Covid-19 pandemic allowed companies to raise cash cheaply and reduce their overall debt.
Higher funding costs are now discouraging some companies from issuing debt as the Federal Reserve rapidly raises interest rates and tightens financial conditions. The yield-to-worst, or the lowest rate an investor can expect to earn short of a default, on the USD High Yield index recently hit 8.62% before easing to 7.92% last week. That is up sharply from 4.2% at the start of the year.
Ratings upgrades have contributed to the declining supply as well. Roughly $64 billion of bonds have migrated into investment-grade territory from speculative status, while only $19 billion of bonds that were investment grade have been downgraded to junk.
Accelerating inflation and higher interest rates began to put pressure on speculative bonds at the start of the year when stocks and bonds fell in lockstep. Investors pulled about $45 billion from high-yield bond funds in the first half, the highest two-quarter total since at least 1992, according to Refinitiv.
So far this year, high-yield bonds have fallen 10%, while investment-grade-rated bonds have dropped 14%. Despite the worrying economic backdrop, junk bonds outperformed their higher-rated peers this year.
“This is the best high-yield bond market in over two decades, in terms of credit quality and liquidity positions” said Lotfi Karoui, chief credit strategist and head of credit research at Goldman. “This is not an old-fashioned, corporate-led recession. Fundamentally, the high-yield market is in good shape.”
Bonds rated double-B, which are one notch below investment grade, comprise 53% of the high-yield space. That is up 10 percentage points from a decade ago, according to the Intercontinental Exchange ICE -0.14%▼. Bonds in the lowest category, triple-C, have dropped to just 11% of the total high-yield market, near historic lows.
Energy companies, the largest constituents of the high-yield universe, weighed on the asset class in previous years. But macroeconomic drivers such as the Russia-Ukraine war and a resurgence in demand for oil sent energy stocks soaring in the first half of the year, even as the broader market dropped sharply.
“Energy firms have deleveraged aggressively, and many posted record performances this year,” said John McClain, portfolio manager for high-yield and corporate credit strategies at Brandywine Global. “They are far more focused on returning cash to shareholders now than in the past.”
Callon Petroleum Co. CPE 6.67%▲ was one of the few high-yield companies to issue debt in the second quarter. The Texas-based oil and natural-gas company issued a $600 million bond at 7.5% last month to help fund redemptions of existing debt due to mature soon. The securities redeemed include a bond that paid 6.125% due in 2024, and a riskier so-called second lien loan that paid 9%, due in 2025.
Pointing to an improved leverage profile, Fitch assigned B-plus ratings to that issue and the company’s previous issue, a higher mark than Callon’s long-term B rating.
“We were able to lower our overall interest-rate expense and improve our long-term debt structure,” said Kevin Smith, director of investor relations at Callon Petroleum.
Elsewhere, Delta Air Lines Inc. DAL 0.19%▲ recently unveiled a $1.5 billion tender offer to repurchase several bonds due over the course of the next few years, with coupon rates ranging from 3.800% to 7.375%.
“Delta Air Lines’ tender is focused on higher coupons, but shows there is still a lot of balance-sheet maintenance to be done in the high-yield space,” said Mr. Meyer of Janus Henderson Investors.
Aviation sector will be disrupted for years, Qatar Airways boss says
Staff shortages in Europe are affecting the carrier most as the industry struggles to shake off pandemic impact
The chief executive of Qatar Airways has warned that disruption across the aviation industry will last for years as companies recover from the effects of the pandemic.
“Covid has damaged the supply chain of the industry . . . I think that it will last for a couple of years — it is not going to go away tomorrow,” Akbar Al Baker told the Financial Times in an interview.
Labour shortages in Europe, delays in aircraft deliveries from manufacturers and a lack of spare parts had all affected Qatar Airways, he added.
Guillaume Faury, chief executive of the world’s largest plane maker Airbus, last week said he expected supply chain issues to continue into next year, with manufacturers facing shortages of raw materials, spare parts and electronic components.
In the case of Qatar Airways, it is the staff shortages in Europe that are having the greatest impact, Al Baker said, because of disruption to flights that is having knock-on effects on the airline’s Doha hub.
This month Heathrow airport imposed an unprecedented passenger cap on airlines to try to avoid more disruption, drawing a furious reaction from Qatar’s regional rival Emirates.
Al Baker sits on the board of London’s Heathrow as a representative of the Qatari sovereign wealth fund, a shareholder in the airport.
He criticised Heathrow for not giving airlines more warning about the passenger cap, which he said was “very difficult to digest”. But he added that the problems were systemic across Europe, and not only at Heathrow.
Qatar Airways is also the largest shareholder in IAG, which owns British Airways, making Al Baker an influential figure in UK aviation.
He has previously been outspoken in his criticism of BA, but offered his full support to the airline’s chief executive Sean Doyle. BA has suffered some of the worst disruption this summer.
“IAG has a huge potential, and I’m sure that in a not too long time they will turn around and be what they were pre-pandemic,” he said. “Keep in mind that they are doing a lot to improve standards and services,” he added.
IAG’s shares are trading at about 70 per cent below their pre-pandemic levels, and BA has been forced to cancel around 30,000 flights this year because of its own staffing problems and disruption at airports.
Al Baker has also been involved in a legal battle with Airbus this year over an allegation that one of its best-selling planes, the A350 wide-body, is defective because of damage to its surface.
He said the dispute, which is being heard in London’s courts, will not stop him from buying more Airbus aircraft in the future.
The manufacturer has said its aircraft are safe, pointing out that no other operator of the jets had grounded their planes.
Despite the pandemic and supply chain problems, Qatar Airways reported a rare industry profit of $1.5bn in the year to the end of March, boosted by its cargo operations.
The airline continued to fly throughout the pandemic and even added routes to many destinations.
Gold Fields defends $5.2bn Yamana bid
South African miner says Canadian target at risk of being snapped up by rivals
The chief executive of South African miner Gold Fields has defended the timing of its $5.2bn bid for Yamana Gold, arguing the “opportunity” to create the sector’s fourth biggest producer might have disappeared if it had waited.
Chris Griffith said Gold Fields was aware that Yamana had talked to other companies as it prepared its all-stock offer.
“We know that other companies are interested in some of the assets,” he said in an interview with the Financial Times. “So I think it is not a certainty these assets will be around in two to three years’ time.”
Shares in Gold Fields slumped 20 per cent on the day the deal was announced in May, with investors alarmed at the 34 per cent premium offered for Toronto-listed Yamana.
Redwheel — a top investor in Gold Fields, which controls 3 per cent for clients — called on Griffith to withdraw the offer and focus on its “excellent organic growth options”, which include the Salares Norte gold mine in Chile, where production is due to start early next year. Redwheel said Gold Fields has “ample time to be opportunistic over the next few years rather than rushing into a significantly dilutive acquisition today”.
If the deal goes ahead Gold Fields shareholders will end up holding 61 per cent of the combined company, which will have a market capitalisation of more than $12bn at current prices.
Griffith, who became chief executive in April 2021, said he always knew the deal would require “substantial engagement” with investors. “Many of the Gold Fields shareholders don’t really know Yamana and the Yamana assets, and likewise with Yamana, many of them won’t know Gold Fields,” he said. “We still see a really, really strong underlying strategic rationale for this deal.”
Gold Fields, which was founded in 1887, argues that buying Yamana will add operations in Canada, Argentina, Chile and Brazil, and provide the Johannesburg-listed company with an extensive exploration pipeline to complement its portfolio of cash generative but mature mines.
Gold Fields will produce 2.3mn ounces of gold this year, rising to 2.8mn in 2024. However, this will fall to as low as 2.1mn by 2030 without a deal because of a natural decline in production.
Griffith said the offer price for Yamana was determined after a seven month due diligence process, and that it had to offer a large premium because the Canadian company was trading at a discount to net asset value and investors would have baulked at a lower price. Yamana is currently trading at a 12 per cent discount to the terms of the offer, a signal that some investors do not believe the deal will happen.
For the deal to go ahead, the transaction requires 67 per cent approval from Yamana shareholders and 75 per cent approval from Gold Fields investors at meetings later this year.
Griffith said he was confident that Gold Fields’ biggest shareholder, South Africa’s state asset manager Public Investment Corporation, would vote in favour of the transaction. “All the discussions that we’ve had with the PIC have been positive,” he said.
However, if the deal is voted down Griffith said Gold Fields would not be on the hook for a $450mn break fee and would continue to look for deals to underpin future growth.
“I think it would be a shame if this was voted down but it doesn’t mean that we are out of options and we can’t look at other options,” he said. “But they will not be . . . in our view of the same quality.”
Beijing detains high-flying Tsinghua semiconductor boss, report says
Former Xinjiang shepherd Zhao Weiguo is latest aggressive dealmaker to fall foul of Xi Jinping’s government
Zhao Weiguo, the former head of an expansive Chinese conglomerate with state backing and deep investments in the global technology sector, has been placed under investigation by officials in Beijing, according to local media.
The 54-year-old, who led cash-strapped chipmaking giant Tsinghua Unigroup for a decade, has been out of contact after being taken from his home by authorities in mid-July, reported Caixin, a Chinese business publication.
The Financial Times has not independently verified the case. Tsinghua did not immediately comment. No further details on the investigation were provided.
The report of Zhao’s detention follows years of intensifying scrutiny of state-backed Tsinghua by investors and the Chinese government after Zhao struggled to repay and refinance the company’s large debts.
The company originated from Beijing’s Tsinghua University, China’s most prestigious engineering school, in the late 1980s. Zhao took control in 2009.
He climbed from obscurity herding animals in Xinjiang, China’s western region, to study at Tsinghua in the 1980s. He went on to make a fortune in property and forged ties with senior members of the Chinese government.
Zhao especially benefited from state support during the administration of Hu Jintao and is believed to maintain a close personal relationship with the former president’s son, Hu Haifeng, according to analysis by Cercius Group, a Montreal-headquartered consultancy specialising in elite Chinese politics. Zhao has denied ties to Hu Haifeng.
His standing with Beijing has been clouded by tensions between Hu Jintao and China’s current president Xi Jinping, the country’s most powerful leader in a generation.
Still, as recently as 2017, the group secured about $22bn from state investors to fund its computer chip acquisitions.
But Tsinghua defaulted on a domestic bond in late 2020. Its total liabilities were estimated at more than $31bn. The default shocked investors given the company’s ties to the Chinese state, and it entered a court-ordered restructuring last year.
Under Zhao, the company bought French chipmaker Linxens and took a majority stake in data networking business H3C from Hewlett-Packard. Attempts at multi-billion-dollar acquisitions of US tech groups Micron Technology and Western Digital failed.
But following years of uncertainty over its future, the company said in a filing this month that it was officially under the ownership of new investors including private sector groups Wise Road Capital and Beijing Jianguang Asset Management, as well as a number of state-affiliated funds. Taiwan’s Foxconn, an Apple supplier and tech assembly giant, has taken a stake in the group via Wise.
Zhao’s downfall also marks the latest in a series of epic corporate collapses among a clutch of previously aggressive Chinese dealmakers, including state-backed group CEFC, insurer Anbang, travel-to-finance conglomerate HNA and financier Tomorrow Group.
Some of the highest-profile billionaires behind China’s debt-fuelled acquisition spree of the past decade have been subsequently jailed or detained, usually on charges relating to corruption.
They include CEFC founder Ye Jianming, Anbang chair Wu Xiaohui as well as HNA chair Chen Feng and chief executive Adam Tan and Tomorrow Group boss Xiao Jianhua.
While many of the tycoons chased foreign property and other prestige acquisitions, Zhao’s investments more closely tracked one of Beijing’s core industrial policy ambitions: for China to be free from its dependence on foreign-made computer chips.
Several of China’s most promising chipmaking groups are in Tsinghua’s stable, including Yangtze Memory Technologies, which aims to rival South Korea’s Samsung and SK Hynix in memory chips.
YMTC, which was founded in 2016 and enjoys state backing, has already more than tripled its production to nearly 5 per cent of the global market. However, the Wuhan-based company has caught the attention of the Biden administration, which is probing whether it supplied Huawei with chips in a potential violation of US export controls.