Asian stocks declined as fresh doubts emerged on whether the Federal Reserve has finished tightening policy, while the Australian dollar retreated after the central bank raised interest rates. An Asian equity benchmark was set to snap a four-day winning streak as major indexes traded lower. South Korea’s Kospi Index fell over 3% after jumping by the most since 2020 on Monday following a renewed ban on short-selling. Contracts for US stocks slipped. Traders are predicting the Fed will lean against the recent easing in financial conditions by saying it will keep its options open on policy. Minneapolis Fed President Neel Kashkari said it’s too soon to declare victory over inflation, despite positive signs that price pressures are easing, and a host of Fed officials — including Chair Jerome Powell — are due to speak over the next few days. Treasuries steadied after yields rose across the curve on Monday. Ten-year yields jumped eight basis points as sentiment was dented by a heavy slate of corporate debt sales and traders readied for a series of auctions beginning Tuesday. The dollar edged higher. Swaps are pricing in more than 100 basis points of rate cuts by the Fed by the end of 2024 from an expected peak rate of 5.37%. On Monday, investors also waded through the Senior Loan Officer Opinion Survey — known as SLOOS — which showed tighter standards and weaker demand persist at US banks. Meanwhile, China reported a deeper-than-expected decline in exports for October that highlighted continued slowdown in global trade and its own fragile economic recovery. The offshore yuan was little changed after the figures were released. oil edged lower as an uncertain demand outlook and fresh doubts on the end of Fed’s tightening outweighed Saudi Arabia and Russia’s extension of supply cuts. US After Hours VMEO +16.1%, TRIP +12%, JELD +6.5% making nice moves following earnings; AMRC -11.7%, SANM -10.1% struggling after earnings; KMI -0.2% steady on NexEra Energy (NEE) M&A news.
Nikkei -1.34% Hang Seng -1.47% CSI -0.34% Shanghai -0.02% Shenzen +0.14%
Eur$ 1.0704 CNH 7.2883 CNY 7.2819 JPY 150.36 GBP 1.2322 CHF 0.9008 RUB 92.5908 TRY 28.4675 WTI$ 79.94 -1.08% Gold 1,971 -0.34% BTC 34,960 -0.21% ETH 1,894 +0.09%
S&P -0.27% Nasdaq -0.23% EuroStoxx -0.41% FTSE -0.24% Dax -0.35% SMI -0.19%
Macro :
- JPMorgan’s Kolanovic Says ‘Knee-Jerk’ Equities Rally Won’t Last
- FTSE's 10x P/E Looks Low But 4.3% 10-Year Brings Double Whammy
- Citadel’s Griffin Says Global Investors Have to Invest in China
Keep an eye on :
Keep an eye on :
- AIBG ID : Ireland Plans to Sell About 5% Stake in AIB Group: Terms
- ABNB US : Italy Seizes €779m From Airbnb, Alleging Unpaid Taxes
- AOX GY : Alstria Office 9M Revenue EU142.1M Vs. EU137.1M Y/y
- AMS SM : Amadeus 3Q Adjusted Profit Beats Estimates
- AMS SM : Amadeus to Buy Back Up To 8.81m Shares for Up To EU625.3m
- BAKKA NO : Bakkafrost 3Q Operating Ebit Misses Estimates
- BIRK US : Birkenstock IPO Was Too High, Say Some Banks That Took It Public
- CAP FP : Capgemini 3Q Revenue Meets Estimates
- CPRI US : Capri Slides on FTC Requests for More Info on Tapestry Deal
- CGG FP : CGG 3Q Segment Revenue Beats Estimates
- CGG FP : CGG 3Q Segment Revenue Beats Estimates
- CLASB SS : Clas Ohlson Oct. Online Sales +17%
- CNHI US : CNH Industrial announces voluntary delisting from Euronext Milan and single listing on the New York Stock
- CPG LN : Compass Sees 4Q Revenue $1.1B to $1.2B, Est. $1.12B
- DTG GY : Daimler Truck Confirms Guidance Despite Industrial Slowdown
- DEMANT DC : Demant Narrows FY Organic Revenue Forecast
- DB1 GY : Deutsche Börse Plans to Buy Back €300 Million of Shares
- ZIL2 GY : ElringKlinger 3Q Ebit Misses Estimates
- ENEL IM : UOL Brasil: Ministry of Justice gives Enel 24 hours to provide information about blackout in São Paulo
- ENGI FP : Engie Boosts FY Recurring Net Income Forecast
- EVK GY : Evonik 3Q Adjusted Ebitda Beats Estimates
- FRA GY : Fraport 3Q Ebitda Beats Estimates
- GT US : Goodyear 3Q Net Sales Misses Estimates
- ICOS IM : Intercos Revenue Beats, Ebitda a Slight Miss
- KPN NA : KPN Sees 2024 Adj. EBITDA AL About EU2.48B, Est. EU2.57B
- MC FP : Birkenstock IPO Was Too High, Say Some Banks That Took It Public
- KN FP : Natixis Sees Opportunities in Japan as Bond Yields Rise
- NEXI IM : CPP, Francisco Partners Among Firms Interested in Nexi: MF
- NOEJ GY : Norma Maintains FY Adjusted Ebit Margin Forecast (1)
- NOVOB DC : Novo Nordisk Initiates New Share Buyback of Up To DKK 4.1b
- OCI NA : OCI 3Q Adjusted Ebitda Misses Estimates
- PGHN SW : Partners Group Is Said in Talks to Buy Pipeline Inspector Rosen
- PSPN SW : PSP Swiss Maintains FY Adjusted Ebitda Forecast, Beats Estimates
- PST IM : Poste Italiane Boosts FY Ebit Forecast, Beats Estimates
- RAA GY : Rational 3Q Ebit Beats Estimates
- SAN FP : Rational 3Q Ebit Beats Estimates
- SHEIN IPO : Shein Is Said to Target Up to $90 Billion Valuation in US IPO
- SINCH SS : Sinch 3Q Ebitda Misses Estimates
- STORB SS : Storskogen 3Q Ebit Misses Estimates
- TIT IM : Telecom Italia Signed Transaction Pact With KKR on Netco
- O2D GY : Telefonica Deutschland 3Q Adjusted Oibda Meets Estimates
- TEP FP : Teleperformance SE 3Q Revenue Misses Estimates
- TOBII SS : Tobii 3Q Operating Loss SEK69M, Est. Loss SEK43.7M
- UBSG SW : UBS 3Q Net Loss $785M
- UBSG SW : UBS’s Kelleher Says Next Crisis Could Happen in Shadow Banking
- WEW GY : Westwing Group Sees FY Adjusted Ebitda EU13M to EU19M
- WE US : WeWork’s Anticipated Bankruptcy Is Disappointing, Neumann Says
- XPP LN : XP Power to Raise Up to £45.4m Gross in Share Issue
- XPP LN : XP Power to Raise Up to £45.4m Gross in Share Issue
>>> Up
* Alm Equity Raised to Hold at Arctic Securities; PT 365 kronor
* HP Inc Raised to Buy at Edward Jones
* Meriaura Group Raised to Reduce at Inderes; PT 0.47 kronor
* Temenos Raised to Reduce at Baader Helvea; PT 64 Swiss francs
>>> Down
* Temenos Raised to Reduce at Baader Helvea; PT 64 Swiss francs
>>> Down
* Andritz Cut to Underperform at BNPP Exane
* Asos Cut to Hold at Investec; PT 370 pence
* Diageo PT Cut to 2,750 pence from 2,950 pence at Deutsche Bank
* Femsa ADRs Cut to Market Perform at Itau BBA; PT $127
* Foot Locker Cut to Inline at Evercore ISI; PT $23
* Hikma Cut to Hold at Jefferies; PT 1,940 pence
* Nilfisk Cut to Hold at SEB Equities; PT 129 kroner
* Nilfisk Cut to Hold at SEB Equities; PT 129 kroner
* VGP Cut to Neutral at JPMorgan
* Viafin Service Cut to Accumulate at Inderes; PT 14 euros
>>> Initiation
>>> Initiation
* Basilea Rated New Buy at Pareto Securities; PT 64 Swiss francs
* Cytokinetics Rated New Buy at B Riley; PT $66
* S4 Capital Reinstated Equal-Weight at Morgan Stanley
* Schott Pharma Rated New Hold at Jefferies; PT 30.40 euros
* Schott Pharma Rated New Buy at Citi; PT 33.50 euros
* Schott Pharma Rated New Buy at Deutsche Bank; PT 34 euros
* Schott Pharma Rated New Neutral at BNPP Exane; PT 31 euros
* Team17 Rated New Overweight at Barclays; PT 355 pence
>>> Call
* Energy Sector Remains Attractive, Repsol Cut: Morgan Stanley
* Team17 Rated New Overweight at Barclays; PT 355 pence
>>> Call
* Energy Sector Remains Attractive, Repsol Cut: Morgan Stanley
* Hikma Cut to Hold at Jefferies, Momentum May Be Reaching Peak
How much to worry about rising defaults
Sooner or later, we are all but guaranteed to get some trouble in corporate debt markets, for the simple reason that rates have risen by almost 5 percentage points in just a few years. Some increase in corporate distress is foreseeable, maybe even healthy. But will it stop at “some”? Is it a matter of the normal credit cycle returning, and companies with fragile financing heading for bankruptcy or restructuring? Or might we be headed for a credit crisis large enough to cause problems at financial institutions, causing market and economic contagion?
These are the questions posed by an excellent Big Read by our colleague Harriet Clarfelt. You should read the whole thing, but we’ll recap the main points.
It begins by disclaiming that things now are fine — that most current defaults are caused by industry- or company-specific issues. But there are worries about the future, as monetary policy continues to squeeze companies and the economy slows. We noted four in the piece: small companies, leveraged loans, extend-and-pretend tactics and private markets. In that order:
[On smaller firms] A recent survey by the National Federation of Independent Businesses showed that US small-caps were paying almost 10 per cent interest on short-term loans in September, up from lows of 4.1 per cent in mid-2020
[On loans] Cash interest coverage on newly issued loans had dropped to 3.16 times by the end of the third quarter, its lowest level since 2007 if compared with previous full years. Interest coverage has also declined for existing loans, data from PitchBook LCD shows, signalling that earnings are not growing quickly enough to keep pace with rising borrowing costs
[On extend-and-pretend and private markets] “If we look at the first three-quarters of this year, distressed exchanges [a type of workout for a faltering company] comprise roughly two-thirds of all corporate family defaults in the US,” says Julia Chursin, senior analyst at Moody’s. She adds that “the majority of them — 78 per cent — were done by private-equity owned companies”
Right now, relatively few companies are getting into trouble, but the trend is poor. Moody’s keeps a list of companies that are rated triple-B-negative or lower, that is, companies which are either C-rated (“of poor standing and subject to very high credit risk”) or right on the cusp of it. The Moody’s chart below shows that the size of that list, in both absolute numbers and as a percentage of the whole high-yield (“speculative grade”) universe, are only slightly above the long-term average, while the default rate is still below the levels of 2015-16, when low oil prices caused a series of defaults in the energy sector:
What that chart shows in the future will be determined by how two vectors — the path of interest rates and probability of recession — interact. When debt needs to be rolled over, the cost of new debt and corporate cash flows must co-operate to avoid problems.
To begin with the first vector, rates, the question is how long companies can wait, hoping for inflation to subside and rates to fall. Much, perhaps too much, is made of the “maturity wall”, the point in the future when a large bolus of debt will have to be refinanced. Cramming all high-yield debt together into a single sum, without adding a measurement of companies’ ability to pay, doesn’t tell you all that much. That said, aggregate maturities give some sense of how bad things might get at their worst, and when. And right now, the picture is not too bad in the US, at least for the next two years. The junk bond and leveraged loan markets total $3tn in outstanding debt between them. For less than $150bn of refinancing to cause a credit market contagion, economic conditions will have to be pretty bad.
Still, a high-rate, recessionary world could be catastrophic for borrowers, who would be pinched by both rising interest expense and falling sales. But such a stagflationary outcome looks remote. More likely is either a low-rates recession, as the Federal Reserve cuts rates to boost activity, or a soft landing where the Fed lowers rates only a little.
A high-rates soft landing is not a common occurrence in history, but chances are it would be survivable. Economic growth gives companies options for staving off default. Capex, a significant expense that is somewhat discretionary, can be cut; so can employment levels. In a pinch, companies can also reduce debt by raising equity, so long as economic conditions are OK. Interest rates are important, but for companies with a functional business model in a growing economy, they are one expense line out of many.
On the other hand, a recession with low rates has happened many times before, and it is plainly bad for creditors, and could be worse this time. Even in a recession, rates might not be as low as the pre- and early-pandemic period in which today’s corporate balance sheets were built. (Virtually every episode of rising default rates in the high-yield bond market is explained by either recession or plunging oil prices, Marty Fridson of Lehmann Livian Fridson Advisors points out.)
So, what are the chances that we get a recession combined with only moderately lower rates, one that starts late enough or lasts long enough to coincide with a high volume of refinancing demand? That is the (slightly long-winded) question.
It is important to note that bond markets are emphatically not signalling trouble ahead. Spreads over Treasuries of triple-B (lowest rung of investment grade) and double-B and single-B (upper parts of high yield) bonds were higher earlier this year, before long term interest rates jumped, and not far from pre-pandemic levels:
Banks, which have been notably cautious lately, seem to be relaxing a bit, too. The Fed’s latest loan officer survey recently came out, and reported that fewer banks are tightening lending standards for business loans:
So (consistent with our case for economic optimism yesterday) while there is no doubt that plenty of individual firms will be forced into restructuring by high rates, the chances of a corporate debt crisis seems low as of now.
But there is an important proviso. One complication in gauging credit risks is that some of the riskiest debt has migrated to private markets. That has been a factor in making public debt markets, especially for high-yield bonds, less risky. Fridson estimates that if default patterns similar to the mild recession in 2001 repeat in 2023, the high-yield bond default rate would peak at 8.5 per cent, versus 11.3 per cent in the dotcom bust, because of better company quality in the public markets. Moody’s forecasts that in a non-recession scenario, the default rate will stay below 5 per cent across public speculative-grade debt.
But even short of a recession, rising defaults may matter most in private markets, which mostly use floating-rate debt. The early signs are troubling. As Harriet’s piece notes, PE-backed distressed exchanges make up a major chunk of this year’s defaults.
The problem for PE is that it is getting harder to shunt losses on to creditors. Researchers have found that high-yield bondholders in leveraged buyouts underperform bond benchmarks, and the underperformance gets worse the more experienced the PE backer is. Enter private credit, which has snapped up LBO debt by offering faster, nimbler loan execution than public markets in exchange for fatter spreads and tighter contracts. If a company defaults, or needs a distressed exchange, someone somewhere must take a haircut. That is a recipe for a legal knife fight between private lenders and private equity investors, a fight both sides could lose. (Armstrong & Wu)
Local leaders seek to reverse 40 years of UK bus privatisation
Franchise network run by Transport for London, a local government body, hailed as a way forward
Nearly 40 years after local bus services across most of Britain were privatised, momentum is building to reverse the move in many areas.
Margaret Thatcher’s 1986 reforms were intended to increase competition and improve a service relied upon by millions of passengers a day. However, after years of declining ridership, local leaders have begun to unpick the overhaul by the Tory prime minister, arguing it has failed on every measure.
They point to the success of London’s extensive bus network, which was left untouched by deregulation and remains under the control of Transport for London, a local government body.
As bus journeys across the capital have grown, under a franchising model common across much of Europe by which private companies run services while TfL retains overall control, ridership elsewhere has fallen by 40 per cent since privatisation and car ownership has risen, according to government data.
Local leaders argue that adopting a similar franchising model to London’s across the country is essential both to closing the economic divide with the capital and to meeting climate change targets.
Liverpool is among those to have adopted the system. “The reason we’re franchising our buses is not based on ideology, but on simple economics,” said Steve Rotheram, Labour mayor of Liverpool city region. Public control would put “passengers before profit”, he said, by allowing local leaders to keep more of the income from fares and reinvest it in the network and in boosting productivity.
“We’ve got decades of evidence that a deregulated system leaves behind the very people who need it most,” he added.
Thatcher’s 1980s reforms allowed private operators across the UK, except for London and Northern Ireland, the choice of which bus services to run and how much to charge.
Buses remain by far the biggest form of public transport — accounting for about half of all journeys. But BBC analysis has found that, in some areas, networks have shrunk by up to half, as operators have cut less profitable routes and local authorities have been forced to withdraw subsidies in response to cuts in central government funding.
Rotheram has taken his cue from another Labour mayor in north-west England — Greater Manchester’s Andy Burnham — who in September began using the franchising model to bring buses back under public control by tapping into powers given to local authorities in 2017.
“I think in some ways it represents the coming of age of English devolution, in that a decision has been taken that rows back some of the misguided policies of the 1980s,” Burnham said at the time.
In recent weeks other Labour mayors, in West Yorkshire, Cambridgeshire and Peterborough, have announced plans to follow suit. The Labour government in Wales is also looking at similar changes.
Local politicians from other parties are also considering an overhaul of local bus services, including Andy Street, Tory mayor of West Midlands, Oxfordshire county council, run by Liberal Democrats and Greens, and Glasgow council, led by the Scottish National party.
Andrew Carter, chief executive of the Centre for Cities think-tank, said “rubbish” public transport was increasingly considered a factor in the poor economic performance of UK cities relative to those in other European countries.
Deregulation represented an “old experiment”, added Carter, one that is “universally regarded” across parties, cities and districts as “having failed”.
Research by data analyst Tom Forth in 2019 concluded that Birmingham’s size — and therefore access to its labour market — effectively halved during rush hour because of poor bus services. His research concluded that this could explain most of Birmingham’s productivity gap with its European comparators.
Those findings have been particularly influential in central government, which has begun to take a more active interest in bus policy, according to one local transport official.
A Centre for Cities paper on Glasgow’s public transport network that argued for a switch to franchising drew similar conclusions last month, estimating that better bus services could increase the city’s effective population by 24 per cent.
Graham Vidler, CEO of the Confederation of Passenger Transport, the trade association for the UK’s bus and coach sector, said he expected franchising to “only gain more prominence in the coming months”.
But he warned financial support was crucial. “In the end, it will take more than a change of regulatory framework to give millions of passengers the service they deserve,” because networks “require a real, sustained investment in the things that matter most to passengers.”
Alistair Hands, regional managing director at Arriva UK Bus, which runs services in London, Wales and Liverpool, said experience in the capital had shown franchised systems could work well, “when combined with measures to promote passenger growth”, such as bus priority lanes. Echoing Vidler, he said that included the need for sustained, long-term investment.
The strain on local government finances is seen as the biggest impediment to change. Regional mayors pushing for franchising have met resistance from council leaders worried about taking on further funding obligations given the dire state of budgets.
Upfront costs alone can run into tens of millions of pounds. Greater Manchester had to budget £85.7mn just for buying and refurbishing bus depots. Burnham has already proposed a hotel tax as one revenue stream once the existing bus funding package runs out in 2025.
Many local leaders believe more central government subsidies will be needed to build out networks. State funding for bus services is low compared to rail, despite a Department for Transport analysis of major bus schemes showing they “delivered benefits worth more than four times their cost”.
Although the UK government has committed new funding to English bus networks since 2019, passengers still only receive 32 pence in subsidy per journey, according to CPT analysis, compared to £3.32 for rail passengers. Scotland has larger gaps.
Sandy Easedale, owner of McGill’s, the largest independent bus operator in Scotland, who is opposed to the changes, warned that “hundreds of millions” of pounds in investment would be needed to create the sort of improved networks being mooted by local leaders.
“They want this wonderful service everywhere, which is fine, but somebody has got to pay for it,” he said. He promised to “fight tooth and nail in the courts” against any attempts to shift to franchising.
Albemarle warns of losing lithium market share to China as prices fall
World’s biggest producer has scaled back its growth plans at a time when Chinese rivals pursue development
Albemarle, the world’s largest lithium company, has warned it could lose market share to Chinese producers after a $4.2bn deal to buy an Australian rival foundered and a collapse in prices prompted a pullback on expansion plans.
The US company last week revealed a review — entailing a reduction and reordering — of its capital expenditure plans in response to investor concerns over spending heavily during a market downturn.
Last month Gina Rinehart, Australia’s richest woman, wrecked Albemarle’s bid to take over Liontown Resources, a crucial acquisition for the company to grow its pool of resources after she built up a strategic stake.
Kent Masters, chief executive of Albemarle, acknowledged the group would be likely to lose market share to Chinese rivals as plummeting prices for the metal vital to batteries in electric cars have led it to pursue a more conservative approach.
“We’re being a little more cautious and investing behind the market, so there’s a risk we lose that share,” he said. “This will probably be helpful for Chinese suppliers.”
Albemarle is on course to hold a 13 per cent share of the global market this year versus 63 per cent for Chinese companies, according to Fastmarkets, while it is the biggest lithium group by market capitalisation.
The scaling back of growth plans by Albemarle highlights a strategic dilemma facing western metals groups as they struggle to invest while commodity prices fall. In contrast, Chinese companies are pushing ahead with development plans, despite the weak market.
Metals analysts say the inability of western companies to invest when cash flows drop is creating a problem for the US and Europe in the race against Beijing for critical minerals in the EV supply chain.
Despite the bumper profits over the previous two years, lithium producers have huge outlays of spending to meet forecasts of a big jump in demand. Albemarle predicts the market will increase fourfold by 2030.
Lithium prices have dropped more than 70 per cent this year to just over $22,000 a tonne, according to Benchmark Mineral Intelligence, on weak EV demand in China and the battery supply chain using up stockpiled material rather than buying fresh material.
As a result of weaker prices, net income for Albemarle tumbled 65 per cent to $320mn in the third quarter and cut its annual sales growth forecast from 40-55 per cent three months ago to 30-35 per cent.
Executives at Albemarle said they were puzzled as to why lithium prices have fallen so low, given that they believe EV demand remains strong.
Despite the likes of LG Energy Solution, Tesla and General Motors warning that high interest rates would hit EV expansion plans, Albemarle believes global sales in 2023 are still on track to hit almost 15mn units, growth of more than 40 per cent year-on-year.
“What we would have thought and believed was that they wouldn’t have gone below $25 per kilogramme. They have. I think all that says is we are in for more volatility,” said Eric Norris, president of Albemarle’s lithium business unit.
“When you have prices that low, inventories that low and the market is still growing, you’re going to see a pretty hard bounce at some point,” he added.
Rinehart also threw a spanner in the works for another Australian deal for the battery metal after building a strategic stake in Azure Minerals that Chilean lithium powerhouse SQM agreed to buy.
Despite the risk of her intervening in deals, Masters insisted Albemarle still had appetite to consider acquisitions of Australian producers and said they have yet to give serious consideration to partnering with Rinehart.
US says reliance on Russian nuclear fuel presents national security risk
Dependence on supplies from Moscow-controlled Rosatom also threatens climate goals, official warns
US reliance on Russia’s nuclear fuel poses a critical threat to national security and climate goals, said a senior Biden administration official, who urged Congress to provide funds to rebuild its domestic supply chain and restrict imports from the country.
Kathryn Huff, assistant secretary for nuclear energy, told the Financial Times it was “gravely concerning” that about 20 per cent of fuel used by the US nuclear reactor fleet is supplied through enrichment contracts with Russian suppliers.
Russia controls almost 50 per cent of global enrichment capacity and had worked successfully to undermine the US nuclear supply chain over many years by dumping cheap enriched uranium products on world markets, she said.
“It’s really critical that we get off of our dependence, especially from Russia,” Huff said in an interview.
“Without action Russia will continue to hold on to this market . . . this is really important for national security, for climate, for our energy independence.”
The US and its allies imposed sanctions against Russia’s oil and gas industries following Vladimir Putin’s full-scale invasion of Ukraine last year, costing Moscow tens of billions of dollars in lost revenues. But Washington has refrained from preventing Russia’s nuclear giant Rosatom from selling nuclear fuel and enrichment services to US and western power plant operators, as there are few alternative supply sources.
The nuclear fuel supply chain begins with mining and milling uranium ore. But it is the chemical process of converting the ore into uranium hexafluoride gas and then enriching the uranium-235 isotope to a level of about 5 per cent that is required for standard forms of nuclear fuel — and this is dominated by Rosatom, experts say.
There are only a handful of western suppliers of enrichment for nuclear fuel, including France’s Orano and Urenco, a UK, German and Dutch consortium. Tenex, a subsidiary of Rosatom, is the only company in the world providing commercial sales of a new type of fuel called Haleu — high-assay low-enriched uranium — that is enriched to between 5-20 per cent and could power a new generation of smaller, more efficient reactors.
Huff said the Biden administration had asked Congress for an extra $2.16bn to support a strategy to incentivise US-based companies to boost enrichment and conversion capacity. The plan would make the Department of Energy a long-term buyer of last resort for companies to assure adequate fuel supply for the expanding future nuclear reactor fleet, she said.
However, the success of this public investment would depend on imposing long-term restrictions on Russian nuclear products and services, she said.
“We have seen in the past that the dumping of cheap Russian enriched uranium products has historically really damaged our fuel cycle and has brought us to where we are today,” said Huff, adding there was bipartisan support for nuclear energy in Congress.
A bill banning uranium imports from Russia passed a subcommittee in the House of Representatives in May. A similar bill is before the Senate.
Concerns about the west’s reliance on Russian nuclear products have helped push up the price of uranium and related products, as utilities seek alternative sources of supply.
“There is alignment in our industry to step away from Russia, but you need something to step to. We really need to increase capacity in that part of the supply chain,” said Maria Korsnick, chief executive of the Nuclear Energy Institute, an industry group in Washington.
The nuclear industry is growing as China and others expand their reactor fleet to meet emissions reduction targets while increasing baseload power capacity.
Huff said five to 10 contracts to build new reactors needed to be signed within the next two to three years if the US were to meet its 2050 climate goals.
“In the next two or three years we need to see those contracts in hand, or else we will not reach the commercial lift-off that is required to get to the amount of clean power we need for 2050,” she said.
The US is working closely with allies — Canada, France, Japan and the UK — to secure the supply chain and has begun funding some projects. It is supporting an expansion of capacity at Urenco’s enrichment plant in New Mexico, which is expected to be complete by 2027.
The Department of Energy has also co-funded a pilot project led by Centrus, which expects to produce its first batch of Haleu fuel within weeks.
“Legally, Russian materials are still available and being bought and sold,” said Daniel Poneman, Centrus chief executive. “But the politics around it have transformed dramatically and not all, but many of the current importers of Russian enriched uranium would like to move to other sources of supply.”
Hezbollah's Nasrallah & The Future Of The War
The expectations for Hizbullah leader Hasan Nasrallah’s speech on Friday were very high; even the U.S. National Security Council’s spokesperson at the White House admitted that they too were awaiting the speech. In the Arab world there was anticipation or a general wish that Nasrallah would declare an official entry into the larger war, thereby igniting a regional conflict that would change the shape of the Middle East.
Hizbullah, unwisely, increased expectations by releasing video teasers showing Nasrallah walking or seated. Israelis and much of the world were holding their breaths. Lebanese were nervous but hopeful that Nasrallah would take their plight into consideration.
But Nasrallah does not operate in a vacuum. There is a very complex context in which he does. In the Arab world, the Western-Gulf alliance has spent billions to demonize Nasrallah and to undermine his standing in the Arab and Muslim worlds; and his standing reached new heights in the wake of the 2006 war with Israel.
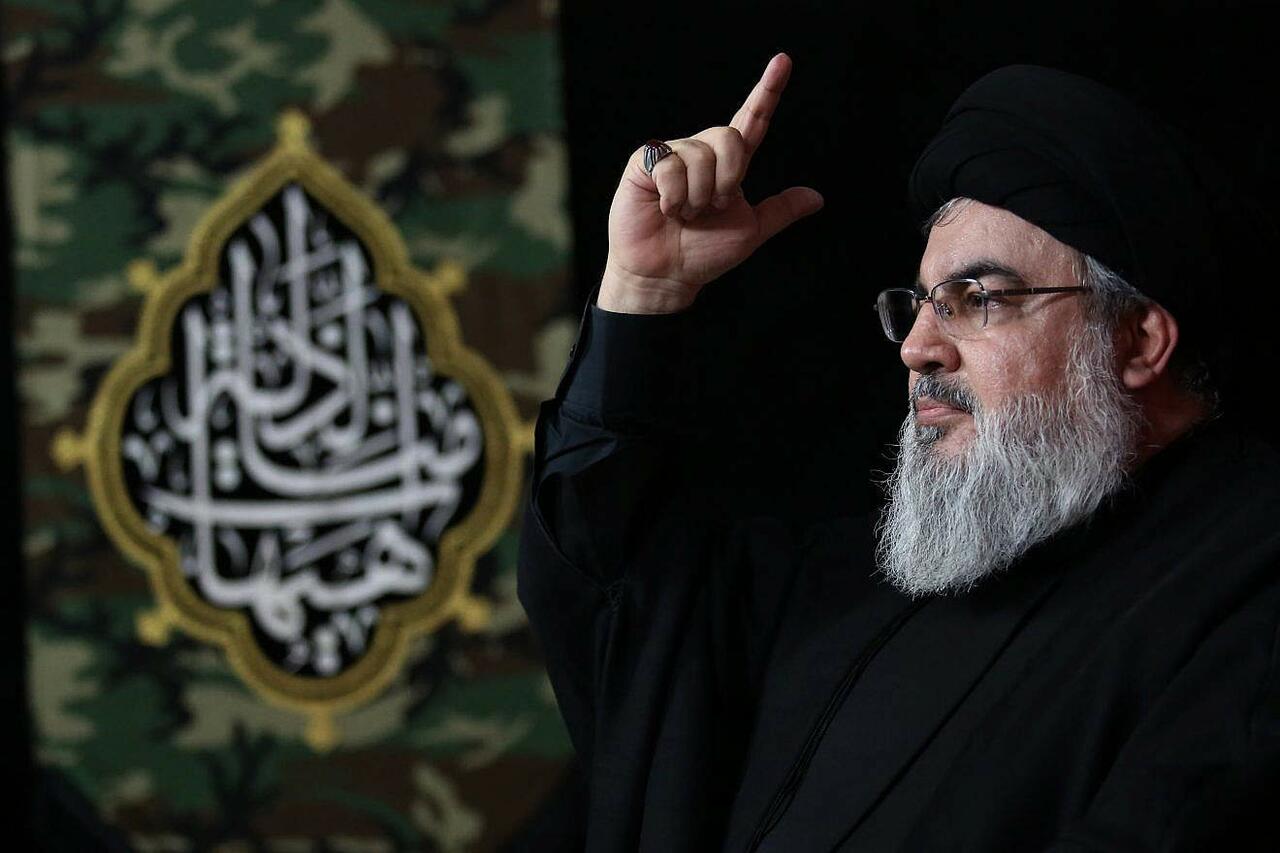
Hizbullah’s involvement in Syria, and the circulation of slogans that were sectarian and religious in nature, aided the Gulf regimes’ campaign against Nasrallah and the party, portraying them as purely Shiite and merely puppets of Iran. The Gulf’s mission was to push the party into a sectarian corner, and the party — through its political behavior in Lebanon — unintentionally aided that mission.
Since the Lebanese economic collapse in 2019, Hizbullah has pursued political options focusing on solidifying Shiite political ranks. This is only understandable from the perspective of the party protecting itself from a Gulf-Israel plot to instigate a Shiite, intra-sectarian, civil war.
Thus it’s not easy to assess the speech with disregard to the political context in which it took place. Nasrallah was addressing many audiences: the party’s rank-and-file, the Lebanese scene, the Arab scene, and his enemies in the West and Israel.
The video teasers before the speech would have worked if there was a dramatic announcement in the form of a major escalation or a declaration of war. When that did not materialize, it made those teasers feel hollow even though they succeeded in a form of psychological warfare against the Israeli enemy (an Israeli newspaper commented that Nasrallah succeeded in tearing the nerves of Israelis).
Hizbulllah is the first Arab political party, or even state if we add them to the mix, which devotes energy and resources to engage in psychological warfare against the Israelis. The PLO had no notion of that, and the speeches of its leaders (and of Arab leaders) were bombastic and emotional and did not rely on a base of military power and preparedness. Nasrallah is an expert on Israel; he spends hours reading about Israel and its politics and military.
Tied Hands
Nasrallah must have felt enormous pressure before the speech. For a leader who uniquely (in the history of Arab leaders and of Israel) makes decisions on the basis of a cost-benefit analysis, Nasrallah’s hands were a bit tied in Lebanon. Half of the country (at least) is under the influence of Gulf regimes and have relatives in the Gulf and fear for their expulsion (Gulf regimes remind Lebanon regularly that if Lebanon were to take stands against the Gulf regimes, those Lebanese immigrants would be expelled en masses).
Furthermore, there is an enormous U.S. media apparatus headquartered in Dubai that coordinates with Israel and Gulf countries in the war on enemies of Israel, especially those who are engaged in resistance against Tel Aviv.
Weeks before Nasrallah’s speech, journalists on the payroll of Gulf regimes and journalists who work for media funded by NATO governments and George Soros came together and promoted a petition rejecting the war between Lebanon and Israel, insisting that Lebanon is too fatigued to participate in a war against Israel. Money was mysteriously made available for those people to buy billboards sending the same message: that Hizbullah should keep Lebanon out of the war.
The movement did not spread much, but it registered with people who are worried about their living conditions, in the wake of the economic collapse and the elimination of people’s life savings. It did not help that Israeli leaders make weekly threats that they would turn Lebanon back to the pre-industrial age or that they would threaten to eliminate Lebanon altogether.
Those genocidal statements don’t get covered in the Western press, but they alarm the Lebanese population; Lebanese know full well that in war Israel targets civilians first and foremost.
Most of the casualties in Israel in the July 2006 war were combatants, while most of the casualties in Lebanon were, typically, civilians. Lebanese infrastructure is in decrepit shape and Israel in the past consistently targeted Lebanese hospitals, power stations, airports, schools, and refugee camps.
That must weigh heavily on Nasrallah’s mind when he makes the cost-benefit analysis.
But there are also the party-stalwarts who have been raised on the slogan, nay expectation, of the liberation of Palestine. They genuinely believe that Israel would reach its demise in the next war.
Those supporters of the party needed to hear from their leader to understand the regional ramifications of the war.
And Nasrallah, it must be pointed out, is now probably the most senior figure in the “axis-of-resistance” in the Middle East. Even Qassim Suleimani (murdered by the U.S.) was lower in rank than Nasrallah ( footage of meetings between the two men confirm that Nasrallah was the senior person in the relationship). Photos of family mourning in Suleimani’s home show a picture of Nasrallah in the house).
Even Ayatollah Khamenei, who is the most senior religious figure in the hierarchy of the axis, defers to Nasrallah on strategic matters (Iranian officials regularly briefed Nasrallah on nuclear negotiations with the West).
Three Signals
When it comes to war with Israel, Nasrallah is the ultimate decision maker.
So he knew expectations were high and that this was a historic moment with the Arab people unified in support of Palestine. He could not stand by or act indifferently. He has not only opened (since the Hamas attack on Israel) the front in the South where his has party lost 55 members so far in clashes with the Israeli occupation army, but he also allowed Palestinian factions (namely Hamas and Islamic Jihad) to use Lebanese territories to fire short range missiles at Israel targets.
The entire political class in Lebanon (in the form of the government and the prime minister) has said that Lebanon does not want war with Israel.
So Nasrallah did not declare war, but sent out these important signals:
- He made it clear that the planning and the timing of the Hamas operation was entirely Hamas and Hamas alone. He said that not even allies of Hamas in Gaza (clearly a reference to Islamic Jihad) knew of the operation because Hamas maintained absolute secrecy. Iran was not involved and that was important to stress because in the Western media all Iranian allies are presented as mere puppets of Iran. The picture is more complicated. In 2011, Hamas supported the Syrian revolt against the Syrian regime although the regime provided Hamas with sanctuary and military support. That stance poisoned the relationship between Hamas and Iran, and even between Hamas and Hizbullah. Hamas later reconciled with Hizbullah, but the Hizbulalh leadership still refuses to meet with Khalid Mishal, the leader behind Hamas’ decision to support the Syrian armed rebellion (he took that decision consistent with the stance of Qatar and Turkey, with which he is very close). Moreover, even the US has finally concluded (according to CNN) that Hizbullah does not merely follow Iranian orders in its decision making.
- Nasrallah wanted to make clear that the front from Lebanon to Syria to Gaza is one and that all members of the resistance camps will be fighting together. He made a reference to the Iraqi allies of Hizbullah.
- Nasrallah was preparing the Lebanese for the next phases of the war. He all but made it clear that a larger war is inevitable but he did not want to be the one to announce it, thereby opening the door for the Gulf-paid media to blame him for that decision. He spoke about phases of this war and reminded the audience about Israeli losses and Hizbullah’s successes in clashes in South Lebanon.
- Nasrallah sent a message to the U.S.: His group won’t be intimidated by the presence of the fleet in the Mediterranean and reminded the U.S. that some of those who fought against the U.S. in Lebanon in 1982-84 are still alive and trained others. He made it clear that Hizbullah would retaliate against U.S. forces if the U.S. strikes Lebanon.
It was not Nasrallah’s best speech, and it did not meet the very high expectations by many. But it achieved what he wanted from the occasion: to put the enemy on notice that Hizbullah would not rule out a major confrontation with Israel and that such eventualities are related to developments on the ground in Gaza.
Capri Holdings and Tapestry (TPR) receive request for additional info from FTC related to its review of the two companies' previously announced transaction (50.66 -0.39)
- Both Capri and Tapestry expect to promptly respond to the Second Request and to continue to work cooperatively with the FTC in its review of the transaction.
- Capri continues to expect that the Transaction will be completed in calendar year 2024.
After Hours Summary: VMEO +16.1%, TRIP +12%, JELD +6.5% making nice moves following earnings; AMRC -11.7%, SANM -10.1% struggling after earnings; KMI -0.2% steady on NexEra Energy (NEE) M&A news
After Hours Gainers:
Companies trading higher in after hours in reaction to earnings/guidance: TMDX +36.1%, VMEO +16.1%, AYX +14.9%, TASK +13.5%, UIS +13.5%, PAY +12.7%, TRIP +12%, DCGO +7.8%, RNG +7.6%, MYGN +7.1%, JELD +6.5%, QTRX +6.5%, HIMS +6.4% (also announced repurchase program), SKWD +6.1%, NEO +6.1%, ROVR +5.9%, IFF +5.5% (continuing agreement with Icahn Capital), CBT +5.3%, MTTR +5.2%, CRGY +4.5%, KIDS +4.2%, ATEC +3.9%, PRAA +3.6%, CTRA +2.9%, AOSL +2.8%, WTRG +2.8%, VECO +2%, FN +1.9%, AMK +1.7%, STEP +1.6% (also appoints new CFO), VNOM +1.5%, FSK +1.4%, TDC +1.1%, COHR +1.1%, GH +0.9%, AAON +0.7%, O +0.6%, FANG +0.5%, NXPI +0.5%, RCKT +0.5%
Companies trading higher in after hours in reaction to news: CPRI +4% (receives additional info request from FTC), MGNX +2.8% (files mixed shelf), VLRS +2.3% (reports October capacity), VTLE +2.2% (stock offering), CWCO +1.7% (acquires Ramey Environmental Compliance), DRS +1.6% (awarded $134 mln production order), SPLK +1.3% (stock offering), BATRA +0.5% (stock offering)
After Hours Losers:
Companies trading lower in after hours in reaction to earnings/guidance: AMRC -11.7%, SANM -10.1%, EVCM -8.5%, SWAV -7.4%, OPK -5.2%, AZPN -5.1%, CXW -2.5%, ICHR -2%, MED -1.9%, VRTX -1.7%, DHT -1.6%, OLO -1.1%, SKT -0.8%, RVMD -0.8%, GT -0.8%, CRSP -0.2%, CXT -0.1%, TALO -0.1%
Companies trading lower in after hours in reaction to news: VTYX -76.9% (announces Phase 2 results), AURA -15.9% (stock offering), CPG -5.7% (to acquire Hammerhead Energy for $2.5 bln; files CDN$500 mln common stock offering), COCO -5.7% (stock offering), MMS -5.6% (completes divestiture of employement services operations), CWAN -3.5% (stock offering), TSLA -2.4% (SpaceX eyeing $15.0 bln in revenue next year, according to Bloomberg), KNF -2.3% (stock offering), -1.9%, WELL -1.8% (stock offering), AEP -0.9% (files mixed shelf), KTOS -0.6% (awarded $579 mln U.S. Air Force contract), LCID -0.3% (integrating NACS by 2025), TPR -0.3% (receives additional info request from FTC), NEE -0.3% (to be acquired by KMI), ABCM -0.2% (shareholders approve DHR acqusition), ASR -0.2% (reports October passenger traffic), KMI -0.2% (to acquire NextEra Energy for $1.815 bln), MCB -0.1% (appoints new CFO)