Le Figaro : Le géant du lait Lactalis perquisitionné dans une enquête pour fraud

Le géant du lait Lactalis perquisitionné dans une enquête pour fraude fiscale aggravée

Le parquet national financier a ouvert une enquête pour fraude fiscale aggravée et blanchiment de fraude fiscale aggravée, a indiqué une source judiciaire.

Le siège de plusieurs sociétés du géant mondial du lait Lactalis a été perquisitionné mardi dans le cadre d'une enquête du parquet national financier (PNF) ouverte pour fraude fiscale aggravée et blanchiment de fraude fiscale aggravée, a indiqué une source judiciaire, confirmant une information du Monde.

Les perquisitions, menées par la Brigade nationale de répression de la délinquance fiscale de la police judiciaire, ont visé le siège du groupe à Laval (Mayenne), ses bureaux à Paris et l'hôtel particulier de son dirigeant, Emmanuel Besnier, également situé dans la capitale, selon une source proche du dossier.

FT : Italy’s parliament approves controversial company board reforms

Italy’s parliament approves controversial company board reforms
Last-minute amendments to capital markets bill curb directors’ ability to put themselves up for re-election

Italy’s parliament has approved a controversial set of measures radically affecting the way that listed companies’ board of directors are appointed, in spite of fierce opposition from international investors.

The measures were an eleventh-hour addition by the rightwing government in Rome to a wider, long-awaited bill designed to reform the country’s capital markets. The bill, which has been in the works for three years, is seen as a way of helping attract stock market listings and prevent Italian companies from moving their headquarters abroad.

The changes, approved along with the wider bill on Tuesday, will override company bylaws on how board of directors are appointed, in effect giving long-term investors with a stake of more than 9 per cent an advantage over other shareholders.

The additions “are foreign material to this bill, it would be more sensible to eliminate them”, said lawmaker Bruno Tabacci, a veteran centre-left lawmaker, speaking in parliament just minutes before the vote.

International investors, as well as both centrist and leftwing opposition parties in Rome, had vocally opposed the proposals which, they warned on Tuesday, would be “hard to digest by the markets” and risked “scaring off foreign investors”.

Some analysts say the measures affecting corporate governance will overshadow the benefits of the broader capital markets reform.

Boards of directors in Italy, including the chief executive, typically have three-year mandates. At the end of the term, shareholders can nominate a new slate of candidates for the next term or the outgoing board has the option to do so, including nominating the old management again.

The most significant change in the new measures limits the outgoing board’s ability to present its own slate of candidates. Up until Tuesday’s changes, such slates had become the standard board appointment mechanism at insurer Generali and at lenders Mediobanca, UniCredit and Banco BPM.

Some local investors, however, such as Francesco Gaetano Caltagirone, a building tycoon and a large investor in Mediobanca and Generali, publicly complained that boards of directors held too much power and said their ability to reappoint themselves should be curbed by law.

The government ultimately sided with his view and supported the last-minute amendments to the bill. Under the new measures, if a minority investor with a stake of 9 per cent or more presents its slate of board nominees, the outgoing board of directors will be barred from presenting its own slate.

>>> US Research Calls

Research Calls
  • Upgrades:
    • Li Auto (LI) upgraded to Buy from Hold at Deutsche Bank; tgt lowered to $41
    • Open Lending (LPRO) upgraded to Equal-Weight from Underweight at Morgan Stanley; tgt raised to $7
    • Palantir Technologies (PLTR) upgraded to Neutral from Sell at Citigroup; tgt raised to $20
    • Palantir Technologies (PLTR) upgraded to Hold from Underperform at Jefferies; tgt raised to $22
    • Tyson Foods (TSN) upgraded to Neutral from Underperform at BofA Securities; tgt raised to $62
    • UPS (UPS) upgraded to Buy from Neutral at UBS; tgt raised to $175
  • Downgrades:
    • Ahold Delhaize (ADRNY) downgraded to Reduce from Hold at HSBC Securities
    • Air Products (APD) downgraded to Neutral from Buy at Seaport Research Partners
    • Bristol-Myers (BMY) downgraded to Neutral from Buy at Redburn Atlantic; tgt lowered to $54
    • Chegg (CHGG) downgraded to Underweight from Neutral at Piper Sandler; tgt lowered to $8.50
    • Chevron (CVX) downgraded to Hold from Buy at DZ Bank; tgt $160
    • CNA Financial (CNA) downgraded to Underperform from Neutral at BofA Securities; tgt raised to $43
    • Embraer SA (ERJ) downgraded to Hold from Buy at HSBC Securities; tgt raised to $19
    • Entain Plc (GMVHY) downgraded to Equal Weight from Overweight at Barclays
    • Euronav (EURN) downgraded to Hold from Buy at Deutsche Bank
    • Illinois Tool (ITW) downgraded to Underweight from Equal Weight at Wells Fargo; tgt lowered to $240
    • Infosys (INFY) downgraded to Hold from Buy at HSBC Securities
    • LVMH (LVMUY) downgraded to Hold from Buy at HSBC Securities
    • McDonald's (MCD) downgraded to Neutral from Buy at BTIG Research
    • Napco Security Systems (NSSC) downgraded to In-line from Outperform at Imperial Capital; tgt $45
    • Plug Power (PLUG) downgraded to Neutral from Buy at Seaport Research Partners
    • RWE AG (RWEOY) downgraded to Hold from Buy at Stifel
    • Saia (SAIA) downgraded to Hold from Buy at Stifel; tgt raised to $526
    • Tesla (TSLA) downgraded to Neutral from Outperform at Daiwa Securities; tgt lowered to $195
  • Others:
    • Agiliti (AGTI) initiated with a Sector Weight at KeyBanc Capital Markets
    • Alcon (ALC) resumed with an Overweight at KeyBanc Capital Markets; tgt $87
    • Avadel Pharmaceuticals (AVDL) initiated with a Buy at UBS; tgt $21
    • Axsome Therapeutics (AXSM) initiated with a Buy at UBS; tgt $111
    • Biohaven (BHVN) initiated with a Buy at UBS; tgt $59
    • Biomea Fusion (BMEA) initiated with a Buy at Truist; tgt $55
    • Cooper (COO) resumed with a Sector Weight at KeyBanc Capital Markets
    • Flywire (FLYW) initiated with a Buy at Deutsche Bank; tgt $27
    • Inspire Medical Systems (INSP) resumed with an Overweight at KeyBanc Capital Markets; tgt $278
    • Integer Holdings (ITGR) resumed with an Overweight at KeyBanc Capital Markets; tgt $125
    • LeddarTech (LDTC) initiated with a Buy at ROTH MKM; tgt $7
    • Lemaitre Vascular (LMAT) resumed with a Sector Weight at KeyBanc Capital Markets
    • Paycom Software (PAYC) initiated with a Neutral at BTIG Research
    • Paycor (PYCR) initiated with a Buy at BTIG Research; tgt $26
    • Paylocity (PCTY) initiated with a Buy at BTIG Research; tgt $200
    • ResMed (RMD) resumed with an Overweight at KeyBanc Capital Markets; tgt $227
    • Sotera Health (SHC) resumed with a Sector Weight at KeyBanc Capital Markets
    • Steris (STE) resumed with an Overweight at KeyBanc Capital Markets; tgt $253
    • TKO Group Holdings (TKO) initiated with a Buy at Northcoast; tgt $105
    • UFP Technologies (UFPT) initiated with a Sector Weight at KeyBanc Capital Markets

Business Of Fashion : Loro Piana Banks on ‘Not Quiet’ Luxury to Continue ‘Magnif

Loro Piana Banks on ‘Not Quiet’ Luxury to Continue ‘Magnificent Growth’
In an in-depth interview with BoF, chief executive Damien Bertrand breaks down the strategy shifts he’s put in place to unlock the uber-luxe label’s growth potential.

KEY INSIGHTS
  • Under CEO Damien Bertrand, ultra-luxe Loro Piana has subtly shifted its strategy in a bid to become more contemporary and appeal to a wider clientele.
  • Key to Bertrand’s strategy has been the launch of leather goods, the brand’s fastest growing category, as well as the introduction of seasonal themes and a “more modern” silhouette.
  • “Loro Piana existed before quiet luxury and will exist afterwards; there are a lot of things [about the brand] that are not quiet at all,” the CEO says.

Don’t call Loro Piana, the uber-luxe label owned and worn by LVMH owner Bernard Arnault, “quiet luxury.” Its chief executive Damien Bertrand who joined the brand two years ago from LVMH stablemate Dior is having none of it. Arnault last month described the northern Italian brand as having enjoyed “magnifique” growth over the past year.

But Bertrand takes issue with those who argue Loro Piana’s sales surge is down to a vogue for pared back luxury despite stellar results at logo-free labels.

“Sometimes, people ask me the question, ‘Is Loro Piana quiet luxury?’ I invariably answer ‘No.’ Loro Piana existed before quiet luxury and will exist afterwards; there are a lot of things [about the brand] that are not quiet at all,” he says.

As an example, Bertrand points to the launch of a prominent pop-up store in the middle of the elite ski resort Zermatt this winter. “It’s not so quiet, but people love it. They have hot wine and browse our collections. We’ve had a lot of new clients who have discovered us,” he says. “We were the first luxury brand in Zermatt, now all the brands want to be there,” he says. “In Dior we did a lot of disruption, in Loro Piana we are doing it too but in a Loro Piana way.” Next year, he plans to take the pop up somewhere else.

If that seems a different tack for the super-pricey, conservative northern Italian cashmere label LVMH acquired from the Loro Piana family a decade ago, that’s because it is. Arnault famously tells families he is not going to change anything when he buys their business. Loro Piana was no exception, according to members of its founding family. Yet the house has changed since its acquisition a decade ago, transformed from cottage industry to global luxury brand. The appointment of Bertrand, a native of Marseille, who spent 20 years at French FMCG behemoth L’Oréal and was made head of womenswear at Dior in 2016, is testament to that evolution.

Under Bertrand’s leadership, Loro Piana’s strategy has shifted subtly in a bid to make the brand more contemporary, and appeal to a wider clientele. Bertrand argues today that, far from being a label solely for the ultra-rich, the “potential of Loro Piana is infinite.” A key part of that new strategy has been the launch of leather goods, the brand’s fastest growing category, says Betrand, albeit from a low base. Last year, Loro Piana finally launched a long-awaited handbag range, the Bale, named after the pillow shaped wool bundle that’s the start of the supply chain. It’s a crucial step.

Arnault acquired Loro Piana a couple of years after failing to seize control of French family-owned ultra luxe maison Hermès. And it’s been clear from the outset that Arnault aims to turn Loro Piana into a credible Hermès rival. Loro Piana is dwarfed in size by Hermès. Analysts estimate annual revenues at the Italian label are around the billion euro mark. Hermès group sales hit 11.6 billion euros in 2022, the latest number available. Still, with last year’s launch of the Bale bag, Loro Piana has decisively entered the segment that drives the majority of Hermès’ growth.

The intention to rival Hermès seems to burn bright for Bertrand, even if it goes unstated. “My mandate is to make Loro Piana the pinnacle of luxury and the most desirable maison in the world,” he says. The Bale bag was just “the beginning of a category.” Interiors are another frontier Bertrand intends to grow.

It’s all part of an overhaul of Loro Piana’s image to make it more contemporary and appeal to a wider clientele. Bertrand says he took his first two years “to rework completely the silhouette,” and to make it “more modern and more harmonised between men and women.” He has also introduced seasonal themes in a (gentle) nod to runway rhythms. This Spring/Summer is an ode to artisanal manufacturing inspired by Italy and Japan. That’s helped drive the brand among younger consumers with shorter attention spans. Bertrand says the average age of its clientele has dropped to between 35 and 40 years old.

Still, Loro Piana’s central raison d’etre remains constant today: the creation of ultra luxe garments out of prized, and increasingly finite, raw materials with stellar price points to match. Access to rare fibres has been fundamental to the label since its founding by the Loro Piana brothers in 1924, but it’s taken on increased commercial significance as the Covid-19 lockdowns made clear the importance of supply chain resilience. Add in the impact of the climate crisis, both extreme heat events and water shortages, and deft management of Loro Piana’s supply chain has become increasingly key to its capacity for growth.

When LVMH bought 80 percent of Loro Piana for €2 billion in 2013, observers attributed its rich premium to its vertically integrated supply chain. Today, that sum is looking like money well spent as brands engage in an arms race for increasing scarce raw materials and manufacturing talent. It also means that Loro Piana’s growth potential is balanced on that finiteness: there is a limit to how much Loro Piana can produce, but perhaps not how much it can sell its goods for.

Loro Piana’s Record Bale competition is a case in point. The nub of the competition, begun by the Loro Piana family more than two decades ago, was to spur merino farmers in Australia and New Zealand to produce ever finer and higher quality wool. Italian academic Stefania Saviolo has argued a shortage of raw materials will mean the supply chain is going to become a branded luxury good itself, right down to the farmers who produced top quality wool. The winners of this year’s Record Bale competition “Pyrenees Park” fit that bill.

But all is not well in the supply chain. The wild vicuña which provide the rare fibres for Loro Piana’s top end ranges are increasingly moving higher into the Andes to avoid hotter weather putting them potentially out of reach of shearers who have rarely worked at such high altitude.

For Bertrand, Loro Piana’s growth model is also linked to a specific relationship with time. Bertrand makes a distinction between Dior, which has a six-month turnaround for collections, and Loro Piana. “It takes us up to 14 months [to create a new product]; the fashion brands do not have the luxury of this time,” he says. Of course, that concept of time without deadline is a pull for the restless global elite who wear Loro Piana themselves (Mark Zuckerberg and Jeff Bezos are clients) and apparently have little of it themselves.

Bertrand is also driving the stickiness of the brand by encouraging Loro Piana clients to see themselves as members of a tribe (the 0.1 percent given the $980 price tag on a pair of its popular Summer Walk Loafers). Customers tend to be “connoisseurs who can recognise each other,” he says. “You will never have big logos but there is a look and feel of our garments.”

The notion that Loro Piana is a badge of belonging to the elite is being fostered by the label’s new sponsorship of elite sports events: it backed the Ryder Cup for the first time last year, and this year will sponsor the Giraglia Regatta, a feature of the summer season on the French Riviera.

But is there a club Loro Piana would rather not be part of? Roy family characters in the hit television series “Succession” wore the brand, including Jeremy Strong’s odious Kendall Roy. Bertrand doesn’t miss a beat. True to the maxim that all publicity is good publicity, Bertrand says he’s “never had or heard a comment from anyone suggesting it was bad publicity.” The clothes were chosen by the actors and production and weren’t product placement, he adds.

Another key issue for Bertrand is manufacturing talent. Loro Piana has 1,200 artisans with the know-how to work its woollen garments, but it’s now doing talks to school children, especially in the regions famous for Italian luxury manufacturing clusters, such as Tuscany for leather goods, Piedmont for textiles and Marche for shoes, to encourage them to become artisans when they leave school. It’s also seeking architects and engineers out of universities.

Those engineers are necessary because today’s Loro Piana “is a mix between the hand and the machine,” says Bertrand. “I need people who can project themselves into the future but we are a gatekeeper of a tradition too,” he explains. He’s not talking about the use of robots but artificial intelligence. As of last year, Loro Piana engineers have been using AI to rapidly spot defects in colour or weave in a bale of wool. “We are implementing it in our factory as we speak,” he says.

It’s another sign this isn’t your mamma’s Loro Piana.
Le Monde : Pour la Cour des comptes, les stations de ski n’ont pas suffisamment

Pour la Cour des comptes, les stations de ski n’ont pas suffisamment pris la mesure du changement climatique
Dans un rapport, la Cour des comptes estime que seuls quelques sites en France peuvent espérer poursuivre une exploitation au-delà de 2050 et que cette évolution est sous-estimée par les maires et les collectivités territoriales.

Dans les trente prochaines années, le changement climatique va bouleverser les équilibres des stations de ski. Toutes ne vont pas mourir, mais toutes seront frappées. Seules « quelques stations » peuvent espérer poursuivre une exploitation au-delà de 2050, affirme la Cour des comptes, dans un rapport publié mardi 6 février. Or, nombre de ces communes ne semblent pas en prendre la mesure.

Ce document de 147 pages, réalisé après un audit de quarante-deux stations de tous les massifs, part d’un constat : le modèle du ski français « s’essouffle », étranglé à la fois par la baisse du nombre de skieurs, par un parc de logements de moins en moins adapté, et par les lourds investissements réalisés par des opérateurs de remontées mécaniques. A tout cela s’ajoute le changement climatique, qui a réduit la quantité de neige, raccourcit les saisons, et nécessite de plus en plus d’investissements dans la production de neige artificielle.

Aujourd’hui, les stations de ski bénéficient d’importantes aides publiques. Ainsi, 23 % du chiffre d’affaires des opérateurs de remontées mécaniques des petites ou moyennes stations est issu des subventions. Cela revient à faire payer le contribuable – et non l’usager – pour une activité touristique, ce qui « pose problème », selon la Cour, qui rappelle que hors de France « les remontées relèvent du secteur privé ».

Baisse de l’enneigement
Ces aides conduisent souvent à financer des modèles d’affaires à l’avenir incertain, et lourdement basés sur l’emprunt. Fragilisées par la baisse de l’enneigement et par un moindre nombre de skieurs, « de plus en plus de stations » ne sont plus en capacité d’atteindre l’équilibre d’exploitation, et sont « fortement déficitaires » (Chalmazel dans la Loire, Le Mont-Dore dans le Puy-de-Dôme, Auron dans les Alpes-Maritimes, Saint-Pierre-de-Chartreuse en Isère…).

« La tendance à la baisse de l’activité ski est insuffisamment prise en compte par les collectivités » dans leurs investissements, écrit la Cour. Elle cite l’exemple de Font-Romeu, dans les Pyrénées-Orientales, qui a adopté un plan de développement maintenant jusqu’en 2047 un nombre de skieurs « stable ». « Plus surprenant encore », Val Louron (Hautes-Pyrénées) indique, dans son plan d’affaires, vouloir presque doubler son nombre de clients, malgré son altitude moyenne, l’exposant de manière très élevée au manque structurel de neige.

Le rapport examine le cas de la neige artificielle, présentée par les acteurs de la montagne comme une solution face au changement climatique. Or, les canons à neige, très coûteux, posent de multiples problèmes, à commencer par leur impact sur la ressource en eau, souvent « sous-estimé ». De plus, si la température augmente trop, les canons ne peuvent pas être utilisés. En outre, les retenues collinaires, qui servent à stocker l’eau nécessaire, créent des conflits d’usage. Ainsi, dans certains cas, les politiques d’enneigement tournent à la « mal adaptation », estime la Cour, qui cite l’exemple de Super-Besse (Puy-de-Dôme), station d’altitude moyenne du Massif central, qui a énormément investi dans des appareils de production de neige, et envisage encore d’étendre cette couverture.

Les rapporteurs se montrent assez critiques sur le développement d’activités hors ski (luges, tyroliennes…), utilisables hiver comme été, pensées « sans stratégie », ce qui amène, par exemple, à des concurrences inutiles entre stations. Et lorsqu’il existe des bilans financiers de ces activités « ils font généralement apparaître un déséquilibre ».

Démantèlement des télésièges
Pour sortir de cette situation, la Cour des comptes appelle à une réforme de la gouvernance, afin que les décisions « ne relèvent plus seulement de l’échelon communal » – ce qui fait bondir, dans sa réponse, l’association qui représente les maires de ces stations. Le rapport propose de conditionner les aides publiques à la prise en compte du changement climatique, et de créer un fonds consacré à la transition de ces territoires, chargé notamment de l’épineuse question du démantèlement des télésièges abandonnés.

Enfin, le rapport établit un tableau comparatif de 163 stations de ski selon un indice de vulnérabilité, fonction du risque climatique et économique auxquels elles font face. Les stations les plus exposées au risque de faillite sont presque toutes situées dans les Alpes du Sud : Roubion-les-Buisses, Ceillac, Chaillol, Laye, Molines-Saint-Véran, Aiguilles, Arvieux… A l’inverse, les grandes stations des Alpes du Nord sont les moins menacées. Tignes, Val-Thorens, Val-d’Isère, Les Deux-Alpes, Valmeinier, Chamonix ou encore Les Ménuires disposent des meilleurs scores de viabilité.

(ZH) 'Markets Are Now Anchoring On Potential Trump Victory' - Ex-Soros CIO Says

'Markets Are Now Anchoring On Potential Trump Victory' - Ex-Soros CIO Says "All Pullbacks Should Be Bought"

“We are expecting an upward trajectory in the US equity markets,” wrote Scott Bessent, a former Soros Fund Management investing chief as he bets on a "Trump rally".
“Barring Biden pulling ahead in substantial fashion, all pullbacks should be bought.”
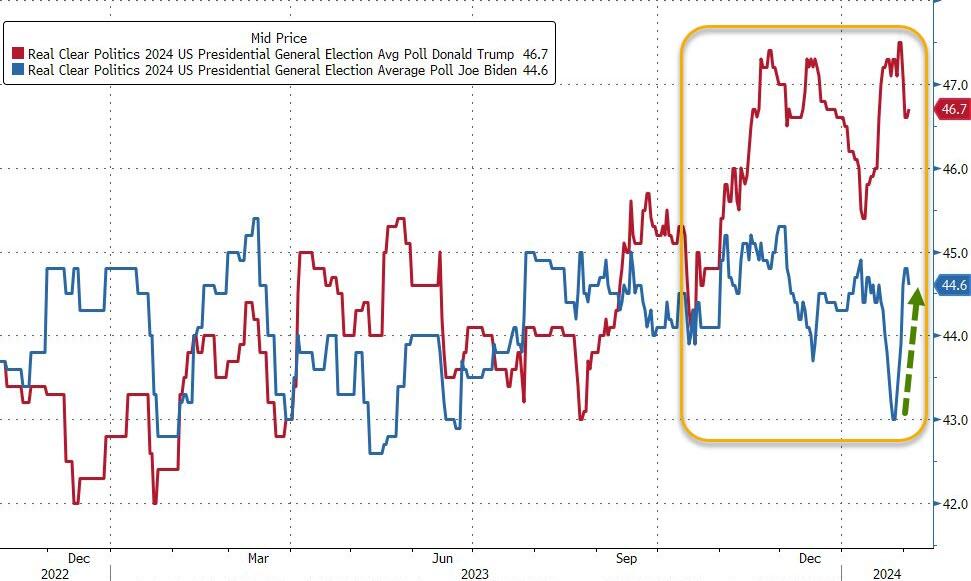
Bessent's bet appears well based as the polls (averaged by Real Clear Politics), Trump has a solid lead over Biden (although Biden - for some reason - saw a surge in the last few days?)...

Source: Bloomberg
“Markets are now anchoring on the potential market-friendly policies of a Trump victory on Nov. 5,” Bessent wrote Wednesday to investors in his Key Square Capital Management macro fund.
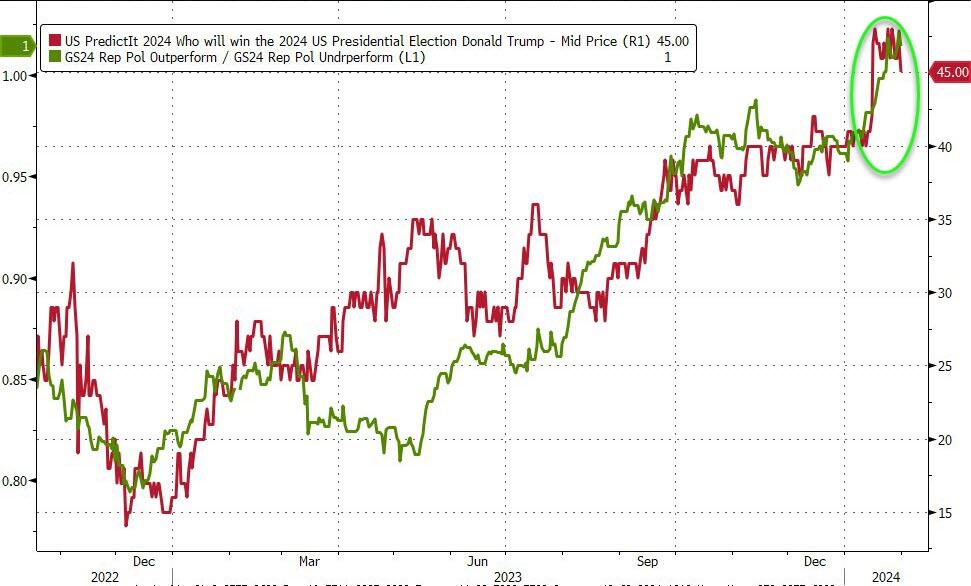
And he is right, as we detailed previously, 2024 Republican Policy Pair basket (full details here) has tracked Trump’s victory odds since late 2022... notably tracking very tightly with the recent surge in Trump's odds...
Source: Bloomberg
Investors anticipating a Trump victory also expect “an extended market-friendly economic, tax and regulatory environment,” Bessent wrote.
So far the so-called improvement in economic conditions has only had a limited impact on voter sentiment about the economy.
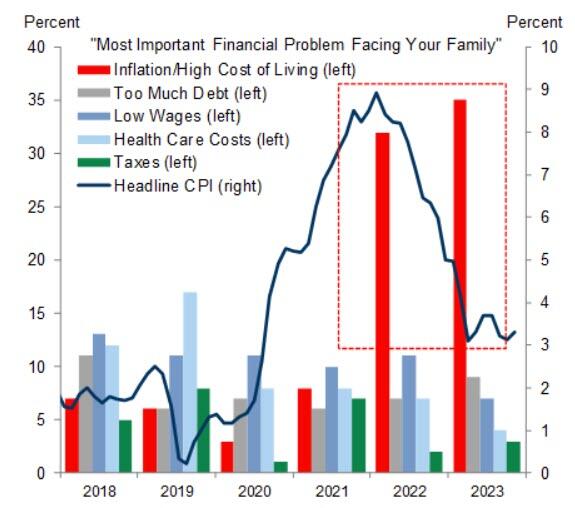
As Goldman shows in the chart below, voters still rated inflation as the most important financial problem for their family in 2023, despite its pace slowing...
Source: Goldman Sachs
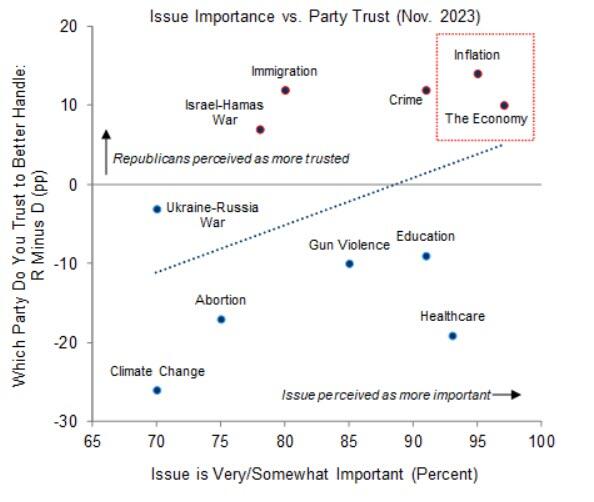
...and that is a positive for Trump as Goldman shows that Republicans score higher when voters are asked which party they trust more to handle inflation and the economy...
Source: Goldman Sachs
And, as Bessent wrote, don't expect a shift any time soon... “The Biden White House economic team has already thrown cold water on a renewal of most Trump-era tax cuts and called for higher taxes on corporates and upper-income Americans."
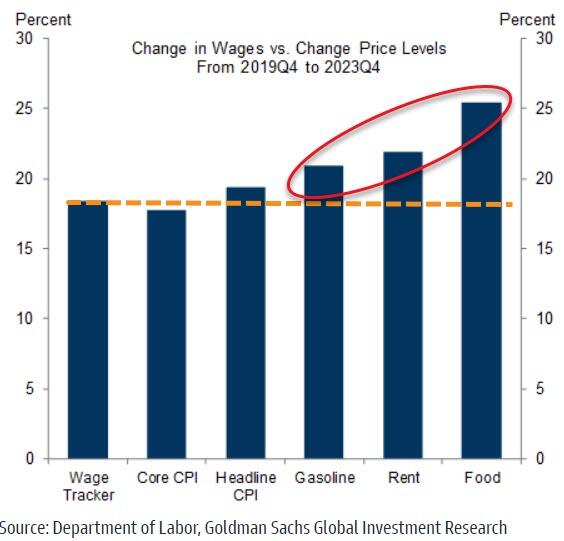
While the Biden White House keeps exclaiming that 'real incomes are rising... so STFU and say thank you America', the fact is that aggregate incomes have risen less than the cost of gasoline, food, and rent - so unless you're homeless and on full welfare,,, this explains the lack of 'belief' in Bidenomics...
Finally, Trump’s success in the polls is also influencing policymakers, according to Bessent. The Biden administration is inclined to “keep the economy buoyant, provide ample liquidity, contain interest rates” and avoid blowups such as the collapse of Silicon Valley Bank last year, he wrote.
Bessent also pointed to Fed Chair Jay Powell’s “dovish pivot” in December when he signaled rate cuts were ahead rather than more hikes.
“While we don’t think the Fed is an explicitly political institution, we think nearly all of Washington, DC is united in wanting to prevent the return of Donald Trump,” he wrote.
As Bloomberg reports, the hedge fund manager pushed back against the notion that another Trump administration would sow chaos, and that the former president would use his second term to seek revenge.
If re-elected, it’s likely that Trump “would seek rejuvenation/redemption,” Bessent wrote.

>>> US Gapping down

Gapping down
In reaction to earnings/guidance
:
  • SYM -18.1%, FN -14.1%, FMC -13.7%, CCK -12.8%, RMBS -10.5%, KE -10.2%, IT -8.5%, CHGG -7.5% (new CFO), JJSF -7%, LEA -5.9%, AMKR -5.5%, CRNC -5.1%, UBS -3.8%, SSD -3.7%, CHKP -3.6%, NVT -3.2%, ENR -2.3%, VVV -2%, ST -1%, WAT -0.7%
Other news:
  • UFPI -7% (increases dividend)
  • HESM -4.5% (prices secondary offerin 10.0 mln shares of Class A stock for gross proceeds of $331 mln)
  • FDMT -2.3% (commences $250 mln public offering; also files mixed shelf)
Analyst comments:
  • PLUG -6% (downgraded to Neutral from Buy at Seaport Research Partners)
  • TSLA -2.7% (downgraded to Neutral from Outperform at Daiwa Securities)
  • ITW -1.4% (downgraded to Underweight from Equal Weight at Wells Fargo)
  • MCD -0.6% (downgraded to Neutral from Buy at BTIG Research)

>>> US Gapping up

Gapping up
In reaction to earnings/guidance
:
  • PLTR +15.8%, COHR +11.7%, VRNS +7%, CHX +6.3%, PINC +6.3% (also completes strategic review process), SPOT +5.5%, BP +5.3%, AUDC +5.2%, LLY +4.8%, FI +3.7%, TM +3.5%, PNM +3.4%, NXPI +3%, GEHC +2.8%, ATHM +2.7%, BRBR +2.6%, CNC +2.3%, DCPH +2.3%, DD +2.1%, ARMK +2%, J +1.8%, ACM +1.6%, LIN +1.6%, CEIX +1.6%, VRTX +1.4% (announces positive results), SKY +1.3%, CBT +1.3%, CARR +1.3%, HIMX +1.1%, WTW +1.1%, AME +1.1%, GBDC +1%, UMC +1% (Jan revs), KKR +1%, SPG +0.9%
Other news:
  • VLRS +5% (January traffic)
  • ARVN +3.1% (Arvinas and Pfizer (PFE) announce that the U.S. FDA has granted Fast Track designation for the investigation of vepdegestrant for monotherapy in the treatment of adults with estrogen receptor positive/human growth epidermal growth factor 2 negative)
  • RPRX +2.6% (discloses MorphoSys (MOR) details following Novartis (NVS) acquisition news)
  • MOR +2% (to be acquired by Novartis AG)
  • INCY +0.8% (asset purchase agreement with MorphoSys)
  • OXY +0.7% (Berkshire Hathaway's (BRK.A) Warren Buffett bought another 4302324 shares worth approx. $245.9 mln)
Analyst comments:
  • LI +8.1% (upgraded to Buy from Hold at Deutsche Bank)
  • LPRO +3.7% (upgraded to Equal-Weight from Underweight at Morgan Stanley)
  • UPS +1.9% (upgraded to Buy from Neutral at UBS)
  • TSN +0.7% (upgraded to Neutral from Underperform at BofA Securities)