WSJ : How the SEC’s Swaps Proposal Could Choke Off Shareholder Activism

How the SEC’s Swaps Proposal Could Choke Off Shareholder Activism
More transparency sounds good. But advocates might be ignoring the downside

A push by the U.S. Securities and Exchange Commission for more transparency around security-based swap positions might seem, on its face, to be a no-brainer.

After all, the misuse of one type of swap, credit default swaps, was a major contributor to the global financial crisis of 2007-08. And a second type, total return swaps, contributed to the multibillion-dollar collapse of Archegos Capital Management last year.

There is, however, a potential downside to the SEC’s proposal for increased disclosure of swap positions that might not be immediately apparent: If passed, the rules could severely restrain shareholder activism—a key market mechanism for holding corporate managements accountable, improving governance and creating sustainable value.

Security-based swaps are financial contracts in which counterparties agree to exchange payments based on, say, changes in a stock’s price. They allow investors to obtain economic exposure to an asset without directly owning it and have beneficial uses such as hedging risk. The SEC’s proposed Rule 10B-1 would require additional disclosure of large positions in such instruments, so that investors‘ counterparties and clients understand their full exposure. More transparency is always good, right?

Well, not always. The main barrier to shareholder activism is that the activist bears the cost, but the benefits are shared by all other shareholders and in many cases wider society—the classic free-rider problem. An activist’s gains are limited to its stake in the company. And if the activist buys more than 5%, it is required to disclose its position, which moves the market and hinders it from buying more. A 5% stake, however, is often insufficient to make activism worthwhile, given that it typically takes six to 12 months of research before an activist investor even meets with a company.

Swaps, however, allow a shareholder to increase exposure without revealing it to the world, raising the incentive to engage with a company to improve its performance. If the SEC forces investors to reveal those positions, activists might not be able to obtain enough exposure to make engagement worthwhile.

There are good public-policy reasons why equity positions should be disclosed, but not swaps. Equity comes with voting rights and the potential ability to influence a company, but swaps don’t. What swaps do provide is an economic incentive for an investor to care about a company’s future—similar to an investment firm tying fund-manager pay more closely to long-term performance, without increasing its holdings in the company.

For its part, the SEC says it benefits from robust engagement with the public and will review all comments submitted during the open comment period. Generally, though it responds to comments received as part of the final rule-making and not beforehand, according to a spokesperson.

Benefits of privacy
Why should we worry about reduced activism? Critics claim that activism inflates short-term profit at the expense of long-term value, but rigorous evidence suggests otherwise.

A seminal paper found that hedge-fund activism boosts a stock price by 7% in the short term, and even more in the long term. One concern is that these gains come from financial engineering rather than improvements in operating performance. But a second study, which obtained confidential data on the productivity of individual plants from the U.S. Census Bureau, found that hedge-fund activism leads to increased plant productivity, primarily through raising labor productivity. Workers’ wages don’t fall, and their hours don’t rise. A third paper, which studied investment, found that hedge-fund activism results in lower research-and-development expenditures but increased innovation. More patents are generated and patent quality increases because hedge funds refocus innovation on the most promising projects. When it comes to environmental outcomes, firms targeted by hedge funds reduce toxic chemical emissions and close heavily polluting plants. And the benefits are wider than just the firm in question—they spill over to peer companies, which improve efficiency to avoid becoming targets themselves.

A positive-sum game
While some see stock-market trading as a zero-sum game—if one investor profits, another loses—activism is a positive-sum game in that it grows the pie for both shareholders and society. Turning around an underperforming company is a public good. To encourage the creation of public goods, the creator needs to obtain a return on its investment. We recognize this with patents. After an innovation has been made, we would like it to be freely available—but doing so would remove the incentive to innovate in the first place. Patents enable innovators to generate a sufficient return to justify the investment in the innovation. The private use of swaps plays a similar role for activists. If the SEC needs swap disclosures for its own monitoring purposes, it could keep such information confidential.

Privacy is important not just to encourage activism, but also to help it succeed. Shareholder engagements are increasingly resolved privately, outside the public eye—92% of activist board placements in 2021 were achieved consensually. Private engagement often leads to more amicable and constructive resolutions. Once a situation becomes public, egos are often at play. The company publicly defends the status quo and opposes the activist’s ideas. Then, if discussions later lead to the company agreeing with the activist’s suggestions, management may be unwilling to implement them as it will lose face. Greater disclosure may increase the number of acrimonious public proxy fights, at great cost to shareholders and companies but at great benefit to lawyers and other advisers.

Transparency has many benefits, but constructive dialogues are often best had in private. As the SEC deliberates new rules, it should consider their impact on such discussions, which typically create long-term value for both shareholders and society.
(ZH) "A Paradigm Shift Western Media Hasn't Grasped Yet" - Russian Ruble Relaunc

"A Paradigm Shift Western Media Hasn't Grasped Yet" - Russian Ruble Relaunched, Linked To Gold & Commodities

With Russia’s central bank having just profoundly altered the international trade and monetary system by linking the Russian ruble to both gold and commodities, journalists in Moscow asked me to write a Q and A article on what these developments mean, and the ramifications of these changes on the Russian ruble, the US dollar, the gold price and the global system of currencies. This article has been published on the RT.com website here.
Since RT.com is now blocked and censored in many Western locations such as the EU, UK, US and Canada, and since many readers may not be able to access the RT.com website (unless using a VPN), my Questions and Answers that are in the new RT.com article are now published here in their entirety.
Who would have thought that citizens of ‘free speech’ Western countries would need a VPN to read a Russian news site?
Why is setting a Fixed Price for Gold in Rubles significant?
By offering to buy gold from Russian banks at a fixed price of 5000 rubles per gram, the Bank of Russia has both linked the ruble to gold and, since gold trades in US dollars, set a floor price for the ruble in terms of the US dollar.
We can see this linkage in action since Friday 25 March when the Bank of Russia made the fixed price announcement. The ruble was trading at around 100 to the US dollar at that time, but has since strengthened and is nearing 80 to the US dollar. Why? Because gold has been trading on international markets at about US$ 62 per gram which is equivalent to (5000 / 62) = about 80.5, and markets and arbitrage traders have now taken note, driving the RUB / USD exchange rate higher.
So the ruble now has a floor to the US dollars, in terms of gold. But gold also has a floor, so to speak, because 5000 rubles per gram is 155,500 rubles per troy ounce of gold, and with a RUB / USD floor of about 80, that’s a gold price of around $1940. And if the Western paper gold markets of LBMA / COMEX try to drive the US dollar gold price lower, they will have to try to weaken the ruble as well or else the paper manipulations will be out in the open.
Additionally, with the new gold to ruble linkage, if the ruble continues to strengthen (for example due to demand created by obligatory energy payments in rubles), this will also be reflected in a stronger gold price.
Gazprom – Natural gas powerhouse and Russia’s largest company
What does this mean for Oil?
Russia is the world’s largest natural gas exporter and the world’s third largest oil exporter. We are seeing right now that Putin is demanding that foreign buyers (importers of Russian gas) must pay for this natural gas using rubles. This immediately links the price of natural gas to rubles and (because of the fixed link to gold) to the gold price. So Russian natural gas is now linked via the ruble to gold.
The same can now be done with Russian oil. If Russia begins to demand payment for oil exports with rubles, there will be an immediate indirect peg to gold (via the fixed price ruble – gold connection). Then Russia could begin accepting gold directly in payment for its oil exports. In fact, this can be applied to any commodities, not just oil and natural gas.
What does this mean for the Price of Gold?
By playing both sides of the equation, i.e. linking the ruble to gold and then linking energy payments to the ruble, the Bank of Russia and the Kremlin are fundamentally altering the entire working assumptions of the global trade system while accelerating change in the global monetary system. This wall of buyers in search of physical gold to pay for real commodities could certainly torpedo and blow up the paper gold markets of the LBMA and COMEX.
The fixed peg between the ruble and gold puts a floor on the RUB / USD rate but also a quasi-floor on the US dollar gold price. But beyond this, the linking of gold to energy payments is the main event. While increased demand for rubles should continue to strengthen the RUB / USD rate and show up as a higher gold price, due to the fixed ruble – gold linkage, if Russia begins to accept gold directly as a payment for oil, then this would be a new paradigm shift for the gold price as it would link the oil price directly to the gold price.
For example, Russia could start by specifying that it will now accept 1 gram of gold per barrel of oil. It doesn’t have to be 1 gram but would have to be a discounted offer to the current crude benchmark price so as to promote take up, e.g. 1.2 grams per barrel. Buyers would then scramble to buy physical gold to pay for Russian oil exports, which in turn would create huge strains in the paper gold markets of London and New York where the entire ‘gold price’ discovery is based on synthetic and fractionally-backed cash-settled unallocated ‘gold’ and gold price ‘derivatives.
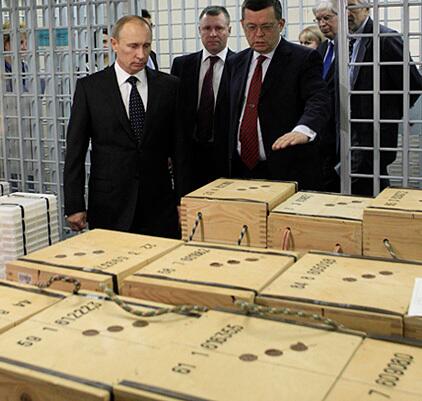
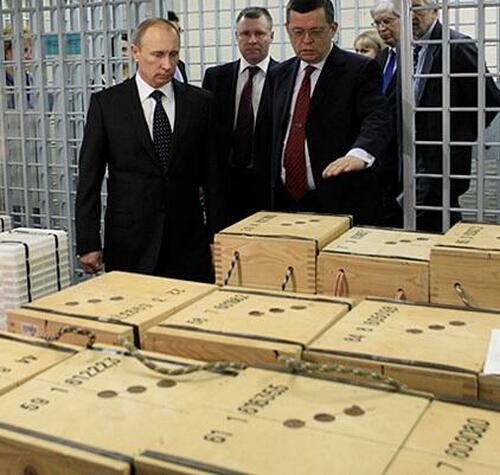
Russian gold bars stored in wooden boxes in the Gokhran vaults, Moscow
What does this mean for the Ruble?
Linking the ruble to gold via the Bank of Russia’s fixed price has now put a floor under the RUB/ USD rate, and thereby stabilized and strengthened the ruble. Demanding that natural gas exports are paid for in rubles (and possibly oil and other commodities down the line) will again act as stabilization and support. If a majority of the international trading system begins accepting these rubles for commodity payments arrangements, this could propel the Russian ruble to becoming a major global currency. At the same time, any move by Russia to accept direct gold for oil payments will cause more international gold to flow into Russian reserves, which would also strengthen the balance sheet of the Bank of Russia and in turn strengthen the ruble.
Talk of a formal gold standard for the ruble might be premature, but a gold-backed ruble must be something the Bank of Russia has considered.
What does this mean for Other Currencies?
The global monetary landscape is changing rapidly and central banks around the world are obviously taking note. Western sanctions such as the freezing of the majority of Russia’s foreign exchange reserves while trying to sanction Russian gold have now made it obvious that property rights on FX reserves held abroad may not be respected, and likewise, that foreign central bank gold held in vault locations such as at the Bank of England and the New York Fed, is not beyond confiscation.
Other non-Western governments and central banks will therefore be taking a keen interest in Russia linking the ruble to gold and linking commodity export payments to the ruble. In other words, if Russia begins to accept payment for oil in gold, then other countries may feel the need to follow suit.
Look at who, apart from the US, are the world’s largest oil and natural gas producers – Iran, China, Saudi Arabia, UAE, Qatar. Obviously, all of the BRICS countries and Eurasian countries are also following all of this very closely. If the demise of the US dollar is nearing, all of these countries will want their currencies to be beneficiaries of a new multi-lateral monetary order.
“It was once said that ‘gold and oil can never flow in the same direction’.”
What does this mean for the US Dollar?
Since 1971, the global reserve status of the US dollar has been underpinned by oil, and the petrodollar era has only been possible due to both the world’s continued use of US dollars to trade oil and the USA’s ability to prevent any competitor to the US dollar.
But what we are seeing right now looks like the beginning of the end of that 50-year system and the birth of a new gold and commodity backed multi-lateral monetary system. The freezing of Russia’s foreign exchange reserves has been the trigger. The giant commodity strong countries of the world such as China and the oil exporting nations may now feel that now is the time to move to a new more equitable monetary system. It’s not a surprise, they have been discussing it for years.
While it’s still too early to say how the US dollar will be affected, it will come out of this period weaker and less influential than before.
What are the Consequences of these Developments?
The Bank of Russia’s move to link the ruble to gold and link commodity payments to the ruble is a paradigm shift that the western media has not really yet been grasped. As the dominos fall, these events could reverberate in different ways. Increased demand for physical gold. Blowups in the paper gold markets. A revalued gold price. A shift away from the US dollar. Increased bilateral trade in commodities among non-Western counties in currencies other than the US dollar.

(ZH) These Are The Richest People In The World In 2022

These Are The Richest People In The World In 2022


--> Visual Capitalist : https://bit.ly/3tZhMbY

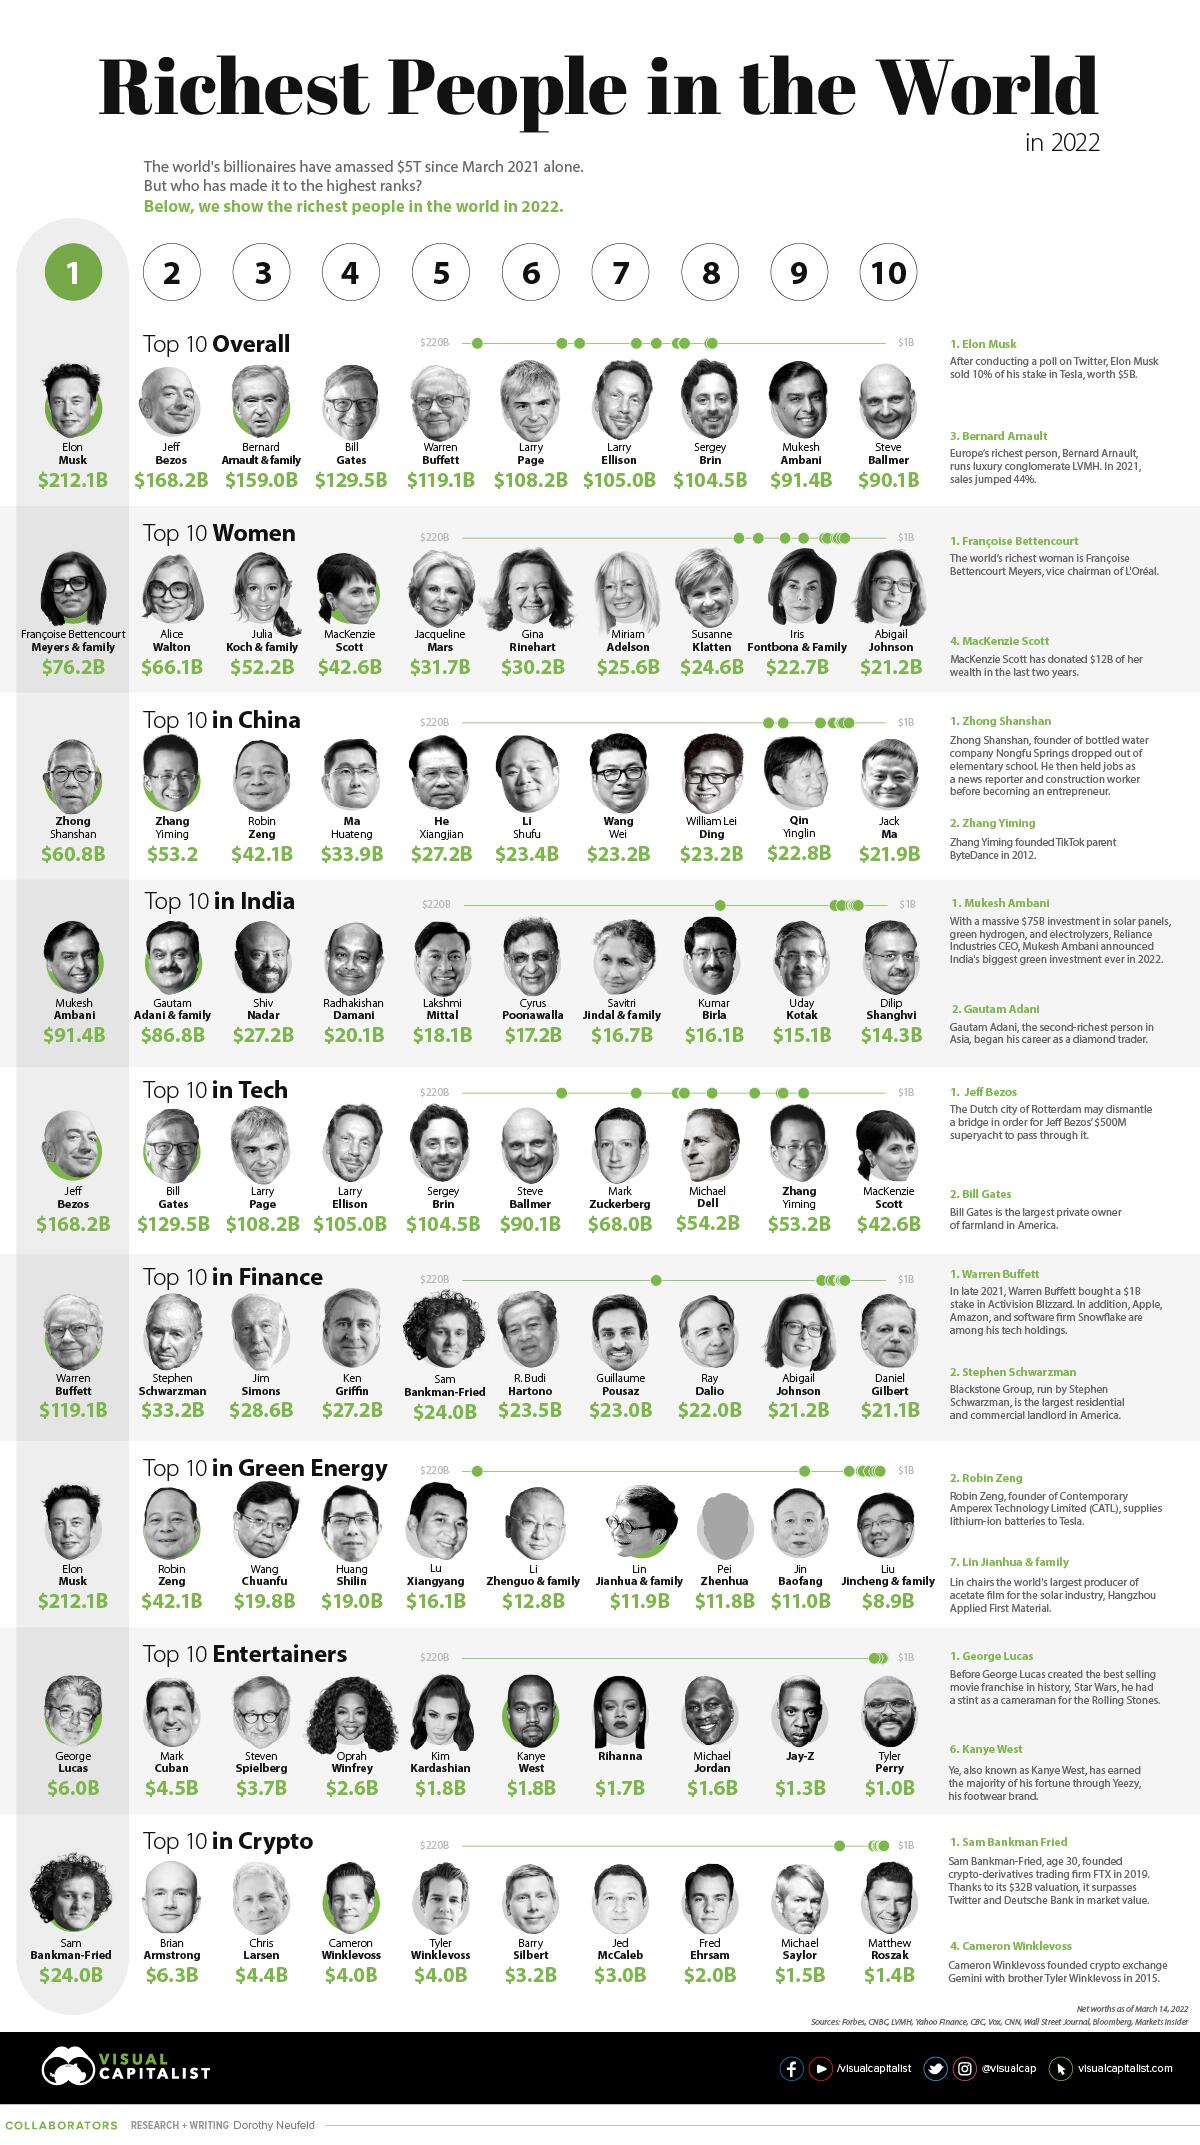
Today, the 10 richest people in the world control $1.3 trillion in wealth.
As Visual Capitalist's Dorothy Neufeld details below, this scale of wealth is equal to approximately 1.4% of the world economy, Amazon’s entire market cap, or spending $1 million a day for 3,000 years. In fact, it’s double the amount seen just two years ago ($663 billion).
As billionaire wealth accumulates at a remarkable speed, we feature a snapshot of the world’s richest in 2022, based on data from the Forbes Real-Time Billionaires List.
Top 10 Richest People in the World
Elon Musk, with a fortune of $212 billion, is the richest person on the planet.
Tesla delivered nearly one million vehicles globally in 2021. Despite facing a computer chip shortage, Tesla deliveries rose 87% year-over-year. Musk, who is also CEO and chief engineer of SpaceX, plans to send the largest rocket ever built into orbit in 2022. It spans 119 meters tall.
Here are the richest people in the world, based on data as of March 14, 2022:
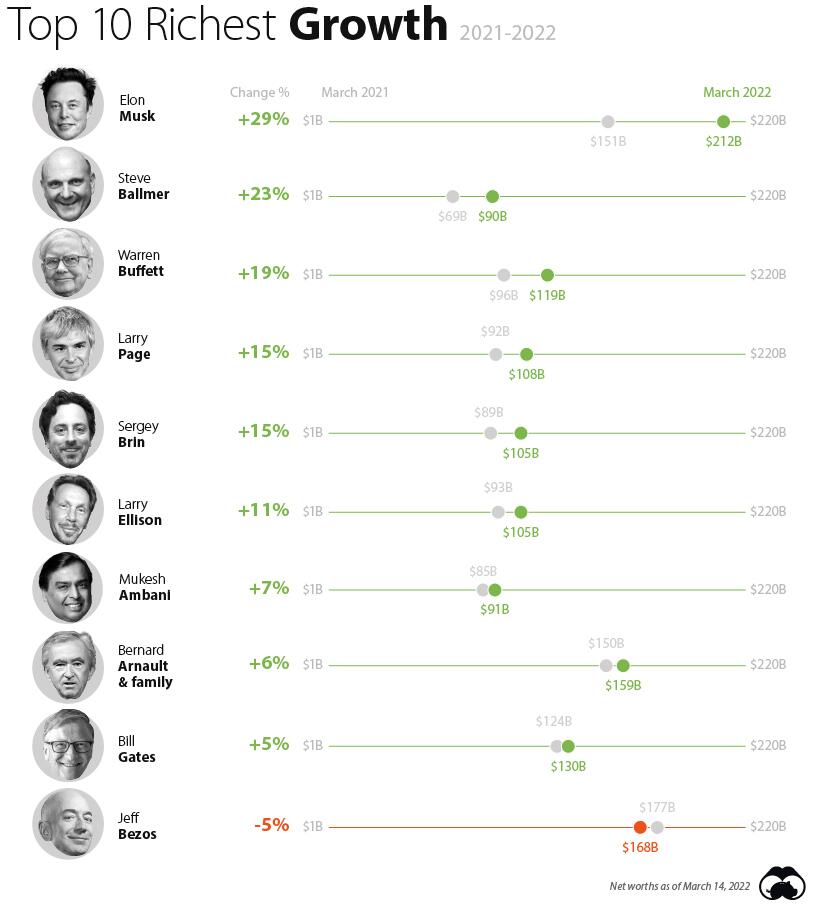
With a net worth of $168 billion, Jeff Bezos falls in second place. Bezos is the only billionaire in the top 10 to see a decline in wealth (-$9 billion) over the year. Since last March, Amazon shares have risen just 3% in light of weaker earnings and lagging retail performance.
Most notably, Mark Zuckerberg, CEO of Meta (formerly Facebook) fell off the top 10 for the first time since 2016. Meta shares plunged after reporting the first-ever drop in global daily active users since 2004.
Growth Rates of the Top 10 Overall
Among the 10 richest people in the world, here’s who saw their wealth rise the fastest:
Musk saw his fortune rise more than any other in this top 10 list. In 2021, Tesla became a trillion-dollar company for the first time, and Musk’s wealth jumped by 29% over the past year.
Crypto Billionaires in 2022
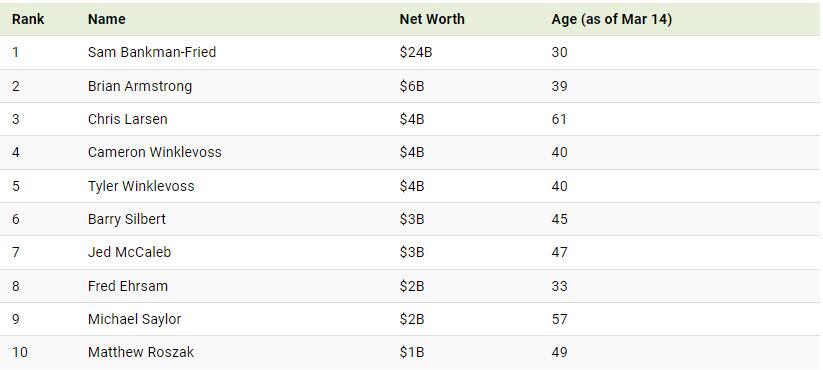
At least 10 people worldwide have seen their wealth climb into the billions thanks to the stratospheric rise of cryptocurrencies.
Sam Bankman-Fried, founder of the FTX crypto derivatives exchange, is at the top, with a jaw-dropping $24 billion net worth. Bankman-Fried launched the exchange in 2019 when he was 27.
FTX now has one million users and a $32 billion valuation.

Following Bankman-Fried is Brian Armstrong, the co-founder of cryptocurrency exchange Coinbase. It is the second-largest cryptocurrency exchange globally after Binance.

Also on the list are co-founders of Gemini cryptocurrency exchange Cameron and Tyler Winklevoss, each with a net worth of $4 billion. Like their rival, Mark Zuckerberg, they have their sights on building a metaverse.
Larger Shifts
Will billionaire wealth continue to accumulate at record rates? If the invasion of Ukraine presses on, it will likely have broader structural outcomes.
Some argue that war is a great leveler, a force that has reduced wealth inequality, as seen in the aftermath of WWII. Others suggest that it increases wealth divergence, especially when the war is financed by public debt. Often, costs have become inflated due to war, putting pressure on low and middle-income households.
Whether or not the war will have lasting effects on wealth distribution is an open question, however, if the pandemic serves as any precedent, the effects will be far from predictable.

WSJ : Tesla Deliveries Rose in Quarter Elon Musk Calls Exceptionally Difficult

Tesla Deliveries Rose in Quarter Elon Musk Calls Exceptionally Difficult
Electric-car maker delivered 310,000 vehicles globally

Tesla Inc. vehicle deliveries rose in the first quarter, but missed Wall Street expectations as the company struggled with global supply-chain disruptions and a brief Covid-19 shutdown at its Shanghai factory.

“This was an *exceptionally* difficult quarter due to supply chain interruptions & China zero Covid policy,” Tesla Chief Executive Elon Musk tweeted Saturday morning. Tesla employees and key suppliers “saved the day,” he added.

The electric-car maker said Saturday that it delivered 310,000 vehicles globally in the first three months of the year, rising about 68% from the same period a year ago. Deliveries were roughly flat from the final quarter of 2021.

Tesla is massively expanding production capacity to meet booming demand, adding new factories as it tries to maintain growth in deliveries by an average of 50%. Wall Street expected Tesla to deliver around 317,000 vehicles in the first quarter to generate what is anticipated to be a record quarterly profit when the company posts earnings in a few weeks.

Other major auto makers reported slowing U.S. sales for the first quarter due to vehicle shortages.

Tesla’s largest factory, located in Shanghai, idled production for the last four days of the quarter due to a Covid-19 outbreak in the city, prompting questions over how it might impact the quarter’s deliveries. The factory builds Model 3s and Model Ys, and last year, Tesla sold more than 470,000 cars that were made at the plant.

The 25-million-person city of Shanghai went into a partial lockdown in recent days amid an outbreak of Covid-19 cases. Residents near the Tesla factory were ordered to stay inside their homes, public transportation was halted and traffic in the area was severely limited.

The China factory also shut down for two days earlier in March while the company tested employees for Covid-19.

“I don’t think it’s going to materially affect deliveries,” Tu Le, managing director of Sino Auto Insights, said ahead of the delivery results. “January, February, March are notoriously slow for vehicle sales in China.”

He said sales figures will continue to be closely watched as the impact of pandemic-related lockdowns on the country is unpredictable.

Model S and Model X vehicle deliveries totaled 14,724. Tesla also delivered a combined 295,324 Model 3 sedans and Model Y compact sport-utility vehicles. The company doesn’t release deliveries by region. Additionally, it said it produced 305,407 vehicles.

The Model 3 and Model Y are Tesla’s bestselling cars and the backbone of its production. Mr. Musk said the company doesn’t plan to introduce any new vehicle models in 2022.

Tesla began delivering Model Ys from a new plant, located in Germany, last month. The company is scheduled to open another factory in Austin, Texas, on Thursday. It says the Germany factory will eventually ramp up to 500,000 vehicles a year, starting with the Model Y.

Global supply-chain issues across industries and record inflation rates could impact Tesla’s growth trajectory.

Mr. Musk last month tweeted that Tesla was seeing “significant recent inflation pressure in raw materials & logistics.” Prices for the Model 3 and Model Y have jumped as much as 30% over the past year, according to Bernstein Research.

Still, analysts predict Tesla will continue its pattern of delivering more vehicles each consecutive quarter for the rest of the year with full-year totals to top 1.5 million cars and SUVs.

FT : Global fundraising in capital markets shrinks by $900bn in first quarter

Global fundraising in capital markets shrinks by $900bn in first quarter
Flow of deals evaporates as investors take fright at volatility and US interest rate path

Global fundraising in capital markets shrivelled by more than $900bn in the first quarter from the same period in 2021 as surging inflation, war in Ukraine and volatile asset prices delayed stock listings and hampered bond deals.

Businesses raised $2.3tn in the first three months of the year through equity sales and new borrowings in bond and loan markets, the smallest sum in six years and down from more than $3.2tn from a year ago, according to data provider Refinitiv.

Bankers and investors say the drop-off in activity stems from dramatic swings in global stock markets and the start of interest-rate rises from the Federal Reserve, which has prompted money managers to shy away from riskier investments and high-flying stocks.

“The hard part and what has been scary about this quarter is the volatility,” said Richard Zogheb, global head of debt capital markets at Citi. “When you have equity markets up a lot and then down a lot, it’s just insane. There is such uncertainty about where things are going.”

New stock market debuts all but dried up in the US, with fewer than two dozen businesses going public in a traditional initial public offering so far this year. Globally, equity sales have raised $131bn, about half the level of last year. That sum is roughly in line with activity in 2019 and 2020, but it is largely because of a string of big listings in Asia, where nine of the year’s 15 largest IPOs have launched. In the US, stock sales are at the lowest since 2009 in the depths of the financial crisis.


The year’s blockbuster stock market debut of LG Energy Solutions in South Korea, which raised nearly $11bn, dwarfs any other float so far this year. That includes the $1.1bn raised by buyout shop TPG Partners in the US and $1bn by Vaar Energi, one of Norway’s biggest oil and gas producers.

Market volatility also pushed borrowing costs in the $10tn US corporate bond market higher, although companies have still been able to raise needed cash.

Total issuance of corporate bonds fell 7 per cent to $1.36tn, just over $100bn short of last year’s levels. The dip was led by a noticeable decline in borrowing from companies that rating agencies consider to be more risky.

Some lenders backed away given the volatility, refusing to provide credit or seeking higher borrowing costs when they could get comfortable with the risks. Lending in the high-yield bond market globally fell 72 per cent to $59bn. Issuance in the US totalled just $34bn for the first quarter, down from $139bn a year prior and the lowest first quarter tally since 2016, when an economic slowdown in China sent shockwaves through global markets.

Yields on junk bonds, debt of lowly-rated corporate issuers, climbed from 4.3 per cent to over 6 per cent, largely as a result of rising benchmark interest rates, rather than a dramatic reassessment of the risk of lending to low-quality companies.

Some stability has crept in to equity and corporate bond markets lately, even as sovereign bonds — the backbone of the global financial system — have continued to slide in value. That has opened the door for some companies, including financial technology company SS&C Technologies, to tap investors for capital after postponing planned borrowings earlier this year.

“Companies can’t wait for ever,” said Alexandra Barth, co-head of US leveraged finance at Deutsche Bank. “There is a hope that we see some stability in Europe. There is an ability to wait for some time but eventually that patience will dissipate and we will see more deals that have to come to market. Eventually companies have to accept that this is the new reality.”

Bankers and investors are waiting for the IPO market to reopen in the US, with several — private companies worth at least $1bn — angling to go public. The recent volatility has prompted some investors, including Fidelity and T Rowe Price, to scale back their assumptions for what some private holdings are now worth. Earlier this month, grocery delivery company Instacart decided to cut its own valuation by 40 per cent to $24bn in a new funding round.


Although some companies have delayed listing plans until the second half of the year, many businesses such as eyecare company Bausch & Lomb have continued to update paperwork with US securities regulators so they are ready to list quickly when market conditions improve.

“The backlog is high and investors have a lot of capital to put to work,” said David Ludwig, head of equity capital markets at Goldman Sachs. “The combination of those two things means once we see more stability in the broader markets, [IPOs] will be welcome.”

WWD : Kering Settles Bottega Veneta Tax Dispute

Kering Settles Bottega Veneta Tax Dispute
Kering is settling a tax case related to Bottega Veneta by paying 186.7 million euros to the Italian Revenue Agency.

MILAN — Kering is settling a tax dispute pertaining to its controlled Bottega Veneta brand through the payment of 186.7 million euros to the Italian Revenue Agency, the Agenzia delle Entrate.

Investigations made by the prosecutor’s office in Milan determined that two Bottega Veneta foreign branches were allegedly actually operating in Italy. The amount due to be paid by Kering relates to additional taxes and interest the prosecutor claims is owed to the Italian government.

“In the spring of 2019, given the rapid changes in its business environment, its strong international growth and some uncertainties of Italian legislation, Bottega Veneta proactively made contact with the Italian Revenue Agency to discuss its tax position,” Kering said Friday in a statement. “This agreement is the result of those discussions. Given the prudent assessment of tax liabilities in Kering’s accounts in recent years, this will have no impact on the group’s results in 2022 or on the normative recurring tax rate in future years. Kering will continue to base its relationship with tax authorities on trust and transparency over the long term.”

Similarly, in 2019, Kering concluded a settlement with the Italian Revenue Agency relating to claims connected to its Swiss subsidiary Luxury Goods International S.A. (LGI). The claims regarded “the existence of a permanent establishment in Italy in the period 2011-2017 with the associated profits, and the transfer prices applied by LGI in the same period with its related party Guccio Gucci SpA.” Kering paid 897 million euros in additional taxes, along with further payment for penalties and interest. The total required payment amounted to 1.25 billion euros.

The investigations identified an alleged tax evasion of 1.4 billion euros. According to the Italian tax authorities, in distributing Gucci products in Italy through a directly operated Switzerland-based company named Luxury Goods International, Kering had intentionally avoided the payment of taxes in Italy.

Among the international companies that have settled with the Italian Revenue Agency, in 2016, Apple paid a sum of 318 million euros and the following year, Google paid a total of 306 million euros to regularize its fiscal position in the country. Other fashion companies that have settled with the Italian tax authorities over the years range from Prada to Bulgari.

(ZH) Yield Curve Inversions & Media's Denial Of History

Yield Curve Inversions & Media's Denial Of History

Yield curve inversion conversations are dominating the media to the point it almost sounds like the start of a bad joke.
“A yield curve inversion walks into a bar. The bartender asks ‘hey, what’s got you down?'”
The conversations are primarily dismissive under the “this time is different” scenario. As noted by Yahoo Finance last week:
“Take a look at the August 2019 inversion. A recession did happen a year and a half later. But it was triggered by a global pandemic — something bond markets could not have possibly foreseen or predicted.”
That isn’t accurate as the recession occurred only 6-months later. Furthermore, the bond market did know there was something very wrong economically as the Fed was engaged in a massive repurchase operation to bail out hedge funds.
As we noted then, all that was required to push the economy into a recession was an “unexpected, exogenous event.” That event turned out to be a pandemic.
Notably, when psychology changes, for whatever reason, the rotation from “risk-on” to “risk-off” will find Treasury bonds as a “store of safety.”Historically, such is always the case during crisis events in markets.
Once again, it is pretty likely investors should not overlook the message from the bond market. Bonds are essential for their predictive qualities, so analysts pay enormous attention to U.S. government bonds, specifically to the difference in their interest rates.
This data has a high historical correlation to where the economy, stock, and bond markets generally head longer term. Such is because everything from volatile oil prices, trade tensions, political uncertainty, the dollar’s strength, credit risk, earnings strength, etc., reflects in the bond market and, ultimately, the yield curve.
Yield Curve Inversions
When it comes to yield curve inversions, the media always assumes this time is different because a recession didn’t occur immediately upon the inversion. There are two problems with this way of thinking.
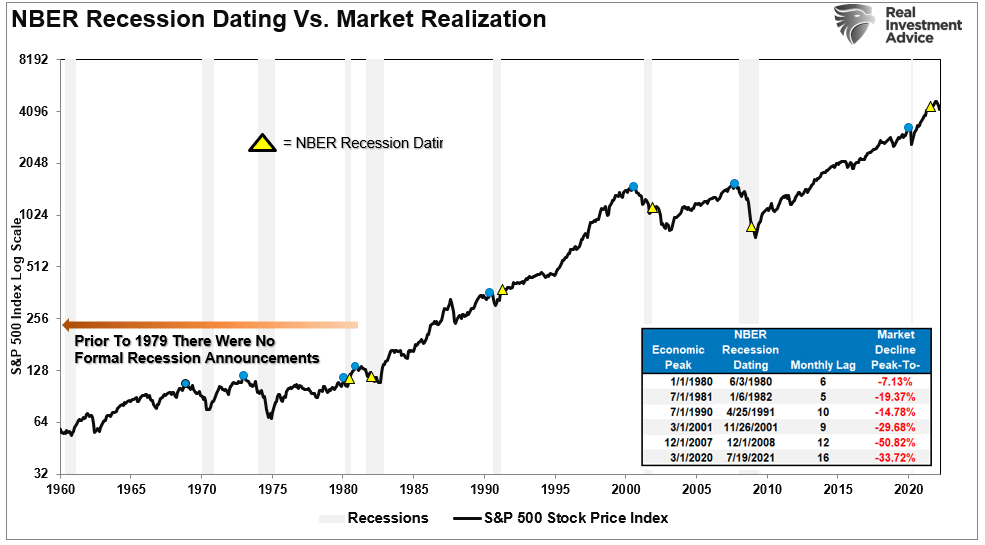
  1. The National Bureau Of Economic Research (NBER) is the official recession dating arbiter. They wait for data revisionsby the Bureau of Economic Analysis (BEA) before announcing a recession’s official start. Therefore, the NBER is always 6-12 months late dating the recession.
  2. It is not the inversion of the yield curve that denotes the recession. The inversion is the “warning sign,” whereas the un-inversion marks the start of the recession, which the NBER will recognize later.
As discussed in “BTFD Or STFR,” if you wait on the official announcement by the NBER to confirm a recession, it will be too late. To wit:
“Each of those dots is the peak of the market PRIOR to the onset of a recession. In 9 of 10 instances, the S&P 500 peaked and turned lower prior to the recognition of a recession.“
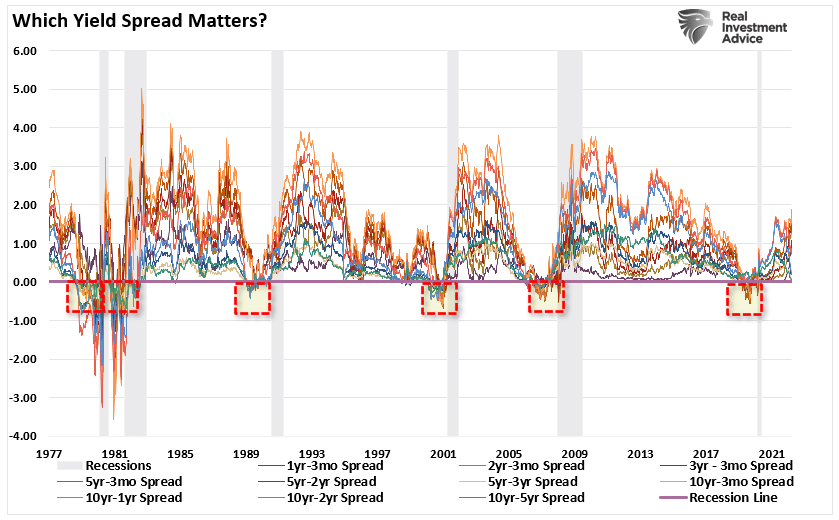
Most of the yield spreads we monitor, shown below, have yet to invert. However, the best signals of a recessionary onset occur when a bulk of the yield spreads turn negative simultaneously. However, even then, it was several months before the economy slipped into recession.
When numerous yield spreads turn negative, the media will discount the risk of a recession and suggest the yield curve is wrong this time. However, the bond market is already discounting weaker economic growth, earnings risk, elevated valuations, and a reversal of monetary support.
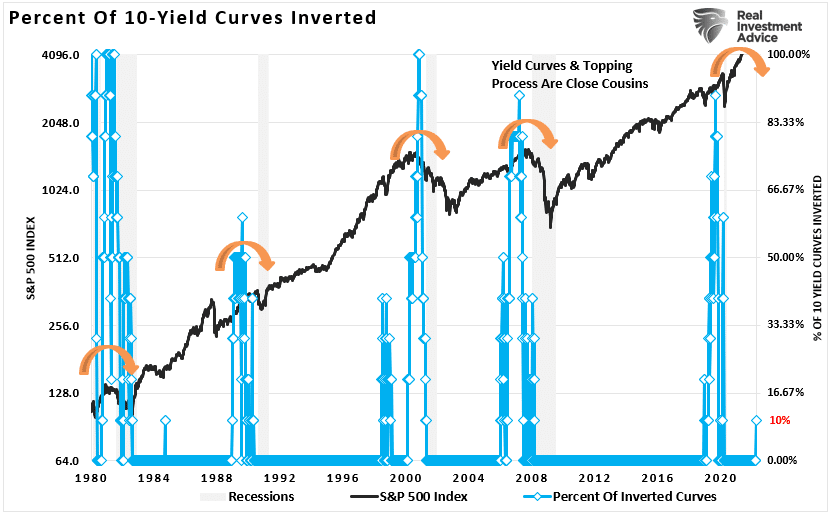
Historically, a recession followed when 50% or more of the tracked yield curves inverted. Every time. (Read this for a complete history.)
Ignore At Your Own Risk
In the World War II real-time strategy (RTS) game Company of Heroes, the engineer squad would sometimes say:
“Join the army they said. It’ll be fun they said.”
Since then, the statement has become a common meme on the internet to espouse the disappointment from various actions, from doing the laundry to getting a job.
Well, the latest suggested action, which will ultimately lead to investor disappointment, is:
“Ignore the yield curve they said. It’ll be fun they said.”
“Historically, equity markets tended to produce some of the strongest returns in the months and quarters following an inversion. Only after [around] 30 months does the S&P 500 return drop below average,”
12-months later, the market was down 35%, and the economy was in the deepest recession since the “Great Depression.”
The yield curve is sending a message that investors should not ignore. Furthermore, it is a good bet that “risk-based” investors will likely act sooner than later. Of course, the contraction in liquidity causes the decline, which will eventually exacerbate the economic contraction.
Despite commentary to the contrary, the yield curve is a “leading indicator” of what is happening in the economy currently, as opposed to economic data, which is “lagging” and subject to massive revisions.
More importantly, while the consumer may be continuing to support growth currently, such can, and will, change dramatically when job losses begin to occur. Consumers are fickle beasts, and it will happen very rapidly when a change in psychology occurs.
While using the “yield curve” as a “market timing” tool is unwise, it is just as foolish to dismiss the message it is currently sending entirely.
History has not been kind to those that do.