Senator Lummis Introduces Landmark Bitcoin Bill: Here's What's In It
The bipartisan Lummis-Gillibrand overhaul legislation has been introduced – here’s everything you need to know about the Bitcoin and crypto bill.
The bipartisan Bitcoin legislation by U.S. Senators Cynthia Lummis (R-WY) from the Senate Banking Committee and Kirsten Gillibrand (D-NY) from the Senate Agriculture Committee has finally been introduced – months after the effort was first announced.
The legislation, coined the Responsible Financial Innovation Act, also referred to as Lummis-Gillibrand, seeks to encourage “responsible innovation” by integrating digital assets into existing laws and providing greater clarity to an industry that is largely unregulated and lacks common standards and defining measures.
Part of the new bill’s mission is to clean up the existing mishmash of bills and legislation (more than 50) that apply to cryptocurrencies, including parts of the Infrastructure Investment and Jobs Act passed last year.
As noted here, “Washington’s efforts to oversee digital assets date back to the Obama administration but remain scatter-shot, rife with holes and overlapping jurisdictions.”
The text boasts 69 pages of detailed definitions and provisions.
SEC AND CFTC: THE WATCHDOGSThe bill tasks the U.S. Securities and Exchange Commission (SEC) and Commodities Futures Trading Commission (CFTC) with the bulk of the work as lawmakers strive to bring the broad cryptocurrency space under the umbrella of specific regulators once and for all.The SEC will regulate digital assets classified as securities whereas the CFTC will be in charge of overseeing those that receive the commodity stamp.The bill itself contains language that will serve as a guiding evaluator for classifying digital assets into one of the two classes.Lummis-Gillibrand proposes an examination of the rights or powers entitled to the holder of a digital asset as well as that asset’s inherent purpose.According to the bill, an ancillary asset is an intangible, fungible asset that is offered, sold or otherwise provided to a person in connection with the purchase and sale of a security through an arrangement or scheme that constitutes an investment contract.The legislation uses the Howey test to determine that an ancillary asset provided to a purchaser under an investment contract is not inherently a security.In order to be classified as a security, the digital asset must provide the holder with a debt or equity interest in a business entity, liquidation rights or entitlement to interest or dividend payments from a business entity, profit or revenue share in a business entity derived “solely from the entrepreneurial or managerial efforts of others,” or any other financial interest in the entity.Digital assets that are not fully decentralized and which benefit from “entrepreneurial and managerial” efforts that determine the value of the assets but are not debt or equity or don’t create rights to profits or other financial interests in a business entity are not classified as securities as long as disclosures are filed with the SEC twice a year.This presumption that an ancillary asset is a commodity can be appealed in court.The legislation also grants the CFTC exclusive spot market jurisdiction over all fungible assets which are not securities, including ancillary assets. Exchanges will need to register with the CFTC to conduct trading activities and will need to abide by rules in the areas of custody, customer protection, prevention of market manipulation and information-sharing. The CFTC will be allowed to charge a small fee on digital asset exchanges to cover increased costs to the agency.The assignment of the CFTC to oversee spot markets could help pave the way for a bitcoin spot exchange-traded fund (ETF) in the U.S. as the bulk of the SEC’s argument against it relate to the lack of regulation on spot markets and the reluctance of exchanges to work with regulators.Both the SEC and the CFTC are also directed by the bill to study and report on the creation of a self-regulatory organization (SRO) that could play a complementary role in working with regulators in the burgeoning market.Finally, the Responsible Financial Innovation Act also tasks the two watchdogs, in consultation with the Treasury secretary, to develop a comprehensive set of guidances for digital asset intermediaries to think about their cybersecurity, including on the topics of security operations, risk identification and mitigation, sanctions avoidance, money laundering and terrorist financing. The agencies are expected to develop rules for such cybersecurity standards.ENERGYLummis-Gillibrand requires a study on the power consumption of digital assets.The study will seek to determine the best ways to encourage innovation while ensuring these technologies work together with other areas of society to help the world move closer to climate goals through the deployment of more renewable energy sources and clean energy as well as reducing energy waste.This task will lie with the Federal Energy Regulatory Commission, which will work in consultation with the CFTC and the SEC to conduct the study. One of its goals is to analyze the type and amount of energy used for mining.TAXESAs previously hinted at by Senator Lummis, the legislation will provision a tax exemption for transactions of up to $200 as a means to encourage the use of digital assets as payment for goods and services. However, the bill notes that all transactions which are part of the same transaction or a series of related transactions will be treated as a single transaction for the purposes of the tax exemption.The bill goes one step further to declare that miners are not to be seen as brokers, and that digital assets obtained from mining activities are not to be treated as income until they are converted into fiat currency.Additionally, Lummis-Gillibrand also specifies that digital asset lending agreements are not generally taxable events, similarly to securities lending transactions, and provisions that certain decentralized autonomous organizations (DAOs) are business entities for tax purposes. However, this requires that the DAO be incorporated or organized under the laws of a jurisdiction as such.Lastly, on the taxation side, the bill requires the U.S. Internal Revenue Service (IRS) to study and clarify issues such as forks and airdrops, merchant acceptance of digital assets, mining and staking, charitable donations and the legal characterization of stablecoins as indebtedness.401(K)Lummis-Gillibrand requires the Government Accountability Office (GAO) to analyze the opportunities and risks associated with investing in digital assets with retirement accounts.GAO’s findings are to be reported to Congress, the Treasury Department and Labor Department.CONSUMER PROTECTIONSIn an attempt to enhance customer protections in the cryptocurrency markets, the bipartisan bill will require providers of digital assets to disclose information about their product, including source code versioning and the legal treatment of each digital asset.The bill also grants the right to a person to keep and control the digital assets they own.OTHER PROVISIONSLummis-Gillibrand also includes provisions on stablecoins, such as requiring issuers to hold U.S. dollars or dollar equivalents to enable redeeming by the customer at any given time; an advisory committee to watch and study the latest developments in the space and make recommendations so that regulations remain up to date and valid; and clear definitions for the different types and styles of digital assets and their related technologies, markets and practices.
In Lummis’ words, the bill will "fully integrate digital assets into [the] financial system" and bring order to the crypto space.
“We can’t overregulate,” adds Lummis. “If we overregulate, it [Bitcoin innovation] will go to other countries.”
Japan’s Debt Debate: Is It Heading for a Titanic Crash?
Top finance officials seek balanced budget, likening the nation to a ship heading for an iceberg, but Abe camp says deficit is misunderstood
TOKYO—When Japan’s leader released his economic vision Tuesday, he left out an important date.
Prime Minister Fumio Kishida deleted a pledge from earlier government statements calling for Japan’s budget to be balanced by 2025. And he declined to give a date by which Japan would do something to lower its government debt, while promising to significantly increase military spending.
It is a bold stance, given that the debt tops ¥1.1 quadrillion or $8.3 trillion at current rates, more than twice the size of the economy. The omission marks a high point in the influence of a group within the ruling Liberal Democratic Party that has embraced a view attributed to former U.S. Vice President Dick Cheney: “Reagan proved deficits don’t matter.”
Many countries added heavily to their debt during the Covid-19 pandemic and a global debate is under way about whether they need to cut back now. Japan’s experience is likely to be instructive because it has the highest government debt among leading economies and at the same time one of the most powerful factions arguing that the world’s understanding of debt is flawed.
This camp, led by former Prime Minister Shinzo Abe, says Japan has room to spend a lot more—including on its defense budget to counter China. The other side of the argument is spearheaded by a vice finance minister who says the country is like the Titanic, heading for a massive iceberg of debt.
Some members of the free-spending group have embraced a maverick American economic school of thought known as modern monetary theory, or MMT. It says countries that issue debt denominated in their own currency, like the U.S. and Japan, won’t ever need to default on debt because they can simply print more currency to pay it back.
“Trying to achieve fiscal balance is meaningless per se,” said Shoji Nishida, a member of Parliament’s upper house from the Liberal Democratic Party who keeps a book by American MMT guru Stephanie Kelton on his desk. “The reason Japan is in a mess is because of the mistaken view by the Ministry of Finance that there is a limit to fiscal resources.”
In recent speeches, Mr. Abe has echoed such theories. He described the central bank, the Bank of Japan, as a subsidiary of the government and said any expiring government debt could simply be rolled over into new debt. The Bank of Japan already owns nearly half of the government’s debt.
This debt downplaying—or denial that it is really debt at all—alarms others in the ruling party and career officials at the Ministry of Finance.
They say every yen spent by the government ultimately has to be recouped through taxes or other revenue—in other words, that outsize borrowing can’t go on forever. Now that the worst of the pandemic is over, they say Japan needs to rein in debt soon.
Last fall, vice minister of finance Koji Yano published an article in the monthly magazine Bungei Shunju denouncing the MMT-oriented camp and comparing Japan to the Titanic.
“I don’t know how far until we crash into it, but we can be sure that Japan is barreling toward an iceberg,” Mr. Yano wrote.
More recently, the weak yen—which fell to another 20-year low against the U.S. dollar this week—has added to concerns that relying on the Bank of Japan to buy government debt at low interest rates could undermine confidence in the currency.
Mr. Nishida, the MMT advocate in the ruling party, called Mr. Yano a con artist, saying he was trying to scare people to preserve the ministry’s longtime power over the nation’s purse strings. Mr. Yano declined to comment through a spokesperson.
Mr. Yano’s argument has won support from many in the ruling party, including former Finance Minister Fukushiro Nukaga.
“I believe it is our role and responsibility to maintain trust in our finances and trust in the currency,” Mr. Nukaga said in an interview.
He said Japan would eventually need to look at raising its national sales tax, which currently stands at 10%. An increase “could actually promote greater consumption by erasing worries about the future,” he said.
Mr. Nukaga leads a ruling party study group that has competed with another group, led by MMT advocate Mr. Nishida. Their tussle came to a head in recent weeks as the Kishida government weighed whether to uphold earlier pledges to get the budget into primary balance by 2025. Primary balance means outlays match revenue, excluding interest payments on government debt and revenue from new issuances.
The final language nodded to the need for healthier finances but mainly sided with the free-spending camp by leaving out the 2025 date. That clears the way for a generous increase to the defense budget next year. Eventually the ruling party wants military spending to reach 2% of gross domestic product, nearly double the current proportion.
MMT advocates say that while governments such as Japan’s have no limits on issuing debt, they do have to deal with the risk of inflation if spending outweighs the economy’s capacity to produce goods and services. Japan’s overall inflation hit 2.5% in April, the highest rate in three decades.
That figure is well below the 8%-plus inflation in the U.S. and it hasn’t deterred the pro-spending faction. It blames Japan’s inflation on the high cost of imports such as oil and gas and it says new spending on defense isn’t likely to overstress the nation’s productive capacity.
Mr. Abe, the former prime minister, “is now a full-throated proponent of deficit spending,” wrote U.S.-based Abe biographer Tobias Harris in a recent commentary. “If the government can continue to run large deficits, then the government does not have to grapple with a guns or butter trade-off.”
Blackstone, Other Large Private-Equity Firms Turn Attention to Vast Retail Market
Firms court individuals with $1 million to $5 million in investible assets
Private-equity firms have spent decades raking in giant sums from pension funds and other big institutions. Now they are going hat in hand to a different kind of investor: everyday millionaires.
Some of the biggest firms, including Blackstone Inc., BX -2.10% Blue Owl Capital Inc., OWL 3.14% Apollo Global Management Inc. APO 2.41% and Ares Management Corp. ARES 0.07% , have created a host of new products aimed at people with $1 million to $5 million in investible assets and are hiring armies of staff to market them to private banks and independent financial advisers.
Behind the effort is the recognition that institutions, which committed nearly $1.3 trillion to private markets in 2021, according to PitchBook, have all but filled up on them. Historically low interest rates since the 2007-09 financial crisis led many to swap a portion of their public stock and bond portfolios for higher-returning investments in private equity, real estate, infrastructure and credit.
That shift is now largely complete. Pension funds and sovereign-wealth funds had an average of 26% and 35%, respectively, of their portfolios in those asset classes as of the end of the year, according to Preqin. Some are even dialing back their private-equity allocations after the recent drop in public markets left them overexposed to it.
So private-equity firms are now looking at another opportunity that is potentially even bigger involving the so-called mass affluent. Individuals worth $1 million or more held $79.6 trillion in investible assets globally in 2020, according to a 2021 report by consulting firm Capgemini SE. CGEMY 0.86% And private-equity firms estimate that less than 5% of that is currently invested with them.
Unlike the typical buyout fund, products for individuals are perpetual or evergreen, meaning the capital is never fully returned. That has made them particularly attractive to publicly traded private-equity firms whose shareholders prize steady growth in management fees.
The upshot has been a scramble to win over the wealthy.
“It’s a land grab,” said Matt Brown, chief executive of CAIS, a platform that gives independent financial advisers access to so-called alternative investment products. “You’re seeing the mutual-fund boom 2.0,” he said, referring to the rise in popularity of mutual funds during the 1990s.
There is no guarantee the effort will succeed. For one thing, it depends on continuing investor confidence, which could be shaken by recent market choppiness, adding to the allure of liquid assets that are perceived to be less risky. Firms say the current environment will demonstrate the stability of their products over the long run.
While institutions can choose from thousands of private-equity funds, many firms are betting that advisers to the wealthy won’t want a long menu of products to evaluate. They argue that moving quickly and spending big now will give them a lasting edge over rivals.
Blackstone, the industry behemoth that launched its first perpetual vehicle aimed at individuals in early 2017—a lower-cost nontraded real-estate investment trust—now sources nearly a quarter of its $915 billion in assets from private wealth. The firm has since added two more funds targeting individuals: a nontraded business-development company and a real-estate vehicle focused on Europe.
Blackstone, which expects to reach $1 trillion in assets this year, said in April it gets $4 billion to $5 billion of inflows a month from the three products combined.
“Our great insight was bringing the fees way down and bringing our quality of investment performance to this space,” said Blackstone President Jonathan Gray.
The firm built a team of 278 people, many of whom educate advisers on its products and service clients. In May, Blackstone filed with the Securities and Exchange Commission to launch a fourth fund, designed to offer individual investors access to its private-equity business, which would for the first time give them a slice of the big corporate leveraged buyouts the firm is famous for.
Though much smaller than Blackstone, Blue Owl was also an early mover in catering to individuals, beginning in 2016. The firm said recently it got an average of about $700 million a month in inflows in April and May from its two evergreen credit funds.
Others are striving to catch up. Soon after becoming Apollo’s chief executive last year, Marc Rowan made expanding the firm’s private-wealth business a top strategic priority. Apollo now has three products and 145 people dedicated to the effort, thanks in part to its December deal to buy the U.S. wealth-distribution and asset-management businesses of Griffin Capital Co.
Apollo in April said it got over 10% of its asset-management fundraising from private wealth in the first quarter and announced plans to introduce one to two new products each quarter over the subsequent 18 to 24 months. Mr. Rowan said 50% of a client’s portfolio could one day be invested in alternatives to publicly traded stocks and bonds.
New products in the pipeline tap Apollo’s traditional investing strengths such as credit, said Stephanie Drescher, the firm’s chief client and product-development officer, who is overseeing the effort.
Ares in April launched one new product for individual investors and filed for another. The firm said it raised $2 billion from wealthy individuals during the first quarter and said it had 105 employees dedicated to the effort.
Blackstone is confident in its first-mover advantage, said Joan Solotar, the firm’s global head of private-wealth solutions.
“It’s not lost on distribution partners—who are being approached by everyone under the sun—that competitors have seen Blackstone’s success and are jumping on the bandwagon,” she said.
Toshiba CEO Doesn’t Want Buyer to Split Up Company
Japanese conglomerate vets 10 proposals amid conflicts on the board
TOKYO—The chief executive of Toshiba Corp. TOSYY -1.04% , the Japanese industrial conglomerate that has put itself up for sale, said he wanted any buyer to keep the company in one piece to promote innovation.
The condition laid out by Chief Executive Taro Shimada could make the sale process more challenging because major global private-equity firms tend to want a free hand in slicing and dicing the companies they acquire. Some analysts have said the parts of Toshiba, which makes power turbines, elevators and semiconductors among other products, might be worth more separately than together.
Toshiba put itself up for auction in late April after shareholders rejected a plan to split the company into two. U.S. private-equity firm Bain Capital and other global firms have expressed interest in making a bid. The company said last week it has received buyout offers from eight investors and two proposals for minority investment.
General Electric Co. , long a model for Toshiba, is splitting into three tightly focused independent companies—aviation, healthcare and power. But such radical surgery has long faced resistance at Japan’s diversified conglomerates, in part because the managers and engineers are mostly lifetime employees attached to the security and prestige of a big corporate name.
In an interview, Mr. Shimada harked back to Toshiba’s heritage as an innovator, observing that it was credited with building the world’s first laptop computer in the 1980s. He said splitting the company into many parts might be efficient in a narrow sense but would deprive researchers of chances to cross-fertilize ideas.
“If we wanted to cut and slice the company, the real jewel would go away,” Mr. Shimada said.
Mr. Shimada cited a technology Toshiba is developing to deliver genetic changes to specific cells such as cancer cells. He said it was invented by a team of 10 specialists from multiple disciplines. “All those different types of top-notch researchers working together would create something completely new,” he said.
Jerry Black, the chairman of a special board committee that is reviewing bids, said he agreed that a large-scale breakup wouldn’t be in Toshiba’s best interests. He said the board needed to consider the feasibility of a buyer’s bid, and a breakup would likely run into trouble with Japan’s industry ministry.
Mr. Shimada released a new business plan last week that calls for lifting revenue by more than 50% over the next eight years. Under the plan, the elevator and lighting businesses, which the company had earlier contemplated selling, are now positioned as core businesses.
The sale process is testing Toshiba’s relationship with foreign shareholders, who own about half the company after they injected capital in 2017.
The company in May nominated new director candidates from major U.S.-based shareholders Elliott Management Corp. and Farallon Capital Management LLC.
Mariko Watahiki, a former judge who serves on Toshiba’s board, dissented on those nominations, saying that if they went through, nearly half of the board would have ties with a small group of major foreign shareholders. She said that would be unfair to other shareholders without such representation.
Mr. Black said the two were nominated based on their individual talents and would help the board assess the bids.
Shareholders will vote on the nominations at Toshiba’s annual meeting on June 28. After that, Mr. Black said the company planned to narrow down the contending bidders to a handful, who would then do more due diligence and offer legally binding bids.
He expressed hope that if the company is taken private, the new owners could transform Toshiba without having to deal with the clamor of contending shareholders and directors that has led the company into turmoil in recent years.
Cipriani to Get New Lifeline With Money From Hedge Fund
King Street Capital said to be in advanced talks to refinance about $150 million of operating debt
A New York City investment fund is poised to provide a financial boost to Cipriani, nearing a deal that would refinance loans for the Italian hospitality company’s U.S. operations while helping fund its future expansion.
King Street Capital Management is in advanced talks to refinance about $150 million of operating debt held by Cipriani’s U.S. subsidiary, according to people familiar with the matter.
That funding would retire loans dating back to 2018 from Ares Capital Corp. , a business-development company that lends to midsize businesses. King Street would also extend additional funding that would help the company grow its brand in the U.S., these people said.
Cipriani, which manages 11 Manhattan restaurants, lounges, clubs and event spaces, has long been associated with celebrities and glitzy nights out. New York City Mayor Eric Adams celebrated his election victory at Casa Cipriani, a luxury hotel and private members’ club on the downtown Manhattan waterfront that opened last September.
Cipriani’s New York restaurants and event spaces suffered during the pandemic, when public-health restrictions prevented restaurateurs from offering indoor dining for long stretches. It was also deluged with cancellations during a surge in Covid-19 cases caused by the Omicron variant, undermining its lucrative holiday-party and other big-event business.
Now, the Prosecco corks are popping again. Cipriani’s business has been recovering over the past several months as the aftereffects of the pandemic recede. The company recently opened the Bellini restaurant, the centerpiece of a soon-to-open Harry’s Table food market in Manhattan, named after the fizzy cocktail created in Venice by founder Giuseppe Cipriani Sr.
At the same time, Cipriani is working to restructure $53 million in mortgage debt backed by two of its properties on 42nd Street and Wall Street, according to people familiar with the matter. The company has been in default since May 2020 on the loan, which is packaged into bonds and was transferred that year to a special servicer, according to real-estate data firm Trepp.
Parent company Cipriani SA, meanwhile, has been expanding throughout the pandemic and now has restaurants, clubs and hotels in more than a dozen cities. The company has plans for another 20 openings world-wide in the next three years, including another Casa Cipriani in Milan in August, which will include a restaurant, lounge spa and hotel and have reciprocity membership with its New York location.
The far-flung hospitality company started with Harry’s Bar in Venice in the 1930s, where Mr. Cipriani served celebrities like Orson Welles and Ernest Hemingway.
In April, the founder’s great-grandson and the company’s current chief executive, also named Giuseppe Cipriani, visited Miami to celebrate the launch of sales for Cipriani Residences Miami.
“This year we’re opening 16 new projects,” said Mr. Cipriani, between sips of a Negroni. “During the pandemic, instead of stopping, I traveled all over the world and we signed onto new projects. We’re very excited.”
From new headsets to a VR bar — fantasy meets reality
Specialist venues offer fully immersive experiences, but for home play the technology still has growing pains ahead
From out on the street, Otherworld looks like the headquarters of a futuristic cult. Nestled under a railway arch in Haggerston, east London, its unmarked entrance gives on to a neon-lit corridor flanked by circular white pods that resemble vertical sensory deprivation tanks. In fact, their function is the polar opposite — at this virtual reality bar, these sci-fi cabins are a gateway to total sensory overload, a high-spec showcase for the potential of VR gaming.
An employee swaddled in layers of cushioned white fabric assembles my friends and me around a glowing table to introduce the games we can sample during our one-hour slot. We could explore Google Earth in VR, paint in 3D with Tilt Brush or shoot each other with laser guns while cackling maniacally. We opt for the latter. After a somewhat convoluted introduction to the system, during which a non-gamer in our group glances at me nervously, we go into our separate pods and don controllers, headphones and headsets. Our physical surroundings are tightly shut out.
The next hour is a genuine hoot. Each game took a few minutes to learn, but before long we were deeply immersed in competitive dance-off Synth Riders, acrobatic sci-fi shooter Hyper Dash and zombie survival game Arizona Sunshine. Though physically separated, we were united as avatars in virtual space and could communicate through our headphones.
The experience of VR gaming benefits greatly from this kind of dedicated space. While Otherworld’s “4D effects” that simulate wind in your hair and sunshine on your face are gimmicky, it offers powerful hardware and a streamlined system for organising multiplayer games. Crucially, the simple fact of having space to wave your arms around (in-game, valiantly beating back zombies; in real life, flailing desperately) made a vital difference to how comfortable you feel being isolated from your surroundings. When I inevitably slammed my real body into the wall during a high-octane shootout, I found it mercifully padded.
I was surprised how much my group, of mixed gaming experience, enjoyed the evening, because after a couple of years’ testing VR games at home, I’ve yet to be convinced. While companies such as Meta, HTC and Snap invest heavily in augmented and virtual reality, arguing that increased immersion in digital space will be a key component of the metaverse, these technologies always seem on the cusp of hitting the mainstream but never quite arrive.
The launch of Meta’s Quest 2 headset in 2020 did mark a significant step forward. Simpler to use and far cheaper than competitors, this model processed the game software in the headset, rather than on a computer or console, meaning it was unable to run sophisticated games — most look as if they’re two decades old. Still, the trade-off of quality for accessibility and affordability appears to be working: the Quest 2 is now the headset to beat, representing 78 per cent of all VR hardware sales in 2021. Yet even now, VR players still only account for 2 per cent of PC gamers on Steam. Why does uptake remain slow?
It’s not that there aren’t any good VR games available; however, there aren’t many of them. You can dance along to Beat Saber or while away a few hours with ingenious puzzle-shooter Superhot. Most other offerings are basic, either because developers are stuck building for the feeble Quest 2 or because they don’t see the profit potential in ambitious development for the limited VR audience. There is just one VR masterpiece: Half-Life: Alyx, a continuation of Valve’s beloved shooter series which boasts stunning visuals, a robust narrative and dozens of small, thoughtful details that exploit the uniquely immersive potential of VR.
Even with a great game to play, I find myself reluctant to get out my headset at home. They still feel bulky, can cause motion sickness, and I find it unnerving to be isolated from the physical surroundings of my small room, especially since my cat has a single-minded desire to trip me up whenever I play. The attempts to show the room around you using headset-mounted cameras still feel technologically primitive. While VR hardware is rapidly developing, this pace of evolution makes it hard to reason that now is the right moment to jump aboard — a far better model could be just around the corner.
VR games still have a niche community of devoted supporters who believe in the technology’s future, as do many big companies: Sony has announced its new PSVR2 headset alongside a new VR Horizon game, Meta is teasing a new headset named Project Cambria, and even Apple has shown a demo of new VR hardware to investors. For home play, though, VR still has some growing pains ahead. Spaces such as Otherworld show the tech’s full potential — so, paradoxically, to experience the full flavour of the virtual world right now you might need to leave the house.
There will be blood
Deutsche Bank predicts that the US corporate default rate will spike to 10 per cent
When he is not regaling us with daily tales of shrubbery thefts, a medley of injuries, golf and some markets, Jim Reid writes Deutsche Bank’s annual Default Study. The 24th one just landed in FT Alphaville’s inbox, and, as ever, it makes for interesting reading.
First of all, it is remarkable just how tranquil a period it has been for corporate debt.
Last year saw one of the lowest junk bond default counts in a decade, and despite the recent market jitters, only 31 companies have defaulted globally this year, the lowest run rate since 2014 according to S&P Global. Even the rolling default rate of uber-junky triple-C rated US companies is the lowest it’s been for nearly four decades, according to Deutsche Bank.
The reality is that aside from a few notably awful spells in the immediate aftermath of the Covid-19 outbreak and the 2008 financial crisis, it’s been a pretty great two decades for corporate debt, with defaults trending lower and lower.
But Reid now sees a regime change lurking.
For most of this study’s history we’ve been convinced the ultra-low default world would hold for as far as the eye can see. However, this year we speculate that things might become more difficult for corporates in the years ahead.Our view has long been that inflation would rise this decade for structural reasons. The pandemic and the aftermath has accelerated and exaggerated this. We’ve previously been relaxed about higher inflation vis-à-vis defaults as we’ve thought the authorities would still have to heavily rely on financial repression to ensure the mammoth global debt pile could be smoothly financed in such a world.However, we now think that such a scenario might be more challenging for funding than we’ve believed in years gone by. Although financial repression will likely stay to some degree, policymakers may find it more difficult to pull all the easy policy levers as they’ve done in the last few decades.As such, we think there’ll be a tug of war between real yields and term premium naturally trending higher (bad for defaults) versus a desire (or need) for the authorities to intervene to prevent the debt super cycle from being exposed (good for defaults). The latter support may be slower to materialise, less aggressive, and more targeted than we’ve been used to if we move to a higher inflation world.
The “good” news is that Reid doesn’t think creditpocalypse is already upon us, as some have fretted. DB forecasts that the overall US junk bond default rate will climb to 5 per cent by the end of 2023 — the year it expects a recession to start — before peaking at 10.3 per cent in 2024.
The default rate for top-tier junk bonds (rated double-Bs) will only peak at 2 per cent, but Deutsche Bank thinks almost half of all triple-C bonds will end up in default.
Defaults will then moderate, but more slowly than has been the norm over the past two decades, and remain elevated at around 4-5 per cent by the end of 2025, DB predicts.
Europe will probably experience a notably less acute default cycle, with the default rate there climbing to 3.8 per cent by the end of 2023, peak at a more sedate 6.6 per cent in 2024 and then drift back to 2-4 per cent.
Defaults in emerging markets, meanwhile, are already on the rise. “Many issuers in the region have been able to pass through rising costs to customers — at least for now — though financing conditions are also tightening,” according to a report from S&P Global Ratings.
There are many reasons why Reid thinks defaults are likely to be structurally higher in the coming era, such as corporate profit margins becoming compressed.
But his central argument is that business cycles will become shorter than more volatile they have been in recent decades, as faster and more entrenched inflation limits how aggressively central banks can react to downturns.
I’ve been on the record as saying that with the debt mountain as it is, the authorities had to almost permanently use financial repression to keep spot real yields negative for the rest of my career. If they turned positive for any length of time, I felt the global debt mountain would be at risk of seeing hard defaults and systemic attacks.
I must admit now inflation is raging, I’m more nervous that there could be periods where the authorities are more powerless when it comes to controlling yields than they have been for the last couple of decades.
. . . If inflation proves stickier over the next decade, then policymakers will have less flexibility to rapidly and aggressively respond to wobbles, crises and recessions. As such, the central bank put may be more difficult to rely on. Business cycles may roll over more frequently than they have over the last few decades, which will likely add to the structural default rate as investors can no longer rely on the authorities in the same way as they have done over the last few decades.
California Lawmakers Want To Buy Up Water Rights And Cut Farming To Stave Off Drought
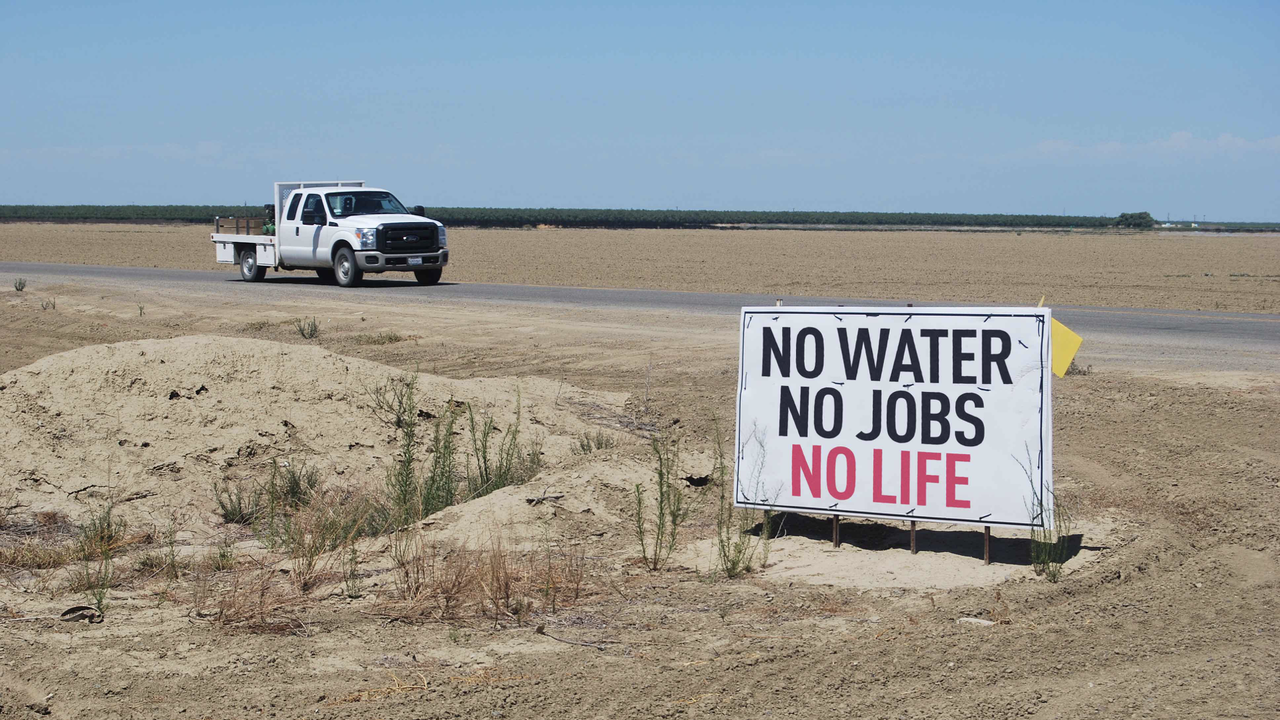
In places like California, water is a hot commodity these days. With a drought in play everyone is looking for someone else to blame, various cities are ordering cuts to daily use for families and individuals, and the primary target for now is California farmers and their legally protected water rights. It is these same rights that legislators now want to "buy" in order to shut down or greatly decrease agricultural production.
California, like most of the world, has a long history of intermittent droughts. Such droughts are simply a fact of life and there is nothing abnormal or extreme about today's conditions when taking past weather events into account. If you ask the mainstream media, though, they will tell you this is the "worst drought in 1200 years" and climate change is the cause.
This is, of course, simply not true. The California droughts in 1976-1977 and 1987-1992 were just as bad if not worse overall than the conditions of today. That's not to say that the current situation is stable, far from it, but the Chicken Little panic on display in the media is driven far more by agenda than by reality. It has become a standard tactic these days to connect every single inconvenient weather scenario to "global warming" despite the fact that there is no evidence to support the claim. There has been an endless array of droughts in CA long before man-made carbon existed.
Climate cultism has perhaps obscured the much bigger problem of water resources in one of the biggest produce growing states in the US, all in the middle of an inflationary crisis that is heading towards mass food shortages according to every single international economic foundation in the world and the Biden Administration. Of course, these foundations helped create the inflationary problems we are facing, and diverting public attention over to weather events and so-called climate change is rather advantageous for them.
In the midst of this circus rages a longstanding battle between California farmers with "senior water rights" and the state government. The majority of California farmland rests in the Central Valley with access to the Sacramento river and other tributaries, and water rights legally protect those farms and their access to these resources. State legislators, environmentalists and people who don't know any better argue that these farms use too much water and should be restricted while the state is under drought conditions.
Some of the more exaggerated stats suggest farms use up to 80% of the state water supply, but more grounded estimates place their usage closer to 40%. Over 50% of California water is already protected and reserved for environmental purposes. Already, hundreds of thousands of acres of farmland are idle and unproductive due to federal cutbacks.
California grows around 30% of America's vegetables and 60% of US fruits and nuts, so it's not surprising that these farms need large amounts of water to operate. This is also the only major industry within the state (beyond shipping ports) that produces necessary commodities for the nation. The tech industry and social media, tourism and Hollywood are not necessary when it comes to an inflationary crisis and are currently shriveling on the economic vine. What matters are commodities that keep people alive and produced in large quantities in order to keep prices down.
The hostility towards CA farmers underscores a misunderstanding of the importance of the industry and in some ways distracts from the mismanagement of ground water resources within major cities. Los Angeles is a notorious water hogging mess of a town, siphoning H2O from the Sacramento River, the Sierras and the Colorado River, and not producing anywhere near enough locally through wells and aquifers. According to the Sierra Club, LA snatches 85% of its water from outside sources.
Essentially, the city should not exist in its current form if logistics are taken into account. And, let's be honest, California is run out of LA and San Fransisco, not Sacramento. The rest of the state is treated as secondary or unimportant by these two population centers.
This has triggered a bit of animosity from many in rural areas and other western states towards California. LA and its inability to provide for itself may have helped inspire a recent agreement reducing water usage from the Colorado River in December of last year. These cuts affect LA the most and this is likely why the city and the state seem to be panicking even more than usual over supplies.
Water management and increasing local sources usually falls at the bottom of the list of solutions among state legislators. It may be that farmers in the state could make some cuts; we have yet to see an analysis on how this would negatively affect crops. But why should they? At bottom, CA farmers are far more important because they actually produce something useful at a time when the country desperately needs to meet food demands and prevent further price inflation. What does LA and San Fransisco produce, other than complaints?
Finally, we have to ask, what if legislators try to buy senior water rights but farmers refuse to sell? What happens then?