FT : Ms Marvel, Disney Plus review — the franchise unveils its first Muslim supe

Ms Marvel, Disney Plus review — the franchise unveils its first Muslim superhero
Iman Vellani charms as teenager Kamala Khan in an adventure story as much about heritage as battling evil

For those who struggle to tell a “cinematic universe” from a “multiverse”, the news of another addition to the Marvel stable might not quicken the pulse. But the release of Ms Marvel, a new six-part series on Disney Plus, is a small yet significant piece of pop culture history. For the first time on screen, the franchise presents a superhero story fronted by a Muslim character. 

She is Kamala Khan, a seemingly typical, gawky high-schooler, played by newcomer Iman Vellani in a charming debut performance. Still only 16, Kamala finds herself under pressure from all sides to figure out what she wants to be in life. Unfortunately, her dream of becoming an Avenger is hardly viable; she’s clumsy, scared of the dark, and lacks supernatural gifts. Yet there is another, more systemic issue standing in her way. “It’s not the brown girls from Jersey City who save the world,” she laments. That won’t be true for much longer, you suspect.

For now, the best she can do is try to win a costume competition at an Avenger fan convention. Rooting around in a box of old ancestral trinkets for something to embellish her outfit with, Kamala stumbles upon an ornate bracelet that once belonged to her great-grandmother, a woman fabled to have had mystic abilities. Sure enough, as soon as Kamala puts it on, she is transformed from a mere lookalike into the real deal, equipped with the (as yet unharnessed) ability to crystallise light and jump dimensions.

Ms Marvel is as much about heritage as it is about adventure. That Kamala is a practising Muslim of Pakistani origin isn’t treated as incidental. Much of the first two episodes is devoted to giving a sense of her world, showing a service at her mosque and the streets of Little Pakistan. At an Eid celebration, Kamala gives her schoolmate a run-through of her community’s cliques, from the “pious bros” to the “illumin-aunties”. 

Numerous battles no doubt await her alter ego, but it’s the conflict at home that promises to deliver the richest narrative thread. Like the recent Pixar film Turning Red (and everything from Bend It Like Beckham to The Big Sick), the series humorously and sensitively reflects on the cultural gulf between parents rooted to tradition and children caught between their sense of identity and the desire to assimilate. 

“Focus on you, your family, your story,” tigerish mum (Zenobia Shroff) tells Kamala after she catches her sneaking back from the convention. Early indications suggest that Ms Marvel will be doing exactly that.
>>> US Gapping down

Gapping down
In reaction to earnings/guidance
:

  • SMG -13.1% (lowered guidance), OLLI -7.2%, SMAR -6.4%, CS -5.6% (Trading update), LOVE -3.2%, OI -2.7%, GWRE -2.1%, CASY -2.1% (also increases dividend)

Other news:

  • RIGL -60.2% (Top-line Results from FORWARD Phase 3 Clinical Trial of Fostamatinib)
  • CDRE -4.6% (stock offering)
  • TER -2.8% (names Greg Smith as president)
  • WTFC -2.7% (prices offering of 3.0 mln shares of common stock at $86.00 per share)
  • EURN -2.7% (INSW completes transaction to sell 50% stake in FSO vessels to EURN)
  • TALS -2.1% (presents additional Phase 2 data and analyses)
  • CCSI -2% (files for 2 mln share offering by selling shareholders)

Analyst comments:

  • CGC -4.2% (downgraded to Underperform from Market Perform at BMO Capital Markets)
  • MO -2.4% (downgraded to Underweight from Equal-Weight at Morgan Stanley)
  • BROS -2.2% (downgraded to Neutral from Overweight at JP Morgan)
  • TGT -1.1% (downgraded to Neutral from Buy at BofA Securities)

>>> US Gapping up

Gapping up
In reaction to earnings/guidance
:

  • CURV +11%, THO +7.2%, KC +5.7%, CPB +4.1%

Other news:

  • DBVT +23.5% (positive topline results from Phase 3 EPITOPE Trial)
  • ALDX +19.2% (achieves primary endpoint in phase 3 tranquility-2 trial)
  • MNOV +11.9% (top-line results from phase 2 clinical trial of MN-166)
  • NVAX +10.1% (FDA advisory committee recommends EUA for its COVID-19 vaccine)
  • PASG +6.9% (cleared its Investigational New Drug application for PBML04)
  • DTIL +5.3% (announces its latest program updates across its allogeneic CAR T pipeline)
  • DOCU +4.6% (expands partnership with MSFT to accelerate anywhere work)
  • WDC +4.1% (provides update on review of strategic alternatives)
  • IMVT +3.3% (Achieves Alignment with FDA on Plans for Phase 3 Clinical Trials of Batoclimab)
  • OCFT +2.3% (upsizes its share repurchase program)
  • GENI +2% (stock offering)
  • EIGR +1.3% (enters into $75 mln term loan agreement with Innovatus)
  • LMDX +1% (achieved CE Mark for two new Fast Lab Solutions molecular tests)

Analyst comments:

  • WFRD +3.9% (initiated with a Buy at Goldman)

WSJ : Moderna’s Covid-19 Vaccine Targeting Omicron Produces Stronger Immune Resp

Moderna’s Covid-19 Vaccine Targeting Omicron Produces Stronger Immune Response
Experimental vaccine, designed to fight Omicron and original virus, found to be more effective against new variant than current shot

Moderna Inc. said a modified Covid-19 booster shot provided a stronger immune response than the company’s original vaccine against the Omicron variant in a new study.

The Cambridge, Mass., company said Wednesday it will submit preliminary data from the study to U.S. health regulators in the coming weeks with the hope of making the modified booster shot available in late summer.

Researchers found that the levels of neutralizing antibodies against Omicron among people getting the modified shot were 1.75 times higher than in people who received a booster shot of the original vaccine, Moderna said.

“I think the data clearly show this is a superior booster,” Moderna President Stephen Hoge said in an interview.

The study didn’t measure the efficacy of the modified booster shot—whether it actually reduces the risk of Covid-19 disease caused by Omicron. The company disclosed the results in a press release. The data haven’t been published in a peer-reviewed medical journal.

Moderna’s modified, “bivalent” booster shot was designed to target in a single shot both the Omicron variant and the original coronavirus strain. The company’s original vaccine, Spikevax, was designed to target the original coronavirus, both as a two-dose primary series and as a booster shot.

Yet the Omicron variant, which began spreading rapidly late last year and is now the dominant strain, has been able to evade some of the protection conferred by the original vaccine because of mutations in a surface protein targeted by the shot.

In response, Moderna and other vaccine makers including Pfizer Inc. have developed new shots that may better target Omicron and other variants.

U.S. health officials are considering whether modified booster shots targeting variants should be used for a fall vaccination drive. Data from studies like Moderna’s will be crucial to the officials’ decision making.

Pfizer and its partner BioNTech SE are also expected to soon release study results on their Omicron-targeting shot.

Moderna said its bivalent vaccine could be used for a fall booster campaign that would potentially give people protection through the winter.

“It’s time to update the vaccines to reflect the virus as it is today,” Mr. Hoge said.

Moderna began testing the bivalent booster shot, code-named mRNA-1273.214, in an ongoing study in March. Some 437 people, who had already received a two-dose primary series and the original booster shot, were given the bivalent shot. Researchers measured their immune-system antibody responses against the Omicron variant one month later.

In addition to finding greater neutralizing antibody levels against Omicron, the study also found that the bivalent shot boosted antibodies against the original strain to higher levels than the original vaccine.

Moderna expects to report in the summer how the antibody levels are holding up in people three months after getting the bivalent booster.

Moderna said the bivalent vaccine had a similar set of side effects as the original booster shot.

The company has already started manufacturing doses of the modified booster and should be able to meet demand if it becomes available for a booster campaign in the fall, Mr. Hoge said.

Moderna also has studied a booster shot that targets only the Omicron variant. But the company concluded that a bivalent shot could offer broader protection against Omicron and other potential circulating variants.

>>> US Early premarket gappers

Early premarket gappers

  • Gapping up:
    • DBVT +17.6%, NVAX +17.4%, CURV +7.4%, DOCU +4.6%, WDC +3.7%, LMDX +2.6%, OCFT +2.3%, AWK +2%, GENI +1.4%, EIGR +1.3%, CPLP +0.9%, VIRT +0.9%, VRNT +0.6%
  • Gapping down:
    • SMAR -7%, CCSI -6.2%, CS -5.9%, CDRE -4.6%, WTFC -4%, TER -2.8%, OI -2.7%, EURN -2.4%, GWRE -2.1%, CF -1.3%, GT -0.7%, PNTG -0.6%, CASY -0.6%, SNY -0.5%

FT : Lira slide accelerates as Erdoğan vows to continue slashing rates

Lira slide accelerates as Erdoğan vows to continue slashing rates
Turkish currency has shed 22% this year and analysts warn fall is ‘likely to continue’ without rate rises

Turkey’s lira continued its slide towards a record low after President Recep Tayyip Erdoğan vowed once again to cut interest rates despite spiralling inflation.

The currency fell to 17 against the dollar on Wednesday, extending a steep slide this week that has come after Erdoğan, a life-long opponent of high borrowing costs, launched an impassioned tirade against them.

The Turkish president said earlier this week that the country had “wasted years” with the misguided view that prices should be controlled by using higher borrowing costs to suppress consumption. Such policies, he said, only benefited “those living a charmed existence and filling their pockets with [the proceeds of] high interest”, including foreign investors.

Erdoğan promised to cut interest rates further even though inflation reached a 23-year high of 73.5 per cent last month, saying: “This government will not raise interest rates. On the contrary, we will continue to cut rates.”


The lira fell about 2 per cent on Wednesday, bringing its losses for the year to 22 per cent after falling almost 45 per cent in 2021. A year ago, the currency traded at just over TL8 against the dollar.

The currency’s steady decline in recent weeks has threatened to test the record lows hit in December, when the country was thrust into a currency crisis after Erdoğan ordered the central bank to announce a series of interest rates cuts despite rising inflation. Besides a fleeting decline past TL18 during last year’s rout, the currency has never consistently traded at such weak levels.

Turkey has one of the world’s lowest interest rates in real terms, standing at minus 59.5 per cent once inflation is taken into account. Negative real interest rates have deterred Turkish citizens from keeping their savings in lira, and have tarnished the allure for foreign investors of holding Turkish assets compared with emerging market rivals.

Erdoğan and senior Turkish officials justified last year’s aggressive rate cuts by arguing that they were pursuing a “new economic model”. They argued that they would be able to tame inflation by harnessing the weak currency to boost exports and investment and eliminate the country’s longstanding trade deficit.

Even before Vladimir Putin’s invasion of Ukraine, critics warned that the plan was a risky economic experiment that was in danger of causing a collapse in the value of the Turkish lira and runaway inflation.

The conflict has compounded the challenges facing Turkey, which imports most of its energy, by pushing up global oil and gas prices and causing a widening current account deficit that has created extra demand for foreign currency.


MUFG analysts Ehsan Khoman and Lee Hardman said in a note to clients this week that it was “unambiguously unsustainable” for Turkey to maintain this approach, warning that the pressure on the currency was “likely to continue in the absence of a policy U-turn”.

The soaring inflation rate has also come with political ramifications for Erdoğan. While Turkey has enjoyed strong growth thanks to loose monetary policy, the escalating cost of living and the pressure on the lira have eroded public support for the Turkish president ahead of elections that must take place before June 2023.

Erdoğan on Monday acknowledged that there was a “cost of living problem” in his country, but insisted that his economic model would soon pay dividends. He said: “We have cast aside the economic prescriptions imposed by imperialist financial institutions that make the rich richer and make the poor poorer by increasing the interest rate.”

>>> Europe : Brokers Upgrades & Downgrades - 8th of June 2022 V2(+)

>>> Up
* AIB Group Raised to Outperform at KBW; PT 3.30 euros
* Assa Abloy Raised to Hold at HSBC; PT 225 kronor
* Atlas Copco Raised to Buy at HSBC; PT 130 kronor
* BT Raised to Hold at HSBC; PT 185 pence
* Hexpol Raised to Buy at SEB Equities; PT 107 kronor
* Iren Raised to Buy at Intesa Sanpaolo; PT 3.20 euros (+)
* Johnson Matthey Raised to Buy at Panmure Gordon; PT 3,888 pence
* MFE Raised to Overweight at JPMorgan; PT 1.20 euros
* MOL Raised to Buy at Erste Group; PT 3,520 forint
* Monnalisa Raised to Accumulate at Banca Akros (+)
* Safran Raised to Outperform at Exane; PT 134 euros
* Sanoma Raised to Buy at Nordea; PT 15.90 euros
* Standard Chartered PT Raised to 991 pence at Jefferies
* Yara Raised to Overweight at Morgan Stanley; PT 580 kroner

>>> Down
* Altria Cut to Underweight at Morgan Stanley; PT $50
* Banco BPM Cut to Add at Intesa Sanpaolo; PT 3.60 euros (+)
* OCI Cut to Equal-Weight at Morgan Stanley; PT 36 euros
* National Express Cut to Hold at Peel Hunt; PT 270 pence (+)
* Schindler Cut to Reduce at HSBC; PT 173 Swiss francs

>>> Initiation
* Investec Rated New Overweight at ABSA Securities
* Kingspan Reinstated Buy at Goldman; PT 105 euros
* Pensionbee Group Rated New Buy at Jefferies; PT 220 pence
* Rockwool Reinstated Neutral at Goldman; PT 2,257 kroner
* Telefonica Deutschland Rated New Sell at Berenberg

>>> Call
* AIB Upgraded at KBW on Strong Deposit Outlook for Irish Banks (+)
* Altria Gets Only Negative Rating as MS Cites Competitive Risks
* Aryzta’s Expected Balance Sheet Deleverage a Positive: Vontobel (+)
* Credit Suisse Warning No Surprise, Yet Weaker Than Expected: JPM (+)
* ‘Hated’ UK Retail Stocks Could See Short Squeeze, Liberum Says (+)
* Inditex 1Q Sales Beat Helped by Strong US Performance, RBC Says (+)
* National Express Cut to Hold at Peel Hunt on School Bus Woes (+)
* Pensionbee New Buy as Jefferies Sees High Growth Continuing
* Pernod Ricard’s Mid-Term Targets Should be Taken Well: Jefferies (+)
* Safran Raised to Outperform at Exane for First Time in 9 Years
* Telefonica Deutschland New Sell at Berenberg on Dividend Risks
* Wizz Air Results In Line, Summer Commentary ‘Bullish:’ Bernstein (+)
* Yara Now Top Fertilizer Pick at Morgan Stanley, OCI Downgraded

(ZH) Hedge Funds Had A Horrible May... And Then They Missed The Month-End Ramp

Hedge Funds Had A Horrible May... And Then They Missed The Month-End Ramp

May was a volatile month for equity markets, starting off ugly and closing strong, but while most equity indices were able to finish slightly green for the month given the large rally in the final full week of May, the same cannot be said for hedge funds.
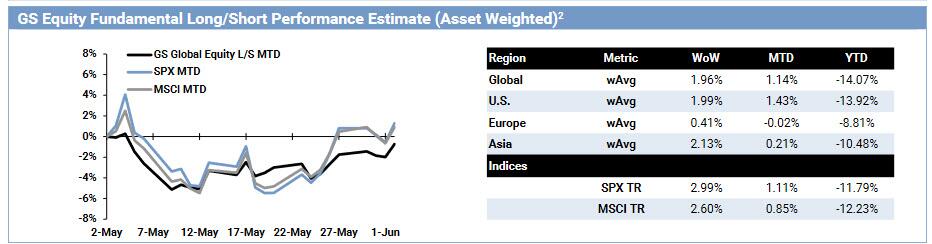
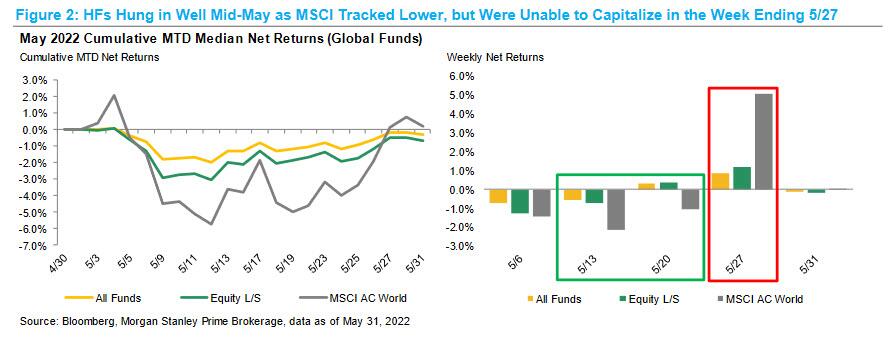
According to the latest weekly report from Morgan Stanley Prime Brokerage (available to pro subscribers), Hedge Funds had felt (and were hammered by) a large portion of the market downside in the first part of May but then hung in well mid-month given most strategies were running lighter net levels at the time. That was as good as it gets however, and HFs then struggled to make back their losses in the final full week of May, capturing only a portion of the rally. This left the average global fund down ~1% for the month.
Digging deeper we find that while the performance of equity markets was quite volatile throughout the month, we did not see nearly the same levels of volatility in HF returns, perhaps due to most strategies running at much lighter net leverage levels (more on HF leverage and positioning below).
According to MS, most of the performance ‘pain’ was felt in the week ending May 6, with HFs posting losses in-line with the MSCI – this also coincided with L/S funds beginning to de-gross. HFs then performed in line with the market for two weeks (weeks ending May 13 & May 20) as HF de-grossing took a pause after May 9, and then HFs returned to adding to gross exposure while keeping nets light.
However, the moderate levels of net leverage then caused HFs to miss out on a large portion of the rally in the week ending May 27 – this lack of upside capture amidst this rally is what ultimately led HFs to lag the index for the month
Goldman's Prime Desk makes a similar conclusion in its May performance post-mortem.
Another notable observation: while performance across all strategies tracked indices relatively well (except for the late month ramp), there is a lot of dispersion both across strategies and intra-strategy through May – the spread between the 90th %-tile and 10th %-tile performers is currently the 2nd widest Morgan Stanley Prime has seen since 2010, trailing only 2020 by a small margin. Among the top performers this year based on investor letters received through April are Systematic Macro (+14.3%), Disc. Macro (+8.3%) and Energy-focused (+4.2%), and while there has been only a small sample of funds who’ve reported for May, these strategies all outperformed the avg. global fund last month. The weaker performers this year have been traditional L/S strategies (-8.4% through May based on our prop estimate), particularly TMT-and HC-focused funds (both down ~14% through Apr based on letters).
Drilling down into L/S fund performance, global Equity L/S total alpha was negative this past month, all of which was driven by the long side given shorts generated positive alpha of ~1%. Longs held globally by L/S funds fell ~2.4% last month vs. the MSCI ending up +0.2%, representing a negative spread of -2.6%.
Even more embarrassing for the billionaires who make up the 2 and 20 crowd - like Gabe Plotkin - this was the 8th consecutive month where long alpha has been negative, the longest stretch we have seen since we began tracking the data in 2010.
Meanwhile, the spread of -2.6% represented the 6th time in the past 8 months where the spread was lower than -2%. To put this into perspective, for the period from the start of 2010 through the end of 3Q 2021, the spread between longs and the MSCI was worse than -2% only nine times.
Looking at global HF positioning and leverage, MS Prime finds two main themes:
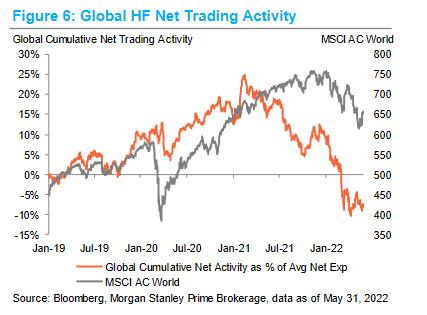
  • THEME #1: HFs Continue to Sell Global Equities, Led by US and China
HFs sold global equities for the 6th consecutive month, with the magnitude of the selling in May larger than what we saw in
April, but smaller than March’s flow.
The selling can be attributed to Equity L/S (long selling) and Stat Arb/Quant (short adds)
funds, and by region, split between N. America, Asia ex-Japan, and LatAm – HFs were, however, net buyers of both Europe
and Japan.
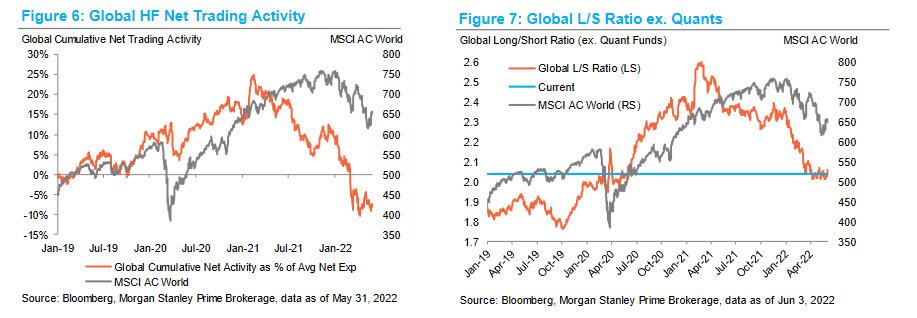
The Global L/S ratio (ex. Quants) ended just above 2.0x at the end of May, right around where it ended in Apr. At its low, the ratio fell all the way to 2.01x but has yet to break below the 2.0x barrier – the last time it did so was in April of 2020.
  • THEME #2: L/S Funds Trim Gross Exp; Gross Lev Now Light Across Most Major Strategies
More important even than dismal performance, May ended up being one the largest month in terms of active gross reductions Morgan Stanley Prime has seen YTD by L/S funds, with most of the gross exposure trimmed specifically within the US and China. While this month was far from the most extreme seen in recent years (Jan ’21 was ~4x larger), it is still a notable break in trend from the gross adds that occurred in April. US L/S gross leverage reached a ~2-year low of ~175% intra-month before recovering to 182% by month-end – in addition to US L/S gross lev, gross across many of the major strategies also hit a 12M low in May and remains in the <10th %-tile both over the last 12M and the last 5 years as of last week.
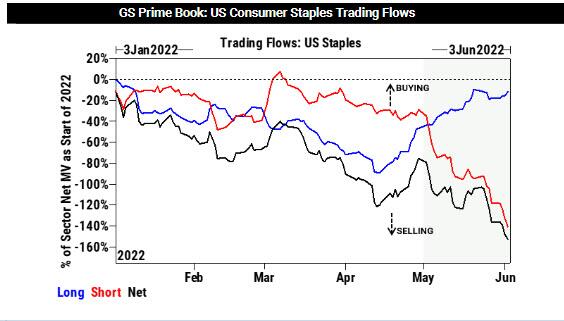
Goldman's Prime Desk makes another interesting observation, which is apropos in light of today's 2nd consecutive guidance cut by Target. According to GS, following challenging earnings results from various companies, Consumer Staples is one of the most net sold sectors in the US, driven entirely by short sales, with short sales outpacing long buys by nearly 5:1. Selling was consistent over the past week as the sector experienced net selling (and short selling) every day over the past week. All industry groups were net sold for the week, with the exception of Food & Staples Retailing, which was marginally net bought. Food Products and Beverages accounted for a large proportion of the net selling flow for the overall sector. Amid this shorting frenzy it is not surprising that relatively within the US, Consumer Staples was one of the worst performing sectors on a five-day basis.
There is much more in the full Morgan Stanley and Goldman Sachs notes, including much more granular detail and in depth analysis of nascent hedge fund themes, with both available to professional subs in the usual place.
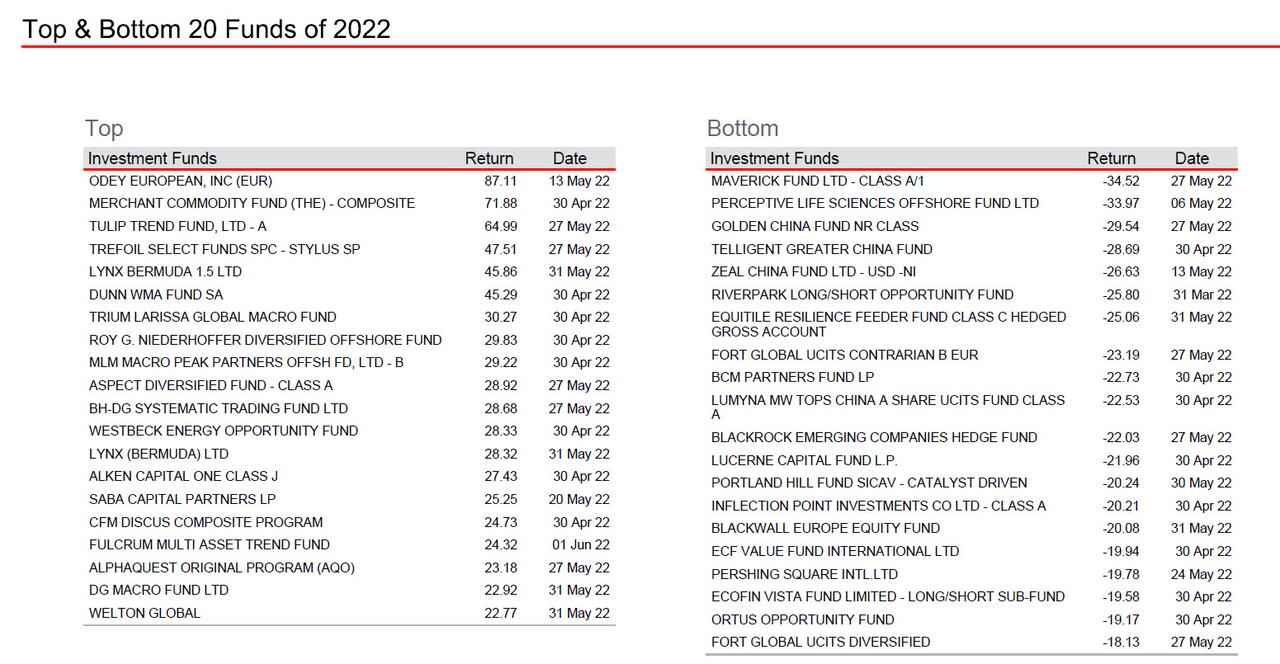
One final observation: courtesy of the latest HSBC hedge fund weekly report (also available to pro subs) here are the best and worst performing hedge funds of 2022:

WWD : Digimarc Cloud-based Technology Makes Authenticity of Products More Secure

Digimarc Cloud-based Technology Makes Authenticity of Products More Secure
The company also released a consumer behavior report showing differences between Generation Z and Baby Boomers.

Digimarc combines product triggers with cloud technology to thwart counterfeiting. WHO IS DANNY - STOCK.ADOBE.COM

Digimarc Corp., a next-generation digital identification and detection-based solution provider, is rolling out a new solution to help brands verify the authenticity of products.

Separately, Digimarc has released insights about consumer behavior in a report that looks at differences in shopping preferences between generational cohorts, including the importance of product authenticity.

Regarding the launch of the Digimarc Brand Integrity digital solution, the company said it works by assigning each product with a serialized digital identity “that can be tracked in the cloud and accessed through a variety of on-package digital triggers, including the industry’s most secure and covert: the Digimarc digital watermark. Adding that this combination of digitized products and cloud-based data “makes the process of authenticating items more accurate and scalable than traditional physical authentication measures,” the company said.

Related Galleries
Queen Elizabeth II and Prince Phillip visit Arlington National Cemetery on July 7, 1976.
PEOPLE
Queen Elizabeth II’s Style Throughout the Years
Saucy Santana
PARTIES
Inside the Coach x The Monster Party
Digimarc also noted that the support of dual-factor authentication, “such as scanning both QR codes and digital watermarks on a single package, provides a strong defense against bad actors accustomed to easily circumventing lesser brand protection measures.”

Ken Sickles, chief product officer at Digimarc, said as counterfeiters have become more sophisticated and supply chains more diffuse, “companies are recognizing that traditional brand protection approaches that are largely reactive and reliant on trained inspectors and specialized equipment are both ineffective and inefficient.”

“Digimarc has created a uniquely digital solution that leverages the ubiquity of smartphones and other digital devices to make product authentication much more streamlined and less prone to human error,” Sickles said, adding that while digitizing products with QR codes is a great starting point, “when coupled with a robust product cloud and covert digital watermarks, brands can gain even greater visibility into their products and offer their consumers the chance to do the same.”

Sickles said the company’s brand integrity solution helps brands “to protect their reputations by giving every product a digital presence connected to a cloud-based record of its journey and interactions proving products’ authenticity, uncovering counterfeits and their origin, and gaining insight into products’ supply chains so that brands can anticipate issues and act fast.”

In the consumer behavior report, Digimarc teamed up with Censuswide to survey shoppers on several topics. Some of the top takeaways include that 80 percent of Baby Boomers “care about whether products they buy are authentic, versus 53 percent of Gen Zers.”

“Boomers also care more about whether brands are reputable and take their environmental responsibilities seriously, with 63 percent of the group saying they are concerned about these factors, followed by 58 percent of Gen Zers, 56 percent of Gen Xers and 55 percent of Millennials,” Digimarc said in a statement.

Sickles said the recent consumer study “shows that Baby Boomers are, surprisingly, more concerned than the youngest shoppers are about buying genuine products from reputable brands that are committed to sustainability,.”

“However, consumers of all ages have significant concerns about how the products they buy are made, where they’re made and what’s in them,” he said. “To address these concerns of shoppers of all demographics, brands need to not only ensure their product and brand integrity, but clearly communicate their trustworthiness and authenticity to consumers.”

Digging deeper into the results showed that Baby Boomers are most concerned about counterfeit goods. “Whether buying new or secondhand, Boomers are most concerned about whether the items they buy are counterfeit (new: 64 percent; secondhand: 54 percent)” while Gen Zers are “the least concerned (new: 53 percent; secondhand: 50 percent).”

Authors of the report said a majority of all age groups are concerned with the ethics of buying something that may be counterfeit, but Baby Boomers are most concerned at 64 percent, followed by Gen Xers with 60 percent and Millennials at 56 percent. Generation Z came in at 52 percent.

Other findings include that with luxury goods, product quality is important to more than three-quarters of all age groups when shopping for luxury goods, “but Boomers and Gen Xers (both at 73 percent) care most about where the luxury goods they purchase were made.”

Additionally, Baby Boomers are much more concerned than Generation Z with what products are made of with — 80 percent of Baby Boomers polled said they are concerned with the ingredients or materials in the products they purchase, compared with 54 percent of Generation Z.