FT : Kellogg to split into three separate food businesses

Kellogg to split into three separate food businesses
Proposed spin-offs will distribute shares to investors in cereal and plant-based companies

US foods group Kellogg is to split into three public companies by spinning off its North American cereal and its plant-based food businesses, which together account for about a fifth of its sales.

The proposed spin-offs will distribute shares to Kellogg investors in the cereal company, which will generate about $2.4bn in net sales, and the plant-based group. Shares will given out pro-rata relative to investors’ stakes in the parent company.

The global food brand said on Tuesday that it expected the North American cereal branch to be split off first and was aiming to complete both transactions by the end of next year.

The plant-based group, which generates about $340mn in sales, will be anchored by the MorningStar Farms brand.

The remaining 80 per cent trunk of the Michigan-based food group, which generated about $11.4bn in 2021 net sales, focuses on snacking, international cereal and noodles, as well as frozen breakfast products in North America. Nearly 60 per cent of net sales are from global snacks, such as Pringles, Pop-Tarts and Cheez-It.

The global snacking business “is expected to be a higher-growth company than today’s Kellogg Company”, the group said in a statement on Tuesday.

North America will represent less than half of its net sales, with emerging markets bringing in around 30 per cent and developed international markets another 20 per cent.

“These businesses all have significant standalone potential,” said Steve Cahillane, Kellogg’s chief executive and chair.

WSJ : Mondelez to Acquire Clif Bar for $2.9 Billion

Mondelez to Acquire Clif Bar for $2.9 Billion
Deal adds Clif Bar, Luna and Clif Kid brands to global snack maker’s food business

Mondelez International Inc. said it would acquire Clif Bar & Co. for at least $2.9 billion, in a deal that adds the brands Clif Bar, Luna and Clif Kid to Mondelez’s food business.

The global food giant said Monday that it would continue to operate Clif Bar’s business out of the company’s headquarters in Emeryville, Calif., and would continue to manufacture products out of facilities in Indiana and Idaho.

Mondelez said it expects the deal, which it said could pay out more to the sellers over time, to close in the third quarter.

The snack maker and other food companies have said they would continue to raise prices amid escalating costs. Mondelez CEO Dirk Van de Put said this month that the company’s price increases haven’t curtailed purchases, which he said was surprising. But there would be more price increases to come over the next year, he said.

Clif bar was started in 1992 by Gary Erickson, who came up with the idea for the company’s eponymous snack while on a 175-mile bicycle ride near San Francisco two years earlier, according to the company’s website. Mr. Erickson, who remains on the company’s board, worked with his mother to develop what he thought was a tastier energy bar than the products available at the time. The company rebuffed a $120 million sale to Quaker Oats in 2000.

Mr. Erickson led the company as co-CEO alongside his wife, Kit Crawford, until Sally Grimes was named chief executive in May 2020. Mr. Erickson and Ms. Crawford have remained on Clif Bar’s board of directors since then, according to the company’s website.

Mondelez said in April that it would pay $1.3 billion to buy the Ricolino confectionery business from Grupo Bimbo.

>>> US Research Calls

Research Calls I

  • Upgrades:
    • ABM Industries (ABM) upgraded to Outperform from Neutral at Robert W. Baird; tgt $50
    • American Tower (AMT) upgraded to Overweight from Underweight at JP Morgan; tgt raised to $285
    • Aveanna (AVAH) downgraded to Equal-Weight from Overweight at Stephens; tgt lowered to $3.50
    • Centene (CNC) upgraded to Outperform from Neutral at Credit Suisse; tgt raised to $88
    • Charles Schwab (SCHW) upgraded to Buy from Neutral at UBS; tgt raised to $75
    • Chewy (CHWY) upgraded to Outperform from Neutral at Wedbush; tgt raised to $35
    • Church & Dwight (CHD) upgraded to Overweight from Equal Weight at Wells Fargo; tgt $95
    • CubeSmart (CUBE) upgraded to Buy from Neutral at BofA Securities
    • Exxon Mobil (XOM) upgraded to Outperform from Neutral at Credit Suisse; tgt raised to $125
    • FMC Corp (FMC) upgraded to Buy from Underperform at BofA Securities
    • LTC Properties (LTC) upgraded to Market Perform from Underperform at BMO Capital Markets; tgt raised to $40
    • Pearson Plc (PSO) upgraded to Buy from Hold at Deutsche Bank
    • Renasant (RNST) upgraded to Outperform from Market Perform at Hovde Group; tgt $34
    • Suncor Energy (SU) upgraded to Outperform from Sector Perform at RBC Capital Mkts
  • Downgrades:
    • Adobe (ADBE) downgraded to Equal-Weight from Overweight at Morgan Stanley; tgt lowered to $362
    • China Petroleum (Sinopec) (SNP) downgraded to Sell from Neutral at Goldman
    • Hyliion (HYLN) downgraded to Underweight from Neutral at JP Morgan
    • Int'l Paper (IP) downgraded to Neutral from Buy at Citigroup; tgt lowered to $46
    • Life Storage (LSI) downgraded to Neutral from Buy at BofA Securities; tgt lowered to $133
    • National Health (NHI) downgraded to Market Perform from Outperform at BMO Capital Markets; tgt $62
    • Pennant Group (PNTG) downgraded to Equal-Weight from Overweight at Stephens; tgt lowered to $17
    • Sunnova Energy (NOVA) downgraded to Neutral from Buy at Goldman; tgt lowered to $24
    • SunPower (SPWR) downgraded to Sell from Neutral at Goldman; tgt lowered to $13
    • UBS AG (UBS) downgraded to Neutral from Outperform at Exane BNP Paribas
    • Under Armour (UAA) downgraded to Market Perform from Outperform at Cowen; tgt lowered to $10
    • WestRock (WRK) downgraded to Neutral from Buy at Citigroup; tgt lowered to $45
  • Others:
    • Arvinas (ARVN) initiated with a Hold at Jefferies; tgt $42
    • Compass (COMP) initiated with a Buy at Compass Point; tgt $8
    • DoorDash (DASH) resumed with a Neutral at Goldman; tgt $67
    • FREYR Battery (FREY) initiated with a Neutral at Goldman; tgt $8
    • Inari (NARI) initiated with an Overweight at Piper Sandler; tgt $100
    • KE Holdings (BEKE) initiated with a Buy at Citigroup; tgt $22.50
    • Mainz Biomed B.V. (MYNZ) initiated with a Buy at H.C. Wainwright; tgt $25
    • Maxar Technologies (MAXR) initiated with an Overweight at Wells Fargo; tgt $39
    • Offerpad Solutions (OPAD) initiated with a Buy at Compass Point; tgt $5.50
    • Opendoor Technologies (OPEN) initiated with a Neutral at Compass Point; tgt $6
    • Palantir Technologies (PLTR) initiated with a Buy at BofA Securities; tgt $13
    • Redfin (RDFN) resumed with a Neutral at Compass Point; tgt $8.50
    • Rexford Industrial Realty (REXR) initiated with a Peer Perform at Wolfe Research; tgt $63
    • Rocket Lab USA (RKLB) initiated with an Equal Weight at Wells Fargo; tgt $5
    • Symbotic (SYM) initiated with an Outperform at Cowen; tgt $18
    • Veeva Systems (VEEV) resumed with a Buy at Guggenheim; tgt $252
    • Virgin Galactic (SPCE) initiated with an Underweight at Wells Fargo; tgt $4

>>> US Gapping down

Gapping down
In reaction to earnings/guidance
:

  • HIMX -2.1% (guidance)

Other news:

  • ACAD -32.1% (provides update from FDA Advisory Committee for NUPLAZID; concluded pimavanserin is ineffective for the treatment of hallucinations and delusions in the ADP population)
  • RADA -3% (RADA Electronic Industries & Leonardo DRS agree to all-stock merger combining top defense technology companies into leader in advanced sensing and force protection)
  • FXLV -1.1% (files for 18857319 share common stock offering by selling shareholders)

Analyst comments:

  • HYLN -3% (downgraded to Underweight from Neutral at JP Morgan)
  • SPWR -2.7% (downgraded to Sell from Neutral at Goldman)
  • IP -2.1% (downgraded to Neutral from Buy at Citigroup)
  • PNTG -1.3% (downgraded to Equal-Weight from Overweight at Stephens)
  • NOVA -0.8% (downgraded to Neutral from Buy at Goldman)
  • ADBE -0.6% (downgraded to Equal-Weight from Overweight at Morgan Stanley)

>>> US Gapping up

Gapping up
In reaction to earnings/guidance
:

  • ALV +8.1% (reaffirms outlook), LEN +3.9%

Other news:

  • CNVY +138% (To Be Taken Private By TPG for $10.50 per share in cash)
  • VALN +83.8% (Valneva SE and Pfizer (PFE) enter into an equity subscription agreement and update terms of collaboration agreement for VLA15)
  • SAVE +8.8% (JetBlue (JBLU) submits proposal with increased offer of $33.50 per share in cash) K +8.4% (plans to separate into three independent companies)
  • BNR +7.6% (announces $10 million share repurchase program)
  • PAYA +7.1% (considering sale according to Bloomberg)
  • EJFA +6.6% (shareholders approve proposed business combination with Pagaya Technologies; will trade on the Nasdaq under symbol "PGY")
  • NRZ +5.3% (to change its name and rebrand as Rithm Capital (RITM); now operates as an internally managed REIT)
  • SWN +5.2% (announces $1 billion share repurchase program)
  • ABMD +5% (entered into a new 10b5-1 plan to continue repurchases of the Company's common stock under the Program)
  • TRMR +4.7% (confirms that it is currently in discussions with Amobee alongside a number of ongoing strategic discussions with other third parties)
  • IREN +4.3% (re-iterated expected total online operating capacity of 3.7 EH/s by the end of Q3 2022)
  • EXAS +4.2% (entered a long-term supply agreement for Ultima's next-generation sequencing technologies)
  • OCGN +3.7% (Publication of Positive Results of COVID-19 Vaccine Trial for Children 2-18 in The Lancet Infectious Diseases)
  • FANG +3.1% (announces further enhancement to its capital return program and intention to increase base dividend)
  • STNG +3.1% (President of the Company and Scorpio Holdings Limited a related party have purchased common shares of the Company in the open marke)
  • AZN +2% (Eplontersen met co-primary and secondary endpoints in interim analysis of the NEURO-TTRansform Phase III trial for hereditary transthyretin-mediated amyloid polyneuropathy (ATTRv-PN))
  • TWTR +1.7% (discloses that it recommends that shareholders vote for the adoption of the merger agreement)
  • JBLU +1.4% (JetBlue (JBLU) submits proposal with increased offer of $33.50 per share in cash)
  • ULCC +1.4% (JetBlue (JBLU) submits proposal with increased offer of $33.50 per share in cash)
  • CRON +1.4% (Cronos Group and Ginkgo Bioworks (DNA) achieve THCV Equity Milestone; Cronos has issued to Ginkgo approximately 2.2 million common shares)
  • MDLZ +1.2% (acquires Clif Bar & Company for $2.9 bln)

Analyst comments:

  • CHWY +5.1% (upgraded to Outperform from Neutral at Wedbush)
  • SU +4.9% (upgraded to Outperform from Sector Perform at RBC Capital Mkts)
  • PSO +4.8% (upgraded to Buy from Hold at Deutsche Bank)
  • CUBE +3.7% (upgraded to Buy from Neutral at BofA Securities)
  • SCHW +3.2% (upgraded to Buy from Neutral at UBS)
  • FMC +3.1% (upgraded to Buy from Underperform at BofA Securities)
  • XOM +2.6% (upgraded to Outperform from Neutral at Credit Suisse)
  • CHD +2.4% (upgraded to Overweight from Equal Weight at Wells Fargo)
  • AMT +2.2% (upgraded to Overweight from Underweight at JP Morgan)
  • CNC +1.6% (upgraded to Outperform from Neutral at Credit Suisse)

>>> US Early premarket gappers

MEarly premarket gappers

  • Gapping up:
    • VALN +83.8%, SAVE +10.4%, ALV +8.1%, TRMR +6.3%, SHEL +6.2%, BP +6%, LEN +5.5%, HIMX +4.8%, BNR +4.6%, TTE +4.5%, IREN +4.3%, XOM +3.5%, NRZ +3.4%, SLB +3.4%, FANG +3.3%, TWTR +3.2%, HAL +3%, ULCC +2.9%, XLE +2.8%, FMC +2.5%, AZN +2.5%, IWM +2.1%, OIH +2.1%, QQQ +1.9%, ACAD +1.9%, SPY +1.8%, USO +1.8%, DIA +1.7%, ABB +1.7%, NOC +1.6%, LMT +1.2%, PSX +1.1%
  • Gapping down:
    • LEV -5.9%, EJFA -4.1%, VXX -3.5%, RADA -3%, FXLV -1.1%

(ZH) Bank of Japan Spends A Record $81 Billion To Avert Collapse, But $10 Trilli

Bank of Japan Spends A Record $81 Billion To Avert Collapse, But $10 Trillion JGB Market Is Now Completely Broken

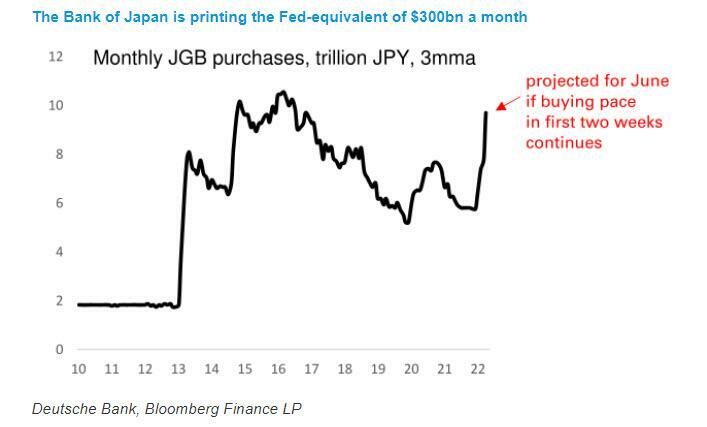
Exactly one week ago, when quantifying the dizzying cost of the BOJ's defense of its Yield Curve Control policy (at the expense of the collapsing yen), Deutsche Bank's George Saravelos calculated that the "the BOJ printer is on overdrive", and if the current pace of buying persists, the bank will have bought approximately 10 trillion yen in June. To put that number in context, it is roughly equivalent to the Fed doing more than $300bn of QE per month when adjusting for GDP.
Somewhat redundantly, the DB strategist said that this is a "truly extreme" level of money printing given that every other central bank in the world is tightening policy and is one of the reasons why he has been bearish on the yen. And as so many have argued, "currency intervention in this environment is simply not credible given it is the BoJ itself that is the cause of yen weakness."
More broadly, Saravelos echoes what we said in our preview of the end of MMT, writing that he worries that "the currency and Japanese financial markets are in the process of losing any sort of fundamental-based valuation anchor" and, as a result, "we will soon enter a phase where dramatic and unpredictable non-linearities in Japanese financial markets would kick in."
He was proven right the very next day, when not an insigificant part of Japan’s bond market imploded as the central bank battles to keep control of its policy goals as some of the largest hedge funds in the world pile on billions in bets that the BOJ is about to lose control, in a repeat of Soros' dramatic crusade against the BOE (which the billionaire democrat ended up winning, and affording him the wealth to be the US government's shadow puppetmaster to this day).
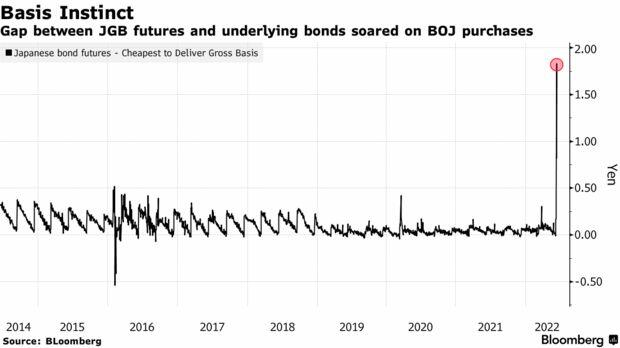
As Bloomberg explained, a small tweak to the Bank of Japan’s bond purchase plan this week blew up an arbitrage strategy popular with overseas investors known as the basis trade (the same basis trade which blew up in 2019 in the US cash/futures market sparking the historic repo crash and the Fed's return to QE). It also exacerbated a supply shortage of government bonds that has ramped up pressure on domestic financial institutions, leading them to turn to the BOJ for help to relieve the strain.
One week ago we described how after four straight days of declines in Japanese bond futures, the central bank announced unlimited purchases of so-called cheapest-to-deliver 10-year notes for Thursday and Friday - securities closest linked to the contracts. That sent the spread between the futures and the bonds underlying them soaring to the widest since 2014 - a massive shock for traders with positions between the two.
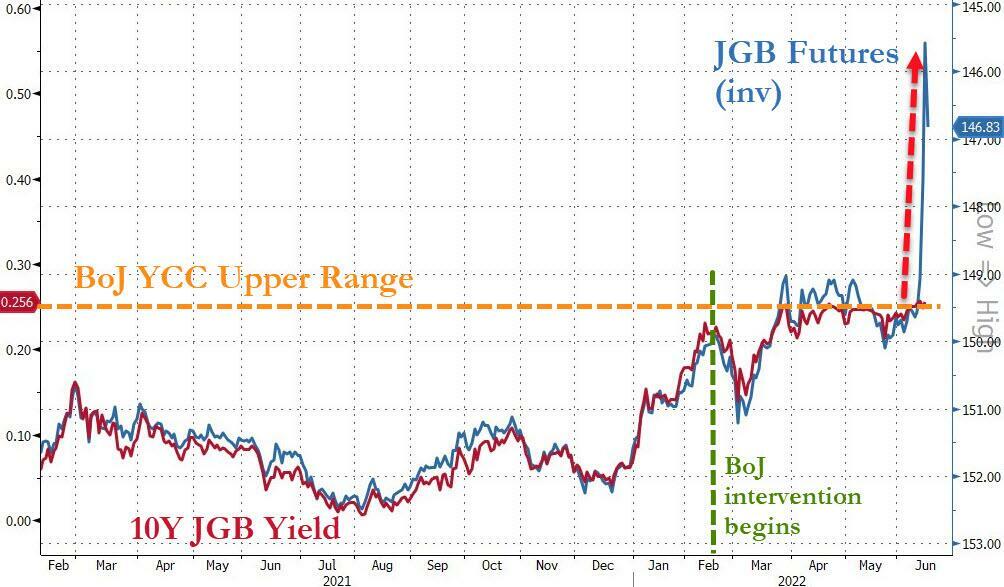
As a result, 10Y JGB futs crashed by the most since 2013 as traders bet that the BOJ will be forced to abandon its pledge to cap yields at 0.25%...
... while the gap between JGB futs and underlying cash bonds soared the most on record.
The chart below is another way of visualizing this historic divergence between futs and cash JGBs, clearly signaling the market's belief that the BoJ will fold on its unlimited bond buying curve control program.
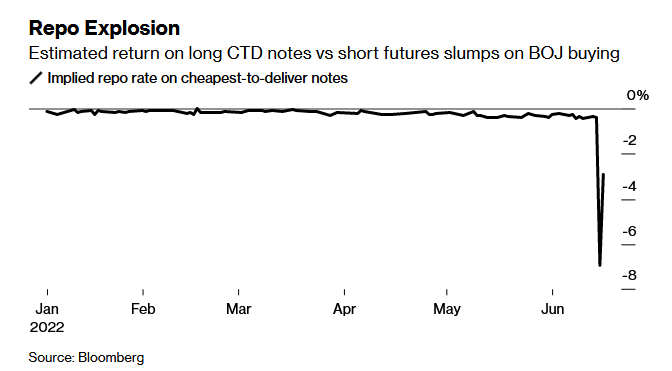
Needless to say, arbs who were short the cheapest-to-deliver bonds and long the futures contracts suddenly faced steep losses and found it impossible to close their positions (remarkably all this was happening in the world's 2nd largest bond markets, amounting to some 1.24 quadrillion yen or about $10 trillion, yet all everyone can talk about is crypto). As Bloomberg notes, the BOJ had effectively cornered the market in the cheapest-to-deliver bonds making it almost impossible for others to purchase them, while the futures price slumped to the brink of a trading halt as those caught out rushed to close.
By late day Wednesday, a Bloomberg estimate of the cost to close this so-called short basis trade widened to about minus 7% from minus 0.4% the day before. It remained at distressed levels Friday -- around minus 2% -- suggesting some investors were still stuck on the wrong side of the trade.
"The selloff in futures has killed arbitrage opportunities,” said Mari Iwashita, chief market economist at Daiwa Securities. “This situation will eventually end up in a total stalemate in markets."
By stalemate, he means "crash."
Speculative attacks on Japanese bonds have mounted as a growing number of funds - most notably the giant, $127 billion BlueBay - bet the BOJ will cave in to pressure and change its increasingly isolated super-easy monetary policy. The central bank confounded its critics Friday, holding firm with its rock-bottom interest rates and continuing with its fixed-rate bond purchase plan.
Benchmark bond yields fell further below the 0.25% ceiling, after the central bank announced a fixed-rate purchase operation for the afternoon.
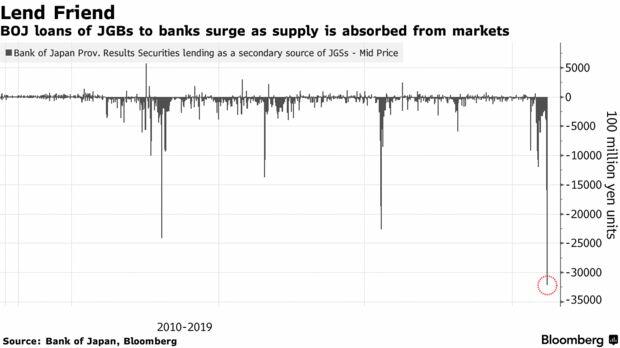
But the bigger problem for the BOJ is that those purchases, which preserving the BOJ's YCC "credibility" (for now) are also sucking up what little liquidity is available in the JGB market, piling pressure on local institutions, something which can be seen in the usage of the BOJ’s lending program -- another gauge of stress in the market.
Yes: on one hand the BOJ continues to buy billions in JGBs via QE, but on the other it is forced to lend what it has bought back into the market to avoid a terminal paralysis of what was once the second deepest bond market.
The amount of bonds the central bank has lent "temporarily" to financial institutions to relieve supply tightness has hit a record, Bloomberg data show. The BOJ lent 3.2 trillion yen ($23.9 billion) of JGBs through its Securities Lending Facility on Thursday, well above the 2.3 trillion yen lent at the peak of coronavirus fears in March 2020.
BOJ Governor Kuroda told reporters on Friday that the BOJ will take appropriate measures to address any decline in bond market liquidity. But he also said he isn’t thinking about raising the 10-year yield ceiling from 0.25%, which means that the liquidity situation will only get worse in the coming days.
“Market functioning and liquidity have deteriorated sharply with the BOJ’s massive JGB purchases,” Barclays strategist Shinji Ebihara wrote in a note.
Meanwhile, and going back to the original point brought up by DB's Saravelos above that the BOJ is spending monstrous amounts of yen just to keep the JGB market from crashing, as traders countdown to the complete Ice-9ing of the Japanese bond market (which in recent months has seen its share of days without a single trade crossing) Bloomberg has calculated how much it cost the BOJ to preserve calm after last week's catastrophic slide in futures, and the answer is some 10.9 trillion yen ($81 billion) of government bond purchases last week, the most on record. By way of comparison, European Central Bank asset purchases under its so-called APP program averaged about $27 billion - per month - this year through May. But fear not, once Europe's dominoes start falling and peripheral yields explode to all time highs, Lagarde's hedge fund will make BOJ's purchases seems like a walk in the park by comparison.
And while every day could be the BOJ's last, market watchers see the temporary calm as an eye in the proverbial hurricane, as the BOJ continues to defy an intensifying global wave of central bank tightening and concentrated market pressure on the yen and government bonds. Treasuries remain a key driver as does the direction of the dollar-yen, hovering around a 24-year low.
“If the yen weakens further as a sell-off in foreign bonds resumes, it would not be surprising were the yen rates market to start testing the BOJ again,” wrote Citigroup Inc. strategist Tomohisa Fujiki in a note.
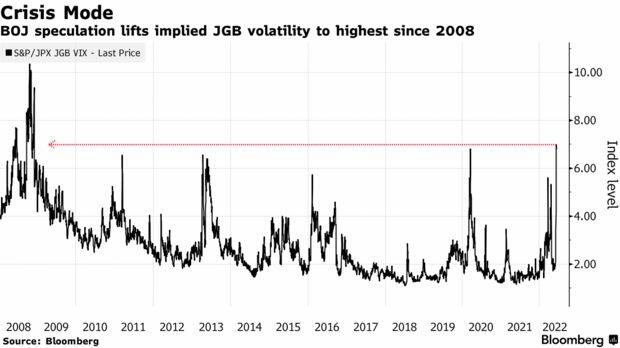
One place where the pressure is building up, is in implied volatility for 10-year JGBs, which however eased modestly after rising to the highest since the global financial crisis in 2008 on Friday. The BOJ said Friday its bond buying will continue for an extended period of time.
“Since the JGB market volatility has been initiated by the global reaction to US CPI and the Federal Reserve’s tightening, the structure keeping it unstable remains quite intact,” said Mari Iwashita, chief market economist at Daiwa Securities. “Even as the BOJ steps up efforts to defend its turf, the structure behind the challenges remain the same.”
Speculative attacks on Japan’s bond market have mounted amid bets the BOJ will cave in to pressure and tweak its increasingly isolated easy monetary policy -- something it reconfirmed at its policy decision Friday. But the impact of the central bank’s bond purchases have squeezed some corners of the futures markets, putting at least some arbitrage traders under pressure.
And yet, the most ominous sign yet for the BOJ is the recent quiet appointment of a Japanese government bond expert with experience of the market turmoil of the late 1990s to a key role in the Finance Ministry, which caught the attention of market watchers in Tokyo. Michio Saito -- dubbed “Mr. JGB” -- will head up a division that covers the bond market and may strengthen lines of communication with the central bank, according to some strategists.
For the BOJ to seek a smooth exit from massive bond purchases, close cooperation with the finance ministry is essential, so the appointment of an experienced person in charge is very significant, Iwashita said. This “is positive news for the market,” she said.
Most disagree, however, although they know better than to take the BOJ head on: after all, shorting JGBs has been a widowmaker trade for decades. Still, there is a sense of ominous capitulation vis-a-vis the Japanese bond market in recent days, almost as if we are now well past the point of no return and the final collapse of not just the JGB market, but the entire fraudulent MMT paradig, is just days if not hours away. Indeed, as Rabobank's Michael Every put it, with every attempt to preserve the status quo, the BOJ is pulling even further on a monetary elastic band that will hurt far more when it does inevitably come snapping back the other way, and concludes that when the BOJ's YCC peg eventually breaks, markets are going to get hit hard: "Japan is currently a source of ultra-cheap financing in a world of rising rates, and with a currency that is only going one way - down. If both reverse at once,… ouch!"
(ZH) St. Petersburg Sets The Stage For The War Of Economic Corridors

St. Petersburg Sets The Stage For The War Of Economic Corridors

In St. Petersburg, the world's new powers gather to upend the US-concocted “rules-based order” and reconnect the globe their way...
The St. Petersburg International Economic Forum has been configured for years now as absolutely essential to understand the evolving dynamics and the trials and tribulations of Eurasia integration.
St. Petersburg in 2022 is even more crucial as it directly connects to three simultaneous developments I had previously outlined, in no particular order:
  • First, the coming of the “new G8” – four BRICS nations (Brazil, Russia, India, China), plus Iran, Indonesia, Turkey and Mexico, whose GDP per purchasing parity power (PPP) already dwarfs the old, western-dominated G8.
  • Second, the Chinese “Three Rings” strategy of developing geoeconomic relations with its neighbors and partners.
  • Third, the development of BRICS+, or extended BRICS, including some members of the “new G8,” to be discussed at the upcoming summit in China.
There was hardly any doubt President Putin would be the star of St. Petersburg 2022, delivering a sharp, detailed speech to the plenary session.
Among the highlights, Putin smashed the illusions of the so-called ‘golden billion’ who live in the industrialized west (only 12 percent of the global population) and the “irresponsible macroeconomic policies of the G7 countries.”
The Russian president noted how “EU losses due to sanctions against Russia” could exceed $400 billion per year, and that Europe’s high energy prices – something that actually started “in the third quarter of last year” – are due to “blindly believing in renewable sources.”
He also duly dismissed the west’s ‘Putin price hike’ propaganda, saying the food and energy crisis is linked to misguided western economic policies, i.e., “Russian grain and fertilizers are being sanctioned” to the detriment of the west.
In a nutshell: the west misjudged Russia’s sovereignty when sanctioning it, and now is paying a very heavy price.
Chinese President Xi Jinping, addressing the forum by video, sent a message to the whole Global South. He evoked “true multilateralism,” insisting that emerging markets must have “a say in global economic management,” and called for “improved North-South and South-South dialogue.”
It was up to Kazakh President Tokayev, the ruler of a deeply strategic partner of both Russia and China, to deliver the punch line in person: Eurasia integration should progress hand in hand with China’s Belt and Road Initiative (BRI). Here it is, full circle.
Building a long-term strategy “in weeks”
St. Petersburg offered several engrossing discussions on key themes and sub-themes of Eurasia integration, such as business within the scope of the Shanghai Cooperation Organization (SCO); aspects of the Russia-China strategic partnership; what’s ahead for the BRICS; and prospects for the Russian financial sector.
One of the most important discussions was focused on the increasing interaction between the Eurasia Economic Union (EAEU) and ASEAN, a key example of what the Chinese would define as ‘South-South cooperation.’
And that connected to the still long and winding road leading to deeper integration of the EAEU itself.
This implies steps towards more self-sufficient economic development for members; establishing the priorities for import substitution; harnessing all the transport and logistical potential; developing trans-Eurasian corporations; and imprinting the EAEU ‘brand’ in a new system of global economic relations.
Russian Deputy Prime Minister Alexey Overchuk was particularly sharp on the pressing matters at hand: implementing a full free trade customs and economic union – plus a unified payment system – with simplified direct settlements using the Mir payment card to reach new markets in Southeast Asia, Africa and the Persian Gulf.
In a new era defined by Russian business circles as “the game with no rules” – debunking the US-coined “rules-based international order” – another relevant discussion, featuring key Putin adviser Maxim Oreshkin, focused on what should be the priorities for big business and the financial sector in connection to the state’s economic and foreign policy.
The consensus is that the current ‘rules’ have been written by the west. Russia could only connect to existing mechanisms, underpinned by international law and institutions. But then the west tried to “squeeze us out” and even “to cancel Russia.” So it’s time to “replace the no-rules rules.” That’s a key theme underlying the concept of ‘sovereignty’ developed by Putin in his plenary address.
In another important discussion chaired by the CEO of western-sanctioned Sberbank Herman Gref, there was much hand-wringing about the fact that the Russian “evolutionary leap forward towards 2030” should have happened sooner. Now a “long-term strategy has to be built in weeks,” with supply chains breaking down all across the spectrum.
A question was posed to the audience – the crème de la crème of Russia’s business community: what would you recommend, increased trade with the east, or redirecting the structure of the Russian economy? A whopping 72 percent voted for the latter.
So now we come to the crunch, as all these themes interact when we look at what happened only a few days before St. Petersburg.
The Russia-Iran-India corridor
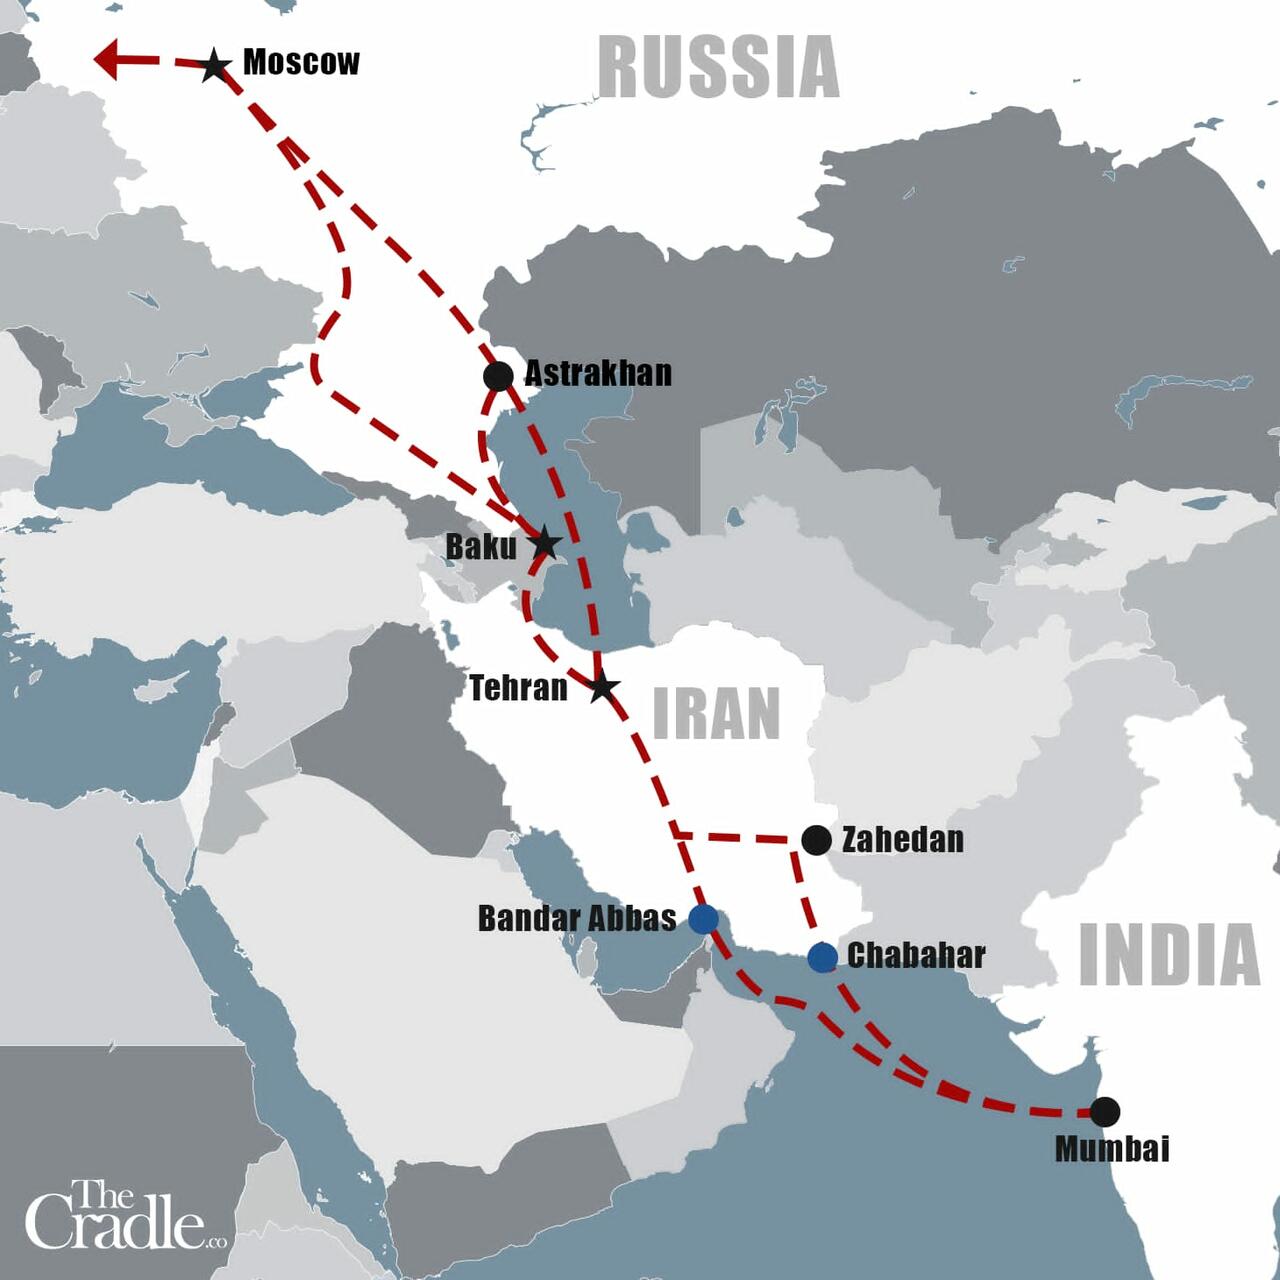
A key node of the International North South Transportation Corridor (INTSC) is now in play, linking northwest Russia to the Persian Gulf via the Caspian Sea and Iran. The transportation time between St. Petersburg and Indian ports is 25 days.
This logistical corridor with multimodal transportation carries an enormous geopolitical significance for two BRICs members and a prospective member of the “new G8” because it opens a key alternative route to the usual cargo trail from Asia to Europe via the Suez canal.
The International North South Transportation Corridor (INSTC)
The INSTC corridor is a classic South-South integration project: a 7,200-km-long multimodal network of ship, rail, and road routes interlinking India, Afghanistan, Central Asia, Iran, Azerbaijan and Russia all the way to Finland in the Baltic Sea.
Technically, picture a set of containers going overland from St. Petersburg to Astrakhan. Then the cargo sails via the Caspian to the Iranian port of Bandar Anzeli. Then it’s transported overland to the port of Bandar Abbas. And then overseas to Nava Sheva, the largest seaport in India. The key operator is Islamic Republic of Iran Shipping Lines (the IRISL group), which has branches in both Russia and India.
And that brings us to what wars from now will be fought about: transportation corridors – and not territorial conquest.
Beijing’s fast-paced BRI is seen as an existential threat to the ‘rules-based international order.’ It develops along six overland corridors across Eurasia, plus the Maritime Silk Road from the South China Sea, and the Indian Ocean, all the way to Europe.
One of the key targets of NATO’s proxy war in Ukraine is to interrupt BRI corridors across Russia. The Empire will go all out to interrupt not only BRI but also INSTC nodes. Afghanistan under US occupation was prevented from become a node for either BRI or INSTC.
With full access to the Sea of Azov – now a “Russian lake” – and arguably the whole Black Sea coastline further on down the road, Moscow will hugely increase its sea trading prospects (Putin: “The Black Sea was historically Russian territory”).
For the past two decades, energy corridors have been heavily politicized and are at the center of unforgiving global pipeline competitions – from BTC and South Stream to Nord Stream 1 and 2, and the never-ending soap operas, the Turkmenistan-Afghanistan-Pakistan-India (TAPI) and Iran-Pakistan-India (IPI) gas pipelines.
Then there’s the Northern Sea Route alongside the Russian coastline all the way to the Barents Sea. China and India are very much focused on the Northern Sea Route, not by accident also discussed in detail in St. Petersburg.
The contrast between the St. Petersburg debates on a possible re-wiring of our world – and the Three Stooges Taking a Train to Nowhere to tell a mediocre Ukrainian comedian to calm down and negotiate his surrender (as confirmed by German intelligence) – could not be starker.
Almost imperceptibly – just as it re-incorporated Crimea and entered the Syrian theater – Russia as a military-energy superpower now shows it is potentially capable of driving a great deal of the industrialized west back into the Stone Age. The western elites are just helpless. If only they could ride a corridor on the Eurasian high-speed train, they might learn something.

WSJ : U.S. Natural-Gas Exporter Completes First Deal With German Buyer

U.S. Natural-Gas Exporter Completes First Deal With German Buyer
Venture Global said it has struck binding agreements to sell LNG to German energy company EnBW Energie Baden-Württemberg AG

Venture Global LNG Inc. has struck the first binding deals by a U.S. natural-gas exporter to supply natural gas to a German company, as the European nation turns to America to help replace supplies from Russia.

On Tuesday, Venture Global said it agreed to sell 1.5 million metric tons of liquefied natural gas a year in two separate 20-year deals with German energy company EnBW Energie Baden-Württemberg AG EBK 1.58% , starting in 2026. Half of the amount will come from Venture’s Plaquemines LNG facility under construction in Louisiana, while the other half will come from another proposed facility in that state, it said.

Mike Sabel, Venture Global’s chief executive, said the agreements were “an important step that manifests Germany’s strategy to diversify its energy mix.”

Germany is fast-tracking the development of LNG import terminals on its northern coast as it seeks to reduce its dependence on Russian energy following Russia’s attack on Ukraine. Germany’s recent support for LNG comes after years in which U.S. companies vying to sell gas into Europe struggled to generate much interest.

Last week, Russia slashed supplies to Europe as it faces tough economic sanctions from Western nations in the wake of the war. On Sunday, Germany said it would restart coal-burning power plants and offer incentives for companies to reduce gas consumption as it seeks to build up gas inventories ahead of winter.

The Biden administration said the U.S. would send more gas to Europe this year and has worked to open doors between U.S. companies and their counterparts in Europe. Venture Global brought its first facility online at Calcasieu Pass in Louisiana earlier this year.

LNG “opens up the possibility of new sources to secure Germany’s gas supply in the current energy transition phase and builds a bridge to a green energy supply,” said Georg Stamatelopoulos, chief operating officer, generation & trading at EnBW.

Last month, Sempra Infrastructure entered a nonbinding agreement to sell LNG to German electricity generation company RWE AG from a proposed site in South Texas. Sempra Infrastructure is a subsidiary of Sempra. In May, Germany and Qatar also signed an agreement to expand LNG trade.

U.S. natural-gas prices have dropped while European prices have climbed following an explosion that forced Freeport LNG, another U.S. natural-gas shipper, to take its export facility in South Texas offline. The company said it doesn’t expect to fully resume operations until late 2022 as it repairs the facility.

Market participants have viewed the disruption as a cap on overseas exports of American shale gas, freeing up domestic supplies that have been squeezed by record-high exports as European countries scramble to secure LNG following Russia’s invasion of Ukraine.

The shale boom made U.S. natural gas cheap and abundant for more than a decade, but the past few months have marked the first time gas exports have significantly affected U.S. natural-gas prices, analysts and executives said.

Exports of natural gas—by LNG tanker and by pipeline to Mexico and Canada—vaulted to a record in March, to about 22% of U.S. gas production, according to the latest available data from the Energy Information Administration.

FT : Hong Kong exchange sets terms for Evergrande to avoid delisting

Hong Kong exchange sets terms for Evergrande to avoid delisting
Chinese property group under pressure as investors dump bonds from junk-rated developers

Chinese developer Evergrande said that Hong Kong’s stock exchange has set the terms for it to avoid delisting, as turmoil in the country’s property sector pushed a gauge of Asian high-yield dollar debt to near-record lows.

The slump for the ICE Bank of America Asian Dollar High Yield index was spurred largely by global investors dumping Chinese developers’ bonds in response to mounting repayment pressures. Last week, Moody’s put the credit rating of Chinese conglomerate Fosun International on review for downgrade.

Evergrande, the world’s most indebted developer, said in an exchange filing on Tuesday that it had until September 20, 2023 to resume trading in its shares. The developer will need to meet a series of conditions including publishing an independent investigation into its property services unit and demonstrating it has sufficient assets to operate.

Failure to meet the requirements would result in Evergrande, whose shares have already been suspended from trading for more than three months, being delisted from Hong Kong’s stock market.

Evergrande also said it was “actively pushing forward” with a plan to restructure its $300bn in liabilities, which it expects to release before the end of July.

Chinese authorities have prioritised completing the construction of Evergrande’s hundreds of projects, which are typically sold to ordinary buyers before completion, over repayment of its approximately $20bn of offshore dollar-denominated bonds.


Chinese developers’ dollar bonds had been squeezed by Moody’s decision last week to put Fosun on review for a potential downgrade, in large part because of the conglomerate’s exposure to China’s beleaguered real estate sector.

The credit rating agency said the review reflected concerns that growing risk aversion would throttle Fosun’s “already tight” liquidity while a downturn in the domestic property market will “also increase credit contagion risk”.

The warning has sent Fosun’s dollar debt tumbling, with its 5.95 per cent bond maturing in 2025 trading below 60 cents on the dollar on Tuesday, according to Bloomberg data.

Beijing has pushed domestic banks to step up lending in an effort to jump-start China’s real estate market. But property prices have languished despite a recent uptick in financing in part because of the impact of harsh Covid-19 lockdowns this year.

Steve Cochrane, chief Asia-Pacific economist at Moody’s, said that while the risk of widespread contagion from China’s property sector remained low, the financing drive could inject more risk into the country’s financial sector if it required banks to lower lending standards.

“That is one of the biggest risks in the economy, in particular in the debt market, today”, Cochrane said.