FT : Russian supply concerns weigh on plane makers’ Covid recovery

Russian supply concerns weigh on plane makers’ Covid recovery
Despite new orders from airlines, aerospace groups face worries over inflation and the availability of important commodities

Large aircraft orders have been few and far between since the coronavirus pandemic caused the grounding of most of the global fleet — and triggered one of the worst crises for the industry in decades.

But, at the start of this month, a bulk order by China’s state airlines for close to 300 Airbus single-aisle A320neo aircraft, worth some $37bn — the first order by the country’s carriers since the start of the crisis — provided the latest sign that the industry is recovering and returning to health.

More aircraft orders are expected to be announced this week by both Boeing and Airbus when the industry gathers at the world’s second-biggest air show, at Farnborough in Hampshire, in the UK.

Both manufacturers — as well as a host of electric air taxi start-ups promising urban air mobility — will also showcase their environmental credentials as the industry seeks to deliver on a pledge to reach net zero emissions by 2050.

Entrepreneurs behind the likes of Joby Aviation, Vertical Aerospace and Lilium, which are targeting scaled deployment of their flying taxis between 2023 and 2025, will all be present. And Boeing’s joint venture, Wisk Aero, will make the European debut of its all-electric vertical take-off and landing air taxi at the show.

One notable absence from this year’s show, however, will be the Russian aircraft industry, in the wake of the country’s invasion of Ukraine. But the war has prompted western governments to reverse years of cuts to their defence budgets. Aerospace and defence executives will be discussing the longer-term implications for their businesses, amid expectations of more contracts.

Despite a more buoyant mood fuelled by recovering demand for new planes from airlines keen to renew their fleets, the industry still faces a challenging operating environment. Soaring inflation, and concerns over the supply of important commodities such as aluminium and titanium in the wake of Russia’s invasion of Ukraine, pose ongoing problems for manufacturers.

Titanium is used to make critical components for aircraft, including landing gear as well as fasteners to the pylons that join an engine to a wing. Both Boeing and Airbus have relied on Russia for a large proportion of their supply of the metal. Although titanium has so far been kept off EU and US sanctions lists against Russia, aircraft companies have tried to reduce their exposure and looked to source alternative supplies.

Uncertain availability of parts and of skilled labour have been among the top two concerns cited by industry executives in recent months, according to Dave Stewart, partner at consultancy firm Oliver Wyman.

Aerospace groups, he says, are facing a “double pinch of volatility” in supply, coming out of the pandemic. “The new normal is to be really agile and to understand the demands of your supply chain. That volatility, whether for parts or labour, is really a challenge for the industry.”

As a result, executives will be watching closely how Airbus — and its hundreds of suppliers — cope with the European company’s pledge to raise production of its best-selling A320 family of aircraft by 50 per cent, to a rate of 65 planes a month by next summer, and then 75 planes a month by 2025.

After slashing production during the pandemic, both Airbus and Boeing are having to respond to strong demand for their medium-sized jets.

Airbus plans to meet the higher output rates by increasing capacity at its existing industrial sites, including building a second final assembly line at its US operation in Mobile, Alabama.

Engine makers and aircraft leasing companies had pushed back against the company’s more aggressive “scenarios” last year. But Airbus has since agreed supply deals with engine makers Safran and MTU for delivery through 2024 — signalling an easing of tensions between the companies.

Even so, getting to the higher production rates will be a “real challenge,” says Kevin Michaels, managing director of Michigan-based consultancy AeroDynamic Advisory. “You’ve got bottlenecks all over the supply chain. In particular, the engine supply chain is really tight.”

Those constraints could yet increase once Boeing ramps-up production of its aircraft. Dave Calhoun, Boeing’s chief executive, recently said he expected the industry’s current supply chain issues to last until possibly late 2023.

The US company has continued to grapple with a series of production and certification issues around some of its models in the wake of two deadly crashes of its 737 Max single-aisle aircraft, its key money-spinner.

It told the FT that it is continuing to “make progress stabilising our 737 production rate at 31 planes a month”, adding that “we are balancing the need to increase the production rate to position us to support increasing demand longer-term”.

Asia, and notably China, where the domestic travel market has remained subdued due to ongoing Covid restrictions, remains the unknown factor in the industry’s recovery.

China is a critical market for Airbus and Boeing, accounting for some 25 per cent of the global aviation growth that the US company has forecast over the next decade.

This month’s order for Airbus planes from Chinese state airlines was the first since 2019. China Eastern Airlines said it would buy 100 of the popular single-aisle A320neo family of jets, Air China will take 64 of the aircraft, while its Shenzhen Airlines subsidiary is purchasing another 32. In addition, China Southern Airlines, a carrier Boeing has historically counted as its biggest customer in the country, said it will buy 96 A320neos, as well as lease additional planes.

But Michaels points out that China’s “air travel market has really lapsed”. What happens there next “is the big wild card to watch in all of this”.

FT : Emmanuel Roman: ‘Markets are a very complicated Impressionist painting’

Emmanuel Roman: ‘Markets are a very complicated Impressionist painting’
The famously literary Pimco chief on generational luck in finance, where you find ideas, and the art of investing in good times — and bad times


Please use the sharing tools found via the share button at the top or side of articles. Copying articles to share with others is a breach of FT.com T&Cs and Copyright Policy. Email licensing@ft.com to buy additional rights. Subscribers may share up to 10 or 20 articles per month using the gift article service. More information can be found at https://www.ft.com/tour.

Emmanuel “Manny” Roman is waiting for me at his table in Marino, an old Italian family restaurant in Hollywood. I am a few minutes late. If anyone has an excuse to be late, it is my guest, the chief executive of Pimco, the giant fund manager. It has some $2tn of assets under management and the markets are in turmoil. I am hotfoot, I explain, from the Getty Museum, on the far side of town.

With the same crisp precision that he might outline to investors his view on whether to stay invested in China or how much to worry about exposure to Russia — his answers, I learn later, are yes and not much — Roman rules on the merits of the Getty and the Los Angeles County Museum of Art. He then urges me to go to The Broad museum, though cautions it is “the collection of a very rich man so it’s incredibly predictable”.

I have come to LA to see another very rich man, but one whose tastes are anything but predictable. Roman is a cosmopolitan French financier who pre-2008 might have been dubbed a “Master of the Universe”. He is also a legendarily literary patron of the arts. I am keen to hear his thoughts on the global outlook at this turbulent time. But I also want to know how his worlds intersect — the world of trading and the world of ideas — if they do at all.

That morning’s front pages in the US are screaming warnings of recession. The decades-long bull run of the bond market which has served Pimco so well has been declared at an end. It is a critical moment for Pimco and for the 58-year-old Roman, who upped sticks from London six years ago, opting to live in LA rather than south of the city in conservative Newport Beach, where Pimco is based.

He is a picture of composure. In fact not once in our Lunch does he look at his phone. I am surprised, I say, he has not had to cancel. He deploys that half-smile that has disarmed so many — some to their cost — over the years. So do the movement of ideas and the movement of markets really come together, I ask? Roman doesn’t pause.

“They totally come together,” he says. “I think markets are a very complicated Impressionist painting. Different pieces contribute to the story.” He gives a whistle-stop tour of his philosophy. “By thinking through the various sectors, stories and people you meet you get a much more holistic picture of what is happening in the economy. Some of it is by data, some of it is by anecdotal stories, some it is by lateral thinking. They are all part of the picture.”

Marino is an oasis on a blazingly hot summer’s day. Mario Marino, one of the two brothers running the show, arrives with a delicate sponge-like cauliflower mushroom cooked in pistachio oil. It is exquisite. Roman signals his approval.

The last time I saw him was in his previous role as the chief executive of Man Group, one of the world’s biggest hedge fund managers, the then sponsor of the Booker Prize, when he presided over its award ceremonies. Publishers were startled to find this “hedgie” had not only read the shortlist but had strong opinions. I ask him to rule on the “Manny myth”: does he really read a new book a week?

The post-Volcker years have been very good for financial markets and for our generation. I call that generational luck

It all started when he was growing up in Paris’s bohemian Montparnasse quarter, he says, mostly raised by his artist father. “He painted, the house was full of books, there was no TV, no car, so what does a boy do when options are fairly limited? I read and I read and I read.” And even now, I ask, running his empire and with a young (second) family?

“The trick is to be able to go lowbrow when you are tired and there’s too many things in your life,” he says. “I always have unread thrillers to hand if I don’t have the energy to read anything interesting.” I say I have devoted myself to Russian classics since the invasion of Ukraine and am travelling with Tolstoy’s short stories. His eyes narrow.

“The Death of Ivan Ilyich . . . That didn’t put you in the best possible mood.” We alight on a shared treasure, A Swim in a Pond in the Rain, a reflection on the art of the 19th-century Russian short story by the American writer George Saunders. “That’s part of what Russia is,” he says, sweeping back to the pressing issues of the day. “There’s a cultural heritage and a pride and a sense of the empire. When you talk of an Impressionist picture, that’s part of it.”

Sal Marino pops over from the kitchen with the second antipasto, raw kingfish. Its centrepiece looks like a minuscule sliced unripe acorn. It is a “green almond”, available for just a month at the start of an almond’s life. “It’s a superfood,” enthuses Sal. It is, also, exquisite, though I do wonder if I am eating the nut equivalent of veal.

I probe Roman’s Impressionist argument about the importance of nuance in investing. Ultimately, if you are trading, is it not also about splashy confident decisions — and timing?

“People trade too much,” he replies. “In the next 12 months there’s going to be plenty of things to do because things break and they become cheap. The discipline is to say, right now not a lot is happening where we can do better than the market. Then all of a sudden it’s a totally different ballgame and you can deploy plenty of capital — and do it very well.

“So the pandemic, terrible as it was, gave a unique opportunity to invest money pretty well. It was a window where things became incredibly cheap. Same with 2008. Same with 2001.”

Where he does agree with me is on the role of timing. His career has coincided with years of loose monetary policy, ultra-low interest rates and quantitative easing, which have allowed firms such as Pimco to prosper despite the financial crisis and the pandemic.

“The post-Volcker years have been very good for financial markets and for our generation,” he says, referring to Paul Volcker, the Fed Reserve chair from 1979-1987 who was credited with ending high levels of inflation. “I call that generational luck.”

The big plays in his career have certainly been well-timed. After an 18-year stint at Goldman Sachs, he joined the swashbuckling hedge fund GLG in 2005, just as markets were reaching a peak, and then helped to prime it for a listing two years later, just before the crash of 2008. Two years later he orchestrated its sale to Man, which was very lucrative for him and his GLG colleagues but not for Man. It was soon clear it had overpaid. In a plot twist worthy of a Chekhov short story, Man had to take writedowns on the business, its chief executive headed to the sidelines . . . and Roman took the top job; the reverse takeover was complete.

It was his record as an unruffleable turnround agent at Man, where assets had risen 38 per cent in his three years in charge, that led to his 2016 appointment to run Pimco’s business and change the culture, with chief investment officer Dan Ivascyn running the money.

It was a troubled inheritance. Pimco’s longtime star, the “bond king” Bill Gross, who had been among the first to spot the trading potential of the bond market, had left in 2014 in a spectacular row. Pimco was known as a hard-charging place. Gross had loved to strut his stuff on the morning talk shows. Roman has kept a far lower public profile, but I am told he and Ivascyn brought a decisiveness after a period of drift. Pimco’s assets dropped precipitously in the 2010s after Gross left and in late 2020 returned to that level.


But does he listen enough? How do you avoid becoming too confident in your judgment, I ask?

“Overconfidence is one of the great sins of mankind — and fund managers,” he says. “It’s easy to build a narrative where you say I have seen this before.” Richard Thaler, the behavioural economist, a friend and a Pimco consultant, “constantly” reminds him “of the bias that all humans have”.

“It’s very hard to escape that sometimes . . . and that’s why thinking through portfolio construction and risk and debating it with people of different backgrounds and age groups is very important . . . And not just people in your own mould.”

His comments have an added relevance as Pimco’s leadership received a letter last year signed by 21 former and current female employees accusing the firm of abusive and discriminatory behaviour to women. Several have filed lawsuits against Pimco.

“It’s an ongoing investigation,” says Roman. “I believe we’ve done nothing wrong. We’ve done our own investigation, and we’ve commissioned a third-party report. What’s very hard to judge is what happened 10 years ago.

“What I try to do is focus on things under my control, which is to be incredibly focused on having a very diverse workforce. I argue that a diverse workforce stops groupthink. The bigger problem is a bunch of white middle-aged men who all think the same . . . and will hit the wall at the same time.”

Mario is back with our homemade gnocchi, cooked to perfection. He also bears two half glasses of an American-style French Sauvignon by Philippe Melka, the former winemaker from Petrus. Roman demurs at the idea of wine and then acquiesces; he did in his London years own one of the more famous cellars in the city.

Now, however, his life in LA with his second wife is very different. And it’s not just that his social life is more limited, his wine cellar is in storage and he has to watch his beloved Arsenal at unreasonable hours on TV. In 2021, a tumultuous year for bonds, Pimco’s third-party assets under management grew by around five per cent. But 2022 has been a shocker for the bond markets.

For Roman, it is inflation that keeps him awake at night. He seems sanguine about the shifting geopolitical tectonic plates, playing down Pimco’s exposure to Russia as “a very small factor in the overall picture”. In the context of emerging markets in general, he argues that predicting politics is a fool’s errand “unless you’re incredibly close to someone who makes the real decisions”. Pricing political risk, however, is a different matter, he says.

“The average yield of the big emerging market countries is 9 per cent instead of 4 per cent. That’s a reasonable argument to make.” As for China, “we are far less worried than other people. It’s a supertanker. Yes, they locked down, but they can push the accelerator and get to 4.5 per cent growth without too many problems.

“But the big existential risk for all fund managers is that something goes very wrong in the US. Because all of a sudden it’s not a small position. It’s a very big position. So housing for example is a near existential risk for everyone because it’s just so big and there are so many ramifications, the banks, the financial system and so on.”

Our main course arrives. Mario offers a crisp barrel-aged Chenin Blanc from the winemaker Arnaud Lambert. Roman sticks with his Sauvignon. I switch and am happier with that decision than the halibut: it is the first disappointment, overcooked we agree.

When I first plotted Lunch, I had imagined slipping to his homeland. Roman follows events there keenly. He is in despair about the travails of Emmanuel Macron.

“It’s highly disturbing that 43 per cent of the French people vote for a neo-fascist and she [Marine Le Pen] is. Macron’s super smart. He’s young, which is not his fault; and he rubs some people up the wrong way. I’m not sure I understand why.”

The more we talk, the more I find myself thinking of a Renoir portrait of a dandyish composer I had just seen at the Getty. Its bright blues and reds had seemed incongruous under the diamond-bright skies of LA — just as does the idea of this soigné Frenchman driving before dawn every day to Pimco’s HQ in Newport Beach, plotting how to stay one step ahead of the markets.

In the face of the bond rout, he inevitably faces renewed pressure to go the way of other big fund managers such as BlackRock and be more of a supermarket. Will he? His reply reminds me of Jeff Bezos’ early maxim: do what you are good at.

“We do a lot of things, everything from government bonds to municipalities to corporate bonds to high yield to private credit to real estate. But . . . we don’t want to be a supermarket. We want to do one thing.” Before he took the job, he and Ivascyn discussed the way ahead and agreed: “We’re not going to do things we don’t really know how to do or we’re not really good at.” The pair cut back a failed expansion into equities and put resources into alternative and private credit strategies that command higher fees.

Ultimately, however, his legacy may well be decided not by the markets but by a play which worked well for him at Man: an emphasis on technology. He has spent what one Pimco-watcher says is a “ton of money” on programmers and engineers in Austin, Texas. The theory is that instead of relying on analysts you turn to algorithms. But is he getting the return on the investment? Unsurprisingly he is bullish.

“We went from zero to 400 people in three years . . . I always say I’m afraid of underinvesting in tech rather than overspending. That’s why scale matters. The amount you have to spend on it is very big. It’s existential. It’s literally existential.”

Sal appears from the kitchen, with Mario and two saucers of elderberry blossom ice cream with royal Rainier cherry.

“Ooh la la,” says Roman.

I have one last go at trying to understand where Roman’s two worlds meet. Pimco is not a quoted company but is wholly owned by Allianz. This gives Roman’s investment managers great freedom, which is all very well when times are good . . . So where do investing ideas come from?

“You very rarely have one great idea,” he says. “You have hopefully a lot of great ideas that, put together in a portfolio, make a lot of sense. From time to time you have one great idea because things get so cheap it becomes an obvious situation . . . but most often markets don’t lead to an outcome where they become so cheap that you can buy them and buy them in size. A lot of the ideas come bottom up. They come sideways.”

We both need double espressos. I’m still not entirely sure if his two worlds intersect but the one does at least provide clues about the other. After I return to London I email him to check a few details and ask about his reading.

“The Murder Rule,” he replies. “Pretty good and more unpredictable than usual. What I need is a new Harry Bosch.” Thrillers by his bedside? Yes, a tricky time on the markets.

WSJ : Fed Officials Preparing to Lift Interest Rates by Another 0.75 Percentage

Fed Officials Preparing to Lift Interest Rates by Another 0.75 Percentage Point
Policy makers are leaning against full-point increase despite June inflation surge

Federal Reserve officials have signaled they are likely to raise interest rates by 0.75 percentage point later this month, for the second straight meeting, as part of an aggressive effort to combat high inflation.

Policy makers left the door open to a larger, full-percentage-point increase at the July 26-27 gathering. But some of them simultaneously poured cold water on the idea in recent interviews and public comments ahead of their premeeting quiet period, which began Saturday.

Some officials pointed to signs that economic activity was softening as they raise rates at a historically brisk pace. “You don’t want to overdo the rate increases. A 75-basis-point hike, folks, is huge,” Fed governor Christopher Waller said Thursday at a conference in Victor, Idaho. “Don’t say, ‘Because you’re not going 100, you’re not doing your job.’”

Before last week, officials had signaled they were leaning toward a 0.75-point, or 75-basis-point, increase this month. After another scorching inflation report was released Wednesday, however, they indicated they would consider a full-point increase.

“We knew this inflation report was going to be ugly, and it was. It was just uglier than we thought,” said Mr. Waller. But, he added, “we don’t want to make policy on one data point, and that’s kind of a critical thing.”

The Labor Department reported the consumer-price index rose 9.1% in June from a year before, a new four-decade high, and showed inflation pressures broadening across the economy.

Demand surged last year from the reopening of the economy and aggressive government stimulus. More recently, Russia’s war against Ukraine aggravated supply-chain disruptions and drove up energy and commodity prices.

Fed officials have raised interest rates at their past three meetings, beginning with a quarter-point increase in March. They followed with a half-point rise in May and a 0.75-point increase last month, the largest since 1994. The Fed hasn’t raised rates by a full percentage point since it began using the federal-funds rate as its primary policy-setting tool in the early 1990s.

Moving rates up too dramatically could cause unnecessary weakness in the economy, Atlanta Fed President Raphael Bostic said Friday at a forum hosted by the Tampa Bay Business Journal in Florida.

Other Fed officials have signaled unease with the recent acceleration in rate rises. “A rapid pace of rate increase brings about the risk of tightening policy more quickly than the economy and markets can adjust,” said Kansas City President Esther George last week.

Since the Fed surprised markets with a larger-than-anticipated 0.75-point rate rise last month, investors have responded in ways that reflect growing worries about recession. Oil and commodity prices have tumbled, and long-term bond yields have declined.

On Friday, a University of Michigan survey of consumers’ long-term inflation expectations fell to its lowest level in a year, which weakened the case for a 1-percentage-point rate rise. Fed officials keep a close watch on households’ and businesses’ expectations of future inflation because they believe such expectations can be self-fulfilling.

Market-based measures of future inflation have also drifted to their lowest levels since Russian President Vladimir Putin’s invasion of Ukraine in late February.

“They can take comfort from that,” said Laurence Meyer, a former Fed governor. “This takes the pressure off of them. I don’t think they want to go 100.”

Investors and some analysts began anticipating a one-percentage-point rate increase at the July meeting after last Wednesday’s inflation report, with interest-rate futures contracts implying an 80% probability later that day, according to CME Group.

“The markets may have gotten ahead of themselves,” Mr. Waller said on Thursday. By Friday, the market implied probability had fallen to less than 30%.

Jay Bryson, chief economist at Wells Fargo, was among those to call for the larger rate rise last week. But on Friday, he said the case had become less compelling. “It’ll be on the table, but trying to get a consensus or a supermajority to go for 100 seems a little bit aggressive,” he said.

Raising rates by a full percentage point could complicate how officials explain their policy strategy going forward. “If you are going to do 100, you better have a damned good story. They don’t have one now,” said Mr. Meyer, who runs the forecasting firm LH Meyer. Officials would have to clarify what had prompted another shift, and what would lead them to maintain an even more aggressive pace, for example.

A 0.75-point rate rise could allow officials to signal their ability to maintain that historically aggressive pace if demand and inflation stay hot or to moderate their increases if they see progress in slowing inflation and economic activity.

Officials could face more difficult decisions later this year over how much higher to push rates, especially if the economy shows more obvious signs of slowing, but with inflation still well above the Fed’s 2% target.

Richmond Fed President Tom Barkin said last week he is focused on raising rates above the inflation level that investors are expecting over the next two years. “Any particular 25-basis-point [change] is not nearly as important to me as the destination,” he said in an interview.

Stronger-than-anticipated inflation could change that destination, giving urgency to raise rates faster and higher than otherwise. St. Louis Fed President James Bullard said Friday he anticipates lifting the fed-funds rate to just below 4% by December, up from his previous projection of around 3.5%.

With another 0.75-point rate rise at the coming meeting, the Fed will have raised the fed-funds rate by as much in the past five months as its combined increases between 2015 and 2018. It would lift the rate to a range between 2.25% and 2.5%, closer to officials’ estimates of a neutral rate that neither stimulates nor restricts demand.

Officials are seeking to raise rates to levels that slow spending, investment and hiring by reducing demand. “They got back to neutral fast,” said Mr. Bryson of Wells Fargo. “Now it’s a question of how fast do they get into restrictive territory, and how restrictive do they get.”

Economists surveyed by The Wall Street Journal this month put the chance of a recession sometime in the next 12 months at 49%. Most of the 62 respondents expect the central bank to raise the fed-funds rate at least above 3.25% by the end of the year and to maintain it at or above that level through next year. Most expect the Fed’s first rate cut to occur by the end of 2023.

Fed Chairman Jerome Powell has said in recent public appearances that it will get harder for the Fed to bring down inflation without a recession if energy prices continue to rise or supply-chain bottlenecks don’t improve. Ideally, officials would slow growth enough to cool price pressures but not so much that the economy tips into a downturn.

“There’s no guarantee we can do that,” Mr. Powell said last month. “The pathways have gotten narrower.”

(ZH) Comparing The Cost Of Living Around The World

Comparing The Cost Of Living Around The World

The amount of money that’s needed to pay for day-to-day expenses like housing and food varies greatly from city to city. And some cities, like New York City, are known as especially expensive places to live.
So how do everyday expenses in New York City truly compare in costs to places like Beirut, Lebanon, or Bangalore, India?
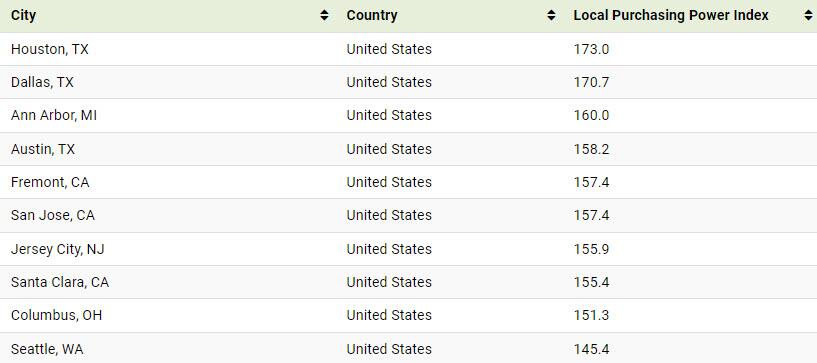
This graphic by Victor Dépré (hypntic.data) uses 2022 data from Numbeo to compare the cost of living and purchasing power in 578 different cities around the world, using New York City as a benchmark for comparison.

The Cost of Living Index
Though New York City is widely recognized as one of the most expensive cities in the world, as Visual Capitalist's Carmen Ang details below, according to Numbeo - the world’s largest database of user-contributed data on cities and countries - there are a number of cities that are actually more expensive than the Big Apple.
Here’s a look at the comparative cost of living in 578 cities. For context, if a city has a cost of living index of 121, that means day-to-day expenses in it are 21% higher than New York’s, on average:
Bermuda’s capital city Hamilton ranks first on the list, with a cost of living that’s nearly 50% higher than New York’s.
Why is Hamilton so expensive? One reason is that nearly everything needs to be imported onto the tiny British archipelago—things like gas, groceries, and clothes—so it’s likely that prices in the territory are steep as a result.
Second on the list is Zurich, Switzerland, where expenses are roughly 30% higher than New York City. Food and beverages are particularly expensive in the region—according to the dataset, groceries are 58% more expensive than groceries in NYC, and restaurant prices are 55% higher.
However, it’s worth noting that while Zurich ranks high on the cost of living index, the city’s purchasing power is also strong, which we will dive into in the next section.
The Local Purchasing Power Index
Purchasing power is a metric that’s used to gauge the number of goods and services someone on an average salary can buy in that specific city.
Taking a look again at Zurich, consumers in the city have about 30% more purchasing power than New York City residents on average, despite having higher costs.
In contrast, the average consumer in Hamilton, Bermuda has a relatively low purchasing power. Based on the average net salary in the city, consumers can afford about 30% less than people in New York City.
Inflation Continues to Drive Prices Up
Amidst rising inflation and increased prices for consumer goods, cost of living has become top of mind for many people around the world.
Since late 2021, the world has been experiencing a cost of living crisis, largely because of pent-up demand following the COVID-19 pandemic, coupled with supply chain issues and the Russia-Ukraine conflict.
But according to UBS Chief Economist Paul Donovan, we’ve likely seen the worst of it, and inflation is likely to decrease across the globe in the second half of the year.

WSJ : Crypto Crash Stalls WeWork Founder Adam Neumann’s Climate Venture

Crypto Crash Stalls WeWork Founder Adam Neumann’s Climate Venture
Investors rushed to startups offering cryptocurrencies backed by carbon-offset credits, then the markets tanked

Former WeWork WE 6.45% Chief Executive Adam Neumann resurfaced with a new company earlier this year, in a buzzy, young industry that aims to use cryptocurrencies to fight climate change.

Months later, that company, Flowcarbon, as well as a host of similar startups, have slowed operations and product rollouts—the latest fallout of tanking markets.

Flowcarbon, one of a group of companies that are issuing cryptocurrencies backed by carbon credits, has decided to “wait for markets to stabilize” before launching its products, said Chief Executive and co-founder Dana Gibber. Other outfits such as Toucan Protocol Association and KlimaDAO have effectively frozen new business as a plunge in crypto coincided with a crackdown on issuance of new cryptocurrency tokens by a big carbon-market registry.

Flowcarbon and its peers are combining cryptocurrency, a type of digital asset that trades on decentralized computer networks, with another largely unregulated and volatile financial instrument: carbon credits.

Such credits are issued by projects that aim to remove carbon-dioxide from the atmosphere or prevent emissions from being produced, through forest planting or conservation, for instance. Each credit represents one metric ton of carbon dioxide removed or avoided. Corporations or individuals buy the credits and retire them to offset their greenhouse-gas emissions, as investors and others demand action to combat climate change.

Most carbon credits are sold through brokers or directly by project developers, a process critics say is clunky, opaque and time-consuming. Flowcarbon and its peers say they can change that by bringing credits onto their networks as crypto tokens—Flowcarbon’s is called the Goddess Nature Token—where they can be traded in large volumes like digital money and destroyed, or “burned,” when the owner wants to offset emissions.

“As someone who bought credits from brokers in the past, buying and burning tokens is far, far easier,” Mark Cuban, a tech billionaire and crypto investor, said in a written response to questions. Mr. Cuban has used Klima tokens to offset 1,100 metric tons of personal and business carbon emissions, according to KlimaDAO data.

Venture capitalists invested around $267 million into climate or carbon-related crypto deals in 2021 and another $156 million this year through early July—a surge in investment from previous years although a fraction of the billions invested in cryptocurrency deals overall, according to research firm Pitchbook Data Inc.

A good chunk of that funding has gone to Flowcarbon, which was co-founded by Mr. Neumann—best known as the ousted head of office-rental firm WeWork. WeWork’s spectacular crash, shelved public offering and bailout in 2019 became the subject of an Apple TV+ drama starring Jared Leto and Anne Hathaway. Flowcarbon says Mr. Neumann isn’t involved in the daily operations of the company.

Mr. Neumann has invested in a number of startups as well as real estate, the Journal has reported. He didn’t respond to a request for comment.

The fledgling industry took off after Toucan and KlimaDAO started selling their tokens in October, driving an influx of money to the carbon markets. At its peak in late October, the value of all Klima tokens in circulation topped $1 billion.

For the six months through March, more than 23 million carbon credits were moved onto crypto networks. That accounted for about 28% of credits removed from the registries where they were listed during that period, according to an analysis by data provider Trove Research Ltd. So far, less than 2% of those credits have been used to offset carbon emissions and the bulk have been traded, according to KlimaDAO data.

During the last three months of 2021, hundreds of millions of metric tons of carbon have been traded through crypto tokens, with a value topping $3 billion, according to KlimaDAO data. That is a similar volume to the carbon-trading activity for all of last year outside of the crypto markets, according to carbon-markets data tracker Ecosystem Marketplace.

Many carbon-market watchers still aren’t sure how helpful carbon-backed tokens will be, or whether they are good for the overall carbon-offset market, given the speculation that has often accompanied cryptocurrencies.

The purpose of carbon credits is offsetting emissions, said Guy Turner, Trove Research’s CEO. “If people are now buying those tokens because they see it’s a money-making machine…I think that’s potentially unhealthy,” he said.

Some see snapping up the credits for investment as healthy. “In order for carbon credits to have a significant impact on the climate crisis, the market for them must scale up by orders of magnitude,” said a group that says it represents KlimaDAO’s core project team and that maintains anonymity of its members. “Speculation plays a critical role in scaling any market” by bringing in enough money to promote easy, liquid trading and accurate prices, they said.

“We think it is OK if people can make money either as an investment or a hedge against higher carbon costs,” Toucan Chairman Julian Sommer said. “But it should not be the only use case.”

In May, Flowcarbon announced it had raised $70 million from presales of its token, as well as money from funds run by big-name venture investors such as Andreessen Horowitz and General Catalyst, among others.

By that time, however, cryptocurrencies were in free fall, having lost $1 trillion in value since November.

Meanwhile, also in May, the biggest carbon-offset registry halted the use of its credits to back new cryptocurrency tokens, saying it was concerned that the current method of creating those tokens was causing confusion in the carbon markets. The registry, Verra, said it is studying new methods of creating the tokens.

Flowcarbon had expected to launch its token by the end of June, but put that plan on hold indefinitely, said Ms. Gibber. In recent weeks, the company has been announcing partnerships to help it offer services like calculation of carbon footprints for credit buyers and loans for credit-issuing projects.

“We invest with a long-term view and remain very confident about the market,” said Arianna Simpson, a general partner at Andreessen Horowitz handling the Flowcarbon investment. General Catalyst declined to comment.

Toucan, Klima and other crypto-carbon startups say they are waiting for Verra to propose a new method of bringing credits onto cryptocurrency networks and hunkering down until the crash in crypto markets eases.

“When everything is up and everyone is having a party, everyone says, ‘Oh, of course we’re going to put money behind carbon,’” said Toucan’s Mr. Sommer. “Now everyone needs to survive.”

WSJ : SIM Cards Are Going Away. Why That’s a Good Thing

SIM Cards Are Going Away. Why That’s a Good Thing
Already popular in Europe and Asia, eSIMs let you connect to a wireless network without a physical card

Since the dawn of the smartphone age, changing your cellular provider followed the same pattern: You’d get a SIM card from your new carrier, find something small enough to poke the tiny hole on the side of your phone, remove your old chip and replace it with the new one.

That process will soon be a thing of the past. Millions of people have moved away from physical SIM cards to virtual ones. One day, the rest of us will do the same.

SIM cards are being replaced by their “embedded” counterparts known as eSIMs. Rather than getting a physical card from a carrier, you’ll instead activate service digitally by logging into an app or by scanning a QR code.

The software connects you to a new cellular network on the fly, letting you quickly sign up for service without tracking down a store. Because phone makers don’t have to include space for the SIM card tray, they can build sleeker devices, say industry veterans. ESIMs even let you have two phone numbers on your phone at the same time: You could have one for work and one for personal calls, or set up an international number alongside your normal service when traveling.

“The vision is, you can get a phone from anyone, and as you’re activating the device, you pick your service operator and off you go,” said Chetan Sharma, a wireless industry analyst who leads his own consulting firm.

ESIMs have become popular in Europe and Asia, where consumers tend to switch between prepaid plans to get the best data package available, he said. In the U.S., people typically stick with one carrier.

The three biggest U.S. wireless providers— T-Mobile, AT&T and Verizon —say a cardless future is approaching here, too. With last year’s iPhone 13, Apple stopped including physical SIM cards in the box. And Motorola’s foldable Razr phone from 2019 didn’t support physical SIMs at all.

“It’s a natural evolution,” said Jeff Howard, vice president of mobile devices and accessories at AT&T. “It’s going to make the experience better down the road.”

Right now, setting up an eSIM isn’t always painless. Even if your phone supports it, your carrier may not. And if you try to move eSIMs between devices, you likely have to go through setup all over again.

A Slow Start
SIM cards relay your user details to the carrier to authenticate your smartphone and enable you to make and receive calls, texts and data.

But when you want to change phones or switch service providers, SIMs can be cumbersome. Anyone who’s hunted for a tool to open the SIM tray (a skinny paper clip, for instance) knows what a pain that can be. Once you actually get the card out, the tiny dimensions of today’s popular nano-SIMs—about the width of an M&M but thinner than a credit card—make them easy to lose. SIM cards also are vulnerable to hacks and have been tracked and exploited by cybercriminals.

ESIMs aim to solve those issues. While they still require a chip inside the phone, that component is smaller than physical SIMs and can’t be removed. No more worries about dropping your eSIM and losing it in your floor crack.

The digital chips allow carriers or device makers to quickly roll out software updates if security vulnerabilities are identified, said Anthony Goonetilleke, group president of technology and head of strategy at Amdocs, an eSIM software company.

“You can suddenly send out a security update to millions of people globally if an issue is found,” Mr. Goonetilleke said. “You can’t do that with physical SIMs.”

Another plus: Activating service over the air makes it easier for customers to switch wireless providers. That’s a big reason why U.S. carriers were hesitant to adopt eSIMs, said Bernd Mueller, head of technology, solutions and strategy at the SIM-card production company Giesecke+Devrient.

Picking Up Speed
You may already have an eSIM-compatible phone and not realize it. Google’s smartphones have had eSIM capabilities since 2017’s Pixel 2, and Apple added it to iPhones starting with 2018’s iPhone XS. Roughly 40% of all phones Verizon carries this year have eSIM capabilities.

Because last year’s third-generation iPhone SE didn’t come with a physical SIM included, Verizon started training staff to onboard more eSIM customers, said Brian Higgins, Verizon senior vice president of device and consumer product marketing. Those customers can set up service through Verizon’s app, rather than getting a SIM in the mail or in a store.

AT&T added an activation guide on its website and will let customers scan a QR code to set up an eSIM on their device. During the setup process on T-Mobile’s network, the carrier prompts customers with compatible phones to activate their eSIM over Wi-Fi.

If you prefer to frequently switch between different phones, it may be simpler to pop your SIM card in and out of devices than to transfer your eSIM back and forth. And if you transfer your cellular plan from a physical SIM to an eSIM, your older card can be permanently disabled.

Physical SIMs won’t disappear immediately, but once Apple stops supporting them in its new iPhones, the writing is on the wall.

Phones with eSIM Capabilities
Here’s a list of phones that work with eSIMs. But check with your wireless provider, since not all carriers support the technology.

• iPhone 13 models: Can have up to two active SIMs—either two eSIMs, or one eSIM and one physical nano-SIM card

• iPhone XR, XS, 11, 12 models: Can have one eSIM and one nano-SIM

• Samsung Galaxy S20 and newer: Supports eSims. Can have two active SIMs, but check the specifics on your particular model

• Samsung Galaxy Z Flip, Fold and newer: Can have one eSIM and one nano-SIM

FT : EDF’s problems pile up as full nationalisation looms

EDF’s problems pile up as full nationalisation looms
French supplier of nuclear energy is struggling with plant shutdowns, build problems and skills shortages

At the site of France’s first new nuclear reactor in more than 20 years, robots are whirring away fixing faulty welding as developer EDF races to open the plant after a decade of delays that have damaged its reputation.

Ahead of it lies a challenge of a different order of magnitude: a construction programme to build six more, just as the French government, which owns 84 per cent of the business already, plans to take full control.

The full nationalisation of EDF, which was announced earlier this month, comes as a series of crises pile pressure on the group’s finances. In theory this will provide it with some relief away from the glare of public markets.

So far, however, the state buyout has raised more questions than it has answered, including how the government thinks it might do a better job at fixing long-running industrial problems that have plagued projects at EDF, some of them as basic as a lack of experienced welders.

“It’s not because the government will now have 100 per cent that it’s going to suddenly take three years less to build a reactor,” one person close to the company said.

“Right now we’re in symbolic territory with this nationalisation. It doesn’t resolve any of the main problems we know the group is facing — will it allow EDF to bolster the skills it needs?” said Cécile Maisonneuve, a senior adviser at the centre for energy and climate at French think thank IFRI. “None of the industrial or regulatory issues were linked to its capital structure.”

Just as Europe attempts to move away from its dependence on Russian gas and grapples with soaring power prices, problems at some of EDF’s existing 56 reactors in France have caused shutdowns and sent its energy output to multi-decade lows.


Instead, it has had to turn to expensive wholesale markets for supply and this is expected to all but wipe out its core profits this year. Rating agencies have warned that this will further push up EDF’s debts, beyond last year’s €43bn, and it is likely to need a second capital injection soon — after one as recently as April.

At the same time, political battles have made EDF’s listed status increasingly untenable. It was made to pay for an annual electricity price cap announced in January to shield consumers from the spiralling market, sparking a stand-off between the state and EDF managers, and enraging minority shareholders.

The Flamanville 3 reactor on France’s northern coast has come to symbolise some of the technical problems faced by EDF and its contractors. Now due to start loading fuel next year, construction began in 2007 with a target finish date of 2012. The budget is now nearly four times the initial €3.3bn estimate.

Setbacks include regulators finding faults in the finishing standards of some of the pipe welding. To address this, EDF commissioned purpose-built robots to work inside the pipes, rather than dismounting an entire piping system already encased in thick concrete walls.

Keeping EDF on track is vital for energy security not just in France but more broadly. Other European nations have long relied on its exported nuclear energy, and its dwindling output has come at the worst possible time as the bloc braces for a potential total cut-off of Russian gas.


French president Emmanuel Macron visits the GE Steam Power System main production site for its nuclear turbine systems in Belfort, France © Maxppp/PA Images
“France has traditionally been the source of cheap nuclear power for its neighbours but now it requires help and this will cause problems in Italy, Switzerland and Britain this winter,” said Phil Hewitt, director at energy consultancy EnAppSys.

The UK is also a major construction client. EDF is building its only new nuclear power plant — Hinkley Point C, a project that has been plagued by cost overruns and delays. All but one of Britain’s remaining nuclear power stations are due to close by the end of the decade.

But its home country is especially reliant. France lags European neighbours on wind and solar power, and is much more focused on nuclear as a source of low-carbon energy.

It accounts for more than 60 per cent of the country’s energy production and in February, the government announced plans for at least six next generation, EDF-made European Pressurised Reactors (EPRs) — a programme of some €50bn that will need to be financed with debt.

In private, French officials have criticised EDF and the way it has managed some operational problems, although the preventive checks and reactor shutdowns were demanded by the regulator.


Please use the sharing tools found via the share button at the top or side of articles. Copying articles to share with others is a breach of FT.com T&Cs and Copyright Policy. Email licensing@ft.com to buy additional rights. Subscribers may share up to 10 or 20 articles per month using the gift article service. More information can be found at https://www.ft.com/tour.

“EDF’s production cuts are not acceptable. It can’t go on like this,” one government official said, adding that full state ownership might help speed up decision making, including for new projects.

“lt allows us to gain time, a few weeks or months here and there. It adds up,” they said.

Some of EDF’s problems are not of its own making. Over the years, successive governments have pushed it into expensive strategic decisions, including the bailout of ailing reactor designer Areva.

It also suffered from a lull in government orders when the world cooled on nuclear power after the Fukushima disaster in 2011.

The energy crisis caused by Russia’s invasion of Ukraine has revived interest in the industry, but even in France, with its long history of construction and large fleet, it has been more than 20 years since the last new reactor came online — at the eastern Civaux site in 1999. Engineers and other skilled workers have deserted the sector to build careers in finance or other industries.


“In that gap between Civaux and Flamanville, we lost our knowledge of how to carry out huge projects and our industrial capacity,” said Alain Morvan, the latest manager brought in to finish the project, during a site visit in June.

With the EPR build in mind, EDF has now begun recruiting more nuclear specialists, and Morvan said there were lessons from Flamanville that could be applied elsewhere.

The company had also been pushing for a new regulatory framework for how nuclear power is sold, and for changes to a system that forces it to sell some of its output at fixed prices to local competitors, which outgoing CEO Jean-Bernard Lévy has called “poison” for the group’s finances.

The French government has yet to say how or when regulation will change and some reforms will require approval from Brussels.

It has also said little about how it might reshape the company — which also has a big renewable energy portfolio and a distribution business — when it takes full control, which is expected via a tender offer worth roughly €7bn in October or November.

EDF declined to comment further on the nationalisation or plans for the group.

Full state control will at least eradicate one very visible problem: since its shares peaked in 2007 after what was, at the time in 2005, one of Europe’s biggest ever IPOs, EDF’s stock has fallen close to 90 per cent.

One banker who has worked with EDF before said: “The original sin was privatising a group operating in nuclear energy to start with.”

In an internal memo to staff in July seen by the Financial Times, Lévy said facing up to future projects as a listed company had become too difficult.

“If the delisting does not solve all of our regulatory, industrial and financial problems, and particularly the scale of our debt, it does allow us to start finding solutions.”

FT : A German gas crisis will cause jitters across Europe

A German gas crisis will cause jitters across Europe
As Russia seeks to make others pay the price for its war in Ukraine, an EU-wide energy security strategy is needed

“We just don’t know. Everything is possible.” This was German economics minister Robert Habeck’s succinct response to the question currently consuming his country’s government, industry and public: when the 10-day scheduled maintenance to the Nord Stream 1 pipeline ends on July 21, will the Russian state-controlled gas exporter Gazprom resume deliveries? Or will Vladimir Putin perform a gasectomy on Germany?

A graph in the Federal Network Agency’s latest supply status report shows how much gas is currently flowing in at three connector points for Russian gas on Germany’s eastern border: none. “The situation,” says the agency, “is tense and a worsening of the situation cannot be ruled out.” 

That is a bit of an understatement. Nord Stream 1 supplies 58 per cent of Germany’s annual gas needs. The benchmark European TTF gas price has already risen by more than 130 per cent since the beginning of Russia’s invasion of Ukraine on February 24, to more than €170 per megawatt hour. In late June, after Russia reduced supplies by 60 per cent, Berlin triggered the second stage of its national gas emergency plan — one step away from gas rationing.

Germany also receives gas from Norway, the Netherlands and Belgium. But Russia could have redirected its gas via alternate routes such as Yamal or the Ukrainian transit pipeline, and it has not. So Germany is falling behind on filling up its gas storage facilities to create reserves for winter.

At the beginning of July, Germany’s three-decade-long trade surplus flipped into a deficit, driven by the rise in gas prices; the country’s wealth is created mostly by energy-intensive industries, whose import costs have soared. Inflation is at a record high, a recession looms and the euro is at parity with the dollar for the first time since 2002. Cheap Russian energy used to be a key source of the country’s global competitive advantage. Now Russia is making Europe and Germany pay the price for Putin’s war.

Germany’s options are few, imperfect and unpleasant. Habeck is bringing dirty coal plants back online, and telling people to take shorter showers. He is streamlining procurement and loosening environmental restrictions to build fixed liquefied natural gas terminals; meanwhile, he is renting floating terminals. And he has wooed authoritarian Gulf leaders in search of alternative LNG supplies. These are painful concessions for a Green politician. But Habeck is in a hurry, and has a strong pragmatic streak.

It gets worse. Germany’s energy emergency law privileges private households over industry — but some companies say that gas rationing or shutdowns could force them to shutter their operations permanently. The government has just passed a law that allows it to bail out firms hit by the energy shock; the gas importer Uniper has already raised its hand. Consumer gas prices might triple.

This dire prospect is causing the Liberals (who are in the government) and the opposition conservatives to loudly criticise Berlin’s decision to shutter Germany’s last three nuclear power plants by the end of the year.

Ironically, it was Angela Merkel’s conservative-liberal coalition that decided in 2011 to phase out nuclear power after the Fukushima power plant disaster in Japan. Since then, Germany has stopped investing in civilian nuclear power technology and expertise. The three plants are at the end of their safely viable lifetimes. They would cover only 6 per cent of the country’s electricity needs; and industry needs process heat, not electricity. In sum: the cost and risk of an extension outweigh the benefit.

Given how much of this pain is self-inflicted, the Schadenfreude in other parts of Europe was foreseeable. Being asked for solidarity by Germany after seeing it ignore criticism and steadfastly pursue its national economic interest for years may be a step too far for many.

Yet a gas crisis in the EU’s economic powerhouse will cause jitters across the continent. Uniper may be Germany’s biggest gas supplier; its main shareholder is the Finnish state-owned energy company Fortum. And Russia has fully or partially cut off gas supplies to almost a dozen EU countries. However, there is no European gas sharing arrangement, only a handful of hastily concluded bilateral “solidarity” agreements. Countries that receive large quantities of non-Russian gas — France, the Netherlands, Spain, Belgium — have not joined.

What is needed now is an EU-wide energy security strategy. Putin is using the threat of a gas cut-off to break Germany’s societal resilience and political will. But he means all of Europe.


FT : We should worry about price of food more than petrol, warns BlackRock’s Fin

We should worry about price of food more than petrol, warns BlackRock’s Fink
The destruction of arable land during the Ukraine war has dangerous global consequences

The dramatic spikes in oil and mineral prices after Russia’s invasion of Ukraine have distracted investors from the long-lasting and more dangerous impact of food inflation, BlackRock founder Larry Fink has warned.

“The one thing I worry about that we don’t talk enough about is food,” he told the Financial Times. “This isn’t just an inflation concern. There are also geopolitical concerns that result from this.”

The prices of energy, petrol and petroleum-based agricultural inputs shot up earlier this year when western nations imposed sanctions on Russia after the invasion. Grain and edible oil costs were also hit hard because Ukraine is a major exporter.

Oil has begun to drop back down this week to pre-invasion levels as traders brace for a sharp drop-off in consumption. But food price inflation remains stubbornly high. The US consumer price index figures for June show that the price of chicken parts and flour are each up close to 20 per cent year on year and margarine has jumped 34 per cent.

“We talk a lot about gasoline prices because that’s what affects Americans but the bigger issue is food,” Fink said. “There has been tremendous destruction of arable land in Ukraine.....Globally the cost of fertiliser is up almost 100 per cent and that additional cost is reducing the amount of fertiliser used in farming. That is harming the quality of the crop worldwide.”

Although lower oil prices have started to feed through to the price at the pump for motorists, consumer goods companies are continuing to see high input costs. Any drop in fertiliser prices is likely to come too late to boost this year’s food harvests.

The World Bank forecast after the invasion that global food prices would rise 20 per cent this year, far outpacing raw materials.

The impact is particularly grim in Africa, which usually imports grain from Ukraine as well as producing its own food. Fertiliser prices there have risen 300 per cent, and the continent is facing a shortage of 2mn metric tons, according to the African Development Bank. It has approved a $1.5bn programme to help farmers fill the gap but warns that total production could fall by 20 per cent this year.

Janet Yellen, the US Treasury secretary, said on Friday that the world was facing “an extremely difficult time for global food security” and urged the G20 group of leading nations to halt stockpiling and export restrictions on food and provide additional financial assistance to countries and people struggling with food insecurity.

Bill Gates, the philanthropist and Microsoft co-founder, flagged similar concerns this week, saying that the reduction in supplies of wheat, edible oils and other foods caused by the war in Ukraine was “driving up food prices, which will increase malnutrition and instability in low-income countries.” He noted in a blog post that improving agricultural productivity in Africa required “far more investment”.

While some consumer products makers and food retailers say they are hopeful that food price inflation will begin to ease, others are preparing for the worst.

Snack foodmaker Mondelez is seeing so much inflation and “availability issues” in edible oils and grains that “we are looking into flexible formulation to make sure that we can replace some ingredients and components that are in shortage with something that is more available,” Luca Zaramella, the chief financial officer said last month.

General Mills is predicting a “significant step up in input cost inflation” to 14 per cent for the fiscal year that started in June. CEO Jeff Harmening said last month that the maker of Cheerios as well as Pillsbury and Betty Crocker home baking products expects to see “reduced consumer spending power”.