(ZH) Space Diamonds From Dwarf Planets May Be Future Of Mining & Manufacturing

Space Diamonds From Dwarf Planets May Be Future Of Mining & Manufacturing

Tiny folded diamonds that fell to Earth from an ancient dwarf star may sound like something from an intergalactic feature film, but researchers from Australia and the United Kingdom have proven the existence of the rare gems after examining a stony meteorite.
Scientists from Australia and the UK have established the existence of lonsdaleite, a rare hexagonal diamond, no bigger than a human hair, that researchers note is layered into a distinctive folded pattern, unlike the earth-formed diamonds that have a cubic structure.
The existence of Lonsdaleite—named after the pioneering British crystallographer Dame Kathleen Lonsdale—has previously been the subject of debate because its very existence could not be proven.
The lead scientist on the research team Prof. Andy Tomkins, from Monash University’s School of Earth, Atmosphere, and Environment, said the mysteries of the rare diamond were what drove him continue researching ureilite meteorites in his lab.
Tomkins said it was a case of curiosity-driven science.
“This is exactly the sort of curiosity-piquing observation that sends scientists diving down rabbit holes for months on end,” he said.
Scientists from Australia and the UK have established the existence of lonsdaleite, a rare hexagonal diamond no bigger than human hair. Image shows the ‘The Rock,’ a 228.31-karat pear-shaped white diamond, in Geneva on May 6, 2022. (Fabrice Coffrini/AFP via Getty Images)
Naturally formed ureilite meteorites contains a higher abundance of diamond than any known rock on Earth. They are also one of the few opportunities to study the mantle layer of dwarf planets.
The samples are created when asteroids collide with a planet while still hot, creating the ideal conditions for lonsdaleite and diamond growth due to moderate pressure and rapid temperature drops in the fluid and gas-rich environment.
“These findings help address a long-standing mystery regarding the formation of the carbon phases in ureilites that has been the subject of much speculation,” Tomkins said.
Tomkins also collaborated with researchers from the CSIRO, RMIT University, the Australian Synchrotron, and Plymouth University to discover samples of lonsdaleite in nature, offering an insight into potential replication of the process for industrial purposes.
“These diamonds are quite special,” said Alan Salek, physicist and RMIT PhD researcher.
“Normal diamonds that you would find here on Earth, like on an engagement ring, have a specific atomic structure that’s cubic. These special diamonds are hexagonal in structure.”
“It’s pretty exciting because it’s a new form of material.”
The unique shape is believed to be why lonsdaleite is stronger than any other diamond.
Significant Implications For Mining and Manufacturing
CSIRO scientist Colin MacRae in a media release, said the discovery has enormous potential for industries like mining.
“If something that’s harder than diamond can be manufactured readily, that’s something industry would want to know about,” MacRae said.
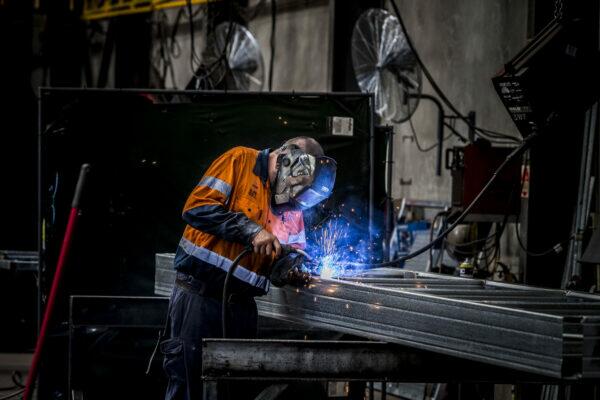
Manufacturing at a Brisbane factory in Australia, on Jan 25, 2017. (AAP Image/Glenn Hunt)
Macrae noted that the discovery meant they could find a way to reproduce the mineral.
“Lonsdaleite could be used to make tiny, ultra-hard machine parts if we can develop an industrial process that promotes the replacement of pre-shaped graphite parts by lonsdaleite,” he said.
At present, the current method for producing industrial diamonds involves chemical vapour deposition, in which diamonds are formed onto a substrate from a gas mix at low pressures.

>>> TradeGate Pre-Market Indications

DAX:
  • Daimler Truck (DTG TH) -0.4%
  • Covestro (1COV TH) -0.5%
  • Infineon (IFX TH) -0.5%
  • Deutsche Bank (DBK TH) -1.2%
  • HelloFresh (HFG TH) -1.3%
  • Vonovia (VNA TH) -1.4%
    • Vonovia Cut to Equal-Weight at Barclays; PT 30 euros
  • RWE (RWE TH) -1.4%
    • Watch Utilities as Germany Considers Takeover of Gas Companies
  • Deutsche Post (DPW TH) -3.7%
    • Watch Mail-Delivery Stocks After FedEx Pulls Annual Forecast
MDAX:
  • TAG Immobilien (TEG TH) +0.6%
  • Grand City Properties (GYC TH) +0.3%
    • Grand City Properties Raised to Buy at Goldman; PT 12.60 euros
  • LEG Immobilien (LEG TH) -1%
  • Commerzbank (CBK TH) -1.3%
  • Telefonica Deutschland (O2D TH) -1.3%
    • Telefonica Deutschland Cut to Equal-Weight at Barclays
  • Lufthansa (LHA TH) -2.2%
  • Stroeer (SAX TH) -2.7%
    • Stroeer Cut to Hold at Deutsche Bank; PT 62 euros
SDAX:
  • Schaeffler (SHA TH) -0.8%
  • About You (YOU TH) -0.9%
  • SMA Solar (S92 TH) -1.6%
  • Hensoldt (HAG TH) -1.9%
  • Shop Apotheke (SAE TH) -2.1%

FT : Dan Loeb’s volte-face on ESPN shines a light on Disney’s woes

Dan Loeb’s volte-face on ESPN shines a light on Disney’s woes
Truce reached with activist investor over sports network has left media group’s chief weighing up his options

In a letter addressed to Disney chief executive Bob Chapek in mid-August, activist hedge fund manager Dan Loeb said a “strong case can be made” for the ESPN sports network to be spun off from the company.

Loeb, known for waging bruising battles against the likes of Sony and Sotheby’s, outlined his argument along with a host of other recommendations to improve performance at Disney, including a board “refresh”, taking full control of the Hulu streaming network and cost-cutting measures.

Less than a month later, however, the aggressive manager of hedge fund Third Point reversed his position on spinning off Disney’s sports network after Chapek told the Financial Times that he had a plan to “restore ESPN to its growth trajectory”. In a tweet, Loeb said he had come to a “better understanding of ESPN’s potential as a standalone business”.

Loeb’s message came as a relief to Disney and ESPN employees, but the episode has shone a light on the deeper problems facing the sports network — and left investors wondering about the details of Chapek’s plan to fix them.

“[Chapek] has got to explain to Wall Street how ESPN can be a good business,” said Rich Greenfield, an analyst at LightShed Partners. “Cable networks are just a challenged business. The problem is less and less people are subscribing to [traditional] TV, and the sports costs keep coming up.”

Neither Disney nor Third Point would comment on the matter, but both emphasised there has been cordial dialogue between Loeb and Chapek.

Once Disney’s profit engine thanks to its commanding share of cable subscribers, a steady stream of affiliate fees and advertising revenue, ESPN has suffered in the streaming age.

Its subscriber base has fallen from a peak of 99.4mn in 2011 to a projected 73.6mn by the end of this year — a drop of more than 25 per cent — according to estimates by S&P Global Market Intelligence.


Worse, its famous cash-spinning ability is expected to shrink dramatically over the next three years, said Scott Robson, senior research analyst at S&P Global. He estimates cash flow will drop from about $2.5bn in 2021 to $1bn in 2025.

“Everybody knows that the . . . cable bundle is deteriorating over time,” Chapek told a Goldman Sachs conference this week. “It’s still a significant business, very appreciative from a cash flow standpoint for us. But at some point, we see the writing on the wall where this is going, and we’re preparing for that.”

Besides cord-cutting, ESPN is facing escalating costs of rights to broadcast sports — driven in part by streaming services run by deep-pocketed Apple and Amazon. Disney expects to pay $10.3bn in contractual commitments for sports programming this year, and an additional $60bn in future commitments.

“These sports rights are getting more and more expensive,” Robson said. “It’s really going to start negatively impacting the bottom line at ESPN.”

But Chapek told the FT he believes ESPN can return to its growth. Crucial to this will be more aggressive marketing of ESPN Plus, its sports streaming network, as part of a bundle with its other streaming platforms, Disney Plus and Hulu. ESPN Plus has about 22.8mn subscribers, or nearly 10 per cent of Disney’s 221mn streaming subscribers.

Chapek noted the enduring power of sports to attract large audiences, even in an age of audience fragmentation. He also believes ESPN can become a force in the rapidly expanding US sports-betting industry — a step that earlier generations of Disney leaders would have thought too racy for the family-friendly company.

Disney acquired a 5 per cent stake in DraftKings, a fantasy sports and betting group, in 2019 when it bought 21st Century Fox. It also has a deal with Caesars Entertainment that gives it the exclusive right to provide sports betting odds to ESPN. Chapek has even floated the idea of launching an ESPN-branded sports betting app, though the company has not started work on this, insiders say.

In his letter, Loeb said it would be easier for ESPN to pursue sports betting outside of Disney. He also said a spin-off would help reduce Disney’s debt, which stood at $46bn at the end of the most recent quarter.

But Loeb’s proposal to spin off ESPN divided Wall Street analysts. Greenfield at LightShed Partners supports the idea, but analysts at MoffettNathanson wrote last month that it would be “financially dangerous to divest ESPN”. Not only are Disney’s revenues reliant on ESPN’s cash, they wrote, but investors aren’t keen on a leveraged asset whose primary business is cable television in the era of cord cutting.


Moreover, recent sports rights deals show the ever-appreciating value of live events. Disney rival Paramount last month more than doubled the price it will pay Uefa for US rights to broadcast the Champions League, now worth $1.5bn over six years.

Apple has reached multibillion-dollar agreements to air Major League Soccer and Major League Baseball, while Amazon last year joined the most expensive package of live sports rights ever sold: the National Football League’s $110bn broadcast terms over 11 years.

Inside ESPN, executives argue that the network is better served with the marketing might of the rest of the Disney company, which includes the ABC broadcast network. They point to the seven-year deal ESPN signed last year with the National Hockey League allowing it to show games on the ESPN cable network, ESPN Plus, the Hulu streaming service and ABC. A similar 12-year plan was signed recently for the rights to the Wimbledon tennis championships.

Even with the headwinds facing its core cable television business, Chapek said Disney had been “deluged” with interest from companies seeking to buy ESPN or join in a spin-off after reports that the company was weighing a sale earlier this year. “If everyone wants to come in and buy it . . . I think that says something about its potential,” Chapek said.

He added: “When the rest of the world knows what our plans are, they will be as confident about that proposition as we are.”

Loeb appears satisfied to wait for Chapek’s plan — at least for now.

>>> Europe : Brokers Upgraddes & Downgrades - 16th of September

>>> Up
* Alcoa Raised to Overweight at Morgan Stanley; PT $66
* Aroundtown Raised to Neutral at JPMorgan; PT 3.10 euros
* Big Yellow Group Raised to Overweight at JPMorgan
* Credit Agricole Raised to Buy at AlphaValue/Baader
* Gecina Raised to Overweight at JPMorgan; PT 112 euros
* Grand City Properties Raised to Buy at Goldman; PT 12.60 euros
* SFS Raised to Hold at Berenberg; PT 75 Swiss francs
* TAG Immobilien Raised to Overweight at Barclays; PT 11 euros

>>> Down
* Adidas Cut to Market Perform at Cowen; PT 155 euros
* Adobe Cut to Neutral at Baird; PT $355
* Adobe Cut to Equal-Weight at Barclays; PT $340
* Aroundtown Cut to Neutral at Goldman; PT 2.70 euros
* Catena Cut to Underweight at JPMorgan; PT 400 kronor
* Credit Agricole Cut to Hold at SocGen
* FedEx Cut to Hold at Stifel; PT $195
* FedEx Cut to Sector Weight at KeyBanc
* FedEx Cut to Neutral at JPMorgan; PT $214
* Fevertree Drinks Cut to Hold at Berenberg; PT 1,000 pence
* InterContinental Hotels Cut to Sell at Citi; PT 4,450 pence
* International Paper Cut to Underperform at Jefferies
* Kojamo Cut to Underweight at JPMorgan; PT 15 euros
* Land Sec. Cut to Sell at Goldman; PT 500 pence
* MFE Cut to Underweight at Barclays; PT 45 euro cents
* Proximus Cut to Sell at SocGen; PT 10 euros
* Royal Mail Cut to Neutral at JPMorgan; PT 270 pence
* Semperit Cut to Hold at Erste Group; PT 20.10 euros
* Stroeer Cut to Hold at Deutsche Bank; PT 62 euros
* Telefonica Deutschland Cut to Equal-Weight at Barclays
* Telecom Italia Cut to Underweight at Barclays; PT 15 euro cents
* THG PLC Cut to Neutral at Goldman; PT 50 pence
* Unite Group Cut to Neutral at JPMorgan; PT 1,075 pence
* Vonovia Cut to Equal-Weight at Barclays; PT 30 euros

>>> Initiation
* Investec Rated New Buy at Berenberg; PT 540 pence
* Landis + Gyr Rated New Buy at Baader Helvea; PT 77 Swiss francs

>>> Call
* Adidas Cut at Cowen on Weakening Data Points, Rising Risks
* Fevertree Cut at Berenberg as Pressures Rise in Core UK Market
* IHG Gets Only Sell as Citi Downgrades on ‘Muted’ Demand Outlook
* Investec Rated Buy at Berenberg on Streamlined Business Offering
* SocGen Says S&P 500 to Hit New Low, Sees Zero EPS growth in 2023
* UCB Risk Profile Now More Balanced, Citi Upgrades to Neutral

>>> What to look at today -16th of September 2022

Equities extended their decline, with US and European futures pointed lower and Asian shares on course for a fifth week of losses while Treasury yields rose, reflecting bets for outsized Federal Reserve interest rate hikes. Stocks slumped from the open in Japan, Australia and Hong Kong following the S&P 500 Index’s lowest close in about two months. Mainland China equities also slumped, with little impact on sentiment from industrial production and retails sales data that beat expectations. The offshore yuan remained on the weaker side of 7 to the dollar, even as the People’s Bank of China set the reference rate for the currency stronger-than-forecast for a 17th straight day. The greenback fluctuated and policy-sensitive two-year Treasury yields held near the highest since 2007. The latest US economic data painted a mixed picture for the economy that backed the view for hawkish monetary policy. The market weakness follows data showing applications for US unemployment insurance fell for a fifth straight week, suggesting demand for workers remains healthy. Retail sales indicated spending on goods is moderating. Other figures showed factory production rose slightly in August while total industrial production, including mining and utilities, fell. University of Michigan data Friday will be parsed for clues on inflation expectations. Oil was poised to fall for a third week amid the deteriorating global economic backdrop, which has fueled demand concerns at a time when the buoyant dollar makes crude more expensive for most buyers. US After Hours FDX -15.1% on guidance; UPS -5.5% in sympathy with FDX; RBLX -1.8% on August metrics, BOWL +7.9% on earnings and stock offering

Nikkei -1.06% Hang Seng -0.56% CSI -1.57% Shanghai -1.44% Shenzen -1.28%

Eur$1 CNH 7.0186 CNY 7.0090 JPY 143.34 GBP 1.1466 CHF 0.9617 RUB 59.7892 TRY 18.2527 WTI$85.18 +0.09% Gold 1,,64.98 -0.1% BTC 119,793.50 -0.30% ETH 1,476.50 -1.78%

S&P -0.77% Nasdaq -0.94% EuroStoxx -0.90% FTSE -0.61% Dax -1.01% SMI -0.51%

Macro :
- SocGen Says S&P 500 to Hit New Low, Sees Zero EPS growth in 2023
- Ether Falls as Ethereum Revamp Turns Into ‘Sell-the-News’ Event

Keep an eye on :
- ARIS IM : Ariston to Buy Centrotec Climate Systems For EU1B: M&A Snapshot
- ASSAB SS : Assa Abloy Will Contest DOJ Block of Spectrum Brands Takeover
- BAYN GY : Brazil Fertilizer Retailer Lavoro Eyes Expansion After SPAC Deal
- BOL FP : Bouveret Takes Over Bollore’s Reorganized E-Mobility Business
- COLR BB : Virya Energy Said to Start Sale of Offshore Wind Firm Parkwind
- 05G GY : CPI Property Group Starts Asset Revamp After Austrian Deals
- DHER GY : Stricken Food-Delivery Orders Face Shaky Road: 2Q Earnings Wrap
- DPW GY : FedEx Sinks After Withdrawing Earnings Forecast; UPS Falls (1)
- ENGI FP : Engie Has Taken FID in Australia Renewable Hydrogen Project
- GTT FP : GTT Holder Engie Offers 2.2m Shares
- JUP LN : Jupiter Asset Plans Restructure in Operational Review: FT
- PAH3 GY : Porsche IPO to Comprise 911m Shares in Nod to Famous Model: Rtrs
- RHM GY : Slovenia to Abandon Purchase of Boxer Armored Vehicles
- ROSN RM : Germany Takes Control Over Rosneft Deutschland
- SAS SS : SAS Confident for Winter as Funding Approved and Travel Rebounds
- SW FP : Sodexo Expands Partnership With Ardent Health Services in US
- UN01 GY : Germany in Talks for Historic Rescue of Gas Firms: Energy Update
- VWS DC : Vestas Considers Developing Wind Farms as Demand Skyrockets: JP
- VIRP FP : Virbac Sees FY Organic Revenue at Constant FX +5% to +10%
- VTWR GY : PE Pursuit of Vantage Stake Is Boon for Vodafone: Street Wrap
- VOW3 GY : Europe Car Sales Return to Growth After Painful Year of Declines

FT : Silver Lake ups stake in Manchester City owner

Silver Lake ups stake in Manchester City owner
Renowned tech investor has turned its sights on sport and is now second-largest shareholder in City Football Group

US private equity group Silver Lake has increased its stake in the parent company of Manchester City Football Club, making it the second-largest shareholder in the business behind its Abu Dhabi owners.

The Silicon Valley-based firm acquired a 4.1 per cent share in City Football Group from China Media Capital, taking its total holding to 14.5 per cent.

Silver Lake, which made a name for itself as a tech investor, has been stepping up its bets on the sports industry, with investments ranging from football and rugby to baseball. This latest deal strengthens its ties to Abu Dhabi’s royal family and Sheikh Mansour bin Zayed Al Nahyan, the billionaire royal who acquired Manchester City in 2008 and established CFG five years later. 

CFG is now one of the biggest sport club owners in the industry, with investments in football clubs ranging from Australia and Japan to Uruguay and the US. Silver Lake bought its original 10 per cent stake in CFG for $500mn in 2019, valuing the business at $4.8bn.

Sheikh Mansour controls CFG through Abu Dhabi-based Newton Investment and Development.

Silver Lake’s growing sports portfolio shows how the balance of power in the industry is changing as private equity groups and billionaires acquire clubs and invest in leagues.

In June, it won approval to invest NZ$200mn in New Zealand Rugby, the organisation behind the All Blacks team, following its acquisition of a minority stake in the Australian Professional Leagues football group.

It is also a shareholder in sports merchandising company Fanatics and in Endeavor, the New York-listed owner of Ultimate Fighting Championship, the mixed martial arts series. In August, it bought Diamond Baseball Holdings, which owns a numbers of clubs in the sport.

Silver Lake bought into City Football Group after Hollywood impresario Ari Emanuel — founder of Endeavor — introduced managing partner Egon Durban to CFG’s Khaldoon al-Mubarak.

The private equity firm has formed deep ties with Abu Dhabi. Mubarak is chief executive of Mubadala, an Abu Dhabi sovereign investment fund that took a stake in Silver Lake in 2020. The following year, Silver Lake paid about $800mn for a stake in G42, an artificial intelligence and cloud computing group with links to Abu Dhabi’s ruling family.

China Media Capital still owns 8.2 per cent of CFG, having originally paid $485mn to amass a 13 per cent stake. That investment, which valued CFG at $3bn, came after China’s president Xi Jinping visited Manchester City’s football academy in 2015.

Chinese investors had bought into a series of European football clubs but many made for the exit after Beijing tightened capital controls in recent years.

Under CFG ownership, Manchester City has won the English Premier League five times and this year overtook rivals to top Deloitte’s annual ranking of the highest revenue-generating football clubs in the world.

FT : Corporate bonds > equities? : A Contrarian Case

Corporate bonds look cheapish

Yesterday Unhedged complained that, given the economic backdrop, stocks looked a little expensive. So what is one to own instead? It is hard to recommend fixed income, given the high volatility — mostly upward volatility — of interest rates. For the first time in a long time, even decent-quality bonds are as scary, or scarier, than stocks.

Another leg up in rates, and leg down in bond prices, cannot be ruled out when no one knows for sure where the Federal Reserve will stop. Flows into bond funds have been deeply and persistently negative all year, except for the brief period this summer when the market saw the mirage of a Fed pivot.

Still, there is a case to be made for buying bonds, and specifically corporate bonds. Here is that case, put very crudely, in a single chart:


That is the yield on bonds from the highest tier of junk-rated bonds, compared to the earnings yield on the S&P 500 (that is, the reciprocal of the price/earnings ratio). Right now, BB bonds yield more. This does not happen very often. The yield differential is about what is was in the acutely frightening early days of the coronavirus pandemic. Are things as bad now as they looked then? There are assorted perfectly technical quibbles that could be raised with this comparison, but it gets to the heart of the argument. Bonds look cheapish, relatively.

Why cheapish, not plain old cheap? A lot of what makes corporates look cheap compared to stocks is higher Treasury yields — a higher risk-free rate. The additional compensation investors are getting for taking on BB default risk, about 330 basis points, is only middling by historical standards. Here is a long-term chart of the spread:

In addition, the compensation for trading down from the lowest rung of investment grade (BBB) to the highest rung of junk (BB) is not all that special. The difference between the BBB and the BB spreads (the spread spread, if you will) stands at 1.4 per cent, just a bit above its 10-year average.

On some measures, high-yield bonds are not cheap at all. Marty Fridson, of Lehmann Livian Fridson, uses a model that shows a fair value spread for the entire high-yield index (BBs and everything junkier) at about 7.2 per cent, well ahead of the 4.8 per cent spread the index currently offers. The main reason is that his model demands more yield when the availability of credit is constrained — as it is now, according to the Fed’s loan officer survey, for example.

During the past few years, most companies pushed their debt maturities years into the future. According to Scott DiMaggio, co-head of fixed income at AllianceBernstein, only about 20 per cent of the bonds in the US market mature in the next three years, “a very manageable number”. But there is more to credit risk than refinancing, as Unhedged recently discussed.

That said, many BB rated bonds are issued by companies that seem very unlikely to default outside of a very severe recession: the index includes Sprint, Ford, Occidental, Yum Brands, T-Mobile and so on.

Interest rate volatility, and the accompanying direction risk, hang over the whole discussion. Investors will remember the brutal 17 per cent fall in the JNK — the largest of the junk-bond exchange traded funds — over the past year. Remember, though, that for most investors duration risk must be weighed against the riskiness of equities and the vulnerability of cash to inflation.

The bonds in the JNK have average maturity of between five and six years. The five-year Treasury has risen almost 2 per cent in the past 12 months. If rates rise another two percentage points, take a moment to think about what that implies about inflation, and what it will do to your stock portfolio.

Finally, the flat yield curve presents an opportunity. Quite good yields are available in bonds with maturities of just a year or two. The yield to worst on Ford’s BB+ bonds maturing in September of 2025 is 6.5 per cent, for example. Sprint’s bonds due June 2024 pay 5.5 per cent.

The corporate bond market is by all accounts very illiquid right now. It is not easy to buy bonds. But I think there is a case to be made for doing so, at the short end, and in the higher reaches of the junk spectrum.

NYPost : Here’s why Patagonia’s billionaire founder Yvon Chouinard is giving awa

Here’s why Patagonia’s billionaire founder Yvon Chouinard is giving away his company

Yvon Chouinard, the billionaire founder of the outdoor apparel brand Patagonia, said on Wednesday he is giving away the company to a trust that will use its profit to fight the climate crisis.

Instead of selling the company or taking it public, Chouinard, who became famous for alpine climbs in Yosemite National Park and has a net worth of $1.2 billion, is transferring his family’s ownership of the company to a trust and a non-profit organization.

“Each year, the money we make after reinvesting in the business will be distributed as a dividend to help fight the crisis,” he wrote in an open letter on the company’s website on Wednesday.

“Instead of extracting value from nature and transforming it into wealth for investors, we’ll use the wealth Patagonia creates to protect the source of all wealth.”

Patagonia will continue to operate as a private, for-profit corporation but the Chouinard family, which controlled the company until last month, no longer own the company, according to the New York Times, which reported the move earlier on Wednesday.

The company’s voting stock is being transferred to the Patagonia Purpose Trust while non-voting stock had been given to the Holdfast Collective, a non-profit dedicated to fighting the environmental crisis and defending nature. The trust will be overseen by members of the family.

While rich individuals often make financial contributions to causes, the New York Times said the structure of the Patagonia founder’s action meant he and his family would get no financial benefit – and in fact would face a tax bill from the donation.seen by members of the family.

>>> US After Hours Summary: FDX -15.1% on guidance; UPS -5.5% in sympathy with F

After Hours Summary: FDX -15.1% on guidance; UPS -5.5% in sympathy with FDX; RBLX -1.8% on August metrics, BOWL +7.9% on earnings and stock offering

After Hours Gainers:

Companies trading higher in after hours in reaction to earnings/guidance: BOWL +7.9% (reports JunQ results, stock offering by selling shareholders)

Companies trading higher in after hours in reaction to news: GEVO +1.2% (breaks ground on its facility), CELU +0.9% (stock offering), EPC +0.1% (organizational changes)

After Hours Losers:

Companies trading lower in after hours in reaction to earnings/guidance: FDX -15.1%

Companies trading lower in after hours in reaction to news: UPS -5.5% (trades in sympathy with FDX), RBLX -1.8% (reports August metrics), AMZN -1.7% (trades in sympathy with FDX), MEOH -0.6% (approves share repurchase program), NVTA -0.4% (experts support testing for cancer patients), KRC -0.1% (mixed securities offering)