WWD : Inside Celine’s New Paris Boutique

Inside Celine’s New Paris Boutique
The brand expanded its haute parfumerie to create a sleek space dedicated to accessories and high jewelry.
PARIS — Celine has unveiled its new boutique on Rue Saint-Honoré.
Hedi Slimane’s brutalist vision is brought to life with sleek brass and slick marble, a wall of mirrors and art installations. Located at 384 Rue Saint-Honoré, the shop is devoted to accessories, fragrance, leather goods and high jewelry, sitting catty corner from its ready-to-wear boutique on Rue Duphot.
The smaller space located at 390 has housed the brand’s haute parfumerie since 2019. Celine took over the old Loewe space next door to create a showcase for its classic Triomphe bags, leather goods and jewelry. In Slimane’s rock-‘n’-roll style, a sparkly gold version of the bag is exclusive to this location, as well as made-to-order pieces.

The new address marks the brand’s sixth stand-alone store in Paris, alongside spots in four of the city’s department stores. The brand says it is embarking on an expansion plan for 2023, and will activate several pop-ups worldwide. There are 180 Celine boutiques across the globe.
The second story private shopping apartment.
Up a gleaming curved staircase, the second floor houses a private salon with cozy chairs and a fireplace for VIP clients. In Slimane style, the boutique showcases several stunning artworks — paintings by Will Boone, sculptures from Ian L.C. Swordy and carved wooden pieces from Augustas Serapinas dot the space.
The 1,400-square-foot space has double-height windows, and beams of sunlight dance off the art pieces Slimane selected. Hanging in the main room is a version of Virginia Overton’s Skylight Gems, a mobile made of three glass ornaments, commissioned by Slimane after he saw the original in New York’s LaGuardia airport.
Virginia Overton’s “Skylight Gems” for Celine.
Taking cues from Art Deco and French Modernism, the now-connected boutiques sourced their black marble floors from France’s Pyrenees mountains, and Slimane selected several brutalist slabs and stumps for seating and decor.
The opening on Dec. 2 was timed just ahead of the brand’s big return to the womenswear runway. Celine closed Paris Men’s Fashion Week in June. It will stage a show at Los Angeles’ Wiltern Theater Thursday to present its fall 2023 collection, giving the brand a jump on February’s fashion season. If Celine will present at Paris Men’s Fashion Week in January has yet to be decided.

>>> US Research Calls

Research Calls

  • Upgrades:
    • Becton Dickinson (BDX) upgraded to Neutral from Sell at Citigroup; tgt raised to $250
    • Best Buy (BBY) upgraded to Neutral from Sell at Goldman; tgt raised to $83
    • Box (BOX) upgraded to Overweight from Neutral at JP Morgan; tgt raised to $34
    • CAE (CAE) upgraded to Overweight from Equal-Weight at Morgan Stanley
    • Crane (CR) upgraded to Overweight from Equal-Weight at Morgan Stanley; tgt raised to $129
    • Glaukos (GKOS) upgraded to Buy from Neutral at Citigroup; tgt $57
    • Lam Research (LRCX) upgraded to Buy from Hold at Deutsche Bank; tgt raised to $520
    • Monday.com (MNDY) upgraded to Overweight from Neutral at JP Morgan; tgt raised to $140
    • PerkinElmer (PKI) upgraded to Buy from Neutral at Citigroup; tgt raised to $170
    • Pulmonx (LUNG) upgraded to Buy from Neutral at Citigroup; tgt lowered to $10
    • QuidelOrtho (QDEL) upgraded to Buy from Neutral at Citigroup; tgt raised to $125
    • Southern (SO) upgraded to Outperform from Peer Perform at Wolfe Research; tgt $76
  • Downgrades:
    • Accenture (ACN) downgraded to Underweight from Neutral at Piper Sandler; tgt $268
    • llogene (ALLO) downgraded to Underperform from Buy at BofA Securities; tgt lowered to $9
    • Baxter (BAX) downgraded to Neutral from Buy at Citigroup; tgt lowered to $58
    • Boyd Gaming (BYD) downgraded to Mkt Perform from Mkt Outperform at JMP Securities
    • Brinker (EAT) downgraded to Sell from Neutral at Goldman; tgt lowered to $28
    • Cheesecake Factory (CAKE) downgraded to Sell from Neutral at Goldman; tgt lowered to $29
    • Curtiss-Wright (CW) downgraded to Equal-Weight from Overweight at Morgan Stanley; tgt raised to $188
    • Genuine Parts (GPC) downgraded to Sell from Neutral at Goldman; tgt raised to $147
    • HEICO (HEI) downgraded to Equal-Weight from Overweight at Morgan Stanley; tgt lowered to $172
    • Illumina (ILMN) downgraded to Sell from Neutral at Citigroup; tgt lowered to $180
    • Johnson Controls (JCI) downgraded to Neutral from Buy at BofA Securities; tgt lowered to $72
    • KLA Corporation (KLAC) downgraded to Hold from Buy at Deutsche Bank; tgt raised to $400
    • Laboratory Corp (LH) downgraded to Neutral from Buy at Citigroup; tgt lowered to $250
    • Leggett & Platt (LEG) downgraded to Underweight from Neutral at Piper Sandler; tgt lowered to $24
    • Micron (MU) downgraded to Hold from Buy at Deutsche Bank; tgt lowered to $55
    • Moog (MOG.A) downgraded to Underweight from Equal-Weight at Morgan Stanley; tgt raised to $89
    • Nevro (NVRO) downgraded to Equal Weight from Overweight at Wells Fargo; tgt lowered to $43
    • OceanFirst Finl (OCFC) downgraded to Neutral from Overweight at Piper Sandler; tgt $25
    • Qualcomm (QCOM) downgraded to Underweight from Equal Weight at Wells Fargo; tgt $105
    • RH (RH) downgraded to Sell from Neutral at Goldman; tgt lowered to $215
    • RxSight (RXST) downgraded to Equal Weight from Overweight at Wells Fargo; tgt lowered to $14
    • Spire (SR) downgraded to Underperform from Neutral at BofA Securities; tgt lowered to $61
  • Others:
    • Affimed Therapeutics (AFMD) initiated with a Buy at H.C. Wainwright; tgt $6
    • Ageas SA/NV (AGESY) initiated with a Sell at Goldman
    • Ambarella (AMBA) initiated with a Positive at Susquehanna; tgt $90
    • Analog Devices (ADI) initiated with a Positive at Susquehanna; tgt $205
    • Coinbase Global (COIN) initiated with a Sector Weight at KeyBanc Capital Markets
    • Elekta AB (EKTAY) initiated with a Sell at Citigroup
    • Essilor International (ESLOY) initiated with a Buy at Citigroup
    • Kinsale Capital (KNSL) initiated with a Hold at Jefferies; tgt $295
    • Palomar Holdings (PLMR) initiated with a Hold at Jefferies; tgt $55
    • Smith & Nephew (SNN) initiated with a Buy at Citigroup
    • Sonova (SONVY) initiated with a Sell at Citigroup

>>> US Gapping down

Gapping down
In reaction to earnings/guidance
:

  • NOTV -24.8%

Select biotech/pharma related names showing weakness after ASH presentation or other data release:

  • ACET -36.4%, AFMD -15.2%, ONCT -6.5%, IGMS -2.7%, GRPH -1.5%

Other news:

  • ABCM -8.4% (provides update on AIM Delisting)
  • IDYA -4.2% (submission of IND Application to the U.S. FDA for PARG development candidate IDE161)
  • AMGN -3.1% (confirms it will acquire HZNP for $116.50/share in cash)
  • RIVN -2.5% (pauses partnership discussions with Mercedes-Benz on electric van production in Europe)
  • NOAH -2.4% (recently received a civil judgment from the Bozhou Intermediate People's Court of Anhui Province)
  • HP -1.1% (increased the maximum number of shares authorized to be repurchased in calendar year 2023 to five million common shares)
  • ACI -0.8% (Issues Statement Regarding the Denial of a Request for Preliminary Injunction by the Attorney General of the State of Washington and Extension of the Temporary Restraining Order on its Special Dividend Payment)

Analyst comments:

  • ACN -2% (downgraded to Underweight from Neutral at Piper Sandler)
  • BYD -0.8% (downgraded to Mkt Perform from Mkt Outperform at JMP Securities)

>>> US Gapping up

Gapping up

Select biotech/pharma related names showing strength after ASH presentation or other data release:

  • GRCL +6%, ARGX +4.2%, ALVR +3.8%, PSTX +3.5%, DTIL +3.4%, CNTA +3.1%, ADPT +2.1%, BEAM +1.6%, IMGN +1.4%, CTIC +1.1%, COGT +1.1%, GLYC +1%

Other news:

  • COUP +26.8% (to be acquired by Thoma Bravo for $81/share, enterprise value of $8 billion; also issued earnings)
  • WEBR +21.5% (to be taken private by BDT Capital Partners for $8.05/share; deal expected to close in 1H23)
  • HZNP +15.4% (Amgen (AMGN) confirms it will acquire HZNP for $116.50/share in cash; no longer in merger discussions with Sanofi (SNY))
  • BVH +10.4% (Amendment of Tender Offer to Increase Offer Price to $25.00 per Share and Extend Tender Offer Until December 23)
  • CNX +2.5% (provides update on Appalachia-Focused strategy)
  • BSX +1.2% (announces strategic investment to acquire majority stake of Acotec Scientific Holdings)

Analyst comments:

  • BOX +3.7% (upgraded to Overweight from Neutral at JP Morgan)
  • GKOS +1.9% (upgraded to Buy from Neutral at Citigroup)
  • BBY +1.8% (upgraded to Neutral from Sell at Goldman)
  • CR +1% (upgraded to Overweight from Equal-Weight at Morgan Stanley)
  • BDX +0.9% (upgraded to Neutral from Sell at Citigroup)

>>> US Early premarket gappers

Early premarket gappers

  • Gapping up:
    • COUO +26% GRCL +17.9%, HZNP +13.7%, BVH +6.8%, ALVR +5%, ARGX +4.8%, DTIL +3.4%, CNTA +3.1%, BEAM +2.1%, FATE +1.6%, BSX +1.2%, COGT +1.1%, OCUL +1.1%, CTIC +0.9%, REGN +0.7%, VRTX +0.6%, GMAB +0.5%, MSFT +0.5%
  • Gapping down:
    • ONCT -14%, ACET -13.7%, LVTX -9.5%, ABCM -6.7%, RIVN -4.8%, IDYA -4.2%, AMGN -3.1%, IGMS -2.7%, GRPH -2.7%, ACI -2.3%, AFMD -2%, ADPT -1.8%, IMGN -0.8%, SGMO -0.6%

FT : Has the index effect evaporated?

Has the index effect evaporated?
Featuring Lloyd Blankfein cameo appearance

Can those lamenting/celebrating/gawping at the not-so-slow-motion car crash of Elon Musk’s Twitter ownership really blame the benchmarking wizards of S&P Dow Jones Indices for the whole debacle?

That’s what a lot of people reckon. When Tesla finally managed to notch up four consecutive quarters of profit in the summer of 2020 and became eligible for inclusion into the S&P 500, it helped spark a wild ride that made it one of the world’s most valuable companies. That transformed Musk into the world’s wealthiest edgelord and allowed him to buy Twitter.

It’s easy to forget that at the start of 2020 Tesla was valued at just $77bn (which even at the time felt punchy). By the end of the year Tesla’s market capitalisation had exploded to $669bn. A year ago it had reached a peak of $1.2tn, and even after the tech wreck of 2022 Tesla is still worth $565.4bn.

This is why a new NBER working paper from Robin Greenwood and Marco Sammon from Harvard Business School is so interesting (it also thanks Lloyd Blankfein, among others, for “helpful comments”). Here is its main findings:

  • The abnormal return associated with a stock being added to the S&P 500 has fallen from an average of 3.4% in the 1980s and 7.6% in the 1990s to 0.8% over the past decade. This has occurred despite a significant increase in the percentage of stock market assets linked to the index. A similar pattern has occurred for index deletions, with large negative abnormal returns on average during the 1980s and 1990s, but only -0.6% between 2010 and 2020.

In other words, the impact of index inclusions and deletions is pretty much statistically indistinguishable from zero. This runs completely counter to popular perception. It obviously makes intuitive sense that several trillion dollars worth of price-insensitive funds suddenly having to buy an included stock would lift it higher.

It should also be pointed out that although all perceived market evils are laid at the feet of index funds, indices have a powerful sway over traditional active funds as well. In fact, we suspect that stockpickers are on average nowadays far more “index aware” than they were back in the day. Even if there were no passive funds, benchmark changes would therefore probably have a big impact (and let’s not forget the impact of index derivatives).

Just to take the Tesla example, S&P Dow Jones itself estimated that index funds would have to dump about $51bn worth of other stocks to make way for Tesla’s inclusion. We’ve even had the first case of alleged index inclusion insider trading.

But Greenwood and Sammon corroborate similar findings by Benjamin Bennett, René Stulz and Zexi Wang in 2020, who found that the long-run impact of inclusion into the S&P 500 had actually become negative.

So what’s up? Greenwood and Sammon explore five possible explanations:

1) The fading effect is caused by different types of companies being included and excluded in recent years compared to the past.

2) The stock market is more liquid nowadays and trading costs are lower, so the impact of index changes becomes more muted.

3) Changes in net demand are much lower than they might seem because companies typically migrate from one index to another. For example, the S&P MidCap index has become a far more popular index.

4) Benchmark changes have become more predictable, and attracted arbitrageurs who front-run buying and selling by index funds.

5) The stock market has become more efficient overall, and liquidity has migrated towards dates where index changes happen, and especially at the end of the day when index funds do most of their trading.

Related to that, here is a gif showing how the “liquidity smile” has turned into a lopsided “liquidity smirk” over the past decade.

Greenwood and Sammon favour the last two explanations, with most of the emphasis on the final one. Here is their tl;dr:

  • Overall, the findings suggest an account along the following lines. In the 1980s, index changes were unanticipated, index funds were small, and there was mispricing in the market. As index funds grew larger, the mispricing deepened and turned into an opportunity. As a result, the market adjusted to take advantage of this opportunity, in part by better anticipating inclusions, and in part by creating arrangements where other institutions stood ready to sell to indexers upon inclusions. This worked to eliminate the anomaly on average, in spite of demand shocks that continued to grow in magnitude over the 2000s and 2010s. In this sense, the decline of the index effect is much like the evidence for other anomalies, that they decline once they are well recognized by the market.

This makes sense, even if the researchers might be underestimating the arbitrage aspect a little. We wonder if the index inclusion effect would look more meaningful if one tweaked the time parameters. Index arbitrage has become a more popular hedge fund strategy in recent years, and that implies the inclusion effect is simply getting spread out over a longer time period.

Some final thoughts on the Tesla saga though, as it would seem to undermine the whole “disappearing index effect” argument. As with everything Musk-related, this is probably just a very idiosyncratic situation, with limited read-through elsewhere.

There are so many hardcore Elon stans and Tesla fans that have repeatedly seized on any excuse to pump shares in the company, from Mars mining to Tesla becoming an insurance giant. Even aside from how owning Tesla has made many rich, Tesla stock ownership has become an extension of their identity. And probable index inclusion is as good a reason as any to buy more.

A large part of the massive ramp-up in Tesla’s market cap was therefore probably the collision of a retail investor buying frenzy with a limited free-float, given a chunk of the Tesla investor base didn’t want to sell.

But here is what Tesla has done compared to Apartment Investment and Management — the company that was ejected from the S&P 500 to make way for Elon’s carmaker — since December 21, 2020, when the change went into effect:

(ZH) The Rise And Fall Of Inflation Risk Factors

The Rise And Fall Of Inflation Risk Factors

This week we will all focus on CPI on Tuesday and the Fed on Wednesday. What Chair Powell says and does on Wednesday will reverberate through the markets. For the record, I expect 50 bps and he will keep a rate hike on the table for the February 1 st announcement.
Rather than attempting to estimate this week’s CPI data (which will be important), today’s report will focus on what will drive inflation (and the economy/markets) after the Fed decision.
We have seven weeks between this FOMC decision and the next one. Seven weeks feels like a lifetime in a market that is prone to large daily and weekly swings. Even the views on the economy are shifting rapidly as more economists seem to be heading in our direction, which is that the recession will start sooner (Q1) and be deeper than most people previously thought.
If anything, the market is pricing in a Squishy Landing. That report tried to define a “squishy” landing and also tried to figure out why markets may misinterpret data as indicating a “soft” landing when the worst is yet to come. Finally, we re-iterated our more pessimistic outlook in that report.
Inflation Factors versus Inflation
Rather than just trying to “estimate” inflation, we examine the factors that “drive” inflation. While we could just estimate various inflation components such as rent, in this report, we will try something different. We will lay out the factors that drive inflation. We believe that these factors do a good job of predicting where inflation and the economy are headed
In theory this is what many do, but we hope that today’s analysis makes it clear how these factors have been behaving (and how they will behave). That will go a long way in explaining why our current outlook is more pessimistic and is strongly in the camp that “the Fed has gone too far already.”
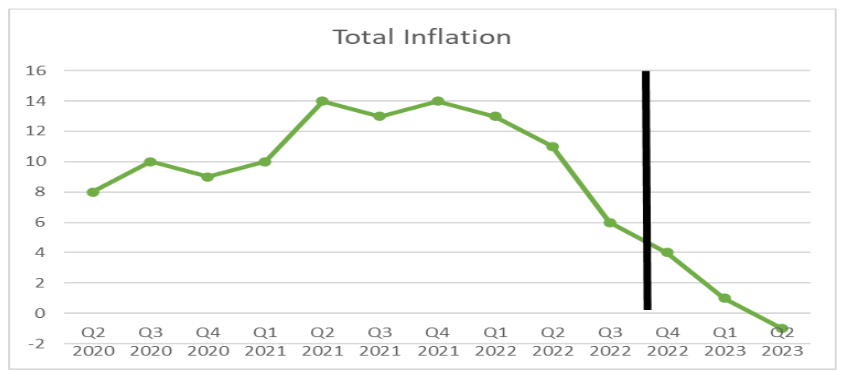
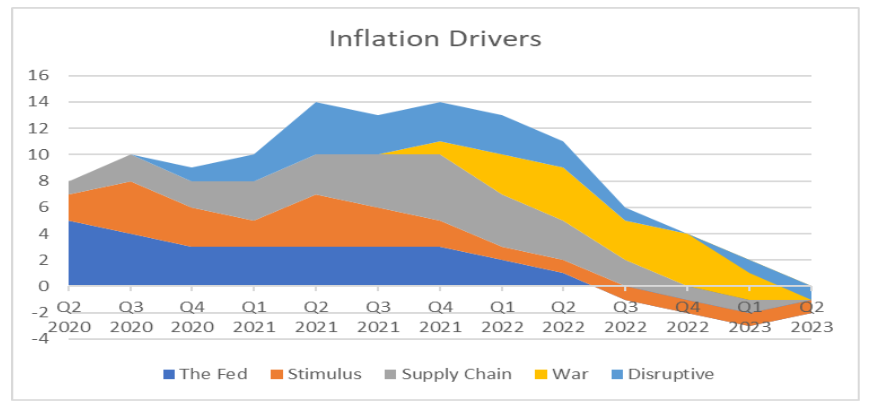
We will address the individual components that go into this model. This model shows the highest inflationary pressures were from Q2 2021 to Q4 2021. It remained elevated for that extended period of time due to a variety of factors (the importance of which changed within that period). The factors have been pointing to steadily declining inflation and growth pressures ever since.
If anything, the factors point to deflationary pressures in Q1 and Q2 next year – which is another way of reaching our conclusion that the economy and markets are in jeopardy of a large “risk-off” trade that will break 2022’s lows on stocks (while yields plummet).
The Inflation Factors
We will use 5 factors. The factors are somewhat broad and the influence that they have on inflation is just an estimate. Yes, inflation and the economy are closely linked. No, our model is not tested and is both arbitrary and subjective. Nonetheless, it seems logical and almost elegant. The explanation fits the narrative of what has been going on, and some version of this “model” has been influencing my thoughts on inflation, the economy, and markets. It is a good starting point for this overall discussion and what to expect in terms of economic data and corporate reporting over the next seven weeks.
The factors that we use are:
  • The Fed. This is primarily focused on rates and the balance sheet. Lower rates are stimulative and higher rates act as a headwind. Balance sheet expansion (QE) is stimulative while balance sheet reduction (QT) is contractionary. Other “extraordinary” measures are included as well.
  • Stimulus. This includes a range of items such as checks sent to individuals, moratoriums on rent/student loans, PPP, and government spending programs like the “Inflation Reduction” Act.
  • Supply Chains. This attempts to broadly incorporate supply chain issues from the actual inability to produce goods to the costs of shipping and transporting. It is difficult to get an exact definition, but we all know it when we see it.
  • War. Russia’s invasion of Ukraine and the sanctions are also factors.
  • Disruptive. Another broad topic and not only is it extremely important, but it has been overlooked by many. It does not just include the wealth gained and lost by investors or the impact on the economy. The spending generated by “disruptive” companies (and even units of larger/more “traditional” organizations) was quite simply massive. This segment can easily include crypto as well as disruptive companies (some of which were already public or recently went public, and others largely benefitted from PE/VC investments). This may be the most contentious factor, which likely makes it the most important in terms of explaining why our outlook remains so pessimistic.
We did not treat wage inflation as an inflation factor. This is a tricky and almost circular issue. Is wage inflation a factor? Certainly, the Fed focuses on wage inflation because it could potentially create “sticky” (or rather “non-transitory”) inflation. From that perspective, it is a factor rather than an output. However, we will treat wage inflation as another output (wage inflation will respond to the other factors, making it okay to ignore in the factor model). It is somewhat circular, which is why we highlight it.
The Fed
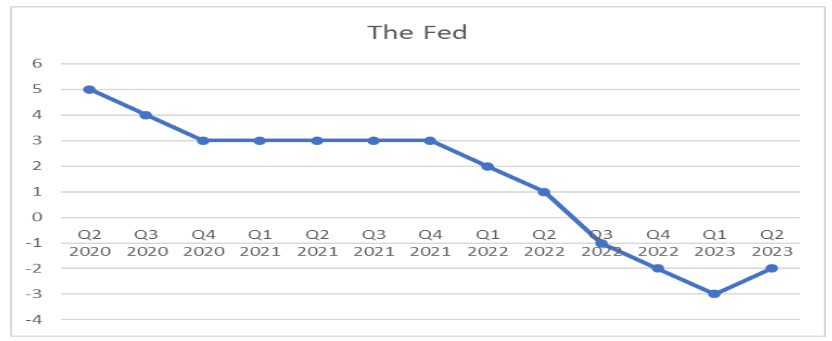
The Fed did everything it could in the immediate aftermath of COVID and the COVID lockdowns. They bought corporate bonds/ETFs, backstopped money markets and corporate new issuance, expanded their balance sheet, and cut rates to zero.
Over time they pulled back on that support. By Q3 of 2022 we saw them acting as a moderate headwind. We should not just expect higher rates for now because the Fed is telegraphing higher rates into the future (while ramping up QT) as well.
By early 2023 the Fed will be a deflationary pressure.
That will start to reverse course as the Fed backpedals (likely smaller QT before rate cuts). In any case, on a standalone basis this might be the right policy, but given how the other factors are behaving, it may be a mistake.
Stimulus
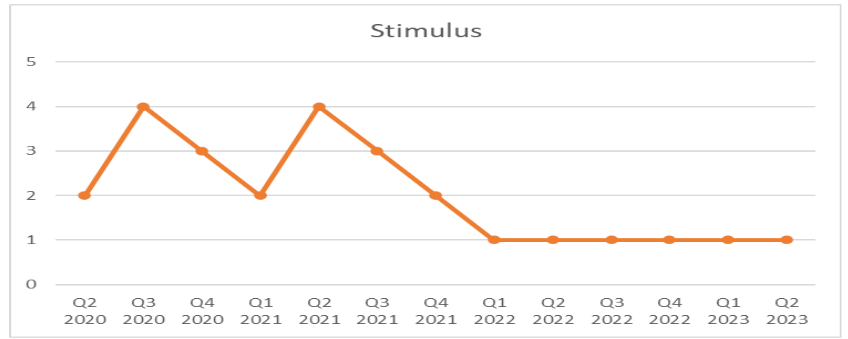
Stimulus started slowly, ramped up, tailed off, ramped back up again, and is now in the process of declining. We’ve left it as a small positive factor for much of this year and next year.
The bump in Q2 2021 may have been the most awkward of the inflation drivers as yet another stimulus package was passed long after there was an obvious need for it (the very nature of inflationary).
We didn’t get a “bounce” in the factor when the so-called “Inflation Reduction Act” was passed, because it wasn’t heavily front loaded, but it is why we leave stimulus as a positive factor going forward.
Supply Chain
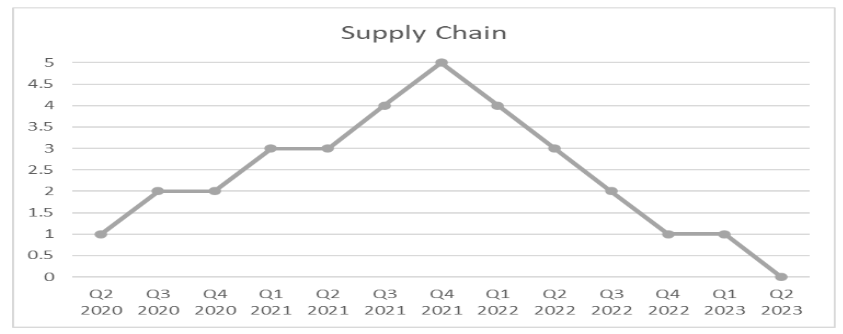
The supply chain issues didn’t manifest themselves right away. In Q2 2020 oil (WTI) futures briefly traded negative. Yes, there were all sorts of weird shortages and mismatches during that time. You could get rolls and rolls of industrial grade toilet paper if you could figure out where to go, but it was virtually impossible to get high quality toilet paper (I’m sure there were other initial issues, but that one sticks out).
It was only over time as we re-opened and inventories got whittled down that supply chain issues started to mount. Add to that the fact that there weren’t enough workers at the docks to unload (let alone ship) things. Supply chain constraints were off the charts (as was the cost of shipping). However, those costs have since come down.
There are still some supply chain issues. Shipping isn’t great, but other issues are much smaller now. Offsetting that pressure further are the inventory builds that we’ve seen across so many industries. It is still a moderately inflationary factor, but should go away by Q2
War
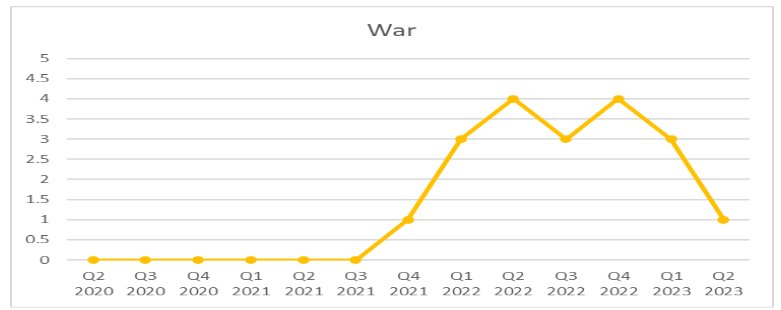
Russia invaded Ukraine in Q1 2022, but as troops were building up before that, we started to see some pressure on commodity prices that could be attributed to the war risk. That escalated post invasion as sanctions took hold. It abated a little in the summer on the energy front (seasonal) and as some deals were attempted on the commodity front. It has ramped back up and that will continue into Q1 of next year and then it should subside into the summer again.
Disruptive
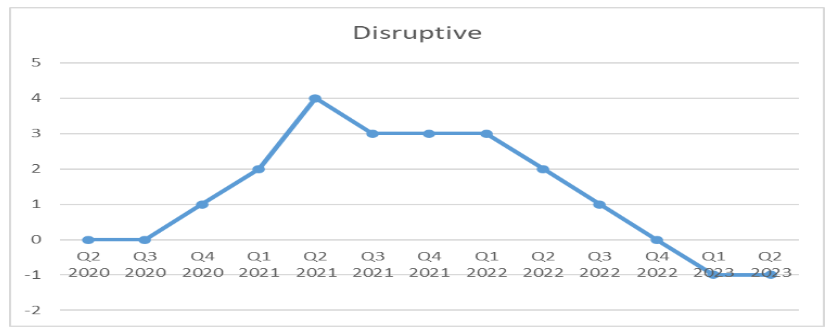
This doesn’t exactly follow the chart of bitcoin, ARKK, or SPAC issuance, but it is probably somewhat linked. Were those just a factor of the other factors, or a factor in their own right?
The wealth created and spent in this subset of the universe (which was unique to this period) is its own driver. It ties into my argument that jobs lost will NOT be the metric of this recession, rather it will be jobs lost multiplied by average pay that will define this recession.
I’m hearing this from programmers, software and hardware sellers, and event planners. The wealth created and spent was enormous, concentrated, and inflationary.
The Whole Picture
This chart might be a little bit messy, but it is a useful illustration of how these various factors have worked to drive inflation.
Thinking about these factors and when they started to turn down (and how inflation/the economy have followed) sends a somewhat chilling message if they are correct.
We are seeing little to no inflationary (growth) pressures in the economy in Q1, yet we are behaving as though fighting inflation is still job number 1.
Bottom Line
Look for growth and inflation to slow, regardless of what the Fed does going forward. Inflation was driven by many factors, most of which are receding on their own.
We have seven weeks of data after this Fed meeting and will be entering into Q4 earnings. I have little reason to be optimistic unless something about these risk factors change. It would be great to have discussions on the appropriateness of these factors and their relative importance.
This model may have many errors, but I welcome the opportunity to discuss/refine it and hopefully it gives you some food for thought on why our inflation and growth projections are on the pessimistic side of consensus.
Good luck on Wednesday and get ready for the next 7 weeks!

(ZH) Dupe Or Designated Defendant? The Criminal Case Against Jack Dorsey

Dupe Or Designated Defendant? The Criminal Case Against Jack Dorsey

The latest Twitter disclosures have raised potential legal liability for Twitter and its executives. No one appears more at risk than Twitter’s former CEO Jack Dorsey
It is an ironic turn of events since Dorsey supported the takeover by Elon Musk and has called for all files to be released without filtering. Dorsey has the feel of a “designated defendant,” someone who was pushed forward by others to take any legal hit.
On its face, Dorsey has vulnerability after the latest release. He was repeatedly asked by members of Congress about censoring and shadow-banning, which has now been confirmed in these files.
In September 2018, Dorsey testified under oath and denied what these files appear to now confirm. Rep. Mike Doyle, D., Pa., asked, “Social media is being rigged to censor conservatives. Is that true of Twitter?”
Dorsey responded, “No.”
Doyle then asked “Are you censoring people?”
“No,” Dorsey said.
“Twitter’s shadow-banning prominent Republicans… is that true?” Doyle asked.
Dorsey again said no.
Dorsey was also asked about my prior testimony on private censorship in circumventing the First Amendment as a type of censorship by surrogate. Dorsey and the other CEOs were asked about my warning of a “‘little brother’ problem, a problem which private entities do for the government that which it cannot legally do for itself.” In response, Dorsey insisted that “we don’t have a censoring department.”
It now appears that the entire company was operating as a censoring department. However, there were in fact super-censors. Dorsey did not mention the Strategic Response Team-Global Escalation Team (SRT-GET), which operated above what journalist Bari Weiss described as “a level beyond official ticketing, beyond the rank-and-file moderators following the company’s policy on paper.”
That group reportedly included Vijaya Gadde, head of Legal, Policy and Trust; Yoel Roth, the global head of Trust and Safety; CEOs Jack Dorsey and Parag Agrawal, and others.
Notably, others at the company made similar denials as Dorsey but may not have done so under oath. In 2018, Gadde and head of product Kayvon Beykpour expressly declared, “We do not shadow-ban. And we certainly don’t shadow-ban based on political viewpoints or ideology.”
Even if untrue, lying in public is generally not a crime. However, when you repeat a lie to federal investigators or Congress or the courts, it becomes a federal offense.
The question is whether Dorsey was left in the dark on these decisions. He was reportedly a member of SRT-GET. However, some of the files indicate that these decisions may have been made without his knowledge. That includes the decision on the Hunter Biden laptop scandal, which Dorsey called a “total mistake.”
Dorsey could quibble over the term “shadow-banning” but the question was obviously meant as a follow-up to the inquiry over “rigging” discourse on the platform. He could also stress other answers, where he tied “shadow-banning” to a more subjective notion of political bias. For example, Dorsey also repeated these statements in public, including an appearance with Sean Hannity on Fox, when he was asked if “Twitter has ever been involved in shadow-banning, Dorsey again categorically denied such practices: “We do not shadow-ban according to political ideology or viewpoint.”
For most people, Dorsey’s comments clearly suggested that there was no shadow-banning. However, he could claim that he knew that they were shadow-banning but that they were not doing so “according to political ideology or viewpoint.” That is clearly refuted by the new files showing a hair-triggered censorship system directed against conservative and Republican posters.
The other defense is lack of knowledge but, even if accepted, that will raise the question of whether this was a case of a designated defendant or willful blindness.
In some cases, there is a suspicion that corporations will assign some executive to sign off on compliance or certifications as the fall guy or designated defendant if things go wrong. The chump is often a junior lawyer or executive who takes personal responsibility for certifying a false fact.
Dorsey is clearly no chump or junior executive. The question is then whether this was a case of willful blindness or an attempt by other executives like Gadde or Roth to give him plausible deniability by keeping him in the dark. He then became the public face in unequivocally and confidently denying practices like shadow-banning.
The greatest defense for Dorsey may be found in the Justice Department itself. Any prosecution of Twitter executives could prove a hard sell for Attorney General Merrick Garland, whose department has been repeatedly accused of pronounced political bias.
While Garland has aggressively pursued contempt sanctions against Trump associates, it is not clear if he would prove as aggressive with Democratic allies like Dorsey or other Twitter executives. He could face that question if the House under the GOP pursues perjury or contempt sanctions.
Dorsey once said about Twitter that “It’s really complex to make something simple.” He may now be hoping that his answers before Congress were simple enough to make any prosecution complex.

(ZH) The Twitter Files: The Corporate Media Ignores The Biggest Story Of The Dec

The Twitter Files: The Corporate Media Ignores The Biggest Story Of The Decade
BY TYLER DURDEN
SUNDAY, DEC 11, 2022 - 09:00 PM
The biggest story of the past decade is not the covid pandemic, the January 6th protests, the war in Ukraine, the BLM riots, or even the stagflationary crisis in the US. Behind these major events is another story, one that connects them all together in a disturbing way. Even more important than the effects of geopolitical and economic chaos is the effect of mass censorship; without the free exchange of information and debate the public remains ignorant. And if the public remains ignorant, crisis events have an increasing potential to explode.
Public perception of national and international affairs is a key determinant of the outcome of disasters and conflicts. This is why governments and elitists from around the world often seek to manipulate the ways in which people digest information. The idea is rather simple – They believe that 'we the people' cannot be allowed to come to our own conclusions. They think we cannot be trusted to develop the “proper” viewpoints and we are not smart enough to understand the implications of governmental decisions.
In other words, they believe the exact opposite of what is outlined in the US Constitution. The establishment will give numerous reasons why they need to censor, suppress, spin and misrepresent the facts of any given situation, but in the end the real rationale is that they have a vision for society that is contrary to our foundations. They have appointed themselves the arbiters of reality to see that vision done. As Edward Bernays, the “father of public relations” once stated in his book 'Propaganda':
“The conscious and intelligent manipulation of the organized habits and opinions of the masses is an important element in democratic society. Those who manipulate this unseen mechanism of society constitute an invisible government which is the true ruling power of our country. ...We are governed, our minds are molded, our tastes formed, our ideas suggested, largely by men we have never heard of. This is a logical result of the way in which our democratic society is organized. Vast numbers of human beings must cooperate in this manner if they are to live together as a smoothly functioning society. ...In almost every act of our daily lives, whether in the sphere of politics or business, in our social conduct or our ethical thinking, we are dominated by the relatively small number of persons...who understand the mental processes and social patterns of the masses. It is they who pull the wires which control the public mind.”
This is pure authoritarianism. It's the stuff of nightmares and revolutions. But for many years now a large subsection of the world has denied such a dynamic exists. It's “conspiracy theory” and “tinfoil hattery” to claim that a small number of elites work together in secret to control public perception and govern our society from the shadows. After all, where is the proof?
Of course, this kind of argument is a coping mechanism for the mentally deficient. Proof of such secretive governance and control is everywhere these days, but some people prefer willful denial. Take for example the ongoing data drops for what is now being called “The Twitter Files.”
The mainstream media is barely responding to the information dump initiated by Elon Musk. They seem to be far more interested in Donald Trump's tax records. When they are forced to acknowledge the story, they are hostile, calling the information “boring” or unimpressive. It's a classic psychological tactic of typical narcissists and criminals – When they get caught, they act indifferent, as if neither the evidence nor their crimes really matter. If getting caught doesn't matter to them, then their crimes must not be all that bad, right?
The content of these files is astonishing, but at the same time it is true that the conclusions are not surprising.
The files simply confirm almost everything conservative and libertarian commentators have been saying for years; all those “conspiracy theories” about Big Tech censorship of conservatives turned out to be true. Not only that, but the theory that government agencies and officials from the DNC worked with Big Tech to silence and undermine their political opponents was also true.
Twitter has long denied that they “shadow ban” users, but this was a lie. The data shows that small groups within Twitter called “strategic response teams” suppressed up to 200 accounts per day. Usually these were accounts of larger and more influential conservative politicians and celebrities. And, these teams operated in coordination with Democrat officials and agencies like the FBI. In some cases the goal was to mute a particular individual. In other cases the goal was to steer national elections.
Internal Twitter communications show that SRT groups spent most of their time fabricating reasons why certain information was subject to TOS. In other words, if Twitter's rules were not being violated, they made up new rules.
The exposure of Twitter is the biggest story of the decade because it provides proof of a hidden cabal. It shows the ugly mechanics behind the scenes and exposes a network of elites and their errand boys who were involved in direct operations to destroy the 1st Amendment for the sake of ideological supremacy.
It's the classic definition of fascism, a definition that Benito Mussolini reiterated when he argued: “Fascism should more properly be called corporatism because it is the merger of state and corporate power.”
And, if this brand of Fascism was happening within the halls of Twitter, then there is little doubt it is also happening at companies like Google/YouTube, Apple, Facebook, etc. Before we had evidence, now we have confirmation.
The corporate media argues over relevance instead of morality because they benefited from the censorship. It's important to remember that one of the first measures Big Tech companies applied after suppressing the alternative media during the pandemic was to then amplify the corporate media. These companies are floundering with dismal audience numbers and dwindling profits. No one listens to them anymore. Yet, as long as they promote the establishment narrative their opinions and disinformation are given priority on nearly every search engine and social media platform.
Of course they aren't interested in the Twitter Files, liars are often “bored” by honest commentary and factual information. Also, their continued existence relies on the censorship of their competition in the alternative media.
The bottom line is this: According to the Bill of Rights, it is illegal for agents of the US government to obstruct the free speech of law abiding American citizens. It does not matter if the action is done by using “private businesses” as middlemen. And, if a private business is colluding with government to implement political policy then it is no longer a private business. Twitter was participating in a form of treason, along with the agencies that they cooperated with. It's a huge story, and one that should lead to punishment for those involved.

Business Of Fashion : How Hedi Slimane Doubled Celine Sales

How Hedi Slimane Doubled Celine Sales
The brand, which has surpassed €2 billion in annual revenue, celebrated its momentum with a fashion show-meets-concert in Los Angeles, where the biggest rock star was arguably the designer.

LOS ANGELES — On Thursday night, as a cold(ish) spell passed through Southern California, the designer Hedi Slimane lit up the facade of the Wiltern, an art deco theatre in Hollywood, with the name Celine, manufacturing a fashion show-meets-rock concert straight out of 2005.

The crowd consisted not of fashion industry people, but friends-of-the-house types. Iggy Pop, Interpol and The Strokes all performed. The Kills’ Jamie Hince and Alison Mosshart DJed. The White Stripes frontman Jack White created the “original soundtrack” that ran on repeat during a runway show populated with idealised takes on the looks that epitomised the era, from kneecap-tight skinny jeans to slouchy boots and ruffled blouses — even a version of the dropped-hem mini so ubiquitous at the time. (Only Pete Doherty, one of the period’s most memorable, and maniacal, rock stars, was missing.)

Slimane called the outing the “Age of Indieness.” Back in the mid-aughts, the then-Dior Homme designer’s skinny silhouettes were made for men, even if they were also worn by adventurous women. Now, he’s mining the look — rebranded “indie sleaze” by the TikTok generation — to create women’s pieces he might have dreamed up 20 years ago.

But Slimane’s continuous playing of the same backbeat has proven to be a valuable asset. For this performance, he once again sold the audience — including several rows of celebrities, from Sonic Youth’s Kim Gordon to “Top Gun: Maverick” star Miles Teller to Dustin Hoffman — on sequined gold dresses, little collarless jackets and military capes, now inflected with the 1970s bourgeois sensibilities in the DNA of Celine, where Slimane has more than doubled sales since his arrival.

Celine doesn’t have as rich a history, nor as many recognisable brand signifiers, as Saint Laurent, the Kering-owned house that Slimane rebuilt in the 2010s. And yet, this year, it is expected to generate at least €2.2 billion ($2.3 billion) in annual revenue, according to analysts, just meeting the target set by LVMH chief executive and chairman Bernard Arnault in 2018. That’s despite a rocky start — Slimane’s radical overhaul of the brand upset devotees of former designer Phoebe Philo — and the shock of the pandemic.

While LVMH does not break out revenue figures for its brands, Celine did share that revenue has multiplied 2.5 times since Slimane’s arrival, with growth across all categories and regions, even in struggling China. In mature markets like Europe and Japan, sales have doubled. In the United States, where the brand was historically unrepresented, they have tripled. And not only are there more customers, but they are younger than they used to be.

“He’s consistent, and the customer today values consistency more than ever,” said Robert Burke, a retail advisor. “They don’t want to look like a fashion victim. There’s some certainty, stability, with Celine.”

For Slimane, there’s no other way of working. “You can only be one thing and only want to be one thing or remembered for one thing … you can only be lucky enough to have one style, a style of your own that becomes a caricature of you, your own ‘sound,’” the designer told journalist Lizzy Goodman during a November 2022 conversation that appeared in a hard-cover pamphlet sent out by the brand. (He also collaborated with Goodman on a poster for the documentary based on her book, “Meet Me in the Bathroom: Rebirth and Rock and Roll in New York City 2001-2011.”) “I’m probably synonymous [with] punk rock and indieness in fashion, beside being known for my androgynous models. I have been precisely this in fashion for more than 20 years. This is the caricature I gladly own.”

At Celine, Slimane’s insistence on consistency is evident in the way he has developed each category. The brand’s handbag offering still includes successes from Philo’s tenure — her Belt bag remains the best seller at Neiman Marcus, for instance. But from removing the accent on the “e” on each bag’s name stamp, to introducing new styles that look at once familiar and fresh, every little bit now reflects his exacting vision.

Burke cited the Ava, a banana-boat shoulder bag that starts at just $990, as a standout, although the Triomphe line, a series of flap bags with a double-C clasp — featured heavily in the show — is now the brand’s top-selling leather-goods range. Part of the allure may be Celine’s relatively low reliance on logos, especially as some shoppers back away from obvious branding: the Triomphe symbol, which has been inserted into sunglasses and belts, too, has a vintage, fairly understated quality.

“Our customer is embracing the idea of a more subtle logo,” said Lana Todorovich, chief merchant at Neiman Marcus.

But it’s not only the bags that are selling. Women’s ready-to-wear has also grown significantly this year in particular, according to multiple retailers. At Neiman Marcus, for instance, sales of Celine ready-to-wear have tripled since 2019.

“When we came out of the pandemic, there was a desire to celebrate in an extroverted way,” Todorovich said. “Now, a normalised way of approaching fashion is coming back.”

Slimane’s talent is in making the best-in-class version of “normal,” everyday items — vintage Levi’s, a trench, a blazer — or the types of things that most luxury shoppers don’t have the patience, or acumen, to thrift. At Celine, he has restructured the atelier into two divisions — tailoring and flou — to allow for the development of couture-level garments, which account for roughly 20 percent of the overall runway collection.

And like most other top-tier fashion brands, Celine has ventured further and further into the highest end of pricing, not only with accessories — such as the personalised Haute Maroquinerie Triomphe, with hardware made of 18k gold — but also through the couture-like pieces it designs for its growing list of private clients.

A show in Los Angeles, where Slimane lived for almost a decade until 2016, highlights the importance of the US market, which has played an outsized role in top-line growth for luxury brands in recent years. But it was also something of a celebration of Celine’s momentum.

“Where Celine is today and where it was a few years ago is night and day,” Burke said. “They’ve nurtured it, and now it’s able to stand on its own.”