Barron’s Weekend Summary: The world has stopped worrying about Covid—and Pfizer is paying the price.
Cover Story:
The world has stopped worrying about Covid—and Pfizer is paying the price. The sales of its two Covid blockbusters may decline over 60% in 2023, after generating a combined $57B in revenue during 2022. And there is considerable uncertainty about demand for both in the coming years. Pfizer stock, too, has fallen out of favor, along with other Covid plays. At $44, it’s down 15% this year, making it one of the worst performers in the S&P 500 SPX -1.04% index. And it’s 30% below its late 2021 peak, badly trailing the rest of the drug group. And therefore: Now looks like the time to buy the stock. Pfizer trades for 13 times projected 2023 earnings and yields 3.7%, more than double the S&P’s dividend rate. The payout, backed by ample earnings and one of the industry’s best balance sheets, looks very safe.
Interview:
Jurrien Timmer, director of global macro at Fidelity Investments, sees himself as a storyteller, connecting the dots between history and current economic trends to get a sense of where markets are headed. Although stocks are much cheaper today than they were a year ago, he worries that U.S. investors are still too sanguine about the outlook for the economy and corporate profits. In other words, they’ve bought into a just-right, or Goldilocks, scenario that seems unlikely to play out. Timmer is part of the firm’s global allocation team that oversees $586B. He expects non-US stocks to outperform this year, and bonds to reward investors as inflation and interest rates return to more normalized levels. Timmer recently spoke with Barron’s about the challenges and opportunities that lie ahead for investors, and why the next 10 years won’t resemble the zero-interest-rate era just past. An edited version of the conversation follows.
Tech Trader:
-The Federal Reserve’s aggressive campaign to raise interest rates may be about to end-and the market’s pendulum has swung decisively back to greed from fear. Just like the good old days. C3.ai AI +18.07% (ticker: AI) shares have doubled over the last month, I suspect largely because they have the ticker symbol AI—and there’s nothing hotter right now than all things AI. Avaya Holdings AVYA +2.56% (AVYA), an old school telecom hardware company on the verge of bankruptcy, has nonsensically doubled since year-end. The triple-digit gainers include battered merchandise like home goods seller Wayfair W –7.70% (W), buy-now-pay-later financing outfit Affirm AFRM –14.14% (AFRM) and, of all things, Coinbase Global COIN –8.38% (COIN), the cryptocurrency trading house. Makes you wonder if SPACs are about to make a comeback.
The Trader:
-The jobs data confirmed is that it’s tough to see a recession, no matter how hard you squint. The release on Friday morning showed that the U.S. economy added a seasonally adjusted 517,000 nonfarm payrolls in January, more than doubling the job growth expected by economists. The unemployment rate at 3.4% is at a nearly 54-year low. Despite that, average hourly wages increased by 4.4% year over year, slower than the 4.8% increase through December. That’s a promising sign that salary growth can slow without widespread job losses—and an economic slowdown. There’s still a big disconnect in the market’s logic. If the labor market and the economy hold up, then the Fed would probably not feel inclined to lower interest rates in the back half of 2023, as futures pricing implies.
-Infrastructure stimulus and the transition to renewable-energy generation could provide a big boost to some stocks in 2023. Unfortunately, one of them won’t be around for investors to play. That would be Atlas Technical Consultants, which Barron’s recommended buying ahead of Congress passing the $1.2T Infrastructure Investment and Jobs Act in late 2021, when shares were around $9. Atlas, which provides engineering and design services, inspection and certification of buildings and public works, and other construction-related services, benefited from the infrastructure-spending buzz in the following months: The stock rose to $13 by March 2022. Those gains didn’t last. By the end of the year, shares were below $6 as investors fretted over Atlas’ substantial debt load in a rising-rate environment.
Features:
-January’s stronger-than-expected jobs report, released this Friday, has surprised—and baffled—economists on Wall Street. Although the latest numbers suggest diminished risks of a recession, they generate more uncertainty about the current state of the economy and the Federal Reserve’s course. Economists called the strong jobs numbers “confusing,” “noisy,” “eye popping,” a “head scratcher,” and a “paradox.” Still, many view it as an “encouraging” sign of the “surprisingly resilient” jobs market: The US economy added more than twice as many jobs in January than economists had expected—nonfarm payrolls increased to 517,000. Unemployment rate fell to the lowest level in at least 50 years, and weekly working hours increased, partially thanks to the warmer winter weather this year that allowed more time for outdoor work. While all this sounds like good news, it isn’t what the Federal Reserve wanted.
-The labor report released Friday shows that fewer Americans are unemployed than any time in the past five decades. The unemployment rate fell to 3.4%, as the economy added 517,000 jobs. But in some industries the rate is much lower. In the category defined as “mining, quarrying, and oil and gas extraction,” for instance, the unemployment rate is now just 0.3%, versus 8.4% a year ago. Only 2,000 people were looking for work in the industry in January, versus 46,000 last year. It’s a testament to the rebound in those industries since the depths of the pandemic, but also to a growing labor shortage.
European Trader:
-As the recovery in international travel continues, and demand in the UK stays strong and pricing remains robust, it might be worth checking into the UK based hotel group Whitbread. The stock has had a stellar start to the year, climbing 20%—in comparison to the broader FTSE 100’s 4% rise. But it might not be too late for investors to book the hotel and restaurant group because there are potential catalysts for more gains. Whitbread’s budget Premier Inn chain is showing no signs of a slowdown, with strong sales in the third quarter and an upbeat outlook. It is also poised to gain market share as UK hotel supply declines, a trend which the company says will keep pricing strong.
Emerging Markets:
-A lot of hype has gathered around India recently. The South Asian giant is on track to surpass China as the world’s most populous nation this year. It’s overtaking its neighbor in economic growth, too. India should expand by 6.1% during 2023, compared with 4.4% for China according to the UN. India’s once-dreaded overpopulation has morphed, in economists’ eyes, into a “demographic dividend”: Citizens with a median age of 27.6, against China’s 37.9, will power progress for decades to come. Timely reforms from Prime Minister Narendra Modi are unleashing this latent juggernaut. That’s the line anyway.
Commodities:
-Silver has sharply outpaced gold’s gains in the past three months, and its classification as both an industrial and precious metal may lead it on a path to even higher prices. From Oct. 31 to Jan. 31, Comex silver futures climbed nearly 25%, outpacing gold’s almost 19% climb, a “statistically unusual amount that shows the precious metals market is bullish on global economic growth in 2023,” wrote Nicholas Colas, co-founder of DataTrek Research, in a Jan. 25 report. He pointed out that silver is primarily an industrial metal, while gold is used mainly as an investment and for jewelry—so the better performance for silver prices supports the idea that the “global economy is in better shape than feared in mid-2022.”
Streetwise:
-This week, Jack Hough takes on activist investors: Activists in general don’t seem to add much value to the companies they target beyond an initial pop in the stock price. They also tend to earn uninspiring returns for their own investors, after taking hefty fees. What’s an activist? A corporate raider without the commitment. If you’ve ever been to a Peewee basketball game and heard parents coaching from the stands, picture one of them walking to the bench, sitting down, grabbing the clipboard, and telling Silas to stop chucking from the outside, Jasper to hit the boards, and Henry to go turn his shorts right-side-out. The actual coach would probably welcome that help as much as CEOs appreciate raiders and activists, the two main types of high-finance buttinskys.
Twitter Hasn’t Paid Bill, M&A Advisory Firm Says
Innisfree M&A sues Twitter for $1.9 million
An advisory firm says Twitter Inc. hasn’t paid its bill after the firm worked for the company on Elon Musk ‘s acquisition last year, the latest contention that the company is shirking debts.
Innisfree M&A Inc. sued Twitter on Friday in New York State Supreme Court, seeking about $1.9 million.
“As of December 23, 2022, Twitter remains in default of its obligations to Innisfree under the Agreement in an amount of not less than $1,902,788.03,” the lawsuit says.
A representative for Twitter declined to comment. Innisfree didn’t respond to a request for comment.
Billionaire Elon Musk in April 2022 said he wanted to acquire Twitter and take the social-media company private. He acquired the company in an October deal that valued Twitter at $44 billion, and has since been working to cut costs and make other changes.
The New York Times earlier reported on the lawsuit.
According to Innisfree’s filing, Twitter hired Innisfree in May to reach out to Twitter’s shareholders and provide analysis and advice ahead of a September meeting, when shareholders would vote on the deal to take Twitter private.
Innisfree says that following that meeting, it sent Twitter an invoice for about $1.9 million. In October, Twitter told Innisfree that the invoice had been “successfully processed” and would be paid in November, the suit says. Innisfree followed up with Twitter when it didn’t receive payment, according to the filing.
Twitter’s failure to pay Innisfree for its work constitutes a breach of agreement, Innisfree says in its lawsuit.
In January, the landlord for one of Twitter’s offices in San Francisco said the social-media company hadn’t paid its rent.
The landlord, in a lawsuit filed in California Superior Court in San Francisco, said Twitter had failed to pay about $130,000.
Other companies, including a software provider, also have sued Twitter in recent weeks in an effort to recoup what they say are overdue payments.
Weekend Papers Summary
NEW YORK TIMES
-Furor over Chinese spy balloon leads to a diplomatic crisis. The Pentagon called the object, which has flown from Montana to Kansas, an “intelligence-gathering” balloon. Beijing said it was used mainly for weather research and had strayed off course.
-A giant balloon floats into town, and it’s all anyone can talk about: A Chinese balloon has been raising a lot of questions for people who live under its path. “I did see it, and it should have been shot,” said a barbecue chef in Billings, Mont.
-US hiring surges with January gain of 517,000 jobs. The report defied expectations and underscored the challenges for the Federal Reserve, which is trying to cool the labor market to fight inflation.
-Job growth is a boost for Biden as he bets on a lasting turnaround. President Biden has for months pointed to solid hiring trends as evidence that his agenda has rebuilt the economy after the pandemic shutdowns.
-Jury rules for Elon Musk and tesla in investor lawsuit over tweets
The case centered on whether investors lost money because they believed Mr. Musk’s social media posts about taking Tesla private in 2018.
-The Advisory Firm Innisfree M&A has sued Elon Musk’s Twitter, saying that Twitter, which Elon Musk bought last year, has not paid it $1.9M for services it rendered for the deal.
-E.M.T.s provided no care for 19 minutes after police beat Tyre Nichols
The board that regulates emergency medical technicians in Tennessee on Friday voted to suspend the licenses of the two E.M.T.s who arrived at the scene and failed to render aid.
-The EU vows more help for Ukraine but tamps down membership talk. European Union leaders met in Ukraine’s capital with President Volodymyr Zelensky, who said Ukraine would not give up on Bakhmut, the eastern city caught in a fierce battle with Russian forces.
-Gautam Adani’s rise was intertwined with India’s. Now it’s unraveling.The tycoon often said the Adani Group’s goals were in lock step with India’s needs. Now, the company’s fortunes are crashing, a collapse whose pain will be felt across the country.
THE FINANCIAL TIMES
-US secretary of state Antony Blinken has cancelled his weekend visit to China after the Pentagon said it discovered a Chinese spy balloon that has been flying over sensitive nuclear missile sites in the western state of Montana. The top US diplomat had been set to travel to Beijing where he had been expected to meet China’s president Xi Jinping. He would have been the first Biden administration cabinet secretary to visit China and the first secretary of state to travel to the country in more than five years.
-By Friday, the Gautam Adani’s listed companies had lost more than $100B of their value and the share sale was off. Adani, once the world’s third-richest man, had fallen to number 17 on Forbes’ list of billionaires. Apart from the future of the billionaire and his business empire, something bigger is on the line: India’s probity in corporate governance and pursuit of a development model in which the state has entrusted a few ultra-rich men with running India’s infrastructure and pioneering investments abroad.
-The UK’s FTSE 100 hit an all-time high on Friday, as the blue-chip index dominated by multinational companies overcame the drag of a domestic economy headed for recession. The FTSE added as much as 1.1% on the day to trade at 7906.58, eclipsing its previous peak in May 2018, before closing at 7902. After ending 2022 up almost 1%, the best-performing developed market index in local currency terms, the FTSE 100 has risen 6.1% in 2023.
-The Bureau of labor Statistics claims that the US economy added more than half a million new jobs last month, taking unemployment to its lowest for decades despite the Federal Reserve’s efforts to raise rates to fight inflation.
US payrolls increased by 517,000 for January, nearly double December’s total and almost triple the consensus forecast of 185,000. The country’s unemployment rate, at 3.4%, is now the lowest for 53 years.
-Google has invested about $300M in artificial intelligence start-up Anthropic, making it the latest tech giant to throw its money and computing power behind a new generation of companies trying to claim a place in the booming field of “generative AI”.
-Amazon, Meta, Alphabet and Microsoft will collectively incur more than $10B in charges related to mass redundancies, real estate and other cost-saving measures, as the Big Tech companies reveal the hefty price they incur to rein in spending. The US companies that have been implementing the largest job cuts in the tech sector disclosed the high costs related to their restructuring efforts in earnings statements released this week.
-EU member states have agreed on the level of price caps to be imposed on shipments of Russian refined oil products, which will come into effect on Sunday as part of a G7 effort to cut Moscow’s export revenues. Ambassadors of the 27 EU states agreed at a meeting on Friday to limit the price of premium products such as diesel at $100 a barrel and that of low-end products including fuel oil at $45 a barrel.
-Volodymyr Zelensky has warned Ukrainian citizens against complacency in the face of an expected Russian offensive and called on western allies to speed up their assistance to Kiev.
The Ukrainian president said he saw signs that in some cities, people were letting their guard down despite ongoing hostilities, a “weakness” his country could not afford. Compared to the start of the war, when “the spirit was stronger”, Zelensky said, “now I see in some cities that they are at rest.”
-Nigeria’s attempt to replace its high-denomination currency notes less than a month before a crucial general election has descended into chaos, with long lines of people forming outside cash machines and fights breaking out inside banks as customers demanded access to their own money.
-The Chinese state over the past three years mobilized millions of workers, who formed the backbone of the country’s battle to contain the virus with lockdowns, quarantines and mass testing. Colloquially known as dabai, or “big whites” owing to their distinctive personal protective equipment, many were doctors and nurses, civil servants and local volunteers who were reassigned to administer Covid tests or staff temporary fever wards.
-CryptoCompare figures also show the total assets under management for digital asset investment products increased almost 37% in January to more than $26B, the highest since May 2022 — the month when crypto’s unprecedented crisis of confidence began. Grayscale’s GBTC — an investment trust designed to track the price of bitcoin — last month notched up $38.9M in average daily volume, a 23% rise from December, according to the crypto data provider. The recent digital asset surge hasn’t taken place in a vacuum, but amid a wider rally for other speculative assets.
-Ford is returning to Formula 1 after a two-decade absence in an effort to drive demand for its electric vehicles, just as the sport starts to shift from the traditional engines for which it is renowned. The US carmaker has joined forces with Red Bull to return to the sport in 2026, when rules requiring the use of sustainable fuels come into force.
-EY has told retired US partners it is considering giving them a cut of the proceeds from a spin-off of its consulting arm, after complaints that the firm’s leadership is cashing in on a business built by previous generations.
NY POST
-President Biden and first lady Jill Biden took out a $250,000 line of credit against their home in the Delaware beach town of Rehoboth – as federal investigators probe both the president and his son, Hunter, a new report reveals. The Bidens secured the loan – which allows them to borrow the quarter of a million dollars against the home’s equity – on Dec. 5, according to county records reviewed by Fox News. It’s unclear from any paperwork why the couple took out the line of credit on the home, reportedly purchased in 2017 for nearly $3M. The White House did not respond to a request for comment from The Post. But the mortgage documents were filed about a month after Biden’s personal lawyers found classified documents at his Washington think tank, the Penn Biden Center for Diplomacy and Global Engagement.
-Bill Gates told BBC interviewer Amol Rajan that he does not believe Elon Musk’s mission to colonize Mars is a good use of funds, saying providing vaccines to people in need should be a higher priority. “It’s actually quite expensive to go to Mars,” Gates said. “You can buy measles vaccines and save lives for $1,000 per life saved, and so it just sort of grounds you, as in — don’t go to Mars.” Last year, Musk confirmed he turned Gates down on an offer to collaborate on philanthropic efforts to combat climate change, after leaked texts between the two showed Musk telling Gates he can’t take him “seriously when you have a massive short position against Tesla, the company doing the most to solve climate change.”
Hedge funds rush to unwind bets on falling markets as stocks surge
Funds seek to cover short positions at a faster pace than height of 2021 meme stock frenzy
Hedge funds wrongfooted by a sharp surge in stocks this week rushed to exit losing bets on falling markets at the fastest pace in years.
Equity markets have risen sharply so far this year, led by many of the speculative stocks that were clobbered hardest during 2022’s global sell-off. Many of the funds that profited from the rout have found themselves poorly positioned for the rebound, which has recently accelerated as investors sensed that interest rates were close to peaking in many major economies.
The resulting flurry of short covering — when investors buy back stocks they had been betting against to limit their losses — was the largest since November 2015, according to a Goldman Sachs note to clients seen by the Financial Times.
The scale of hedge fund buying, which helped fuel a 3.3 per cent jump in the Nasdaq index on Thursday, eclipsed that seen in January 2021, when retail investors co-ordinating their actions on forums such as Reddit sent the price of GameStop and other meme stocks rocketing, inflicting huge losses on some funds.
Funds closed their bets primarily against US stocks but also against European companies.
Bets against stocks that had previously been falling for a long period were “under MAX pressure”, Goldman wrote in a separate note on Thursday seen by the FT.
“We saw [an] explosive move higher” in software stocks “driven by consistent hedge fund covers [short covering] all session,” it added.
The bank estimated on Thursday that quantitative hedge funds lost around 1.3 per cent that day, their worst day in more than six months.
Among stocks that have stung hedge funds this year is online car retailer Carvana, which fell 98 per cent last year but which is up 200 per cent in 2023. Short interest — a measure of the size of bets against the stock — was at 30 per cent as of Thursday, according to S&P Global Market Intelligence, compared with less than 5 per cent a year ago when its shares were far higher.
Short interest in cinema chain AMC Entertainment, whose shares fell 76 per cent last year but have risen 49 per cent this year, is running at 29 per cent, only a slight reduction since the start of the year.
The rally in stocks that were hard hit last year “has likely provided a big technical tailwind for the non-profitable tech universe and has been hurting the [hedge fund] systematic community”, wrote analysts at Goldman.
“It is hard to fight the risk-on momentum,” wrote analysts at Natixis. “The market remains focused and reassured by the near end of the [interest rate] tightening cycle . . . Retail/meme stocks are outperforming strongly.”
On Wednesday the US Federal Reserve raised interest rates by a quarter of a percentage point, a smaller move than its series of large hikes last year, which raised hopes that borrowing costs may soon peak.
However, some of that enthusiasm was tempered on Friday stocks by strong jobs data, which revived fears that the Fed may have to keep rates higher to control inflation.
A New Supercycle Is Starting, Says This Macro Strategist. How to Invest.
Jurrien Timmer, director of global macro at Fidelity Investments, sees himself as a storyteller, connecting the dots between history and current economic trends to get a sense of where markets are headed. Although stocks are much cheaper today than they were a year ago, he worries that U.S. investors are still too sanguine about the outlook for the economy and corporate profits. In other words, they’ve bought into a just-right, or Goldilocks, scenario that seems unlikely to play out.
Timmer joined Fidelity in 1995 as a technical research analyst, and now is part of the firm’s global allocation team that oversees $586 billion. He expects non-U.S. stocks to outperform this year, and bonds to reward investors as inflation and interest rates return to more normalized levels.
Timmer recently spoke with Barron’s by phone about the challenges and opportunities that lie ahead for investors, and why the next 10 years won’t resemble the zero-interest-rate era just past. An edited version of the conversation follows.
Barron’s: Is the U.S. economy headed for a soft landing or a recession?
Jurrien Timmer: The recession call would seem obvious here, with the Treasury yield curve the most inverted in 40 years, and the Federal Reserve intending to take interest rates above 5%. Every time the Fed has gone that far into the restrictive zone—two to three percentage points above a neutral rate at which the economy is theoretically in balance—we’ve had a recession. The valuation of the S&P 500SPX –1.04% , as measured by the price/earnings multiple, declined by 31% last year. The question is, how much is priced in?
What is confusing the picture is that, as the U.S. is possibly going into a recession, China is finally coming out of its Covid lockdown. Three years of pent-up consumer-spending demand is being unleashed. China isn’t going to be able to prevent a U.S. recession, but it could prevent an earnings recession because a big chunk of S&P 500 revenue and earnings comes from abroad.
What does that mean for U.S. stocks?
The market is still pricing in too much of a Goldilocks outcome, given that the S&P 500 is trading for 18 times forward earnings. Also, consensus earnings estimates are flat for this year but show 10% growth for 2024. The market is anticipating a quick rebound in earnings. Investors are expecting the Fed to take rates up to 5%-ish but keep them there for only a New York minute, before pivoting to cut rates to less than 3%.
This Long-Term Investor Is Sticking With Tesla and Cloud Stocks. Here’s Why.
We would need inflation to fall off a cliff for that to happen. The October 2022 low in stocks might well be a bottom, but it is hard for me to see the catalyst for a new bull market. To go from a 5% to 2.75% federal-funds rate in a year would also require a recession. The Fed has been explaining that it isn’t going to cut rates that fast because inflation, although moderating, isn’t likely to go back to 2%. For the inflation rate to average 2% over the next five years, it would need to fall below that and rise again.
Non-U.S. stocks are doing better than U.S. shares this year. Will that outperformance to continue?
Yes. Part of the outperformance so far has been because the dollar is falling in value, and partly, big earnings declines have already occurred in emerging and foreign markets. Relative valuation is compelling, but big performance moments are driven by relative earnings. The relative-earnings picture is improving [for foreign stocks], with China scraping off of a deep bottom while the U.S. is coming off a top. Corporate earnings growth in the U.S. was 50% in 2021. It was down to zero in 2022 and is probably contracting this year, while China and emerging markets are seeing the opposite.
What else does the rest of the world have going for it?
The past eight to 10 years have been about megacap stocks. Because the S&P 500 is laden with these big growth companies, that has led to outperformance for the U.S. versus the rest of the world.
When I look at a chart of the top 50 stocks relative to the bottom 450 stocks, I see a couple of waves: the original Nifty 50 stocks of the early 1970s, the market during the dot-com period, and a similar wave from 2014 to 2022. It looks like that wave has ended, partly because of the interest-rate reset by the Fed.
So, what comes next?
If the low-interest-rate era has ended, it may well mean that the secular trend has changed from the megacap growth stocks, which dominated from 2014 to 2021, to “everything else”—such as value stocks, small-caps, commodities, and international equities. This also happened during the original Nifty 50 era of the early 1970s, and again during the tech boom of the late 1990s.
There are market cycles of four to five years, but also secular trends or supercycles spanning decades. We have been due for growth stocks to pass the baton to the rest of the market [after a growth supercycle].
What does this mean for future returns?
The bull market was driven by low interest rates, lower taxes, companies earning a lot of free cash flow, and returning the excess to shareholders.
Since the financial crisis, initial public offerings and secondary offerings for S&P 500 companies have raised a combined $2.5 trillion, compared with $20 trillion spent on share buybacks and mergers and acquisitions.
People don’t appreciate how much buybacks and financial engineering contributed to the S&P 500’s outsize return. If companies are going to buy back fewer shares, that would lower the share of earnings returned to shareholders, which suggests a lower valuation.
That goes back to the narrative of outperformance for non-U.S. stocks. One reason the U.S. has collected such a premium [relative to foreign markets] is because more of its earnings were paid out to investors via buybacks and dividends. [As this trend wanes], we could see a leveling of the playing field for non-U.S. stocks.
What is the outlook for bonds after last year’s losses?
Over the past 150 years, periods of above-average inflation produced a positive correlation between stocks and bonds. That correlation was deeply negative during the past decade or more, but has now flipped to zero. Historically, when the 10-year inflation rate is above average, or 3%, this correlation has been positive. We are still at the average inflation rate, based on the 10-year annualized change in the consumer price index, so the jury is out as to whether the correlation will continue to be positive.
What parts of the bond market are attractive?
If you don’t think inflation is going to go all the way back to 2%, then the TIPS [Treasury inflation-protected securities] market offers value at these levels. Corporate bonds do, as well. High-yield corporate spreads have remained stable at around 450 basis points [4.5 percentage points above Treasury yields]. This appears to confirm the soft-landing narrative, but could also be the result of corporate issuers having “termed out,” or swapped short-term for long-term debt when interest rates were low.
What role does deglobalization play in your inflation outlook?
Deglobalization would suggest the run rate for inflation is going to be higher. The U.S. is about 10 to 15 years behind Japan in terms of demographic trends, such as the shrinking of the labor force. For Japan, that shrinkage has been deflationary, but that was during an era when the supply of available labor was rapidly expanding, with Eastern Europe [joining the global economy] during the 1990s and China since the 2000s. That labor arbitrage seems to have mostly played out, which suggests any further slowing in the labor force may be more inflationary than what was experienced in Japan.
Population is peaking in China, Japan, the U.S., and Europe, but it is less likely to be deflationary than in the past. Plus, geopolitical tensions that cause deglobalization would suggest that inflation’s run rate will be higher as countries reshore or bring supply chains closer to home. That requires infrastructure and capital expenses, not to mention labor. It could lead to resource scarcity, which is inflationary. That’s the opposite dynamic of the offshoring era that started when China joined the World Trade Organization in the early 2000s.
Also, during Covid, two to three million baby boomers retired. That, coupled with a more stringent immigration policy, means we have a labor shortage. The resultant inflation is what the Fed is trying to fight. The Fed is willing to induce a recession in the near term to preserve price stability.
How will this fight play out?
The risk is that inflation will come down, but not enough for the Fed’s liking, or not enough to prevent inflation from accelerating from a higher base in the next economic expansion. That’s what happened in the late 1960s and early ’70s. Inflation never got below its five-year trend; there was a series of higher lows.
If inflation is higher, how should investors think about diversification?
A 60% equities/40% bond portfolio produced an average annual return of 9% between 1950 and 2022. In the past 10 years, the S&P 500 and [the Bloomberg US Aggregate Bond Index] were all you needed. If you bought international stocks, they added to volatility and took away return. There was no reason to be an active investor. There is every reason to be an active investor for the next five or 10 years. That’s where the game is going to be.
What will market cycles look like in coming years?
During the Great Moderation from the late 1990s until more recently, we had a period of low interest rates, low inflation, low volatility. The cycle was smoothed out because of globalization, and inflation was tamed.
The cycle will return toward more of a typical four-year business cycle. The Fed is going to play a bigger role more often than in the past. [The market] will be more volatile than what investors are used to, and that speaks to the need to be more diversified.
What stands out in your charts?
We have had a huge reset—with the S&P 500 P/E going from 30 to 18—that has brought value to all corners of the market. For the millennial or the Gen Z investor just starting a 401(k), it’s a tremendous opportunity. For retirees in the withdrawal stage, 2022 was a perfect storm for the 60/40 portfolio, with a bear market and bond-market losses. The good news is that it came after many years of outsize returns.
True enough. Thanks, Jurrien.
Les 100 restaurants à tester au moins une fois dans sa vie à Paris

Since its initial introduction, Apple’s CarPlay platform has become ubiquitous. It’s available in the vast majority of new cars on the market today, and for good reason: it’s one of the top things people look for when buying a new car.
At WWDC last June, Apple announced what it calls the “next generation of CarPlay.” This new CarPlay interface is set to debut in new cars as soon as later this year, and it’s going to be a big change.
An all-new design for CarPlay
CarPlay was originally launched as “iOS in the Car” as part of iOS 7 and was rebranded as CarPlay shortly thereafter. Since that rebrand, CarPlay’s interface hasn’t changed much. The biggest design change came with iOS 13, when Apple introduced a new Dashboard interface with different “cards” for apps like Maps, Music, and more.
The “next generation” of CarPlay, however, will pretty much give the CarPlay interface a complete overhaul. While we haven’t gotten a chance to try the new CarPlay design, Apple’s imagery from WWDC offered a sneak peek.
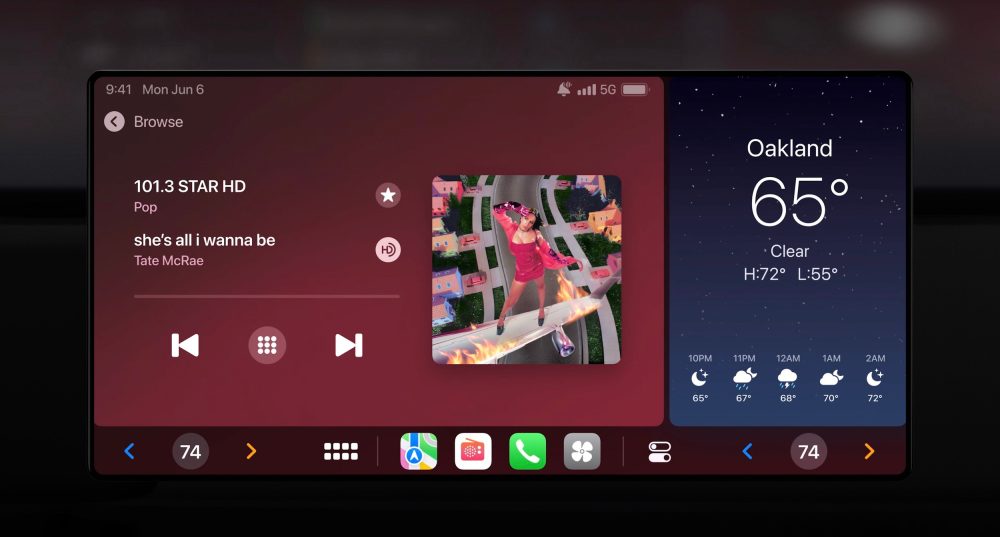
The new design still relies on a grid of app icons as its primary user interface element, but there are plenty of other changes surrounding that app grid. There will be a split-view style interface for showing multiple apps at the same time, as well as a Dock at the bottom with quick access to recently-used apps.
Where the new CarPlay interface really shines, however, is with how it can take over your car’s entire infotainment system. This includes the center console display in its entirety, as well as any other displays like one behind the steering wheel.
Apple explains:
CarPlay has fundamentally changed the way people interact with their vehicles, and the next generation of CarPlay goes even further by deeply integrating with a car’s hardware. CarPlay will be able to provide content for multiple screens within the vehicle, creating an experience that is unified and consistent.

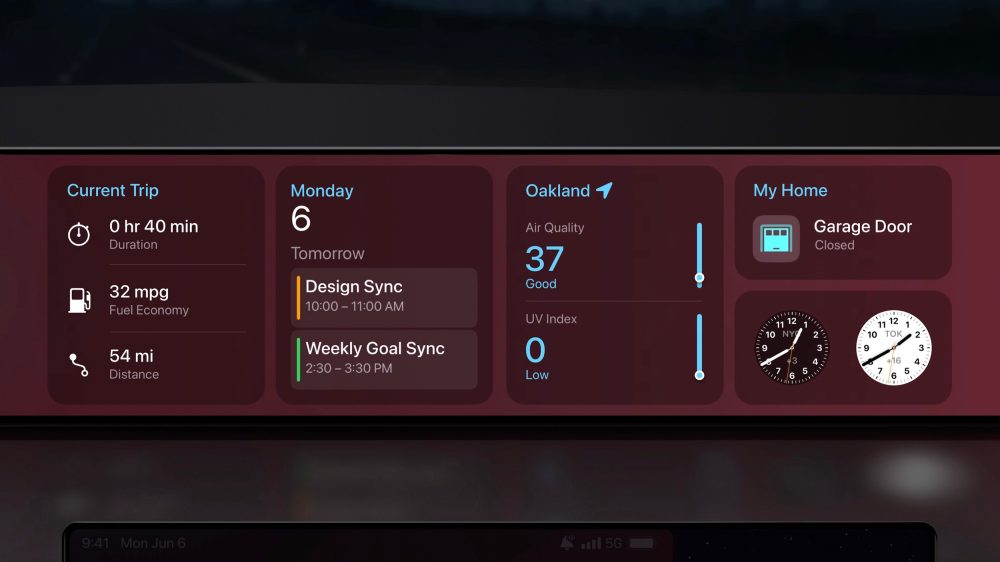
One of Apple’s mock-ups of the new design uses a car that’s similar in style to the Mercedes-Benz EQS, where there’s basically one large display that stretches from behind the steering wheel to the passenger side. The interface looks to be completely modular, with different tiles and widgets for apps like weather, HomeKit, and more.
Another mockup (at the top of this story) shows a car that’s very similar to the Ford Mustang Mach-E, which features a portrait-oriented center display and a smaller instrument cluster behind the steering wheel.
In these images, you can see how the CarPlay interface can adjust based on different screen sizes. It’s where the “modularity” of the widgets and cards comes into play. But the key to this new design is that it completely replaces the car manufacturer’s software interface.
Deeper integration with cars
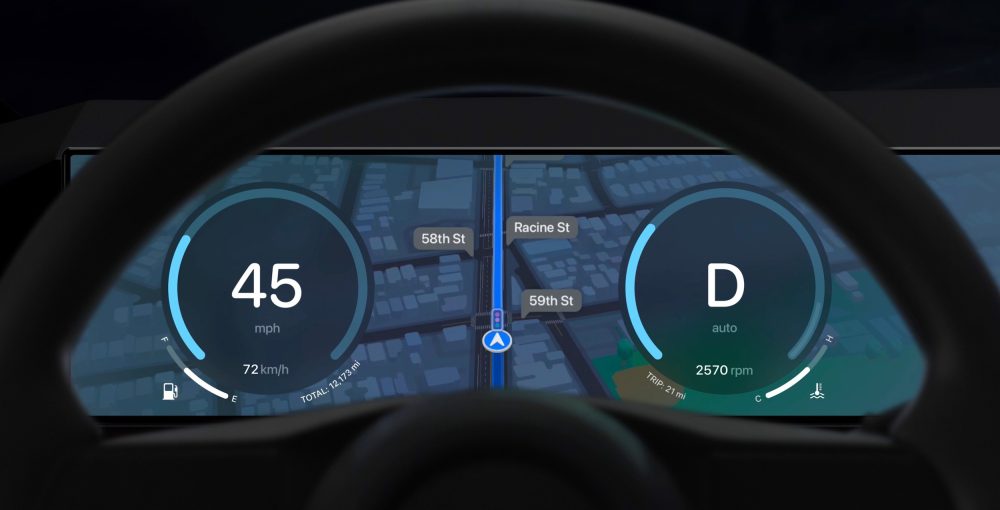
If CarPlay is going to take over your entire in-car experience, then it needs to be able to access all of the features and functionality of your car. With this in mind, the “next generation” of CarPlay will have access to a much broader range of car features than before. Apple says that this is accomplished by your iPhone communicating with your car’s real-time system.
This includes things like climate control, fuel and battery charge levels, radio controls, instrument cluster data, and more. “CarPlay will seamlessly render the speed, fuel level, temperature, and more on the instrument cluster,” Apple says. “Deeper integration with the vehicle will allow users to do things like control the radio or change the climate directly through CarPlay.”
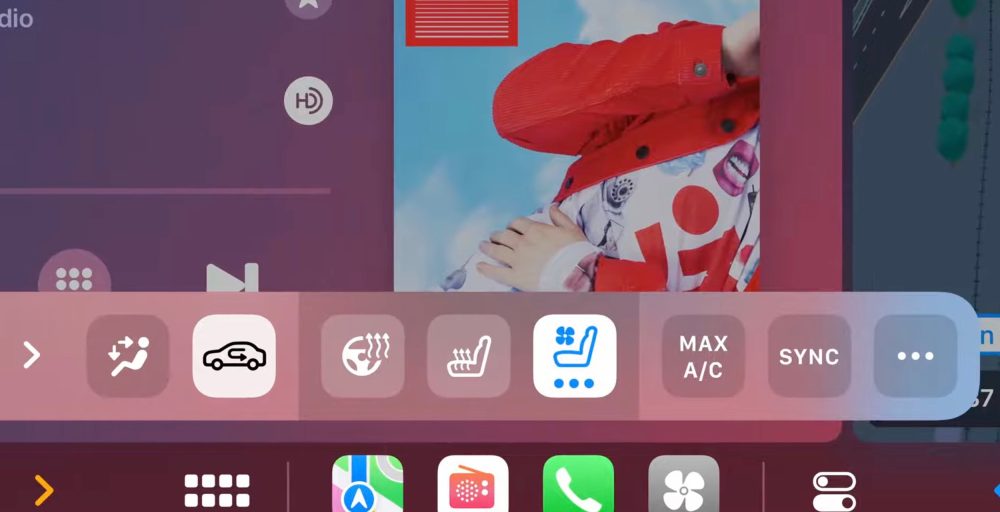
Think of it this way: everything you previously had to use your car’s native interface for will now be fully integrated with CarPlay itself. In an ideal implementation, this means you’ll only ever interact with CarPlay.
Design customization
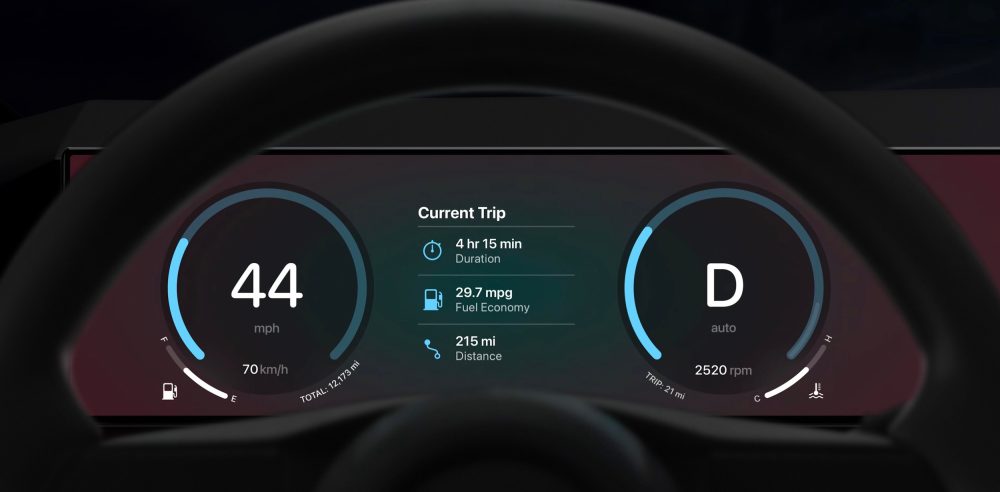
With all of this data, the aforementioned design changes make a lot more sense. You’ll be able to personalize your driving experience by choosing different gauge cluster designs and managing the layout of the instrument cluster itself. Apple says it carefully crafted different instrument cluster designs, “ranging from the modern to the traditional.”
Apple also says there will be different layout options for yet another level of customization. You’ll also be able to pick custom fonts, font sizes, and font colors for the various aspects of your car’s interface.
Meanwhile, CarPlay widgets will give you at-a-glance information from apps like Music and Weather.
Release date
Apple says that the first cars with support for this next generation of CarPlay will be announced sometime in late 2023. We do, however, know some details on which automakers have signed on to support this new CarPlay interface.
- Land Rover
- Mercedes Benz
- Lincoln
- Audi
- Volvo
- Honda
- Porsche
- Nissan
- Ford
- Jaguar
- Acura
- Polestar
- Infiniti
- Renault
One thing to remember, however, is that the adoption and implementation details of this new CarPlay are outside of Apple’s control. Ultimately, it’ll be up to each of these automakers and their respective timelines to roll out the new CarPlay design. And most of those automakers have been quiet on their plans so far.
Apple says that it will share “more information about the next generation of CarPlay” ahead of the official launch later this year. Keep in mind that the design Apple showed off at WWDC was a “sneak peek,” so there will be changes between it and what’s ultimately released.
How quickly does COVID immunity fade? What scientists know
Vaccination, infection with SARS-CoV-2 and a combination of both provide varying degrees of protection.
Three years into the pandemic, the immune systems of the vast majority of humans have learnt to recognize SARS-CoV-2 through vaccination, infection or, in many cases, both. But just how quickly do these types of immunity fade?
New evidence suggests that ‘hybrid’ immunity, the result of both vaccination and a bout of COVID-19, can provide partial protection against reinfection for at least eight months1. It also offers greater than 95% protection against severe disease or hospitalization for between six months and a year after an infection or vaccination, according to estimates from a meta-analysis2. Immunity acquired by booster vaccination alone seems to fade somewhat faster.
But the durability of immunity is much more complex than the numbers suggest. How long the immune system can fend off SARS-CoV-2 infection depends not only on how much immunity wanes over time but also on how well immune cells recognize their target. “And that has more to do with the virus and how much it mutates,” says Deepta Bhattacharya, an immunologist at the University of Arizona College of Medicine in Tucson. If a new variant finds ways to escape the existing immune response, then even a recent infection might not guarantee protection.
Omicron era
Omicron has presented just such a scenario. In late 2021 and early 2022, the main Omicron subvariants that were causing infections were BA.1 and BA.2. By mid-2022, the BA.5 wave was gathering strength in some countries, raising the prospect that those who’d already had one round of Omicron could soon be exposed to another. Data are now providing a sense of the risk of reinfection over time.
In one study1, researchers looking at Portugal’s national database of infections studied vaccinated people who became infected during the BA.1/BA.2 wave. Analysis showed that 90 days after an infection, this population had high immune protection — their risk of becoming infected with BA.5 was just one-sixteenth that of people who had been vaccinated but never infected. After that, hybrid immunity against infection declined steeply for a few months and then stabilized, ultimately providing protection for eight months after infection, the duration of the study.
Another study3 looked at 338 vaccinated health-care workers in Sweden, some of whom had had a previous SARS-CoV-2 infection. The authors found that workers with hybrid immunity had some level of protection against infection with BA.1, BA.2 and BA.5 for at least eight months. Swabbing of these workers’ noses revealed high levels of ‘mucosal’ antibodies, which are thought to be a better shield against infection than antibodies that circulate in the blood.
A study4 in Qatar compared the infection risks of people who had never caught SARS-CoV-2 with those of people who’d had a previous infection with Omicron or an earlier variant. Both groups included vaccinated and unvaccinated individuals. The results show that more recent infections provide greater protection than older ones in all cases. But because the virus kept evolving, the authors couldn’t untangle whether those differences were because of waning immunity, the virus’s growing ability to evade the immune response or, more likely, a combination of the two.
Infection reprieve
Taken together, the studies suggest that hybrid immunity provides some protection against infection for at least seven or eight months, and probably longer. “That’s pretty good,” says Charlotte Thålin, an immunologist at the Karolinska Institute in Stockholm and an author of the Swedish study.
Other data suggest that in people whose immunity arises only from vaccination, a booster dose provides relatively short-lived protection against infection. Researchers in Israel studied more than 10,000 health-care workers who had not previously been infected; all received either three or four doses of the vaccine made by Pfizer and BioNTech5. The authors found that the fourth dose’s efficacy against infection fell rapidly. In fact, after four months, the fourth dose was no better than three doses at preventing infection.
However, “we are talking just about what we call relatively mild disease”, says study co-author Gili Regev-Yochay, an epidemiologist at Sheba Medical Center Tel Hashomer in Ramat Gan, Israel. None of the people in the study developed severe COVID-19.
What about those who haven’t been vaccinated? Another study6 in Qatar suggests that if the virus doesn’t change, infection-based immunity against reinfection can last up to three years. But that immunity can fade faster if the virus mutates. The authors studied data from unvaccinated people who were infected with a pre-Omicron variant. Fifteen months later, those infections were less than 10% effective at protecting against Omicron infection. And it is much riskier to rely on immunity from infection than to get immunized.
But it’s nearly impossible to apply the study results to predict an individual’s risk of becoming infected in future. Immunity depends on a variety of factors, including genetics, age and sex. And past risk of infection isn’t necessarily a good predictor of the risk of future infection, because new variants are continually arising.
Booster break
How growing global hybrid immunity will affect the timing and frequency of infection surges isn’t yet clear. Neither is it clear how this will influence health officials’ decisions about when to offer future booster doses.
For people who are at high risk of developing severe COVID-19, it might make sense to get boosters frequently. Younger individuals without any risk factors who live in regions where the virus has been circulating freely “may already have very significant protection that may not require as frequent boosters”, says Luís Graça, an immunologist in the Faculty of Medicine at the University of Lisbon and a co-author of the Portuguese study. Another option might be to give a booster when antibody levels fall below a certain threshold, says Regev-Yochay.
Thålin understands how frustrating the caveats and uncertainty can be, but says that researchers aren’t likely to pin down an answer anytime soon. “The virus is evolving so fast,” she says. “What’s true today might not be true tomorrow.”