FT : How a SEC rule change has opened more doors for activists

How a SEC rule change has opened more doors for activists
Despite companies rewriting bylaws to strengthen defences, more investors have won board seats in proxy battles

When the Securities and Exchange Commission introduced a rule change to make it easier for shareholder activists to elect board nominees, there was a notable dissenting opinion from one its commissioners.

Hester Peirce warned that the change would advance special interests rather than enhancing corporate value. Using a light-hearted example, she said even a passionate activist on issues surrounding bees would have leverage to demand companies “put beehives on the roof of each office building”.

The new rules have been in effect since last September. So far, no known proxy battles over beehives. But shareholder activists have made boardroom advances in a busy year for proxy showdowns in the US.

Activists have won 88 board seats through May 31, up from 77 at that point last year, according to Diligent, a data provider. Big activist firms like Nelson Peltz’s Trian and Elliott also scored concessions from Disney and Salesforce respectively without obtaining board seats.

And on Monday, a fight between an activist investor and Masimo, a small medical device maker, will climax at the company’s annual shareholder vote. Politan Capital Management, run by New York-based activist investor Quentin Koffey, has alleged that the corporate governance of Masimo is broken and the company is in need of more independent oversight. Politan has nominated Koffey and another candidate to Masimo’s board. The fight will be key test of a shift in corporate governance influenced by the SEC rule change.

For activists, the new “universal proxy” rule guarantees that all board candidates will appear on shareholder ballots at a company’s annual meeting. It also allows shareholders to pick and choose individual directors. Previously, unless shareholders turned up in person to an AGM, they were forced to vote for a slate of the company’s nominees in contested elections or those of the activists.

Proposed by the SEC in 2016, the rule change was applauded by activists such as Carl Icahn and was not adopted until Democrats came back into power under president Joe Biden.

The universal proxy voting rules raised concerns among companies that potential activists — environmentalists, labour unions and human rights advocates — would have an easier time waging proxy campaigns. Hester argued any activist “need only to dangle the possibility of buying a few shares and putting forward directors to scare management into the negotiating room”.

For months, Wall Street’s big law firms warned clients of boardroom chaos, predicting non-traditional activists would try to nominate directors. Fears peaked when a former Warner Music executive launched a campaign in early December to put herself forward for a board seat, relying on the universal proxy rule change. Fearing an activism surge, hundreds of companies rewrote their corporate bylaws to make life harder for activists.

Some bylaw changes demanded more information from activists, including about their funders. Masimo approved such changes last year, and in October, Koffey sued the company to overturn its bylaw changes. Masimo eventually relented and allowed Koffey’s nominees to proceed to a vote on Monday.

“Companies were weaponising their bylaws a lot more than ever,” said Elizabeth Gonzalez-Sussman, vice-chair of the activism practice at law firm Olshan.

But while bylaw changes might ward off unsophisticated activists, they offer only a false sense of security. If activists will splurge on a court fight to war over arcane bylaw changes, then these defences will prove beatable, says Richard Thomas, a managing director at Lazard. 

“If the juice was worth the squeeze it is going to be worth the squeeze no matter what the bylaws say,” he says. “You really don’t avert a problem simply by bylaw changes.”

The activists’ successes in winning more board seats this year also show conventional shareholders and asset managers approve of the need for board overhauls at certain companies. On the Masimo battle, asset manager Neuberger Berman has already said it is voting for Koffey, who previously worked at DE Shaw and Elliott Management, and his other candidate, citing concerns about corporate governance at the company.

Shaun Mathew, a partner at law firm Kirkland & Ellis, says the fundamentals of activism did not change because of the SEC’s universal proxy changes. Rather, they “may have made it somewhat easier for activists to win at least one board seat”. In the months ahead, “boards should also not take too much comfort”. Perhaps boards would have preferred a “bee activist” after all.

Barrons : The Age of Oil Will Endure. These Drilling Stocks Could Be Gushers.

The Age of Oil Will Endure. These Drilling Stocks Could Be Gushers.

Offshore oil drillers were about the worst place to be in 2020 as oil prices were falling and demand for crude seemed to be seeping away. Now, the stocks may be the ones to own as investors realize that oil will be needed to make the world go around for decades.

Make no mistake, it was a historic downturn for providers of offshore rigs over the past few years. Oil prices tumbled during the pandemic lockdowns as driving nearly ceased, while the pivot toward renewable energy caused big oil companies to reduce their spending on drilling in hard-to-reach locales. Rigs were taken out of commission as they became too costly to operate profitably, but it wasn’t enough. Many of the offshore drillers eventually filed for bankruptcy in 2021 and 2022, wiping out investors who had bought shares as a value play.

What a difference 12 months makes. The drilling companies, including Noble (ticker: NE), Valaris (VAL), and Seadrill (SDRL), emerged from bankruptcy in strong financial shape and are poised to thrive as major energy companies ramp up their offshore spending.

The stocks are down from early-year highs as oil prices have fallen to under $70 a barrel from the low $80s. The drop in crude, however, isn’t expected to dampen the industry’s ambitious offshore investment plans. Offshore drillers are benefiting as they get higher leasing rates for their rigs, which portend better earnings in the coming years.

Most of the operators have little or no net debt after restructuring their balance sheets in bankruptcy. And while none of the companies pays a dividend, some companies are initiating or expanding buyback programs, and payouts could be reinstated as free cash flow grows sharply in the coming years. With the risks to investors reduced, the stocks look like a buy.

“We are in the second year of what we view as a minimum of a five-year…investment growth cycle,” says David Anderson, a Barclays analyst, who views the offshore drillers as the most attractive area of the energy service sector.

The offshore industry is a concentrated niche led by Noble, Transocean (RIG), Valaris, Seadrill, and Diamond Offshore Drilling (DO), and their rigs are increasingly in demand. Global oil production is now running at about 100 million barrels a day, and isn’t likely to change much over the coming decade.

SEE ALL THE STOCKS WE’RE BULLISH—AND BEARISH—ON
Picks & Pans
Offshore fields are critical to maintaining the pace. While an onshore well that uses hydraulic fracturing, or fracking, can produce 1,000 barrels of oil a day, offshore fields like one off the coast of Guyana in South America can hold billions of barrels of crude, and individual wells can produce 20,000 barrels of oil a day, according to Evercore ISI analyst James West. The annual rate of production declines for offshore wells are typically in the single digits, versus 50% or more for the first year for fracked wells in the U.S.

Despite being hounded by climate activists, European majors like Shell and BP have pivoted back to oil and pleased their investors after de-emphasizing investments in renewable energy.

“There’s a realization that the oil age will last longer than many prognosticators have suggested,” says West. “The major energy companies recognize they need baseload oil production, and they need offshore for that.”

Just follow the money. Oil-service industry leader SLB (SLB), formerly known as Schlumberger, highlighted the offshore opportunity this past week, projecting that major oil companies would commit up to $500 billion in new projects from 2022 through 2025. And for good reason—SLB noted that 85% of offshore fields are profitable even if oil prices drop to $50 a barrel.

There are two main types of rigs: jackups, which operate in shallow water of 500 feet or less, and deepwater rigs, either ships or floating platforms that can operate in 10,000 feet of water, with reservoirs often several miles below the seafloor. The latter command the highest rates, and they are the ones owned and operated by the public offshore drillers.

There are now 100 to 150 deepwater rigs operating in such places as the Gulf of Mexico, the North Sea, and Guyana. Day rates on these rigs bottomed at about $125,000 a day at the height of the Covid crisis in May 2020 and now are approaching $500,000 a day. With the rigs’ operating costs generally below $150,000 a day, current contracts are highly profitable.

Not all of that is flowing through to the drillers just yet. Current earnings are depressed because of older contracts carrying lower leasing rates, but profits are expected to ramp up sharply in 2024 through 2026 as a result of higher rates on more recent contracts.

The bankruptcies, consolidation, and tight supply also have produced more pricing discipline. And there is virtually no new construction of rigs, which can cost nearly $1 billion each. That should keep the most desirable rigs in short supply, and limit overspending by the offshore drillers. Earnings at Noble, for instance, are expected to more than double, to nearly $6 a share in 2024 from $2.45 this year, and head even higher in 2025.

Noble is a favorite of Barclays’ Anderson, who says it has an “enormous recontracting opportunity” in the next two years, a clean balance sheet, and a buyback program under way. In May, Noble inked a 2.5-year contract with Petrobras , the Brazilian oil company, for a floating rig at $490,000 a day, a new high for the current cycle. Anderson has a $56 price target on Noble, up more than 50% from Friday’s close of $35.62. At 9.1 times 12-month forward earnings, it’s slightly more expensive than other drillers, but also slightly higher quality.


Valaris stock has lagged behind peers in 2023 because it agreed to lease a group of rigs in the past year or so at what are now below-market rates, which means its re-contracting opportunity will take longer to play out. Valaris has an attractive rig joint venture with Saudi Aramco, the state-controlled Saudi oil giant, that could be taken public in the coming years. “Valaris is well positioned with a high quality deepwater fleet with a handful of rigs being reactivated,” says West. He also likes the Saudi joint venture and has an Outperform rating and $86 price target on Valaris stock, which closed on Friday at $56.56.

Diamond Offshore has the smallest market value of the main offshore drillers, and fewer high-quality assets, but they include four “seventh-generation drillships,” the latest models. Diamond, which trades at nine times projected 2024 earnings, is another Anderson pick, in part because its small size could make it a consolidation target. He has a $20 price target, up more than 60% from a recent $12.37.

Seadrill, meanwhile, has been a consolidator, and could benefit from a $1 billion merger earlier this year with the privately held Aquadrill that resulted in what the company called a “best in class” fleet, with seven seventh-generation drillships. With low-price legacy contracts expiring, Seadrill’s earnings could ramp up in the years ahead. At $38, it trades for eight times projected 2024 earnings.

Transocean is the riskiest of the drillers—but may also have the most reward. It is the industry leader, with the most operational deepwater rigs, while owning the most that have been mothballed and could be returned to market.

The company has considerable debt of $7 billion against a market value of $4 billion. It is the only major rig operator to have avoided bankruptcy. The debt means higher risk for Transocean stock, which trades around $6, or 15 times projected 2024 earnings. But paying it down could push equity prices higher as ownership passes from bondholders to stockholders.

The company could be “one of the greatest deleveraging stories” in energy in the coming years, with potential annual free cash flow of $1 billion in 2024 through 2026, Anderson says. Ultimately, its equity amounts to a turbocharged play on an industry revival, and investors can also buy its debt, like the 6.8% bonds due in 2038, now yielding about 11%.

The risks to these companies are real. They include the finite life of the rigs, which should run another 20 to 25 years or so, but could be cut short by the energy transition, and the companies’ linkage with oil prices, which are likely to be volatile. But it’s dawning on the world that oil will be a key energy source for decades. The consolidated, financially disciplined rig industry could be one of the best ways to play that longevity.

>>> US Close Dow -0,65% S&P-0,77% Nasdaq -1,01%

Closing Stock Market Summary

The stock market closed the week on a downbeat note. Ongoing consolidation efforts contributed to some of the weakness, although concerns about global growth prospects were another contributing factor. The major indices hit their best levels in the early afternoon trade as a few mega cap stocks recovered from opening losses, yet selling picked up again to interrupt that rebound effort.

Ultimately, the major indices all closed in negative territory with losses ranging from 0.7% to 1.4%.

The downside moves followed a slate of disappointing preliminary June manufacturing PMIs for Japan, Germany, the UK, the eurozone, and the U.S., all of which came in below 50 (i.e. the dividing line between expansion and contraction). Following yesterday's central bank rate hikes, those reports fueled worries that prior rate hikes may be adversely impacting economic activity, specifically in the manufacturing sector.

Growth concerns manifested themselves in falling commodity prices, the outperformance of the dollar, and sliding Treasury yields. The U.S. Dollar Index rose 0.5% today to 102.91. WTI crude oil futures fell 0.4% to $69.18/bbl and copper futures fell 2.0% to $3.80/lb. The 2-yr note yield fell five basis points to 4.75% and the 10-yr note yield fell six basis points to 3.74%.

Today's retreat in the stock market was broad and orderly. Decliners led advancers by a greater than 2-to-1 margin at both the NYSE and the Nasdaq. 24 of the 30 Dow components logged declines and all 11 S&P 500 sectors closed in the red. 

The communication services (-0.3%) sector saw the slimmest loss, boosted by a gain in Meta Platforms (META 288.73, +3.85, +1.4%). Other sectors exhibiting relative strength included the health care (-0.3%) and financials (-0.4%) sectors. Meanwhile, the utilities (-1.5%) and consumer discretionary (-1.1%) sectors fell to the bottom of the pack. 

Trading volume was extremely heavy today, reflecting the reconstitution of the Russell Indexes. 

  • Nasdaq Composite: +28.9% YTD
  • S&P 500: +13.3% YTD
  • Russell 2000: +3.4% YTD
  • S&P Midcap 400: +3.5% YTD
  • Dow Jones Industrial Average: +1.8% YTD

Reviewing today's economic data:

  • June IHS Markit Manufacturing PMI - Prelim 46.3; Prior 48.4
  • June IHS Markit Services PMI - Prelim 54.1; Prior 54.9

There is no U.S. economic data of note on Monday.

WSJ : Yellen Says More Bank Mergers Likely This Year

Yellen Says More Bank Mergers Likely This Year
Treasury secretary says she doesn’t see ‘huge threat,’ but comments show regulators bracing for turbulence

PARIS—Treasury Secretary Janet Yellen said more banks will probably seek to merge this year as higher interest rates and recent banking turmoil are making it more expensive for them to hang onto depositors.

Some smaller banks have said they are paying more on savings accounts after the Federal Reserve began quickly raising rates last year. Yellen said that trend has continued following the collapses of Silicon Valley Bank and Signature Bank in March, when small and midsize banks across the country saw depositors jump to larger institutions they believed were less vulnerable.

Paying higher rates for deposits is denting those banks’ profitability, Yellen said, which could become apparent in banks’ second-quarter earnings next month. She said she didn’t expect a return of the instability of earlier this year, but weaker earnings could put pressure on stock prices and potentially prompt some banks to merge.

“I don’t think it’s a huge threat to the sector, but there will probably be banks that end up wanting to merge,” Yellen said in an interview in Paris, where she is attending meetings on debt and climate projects in the developing world.

Yellen didn’t name any banks she was watching. She has previously said it was possible some banks could look to buy each other, but her new comments are the clearest sign that regulators are bracing for industry turbulence when banks report their second-quarter earnings.

Bank regulators have been reluctant to let big lenders buy each other recently. But some banking experts have said they would need to allow more mergers to shore up confidence in the system. Regulators seized First Republic Bank and sold the bulk of its operations to JPMorgan Chase in May.

Yellen said more consolidation in the banking industry could be healthy, though she has warned against the biggest banks becoming bigger.

“We certainly don’t want overconcentration and we’re pro-competition, but that doesn’t mean no” mergers, she said. “We have more banks, relatively speaking, in the United States than almost any country of which I’m aware.”

While she doesn’t expect any decline in earnings to send the industry back into crisis, federal regulators are watching for signs of trouble. The Financial Stability Oversight Council, an interagency panel of regulators led by Yellen, met last week to discuss the banking sector, focusing on risks banks face in their lending for commercial real estate.

Yellen said those risks primarily lie in the loans smaller banks have extended for office buildings.

A shift toward remote work has undermined the value of many office buildings, while higher interest rates have increased the cost of many commercial mortgages. That has left many landlords at risk of default, which could in turn create trouble for the smaller banks that hold much of that debt. About $270 billion in commercial mortgages held by banks is set to expire this year, according to data provider Trepp.

Yellen said she doesn’t expect office-building loan defaults to cause broad fallout, though it could cause additional banks to fail. She said smaller banks have generally been conservative in their lending.

“There may be some problems from this, but I think it’s going to be manageable,” she said. “But I don’t really think that this is systemic.”

>>> 'Double Trouble' Swirls Deep In Tropics As Cindy Forms With East Coast In Cr

'Double Trouble' Swirls Deep In Tropics As Cindy Forms With East Coast In Crosshairs

Tropical Storm Cindy formed Thursday night over the Atlantic Ocean, while Tropical Storm Bret churns in the Caribbean Sea. Two named storms swirling in June are an extraordinarily rare event.
As of 0500 ET, TS Cindy was located about 990 miles east of the Lesser Antilles, moving west-northwest at 15 mph with maximum sustained winds of 45 mph.
"On the forecast track, the system is expected to remain well east and northeast of the northern Leeward Islands through early next week," the NHC said. "Some strengthening is forecast during the next couple of days."
Computer models show TS Cindy's possible trajectory is near the US East Coast sometime late next week though nothing is concrete.
Meanwhile, Tropical Storm Bret is moving westward over the Caribbean Sea with maximum sustained winds of 60 mph.
According to meteorologist Philip Klotzbach at Colorado State University, the two tropical storms simultaneously forming in June have not happened since 1968.
Perhaps what's leading to increased tropical activity is a marine heatwave in the Atlantic.

>>> Half Of Russia's Strategic Missile Units Have Been Rearmed With Hypersonics:

Half Of Russia's Strategic Missile Units Have Been Rearmed With Hypersonics: Putin
BY TYLER DURDEN
FRIDAY, JUN 23, 2023 - 04:00 AM
Russian President Vladimir Putin has in fresh statements revealed the status of Russia's hypersonic and nuclear-capable arsenal within the context of the Ukraine war.
In early May, Ukraine's military claimed to have intercepted Russian ballistic missiles for the first time in the conflict, using a US-made anti-air defense system. The Kremlin rejected the claims, but did confirm it had been using hypersonic missiles within specific or limited operations and long-range launches.
Putin said Wednesday, as translated in TASS: "About half of the units of Russia’s Strategic Missile Force have been equipped with the latest Yars missile systems and are being rearmed with modern Avangard warheads."
He was speaking at an event honoring graduates of military academies and stressed the "unconditional priority" of missile readiness.
The Russian president continued:
"In light of the new challenges and invaluable experience of the special military operation we will continue to improve the Armed Forces in every possible way," he said, adding that the most important task here was to develop the nuclear triad as the key guarantee of Russia's military security and global stability.
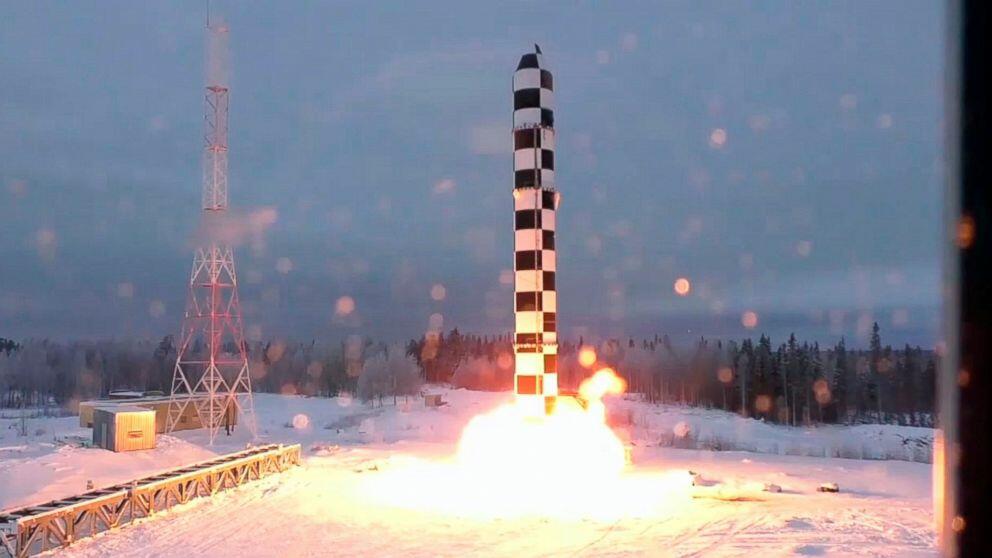
Putin also announced that new Sarmat missile launchers would enter duty soon.
"In the near future, the first launchers of the Sarmat complex with a new heavy missile will be put on combat duty," he said.
"The arsenals of aviation and naval components of strategic nuclear forces are being replenished in strict accordance with the timetable," he emphasized. "Russia’s nuclear triad allows for effective and guaranteed strategic deterrence and maintains the global balance of power," Putin concluded.
As for the feared Sarmat, which is Russia's new super-heavy intercontinental ballistic missile (ICBM), state media has also continued touting it will soon be deployed.
The ultra-large Sarmat missile has been dubbed in the West as the 'Satan II' - which is nuclear capable. In February of this year there were reports the Russian military tested the weapon, but the test may have failed.

>>> US Gapping down

Gapping down
In reaction to earnings/guidance
:

  • XAIR -6.4%

Other news:

  • SPCE -10.5% (entered into a distribution agency agreement for the offer and sale of up to $400000000 of shares of common stock)
  • ASLN -3.4% (ASLAN Pharmaceuticals announces publication in clinical immunology highlighting Eblasakimab's unique mechanism of action in the treatment of atopic dermatitis)
  • TYGO -3% (stock offering relates to warrants)
  • TAST -2.9% (stock offering by selling shareholder)
  • AVDL -2.6% (JAZZ seeks court action to declare FDA's approval of AVDL's Lumryz as unlawful)
  • AKRO -2.6% (Presents Analyses of Phase 2b HARMONY Study at the 2023 International Liver Congress Reinforcing and Characterizing EFX-Related Improvements in Liver Histopathology)
  • MSGE -2.4% (prices secondary offering of and concurrent share repurchase)
  • GNW -1.8% (discloses security breach)
  • JAZZ -1% (JAZZ seeks court action to declare FDA's approval of AVDL's Lumryz as unlawful)
  • MRNA -1% (completes submission to FDA for its updated COVID-19 vaccine)

Analyst comments:

  • UAA -2.6% (downgraded to Equal Weight from Overweight at Wells Fargo)
  • VTRS -2% (downgraded to Underweight from Equal Weight at Barclays)
  • ACN -1.4% (downgraded to Market Perform from Outperform at TD Cowen)

>>> US Gapping up

Gapping up
In reaction to earnings/guidance
:

  • APOG +6.6%, KMX +6.1%, SWBI +5.3% (also increases dividend)

Other news:

  • TRUP +15.8% (provides update on its rate filing approval status in CA and NY)
  • MGTX +9.3% (to present data from Phase 1 AQUAx study and provide update on phase 2 study of AAV-hAQP1)
  • IONQ +9.3% (increases its 2023 bookings expectations by 25%)
  • GSK +5.4% (provides Zantac litigation update)
  • ICPT +4.1% (receives Complete Response Letter from FDA for obeticholic acid as a treatment for pre-cirrhotic fibrosis due to NASH; to restructure to focus on rare and serious liver diseases; significantly reduces operating expenses)
  • EGLE +3.9% (to repurchase Oaktree Capital's entire 28% stake for $219.3 mln)
  • MMM +3.8% (enters into broad class resolution to support PFAS remediation)
  • BC +2.1% (provides update on previously reported IT security incident)
  • SAH +1.5% (suspends operations at eight EchoPark locations)

Analyst comments:

  • W +2.5% (upgraded to Market Perform from Underperform at MoffettNathanson)

FT : Italian oil major Eni buys Neptune Energy for $4.9bn

Italian oil major Eni buys Neptune Energy for $4.9bn
Carlyle-backed group in European sector’s biggest cash deal for almost a decade

Italy’s Eni has agreed to acquire private equity-backed Neptune Energy for $4.9bn in the largest cash deal in the European oil and gas sector for almost a decade.

London-headquartered Neptune produces oil and gas from fields in eight countries, including the UK, Norway, Germany, Algeria, the Netherlands and Indonesia, where it already shares a licence with the Italian energy major.

Under the terms of the deal announced on Friday, Eni will acquire Neptune for $2.6bn, while Var Energi — Eni’s Norwegian listed subsidiary — will acquire the company’s operations in Norway for $2.3bn. Eni owns 63 per cent of Var Energi.

The transaction is particularly significant given European oil majors such as Eni, BP and Shell have been more likely to sell oil and gas assets than to buy them since setting targets to cut carbon emissions and shift to greener forms of energy.

Eni chief executive Claudio Descalzi told the Financial Times that Neptune’s portfolio of gasfields, many of them close to European markets or with access to them, were an “exceptional fit”.

“Clearly the trend is acquiring renewables or other green [energy projects] . . . but this is a deal that is in line with our transition path,” he said.

Eni expects demand for natural gas, which has lower carbon emissions than oil, to continue to grow as countries use more of the fuel as part of the transition to renewable energy. Eni wants 60 per cent of its group-wide production to be gas by 2030.

“I am always very reluctant to do any kind of M&A deal, assets maybe, but companies [are] very rare,” Descalzi added. “This was I think an exceptional fit for Eni in this particular moment.”

State-owned China Investment Corporation owns 49 per cent of Neptune, with private equity groups Carlyle and CVC Partners owning 30.6 per cent and 20.4 per cent respectively.

Neptune produces about 135,000 boe/d, roughly three-quarters of which is natural gas. About 10 per cent of its production comes from UK waters.

Since acquiring the assets from French utility Engie in 2017 for $3.9bn, Neptune’s shareholders had invested more than $4bn in expanding the resource base, reducing the carbon intensity of operations and developing the potential for future carbon capture and storage, said Bob Maguire, a managing director at Carlyle.

“For that reason, it’s an attractive business. It represents an opportunity for a strategic buyer like Eni both to replenish its reserve base . . . but also to be accretive to its own carbon metrics,” he added, pointing to the lower carbon intensity of much of Neptune’s production, particularly compared with conventional oil.

Neptune’s owners had initially targeted an initial public offering last year but failed to drum up enough interest from public markets, which are increasingly reluctant to invest in oil and gas producers.

Founded in 2015 by Sam Laidlaw, the former chief executive of Centrica, Neptune made a net profit last year of $924.4mn from revenues of $4.6bn, and had net debt of $1.7bn. The shareholders have received $2.7bn in dividends since 2018, according to Neptune.

Carlyle declined to comment on the return it will make on its investment in Neptune if the deal is approved.

Shares in Eni, which is 30 per cent owned by the Italian government, were down 1.55 per cent on Friday morning, while Var Energi stock was up 3 per cent.

Parminder Singh, a managing director at Carlyle, said the investment had demonstrated the fund’s thesis that returns can be made by investing in oil and gas assets that are often “overlooked by the market”.

“There’s going to be significant oil and gas production for decades to come. We know that but someone has to own that in the right way,” he said.

In the UK and the Netherlands, Neptune is developing CCS projects that aim to pump more than 9mn tonnes of carbon dioxide a year from British and Dutch emitters into the company’s depleted reservoirs.

If successful, that would exceed the emissions from Neptune’s own operations and the use of the fuel it sells. “This is a business decision, we can either decommission that infrastructure or repurpose it,” Singh said. “The ambition is to store more carbon than we emit.”

The transaction is expected to close by the end March 2024. Neptune’s assets in Germany are not part of the deal and will continue to operated by the current shareholders.