>>> Dow +0,04% S&P -0,09% Nasdaq -0;16% Russell +0.61%

Closing Stock Market Summary
The S&P 500 and Nasdaq Composite closed near their lows of the day, registering slim declines due to relative weakness in the mega cap space. The Dow Jones Industrial Average, meanwhile, eked out a 0.04% gain while the Russell 2000 and S&P Mid Cap 400 rose 0.6% and 0.4%, respectively.

There was an underlying positive bias throughout the session, but buyer enthusiasm faded somewhat as the session progressed. Shortly after the open, advancers led decliners by a better than 9-to-2 margin at the NYSE and a better than 3-to-1 margin at the Nasdaq. At the close, advancing issues had a less than 2-to-1 lead at the NYSE and a 3-to-2 lead at the Nasdaq. The equal-weighted S&P 500 logged a 0.4% gain, but had been up as much as 1.1% at its high.

Six of the S&P 500 sectors closed higher while five of them declined. The real estate sector (+0.7%) led the gainers while the communication services sector (-1.1%) saw the biggest decline due to its lagging mega cap constituents.

A drop in Treasury yields provided a measure of support for stocks in this seasonally strong period for the market. The 2-yr note yield settled seven basis points lower than yesterday at 4.66% and the 10-yr note yield declined seven basis points to 4.27%.

Those moves were partially a reaction to some pleasing inflation data out of Germany, Spain, and Australia, and the notion that the Fed could cut rates in the first half of 2024. Notably, however, Richmond Fed President Barkin (2024 FOMC voter) said today at the CNBC CFO Council Summit that he thinks it is premature to talk rate cuts and that he is not taking the possibility of further rate hikes off the table, as he believes inflation is likely to be more stubborn than he would like it to be.

Still, the fed funds futures market is still pricing in a 79.8% probability of a rate cut at the May FOMC meeting versus a 54.7% probability one week ago, according to the CME FedWatch Tool.

Other factors that helped to drive today's positive bias included an upward revision to Q3 real GDP to 5.2% from 4.9%, General Motors (GM 31.60, +2.71, +9.4%) announcing an accelerated $10 billion share buyback program and 33% increase in its dividend, and the favorable response to earnings results from CrowdStrike (CRWD 234.44, +22.09, +10.4%), NetApp (NTAP 89.54, +11.43, +14.6%), Intuit (INTU 577.23, +12.16, +2.2%), Workday (WDAY 263.49, +26.16, +11.0%), and Foot Locker (FL 27.67, +3.83, +16.1%).

Market participants were also digesting the Fed's November Beige Book, which did not move the stock or bond markets that much. The main point from the release was that, on balance, economic activity slowed since the previous report and demand for labor continued to ease.
  • Nasdaq Composite: +36.2%
  • S&P 500: +18.5%
  • Dow Jones industrial Average: +5.7%
  • S&P Midcap 400: +4.9%
  • Russell 2000: +2.4%

Reviewing today's economic data:
  • Weekly MBA Mortgage Applications Index 0.3%; Prior 3.0%
  • Q3 GDP - Second Estimate 5.2% ( consensus 4.9%); Prior 4.9%; Q3 GDP Deflator - Second Estimate 3.6% ( consensus 3.8%); Prior 3.5%
    • The key takeaway from the report is that the U.S. economy was effectively booming in the third quarter despite higher interest rates, aided by a strong labor market and disinflation that fueled healthy consumer spending activity.
  • October Adv. Intl. Trade in Goods -$89.8 bln; Prior was revised to -$86.8 bln from -$85.8 bln
  • October Adv. Retail Inventories 0.0%; Prior was revised to 0.4% from 0.9%
  • October Adv. Wholesale Inventories -0.2%; Prior was revised to 0.1% from 0.0%

Looking ahead, Thursday's economic calendar features:
  • 8:30 ET: Weekly Initial Claims ( consensus 215,000; prior 209,000), Continuing Claims (prior 1.840 mln), October Personal Income ( consensus 0.2%; prior 0.3%), Personal Spending ( consensus 0.2%; prior 0.3%), PCE Prices ( consensus 0.1%; prior 0.4%), and Core PCE Prices ( consensus 0.2%; prior 0.3%)
  • 9:45 ET: November Chicago PMI ( consensus 45.0; prior 44.0)
  • 10:00 ET: October Pending Home Sales (consensus -2.3%; prior 1.1%)
  • 10:30 ET: Weekly natural gas inventories (prior -7 bcf)
>>> Victoria's Secret misses by $0.08, reports revs in-line; guides Q4 EPS in-li

Victoria's Secret misses by $0.08, reports revs in-line; guides Q4 EPS in-line, revs in-line; guides FY24 EPS in-line (23.57 +1.24)
  • Reports Q3 (Oct) loss of $0.86 per share, excluding non-recurring items, $0.08 worse than the FactSet Consensus of ($0.78) and vs company guidance of ($0.70)-($0.90); revenues fell 4.0% year/year to $1.27 bln vs the $1.27 bln FactSet Consensus.
    • Total comparable sales decreased 7% year-over-year.
    • "Our sales trend in North America continued to improve as planned each month throughout the third quarter with October being our strongest month."
  • "We are excited with early holiday sales trends in November in North America both in our stores and through our digital experiences online. The November sales and margin result was our best monthly performance in nearly two years."
  • Co issues in-line guidance for Q4, sees EPS of $2.20-2.60, excluding non-recurring items, vs. $2.44 FactSet Consensus; sees Q4 revs increasing 2-4%, which translates to ~$2.06-2.10 bln vs. $2.07 bln FactSet Consensus.
  • Co issues in-line guidance for FY24, sees EPS of $1.85-2.25, excluding non-recurring items, vs. $2.17 FactSet Consensus. The Company is forecasting full year 2023 net sales to decrease in the range of 2% to 3% compared to last year.

>>> PVH beats by $0.16, misses on revs; guides Q4 EPS below consensus, revs belo

PVH beats by $0.16, misses on revs; guides Q4 EPS below consensus, revs below consensus; increases repurchase plan by $150 mln (91.50 +1.43)
  • Reports Q3 (Oct) earnings of $2.90 per share, excluding non-recurring items, $0.16 better than the FactSet Consensus of $2.74; revenues rose 3.6% year/year to $2.36 bln vs the $2.41 bln FactSet Consensus.
  • Co issues downside guidance for Q4 (Jan), sees EPS of $3.45, excluding non-recurring items, vs. $3.51 FactSet Consensus; sees Q4 revs to decline 3-4% yr/yr, implying $2.39-2.41 bln vs. $2.59 bln FactSet Consensus.
  • The Company completed its previously announced sale of its Heritage Brands intimate apparel business on November 27, 2023. The $160 million cash purchase price is subject to adjustment. There is a potential earn out of up to $10 million based on calendar year 2024 net sales of a portion of the sold business.
  • Planned share repurchases in 2023 to increase to approximately $550 million from up to $400 million previously.

>>> Snowflake beats by $0.09, beats on revs, product revenue up 34%, well above

Snowflake beats by $0.09, beats on revs, product revenue up 34%, well above its guidance, guides for Q4 product revenue growth of 29-30% (175.47 +3.92)
  • Reports Q3 (Oct) earnings of $0.25 per share, $0.09 better than the FactSet Consensus of $0.16; revenues rose 31.8% year/year to $734.2 mln vs the $713.75 mln FactSet Consensus.
  • Non-GAAP operating margin of 10%.
  • Product revenue of $698.5 mln, up 34%, and well above its guidance of $670-$675 mln.
  • Net revenue retention rate of 135%.
  • Guides for Q4 product revenue of $716-$721 mln, representing yr/yr growth of 29-30%. Guides for Q4 non-GAAP operating margin of 4%.

>>> Salesforce beats by $0.06, reports revs in-line; guides Q4 EPS above consens

Salesforce beats by $0.06, reports revs in-line; guides Q4 EPS above consensus, revs in-line (230.35 +5.43)
  • Reports Q3 (Oct) earnings of $2.11 per share, excluding non-recurring items, $0.06 better than the FactSet Consensus of $2.05; revenues rose 11.3% year/year to $8.72 bln vs the $8.71 bln FactSet Consensus.
    • Current Remaining Performance Obligation of $23.9 Billion, up 14% Y/Y, 13% CC.
    • Non-GAAP Operating Margin of 31.2%.
  • Co issues guidance for Q4, sees EPS of $2.25-2.26, excluding non-recurring items, vs. $2.18 FactSet Consensus; sees Q4 revs of $9.18-9.23 bln vs. $9.22 bln FactSet Consensus.

(ZH) Panama Canal Chaos Might Spread To Suez, Greek Shipping Exec Warns

Panama Canal Chaos Might Spread To Suez, Greek Shipping Exec Warns

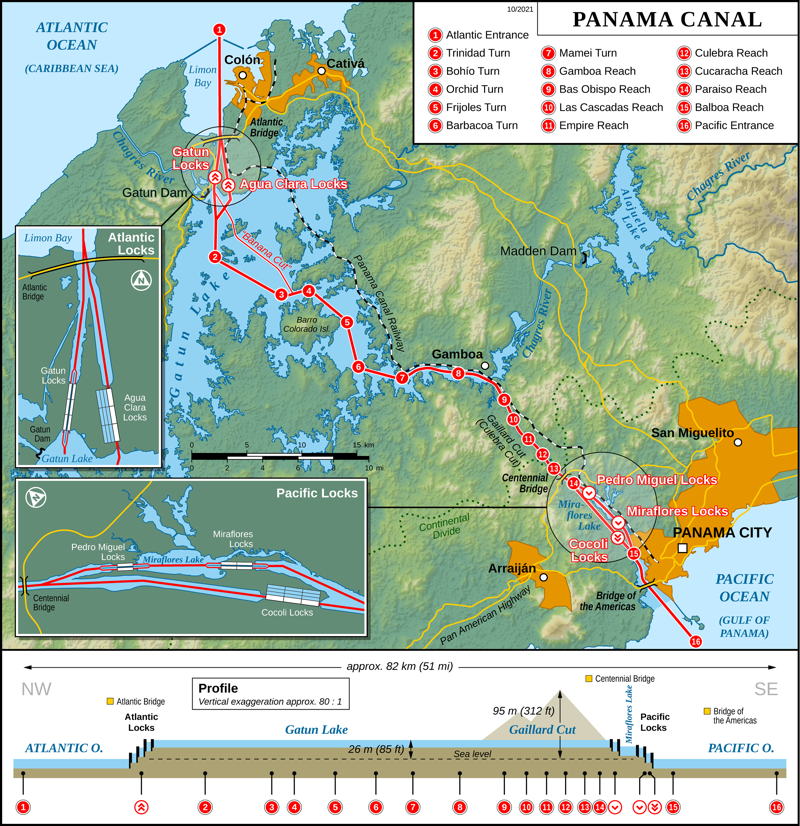
The giant bottleneck building at both entrances of the Panama Canal might spread to Egypt's Suez Canal. This is according to Bloomberg, which quoted a top executive at Greek shipping firm Angelicoussis Group during a conference in Athens.

Sveinung Støhle, the company's deputy chief executive officer, said, "Suez will need to take a lot more vessels" because the drought-stricken Panama Canal has sailing restrictions.

He noted that the Suez Canal, which serves as an alternative route for ships traversing between the US and Asia, has historically managed congestion issues "very well over the years," making it "less of an issue, but obviously, it's something you need to be aware of."

The bottleneck at the Panama Canal has only allowed companies with pre-booked slots to sail the canal, Støhle said. He said only four or five LNG vessels are sailing the canal each month, down from about 30 before restrictions were put in place earlier this year.

"If you can't go via the Panama Canal, you must add one more ship for the same volume," he said. "Where do you get the ships from? That's is going to be a challenge."
* * *
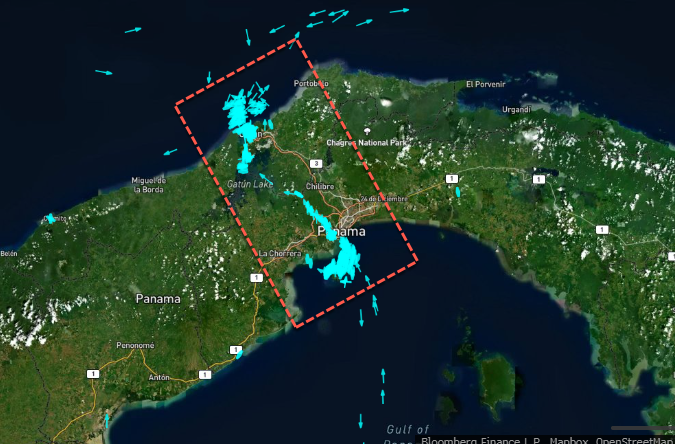
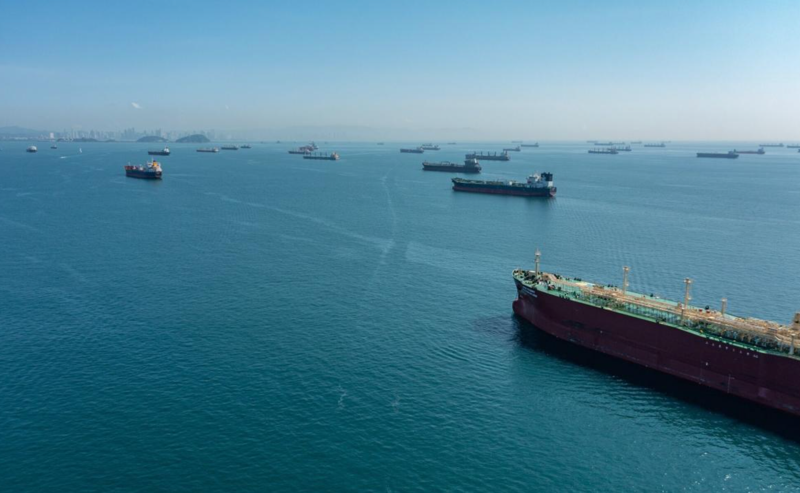
Panama Canal is one of the world's most important trade routes. In the second half of this year, we have detailed in-depth about a parking lot of commercial vessels building on either side of the canal amid worsening drought conditions across Central America. This has reduced the number of ships sailing through the waterway, as the bottleneck has forced one of the world's largest operators of chemical tankers to reroute its fleet.

Bloomberg reports that London-based Stolt-Nielsen has begun to charge customers for longer routes, avoiding the massive bottleneck at the Panama Canal.
The canal has been battered by a severe drought this year caused by the El Niño phenomenon (read: here & here). As a result, canal authorities have imposed sailing restrictions to 25 a day. And if conditions worsen, restrictions could end up with only 18 vessels transiting the waterway daily by February. For some context, the maximum number of sustainable bookings is between 38-40 per day.
Instead of the Panama Canal, Stolt-Nielsen's chemical tankers are being diverted around the Cape of Good Hope or through the Strait of Magellan off the tip of South America. The extra distance has forced customers to pay additional transiting costs. Those numbers weren't revealed in the report.

"Stolt Tankers has found that the service through the Panama Canal has become increasingly unreliable in recent months," the company said in an email response to Bloomberg.

The email continued, "Our customers need reassurance that their cargo will arrive on time to avoid negatively impacting their supply chains, therefore, we have been rerouting our ships via the Suez Canal."

Experts believe canal authorities will increase traffic once the rainy season begins mid-2024. Some vessels have waited nearly three weeks to pass through the waterway. According to Stolt-Nielsen, other shipping companies are notifying customers about similar strategies to manage the congestion at the canal.

FT : Farfetch shares plunge despite talk of founder taking it private

Farfetch shares plunge despite talk of founder taking it private
Online luxury retailer tells investors past forecasts ‘should no longer be relied upon’

Shares in Farfetch fell by as much as 50 per cent on Wednesday, despite reports that its founder could take the luxury online retailer private following a collapse in its market value.

Farfetch had been due to report quarterly results on Wednesday but postponed the announcement, saying it would “not be providing any forecasts or guidance at this time, and any prior forecasts or guidance should no longer be relied upon”.

Richemont, the Swiss luxury group that has been one of the ecommerce group’s main backers, also said it had no plans to invest any more money in Farfetch. 

José Neves, who launched the online retailer in the central London district of Clerkenwell in 2008, is exploring the option of taking it private with advisers at JPMorgan and Evercore, according to people with knowledge of the situation.

Farfetch, JPMorgan and Evercore declined to comment.

The company’s market value peaked at $23bn in early 2021 as pandemic luxury shopping boomed, but has since shrunk to below $400mn. The shares have lost more than 95 per cent of their value since it went public in New York in 2018. They rose by 22 per cent in US trading on Tuesday after the Daily Telegraph first reported the potential plan to take it private.

Neves owns 15 per cent of Farfetch but controls 77 per cent of the voting rights thanks to a dual-class share structure. Other large investors besides Richemont include Alibaba, the Chinese ecommerce group, and Artemis, the family holding company of the billionaire Pinault family.

Richemont, which owns jewellers Cartier and Van Cleef & Arpels, agreed to sell a stake in its lossmaking Yoox Net-a-Porter online fashion and accessories platform to Farfetch in 2020, but the deal has yet to close due to regulatory delays. It is unclear what a delisting would mean for the transaction.

Richemont on Wednesday said that it was “carefully monitoring the situation” but had no plans to put new funds into Neves’ company. 

“Richemont would like to remind its shareholders that it has no financial obligations towards Farfetch and notes that it does not envisage lending or investing into [the company],” the Swiss group said. 

Farfetch sells luxury goods to consumers online, obtaining inventory from independent boutiques and directly from some luxury brands. It also licences its technology to brands and department stores including Harrods, which operate their own websites.

However online shopping in luxury differs from ecommerce in other sectors because big brands like Hermes and Louis Vuitton tightly control distribution and see their high-end stores as key to wooing buyers. The top brands sell online via their own websites and are reluctant to relinquish control over their pricing and carefully curated images.

Even as its revenue has expanded and its staff swelled to over 6,000 at its peak in 2021, Farfetch has consistently reported operating losses over the past five years, which Neves has justified by saying the company was still in investment mode. Its business model is also burdened by a high cost base and thin margins. 

Farfetch’s deal with Richemont received the go-ahead from EU regulators last month. Under the terms, Farfetch would take a 47.5 per cent stake in Yoox Net-a-Porter and Richemont would receive Farfetch shares in exchange. A system of put and call options would also leave Farfetch with a chance to acquire the remainder of the company in the next five years, or allow Richemont to sell to other investors or list shares. 

Yoox Net-Porter has become an expensive problem for Richemont, which has lost market share to nimbler competitors, including Farfetch, and fumbled technology upgrades. Richemont has taken the ecommerce platform off its balance sheet and has had to write it down several times, to the tune of over €3bn. 

However, the value of Farfetch shares has declined drastically since the deal was struck, from around $10 each to around $1 currently. 

“Richemont would have to accept a significantly lower value for Yoox-Net-a-Porter or agree on new deal terms with Farfetch. Taking Farfetch private could facilitate a compromise on new terms,” said Rogerio Fujimori at Stifel. 

Given the collapse in Farfetch’s share price and Neves’s control over voting rights, “the market may see a buyout as the best solution for [the company] to resolve its problems without the pressure from external shareholders”, he added.