(ZH) Something Broke In Markets On Thursday

Something Broke In Markets On Thursday

This Friday is going to be a session for active short-term traders, and it will likely be unpleasant for investors.

Something broke in markets on Thursday. There are a few things that worry me about the latest bout of risk aversion. This is in context that I’ve been an unrelenting stocks bull since the December Fed meeting...

But now I’m uneasy...

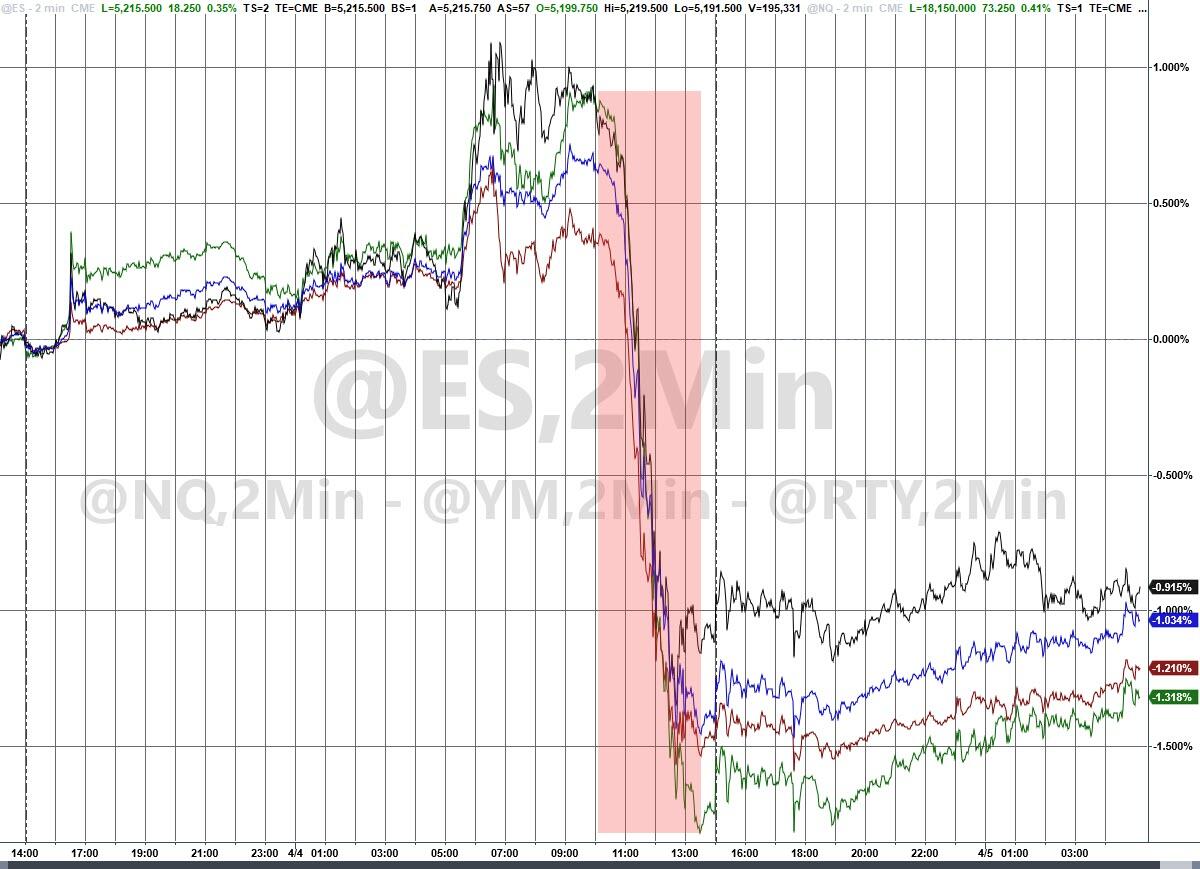
The Thursday selloff confused people.
Initially, many blamed the comments from Fed’s Kashkari about there potentially being no US rate cuts this year.
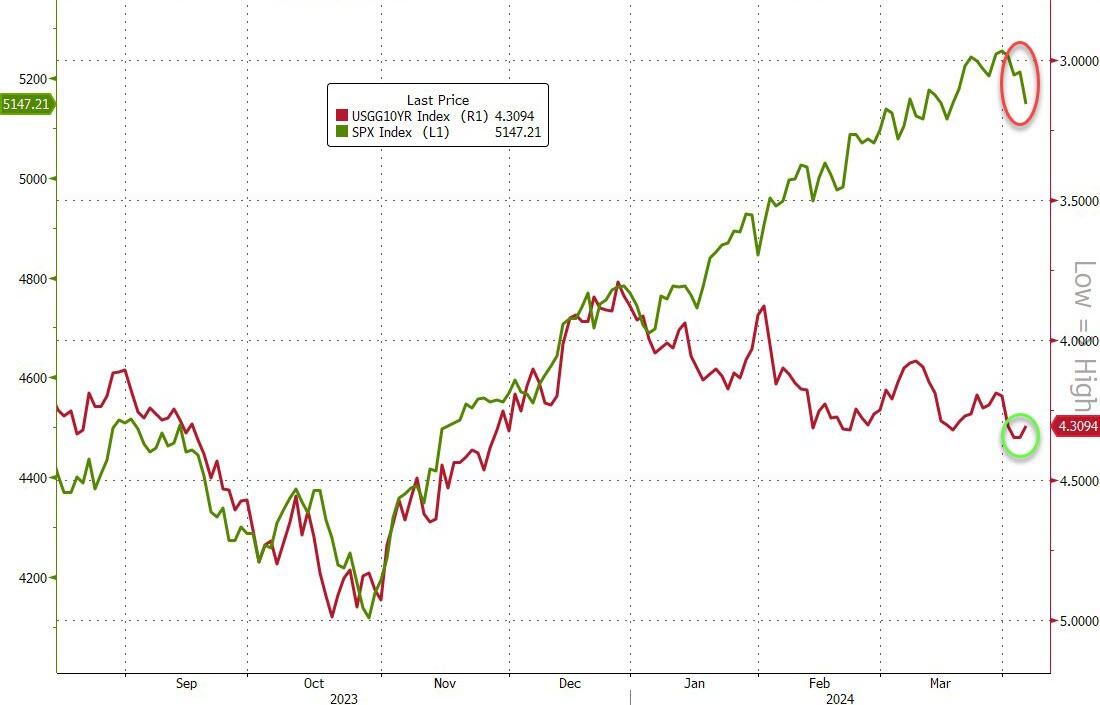
However, a quick look at a few charts shows that (a) yields fell rather than climbed, so his hawkish lines did not impact, and (b) equities started selling off before his headlines.
It’s never a good sign when people struggle to identify why stocks have a relatively large swoon.

If an asset is weak without an obvious catalyst, it suggests that it can really get destroyed if a genuine risk materializes.

For good order, the weakness in E-minis coincided with the oil price rise that in turn followed the Netanyahu headlines.

We have key US data this morning at a time of vulnerability for the market in terms of the Fed narrative.

We’ve run a long way on the idea of the Fed being dovish despite a strong US economy.

We’re getting closer to the point where we must acknowledge that either the Fed won’t be easing soon, OR the economy is in more trouble than we thought.

It means that we’re in the unusual-in-recent-times setup where a big surprise in either direction could hurt stocks today.
(For clarity and consistency, I would only see this as a multi-week consolidation/retrenchment and not some long-term bearish turning point).
Middle East tensions have escalated substantially just before the weekend, further supporting the idea of taking some risk off the table.
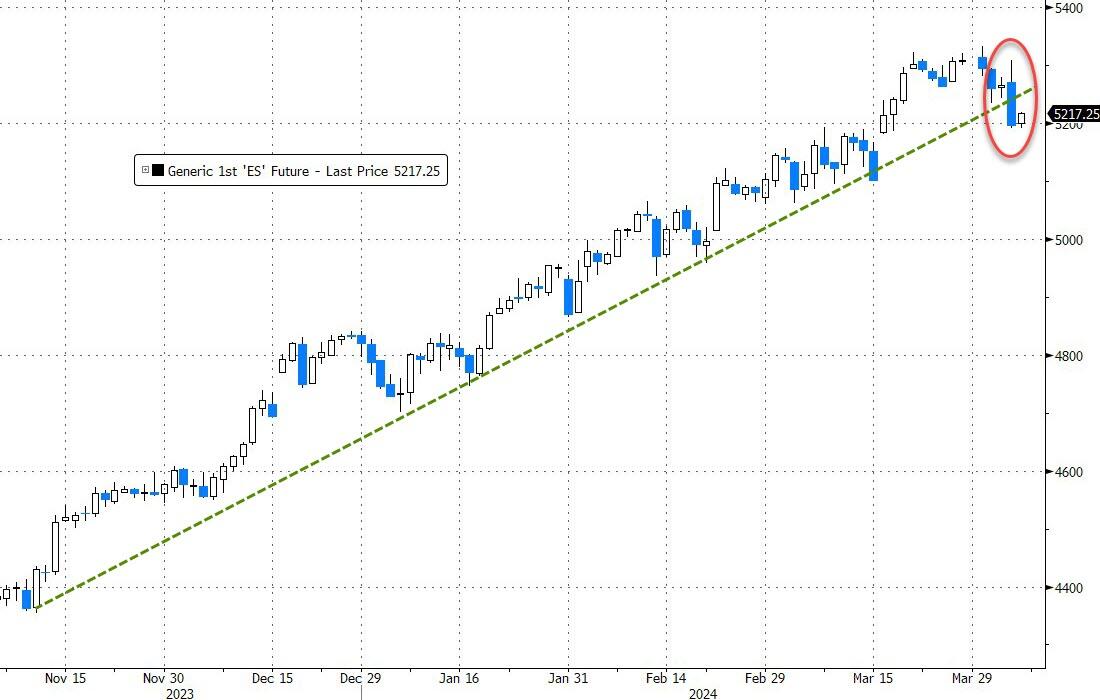
And, let’s face it, the 5-month E-minis chart below just looks horribly negative. If you’ve ridden the rally until here, this chart is your siren call to take some profits.
And if you’ve been desperate to fight these bubblicious markets, you have now been given the green light.

I remain structurally bullish for the year ahead and yet if I was back in a trading seat, I’d probably want to be tactically underweight into the weekend.

It’s that kind of contradiction that will make this Friday an unpleasant markets session for all but the most nimble of traders.

TechCrunch : As deal rumors fly, Alphabet and HubSpot would be a strange pairing

As deal rumors fly, Alphabet and HubSpot would be a strange pairing

Reuters reported on Thursday that Google’s parent company, Alphabet, is exploring the possibility of buying Boston-based HubSpot, a CRM and marketing automation company with a market cap of over $33 billion – a number that has been climbing on those reports.

If such a deal were to happen, the cost would likely be pretty substantial, involving some significant premium over the current value. It would have to be to motivate the company to sell and become part of the search giant. It’s worth noting that the two companies have a relationship already — a partnership to use Google ads to drive sales in HubSpot — which can sometimes be the start of an acquisition discussion like this.

While Google/Alphabet has been extremely acquisitive over the years, the largest deal that it’s ever made was spending $12.5 billion for Motorola Mobility in 2011. It later sold it to Lenovo for just $2.91 billion, so it would have reason to be gun shy on a much larger price tag. More recently the largest deal involved spending $5.4 billion for security intelligence platform Mandiant in 2022. Google usually stays under $3 billion, so a deal of this scope would be very much out of character for the company.

When you combine that with the austerity program that most tech companies have been on in recent years, and a warning from Google CEO Sundar Pichai in January that more job cuts were coming, it’s not the type of deal that seems likely in a belt tightening climate, and certainly one that might be tough to justify to employees if those kind of optics actually matter. Yet with a huge cash horde of $110 billion on hand as of the end of last year, it certainly has the cash to make the move if it wants to.

Another issue the company could face in trying to buy HubSpot is a hostile regulatory environment for large deals. The U.S., the U.K and the EU have been monitoring large deals closely these days. Some, like Adobe’s attempt to buy Figma for $20 billion didn’t make it to the finish line because of competitive concerns. It’s not clear that Alphabet would face those same concerns with a CRM tool. HubSpot faces pretty powerful competition from Adobe and Salesforce, two well-capitalized firms, so this wouldn’t give Google a lock on that market by any means, but if there’s a risk, there’s sure to be a termination fee involved to hedge against that, another factor the company would need to take into consideration.

The question is what is the likelihood of such a deal coming to fruition and what would it give the companies that they can’t get from the existing partnership. As one analyst said to me, it doesn’t feel likely, but you never know.

WSJ : Telecom Italia Gets $1.6 Bln in Bridge Financing Until Close of Network Sa

Telecom Italia Gets $1.6 Bln in Bridge Financing Until Close of Network Sale
The financing deal, with a maturity of up to 18 months, strengthens the company’s liquidity structure

Telecom Italia TIT -1.23%decrease; red down pointing triangle said it signed an agreement for 1.5 billion euros ($1.63 billion) in bridge financing to cover its needs until completion of a planned sale of its fixed-network unit.

The Italian telecommunications company said Friday that the deal, with a maturity of up to 18 months, strengthens its liquidity structure and seeks to cover its refinancing needs until the network deal is completed.

Conditions of the agreement are in line with market benchmarks, the company said.

WSJ : Samsung Doubles Down on Texas as U.S. Chip Epicenter

Samsung Doubles Down on Texas as U.S. Chip Epicenter
South Korean firm ramps up investment to $44 billion for hub near Austin making advanced semiconductors

Samsung 005930 -0.94%decrease; red down pointing triangle Electronics plans to more than double its total semiconductor investment in Texas to roughly $44 billion, according to people familiar with the matter, a significant breakthrough in the U.S.’s quest to make more of the world’s cutting-edge chips.

The South Korean company’s new spending will be concentrated in Taylor, Texas, where Samsung is building a semiconductor hub and has other nearby existing operations, the people said. The additions include a new chip-making factory, and a facility for advanced packaging and research and development.

Samsung is one of just three firms, along with Intel and Taiwan Semiconductor Manufacturing, capable of producing advanced logic semiconductors vital to artificial intelligence and national defense. These companies sit at the heart of the Biden administration’s push to strengthen the U.S.’s chip-making capabilities, as Washington simultaneously seeks to undercut Beijing’s tech advances.

To help finance the broader Texas expansion, Samsung is expected to receive billions of dollars in subsidies from the U.S. Chips Act, the people said. Talks with the Commerce Department remain ongoing, though Samsung is expected to receive one of the largest payouts given to a single company.

An event to announce Samsung’s broadened investments is expected to be held on April 15 in Taylor, according to the people familiar with the matter. Samsung declined to comment. The Commerce Department declined to comment, saying that it is unable to discuss any specific company projects.

Samsung’s additional investments add to the $17 billion that the company had previously committed more than two years ago to Taylor, located just outside of Austin, for a cutting-edge chip-making plant.

The factory broke ground in 2022, with plans to start mass production as early as this year. The costs of building this first chip-making plant have increased due to inflation and other factors, requiring several billion dollars in extra investment, according to people familiar with the matter.

The second Taylor-based chip factory is expected to cost more than $20 billion, the people said. Samsung’s R&D efforts are expected to be warehoused inside those two plants. The size of the investments in these two factories could shift depending on market conditions.

The planned facility for advanced packaging—a key final step in the production of high-end AI chips like those made by Nvidia—will have a price tag of roughly $4 billion, the people said.

Earlier on Friday, Samsung said it expects a 10-fold increase in its first-quarter operating profit, to roughly $4.9 billion. This tops industry analysts’ estimates, as the chip industry awakens from a protracted downturn.

Samsung’s supersize chip investment in Texas adds fresh momentum to one of President Biden’s marquee domestic agendas as he seeks re-election in November. Many of the highest-profile projects have seen costs rise and face delays.

U.S. chip-making dominance has been a priority for Washington, which has earmarked tens of billions of dollars in subsidies to woo back local production that had migrated to Asia.

The Chips Act, which passed two years ago, set aside $53 billion in grants for projects like Samsung’s—and the money has only recently begun to flow.

Intel was awarded $8.5 billion for several chip plants planned in the U.S. last month, following a $1.5 billion grant to GlobalFoundries for projects in New York and Vermont in February. TSMC and Idaho-based Micron, a memory chip maker, are also expected to receive grants under the program.

The spree of projects aims to bolster domestic supplies of critical semiconductors. The U.S. share of chip-making declined to about 12% in 2020 from 37% in 1990, a fall that is increasingly seen as a national-security liability in an age when chips underpin advanced weapons, cyberwarfare and AI.

In a speech in February, Commerce Secretary Gina Raimondo said that based on the level of industry interest in Chips Act funding, the U.S. was on track to produce roughly 20% of the world’s most advanced logic chips by the end of this decade.

Samsung’s big bet in Texas is comparable to those made by its chief rivals. TSMC is building two chip-making factories in Arizona, with a projected investment of $40 billion. Intel’s total investment in U.S. projects in the next five years is expected to exceed $100 billion.

Samsung began semiconductor operations in Austin in 1996, starting with memory chips. The site later transitioned into the contract chip-manufacturing business. The Taylor chip making plants are expected to be filled with equipment for producing the industry’s cutting-edge logic chips for customers.

Two years ago, Samsung floated the prospect in filings made to the Texas controller’s office of potentially investing upward of $200 billion toward building 11 new chip-making plants in Texas over the next two decades.

Samsung, the world’s largest memory maker by revenue, is also racing alongside South Korea’s SK Hynix and Micron for leadership in high bandwidth memory, a critical component of artificial-intelligence computing.

HBM can speed up computing times by stacking multiple DRAM memory—used commonly for helping devices or servers multitask—on top of each other and merging them as one.

HBM has become the go-to type of memory to work in tandem with graphic-unit processors made by the likes of Nvidia that power AI computing. To enable faster data-processing speeds, the two types of chips are currently bundled together using “2.5-D” packaging techniques. Major chip makers including TSMC, Samsung and Intel are investing in 2.5-D packaging as well as next-generation 3-D packaging.

Earlier this week, South Korea’s SK Hynix announced its plans for a $3.9 billion facility in West Lafayette, Indiana, for advanced chip-packaging, mainly for HBM. SK Hynix is the exclusive partner to Nvidia for the most-advanced HBM currently in the market.

Samsung’s planned advanced chip-packaging facility is expected to carry out packaging for HBM and provide 2.5-D and 3-D packaging technologies, according to people familiar with the matter.

At one of his company’s events last month for AI developers, Nvidia Chief Executive Jensen Huang said his company was in the process of determining whether Samsung’s next-generation “HBM3E” product could be a viable option. He stopped by Samsung’s booth and autographed one of the chips. He wrote: “Jensen approved.”

FT : Thames Water parent company says it has defaulted on debt

Thames Water parent company says it has defaulted on debt
Formal notice to bondholders fires starting gun on potentially messy restructuring

Thames Water’s parent company has sent a formal notice to bondholders informing them that it has defaulted on its debt, firing the starting gun on a potentially messy restructuring at the owner of Britain’s largest water utility.

On Friday, one of the holding companies that owns Thames Water announced that interest payments due earlier this week on a £400mn bond “have not been paid” and it issued a “formal notice of default”.

The bonds were issued by Kemble Water Finance, which sits above the nearly £15bn of debt at the Thames Water utility companies. Those companies should be unaffected by the move. Kemble last week told bondholders that it intended to stop paying interest on bonds.

The default threatens to wipe out the stakes of Thames Water’s nine shareholders, which include the Chinese and Abu Dhabi sovereign wealth funds as well as Canadian and UK pension funds. The shareholders last week said that actions by water regulator Ofwat had made the company “uninvestable”.

>>> US Research Calls

Research Calls
  • Upgrades:
    • Acadia Realty Trust (AKR) upgraded to Buy from Neutral at BofA Securities; tgt raised to $20
    • Agilent (A) upgraded to Buy from Hold at Stifel; tgt raised to $163
    • AngioDynamics (ANGO) upgraded to Outperform from Perform at Oppenheimer; tgt $12
    • Cinemark (CNK) upgraded to Overweight from Underweight at Wells Fargo; tgt raised to $23
    • Eaton (ETN) upgraded to Outperform from Sector Perform at RBC Capital Mkts; tgt raised to $371
    • First Horizon (FHN) upgraded to Outperform from Mkt Perform at Keefe Bruyette; tgt raised to $18
    • Fox Corporation (FOXA) upgraded to Buy from Neutral at Seaport Research Partners; tgt $37
    • Krispy Kreme, Inc. (DNUT) upgraded to Overweight from Neutral at Piper Sandler; tgt raised to $20
    • Lindsay Corp (LNN) upgraded to Buy from Neutral at Northcoast; tgt $142
    • Ollie's Bargain Outlet (OLLI) upgraded to Buy from Hold at Loop Capital; tgt raised to $90
    • Outset Medical (OM) upgraded to Buy from Neutral at CL King; tgt $6
    • Public Storage (PSA) upgraded to Overweight from Equal Weight at Wells Fargo; tgt raised to $310
    • Royal Bank of Canada (RY) upgraded to Outperform from Market Perform at BMO Capital Markets
    • Snowflake (SNOW) upgraded to Buy from Neutral at Rosenblatt; tgt $185
    • SoFi Technologies (SOFI) upgraded to Mkt Perform from Underperform at Keefe Bruyette; tgt raised to $7.50
    • Tanger Factory (SKT) upgraded to Neutral from Underperform at BofA Securities; tgt raised to $31
    • Western Digital (WDC) upgraded to Buy from Neutral at Rosenblatt; tgt raised to $115
  • Downgrades:
    • Achilles Therapeutics (ACHL) downgraded to Neutral from Overweight at Piper Sandler; tgt lowered to $2
    • Altice USA (ATUS) downgraded to Underweight from Equal Weight at Wells Fargo; tgt lowered to $1
    • Core & Main (CNM) downgraded to Neutral from Buy at Citigroup; tgt raised to $64
    • Energous (WATT) downgraded to Neutral from Buy at Ladenburg Thalmann; tgt lowered to $2
    • Gulfport Energy (GPOR) downgraded to Sector Weight from Overweight at KeyBanc Capital Markets
    • Kimco Realty (KIM) downgraded to Neutral from Buy at BofA Securities; tgt lowered to $20
    • Plug Power (PLUG) downgraded to Sell from Neutral at Citigroup; tgt $2
    • Retail Opportunity Investments (ROIC) downgraded to Underperform from Neutral at BofA Securities; tgt lowered to $12
    • Scotts Miracle-Gro (SMG) downgraded to Hold from Buy at Truist; tgt raised to $75
    • ShockWave Medical (SWAV) downgraded to Peer Perform from Outperform at Wolfe Research
  • Others:
    • Ardelyx (ARDX) initiated with an Outperform at Leerink Partners; tgt $14
    • Farmers and Merchants (FMAO) initiated with a Market Perform at Hovde Group; tgt $22
    • Gossamer Bio (GOSS) resumed with an Outperform at Wedbush; tgt $4
    • Immunic (IMUX) initiated with a Buy at Brookline
    • Ovid Therapeutics (OVID) initiated with an Outperform at Wedbush; tgt $8
    • Vertiv (VRT) initiated with an Outperform at Oppenheimer; tgt $96
    • Wolfspeed (WOLF) initiated with a Neutral at Mizuho; tgt $30

>>> US Early premarket gappers

Early premarket gappers
  • Gapping up:
    • GRIN +25.3%, KRUS +7.7%, OLPX +3.4%, CRBU +1.8%, TECK +1%, UTI +0.7%, ACM +0.7%
  • Gapping down:
    • IVVD -4.2%, HIW -2.3%, SNX -1.8%, HUT -1.8%, HIVE -1.3%, SNY -1.2%, TDOC -1.1%, CCCS -0.9%

FT : Hedge funds circle struggling UK investment trusts

Hedge funds circle struggling UK investment trusts
Cornerstone of UK equity market under pressure from low-cost competition and higher interest rates

Hedge funds are pouncing on the UK’s £200bn investment trust sector as it is shunned by investors and hit by competition from cheaper rivals.

Investment trusts, a cornerstone of UK equity markets with roots stretching back more than a century, have seen a gap open up between their share prices and the value of the assets they hold while they battle the worst year for raising capital in a decade.

The discount, which stands at an industry average of 9 per cent to net asset value, has put some investment trusts on the brink of being wound up or targeted by hedge funds including Paul Singer’s Elliott Management and Boaz Weinstein’s Saba Capital.

Their troubles have weighed down the broader UK equity market. The FTSE 100 is closing in on its February 2023 record, in contrast with US and European indices that have hit a succession of all-time highs this year.

“Investment trusts used to be a uniquely British success story and a vibrant part of the market,” said James de Bunsen, a portfolio manager on Janus Henderson Investors’ multi-asset team. “That has totally gone.”

In recent years the trusts, which act as closed-ended investment funds, have become less popular as higher interest rates lured investors into government bonds. That pushed the discount rate as high as 17 per cent, its widest since the financial crisis.

The proliferation of alternative vehicles allowing easy access to a range of global assets — such as exchange traded funds — has also hurt the sector.

Investment trusts make up 27 per cent of the companies in the FTSE 350 index. They include Baillie Gifford’s flagship Scottish Mortgage Investment Trust, Bill Ackman’s £7.4bn Pershing Square Holdings, and the £2.5bn RIT Capital Partners trust.

They date back to the Victorian era, when they were created to widen access for individual investors to investments across the British empire. They offer a set number of shares, which investors can trade among themselves without affecting the pool of cash managers have at their disposal.

That makes it easier for them to invest in assets that are difficult to sell in a hurry, such as property or private equity. This is in contrast with open-ended funds, which constantly issue and redeem new shares or units in response to demand.

“Once upon a time you couldn’t buy shares in emerging market tech so you bought an investment trust,” said one hedge fund executive. “Today there are many ETFs that track emerging market tech and investors have a lot more choice; what was once a very unique product is not that unique anymore.”

Their woes, which are a further drag on London’s already underperforming stock market, have attracted the attention of activists who are pushing trusts to return capital to investors.

Last month Elliott disclosed a 5 per cent stake in Scottish Mortgage Investment Trust a week after the FTSE 100 trust announced a £1bn stock buyback to try and prop up its ailing share price. The US investment firm had been a shareholder for several months before the disclosure.

Saba has built a stake of about $1.3bn in derivatives and shares in UK trusts, according to a source familiar with the matter.

These positions include a £70mn stake in Baillie Gifford’s US Growth Trust, an $88mn stake in JPMorgan’s European Discovery Trust and a £62mn stake in the BlackRock Smaller Companies Trust, according to regulatory disclosures the past few months.

Others are following Scottish Mortgage’s example. Industry buybacks hit a record £3.6bn last year, according to the Association of Investment Companies. Others have cut fees, closed or merged their funds, including the £1.2bn consolidation agreed by Fidelity and Abrdn last year.

“We strongly support the company’s recently announced £1bn buyback — the largest buyback programme ever announced by a UK closed-end fund — and look forward to continuing our engagement,” said Nabeel Bhanji, partner at Elliott, in a statement. Scottish Mortgage declined to comment.


But other investment trusts face a battle to survive. Capital raisings, the industry lifeblood for new funds, have dried up. Last year there were just two initial public offerings, worth a total of £43mn, while secondary fundraising dropped from £5.2bn in 2022 to £1.1bn, according to the Association of Investment Companies.

A number of investment trusts that invest in green energy have been unable to raise equity as a result of their discounts, fuelling fears that the sector’s woes are starving the UK of badly needed green investment.

Many trusts are required to hold a vote if the discount between its share price and its net asset value hits a threshold. Several environmentally focused trusts, including the UK’s largest, the £3.2bn Greencoat UK Wind, are close to this threshold or have crossed it.

Elliott is not planning to sell its stake in SMIT, according to a person familiar with the fund’s strategy, who added that the investment trust has “more to do” regarding buybacks. However, Weinstein is considering several tactics, including share buybacks or pushing for fund liquidations in extreme cases. Saba Capital declined to comment.

Some fund managers also blame regulatory changes for choking demand. In 2022, the way investment trusts’ fees were presented to some investors was changed, in response to new guidance on rules originally introduced in 2018. Critics argue that the UK’s interpretation of the rules — which also cover EU funds — means British trusts’ fees are artificially inflated.

Last month, a group representing 109 trusts wrote to chancellor Jeremy Hunt warning that the current set-up “cannot be allowed to continue”.

It added that the rules were driving investors to EU-domiciled funds and exacerbating the poor performance of the UK stock market. A regulatory overhaul could unlock £7bn per year of lost investment to the UK at no cost to the taxpayer, it concluded.

“This is a self-inflicted own goal,” said Baroness Ros Altmann, who last year proposed a private members bill last year to change the regulatory requirements. “Other countries are taking advantage of our companies . . . the industry is dying.”

A Treasury spokesperson said: “We recognise [the] industry’s concerns and are working at pace with the FCA to repeal and replace EU-inherited retail disclosure rules, including for investment trusts.”

But activist hedge funds say the trusts must prove their value to investors, rather than waiting for government intervention.

“The reality is that some of these discounts are driven by things which are fixable,” said the hedge fund executive. “Sometimes you need to change the manager, sometimes the mandate, and sometimes the governance structure.”