FT : It is time to talk about eurobonds again

It is time to talk about eurobonds again
The ability to issue debt is implied in Macron’s call for a fiscal union

The election of Emmanuel Macron as French president brings the first opportunity since the start of the eurozone for a serious discussion about eurobonds. Debt instruments for the eurozone come in different flavours, and can be used for different purposes. It makes no sense to say that you are in favour of or against them unless you talk specifics.

It is true that Mr Macron has never suggested a eurobond to mutualise legacy debt. Over the past 10 years, there have been several proposals in that direction. The Bruegel think-tank in Brussels proposed a scheme in 2010 to mutualise parts of the existing national debt, but no more than 60 per cent of a country’s gross domestic product. The German Council of Economic Advisers proposed a debt redemption bond, a eurobond with the explicit purpose for debt reduction.

A more recent discussion focused on a clever securitisation scheme: the EU would buy up a portion of national sovereign debt and turn it into European Safe Bonds. This is similar to the way banks used to buy up mortgage-backed securities and turned them into hideously complicated collateralised debt obligations. We all know how that went.

The only indirect mutualisation that is taking place is the European Central Bank’s programme of asset purchases. Mutualisation is not the officially declared goal but a side effect. But the purchases will eventually end.

The eurobonds we are discussing today are different. They are the eurobonds implicit in Mr Macron’s proposal for a fiscal union. A fiscal union worth the name requires limited tax-raising powers and the ability to issue debt — eurobonds in other words. Germany’s Social Democrats also want something they call a “fiscal union”, a joint eurozone budget, funded by member states, for the explicit purpose of funding investment. But this is not a fiscal union. It is a slush fund. So we should beware of grand labels and always ask what is behind them.

The extreme options of creating a federal state or just reclassifying some portions of national spending as European are either unfeasible or not useful. Much more interesting is the intermediate option of a clearly focused eurozone budget limited to a few areas.

I would like the eurozone to do three things: first, set up a re-insurance system for national unemployment funds. If one member state suffers a shock, its unemployment insurance system would receive compensation. This is not redistribution from the north to the south. The flows could go in the opposite direction.

The second would be a defence procurement union. Defence procurement represents one of the few areas where harmonisation achieves large cost savings. Finally, there should be the capacity to create a fiscal backstop for the financial sector in a crisis.

Such a fiscal union would be small. It would act as only a very limited macroeconomic stabiliser. But it would be preferable to the current rules-based system that leaves little room for counter-cyclical policies.

Over time, the eurobonds would replace national sovereign debt. If a country wants to default on its legacy debt, let it. The eurobonds would dismantle the toxic nexus between banks and governments. The no bailout rule would suddenly make sense. This is an environment in which states can default.

Others have raised a further issue: a fiscal union is neither necessary nor sufficient for the sustainability of the eurozone because it does not address internal imbalances. I agree that a limited fiscal union would not be able to get Germany to raise wages. But we should think about it as the beginning of a process. More political integration will need to follow.

There are alternatives to a fiscal union, but they are either implausible or politically unpalatable. For example, it is theoretically possible to allow member states to drop out of the eurozone. But this is not an outcome that policymakers are actively seeking or discussing because it is too risky, and would threaten the cohesion of the EU.

Another frequently mentioned minimalist solution is a pure banking union. Since banks are the most fragile part of the economy, a banking union would provide sufficient reinsurance against financial crises. But for this to work, it has to be perfect. It would require a fiscal resolution capacity and a common deposit insurance system. The eurozone has neither.

The reason pro-Europeans like me keep banging on about eurobonds and fiscal union is not that we seek the maximum possible degree of European integration (although some of us do). More important is that this option is the most effective among the choices available and, yes, also the most realistic. There really are no alternatives in the long run.
NY Post : Art sales aren’t booming despite record sell-off

Three billionaire art collectors sold trophy works at Christie’s and Phillips auction houses last week, but the sell-off doesn’t mean the market has peaked.

“I don’t see it as a top,” Kenny Ackerman of Ackerman’s Fine Art told The Post. “It’s just a good time to be flipping things around.”

The market is certainly healthy. Jean-Michel Basquiat’s “Untitled” sold for a record $110.5 million at Sotheby’s Thursday.

But hedge funders selling their art aren’t desperate to unload, sources said. Steven A. Cohen likely auctioned off his “La Hara” by Basquiat for practical reasons, said fellow hedgie Ackerman, a former trader who locates investment-quality pieces for collectors.

“The guy’s worth $12 billion and sells a painting for $35 million — that’s not even the tip of the iceberg,” Ackerman said. “He might have bought two Basquiats a month ago and doesn’t have room for all three on his wall.”

Cohen offered the painting anonymously, as did the other billionaires, but was outed by those familiar with his $1 billion collection.

His sale of “La Hara” for $35 million easily cleared the estimated range of $22 million to $28 million.

Francois Pinault, who auctioned off Rudolf Stingel’s “Untitled (After Sam),” was even less motivated to sell than Cohen. The French businessman, worth over $20 billion, sold the piece through his own auction house, Christie’s. It fetched $10.6 million, barely above its low-end estimate of $10 million.

Leon Black of Apollo Global Management did better with his sale of Wassily Kandinsky’s “Oben und links.” The work commanded $8.3 million — well outside of its top estimate of $7 million, but a mere rounding error for the private-equity titan who’s worth $5.2 billion.

If Black is ever forced to sell his “The Scream” by Edvard Munch, that would be a cry for help. Black paid $120 million for the iconic artwork in 2012 — a record price, at the time, for an auctioned piece — then kept his identity as the buyer secret for two months.

>>> France and Germany in dispute over where EU's top financial regulator should

France and Germany in dispute over where EU's top financial regulator should be located after Brexit as infighting begins over institutions that will be moved out of London - financial press (update) 
- Officials say France won’t support the relocation of the European Banking Authority (EBA) to Frankfurt from London after the Brexit. France wants the EBA located in Paris in order to secure its status as the new financial center for the EU. 
- Officials say that because of the dispute Paris and Frankfurt will likely be taken off the table as hosts for the EBA. 
- The EBA will have to vacate its offices in London by March 30, 2019.
- A variety of EU members are also hoping to get the European Medicines Agency when it moves from London post- Brexit.

REuters - Decisively re-elected, Rouhani defies hardliners, pledges to open Iran

Decisively re-elected, Rouhani defies hardliners, pledges to open Iran

President Hassan Rouhani pledged on Saturday to open Iran to the world and deliver freedoms its people have yearned for, throwing down a defiant challenge to his hardline opponents after securing a decisive re-election for a second term.

Rouhani, long known as a cautious and mild-mannered establishment insider, reinvented himself as a bold champion of reform during the election campaign, which culminated on Friday in victory with more than 57 percent of the vote. His main challenger, hardline judge Ebrahim Raisi, received 38 percent.

In his first televised speech after the result, Rouhani appeared to openly defy conservative judges by praising the spiritual leader of the reform camp, former President Mohammad Khatami. A court has banned quoting or naming Khatami on air.

"Our nation's message in the election was clear: Iran's nation chose the path of interaction with the world, away from violence and extremism," Rouhani said.

U.S. Secretary of State Rex Tillerson, whose country has had no diplomatic relations with Iran since 1980, said he hoped Rouhani would use his second term to end Tehran's ballistic missile program and what he called its network of terrorism.

Iran denies any involvement in terrorism and says its missile program, which U.S. President Donald Trump recently targeted with new sanctions, is purely for defense purposes.

Although the powers of the elected president are limited by those of unelected Supreme Leader Ayatollah Ali Khamenei who outranks him, the scale of Rouhani's victory gives the pro-reform camp its strongest mandate in at least 12 years to seek the sort of change that hardliners have thwarted for decades.

Rouhani's opponent Raisi, a protege of Khamenei, had united the conservative faction and had been tipped as a potential successor to the 77-year-old supreme leader. His defeat leaves the conservatives without an obvious flag bearer.

The re-election is likely to safeguard the nuclear agreement Rouhani's government reached with global powers in 2015, under which most international sanctions have been lifted in return for Iran curbing its nuclear program.

And it delivers a setback to the Revolutionary Guards (IRGC), the powerful security force which controls a vast industrial empire in Iran. They had thrown their support behind Raisi to safeguard their interests.

CHEERING AND DANCING

Thousands of people gathered in central Tehran to celebrate Rouhani's victory. Videos on social media showed young people clapping and chanting "We love you Hassan Rouhani, we support you."

Some youngsters wore wristbands in violet, the color of Rouhani's campaign. Others wore green, representing the reformist movement crushed by security forces after a 2009 election, whose leaders have been under house arrest since 2011.

During campaigning, Rouhani promised to seek their release if re-elected with a stronger mandate.

"We won. We've done what we should have for our country. Now it's Rouhani's turn to keep his promises," said coffee shop owner Arash Geranmayeh, 29, reached by telephone in Tehran.

Videos from the cities of Kermanshah, Tabriz and the holy city of Mashhad showed hundreds of people in the streets, cheering and dancing.

Rouhani, 68, faces the same limits on his power to transform Iran that prevented him from delivering social change in his first term, and that thwarted Khatami, who failed to deliver on a reform agenda as president from 1997-2005.

But by publicly thanking "my dear brother, Mohammad Khatami" in his victory speech, Rouhani seemed to take up that mantle. It was a remarkable challenge to the Shi'ite Muslim religious judicial authorities, who have blacklisted Khatami from public life for his support for other reformists under house arrest.

Many experts are skeptical that a president can change much in Iran, as long as the supreme leader has veto power over all policies and control over the security forces. Some said the pattern was all too familiar from Rouhani's first victory four years ago and Khatami's victories the previous decade.

"The last two decades of presidential elections have been short days of euphoria followed by long years of disillusionment," said Karim Sadjadpour, senior fellow at the Carnegie Endowment who focuses on Iran.

"Democracy in Iran is allowed to bloom only a few days every four years, while autocracy is evergreen."

The re-elected president will also have to navigate a tricky relationship with Washington, which appears at best ambivalent about the nuclear accord agreed by former U.S. President Barack Obama. Trump has repeatedly described it as "one of the worst deals ever signed", although his administration re-authorized waivers from sanctions this week.

Trump arrived on Saturday in Saudi Arabia, his first stop on the first trip abroad of his presidency. The Saudis are Iran's biggest enemies in the region and are expected to push hard for Trump to turn his back on the nuclear deal.

Speaking at a joint news conference with his U.S. counterpart in Riyadh, Saudi Foreign Minister Adel al-Jubeir said Iran's presidential election was an internal matter. "We want to see deeds, not words" from Iran, he added.

Kuwait's emir Sheikh Sabah Al-Ahmad Al-Jaber Al-Sabah, an ally of Saudi Arabia, congratulated Rouhani on his re-election.

BREAKING TABOOS

Rouhani's reinvention as an ardent reformist on the campaign trail helped stir the passion of young, urban voters yearning for change. At times he broke rhetorical taboos, attacking the human rights record of the security forces and the judiciary.

During one rally he referred to hardliners as "those who cut out tongues and sewed mouths shut". In a debate last week he accused Raisi of seeking to "abuse religion for power". The language at the debate earned a rare public rebuke from Khamenei, who called it "unworthy".

The contentiousness of the campaign could make it more difficult for Rouhani to secure the consent of hardliners to carry out his agenda, said Abbas Milani, director of the Iranian Studies program at Stanford University.

"Rouhani upped the ante in the past 10 days in the rhetoric that he used. Clearly it's going to be difficult to back down on some of this stuff."

The Guards could also use their role as shock troops of Iran's interventions across the Middle East to try to derail future rapprochement with the West, said Meir Javedanfar, an Iranian-born lecturer at Israel's Interdisciplinary Center Herzliya.

"Since the 1979 revolution, whenever hardliners have lost a political battle, they have tried to settle scores," he said.

"I would worry about the more confrontational policy of the IRGC in the Persian Gulf ... and more confrontational policy with the U.S. and Saudi Arabia."

Among the congratulatory messages sent to Rouhani by world leaders, Iran's battlefield ally Syrian President Bashar al-Assad looked forward to cooperating "to strengthen the security and stability of both countries, the region and the world".

The biggest prize for Rouhani's supporters is the potential to set Iran's course for decades by influencing the choice of a successor to Khamenei, who has been in power since 1989.

A Raisi victory would have probably ensured that the next supreme leader was a hardliner. Rouhani's win gives reformists a chance to build clout in the body that chooses the leader, the Assembly of Experts, where neither reformists nor conservatives dominate.

Khamenei praised Iranians for their big turnout after voters queued up for hours to cast their ballots. The strong turnout of around 73 percent of eligible voters appeared to have favored Rouhani, whose backers' main concern had been apathy among reformists disappointed with the slow pace of change.

Many voters said they came out to block the rise of Raisi, one of four judges who sentenced thousands of political prisoners to death in the 1980s, regarded by reformers as a symbol of the security state at its most fearsome.

"The wide mobilization of the hardline groups and the real prospect of Raisi winning scared many people into coming out to vote," said Nasser, a 52-year-old journalist.

"We had a bet among friends, and I said Raisi would win and I think that encouraged a few of my friends who might not have voted to come out and vote."

(TechCrunch) Bitcoin just surged past $2,000 for the first time

Bitcoin just surged past $2,000 for the first time


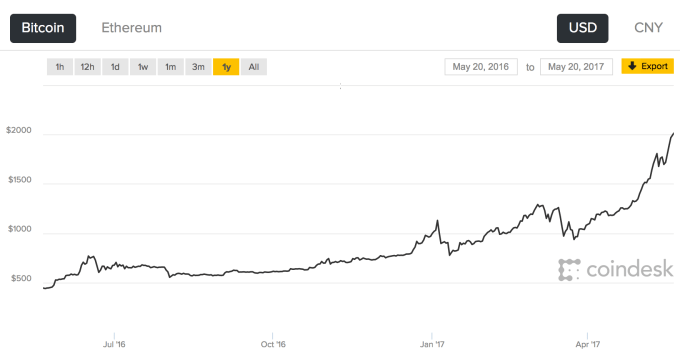
The world’s most popular cryptocurrency is now worth over $2,000 per coin. That’s according to a range of bitcoin exchanges, including Coinbase and Kraken. That valuation puts the total market cap of bitcoin — the total number of coins in circulation — at $32.92 billion.
Bitcoin has been on a tear this year, as this chart from Coindesk shows.
Bitcoin first broke the $1,000 valuation mark way back in 2013, but a combination of factors — including the implosion of then-top exchange Mount Gox — saw the currency drop in value. Support from financial institutions trialed bitcoin and blockchain-based services, and a general stability following new regulation in China, saw bitcoin return to the $1,000 mark again at the end of last year. Since then, its valuation has continued to grow consistently through 2017.
When we wrote about bitcoin (and ethereum) hitting all-time highs back at the end of April, you could buy a bitcoin coin for $1,343. Now, some three weeks later, the valuation is up 50 percent. The price of a coin rose 12 percent over the past week alone.
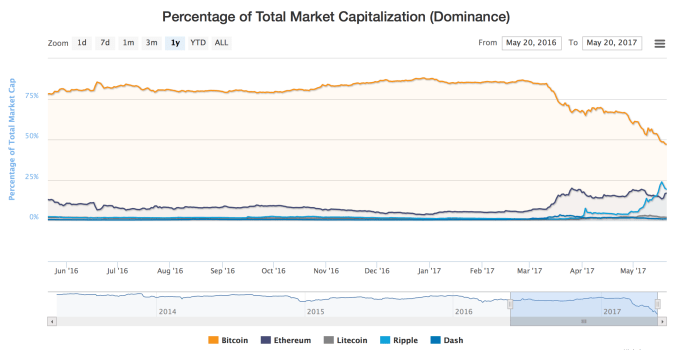
But bitcoin isn’t the only cryptocurrency on the rise. Ripple, the centralized currency that is aiming to be a settlement protocol for major banks, has surged more than 10x, or 1000% in under a month making it now the second most valuable cryptocurrency (only behind bitcoin) in circulation.
Similarly, ethereum, a cryptocurrency designed to function as a blockchain-based computing platform for developers, is now trading $130 per coin with a total market cap of just under $12B, which represents a a little more than a 2x increase over the last month.

The result of these increases is that bitcoin no longer constitutes the majority of the market cap for all cryptocurrencies. Today the total market cap of bitcoin represents just 47% of total cryptocurrencies – up until a few months ago it consistently hovered around 80%.
Why have these other cryptocurrencies been performing so much better than bitcoin? Some say it’s because of bitcoin’s scaling issue. The currency has grown so large that the network is having trouble quickly confirming transactions unless users attach hefty fees for minors. And while the problem can be fixed with solutions like SegWit or Bitcoin Unlimited, the most powerful miners (who effectively control the codebase of bitcoin) haven’t been able to come to a consensus on which new protocol to implement.
While increases of 10x in a month would typically be an obvious sign of a bubble, it’s a little different with cryptocurrencies because no one really knows how much they should be worth. Unlike a company there are no assets or revenues we can use to assess a predictable valuation. So in one sense, a total cryptocurrency market cap of $70B is insane – considering there is no tangible value behind it.
But on the other hand, if (any of) these cryptocurrencies actually replace or supplant a global store of value like gold, then $70B is nothing. For example, the total estimated value of all gold mined is around $8.2 trillion USD. Meaning that right now all cryptocurrencies put together don’t even equal 1% of the world’s gold reserves. Similarly, there is currently about $1.5 trillion USD in circulation, meaning that all cryptocurrencies today are still worth less than 5% of USD in circulation.
The currency is in unchartered waters at $2,000, but some pundits believe it has the potential to reach $10,000 (or more). To achieve this the community would likely have to sort out the scaling issue, which would give investors confidence that bitcoin’s infrastructure be able to support it as it grows.

FT : Athens calls on creditors to strike a deal

Athens calls on creditors to strike a deal
Greece says it has pushed through painful reforms and upheld bailout agreement

Greece is calling on its creditors to strike a deal that would allow it to honour billions of euros in debt repayments, arguing that it has upheld its side of the bargain by pushing through painful tax and pension reforms.

IMF officials and eurozone finance ministers will hold talks on Monday intended to pave the way for Athens’ next tranche of bailout aid so that it can make more than €7bn of debt repayments in July.

“Greece has done its bit, most would say more than its bit,” Euclid Tsakalotos, Greece’s finance minister, told the Financial Times.

He added that a deal would open the door to the country’s participation in the European Central Bank’s economic stimulus programme and provide “the signal to the markets that so many investors have been waiting for”.

The aid is dependent on bringing the IMF into the bailout programme as a financial partner.

But the fund has clashed with Greece’s eurozone creditors and, in particular, Germany, warning repeatedly that the country’s debt is unsustainable.

In response to the fund’s concerns, Greece has adopted tax, pension and labour market reforms that have brought protesters on to the streets in force. Last week the government was rocked by a 24-hour general strike, with further strikes either planned or under way in the shipping industry and local government.

The fund also insists that Greece’s eurozone creditors make more specific commitments to debt relief to make Athens’ burden more manageable.

But Wolfgang Schäuble, the finance minister for Germany, which holds a general election in September and whose public is increasingly resistant to further aid for Athens, argues that the need for further debt relief has yet to be established.

The European Commission has warned that the delays are wreaking economic damage on the country. Last week it slashed its growth forecasts for Greece saying that the uncertainty is already acting as a brake on investment.

Pierre Moscovici, the EU’s economy commissioner, echoed Mr Tsakalotos’ call for a swift deal. “It is clear that the Greek authorities are working hard to keep their end of the bargain,” he said. “I hope that all Greece’s partners will now keep theirs.”

EU officials warn that the Greek programme will run into logistical problems if a deal is not reached soon, especially given that approval procedures will be needed in some national parliaments to sign off the release of bailout aid.

One senior EU official puts the prospect of an accord on Monday at “50-50”.

According to people briefed on the talks, the sides have made progress in recent days with a tentative agreement that Greece’s current target of a primary surplus of 3.5 per cent of gross domestic product should be maintained for a further four years after 2018.

The main forms of debt relief envisaged by euro zone governments are maturity extensions for older bailout loans, and deferral of interest payments. Governments have firmly ruled out any cut in what Greece owes, while interest-rate caps also pose political and practical obstacles.

The talks have become snarled up on competing IMF and European predictions for Greece’s budget surpluses and growth stretching decades into the future. One person involved said planning debt relief based on the most pessimistic IMF forecasts would lead to Greece not paying off some bailout debts until after 2100, an outcome no one is seriously considering.

>>> Barrons weekend summary: positive cover story on select retailers; positive

Barrons weekend summary: positive cover story on select retailers; positive on Berkshire 
* Cover story: As AMZN continues to shake up the retail sector, forcing traditional players to adapt or close, “nine retail plays could thrive in a marketplace growing more competitive by the hour” (Positive on COST, WMT, LOW, BID, GGP, PRTY, BBY, HD, JWN). 
* Features: 1) The 2017 Barron’s 500, measuring operating performance based on cash flow and revenue growth, is topped by ABC, ABBV, MAR, SLF, and NVR; 2) Positive on Berkshire Hathaway: Company’s results are driven more by wholly owned businesses such as Burlington Northern and Berkshire Energy than its big equity portfolio. 
* Tech Trader: Cautious on PI, MRAM: Small chip companies offer genuine innovations and real breakthroughs that could put them at the forefront of new trends, though a bet on their stocks comes with some risk. 
* Trader: Leuthold Group chief investment officer Doug Ramsey said market breadth is too strong to suggest a top, while Marketfield Asset Management isn’t letting the threat of impeachment proceedings against Donald Trump change its outlook; At the recent SALT Conference, “the one thing everyone could agree on was that the turmoil that had engulfed the president is bad for the U.S.”; At the SALT conference, many investors agreed that master limited partnerships are investable again. 
* Profile: Sumanta Biswas and Bernard Horn, managers of the Pear Tree Polaris Foreign Value Small Cap fund, say this is an era of great opportunity for investors in foreign stocks (top 10 holdings: Dragerwerk, WorleyParsons, PrimaMeat Packers, Arcadis, Crest Nicholson Holdings, DFDS, freenet, BBA Aviation, Loomis, Taiwan Union Technology). 
* Interview: Dana Telsey, chief executive of the Telsey Advisory Group, says retailers are still good investments, though the sector is going through changes in how and what people buy. 
* Follow-Up: 1) Jeremy Siegel of the Wharton School says that if Donald Trump is impeached, the Dow could rise by 1,000 points, or 5%, even before vice president Mike Pence takes the helm; 2) Positive on FDC: Shares still trade at attractive below-market levels, and investors should hold onto them; 3) Cautious on Badger Daylighting: A number of questions about the company’s business remain, and investors should avoid shares until they understand what’s going wrong. 
* European Trader: Positive on VOD: British mobile phone operator seems to be improving its performance after struggling with competition and regulatory pressures. Asian Trader: “As the U.S. becomes ever more entangled in investigations of its recent presidential election mess, China is quietly easing itself to the forefront of the world stage.” 
* Emerging Markets: The MSCI index will next month likely confirm that Argentina will rise from a frontier to an emerging market in 2018, attracting new funds and investors. 
* Commodities: Oil prices are rising ahead of a May OPEC meeting at which the group will revisit last year’s decision to reduce production in order to boost prices. 
* Streetwise: With 51% of active managers beating their benchmarks this year, up from 31% in 2016, bullish strategists are struggling to persuade investors to keep buying stocks a little longer.

FT : Mall owner Intu faces FTSE 100 relegation on retail woes

Mall owner Intu faces FTSE 100 relegation on retail woes
Retail property owners are being hit by pessimism over the fortunes of their tenants

Intu Properties, the shopping centre owner, faces relegation from the FTSE 100 index next week in the latest sign of investor pessimism over the retail sector.

The performance of the real estate investment trust’s share price places it on track to be relegated in the review to be announced on May 31, according to analysts at Numis Securities. Its stock would need to rise about 11 per cent to save it from falling out of the FTSE 100.

Shares in Intu, which owns shopping centres including Lakeside in Essex, are trading at a 32 per cent discount to the book price of its properties, which reflects investor pessimism about the retail sector, said Robert Duncan, analyst at Numis.

“The pace of change in retail is only going one way and it’s not getting any slower . . . I can see no reason at this time to invest in retail property,” he said.

Retailers have been under pressure this year from burgeoning inflation and low real wage growth, which has added to the impact of e-commerce on the profitability of stores. This in turn has led to worries about rents and occupancy of retail property.

Like several international retail property groups, Intu has drawn attention from short-sellers. It is subject to $468m of short positions, according to data from S3 Partners.

Membership of the FTSE 100 index is mainly based on market capitalisation, but entrants must also meet criteria in areas such as liquidity and free float. The annual review, to be unveiled on May 31 and implemented on June 16, sparks reactive trading by index trackers, estimated to make up 8 to 10 per cent of the market.

Intu may be replaced in the blue-chip index by G4S, the security group that has been implementing a turnround plan since it was ejected in 2015.

But another contender is Segro, the industrial property group that has benefited from the same e-commerce trend that has hurt companies like Intu. Segro provides warehouse space to host the types of online sellers that are taking market share from traditional high street retailers.

In a further reflection of this trend, Debenhams risks relegation from the FTSE 250 amid worries that department stores are being particularly hard hit by online competition.

Debenhams said last month it would shift towards services like cafés and beauty salons within its stores. But John Stevenson, analyst at Peel Hunt, said: “Debenhams needs a fairly radical overhaul in order to be relevant to consumers and to drive sales.”

Also in the FTSE 250 relegation zone are Restaurant Group, owner of Chiquito and Garfunkel’s, Scottish Investment Trust, Keller Group, a ground engineering company, and Allied Minds, which specialises in turning research inventions into start-ups. BH Macro, a vehicle of the hedge fund Brevan Howard, and the private equity group SVG Capital are also in danger of falling out of the FTSE 250.

Lining up to replace them are companies such as the corporate buyer Melrose Industries, the newly London-listed hedge fund Pershing Square Holdings, Sirius Minerals and the thread manufacturer Coats Group.

Also in line for promotion to the FTSE 250 are Stobart Group, an infrastructure and support services business, the IT services provider FDM Group, the Georgian bank TBC and the waste managers Renewi.

FT : Noble Group struggles to prove its turnround will work

Noble Group struggles to prove its turnround will work
Investors reacted badly to the commodities trader’s latest weak results

Over the past 18 months, Noble Group has tried to get itself out of a deep hole by raising almost $3bn through asset sales and bond and share issues.

But for what was once Asia’s largest commodities trader, this fundraising effort might not be enough.

Noble’s shares have dropped sharply after the company revealed this month that problems with contracts to buy and sell coal had left it nursing a $129m net loss in the first quarter of 2017. The prices of its bonds have meanwhile declined to levels that suggest traders see a high risk of default.

This is just the latest setback for Noble and its founder and largest shareholder Richard Elman, who warned at the results that the company may not be profitable until 2019.

Noble has been battered since 2015, as the then downturn in commodities markets coincided with questions about the company’s accounting. Its shares have plunged more than 90 per cent since analysts led by a little known research firm called Iceberg started highlighting how Noble’s profits on long-term contracts to source and supply commodities were not fully matched by cash flow, and this in turn focused attention on whether it could service its large debt load.


Noble founder Richard Elman © Bloomberg
More than two-thirds of the $3bn raised by Noble has been used to repay loans during 2016 and 2017. But the company still had $3.2bn of net debt at March 31.

Unless Noble can bring about a successful conclusion to its lengthy search for a major new shareholder, the company has its work cut out to convince investors and creditors that it has a future.

“It’s too soon to say the banks have given up on Noble but if things don’t improve in the next few months it will get a lot more difficult,” says Mervin Song, analyst at DBS.

“Any respite will be temporary if they can’t show a return to profitability, stronger cash flow, and most importantly an ability to service their loans.”

Noble had sought to draw a line under its troubles in May 2016, when it installed Jeff Frase and William Randall as co-chief executives.

They have persisted with a shrink-to-survive strategy that was pursued by previous chief executive Yusuf Alireza, meaning that Noble has over the past two years largely exited agricultural and metals trading.

But the strategy of doubling down on coal and oil trading does not appear to be working — the company recorded a cash outflow from operating activities of $323m in the first quarter.

A test of Noble’s relationships with its banks is now under way as it tries to renew a $2bn credit facility that helps finance its trading.


This loan involving several banks was due to be repaid this month, but Noble secured a 45-day extension to assist talks with the lenders.

Noble wants a key condition on the facility relaxed, by reducing the stipulation on the company’s minimum tangible net worth — an indication of what might be recovered in a liquidation — from $3bn to $2.5bn, according to people familiar with the negotiations.

One banker involved in the talks said if the loan was renewed, his group would not be among the participating lenders under guidance from his risk department. Noble declined to comment.

Another key test for Noble and its ability to cope with its debt load will come next year when it must find $1.5bn to repay a $379m bond and a $1.14bn loan.

Analysts say the company, to refinance this debt, will probably have to raise funds through a bond issue, share sale or disposals.

They estimate Noble has about $700m in cash plus $400m of unused credit lines, although some of the company’s money is tied up with brokers in derivatives to hedge its trading.

All Noble’s fundraising options appear to face challenges. Issuing new debt could be difficult after Fitch and Moody’s cut Noble’s credit rating further into junk territory last week.

The sale of a stake in Noble to a strategic investor is a possibility, but bankers are doubtful that Sinochem, the Chinese state-controlled chemicals group long mooted as a white knight for the trader, will be interested now it is in merger talks with ChemChina.

Paul Brough, who this month replaced Mr Elman as Noble chairman, has embarked on a strategic review.

“Noble’s resilience has been tested before and will be tested again but given the people and businesses we have at our disposal I am confident that we will develop solutions that will appeal to our bankers, creditors and shareholders,” he said in a statement.

The company has previously strongly defended its financial reporting, and a review by accounting firm PwC in 2015 said it was in line with industry practice.

One asset Noble could sell to raise cash is its portfolio of contracts to source and supply commodities. The net fair value of these deals — or money Noble says it reasonably expects to receive from the contracts — stood at $2.83bn, including hedges, at March 31.

There has, however, been a long-running debate about the value of the contracts, started by Iceberg.

For Noble and Mr Elman, generating cash from these contracts might be the only way to prove the market wrong.

“The market has no confidence in the business model,” says one banker with exposure to a Noble loan maturing next year. “No matter what they say or do, the results don’t get better.”

FT : $350bn of deals as Trump arrives in Saudi Arabia

$350bn of deals as Trump arrives in Saudi Arabia
US president hopes to rekindle a strategic relationship grown frosty under Obama

President Donald Trump was met by King Salman in Riyadh on Saturday morning, with officials pledging deals of around $350bn as the two allies rekindle a relationship that had grown frosty under the Obama administration.

The agreements included a $110bn arms package that the White House said would help Saudi Arabia and the Gulf states face Iranian threats and contribute to counter terrorism operations, “reducing the burden on the US military,” a White House official said.

The value of the deals signal a revived partnership that promises Saudi investment into US infrastructure in return for US arms deals for the kingdom.

Saudi Arabia is also looking for US support as Riyadh tries to transform its oil-reliant economy after the sustained drop in crude prices triggered a budgetary crisis and rapid deceleration.

The kingdom hopes to cement this renewed commercial partnership with a common vision to check Iranian ambitions in the Arab world.

Mr Trump on Saturday began a number of political and economic meetings with the Saudi leadership. On Sunday he will give a speech on Islam when he meets 50 Muslim leaders.

The king, walking with the aid of a stick, accompanied Mr Trump up a red carpet at the royal terminal of Riyadh’s airport, with the president’s wife Melania following at the back of the small welcoming committee.

Mrs Trump, who like many foreign dignitaries did not cover her head or wear the black abaya robe, was nonetheless conservatively dressed in flowing dark trousers and blouse, accessorised with a gold belt.

TV footage of the president’s blonde daughter Ivanka caused an instant sensation online. The hashtag “#TrumpsDaughter” trended on twitter in the region, including one man asking the president for her hand in marriage. Others satirised Saudis’ infatuation with the mother-of-three.

As the president landed, dozens of chief executives from Saudi Arabia and the US were convening at a forum where they discussed Saudi financial flows into America, and how the US could help diversify the kingdom’s oil-reliant economy.

“The government is taking a back seat and putting the private sector as the locomotive to drive the economy,” said Khalid al-Falih, the Saudi energy minister. “There will be risks, but we will work with you to mitigate it.”

Saudi Aramco, the state oil company, signed more than $50bn worth of deals on Saturday, around $22bn of which were new memorandums of understanding, including:

● Investing $7bn with Rowan over 10 years to own and operate drilling rigs, creating 2,800 jobs in Saudi Arabia.

● Extending a joint venture with Nabors for oil well services, seeing $9bn of investment over 10 years, creating up to 5,000 jobs in the kingdom.

● A new joint venture with National Oilwell Varco in Saudi Arabia to manufacture driving rigs and equipment, seeing $6bn of investment over 10 years.

Aramco also said it would boost operations at its US refinery unit Motiva, with a planned $12bn investment with a likely additional $18bn by 2023. The deal aims to create 12,000 jobs by 2023.

Six firms — including Honeywell, McDermott and Weatherford — signed MOUs to expand Aramco’s use of locally produced goods and services, bringing $19bn of investment to the kingdom.

Aramco also signed a deal with GE to deliver $4bn worth of savings via digitisation of the oil firm’s operations. This was part of a GE package of valued at $15bn.

When deputy crown prince Mohammed bin Salman visited Washington earlier this year, the White House estimated that Saudi investment pledges could rise to around $200bn.

In the defence sector, Lockheed Martin signed a $6bn deal to assemble 150 Blackhawk helicopters in the kingdom, supporting 450 jobs. Raytheon and General Dynamics also signed agreements to support the localisation of defence contracts.

The deals support Prince Mohammed’s plans for the world’s third-largest spender on arms to create a domestic industry led by the newly formed company Saudi Arabia Military Industries. The kingdom wants to source half of defence spending locally by 2030 from 2 per cent now.

Saudi Arabia’s sovereign Public Investment Fund pledged $20bn for a $40bn Blackstone US infrastructure fund, with $20bn to be raised from other parties. Blackstone said it expects, with debt financing, to invest $100bn in infrastructure projects, mainly in the US.

“This potential investment reflects our positive views around the ambitious infrastructure initiatives being undertaken in the US as announced by President Trump,” said Yasir Al Rumayyan, managing director of PIF.

PIF was also an anchor investor in SoftBank’s Vision Fund, which on Saturday finalised its first close at $93bn.

As well as PIF, the technology fund — which is targeting a final close at $100bn within six months — received investments from PIF Mubadala Investment Company of the United Arab Emirates, Apple Inc., Foxconn Technology Group, Qualcomm Incorporated and Sharp Corporation.

PIF is believed to have pledged $45bn for the fund, which is expected to invest significantly in the US.

Dow Chemical, whose chief executive Andrew Liveris co-chaired the Saudi-US CEO Forum on Saturday, agreed to invest more than $100m for a polymers manufacturing plant, while studying a proposed investment in silicones production.

Majed bin Abdullah Al Kassabi, the minister of commerce and investment, granted new licenses to 19 US companies that will start operations in Saudi Arabia, including names such as Citigroup and Whirlpool.

At the close of the Saturday morning forum, about 70 senior Saudi executives and US chief executives boarded buses outside the Four Seasons hotel, bound for lunch with King Salman and Mr Trump at the royal court.

The elite business delegation is set to hold postprandial talks with prince Mohammed, architect of the kingdom’s reform plans.

Around 30 US executives were approved to attend the lunch, including names such as Larry Fink of BlackRock, Michael Corbat of Citigroup, Roy Harvey of Alcoa, Adena Friedman of Nasdaq and financial adviser Michael Klein.

Amid tight security, royal guards took the executives’ phones, before they boarded the coaches.