TechCrunch : Gunshot detection technology ShotSpotter soars 26% in public debut

Gunshot detection technology ShotSpotter soars 26% in public debut

Fundings & Exits IPO ShotSpotter
Gunshot detection technology ShotSpotter soars 26% in public debut
Posted 5 minutes ago by Katie Roof (@Katie_Roof)
Next Story

Investors greeted ShotSpotter with a warm reception on Wednesday, on its first day as a public company. After pricing the IPO at $11, the stock closed at $13.86, or up about 26%.

ShotSpotter notifies police departments about gun violence by using sensors that ignore ambient noise. Their sophisticated technology alerts authorities within 45 seconds of the trigger being pulled.

It’s currently used in about 90 cities, including New York, Chicago and San Francisco. ShotSpotter estimates that about 80% of gun violence goes unreported, and they are in the process of convincing municipalities worldwide that their technology will reduce fatalities.

According to CEO Ralph Clark, it’s not just about catching assailants, but they hope to deter crime also. “No police response leads to normalization of gun violence,” he claims.

Shotspotter makes money by charging local governments on an annual subscription basis. According to their IPO filing, they had just $15.5 million in revenue last year and $11.8 million the year before. Losses increased from $6.2 million to $6.9 million in that timeframe.

That is likely why the IPO was so small, raising just over $30 million. They will be using some of the proceeds to pay down debt.

But they are optimistic they will expand to more cities, because clearly “gun violence is a fairly big problem in the U.S. and globally,” said Clark. “We want to continue to invest in customer success,” he said.

The largest stakeholders are Lauder Partners, Motorola Solutions and Claremont Creek Ventures. The Mountain View, CA.-based company previously raised at least $67 million in funding.

CNN Tech : The billion dollar war over maps (Tom Tom !!!!!)

During a test drive near Ford's Michigan headquarters, the team noticed something strange with its self-driving cars.
Each car shifted slightly at the same point in the lane "as if they were avoiding a pothole," says Jim McBride, Ford's senior technical leader for autonomous cars.

The problem wasn't the cars -- it was the map.
The team had just updated its 3D map of the test route, which helps guide self-driving cars. But a minor glitch caused one pixel on the map to have the wrong data value. It told the car a spot in the ground was raised 10 inches, when it was perfectly level.
"The new map looked perfect to the human eye," McBride says. But not to the eye of a self-driving car. "A single incorrect pixel," he says, was enough to throw off the cars.

The power of that tiny mapping glitch, which happened a few years ago, highlights the newfound importance of a product many consumers likely take for granted.
For much of the last decade, digital maps have helped people pull up basic directions while walking and driving. But tech and auto companies are investing in a new generation of maps for a much more demanding audience: self-driving cars.
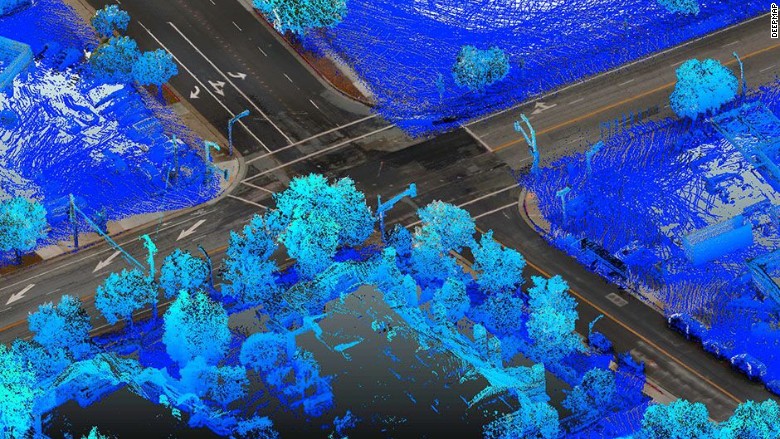
These maps, often referred to as HD maps, go far beyond basic turn-by-turn directions. Some incorporate continuously updating data on lane markings, street signs, traffic signals, potholes and even the height of a curb -- all down to the centimeter.
The maps help the car place itself in the world with a greater degree of accuracy, augmenting the sensors in the vehicle.
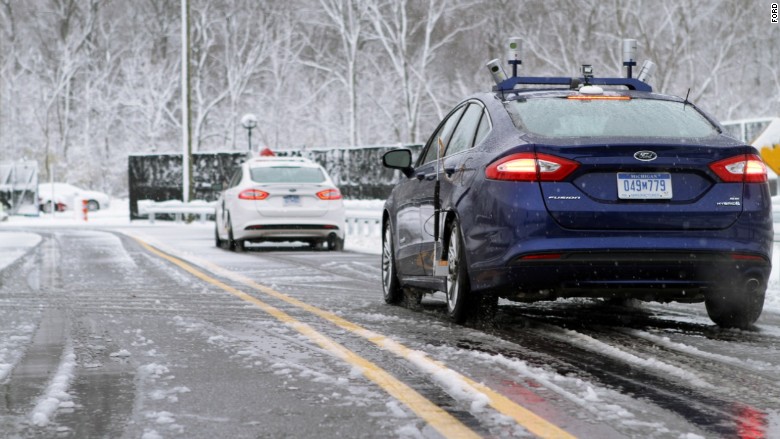
As an example, McBride says maps can guide cars when the lane markings are covered by snow or a truck is blocking the car's view of a traffic signal. It can also free up car sensors to focus on detecting objects not included on the map, like pedestrians.
Maps may not get as much attention as videos of self-driving cars on the road, or the LIDAR laser sensors at the heart of a blockbuster lawsuit between Uber and Google (GOOGL, Tech30). But they are a key piece of the puzzle under the hood.
Maps could help ensure safer deployment of self-driving cars in the next years. And they may just have the potential to create a new billion-dollar industry.
"If you have an autonomous car, then the map is not going to be an optional feature," says John Ristevski, former VP of Here, a mapping business once owned by Nokia that offers HD maps. "It's going to be a core component of the vehicle that will produce ongoing revenue."
Ford's self-driving cars use 3D maps to navigate snowy roads.
Unlike traditional navigation systems sold by companies like TomTom, HD maps may need to be updated as much as daily for certain regions. For example, a busy city street that goes through construction and pedestrian areas might need more frequent data than a long, uninterrupted freeway.
Ristevski says that opens up the possibility of a subscription model that could one day bring in "billions" for mapping companies.
The race to build up this next generation of maps is only getting more crowded. Google, Uber, Ford (F) and others are each working to collect data for HD maps with sensors in their autonomous cars.
At Waymo, Google's self-driving car division, staffers parse out the data collected to identify objects like driveways and fire hydrants. The cars then "automatically send reports back to our mapping team whenever they detect changes" like construction, according to the company.
But this approach is difficult even for companies with a strong bench of technical talent.
"If you thought creating regular maps for Google was hard, creating self-driving maps is much, much harder," says Brian McClendon, Uber's former VP of maps who previously worked on Google Maps. "The amount of data involved is huge. The precision required is very hard as well."
A number of automakers, including General Motors (GM) and Volkswagen (VLKAF), have opted to lean more on third-party services to get their maps off the ground.
Mobileye, a self-driving car firm recently acquired by Intel for $15 billion, inked agreements in April with Volkswagen, BMW and Nissan (NSANF) for a mapping product. The goal is to pool together mapping data from car manufacturers "to generate as much scale as possible," says Dan Galves, Mobileye's chief communications officer.
"You can spend the money, hire the people -- assuming you can hire the right guys -- but that will take years. That happens too late for this race," says James Wu, a veteran of the mapping teams at Google and Apple (AAPL, Tech30).
His startup, DeepMap, announced $32 million in funding last month that will provide a "full-stack mapping service" to companies. Other mapping startups like Civil Maps, backed by Ford, and Mapbox are also working with automakers.
Carmera, another startup, came out of stealth mode this week with $6.4 million in funding and plans to crowdsource "real-time" data for maps. That includes offering "pedestrian analytics" and a "real-time event feed" for construction and road closures.
A sample map for a self-driving car from DeepMap
Google remains the obvious frontrunner. The company has deep pockets and a longer history investing in self-driving cars and mapping products like Street View and Google Earth.
Lars Rasmussen, co-creator of Google Maps, remembers Google founders Larry Page and Sergey Brin telling his team years ago that they'd "have to spend billions of dollars" on maps "and it's worth it."
"I think one of the reasons that [maps] excited Larry was that he had this idea of self-driving cars," says Rasmussen, who left Google for Facebook in 2010.
Google may have won the first online mapping battle (sorry Apple), but the HD maps market is still in its early days. The winner -- or winners -- is far from the finish line.
If you believe self-driving cars will eventually operate everywhere, then every city and street will need to be mapped out in granular detail. To put that in context, Uber's self-driving car team is currently mapping just one city, according to its website: Toronto.
"It's a green field," says Sravan Puttagunta, founder and CEO of CivilMaps. "No company has established a majority market share, and even the ones that have a couple cities are spending billions maintaining those maps."
As the race heats up, there is a lingering question in the industry about how useful these costly maps will be down the road. Some argue the cars will eventually get smart enough, with deep learning technology, not to need to rely on extensive maps.
"In the short term, I can see where it's vital, but that long term may not even be 10 years," says Rebecca Lindland, executive analyst with Kelley Blue Book. The "conundrum," she says, is just as comprehensive maps hit the market, car companies "don't need them anymore."
The team at Ford is "looking at the possibility" of developing algorithms for the car that don't require a prior map, according to McBride. But he's skeptical of ditching maps entirely.
"You'd still save the data that you took the first time you drove there," McBride says, "and use it for the second, third and tenth time to make it better."

WSJ : Russia’s Rosneft Stake Sale Came With a Twist: Moscow Always Wanted It Bac


From: LAURENT CHEKROUN (MAKOR SECURITIES LO) At: 06/07/17 14:42:36
Subject: WSJ : Russia’s Rosneft Stake Sale Came With a Twist: Moscow Always Wanted It Bac
Russia’s Rosneft Stake Sale Came With a Twist: Moscow Always Wanted It Back
Initial $11.5 billion sale to Qatar and Glencore gave Russians cash to address budget squeeze

Russia’s sale of one-fifth of its state-owned oil company to Qatar and commodities giant Glencore GLNCY -0.34% PLC last year had an unusual provision: Moscow and Doha agreed Russia would buy a stake back, people familiar with the matter said.

Russian President Vladimir Putin hailed the €10.2 billion ($11.5 billion) sale of the PAO Rosneft stake in December as a sign of investor confidence in his country. But the people with knowledge of the deal say it functioned as an emergency loan to help Moscow through a budget squeeze.

Moscow agreed with Qatar that Russia would buy back at least a portion of the stake from the rich Persian Gulf emirate, the people said. The Qatar Investment Authority and Glencore, the Swiss-based commodities giant, formed a partnership to buy the 19.5% stake in Russia’s energy jewel at a time when Mr. Putin’s government needed cash.
The people with knowledge of the deal say the buyback arrangement was negotiated with involvement from Mr. Putin and the emir of Qatar, Sheikh Tamim bin Hamad Al Thani. Russia and Qatar saw it as an opportunity to build a bridge between countries that had taken up opposite sides in the Syrian civil war, the people said. One of the people said the buyback would happen in the next 10 years.

Kremlin spokesman Dmitry Peskov said he didn’t agree with the characterization of the deal as an emergency loan. He didn’t respond to further questions.

Glencore and the Qatar Investment Authority said the deal’s contract contained no right for Russia to buy back Rosneft shares from the consortium they created.

“The transaction did not include an option or agreement for Rosneft, Rosneftegaz or the Russian state to buy the stake or parts of the stake acquired by the consortium,” Glencore said.

“The consortium alone controls the future ownership of these shares,” the Qatar Investment Authority said through a London public-relations firm.

Rosneft, the world’s largest listed oil producer, is traded publicly in Moscow, but it isn’t easy to buy and sell large pieces of the company because it remains majority-owned by the Russian state and is an instrument of economic power for Mr. Putin.

The people familiar with the deal said a time-limited structure and a buyback agreement for the deal worked for both Qatar and Russia.

Qatar wanted its Rosneft stake to be temporary, the people said. The emirate believes it will profit from selling the shares back to Russia at a later date, the people said, betting that oil prices will rise and push up Rosneft’s share price. Qatar saw the political benefits of giving Russia access to quick cash as a sort of loan to address a budget deficit that had widened due to lower oil prices, the people said.

After the deal, a range of talks opened between Russian and Qatari businesses on a scale not seen before, Russian news agencies have reported.

For Russia, a temporary deal was also preferred by Igor Sechin, a Putin confidante who runs Rosneft and its parent company Rosneftegaz, one of the people said.

Until the deal with Qatar and Glencore, Mr. Sechin had publicly opposed privatizing any more of Rosneft, which is already 20% owned by BP PLC. That ownership slice came about when BP sold its share of Russian oil company TNK-BP in exchange for the piece of Rosneft, and cash.

According to people familiar with the matter, Mr. Sechin approached Glencore about a deal under pressure from Mr. Putin, who needed to raise cash during a 2016 budget crunch, when oil prices fell to 12-year lows. Russia’s federal budget relies on the oil-and-gas industry for about a third of its revenue. Glencore executives said the stake was too big for it alone, the people said, so the company brought in its biggest investor, the Qatar Investment Authority.

When the deal was announced in December, Mr. Putin denied it was done “because we lack money for particular budget expenditure items.” He said at a news conference that Glencore and Qatar would “improve the management quality” of Rosneft. The deal was called the largest-ever foreign investment in a Russian company.

Shares in Rosneft rallied around 20% higher in the four weeks following the deal’s announcement on Dec. 7. Those gains have been erased, with the share price down around 25% since the start of the year.

Russia has since pushed Glencore and Qatar to find other investors to demonstrate the foreign interest in the Rosneft stake, sparking talks with companies and sovereign wealth funds, according to people familiar with the matter.

Glencore shares rose after the December announcement, partly because it gives the company access to trade 220,000 barrels a day of Rosneft crude for five years—a lucrative piece of Russian market share.

Subsequent public disclosures have revealed parts of the deal’s complex structure.

Glencore says it only put up €300 million ($338 million) in equity for its stake, not the more than €5 billion implied by taking half a 19.5% piece of Rosneft valued at more than €10 billion. Qatar’s investment totaled only about €2.5 billion, Glencore said.

In an unusual arrangement, the rest of the financing was provided by Russian banks, which contributed €2.2 billion, and Italian bank Intesa Sanpaolo SpA, which lent €5.2 billion to the Glencore-Qatar consortium, according to a Dec. 10 new release issued by Glencore. The financing is “non-recourse,” Glencore said in the release, meaning the lenders couldn’t pursue Glencore and the Qatar Investment Authority if they weren’t repaid.

An Intesa spokesman said the loan to the Qatar/Glencore partnership “is covered by a robust package of guarantees.” Intesa is trying to spread the risk of its loan by syndicating it to other banks, but a person familiar with the matter said the bank hasn’t yet found willing banks.

Under the deal, the Rosneft shares aren’t held directly by Glencore and Qatar but by a U.K. limited liability partnership, according to British corporate records.

If there is an option for Rosneftegas or Rosneft to buy back a stake, then such a LLP entity is exempt from having to pay capital-gains taxes, said Sergey Vakhrameev, a Zurich-based portfolio manager of GL Asset Management, which invests on behalf of private clients, family offices and funds.

Mr. Vakhrameev said he studied the corporate records of the deal as part of his work focusing on Russian companies. He said he had no knowledge that Rosneft plans to buy the shares back.

“The structure of the deal is unusual,” said Mr. Vakhrameev, who, among other aspects, referred to the several limited-liability partnerships set up in the U.K., along with entities in Singapore, that apparently will facilitate the original deal. “It is nontransparent.”

After the deal was announced, Mr. Putin awarded one of Russia’s top honors for foreigners—the Order of Friendship—to Qatar Investment Authority’s chief executive, Sheikh Abdullah bin Mohammed bin Saud Al-Thani, Intesa’s chief executive, Carlo Messina, and Glencore’s chief executive, Ivan Glasenberg.
WSJ : Russia’s Rosneft Stake Sale Came With a Twist: Moscow Always Wanted It Bac

Russia’s Rosneft Stake Sale Came With a Twist: Moscow Always Wanted It Back
Initial $11.5 billion sale to Qatar and Glencore gave Russians cash to address budget squeeze

Russia’s sale of one-fifth of its state-owned oil company to Qatar and commodities giant Glencore GLNCY -0.34% PLC last year had an unusual provision: Moscow and Doha agreed Russia would buy a stake back, people familiar with the matter said.

Russian President Vladimir Putin hailed the €10.2 billion ($11.5 billion) sale of the PAO Rosneft stake in December as a sign of investor confidence in his country. But the people with knowledge of the deal say it functioned as an emergency loan to help Moscow through a budget squeeze.

Moscow agreed with Qatar that Russia would buy back at least a portion of the stake from the rich Persian Gulf emirate, the people said. The Qatar Investment Authority and Glencore, the Swiss-based commodities giant, formed a partnership to buy the 19.5% stake in Russia’s energy jewel at a time when Mr. Putin’s government needed cash.

The people with knowledge of the deal say the buyback arrangement was negotiated with involvement from Mr. Putin and the emir of Qatar, Sheikh Tamim bin Hamad Al Thani. Russia and Qatar saw it as an opportunity to build a bridge between countries that had taken up opposite sides in the Syrian civil war, the people said. One of the people said the buyback would happen in the next 10 years.

Kremlin spokesman Dmitry Peskov said he didn’t agree with the characterization of the deal as an emergency loan. He didn’t respond to further questions.

Glencore and the Qatar Investment Authority said the deal’s contract contained no right for Russia to buy back Rosneft shares from the consortium they created.

“The transaction did not include an option or agreement for Rosneft, Rosneftegaz or the Russian state to buy the stake or parts of the stake acquired by the consortium,” Glencore said.

“The consortium alone controls the future ownership of these shares,” the Qatar Investment Authority said through a London public-relations firm.

Rosneft, the world’s largest listed oil producer, is traded publicly in Moscow, but it isn’t easy to buy and sell large pieces of the company because it remains majority-owned by the Russian state and is an instrument of economic power for Mr. Putin.

The people familiar with the deal said a time-limited structure and a buyback agreement for the deal worked for both Qatar and Russia.

Qatar wanted its Rosneft stake to be temporary, the people said. The emirate believes it will profit from selling the shares back to Russia at a later date, the people said, betting that oil prices will rise and push up Rosneft’s share price. Qatar saw the political benefits of giving Russia access to quick cash as a sort of loan to address a budget deficit that had widened due to lower oil prices, the people said.

After the deal, a range of talks opened between Russian and Qatari businesses on a scale not seen before, Russian news agencies have reported.

For Russia, a temporary deal was also preferred by Igor Sechin, a Putin confidante who runs Rosneft and its parent company Rosneftegaz, one of the people said.

Until the deal with Qatar and Glencore, Mr. Sechin had publicly opposed privatizing any more of Rosneft, which is already 20% owned by BP PLC. That ownership slice came about when BP sold its share of Russian oil company TNK-BP in exchange for the piece of Rosneft, and cash.

According to people familiar with the matter, Mr. Sechin approached Glencore about a deal under pressure from Mr. Putin, who needed to raise cash during a 2016 budget crunch, when oil prices fell to 12-year lows. Russia’s federal budget relies on the oil-and-gas industry for about a third of its revenue. Glencore executives said the stake was too big for it alone, the people said, so the company brought in its biggest investor, the Qatar Investment Authority.

When the deal was announced in December, Mr. Putin denied it was done “because we lack money for particular budget expenditure items.” He said at a news conference that Glencore and Qatar would “improve the management quality” of Rosneft. The deal was called the largest-ever foreign investment in a Russian company.

Shares in Rosneft rallied around 20% higher in the four weeks following the deal’s announcement on Dec. 7. Those gains have been erased, with the share price down around 25% since the start of the year.

Russia has since pushed Glencore and Qatar to find other investors to demonstrate the foreign interest in the Rosneft stake, sparking talks with companies and sovereign wealth funds, according to people familiar with the matter.

Glencore shares rose after the December announcement, partly because it gives the company access to trade 220,000 barrels a day of Rosneft crude for five years—a lucrative piece of Russian market share.

Subsequent public disclosures have revealed parts of the deal’s complex structure.

Glencore says it only put up €300 million ($338 million) in equity for its stake, not the more than €5 billion implied by taking half a 19.5% piece of Rosneft valued at more than €10 billion. Qatar’s investment totaled only about €2.5 billion, Glencore said.

In an unusual arrangement, the rest of the financing was provided by Russian banks, which contributed €2.2 billion, and Italian bank Intesa Sanpaolo SpA, which lent €5.2 billion to the Glencore-Qatar consortium, according to a Dec. 10 new release issued by Glencore. The financing is “non-recourse,” Glencore said in the release, meaning the lenders couldn’t pursue Glencore and the Qatar Investment Authority if they weren’t repaid.

An Intesa spokesman said the loan to the Qatar/Glencore partnership “is covered by a robust package of guarantees.” Intesa is trying to spread the risk of its loan by syndicating it to other banks, but a person familiar with the matter said the bank hasn’t yet found willing banks.

Under the deal, the Rosneft shares aren’t held directly by Glencore and Qatar but by a U.K. limited liability partnership, according to British corporate records.

If there is an option for Rosneftegas or Rosneft to buy back a stake, then such a LLP entity is exempt from having to pay capital-gains taxes, said Sergey Vakhrameev, a Zurich-based portfolio manager of GL Asset Management, which invests on behalf of private clients, family offices and funds.

Mr. Vakhrameev said he studied the corporate records of the deal as part of his work focusing on Russian companies. He said he had no knowledge that Rosneft plans to buy the shares back.

“The structure of the deal is unusual,” said Mr. Vakhrameev, who, among other aspects, referred to the several limited-liability partnerships set up in the U.K., along with entities in Singapore, that apparently will facilitate the original deal. “It is nontransparent.”

After the deal was announced, Mr. Putin awarded one of Russia’s top honors for foreigners—the Order of Friendship—to Qatar Investment Authority’s chief executive, Sheikh Abdullah bin Mohammed bin Saud Al-Thani, Intesa’s chief executive, Carlo Messina, and Glencore’s chief executive, Ivan Glasenberg.

(Exane) Renault Nissan : The Urge to merge.

A Renault-Nissan merger has never been in itself a reason to own Renault. However, the probability of a government stake sale looks to be the highest for some time. Although not our base case, we see +20-30% upside, only adding to Renault’s optionality.
Is the probability of a full merger increasing?
The French government’s road block on a potential Renault-Nissan merger may soon be lifted. A sale of its 4.7% stake in the coming months could be the first stepping stone in the French government ending its 70-year involvement in Renault. With a seemingly pro-business president in place, the probability of a full government sell down looks to be the highest for some time, leaving the Alliance free to optimise its shareholder structure.

How could a combination work? How does it create value?
In this note we model 3 scenarios for how a potential merger may mechanically play out, showing that there is potentially 20-30% upside from combining the shareholder structure. The upside is not obvious at first, with the combined entity already trading at c.5.5-6x P/E - not notably cheap vs. peers GM, VW etc. However we believe a re-rating closer to 7x can be justified if sufficient new synergy targets accompany any announcement. As we have seen with PSA in the wake of the Opel deal, P/E is not the constraining factor given the promise of future synergies. The cleanest solution (with the most upside) would be for Nissan to buy the French government’s 15% stake before then merging with Renault.

When could it happen?
We expect the government first sells down the temporary 4.7% stake it built in 2015. Although the government can realise a profit if sold today (breakeven is EUR84 per share inc. dividends), it may wait until after the AGM on June 15th or until the 2016 dividend is paid on June 21st – not to mention the outcome of the French fraud investigation. This then leaves greater emphasis on the Alliance mid-term strategic presentation in October, where we expect Renault and Nissan to outline their coming 5 year plans – with the added optionality of any structural change.

WSJ : In Biotech, No News Is Bad News

In Biotech, No News Is Bad News
Lack of rally after cancer conference should concern investors


Biotech stocks have a special need for catalysts. The relative absence of them of late should concern investors.

The American Society of Clinical Oncology annual meeting passed without much of a stir, at least from an investor point of view.

There were exceptions like Loxo Oncology , whose shares rocketed 40% higher Monday after the company presented encouraging preclinical data. But that didn’t translate into a broad stock rally—the S&P Biotechnology Select Industry Index essentially hadn’t budged through Tuesday.

At first blush, that shouldn’t be too concerning. The index is up 19% so far this year, and plenty of companies within the index are focused on treatment categories besides oncology.

But the lack of a stronger rally isn’t something to dismiss altogether. The majority of stocks within the index aren’t profitable, and depend heavily on positive sentiment to attract investors. Major medical meetings, like recent ASCO one, are generally the best place to find such catalysts that attract investor interest. In true bull markets, like the one observed from 2013-2015, data presented at the meeting sends the biotech index sharply higher.

Without such obvious catalysts on the horizon, biotech stocks are at risk for a reversal.

That is especially true because expected blockbuster drug launches are in relatively short supply this year. Just three drugs being introduced this year are expected to top $2 billion in annual sales by 2022, according to research firm Evaluate Pharma.

Companies with obvious catalysts should continue to turn in a strong performance. Vertex Pharmaceuticals , the top performing stock in the S&P 500 so far in 2017 as of Tuesday’s close, will have hotly anticipated cystic fibrosis data later this year. Regeneron Pharmaceuticals shares are up more than 25% so far this year as its blockbuster dermatology drug, Dupixent, hits the market.

But for investors holding companies without such a hook, it is likely that no news will eventually turn into bad news.

>>> US Gapping down

Gapping down
In reaction to disappointing earnings/guidance
:
  • DLTH -11.3%, ALOG -9.5%, SIGM -7.3%, NAV -7%, AMBA -4.6%, (also authorized the repurchase of up to an additional $50 million of its ordinary shares over a twelve-month period commencing July 1, 2017), OXM -2.7%, PLAY -2.5%, (also adds $100 mln to repurchase ), UNFI -2.2%, USPH -1.1%
Other news:
  • KMDA -7.9% (to assume ownership from Shire (SHPG) of the Investigational New Drug application approved by the FDA for the Phase 2/3 study evaluating Alpha-1 Antitrypsin)
  • EXAS -4.1% (prices common stock public offering of 7 mln shares at $35/share)
  • GBDC -2.1% (announces public offering of 1.75 mln shares of its common stock)
  • SHPG -1.7% (KMDA to assume ownership from Shire of the Investigational New Drug application approved by the FDA for the Phase 2/3 study evaluating Alpha-1 Antitrypsin)
  • VLRS -1.2% (May traffic)
  • UPLD -1.1% (to offer and sell shares of its common stock)
  • AZN -1.1% (to divest rights to Zomig outside of Japan for $200 mln)
Analyst comments:
  • QHC -2.6% (initiated with an Underweight at Morgan Stanley)
  • RCII -2.6% (downgraded to Sell from Hold at Loop Capital)
  • IRM -2.3% (downgraded to Sell from Hold at Deutsche Bank)
  • IMAX -1.4% (downgraded to Hold from Buy at The Benchmark Company)
  • KO -0.8% (downgraded to Market Perform from Outperform at BMO Capital)
  • PEP -0.7% (downgraded to Market Perform from Outperform at BMO Capital)
  • CYH -0.5% (initiated with an Underweight at Morgan Stanley)

>>> US Gapping up

Gapping up
In reaction to strong earnings/guidance
:
  • CVNA +8.1%, SEAC +7%, KEYS +6%, HOME +1.3%
M&A news:
  • SAN +1.6% (to purchase Banco Popular Espanol SA)
Other news:
  • DRWI +58% (awarded contract from SmartSky Networks, a North American 4G LTE inflight service provider)
  • NNVC +37.8% (reports 'excellent' inhibitory effects of its topical shingles treatment candidates against VZV in multiple cell culture studies)
  • WINS +7.7% (after more than doubling share price yesterday - closed up 107%)
  • NVAX +4.9% (announces that data from the second of two Phase 2 trials of its RSV F protein recombinant nanoparticle vaccine candidate)
  • CTIC +4.6% (modestly rebounding following following yesterday's decline)
  • DVAX +4.3% (Point72 Asset Management increases passive stake )
  • PLX +4.2% (will present phase II trial results for alidornase alfa (PRX-110) for the treatment of Cystic Fibrosis)
  • AMD +3.4% (continued strength)
  • GRAM +3.4% (sells stake in GMD)
  • EGLT +3.3% (partners w/ Ascend Therapeutics to co-promote SPRIX Nasal Spray to more than 9,000 women's healthcare practitioners)
  • HA +2.2% (reports May 2017 traffic statistics with RPMs +8%, ASMs +5% and load factor +2.4 pts; sees Q2 Operating Revenue Per ASM +7.5-10.5%, prior +5.5-8.5%)
  • DXCM +1.2% (announces FDA approval of the Dexcom G5 mobile app for Android devices)
  • HOLX +1.2% (FDA has approved co's Genius 3D Mammography exam), .
Analyst comments:
  • CTSO +3.8% (initiated with a Outperform at Cowen; tgt $7)
  • RBS +2.6% (upgraded to Hold from Sell at Investec)
  • ORA +1.6% (upgraded to Overweight from Neutral at JP Morgan)
  • LPNT +0.9% (upgraded to Outperform from Mkt Perform at Leerink Partners)
  • DPS +0.5% (upgraded to Outperform from Market Perform at BMO Capital)