Closing Market Summary: Stocks Rally Following Yellen TestimonyThe stock market cruised to a comfortable win on Wednesday as investors dialed back their rate-hike expectations a bit following Fed Chair Janet Yellen's semi-annual monetary policy testimony. The Dow climbed 0.6% to a new record high while the Nasdaq and the S&P 500 settled with gains of 1.1% and 0.7%, respectively.
Fed Chair Yellen came off a bit more dovish in the prepared remarks she delivered before the House Financial Services Committee, saying that "...the federal funds rate would not have to rise all that much further to get to a neutral policy stance." This statement created a sense that the Fed may in fact follow a shorter path of rate hikes that will keep the longer-run neutral level of the federal funds rate below levels that prevailed in previous decades.
Today's statement eased some of the rate-hike concerns that surfaced last week following the release of the FOMC minutes from the June meeting, which initially left the impression that the Fed plans to press on with a tightening of policy despite the persistence of below-target inflation data. At the stock market's close, the implied probability of a December rate hike had declined to 52.0% from 58.9% on Tuesday, according to the fed funds futures market.
Treasuries rallied across the curve on Ms. Yellen's remarks with the benchmark 10-yr yield dropping four basis points to 2.32%. However, currency traders were a bit more undecided in their interpretations, leaving the U.S. Dollar Index (95.49, 0.00) at its unchanged mark.
On Wall Street, all 11 sectors finished in positive territory with the top-weighted technology group (+1.3%) pacing the advance. The tech space's heaviest component by market cap--Apple (AAPL 145.74, +0.21)--struggled amid continued concerns of production and delivery delays for the newest iPhone, but mega-cap names like Facebook (FB 158.90, +3.63), Microsoft (MSFT 71.15, +1.16), and Alphabet (GOOGL 967.66, +14.13) picked up the slack, settling with gains between 1.5% and 2.3%.
Chipmakers also outperformed, pushing the PHLX Semiconductor Index higher by 1.6%, with NVIDIA (NVDA 162.51, +6.63) leading the charge. The company jumped 4.3% after NVDA shares were upgraded to 'Buy' from 'Hold' at Sun Trust.
However, on the downside, a couple of notable sectors underperformed on Wednesday, keeping the broader market's gain somewhat in check. The most influential of these groups was the financial sector (+0.1%), which was weighed down by the notion that interest rates could be suppressed for longer than some expected.
The energy sector (+0.3%) also struggled after the weekly crude inventory report from the Energy Information Administration (EIA) showed that U.S. production increased by 59,000 barrels per day last week. However, on a positive note, the EIA did report a draw of 7.6 million barrels, which was much larger than the 2.9 million barrel decline that the consensus was anticipating.
Crude oil was trading around 2.5% above its flat line going into the EIA release, but gave back a good portion of that gain in the aftermath. The energy component settled higher by 1.1% at a price of $45.53/bbl.
As for the remaining sectors--consumer discretionary (+0.8%), industrials (+0.6%), materials (+1.1%), health care (+0.7%), consumer staples (+0.6%), utilities (+0.9%), telecom services (+0.5%), and real estate (+1.3%)--most finished roughly in line with the benchmark index.
Wednesday's economic data was limited to the Fed's Beige Book and the weekly MBA Mortgage Applications Index:
- The Fed's Beige Book showed that economic activity expanded across all 12 Federal Reserve Districts in June at a slight to moderate pace. In addition, the majority of districts expect to see modest to moderate economic growth in the months ahead.
- The weekly MBA Mortgage Applications Index declined 7.4% to follow last week's 1.4% increase.
On Thursday, investors will receive several economic reports, including the Producer Price Index for June (consensus -0.1%) at 8:30 ET, the weekly Initial Claims Report (consensus 245,000) also at 8:30 ET, and the June Treasury Budget at 14:00 ET.
- Nasdaq Composite +16.3% YTD
- S&P 500 +9.1% YTD
- Dow Jones Industrial Average +9.0% YTD
- Russell 2000 +5.0% YTD
Boeing on aftermarket acquisition prowl, sector advisors say
11 JUL 2017
On the heels of launching its new Global Services division, Boeing [NYSE:BA] is primed to make a sizable acquisition in the aftermarket services space, several sector advisors said.
AAR [NYSE:AIR], KLX [NASDAQ:KLXI], Warburg Pincus-backed Wencor Group and Wesco Aircraft Holdings’ [NYSE:WAIR] Haas Group International were identified as prospective targets for the aerospace giant by the sector advisors surveyed.
Last fall, Chicago-based Boeing announced plans to form the division and grow sales of the services business to USD 50bn within the next 10 years. The unit, which started operating on 1 July, encompasses the services businesses from Boeing’s government, space and commercial sectors.
Five of the sector advisors said for Boeing to meet this lofty goal, the company will likely need to make a major acquisition.
Speaking on the company’s 1Q17 earnings call in April, Boeing president and CEO Dennis Muilenburg said the company intends to hit the aggressive revenue target primarily through organic growth, although he acknowledged it would be complemented with inorganic growth. Boeing declined to comment.
Wood Dale, Illinois-based AAR is a mix of maintenance, repair and overhaul (MRO) services and supply chain support. The first sector advisor said Boeing needs to look to grow in both these areas.
AAR’s presence in logistics, distribution and MRO makes it one of the most logical acquisitions in the aftermarket space for Boeing, the second sector advisor said. The third sector advisor also noted AAR, which has a USD 1.2bn market capitalization, would add scale to Boeing’s presence in aftermarket services.
A Boeing/AAR deal is not a new idea. According to the fourth sector advisor, AAR has approached Boeing in the past to sound out a potential deal. It could not be learned if the talks progressed or if AAR has any current interest in a transaction.
Arguing against the logic of a deal, an additional sector advisor said AAR is heavily tilted toward MRO services, a business that has not been particularly attractive to companies like Boeing that manufacture airplanes. Another sector advisor highlighted that AAR is not a pureplay aftermarket services company.
If, however, Boeing wants to make an impact in the space, the first sector advisor said it would need to be fully embedded in both aftermarket and supply chain management. Another sector advisor acknowledged that “it’s hard to aftermarket without services.”
This week AAR announced that Michael D. Milligan was appointed CFO effective 1 September. The press release noted Milligan has significant finance and accounting expertise, as well as merger and acquisition experience, leading numerous transactions during his time at equipment rental company NES Rental. Earlier this year, United Rentals [NYSE:URI] acquired NES for USD 965m from its majority owner, Diamond Castle Holdings.
KLX, which was spun out of B/E Aerospace in 2014, may be less attractive to Boeing given its presence in oil & gas, said the second sector advisor. The company operates in two segments: Aerospace Solutions Group (ASG) and Energy Services Group (ESG). KLX’s ASG business generated USD 1.34bn in sales for the year ending 31 January 2017. The company’s ESG business posted USD 153.2m in revenue for the same time period.
Since being spun out, KLX has made several acquisitions, including Herndon Aerospace in 2016 for USD 210m, in addition to continuing to grow its oil & gas arm in spite of the industry fall off. ESG increased the number of its agreements with customers by over 115% from over 400 as of 31 January 2016 to over 900 as of 31 January 2017. KLX has a market capitalization of USD 2.7bn.
Wencor, which provides aircraft replacement parts and MRO services, has been struggling and may not be ripe for a deal despite a mature holding period, said three of the sector advisors. Warburg Pincus acquired the business from Odyssey Investment Partners for an undisclosed amount in 2014. The deal was reportedly valued at between USD 800m and USD 900m. Warburg lists its Wencor investment as being “late stage.”
In March 2016, Moody’s downgraded Wencor to Caa1 from B3. At the same time, the company’s senior secured rating was downgraded to B3 from B2 and the second lien term loan was downgraded to Caa3 from Caa2.
Haas Group, a provider of chemical supply chain management solutions to sectors such as commercial aerospace, could appeal to Boeing, said the second sector advisor, given its presence in distribution and logistics. Wesco Aircraft acquired Haas Group from The Jordan Company in 2014 for USD 550m.
At the Paris Air Show last month, Boeing released a forecast for aerospace services demand, projecting the need for expansive services over the next 10 years, valued at USD 2.6 trn.
The announcement veers from Boeing’s focus on developmental programs such as KC-46A Pegasus Tanker and 787 Dreamliner airliner. In January, the US Air Force awarded Boeing USD 2.1bn for 15 KC-46A tanker aircraft, spare engines and wing air refueling pod kits. Two months later, Boeing’s 787-10 Dreamliner completed its first flight.
With these programs launched, Boeing now has room to focus on aftermarket services, said one of the sector advisors. Boeing’s last major acquisition in aftermarket parts and services was in 2006 when it bought Aviall for close to USD 2bn.
Warburg Pincus and Wesco declined to comment. AAR, KLX and Wencor did not return requests for comment.
After big layoffs Soundcloud founder says its strategy is now to “take back control”
At Tech Open Air Berlin Soundcloud co-founder Alex Ljung gave his first major public interview to me today.
In the interview he batted back claims that Soundcloud (SC) is facing tough times, insisting that by drastically cutting headcount by 173 people recently and closing two major offices, Soundcloud is on its way to “taking back control” of its destiny, and remaining a major independent force in the music and tech industry. He also hinted that new products were being planned and championed Soundcloud’s still unique ability for artists to upload their music and be discovered, unlike the major music streaming platforms such as Spotify, Apple Music and Deezer.
“We had to lay-off 173 people from our team, or 40% of Soundcloud. All of them are incredible people. It’s incredibly sad. But we’re very focused on doing what we can to support them,” he said.
“We saw the amount of support [for these people] from the SC community. They produced a google doc themselves, which SC is also supporting. I wasn’t concerned the news [about the layoffs] leaked, because at that moment I had to deal with telling the company, which was more important.”
I suggested to him that SC was rumoured to be still hiring people as close to two weeks before the announcement. He suggested that this was just circumstantial: “This is part of a shift in strategy. We [often] hire people in several countries and it takes a while before they join the company.”
Soundcloud turned over €21.1m in revenue in 2015 – up 21.6% on the prior year. However, in the same period, operating losses widened 25% to €48.6m – as net losses accelerated 30.9% to €51.2m. Operating losses are more than double the size of that compared to revenue. By cutting staff and closing offices they’ve achieved a total saving of €16.9m. So, surely this is a problem? They still have a big gap between revenue and profitability.
Ljung was combative: “We’re one of the largest music platforms in the world. Even just yesterday we were in the top 20 of all the app downloaded in the app store. So we still have an enormous user base and growth and engagement. So the platform is still growing. Creators are huge on the platform. The numbers of tracks are still growing. So everything in terms of the business is doing well.”
He said they have many more music licenses, and now ad revenues, subscriptions from Go and Go+ products.
But, I asked, could they have not foreseen these coming problems earlier?
“We decided we’re going to grow our way into this. We doubled revenues in last 12 months. We decided we would take more control. We laid off 173 people, that’s a considerable cost saving, consolidated offices, our users are going up, revenues are doubling and the reason for this is we’re taking more control of our own future, creating a path to profitability and ensuring our independence at Soundcloud.”
He refused to answer if they had previously been trying to raise a rumoured $250m, but did say: “We are fundraising at this point but that’s not as interesting as music on the platform…”
“We have licenses with pretty much the entire music industry and are very supported by the entire music industry. We’re monetising content for the industry. And these days we have emerging talent on SC. The music industry is supportiver”
I put it to him that not all in the industry were supporting: They compete now with Spotify, Deezer etc
“We are building an independent SC which is completely unique. You can can find artists there that don’t exist anywhere else. Many are the next ones to accept Grammys. There is tremendous financial and cultural impact on SC. It will stay strong.”
But he continually batted away rumours of an acquisition.
I put it to him that SC could have built a truly disruptive force, against the old-fashioned music industry. Why didn’t they do it?
“The truth is some artists get lots of support from the established industry
and some do it all by themselves. SC is for all those artists. We wanted to work with the music industry not against it. Artist independence and control is at the heart of SC.”
“The last 10 years, have been incredibly exciting. You don’t have to go to a major label because of SC. That allowed artists to share, and it created options for them [they didn’t previously have].”
So what of the future?
“We are incredibly strong with creators, that will continue to be a focus. We’re are also one of the largest listener platforms. Revenue is growing fast. For the future we’re going be doing less things that other people are doing and more things which will be completely unique to SC.”
“We’re finally at a point where music industry streaming revenue is growing rapidly. Outside of that we still have a world where MOST people are NOT streaming music. But streaming is here to stay. Most people will now move to streaming over the next 10 years.”
“If you zoom out, streaming is really picking up speed. There are several platforms doing very well. For the music industry it’s great but most have the same $9.99 model. They have all come to the market with a very similar offering for new subscribers in the market.”
“As the companies are competing, a lot of the users are using all these platforms but they are ALSO using SC as well because they can get something there they can’t get anywhere else. Plus you can interact directly with the artists.”
He hinted at the fact that Soundcloud is doubling-down in the fact that musicians can upload themselves.
Lastly I asked him how he was.
“To be honest, I’m a little tired,” he said, before coming back with a big exhortation of Soundcloud’s ability to find new musicians.
I looks like we’ll have to see how this record plays out to the end.
Man vs. Machine: How Has Indexing Changed the Market?
The active/passive debate has obscured a major concern: Will increased indexing impact the market.
The index numbers, from Bloomberg Intelligence, are staggering, though the trend should be familiar: Indexing has enjoyed a larger halo in recent years, and the exchange-traded-fund industry has been enthusiastically churning out new products. Meanwhile, the burdens of public listings and easier access to private capital has shrunk the available number of stocks.
How is this boom in index products affecting the stock market? The question is especially pertinent these days, as benchmarks such as the Standard & Poor’s 500 index and the Nasdaq Composite nuzzle serial new highs, and actively managed funds struggle to keep up. This has fired up an active-versus-passive debate that has become as enduring as Federer versus Nadal, as divisive as Democrat versus Republican.
There’s no question who’s winning the popular vote. Investors have been pulling money from active funds and plowing it into their passive peers. Through the first five months of this year, investors steered $338 billion into passive mutual funds and ETFs—that’s on top of last year’s record inflows of $506 billion, according to Morningstar. If this pace keeps up, passive funds could take in more than $800 billion in 2017, a 60% jump from 2016’s record and nearly double the haul from 2015.
Most of the attention around this trend has been devoted to the underlying investment philosophy—whether investors are better off with low-cost, broad-market indexes or active stock-picking. Some ETFs have presented investors with a hybrid approach, known as “smart beta,” though it’s really just old-school quant investing: These ETFs take active strategies, choosing stocks based on certain metrics or fundamentals, and create a formula that forms the basis of an index. Indexes, therefore, are no longer slices of the market, though they are still passive investments. But the active/passive debate has obscured the bigger issue: What does the indexing boom mean for the long-term health of the stock market—and the investors who rely on it?
Passive and quantitative strategies now account for 60% of equity assets, up from less than 30% a decade ago, says Marko Kolanovic, JPMorgan’s global head of macro quantitative and derivatives research. By his estimates, just 10% of trading volume originates from fundamental discretionary traders. Last year, four of the five most heavily traded securities were ETFs; Bank of America (ticker: BAC) was the lone stock to make the list. Vanguard Group now owns a 5% stake or more in 491 S&P 500 stocks, up from 116 in 2010, according to Bank of America Merrill Lynch.
There’s no question that passive funds have a place in the market; the problem is if they become the market. When money pours in, passive funds must buy stocks in the same proportion as the indexes they track—with no regard for stock price or fundamental information. Therein lies the conundrum: Indexing works because it can piggyback on the wisdom of the crowd, but its very rise shrinks the crowd whose decisions help make the market.
Jim Grant, founder of Grant’s Interest Rate Observer, recently tallied the assets held by price-insensitive buyers. His partial list counts global central banks, ETFs, and indexed mutual funds, and has already surpassed $21 trillion.
AT WHAT POINT does passive investing distort or destabilize the market? That threshold is hard to pinpoint—except in hindsight, and by then it may be too late. In Japan, 67% of assets under management are in passive strategies, yet the market still seems to function. Some argue that passive, at 37% of U.S. fund assets, is too small to affect the market. But that sounds like wishful thinking, and it echoes the argument prevalent a decade ago that subprime, at 23.5% of mortgage originations in 2006, was simply not big enough to affect the housing market, let alone the financial system.
Mike O’Rourke, Jones Trading’s chief market strategist, says the exceptionally easy financial conditions created by central banks damped volatility and paved the way for indexes’ liftoff. “The nearly decadelong period of unconventional accommodation created a rising-tide environment where investors can outsource their decision-making to the S&P index committee,” he says. “Computer trading and quant models grew up in this very forgiving environment,” and the combination of computing power and data history matured to a level that allowed widespread implementation.
On top of that, trading volume declined after the financial crisis and even today is about 30% lower than in 2009, O’Rourke says. Passive funds’ growth against lighter volume further magnified their influence. Today, “it’s much harder and takes much longer for fundamental views to prevail in the market,” he says. “But as monetary policy normalizes, the market will slowly regain parts of its old behavior.”
Aaron Brask, a former Barclays strategist who now runs his own investment management firm, sees parallels between today’s blind buying and events leading to the credit crisis. Back then, the crowded trade was buying credit products blessed by rating agencies, never mind the quality of the mortgage securities or the rating agencies’ conflict of interest. “When investors stopped conducting their own due diligence and started relying on rating agencies, it opened the door for capital misallocation, and ultimately culminated in the credit crisis,” Brask says.
FOR INDIVIDUAL INVESTORS, indexing offers many advantages. It’s a cheap, easy way to bet on any market sector or theme, without worrying about picking the wrong stock. But these advantages come with risks that are easy to forget, especially in a bull market. With cap-weighted indexes, index buyers have no discretion but to load up on stocks that are already overweight (and often pricey) and neglect those already underweight. That’s the opposite of buy low, sell high.
“By definition, index funds also guarantee that you will suffer 100% of the next bear market’s decline,” notes James Stack of InvesTech Research. The same risk management that causes active managers to underperform in a bull market can lessen the pain of a correction, but passive funds have no option to hoard cash or diversify. Stack found that the Vanguard Total Stock Market Index fund (VTSMX) took 43 months to recover its losses after the 2000 bear market. In comparison, InvesTech’s model portfolio, which didn’t fare as well during the bull market, took just 11 months to bounce back.
Savita Subramanian, an equity strategist at Bank of America Merrill Lynch, has extensively studied the impact of passive strategies. She found, for instance, that buying the 10 stocks most underweight by active funds, while selling the 10 that are most overweight by active funds, earned annualized returns near 19% since 2008. Active funds are lagging behind passive funds, and “every time they see redemptions, they’re forced to sell overweight stocks to raise cash,” Subramanian says. Such “crowding risk is particularly acute at quarter end, when allocators tend to rebalance.”
Also, companies with the highest crop of shares held by passive funds are becoming more volatile, since heavy passive ownership shrinks the float of shares available to other investors. “When you buy big stocks that are in many indexes, you tend not to worry about liquidity,” Subramanian says, “but they may not be as liquid as you think.”
Subramanian compared the 100 stocks most widely held by passive investors, and found these have a “true float” of 81.5%, versus an average 85.2% for all stocks. As a result, those 100 stocks had historical volatility near 24.5% (versus 20.9% for all stocks) and saw maximum price declines of 30.3% (versus 23.7% for all stocks).
THERE ARE OTHER WAYS in which market liquidity can become distorted. Consider this example from a 2015 study by S&P Capital IQ: Exxon Mobil (XOM) makes up 1.67% of the S&P 500’s weight, more than five times that of a smaller company like Netflix (NFLX), at 0.3%. Yet Netflix has more-liquid shares. This means Exxon could see index-driven share buying or redemptions five times bigger than Netflix’s, which could trigger price swings in the less-liquid stock. “A structural problem may arise when the liquidity demanded by the ETF exceeds the liquidity available to some of the underlying holdings,” notes S&P Capital IQ. Normally, that effect is muted. But in a liquidity crisis, it can become magnified.
Even Vanguard founder Jack Bogle, who launched the world’s first index fund in 1976, warns that ETFs’ impact on stock trading “has reached mammoth proportions.” In 2016, for instance, the dollar volume of trading in the 100 largest ETFs reached $13 trillion, only slightly less than the trading in shares of the 100 biggest stocks. Yet the market cap of those ETFs was just $1.6 trillion, a mere fraction compared with the $12.8 trillion market cap for stocks. This has resulted in annualized turnover of 120% for stocks, but nearly 880% for the ETFs. Bogle warns that the implications of this rapid trading in ETFs “have yet to be fully examined.”
When an Aug. 24, 2015, flash crash halted trading in almost 20% of U.S.-listed ETFs, stock traders blamed ETFs, while ETF traders pointed the finger at stocks. This is like “blaming the driver in front of you for slamming on his brakes while you were tailgating,” notes Andy Martin of 7Twelve Advisors. The frustration: “We sense there are potentially lethal connections between these various components, but fear that when we see how they behave under extreme stress, it will be too late.”
Of course, what many bemoan as the demise of active managers really is just the demise of lousy active managers. Once upon a time, most New York Stock Exchange stocks were owned by individuals who took their advice from swashbuckling brokers who may or may not have done their homework. It was easier to beat the market with fundamental analysis and a shrewd understanding of human crowd behavior. That spawned a generation that crowded into business schools who wanted to become money managers, but it also sired managers who weren’t up to the task. The economist Eugene Fama once said he’d like to compare stockpickers to astrologers, but he didn’t want to bad-mouth astrologers.
All that changed with computers, institutionalized trading, and the information age. Now, the smart kids want to work for Google, and even on Wall Street, it’s the geeks fluent in quant who collect the big bonuses.
Laurence B. Siegel, director of research at the CFA Institute Research Foundation, found that risk-management strategies like holding cash or diversification did not fully explain active funds’ underperformance from 1992 to 2017. To gauge how robots might fare against human stockpickers, he looked at a benchmark comprising the bottom 30% of U.S. large-cap stocks by price-to-book valuations, because that’s what the world’s dumbest robot might use to start a value fund. To his surprise, the dumb-robot benchmark outperformed the equal-weighted composite of active value funds. “A majority of active managers did not make decisions that were easy enough that a robot could make them,” Siegel writes.
AT WHAT POINT do we say that passive’s rise might be distorting the market? “The canary in the coal mine is when you see the better active managers starting to really beat the market,” says John Rekenthaler, Morningstar’s vice president of research. “Then we can say pricing mechanisms may be breaking down, and the market is becoming inefficient.”
We may be getting close to that point. The flight from active shows signs of slowing: Investors yanked a record $343 billion from active funds last year, but so far this year, the exodus has shrunk to just $6 billion. June marks the fourth straight month when more than half of large-cap managers beat their benchmarks—the longest such streak since at least 2009, according to BofA Merrill Lynch.
Martijn Cremers, a University of Notre Dame professor who has closely studied active managers, found that they’re becoming even more active in their stock-picking in response to the passive onslaught, essentially by building portfolios that are more differentiated from the benchmarks. Stock-picking by these active managers, he says, is also becoming “more successful—consistent with the notion that stock-picking opportunities increase if there is more passive investing.”
Fed Chair Yellen Q&A: focused on trying to achieve 2% inflation target and there has been no discussions on raising it
- Reiterates intention to return to a Treasury only portfolio
- 2% is not a ceiling, rather a symmetric objective
- Repeats recent lower inflation readings appear to be result some temporary measures at work
- Reiterates that the Fed should not follow any mechanical rule on monetary policy
- Balance sheet normalization process should start this year and "relatively soon"
- Intend to serve out my term (Feb 2018) and to achieve our mandated objectives; have not given any thought to another term
GRMN - Hearing strength attributed to takeover chatter - MSFT speculated as possible suitor
OPEC Sec Gen Barkindo: oil market rebalance is taking longer on changing fundamentals; calls on shale oil producers to join efforts to stabilize the market - OPEC wants to see an orderly recovery of output in Libya and Nigeria; happy to see Libya, Nigeria and Iran production recovering fast
Vast iceberg breaks off Antarctic’s Larsen C ice shelf
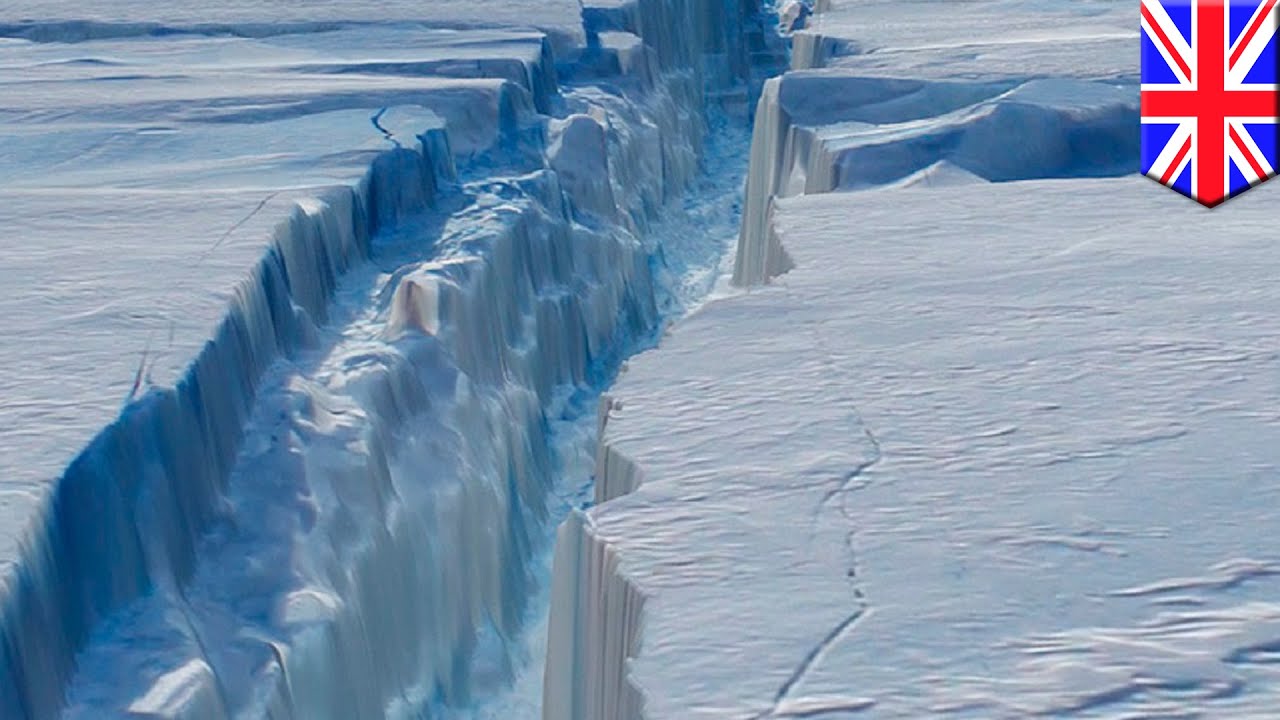
Scientists say ‘little doubt’ that climate change is causing ice shelves to disappear
A vast iceberg nearly the size of the US state of Delaware has finally broken away from Antarctica, changing the frozen landscape forever.
Scientists have been waiting months for the dramatic calving of the iceberg, one of the biggest on record at almost 6,000 square kilometres, after huge cracks emerged on the Larsen C ice shelf in West Antarctica.
That left the one trillion tonne iceberg hanging by a thread of ice just 4.5km wide, according to researchers at Project Midas, a UK-based research project investigating the effects of a warming climate on the Larsen C shelf.
Because ice shelves are floating extensions of land-based glaciers that flow into the ocean, the splitting off of the gigantic iceberg is not expected to have any immediate effect on sea levels.
However, ships could face extra risks if the iceberg breaks up and parts of it drift into warmer waters.
The iceberg could remain in one piece but is more likely to break into fragments according to Adrian Luckman, a professor at Swansea university and lead investigator of the Midas project.
“Some of the ice may remain in the area for decades, while parts of the iceberg may drift north into warmer waters,” Prof Luckman said.
Because ice shelves act as huge buttresses that hold back glaciers flowing down to the coast, researchers will be watching the Larsen C shelf closely for further signs of deterioration.
When the Larsen A and B ice shelves further north of Larsen C collapsed in 1995 and 2002 respectively, there was a “dramatic acceleration” of the glaciers behind them, said David Vaughan, director of science at the British Antarctic Survey.
This led to larger volumes of ice making its way into the ocean, contributing to sea level rise, Prof Vaughan added. “If Larsen C now starts to retreat significantly and eventually collapses, then we will see another contribution to sea level rise.”
Martin O’Leary, another glaciologist with the Midas project, said his team was not aware of any link between the latest calving and human-induced climate change. However, he said the move puts the ice shelf in a vulnerable position.
“This is the furthest back that the ice front has been in recorded history. We’re going to be watching very carefully for signs that the rest of the shelf is becoming unstable,” he said.
Scientists at the British Antarctic Survey (BAS) said there was “little doubt” that climate change was causing ice shelves to disappear in some parts of Antarctica, but no obvious sign that climate warming was causing the whole of Antarctica to break up.
“There are other parts of Antarctica which are losing ice to the oceans but those are affected less by atmospheric warming and more by ocean change,” said Prof Vaughan. “Larsen C itself might be a result of climate change, but in other ice shelves we see cracks forming which we don’t believe have any connection to climate change.
“For instance on the Brunt Ice Shelf [in Antarctica] where BAS has its Halley Station, there those cracks are a very different kind which we don’t believe have any connection to climate change.”
AMZN - Reports 'Prime Day' 2017 up 60% y/y with sales by small business and entrepreneurs grew by even more - Tens of millions of Prime members made a purchase on Prime Day 2017, more than 50 percent higher than the prior year
German Fin Min Schaeuble: Space available for tax cuts in Germany is bigger than 0.5% of GDP
- Have to consider global competitiveness in setting tax policy after the election
- The development of monetary policy is problematic for finance ministers and for economies over the medium term