Closing Stock Market SummaryThe S&P 500 rose 1.2% on Tuesday, as reported progress in peace talks helped keep the positive momentum intact despite a key inversion in the Treasury market. The Nasdaq Composite (+1.8%) and Russell 2000 (+2.7%) outperformed the benchmark index while the Dow Jones Industrial Average rose 1.0%.
The positive start was catalyzed by news that Russia agreed to reduce military operations near Kyiv and that it's willing to speed up the timeline for a meeting between Presidents Putin and Zelensky. President Biden and European leaders were more skeptical, with Mr. Biden saying they were going to wait and see for what Russia does instead of believing its words.
The stock market took the reports at face value, using the news as a good excuse to maintain its rebound-minded intentions. Shares of Apple (AAPL 178.96, +3.36, +1.9%) rose for the 11th straight session, and ten of the 11 S&P 500 sectors finished in positive territory.
The heavily-weighted information technology (+2.1%) and consumer discretionary (+1.5%) sectors were among the top performers behind the real estate sector (+2.9%), while the energy sector (-0.4%) bucked the positive trend amid a decline in oil prices ($104.33, -2.14, -2.0%).
Oil, like other commodities and the dollar (98.41, -0.68, -0.7%), was pressured by the prospects of a ceasefire agreement. The dollar weakened against a stronger euro (+0.9% to 1.1088).
Elsewhere, a widely-followed recession indicator in the Treasury market briefly flashed red for the first time since 2019. Specifically, the 2-yr yield (+1 bps to 2.35%) briefly traded higher than the 10-yr yield (-8 bps to 2.40%), which is typically viewed as a harbinger for a recession between 6-24 months after the inversion.
Bullish investors noted that equities tend to rally in the months between the inversion and recession while others downplayed the significance of the indicator, arguing that the Fed's policy accommodation has distorted the long-end of the curve.
On a related note, Philadelphia Fed President Harker (non-voter in FOMC) told CNBC that an inversion of the yield curve has mixed evidence regarding recession indicators. Former New York Fed President Dudley opined in a Bloomberg piece that a recession is "virtually inevitable" because the Fed is behind the curve.
Reviewing Tuesday's economic data:
- The Conference Board's Consumer Confidence Index rose to 107.2 in March (consensus 107.5) from a downwardly revised 105.7 (from 110.5) in February. In the same period a year ago, the index stood at 109.0.
- The key takeaway from the report is that consumers benefited from continued growth in late Q1, though expectations for the near future continued weakening, which has the potential to pressure future spending plans.
- Job openings decreased to 11.266 million in February from a revised 11.283 million (from 11.263 million) in January.
- The FHFA Housing Price Index for February increased 1.6% m/m (consensus 1.3%), and the S&P Case-Shiller Home Price Index for February increased 19.1% yr/yr (consensus 18.7%).
Looking ahead, investors will receive the third estimate for Q4 GDP, the ADP Employment Change report for March, and the weekly MBA Mortgage Applications Index on Wednesday.
- S&P 500 -2.8% YTD
- Dow Jones Industrial Average -2.9% YTD
- Russell 2000 -5.0% YTD
- Nasdaq Composite -6.6% YTD
"Hard Landing Virtually Inevitable" - Countdown To Recession Begins As 2s10s Curve Inverts
While several asset-gatherers and commission-rakers will try to gaslight investors into monitoring the steepening in the 3M2Y spread - "see no recession to fear there"; for anyone who has actually lived through a Fed hiking cycle, or has read any market history, the 2s10s curve is the most-monitored, the most-studied, and the most accurate predictor of recession the market has to offer.
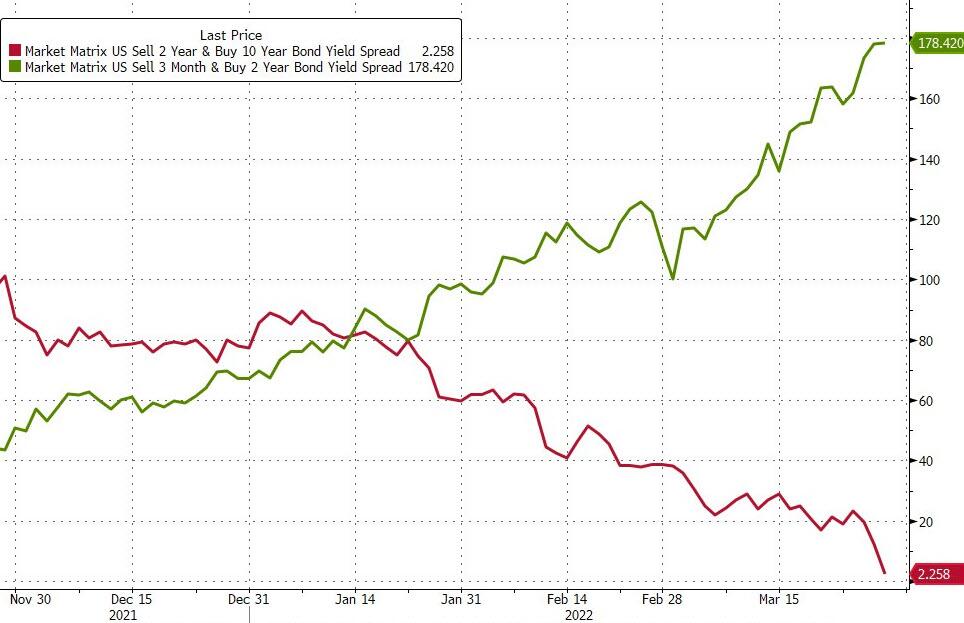
And today, after a long wait...
...2s10s has finally inverted...(according to Bloomberg data 2s10s spread was -0.23bps)
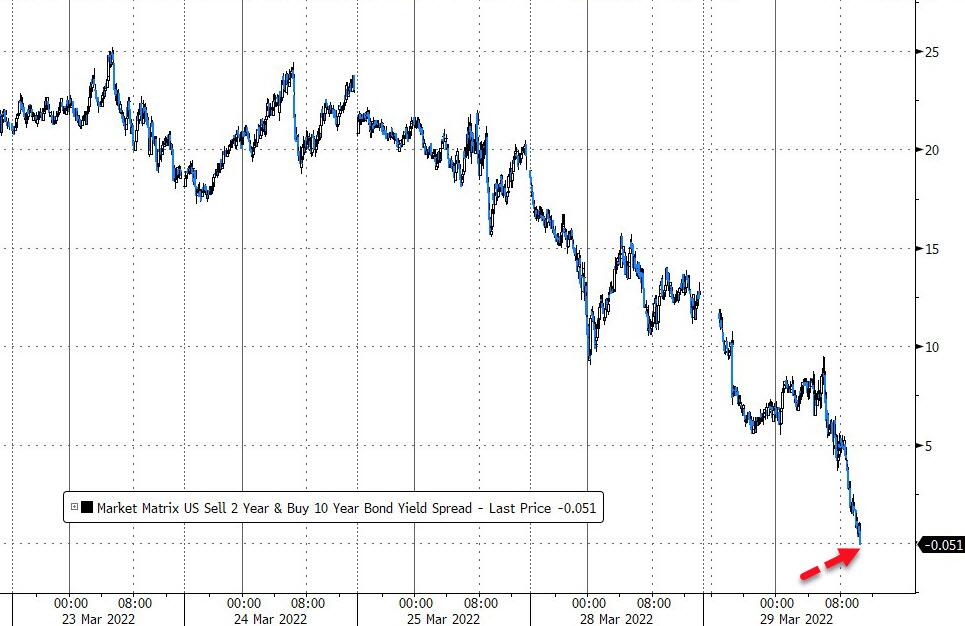
...chasing the rest of the curve (3s10s, 5s10s, 5s30s, 20s30s) all into inversion...
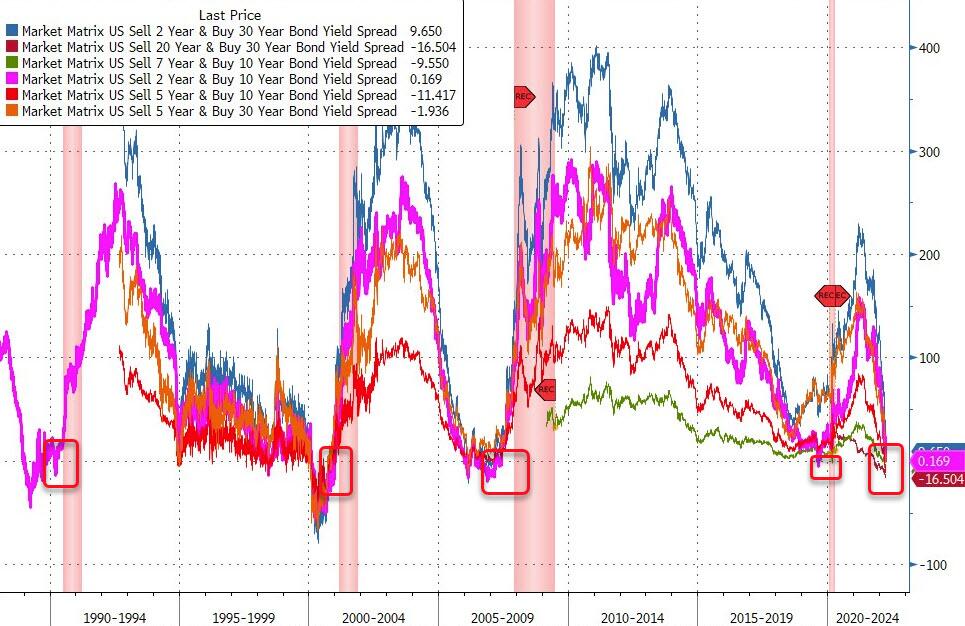
As Deutsche Bank's Jim Reid notes this morning, there has never been such a directional divergence possibly because the Fed have never been as behind the curve as they are today.
For a sense of just how far behind, The Taylor Rule suggests given the current inflation rate and unemployment rate, The Fed needs to hike by an absurd-sounding 1155bps to get back to 'normal'...
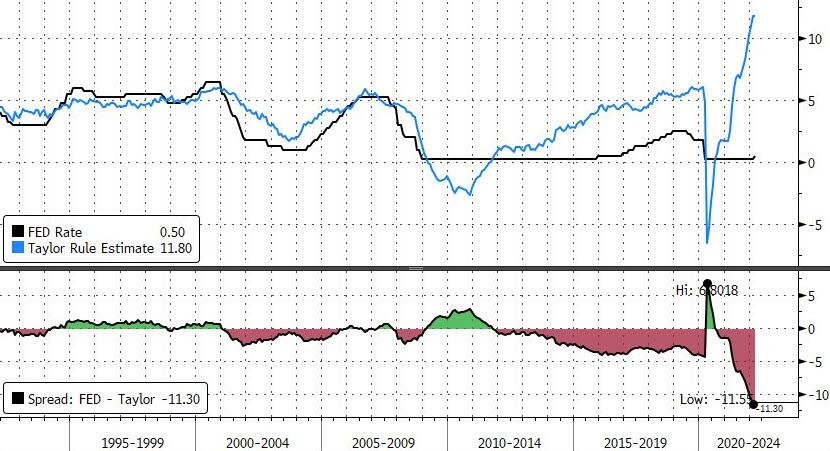
But back to the divergences in the curve, Reid notes that the remarkable thing is that the two have always gone hand in hand directionally until around December 2021 when 3m10s started to steepen as 2s10s collapsed.
If market pricing is correct, they will rapidly catch up over the next year so it’s possible that in 12 months’ time this measure will be flat.
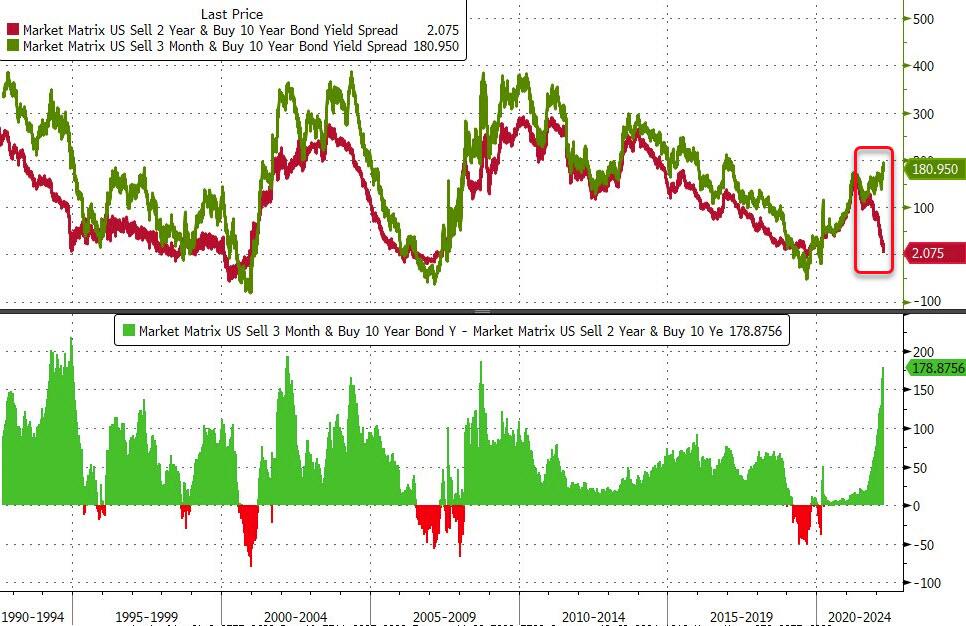
As a reminder, every hiking cycle that has inverted the curve has led to a recession within 1-3 years.
The table from DB below shows the details of every Fed hiking cycle over the last 70 years alongside the time to recession, yield curve shape, and inflation at the first hike. DB has ordered this by length of time from first hike to recession to demonstrate that the quickest recessions following hikes were associated with an inverted curve by the time the Fed stopped hiking.

On average it takes around three years from the first Fed hike to recession. However all but one of the recessions inside 37 months (essentially three years) occurred when the 2s10s curve inverted before the hiking cycle ended. With all the recessions that started later than that, none of them had an inverted curve when the hiking cycle ended. In fact, hiking cycles that ended with the curve in positive territory saw the next recession hit 53 months on average after the first rate hike, whereas the next recession for hiking cycles that ended with an inverted curve started on average in 23 months, just under two years. All these cycles eventually saw an inverted curve but this happened after the Fed stopped hiking. As a reminder, none of the US recessions in the last 70 years have occurred until the 2s10s has inverted. On average it takes 12-18 months from inversion to recession. Then again, the Fed has never before started a rate hiking cycle when inflation was already 7.9%.
Many would prefer to ignore this indicator, or make general excuses for why it's different this time "because of QE", "because of COVID", "because of Putin", but as Jim Reid explains so eloquently:
...for me I think about it very differently. I don’t care why the curve inverts as I think the transmission mechanism is through animal spirits. When a curve is steep it should encourage entrepreneurial behaviour as borrowing costs at the front end are low relative to potential returns. In an inverted curve environment, the rational investor/entrepreneur/business should be more risk averse and either place more money in safe assets at the front end or do less animal spirits enhancing longer-term investments/economic activity.
As Reid notes, this all operates with a lag but if I exaggerate to illustrate, if 2yr yields are 5% and 10yr yields are 1% then rational economic agents will be highly likely to park money at the front end and wait for better opportunities irrespective of how negative the term premium is.
But, as a new Piper Sandler study finds, stocks and bonds tend to do quite well in the window between yield-curves inverting and the onset of the actual recessions.
“The broad stock-market appreciates between inversions and the onset of the subsequent recession,” Roberto Perli, the head of global policy at Piper Sandler, wrote in a note with his colleagues Tuesday.“With the exception of the Volcker years, fixed-income assets always appreciated, with mortgages, investment-grade corporates, and munis as top performers.”
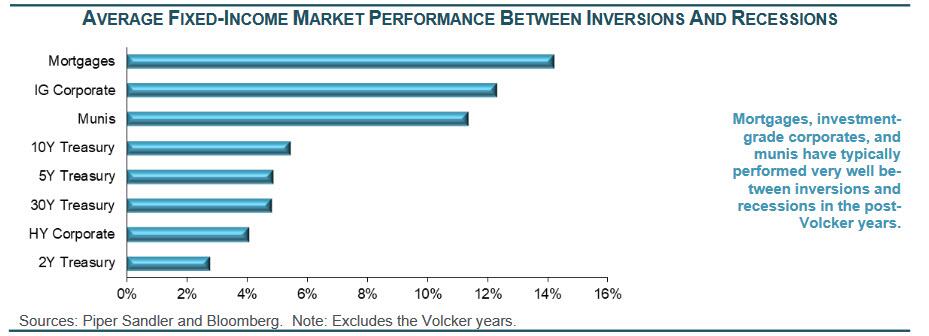

“Overall, the message seems clear for equity and fixed-income investors alike: Don’t get too gloomy as soon as the yield curve (or a portion of it) inverts -- doing so is very likely to leave performance on the table,” Perli wrote.
We do note that this study 'excludes the Volcker years' and the 'burst of the equity bubble' - consider that before piling in.
However, bear in mind that this could well be what The Fed wants - politics and plunge protectors aside - as the only solution to soaring inflation...
In fact, for those who still believe 'the consumer is strong' and 'just look at the stock market', we suggest just look at sentiment surveys - all crashing to multi-decade lows as inflation expectations hit multi-decade highs.
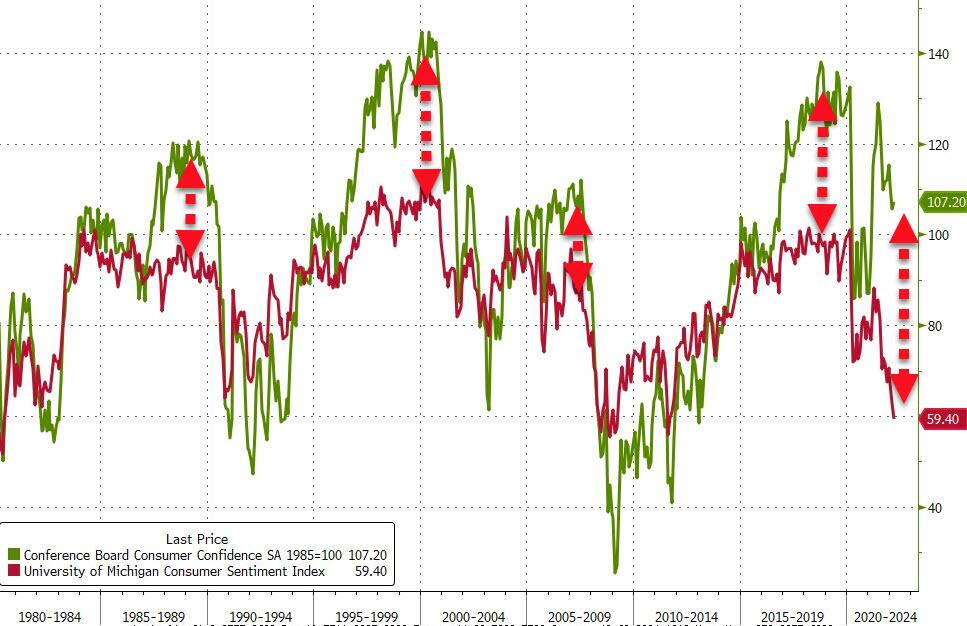
As none other than the former head of the Hew York Fed, Bill Dudley, wrote this morning, The Fed’s application of its framework has left it behind the curve in controlling inflation. This, in turn, has made a hard landing virtually inevitable.
Which Major Currency Will Be The First To Fall?
...Could the euro beat the Yen in the race to the graveyard?
Before saying anything else, it is important to note, when it comes to the major currencies, it is safe to assume they are manipulated by central banks. It is in the best interest of Central Bankers to keep them trading in a rather tight pattern as so not to rock the foundation of the global financial system. On top of the stress being placed upon economies due to the war in Ukraine, the one thing bankers don't want to deal with is the growing fear the fiat monetary system is about to fail.
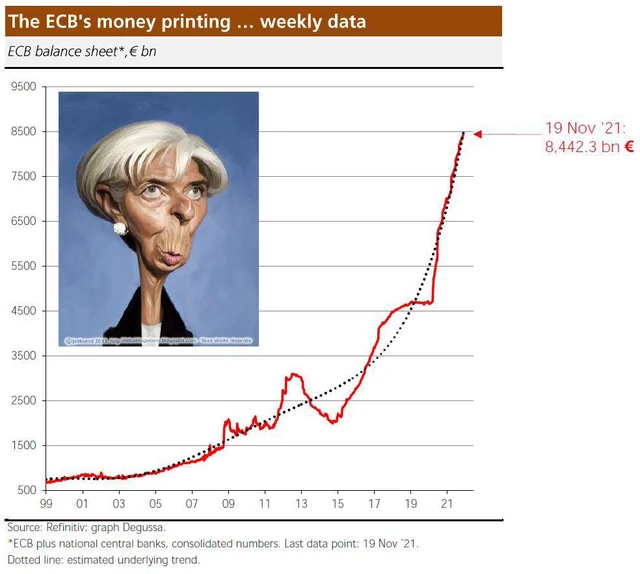
The destruction of the myth that a major currency cannot fail could create a situation where we would see skittish investors dumping currencies in mass. As wealth rushed from currencies into tangible assets inflation would soar. When a currency implodes it fosters a transfer of wealth from those holding the now worthless paper to those holding other currencies or tangible assets. The group-think of all the major central banks until just recently has been concreted into a global monetary policy favoring inflation in order to support economic growth. This monetary policy is now being challenged by rising prices at the same time economies are slowing.
It is important to remember that fiat currency systems depend on the faith of its users and participants to survive. The emergence of a slew of new cryptocurrencies is an indication faith in the current fiat currencies is beginning to wane. These digital currencies that have flooded the market are disconnected from central banks. Also adding to the perception we are about to see a major shakeup in the global financial system are efforts by countries such as China and Russia to move more trade away from the dollar. This is happening at the same time we see the cost of living for the 16 nations that share the euro currency rose to 5.1% in January, a new record high, few interest rate increases expected in 2022, and a time the German PPI is 18% and Spain’s 31%.
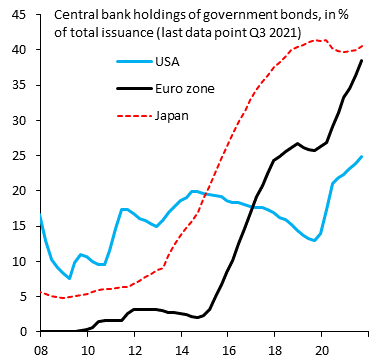
Recently, Zoltan Pozsar, an Investment Strategist at Credit Suisse and is based in New York, has appeared all over the media touting a theory that would affect us all. He is touting the idea Russian sanctions combined with its relationship with China and a crisis in some commodities are threatening the dollar’s reserve status. He claims this will bring about a Bretton Woods III event where commodity collateral may repave the road to hard money.
While Pozar may not be completely right, if we are moving in that direction, the effect has broad implications for all of us. It would substantially redefine the relationship between fiat currency and tangible assets. A strong argument can be made that even though the BOJ is the top dog when it comes to monetizing debt it may not be for long. The ECB is catching up in the percentage of central bank holdings of government bonds in percent of total issuance. Considering all of Europe's problems the big issue is envisioning a scenario from which an economic renaissance might flow.
To say the Euro-zone banking system deception which has been going on for many years is continuing understates the size of the fraud occurring before our eyes. A program known as "Target 2" has been the salvation of the euro and is responsible for preventing countries from collapsing. Since 2015 when Draghi started QE, the Bundesbank has been buying bonds on the market. The Italian central bank is dependent on the ECB which buys Italian government bonds. Germany then sends euros to Italy transferring the debt via Target 2 to their German bank. The growing differences in the Target 2 balance sheet are the result of the Germans taking these bonds. Italians have also added to the capital flight by liquidating their bonds and sending their money abroad.
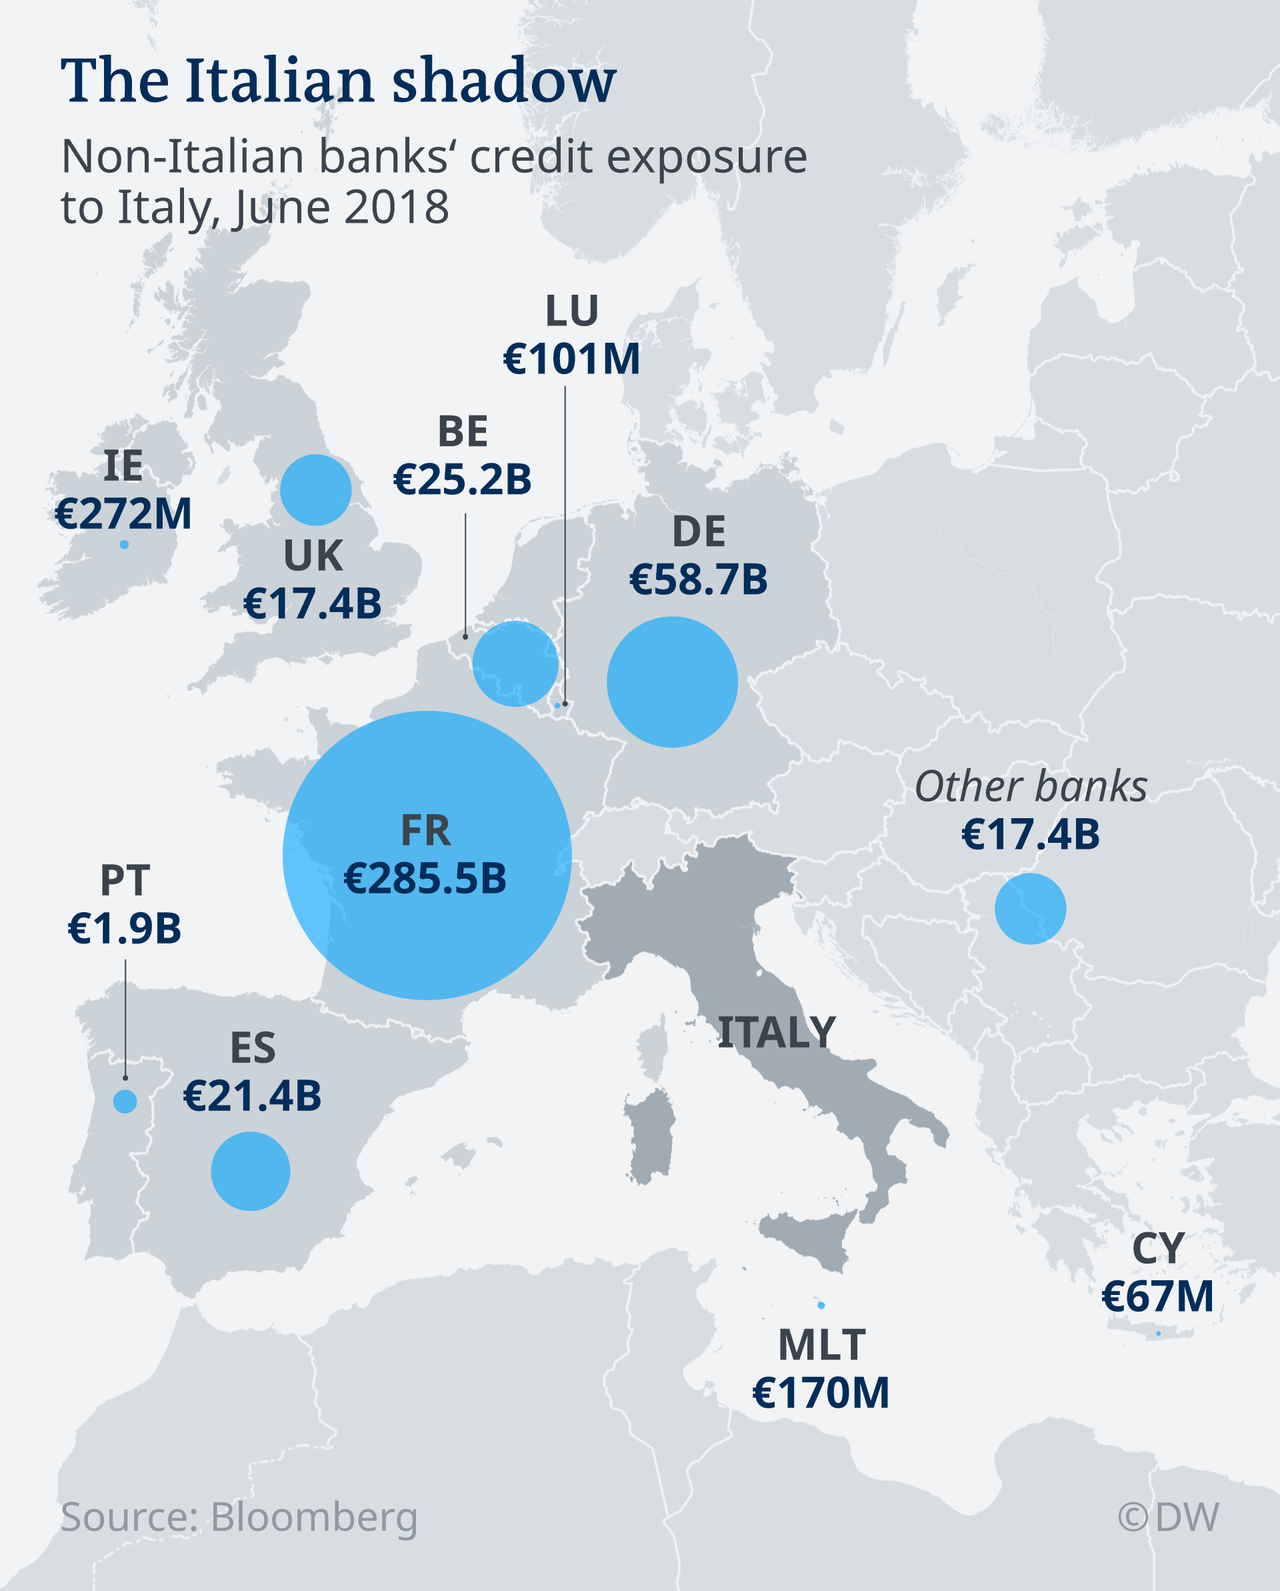
Italy Is Far Worse Post Covid-19
Target 2 translates into enormously huge debt claims on the Germans that are not covered by any securities. In short, if Italy (or even Spain) would withdraw from the Euro-zone, the Germans would be left holding worthless paper. The bottom-line is Brussels and Germany must continue buying what could be considered, "bad debt" to keep the system afloat. All this raises the question of when the value of the euro will begin to reflect the stress which has been masked over and greatly ignored. In short, the choice of Europe has been whether to put a lot of bad debt on the balance sheet of the European Central Bank or deal with defaults and the contagion that flows from them. To be clear, many German economists criticize Target 2 and see it as a check that cannot be cashed.
As for the yen, for a long time, many investors have viewed it as a safe-haven currency, so much in fact that it has been called a "widowmaker" trade for those betting on its decline. For years Japan has been the poster child and living proof that low-interest rates do not guarantee economic growth and prosperity. Going unnoticed by many investors is that the BOJ has been pumping up Japan's stock market by buying into the ETF market. This has morphed into a program that seems akin to Mario Draghi's fraud of doing "whatever it takes" to give the appearance their economy is moving forward. Following along the line of thought that while there is no way of avoiding the final collapse of a boom brought about by credit expansion years ago, Ludwig Von Mises wrote; "The alternative is only whether the crisis should come sooner as the result of a voluntary abandonment of further credit expansion, or later as a final and total catastrophe of the currency system involved." In short, the BOJ now has little choice but to go all-in which strips away any illusion all is well.

Japan Led The Way In This Experiment
Before the "Bernanke has all the answers" era, many of us criticized Japan for failing to own its problems. At the time the idea was that only by letting its zombie banks and industries fail could Japan clean out the system and move forward. Instead, the Government of Japan ran huge deficits and ran up massive debt. For decades Japan languished and avoided disaster only by the fact that it enjoyed a large trade surplus year after year and was able to pigtail onto the rapid growth occurring in China. Today much of that trade surplus has vanished but Japan's massive debt remains.
After 2008 Japan decided to put itself on the leading edge of an experiment to propel its economy forward. This includes the BOJ not only expanding its balance sheet but pumping up the market by jumping into the ETF market, what the country is not doing is taking big steps toward economic reform. All this has morphed into a program that seems to share a key focus on doing "whatever it takes" to keep the economy moving forward. The problem in pursuing the flawed policy of never allowing the market to slip but putting it on a path ever upward until everyone doubting the strength of the market finally capitulates is that it thwarts true price discovery.
After 2008 Japan decided to put itself on the leading edge of an experiment to propel its economy forward. This includes the BOJ not only expanding its balance sheet but pumping up the market by jumping into the ETF market, what the country is not doing is taking big steps toward economic reform. All this has morphed into a program that seems to share a key focus on doing "whatever it takes" to keep the economy moving forward. The problem in pursuing the flawed policy of never allowing the market to slip but putting it on a path ever upward until everyone doubting the strength of the market finally capitulates is that it thwarts true price discovery.
Recently articles have surfaced exploring how the central banks and governments have distorted true price discovery in stock markets across the world. By buying stocks they are taking or transferring branches of industry or commerce from the private sector to state ownership or control. The keyword here is "ownership." This is because the state may choose to abdicate control over decisions leaving them in the hands of management. It has been estimated the BOJ holds around 35 trillion yen, accounting for roughly 80% of Japan’s ETF market. In some ways, the actions of Japan's central bank could be considered nothing more than a new model of "stealth nationalization."
This is a course filled with moral hazard since it destroys true price discovery the bedrock of free markets. We cannot underestimate the importance between assets prices and the feedback signals they send. These are critical in determining value, especially when it comes to assets such as stocks, bonds, currencies, or paper promises which carry no utility value and can perform no useful task. When true price discovery is lost or impaired management teams no longer get market feedback as to whether an executive decision is good or bad, this dilutes the market's ability to reward and punish companies no matter how disastrous their decisions.
To keep the illusion of a viable economy alive central banks must continue expanding credit and debt so the wheels do not come off the economy. It is hard to create the illusion all is well if unemployment soars and defaults skyrocket. This means the central banks remain trapped in a box Ben Bernanke built, Janet Yellen reinforced, and Jerome Powell has not tried to escape from. It is easy to see how central bank policy, right or wrong, falsely accomplishes two things, it bolsters and supports current holdings while reinforcing the image markets are climbing higher because our economic future is getting brighter which is a narrative mainstream media is glad to provide.
This may have started as a "short-term solution" but Ben Bernanke upped the ante by setting the money printing machines on high and flooding America and the world with QE. When other central bankers embraced this solution the world embarked on a grand experiment. The big problem is momentum seems to ebb shortly after each new wave of stimulus and another fix seems to constantly be needed. Current policies are not creating true growth in productivity or real wealth but simply driving up the value of certain markets and assets. This benefits those who own or have assets but does little or even hurts the poor or those who have nothing. It also increases economic inequality and social unrest. The harsh reality central bankers, politicians, and the world must face is the medicine for curing high inflation is high-interest rates. This will not go down well and to some an unacceptable solution.
This may have started as a "short-term solution" but Ben Bernanke upped the ante by setting the money printing machines on high and flooding America and the world with QE. When other central bankers embraced this solution the world embarked on a grand experiment. The big problem is momentum seems to ebb shortly after each new wave of stimulus and another fix seems to constantly be needed. Current policies are not creating true growth in productivity or real wealth but simply driving up the value of certain markets and assets. This benefits those who own or have assets but does little or even hurts the poor or those who have nothing. It also increases economic inequality and social unrest. The harsh reality central bankers, politicians, and the world must face is the medicine for curing high inflation is high-interest rates. This will not go down well and to some an unacceptable solution.
For years, Japan and Italy, both mired in debt, have been on artificial support. Not only the size of the debt, but the quality of the debt, suggest a huge drop in the values of their currencies must occur. Weakness in the euro or even the yen almost certainly will result in a stronger dollar which could be the catalyst for a crisis in currencies issued by emerging market economies. In short, there is the potential to see such an incident over to the rest of the developed world and evolve into a global deleveraging event. This will most likely be seen as part of the great reset many of us have come to expect will occur at some point. Meaning, promises will be broken and rules will be rewritten as we go through the wash. If I'm correct this reset will involve a massive transfer of wealth with many people having their assets rinsed away as society gets put through the wringer.
China’s Covid-19 Challenge Could Boost Luxury E-Commerce Again
The first coronavirus lockdowns in 2020 proved a major turning point for services like Tmall’s Luxury Pavilion. General manager Janet Wang weighs in on what’s changed and what’s next as Shanghai enters lockdown again.
When Janet Wang returned to Alibaba as general manager of its Tmall Luxury Pavilion in early 2021, she found much had changed since she had left the Chinese e-commerce behemoth five years before.
In 2014, when Wang helped bring Burberry on board as the platform’s first luxury brand, the idea of selling on Tmall was still anathema to most top-end players.
Today, almost 200 brands operate stores on Tmall’s Luxury Pavilion, a dedicated space for the segment which the platform first launched in 2017.
The clambering by luxury brands to join China’s biggest e-commerce platform has been particularly heated since the beginning of 2020, when the country first entered widespread lockdowns to stem the spread of Covid-19. That year, an average of one new flagship store per week opened on Luxury Pavilion, which is now home to brands including Cartier, Gucci, Prada, Armani and Hermès.
“The first outbreak accelerated the penetration of online luxury, which doubled or even tripled,” Wang explained. For brands, “it’s more than just a sales channel. It’s a vehicle that they can use [to harvest] consumer insights and then build their strategies around it.”
The platform’s broad reach and immediacy can make it a bellwether for how the interests of China’s luxury consumers are evolving: Today, Wang says, watches have overtaken handbags as the preferred luxury category among online shoppers from lower-tier cities, with even sales of million-yuan ($157,000) Vacheron Constantin timepieces becoming an increasingly regular occurrence.
In first- and second-tier cities, sales are increasingly driven by young women who use the platform to access niche designer brands that are not widely available in China. This trend has been accelerated by the opening of multi-brand giant Farfetch’s store on Luxury Pavilion 12 months ago, which brought 3,000 labels to the platform.
Owner Alibaba doesn’t routinely break out growth rates for Luxury Pavilion, but early last year Tmall told local media outlets that the unit’s quarterly sales had more than doubled year-on-year, rising 159 percent in a signal that one year into the pandemic, the relevance of online sales for luxury in China showed no signs of abating.
In 2022, online luxury platforms like Tmall’s Luxury Pavilion and its 900 million active users are once again poised to see an increase in attention, and investment, from luxury brands, Wang says. As the wave of coronavirus’ Omicron variant fades in much of the world, its belated spread in China is making physical retail and events in the country more fraught than they have been at any time since the initial wave of lockdowns and store closures over two years ago.
On Sunday evening Shanghai authorities announced the city of over 25 million would begin locking down its population (half the city is locked down for five days beginning Monday this week, the other half enters lockdown on April 1) in order to calm record high infection rates in the commercial capital.
On hold are not only Shanghai Fashion Week (which was due to begin on Mar. 25) but also brand’s events, in-store launches and activations that have become an increasingly regular fixture in the city, as global brands look to tap surging domestic demand from Chinese consumers who, since the pandemic, rarely enjoy the opportunity to travel and shop abroad.
Shanghai’s lockdown comes weeks after another first-tier city and important luxury hub in the country’s south, Shenzhen, home to 17.5 million, also effectively closed for business due to a seven-day lockdown. With the more-contagious (if less lethal) Omicron variant now getting a foothold in China, it’s a fair bet that the country’s “Covid Zero” strategy will lead to further disruptions for physical retail in the months to come.
But unlike the first half of 2020, luxury brands now have two years of experience operating under pandemic conditions. As a result of this experience, as well as a more robust e-commerce infrastructure, they may see only a “modest headwind” from China’s outbreak, according to Luca Solca, head of luxury goods research at Bernstein.
“I think brands should only be concerned to a point: over the past two years, brands have perfected remote selling and digital distribution,” he said. “It will be a matter of going back to that, this time having accumulated useful experience on how to run these operations.”
History repeating?
Indeed, even as Covid-19 propelled China’s luxury industry—data from The State of Fashion 2022, a report co-published by The Business of Fashion and McKinsey & Company, showed domestic sales surging 70 to 90 percent above 2019 levels by the end of last year—growth has been uneven across both luxury brands and shopping channels.
Online sales of personal luxury goods in China grew by almost 56 percent last year, while offline sales grew 30 percent, according to consultancy Bain.
In 2021, online’s share of China’s luxury market had reached a total of about 19 percent, excluding duty-free shopping, Bain said. With duty-free penetration included, total luxury online penetration in China accounted for approximately 26 percent of total sales.
Still, brick-and-mortar remains a key channel for brand building and discovery.
This is one of the problems with the hypothesis that China’s current outbreak and resulting lockdowns will boost online luxury even further in 2022, according to Pablo Mauron, China managing director and partner at Digital Luxury Group (DLG). The absence of the luxurious world created by physical stores and events means there are fewer opportunities for brands to entice consumers in the real world, which is often a key step before they complete purchases online.
Even online players, including Farfetch, have pointed to the importance of offline contact and connection to its Chinese consumers, treating its “Private Client”, top tier customers to exclusive experiences, such as a behind-the-scenes visit to Dior’s Shanghai exhibition, dinners in Chengdu and master classes in Beijing.
In a world without physical experiences, staying connected naturally becomes more of a challenge.
Luxury’s growth — both online and off — could also be thwarted by the uncertainty sparked by the current outbreak, which has seriously dented the confidence of China’s middle class.
“Generally speaking, the [Chinese consumer] confidence is low and a lot of the middle class will be financially, economically impacted by the situation,” Mauron said. “The old notions about ‘revenge buying’ aren’t relevant at the moment [as] people are just trying to make sure they can get enough food if their city goes on a wider lockdown [and] people aren’t necessarily seeing any compensation from their employers or the government [to soften] the economic impact.”
The confidence of high-net worth consumers has also been dealt a blow by the weakening of China’s property and stock markets.
For Tmall’s Luxury Pavilion, another challenge is the acceleration of consumer interest in rival Chinese e-commerce channels such as Douyin (China’s version of TikTok, known for its unbeatably addictive algorithm), which last year launched its own brand flagships. JD.com has also made major luxury sector moves over the pandemic period, notably partnering with certain LVMH brands that have long hesitated to join third-party platform players.
According to Wang, the impact of the current outbreaks will depend on their length and severity. Still, as the gap in brand building and experience between online and offline channels has narrowed in recent years, it has become easier to engage luxury consumers digitally.
“Consumers have to get what they want right away. A lot of these digital services and offerings we are seeing [in 2022] also have a very luxurious experience, so I don’t think this will cut off [the growth in online luxury shopping]. In fact, I think that brands will only invest further in online to further their connection with their customers,” she added.
Navigating a Difficult Period
The current situation in China, while difficult, is best navigated by brands staying close to their customer base and offering them the best and most luxurious experience they can, Wang said.
Livestreaming can help, she says, as well as one-on-one video services, which have recently been launched by several brands on Luxury Pavilion. Brands can use Tmall’s data about search history and product interest to better target individual customers during those appointments.
Brands including Cartier have also utilised 3D product rendering within their livestreams to give consumers a view of products as close to reality as possible. Next on the agenda, according to Wang, are further explorations of the metaverse and NFTs, called “digital collectibles” in China or XR: with brands experimenting with “extended reality” experiences for luxury retail.
Brands may be well-served to offer livestreams and other services late into the night, as Luxury Pavilion sees an uptick in browsing activity among younger consumers after midnight, Wang says.
While much of China rues the ways in which 2022 feels like 2020 all over again, and as key physical retail remains interrupted in major centres like Shanghai, luxury brands and the online platforms they partner are hoping history will repeat itself in another way: by providing a similar boost to luxury sales during a difficult period.
Fortescue and E.ON sign deal to replace Russian gas with Australian green hydrogen
MoU agreed to deliver 5mn tonnes of carbon-free fuel to Germany and the Netherlands
Australian billionaire and Fortescue chair Andrew Forrest has pledged to produce and export enough green hydrogen to Germany to replace about a third of its gas imports from Russia, in an ambitious plan he said would require $50bn in investment.
The move to produce 5mn tonnes of hydrogen, part of a memorandum of understanding between Forrest’s Fortescue Metals and German energy group E.ON, would mean building from scratch enough renewable energy capacity to power a country roughly the size of the UK.
A solution would also have to be found to the problem of liquefying and shipping vast volumes of hydrogen from one side of the globe to another at a viable price.
Under the MoU signed on Tuesday, Fortescue and E.ON agreed to develop a feasible hydrogen supply chain between Australia, Germany and the Netherlands, described by E.ON chief executive Leo Birnbaum as a “hydrogen bridge”.
E.ON would distribute the hydrogen to its 50mn customers as replacement for gas in heating and industrial processes.
Green hydrogen is produced using renewably powered electrolysers to split water into hydrogen and oxygen, a process entirely free of carbon emissions. However, it is considerably more expensive to manufacture than traditional carbon-intensive “grey” hydrogen, which is made from natural gas.
In the past year, Fortescue has agreed billions of dollars of green hydrogen supply deals but has yet to start commercial production of the zero-emission fuel. It has, however, started construction of the world’s largest manufacturing facility for electrolysers and expects to produce its first green hydrogen in Tasmania by 2024.
Forrest, who is Australia’s second richest person, told a press conference on Tuesday that the company was on an “emergency footing”, following Russia’s invasion of Ukraine and Europe’s subsequent commitment to reduce dependence on Russian gas imports.
He insisted that the considerable cost hurdles to creating a viable market in green hydrogen would be solved, claiming: “Liquid hydrogen will become the largest seaborne trade in the world.”
Forrest said the energy required to manufacture the hydrogen would be generated in Australia from a mix of wind and solar but gave no precise details of where those projects would be built.
Fortescue has previously promised to produce a total of 15mn tonnes of green hydrogen by 2030, requiring 200 gigawatts of wind and solar to be built, through its green energy subsidiary Fortescue Future Industries (FFI).
Forrest has told Fortescue investors that the company will pump 10 per cent of its annual after-tax profits into FFI, which recently appointed Guy Debelle, former deputy governor of Australia’s central bank, as its new chief financial officer.
The EU is targeting 20mn tonnes of hydrogen production and imports by 2030 under its new plan to reduce dependence on Russian gas.
E.ON is not the only German company to sign a hydrogen deal with Fortescue. Bayer spin-off Covestro announced in January its intention to procure 100,000 tonnes of green hydrogen equivalent per year from FFI, starting in 2024.
The German government said last week that a faster ramp-up of hydrogen infrastructure would be necessary to achieve its aim of being largely independent of Russian gas by the summer of 2024.
Robert Habeck, economics minister and vice-chancellor, also announced that Germany had accelerated and expanded its hydrogen partnership with the United Arab Emirates.
Habeck, who was present at the Fortescue announcement, endorsed the deal.
“The race for large scale production and transportation of green hydrogen has taken off,” he said. “The agreement between E.ON and FFI is a major step forward and puts them in pole position for the delivery of green hydrogen to German industry.”
Australia’s huge tracts of unused land plus plentiful sun and wind resources have made it a popular location for green hydrogen projects and the government claims it has “the largest pipeline of announced green hydrogen projects in the world”.
Steven Mnuchin’s private equity group buys cyber security company
Former Treasury secretary under Trump launched Liberty Strategic Capital with $2.5bn last year
Steven Mnuchin’s private equity group has made its first buyout since he stepped down as US Treasury secretary in the Trump administration, taking a controlling interest in mobile cyber security company Zimperium for $525mn.
Liberty Strategic Capital, Mnuchin’s firm, has focused on cyber security with four minority investments since its launch last year. Mnuchin raised $2.5bn from a group of backers that included Japan’s SoftBank, Saudi Arabia’s Public Investment Fund and Abu Dhabi’s Mubadala.
Zimperium, founded by two Israeli security experts, provides companies with technology to stop criminals from hacking the mobile devices of their employees to obtain sensitive information.
The Dallas-based company claims it is capable of thwarting mobile attacks such as the one carried out by NSO Group’s Pegasus, the Israeli military-grade spyware manufacturer that created software to trace the phones of journalists and human rights activists around the world.
“It’s clear that mobile is the new front line for cyber security,” Mnuchin said. “We believe Zimperium has positioned itself as the leader in securing mobile endpoints and applications.”
Prior to joining Donald Trump’s administration, Mnuchin worked for several years on Wall Street, climbing to the top ranks of investment bank Goldman Sachs.
He left Goldman in 2002 and later launched hedge fund Dune Capital Management and a film studio called Dune Entertainment. Following the 2008 financial crisis, he went on to turn around the failed California-based lender IndyMac, which was later acquired by CIT Group for $3.4bn.
Mnuchin was not the first Treasury secretary to have previously worked at an investment bank. Many have then left government to join the lucrative world of private equity buyouts.
John Snow, who served under President George W Bush, moved to Cerberus Capital Management, while Tim Geithner, Barack Obama’s first Treasury secretary, is president of Warburg Pincus, which will sell its stake in Zimperium.
Jack Lew, Obama’s second Treasury secretary, is a managing partner at private equity group Lindsay Goldberg, and Hank Paulson, who also served under Bush, is executive chair of a climate investment fund at TPG.