Closing Stock Market SummaryThe S&P 500 advanced 0.6% on Monday after being down as much as 1.7% earlier in the day. The Nasdaq Composite (+1.3%), Dow Jones Industrial Average (+0.7%), and Russell 2000 (+0.7%) followed similar price action, with the tech-sensitive Nasdaq scoring the performance edge.
Seven of the 11 S&P 500 sectors closed higher after each traded lower during the session. The information technology (+1.4%) and communication services (+1.5%) sectors, which are this month's worst-performing sectors, outperformed, while the energy sector (-3.3%) was by far the worst performer today.
There wasn't a specific catalyst that drove the market off session lows, suggesting the market simply bounced from a short-term oversold condition, aided by short-covering activity. The S&P 500 was down 6.9% between last Thursday's intraday high (4512.94) and today's intraday low (4200.82).
The downside momentum corresponded with underlying growth concerns, specifically tied to the Fed's hawkish mindset, China's zero-tolerance policy for a worsening COVID-19 situation, and Russia's invasion of Ukraine that has shifted towards a landgrab strategy in eastern Ukraine.
Despite the comeback, growth concerns were still evident in the eight-basis-point decline in the 10-yr yield (2.83%), the 3% decline in oil prices ($98.63/bbl, -3.37, -3.3%), the underperformance of the value/cyclical stocks, and the relative strength of the growth stocks.
The mega-caps, being some of the more beaten-up stocks this month, led the recovery effort in front of their earnings reports this week. The Vanguard Mega Cap Growth ETF (MGK 214.30, +2.64) rose 1.3% while the Invesco S&P 500 Equal Weight ETF (RSP 152.85, +0.46) increased just 0.3%.
In corporate news, Twitter (TWTR 51.70, +2.77, +5.7%) confirmed a definitive agreement to be acquired by an entity wholly owned by Elon Musk for approximately $44 billion, or $54.20 per share, in cash. Coca-Cola (KO 65.94, +0.69, +1.1%) set an all-time high after beating top and bottom-line estimates.
Separately, the U.S. Dollar Index increased 0.5% to 101.71. The 2-yr Treasury note yield fell nine basis points to 2.63%.
Investors did not receive any economic data on Monday. Looking ahead to Tuesday, investors will receive the Conference Board's Consumer Confidence Index for April, New Home Sales for March, Durable Goods Orders for March, the FHFA Housing Price Index for February, and the S&P Case-Shiller Home Price Index for February.
- Dow Jones Industrial Average -6.3% YTD
- S&P 500 -9.9% YTD
- Russell 2000 -13.0% YTD
- Nasdaq Composite -16.9% YTD
Crash Is King
This may be one of many revaluations of capital vis-a-vis labor and resources and core vis-a-vis periphery.
You've heard the expression "cash is king." Very true. But it's equally true that "crash is king:" when speculative excesses collapse under their own extremes, the crash crushes all other narratives and becomes the dominant dynamic.
Everything that the mainstream uses to predict "value," market action and "the future" is tossed out the window. Price-earnings, "growth," "innovation," cash flow, yields, the bat-guano-quatloo carry trade, etc., etc., etc.-- none of it stops the crash or makes sense of the crash, which happens for systemic reasons beyond conventional explanations.
In the context of conventional concepts of "value" and central bank power, crashes are impossible. According to conventional explanations, the central banks control the markets and so crashes are brief and shallow because the banks will quickly change course and flood the financial markets with free money.
In the conventional view, markets are rational and liquid: there will always be a a buyer for every seller (i.e. liquidity) because there will always be a rational reason and cash/credit available to buy an asset at the current price.
Crashes reveal this as false: there is no buyer for every seller in crashes because it's not rational to buy assets which have been grossly overvalued and are resetting at new valuations in a chaotic freefall. Indeed, the entire concept of "value" is in doubt, and as we all know, markets hate uncertainty.
Secondly, there may not be cash or credit available to purchase assets, as credit dries up as fast as liquidity: the last thing lenders want is for reckless gamblers to borrow their money and then lose it all trying to catch the falling knife.
This is why crash is king: when liquidity dries up, the entire structure of "there's always a buyer" collapses. When there are only sellers and few buyers, markets crash. When the underlying value of the asset can no longer be known with any certainty, it's not rational to gamble that the first or second leg down is "the bottom."
When future supply and demand are up in the air, tumbling chaotically, there is no way to pin down the value of anything. Money and credit are no different than any other commodity: the cost and value of money is dictated by demand for that particular flavor of "money" and credit. When "money" loses purchasing power and credit is no longer available, the demand for assets collapses right as assets are dumped to limit losses and raise cash.
It may be time to revisit core and periphery. Like many others, I find the model insightful and useful: The Core-Periphery Model (June 11, 2013).
Crashes reveal what's core and what's periphery because the core controls the destiny of the periphery. In systems terminology, the initial conditions set the parameters of potential options and the limits of the efficacy of various choices. The core's initial conditions are considerably more constructive than the initial conditions of the periphery.
In network terms, every connection between nodes runs through the core. This is not the case for the nodes. The dependency chains are asymmetric: each node looks stable and independent until push comes to shove. Everyone is dependent but some are less dependent than others.
The vast majority of the grandiose claims of what's truly core will be revealed as false in a crash. The crash in core assets is less severe and the bounce back is quicker, as the underlying value of the core resets more readily.
Crashes in the periphery are one-way slides. These assets never recover their speculative-excess valuations because the eventual reset of underlying value strips out all the artificial / phantom value.
It's instructive to look at these charts of the Japanese yen (USDJPY). Something is happening, and the punditry is rushing to stake claims of understanding it all. I am circumspect about this tsunami of explanations. There are a lot of major revaluations underway and these act as feedback for each other in complex ways.
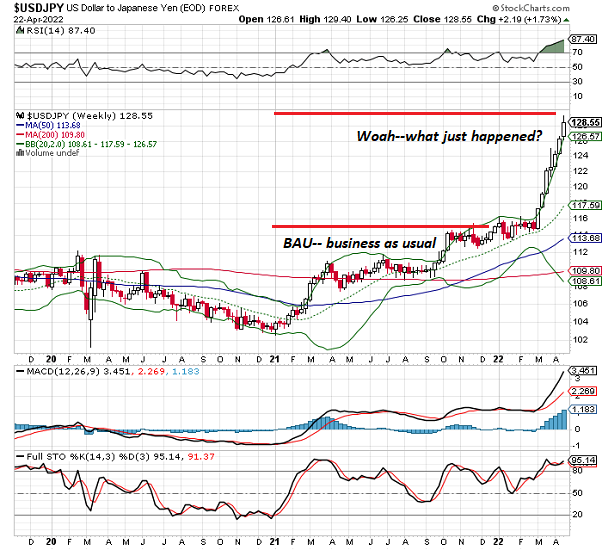

This suggests to me that any one explanation will very likely be wrong / misleading.
It may be nothing more than a zephyr, but I find it interesting that the long-term chart of the USD-Yen appears to be a multi-decade inverse head and shoulders which if it plays out would suggest a massive revaluation of the yen is underway in the direction of devaluing the purchasing power of the yen.
This may be one of many revaluations of capital vis a vis labor and resources and core vis a vis periphery. Cash may be king but when crash is king you have to choose the right kind of cash to avoid the general decimation of "wealth."
Every node claims to be core, but that's not how it works. There may only be one core. While the crash will garner everyone's attention, it's the aftermath of the crash that will inform us what's core and what's periphery.
China Unexpectedly Cuts FX Reserve Ratio To Support Plunging Yuan
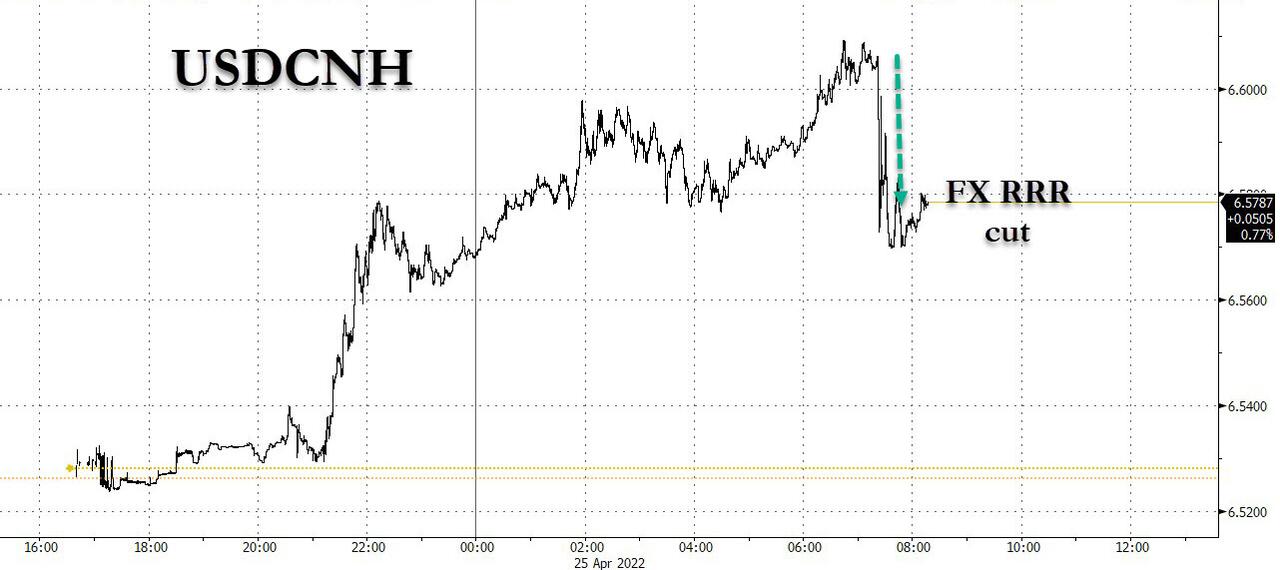
Just minutes after the offshore yuan's extended slide dragged it below the key psychological level of 6.60, a level not breached since Nov 2020, China signaled that while it is now ok with a sliding yuan, there is a limit how much devaluation it will take, and shortly after 7am EDT the PBOC moved to limit the drop in the yuan by cutting the reserve requirement, or how much money banks need to have in reserve for their foreign currency holdings.
The move, which is the opposite of a RRR hike unveiled by the PBOC back in December and which was meant to prevent the yuan from rising too far, came after the yuan plunged in reaction to a growing Covid-19 outbreak in Shanghai and as of this weekend, Beijing too. Financial institutions will need to hold 8% of their foreign exchange in reserve starting May 15, the central bank said in a statement Monday, down from than the current level of 9%.
In a statement, the PBOC said that the cut is aimed at “increasing banks’ capabilities of forex fund use” and will help liquidity management. The change would increase the supply of dollars and other currencies onshore and relieve the yuan’s weakness.
Today' cut follows two hikes last year when the central bank was trying to limit a strong currency, the opposite of the situation now.
While the news did manage to prop up the yuan modestly, with the offshore yuan narrowing arrowed its loss to 0.7% from 1.3% earlier in the day and trading at 6.5711 to the dollar after the announcement, it is still down on the day, and we don' anticipate any material reversal in the recent downtrend in the yuan since China' economy is desperately in need of more stimulus or faces a major hit to growth, both of which hint at far more weakness in the yuan.