>>> Europe : Brokers Upgrades & Downgrades - 25th of April 20222

>>> Up
* Alma Media Raised to Accumulate at Inderes; PT 11 euros
* BioMarin Raised to Overweight at Morgan Stanley; PT $113
* CD Projekt Raised to Hold at Berenberg
* Engie Raised to Buy at Deutsche Bank
* GTT PT Raised to 150 euros from 95 euros at Berenberg
* Novo Nordisk ADRs Raised to Outperform at Cowen; PT $130
* Savills Raised to Buy at Peel Hunt; PT 1,325 pence

>>> Down
* Barrick Gold Cut to Market Perform at Bernstein; PT C$27
* dotdigital Cut to Hold at Berenberg; PT 100 pence
* Kellogg Cut to Hold at Deutsche Bank; PT $73
* National Grid Cut to Hold at Deutsche Bank; PT 1,220 pence
* Newmont Corp Cut to Market Perform at Bernstein; PT $57
* Nimbus Group Cut to Hold at Nordea
* Sinch Cut to Hold at Nordea
* Terna Cut to Hold at Deutsche Bank; PT 8.30 euros

>>> Initiation
* ABG Sundal Collier Rated New Neutral at SpareBank
* Creo Medical Rated New Buy at Numis; PT 250 pence
* Danske Bank Reinstated Buy at HSBC; PT 161 kroner
* DoorDash Rated New Equal-Weight at Morgan Stanley; PT $100
* RTL Resumed Hold at Deutsche Bank; PT 59 euros
* Snowflake Rated New Outperform at Wolfe; PT $250
* Warner Bros Discovery Reinstated Equal-Weight at Morgan Stanley

>>> Call
* GTT Gets Street-High Target at Berenberg on LNG Order Wins
* Novo Nordisk Upgraded to Outperform at Cowen on Wegovy Potential
* Savills Raised as Peel Hunt Sees Opportunity After Stock Drop

>>> What to look at today - 25th of April 2022

Stocks, U.S. futures and commodities sank with Treasury yields Monday as China’s worsening Covid situation amplified concerns about a slowdown in demand in the world’s second-largest economy. MSCI Inc.’s Asia-Pacific gauge fell for the sixth session in seven with sharp declines in Hong Kong and China. S&P 500 and Nasdaq 100 futures contracts dropped in a sign of further weakness to come. European futures fell. Treasuries paused the rout of the past week that roiled markets and the dollar extended an advance as investors opted for safe havens. Crude fell below $100 a barrel and iron ore slumped in Singapore. Palm oil jumped after Indonesia, the world’s largest exporter of the commodity, halted exports of cooking oil and its raw materials amid a local shortage. China locked down some areas of Beijing and ordered mandatory Covid testing in a district as policy makers raced to prevent a repeat of the outbreak that’s hobbled Shanghai. The yuan fell to the lowest since April 2021 and led declines in emerging-market currencies.
Fears a wider lockdown in the Chinese capital amid the government’s steadfast adherence to its Covid-zero policy is spooking investors. They are worried about disruptions to the global supply chain and a deteriorating economic outlook from the Shanghai restrictions as well as disappointment at policies to shore up growth and stabilize markets. he war in Ukraine continues to provide an uncertain backdrop for the markets. U.S. Secretary of State Antony Blinken and Defense Secretary Lloyd Austin arrived in Kyiv for talks as Russia’s war on Ukraine enters its third month. The euro erased gains made after Emmanuel Macron’s win on a pro-business, pro-Europe platform in the French election removed a key risk for markets. Markets in Australia and New Zealand are closed for holidays Monday.

Nikkei -1.81% Hang Seng -3.15% CSI -2.85% Shanghai -3.20% Shenzen -4.36%

Eur$ 1.0775 CNH 6.5954 CNY 6.5530 JPY 128.59 GBP 1.2806 CHF 0.9583 RUB 77.3698 TRY 14.7428 WTI$ 99.19 -2.80% Gold 1,917.48 -0.73% BTC 39,190 -0.82% ETH 2869 -2.51%

S&P -0.75% Nasdaq -0.69% EuroStoxx -1.67% FTSE -1.34% Dax -1.58% SMI -1.31%

Macro :
- Beijing Outbreak Fear Sinks Stocks and Commodities: Macro Squawk
- German Arms Maker Seeks to Send 100 Tanks to Ukraine: Welt
- Europe Risks Rationing If Putin Cuts Off Russian Gas Supply
- Stocks Will Shake Off Gloom and Shine, Defiance’s Jablonski Says
- Cathie Wood Says Fed Won’t Hike as Much as Market Priced In
- Four SPAC Offerings Aborted as Investors Flee Blank Checks
- Ukraine Fallout ‘Manageable’ for Europe’s Banks: EBA to HB

Keep an eye on :
- AIR FP : Boeing to Push Back 777X Program by 9-12 Months: The Air Current
- AIR FP : MHI to Spend 10b Yen to Boost Airbus Parts Supply: Nikkan Kogyo
- ANTIN FP : Antin 1Q Assets Under Management EU22B
- A2A IM : Carlo Tassara Notifies Added Writ to A2A and EDF Subsidiary
- ALIV SS : Autoliv to Build Airbag Factory in Japan’s Aichi: Nikkei
- AZA SS : Avanza 1Q Operating Income Meets Estimates
- BBVA SM : BBVA Raises Offer Price for Garanti to 15 Liras Per Share
- CSGN SW : Norway Wealth Fund Votes for Special Audit of Credit Suisse
- RACE IM : Ferrari Looking for Partnerships, Not Mergers: CEO Vigna to Sole
- G1A GY : GEA Group Says Kempf Designated as Chairman of Supervisory Board
- IBE SM : Spain’s Calvino Says a Cap on Gas Prices Could Halve Energy Bill
- ICAD FP : ICADE 1Q Revenue EU413.9M Vs. EU392.5M Y/y
- TKWY NA : Cat Rock Capital Urges Just Eat Shareholders to Vote Against CFO
- KER FP : Gucci Miss Dents European Luxury Wiping Out Over $10 Billion
- NOVOB DC : Novo Nordisk Says EMA Grants Positive Opinion on Insulin Storage
- PHIA NA : Philips 1Q Adjusted Ebita Misses Estimates, Philips Earnings Miss as Dutch Firm Warns of Supply Snarls
- RECSI NO : Hanwha to Support REC Effort to Reopen Moses Lake From 2023
- RNO FP : Two Chinese Firms Eye Purchase of Renault AvtoVaz Stake: Report
- ROG SW : Roche 1Q Sales Beats Estimates, *ROCHE SEES SALES OF COVID PRODUCTS DOWN ~CHF2B TO ~CHF5B
- SCYR SM : Sacyr Enters Into Second Shares Derivatives Agreement
- SDRL NO : Seadrill Says Sonadrill JV Wins Ten-Well Contract With Options
- SHEL LN : Ukraine Criticizes Shell’s Rules on Russian Fuel Purchases
- TE FP : Technip Energies 1Q Adjusted Recurring Ebit Beats Estimates
- TED LN : Authentic Brands Group Weighs Bid for Ted Baker, Sky Reports
- TSLA US : ‘Weak Sauce’ Taunt Highlights Musk’s 2018 Spat With Saudi Fund
- THG LN : THG Rises Briefly on Betaville Mention Before Erasing Gains
- TWEKA NA : TKH 1Q Return on Sales 13.4% Vs. 9.6% Y/y
- UBI FP : Take-Two, Electronic Arts Rise on Reported Interest in Ubisoft
- VLA FP : Valneva Says CHMP Requests More Data on Covid Vaccine Candidate
- VIV FP : Vivendi 1Q Revenue Beats Estimates
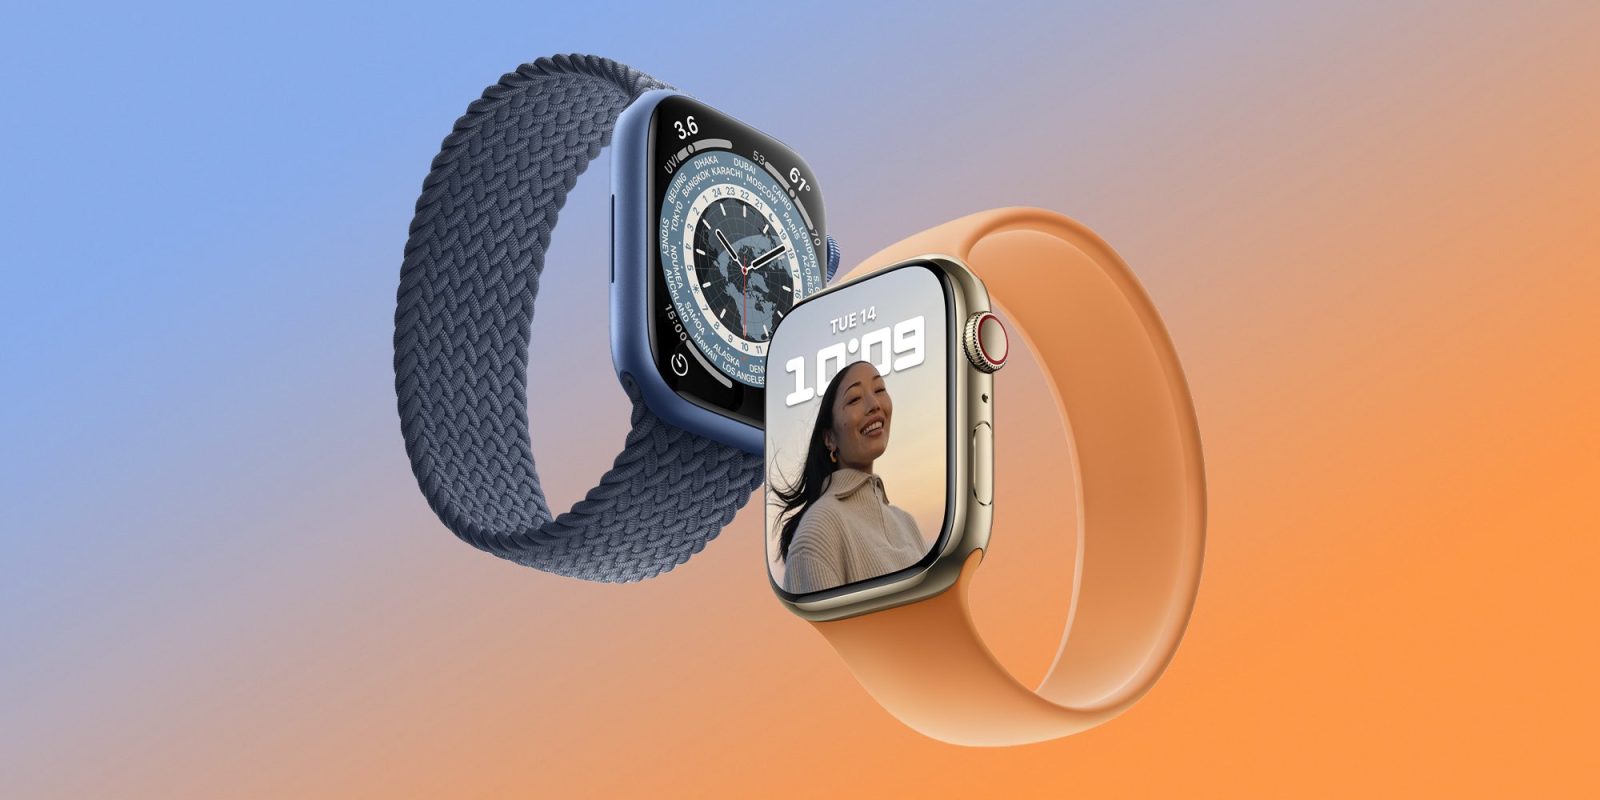
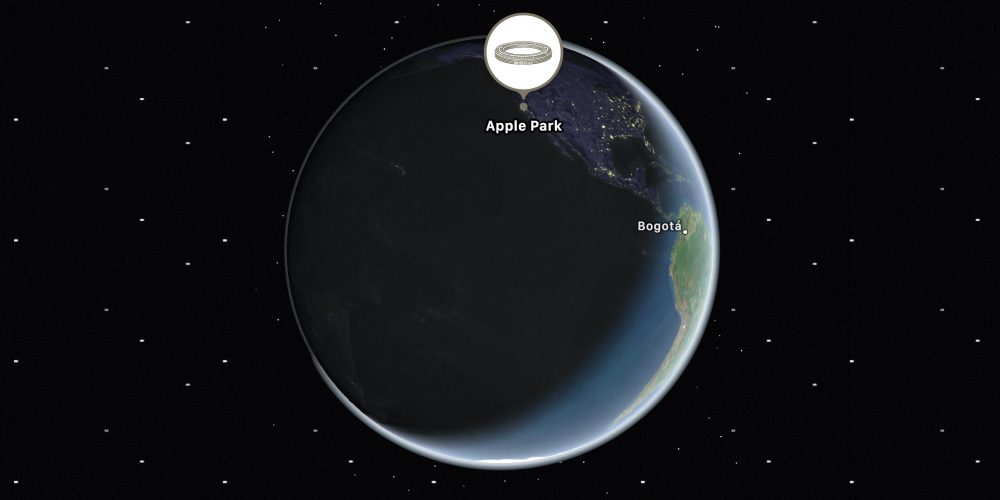
9to5Mac : Apple Watch could feature satellite connectivity in a future model


Last year, rumors about the iPhone 13 getting a satellite connectivity started to spread. Although this iPhone didn’t get the feature, it’s rumored that the upcoming iPhone 14 could have it for emergencies or to send short texts to emergency contacts when out of cellular service range.
Now, according to a new report by Bloomberg’s Mark Gurman, the next Apple Watch could also feature this extra technology.


In his Power On newsletter, the journalist says ”the Apple Watch is also destined to get that functionality,” although Gurman believes Apple’s timeframe could be this year or 2023.


Whether it’s on the iPhone or Apple Watch, the technology would provide an alternative to the Garmin inReach Explorer and SPOT, handheld satellite communicators with similar features.
There have been signs lately that Apple and its apparent satellite partner Globalstar Inc. might be getting closer to launching such a feature. In February, Globalstar said it reached an agreement to buy 17 new satellites to help power ’continuous satellite services’ for a ’potential’– and unnamed – cusstomer that had paid it hundreds of millions of dollars.


Since rumors point out that Apple could be aiming for three new Apple Watches this year – the regular model, a new SE, and a brand new Watch destined for extreme sports –, it would make sense if at least the regular model and the rugged Apple Watch get this feature.


Last year, Gurman was already doubtful about satellites communication launching with the iPhone 13 by saying the hardware wasn’t ready yet for the new phones. Now, even if this feature launches this year, it will likely be restricted to key markets. Here’s what he wrote in August 2021:


“The emergency features will only work in areas without any cellular coverage and only in select markets. Apple envisions eventually deploying its own array of satellites to beam data to devices, but that plan is likely years away from taking off.”


Would you think this could be the next big feature on the Apple Watch? You can read our full roundup of what to expect about the Apple Watch Series 8 here. Don’t forget to share your thoughts on the comment section below.

WSJ : Melvin Capital Management Scraps Plan to Start Charging Performance Fees A

Melvin Capital Management Scraps Plan to Start Charging Performance Fees Again
‘I am sorry. I got this one wrong,’ Melvin founder Gabe Plotkin writes to clients

Gabe Plotkin scrapped a plan to start charging performance fees again at his beleaguered hedge fund, Melvin Capital Management, after encountering backlash from investors.

Mr. Plotkin on Thursday told clients he planned to shrink the size of Melvin’s hedge fund by several billion, to $5 billion, and resume charging performance fees even though his investors are still sitting on steep losses. Those who had been invested at the start of 2021 have lost 51.8% through March, after a big hit Melvin suffered in January of last year due to the meme-stock rally.

While Melvin planned to charge reduced incentive fees for 30 months and Mr. Plotkin had also laid out a set of investor-friendly changes, his move to buck the industry standard of holding off on charging performance fees until he had made clients whole generated surprise and criticism from some of his investors, as well as other industry participants.

“I am sorry. I got this one wrong. I made a mistake. I apologize,” Mr. Plotkin wrote in a Sunday message to investors that was viewed by The Wall Street Journal. His reversal was earlier reported by the New York Post.

He said Melvin would take two to three weeks to reassess in light of the feedback it had received before coming back with another proposal, despite enough sign-on from investors to move forward with his original restructuring plan.

“Some of you feel that we were not being a good partner. Upon reflection, you are right,” he wrote.

Mr. Plotkin said he had been too focused on retaining his team and the favorable reaction of several investors Melvin had had initial conversations with to realize his plans were “tone deaf.”

FT : Italy can deal with higher interest rates

Italy can deal with higher interest rates
ECB should not let worries over country’s debt stand in way of greater monetary policy action against inflation

As inflation rises in the eurozone, the pressure is inevitably building for the European Central Bank to step up planned monetary policy action.

In March, European Central Bank president Christine Lagarde explained how the overdue normalisation of monetary policy was envisaged in Frankfurt: in the third quarter, bond purchases could be reduced to net zero with only maturing securities to be replaced. Only then would interest rates be raised “gradually”.

The ECB is likely to be concerned that a more rapid normalisation of monetary policy, comparable with moves by the US Federal Reserve or the Bank of England, could entail risks to financial market stability. For this reason, it may prefer to move only cautiously, almost as if on eggshells.

What seems to be the problem? A key concern appears to be Italy. Will the country be at risk of descending into a debt abyss if super-loose interest rates rise?

The ECB may feel it has been wrongfooted once. Back in March 2020, Lagarde stated in one of her first press conferences that the ECB was not there to close government bond spreads. That is not wrong, of course. But her words had not yet faded away when a formidable sell-off of Italian government bonds began, worse than on any single day of the euro crisis. Lagarde had to row it all back immediately.

But the ECB needs to leave the difficulties of that day behind. It should not stand in the way of tightening monetary conditions more courageously than it has hitherto communicated. The fear that Italy’s high debt load could pose a challenge to monetary normalisation cannot be dismissed out of hand. But Italy’s resilience has become much more solid than many doomsayers give it credit for.

Last month’s announcement from Lagarde that the ECB would end its colossal bond purchases sooner than generally expected provoked a comparatively restrained reaction in Italian government bonds.

For sure, it will not be without consequences if the ECB stops buying the equivalent of all new issues of euro government bonds, as has been the case for the past two years. Interest rates have already risen. Spreads are likely to widen further. But that is a healthy market response and should not be feared.

Italy is in a better position than many observers believe: high inflation is reducing government debt. With inflation-driven nominal growth of 10 per cent, Italy’s debt ratio falls by 15 per cent of GDP in 2022, other things being equal. That helps.

It helps even more that effective interest rates are very low. Italy pays an average interest rate on its outstanding debt that has declined to only 2 per cent, right at the ECB’s inflation target and well below inflation. Higher-yielding bonds issued a decade ago are still maturing and can be refinanced more cheaply today. The effective interest burden will therefore remain low or even fall for a few more years.

Something else is both unusual and favourable. Italy currently has a stable and competent government that enjoys broad parliamentary support. This is by no means a matter of course in a country where the last “elected” prime minister, meaning the candidate heading the victorious party list, was one Silvio Berlusconi, almost fifteen years ago.

Finally, Italy will have to issue less debt than many realise. The average life of Italy’s public debt is seven years, even if the Treasury has not taken advantage of the super low rates to extend its maturity profile. Only a small portion needs refinancing every year. And Rome busily pre-funded in the first quarter while the ECB’s €1.85tn “pandemic emergency purchase programme” of asset buying was still up and running.

Rome’s borrowing needs will be further reduced through substantial budgetary relief from the Next Generation EU reconstruction fund. Between 2023 and 2025, Italy can expect annual grants of more than 1 per cent of its gross domestic product and a little more than that again through cheap EU loans.

This makes it much more likely that prime minister Mario Draghi will be able to push through structural reforms to address Italy’s growth weakness than any of his predecessors, including Mario Monti, who had to run austere public finances.

The risk of inflation getting out of control is rapidly rising. The ECB must shift up a gear. The worry that Italy cannot cope financially is unfounded. It can and it will. All the stars are aligned, and it won’t get any better than this. The longer Lagarde hesitates, the more likely it becomes that an Italian government crisis will get in the way. Then it would get truly tricky to increase rates. Don’t wait!

FT : Gates-backed company accused of firing whistleblowers who flagged misconduc

Gates-backed company accused of firing whistleblowers who flagged misconduct
US-listed Ecolab also praised ‘integrity’ of compliance culprit

Ecolab, the hygiene company backed by Bill Gates, last year praised the “integrity” of an executive who resigned over an alleged compliance breach and later fired two employees who had flagged the misconduct internally, the Financial Times can reveal.

The compliance saga, which took place at a German subdivision of the $50bn US-listed company, highlights the pitfalls for multinational companies from potentially mishandled compliance investigations.

Ecolab, based in St Paul, Minnesota, employs 47,000 staff globally and generates $13bn in annual revenue by offering water purification, hygiene and pest control services.

Bill Gates’ family office Cascade Investment is its largest shareholder, owning 10.7 per cent of the company. The trust of the Bill & Melinda Gates Foundation holds another 1.5 per cent in the group.

In April 2021, its compliance team found that a manager in Germany had violated the company’s code of conduct, according to Ecolab.

The individual, who is not being named for legal reasons, was found to have shared confidential and sensitive client data from two key competitors with colleagues using work email.

The extensive data contained several lists of clients, contracts with clients, and information on the revenue rivals generated with their individual customers, including a US army base in Germany, people familiar with the case said.

One of the rival’s client lists referenced many hygiene issues at particular supermarkets, restaurants and bakeries across Germany.

Ecolab’s code stipulates that employees must “understand what is ethical and unethical or legal and illegal in gathering and using trade information”, and states that they must “avoid any inappropriate or illegal means of gathering information about competitors or customers”.

The company said in a statement: “We can confirm that the matter was investigated by our compliance department immediately when it was raised in April 2021 and an Ecolab employee left the company soon after.”

It added that it did not pay any severance to that employee as “a violation [of the code of conduct] was established” and the manager left “shortly afterwards by mutual agreement”.

Three months after the compliance complaints were filed, Ecolab then fired the two whistleblowers, arguing their jobs had become obsolete in an internal restructuring.

In a court hearing in Frankfurt in February, one of the whistleblowers said the reorganisation was a mere pretext to fire him in retaliation for speaking out against superiors.

“They wanted to get rid of me because they saw me as someone who had fouled his own nest,” he told the judge, pointing out that Ecolab issued a job ad advertising a role that matched his own just one month after the dismissal. A lawyer for Ecolab disputed those arguments in court.

People familiar with the case said the two whistleblowers were the only employees who lost their jobs in that reshuffle, and that the company shortly afterwards hired another person for a similar job.

However, one of the people added that five more employees left the company several months later when a regional office was closed.

The judge presiding at the Frankfurt employment tribunal said “the connection [between the compliance case and the termination] seems questionable to me”, pointing to the sequence of events and stating that it was unreasonable to believe a company would fire employees for reporting misconduct.

Ecolab eventually settled both employment lawsuits, paying the former employees about €45,000 in severance pay. As part of the settlement, the employees formally stated that none of their rights had been violated by the company.

The company said in a statement it never has or would “dismiss an employee because they raised compliance-related concerns”, adding that the case at issue was “a complex situation where the motives of multiple individuals may not be immediately clear”.

Ecolab declined to comment on whether it investigated how the data was obtained, if other employees might have been involved and if it was ever used by its sales force.

Marcel Leeser, a partner at the Cologne-based law-firm Hoecker who represents the manager that resigned following the compliance probe after being accused of the data misuse, said the departure was entirely voluntary and stressed his client did not commit any wrongdoing.

The manager was later issued with an extremely positive employment reference, explicitly praising their “integrity” and stating that they had always conducted their work to Ecolab’s highest satisfaction.

Ecolab said “we were unaware” that such a favourable employment reference had been issued.

“Given all that we know of the circumstances, we consider it unfortunate and are surprised that an employment reference was provided,” the company said.

It added that “we believe that it includes language suggested by the ex-employee”. Leeser denied his client had any involvement in the drafting of the reference.

Cascade and the Bill & Melinda Gates Foundation declined to comment.

FT : Activist urges investors to move against Just Eat Takeaway’s board

Activist urges investors to move against Just Eat Takeaway’s board
Cat Rock Capital calls for removal of finance chief and most of food delivery group’s supervisory team

Just Eat Takeaway.com is set for a showdown with investors at next week’s annual meeting, with one top shareholder alleging that the company misled shareholders on its financial firepower ahead of two crucial votes to approve last year’s $7.3bn Grubhub deal.

Cat Rock Capital, one of the food delivery group’s top five shareholders, published an open letter on Monday calling on other investors to join it in voting against the re-election of finance chief Brent Wissink and most of JET’s supervisory board, including its chair, Adriaan Nuhn, at the meeting in Amsterdam on May 4.

In the letter, seen by the Financial Times, Cat Rock’s founder and managing partner, Alex Captain, said JET’s management and supervisory boards had “failed all stakeholders”, overseeing a “catastrophic destruction of equity value in the past two years”.

Cat Rock’s letter follows an earlier declaration by another JET investor, Lucerne Capital, that it planned to vote against the re-election of Wissink and the six-person supervisory board next week, as well as abstaining from voting to re-elect Jitse Groen as chief executive.

Despite the huge boost to food delivery apps provided by two years of sporadic lockdowns, Just Eat Takeaway’s stock has lost more than two-thirds of its value since it announced the acquisition of US food delivery group Grubhub in June 2020.

Groen said last week that JET was now assessing whether to sell some or all of Grubhub, less than a year after the deal closed, as well as downgrading its growth forecasts for the year.

Captain hopes a new chief financial officer could “restore credibility with the capital markets” after the company underestimated the scale of its losses in the past two years.

“JET’s management and supervisory boards torpedoed the company’s share price by providing a misleading outlook on the company’s profitability in advance of the Grubhub shareholder votes in October 2020 and June 2021,” Captain said. “These misleading financial disclosures led to two massive profit downgrades in 2021 and the complete loss of trust in the company’s financial guidance.”

JET said its management team “shares investor disappointment in the recent share price performance” but recent actions such as potentially selling Grubhub “are intended to create significant shareholder value”. 

“We have always acted in good faith and in line with our obligations with regard to our market communications, including in respect of the Grubhub acquisition,” JET said.

“We believe that Cat Rock’s proposal to remove key supervisory and management board members, would be both value destructive and destabilising.”

Until last year, Connecticut-based Cat Rock, which owns 6.9 per cent of JET, had been one of the company’s biggest cheerleaders. It successfully pushed for the merger of Takeaway.com, which Groen founded 22 years ago, and UK-based Just Eat, in early 2020. Captain said then that Groen’s experience as an entrepreneur and operator could help revive Just Eat, which was suffering as Uber Eats and Deliveroo took market share.

But Captain has lost patience with Groen in recent months, first urging him to unwind the Grubhub deal last summer.

Meanwhile, Institutional Shareholder Services, an influential investor advisory group, has recommended that its clients vote against the re-election of Nuhn, JET’s chair, citing concern over lack of gender diversity on the board.

ISS does, however, recommend voting in favour of the re-election of the management board, including Groen and Wissink, saying in its report this month that there was “no known controversy” surrounding the candidates.

WWD : Bell & Ross Debuts Hued Limited-edition Vintage Styles

Bell & Ross Debuts Hued Limited-edition Vintage Styles
Available in three options, each one is limited to 500 pieces.


While its signature cockpit instrument-inspired square case designs tend to dominate enthusiastic conversations surrounding the brand, Bell & Ross also offers a wide range of more-conventional sports watches.
The bright-colored dial trend continues to maintain a stronghold in the watch arena, with brands from Rolex to Omega and Oris getting in on the action. Now it’s Bell & Ross’ turn, as the aviation-focused brand has just released two limited-edition color variants of its vintage-inspired BR V2-92 in Orange and Full Lum.
Both styles share the same 41mm round stainless steel case design — a domed sapphire crystal with AR coating, calibre BR-Cal.302 automatic movement, sapphire crystal display back with quarter-hour numerals, an attractive typography and a minute track on the dial, not to mention a bi-directional timing bezel. For this outing, both the BR V2-92 Orange and Full Lum step away from true dive watches by offering only 100 meters of water resistance.


Bell & Ross BR V2-92 Full Lum.
Bell & Ross BR V2-92 Orange.
The Orange novelty pays tribute to the world of skateboarding with its neo-retro design and its pop color associated with the sport, which was born in California in the ’70s.
The Full Lum features the same design as the Orange variation, but with a full luminescent dial. As its name suggests, it boasts a fully lumed dial in pale green, with its hands and markers denoted in yellow with black outlines. In dark conditions, the main dial surface’s lume glows with an ice blue hue, standing out from the dial hardware’s green glow in images.
Both the Full Lum and Orange timepieces will be available on Tropic-style black rubber straps, with the Orange also featuring a stainless steel three-link bracelet. Each style will be limited to 500 pieces and they are available now at Bell & Ross’ online shop, with the Orange pieces starting at $3,500 (on rubber) and $3,800 (on stainless bracelet) and the Full Lum (only available in a rubber option) for $3,800.
Bell & Ross BR V2-92 Orange.
Bell & Ross BR V2-92 Full Lum.

WSJ : Twitter, Elon Musk Are in Talks to Strike a Deal

Twitter, Elon Musk Are in Talks to Strike a Deal
Turn of events comes days after the billionaire unveiled his $43 billion bid for the social-media company

Twitter Inc. TWTR 3.93% is in discussions to sell itself to Elon Musk and could finalize a deal as soon as this week, people familiar with the matter said, a dramatic turn of events just 10 days after the billionaire unveiled his $43 billion bid for the social-media company.

The two sides met Sunday to discuss Mr. Musk’s proposal and were making progress, though still had issues to hash out, the people said. There are no guarantee they will reach a deal.

Twitter had been expected to rebuff the offer, which Mr. Musk made April 14 without saying how he would pay for it, and put in place a so-called poison pill to block him from increasing his stake. But after the Tesla Inc. TSLA -0.37% chief disclosed that he has $46.5 billion in financing and the stock market swooned, Twitter changed its posture and opened the door to negotiations, The Wall Street Journal reported earlier Sunday.

Mr. Musk has said from the beginning that his $54.20-a-share offer is his “best and final,” and he reiterated to Twitter Chairman Bret Taylor again in recent days that he won’t budge on price, some of the people said. The conversations between the two sides were expected to focus on issues including what Mr. Musk would pay should an agreed deal fall apart before being consummated.

Twitter is slated to report first-quarter earnings Thursday and had been expected to weigh in on the bid then, if not sooner.

The potential turnabout on Twitter’s part comes after Mr. Musk met privately Friday with several shareholders of the company to extol the virtues of his proposal while repeating that the board has a “yes-or-no” decision to make, according to people familiar with the matter. He also pledged to solve the free-speech issues he sees as plaguing the platform and the country more broadly, whether his bid succeeds or not, they said.

Mr. Musk made his pitch to select shareholders in a series of video calls, with a focus on actively managed funds, the people said, in hopes that they could sway the company’s decision.

Mr. Musk said he sees no way Twitter management can get the stock to his offer price on its own, given the issues in the business and a persistent inability to correct them. It couldn’t be learned if he detailed specific steps he would take, though he has tweeted about wanting to reduce the platform’s reliance on advertising, as well as to make simpler changes such as allowing longer tweets.

Some shareholders rallied behind him following the meetings. Lauri Brunner, who manages Thrivent Asset Management LLC’s large-cap growth fund, sees Mr. Musk as a skilled operator. “He has an established track record at Tesla,” she said. “He is the catalyst to deliver strong operating performance at Twitter.” Minneapolis-based Thrivent has a roughly 0.4% stake in Twitter worth $160 million and is also a Tesla shareholder.

Mr. Musk already has said he is considering taking his bid directly to shareholders by launching a tender offer. Even if he was to get significant shareholder support in a tender offer—which is far from guaranteed—he would still need a way around the company’s poison pill, a legal maneuver it employed that effectively blocks him from building his stake to 15% or more.

One oft-employed tactic to push a bid, seeking to gain control of the target’s board, is out of reach for now. Twitter’s directors have staggered terms, meaning a dissident shareholder would need multiple years to gain control rather than a single shareholder vote. Twitter tried last year to phase out the staggered board terms given that they are frowned upon by the corporate-governance community, but not enough shareholders voted on the measure. The company is attempting to do so again at this year’s annual meeting set for May 25. Only two directors are up for re-election, and it is too late for Mr. Musk to nominate his own.

Twitter’s shares have been trading below his offer price since he made the bid April 14, typically a sign that shareholders are skeptical a deal will happen, though they did close up roughly 4% Friday at $48.93, the day after he unveiled financing for the deal. Mr. Musk has indicated that if the current bid fails, he could sell his stake, which totals more than 9%.

The financing included more than $25 billion in debt coming from nearly every global blue-chip investment bank aside from the two advising Twitter. The remainder was $21 billion in equity Mr. Musk would provide himself, likely by selling existing stakes in his other businesses such as Tesla. The speed at which the financing came together and the market selloff in recent days—which makes the all-cash offer look relatively more attractive—likely contributed to Twitter’s greater willingness to entertain Mr. Musk’s proposal.

Twitter’s board should engage with Mr. Musk since its stock has “gone nowhere” since the company went public eight years ago, Jeff Gramm, a portfolio manager with Bandera Partners LLC, a New York hedge fund with about $385 million under management, said earlier. The firm last bought Twitter shares in February and owns about 950,000 overall, which accounts for about 11% of its portfolio.

Mr. Gramm said Twitter’s board can’t walk away from Mr. Musk’s offer without providing an alternative that gives real value to shareholders. “I’m not sure what that can be at this stage besides finding a higher bid,” he said.