(ZH) Goldman Sees S&P Tumbling To 3150 When The Recession Hits

Goldman Sees S&P Tumbling To 3150 When The Recession Hits

After plunging on Friday, S&P futures are starting off the new week even lower with spoos at 3,860 in Sunday evening trade, just 4 points away from a bear market (3856 is 20% off the January all time high), with all other assets - treasuries, commodities and cryptos - all puking as well in the latest "crash correlations to 1" trade as markets freak out that the Fed will crash and burn everything - stocks, bonds, the economy, Biden's approval rating - just to contain inflation, forgetting that once the Fed achieves its mission of a hard landing (because a soft-landing won't push jobs nearly low enough to short-circuit the wage-price spiral), it will be up to the Fed to restart the US economy (since Democrats will be kicked out of Congress in an avalanche this November) and with Biden president, there will be no fiscal stimulus for at least two more years.
With that in mind, Goldman's chief equity strategist - whose economists now expect the Fed to hike 50bps in September, if keep the June hike at 50bps despite some banks such as Barclays now expecting a "surprise", non-consensus 75bps rate hike this week - cautions clients that equity valuations remain far from depressed, to wit:
The median S&P 500 constituent’s P/E ratio of 18x ranks in the 87th percentile since 1976. For context, in March 2020 the median stock’s P/E was 14x (47th-percentile). Valuations appear more attractive in the context of interest rates, but still do not look “cheap.” The 540 bp gap between the median stock’s EPS yield and the real 10-year Treasury yield ranks in the 49th percentile, whereas in March 2020 the yield gap was 727 bp (7th percentile).
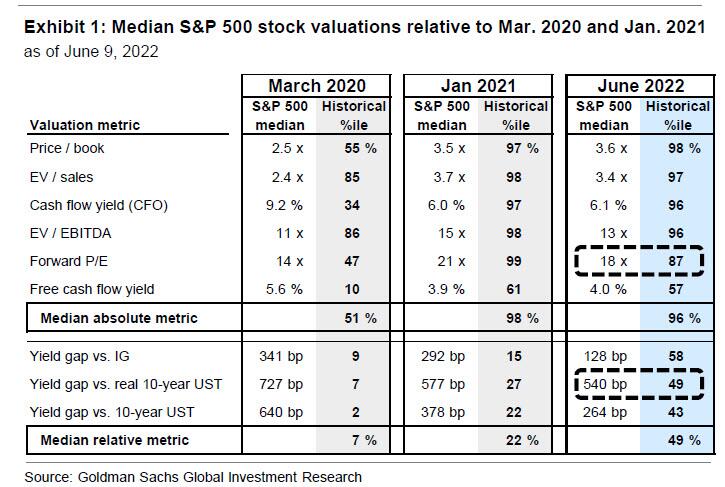
Yet as David Kostin writes in his latest Weekly Kickstart note (available to professional subs) his base case forecast valuation is expected to remain roughly flat while earnings growth does the heaving lifting and pushes the S&P back to 4300 at year-end 2022, some +10% from here - or at least until Kostin slashes his year end forecast once again, and for the 4th time in a row- as he himself hedges when warning that "inflation surprises like this morning’s will also affect the path of multiples, for better or worse."
How do we know that Kostin is just biding his time until he cuts his S&P price target again (which will likely mark the bottom of stocks in the current cycle)? Because as he admits next, "some of the economic developments that have boded well for the Fed’s battle with inflation have intensified concerns about the earning outlook." As a result, he notes that while "Valuations dominated investor focus in early 2022, but recent client conversations have centered on risks to EPS estimates" which of course is not news to regular readers and to those who have been focusing on Wall Street's more bearish strategists, such as Morgan Stanley's Mike Wilson, who has been warning for a while now that attention has shifted from multiples to earnings. Anyway, back to Kostin who writes that "company announcements have added to these concerns. Just weeks after shares fell by 25% on disappointing 1Q margins, Target (TGT) cut margin guidance this week as it struggles to manage excess inventory. Investors have also focused on a string of downbeat comments from tech companies. In recent weeks firms including AMZN, MSFT, and NVDA have signaled intentions to slow hiring. This development is positive in terms of balancing the labor market but reflects management anxiety about growth and inflation."
Catching up to what Wilson has been saying for months, Kostin finally concedes that he, too, "expects further downward revisions to consensus earnings estimates."
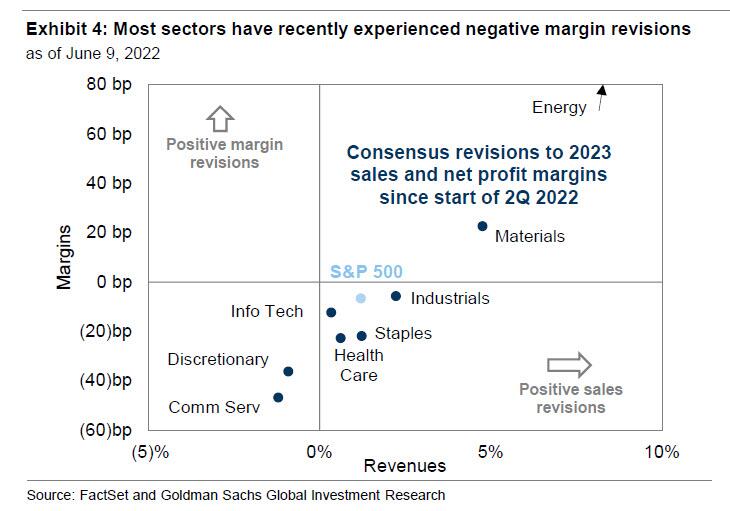
The Goldman strategist also warns that while "margins have driven the majority of recent analyst cuts, estimates still appear too high" and Kostin now expects S&P 500 net margins excluding Financials and Energy will slip from 12.7% in 2021 to 12.6% in 2023, even as consensus idiotically expects a 30 bps rise to 13.0%, even though most sectors (with the notable exception of Energy) have recently experienced negative margin revisions.
Keeping in mind that his latest note is just a placeholder for the forthcoming S&P price target cut, Kostin notes that his "base-case 2023 EPS forecast is $239, 5% below consensus of $251. If the economy contracts, the 13% median historical recession decline would bring 2023 EPS to $200. If the economy avoids recession, but margins and revenues for most sectors return to pre-COVID trends, S&P 500 EPS would equal roughly $215."
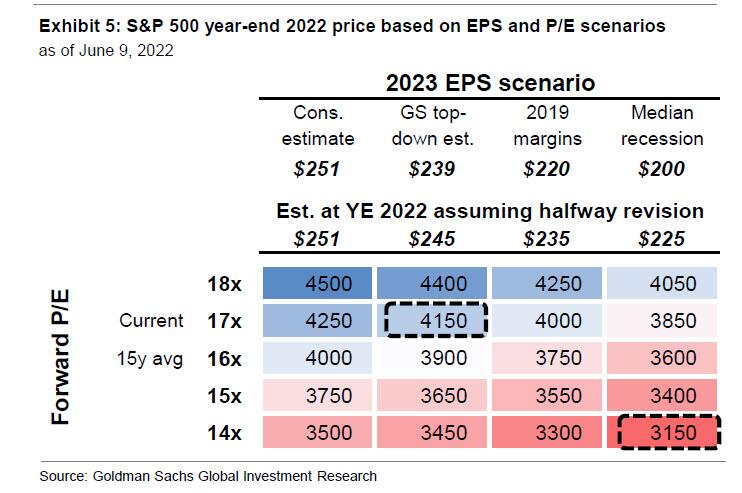
The chart below summarizes the potential S&P 500 levels at year-end 2022 based on various EPS and P/E scenarios (which a first year analyst can do on their own, of course). The scenarios assume that by year-end consensus 2023 EPS forecasts move halfway from current estimates to eventual actual EPS. For example, if the consensus 2023 EPS estimate moves halfway to our top-down forecast of $239 and the P/E multiple remains at 17x, the implied index level would equal 4165. If the EPS estimate moves to $225, halfway to the recession scenario of $200, a 14x P/E would bring the S&P 500 to 3150.
What we find more interesting is Goldman's admission that a worst-case scenario is likely, and what that would mean for the S&P:
In a recession, if the EPS estimate moves halfway to $200, a 14x P/E would bring the S&P 500 to 3150.
What does all this mean for investors, especially those who aren't dumping everything yet because they realize that the coming Fed freakout and equity ETF buying will be something never before seen:
Investors looking for value opportunities should consider both valuations and potential downside risk to earnings estimates. For example, at the sector level, Energy trades well below its 30-year average P/E multiple in absolute terms, and close to record lows relative to the S&P 500. Even haircutting its EPS by the median of the past six recessions, the P/E ratio today would still rank below the 30-year average. While Health Care trades at a P/E close to its 30-year average, it has grown EPS during each of the last six recessions, and looks more attractively valued today than other defensive sectors like Utilities.
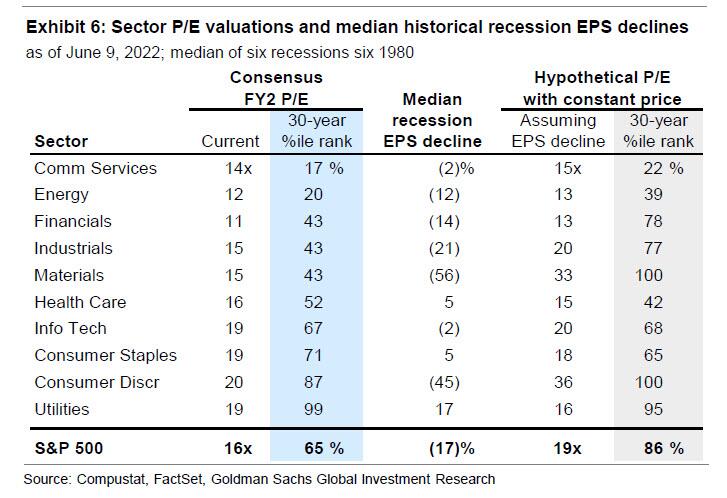
What about growth stocks ahead of the coming recession? Somewhat controversially, Kostin is not overly negative here, and writes that at a factor level, "the macro environment is becoming more favorable for Growth stocks" yet valuations is one reason he still prefer “quality” attributes.
Hints of easing inflation and less need for FCI tightening help explain the recent Growth stock rebound, including the past month’s 30% return for the GS Non-Profitable Tech Basket (GSXUNPTC). Concerns about corporate earnings also increase the appeal of secular growth stocks. However, the outlook for the Fed’s battle with inflation remains uncertain, as underscored by today’s CPI data and our commodity strategists raising their Brent forecast to $140/barrel. In addition, the valuation spread between Growth and Value remains wide relative to history. In contrast, our sector-neutral low volatility, high profit margin, and high return on capital factors each trade at discounts to their historical average valuations.
Bottom line: we commiserate with Kostin who is tacitly hinting that yet another S&P price target cut is looming, especially when one considers that a recession is now just months if not weeks away, (one which as Kostin concedes would send the S&P tumbling to 3,150) an outcome which is abundantly clear when reading the latest note from that other Goldman trader and strategist, Tony Pasquariello, who unlike Kostin is not afraid to say what he really thinks.

(ZH) Ethereum Tumbles Below Holders' Average Cost Basis

Ethereum Tumbles Below Holders' Average Cost Basis

While bitcoin remains stuck to a $30,000, trading in a $2k range around the "nice, round number" for the past month...
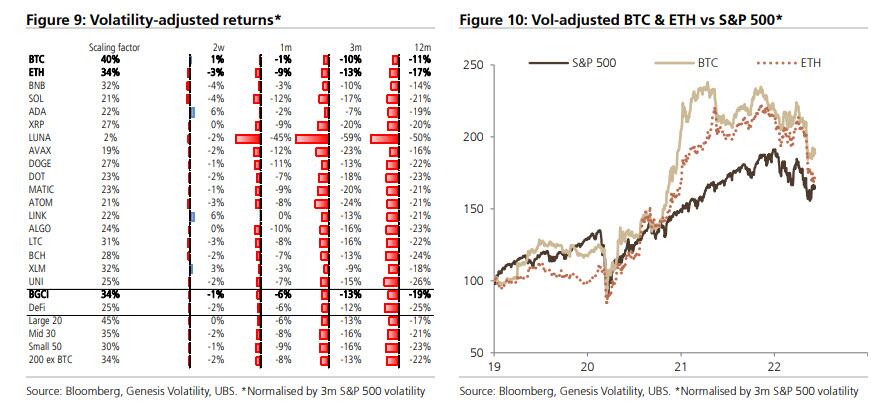
... In its latest weekly Crypto Compass note, UBS writes that what is most stunning is how bitcoin's biggest challenger, ETH has totally retraced its entire outperformance since late 2020 to the point where it has merely level-pegged with benchmark equities since both then and the start of 2019 for an equivalent unit of risk invested.
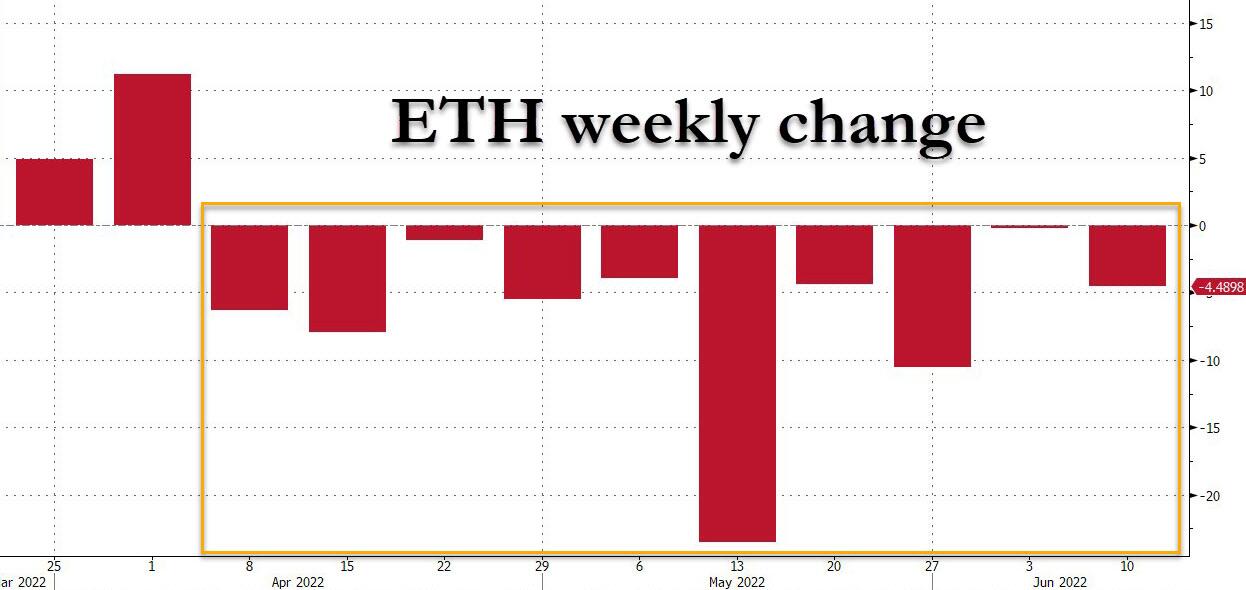
Worse, after relentlessly dropping for 10 consecutive weeks..
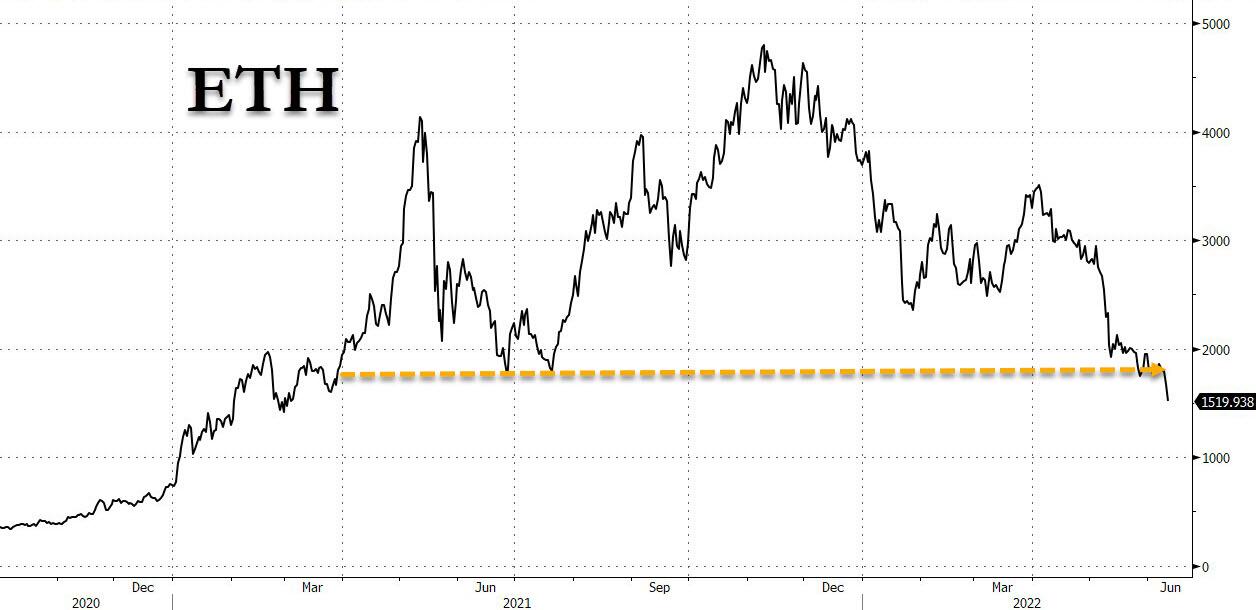
... the token which forms the backbone for web3, and which Goldman called the "Amazon of information" has just taken out a key long-term long-term support, tumbling 12% on Sunday to 1,500.22, the lowest price since Jan 2020.
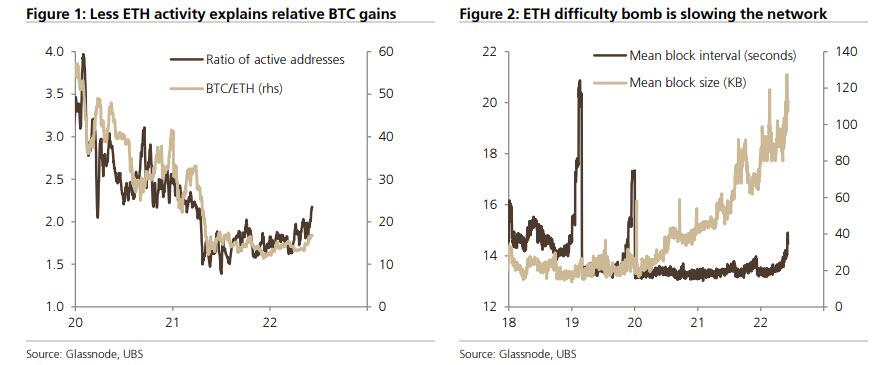
There are several reasons for Its latest relative softening according to UBS, chief among which is a sharper drop-off in activity that is a casualty of weaker transactional demand for Ethereum-based defi and NFTs. which in turn is a function of Fed tightening which is causing asset prices to tumble uniformly (in stocks, bonds and yes, crypto too) as "crash-correlations" approach 1.
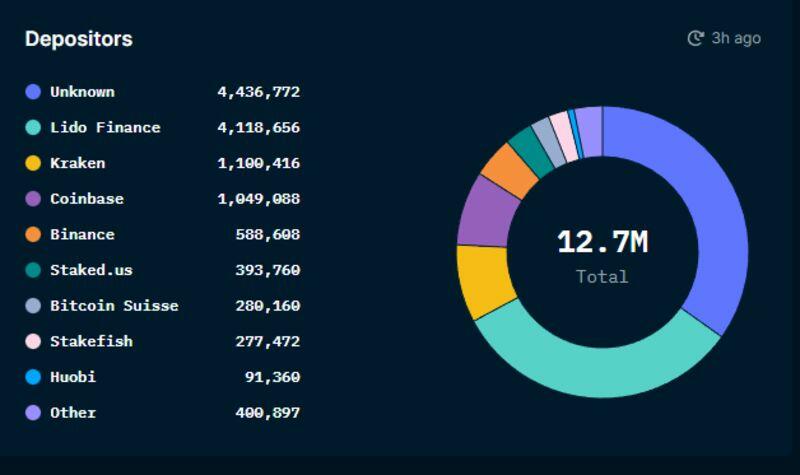
Some also point to concerns about a Terra-like implosion due to misplaced fears that a security attack on staked Ethereum could lead to a "fat tail" outcome ahead of the ETH 2 transition later this year due to 4 million ether deposited at Lido Finance, making the exchange a concentrated holder and threatening a centralized attack on the broader ETH network (Lido developer Vasiliy Shapovalov disagrees).
Additionally, some slowing in the network as the so-called 'difficulty bomb' begins to bite ahead of the late-summer Merge may also be exerting some drag.
Amid this wholesale selloff, bear-market blues, liquidations and outright capitulation have set in among even the most ardent crypto proponents (e.g., here). So much so that some have started to highlight how native technical indicators skew the balance of risks henceforth heavily to the downside.
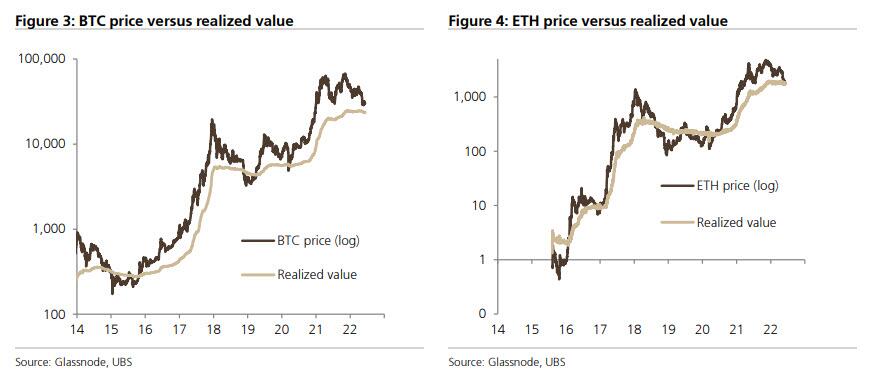
Yet in comparison to prior 'crypto winters,' bitcoin's price has yet to fall below holders' average cost base (23,500), although after today's drop, ether is now below the average cost basis which according to UBS is at 1,750.
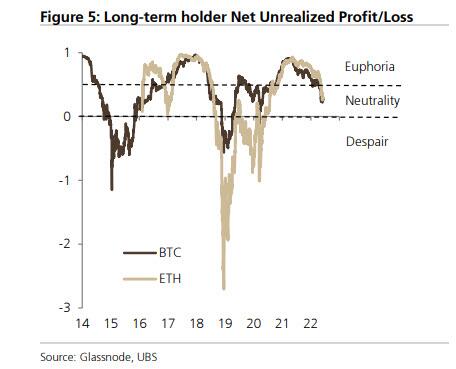
Furthermore, net unrealized profit/ loss metrics highlight specifically how long-term holders have yet to be tested.
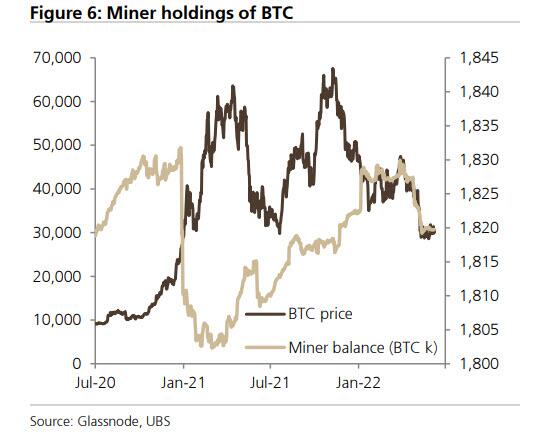
One way UBS suggests this could happen is via miners capitulating to sell down holdings of existing coins: indeed, their sales in early May coincided with the last lurch lower to and through 30k.
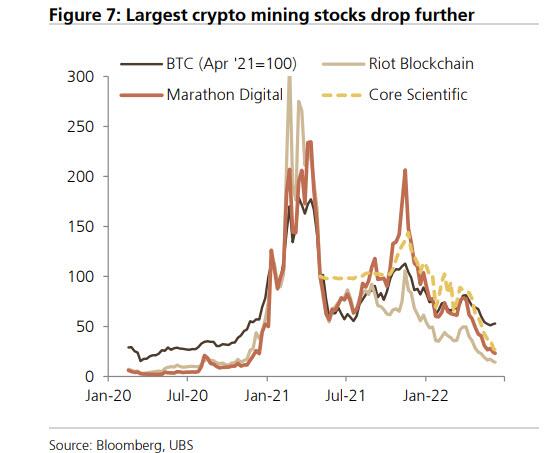
Indeed, miners' businesses remain under significant pressure due to high energy costs and capex commitments, so their stock prices continue to make fresh lows even as the broader market has consolidated or even rebounded somewhat.
Meanwhile, as UBS adds, there has been little positive news to offset investor concerns, and the Swiss bank proceeds to list some of these, starting with stablecoin issuers who have been put on notice by UST's collapse, while officials should feel spurred on to clamp down by Do Kown's plans for Terra2, Justin Sun's launch of the effective copycat USDD, and Tether's expansion onto Tezos. Japan's Diet has passed legislation allowing only banks and other licensed financial institutions to issue yen stablecoins as of next year. New York's Department of Finance likewise formalized guidance mandating full backing via short-dated T-bills or equivalent, segregated accounts and monthly audits by independent US CPAs. And a new UK consultation paper just floated procedures for dealing with failed issuers and makes provisions for systemically important designation
Amongst the familiar fare of hacks, and outages, two additional items stood out in UBS' review of key events. One was the SEC moving to investigate Binance over its 2017 BNB exchange coin listing. The latter's price fell almost 10% in consequence. But the action matters beyond the fact that it involves the largest exchange by volumes and the industry's third largest non-stablecoin. It signals a fresh effort to enforce securities registration that will be applicable to the vast majority of crypto ventures. This comes atop other probes into the company that were already underway. These involve possible trading abuses by corporate insiders, insufficient segregation of the firm's local US subsidiary and concerns that it has been conducting unregulated broker-dealer activities. There is also the issue of whether founder CZ's ownership stakes in market-makers that are active on the platform constitute conflicts of interest.
That said, UBS is quick to caution that none of this is to argue that crypto is sliding into oblivion, quite the contrary - after all Wall Street and Silicon Valley have invested tens of billions in crypto infrastructure and manpower (most did so around the time cryptos peaked),. Yet what it does point to is how the future will look very different. According to UBS' James Malcom, players will have to embrace regulation and collaborate with existing financial service providers; thus Singapore's just-launched Project Guardian, which represents a pilot project for the central bank to explore tokenized bonds and deposits via the establishment of permissioned liquidity pools in collaboration with DBS, JPMorgan and Marketnode. They must also have to compromise even as they seek to disrupt longstanding tradfi practices, per FTX's bold bid to disintermediate derivatives trading by clearing customers' swaps without the involvement of FCMs.
The good news is that, as UBS concludes, those who can last beyond the near-term downward pressure and volatility, the longer-term demand-side outlook looks exceedingly healthy when recast in such terms. Accenture's newly released Future of Asian Wealth Management survey revealed that more than half of its 3,200 respondents already hold digital assets, and nearly three quarters plan to do so by year-end. However, two thirds of the 500 financial advisors surveyed have no plans to offer such services due to regulatory uncertainty and unfamiliarity with the space, which would require specialized research capabilities plus substantial investment in training for relationship managers. Little wonder satisfaction ratings with primary counterparts score rather lowly. It is also not surprising that many allocators end up relying on potentially less reliable online advice in consequence. UBS' Global Family Office Report 2022 finds, by contrast, most of the bank's clients are 'cryptocurious' rather than 'crypto-committed'— wanting to learn about the space rather than invest. It pegged just a quarter of Asian participants as active in the space, though that rises to more than a third in North America. The vast majority of allocations amount to less than 3% of portfolios and are being made to better understand the technology as much as on the expectation of strong, diversified returns at this point.
As for Ethereum's latest tumble, it could certainly fall more amid capitualtory liquidations, now that selling below the average cost basis means cementing losses for retail investors. But when it comes to institutions one can be certain that instead of writing off their investments in the web3 space, most will simply double down, and why not: it is already widely accepted that after the Fed hikes enough to push the economy into recession (or depression) in the next few months, it will then proceed to aggressively cut rates again...
... with the benefit of QE again, and the moment Powell capitulates - which will be some time in late 2022 or early 2023 - is when all the "growth", high-beta assets that have gotten destroyed in the past few months, will erupt to new all time highs in anticipation of the biggest liquidity injection yet, one which is simply mandatory if for no other reason than central banks have to fund and finance the $150 trillion (with a T) spending over the next 30 years (via QE) that is unavoidable if the progressive "climate change" agenda is to pass. And it will - too many politicians and parties have staked their entire existence on it. Finally, none of this accounts for the growing risk that China, and its $54 trillion in bank assets or 150% more than the US...
... will suffer another devaluation, sparking another massive capital exodus using bitcoin and other crypto instruments.

>>> Barron’s Weekend Summary

Barron’s Weekend Summary: An exclusive analysis by Barron’s shows that the profits of gas stations are actually down this year.

Cover Story:
-An exclusive analysis by Barron’s shows that the profits of gas stations are actually down this year. And that holds important implications for Washington, where President Joe Biden and his allies have suggested that drivers are being gouged by gas stations. Democrats in both houses of Congress have introduced price-gouging legislation that would put fuel sellers, both wholesale and retail, under greater scrutiny.

Interview:
Jan van Eck tries to understand the future by drawing on the past. In the summer of 2020, as Covid ravaged communities and disrupted workplaces, the CEO of VanEck, an $80.4B asset manager, decided that the firm’s summer interns needed to take a step into the past and learn some market history. He created and taught a 16-unit course on the history of finance, beginning with one of his favorite historical figures, Alexander Hamilton: “I’m always looking for disruptive, transformative trends or technologies or political developments,” says van Eck. “History can help us identify different scenarios and outcomes.”

Tech Trader:
-Aside from retailers Walmart and Amazon.com, Apple generates more revenue than any other American company. This year, the total should approach $400B. The business generates huge amounts of cash and increasingly returns it to shareholders. But investors have made Apple the country’s most highly valued company largely due to its ability to innovate—to deliver new ideas that can drive revenue even higher.

The Trader:
-Despite the S&P 500SPX’s 18% drop this year, corporations continue to buy back their shares, or announce plans to do so. Most recently, AmerisourceBergen announced a $1.0B buyback plan on June 1, while Broadcom announced a $10B plan on May 26, and Nvidia increased its plan to $15B on May 23. In fact, more than $300B of share repurchases have been announced over the past three months, according to Deutsche Bank data.
-The Federal Reserve wants to fight inflation. But it wants to observe a different measure of inflation: the personal consumption expenditure price index, which is reported by the Bureau of Economic Analysis as part of its monthly personal income and outlays report. That measure of inflation increased 0.24% in April, for a 6.3% year-over-year gain. Excluding food and energy prices, the core PCE index was up 0.34% in April and up 4.9% from a year earlier. PCE is lower than CPI, but it’s still far too hot, and the next reading, due June 30, is unlikely to give an all-clear signal.

Features:
Exxon Mobil is expected to generate about $41B of net income in 2022, up from $23B last year. But Exxon’s profits should trail well behind Apple, Microsoft, Alphabet, and JPMorgan Chase.

With gasoline prices hitting a record $5/gallon and inflation running at more than 8%, energy companies are taking political heat again with some in Washington raising the possibility of a UK-style windfall profits tax.
-The US housing sector is in the midst of the biggest slowdown in over a decade, one economist says. But don’t expect prices to fall back down to earth just yet. “The U.S. housing market is at the beginning stages of the most significant contraction in activity since 2006,’” Len Kiefer, deputy chief economist at Freddie Mac, tweeted. “It hasn’t shown up in many data series yet, but mortgage applications are pointing to a large decline over summer,” he explained.

European Trader:
Linde is one of three major industrial-gas makers, alongside Air Products & Chemicals and Air Liquide. The relative scarcity of such providers ensures that Linde is able to pass on higher raw materials costs, and the diversity of its projects makes it less susceptible to swings in the economic outlook. What’s more, despite dealing in chemicals and carbon-emitting natural resources, Linde scores highly in the MSCI environmental, social, and governance rating. That’s due to the kinds of projects Linde works on—carbon capture and storage, for example. The company also has ambitious plans to reduce the greenhouse gases it emits and to double its purchase of renewable energy by 2028.

Emerging Markets:
-In Mexico the 68-year-old President Andres Manuel Lopez Obrador, a favorite to win a second presidential term in 2024, has been surprisingly successful in combining popular social largess with a tight fiscal belt, a mixture he labels “republican austerity.” Half of Mexico’s 130M citizens have benefited from either cash transfers or minimum wage increases since AMLO took office in 2018, Wood estimates. The president found extra cash by collecting back taxes and cutting state salaries, among other means. He refrained from stimulus to counter the effects of Covid.

Commodities:
-Risk-tolerant investors should consider selling short November-dated random- length lumber futures contracts on the CME futures exchange. Alternatively, they might short stocks of lumber companies such as those held in the iShares Global Timber & Forestry ETF. Lumber prices have been on a roller-coaster over the past couple of years. In May 2021, lumber futures reached an all-time high price of $1,711, almost six-times higher than the $300 of April 2020, according to TradingEconomics.com. Prices have subdued considerably since that peak as lumber mills started to operate at full capacity and the housing market slowed.

Streetwise:
-This week Jack Hough looks at the problems of people trying to lose weight and the products they can take to facilitate their related dieting efforts: “There are powerful new medicines for weight loss. I’ll pass, for reasons I’ll explain, but Wall Street is making colossal sales projections for two key pharma players. The first is Denmark’s Novo Nordisk, the world’s top maker of insulin. For more than a decade, it has sold drugs thathelp manage blood sugar levels, with the happy side effect of weight loss, so it has won approvals for both Type 2 diabetes and obesity. The drugs are called GLP-1 agonists, meaning they mimic a certain hormone that both stimulates insulin secretion and causes a feeling of fullness.

CB : Here’s Which VC-Backed Companies Are Going Public Via SPAC In 2022 (So Far)

Here’s Which VC-Backed Companies Are Going Public Via SPAC In 2022 (So Far)

Last year was a banner year for special-purpose acquisition companies, but this year hasn’t been nearly as active for the SPAC market.

The public markets have been rocky since the beginning of the year, and far fewer companies have made public market debuts. And many of the SPACs that went public last year ended the year trading down. Still, as of mid-June, there are around 600 SPACs hunting for targets–and facing a time crunch–and a handful of announcements of SPAC mergers have been made so far this year.

To keep track, we’ve scoured news reports and press releases to compile a list of VC-backed companies that have announced their plans to go public through a SPAC. Separately, we’ve included VC-backed companies that completed their SPAC mergers this year.


SPAC mergers of VC-backed companies announced in 2022
  • Date announced: Jan. 17, 2022
  • Acquirer: GFJ ESG Acquisition I SE
  • Valuation: 450 million euros (roughly $514.2 million)
  • What it does: Smart thermostat maker
  • Some investors: Shortcut Ventures, Inven Capital
  • Date announced: Jan. 20, 2022
  • Acquirer: Silver Spike Acquisition Corp. II
  • Valuation: $446 million
  • What it does: Biotech company focused on psychedelics for therapy
  • Some investors: Palo Santo Fund
  • Date announced: Jan. 25, 2022
  • Acquirer: Sports Ventures Acquisition Corp.
  • Valuation: $1.7 billion
  • What it does: Visual effects for movies and TV
  • Some investors: Arbor Ventures, Novator Partners
  • Date announced: Jan. 26, 2022
  • Acquirer: Social Capital Suvretta Holdings I
  • Valuation: $1 billion
  • What it does: Cognitive therapeutics and diagnostics
  • Some investors: DG Ventures, Silicon Valley Bank
  • Date announced: Jan. 27, 2022
  • Acquirer: Breeze Holdings
  • Valuation: $1.4 billion
  • What it does: Deploys, moves and removes satellites
  • Some investors: Seraphim Capital, Green Arrow Capital
  • Date announced: Feb. 1, 2022
  • Acquirer: AngelPond
  • What it does: Open-source database for cloud management
  • Valuation: $672 million
  • Some investors: Intel Capital, Alibaba
  • Date announced: Feb. 8, 2022
  • Acquirer: DPCM Capital
  • What it does: Quantum computing
  • Valuation: $1.6 billion
  • Some investors: BDC Venture Capital, Goldman Sachs
  • Date announced: Feb. 14, 2022
  • Acquirer: Software Acquisition Group Inc III
  • What it does: E-commerce services
  • Valuation: $646 million
  • Date announced: March 3, 2022
  • Acquirer: Provident Acquisition Corp.
  • What it does: Software for beauty and cosmetics companies
  • Valuation: $1 billion
  • Date announced: March 8, 2022
  • Acquirer: ACMI Acquisition Corp. II
  • What it does: Carbon recycling technology
  • Valuation: $1.8 billion
  • Date announced: March 8, 2022
  • Acquirer: Endurance Acquisition Corp.
  • What it does: Satellite communications company
  • Valuation: $813 million
  • Date announced: April 4, 2022
  • Acquirer: Riverview Acquisition Corp.
  • What it does: Private label coffee company
  • Valuation: $1.1 billion
  • Date announced: April 19, 2022
  • Acquirer: East Stone Acquisition Corporation
  • What it does: Electric vehicle development
  • Valuation: $2.5 billion
  • Date announced: April 18, 2022
  • Acquirer: I2PO
  • What it does: Music streaming company
  • Valuation: $1.1 billion
  • Date announced: May 2, 2022
  • Acquirer: Mountain Crest Acquisition Corp. IV
  • What it does: Electric vehicle manufacturing
  • Valuation: $1.7 billion
  • Date announced: May 9, 2022
  • Acquirer: Tiga Acquisition Corp.
  • What it does: Dating app for the LGBTQ+ community
  • Valuation: $2.1 billion
  • Date announced: May 10, 2022
  • Acquirer: Lakeshore Acquisition I Corp.
  • What it does: Sleep apnea device maker
  • Valuation: $168 million
  • Date announced: May 12, 2022
  • Acquirer: Kensington Capital Acquisition Corp. IV
  • What it does: Lithium battery tech
  • Valuation: $1.3 billion
  • Date announced: May 16, 2022
  • Acquirer: Chardan NexTech Acquisition 2 Corp.
  • What it does: Lithium battery manufacturing
  • Valuation: $500 million
  • Date announced: May 17 2022
  • Acquirer: EdtechX Holdings Acquisition Corp. II
  • What it does: VR-enabled learning
  • Valuation: $195 million
  • Date announced: May 18, 2022
  • Acquirer: Tuscan Holdings Corp. II
  • What it does: Private plane operations
  • Valuation: $1.42 billion
  • Date announced: May 26, 2022
  • Acquirer: Cova Acquisition Corp.
  • What it does: Smart car technology
  • Valuation: $3.8 billion
  • Date announced: May 31, 2022
  • Acquirer: Gesher I Acquisition Corp.
  • What it does: Freight booking platform
  • Valuation: $435 million
  • Date announced: June 1, 2022
  • Acquirer: Americas Technology Acquisition Corp.
  • What it does: Mass mobility company
  • Valuation: $208 million

Completed SPAC mergers of VC-backed companies in 2022
Data according to SPACTrack
  • Date Completed: Jan. 5, 2022
  • Acquirer: VPC Impact Acquisition Holdings III, Inc
  • What it does: Banking app
  • Date Completed: Jan. 11, 2022
  • Acquirer: Petra Acquisition Inc.
  • What it does: Immunologic therapeutics and diagnostics
  • Date Completed: Jan. 13, 2022
  • Acquirer: Decarbonation Plus Acquisition Corporation II
  • What it does: EV charging
  • Date Completed: Jan. 20, 2022
  • Acquirer: Power and Digital Infrastructure Acquisition Corp.
  • What it does: Transaction processing and app development
  • Date Completed: Jan. 25, 2022
  • Acquirer: CF Acquisition Corp. V
  • What it does: Satellite data company
  • Date Completed: Feb. 2, 2022
  • Acquirer: Environmental Impact Acquisition Corp.
  • What it does: Biotech company for RNA research for human and planet health
  • Date Completed: Feb. 2, 2022
  • Acquirer: Ivanhoe Capital Acquisition Corp.
  • What it does: EV battery maker
  • Date Completed: Feb. 4, 2022
  • Acquirer: ECP Environmental Growth Opportunities Corp.
  • What it does: Manufacturing solutions
  • Date Completed: Feb. 4, 2022
  • Acquirer: Merida Merger Corp. I
  • What it does: Cannabis marketplace
  • Date Completed: Feb. 10, 2022
  • Acquirer: Growth Capital Acquisition Corp.
  • What it does: Lidar technology
  • Date Completed: Feb. 15, 2022
  • Acquirer: Thayer Ventures
  • What it does: Luxury travel service
  • Date Completed: March 2, 2022
  • Acquirer: Supernova Partners Acquisition Co. II
  • What it does: Quantum computing
  • Date Completed: March 18, 2022
  • Acquirer: Bridgetown 2 Holdings Ltd.
  • What it does: Real estate website for buyers and sellers
  • Date Completed: March 21, 2022
  • Acquirer: Motive Capital Corp.
  • What it does: Private securities marketplace
  • Date Completed: March 25, 2022
  • Acquirer: Tailwind Two Acquisition Corp.
  • What it does: Satellite provider
  • Date Completed: March 29, 2022
  • Acquirer: FirstMark Horizon Acquisition Corp.
  • What it does: Internet service company
  • Date Completed: March 31, 2022
  • Acquirer: Queen’s Gambit Growth Capital
  • What it does: App-based transportation booking company
  • Date Completed: April 4, 2022
  • Acquirer: Poema Global Holdings Corp.
  • What it does: Electric scooters
  • Date Completed: April 27, 2022
  • Acquirer: Archimedes Tech SPAC Partners
  • What it does: Voice-enabled artificial intelligence technology
  • Date Completed: May 2, 2022
  • Acquirer: Spring Valley Acquisition Corp.
  • What it does: Energy technology
  • Date Completed: May 18, 2022
  • Acquirer: Artisan Acquisition Corp.
  • What it does: Genetic and diagnostic health testing
  • Date Completed: June 9, 2022
  • Acquirer: Dynamics Special Purpose Corp.
  • What it does: Cancer therapy

CrunchBase : The Week’s 10 Biggest Funding Rounds: Biotech’s Big Week; Resilienc

The Week’s 10 Biggest Funding Rounds: Biotech’s Big Week; Resilience Takes Top Spot With $625M Round

Drug developers and health care tech had no problem attracting investors’ interest this week, as biotech startups took four of the top 10 rounds. In addition, another company in the health care space made the list. However, in general, rounds continue to trend lower, as there was only one raise more than a quarter-billion dollars this week in the U.S.

1. National Resilience, $625M, biotech: Raising rounds of more than a half-billion dollars can make a company pretty resilient. San Diego-based National Resilience has now raised two such rounds in about 10 months. The company, an end-to-end biopharmaceutical manufacturing and development firm, announced this week it raised a $625 million Series D after closing a previously unannounced $600 million Series C in August. Resilience develops therapeutics in its 10 facilities across North America. The company has more than 1 million square feet of manufacturing space and over 1,600 employees. Although it did not announce who specifically participated in the round, it said it included “venture capital funds, public mutual funds, pension funds, biopharma companies, sovereign wealth funds and private family offices, among others.” Resilience has now raised more than $2 billion in equity since being founded in 2020, according to the company.

2. Knock, $220M, fintech: The housing market is hot and homebuyers need to move fast. Knock’s home-buying app lets people do just that. It lets existing homeowners access the cash they need before they even sell their current home. The New York-based company closed a $220 million round led by the Foundry Group. While some expect to see the housing market weaken as interest rates rise, the Opendoor competitor seems to be betting that the current market stays strong. Founded in 2015, Knock has now raised a total of $900 million of debt and equity, according to the company.

3. Branch, $147M, insurance: Columbus, Ohio-based Branch became one of the latest unicorns to join the growing herd this week. The insurtech company locked up a $147 million Series C led by Weatherford Capital that values it at $1.05 billion. Branch allows companies to bundle home and auto insurance in a single transaction, using data and automation to make the monotonous process of buying insurance easier. The company claims it has helped members save an annual average of $548. Founded in 2019, the company has now raised nearly $230 million, according to Crunchbase data.

4. Aledade, $123M, health care: Trying to help doctors provide better care is a big undertaking, and now Bethesda, Maryland-based Aledade has more money to try to do it. The company raised a $123 million Series E led by OMERS Growth Equity. Fidelity Management & Research Co. and other current investors also participated. The company did not release a valuation, but Business Insider reported it as $3.1 billion. Aledade, which realized more than $300 million in revenue last year, offers a platform to help doctors create and run accountable care organizations, providing coordinated care among doctors. Founded in 2014, the company has raised nearly $418 million, according to Crunchbase.

5. Mineralys Therapeutics, $118M, biotech: As we said earlier, biotech was big this week. Philadelphia-based clinical-stage biopharmaceutical company Mineralys Therapeutics raised a $118 million Series B led by RA Capital Management and Andera Partners. The company is developing new therapies for uncontrolled hypertension. Founded in 2020, the company has raised a total of $162 million, according to Crunchbase data.

6. Vanta, $110M, security: San Francisco-based security monitoring platform Vanta closed a $110 million Series B at a $1.6 billion valuation led by Craft Ventures. Founded in 2017, the company has raised $163 million, according to Crunchbase.

7. Immuta, $100M, cybersecurity: Boston-based data security firm Immuta secured a $100 million Series E led by NightDragon. Founded in 2015, the company has raised $267 million to date.

8. Shield AI, $90M, artificial intelligence: San Diego-based cybersecurity provider Shield AI, which develops AI pilots for the defense industry, raised $90 million in equity and $75 million in debt as part of a Series E led by Snowpoint Ventures valuing the company at $2.3 billion. Founded in 2015, the company has raised more than $500 million, according to Crunchbase.

9. Owkin, $80M, biotech: New York-based AI precision-medicine company Owkin raised $80 million from Bristol Myers Squibb, Business Insider reported. Founded in 2016, the company has now raised more than $334 million, according to Crunchbase.

10. Code Biotherapeutics, $75M, biotech: Hatfield, Pennsylvania-based biotechnology firm Code Biotherapeutics closed a $75 million Series A led by Northpond Ventures. Founded in 2020, the gene therapy company has raised a total of $85 million, according to Crunchbase.

Big global deals
Three of the five biggest rounds this week happened outside the U.S., including one deal across the pond worth more than $1 billion.

  • London-based software consultancy and developer The Access Group closed a round worth more than $1.2 billion from existing shareholders Hg and TA Associates.
  • London-based edtech platform Multiverse raised a $220 million Series D.
  • Singapore-based software developer Envision Digital locked up a $210 million Series A.