- Uniper (UN01 TH) +9.1%
- Watch Utilities, Industrials as Nord Stream Resumes Flows (1)
- ASMI (AVS TH) +3.8%
- ASM International Update Shows ‘Blowout’ Orders: Jefferies
- Nokia (NOA3 TH) +2.6%
- Nokia 2Q Profit Beats Estimates in Growing Market for 5G Gear
- Rio Tinto (RIO1 TH) +2%
- Recession Dread, High Gas Prices a Poor Recipe for EU Materials
- Thyssenkrupp (TKA TH) +1.7%
- Covestro (1COV TH) +1.4%
- Adyen (1N8 TH) +1.4%
- ASML (ASME TH) +1.4%
- China’s Top Chipmaker Makes Big Tech Advances Despite US Curbs
- RWE (RWE TH) +1.4%
- Fortum (FOT TH) +1.3%
- Essity (ESWB TH) -0.6%
- Essity 2Q Adjusted Operating Profit Misses Estimates
- BNP Paribas (BNP TH) -0.7%
- Lufthansa (LHA TH) -0.7%
- Kering (PPX TH) -0.7%
- Kering Due Other Brands’ Strength, Some Gucci Pickup: 1H Preview
- Generali (ASG TH) -1.2%
- Stellantis (8TI TH) -1.5%
- SAP (SAP TH) -1.9%
- SAP Cuts 2022 Operating Profit Outlook as Licenses Revenue Falls
- Intesa Sanpaolo (IES TH) -2.4%
- Watch Italian Stocks as Draghi’s Government on Brink of Collapse
- BE Semiconductor (BSI TH) -2.5%
- BE Semiconductor 2Q Gross Margin Beats Estimates
- UniCredit (CRIN TH) -3.3%
- Watch Italian Stocks as Draghi’s Government on Brink of Collapse
DAX:
- RWE (RWE TH) +1.9%
- Watch Utilities, Industrials as Nord Stream Resumes Flows (1)
- Qiagen (QIA TH) +1.8%
- Daimler Truck (DTG TH) +1.5%
- HeidelbergCement (HEI TH) +1.1%
- Covestro (1COV TH) +1.1%
- SAP (SAP TH) -1.8%
- SAP Cuts 2022 Operating Profit Outlook as Licenses Revenue Falls
MDAX:
- Uniper (UN01 TH) +11%
- Watch Utilities, Industrials as Nord Stream Resumes Flows (1)
- Thyssenkrupp (TKA TH) +2.3%
- Jungheinrich (JUN3 TH) +1.4%
- Fraport (FRA TH) +1.3%
- Aroundtown (AT1 TH) +1.2%
- Delivery Hero (DHER TH) -0.6%
- Lufthansa (LHA TH) -0.6%
SDAX:
- Salzgitter (SZG TH) +1.8%
- DWS (DWS TH) +1.6%
- DWS Raised to Outperform at KBW; PT 41 euros
- Heidelberger Druck (HDD TH) +1%
- AUTO1 (AG1 TH) +0.9%
- Schaeffler (SHA TH) -0.7%
- VERBIO Vereinigte (VBK TH) -0.9%
Asian stocks slid with US futures Thursday as investors weighed signals from the latest corporate earnings and geopolitical risks in Europe. An Asian stock gauge is on track to end a three-day winning streak, dragged down by Hong Kong. Futures retreated in the US and Europe, where Italy’s government looked set to collapse. The S&P 500 posted its first back-to-back gain in almost two weeks, while the Nasdaq 100 outperformed.
The euro gained ahead of a European Central Bank meeting where it is expected to hike for the first time in more than a decade, almost certainly raising rates by 25 basis points. It will also unveil its new crisis management tool. The dollar edged lower. The yen was under pressure after the Bank of Japan maintained its policy rate and lowered its economic growth forecast for this year. Treasury yields slipped. Gold was near an 11-month low. Bitcoin dropped below $23,000. Tesla Inc. disclosed that it sold about 75% of holdings of the cryptocurrency during the second quarter. Risk sentiment remains fragile as investors debate whether equities have reached a trough after this year’s selloff amid the war in Ukraine, a slowdown in China and the prospect of a US recession. Investors are also assessing earnings to gauge how companies are managing amid the highest inflation in generations and escalating borrowing costs. US President Joe Biden said he expects to speak to Chinese leader Xi Jinping “within the next 10 days” as Washington considers lifting some tariffs on Chinese imports. Oil was back below $100 a barrel as growing stockpiles of crude and gasoline tempered fears of a tight market. US After Hours TSLA +0.7% flat on earnings; AA +6.7%, CSX +3.9%, LVS +2.3% higher on earnings; SMCI +24% jumps on bullish guidance; UAL -7.1% falls on earnings; CCL -9.5% falls on $1 bln stock offering
Nikkei +0,30% Hang Seng -0,81% CSI -0,57% Shanghai -0,47% Shenzen -0,13%
Eur$ 1,0217 CNY 6,7617 CNH 6,7667 JPY 138,21 GBP 1,1988 CHF 0,9703 RUB 54,8667 TRY 17,5817 WTI$ 98,89 -1% Gold 1,692,02 -2,3% BTC 22,843 -1,8% ETH 1,485-2,5%
S&P +0,18% Nasdaq +0,09%% EuroStoxx +0,22% FTSE +0,17% Dax +0,43% SMI +0,34%
Macro :
- China’s Credit Market Rocked by More Debt Delays, Plunging Bonds
- Italy Coalition on Cusp of Collapse as Parties Abandon Draghi
- Putin Signals Gas Pipeline Will Restart as Clock Ticks Down
- ByteDance Valuation Drops Below $300 Billion in Private Deals
- German Gas Orders Signal Nord Stream Flows Capped at 30%
Keep an eye on :
- ABBN SW : ABB 2Q Operating Ebita Beats Estimates
- ABBN SW : ABB to Spin Off, List Accelleron Turbocharging Business
- AIR FP : Dassault Aviation CEO Says Fighter Jet With Airbus Under Threat
- ANTIN FP Antin Assets Under Management EU22.4B
- MT NA : *ALCOA 2Q ADJ EBITDA $913M, EST. $908.7M -->+5%
- ARYN SW : Aryzta to Repurchase EU50M of Euro Hybrid Bond
- ASM NA : ASMI 2Q Operating Profit Misses Estimates
- BAS1V FH : BasWare 2Q Net Sales Meets Estimates
- BG AV : Bawag 2Q Pretax Profit Beats Estimates
- BESI NA : BE Semiconductor 2Q Gross Margin Beats Estimates
- BA US : *BOEING PREPARES TO INCREASE 787 PRODUCTION, DJ SAYS
- BOL SS : Boliden 2Q Adjusted Operating Profit Beats Estimates
- BOSN SW Bossard 1H Ebit Beats Estimates
- BYS SW : Bystronic 1H Net Revenue Meets Estimates
- CCL LN : Carnival Drags on Peers After $1 Billion Stock Offering
- CMBN SW : Cembra Money Bank 1H Net Income Beats Estimates
- AM FP : Dassault Aviation 1H Adjusted Net Sales Beats Estimates
- AM FP : Dassault Aviation CEO Says Fighter Jet With Airbus Under Threat
- DPH LN : Dechra Pharma to Raise About £180m at GBP34.3/Share
- ECV GY : Encavis EIF II Invests >EU1b in Renewable Energy Power Plants
- GET FP : Getlink 1H Revenue Beats Estimates
- GIVN SW : Givaudan 1H Ebitda Beats Estimates
- GOG LN : Kelsian Soars Most Since 2013; Says Won’t Make Go-Ahead Bid
- ITP FP : Interparfums Raises FY Sales Target to EU630M-EU640M
- IPH FP : Innate Pharma Says Sanofi Picks Its Drug Candidate for Dev.
- INTRUM SS : Intrum 2Q Revenue Beats Estimates
- IPS FP : Ipsos 1H Revenue Matches Estimates
- JD/ LN : JD Sports Fashion In Talks to Sell Footasylum to Aurelius: Sky
- LEON SW : Leonteq 1H Pretax Profit CHF145.8M
- MC FP : Capri Gains After Revealing $8b Revenue Target at Investor Da
- MNG LN : Saudi Prince Alwaleed’s Kingdom Holding Invests 1b Riyals in M&G
- NOKIA FH : Nokia 2Q Adjusted Operating Profit Beats Estimates
- NOS PL : NOS 2Q Revenue Beats Estimates
- ORP FP : Orpea 2Q Organic Revenue +7.7%
_ PUB FP : Publicis Sees FY Operating Margin 17.5% to 18%, Saw About 17.5%
- ROG SW : Roche Appoints Thomas Schinecker as New CEO
- ROG SW : Roche 1H Core EPS Beats Estimates
- SAP GY :SAP Cuts 2022 Operating Profit Outlook as Licenses Revenue Falls, SAP Announces up to EU500M Share Repurchase Program
- SK FP : SEB 1H Sales Misses Estimates
- DIM FP : Sartorius Stedim Biotech 1H Revenue Misses Estimates, Sartorius Maintains FY Adjusted Ebitda Margin Forecast
- SHEL LN : *SHELL PUTTING US GULF OF MEXICO ASSETS UP FOR SALE: RTRS
- SINCH SS : Sinch Says CEO Oscar Werner Steps Down
- TE FP : Technip Energies Gets EU50m-EU250m Contract From Neste
- HO FP : Thales Boosts FY Sales Forecast
- THULE SS : Thule 2Q Net Sales Misses Estimates
- VLA FP : EU Amends Valneva Covid Vaccine Deal; Cuts Order to 1.25M Doses
- VTWR GY : Vantage Towers 1Q Rev. Ex Pass Through EU262.1M Vs. EU245.8M Y/y
>>> Up
* Ahold Delhaize Raised to Buy at HSBC; PT 29 euros
* Axfood Raised to Hold at SEB Equities
* Catena Raised to Overweight at Barclays; PT 490 kronor
* Stendorren Fastigheter Raised to Buy at Handelsbanken
* Telia Raised to Accumulate at Inderes; PT 41 kronor
>>> Down
* Alma Media Cut to Hold at SEB Equities; PT 11 euros
* Castellum Cut to Underweight at Barclays; PT 135 kronor
* Entra Cut to Underweight at Barclays; PT 115 kroner
* GSK ADRs Cut to Hold at Spin-Off Research; PT $45
* Harvia Cut to Accumulate at Inderes; PT 27 euros
* HelloFresh Cut to Hold at Kepler Cheuvreux; PT 33 euros
* Jupiter Cut to Underperform at KBW; PT 121 pence
* Midwich Cut to Hold at HSBC; PT 650 pence
* Mondi Cut to Equal-Weight at ABSA Securities; PT 1,662.29 pence
>>> Initiation
* Euronav Rated New Hold at Jefferies; PT $14
* FLEX LNG Rated New Hold at Jefferies; PT $26
* Golden Ocean Rated New Buy at Jefferies; PT $14
* GSK Resumed Neutral at Citi; PT 1,975 pence
* Haleon Rated New Buy at Citi; PT 360 pence
* Swatch Rated New Hold at Jefferies; PT 260 Swiss francs
>>> Call
* ASM International Update Shows ‘Blowout’ Orders: Jefferies
* Dassault Aviation 1H is a ‘Quality’ Beat, Morgan Stanley Says
* GSK Neutral at Citi as Vaccines Strong, Oncology ‘Underwhelming’
* Jefferies Initiates on Marine Shipping, Scorpio Among Top Picks
* Publicis Sees No Negative Impact From Inflation, Raises Guidance
* Swatch Rated New Hold at Jefferies, Cautious Over Weaker Growth
ECB Preview: First Rate Hike In 11 Years, And Another Major Policy Mistake
Submitted by Newsquawk
Summary:
- ECB policy announcement due Thursday 21st July; rate decision at 13:15BST/08:15EDT, press conference from 13:45BST/08:45EDT
- The ECB is set to finally pull the trigger on rates; discussion will be over 25bps or 50bps
- Policymakers are expected to unveil details of the anti-fragmentation tool
OVERVIEW: After standing pat on rates in June, the ECB is finally set to pull the trigger and commence its rate-hiking cycle for the first time since June 2011 (when it sparked a sovereign debt crisis and cut rates three months later). This particular rate hike will be an even bigger policy error as it comes just as Europe's economy slams the breaks into a big recession and ahead of what will be a freezing winter.
Up until this week, analysts had been near unanimous in their view that the hike would be by 25bps given the explicit nature of the June statement. However, recent reporting has suggested that policymakers will now discuss the possibility of a 50bps move. Accordingly, markets now assign a 60% chance to such a move vs. around 33% at the start of the week. If policymakers opt for a 25bps move this time around, the statement will likely reaffirm the pledge to raise rates by a larger increment in September, depending on the medium-term inflation outlook.
The July meeting will also likely see the Governing Council present details of its new anti-fragmentation tool - Transmission Protection Mechanism (TPM). It remains to be seen how much in the way of details the ECB will provide on its new tool as policymakers might prefer to use a "whatever it takes" approach rather than tempt bond-sellers with a specific number. Furthermore, the issue of conditionality will also be key when assessing the efficacy of such a tool, particularly in lieu of recent events in Italy whereby domestic politics has seen the IT/GE spread widen; something which Northern nations will likely impress is not as a result of ECB monetary policy.
PRIOR MEETING: As expected, the ECB opted to stand pat on rates whilst announcing its intention to tighten by 25bps at the July meeting. Beyond July, policymakers stated they will consider larger increments if the medium-term inflation outlook persists or deteriorates. On the balance sheet, as expected, the Governing Council announced its decision to end net asset purchases under the APP as of July 1st. Note, the policy statement offered no fresh guidance on how it could deal with the issue of market fragmentation as it commences its rate hiking cycle. The 2022 inflation outlook was upgraded to 6.8% from 5.1%, with 2024 inflation seen above target at 2.1% vs. prev. view of 1.9%. At the accompanying press conference, President Lagarde was pressed further on how the Bank intends to deal with fragmentation, to which she noted that it can utilise existing tools, such as reinvestments from PEPP and, if necessary, deploy new instruments. Later in the press conference, Lagarde noted that there is no specific level of yield spreads that would be a trigger for an anti-fragmentation policy. From a more medium-term perspective, the President was questioned about where the Governing Council judges the neutral rate to be, however, she remarked that this issue was deliberately not discussed.
RECENT ECONOMIC DEVELOPMENTS: June's Eurozone inflation metrics saw headline Y/Y CPI rise to 8.6% from 8.1%, whilst the core (ex-food and energy) reading ticked higher to 4.6% from 4.4%. In terms of market-based expectations, the Eurozone 5y5y inflation rate has fallen to around 2.09% vs. 2.26% seen at the prior meeting. On the growth front, Q2 GDP metrics will not be released until 29th July. However, in terms of timelier survey data from S&P Global, June's PMI figures saw the EZ-wide composite metric slip to 52 from 54.8 with the report noting that the data suggests "that risks have increasingly tilted towards the economy slipping into a downturn at the same time that inflationary pressures moderate, but remain elevated". On the employment front, the unemployment rate continues to decline with the May print easing to 6.6% from 6.7%. Also of note for the Eurozone economy has been the performance of the EUR with EUR/USD falling from a 1.13 handle at the start of the year to just below parity (briefly) last week; a decline of roughly 12.5% peak-to-trough. From a broader perspective, the ECB's nominal effective exchange rate (NEER) has fallen around 3.9%.
RECENT COMMUNICATIONS: Since the prior meeting, President Lagarde said she expects the ECB to raise the key ECB interest rates again in September after a 25bp hike in July, adding that the calibration of the September hike will depend on the updated medium-term inflation outlook. On fragmentation, Reuters sources suggested that the President told EZ Finance Ministers that the goal of anti-fragmentation is not to close spreads. but to normalise spreads. In terms of the hawk-dove divide at the Bank, Germany's Nagel warned the ECB against lowering borrowing costs for the Eurozone's southern members, stating that the focus should be on fighting off inflation, which may require more rate hikes than now projected. Nagel is of the view that the anti-fragmentation tool should only be activated in exceptional circumstances with narrowly defined conditions and duration. Latvia's Kazaks has suggested that a 25bps hike in July and 50bps in September is the base case, but it is worth looking at 50bps in July. At the other end of the spectrum, Italy's Panetta has continued to stress that normalisation should be gradual, adding that the surge in inflation does not reflect excess demand in the Eurozone. Furthermore, Panetta notes that the anti-fragmentation tool is needed for the ECB to hit its mandate. Elsewhere, Greece's Stournaras has stated that he sees no signs of second-round effects in the Eurozone. On the FX rate, France's Villeroy has stated that the ECB watches the EUR closely as it is important for prices, adding that it is not the EUR that is weak, but the USD that is strong. These comments (13th July) were later followed up by a statement from an ECB spokesperson noting that "we are always attentive to the impact of the FX rate on inflation, with our mandate for price stability. ECB does not target a particular exchange rate".
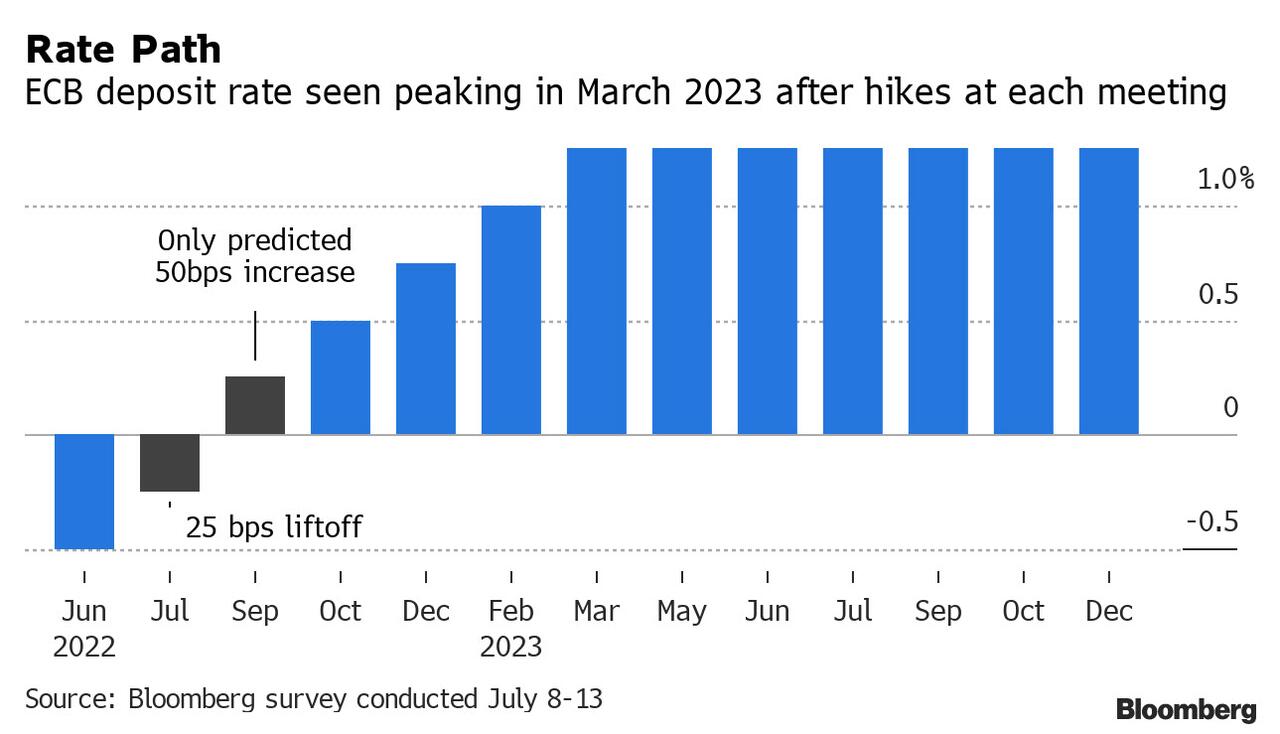
RATES: Analysts surveyed by Reuters (8th-15th July) look for the ECB to hike the deposit, main refi and marginal lending rates by 25bps to -0.25%, 0.25% and 0.5% respectively. In terms of the breakdown of analyst views for the deposit rate, all 63 analysts expect the Bank to move on rates with 62/63 looking for a 25bps hike and just one looking for a larger hike of 50bps. This view appeared to be relatively well cemented given how explicit ECB comms had been over the possibility of a 25bps move for the upcoming meeting. However, source reporting by Reuters and Bloomberg has revealed that policymakers are now set to debate the possibility of a 25bps or 50bps hike at the upcoming meeting. In terms of market pricing, at the start of the week 33bps of tightening was factored in, which implied that a 25bps hike was fully priced with a 32% chance of a 50bps hike. Following the aforementioned reporting, this has now risen to a 60% chance. Reporting has suggested that the Governing Council could be granted cover to shift away from its prior guidance given comments by President Lagarde on June 28th that there are "clearly conditions in which gradualism would not be appropriate". That said, it remains to be seen whether or not there is sufficient support for a 50bps move on the Governing Council. Some desks suggest that a 50bps move would make sense given that the Bank is already clearly behind other major central banks in their effort to tame inflation and a 25bps hike seems relatively minor compared to the magnitude of some of the ECB's peers. ING believes there is a small chance of a 50bps move this week given that some members already wanted to commence the hiking cycle in June. Furthermore, by the time of the September meeting, policymakers could be "looking a recession into the eyes", which would be an unconventional time to increase the pace of hikes. Also, the recent weakening of the EUR could bolster the case for a 50bps move, albeit Rabobank is of the view that it is doubtful whether such a move would provide much in the way of support for the EUR at this current juncture. Rabobank also makes the point that if the ECB does unveil its ‘Transmission Protection Mechanism’ this month, it could move by 50bps to get the hawks on board. However, Rabo believes that the ECB would prefer to wait and see how its new instrument is received by markets before moving by larger increments. Looking beyond the upcoming meeting, a 50bps hike is fully priced in for September with the year-end deposit rate seen rising to 1% which would imply 75bps of tightening beyond September.
BALANCE SHEET: After offering no fresh guidance at the June meeting on how it could deal with the issue of market fragmentation as it commences its rate hiking cycle, the ECB was forced to carry out an ad-hoc meeting to address the matter. At which, policymakers decided to flexibly reinvest redemptions from PEPP whilst mandating staff to accelerate the completion of an anti-fragmentation tool. In the aftermath of the meeting, reporting via Reuters suggested that the bond scheme would come with loose conditions and aimed at bringing yield spreads back into line with fundamentals. It was also later reported that officials were unsure whether or not the size or duration of such a bond-buying scheme would be announced. One argument for announcing the size would be that it could help show the ECB's commitment to avoiding fragmentation, whilst not being seen as giving governments a blank cheque. That said, if the number underwhelmed, it could place pressure on bond markets. Note, any purchases under such a tool would likely be sterilised whereby the scheme could be paired with auctions aimed at draining cash from the banking system. On July 7th it was reported that the new tool would be named the Transmission Protection Mechanism (TPM), however, a lot of
work was still yet to be done and it was uncertain if it would arrive in time for July. More recently (19th July) reporting from Reuters has suggested that conditionality for the tool could "include the targets set by the Commission for securing money from the European Union Recovery and Resilience Facility as well as the Stability and Growth Pact", whilst some wanted involvement from the ESM, but this option was now likely discarded. Note, it remains to be seen whether or not the tool will be announced at the upcoming meeting with President Lagarde reportedly "redoubling efforts to get a deal done". Should the tool be unveiled at the upcoming meeting, analysts at ING highlight that the main issues would be "how to define a ‘neutral’ or ‘economically justified’ spread, the size of such a tool and the degree of conditionality". However, a mere "whatever it takes" pledge could present optics that "such a commitment when starting a rate hiking cycle is like hitting the brakes and the accelerator simultaneously". From a rates perspective, it is likely that hawks would try and negotiate a more aggressive hiking cycle if the conditionality of the TPM is seen to be generous to southern nations. On which, investors will be mindful of the recent political turmoil in Italy, which, at the time of writing could see current PM Draghi leave government and possibly trigger early elections. The prospect of such an outcome has seen the IT/GE 10yr spread widen to in excess of 230bps from sub-200bps levels at the beginning of the month. Given the clear impact of domestic politics on the spread in this instance, there is likely to be increasing tensions between southern and northern nations on the conditionality and implementation of the tool than there otherwise would have been. If the conditionality is perceived to be too strict as a result, it may fail to act as a deterrent for spread-widening.
work was still yet to be done and it was uncertain if it would arrive in time for July. More recently (19th July) reporting from Reuters has suggested that conditionality for the tool could "include the targets set by the Commission for securing money from the European Union Recovery and Resilience Facility as well as the Stability and Growth Pact", whilst some wanted involvement from the ESM, but this option was now likely discarded. Note, it remains to be seen whether or not the tool will be announced at the upcoming meeting with President Lagarde reportedly "redoubling efforts to get a deal done". Should the tool be unveiled at the upcoming meeting, analysts at ING highlight that the main issues would be "how to define a ‘neutral’ or ‘economically justified’ spread, the size of such a tool and the degree of conditionality". However, a mere "whatever it takes" pledge could present optics that "such a commitment when starting a rate hiking cycle is like hitting the brakes and the accelerator simultaneously". From a rates perspective, it is likely that hawks would try and negotiate a more aggressive hiking cycle if the conditionality of the TPM is seen to be generous to southern nations. On which, investors will be mindful of the recent political turmoil in Italy, which, at the time of writing could see current PM Draghi leave government and possibly trigger early elections. The prospect of such an outcome has seen the IT/GE 10yr spread widen to in excess of 230bps from sub-200bps levels at the beginning of the month. Given the clear impact of domestic politics on the spread in this instance, there is likely to be increasing tensions between southern and northern nations on the conditionality and implementation of the tool than there otherwise would have been. If the conditionality is perceived to be too strict as a result, it may fail to act as a deterrent for spread-widening.
Finally, in terms of the market reaction, ING writes markets - by a small majority - exect policymakers in Frankfurt to deliver the previously announced 25bp rate hike on Thursday and leave the door open for a 50bp increase in September (although it wouldn't be a shock if the ECB goes all the way with 50). The overnight index swaps market is pricing in 30bp for this week and nearly 200bp of tightening by June 2023. The Bank's message may fall slightly below market expectations, and trigger some dovish re-pricing across the EUR curve.
The deployment of the anti-fragmentation tool will be all the more interesting as the recent Italian political crisis has increased the chances of a sharp re-widening of Italian sovereign spreads. Here, the details about the conditionality to access the anti-spread tool will be key and may drive part of the market's reaction.
ING identifies four different scenarios (with the second being its base case) and include its estimated impact on EUR/USD and German 10Y yields.
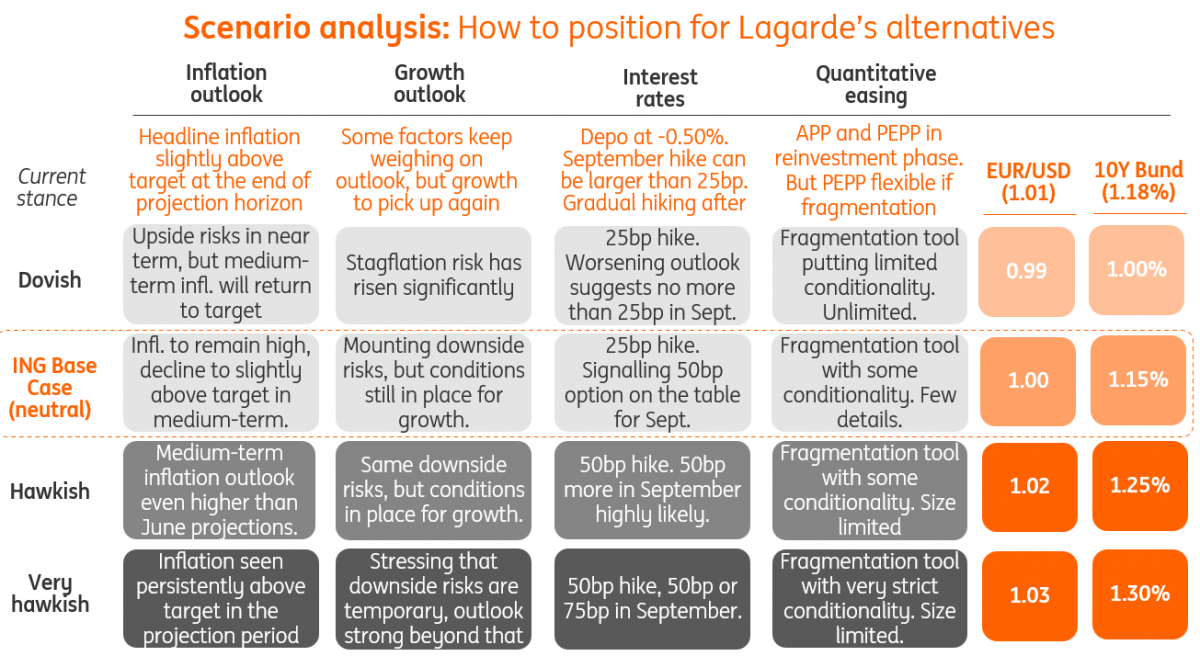
The bank notes that while there is no doubt that the ECB is unhappy with the recent weakness of the euro – not only against the dollar, but on a trade-weighted basis - recent hawkish surprises by the ECB have, however, failed to offer sustained support to the euro, and a larger-than-expected move (a 50bp rate hike) or more hawkish-than-expected forward-looking language may fail to generate enough lift to the euro, a view shared by JPMorgan (which writes that gas supply concerns will undercut the euro, even if the ECB hikes interest rates by 50 basis points Thursday, as developments on Nord Stream 1 are likely to be “the single most important issue for FX markets this week” and A 50bp ECB hike wouldn’t support the common currency if it’s followed by curtailed gas supplies).
This is especially due to the mounting downside risks in the eurozone, mostly related to the threat of a gas supply crunch in the coming months (or during winter) and more recently about Italy falling back into political uncertainty.
Feds Eye Criminal Charges For Hunter Biden As Probe Reaches 'Critical Stage'
The Department of Justice is weighing possible charges against Hunter Biden, after investigations into his business dealings and false statements involving his purchase of a gun have reached a 'critical juncture,' CNN (!?) reports.
Sources say that the probe has intensified in recent months 'with discussions among Delaware-based prosecutors, investigators running the probe and officials at Justice Department headquarters.'
While no final decision has been made, the possibility of dropping charges on Hunter would put a longstanding guideline to avoid bringing politically sensitive cases close to an election.
Discussions recently have centered around possibly bringing charges that could include alleged tax violations and making a false statement in connection with Biden's purchase of a firearm at a time he would have been prohibited from doing so because of his acknowledged struggles with drug addiction....Adding to the pressure, Republicans in Congress have already announced that if they take over the House of Representatives after the midterm elections, they plan to launch new investigations and hold hearings to examine the conduct of Hunter Biden and others in the Biden family. -CNN
The debate over whether to bring the case this close to midterms has revolved around the fact that Joe Biden isn't on the ballot.
While the DOJ probe initially focused on Hunter Biden's financial and business activities in foreign countries while his father was vice president, investigators had expanded the scope to include whether Hunter and associates violated money laundering, campaign finance, tax and foreign lobbying laws - and whether he broke federal firearm and other regulations, according to multiple sources.
These matters have been narrowed down to tax and gun-related charges - which means the Biden family will likely be shielded from scrutiny over improper business dealings which leveraged Joe Biden's position of power - and which Joe Biden provably lied about discussing with Hunter.
So Hunter gets a pass on all this?
In March, CBS News' Catherine Herridge reported that two associates of the younger Biden testified before a grand jury last fall about a shady, now-bankrupt Chinese energy company linked to the infamous "10 for the big guy" from Hunter's emails.
"Federal officials are looking at his foreign business dealings, including his ties to a Chinese energy company," said "CBS Mornings" host Tony Dokoupil.
"The investigation began as a tax inquiry years ago and has expanded into a federal probe involving the FBI and IRS," Herridge added. "A source familiar with the investigation now tells CBS News, two men who worked with Hunter Biden when his father was Vice President were called to the grand jury last fall."
According to records reviewed by CBS along with congressional documents, the feds are looking at "multiple financial transactions involving an energy company called CEFC. Republicans accuse the business of being an arm of the Chinese government. In 2017, the year Joe Biden left the Vice Presidency, a $1 million retainer was signed with a Chinese energy company for Hunter Biden's services as a lawyer.
His client, a CEFC official, Patrick Ho, was later convicted on international bribery and money laundering charges on unrelated work in Africa."
For those who've been keeping up with our reporting since October2020 when the Hunter Biden laptop story broke (and was immediately suppressed by the media), CEFC was the company that the Bidens allegedly accepted a $5 million interest-free loan that enraged their business partner, Tony Bobulinski - who flipped on the Bidens following a Senate report which revealed the $5 million 'loan.'
According to the former Biden insider, he was introduced to Joe Biden by Hunter, and they had an hour-long meeting where they discussed the Biden's business plans with the Chinese, with which he says Joe was "plainly familiar at least at a high level."
Text messages from Bobulinski also reveal an effort to conceal Joe Biden's involvement in Hunter's business dealings, while Tony has also confirmed that the "Big guy" described in a leaked email is none other than Joe Biden himself.

"You can imagine my shock when reading the report yesterday put out by the Senate committee. The fact that you and HB were lying to Rob, James and I while accepting $5 MM from Cefc is infuriating," wrote Bobulinski to Jim Biden. (Via the Daily Caller's Chuck Ross):
CEFC was paying Hunter $850,00 per year according to an email from Biden business associate James Gilliar to Bobulinksi - which is also the source of the "10 held by H for the big guy" email.
Emails obtained by the New York Post show that Hunter "pursued lucrative deals involving China’s largest private energy company — including one that he said would be “interesting for me and my family.”" according to the report.
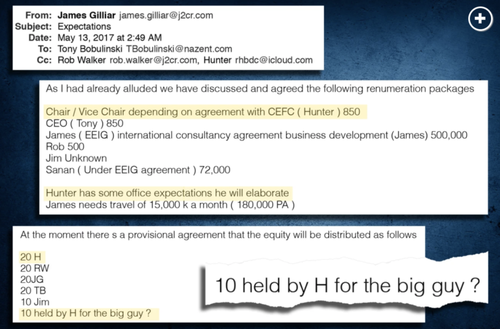
You can read more on Hunter and the CEFC here. As an aside, but of course not coincidental we're sure, the Clinton Foundation accepted a donation between $50,001 and $100,000 from CEFC.
But yes, let's focus on Hunter's tax evasion and gun issues.
"We Decided To Stop Paying": China's Mortgage Payment Boycott Spreads As Property Suppliers Refuse To Pay Their Bills
The Great Debt Jubilee is picking up speed: China's homebuyer mortgage boycott, which prompted Beijing to scramble to avoid a potentially devastating crash in what is the world's biggest asset...

... is spreading, and according to Bloomberg, some suppliers to Chinese real estate developers are now also refusing to repay bank loans because of unpaid bills owed to them, a sign that the loan boycott that started with homebuyers is starting to spread.
In a jarring case study of what happens when a ponzi scheme goes into reverse, hundreds of contractors to the property industry complained that they can no longer afford to pay their own bills because developers including China Evergrande Group still owe them money, Caixin reported, citing a statement it received from a supplier Tuesday.
Similar to homebuyers who have taken a stand and refuse to pay for properties that remain uncompleted, one group of small businesses and suppliers circulated a letter online saying they will stop repaying debts after Evergrande’s cash crisis left them out of pocket.
“We decided to stop paying all loans and arrears, and advise our peers to decline any requests to be paid on credit or commercial bill,” the group said in the letter dated July 15, which was sent to the developer’s Hubei office. “Evergrande should be held responsible for any consequence that follows because of the chain reaction of the supply-chain crisis.”
As Bloomberg oh so perceptively puts it, "the payments protest is the latest sign of how a movement by homebuyers to boycott mortgages on unfinished homes in China is spreading to affect other sectors in the economy."
Yes it is, and it's also why Beijing should be freaking out (if it isn't), because what is taking place in China is far worse than what took place in March 2020 when the global credit machinery ground to a halt, only back then it's because there was no other option, now it's a voluntary development and not even fears of reprisals from China's ruthless, authoritarian, Lebron-beloved dictatorship is stopping millions of people from calling for a systemic boycott, one which can topple China's entire $60 trillion financial system in moments.
It's so bad, even Bloomberg has given up trying to put lipstick on this particular pig:
The development underscores a dilemma for Xi Jinping’s government as it grapples with who to bail out as the country’s property crisis deepens: Relief for some borrowers could prompt threats of non-payment by a whole host of others. While bending to demands for support could put a strain on state finances, ignoring them might lead to a spiral of defaults as more and more borrowers refuse to meet their obligations.
The mortgage strike, which kicked off in late June in a stalled Evergrande development in Jingdezhen, has rapidly grown to at least 301 projects in about 91 cities. The protests have exacerbated the country’s real estate woes and threaten to derail attempts to revive the market amid an economic slowdown. According to some estimates, millions of mortgages are now involved.
On Monday, we reported that as the pressure on Beijing rises to take measures, authorities urged banks to boost lending to builders to help complete the projects, and are also considering giving homeowners a grace period on payments.
Homebuyers’ refusal to pay mortgages stems from the widespread practice in China of selling apartments before they’re built. That practice imploded in the past year, as overleveraged Chinese developers were swept by a wave of insolvency, and have been in crisis mode over debt repayment as funds ran dry, and as construction stopped on more and more projects.
Chinese banks claims that the risks from the housing loan nonpayments are controllable, and so far have disclosed only 2.1 billion yuan ($311 million) of credit at risk. That, of course, is a lie: GF Securities Co. expects that as much as 2 trillion yuan of mortgages could be impacted by the boycott. That's millions of mortgages.
Overall, Chinese banks sit on 38 trillion yuan of outstanding residential mortgages and 13 trillion yuan of loans to the country’s beleaguered developers.
More Than 100 Million Americans Face Dangerous Heat Wave
Triple-digit temperatures expected in states across the country
More than 100 million Americans were in the path of a dangerous heat wave Wednesday, from the West to the Northeast, officials said.
Temperatures in the triple digits were recorded from Arizona to Louisiana, according to the National Weather Service.
Forecasters warned the roughly one-third of Americans that were under heat alerts to drink fluids and stay out of the sun, saying that excessive heat could cause them to develop heat-related illnesses.
“Scorching heat will remain a major weather story over at least the next few days,” said Cody Snell, a meteorologist for the NWS. He added that even low temperatures would remain warm in the upper 70s or low 80s.
The heat was especially sweltering Wednesday in central California, the Southwest, the Plains, the mid-Atlantic and the Northeast, which were under excessive heat warnings and heat advisories. The conditions threatened to fan the patchwork of 86 fires burning across the U.S. on Wednesday, according to the National Interagency Fire Center.
Officials across the country opened cooling centers to keep residents out of the sun. Boston officials declared a heat emergency through Thursday, while Connecticut Gov. Ned Lamont activated the state’s “extreme hot weather protocol.” In New York, Gov. Kathy Hochul warned residents to stay indoors because of the heat and humidity.
Philadelphia issued its first heat-health emergency of the summer for Thursday, ahead of hot and humid conditions forecast through Sunday. A special healthline will be available, cooling sites will be opened and dozens of parks will have “spraygrounds” where residents can cool off.
Tuesday was the hottest day of the year across Oklahoma and western northwestern Texas, according to the National Weather Service in Norman, Okla. A high of 116 degrees was recorded at two places in the state and the lowest high temperature on Tuesday in the entire state was 106 degrees.
Dallas reached 109 degrees on Tuesday, breaking the 2018 record of 108 degrees. And temperatures in North Texas were set to reach at least 105 degrees on Wednesday, according to the National Weather Service in Fort Worth, Texas.
The hot, dry conditions increased the potential for significant wildfires in parts of the state, according to the Texas A&M Forest Service. The service said it responded to 24 wildfires over 7,774 acres on Tuesday.
The National Weather Service said “anomalously high” temperatures are expected to stay through the week in most of the country, with triple digits expected in parts of the South-Central U.S. Hotter temperatures will occur in the Pacific Northwest early next week.
Parts of the Midwest were expected to be spared from much of the heat. Instead, Instead, cooler weather is forecast for the Great Lakes region, with highs in the 70s and 80s, the NWS’s Weather Prediction Center wrote in a forecast on Wednesday afternoon.
July has been a relentlessly hot month in Europe, too, where a record-breaking heat wave has been blamed for hundreds of deaths across the continent. The heat and a drought fueled wildfires across swaths of Southern Europe, forcing thousands of people to evacuate their homes.
Rising temperatures around the world, which most climate scientists attribute to greenhouse-gas emissions, have caused a record number of heat waves, droughts and wildfires. Last year was one of the hottest on record, according to two federal agencies, which also reported that the U.S. recorded its hottest summer last year since 1936.
The big collateral call facing UK pension funds
Some schemes might have to sell riskier assets as part of trades to hedge liabilities
The number £1.5tn is big — at least in a UK context. It is 40 per cent of the UK institutional asset management market, two-thirds of gross domestic product and about the size of the government’s total debt, after stripping out bonds held by the Bank of England.
This is the quantum of liabilities held by UK pension funds that have been hedged with so-called Liability Driven Investment trades, according to the asset management trade body The Investment Association.
LDI is big business, having more than tripled in size over the past decade, and the reason is simple — it helps funds manage the risks in meeting their pension promises for members, partly through derivatives.
But now funds are facing calls from counterparties to put up collateral to fund those trades. The sums are potentially huge and asset sales to meet the calls could have a knock-on effect to markets such as equities.
For the past 25 years, the fall and fall in long-dated bond yields has delivered a costly headwind to pension funds. Thousands of firms that sponsor defined benefit pension schemes — typically now closed to new entrants — have seen the accounting value of their liabilities soar. When bond yields fall, the present value of those future liabilities is discounted at a lower rate.
The Pensions Regulator estimates that every 0.1 percentage point fall in UK gilt yields increases a conservative measure of UK scheme liabilities by £23.7bn. In the decade to December 2020, long-dated, 25-year gilt yields fell by more than 3.5 percentage points and scheme liabilities increased by £960bn (about 40 per cent of GDP).
Pension schemes can’t control wild swings in their liabilities’ value. But they are not completely helpless. They can invest their assets so that they become relatively indifferent to bond market gyrations, and this is where LDI comes in.
As bond prices determine the valuation of pension liabilities, moving pension assets into bonds will effectively hedge the volatility of liabilities. The problem is that few pension schemes are well-funded enough to make this trade. Instead, schemes invest a portion of their assets in liability-matching bonds and a portion in growth assets — corporate credit, equities, property. They then hedge the risks of that strategy with derivatives, using bond assets as collateral.
The hope is that growth assets will deliver decent returns and make them fully funded while the derivatives will desensitise them to future interest rate swings. The results have been good, but have also left pension funds as counterparties to enormous quantities of leverage in the financial system.
Despite £1.5tn invested in LDI strategies, UK pension funds remain under-hedged. As such, while the rise over recent months in yields on long-dated bonds has been awful news for return-seeking holders of them, it is great news for pension scheme funding.
Since the end of 2020, long gilt yields have increased by 1.7 percentage points, helping to take a third of UK DB pension schemes from deficit to surplus. The UK’s Pension Protection Fund has estimated that system-wide pension funding has improved by £350bn over that time.
But accompanying this rise in yields are large losses and collateral calls for schemes engaging in leveraged LDI derivative trades. How large? An upper-end estimate, if LDI was implemented entirely through derivatives, would be a collateral call of over £380bn — but in truth we don’t know the precise mix of bonds and derivatives deployed.
To be clear, this was the plan: losses should match declining scheme liability values. As such, funding ratios should be unaffected. Furthermore, schemes engaging in LDI will have stress-tested rising yield environments and have collateral suitably sized to withstand such a shock. However, bond yields have risen more than standard stress tests envisaged — largely or entirely wiping out scheme collateral buffers. Those schemes with depleted excess collateral buffers now face decisions as to how and when they will restore them.
Does this matter? LDI managers claim that their activities pose no systemic risk, and I read the Bank of England financial policy committee’s silence as agreement. But UK pension funds are collectively very large derivative counterparties and they move together.
Scheme collateral buffers have been markedly depleted across the board and require rebuilding; this can only realistically happen by selling growth assets like corporate debt, equities and property. So, while rising yields are good news for pension scheme funding levels, they look a likely catalyst for a further liquidation of risky assets.
After Hours Summary: TSLA +0.7% flat on earnings; AA +6.7%, CSX +3.9%, LVS +2.3% higher on earnings; SMCI +24% jumps on bullish guidance; UAL -7.1% falls on earnings; CCL -9.5% falls on $1 bln stock offeringAfter Hours Gainers:
Companies trading higher in after hours in reaction to earnings/guidance: SMCI +24%, AA +6.7% (also authorizes new $500 mln share repurchase program), RLI +4.9%, CSX +3.9%, VMI +2.9%, LVS +2.3%, MCRI +2%, KMI +1.3%, STLD +1.2%, CVBF +1.1%, TSLA +0.7%, SLG +0.1%
Companies trading higher in after hours in reaction to news: SAP +3.7% (PDFS to collaborate with SAP), ABUS +3.1% (to discontinue development of hep-B core inhibitor vebicorvir), OSK +0.4% (US Postal Service plans to increase its EV order from OSK, according to Reuters), EQT +0.2% (increases dividend), SWK +0.1% (increases dividend)
After Hours Losers:
Companies trading lower in after hours in reaction to earnings/guidance: XM -7.8%, UAL -7.1%, DFS -3.5%, UMPQ -3.5%, LSTR -3.3% (also increases dividend), KNX -1.4%, CCK -1.3%, SEIC -1%, EFX -0.3%, FNB -0.1%, FR -0.1%
Companies trading lower in after hours in reaction to news: VERV -13.2% (commences $200 mln stock offering; also announces research collaboration with VRTX, which will buy a $35 mln stake in VERV), CCL -9.5% (commences $1 bln stock offering), ASMB -5.5% (discontinuing further development of core inhibitor, vebicorvir; also chief medical officer and CFO to step down), ALL -4.9% (reports catastrophe losses for Q2), COIN -3% (on news that TSLA converted 75% of its Bitcoin purchases into fiat currency), BITO -0.5% (on news that TSLA converted 75% of its Bitcoin purchases into fiat currency), VRTX -0.5% (VRTX announces research collaboration with VERV, will invest in a $35 mln stake in VERV), BAC -0.3% (increases dividend), F -0.3% (to provide EV plan update on Thursday), OLN -0.1% (COO to retire), MO -0.1% (Juul Labs saw revenue drop amid US govt crackdowns on teenage vaping, according to Bloomberg)
