Western banks struggle to exit Russia after Putin intervention
Advisers warn that Kremlin favourites could hijack sales of subsidiaries
Advisers to western banks trying to exit Russia say a law introduced by Vladimir Putin is disrupting sales and allowing deals to be hijacked by business people close to the Kremlin.
Almost a year into the invasion of Ukraine, only a handful of western banks have managed to leave Russia, albeit at steep cost, while others have made the choice to hold on to their businesses in the country.
For the majority trying to sell their Russian assets, however, hopes for a swift exit were shattered when Putin last year said foreign owners from “unfriendly” countries could not complete deals without his approval. The list of implicated companies includes 45 banks with subsidiaries in Russia.
Advisers working on deals expect the Russian president’s intervention to thwart some sales already under discussion, while fundamentally altering the terms of others.
They predict already agreed sale prices to fall by up to half as the Kremlin exerts more influence on deals. And they say would-be buyers who were originally beaten to deals have gained presidential approval and are attempting to hijack sales from rivals who lack the Kremlin’s favour.
“There are some very powerful Russians with close links to the Kremlin who are trying to use their influence to grab these entities from fleeing foreigners,” said a person involved in negotiations, one of several people who spoke to the Financial Times on condition of anonymity because of the sensitive nature of talks with the Russian government.
“We’re working on [these types of deals] every day, but it’s becoming more and more challenging all the time,” said Laura Brank, partner at law firm Dechert, who is advising western banks on selling their Russian subsidiaries.
“The situation is very fluid and rules are really not clear.”
Within days of Russia’s invasion of Ukraine, western banks that had spent decades slowly building up their Russian branches faced a stark choice about whether to sell the business quickly and swallow a heavy loss, or hold on and gradually wind it down.
The western sanctions and Moscow’s counter-sanctions made the country all but impossible to do business in for foreign banks.
Austria’s Raiffeisen Bank International, the western lender with the biggest presence in Russia and Ukraine, increased its currency hedging and cash reserves in expectation of customers withdrawing their savings as troops gathered at the border at the start of last year.
But the invasion on February 24 caught the bank’s executives — like most western bankers — off guard.
“It was one of the most shocking days in my life,” said Hannes Mösenbacher, chief risk officer at Raiffeisen.
Raiffeisen’s subsidiary is the biggest on the Kremlin’s list — with 4.2mn customers and 9,400 staff in Russia on the eve of the invasion — and the bank has yet to figure out how it will dislodge itself from the country.
Of its €22.9bn of assets in Russia at the start of 2022, only €354mn was exposed to financial institutions that came under western sanctions and €119mn to other companies hit with sanctions.
In late July, HSBC agreed to sell its Russian subsidiary to local lender Expobank in a deal that would allow it to exit a country that had become politically toxic since Moscow’s invasion of Ukraine at the start of the year.
But that sale has now been held up. HSBC said it was still working on trying to complete the transaction, but a person with knowledge of its plans said it was up to Expobank as the acquirer to secure approval from Putin.
“For us, there is no change from when the deal was signed,” said the HSBC executive. “It just needs to go through these machinations.”
One bank that managed to shift its Russian subsidiary before the presidential decree was France’s Société Générale, which agreed in April to sell its Rosbank business as well as its Russian insurance operations to an investment company founded by billionaire Vladimir Potanin.
Along with Raiffeisen and Italy’s UniCredit, SocGen had one of the largest exposures to Russia of any western bank, with €18.6bn of assets at the start of 2022. Rosbank employed 12,000 people.
SocGen was able to cut a swift deal because it sold to Potanin, one of Russia’s richest men with close links to the Kremlin, who was only sanctioned by the US last month. The French bank had also bought the business from Potanin in 2008.
“We did it very, very quickly — it helped that we sold it to somebody who knew the bank well,” said a SocGen executive. “We even got congratulatory calls from rivals saying how efficiently and orderly we were able to get rid of it.”
However, in reaching such a hasty sale, SocGen was forced to take a €3.3bn hit.
Other banks looking for a quick exit did not have a ready buyer waiting in the wings, nor were they prepared to absorb such a financial hit as SocGen took.
UniCredit’s Russian operations include 2mn customers and 3,500 staff. Chief executive Andrea Orcel even considered upping its exposure by buying Russian bank Otkritie just weeks before the invasion. By mid October its total exposure to Russia still stood at €7bn.
The Italian bank’s failure to cut ties with Russia has caused friction with the European Central Bank, the FT has reported, after Orcel said over the summer that writing off the business or selling it at a discount was “not morally correct”.
More recently, however, the bank has said it is “committed to disengaging from Russia in an orderly and decisive fashion”, which Orcel said was different to the “dump it all” strategies pursued by other banks, without naming them.
“You are dumping it to the very people you’re trying to fight,” he said at a Bank of America conference in September. “We are trying to make sure there is an orderly containment of what we have, and eventually exit, but in a way that is not a gift.”
It has, however, agreed to sell RN Bank, its Russian joint venture with Renault and Nissan, to Lada-maker Avtovaz. The deal was given the green light by Putin at the end of November.
Citigroup, whose local subsidiary is subject to the decree, has taken a different approach to dealing with its exposure, which stood at $7.5bn at the end of December.
Having failed to find a buyer for its Russian business for more than a year, the US lender has decided instead to wind the business down.
Last month the bank sold a portfolio of Russian consumer loans to Uralsib, a local commercial lender.
It also plans to close most of its institutional banking services in Russia by the end of the first quarter of 2023, though its custody operations are likely to prove harder to disentangle, according to people with knowledge of the business.
Intesa Sanpaolo chief executive Carlo Messina has outlined his intention to turn Italy’s largest lender by assets into a “zero Russia exposure bank” by winding down cross-border loans between Italian and Russian companies, which make up the majority of its business in the country.
But like the other western banks stuck in the country, the fate of its Russian subsidiary rests in Putin’s hands.
“It’s an extremely difficult situation for us as it is for most banks,” said the executive at one bank with a subsidiary on the restricted list.
“The fact of initially not being able to sell to sanctioned entities and now keeping all these banks hostage plays into what the Russian government wants. There is no incentive to make it easy for banks to leave.”
He added: “We’re in limbo, but it’s not for lack of desire to resolve it. It’s just very hard to see what the path out of this is.”
Euronext to switch derivatives clearing to Italy in 2024
Exchanges group prepares to move financial and commodity derivatives away from French capital to Milan
Euronext has agreed a deal to move part of its clearing business from a subsidiary of the London Stock Exchange Group, reducing its reliance on its British rival in a controversial area of Europe’s capital markets.
Euronext, the biggest operator of stock markets in Europe, has agreed a €36mn termination fee with the LSE that ends a dispute between the two over the future over clearing of Euronext’s equity, derivatives and commodities business.
The group also said it was open to selling its 11.1 per cent stake in the French arm of LCH back to its British majority owner, further simplifying the complex web of cross-shareholdings between the two exchanges and their clearing houses.
Amsterdam-listed Euronext has been looking to renegotiate a 10-year deal with LCH in Paris to clear the business since it purchased Borsa Italiana for €4.4bn in 2021 from the LSE. The agreement between Euronext and LCH, which is majority-owned by the LSE, was due to expire in 2027.
The Borsa Italiana deal included the CC&G clearing house in Milan, which meant that Euronext no longer had to rely on services from the LSE.
A clearing house stands between two parties in financial transactions, helping manage adverse fallout across markets should an entity default. They have become politicised in Europe since the UK voted to leave the EU, with European politicians keen to repatriate as much business as possible to the eurozone. LCH, which has both British and French subsidiaries, is one of the world’s largest clearing houses.
As part of the agreement Euronext will begin moving the business to Italy from late 2024. Stéphane Boujnah, chief executive of Euronext, told the Financial Times that one of the “peculiarities of the situation” was that “we terminate our relationship with the clearing house of LCH SA because LCH sold us another clearing house.”
Boujnah added that “having full control of the derivatives clearing chain is changing significantly our ability to build a more ambitious derivatives strategy . . . Things that we were not able to do when we were just clients of a competitor.”
Boujnah said it was “more their option than ours” as to whether LCH Group, the umbrella company that owns LCH’s French arm, would buy back the 11.1 per cent stake from Euronext.
LSEG said that the French arm of LCH is “strategically important” to the group, “clearing the majority of the eurozone repo market and the majority of the Euro credit derivatives market, in addition to many European equity market venues.”
Elon Musk, Tesla Poised for Trial Over Tweets Proposing to Take Car Maker Private
Plaintiff alleges tweets about a potential deal, which never materialized, cost investors billions
Elon Musk is headed to court in a securities-fraud trial over tweets from 2018 in which he floated the possibility of taking Tesla Inc. private, with in-person jury selection poised to begin Tuesday.
The class-action case originates with an Aug. 7, 2018 tweet in which the Tesla TSLA -0.94% chief executive said, “Am considering taking Tesla private at $420. Funding secured.”
An investor, Glen Littleton, sued Tesla, Mr. Musk and members of Tesla’s board at the time, alleging that Mr. Musk’s tweets were false and cost investors billions by spurring swings in the prices for Tesla stock, options and bonds. In court filings, Mr. Musk has said he was indeed considering taking Tesla private and believed he had the support of Saudi Arabia’s sovereign-wealth fund to do so. The deal, which would have been valued around $72 billion, never materialized.
U.S. District Judge Edward Chen, who is overseeing the San Francisco jury trial that is scheduled to run through Feb. 1, has ruled that Mr. Musk’s tweets about taking the company private weren’t true and that he acted recklessly in making them.
Questions for the jury include whether Mr. Musk’s tweets were material to investors and whether he knew they were untrue.
The case is unusual in that securities-fraud cases usually resolve before going to trial, such as through a settlement, said Jill Fisch, a securities-law professor at the University of Pennsylvania. The defendants in this case face “an uphill battle” in light of the judge’s pretrial decision about the veracity of Mr. Musk’s statements, she said.
Attorneys for the lead plaintiff didn’t respond to a request for comment, nor did an attorney for Tesla, Mr. Musk and the other board members.
Mr. Musk is expected to take the stand as early as Wednesday, some two months after he did so in Delaware in a trial over his pay package at Tesla. In 2021, he also appeared before Delaware’s business-law court to defend Tesla’s roughly $2.1 billion 2016 takeover of home-solar company SolarCity Corp.
Also on the list of possible witnesses are Tesla board chair Robyn Denholm, board members Ira Ehrenpreis, James Murdoch and Kimbal Musk —the CEO’s brother. The head of investor relations, Martin Viecha, also may be called.
This week’s trial comes at a busy time for Mr. Musk, who has been scrambling to turn around Twitter Inc. after buying the social-media company last fall in a deal valued at $44 billion. His rocket company SpaceX is pushing for the first orbital launch of a new rocket Mr. Musk wants to use for deep-space missions.
Tesla, meanwhile, has slashed prices across its vehicle lineup, with some of last week’s cuts in the U.S. nearing 20%, in a bid to juice demand. The company’s stock has fallen roughly 70% since its peak in November 2021, erasing around $850 billion in market value. Mr. Musk’s personal wealth has fallen more than $200 billion in that time, according to the Bloomberg Billionaires Index.
Court proceedings involving Mr. Musk can be feisty. In the SolarCity case, for example, Mr. Musk called opposing counsel a “bad human being.”
In advance of this week’s trial, Mr. Musk asked the court to move the trial to Texas on the basis that potential jurors in San Francisco could be biased against him. Judge Chen rejected the request.
“It isn’t that hard it seems to me to find 15 people,” he said.
The court requires nine jurors and six alternates to proceed with the case. Roughly 190 potential jurors were asked to fill out questionnaires about their views of Mr. Musk and other issues. The court plans to bring in about 50 of them for further questioning Tuesday.
Opening arguments could start as early as Tuesday after the jury is selected.
The lead plaintiff is seeking damages for investor losses he alleges stemmed from Mr. Musk’s and Tesla’s statements. Tesla stock closed up 11% the day Mr. Musk initially tweeted about potentially taking Tesla private, later giving back all those gains and falling further as questions emerged about the deal.
The defendants have said the plaintiff won’t be able to prove to a jury that the statements were materially false. Mr. Musk was considering taking Tesla private, the defendants have said, even if some of his assertions about the deal may not have been literally accurate.
Defendants, in a trial brief, said Mr. Musk believed he had secured backing to take the car maker private from Saudi Arabia’s sovereign-wealth fund, the Public Investment Fund. A lawyer for the defendants said Friday that his team had chosen not to enforce subpoenas calling on fund representatives to testify. The sovereign-wealth fund didn’t respond to a request for comment.
Mr. Musk and Tesla each agreed in 2018 to pay $20 million to settle civil charges brought by the Securities and Exchange Commission over the same tweets. Mr. Musk also agreed to step down as chairman of the company, while remaining CEO. He later said in legal filings that he felt pressured to settle with the SEC. Last year, a federal judge denied Mr. Musk’s request to scrap his settlement.
Temenos: CEO exit highlights the perils of software-as-a-service shift
Management have worsened the blow to investor confidence by over promising and under delivering
If you have always doubted national stereotypes, revel in the unreliability of Switzerland’s Temenos. You might not ask this lot to fix your cuckoo clock, let alone install your banking software, given recent managerial mishaps. Shares have halved since 2019. Chief executive Max Chuard has just resigned. His nemesis, Petrus Advisers, is hardly keener on chair Andreas Andreades.
In fairness, Temenos is not the only European software group that has found the transition to selling software-as-a-service hard going. SAP of Germany and the UK’s Sage have form of their own. City readers with long memories will meanwhile recall the rough ride that cyclical demand for banking software gave the likes of Misys.
Switching to SaaS means revenues and profits booked up front are spread over longer periods. The management of Temenos have exacerbated the blow to investor confidence by over promising and under delivering. A profit warning in October shaved a quarter from full year operating earnings.
Temenos is mature for an IT business at 30 years old. Chuard and executive chair — now interim chief executive — Andreades have been there for 20 years. Chuard is leaving following better-than- expected fourth-quarter results published on Monday. A 10 per cent pop in the shares may reflect joy at either, or both, of these factors.
Temenos, which is worth about SFr4.6bn, has underperformed peers like FIS and Fiserv. These have lost one-third and gained two-fifths respectively since 2019, albeit that they are oriented to payment services. Temenos hardly looks cheap at 23 times price to forward earnings. Both Fiserv and FIS have managed to increase earnings against a decline at Temenos over the period.
Petrus wants Temenos to set realistic targets and disclose more data. The group is still guiding for higher margins by 2025. Analysts think it may meet such targets, although almost two years later according to Visible Alpha.
The activist is also calling for a greater focus on the US. Temenos’s 2 per cent market share there is very low given its relative strength in the European market.
Petrus wants Andreades, who will step down as chair in six months anyway, to follow Chuard out the door. In the meantime, optimistic targets leave shareholders primed for further disappointments. Would-be consolidators would be cuckoo if further slip-ups do not prompt them to swoop in.
Asian shares started the week higher while the dollar declined amid a tailwind from easing inflation expectations that has fueled January’s rally in riskier assets. A benchmark of Asian equities climbed about 0.4%, putting it on course for the highest level since June. US futures rose after stocks on Wall Street closed at the strongest level in a month on Friday and contracts for European shares advanced. Japanese markets painted a different picture with the Topix index trading lower as the yen’s rebound continued to weigh on exporters. Investors also remain on guard for another surprise from the Bank of Japan when it sets policy on Wednesday. The yen strengthened to levels last seen in May and Japan’s benchmark 10-year bond yield pushed above the top of the BOJ’s ceiling for a second day. The greenback was down against both emerging-markets and Group-of-10 currencies on bets that the Federal Reserve will slow the pace of interest-rate hikes. Australia’s dollar strengthened above 70 cents for the first time since August, a reflection of improved appetite for riskier assets. Bitcoin traded above $21,000 following a rebound over the weekend, when it surged amid optimism that it may have bottomed. The impact of surging Covid infections was also on the minds of traders, but not enough to hold back the Shanghai Shenzhen CSI 300 Index, which jumped about 2%. The World Health Organization has urged China to share more detailed information on the spread of virus after the government’s announcement of almost 60,000 related deaths in a month. The People’s Bank of China kept the rate of its one-year medium-term lending facility unchanged and added less cash than expected into the banking system before the Lunar New Year holidays. The move is likely to fuel speculation the central bank may use other channels to ensure there’s adequate liquidity. The busy week will also be punctuated by more corporate earnings, such as Wall Street heavyweights Goldman Sachs Group Inc. and Morgan Stanley. iron ore declined after China pledged to tighten supervision on pricing after the metal’s surge in recent months. Oil slid and gold rose.
Nikkei -1.13% Hang Seng -0.68% CSI +1.49% Shanghai +0.99% Shenzen +1.30%
Eur$ 1.0858 CNH 6.74100 CNY 6.7005 JPY 127.64 GBP 1.2267 CHF 0.9238 RUB 68.9983 TRY 18.7871 WTI$ 79.34 -0.65% Gold 1,921.35 +0.06% BTC 21,167 +1.25% ETH 1,573 +1.33%
S&P -0.05% Nasdaq -0.17% EuroStoxx +0.31% FTSE -0.04% Dax +0.25% SMI +0.11%
Macro :
- Germany Faces €12B Financing Gap in 2024 Budget: Handelsblatt
- Lithium’s Next Big Risk is Grand Supply Plans Falling Short
- German Industry Moves Past Worst of Energy Crunch Battle
- Hedge Funds Go Bearish on Gas for 1st Time Since Pandemic Began
- Germany’s Embattled Defense Minister Plans to Resign, Bild Says
- Switzerland Aims to Soften Restrictive Arms Export Law, NZZ Says
- Scaramucci Invests in Crypto Firm Set Up by Ex-FTX US Head
Keep an eye on :
- AIR FP : Crashed Nepal Plane’s Flight Data Recorder Found: Reuters
- BBVA SM : *BBVA CHAIRMAN SAYS BANK EXPECTS TO BOOST DIVIDEND IN 2023
- BILL SS : Siemens Energy Gains as Billerud Slips: EMEA Resources Wrap
- BA/ LN : UK Will Send Major Battle Tanks, More Artillery to Ukraine
- 1COV GY : Covestro Prelim FY Net Loss About EU300M
- CSGN SW : UBS Doesn’t Plan to Buy Credit Suisse or US Firms: Kelleher
- CSGN SW : Credit Suisse Set to Cut 10% of European Investment Bankers: FT
- ENI IM : Italy’s Gas Supply Set to Be More Secure Next Winter, Eni Says
- FRA GY : Fraport Dec. Frankfurt Airport Passengers +46.2%
- HYQ GY : Hypoport Mortgage Finance Business Stable After Sharp 2H Decline
- JNJ US : Johnson & Johnson Slashes Production of Covid-19 Shot, WSJ Says
- LAND LN : Sky News: Land Securities lines up Channel 4’s Cheshire as next chairman
- LDO IM : Crashed Nepal Plane’s Flight Data Recorder Found: Reuters
- MJH LN : MJ Hudson Expected to Announce Takeover Approaches: Sky
- MOWI NO : Mowi Prelim 4Q Ebit Beats Estimates
- ORSTED DC : Orsted Plans Major Offshore Wind Expansion in Sweden, DI Reports
- PFE US : Pfizer Bivalent Vaccine Linked to Stroke in Preliminary Data
- PROX BB : Proximus Sees 2023 Adjusted Ebitda About -3%
- RECSI NO : REC Silicon Says Moses Lake Restart Activities Progressing Well
- RNO FP : Renault Said to Be Open to Concessions to Strike Nissan Deal
- ENR GY : Germany Targets Three New Windmills a Day for Energy Reboot
- SIKA SW : Sika to Sell Concrete Assets to Ineos to Gain Antitrust Approval
- TEMN SW : Temenos Prelim 4Q Non-IFRS Ebit Misses Estimates
- TEMN SW : Temenos Seeks New CEO as Chuard Steps Down
- 700 HK : Alibaba and Tencent Could Boost Inflows for Tech ETFs in 2023
- UN01 GY : LNG TENDER: Uniper Buys Feb. Cargo to Europe at TTF Discount
- VOW GY : Ford Set to Cut Dependence on VW Electric Vehicle Tech: FT
- WBD IM : Webuild Unit Wins $218m Highway Contract in Florida
>>> Up
* Amgen PT Raised to $300 from $260 at Argus
* DWS Raised to Buy at Jefferies; PT 40 euros
* Essity Raised to Buy at Handelsbanken
* Lloyds Bank Raised to Reduce at AlphaValue/Baader
* Man Group Raised to Buy at Jefferies; PT 285 pence
* Novo Nordisk Raised to Hold at Handelsbanken
* Verbund Raised to Neutral at Credit Suisse; PT 81 euros
* Ypsomed Raised to Outperform at Credit Suisse
>>> Down
* Abrdn plc Cut to Hold at Jefferies; PT 215 pence
* Airbus Cut to Hold at Berenberg; PT 120 euros
* Atlas Copco Cut to Underperform at RBC
* Centamin Cut to Market Perform at BMO; PT 130 pence
* Collector Bank Cut to Sell at SEB Equities; PT 31 kronor
* Dow Cut to Hold at Fermium Research; PT $60
* HSBC Cut to Hold at Investec; PT 595 pence
* Orange Cut to Hold at Jefferies; PT 10 euros (cut from 12,40 euros)
* Rational Cut to Hold at HSBC; PT 670 euros
* Rotork Cut to Sector Perform at RBC
>>> Initiation
* Alfa Financial Rated New Add at Peel Hunt; PT 210 pence
* Alphabet Rated New Add at CTBC Securities; PT $102
* Autostore Rated New Sell at DNB Markets; PT 18 kroner
* Eckoh Rated New Buy at Peel Hunt; PT 60 pence
* Equals Group PLC Rated New Buy at Peel Hunt; PT 135 pence
* Network International Rated New Buy at Peel Hunt; PT 420 pence
* Tencent Music ADRs Rated New Buy at Daiwa; PT $11
* WAG Payment Solutions Rated New Buy at Peel Hunt; PT 140 pence
* Wise Rated New Hold at Peel Hunt; PT 600 pence
>>> Call
* Airbus Gets ‘Reluctant’ Cut at Berenberg on Near-Term Caution
* DWS and Man Group Upgraded at Jefferies, Abrdn Downgraded
* Europe Industrials Still Resilient, But Upside More Limited: RBC
* European REIT Financing Footings Redefined by End to Zero Rates
* Morgan Stanley’s Secker Says Europe Outperformance Should Extend
* Orange Cut at Jefferies on Lower Growth Prospects Into FY23
* Verbund Upgraded by Credit Suisse With Shares Now Fairly Valued
IMF Warns Unraveling Economic Ties Could Shrink Global Output
Lender points to rising trade, migration and investment barriers
Declining international cooperation and commerce could shrink the global economy, particularly harming low-income countries, the International Monetary Fund said in a new study.
The report cited several ways that government policies are driving a reversal of global economic integration, such as by restrictions on trade, immigration and cross-border capital flows. The authors labeled this process geoeconomic fragmentation and warned it could lower global gross domestic product by up to 7% over an unspecified “long-term” period.
If technology sharing is also restricted, the losses would be even greater, from 8% to 12%, in some, mostly lower-income and emerging economies, said the staff report, released Sunday.
This could undo the economic globalization of recent decades that the IMF said has reduced poverty in developing countries and delivered lower prices to low-income consumers in advanced economies.
“The global economy may be on the brink of a reversal of the steady increase in integration that characterized the second half of the 20th century,” the multilateral lender said in its analysis. “While fragmentation may entail strategic advantages for some countries in selected cases, it is very likely to involve significant economic costs in the aggregate.”
The costs “would include higher import prices, segmented markets, diminished access to technology and to both skilled and unskilled labor, and ultimately reduced productivity which may result in lower living standards,” the IMF said.
The IMF concluded that the Covid-19 pandemic and Russia’s invasion of Ukraine further strained trade ties that were tested by a shallow and uneven recovery from the 2008 financial crisis as well as the U.K.’s exit from the European Union and continuing trade tensions between Washington and Beijing.
The IMF noted that at the height of the pandemic, countries limited their exports of medical goods and foodstuffs with export bans that accounted for about 90% of trade restrictions.
Moreover, the war in Ukraine and associated sanctions placed by the West on Russia and Belarus led to “major dislocations in energy and agricultural commodity markets.”
The lMF said that the U.S., European Union and China had all enacted recent measures to promote domestic high-tech production. Companies, too, were moving their supply chains to minimize risk, with key words such as “reshoring,” “near-shoring” and “onshoring” appearing more frequently in company earnings calls and reports, the IMF said.
This trend toward fragmentation in trade would likely reduce opportunities for emerging economies and slow the reduction of poverty, according to the IMF.
Rising barriers to the flow of labor across borders could also slow down innovation and technological diffusion, the IMF said. Economic fragmentation could also constrict options for international investing, which would hinder development. The trends are likely to lead to uncertainty and to make cooperation on challenges such as climate change more difficult, the lender said.
Fragmentation is likely to contribute to splintered regulation, making some forms of international banking untenable and raising the cost of financing, according to the IMF. Countries that wanted to preserve stability would likely have to rely on “costly self-insurance” such as reducing external debt to bolster themselves against shocks.
The IMF recommends ensuring trade cooperation on global public goods and fair competition, while protecting the most vulnerable populations. Further, the lender recommends preserving minimal cooperation through what it calls guardrails, for example, “safe corridors” to enable the movement of critical goods and services.
It also recommends that countries try to achieve a small number of common goals in areas where they have broad alignment. “Open a path for rebuilding trust,” the IMF said. One such area could be a new digital international payment system.
The report comes amid multiple signs that the global economy slowed toward the end of 2022 under the weight of high inflation and rising interest rates, combined with challenges caused by the war in Ukraine and effects of Covid-19 in China.
The World Bank earlier this month sharply lowered its forecast for global economic growth in 2023 and noted an elevated risk of a worldwide recession. The bank expects growth to slow to 1.7% in 2023, down from an estimate of 3% growth in June. That would mark the third-weakest pace of global growth in nearly three decades, overshadowed only by the 2009 and 2020 downturns, according to the World Bank.
Fully Priced-In: Even Goldman Expects Sharp Contraction In Profit Margins In 2023
There has been a bizarre episode of cognitive dissonance developing within Goldman's trading desk and research departments over the past three months: as readers may recall, some time in late September, just as stocks slumped near their 2022 lows for the second time, Goldman's chief equity strategist David Kostin - who had heretofore been one of the staunchest equity bulls - slashed his market outlook and his S&P price target, which he now sees closing unchanged from its Friday level, or right at 4,000. That's right, Goldman clients can now take a 11 and a half month vacation, spare themselves the emotional rollercoaster that is to follow, and come back for the last day of trading in 2023 when Goldman expects stocks to be... unchanged.
Of course, when Goldman started turning bearish some three months ago (which just happened to coincide with that other permabull Marko Kolanovic also turning bearish), we said that that was the bottom and so far, some 400 S&P points higher, our cynicism has been proven correct.
But as so often happens, with Goldman so bearishly positioned at a time when the Fed is hinting that a rate hike pause is imminent and the market is expecting at least 50bps of rate cuts in the second half, last week saw the first tentative signs that Goldman's strategists and economists are starting to turn bullish again, which means that the countdown to a material upgrade in Goldman's year-end price target (to, say, 4,500) has begun.
Indeed, in the past week, two top Goldman strategists, Jan Hatzius and Dominic Wilson highlighted the "improving investing landscape" in two notes this week: “Mostly Better News” (available to pro subs here) and “A Bit More Room to Grow” (also available to pro subs), pointing out that after the latest payrolls and CPI data, "markets are now pricing in the soft landing for the US economy that we forecast; Europe no longer appears to headed towards a recession either (Goldman also raised its GDP growth forecast into positive territory earlier this week in "10 Questions for 2023" and no longer expects a European recession)" and Goldman even saw upside to its China growth forecast which now anticipates a 4Q23/4Q22 GDP growth pace of over 7%.
But, as Goldman strategist Chris Hussey notes in his Friday weekly recap, "just like in Legoland, this 'Everything is awesome!' environment may still be riddled with risks that our strategists and analysts also highlight this week from macro to micro."
One such risk was brought up by none other than David Kostin, who remains one of the bearish holdouts withing Goldman (not for long) and continues to sound a cautious tone in a fresh note this week, urging the bank's clients to "buy protection" in his note “strategies for soft and hard landings.” According to Kostin, the biggest red flag: downward earnings revisions have been extreme and have only looked like this in past recessions (2000 and 2008).
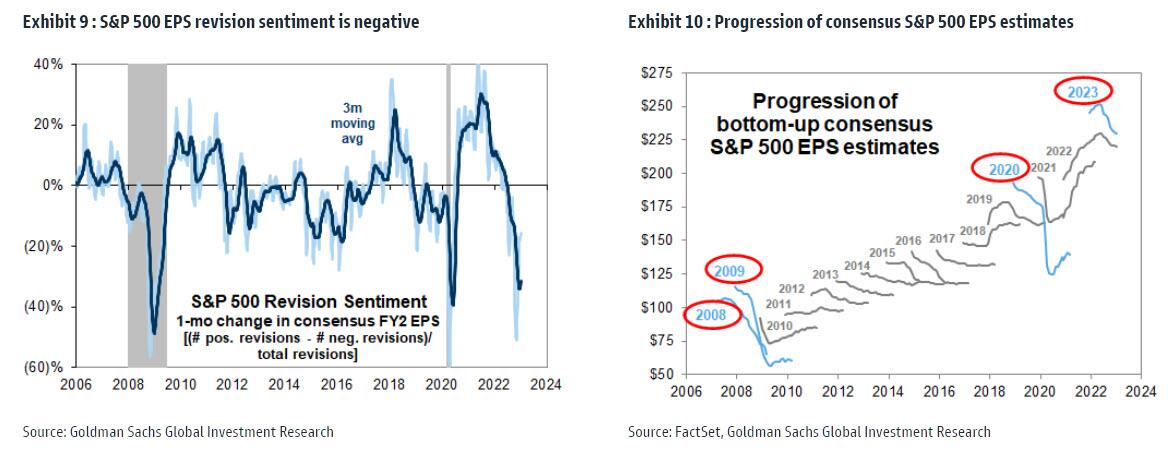
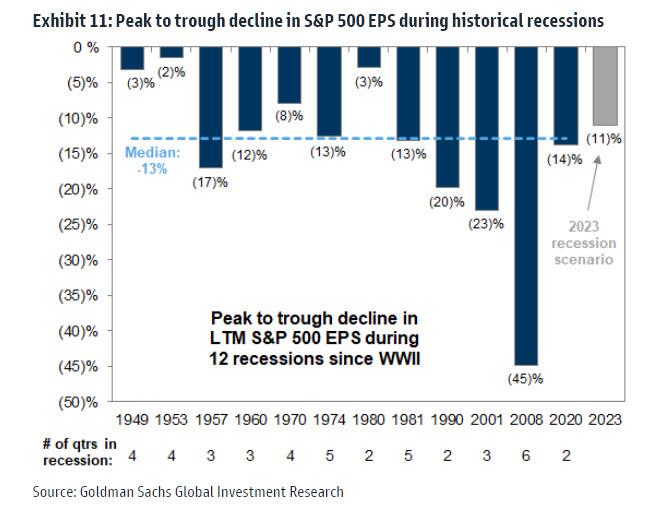
As such, Kostin is hesitant to look through this dependable market indicator and believe prudent portfolio managers should at least consider the implications if a hard landing transpires.
Over the weekend, Kostin continued this game of good cop (Hatzius, Wilson) vs bad cop (Kostin), writing in his latest weekly Kickstart note (available to pro subs here) that "negative consensus earnings revisions and analyst expectations for a lackluster 4Q 2022 earnings season continue the trend of weakening corporate profitability in recent quarters." Additionally, the S&P's trailing 4-quarter return on equity declined by 29 bp to 20.6% in 3Q 2022 driven by a contraction in margins: as Kostin calculates, "at a sector level 7 of 11 S&P 500 sectors experienced declining ROE, with Info Tech suffering the largest drop and Energy expanding the most." Looking ahead, Kostin warns that an upwards inflection in S&P 500 ROE will be difficult to achieve in 2023, "as headwinds from a higher cost of capital and higher taxes will place further strain on profitability."
Of course, this is all taking place as Q4 earnings season kicked off in earnest on Friday with large banks reporting mixed results, and with consensus expecting the aggregate S&P 500 index to post -1% EPS growth in 4Q 2022 vs. 4Q 2021 and decline by 5% excluding the Energy sector. As shown in the charts above, earnings revisions have recently been very negative, adding to many investors’ concerns about a potential recession on the horizon.
What does all of this mean for corporate profitability? Clearly, nothing good: according to Kostin, the increasingly negative consensus earnings revisions and current analyst expectations for a lackluster 4Q 2022 earnings season continue the trend of weakening corporate profitability in recent quarters. To wit, S&P 500 trailing 4-quarter return on equity declined by 29 bp to 20.6% in 3Q 2022. The decline in ROE represented the third consecutive quarterly decline following the metric’s all time high of 22% in 4Q 2021 (despite the recent declines the latest figure still ranks in the 99th percentile of S&P 500 ROE going back to 1975, meaning there is a lot more downside from here).
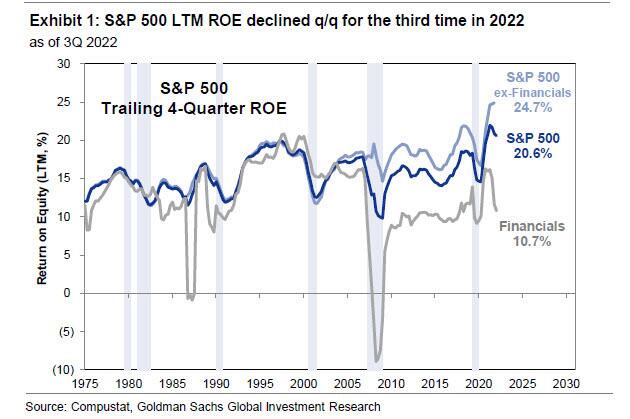
The Goldman strategist finds that contraction in profit margins was the main reason for the ROE decline last quarter: "We use a five-factor DuPont decomposition to analyze the drivers of ROE.Falling EBIT margins drove 69 bp of ROE contraction (Exhibit 2). Margins had already begun to decline in both 1Q and 2Q 2022 after a full year of expansion in 2021, and the trend continued in 3Q 2022. Index-level LTM EBIT margins contracted q/q by 48 bp in 3Q (vs. -90 bp in 2Q and -47 bp in 1Q). Slightly higher interest and tax expenses also weighed on ROE during 3Q (contributing -20 bp total). These headwinds were offset by higher asset turnover, which contributed +62 bp to ROE."
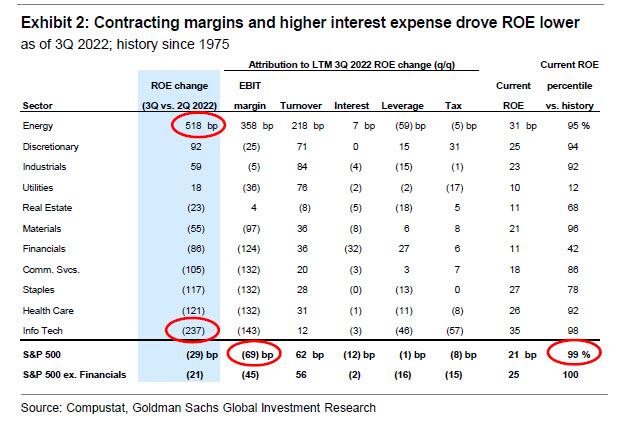
Financial jargon aside, while most sectors saw ROEs fall last quarter, they also enjoy profitability well above historical averages. 7 of 11 S&P 500 sectors experienced declining ROE, with Info Tech suffering the largest drop (-237 bp) and Energy expanding the most (+518 bp). The increase in Energy ROE was driven by margin expansion, contrasting with contracting margins in every other sector except for Real Estate. In addition to Energy, Consumer Discretionary, Industrials, and Utilities saw slight ROE gains. Despite lackluster ROE growth over the past three quarters, 9 of 11 sectors’ levels of ROE still stand above their historical sector averages, and 6 have ROEs currently in the top decile vs. their sector’s history.
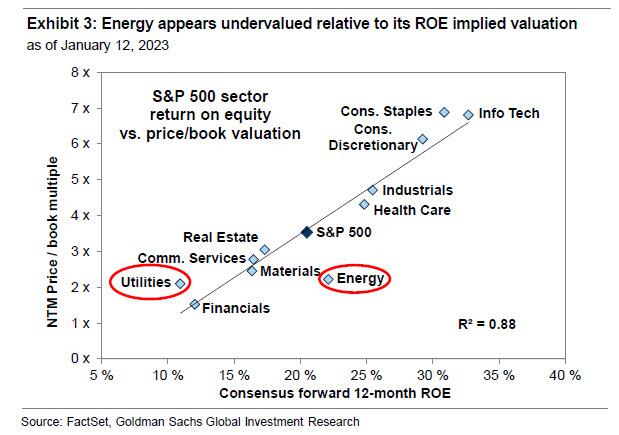
Ironically, while to some this may mean that Energy - which was the blowout outperforming segment in 2022 - is overvalued, the reality is just the opposite, and with most sector P/B valuations currently well-ordered based on ROE, Energy and Utilities remain outliers. Energy remains below the P/B implied by its expected ROE while Utilities’ valuation appears stretched. In the case of Energy, the lackluster valuation is likely due to consensus expectations for -15% EPS growth in 2023 (after +161% growth in 2022) and lower long-term growth expectations relative to other sectors. Meanwhile, utilities valuations have benefitted in part due to the attractiveness of the sector’s defensive attributes amid heightened recession concerns.
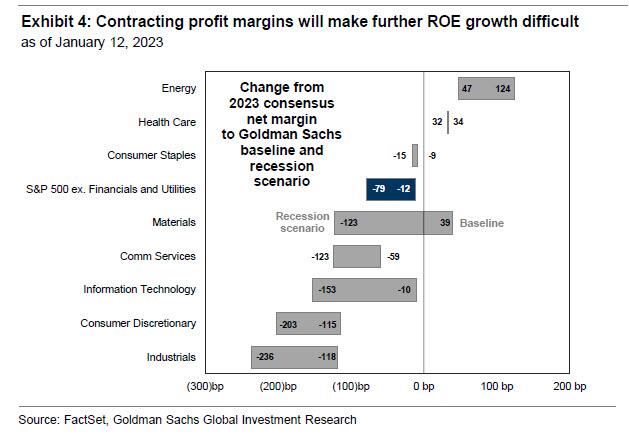
Looking ahead, the bearish Goldman strategist concedes that "an upwards inflection in S&P 500 ROE will be difficult to achieve in 2023" and he expects margins for most sectors to contract while also expecting further cut in current consensus EPS estimates to bring them closer to Goldman's baseline and recession scenarios (which is odd since Goldman chief economist Jan Hatzius is adamant that a recession will not happen, but that's all part of Goldman's "good cop, bad cop" CYA routine). As other ROE headwinds, Kostin lists taxes, leverage, and borrow costs.
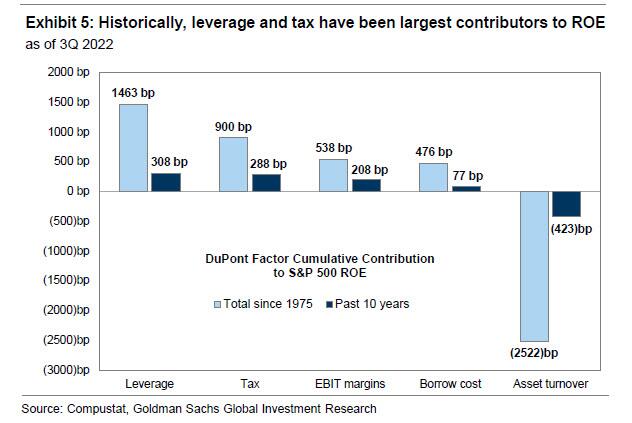
Taking a closer look at margin hurdles, Goldman notes that historically, higher leverage and lower taxes have been the largest contributors to ROE. Indeed, since 1975, declining interest rates and corporate tax rates have been the strongest tailwinds to corporate profitability. Declining interest rates have allowed firms to utilize higher leverage to bolster equity holder returns, resulting in a cumulative contribution of +1463 bp to ROE while lower borrow costs have contributed +476 bp to ROE over the period. Similarly, declining corporate tax rates have contributed +900 bp. On the other hand, lower asset turnover has been the largest detractor from ROE, shaving off -2522 bp over time.
Here, Kostin warns that "near-term improvements to ROE from higher leverage will be unlikely given higher cost of capital", i.e. the Fed's tightening. The weighted average cost of capital (WACC) for US firms has spiked by 200 bp to 6%, the highest level in a decade and the largest 12-month rise in 40 years, or since the Volcker Fed.

Goldman expects the WACC in 2023 will remain near the current level (which of course, is as good as tell as any that Powell will very soon be slashing rates). The direct consequence of a higher WACC is costlier leverage, which will ultimately disincentivize firms from boosting ROE through this channel in 2023. As an aside, despite higher WACC, borrow costs will be less of a dramatic headwind, as most S&P 500 debt is fixed rate with long maturities. 75% of S&P 500 debt is fixed, and only 24% of total debt is expected to mature between 2023 and 2025.
Finally, Goldman warns that higher taxes in 2023 will also be a headwind for ROE expansion. While new corporate taxes from the Inflation Reduction Act (IRA) should reduce S&P 500 EPS by less than 2% in 2023, the direction of the change in tax expense will now weigh on ROE instead of supporting it.
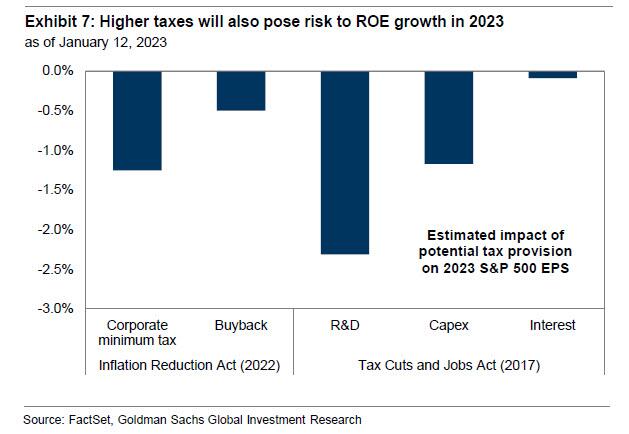
According to the Goldman strategist, This impact should be pronounced for sectors with low effective tax rates such as Info Tech and Health Care which will face a larger impact from minimum tax provisions. Sunsetting provisions from the 2017 Tax Cuts and Jobs Act and the new 1% excise tax on buybacks introduced in the IRA will place additional tax-related strain on ROE.
Of course, none of what Kostin claims above is incorrect (he goes on to note that in a challenging environment for ROE growth, stocks that were expected to grow ROE outperformed the S&P 500 by 10 pp in 2022 and then pitches Goldman's ROE growth basket which contains 50 stocks with the highest consensus-expected ROE growth during the next 12 months, the full list available to pro subs) but what we find most notable is that now that even Goldman fully embraces the core pillar of the 2023 bear case (as laid out by Michael Wilson some 6 months ago), the reality is that while sellside analysts may be slow to trim their optimistic outlooks, most on Wall Street have applied their own personal discounts to consensus, and more importantly, the margin contraction and EPS shrinkage narratives are both fully priced in by now, and only a full-blown recession can lead to further downward repricings. In other words, now that a sharp slide in inflation is the base case, the longer the Biden Dept of Labor ignores reality and pretends that job growth is there, the higher stocks will rise.