>>> Weekend Papers Summary

Weekend Papers Summary

NEW YORK TIMES
-No end in sight to war in Ukraine. Russia, Ukraine and the West face daunting challenges in moving forward, with no clear sense of what an attainable victory might look like.
-Protests and defiance mark a year of Russia’s war on Ukraine. On the anniversary of the invasion, President Volodymyr Zelensky vowed victory if Ukraine and its allies remained united “as one strong fist.”
-Biden reaffirms support for Ukraine amid concerns about Russia-Iran ties. The Biden administration announced new measures targeting Moscow and supporters of President Vladimir V. Putin’s war.
-Rare and dangerous: Southern California faces blizzard conditions. snow, high winds and intense rain hit parts of the state Friday. Blizzard warnings were in effect until Saturday afternoon in four counties.
-Nearly 600,000 still without power in Michigan after snowstorm. Customers in the Upper Midwest were in the dark on Friday evening after snow and ice hit the region this week, resulting in one death.
-Murdaugh hammered by prosecutor over where he was on night of killings. The intense cross-examination of Mr. Murdaugh, who is charged with killing his wife and son, came as he concluded his testimony in his own defense.
-12 States Sue FDA, Seeking Removal of Special Restrictions on Abortion Pill. The suit argues that rules applying to mifepristone unnecessarily limit patients’ access to medication abortion.
-Vice CEO’s departure signals fallen hopes for digital media. Nancy Dubuc is leaving the media company, which is exploring a sale of some or all of the business, after nearly five years there.
-In town where train derailed, lawyers are signing up clients in droves. Attorneys have poured into East Palestine, Ohio, filing more than a dozen lawsuits so far on behalf of residents.
-Canada saw a deadly derailment. A decade later, little has changed. In 2013, a train loaded with oil jumped the tracks in Quebec, killing 47 people. But despite repeated calls for an inquiry, none was ever convened.
-Doctor describes and denounces CIA practice of ‘rectal feeding’ of prisoners. In a hearing at Guantánamo Bay, an expert gave a graphic public depiction of torture after the Sept. 11, 2001, terror attacks.
-Cambodia investigates after father and daughter infected with bird flu. Two family members were infected with H5N1; the daughter died. Eleven contacts, some with symptoms, have tested negative, according to the WHO.

THE FINANCIAL TIMES
-US President Joe Biden has said he did not think China would send weapons to Russia to help its military campaign in Ukraine, in comments that appeared to undercut claims from his top officials that Beijing was considering the idea.
-Stephen Schwarzman, the founder of Blackstone Group, received record income of nearly $1.3B in 2022, as assets under management and profits rose at the world’s largest private equity firm.
-Shell, ExxonMobil and the Dutch government earned €429B from exploiting the Groningen gasfield, but left thousands of residents with cracked homes and health issues, a parliamentary investigation has found.
The geological destabilization caused by drilling at Groningen, Europe’s largest natural gas reserve, resulted in 1,594 earthquakes and damaged more than 85,000 buildings, a Dutch parliamentary report concluded on Friday.
-Trafigura failed to require analysis certificates, ignored incorrect customs codes and missed other “red flags” that alarmed its bankers on nickel shipments it later discovered to be fraudulent, according to court documents obtained by the Financial Times on Friday.
-UK Prime Minister Rishi Sunak is already in a precarious position: the Conservatives trail the Labour opposition by about 20 points in the polls, his party is fractious, his two predecessors, Boris Johnson and Liz Truss, are agitating in the wings, and a general election must be called by the end of next year.
-When the US drugs company Abbott Laboratories acquired a small division of the German chemicals group BASF for $6.9B 23 years ago, its shares fell on fears that it had overpaid. But the deal was an amazing bargain. Humira, the promising medicine that came with it, is now the industry’s biggest blockbuster, with cumulative revenues of more than $200B. The anti-inflammatory drug used to treat rheumatoid arthritis and a range of other autoimmune conditions, is very expensive, costing more than $80,000 a year per patient in the US.
-Nigerians will on Saturday go to the polls to elect their next president, marking the end of a draining election campaign notable for the emergence of a credible alternative to the country’s two dominant political parties. The main candidates have spent five months crisscrossing Africa’s largest democracy as voters prepare to elect a replacement for President Muhammadu Buhari, who is standing down after eight years in power.
-Penguin Random House has announced that it will publish the original versions of Roald Dahl’s books alongside updated editions following an outcry over changes to the celebrated stories that were branded “absurd censorship”. Puffin, an imprint of Penguin Random House, was accused of censoring the classic children’s books after its “Roald Dahl books for young readers” edition was edited to rewrite or remove language deemed offensive, such as descriptions of obesity.
-Bosses at Europe’s largest companies received “surprisingly high” bonus levels for meeting goals to cut carbon emissions in 2022, easily achieving their targets despite inadequate progress on global warming, the latest executive pay expert report finds.
More than three-quarters of Europe’s 50 largest companies now include some form of carbon target in their executive pay packages, a new report from PwC and the London Business School said.
-The US will make “no apologies” for prioritizing American jobs in its push to lead the global clean energy contest, the White House official responsible for the $369B green funding drive has said. In an interview with the Financial Times, John Podesta, Joe Biden’s senior clean energy adviser, pushed back at criticism that the US Inflation Reduction Act would divert investment and undermine the EU economy. He argued allies who have hit out at the IRA should “welcome US leadership”.

NY POST
-As he prepared to board Marine One for a weekend getaway to Delaware on Friday, President Biden told reporters that he has no plans to visit East Palestine, Ohio — and that he hasn’t been invited amid rancor over the administration’s handling of the toxic train derailment. “At this moment, no,” Biden, 80, responded outside the White House when asked if he had any plans to visit the town near the Ohio-Pennsylvania border, where dangerous chemicals spilled onto the ground and toxic smoke billowed into the air after a Norfolk Southern train derailed on Feb. 3.
The toxic spill and ensuing fire forced the evacuation of roughly 5,000 panicked residents. Tens of thousands of animals in the area have also reportedly died in the weeks after the derailment, troubling residents.
-Meta Platforms said Friday it was releasing a new large language model based on artificial intelligence aimed at the research community, becoming the latest company to join the AI race.
The battle to dominate the AI technology space, which until recently existed in the background, kicked off late last year with the launch of Microsoft-backed OpenAI’s ChatGPT and prompted tech heavyweights from Alphabet to China’s Baidu to create their own offerings.
Barron’s : BATS Its Stock Could Soar 25%.

British American Tobacco BATS +1.02% is a sleeping giant of the United Kingdom stock market that may be about to wake up.

The U.K.’s FTSE 100UKX –0.37% Index is trading at record highs, closing above 8,000 points for the first time in its history earlier this month. British American Tobacco’s (ticker: BATS.UK) total return of 6,891% since the index launched in 1984 is the largest of any original constituent company, according to FTSE Russell data.

The stock has blown hot and cold in recent years, though. Shares are down 30% over five years—but that might be about to change. The company is building an impressive portfolio of alternatives to cigarettes, while a pending regulatory decision over its Vuse Alto vaping product could provide a near-term catalyst.

Another big reason to hold the stock amid these uncertain macroeconomic times: the company’s attractive 7.4% dividend yield. Quarterly dividends are also paid to holders of BAT’s American depositary shares (BTI).

BAT owns cigarette brands including Camel, Lucky Strike, Pall Mall, and Dunhill as well a range of vapor and heated tobacco products. The London-listed company, founded in 1902, has more than 52,000 employees worldwide and operates across more than 180 countries.

There were plenty of positives to take from the tobacco giant’s full-year earnings earlier in February, despite declining cigarette volumes in the U.S. The company said it expects its “new category” segment—which includes vapor, heated tobacco, and oral tobacco products—to be profitable in 2024, a year ahead of schedule. The unit is also on track to meet BAT’s target of five billion pounds sterling ($6 billion) in revenue by 2025.


But the share price reaction was negative, which Deutsche Bank analyst Gerry Gallagher attributed to the lack of a stock-buyback announcement. BAT said the board has decided to take a “pragmatic approach” to prioritize strengthening its balance sheet.

The market was expecting a buyback of £1 billion to £2 billion, Gallagher said. He noted the positive commentary around new-category revenue and said the bank’s analysts remain “committed buyers” of the shares. He has a £40 price target on the stock, 26% above Wednesday’s close.

Revenue and earnings look set for solid growth in the coming years. The tobacco giant reported revenue of £27.7 billion in 2022, and analysts expect that to rise to £28.8 billion this year and £30 billion in 2024. Profit is estimated to rise from 371.4 pence a share last year to 392.3 pence in 2023 and 417.5 pence next year. BAT’s Vuse vapor brand is one of its trump cards. The company said in 2022 that it had become the market leader in the U.S., the world’s largest vapor market.


But Vuse is also holding the stock back. Vuse Alto is pending market authorization from the U.S. Food and Drug Administration. New legislation passed in March 2022 requires companies to submit a premarket tobacco-product application, or PMTA, to keep vaping products on the market.

Two other Vuse products—Vibe and Ciro—were authorized last year, but their menthol variants were denied last month. If Vuse Alto gets the green light from regulators, it could be a significant catalyst for the stock. While there is uncertainty about U.S. cigarette demand and the Vuse Alto regulatory decision, the current valuation incorporates “much of those downside risks,” says J.P. Morgan analyst Jared Dinges.

The stock is cheap, trading at 7.5 times estimated 2024 earnings, compared with the industry average of 9.93, according to FactSet.

BAT has an appealing dividend yield amid tough economic conditions, and at best there’s plenty of upside ahead, if investors can see through the smoke.

>>> Weekly Market Update

Weekly Market Update: More stubborn inflation data and Russia bear swat markets

US investors returned to a holiday shortened trading week with geopolitics back in focus. President’s Biden’s surprise trip to Kyiv ushered in a string of headlines from both sides in the lead up to the one-year anniversary of Russia’s invasion of Ukraine. Ultimately, new rounds of sanctions, tariffs, and aid were introduced by the West, even as high-level Chinese officials visited Moscow, sparking speculation about Beijing’s designs on acting as either a peace broker or arms broker in the conflict.

Stock markets continued to encounter resistance in the form of rising interest rates. The economic data and central bankers’ signaling remained supportive of the higher-for-longer narrative that has gained traction as investors have had to adjust to the stronger than expected January data. That theme culminated on Friday when the S&P fell to roughly a 1-month low after hotter than expected January PCE data spooked the market. The month over month core PCE reading of 0.6% was the largest monthly rise since August. Moreover, it got a boost from the category that Chair Powell has highlighted recently: core non-housing service prices. That sub-index also rose by nearly 0.6%, which was its largest gain since November 2021, illustrating this very large component of core inflation is not yet showing any real signs of deceleration. After that data, the US 2-year yield climbed above 4.8% and futures markets began to price in the terminal fed funds rate to exceed 5.4% later this year. The Dollar firmed up to the best levels in roughly two months while commodities and risk assets in general weakened into the end of the week. For the week, the S&P lost 2.7%, the DJIA was off 3%, and the Nasdaq fell 3.3%.

Growth and inflation tensions played out in corporate news this week. Discount retailer Dollar General, which usually flourishes during recession, announced it is cutting quarterly guidance, citing bad winter weather. Walmart beat analyst expectations handily, noting that the big box retailer is managing to contain capex costs and attracting more higher-end customers looking for bargains. Home Depot’s numbers were shakier, reporting a 6% decline in customer transactions and guiding a decline in earnings for the year, perhaps signaling more weakness in the housing market. Contrary to that, homebuilder Toll Brothers reported strong quarterly results and affirmed guidance, noting that it is seeing an uptick in demand continuing as recently as last weekend. In the tech world, Cybersecurity firm Palo Alto reported strong quarterly results and gave solid guidance, sending share higher. Intel continued to flounder, cutting its dividend by two thirds, though affirming its guidance. Adobe shares fell to their lowest levels of 2023 after reports emerged that the DOJ is preparing a suit to block its $20B acquisition of Figma.


MON 2/20
(TW) Taiwan Jan Export Orders Y/Y: -19.3% v -24.0%e; Sees Feb orders down between -10.8% and -6.9% y/y
(HK) Macau Jan tourist arrivals at 1.4M, +101.3% y/y
(US) US Pres Biden: Ukraine will get new military aid package worth $500M to be announced on Feb 21st; Will include HIMARS ammunition - statement from Kyiv
(NL) Dutch intelligence agency official: Russia tried to gain intelligence to sabotage critical infrastructure in the Dutch part of the North Sea; Russia may target Netherlands' offshore infrastructure - press
(TR) Magnitude 6.4 earthquake strikes Turkey-Syria border region

TUES 2/21
(FR) FRANCE FEB PRELIMINARY MANUFACTURING PMI: 47.9 V 51.0E (moves back into contraction); Composite PMI highest since July 2022
TSM Reportedly considers to delay its Europe fab by two years to 2025 amid automotive chip shortage is no longer as severe as it was – press
(JP) Japan Cabinet Office (Govt) Feb Monthly Report: Maintains overall economic assessment
(RU) Russia Pres Putin: We are in difficult times, prior to historical events; We will decide tasks of special military operation step by step; Vows to continue military operation in Ukraine - Federal Council address
(UK) FEB PRELIMINARY MANUFACTURING PMI: 49.2 V 47.5E (7th straight contraction); Composite PMI highest since June 2022
(DE) GERMANY FEB ZEW CURRENT SITUATION SURVEY: -45.1 V -50.5E; EXPECTATIONS SURVEY: 28.1 V 23.0E
(RU) Russia Pres Putin: Russia suspends participation in START nuclear arms treaty [**Note: inspections had been halted since 2020]; We suspend participation, not withdrawing from this; Will not allow NATO to inspect our nuclear objects - Federal Council address
HUN Reports Q4 $0.04 v $0.11e, Rev $1.65B v $1.56Be; Optimistic that destocking will end in H1 2023; Notes seeing some green shoots in areas like China, automotive, and aerospace, but construction demand globally is still under pressure
GIS Raises FY23 outlook; Continues to expect to deliver top-tier shareholder returns
HD Reports Q4 $3.30 v $3.27e, Rev $35.8B v $35.9Be; Raises Quarterly dividend 10% to $2.09 from $1.90 (indicated yield 2.63%); Announces $1B investment in associates
WMT Reports Q4 $1.71 v $1.52e, Rev $164.1B v $159.7Be; Guides FY24 EPS short of consensus; Raises Quarterly dividend 1.8% to $0.57 from $0.56 (indicated yield 1.56%)
(US) Feb Philadelphia Fed Non-Manufacturing Regional Index: +3.2 v -6.5 prior
(US) FEB PRELIMINARY S&P/MARKIT MANUFACTURING PMI: 47.8 V 47.4E (5th month of contraction); Services moves into expansion territory
(NZ) Fonterra Global Dairy Trade Auction Dairy Trade price index: -1.5% v +3.2% prior
(RU) Reportedly China's Xi to travel to Moscow in the spring; Xi expected to push Putin for peace talks with Ukraine – press
(EU) ECB chief Lagarde: Seeing no EU country in recession in 2023
(US) FERC grants Freeport LNG request to commission including cooldown of liquefaction Train 2 – filing
PANW Reports Q2 $1.05 v $0.78e, Rev $1.66B v $1.65Be

WED 2/22
RIO.AU Reports FY22 underlying Net $13.3B v14.0Be, underlying EBITDA $26.3B v $37.7B y/y, Rev $55.6B v $63.5B y/y
BN.FR Reports FY22 Net €959M v €1.92B y/y, Recurring Op €3.38B v €3.35Be, Rev €27.7B v €27.4Be
(JP) Semiconductor Equipment Association of Japan (SEAJ) Jan Chip-making Equipment Y/Y: -2.1% v +1.1% prior
STLA Reports FY22 adj Op €23.3B v €21.5Be, Rev €179.6B v €176.1Be; Plans up to €1.5B share buyback through 2023; Notes slow but steady improvement in chip supplies
(CN) China said to urge the State-run companies to drop the big four international auditors and use local ones citing data risk – press
7267.JP Said to raise wages by 5% (biggest increase in 30 years) - press
BIDU Reports Q4 (CNY) 16.87 v 13.90e, Rev 33.1B v 32.1Be; Announces $5B share buyback (10% of market cap) through Dec 2025; Plans to integrate Ernie bot into a number of Baidu's businesses
(US) Fed’s Bullard (Non-Voter): I think markets have overpriced a recession in 2023; US economy is stronger than what we previously thought which adds up to markets needing to price in tougher road for inflation and rates – CNBC
INTC Cuts Quarterly dividend 65.8% to $0.125 from $0.365 (indicated yield 1.92%); Affirms Q1 -$0.15 v -$0.15e, Adj Rev $10.5-11.5B v $11.1Be
(RU) Russia Foreign Ministry: We appreciate China's balanced position on Ukraine issue; "Vision" very much the same between us
TOL Exec: Uptick in demand continued through last weekend - post earnings comments
(RU) Russia said to cut crude exports from western ports by 25% in March versus Feb – pres
(US) FEB FOMC FEB MINUTES: ALL PARTICIPANTS AGREED MORE RATE HIKES NEEDED TO ACHIEVE JOB AND INFLATION OBJECTIVES; A FEW CALLED FOR A 50 BPS HIKE
(US) US said to consider releasing intelligence related to China potentially transferring arms to Russia - US financial press
(KR) BANK OF KOREA (BOK) LEAVES 7-DAY REPO RATE UNCHANGED AT 3.50%; AS EXPECTED

THRS 2/23
ENI.IT Reports Q4 adj Net €2.5B v €2.1B y/y, adj Op €3.59B v €3.81B y/y, Rev €31.3B v €26.8B y/y
(RU) Reportedly Russia Pres Putin has already gamed out the possibility of using a nuclear weapon in Ukraine; Putin’s calculation implies that Russia is more committed to the Ukraine war than the West - FT
(EU) NATO Sec Gen Stoltenberg: See signs China is considering giving arms to Russia; Closely monitoring Russia on their nuclear weapons
TSM Reportedly TSMC's 5nm demand has suddenly increased recently as urgent orders came from NVIDIA, AMD and Apple, mainly for AI and server chips - DigiTimes
(EU) EURO ZONE JAN FINAL CPI Y/Y: 8.6% V 8.6%E; CPI CORE Y/Y: 5.3% V 5.2%E (record high)
(CN) Reportedly Citic Group Chairman Zhu Hexin is is the leading candidate for PBOC Gov post; China said to be preparing to shake up leadership of its financial system - US financial press
BABA Reports Q3 $2.79 v $2.29e, Rev $35.9B v $35.5Be; Expects continued recovery in consumer sentiment, economic activity
BRE Reports Q4 $1.33 v $1.19e, Rev $8.19B v $8.13Be
DG Cuts Q4 $2.91-2.96 (prior $3.15-3.30) citing lower-than-anticipated sales and higher-than-anticipated inventory damages; Notes Nov and Jan SSS were as expected, Dec SSS lower than expected as a result of the storm Elliott
HUM Raises FY23 individual Medicare Advantage products at least 775K (prior at least 625K) citing continued higher than anticipated sales volumes and favorable member retention early in 2023; Affirms FY23 >$28.00 v $28.02e
(US) INITIAL JOBLESS CLAIMS: 192K V 200KE; CONTINUING CLAIMS: 1.65M V 1.70ME
(US) Q4 PRELIMINARY GDP ANNUALIZED Q/Q: 2.7% V 2.9%E; PERSONAL CONSUMPTION: 1.4% V 2.0%E
(US) Q4 PRELIMINARY GDP PRICE INDEX: 3.9% V 3.5%E; CORE PCE Q/Q: 4.3% V 3.9%E
(US) DOE CRUDE: +7.7M V +2ME; GASOLINE: -1.9M V +0.5ME; DISTILLATE: +2.7M V -0.5ME
(CN) Reportedly China and Russia negotiating the purchase of 100 strike drones, which could be delivered as soon as Apr 2023 - German press
INTU Reports Q2 $2.20 v $1.43e, Rev $3.0B v $2.90Be
SQ Reports Q4 $0.22 v $0.27e, Rev $4.65B v $4.53Be
SQ Jan-Feb 2023 Combined Gross Profit +25% y/y - shareholder letter
(JP) JAPAN JAN NATIONAL CPI Y/Y: 4.3% V 4.3%E; CPI EX-FRESH FOOD (CORE) Y/Y: 4.2% V 4.3%E (highest annual pace in 41 years)
(JP) BOJ GOV NOMINEE UEDA: Reiterates current monetary easing is appropriate; it takes time to achieve sustainable inflation (2% target) - Parliament testimony
(CN) China Ministry of Foreign Affairs (MOFA) releases proposal related to Ukraine; Calls for ceasefire and resuming peace talks; Calls for respecting the sovereignty of all countries; Dialogue and negotiation are the only viable solution to the Ukraine crisis

FRI 2/24
BAS.DE Reports final Q4 €0.09 v €0.30e, adj EBIT €373M v €420.2Me, Rev €19.3B v €20.1Be; Plans to eliminate 2.6K jobs in cost cutting initiative (2% of global workforce); To close one of two ammonia plants in Ludwigshafen
(US) US HIKING TARIFFS ON OVER 100 RUSSIA METALS, MINERALS AND CHEMICALS WORTH $2.8B; CONFIRMS NEW SANCTIONS AGAINST RUSSIA; ALSO TO SANCTION SOME THIRD-COUNTRY FIRMS, INCLUDING IN CHINA AND EUROPE – PRESS
WAF.DE Reports prelim Q1 Rev -15% q/q citing expected inventory adjustments for the next quarters and short-term postponement of delivery volumes of some customers in H1 2023
ERICB.SE Reportedly to cut 8.5K workers globally (~8% of total) – press
GM Spokesperson: Confirms GM to halt production at its Fort Wayne Truck Assembly plant in Indiana from Mar 27th for two weeks, citing DSO inventory bloat (**Note: 2nd time in 1 year) - press
(US) JAN PERSONAL INCOME: 0.6% V 1.0%E; PERSONAL SPENDING: 1.8% V 1.4%E
(US) JAN PCE DEFLATOR M/M: 0.6% V 0.5%E; Y/Y: 5.4% V 5.0%E (1st acceleration in annual pace in 7 months)
(US) FEB FINAL UNIVERSITY OF MICHIGAN CONFIDENCE: 67.0 V 66.4E
(US) Fed’s Bullard (Non-Voter): Soft landing is feasible; Expect inflation to come under control in quarters and years ahead
(US) Atlanta Fed GDPNow: Raises Q1 GDP from 2.5% to 2.7%

>>> TradeGate Pre-Market Inidcations

DAX:
  • Fresenius SE (FRE TH) +0.8%
  • RWE (RWE TH) +0.7%
  • Deutsche Bank (DBK TH) -0.4%
    • Deutsche Bank Criticized by ECB Over Derivatives Probe, FT Says
MDAX:
  • Rheinmetall (RHM TH) +2%
  • Siltronic (WAF TH) +1.1%
  • Puma (PUM TH) +0.9%
  • Delivery Hero (DHER TH) +0.8%
  • TAG Immobilien (TEG TH) +0.8%
SDAX:
  • Grand City Properties (GYC TH) +1.8%
  • Traton (8TRA TH) +1.8%
  • Hensoldt (HAG TH) +1.7%
  • Ceconomy (CEC TH) +1.2%
  • Heidelberger Druck (HDD TH) -0.8%
  • SUSE (SUSE TH) -1%
  • Bilfinger (GBF TH) -1.1%

>>> Europe : Brokers Upgrades & Downgrades - 20th of February 2023

>>> Up
* Alpha Services Raised to Buy at Citi; PT 1.60 euros
* CVC INCOME & GROWTH LIMI Raised to Positive at Stifel
* Danske Bank Raised to Outperform at KBW; PT 205 kroner
* Novozymes Raised to Neutral at Credit Suisse
* Orsted Raised to Buy at Jefferies; PT 800 kroner
* Palfinger Raised to Buy at Hauck & Aufhaeuser; PT 36 euros
* Sampo Raised to Buy at HSBC; PT 53 euros
* Storskogen Raised to Neutral at JPMorgan; PT 11 kronor

>>> Down
* Demant Cut to Hold at HSBC; PT 215 kroner
* Fortnox Cut to Hold at SEB Equities; PT 60 kronor
* Handelsbanken Cut to Underperform at KBW; PT 120 kronor
* Lemonsoft Cut to Reduce at Inderes; PT 8.80 euros
* Raiffeisen Cut to Neutral at Exane
* SEB Cut to Underperform at KBW; PT 145 kronor
* Spectris Cut to Hold at Berenberg; PT 3,470 pence
* Telefonica Cut to Hold at Deutsche Bank; PT 5 euros

>>> Initiation
* AIB Group Rated New Outperform at Credit Suisse; PT 4.80 euros
* Bank of Ireland Rated New Outperform at Credit Suisse
* Medica Rated New Buy at Panmure Gordon; PT 187 pence

>>> Call
* Citi’s Buckland Expects Contrarian Stock Trades to Fizzle Out
* Credit Suisse Bullish on Irish Banks on ‘Unique’ Opportunity
* Gas Crisis Underpins Vestas, Nordex, SMA Solar and Peers' Growth
* Orsted Raised to Buy at Jefferies as Risk/Reward Starts to Shift
* Spectris Cut to Hold, Oxford Instruments Preferred at Berenberg

>>> What to look at today - 20th of February 2023 (US Closed for President Day)

Stocks in Asia edged higher and the dollar was little changed as investors weighed hawkish comments from Federal Reserve officials and geopolitical tensions. A gauge of Asian stocks climbed, while US futures pared losses following a decline in the S&P 500 Index on Friday as it slid for a second week.  A report from Goldman Sachs Group Inc. tipping a rebound in Chinese stocks added something of a counterweight to the flow of news damping appetite for equities. Separately, Chinese lenders followed the central bank by keeping their benchmark lending rates unchanged Monday, with analysts expecting possible reductions in coming months to support the economic recovery. The dollar advanced versus most of its Group-of-10 peers following a weekend that saw no cooling of US-China tensions.  investors are focused on the shifting outlook for interest rates, with traders fully pricing in quarter-point interest rate increases at the Fed’s next two meetings after policy makers said Thursday that bigger hikes were not out of the question.  The moves in currencies and bonds around Asia on Monday were modest, in part reflecting the Presidents’ Day holiday in the US. There was no cash Treasuries trading Monday. Looking further ahead this week, investors will also be watching for more commentary on the American consumers as Walmart Inc. and Home Depot Inc. kick off a slew of retail earnings reports. Further signs of resilient economy could provide more reasons for the Fed to hold rates higher for longer. Morgan Stanley equity strategist Michael Wilson warned that even though economic situation appeared to have improved at the margin, with additional liquidity provided by central banks, it would not forestall an earnings recession. “The bear market rally that began in October from reasonable prices and low expectations has morphed into a speculative frenzy based on a Fed pause/pivot that isn’t coming,” he wrote in a note. In commodities, oil climbed after capping its longest string of daily losses on the year last week. Rising US oil inventories and the prospect of further tightening by the Fed last week eclipsed the lift from signs that Chinese energy demand is improving. Gold slid.

Nikkei +0,07% Hang Seng +0,92% CSI +2,09% Shanghai +1,78% Shenzen +1,41%

Eur$ 1,0688 CNH 6,8717 CNY 6,8654 JPY 134,15 GBP 1,2035 CHF 0,9245 RUB 74,1150 TRY 18,8626 WTI$ 76,77 Gold 1,844 BTC 24,456 -0,40% ETH 1,687

S&P +0,02% Nasdaq +0,09% EuroStoxx +0,35% FTSE +0,42% Dax +0,32% SMI +0,28%

Macro :
- Fed QE Legacy Means Traders Underestimate Rate Path: Macro View
- Citi’s Buckland Expects Contrarian Stock Trades to Fizzle Out
- US-China Meeting Only Worsens Tensions Over Balloon, Russia
- Aluminum Gains as China Cuts Capacity Due to Energy Shortages
- Iran Nuclear Inspectors Find Uranium Enriched to 84% Purity

Keep an eye on :
- ADJ GY : Adler Group Amends Terms With Bondholder Group on Restructuring
- ALM SM : Almirall Sees 2023 Ebitda EU165M to EU180M
- BSGR NA : B&S CEO Tako de Haan Resigns; Company Delays FY Results
- COL SM : *COLONIAL WEIGHS SELLING IBM OFFICES IN MADRID: EL CONFIDENCIAL
- EDF FP : EDF Says Price Tag of UK Nuclear Power Plant Soars on Inflation
- EO FP : Faurecia to Sell ‘SAS’ Cockpit Modules Unit to Motherson Group
- EO FP : Faurecia FY Ebitda Beats Estimates, UPGRADES COST, SALES SYNERGIES FROM HELLA ACQUISITION
- FWONA US : Formula 1 Will Never Go Electric, CEO Tells Italian Newspaper
- FUR NA : Fugro Secures Offshore Wind Program on US East Coast
- GREEN BB : Greenyard 3Q Revenue EU1.11B Vs. EU1.04B Y/y
- RMS FP : If Consumers Are Saviors, Upcoming Retail Earnings Will Show It
- HRGI NO : Horisont Energi, Neptune Energy, EON Sign CCS Value Chain MoU
- ICAD FP : ICADE FY Group Net Current Cash Flow per Share Beats Estimates
- KUD SW : Kudelski Group Sells DVNor Assets to Pixlo of Sweden; No Terms
- META US : Meta's Subscription Pivot Aimed at Creators, Retention: React
- MRW LN : Morrisons to Make Price Cuts Worth £25 Million to Help Shoppers
- NOVN SW : Novartis Designates Firmenich CEO Ghostine Chairman of Sandoz
- REJLB SS : Rejlers to Buy Eurocon Consulting in Cash for SEK10.75 per Share
- RNO FP : Renault’s Alpine Seeking Women Drivers for its Formula 1 Team
- SAF FP : Safran Sees 50% Jump in 2023 Aircraft Engine Deliveries: Echos
- SHUR BB : Shurgard FY Net Operating Income EU219.2M Vs. EU194.4M Y/y
- STAN LN : StanChart HK Plans to Hire Up to 500 Staff This Year, SCMP Says
- SUN SW : Sulzer FY Ebit Misses Estimates
- TIT IM : CDP’s Telecom Italia Bid May Need Competition Fixes, Report Says
- TSCO LN : Sky News: Supermarket giant Tesco to explore sale of banking arm
- VLA FP : Valneva Says FDA Accepts Chikungunya Jab for Priority Review

CrunchBase : The Week’s 10 Biggest Funding Rounds: Dreamscape and SandboxAQ See

The Week’s 10 Biggest Funding Rounds: Dreamscape and SandboxAQ See Monster Raises

Huge rounds were the theme of the week, as we saw six rounds of $100 million or more — including two of a half-billion dollars or more. What’s interesting is all the rounds came from different sectors — although one could argue two were in cybersecurity. While AI is dominating the headlines, investors placed bets in several other areas too this week.

1. Dreamscape, $850M, real estate: One of the difficult aspects of creating this list is trying to figure out what is debt and what is actually growth equity in many of these larger rounds. (This will come up again further down the list.) New York-based Dreamscape, a real estate development and investment firm, completed an $850 million capital raise this week. However, it’s unclear what was debt and what was equity. We do know Wells Fargo led the debt syndicate and Raymond James led the equity private placement, but that’s about it. We don’t know how much of that $850 million was equity. Regardless, it is a big raise. The firm will use the proceeds to create two new platforms: Dreamscape Entertainment Properties and Dreamscape Entertainment Integrated Resorts, both involving gaming, hospitality and entertainment.

2. SandboxAQ, $500M, AI: Nearly a year after spinning out of tech giant Alphabet, AI and quantum computing startup SandboxAQ finally announced more funding details this week, saying it had raised a $500 million round. SandboxAQ is examining the related effects of both AI and quantum — which is where the company gets “AQ” — to develop commercial products for telecom, financial services, health care, security and other computationally intensive sectors. One aspect of security the startup is looking at is how companies and the government can replace current public-key cryptography algorithms with algorithms that are resistant to quantum computer-based attacks. Quantum computing is a level of compute much faster and at a level superior to classical computers that examines quantum states to perform computation. Investors named included Breyer Capital, former Google CEO Eric Schmidt, Thomas Tull, First Light Capital Group, funds and accounts advised by T. Rowe Price Associates, Guggenheim Investments, Time Ventures, Section 32, Parkway Venture Capital and other funds and investors.

3. Deepwatch, $180M, cybersecurity: Cybersecurity funding has proven resilient, even in this down market. Managed detection and response company Deepwatch is the latest in the sector to close a big round — locking in a $180 million round of “equity investments and strategic financing.” The financing comes from a handful of investors, including Vista Credit Partners — Vista Equity Partners’ “credit-investing strategy offering flexible, customized debt and structured equity financing,” per its website. However, the company declined to offer a breakdown of the round pertaining to equity investment and debt/credit. The Tampa, Florida-based startup reported 100% sales growth in 2022 while announcing the funding. Founded in 2019, the company has now raised $256 million, per Crunchbase.

4. Juniper Square, $133M, financial services: Ever wonder how GPs and LPs communicate? Well, one way is through San Francisco-based Juniper Square’s platform, which allows GPs and LPs to connect and manage their partnerships. The company announced a $133 million growth capital round this week led by Owl Rock. According to the company, more than 1,800 GPs use Juniper Square to help support more than 32,000 investment partnerships and $700 billion in LP capital. Founded in 2014, the company has raised $241 million in funding, according to Crunchbase.

5. Via, $110M, transportation: Nearly everyone has changed the way they travel and commute in the last several years. New York-based transit company Via locked up a $110 million round to help cities and agencies better traverse that changing landscape of transportation. The new round values the company at $3.5 billion and was led by 83North. The company ended 2022 with an annualized revenue run-rate of over $200 million, more than doubling since the previous financing round — a $130 million Series G in November 2021. Via plans to use the money to further expand its line of products that help cities and transit agencies improve the efficiency of their transportation systems. Founded in 2012, Via has now raised around $900 million, per Crunchbase.

6. R-Zero, $105M, biotech: Salt Lake City-based biosafety technology startup R-Zero closed a $105 million funding round led by the global investment firm CDPQ. Founded in 2020, the company has now raised more than $170 million, per Crunchbase.

7. Hexagon Bio, $77M, biotech: Menlo Park, California-based Hexagon Bio, a biopharmaceutical company focused on medicines encoded in the global metagenome, raised a $77.3 million Series B. New investors in the round include the Canada Pension Plan Investment Board. Founded in 2016, the company has now raised nearly $271 million, according to Crunchbase.

8. NanoGraf, $65M, batteries: Chicago-based battery materials company NanoGraf raised a $65 million Series B led by Volta Energy Technologies and CC Industries. Founded in 2012, the company has raised nearly $90 million, per Crunchbase.

9. Checkerspot, $55M, advanced materials: Alameda, California-based Checkerspot, which designs materials used for outdoor recreational products, closed a $55 million Series C led by ArrowMark Partners. Founded in 2016, the company has raised $109 million, according to Crunchbase.

10. Descope, $53M, software: Los Altos, California-based Descope raised a $53 million seed round led by Lightspeed Venture Partners and GGV Capital and emerged from stealth. The company has launched a new authentication and user management platform for developers.

9to5 : Exclusive: This is iPhone 15 Pro: Thinner bezels, thicker ‘curve’ design,


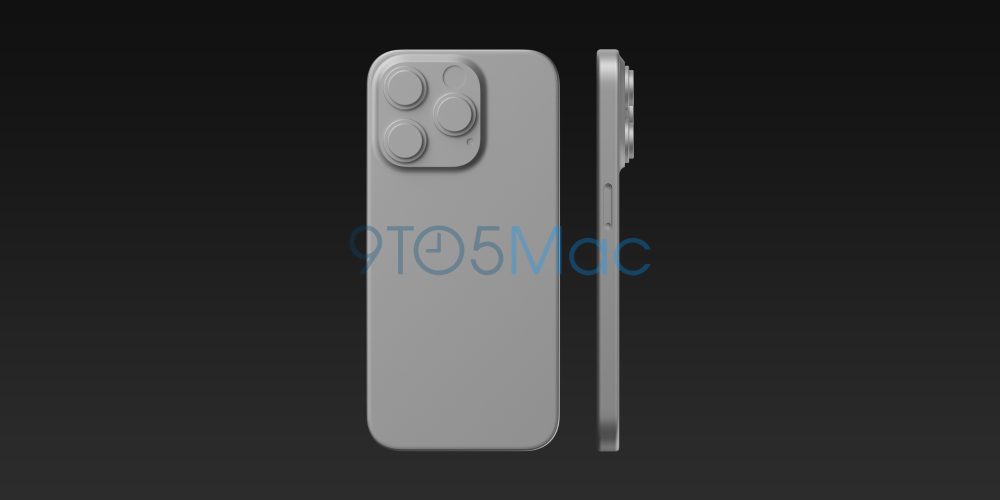
We have obtained exclusive renders of the upcoming iPhone 15 Pro, based on a CAD model provided to 9to5Mac by a reliable case manufacturer and 3D Artist Respective Render Man Ian Zelbo. The renders show some significant changes to the design and features of Apple’s flagship smartphone, which is expected to launch later this year.

CAD files like the ones these renders are based on are given by Apple to factories in Asia to prepare phone cases ahead of launch. This is to ensure that cases are available when the device launches.
The specific CAD here comes from a factory out of China that is seemingly the first to get these files. Historically, CAD files are accurate to the final device in terms of both dimensions and design, as having inaccurate ones would be costly to case designers and factories.
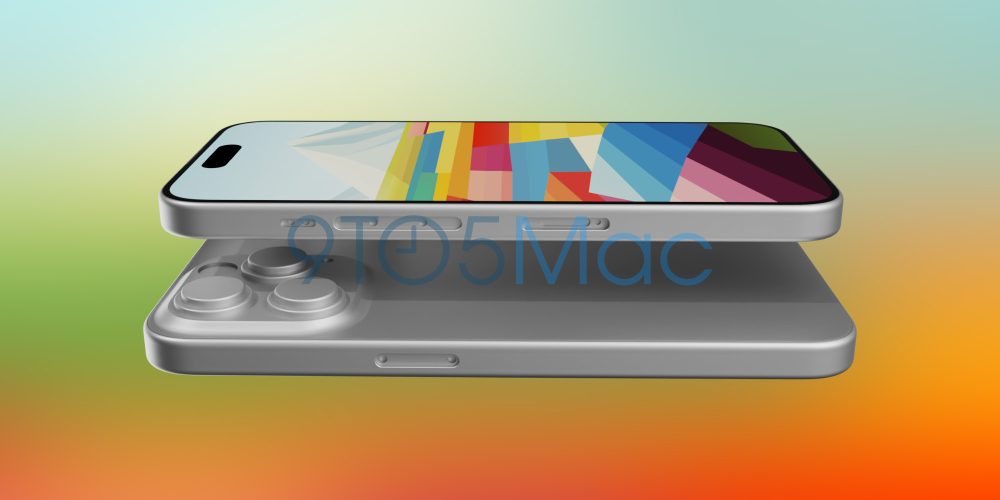
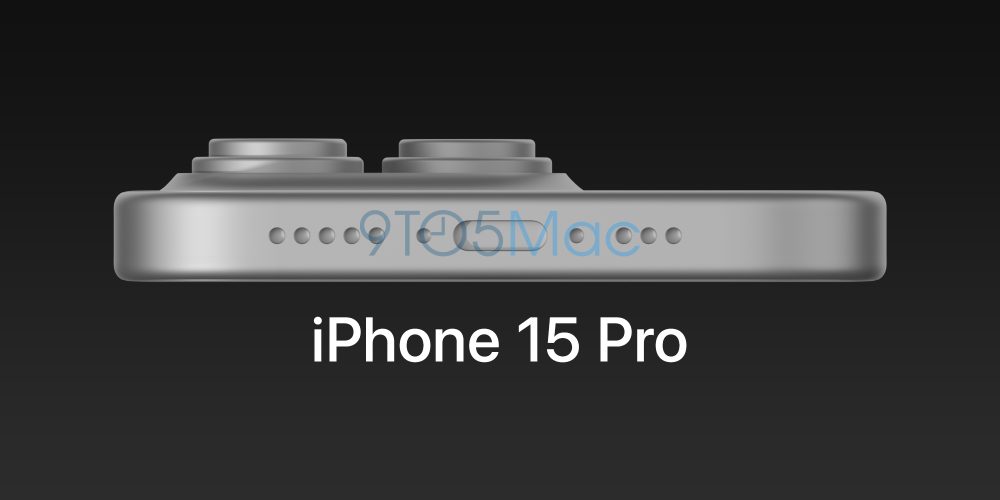
The most noticeable change is the switch from the Lightning port to USB-C, which would mark a major departure from Apple’s proprietary connector that has been used on iPhones and most Apple accessories since 2012.
This could be due to the pressure from the European Union, which has been pushing for a common charging standard for all smartphones and devices. Unfortunately, this might be limited to cables approved for Apple’s MFi program for data transfer speeds and charging speeds.
USB C Port on iPhone 15 Pro
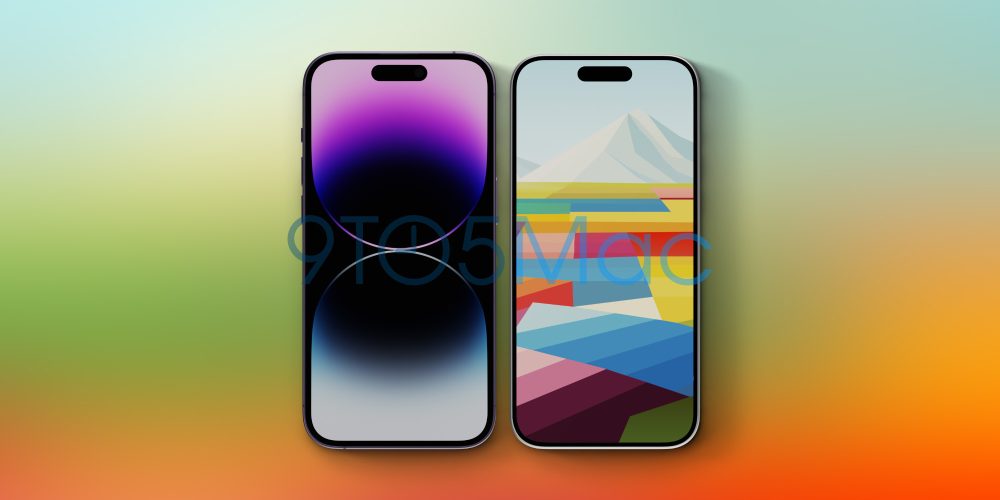
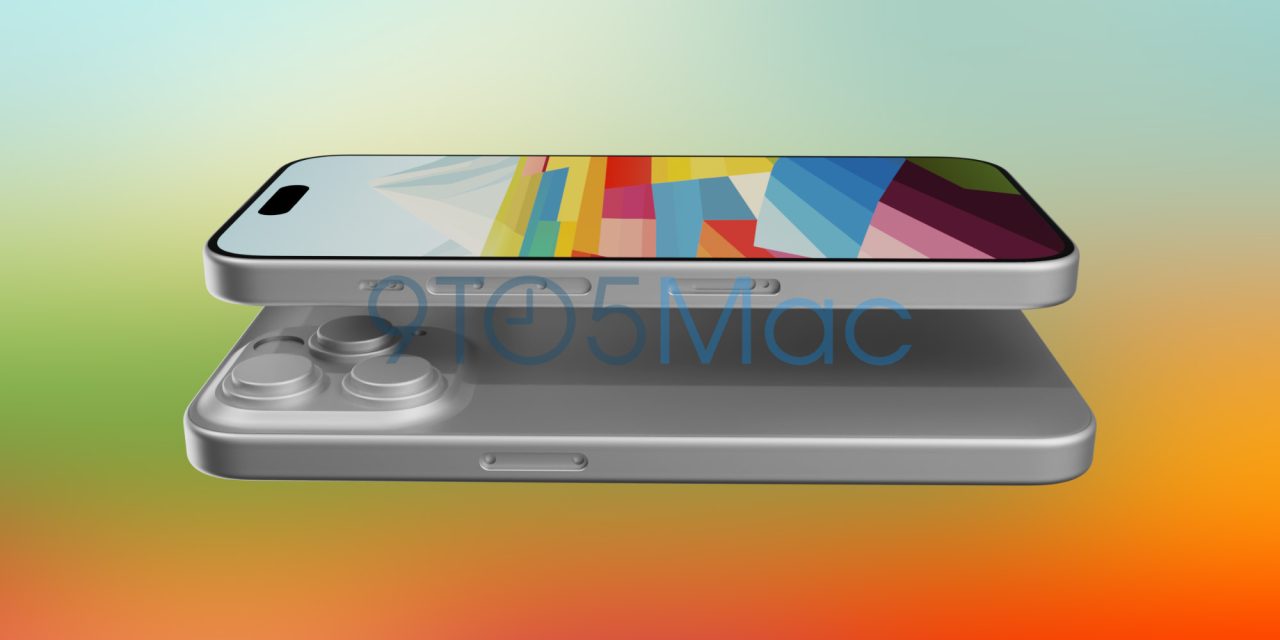
Another change is the curvature of the edges, both on the glass and on the metal frame. The glass curves slightly around the edges, creating a more seamless transition to the frame. The frame itself is also more curved than before, resembling the design of the 14-inch and 16-inch MacBook Pros and new M2 MacBook Air. This could make the phone more comfortable to hold and less prone to accidental touches.
The camera bump on the back is also thicker than before, indicating that Apple may have upgraded the camera system with new sensors or lenses. The camera layout remains similar to the iPhone 14 Pro, with three lenses and a LiDAR scanner arranged in a square module. The camera lenses are thicker in this generation, likely hinting at larger image sensors.
On the side of the phone, we can see some changes to the volume rockers and the mute switch. The volume rockers look like capacitive buttons instead of physical ones, which has been rumored. Given the renders we can not say this for certain, but it seems very likely. The mute switch also looks redesigned, with a smaller and rounder shape similar to that of the capacitive buttons.
iPhone 14 Pro vs. iPhone 15 Pro CAD
The renders do not show any details about the resolution of the iPhone 15 Pro, but we expect it to be similar to the iPhone 14 Pro. The body of the device is a few mm smaller with a thinner bezel, so it’s likely we’ll see the same 6.1-inch display in a slightly smaller body. The Dynamic Island is still present and looks to be about the same size as the iPhone 14 Pro.
These renders are based on an early CAD model and may not reflect all aspects of Apple’s final design. However, they do give us an idea of what we can expect from one of this year’s most anticipated smartphones and all of the important changes, like a more comfortable frame and USB-C.

WWD : Beauty and Home Care Are Starting to Merge

Beauty and Home Care Are Starting to Merge
Diptyque dish soap, anyone?

Chores are about to get a whole lot chicer.

High-end beauty brands are infiltrating the homewares market with new products meant to elevate everything from washing laundry to doing dishes, and make sure things smell good along the way.

There’s an ultra-luxe laundry detergent from LVMH Moët Hennessy Louis Vuitton-backed Maison Francis Kurkdjian, a room spray meant to purify the air from Courteney Cox’s Homecourt, plus an intention-oriented fragrance diffuser from Kris Jenner’s Safely.

There’s a strong business case behind the bevy of new products — Fortune Business Insights reports the market for household cleaning products will reach over $334 billion by 2029.

Here, some of the products cashing in on the buzz.

Maison Francis Kurkdjian Aqua Universalis Scented Laundry Detergents, $45.
Maison Francis Kurkdjian Aqua Universalis scented laundry detergents.
Aqua Universalis, one of the brand’s bestsellers, features notes of bergamot, lemon and lily-of-the-valley, and has been born as a fabric softener and two respective detergents for bright and dark colors.
Homecourt Room Deodorant, $30.
Homecourt Room Deodorant.
Homecourt offers its signature scents as a room spray, with added charcoal meant to purify air and zinc ricinoleate to neutralize odors. Fragrances include Steeped Rose, Neroli Leaf, Cipres Mint and Cece – founder Courteney Cox’s signature scent.
Safely Scent Diffuser Starter Kit, $6.29.
Safely Scent Diffuser.
Kris Jenner’s new launch for home-care brand Safely takes notes from daughter Kourtney Kardashian, a longtime proponent of clean living. Safely’s latest manifestation, scent diffusers, comes in three scents: Bright, Rise and Calm.
Dirty Labs Bio Enzyme Laundry Detergent in Murasaki, $14.
Dirty Labs Bio Enzyme Laundry Detergent.
SCOTT SNYDER
Hypoallergenic laundry brand Dirty Labs has added notes of jasmine, matcha and vetiver to its hero detergent.
Diptyque La Droguerie Collection. Prices range from $15 to $72.
Diptyque La Droguerie Collection.
PHOTO COURTESY OF DIPTYQUE
The home fragrance heavyweight has coupled complex fragrances in a host of cleaning products, such as dish soap, surface cleaner and a basil-scented odor-reducing candle.