The Regional Bank Selloff Visualized
A look at the health of six regional lenders
In a week that included another interest-rate hike by the Federal Reserve and a rescue of First Republic by JPMorgan Chase, the KBW Regional Banking Index, which tracks regional banks in the U.S., was down 28% this year, through Friday.
This comes after two months of turbulence in the banking industry that was triggered by the collapse of regional lenders Silicon Valley Bank and Signature Bank. Some banks have suffered more than others. PacWest Bancorp PACW 81.70%increase; green up pointing triangle has seen its market capitalization decline by 75% this year. Metropolitan Bank Holding’s MCB 16.21%increase; green up pointing triangle market cap shrank by 60% since the beginning of the year, while Western Alliance Bancorp WAL 49.23%increase; green up pointing triangle and First Horizon’s value waned by 53% and 55%, respectively.
Each bank experienced a reduction in deposits during the first quarter. As the Fed continued raising interest rates this year, many customers moved their money out of checking accounts and into products such as money-market funds and Treasurys, which are paying greater yields.
Short interest in regional-bank stocks has picked up since Silicon Valley Bank failed in mid-March. As of Wednesday, more than 18% of PacWest’s shares were sold short, according to data from S3 Partners.
Short sellers, often active institutional investors, sell shares that they have borrowed in hopes that they can buy them back at a lower price.
UBS narrows list of Credit Suisse executives for leadership team
Chief executive Sergio Ermotti is banking they will help make the rescue deal work
UBS chief executive Sergio Ermotti has shortlisted the Credit Suisse executives he plans to make part of his management team, betting they can help make a success of the most significant banking deal since the financial crisis.
Among the Credit Suisse executives most likely to survive the takeover are Dixit Joshi, chief financial officer, Francesca McDonagh, chief operating officer, and André Helfenstein, head of the Swiss business, according to several people familiar with the plans.
Ermotti, who returned to run UBS in March after the bank agreed to rescue its Zurich rival in a $3.25bn deal orchestrated by Swiss authorities, is planning to unveil his new top team in the next week, with the takeover due to be completed by early June.
UBS is preparing for a costly and risky integration process as it attempts to combine two global systemically important financial institutions in the most significant banking deal since the financial crisis.
Colm Kelleher, the bank’s chair, has said the integration could take up to four years, while elements of the deal — including the decision by Finma, the Swiss banking regulator, to wipe out $17bn worth of bonds — are being challenged in the courts.
The completion of the deal hinges on receiving regulatory approval and sign off from competition authorities. While most main regulators have given a green light, the European Commission said the EU’s antitrust bodies will make a decision by June 7.
Joshi and McDonagh joined Credit Suisse late last year, leaving them untainted by the bank’s recent scandals.
Joshi started as CFO on October 1 and was immediately thrust into the bank’s efforts to hold on to fleeing customers following a damaging weekend of social media rumours about its financial health.
He was heavily involved in the bank’s $4.3bn capital raise in his first few weeks in the job. His brief stint in the role has also been marked by Credit Suisse delaying the release of its annual report in March after the US Securities and Exchange Commission made some last minute requests for additional information over its internal controls dating back to 2019.
McDonagh, who left her role as chief executive of Bank of Ireland to join Credit Suisse, was hired to be head of the Emea region. But before she started, she was given the COO role and instructed to oversee a huge restructuring of the business.
As part of cutting $2.8bn in costs over three years, she had begun to reassess Credit Suisse’s global office footprint — including its underused 21-storey London headquarters in Canary Wharf, which it leases from the Qatar Investment Authority. But that review was put on hold when the deal with UBS was struck.
Helfenstein has run Credit Suisse’s domestic bank for the past three years and is the longest-serving executive board member, having joined when Thomas Gottstein became chief executive in 2020.
UBS executives see Credit Suisse’s domestic business as its “jewel in the crown” and would prefer to keep it intact. But combining it with UBS’s own Swiss business has proved unpopular domestically and executives have said all options are on the table for the unit.
Last week Swiss newspaper NZZ reported that Tom Naratil, who ran UBS’s US business and was co-head of its wealth management division until last year, would return as part of the new management team as chief financial officer.
Naratil has undertaken a finance role at West Point, the US military academy, this year, having left UBS in October. He had previously been UBS’s CFO between 2011 and 2015.
UBS declined to comment on plans for the new executive team.
Climate graphic of the week: Will El Niño return for a heated-up 2023?
Meteorologists calculate the chances of the weather phenomenon that warms the surface of the Pacific Ocean
Scientists are calculating the chances of the world experiencing record temperatures this year as they assess the likelihood of the return of the El Niño weather phenomenon that is associated with heat and drought.
El Niño involves the warming of the Pacific Ocean’s surface, which drives changes in temperature and rainfall patterns across the globe.
The World Meteorological Organization warned this week that the probability of El Niño developing this year was increasing, and its re-emergence would “likely fuel higher global temperatures”.
There was “a 60 per cent chance” that El Niño would develop between May and July, rising to 80 per cent between July and September, it forecast.
The US National Oceanic and Atmospheric Administration also issued an “El Niño Watch” alert in April that concluded there was a 62 per cent chance of El Niño developing between May and July.
The return of El Niño would be a long-anticipated transition from the rare three-year cycle of the corresponding La Niña weather pattern — the opposite weather phenomenon that involves the cooling of the Pacific Ocean’s surface temperature.
This weather system was officially declared at an end by meteorologists earlier this year, after taking its toll with devastating floods in the US and Australia and catastrophic drought in Africa and South America.
Below-average rainfall in 2021 and 2022 was one factor that led to the record drought in the Horn of Africa, and was in part a result of the presence of La Niña.
“The unusually stubborn La Niña has now ended” and neither La Niña nor El Niño were active, said the WMO last week.
There had been a “significant increase” in Pacific Ocean sea surface temperatures since February, however, the group said.
Although three years of La Niña had acted as a temporary “brake” on global temperatures, the last eight years were the warmest on record, said Petteri Taalas, the WMO’s secretary-general.
“The development of an El Niño will most likely lead to a new spike in global heating and increase the chance of breaking temperature records,” he said.
A strong El Niño event occurred between 2015 and 2016, with 2016 the hottest year on record.
If El Niño develops, regions such as South America, the southern US and the Horn of Africa would be likely to experience increased rainfall and potential flooding, while the risk of drought would increase in regions including Australia and Indonesia.
The UN’s Food and Agriculture Organization said in April that it was “scrutinising” at-risk areas that might suffer food insecurity during an El Niño period and any “anticipatory action” that could be taken to mitigate the effects.
Potential FAO actions included liaising with government officials and putting seed reserves in place, depending on the severity of the situation.
Brazil and South Africa were among the cereal-producing countries at risk of abnormally dry conditions and potential crop failures during an El Niño year, for example, the group said.
For an El Niño event to be declared, equatorial Pacific Ocean temperatures need to rise above a certain threshold, while changes in the atmosphere, such as winds at the equator, must also be detected.
The onset of El Niño was “harder to predict a long time in advance”, said the EU’s Copernicus Climate Change Service. Forecasting what might happen is particularly challenging towards the start of the year during the transition away from La Nina to either neutral or El Niño.
On Friday, the World Weather Attribution group of scientists concluded that climate change made this year’s record-breaking April heatwave in Spain, Portugal, Morocco and Algeria “at least 100 times more likely”.
The levels of heat recorded “would have been almost impossible” without human-driven warming, it said. Temperatures have already risen by at least 1.1C in the industrial era.
TikTok reportedly monitored users who watched gay content
TikTok reportedly compiled a list of users who were being monitored after they watched gay content on the app, according to former employees who protested the policy.
The popular video-sharing service kept tabs on users who frequented clips that were tagged under headings including LGBT (lesbian, gay, bisexual, transgender), according to The Wall Street Journal.
Former TikTok employees told The Journal that information about users’ viewing habits were compiled and stored on a dashboard.
The ex-employees based out of the company’s offices in the US, UK, and Australia said they flagged the issue to top executives in 2020 and 2021, according to The Journal.
The former employees expressed their concerns that the information would be shared with outside parties or could be used to blackmail TikTok users, The Journal reported.
Social media companies including Facebook, Instagram, Twitter, YouTube, and others have been criticized in years past for gathering user data on their online habits for the purpose of tailoring their targeted ads.
The Post has sought comment from TikTok and its parent company, the Chinese-based multinational ByteDance.
“Safeguarding the privacy and security of people who use TikTok is one of our top priorities,” TikTok said in a statement provided to The Journal.
Last year, the prominent LGBT advocacy group GLAAD, which is an acronym for the Gay and Lesbian Alliance Against Defamation, demanded that tech companies take steps to safeguard user data and privacy.
“This includes ceasing the practice of targeted surveillance advertising, in which companies use powerful algorithms to recommend content to users in order to maximize profit,” GLAAD said in the report.
TikTok’s handling of user data and the fear that its Chinese parent company’s ties to the ruling Communist Party in Beijing makes American users vulnerable to espionage are at the source of US lawmakers’ concerns about the app.
Calls to ban TikTok in the US have grown despite the company denying that it is providing the Chinese government with Americans’ user data.
TikTok has already been banned from government-issued phones in countries such as Canada and Australia over concerns about whether the Chinese government can access user data or influence what people see on the popular app.
TikTok said on Tuesday its head of US trust and safety, Eric Han, will depart the company on May 12.
In March, a Canadian cybersecurity firm found that TikTok’s parent company was tracking the websites of dozens of US state governments.
The Biden administration has navigated tough Republican opposition toward TikTok, as GOP lawmakers have called for a crackdown — and hit Democrats over their permissive stance on the Chinese app.
US Bank-Run Escalates: Deposit Outflows Top $360 Billion In Last 3 Weeks


The bank run continues to accelerate...

...especially if one looks at non-seasonally-adjusted data.
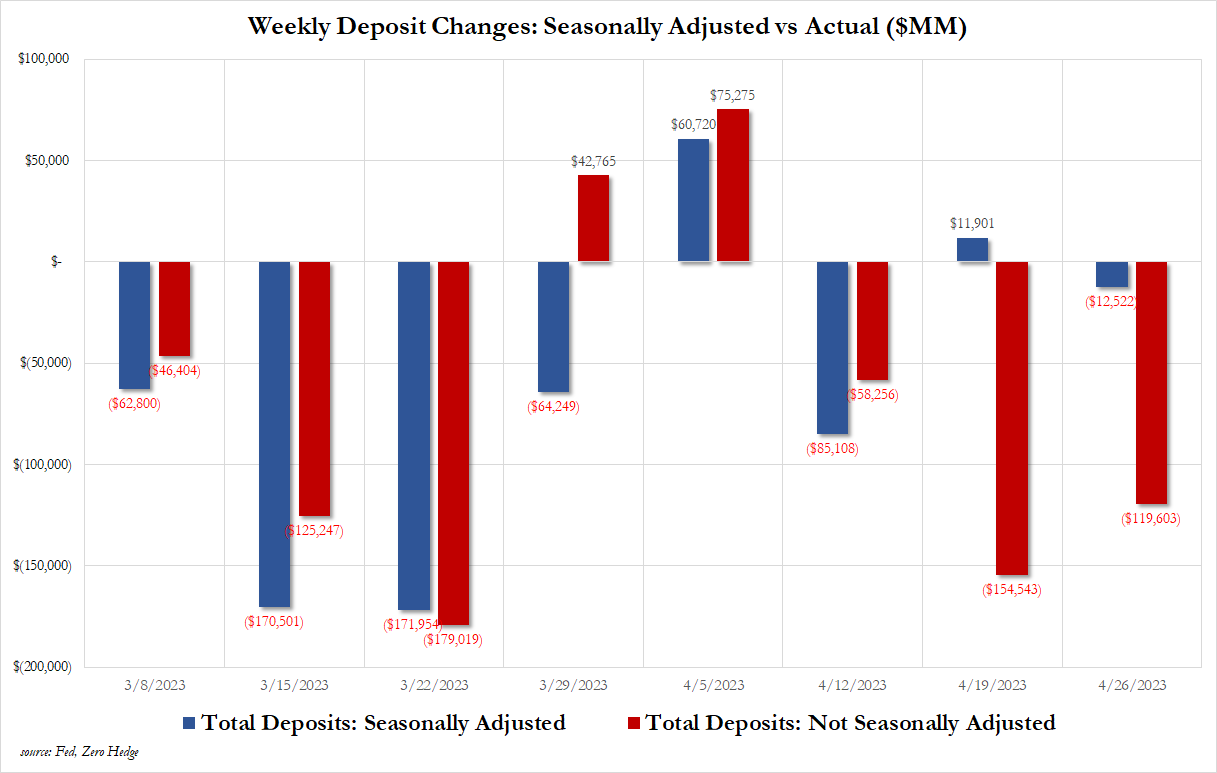
Crucially that is over 360 billion of deposit outflows from US banks in the last 3 weeks.
And here is the source data:
SA:

NSA:
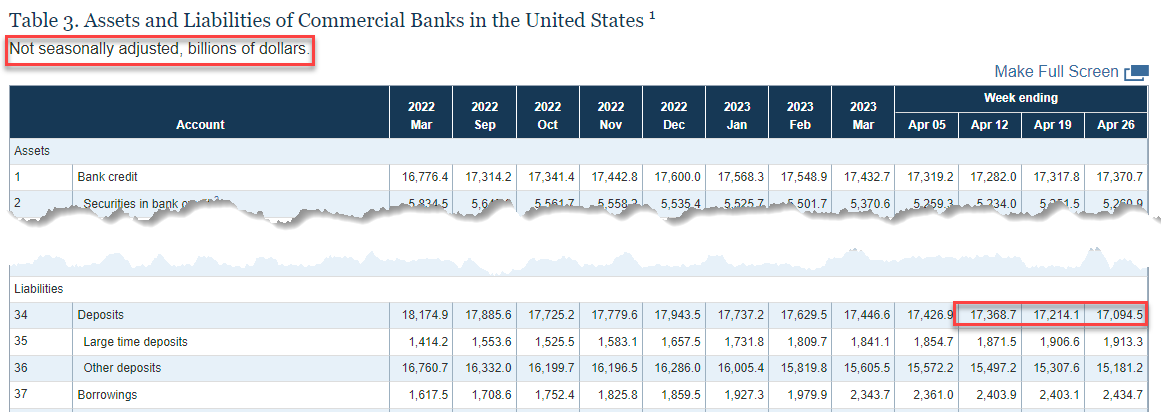
How much of this tax related, and how much is a bank run, and how does the Fed know which is which?
Sure, some of this is tax outflows, but the Fed is just using a historical seasonal adjustment factor AS IF there is no bank run which is traditionally the case...
* * *
After yesterday's massive money market inflows, expectations are that tonight's data from The Fed's H.8 report will show major deposit outflows from US commercial banks (despite today's exuberant bounce in some regional bank shares). Bear in mind, as we detailed yesterday, that The Fed's emergency bank rescue facility usage remains extremely high and has shown now signs at all of easing...
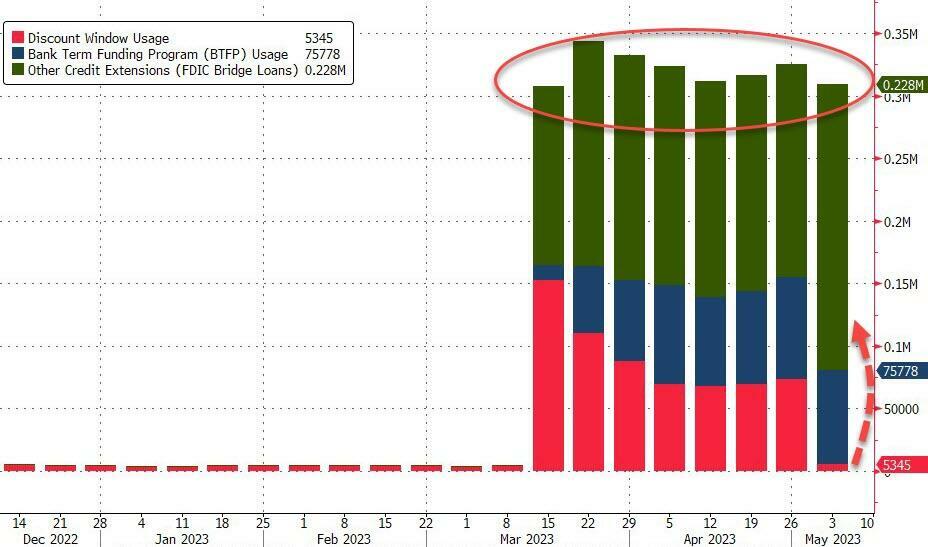
Source: Bloomberg
On a seasonally-adjusted basis, total US Commercial Bank deposits fell $12.5 billion during the week ended 4/26...
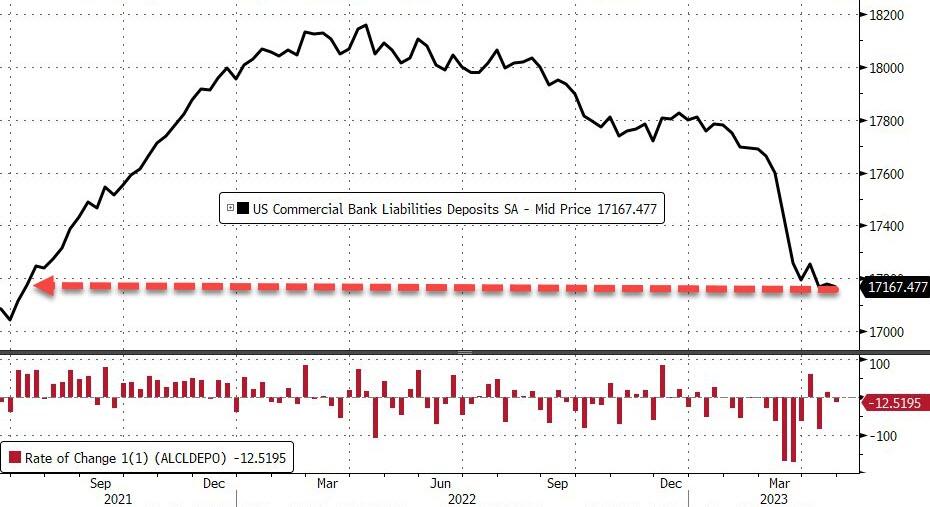
Source: Bloomberg
However, on a seasonally adjusted basis, US commercial bank deposits (ex-large time deposits) increased last week (during the week-ending 4/26), rising $10.92 billion...
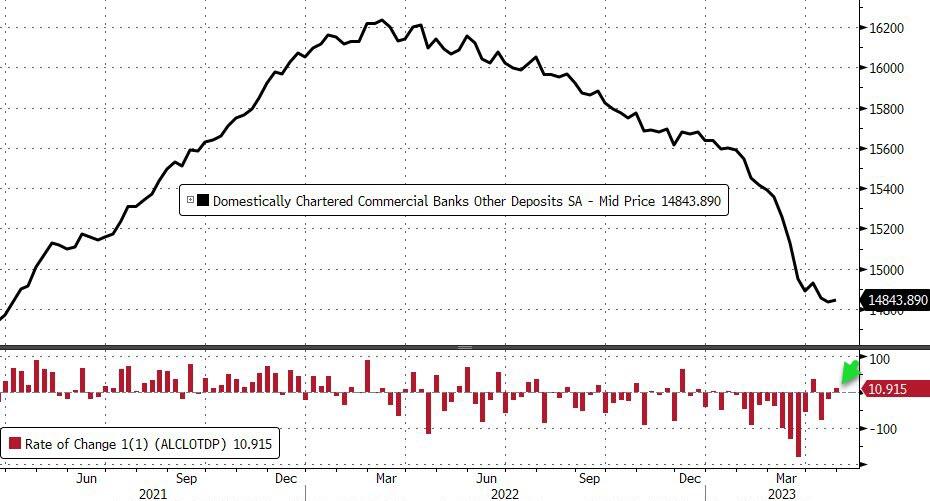
Source: Bloomberg
On a non-seasonally-adjusted basis, US commercial bank deposits (ex-large time deposits) tumbled again, down $113 billion (also at its lowest since April 2021)...
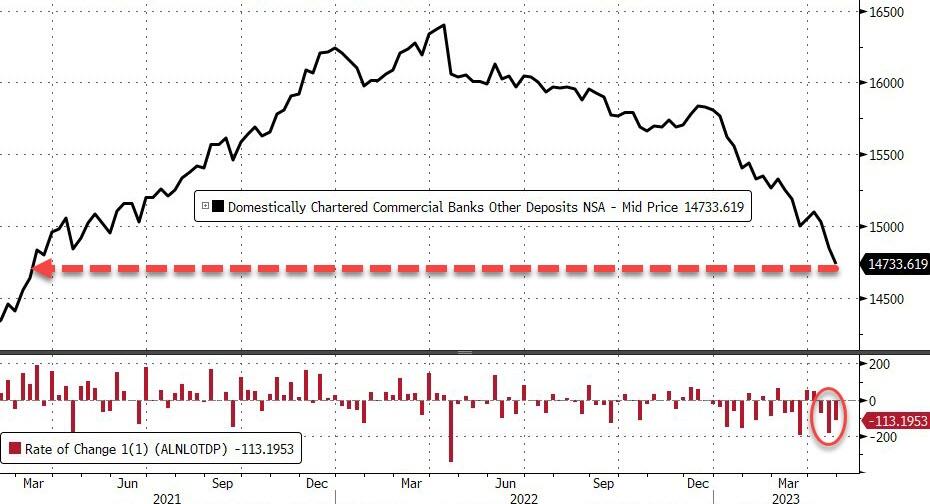
Source: Bloomberg
That is over $360 billion in outflows in the last 3 weeks... but but but SVB fixed everything?
And judging by yesterday's money market inflows, the deposit outflows continued this week (remember, despoist data is lagged a week to money market and Fed balance sheet data)...
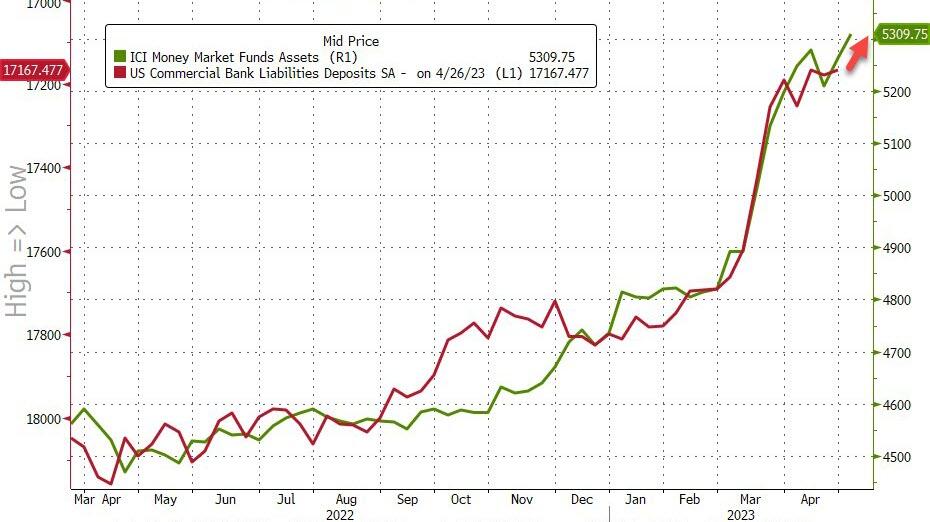
Source: Bloomberg
Large and Small banks saw very modest inflows (on a seasonally adjusted basis) but foreign banks saw large outflows...
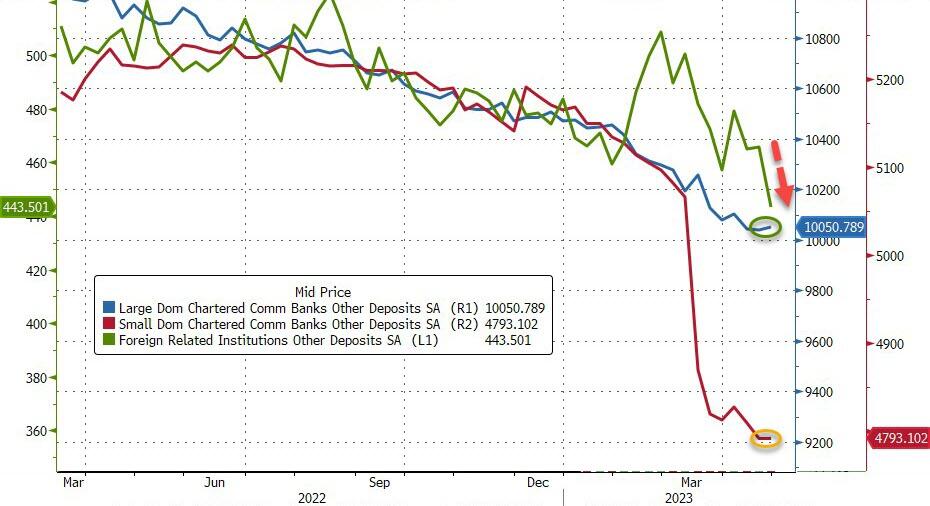
Source: Bloomberg
Foreign banks saw the biggest weekly outflows since 6/30/2021...
- Large Banks +$10.3 billion
- Small Banks +$584 million
- Foreign Banks -$22.14 billion
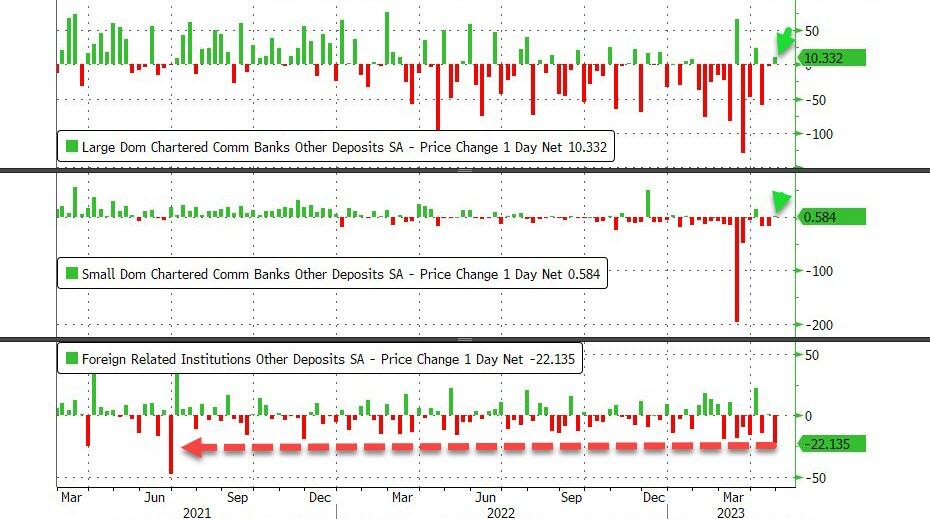
Source: Bloomberg
However, what really matters is the non-seasonally-adjusted data which saw major outflows across small, large, and foreign banks...
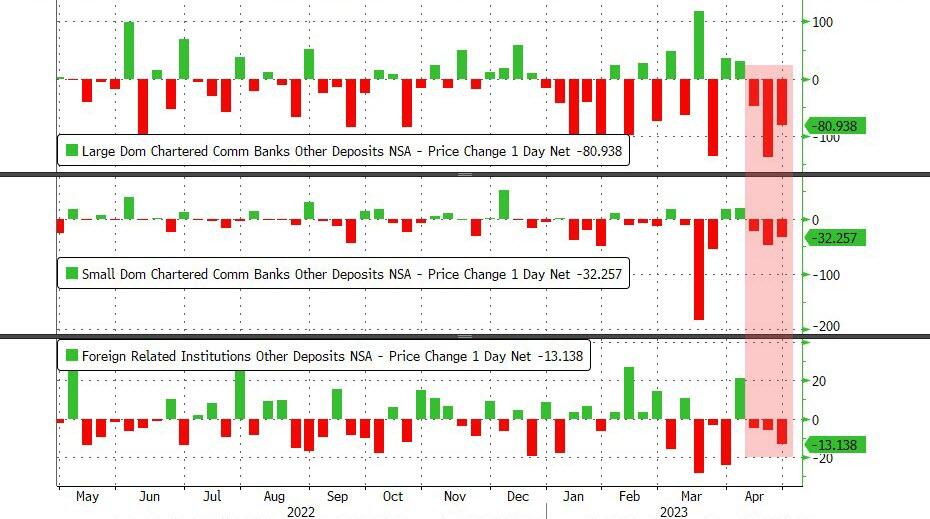
Source: Bloomberg
In context, the bank run is escalating...
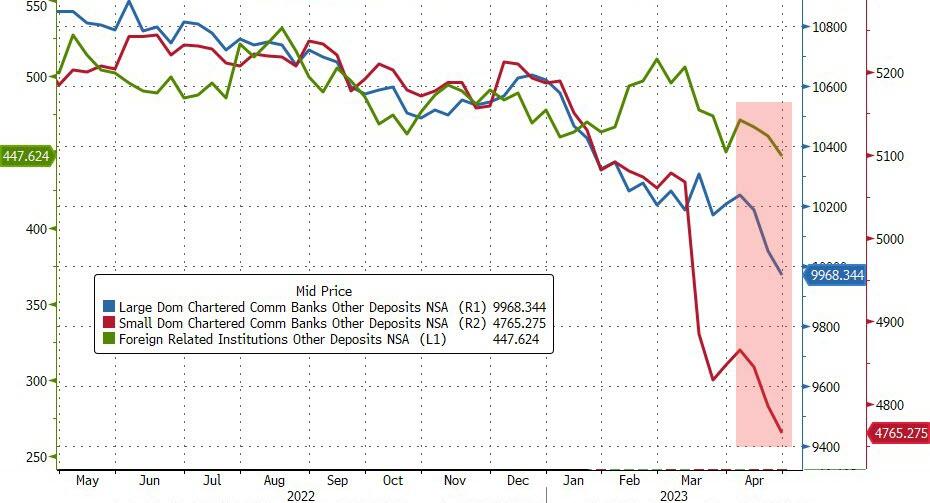
On the other side of the ledger, Commercial bank lending rose $41.6 billion in the week ended April 26 after increasing $12.4 billion the prior week, according to seasonally adjusted data.
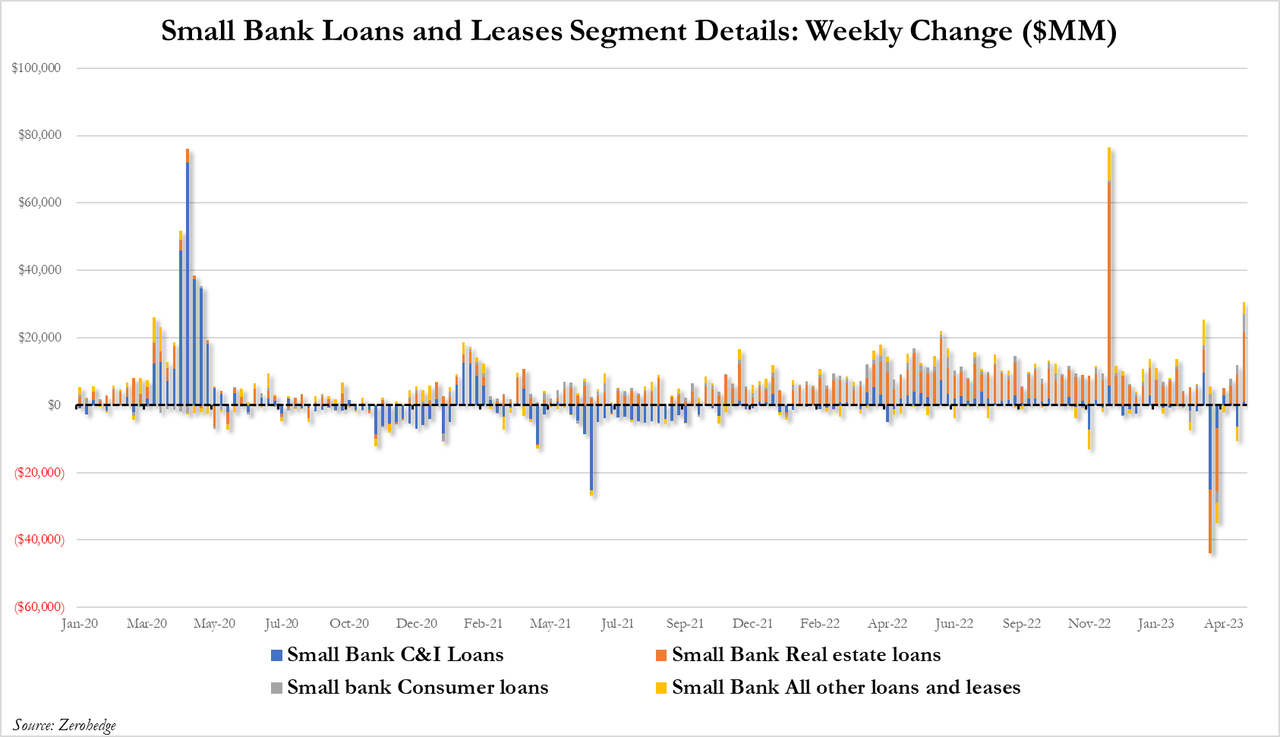
Small bank lending exploded higher to $30.6 billion...
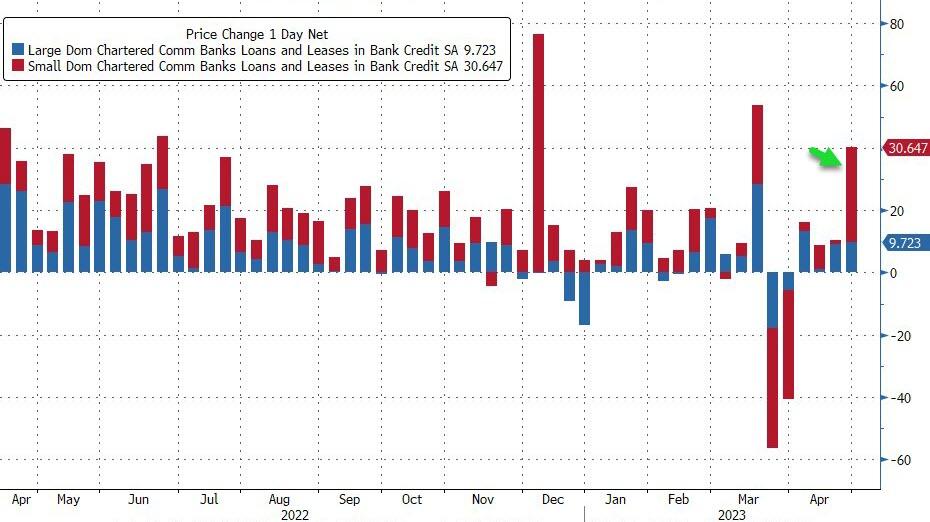
Small Bank Weekly Change:
- Small Bank C&I Loans: +$1.1BN
- Small Bank Real Estate Loans: +$20.6BN
- Small Bank Consumer Loans: +$5.3BN
- Small Bank All other Loans and Leases: +$3.7BN
Anyone else wonder how and to whom the small banks lent that much in CRE loans? Money good?
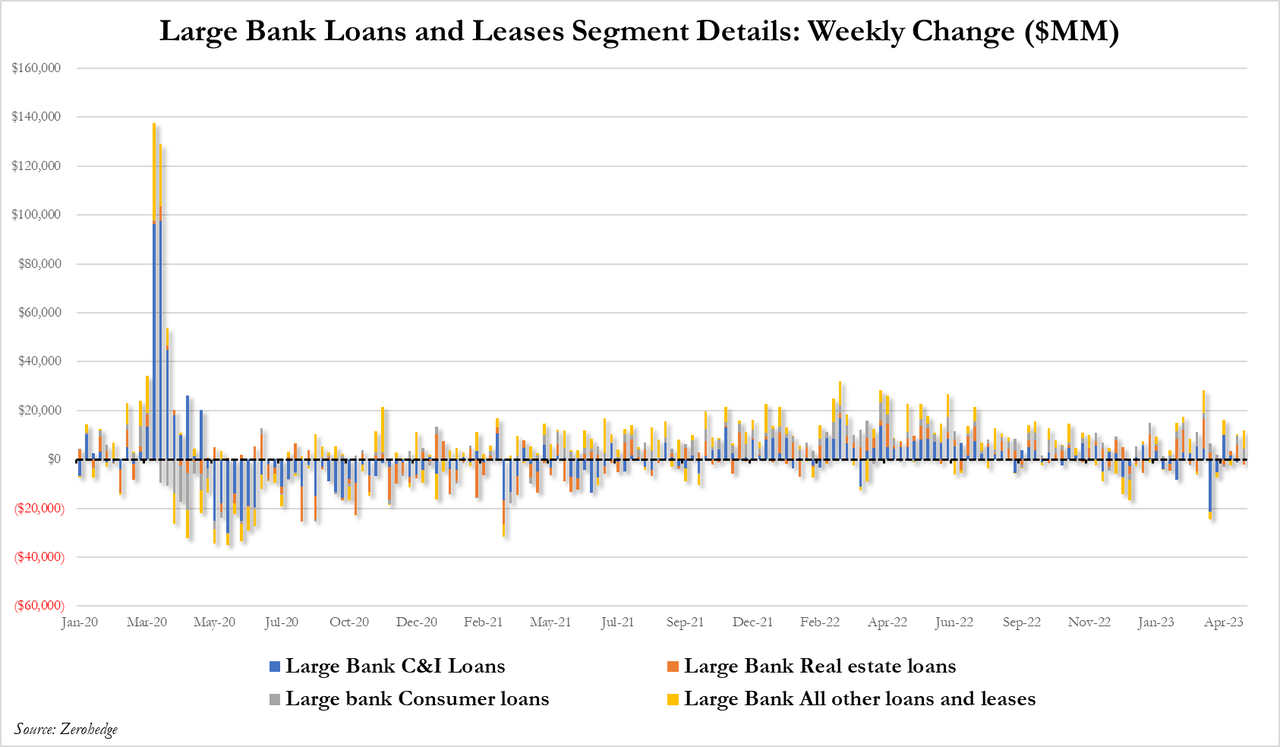
Large Bank Weekly Change:
- Large Bank C&I Loans: -$0.4BN
- Large bank Real Estate Loans: -$1.7BN
- Large Bank Consumer Loans: +$4.4BN
- Large Bank All other Loans and Leases: +$7.4BN
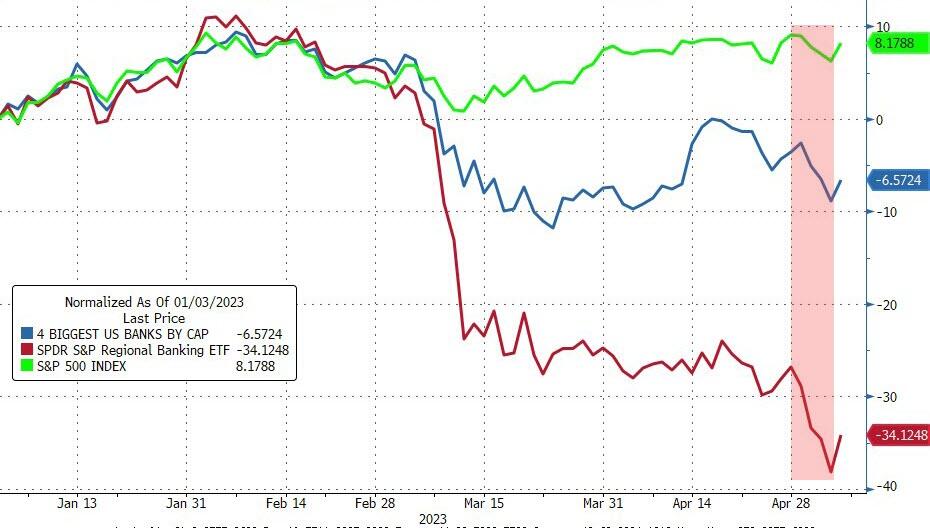
Despite today's bounce, it was another ugly week for bank stocks(big and small)...
Source: Bloomberg
So you still believe the banking crisis over?
Finally, we remind readers, this data does not include this week's potential problems (as the deposit and loan data is lagged by a week).
Mystery Trader Bets $5 Million On VIX Exploding To 70 By September