WSJ : Marlboro Maker Hits Reset on $2 Billion Bet on Medicine

Marlboro Maker Hits Reset on $2 Billion Bet on Medicine
Philip Morris considers selling stake in a recently acquired pharmaceutical business after setbacks

Philip Morris International’s PM 0.37%increase; green up pointing triangle push into healthcare is faltering, prompting the tobacco giant to consider options such as selling a stake in its biggest pharmaceuticals unit.

In 2021, the tobacco giant agreed to acquire three pharmaceutical companies for a total of more than $2 billion as part of a plan to pivot away from cigarette sales. The deals inserted the Marlboro maker into the market for inhalers and other treatments for respiratory diseases that are linked to cigarette smoking.

Philip Morris’s struggles came into view over the summer, when the company took a $680 million charge on its wellness and healthcare business and postponed its ambitious revenue goals for the business.

Now, Philip Morris is considering the possible sale of a stake in its biggest pharmaceuticals unit, as it searches for a new partner to help it make the business work. Philip Morris acquired that business, an inhaled-medication company called Vectura Group, in a $1.24 billion deal after winning a bidding war against private-equity firm Carlyle Group.

Philip Morris has had discussions with Deutsche Bank on a range of options to try to grow its wellness and healthcare division, according to people familiar with the matter. The tobacco company said it is looking to bring on a partner to help operate and grow Vectura’s drug manufacturing outsourcing business, possibly through a sale of a majority or minority stake in that business. Other options include a licensing or royalties deal or a commercial partnership, Philip Morris said.

Philip Morris didn’t anticipate how long it would take to develop pharmaceutical products—and particularly inhaled medications, according to people who have worked in Philip Morris’s health and wellness business. The tobacco giant was hit by “that realization of what a long road pharma can be,” one of those people said.

Philip Morris remains committed to developing its healthcare business and continues to see potential in several areas, including inhalable drugs, nicotine-replacement therapies and medicinal cannabis, the company’s finance chief, Emmanuel Babeau, said on a call with analysts in July.

“Our ambition to build and monetize our product pipeline are unchanged,” he said, adding that in the early days of product development, “certain headwinds are to be expected.”

In addition to the Vectura acquisition, Philip Morris in 2021 agreed to pay more than $700 million, including the assumption of debt, to buy Fertin Pharma, a Danish maker of gums and lozenges that can be used to deliver nicotine, cannabis, vitamins or cold medicine. Philip Morris also acquired OtiTopic, a U.S.-based developer of an inhalable aspirin to prevent heart attacks, for an undisclosed sum.

Philip Morris bet it could parlay its expertise in inhalation and aerosolization into a pharmaceutical business and projected that it would generate at least $1 billion dollars in annual net revenue from health and wellness products by 2025.

But two years on, the wager has been a losing one—at least so far—demonstrating the challenges big tobacco companies face trying to diversify their operations amid declining smoking rates.

In July, Philip Morris took a $680 million charge to reflect the slumping value of its healthcare and wellness business after parts of all three business units suffered setbacks.

A clinical trial for OtiTopic’s treatment was unsuccessful, and Philip Morris said it wouldn’t submit it this year to the U.S. Food and Drug Administration. The company also said its drug manufacturing outsourcing business, which came with the acquisitions of Vectura and Fertin, had developed slower than expected and incurred rising costs.

The healthcare division’s operating losses deepened in the second quarter, while its revenue was unchanged at $76 million.

There was widespread opposition to a cigarette maker branching out into treating respiratory diseases when a much bigger part of its business remains a major contributor to those health problems.

The Vectura deal proved particularly controversial for Philip Morris. In one letter to the U.K. government, dated Sept. 16, 2021, 35 signatories including several doctors argued the deal was “not in the public interest and that it creates perverse incentives for PMI to increase harm through smoking so they might then profit again through treating smoking related diseases.”

A Philip Morris spokesman said the letter’s assertions are “flat-out ridiculous. The company is very clear about its direction and future in products that can reduce risk.”

WSJ : SEC Charges Investment Adviser Linked to Russian Oligarch Roman Abramovich

SEC Charges Investment Adviser Linked to Russian Oligarch Roman Abramovich
Concord Management invested billions of dollars on behalf of its sole client, the SEC says

New York-based investment adviser Concord Management and its owner face Securities and Exchange Commission charges for operating as an unregistered investment adviser to a single client, a wealthy Russian with connections to the Russian government.

Concord allegedly invested billions of dollars from at least 2012 through March 2022 on behalf of its sole wealthy Russian client without registering with the SEC, the agency said Tuesday. The agency didn’t name the client, but Concord Management has been linked to Roman Abramovich, a Russian oligarch with ties to Russian President Vladimir Putin. Last year, U.S. hedge-fund firms that had investments from Abramovich were told to freeze his assets after the British government placed sanctions on him.

The charges are an unusual example of the SEC’s involvement in the expansive sanctions and export control regime that the U.S. and its allies imposed on Russia following its 2022 invasion of Ukraine. The SEC normally polices investment advisers to help protect the public, but Concord only managed the money of a single client.

SEC enforcement head Gurbir Grewal said that Concord Management’s failure to register as an adviser “skirted rules crucial to the commission’s ability to monitor the market for abuse.”

The SEC doesn’t have a direct role in enforcing sanctions violations, but prominently noted Concord’s work for a client who was targeted by sanctions last year in its announcement of the action.

A spokesperson for Concord Management and its owner Michael Matlin expressed disappointment with the SEC’s decision to charge, but added that “we are confident that a full and fair review of the applicable law and relevant facts will underscore that Concord Management and Michael Matlin complied with all regulatory and legal requirements.”

A spokesperson for Abramovich didn’t immediately respond to a request for comment.

Between 2012 and at least 2022, the firm employed about 10 staffers, most of whom were serving as investment analysts, the SEC alleges, but most weren’t made aware of who the sole client was. Concord staff allegedly became aware over time of the identity of the client, but with limited visibility regarding the beneficiary of the funds being managed they typically described the firm to outside parties as a fund of funds or a family office for high-net-worth European individuals, according to the complaint.

The SEC said that while most of the investments were made in hedge funds, Concord allegedly invested in at least six private-equity funds, and provided supervision and management services, including due diligence and investment negotiations, investment execution and portfolio monitoring.

As of January 2022, Concord allegedly managed investments in 112 different private funds for the client with an estimated total value of $7.2 billion, according to the SEC.

The SEC also alleged that a month before the U.K. and European Union designated the client as a sanctioned individual in March 2022 and froze the client’s assets, Concord and Matlin aided the client in attempts to sell off his investment portfolio.

“We allege that Concord flouted the registration requirements of the federal securities laws for over a decade, earning more than $80 million for providing investment advice to its billionaire client during that time,” said Grewal.

FT : Deutsche Bank struggles with fallout after huge Postbank IT migration

Deutsche Bank struggles with fallout after huge Postbank IT migration
Regulator makes unprecedented rebuke as many clients locked out of their accounts for weeks

Deutsche Bank is struggling with the fallout from the most ambitious and fraught IT integration in its history, including customers being locked out of their accounts.

The bank said in July that the migration of 12mn Postbank clients and 50bn individual data sets to a different IT system in July had unfolded without glitches but its German retail business has since been beset with problems.

Service centres have been overwhelmed by a jump in client inquiries and a number of critical internal workflows have stopped working. As a result, thousands of clients, many of them vulnerable people with few financial resources, have been locked out of their accounts, often for weeks.

Earlier this month, the disruption drew an unprecedented public rebuke from financial watchdog BaFin, which criticised Deutsche for “considerable disturbances in the handling of customer business” and reminded the country’s biggest bank that it was required to “comply with the relevant statutory deadlines for the protection of customers”.

BaFin’s reprimand led to a public apology and greater efforts to resolve the issues. It left the bank “shell-shocked”, according to a person familiar with the matter.

Fixing the issues has become a top priority for chief executive Christian Sewing, who ran the retail business between 2015 and 2018. After the BaFin criticism, he addressed staff in a town-hall meeting and receives twice-weekly progress briefings. A party to celebrate the completion of the project was called off even before BaFin’s intervention.

Deutsche has warned that it will take more than three months to fix the remaining problems and some senior managers are bracing for a formal BaFin sanction, possibly a fine. The watchdog said it might impose “supervisory measures if appropriate” and declined to comment further. 

The woes are the latest to stem from Deutsche Bank’s ill-fated takeover of domestic rival Postbank in 2010, a troubled retail lender that was once part of Germany’s state-owned postal service. Over the past decade, Deutsche failed to find a buyer for Postbank and botched an earlier IT integration effort.

In 2017, Deutsche decided it would go ahead with a full integration of Postbank, keeping only the brand and its branches. This project, dubbed “Unity”, was completed in July when the final batch of clients and contracts was moved on to Deutsche’s IT systems.

While the bank insists that no data was lost or corrupted in the process, some internal workflows have all but collapsed since then.

One example is the handling of “garnishments” — the requirement for banks in Germany to deduct funds from a customer’s account if a creditor has secured a legal warrant. Deutsche is struggling to comply with a rule that a minimum amount must be left in an account after money has been deducted for garnishments.

In the meantime, thousands of clients have been cut off from their accounts, in some cases for weeks. That has left some households dependent on just one bank account facing difficulties in paying for food, rent and other bills.

“Fixing the garnishments issue is our top priority,” said a person familiar with the matter, adding that Deutsche has recently rolled out a tool that can help.

According to people familiar with the matter, Deutsche has more than 3,000 accounts that are affected by garnishments on a daily basis. The number of such accounts has jumped by a third in recent months as the German economy has slowed.

Verbraucherzentrale NRW, a consumer protection group, called the bank’s handling of garnishments “catastrophic”. The consumer group said that the picture has not meaningfully improved since BaFin’s intervention in early September and that complaints from Postbank clients continue to mount.

In its reprimand of Deutsche, BaFin said that the number of complaints was so high that it could not respond to them individually.

People familiar with the “Unity” project told the Financial Times that Deutsche had failed to give Postbank staff enough training on its own systems. In some cases, Deutsche replaced automated Postbank workflows with its own ones that require more manual intervention — leading to backlogs.

One area that has been disrupted is the ability of Postbank customers to draw down on mortgages taken out for construction projects.

The delay has left clients unable to cover construction bills, leading in some cases to work being halted. In one instance, a family that lost their home in the Ahr valley flooding two years ago had to move into a hotel because their rebuilding project stalled, according to a person familiar with the case.

Customer services have also been overwhelmed by inquires, resulting in long waiting times. On Trustpilot, an internet site where users can rate companies, Postbank is the lowest-ranked German bank with a score of 1.2 out of 5.

Deutsche insists that the disruption facing customers will not endanger its goal of cutting annual costs in retail banking by €300mn by 2025. People familiar with the matter said the bank has not yet seen a significant rise in account closures.

Disgruntled Postbank staff have aired their frustration internally, flooding Deutsche’s intranet with scathing comments, according to people familiar with the details. One remarked that while the top management had the ambition to operate a Michelin-star restaurant, its retail clients had to put up with “the quality of a chip shop”.

FT : Uber warns of threat to drivers in ‘hundreds’ of cities under EU gig work p

Uber warns of threat to drivers in ‘hundreds’ of cities under EU gig work plan
Prices paid by consumers would also rise if Brussels enacts Platform Work Directive, says Uber’s European chief

A top Uber executive has warned that Brussels’ proposals to designate gig workers as de facto employees will force its ride-hailing service to shut down in hundreds of cities across the bloc and raise prices by as much as 40 per cent if enacted.

Anabel Díaz, head of Uber’s mobility division in Europe, urged lawmakers debating the EU’s Platform Work Directive this week to approve rules that preserve what she described as self-employed workers’ desire for flexibility.

“If Brussels forces Uber to reclassify drivers and couriers across the EU, we could expect to see a 50-70 per cent reduction in the number of work opportunities,” Díaz said. This would cause Uber to cease operating in “hundreds” of the 3,000 cities across the EU that it serves today, she added.

A new law giving drivers full working rights would also force Uber to raise the prices paid by consumers, Díaz added. “It could drive up prices by as much as 40 per cent for consumers in major cities — according to the European Commission’s own estimates — and with fewer drivers, riders could expect to experience significantly longer wait times.”

Her comments come in the week that the EU’s main institutions — the European Commission, the parliament and the Council of Ministers — have kick-started negotiations over the final text of the new law, which is aimed at improving economic conditions for gig workers in the bloc.

The law is likely to represent a significant change from the status quo in Europe, where the majority of platform workers are presumed to be self-employed, meaning they lack access to labour rights and benefits, such as paternity leave and a minimum salary.

Speaking to the Financial Times, Díaz warned of the consequences of the proposed EU legislation, which would give people who work for digital platforms — including drivers for ride-hailing services and food delivery drivers — the rights of full-time workers by default.

She said Uber is “sincerely committed to the European social model” but warned that similar rulings classifying drivers as employees in Spain and Geneva have led to “devastating” job losses.

“In order to manage the costs of employment, Uber would be forced to consolidate hours across fewer workers,” she said. “Drivers and couriers would need to apply for an open role, if one is available; show up for shifts at specific times and places; accept every trip they receive; and agree not to work on other apps.”

Díaz denied, however, that changes in the law would hit Uber’s profitability in Europe. “This isn’t about Uber’s profits,” she said. “We have already proven our ability to grow in places like Germany and Spain using a third-party employment model.”

In Germany, Uber contracts fleet management companies, who employ their drivers, in order to operate under local rules. Uber says its prices are higher in Germany as a result and its ride-hailing service is only available in major cities where it can expect a steady stream of demand.

In the UK, following a high-profile court ruling in 2021, Uber operates under a different model: its drivers are designated as “workers”, entitling them to benefits such as holiday pay and sick leave, while falling short of full employee status.

Despite the warnings from Uber and rivals in the sector such as Bolt about the proposed platform worker rules, EU officials have pushed back at what some see as the tech industry’s lobbying tactics.

At the launch of the EU’s proposal, Nicolas Schmit, EU commissioner for jobs and social rights, said: “This is about establishing clear criteria and looking at the facts. If the platform is in fact an employer, then the people working for it are entitled to the same rights and protection as workers in the ‘offline’ world.”

FT : Dithering and indecision: the British infrastructure curse

Dithering and indecision: the British infrastructure curse
Failure to make and stick to plans means big projects cost far more than they should while hampering their benefits

When not writing this column, I am overseeing my own once-in-a-generation infrastructure project. As dust levels rise and bank balances fall, I am determined to relieve bedroom bottlenecks and improve cohabiting comfort while maintaining the fiscal discipline that my mortgage provider demands. 

As such, I am pioneering a world-first save on stairs programme (SoS). The value of my extra home capacity will not be compromised by near-term reliance on alternative connectivity arrangements, like ladders or perhaps a rope. Thanks to the UK government and its work on HS2 for inspiring this innovative solution.

The £100bn high-speed railway is becoming the poster child for the curse of British infrastructure. Depending on who you ask, it is too big, too expensive, or the wrong thing to be doing to start with. Even its supporters (me included) despair. After axing the eastern leg to Leeds, the government is considering scrapping the western leg to Manchester and ending the route outside central London at Old Oak Common. What benefits would remain? “Virtually none,” concludes one person involved in its lengthy inception. 

HS2’s wider benefits were never well understood or communicated. Speedier trains mean shorter journey times. But a high-speed line should also free up capacity elsewhere for more local services or freight, and act as a backbone to other improvements. Now, as political will fades, the congested capital may not have easy access to HS2 and the part of the country that should benefit most (the north) faces being cut out entirely. Yet the 2020 Oakervee review, the basis for HS2’s approval, said “the full network is needed to realise the benefits of the investment”.

Indecision is both a symptom and cause of Britain’s infrastructure plight: that everything costs so much to build. My colleague John Burn-Murdoch has looked at how sclerotic planning and nimbyist tendencies push up costs, with rail projects, road lanes or motorway bridges far more expensive than in most other countries. Another issue is the UK’s peculiar inability to write down a long-term plan for its infrastructure, debate it and stick to it.

Dithering is inherently costly in building projects. Bills tick up while everyone deliberates. Contracts must be recut. An industry rule of thumb holds that a fifth of a project’s capital cost goes to design and development. Each efficiency or change risks writing off past work and incurring more design costs, especially for something as complex as HS2. 

Political thumb-sucking, and disinclination to commit to steady spending over the medium to long term, are particular problems. The UK is a laggard in rail electrification, with costs ballooning to as much as three times over the initial budget because of a lack of consistency, argues Sam Dumitriu from campaign group Britain Remade. Germany has plodded along electrifying 200km of lines a year; the UK has bounced from nearly 600km in some years to zero in others. 

Bemoaning start-stop investment isn’t new: a 2010 Treasury report into “excessively high” infrastructure costs found that “the lack of visible and continuous pipeline of forward work flow” was one of the biggest issues to address.  

One knock-on effect is in skills, both in industry and government. Despite efforts such as the Major Projects Leadership Academy, the ability of the civil service to oversee big infrastructure development remains questionable, meaning greater reliance on consultancies. Companies have little incentive to invest in training and career development without a pipeline of work. Specialist skills, such as that taught at the welding academy set up for the nuclear construction at Hinkley Point C, dwindle when there isn’t more work to move on to. Knowhow isn’t transferred from one (preferably standardised) project to the next. 

A patchy pipeline contributes to a fragmented UK sector, again something flagged in the 2010 report. Companies don’t build bigger in-house capabilities or invest in advanced technology when their biggest client is erratic. The UK’s biggest construction group, Balfour Beatty, with about £9bn in revenues last year, is dwarfed by French or Spanish contractors such as Vinci with €62bn in revenues or ACS with €34bn. 

Large UK contractors employ only 14 per cent of the construction workforce, with 86 per cent in small and medium-sized enterprises, according to Noble Francis at the Construction Products Association. “The volatility of infrastructure demand means that the business models of contractors are not based on the most efficient ways of working but on dealing with volatility, which means subcontracting out the cost, activity and risk to smaller specialist contractors,” he says. 

If I ever embark on another personal infrastructure project, I will have learnt from current experience. It’s not obvious that the UK, over many decades, can say the same.

>>> US After Hours Summary: CATC +22% to merge with EBC; JPM increases dividend;

After Hours Summary: CATC +22% to merge with EBC; JPM increases dividend; HAIN +4.8% CEO bought shares

After Hours Gainers:
Companies trading higher in after hours in reaction to earnings/guidance: SCS +2.8%
Companies trading higher in after hours in reaction to news: CATC +22% (CATC to merge with EBC), ATRA +8.2% (to submit Tab-cel BLA in Q2 following FDA agreement on comparability), HAIN +4.8% (CEO bought 10000 shares), NNDM +4.8% (receives approval from Israeli court to resume share repurchase plan), SLVM +2.5% (increases regular dividend by 20%; also declares special dividend of $0.30/sh), AGX +2% (increases dividend), AKAM +1.3% (amends by-laws), AJG +1% (to acquire Eastern Insurance Group), TRTN +0.5% (BIP receives all regulatory approvals to complete TRTN acquisition), INTC +0.5% (provides update on CNBC), PINS +0.4% (authorizes $1 bln stock repurchase program), HPE +0.3% (makes changes to its organizational structure and executive leadership; creates new Hybrid Cloud business unit), TPC +0.1% (awarded $47 mln National Park Services project)

After Hours Losers:
Companies trading lower in after hours in reaction to earnings/guidance: None
Companies trading lower in after hours in reaction to news: SKIL -5.6% (approves 1-for-20 reverse stock split), TSHA -3.4% (discontinuing development of TSHA-120 in GAN), PR -1.7% (stock offering), EBC -0.2% (CATC to merge with EBC), ETD -0.1% (plant in Vermont, resumes ops)

TechCrunch : AI startup speeds up the creation of climate-resilient crops

AI startup speeds up the creation of climate-resilient crops
Image Credits: Bryce Durbin / TechCrunch

Creating crops that’ll endure climate change — think worse droughts, heat waves and pests — is a time-consuming and costly feat. Avalo is betting its machine learning models can speed that process up and make it a whole lot cheaper too.
The Durham, North Carolina–based startup, which pitched onstage at the TechCrunch Disrupt Startup Battlefield competition, doesn’t edit plant genes or breed crop varieties the traditional way. Instead, the AI company aims to supercharge crop breeding by quickly identifying the genetic basis of complex traits, such as heat tolerance.

In doing so, Avalo avoids much of the guesswork and waiting typically involved in crop breeding. CEO Brendan Collins explained in a call with TechCrunch, “We actually don’t care about the plant expressing the [desired] trait in the field, because we just genotype all the seedlings, and we know which ones are going to be the winners and which ones are going to be the losers already.”

Instead of testing crosses annually, Avalo “can bring seedlings into growth chambers and greenhouses and breed them under accelerated conditions,” said Collins. For most row crops, that translates to “four development cycles” in a single year versus just one, the CEO added.

The process is based on Avalo science chief Mariano Alvarez’s post-doctoral studies at Duke. TechCrunch did a deep dive into it two years ago, when Avalo had only secured a $3 million seed round. The startup has since raised another $3 million and today announced its intent to raise a $10 million Series A this fall.

According to Collins, Avalo proved its process recently when it created a fast-maturing broccoli variety for a vertical-farming startup called Iron Ox. Collins says Avalo succeeded, only you can’t try it yet, because the effort collapsed as the vertical-farming bubble popped earlier this year.

Avalo is still working with greenhouses to get the advanced broccoli on the market, but the CEO said he is now more focused on the startup’s other efforts. They include aiding in the cultivation of a latex-producing dandelion; finding and licensing valuable traits, such as pest-resistance, in soy and corn; and a just-launched effort to cultivate drought-tolerant cotton.

(Avalo’s co-founder and COO, Rebecca White, grew up on a cotton farm in Texas, Collins told TechCrunch. It happens that Collins and White were en route to the COO’s family farm when they pulled over to take my call.)

Ultimately, Collins sees Avalo as a company that will democratize access to world-class genomics.

“Since the 1950s, corn has had a 300% yield increase, and that’s because so much effort and money has been put into corn,” the CEO said before posing a question: “What could agriculture look like if we’re able to give that same level of resources for a fraction of the cost to all the other crops in the world?”

Evolving staples to withstand heat and drought isn’t agriculture’s (nor agtech’s) sole response to climate change.
Resilient crops overlooked or even previously outlawed by colonizers, such as amaranth, are getting renewed attention. Rising temps mean famers are also putting money toward crops that would not have previously thrived in their respective growing regions. That’s why you’ll see more mangos and avocados in Northern California and more grapevines in the U.K.

On the tech side, numerous companies are exploring ways to re-create beloved flavors with fewer resources. Berkeley Yeast modifies yeast to taste hoppy, giving brewers the option to ditch water- and energy-intensive hops altogether. Atomo, a “beanless coffee” startup, takes a less academic route; it combines roasted date seeds and chicory to make its oat lattes, and in doing so it avoids the cultivation of water-intensive coffee beans.

There are also plenty of tech firms exploring new ways to limit water and fertilizer waste, such as Verdi, SupPlant, Pivot Bio and Carbonwave. Avalo has some comparably more-direct competitors in crop discovery, too, including Keygene and Benson Hill.

TechCrunch : Beyond Aero is building a hydrogen-powered jet

Beyond Aero is building a hydrogen-powered jet
Image Credits: Beyond Aero

The aviation industry is well aware of its carbon footprint, but it’s not an industry where things change quickly. Batteries may be an option for short-range eVTOL use cases, but for anything else, they still weigh too much compared to the amount of energy they can hold. There’s another option, though: hydrogen. That’s what Toulouse, France–based Beyond Aero is betting on, as it looks to bring a hydrogen-powered business jet to market.

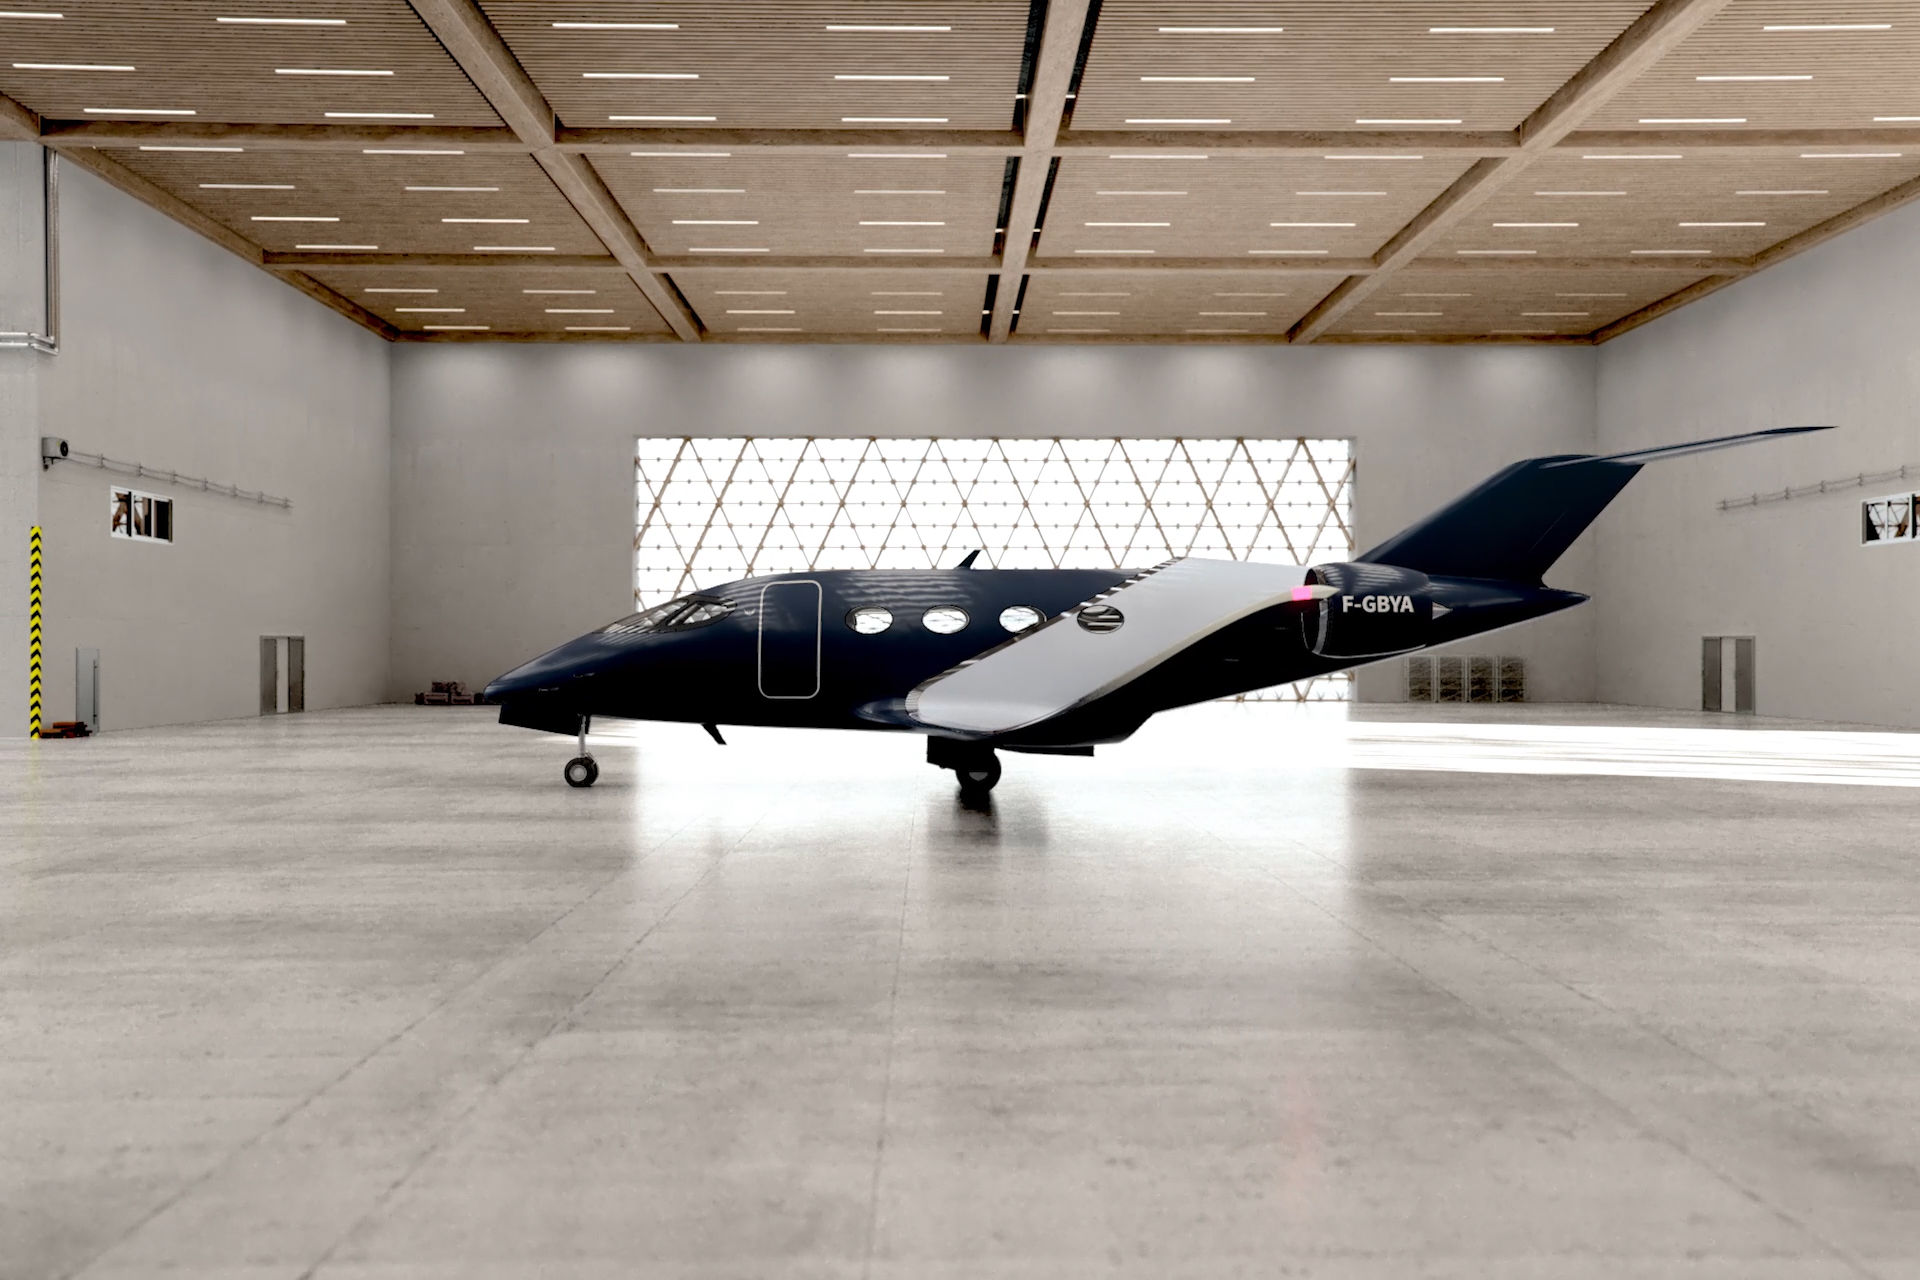
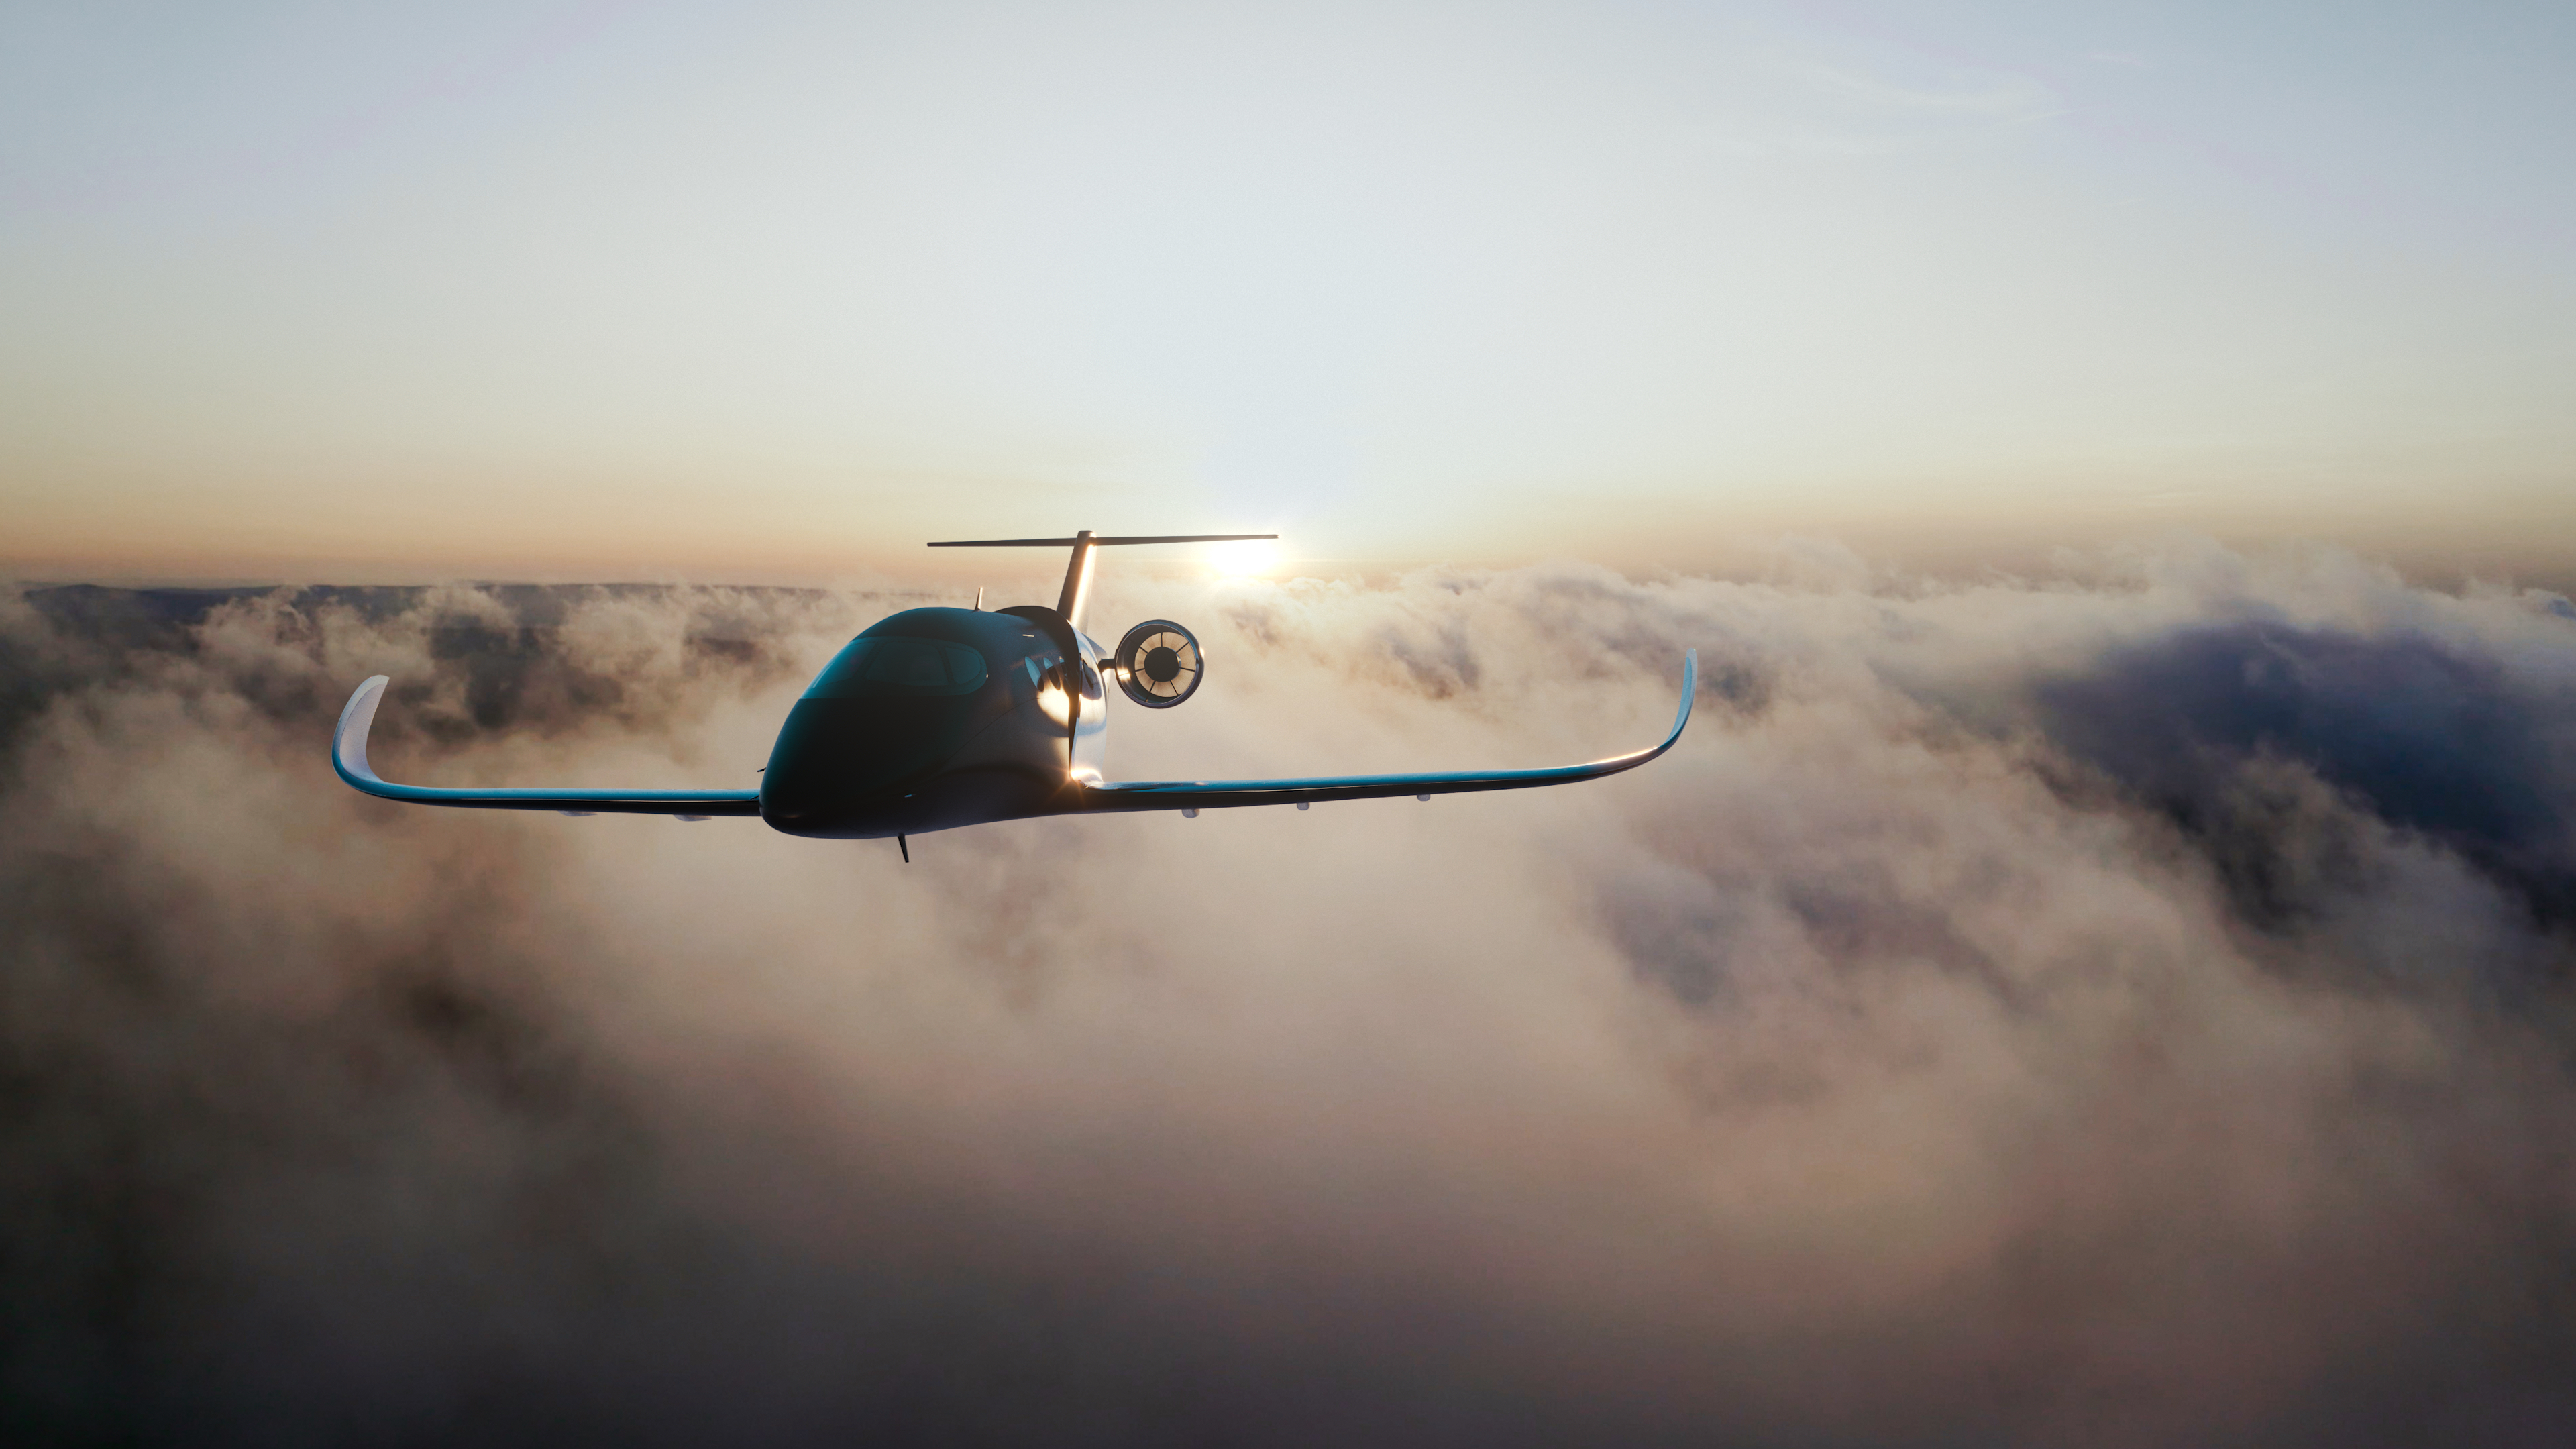
The company, which is part of our Battlefield startup competition at Disrupt this week, is currently ground-testing an 85 kW hydrogen-based propulsion system, with flight tests of its single-engine test bed scheduled for later this year. The company plans to launch with a business jet, the Beyond Aero One, with a range of up to 800 nautical miles, a speed of about 310 knots (or just over 356 miles per hour) and seating for up to eight passengers. The vision is significantly broader, though, with plans to launch a commuter jet and potentially even larger planes in the future.

Image Credits: Beyond Aero

The company was founded by longtime friends Eloa Guillotin (CEO), Hugo Tarlé (CTO/COO) and Valentin Chomel (Product and Strategy). While Guillotin and Tarlé are in entrepreneurship, Chomel worked in the aerospace industry before. While working on flight test instrumentation at Safran, one of the world’s largest aircraft equipment manufacturers in the world, he discovered eVTOLs and hydrogen propulsion systems. Chomel started his PhD, focusing on the technology roadmap to electrification, but in the evenings, he would end up talking to his two friends who were also looking for what to do next and dabbling in IoT and sports tech.

“I said, ‘Guys, you are passionate about aircraft, let’s build an aircraft as a company.’ There is a huge market opportunity because everything will need to change,” Chomel told me.

Things started snowballing from there, with Chomel then quitting his PhD and the three of them starting the company from the ground up.

Chomel argues that in many ways, it’s easier for a startup to build an aircraft from the ground up than for a large business like Boeing or Airbus to make the switch from their existing systems to something entirely new. The founders also argue that it will take a very long time before electric aviation will take off. Hydrogen fuel cells, on the other hand, are already being deployed widely in heavy ground transportation, including buses and trucks. “Basically, our aircraft is three trucks,” Chomel joked.


Image Credits: Beyond Aero

The challenges, he noted, are mostly around hydrogen storage and thermal management for hydrogen in an aviation setting. The company has a number of patents around this already. One involves placing the hydrogen tanks in a fairing under the aircraft’s main body, while another covers a heat management system. The hydrogen system needs a relatively large heat exchanger, which would create additional drag on the plane, reducing its range and with that, its usefulness. “All of our IP is in how to make a hydrogen aircraft — not how to make a hydrogen powertrain. We haven’t revolutionized that,” he said. Instead, the team’s focus is on integrating all of these systems.

Beyond Aero’s current focus is on getting its demonstrator into the air and testing its core assumptions. After that, it will start work on the business jet. Given the massive carbon emissions of business aviation per passenger mile flown, the team believes that this isn’t just technologically achievable but also a massive market that is asking for an alternative to today’s jet fuel–burning engines. “We want to meet a market with clients that have a problem with the public image [of private jet ownership], personal conviction or ESG goals of their company,” Chomel said. Those clients have millions of dollars available to buy a Falcon or Gulfstream, but those players don’t offer any alternatives either.

Beyond Aero was part of Y Combinator’s Winter ’22 batch. The company raised funding before joining YC, during and after, for a total of three rounds so far, with Initialized, Air France and a number of unicorn founders investing in the company over the course of these rounds.

The team argues that it can rely on the vast existing aviation ecosystem for acquiring all of the parts it needs to build its plane, including the actual airframe. One challenge it will likely face, though, is ensuring that enough aircraft have hydrogen available for its plane to refuel. Hydrogen itself is already widely available, but there is no refueling infrastructure yet and there is obviously a bit of a chicken-or-egg problem here: Nobody is going to buy a jet they can’t reliably refuel and nobody is going to invest in building that infrastructure until there is demand.

Chomel argues that airports would only need to have a mobile hydrogen tanker trailer available, though even that takes a bit of an investment, all while these airports are also looking to move to sustainable aviation fuel and away from leaded 100LL fuel for the general aviation piston fleet.

>>> US Close Dow -0,31% S&P -0,22% Nasdaq -0,23% Russell

Closing Stock Market Summary
The major indices ended the day in negative territory, but closed well off their lows of the day, paced by the ebb and flow of the mega cap stocks. The Vanguard Mega Cap Growth ETF (MGK) had been down 1.0% at its low before closing with a 0.2% loss. Other stocks, however, also improved in the afternoon trade.

The market-cap weighed 500 and the Invesco S&P 500 Equal Weight ETF (RSP) both fell just 0.2%. Market breadth was negative, but modestly so. Decliners had a less than 3-to-2 lead over advancers at both the NYSE and the Nasdaq.

An intraday pullback in crude oil, which topped $92.00/bbl earlier in the session, aided the afternoon recovery effort. WTI crude oil futures settled 0.04% lower at $90.49/bbl.
The overall negative bias was partially driven by hesitation in front of Wednesday's FOMC announcement, which will also feature an updated Summary of Economic Projections and dot plot.

Rising market rates acted as another headwind. The 2-yr note yield rose eight basis points to 5.12% and the 10-yr note yield rose five basis points to 4.37% despite a $13 billion 20-yr bond reopening that was met with solid demand.

Only two of the S&P 500 sectors closed in the green -- health care (+0.1%) and communication services (+0.01%) -- while the energy sector (-0.8%) saw the largest decline.

Instacart (CART 33.70, +3.70, +12.3%) was an individual stock standout. The company priced its IPO at $30/share last night, opened for trading at $42, but gave back a big chunk of that opening gain.

  • Nasdaq Composite: +30.7% YTD
  • S&P 500: +15.7% YTD
  • S&P Midcap 400: +5.3% YTD
  • Russell 2000: +3.7% YTD
  • Dow Jones Industrial Average: +4.1% YTD
Today's economic data was limited to housing starts, which hit their lowest level in August (1.283 million) since June 2020, and building permits -- a leading indicator -- which were up 6.9% month-over-month to a stronger-than-expected 1.543 million with permits for single units up 2.0%.

Wednesday's economic calendar features:
  • 7:00 ET: Weekly MBA Mortgage Index (prior -0.8%)
  • 10:30 ET: Weekly crude oil inventories (prior +3.96 mln)