>>> TradeGate Pre-Market Indications

DAX:
  • VW (VOW3 TH) -1.1%
  • Infineon (IFX TH) -2.1%
    • STMicro Outlook Misses as Industrial Chip Slump Drags On (1)
MDAX:
  • Aixtron (AIXA TH) -1%
  • Aroundtown (AT1 TH) -1.4%
    • Bloomberg Europe Corporate Index Up, OAS Unchanged
  • Jenoptik (JEN TH) -1.5%
SDAX:
  • PVA TePla (TPE TH) +1.2%
  • flatexDEGIRO (FTK TH) -1.2%
  • MorphoSys (MOR TH) -1.3%
    • German Holdings Round-Up: Nagarro, MorphoSys, Covestro
  • Norma (NOEJ TH) -2.1%

>>> Europe : Brokers Upgrades & Downgrades - 25th of January 2024

>>> Up
* ASML ADRs PT Raised to $1,000 from $850 at Argus
* ASML ADRs PT Raised to $950 from $855 at Wells Fargo
* ASML ADRs Raised to Buy at Fubon; PT $980
* Bawag Raised to Accumulate at Erste Group; PT 56 euros
* Buzzi SpA Raised to Buy at Berenberg
* FDJ Raised to Outperform at BNPP Exane; PT 43 euros
* Pihlajalinna Raised to Accumulate at Inderes; PT 8 euros

>>> Down
* Castellum Cut to Hold at Arctic Securities; PT 150 kronor
* Everfuel Cut to Neutral at SpareBank; PT 10 kroner
* Hertz Cut to Neutral at JPMorgan; PT $11
* Nurminen Logistics Cut to Accumulate at Inderes; PT 1.40 euros
* Puma Cut to Hold at Jefferies; PT 40 euros
* Puma Cut to Neutral at Oddo BHF; PT 44 euros
* UniCredit Cut to Hold at Deutsche Bank; PT 27.90 euros

>>> Initiation
* Ashtead Reinstated Buy at Panmure Gordon; PT 6,333 pence
* Brembo Rated New Buy at Berenberg; PT 14 euros
* Direct Line Resumed Overweight at JPMorgan
* Grainger Rated New Buy at HSBC; PT 295 pence
* GSK ADRs Rated New Equal-Weight at Morgan Stanley; PT $44

>>> Call
* Deutsche Bank’s Nolting Says US Stocks Ripe for a 10% Drop (1)
* Puma Cut at Jefferies, 2024 Guidance Difficult to Reconcile

>>> What to look at today - 25th of January 2024

Most Asian stocks rose, led by a rally in China and Hong Kong, as investors bet that the latest stimulus measures from Beijing provide a floor for the country’s cratering stock market. Shares in Hong Kong and mainland China rallied, adding to Wednesday’s sharp gains, after the People’s Bank of China surprised investors with plans to cut the reserve requirement ratio for banks next month and hinted at more. Stocks in South Korea and Japan declined. SK Hynix Inc., the world’s no. 2 maker of memory chips, dropped as investors assessed its fourth-quarter results and the outlook on the chip sector. US equity futures were little changed. PBOC Governor Pan Gongsheng said Wednesday the RRR will be cut by 0.5 percentage points on Feb. 5 to inject 1 trillion yuan ($140 billion) in long-term liquidity. The regulators followed up the PBOC announcement by adding more measures to bolster the slumping property and stocks.  Still, doubts persist if the latest monetary stimulus will prove to be the panacea investors have been hopping for after a turbulent start to the new year. Since 2020, cuts to the RRR have not boosted China stocks, with CSI 300 benchmark losing nearly 4% three months after such a reduction.  Meanwhile, the dollar strengthened against all of its major Group of 10 peers and treasury yields steadied in Asia trading after 30-year yields climbed to the highest level so far this year in Wednesday’s session following a poor auction.  In Japan, yield on the benchmark 10-year government bond climbed after a sharp jump Wednesday as investors bet that the Bank of Japan remains on track to end its negative interest rate policy later in the year. Later Thursday, focus will shift to the European Central Bank. While policy makers are expected to keep rates on hold this week, attention will be on clues for the path forward. Euro-area data Wednesday showing private-sector activity contracted again in January points to the ECB holding off from rate cuts till June, according to Bloomberg Intelligence. In the US, investors will parse a slew of US economic data — including gross domestic product — due Thursday, as they mull when the Federal Reserve will cut interest rates.  Oil advanced to trade near a one-month high after US crude inventories dropped by far more than expected. US After Hours IBM +7.2%, RMD +6.6%, URI +4.4%, LVS +2.9% higher on earnings; ETD -8.1%, HXL -8%, TSLA -3.5% lower on earnings.

Nikkei +0.03% Hang Seng +2.14% CSI +1.85% Shanghai +2.88% Shenzen +2.40%

Eur$ 1.0876 CNH 7.1670 CNY 7.1622 JPY 147.77 GBP 1.2710 CHF 0.8647 RUB 88.8149 TRY 30.2627 WTI$ 75.39 +0.40% Gold 2,016 +0.10% BTC 39,940 +0.40% ETH 2,212 -0.16%

S&P +0.05% Nasdaq +0.02% EuroStoxx -0.10% FTSE -0.21% Dax -0.22% SMI -0.16%

Macro :
- Deutsche Bank’s Nolting Says US Stocks Ripe for a 10% Drop
- UK Makes 1 Million Vehicles Again for the First Time Since 2019
- EU Sees Power Generation Doubling by 2050 to Reach Net Zero

Keep an eye on :
- AF FP : Dutch Govt Likely to Postpone Schiphol Flight Cap Again: FD
- ASY FP : Assystem Sells Its 5% Stake in Framatome to EDF for €205M
- BA US : Boeing Halted From Further Max Production Increases by FAA --> -3%
- BA US : Panama’s Copa Air Plans to Restart 737 Max 9 Flights Thursday
- BA US : *UNITED SAYS IT WILL RESUME MAX 9 FLIGHTS STARTING ON JAN. 28
- BA US : Alaska Air to Bring First 737-9 Max Back Into Service Friday
- IAG LN : IAG’s €400 Million Air Europa Deal Gets EU In-Depth Probe
- CA FP : Carrefour to Buy 31 Stores From Intermarché
- CDI FP : Reporting today Post Market
- CGON US : CG Oncology Raises $380 Million in Nasdaq IPO Priced Above Range
- DD US : *DUPONT SUFFERS WORST DAY SINCE 2008, CLOSING LOWER BY 14%
- EDF FP : Fr. government presses the UK to help fill multibillion-pound hole in nuclear projects - FT
- EDPR PL : EDP Renovaveis Secures 15-Year PPA to Sell Energy in Germany
- ELM LN : KPS Explored, Paused Takeover Offer for UK’s Elementis: Reuters
- EMMN SW : Emmi FY Sales Meets Estimates
- ESSITYA SS : Essity 4Q Net Income SEK2.89B
- GET FP : Getlink 4Q Revenue Meets Estimates
- GIVN SW : Givaudan FY Ebitda Misses Estimates
- GRNG SS : Granges 4Q Adjusted Operating Profit Beats Estimates
- HMB SS : H&M Inks Deals for Clean Power From New Solar Parks in Sweden
- MC FP : Reporting today Post Market
- MAERSKB DC : Maersk Confirms Attempted Attacks on Two Vessels Near Red Sea
- MDM FP : Maisons du Monde 4Q Sales EU329.6M Vs. EU358M Y/y
- MAU FP : Maurel & Prom Says Has Made Proposals to Gabon on Assala
- MSFT US : Microsoft Closes at Record, Ends Just Shy of $3 Trillion Value
- AERO SW : Montana Aerospace Misses ‘23 Sales Goal on E-Mobility Challenges
- NETC DC : Netcompany Sees 2024 Adjusted Ebita Margin 15% to 18%, Est. 14%
- NOKIA FH : Nokia 4Q Adjusted Operating Profit Beats Estimates
- PARA US : David Ellison Makes Offer for Redstone Family’s Media Empire
- PPH LN : PPHE Hotel Sees Earnings Above Expectations
- PUB FP : Publicis Prelim 4Q Organic Revenue Beats Estimates
- SBMO NA : SBM Offshore Names Oivind Tangen CEO to Succeed Bruno Chabas
- SEBA SS : SEB to Start SEK1.75b Buyback Program of Class A Shares
- SEBA SS : SEB 4Q Net Interest Income Misses Estimates
- SRG IM : Snam Raises FY Adj Net Guidance, Sees ~4% Annual Growth in Plan
- GLE FP : Societe Generale Mulls Sale of Fintech Shine: Echos (Jan. 24)
- STM FP : STMicroelectronics 1Q Net Revenue Forecast Misses Estimates
- S30 FP : Solutions 30 4Q Revenue EU285.7M Vs. EU247.8M Y/y
- TSLA US : Tesla 4Q Adjusted EPS Misses Estimates
- TSLA US : Musk Wants Dual Class of Stock to Boost Tesla Stake to 25%
- TSLA US : Tesla’s Battery-Business Growth Set to Outpace EVs This Year
- TOD IM : Tod's FY Sales Meets Estimates
- TRYG DC : Tryg 4Q Profit After Tax Beats Estimates
- VOW GY : Mexico’s Audi Plant Workers Begin Strike, El Financiero Reports
- VU FP (ex SESL FP) : VusionGroup 4Q Sales EU238.2M Vs. EU153.2M Y/y

TechCrunch : Forget Apple Vision Pro — rabbit r1 is 2024’s most exciting launch

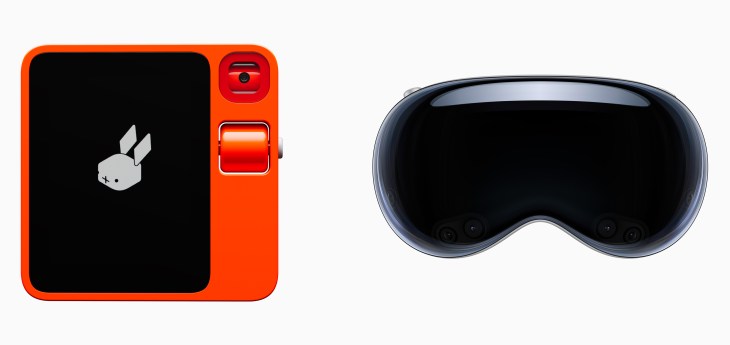
Forget Apple Vision Pro — rabbit r1 is 2024’s most exciting launch yet
Apple is doing everything it can to make VR happen, but a tiny startup has a better vision of the future
Image Credits: rabbit / Apple

The year is off to a quick start in terms of new product launches and availability, even leaving aside the usual mid-tier smorgasbord that is CES. Apple just started pre-sales of its Vision Pro mixed reality headset, with shipments beginning in early February; meanwhile, Samsung debuted the next generation of the only viable iPhone competitor out there, the Galaxy S-series. Despite these heavyweights trying to front-run the year, however, a startup’s oddball take on what the future of personal tech might look like is the most exciting thing to happen in gadgets in a long, long while.

I’m talking about the rabbit r1, the AI-powered hardware unveiled with a fairly impressive, if low-budget impression of an old-school Apple keynote in a small conference room deep within the rabbit’s warren of a Las Vegas casino during CES. The r1 deserves praise just for its physical design, which is a tidy bit of kit created in partnership with Teenage Engineering, the gadget “it” brand of young millennials and Gen Z everywhere.

Unlike the Apple Vision Pro, which looks like the lavish, over-slick encumbered bit of technology’s past masquerading as technology’s future that it is, the rabbit r1 has a pared down, satisfying economy that I think comes much closer to what future generations want from their tech. On the functionality side, Vision Pro is an exercise in UI over saturation; the r1 aims to be as close as you can currently get to having no UI at all.

--> Watch Video of Rabbit 1 : https://bit.ly/42faLU4

The premise of the rabbit r1, in case you missed it, is that it does most, if not all, of what your smartphone can do, but it uses AI to accomplish all the tasks in response to natural language queries. So that could be playing music, booking airfare, providing directions, hailing a ride, ordering food, translating in real time and much more.

There are tons of questions remaining regarding how the rabbit r1 will work in real-world situations, and how rabbit’s business model (which so far seems to only involve selling individual units at a flat price of $199, without any recurring subscription fees) will work. But the rabbit r1 already has the kind of organic hype that would-be competitors like the Humane AI pin wished they’d been able to drum up with their carefully tuned, but massively overblown protracted promo campaign.

On the other hand, we know quite a lot about how Apple Vision Pro works and performs, thanks to a recently expanded hands-on preview program that engaged the media and influencers to come and try out the headset in demos occurring in the run-up to today’s pre-order day, and everyone seems more than impressed with the device’s performance and visual prowess. Reactions are more mixed on everything from the complexity of setup, to user interface elements like the visual keyboard, to long-term wearability and comfort.

The rabbit r1, like the Humane AI pin and other AI-first devices starting to come to market doubtless have a ton of kinks to work out before they get to a place where they’re overall useful, but generative AI already shares something in common with the last major computing paradigm Apple revolutionized — the mobile phone. Specifically, it’s being used and appreciated everywhere by average consumers. I’ve lost count of how many people tell me they just use ChatGPT daily for their actual work, who have nothing to do with the technology industry. The reverse is also true: No one I know who isn’t someone professionally connected to tech owns or regularly uses a VR headset of any kind.

Apple made the iPhone when people were already in love with cell phones and were beginning to fall in love with smartphones. Rabbit is introducing the r1 when people are already in love with AI, as the term applies to large language models like ChatGPT. Apple, meanwhile, is introducing the Vision Pro to a world where a decade or so of trying has utterly failed to create any kind of mass uptake of virtual, mixed or augmented reality headset use.

If Apple is right and “spatial computing” becomes the next big platform shift, I suspect I’ll be too old to care that I was wrong by the time it does. But increasingly, I think companies like rabbit are working with a more realistic and viable version of computing’s future than some of the legacy players out there who are trying, and failing, to shot-call the next big thing.

FT : UK updates water company insolvency laws amid fears over sector’s finances

UK updates water company insolvency laws amid fears over sector’s finances
New rules provide more options for special administrators to restructure groups unable to repay their debts

The UK government is updating water company insolvency laws as fears grow over the financial health of the privatised monopolies — including the country’s largest, Thames Water.

The Department for Environment, Food and Rural Affairs last week quietly issued legislation to update the three-decade-old special administration regime for water monopolies in England and Wales.

The new law provides more options for special administrators to restructure companies that are unable to repay their debts and may make it less likely that the government is forced into renationalising water utilities.

The update comes as fears grow over the financial stability of Thames Water, which is owned by private equity firms, pension funds and sovereign wealth funds.

The company provides water and sewerage services to about 25 per cent of the UK population and is struggling under the weight of its £18.3bn group debt burden.

The legislation contains provisions that will allow a water monopoly to enter administration, restructure its borrowings and then exit as a “going concern”.

Under the current rules, water company assets have to be sold off, and the corporate entity liquidated, if they go into administration. The new rules would allow existing shareholders to potentially retain a stake.

One restructuring lawyer said the new rules could help the government avoid the costs of temporary or permanent renationalisation because a restructuring that retains existing shareholders would be easier.

The lawyer also warned that creditors might suffer bigger losses than they might have under the current regime.

The government said it would take “no ownership or management” of a company under the special administration regime.

Another change enables special administrators to transfer the water company’s assets to a subsidiary and then sell the shares in that subsidiary. 

Kate Stephenson, partner at law firm Kirkland & Ellis, said this change was “intended to maximise value on a sale — by ringfencing the value and enabling potential tax savings, thereby attracting buyers”.

The update, which the government expects to come fully into force by the spring, also ensures that the special administration regime can be used as an “enforcement” tool against water companies that have “performance” issues, according to a Defra guidance note on the legislation.

These include a utility breaching its “statutory functions or licensed activities to such an extent that it is inappropriate for the water industry company to hold its appointment,” Defra said.

Experts added that this could include water supply and sewage pollution issues. Water companies are facing a number of court cases over sewage pollution that could find them in breach of licence conditions.

Colm Gibson, managing director at Berkeley Research Group, said investors should pay attention to the “increasing emphasis on using special administration for companies that perform poorly”.

“These changes make it harder for shareholders to mount a legal challenge if they disagree with the special administrator,” he added.

Defra said the “modernisation” of the law was intended to ensure that the “legislation for the Water Industry Special Administration Regime reflects modern insolvency and business practices . . . and to ensure the uninterrupted provision of vital public services”.

The special administration regime for water monopolies in England and Wales was drawn up soon after the industry was privatised in 1989.

It allows the regulator, Ofwat, or the secretary of state to appoint special administrators from private insolvency companies to manage the business in the case of a financial collapse so that essential services can be kept running.

Ofwat is concerned about the financial stability of several water companies, which are facing higher energy, labour and financing costs. They have asked the regulator to agree steep increases to customer bills between 2025 and 2030. A draft decision is expected in June.

Thames Water said: “Thames Water Utilities Limited is in a solid financial position and has supportive shareholders.” Ofwat declined to comment.

FT : Lithium price plunges on slowing Chinese demand for electric vehicles

Lithium price plunges on slowing Chinese demand for electric vehicles
Miners slash costs and scale back plans to increase production after battery metal’s price plummets more than 80% in 12 months

Lithium miners are cutting costs and scaling back plans to expand production after slowing demand in China for electric vehicles crushed the price of the battery metal.

The price of lithium has tumbled more than 80 per cent in the past year to $13,200 per tonne, its lowest level since 2020, after excessive levels of supply hit the market, according to data group Benchmark Mineral Intelligence.

The fallout has pushed miners — mainly in Australia, which produces 40 per cent of the world’s supplies — to constrain production as decelerating demand for electric vehicles leaves stockpiles of half-processed material through the supply chain.

“We’re going through a period where too many new projects came online in too short a space of time,” said William Adams, head of commodity markets research at Fastmarkets, a price reporting agency. “We’ve just started to see the pullback.”

While lithium has not fallen as low as its 2019-2020 slump, when it hit a trough of about $6,000 per tonne, the profitability of many producers is stretched at current levels.

Goldman Sachs estimates a surplus of 200,000 tonnes of lithium carbonate equivalent, or 17 per cent of global demand, this year, which will require “substantial supply cuts” to balance the market.

But politicians and executives in Australia worry that it is miners there which are most exposed to the unexpected speed and depth of lithium’s decline, after their projects were the first to feel the ripple effects.


On Wednesday Pilbara Minerals, a key player in Australia’s lithium industry with a A$10bn market value, warned that it would not pay a first-half dividend after a 46 per cent drop in revenue in the three months to December, due to the volatile price for lithium.

Earlier this week Liontown Resources had an agreed A$760mn loan to bring its maiden Kathleen Valley project into production unexpectedly canned because of the sliding lithium price. The lending package for Kathleen Valley, set to be one of the world’s largest lithium mines, was contingent upon a previous, higher price forecast.

The group, backed by Australia’s richest person Gina Rinehart, is reviewing its mine expansion and scrambling to secure a smaller loan after its share plummeted by a fifth, valuing the company at less than A$2.2bn ($1.45bn).

Albemarle, one of the world’s largest lithium companies, has forecast that capital expenditure this year will drop to $1.6bn from $2.1bn in 2023, to conserve cash. It will also cut jobs and $95mn of annual costs.

Core Lithium, operating out of Australia’s Northern Territory, said this month it had stopped mining and was going to write down the value of its assets, as it shifted its business to merely processing stockpiled ore due to the price collapse.

The rush to halt a potential gush of new supplies on to the market comes with manufacturers already struggling to shift the backlog of lithium in global supply chains. In particular, electric vehicle sales have cooled in China, the world’s largest market, and automakers warn of a “bloodbath” from discount wars on unprofitable electric models.

Fully electric vehicle sales increased 84 per cent to 5.4mn units in 2022 but preliminary data suggests growth last year was only 25 per cent, according to official Chinese data.


Australia’s mining minister Madeleine King met industry heads on January 18 to discuss an “urgent plan” to address the impact on local miners of the price crashes in lithium and also in nickel, which fell 43 per cent last year on oversupply issues.

“Commodities traditionally go through natural and cyclical boom and bust cycles, but the potential prolonged impact this could have on Australia’s energy transition, local workforce and development of Australia’s minerals sector is a matter of great concern,” she said in a statement.

Analysts have forecast that China could use the downturn to expand its share and strategic grip across the global lithium market.

Chinese producer Ganfeng Lithium agreed last week to almost double its purchases of spodumene concentrate — a mineral from which lithium can be extracted — over the next three years from Pilbara.

Some Chinese producers of lepidolite, a low-grade, high-cost source material of lithium, have cut output but not as much as expected, says CRU Group, another commodity data firm. New African operations run by Chinese companies are also unprofitable yet less corrective action is being taken, according to CRU Group and Fastmarkets.

“China will see the pullback in prices as an opportunity to stake more claim in the market,” said Adams. “If you look at the huge price increases in 2021 and 2022 for lithium, China managed to react very quickly.”

Martin Jackson, head of battery raw materials at CRU Group, said it was surprising many big western producers were cutting spending as they run some of the industry’s lowest cost operations.

However, he said some prospective producers had “unrealistic” expectations of future prices from the studies that are crucial to securing financing.

Lake Resources, which is planning to develop the Kachi deposit in Argentina, used a long-term price of $31,000 per tonne, he said.

And while the market grapples with the low prices, analysts point out that lithium remains an immature and nascent market, prone to volatile periods.

“Lithium balances are sensitive to small shifts in demand or supply growth, so the market is susceptible to heightened price volatility,” said analysts at Citi. “A supply reaction to the current lower price environment could prime the market for a rebound in the second half of 2024.”
FT : SEC should reconsider proposed rules on capital lock-ups

SEC should reconsider proposed rules on capital lock-ups
Mooted changes could have a negative impact on how the US Treasuries market functions

To maintain financial stability and protect investors, it is critical that companies dealing in government securities are well capitalised at all times.

That seems a clear and obvious goal for regulators. But changes to regulations proposed by the Securities and Exchange Commission may have unintended consequences in this regard, potentially damaging the world’s most important financial market.

Much of the attention over the SEC’s rule changes so far has focused on the proposed expansion of the definition of a “government securities dealer”, drawing complaints from the likes of BlackRock and Citadel. 

If a firm buys or sells enough US Treasuries within a given period of time, the SEC proposes to classify it as a dealer, subject to all of the associated capital, reporting and other requirements. Some commenters (including me) believe that a quantity threshold, on its own, is inappropriate. That rule could capture firms that aren’t actually in the business of providing liquidity to the market, a standard criterion for being considered a dealer.

But the main concern I have raised in a comment submission on the SEC proposals is the potential adverse implications for Treasury market liquidity of putting the newly registered dealers under an existing “capital lock-up” rule. This rule states that a capital contribution to a dealer does not count towards its regulatory capital if it is withdrawn within a year. 

This lock-up could exacerbate episodes of market dysfunction, which will probably become more frequent and severe given the burgeoning size of the Treasury market relative to the capacity of the dealers to cope with the volumes of trading.

Some of the firms that will be required by the SEC to register as government securities dealers rely for capital on parent companies that have other trading businesses.

A parent has the option to move, or downstream, capital to its trading subsidiaries opportunistically, whenever market conditions suggest that expected returns are higher, relative to risk.

If a subsidiary becomes registered as a government securities dealer, then capital downstreamed to that business must not be redeemed for at least a year if it is to be taken into account for regulatory capital requirements.

Thus, to make efficient use of its capital, the parent is likely to choose to trap less of its funds in its government securities dealer.

As a result, when US Treasury market liquidity deteriorates, as happened in the Covid shock of March of 2020, we can expect less capital to be committed to the US Treasury market by firms that must newly register as government securities dealers. Further, capital formation by hedge funds and principal trading firms with separately capitalised trading businesses would probably also be reduced.

As a simplified illustrative example, suppose a parent has trading subsidiaries A and B that are not regulated as dealers. In March of a given year, a supply shock presents a significant profit opportunity for firm A. The parent transfers $100mn of capital to firm A to backstop risky new positions. 

By April, the positions that were added by firm A in March are liquidated and $100mn of capital is returned to the parent. Then, in June, a big profit opportunity for firm B leads the parent to downstream $100mn of capital to B. Had firm A been subject to the SEC’s capital lock-up rule, however, this flexible approach to deploying parent capital would not be possible. 

The $100mn capital contribution to firm A would not count towards the regulatory definition of capital for the business unless it stays with it for a year. Aware of this in March, perhaps the parent would have invested only, say, $40mn of its capital in firm A. This would leave $60mn of discretionary parent capital available to address new profit opportunities for firms A and B at later points in time over the subsequent year.

I think the SEC is right to expand the definition of a dealer. However, the commission may also want to consider an amendment to its capital lock-up rule. It should allow capital contributions to count towards the definition of regulatory capital even if withdrawn within a much shorter period of time than one year, provided that the dealer meets its other capital requirements.

I do not see a good case for requiring contributions of capital to remain in a dealer long after they are needed to buffer actual solvency risks. This is a chance for the SEC to reconsider the impact of its rules on Treasury market liquidity.

FT : Signa moved more than €300mn to René Benko-linked entities before insolvenc

Signa moved more than €300mn to René Benko-linked entities before insolvency
Documents show administrator does not expect the money to be recouped

A Signa Group company transferred more than €300mn to two entities controlled by the family of its Austrian founder René Benko before the collapse of the property giant, according to financial documents reviewed by the Financial Times.

Signa Development, one of the three companies that oversaw the conglomerate’s investments — which include a stake in New York’s Chrysler building — lent €125mn to Laura Finance Holding GmbH and another €190mn to Laura Holding GmbH, as part of large outflows of money last year, the documents show.

Both recipients are subsidiaries of the Innsbruck, Austria-based Laura Foundation. While its beneficiaries are not disclosed, the foundation is controlled by Benko’s mother, Ingeborg, according to Austrian public records. Benko’s daughter is called Laura.

The failure of Signa, whose portfolio also includes stakes in London’s Selfridges and Berlin’s KaDeWe, has been a high-profile sign of the stress across the European commercial property market following a rise in interest rates. But lenders facing billions of losses are now raising questions over how the complex, leveraged web of companies was run under the effective control of its 46-year-old politically connected billionaire founder.

The Financial Times spoke with Signa creditors and advisers to the group and reviewed three years of internal accounts, shareholder presentations, and its non-public insolvency filings for Signa Development to substantiate information about the transfers.

Details of the transfers to the Laura entities only came to light on December 29, when after weeks of silence, creditors received documents from Signa’s lawyers relating to insolvency proceedings and the group’s balance sheet. Creditors have been given no explanation of what the transfers were for, people close to the lenders said.

The administrator expects to recover none of the money, according to Signa Development’s insolvency filing.

As well as the payments to the Laura companies, Signa Development transferred hundreds of millions to other Signa group entities.

The way Benko ran the Signa group meant large sums of money were often lent between corporate entities in its structure, without explanation to investors. That practice ramped up in the last year as the Signa Group’s finances came under increasing strain.

Signa Development’s management and administrator did not respond to requests for comment.

Benko did not respond to a request for comment via his personal corporate email address.

Under the Austrian “self-administration” insolvency procedure, Signa Development’s own management team is overseeing the restructuring of the company. Erhard Grossnigg, an insolvency expert, has been brought on to the company’s board to help. A third-party administrator, Andrea Fruhstorfer of the Austrian law firm EcoLaw is supervising the process.

The Signa Group’s collapse is one of the most complicated corporate bankruptcies in Europe. The conglomerate never published consolidated accounts, and its three holding companies have different administrators, management teams and creditor groups.

Before its collapse, Signa estimated its property assets to be worth €28bn.

Christoph Stapf, the administrator appointed to oversee the wind-down of Signa Holding, the group’s main company, said last month that the group’s organisation chart, which he had only just finished reviewing, ran to 46 A3 pages.

The group comprises more than 1,000 corporate entities. Signa Development alone sits on top of more than 250 of them.

Benko held no formal managerial role in Signa after being convicted for bribery by an Austrian court in 2013. However, he exercised control through a shareholding structure ultimately linked to his family foundations that made him one of only a handful of people able to understand the functioning of the group.

The line between his personal interests and those of the company was often blurred. Privately controlled shell companies linked to the Laura Foundation invested in developments alongside other Signa entities, and Signa Holding funded personal properties used by the tycoon and his private jet, according to corporate organisation charts seen by the FT.

Over the years Benko succeeded in bringing on board dozens of external shareholders and lenders at various levels of the Signa structure.

Signa Development creditors — which include dozens of European banks, owners of profit participation notes bondholders and third-party shareholders — were blindsided by disclosures in November about the company’s health, said several of them, speaking under the condition of anonymity.

Signa Development disclosed long-overdue accounts for the first half of the year to them early that month, revealing only €32mn left as cash equivalents.

Following the successful sale of several large assets in the second quarter, creditors had been expecting to see a figure nearly 10 times that sum, people close to them said.

In its first-quarter earnings, Signa Development had also told investors the company had a €1bn capital cushion.

In explaining where the cash had gone, Signa Development said that it had lent hundreds of millions of euros “through the ordinary course of business cash management operations with Signa Group entities”.

Signa Developments parent company, Signa Holding, filed for bankruptcy four weeks later.

On December 11, Signa Development’s board announced it had fired the company’s chief executive, Timo Herzberg, with immediate effect, for what it claimed were “gross violations” of his duties. Herzberg did not respond to a request for comment.

Signa Development itself entered insolvency three weeks later — on the final business day of the year.