FT : British Steel owner preparing to bring forward blast furnace closures

British Steel owner preparing to bring forward blast furnace closures
Move by Jingye is expected before Christmas and would put at risk thousands of jobs

The Chinese owner of British Steel is preparing to bring forward plans to close its blast furnaces in Lincolnshire as talks with the government over a £500mn state aid package to move to greener forms of production have stalled.

The closure by Jingye, which would put at risk thousands of jobs at British Steel’s flagship Scunthorpe site and leave the UK unable to make steel from scratch, is expected to happen before Christmas, said people familiar with the talks.

Unions have previously raised fears that about half of the company’s 4,500-strong workforce could be made redundant in such a scenario.

One person close to the talks said a crunch point would come in mid-September and that there were signs of ministers and Jingye not reaching a deal.

“The likely outcome is the blast furnaces at Scunthorpe to close with thousands of direct jobs . . . to go before Christmas,” he said. 

Ministers are meanwhile moving closer to a revised taxpayer-backed accord with Britain’s largest producer, Tata Steel, that will preserve steel making via electric arc furnaces at Port Talbot in south Wales, albeit also with job losses, according to people familiar with the talks. An announcement could come as early as next week, the people said.

The closure of the Scunthorpe furnaces with no compromise deal in place over how to transition to electric arc furnaces would be a blow to the government’s promise that decarbonisation of Britain’s steel industry would not lead to deindustrialisation.

Labour has said it would make £2.5bn available as potential assistance to the industry as it decarbonises. That would be on top of the £500mn already offered to Tata by the previous Conservative government.  

China’s Jingye has been in talks with the government for more than two years over taxpayer aid to help British Steel, the second-largest producer, move to greener forms of production at Scunthorpe.

The company — a key supplier for UK rail — last year proposed keeping its two blast furnaces online while it builds two less carbon-intensive electric arc furnaces as part of a request for more than £500mn in direct investment support. 

As part of its proposal to close the blast furnaces early, British Steel put forward the option of importing semi-finished steel from abroad, including from China, in order to keep supplying its key rail customers while the two electric arc furnaces were built, a process that could take three years.

Such a move would require approval from rail authorities to ensure appropriate safety standards are met. But industry and Whitehall figures said the government was minded to reject any such request.

Colin Richardson, head of steel at price reporting agency Argus Media, said “the sad reality remains, companies cannot produce steel profitably via the blast furnace route in the UK”.

British Steel has previously said it was losing more than £1mn a day and in accounts for 2021, which were signed off only in July this year, said it had made “significant losses” in 2022, 2023 and 2024 so far.

The company told the Financial Times it was in “ongoing talks” with the government about the future of its UK operations and that “while progress continues, no final decisions have been made”.

In the meantime, unions are nearing an accord with Tata on an enhanced redundancy package and investment commitments, paving the way for a deal between the company and the government, people close to the talks confirmed.

Under Tata’s deal with the previous Tory government, it would invest £750mn in the production of green steel via an electric arc furnace, triggering up to 2,800 job losses but preserving steelmaking in Wales.

That agreement was not ratified, however, before the general election in July. The new deal is widely expected to limit compulsory redundancies.

Tata said it continued to “work closely with the UK government to finalise discussions around the Grant Funding Agreement”.

The government pointed to remarks on Thursday by industry minister Sarah Jones, who told MPs the government was “clear that decarbonisation must not mean deindustrialisation”.

Talks over Port Talbot had “advanced in recent weeks”, said Jones, adding ministers continued to hold talks with British Steel “over a similar package vein”.

CrunchBase : Amid Adversity: Israeli Tech M&A Focuses On High-Value Deals In 202

Amid Adversity: Israeli Tech M&A Focuses On High-Value Deals In 2024

Despite the local unrest and economic uncertainty, the Israeli tech industry has shown resilience. In this article I will cover M&A trends since the start of 2024 compared to the same period in 2023. The trend is characterized by fewer but substantially larger deals compared to the previous year with continuing dominance of North American buyers, and a growing domestic M&A appetite.

Fewer deals, larger sizes
In 2024, from Jan. 1 to Aug. 30, there were 36 M&A deals involving tech companies headquartered in Israel, down from 44 during the same period in 2023. However, the median deal size in 2024 surged to $300 million, a dramatic increase from the $39 million median in 2023. This significant jump suggests that, despite the challenging environment, global investors continue to recognize and capitalize on the value of Israeli tech. The number of deals with announced deal sizes also increased slightly from 10 in 2023 to 11 in 2024, highlighting sustained interest and confidence in these transactions.

This report could have been even more drastic had the Google/Wiz $23 billion deal occurred in July 2024.


Total deal values surge
The total value of announced deals since the start of 2024 reached $3.9 billion, nearly quadrupling the $1 billion recorded in the same period during 2023. This surge in deal value underscores the increasing interest from global buyers in acquiring significant Israeli tech assets, particularly in high-growth sectors.
Continuing strong presence of North American buyers and growing domestic consolidation
  • In 2024, North American companies remained key players in the Israeli tech M&A landscape, leading many of the largest acquisitions, although their numbers slightly decreased compared to 2023. Despite the reduction, North American firms, particularly from the U.S., continued to play a dominant role in acquiring high-value Israeli tech assets, especially in AI, cybersecurity and enterprise software.
  • At the same time, there was notable growth in domestic consolidation with an increase in the number of Israeli companies themselves becoming acquirers. This suggests that while global interest remains strong, Israeli firms are increasingly consolidating within their own market to strengthen their competitive positions.
  • European participation also remained steady, indicating sustained interest from Europe in leveraging Israeli technological innovations. These trends underline Israel’s enduring appeal as a hub of technological innovation, with continued engagement from global players, particularly in sectors critical to the future of business and healthcare.

Notable Deals in 2024 and 2023
The Israeli tech M&A landscape in 2024 and 2023 saw several significant acquisitions that underscore the global interest in Israeli innovation.
2024 Highlights:
2023 Highlights:

FT : For European carmakers, EVs are a Catch-22

For European carmakers, EVs are a Catch-22
The uncertain move towards electrification coupled with a slump in sales overall pose investment problems

That European carmakers were going to struggle with the transition to electric vehicles was a given. New, native EV entrants such as Tesla and BYD were always likely to make inroads, leading to share losses for traditional incumbents. The bad news is that a delayed transition is not proving any easier to navigate. 

That was the message emerging from the industry this week. Take Volvo Cars’ decision to water down its 2030 target to go full plug-in electric. This highlights how expectations on the speed of EV take-off have changed. More expensive cars, plus a dearth of charging infrastructure have conspired to slow global growth rates. In Europe, where subsidies have been cut, sales have actually gone into reverse in the past few months.  

But this delay offers no respite for traditional automakers. Their plight is epitomised by Volkswagen, which is considering shutting factories in Germany for the first time in its 87-year history. This comes after the announcement of the potential closure of a Belgian plant over the summer. 

The group’s problem is that people are not just eschewing EVs in favour of traditional cars. They are buying fewer cars overall. Indeed, European unit sales (including the UK and EFTA countries) were 12.8mn in 2023 — far below the pre-Covid peak of 15.8mn in 2019 — and growth in the first seven months of 2024 was an anaemic 3.9 per cent, according to Bernstein. How much of the lost volume is cyclical and how much is structural is anyone’s guess. (VW itself is not optimistic.) But at this rate, it will not be regained any time soon. 

Ordinarily, carmakers in a slump would rush to launch new, cheaper cars — even at lower margins — to entice consumers and keep factories ticking over. But the uncertain trajectory towards electrification makes it hard to invest in new internal combustion models.

Cheap European EVs, meanwhile, remain a far-off dream. This limbo affects consumers, too, who may be putting off buying a new car until the fog clears. That helps explain Volkswagen’s decision to focus on cutting costs and capacity instead. Already, Harald Hendrikse at Citigroup forecasts, the group will miss its margin target for the year. 

It is hard to see how European carmakers can thrive while the market is in a muddle. And when EVs do finally resume their growth path — as seems inevitable — they will have to grapple with margin dilutive sales and fierce competition. The sector’s path looks anything but smooth.

FT : Talk of a coming crackdown on social media companies is overblown

Talk of a coming crackdown on social media companies is overblown
Brazil’s X ban and Telegram founder’s arrest are exceptions, not the rule

Is the political power of social networks (and their founders) past its peak? Politicians who feel they have been badly treated on social media or worry about a tide of misinformation might be tempted to think so, after two dramatic events that have dominated the tech headlines in the past couple of weeks. But I don’t think this is the turning point some people are saying it is.

The two events in question were the arrest of Telegram founder Pavel Durov in France, and Brazil banning Elon Musk’s X in an escalating fight over his refusal to remove accounts deemed to promote hate speech. It’s tempting to think that it’s getting harder for networks to carry illegal content with impunity.

In fact, Telegram and X have become outliers among social networks, whether for ideological reasons (they both have an absolutist attitude to free speech) or self-interest (they have fewer resources, which would make it hard to apply the kind of content moderation seen on other networks). Most social networks don’t operate this way.

In their book Who Controls the Internet? the US academics Tim Wu and Jack Goldsmith pointed out nearly 20 years ago that governments clearly have the power through local laws to determine what happens online inside their countries. The only question is whether officials have a way to enforce those laws, through seizing assets or arresting the staff of uncooperative companies, or applying some other leverage.

The latest social media showdowns bear this out. Durov, who is based in Dubai, was arrested when his private jet touched down in France, putting himself within reach of authorities. Musk’s confrontation with Brazil came to a head after he withdrew staff out of concern they’d be arrested for not complying with Supreme Court orders (which the X owner alleged amounted to censorship). Brazil then shut down X for not obeying a law that requires it to have local representatives — an example of the so-called “hostage-taking laws” that have become common over the past decade as more countries have tried to exert some power over internet companies based far away.

One wild card here is Musk’s Starlink satellite network, which can beam its signals across national borders. Starlink said over the weekend that it wouldn’t obey Brazil’s order to block X in the country. But Musk has since backed down. Starlink’s accounts in Brazil were frozen and it still needs local regulatory approval to sell its terminals inside the country — evidence that, whatever the appearances, it isn’t beyond the reach of national law.

What’s notable about these cases is that they don’t reflect the passage of new laws to clean up social networks or fresh determination by national politicians to exert their power. They’re the result of an activist judiciary.

As the FT’s John Thornhill points out in this Tech Tonic podcast, Durov’s arrest was actually something of an embarrassment to President Emmanuel Macron, who had been angling to get Telegram to move its headquarters to France.

There’s nothing particularly new about the issues in the Telegram case. It’s accused of turning a blind eye to a wave of illegal material it has been hosting. This is little different to the attack on illegal music sites such as Napster and LimeWire two decades ago. As long as unlawful material like this remains on the “dark web”, it’s hard to control. But once it lands on a site that is within the reach of law enforcement (and the FT’s Hannah Murphy pointed out earlier this year that clearly applies to Telegram) then some kind of action becomes inevitable.

Brazil’s Supreme Court, meanwhile, is trying to apply standards of speech that are enshrined in the country’s constitution. As in many democracies, hate speech in Brazil is considered illegal, unlike in the US. Inevitably, the issue has become a matter of vicious partisan politics, but it’s inevitable that courts will try to draw the lines around what is legally permissible.

Musk, with his penchant for conflict, is highly likely to march into more fights like this around the world. And any network that openly carries illegal material and refuses to co-operate with law enforcement, as Telegram is accused of doing, can expect similar treatment.

But most established social networks have learnt these lessons — and don’t go out of their way to provoke a fight. If anything, they might have gone too far in the other direction, as evidenced by Mark Zuckerberg’s rather startling admission last week that Meta bowed to White House pressure to censor Covid-19 content during the pandemic. He claims he won’t make the same mistake again, though the temptation will always be to accede to political influence like this.

What do you think Rana, should we be seeing what’s going on in Brazil and France as evidence of a new crackdown on social networks? And even if that’s the case, what are the chances it will change what we see online?

Who will win the 2024 presidential election? Join FT journalists for an exclusive subscriber webinar on September 12, as panellists assess who is likely to prevail in the race for the White House. Register for free here.

Recommended reading
In his latest FT column, Elon Musk is an unguided geopolitical missile, Gideon Rachman comes to a different conclusion. He argues that the “age of impunity” is over for social networks and they’ll be regulated more like media companies. We’ll see.

For a deep dive on the havoc Musk is causing around the world with his intemperate tweeting and naively absolutist stance on free speech, read Hannah Murphy’s story: Who’s afraid of Elon Musk. It was published just before things came to a head in Brazil. 

Amid all the hype that surrounds public debate over artificial intelligence, this rather sober look at the practical uses — and limitations — of AI in drug discovery is worth a read. AI could make the discovery process more efficient, though it’s just one tool among many.

Rana Foroohar responds
Richard, what a great topic you’ve raised here. I’ve been thinking about these very same issues. I do think we are reaching a tipping point, not in action per se but in understanding, and I see the big issue here as a square off between public and private power.

Platforms have done a very good job, as big banks before them did, of making the case that they are special and shouldn’t be subject to the laws that other industries and individuals have to abide by. And yet, as you point out, it’s possible for platforms to do a better job moderating something like, say, hate speech if they do what everyone else does — employ people to do it. One key reason that margins are so huge in such firms is that they employ vastly fewer people relative to their market cap or revenue than either traditional media or previous generations of technology firms did. But that comes with risks and governments have a right to take action when the risks threaten their civil societies and democracies. 

And yet, there’s another issue here, which is that even liberals in countries such as the US are still operating with a neoliberal understanding of the world. Consider, for example, the way in which liberal Supreme Court justices like Sonia Sotomayor, Ketanji Brown Jackson and Elena Kagan ruled in Moody vs. NetChoice. They vacated and sent back to lower courts state laws that sought to limit social media companies ability to edit how people communicate on their platforms. That approach essentially gives the platforms power over the state and the people. Private power trumping public power is one of the core problems of the neoliberal approach.

Now, it’s true that if you live in, say, Turkey or Iran, maybe you trust Google more than your government. But do I as an American citizen want to see private companies being given the power to make their own free speech rules rather than the state taking power to set those rules? No, I don’t. I think it simply creates a tailwind for people like Elon Musk, who have way too much power as it is, to take more in ways that threaten liberty and civil society. All this is part of a larger issue, which is the rise of a kind of super capitalism that wants to be free from any public control, which Quinn Slobodian has written about so well in his book Crack Up Capitalism. 

I think that these platforms will ultimately have to become public utilities (if, like Google, they really are necessary for the public good, like water or electricity) and be subject to the same expectations as other regulated companies. If that means hiring actual content moderators is so uneconomical that it puts them out of business, so be it. I don’t think the world would suffer if X went away.

So, I guess my answer to you is that while we haven’t reached a clear silver bullet regulatory solution for how to put Big Tech in check, I think we are slowly but surely coming to understand the stakes here. They aren’t detailed and technocratic (as the companies would like us to believe, since that creates complexity that allows them to obfuscate), but rather simple: do we want to go back to the 19th century, or would we prefer to live in a world in which nations can successfully curb the power of oligarchs?

The Information : What SSI’s $5 Billion Valuation Really Means

What SSI’s $5 Billion Valuation Really Means

It’s the billion-dollar baby of artificial intelligence. Safe Superintelligence Inc., the AI startup launched by former OpenAI chief scientist Ilya Sutskever, announced Wednesday it had raised a whopping $1 billion from big-name venture capital firms, including Sequoia and Andreessen Horowitz.

That’s a huge amount of money for a three-month-old company with 10 staffers, no product and a “singular focus” on creating “safe” AI rather than a money-making product (at least in the short term). While a few other AI startups have raised billion-dollar or greater funding rounds, most obviously Elon Musk’s xAI, as well as CoreWeave and Scale AI, according to Crunchbase, they’re all more advanced, with actual products and businesses.

Even more strikingly, a Reuters article, which SSI offered up as containing more details about the fundraising, said SSI was being “valued” at $5 billion, whatever that means. That ranks SSI as among the most highly valued AI startups around, judging by our ranking of generative AI startups.

To be sure, at this very early stage of SSI’s life, the valuation that its investors ascribe to it is presumably a totally arbitrary number. There’s no revenue to put a multiple against. Maybe the investors are putting a multiple on Sutskever—who worked at Google before co-founding OpenAI—by comparing him to Character co-founders Noam Shazeer and Daniel De Freitas.

Google paid $2.7 billion to get both Shazeer and Freitas when the tech giant agreed to hire most of Character’s staff last month. In other words, SSI’s valuation implies Sutskever is worth nearly two times what Shazeer and De Freitas are. It surely helped that tech investor Daniel Gross, who we profiled here, is a co-founder of SSI with Sutskever.

Of course, crazy valuations are par for the course among AI startups. That was evident from this ranking of valuations for such firms, which my colleague Stephanie Palazzolo put together earlier this year.

That’s mostly due to investor excitement over the potential of AI to change the world, for sure. But a contributing factor may be that major cloud providers and Nvidia have invested in some startups, such as Anthropic, CoreWeave and OpenAI, which in turn end up buying either cloud services or chips from the tech giants. For that reason, the big tech companies can make investments at inflated valuations because they don’t need a financial return from their bets.

Speaking of OpenAI, the ChatGPT creator is reportedly fundraising right now at a $100 billion valuation, which, given the brand name and market strength of its flagship product, may not be that crazy. But the best definition of value is what someone would pay for something in the open market. Would OpenAI fetch $100 billion in an auction? It loses billions of dollars a year and, given the cost of training and running large language models, could be years away from profitability. The need to subsidize the firm to such a degree surely would affect a buyer’s attitude.

By the same token, is there anyone out there who would pay $5 billion to buy SSI right now? If so, Sutskever should just sell now and head for the hills. That would be the quickest fortune he’s ever likely to make.

Verizon’s Round-Trip Sale and Buyback
Cute. Verizon is poised to buy Frontier Communications, according to The Wall Street Journal, the same company that in two separate deals over the past 15 years bought a big chunk of Verizon’s phone lines.

The news sent Frontier’s stock surging 38%, raising its market capitalization to $9.6 billion. That, by the way, is less than the $10.5 billion in cash Verizon received from Frontier when it sold its second tranche of phone lines in 2016.

Those deals didn’t work out too well for Frontier, which took up billions in debt to buy declining businesses (which is why Verizon sold them). Frontier went through bankruptcy in 2020, getting rid of most of the debt. Since then it’s been ramping up its phone line upgrades to fiber, which is capable of delivering superfast internet. If Verizon buys back these businesses, it’ll get the benefit of those upgrades.

Denial of the Day
When is a subpoena not a subpoena? When it’s a civil investigative demand.

Nvidia told the news media today that it had not been subpoenaed by the Justice Department as Bloomberg had reported Tuesday night when it highlighted the news that the DOJ’s antitrust review against the AI chipmaker was moving ahead. Today, however, the news outlet noted that the request for information was in the form of a “civil investigative demand.” That may not technically be a subpoena, but the difference is largely semantic.

>>> US Gapping down

Gapping down
In reaction to earnings/guidance
:
  • PL -10.1%, SWBI -7.6% (also authorizes new $50 mln share repurchase program), AVGO -7.5%, BRZE -5.7%, DOOO -5.4%, DOCU -0.8%, FAST -0.8% (August sales)
Other news:
  • MBLY -3.2% (INTC exploring sale of part of its MBLY stake, according to Bloomberg)
  • AVB -1.9% (prices offering of 3.2 mln shares of common stock for gross proceeds of ~$710.4 million)
  • WBX -1.6% (stock offering by selling shareholders)
  • SERV -1.1% (stock offering by selling shareholder)
  • HUT -1.1% (Operations Update for August)

>>> US Gapping up

Gapping up
In reaction to earnings/guidance
:
  • AGX +21.6%, BOWL +12.4%, NX +11.6%, PATH +7.9% (also CFO to also become COO; also increases share buyback auth by $500 mln), GWRE +7.7%, ABM +7%, BRC +5.8%, IOT +5.3%, AOUT +4.3%, SMAR +4%
Other news:
  • FFIE +20.3% (receives $30 million in financing commitments from the Middle East, the United States, and Asia)
  • TVTX +6.7% (FDA grants full approval of FILSPARI)
  • HELE +6.1% (authorizes new $500 mln share repurchase program)
  • RNAC +6.1% (announces new employment inducement grant)
  • BRC +5.8% (increases dividend)
  • BBW +2.9% (announces deal with KC Chiefs)
  • X +2.3% (CLF CEO appears on CNBC; CLF still interested in acquiring X)
  • ELUT +1.7% (first-ever patient implant of EluPro)
  • PFMT +1.4% (tentative award from NY state)
  • GSK +1.1% (reports Phase III results for Nucala in COPD; meets primary endpoint)
  • NVO +1% (to present new data from key diabetes and obesity trials at the 60th annual meeting of the European Association for the Study of Diabetes)

>>> US Research Calls I

Research Calls I
  • Upgrades:
    • Amneal Pharmaceuticals (AMRX) upgraded to Neutral from Underweight at JP Morgan; tgt $9
    • Carrier Global (CARR) upgraded to Peer Perform from Underperform at Wolfe Research
    • Coinbase Global (COIN) upgraded to Equal Weight from Underweight at Barclays; tgt lowered to $169
    • Eaton (ETN) upgraded to Peer Perform from Underperform at Wolfe Research
    • Fortive (FTV) upgraded to Outperform from Neutral at Mizuho; tgt raised to $90
    • Grupo Aeroportuario (OMAB) upgraded to Overweight from Equal-Weight at Morgan Stanley; tgt lowered to $77
    • Hubbell (HUBB) upgraded to Buy from Hold at Deutsche Bank; tgt raised to $441
    • Intra-Cellular Therapies (ITCI) upgraded to Overweight from Neutral at Piper Sandler; tgt raised to $92
    • NIO (NIO) upgraded to Overweight from Neutral at JP Morgan; tgt raised to $8
    • RadNet (RDNT) upgraded to Overweight from Equal Weight at Barclays; tgt raised to $79
    • Robinhood Markets (HOOD) upgraded to Equal Weight from Underweight at Barclays; tgt raised to $20
    • U.S. Steel (X) upgraded to Outperform from Neutral at Exane BNP Paribas; tgt $40
  • Downgrades:
    • Bloom Energy (BE) downgraded to Hold from Buy at Jefferies; tgt lowered to $11
    • Concrete Pumping (BBCP) downgraded to Neutral from Buy at UBS; tgt lowered to $6.25
    • Fortive (FTV) downgraded to Peer Perform from Outperform at Wolfe Research
    • KBR (KBR) downgraded to Hold from Buy at TD Cowen; tgt $72
    • Organon (OGN) downgraded to Underweight from Neutral at JP Morgan; tgt raised to $20
    • Super Micro Computer (SMCI) downgraded to Neutral from Overweight at JP Morgan; tgt lowered to $500
  • Others:
    • 3M (MMM) initiated with an Underweight at Morgan Stanley; tgt $125
    • Alarm.com (ALRM) initiated with a Neutral at Goldman; tgt $64
    • Allurion Technologies (ALUR) initiated with a Buy at ROTH MKM; tgt $2
    • Amicus Therapeutics (FOLD) initiated with a Buy at Jefferies; tgt $18
    • Archrock (AROC) initiated with an Overweight at JP Morgan; tgt $24
    • Bicycle Therapeutics (BCYC) initiated with an Outperform at RBC Capital Mkts; tgt $35
    • Booking Holdings (BKNG) initiated with a Hold at Truist; tgt $4100
    • Burford Capital (BUR) initiated with a Buy at Deutsche Bank; tgt $18
    • Carrier Global (CARR) initiated with an Equal-Weight at Morgan Stanley; tgt $75
    • Chord Energy (CHRD) initiated with a Hold at Jefferies; tgt $160
    • Corning (GLW) added to 90-day positive catalyst watch at Citigroup
    • Dakota Gold Corp. (DC) initiated with an Outperform at BMO Capital Markets; tgt $6
    • Eaton (ETN) initiated with an Overweight at Morgan Stanley; tgt $370
    • Emerson (EMR) initiated with an Underweight at Morgan Stanley; tgt $105
    • Expedia Group (EXPE) initiated with a Hold at Truist; tgt $148
    • Fastenal (FAST) initiated with an Equal-Weight at Morgan Stanley; tgt $72
    • Finward Bancorp (FNWD) resumed with an Outperform at Hovde Group; tgt $31
    • Fortive (FTV) initiated with an Overweight at Morgan Stanley; tgt $89
    • Gates Industrial (GTES) initiated with an Equal-Weight at Morgan Stanley; tgt $19
    • Grainger (GWW) initiated with an Equal-Weight at Morgan Stanley; tgt $990
    • Honeywell (HON) initiated with an Equal-Weight at Morgan Stanley; tgt $210
    • Hubbell (HUBB) initiated with an Equal-Weight at Morgan Stanley; tgt $407
    • Ingersoll-Rand (IR) initiated with an Equal-Weight at Morgan Stanley; tgt $97
    • Janux Therapeutics (JANX) initiated with a Buy at Stifel; tgt $70
    • Johnson Controls (JCI) initiated with an Overweight at Morgan Stanley; tgt $85
    • MicroStrategy (MSTR) initiated with an Overweight at Barclays; tgt $146
    • Nurix Therapeutics (NRIX) resumed with an Outperform at Robert W. Baird; tgt $26
    • OneSpan (OSPN) initiated with a Buy at Rosenblatt; tgt $20
    • ORIC Pharmaceuticals (ORIC) initiated with a Buy at Stifel; tgt $20
    • Otis Worldwide (OTIS) initiated with an Equal-Weight at Morgan Stanley; tgt $97
    • Perpetua Resources (PPTA) initiated with an Outperform at National Bank Financial
    • Rockwell Automation (ROK) initiated with an Overweight at Morgan Stanley; tgt $320
    • Stanley Black & Decker (SWK) initiated with an Equal-Weight at Morgan Stanley; tgt $107
    • Trane (TT) initiated with an Overweight at Morgan Stanley; tgt $425

(Zero Hedge) Is The "Everything Bubble" About To Pop?

Is The "Everything Bubble" About To Pop?

Among the big winners of the Everything Bubble is--yes, I know you're shocked--Wall Street.
Is the "Everything Bubble" about to pop? Let's start with what we're told: there is no bubble , all the assets soaring to unprecedented heights are reasonably priced at a "permanently high plateau" because of AI, scarcity of housing, scarcity of Ferraris, interest rates trending down, the Fed waving dead chickens around the campfire, people buying toothpaste, and so on: you name it, it's a reason for assets to drift higher.
This all sounds rather splendid, but somehow the pump inflating the bubble goes unmentioned: it's the money, Honey , the tens of trillions of yen, yuan, euros, dollars, pesos, etc., being borrowed or conjured into existence since the last spot of bother in 2008, where each unit of currency enters the global free-for-all chasing assets.

Thanks to historically low yields, cash is trash and the way to make a killing is to rotate from AI chip makers to Ferrari to Colgate, and then on to the next hot sector: maybe uranium, maybe bat guano, maybe a new doggy-themed crypto, maybe the next iteration of the yen carry trade, it doesn't really matter because capital is digital and therefore mobile.
Hand-in-hand with the endless spew of new "money" and credit are financialization and globalization , which have transformed every asset into a fully globalized, commoditized asset that can be securitized, packaged, collateralized and leveraged in a financier's Heaven of finance becoming the measure of all things .
The house across the street is no longer shelter: it's a financialized asset that's now part of a portfolio of rental properties owned (and leveraged) by some entity based in Dubai, which might securitize the portfolio and sell it to pension funds in Norway.
Or it's one of dozens of short-term vacation rentals (STVR) in a wealthy family's private wealth management portfolio.
The same holds true for every asset on the planet. Farmland isn't for growing food--it's for growing wealth as the global "scarcity" of places to stash capital drives its value out of the reach of those who would actually like to use the land to grow food.
For the wealthy, what's abundant is credit, and what's scarce is assets to soak up the sea of ​​capital sloshing around the wealth management funds, philanthro-capitalist foundations, and other outposts of the top 0.1%, which as this chart illustrates, have ridden the credit-fueled Everything Bubble to unprecedented heights of private wealth.
We're told the bubble is a tide raising all boats, but this is, ahem,misinformation, as the bottom 50%'s share of the financial windfall remains a signal-noise of 2.6%.
The primary effect of the Everything Bubble is an extreme of wealth-power inequality. As the chart above illustrates, the wealthy got much richer while everyone else acquired more debt, ie the obligation to pay more of one's earnings to the wealthy who own the mortgage, auto loan, student loan. etc.
There's a funny little effect of extreme wealth-power inequality known as social disorder which can manifest in all sorts of equally funny ways, as popular uprising, wildcat strikes, opting out , civil disobedience, and various other ways of expressing no mas .
Here we see just how extreme the Everything Bubble has become in residential real estate, nearly doubling the insanity of the 2006 housing bubble. Recall that the Case-Shiller Index tracks the market price of the same houses over time, so there's no way to game the statistics.
Among the big winners of the Everything Bubble is--yes, I know you're shocked--Wall Street , as the broker-dealer index has outpaced even the bubblicious S&P 500 stock index.
The Everything Bubble is global , which means its deflation is going to hurt the entire global economy. Consider this chart reflecting the concentration of China's household wealth in housing: almost 80% of all household wealth is in housing, a bubble which is now popping despite the authorities' efforts to reinflate the bubble. Prices are off 25% to 37% in Tier 1 cities, and even more in Tier 2 and 3 cities.
The reverse wealth effect as the primary store of household wealth wilts will be monumental. Trust isn't just personal? trust is the critical glue in markets and governance. Once trust is lost, it's somewhere between difficult and impossible to win it back.
That the bloom is off the Everything Bubble Rose is visible in anecdotal evidence dribbling in from the real world: housing valuations in various markets are off 25% from their peak, housing inventories are rising, sales are slowing, restaurant chains are going belly-up , credit card debt is soaring to new heights, dollar-store stocks are cratering, and so on.
But hey, the real world doesn't count? the only thing that matters is financialized assets going up. If the yen-quatloo pair is taking off, everything's good.
There are a couple of funny things about amassing $315 trillion in debts globally to drive "growth": one is the interest due on all that debt , which becomes unsustainable should yields rise, and inflation, which either pushes yields higher, making it impossible to continue funding "growth" with more debt, or it lays waste to the purchasing power of wage earners' incomes, popping the bubble of free-spending consumption propping up the global economy and debt bubble .

9to5 : This iPhone 16 Pro camera upgrade will fix a major pain point

The iPhone 16 Pro unveiling is only days away, but we already know what to expect. One key camera upgrade coming is a brand new 48MP Ultra Wide camera. I never take Ultra Wide 0.5x shots, but I’m thrilled about this change for one reason: no more anxiety when I see the flower icon in the Camera app.

Macro mode anxiety
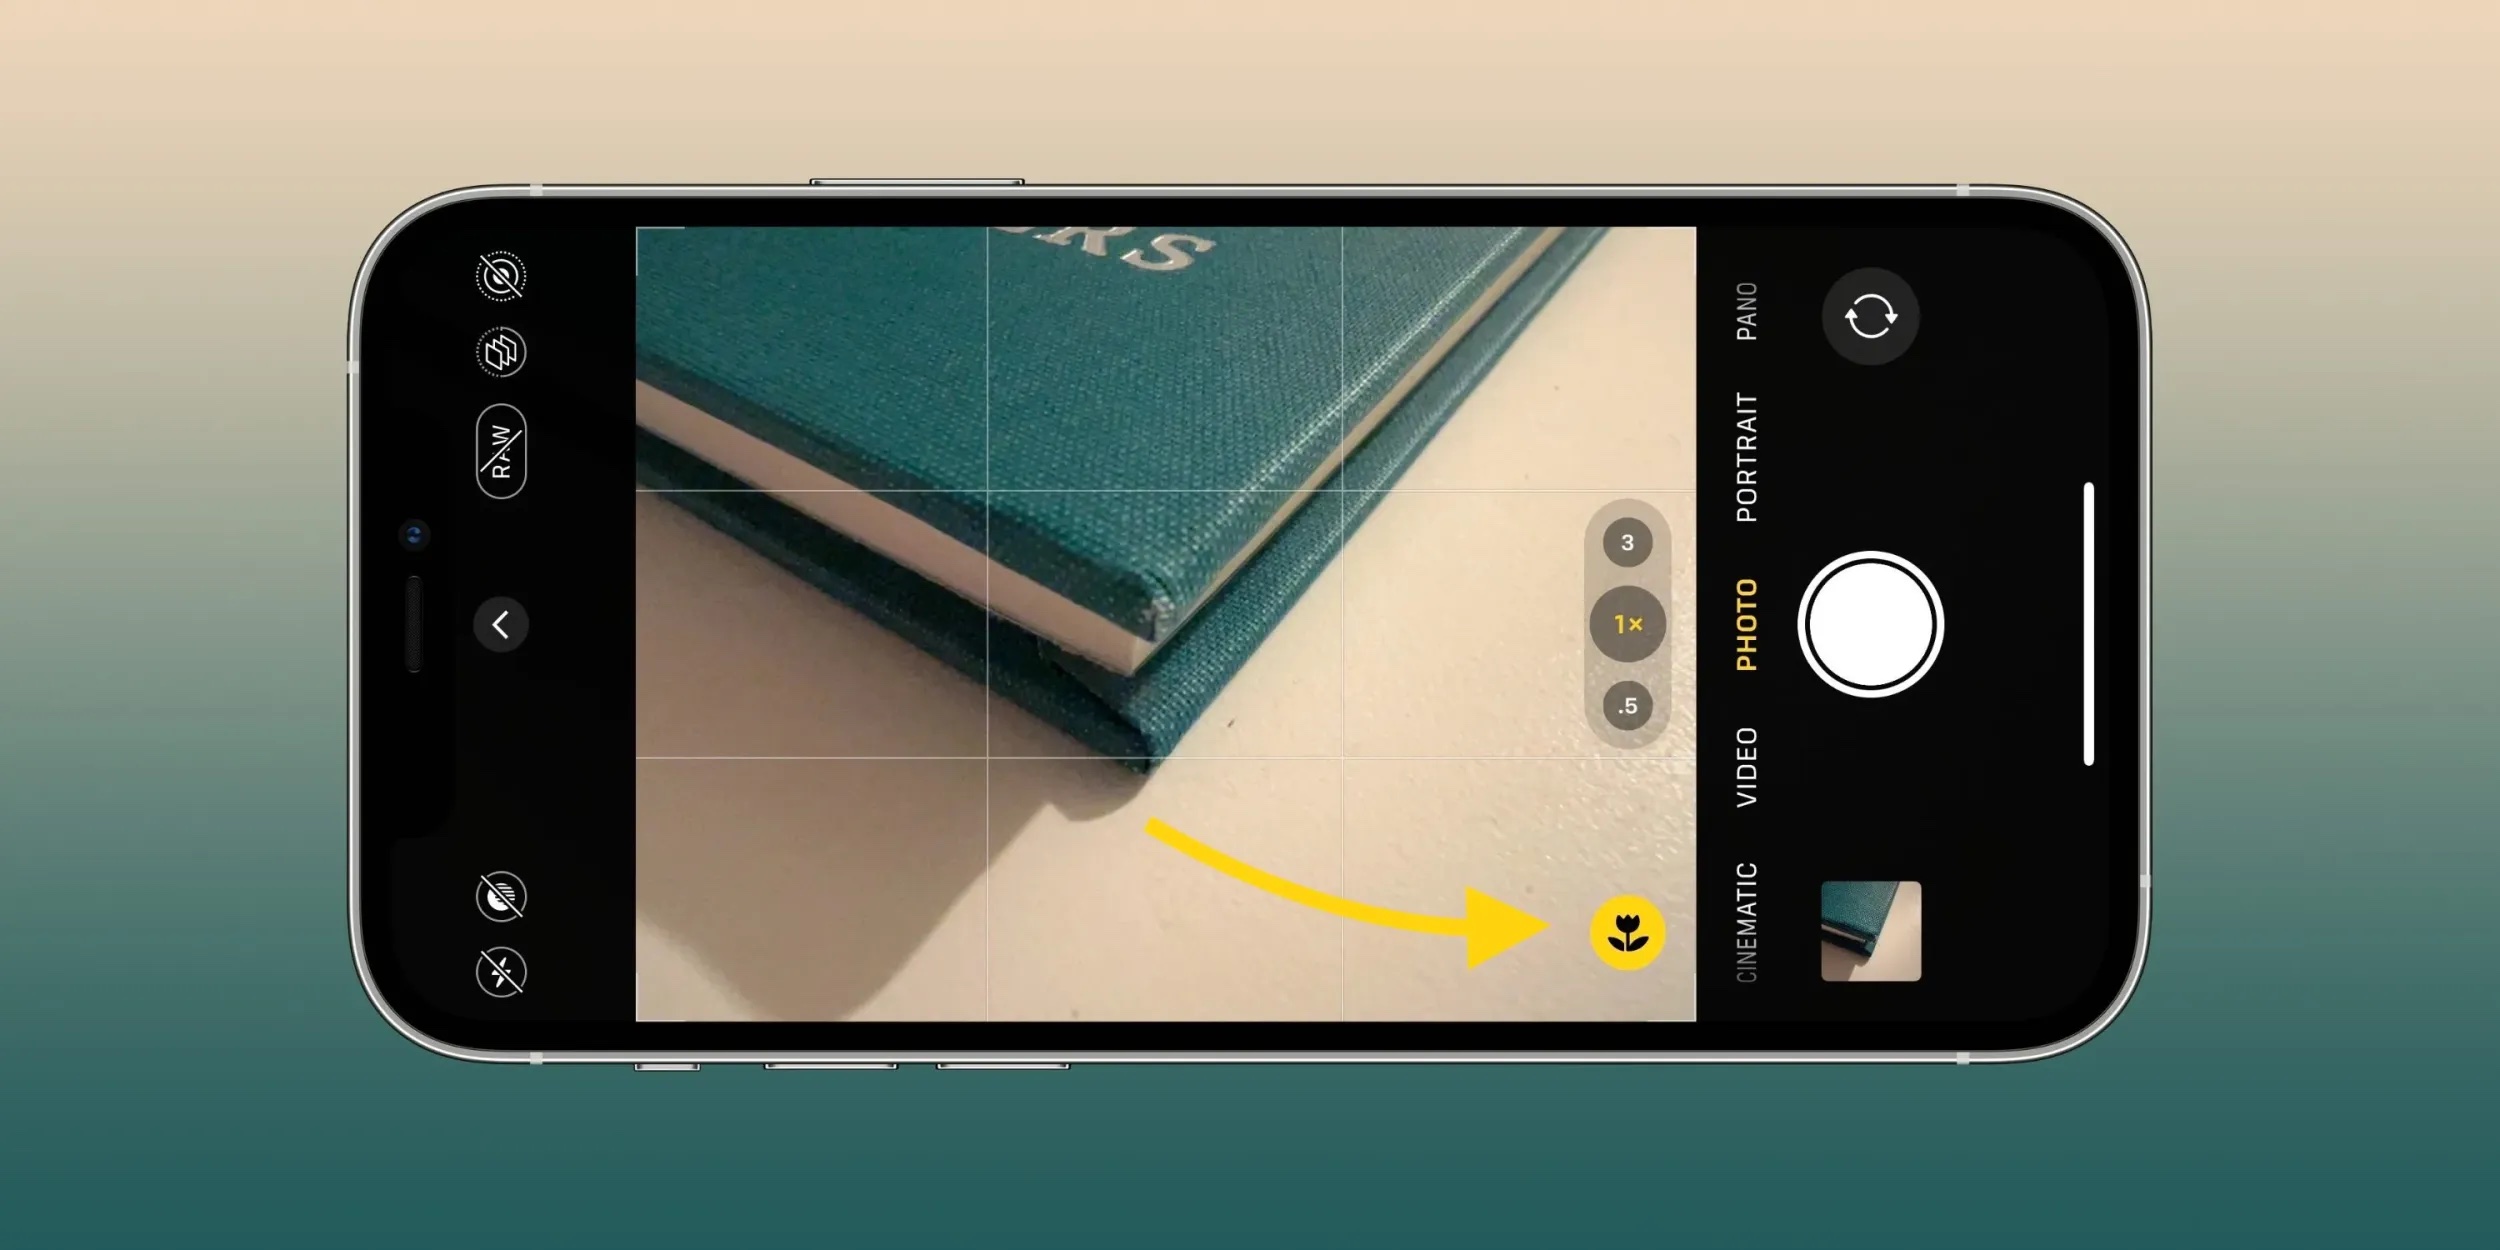
Are you familiar with the flower icon in the Camera app? It shows up whenever your iPhone gets especially close to a photo subject.
The icon means your device has switched from the main camera to the Ultra Wide. It does this to enter macro mode so you can take a sharp, super-close shot.
The problem is, the Ultra Wide camera is currently of lower quality than the main camera. You may not notice when lighting conditions are ideal, but in many other cases the switch to macro mode produces a noticeably lower quality image.
As a result, I’ve gotten in the habit of trying to get my iPhone close enough to subjects that the main camera is still used, but not so close that the flower icon appears and the Ultra Wide is used.
New 48MP Ultra Wide means high quality macro
I don’t enjoy the fisheye-type look of the Ultra Wide camera’s normal 0.5x shooting mode. So naturally, getting a higher quality fisheye photo isn’t something I’m interested in.
But the iPhone 16 Pro’s rumored 48MP upgraded Ultra Wide will also enable better macro photos. And I can’t wait.
I suspect I’m not alone in vehemently avoiding macro mode when I can. And that’s a shame. A key iPhone camera feature shouldn’t be avoided like the plague.
When I get an iPhone 16 Pro, and its Ultra Wide lens can actually keep up with the main camera’s quality, macro mode will be great. I’ll use it all the time, and won’t mind when the flower icon pops up.
If the two camera lenses are truly on the same level, maybe Apple doesn’t need the flower icon at all.
Ideally, users should be able to simply point and shoot without needing to think about which camera is used.
That’s the dream, at least.