FT : Valentino’s Jacopo Venturini: ‘We are selling dreams, emotions and entertai

Valentino’s Jacopo Venturini: ‘We are selling dreams, emotions and entertainment’
The chief executive on his strategy for the Italian luxury house — and the new creative direction under Alessandro Michele

Jacopo Venturini, chief executive of Valentino, has a message that he wants to get across: “There is no magic formula. To me, it doesn’t exist.”

The company is in the midst of a transformation that includes a new creative direction led by former Gucci star designer Alessandro Michele. Venturini and Michele are a tried-and-tested team, having worked together at the Kering-owned brand for four years. At the time, Venturini led Gucci’s merchandising. (Kering also bought a stake in Valentino from Qatar’s Mayhoola in July 2023, and has the option to take full control of the house by 2028.)

For some, that raises the question of whether Venturini is attempting to recreate the sparkle from his time at Gucci, when the brand took a more fashion-forward approach, with buzzy accessories and gender-fluid styling that proved a hit. Its sales more than doubled from €3.9bn in 2015 to more than €10bn in 2022. Operating profits more than tripled.

Much hinges on Michele’s official debut at Valentino, taking place via a show at Paris Fashion Week this month, to lift the fortunes of the Italian couture house, which saw a 3 per cent year-on-year dip in 2023 profits, at constant exchange rate, to €1.35bn (a slump that Venturini attributes to the broader luxury slowdown).

“What I can tell you is that in my experience, at any company I’ve been at, I did my job in a different way,” he says, from Valentino’s headquarters in Milan. “The DNA of a company is much stronger than any formula.”

The idea of harmony is a crucial part of Venturini’s thinking. When we meet in his circular office, filled with vases and handicrafts (curated to feel less corporate and more like a living room), Venturini is wearing a white tee under a blue striped shirt, its cuffs jutting out from under the sleeve of his jacket, and trousers in a shade of dark rose taupe. Layers of jewellery hang from his neck and adorn his wrists and fingers. His style and overall demeanour is less that of a typical CEO and more akin to a film director.

Born and raised in Milan (where his family has been based for generations), Venturini’s interest in clothes developed from a young age — but there was more to it than figuring out how to dress. “I’ve always been fascinated by the identity of different brands,” he says. Familial expectations led him to study economics and business at the city’s Bocconi university. His first job was as a buyer for Italian department store La Rinascente, from 1995 to 1999.

His first encounter with Valentino was in 2000, when founder Valentino Garavani was still at the company; Venturini worked on the merchandising of men’s and womenswear as brand manager, until 2004. He then moved to Prada before returning to Valentino in 2008 as ready-to-wear collection and retail image director. In 2015 he left for Gucci.

“They called me at Gucci when Alessandro was named creative director,” Venturini recalls. “[It] was a great opportunity, but I decided to sign after I saw the [designs] of Alessandro. After I saw his first show, I wrote to [former Gucci CEO Marco] Bizzarri: ‘I’m coming, he’s a genius.’ I was excited by the way he was looking at Gucci in what I thought was the real essence of [the brand] in the ’70s, the period in which they started going towards [ready-to-wear] clothes and lifestyle.”

Now at Valentino for the third time, Venturini, who was appointed CEO in 2020, wants to do things differently, starting with a repositioning of the brand. “I would like Valentino to be positioned in the world of the maison de couture where it was born, in 1960, and where it still deserves to be.” He also emphasises creating “a sustainable culture of the irresistible”.

What that looks like, in practice, is a departure from the traditional show cycle in favour of “seasonless” collections that are “really meaningful”, says Venturini. Instead of staging four separate men’s and women’s ready-to-wear shows a year, and a couture collection twice yearly, the brand will present co-ed shows twice a year, in which the women’s and men’s collections will be presented together. There will also only be one couture show a year.

“The luxury system became too mechanical over the last 15 years and it’s probably due to the immense growth it has had,” reflects Venturini. “We don’t give the time to breathe between one expression of creativity and another. I talked about that with Alessandro and the ways to give more space. So we made this decision, because it’s much better to do one great show.”

Going co-ed is a shift that Michele also engineered when he was at Gucci. When it was put in motion in 2017, the designer justified it by saying that unified collections allowed him time to be more thoughtful and reflected his gender-fluid approach to design. (In 2022, Gucci returned to showing separate collections).

Other luxury houses have slowed down their pace: Ferragamo’s runways are currently co-ed; Balenciaga presents a couture collection yearly; and Maison Margiela’s ready-to-wear and couture shows are irregular. A growing number of smaller independent fashion designers similarly stage a show once a year.

Venturini is also rethinking Valentino’s points of distribution. Direct sales currently account for 75 per cent of the business; the goal is to grow that figure to 80 per cent. He caveats that “co-operation” with selected wholesale partners remains vital because “they have a point of view that is very different to ours, and they see the entire market”.

Since November 2022, Valentino has been rolling out new store concepts globally, with the aim of putting the customer first. The brand’s boutiques, now offering more intimate and exclusive areas reserved for private appointments, have “a more cosy and home-like feeling”, according to Venturini. “At the same time, everything has to do with efficiency.”

Changes such as improved stock management and back-of-house systems aren’t discernible to the public eye but are crucial in that they allow store advisers to spend valuable time with their clients, Venturini explains. He has also overseen training to make store staff more knowledgeable about a wider breadth of products. “Clients are not interested if you are in charge of bags, or in charge of shoes. You have to know how to sell all the different categories.” He continues: “We are selling dreams, emotions and entertainment. We can’t be mechanical in the way we do things.”

Keeping Valentino’s long-standing customers happy is a priority. “We are quite resilient because we have a strong base of clients who are very loyal,” says Venturini. That requires maintaining pricing stability (there have been some price increases due to rising production costs, he admits) and expanding product categories, including costume jewellery, to “complete the wardrobe of our clients”. Elevation remains top of mind; Venturini terminated the sub-label Red Valentino at the start of the year.

To communicate Michele’s new vision, an advertising campaign will be rolled out in October when the designer’s first collection (a pre-spring 2025 lookbook with his first designs were unveiled in June) arrives in stores. But there will be no erasing of Valentino’s past, says Venturini. Signatures such as the Rockstuds (square studs applied to bags and shoes, created in 2010 by Garavani and now the brand’s most recognisable motif) will remain — even if, in recent years, they have started to feel stale, in part because of rising counterfeits and an association with aspirational shoppers.

“An iconic product should always stay,” Venturini asserts. “It’s not easy to have a product that sells for 14 years, so we should defend it.” While ready-to-wear makes up the bulk of Valentino’s business, its accessories offering could be re-energised, he acknowledges. Will Michele be able to create the next Rockstud, whatever that may be? “For sure,” says Venturini. “I am sure he will do that.”

>>> Europe : Brokers Upgrades & Downgrades - 12th of September 2024

>>> Up
* ABN Amro GDRs Raised to Neutral at JPMorgan; PT 15.30 euros
* Alten Raised to Outperform at BNPP Exane; PT 115 euros
* Commerzbank Raised to Overweight at JPMorgan; PT 17.20 euros
* Derwent London Raised to Outperform at Bernstein
* Equinor Raised to Hold at Berenberg
* HIAG Immobilien Raised to Buy at Baader Helvea
* Icade Raised to Outperform at Bernstein
* Land Sec. Raised to Outperform at Bernstein
* Sage Raised to Outperform at BNPP Exane; PT 1,200 pence
* TAG Immobilien Raised to Outperform at Bernstein
* TeamViewer Raised to Neutral at BNPP Exane; PT 13 euros
* Veolia PT Raised to 45.30 euros from 43.40 euros at Oddo BHF

>>> Down
* Air France-KLM Cut to Add at AlphaValue/Baader
* Antin Cut to Neutral at Citi; PT 14.30 euros
* Ionos Cut to Neutral at BNPP Exane; PT 27 euros
* Planisware Cut to Underperform at BNPP Exane; PT 23 euros
* WDP Cut to Underperform at Bernstein

>>> Initiation
* GlobalData Rated New Buy at Berenberg; PT 295 pence
* Kongsberg Automotive Reinstated Buy at ABG; PT 2 kroner
* Lime Technologies Rated New Buy at Nordea; PT 405 kronor
* RELX Rated New Buy at ING; PT 4,309.40 pence
* Safran Started at Outperform by RBC, Target Started at EUR240

>>> Call
* Avanza Concerns Overdone, Citi Opens Upside Catalyst Watch
* GlobalData New Buy at Berenberg, Has Multiple Growth Levers
* Safran New Outperform at RBC on Continued Aftermarket Strength
* Veolia PT Boosted to Street-High at Oddo BHF on Growth Strategy

TechCrunch : Mark Zuckerberg says he’s done apologizing

Mark Zuckerberg says he’s done apologizing

The home of the Golden State Warriors was packed on Tuesday evening this week, but it wasn’t to watch Steph Curry. Thousands of fans gathered at the Chase Center in downtown San Francisco to watch one of Silicon Valley’s biggest ballers, Meta CEO Mark Zuckerberg, sit down for a conversation with the hosts of the Acquired podcast, David Rosenthal and Ben Gilbert.

Shortly after hopping onstage, Zuckerberg joked that he might need to schedule his next appearance in order to apologize for whatever he was about to say. After a beat, he added that he was just kidding and that, in fact, his days of apologizing are over.

Zuckerberg has had something of a rebrand recently. He raises cattle in Hawaii now, has long bouncy curls and a gold chain, and commissions Roman-style statues of his wife. Onstage, the Facebook founder wore a boxy T-shirt he designed himself alongside fashion designer Mike Amiri that read “learning through suffering” in Greek letters.

The tongue-in-cheek comment about apologizing was a reference to Nvidia CEO Jensen Huang, who himself addressed a flub he’d made on the Acquired podcast earlier this year, via a pre-recorded video on a screen hanging over the crowd. Huang’s original comment — that he never would have started Nvidia if he knew what he did today — was grossly taken out of context, he said. In the video, he clarified that he absolutely would start Nvidia again, and that his comment was more about the blissful ignorance of startup founders.

While Zuckerberg’s opening comment was just a friendly jab at Huang, it set the tone for Zuckerberg’s new attitude toward life and business. The founder of Facebook has spent a lot of time apologizing for Facebook’s content moderation issues. But when reflecting on the biggest mistakes of his career, Zuckerberg said his largest one was a “political miscalculation” that he described as a “20-year mistake.” Specifically, he said, he’d taken too much ownership for problems allegedly out of Facebook’s control.

“Some of the things they were asserting that we were doing or were responsible for, I don’t actually think we were,” said Zuckerberg. “When it’s a political problem… there are people operating in good faith who are identifying a problem and want something to be fixed, and there are people who are just looking for someone to blame.”

The vague comments seemed to be about critics blaming Facebook for its part in Donald Trump’s election victory in 2016. Among other things, a firm called Cambridge Analytica took Facebook users’ data and attempted to use it to influence voters to choose Trump. Foreign actors also used the platform in an attempt to influence the election and sow political division, culminating in years of bad press for the company and in Zuckerberg testifying before Congress. (It’s unclear how effective these campaigns actually were.) In the months following the 2016 election, Zuckerberg lamented how almost no one had good things to say about Facebook.

Now, however, Zuckerberg says he’s found the right balance on political issues. He didn’t say much more than that, but his recent actions are instructive.

In August, the Meta CEO sent a letter to House Republicans effectively apologizing for censoring misinformation around COVID-19 in 2020, and bending to demands from the Biden administration. Zuckerberg said he regrets not being more outspoken about the pressure from government officials at the time. In the future, Zuckerberg said he would “push back if something like this happens again.”

Meanwhile on Meta’s platforms, Facebook and Instagram have removed all special restrictions for Trump’s social media accounts. These restrictions were originally placed on his accounts after the January 6 insurrection in 2021, but will not impact Trump’s accounts going into the 2024 election.

In July, while not going as far as to endorse a specific candidate for U.S. president, the Meta CEO also called Trump a “badass” for lifting his fist in the air after someone attempted to assassinate him.

On Tuesday night, Zuckerberg said he’s more excited about projects outside of social media these days, describing Meta as a “human connection” company at its core. The Meta CEO noted how no one gets out of bed in the morning and goes “f— yea, social media!” Instead, he wants to make more “awesome” products, seemingly referring to Meta’s AR glasses, VR goggles, and open source AI efforts.

Zuckerberg was pressed at one point about whether he regrets naming the company Meta, which signaled the company’s pivot toward the metaverse. The CEO simply replied, “Meta is a good name.”

Regardless of where Zuckerberg’s focus is, Meta’s social media platforms are still where billions of people convene every day. That means content moderation issues will arise, and the CEO will ultimately have to make consequential decisions.

Electrek : Ferrari’s first EV spotted testing ahead its debut [Video]

The all-electric Ferrari we’ve been waiting for is almost here. Ferrari’s first EV was spotted out for testing near its Maranello factory in Italy. Check out the video below to get a closer look.

Although Ferrari has not officially revealed its first electric model, CEO Benedetto Vigna has given us some clues about what to expect.
According to Vigna, one thing is guaranteed: The electric Ferrari will be “a lot of fun” to drive, as you would expect from the luxury sports car maker.
“People buy a Ferrari because when they buy a Ferrari, they have a lot of fun,” Vigna boasted earlier this summer. Ferrari’s CEO confirmed the brand’s first EV will launch in 2025, promising it will be made “the right way.”
Vigna explained that you don’t buy a Ferrari for a single purpose; “It’s a combination of things.” These Ferrari-like elements, including unique sounds, will be a staple in its upcoming EV.
In June, a Reuters report claimed that the electric Ferrari would cost over $500,000. Vigna said the report was “a surprise” but didn’t deny (or confirm) the price.
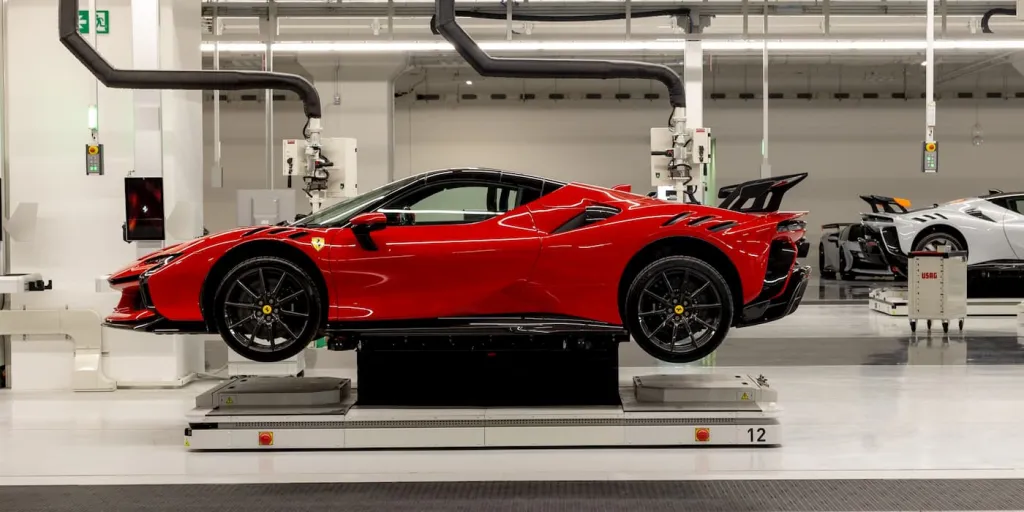
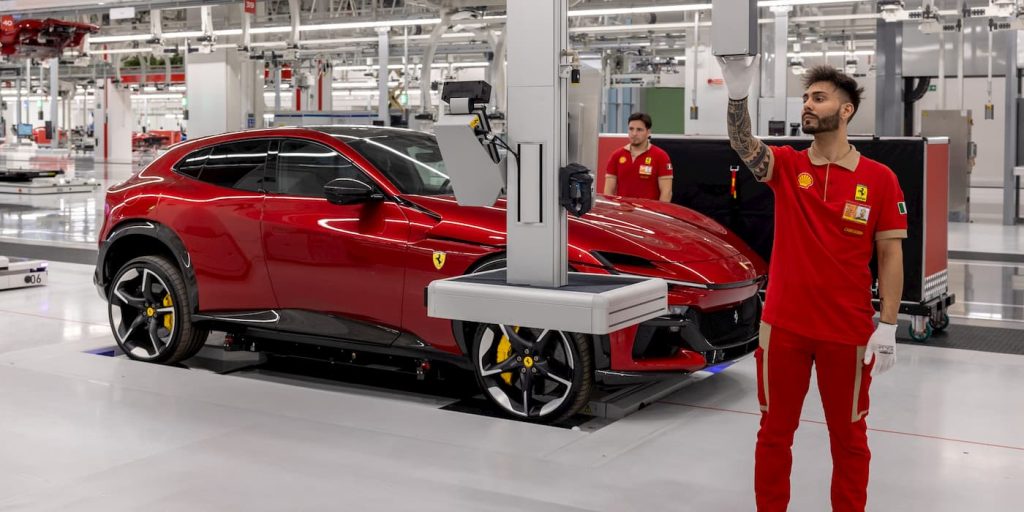
Inside Ferrari’s new e-building (Source: Ferrari)
Ferrari’s first EV spotted testing ahead of its debut
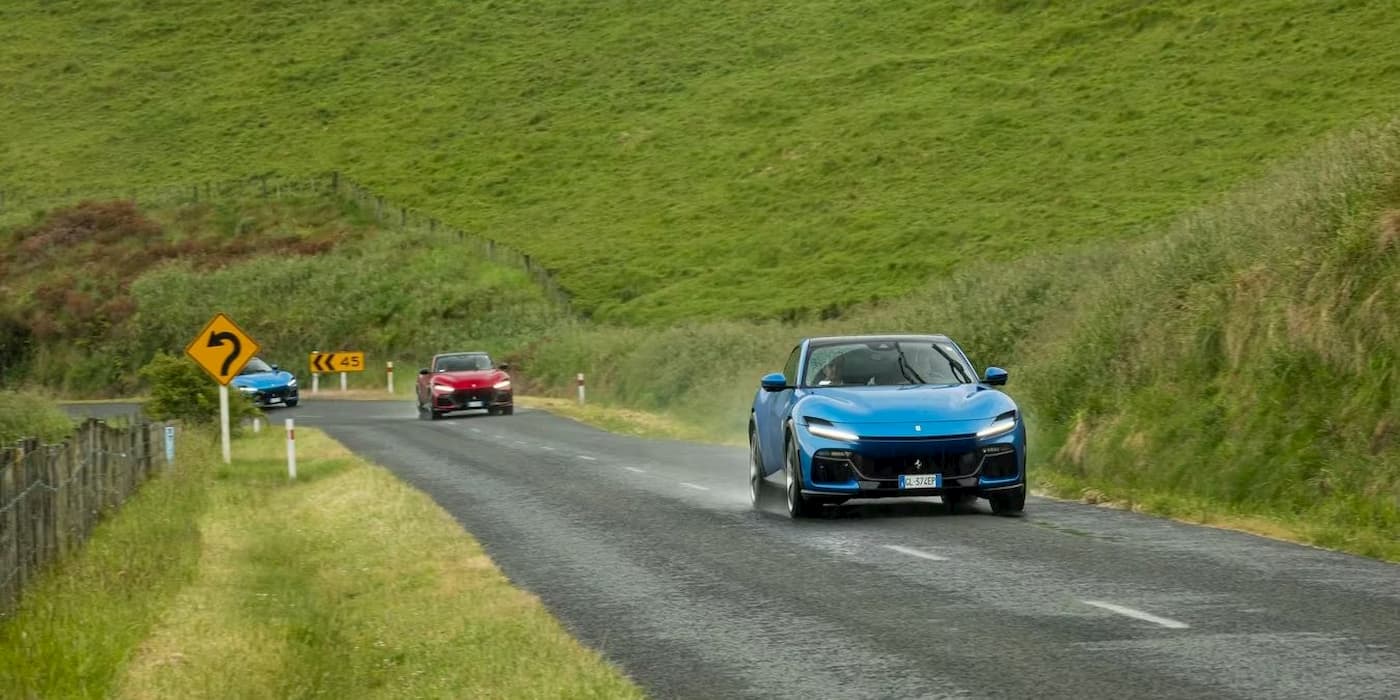
Ahead of its official debut, Ferrari’s first EV was caught testing near its Maranello plant. The video from Acriore gives us our best look yet at the luxury electric model.
The vehicle is covered in camouflage and even has a fake exhaust, but the big yellow high-voltage sticker on the front and rear indicates it is electric.
Ferrari’s first EV testing in Italy (Source: Acriore/ YouTube)
As the vehicle passes, you can hear clear exhaust noises, suggesting Ferrari is working on its own noise-generating system. It could be something like Dodge’s Fratzonic Chambered Exhaust for the electric Charger.
Ferrari opened its new e-building this summer, where the electric model will be built. Vigna said the new factory will “light up Ferrari’s future.”
Inside Ferrari’s new e-building (Source: Ferrari)
The electric Ferrari is expected to debut later this year ahead of sales in 2026. Ferrari launched its first plug-in hybrid last year, the SF90 Stradale. By 2026, the Italian sports car maker aims for 60% of sales to be EV or PHEV.
Ferrari will also build batteries, electric motors, and inverters at its e-building. Word on the street is that the company is already working on its second EV. Stay tuned for more.

The Information : Oracle Exec: AMD Gaining Favor in Nvidia-Dominated Market for

Oracle Exec: AMD Gaining Favor in Nvidia-Dominated Market for AI Chips

The Takeaway
Karan Batta, a top Oracle cloud executive, says competition with Nvidia is necessary to reduce hardware costs—and control expenses for businesses that want to make their own AI apps by running their own large language models.

Despite Nvidia’s booming growth in selling data center chips for artificial intelligence, some customers developing AI are turning to chips from smaller rival Advanced Micro Devices, said Karan Batta, a senior executive in Oracle’s cloud business. Oracle rents out chips from both companies.

“What we’re finding now is customers are not necessarily tied to any one particular vendor for inferencing,” Batta said. Inference computing refers to AI that has already been developed and is powering applications.

“There’s a lot of effort being put into AMD, and [the company is] doing a good job” at improving its chips’ performance, he said.

Batta declined to provide specifics or names of customers, but his comments show how Oracle wants to reduce its dependence on AI chip leader Nvidia, similar to Microsoft and other cloud providers.

While AMD’s latest flagship server chips, launched in 2023, may not be as powerful as the latest Nvidia flagship—the H100, launched in 2022—executives at Oracle and Microsoft feel they have little choice but to support AMD to promote competition.

In the meantime, Oracle and other cloud providers are booming as they rent out more Nvidia servers to customers such as OpenAI and Elon Musk’s xAI. Oracle is a distant fourth place behind Amazon Web Services, Microsoft Azure and Google Cloud in server rentals in the U.S. It generated $2.4 billion from that business in the August quarter, up 45% from a year earlier.

Oracle entered cloud computing relatively late but got somewhat lucky last year, as its business benefited from a frenzy among AI startups to secure cloud servers. It also has an advantage with some AI developer customers because it’s not a competitive threat to them; Oracle, unlike its bigger rivals, isn’t developing its own large language models similar to OpenAI’s GPT-4.

The boom in AI server rentals reflects the development or training of new AI models. But many businesses have yet to adopt LLMs aside from using applications such as ChatGPT, GitHub Copilot and a handful of others in areas like customer service. Those businesses’ leaders have said the technology is not useful enough or costs too much.

As Nvidia runs away with the server chip market, competition is needed to drive down hardware costs, said Batta. Doing so will keep AI inference costs under control for businesses that want to use LLMs to make their own AI apps or want to buy such apps from software vendors, he said. The cost to rent Nvidia chips for inference has been dropping, but its next flagship AI chips might change that.

Other Nvidia customers have expressed similar concerns privately, reflecting fear that Nvidia products will continue to command a large premium if AMD or others don’t eat into its share of the market. So far, that hasn’t really happened. AMD said its data center revenue rose 115% to $2.8 billion in the June quarter compared to the same period a year ago, while Nvidia data center revenue rose 154% to $26.3 billion in the July quarter.
“Nvidia innovates constantly to deliver enhanced value to our customers, enabling AI for every cloud and enterprise,” an Nvidia spokesperson said in a statement.

Oracle’s use of AMD hardware could also help it guard against potential Nvidia supply shortages, Batta said. Such shortages occurred throughout much of last year.

As Oracle looks to capture more of the market for powering AI model training, co-founder Larry Ellison said Monday that it is designing a data center with a capacity of more than one gigawatt, enough to power a city like San Francisco. Batta declined to provide details on that data center or when it might be operational.

To support its expansion, Oracle is investing in its ability to string together clusters of AI chips so they can act like a single computer—the ideal setup for training new LLMs, he said.

Those improvements include changes to how Oracle cools the heat-generating chips and builds tunnels for cables to link chips across different buildings so they don’t all need to be in the same place. Oracle plans to at least double the size of the interconnected groups of chips, known as clusters, it offers customers—from 64,000 graphics processing units to more than 128,000, he said without specifying the timeline.

Oracle can still benefit from demand for AI training even if startups are using other clouds to develop their core models, Batta said. For example, companies also need hardware for other purposes like fine-tuning, in which developers hone a model for a specific task. Some AI companies are buying access to older chips for those workloads, Batta said.

That might be a reference to a deal Oracle struck with OpenAI and Microsoft to use a facility in Texas next year, according to the AI Data Center Database, but Batta declined to comment on specific companies.

Oracle recently faced a setback when Musk decided to build his own GPU cluster in Memphis rather than rent one from Oracle because it couldn’t move fast enough to set up the data center. Batta said it was too early to say whether xAI can get its Colossus cluster of 100,000 H100s completed faster than Oracle would have.

“I don’t have a baseline to compare with. Am I way faster [than xAI]? Am I way slower?…I do think if you compare us with other cloud providers, we feel like we’re one of the fastest, if not the fastest, from an AI compute perspective.”

WWD : Aura Blockchain Crosses 50 Million Product Mark

Aura Blockchain Crosses 50 Million Product Mark
The consortium launched by LVMH, Prada and Cartier has 50 million luxury products registered, including upcoming collections from Jil Sander, Maison Margiela and Marni, among others.

PARIS — Aura Blockchain Consortium has crossed the 50 million mark, hitting a milestone with that many luxury products now registered with the technology.

The Switzerland-based group now encompasses 50 members, from the founding five in 2022 which included LVMH Moët Hennessy Louis Vuitton, Diesel parent company OTB Group, Prada Group, Richemont’s Cartier and Mercedes-Benz.

The 50 million number comes just three months after the consortium registered 40 million products on its private blockchain.

“This is showing a great acceleration of the brands joining, but also implementing and preparing the information that is going to be put on the [digital product passports],” Aura Blockchain Consortium chief executive officer Romain Carrere.

Digital product passports, or DPPs, connect a physical product to a digital record that can house product information and sourcing through the supply chain for a deep dive on traceability. They are one of the requirements of the European Union’s upcoming Ecodesign for Sustainable Product Regulation, which will start rolling out next year for apparel and textiles.

Brands are adapting quickly to the new technology, which can trace product through resale and repair, as well as authenticate and combat counterfeiting.

“If we look at groups like OTB, they have announced that starting with their fall collection, they will put all of their products on the blockchain,” Carrere said.

Other brands will also add a certificate of authenticity for their garments and accessories, including Jil Sander, Maison Margiela and Marni with their fall 2024 collections equipped with the technology.

“This shows we are growing, and we are working with many other brands that we haven’t announced yet,” he added.

The blockchain can include both upstream, meaning production and sourcing info, and downstream, meaning loyalty programs or insurance tied to an object, as well as repair and resale.

Carrere highlighted that because the consortium was founded by brands and has a nonprofit status, it is being built to fit their needs and can adapt to various brands, from jewelry and hard luxury to automobiles.

“A strong point is that since we were created by brands for brands, we have the information they share, the information of what they need, so we are able to build the technology that represents their needs.”

The tech standards that Aura’s blockchain is creating are establishing a framework and technological standard that will help brands adapt to DPP needs.

The blockchain’s private and closed network will also support the privacy concerns of luxury brands. The consortium’s technology can be used across brands but is not proprietary to any one brand. Its tech will enable member brands to prepare for the sustainability-focused requirements of the European Union.

“That was a real need from the luxury brands, that we are really focusing on the longevity of the product data, and also the fact that we are independent and we can never be bought out,” he added.

Carrere added that Aura is growing its Geneva-based team to accommodate the additional brands that are joining the consortium as more get up to speed ahead of the DPP rollout in Europe.

WWD : FTC Makes a $365 Million Argument Against Tapestry’s Deal to Buy Capri

FTC Makes a $365 Million Argument Against Tapestry’s Deal to Buy Capri
A hearing in Manhattan federal court dug into the analysis underpinning the government’s case against the $8.5 billion acquisition.

The Federal Trade Commission sued to stop Tapestry Inc.’s $8.5 billion deal to buy Capri Holdings, in large part on the grounds that putting Coach, Kate Spade and Michael Kors all under one roof would be bad for American consumers.

On Wednesday, the federal court hearing for a preliminary injunction that’s expected to determine whether the deal can go forward or not, put a number on that concern — $365 million.

That’s the “loss of consumer welfare” annually that was attributable to potential price increases that could result from the deal, according to the merger analysis of economist Loren Smith, who reviewed the transaction for the FTC and testified before Judge Jennifer Rochon.

Smith said that Tapestry, which owns Coach, Kate Spade and Stuart Weitzman, would have a big incentive to raise prices or cut the value of the products it sells after buying Capri and its brands, Michael Kors, Versace and Jimmy Choo.

The economist said that the accessible luxury brands at the core of the case — Michael Kors, Coach and Kate Spade — can not currently raise prices without also boosting the value they give to consumers given the competitive environment. In that, he echoed a point made by Joanne Crevoiserat, Tapestry’s chief executive officer, on the stand on Tuesday.

But Smith said the pricing dynamic would change once the deal is done.

That’s because his analysis of data in the case — including internal branding research produced in discovery — suggested that if Michael Kors lost customers by raising prices, those customers would likely turn to either Coach or Kate Spade (and vice versa).

“If I own the brands, I don’t care so much that just happened,” Smith said.

Smith’s merger simulation showed that Coach could raise its average price on a handbag from $145 before the merger to $159 after. Kate Spade could go from $108 to $122 and Michael Kors could push its $103 average up to $133.

Combined, that would be a 17 percent hike in price, or a commensurate decline in value for the same prices.

All together, that works out to $365 million annually.

WSJ : Private Markets Seem Out of Reach for Individual Investors. BlackRock Thin

Private Markets Seem Out of Reach for Individual Investors. BlackRock Thinks It Has an Answer.
Asset manager teams up with Partners Group to offer wealthy investors a preset portfolio

It might be getting easier for individual investors to tap in to the opaque world of private markets.

BlackRock BLK -0.76%decrease; red down pointing triangle plans to offer wealthy investors a way to access areas such as private equity and private credit in an attempt to build a new revenue stream. The asset manager is joining with private-equity firm Partners Group PGHN 0.09%increase; green up pointing triangle to create a so-called model portfolio that wealth advisers could use to help clients invest in a variety of private-market offerings in one fell swoop.

The move is the latest push by BlackRock, which made its name managing publicly traded stocks and bonds, into the more lucrative business of private investments. Private funds tend to charge investors higher fees and are harder to sell than publicly traded investments. But investors are increasingly looking for ways to access the growing sector.

BlackRock and Partners Group see an opportunity in bringing private markets to individuals in a simplified way.

“There’s currently a zoo of documents for financial advisers, who know they should be doing more in private markets, but don’t know enough and, frankly, are a little worried about using individual products,” said Mark Wiedman, head of the global client business at BlackRock.

Institutional investors such as pension funds and sovereign-wealth funds have ramped up their exposure to private markets over the past several decades as a way to diversify and potentially collect higher returns. As growth in that market has slowed, private-equity firms such as Blackstone, Apollo Global Management and KKR have launched a slew of products targeting wealthy individuals, who tend to have little to no exposure to private markets.

Other traditional asset managers have also teamed up with private-markets specialists. State Street and Apollo on Tuesday announced a partnership to launch an exchange-traded fund and other products focused on private credit.

BlackRock remains a relatively small player in private markets, but it has spent billions this year on acquisitions to beef up its offerings. It agreed to buy private-market data-provider Preqin and Global Infrastructure Partners, which invests in assets such as gas pipelines and data centers.

The private-markets model portfolio from BlackRock and Partners will be available early next year to advisers and wealth-management clients who are “qualified,” meaning they have at least $2.2 million in net worth excluding their primary residence. An individual who wants a 10% allocation to private markets could do so through a single investment.

The firms didn’t yet have details on the product’s fees.

Model portfolios, or preset investment templates for financial advisers, have soared in popularity in recent years, collecting trillions in assets. BlackRock alone manages $131 billion in such portfolios.

Partners was an early mover in private wealth, and launched the first U.S. private-equity fund aimed at individuals in 2009. Still, as a Swiss firm, it isn’t as well known in the U.S. as its competitors. By joining forces with BlackRock, which has roughly 30,000 wealth advisers using its model portfolios, Partners hopes to extend its reach.

Wiedman and Partners CEO Dave Layton said they hatched the idea for the product when they ran into each other on a plane from Los Angeles to San Francisco earlier this year.

Layton, who had just attended the Milken Institute Global Conference, told Wiedman he was concerned about the amount of resources his competitors were rapidly plowing into private wealth.

“We have seen a real, incredible push by many of our peers to pivot into a space where we’ve been for a long time,” Layton said.

FT : Spain vetoed Hungarian bid for train group ‘over Ukraine concerns’

Spain vetoed Hungarian bid for train group ‘over Ukraine concerns’
Madrid did not want Budapest to acquire Talgo gauge technology that Kyiv needs for its rail system, says official

Spain blocked the Hungarian takeover of a Madrid-based trainmaker on the grounds that Viktor Orbán’s Russia-friendly government should not acquire technology that could be useful to Ukraine, according to people familiar with the matter.

A senior Spanish government official said Madrid vetoed the €619mn bid for Talgo in part because the company could aid Ukraine’s reconstruction by helping it strengthen its rail links with the EU.

“One of Ukraine’s biggest interests is the rail connection,” the official told the Financial Times, stressing that Talgo could help Ukraine overcome one big impediment: the fact its rail tracks are a different width.

Spain has classified the documents explaining its decision — which it made on “public security and order” grounds — and declined to comment on whether its concerns are linked to Orbán and his relations with Russia, which have been the closest of any western leader since Moscow’s full-scale invasion of Ukraine.

Spain’s Prime Minister Pedro Sánchez has criticised Orbán as the “pro-Putin” leader of the “international far right” and said the Hungarian prime minister “wants to bring Ukraine to its knees”.

Ganz-Mávag, the consortium that launched the Talgo bid in March, is backed by an investment arm of the Hungarian state and trainmaker Magyar-Vagon, which Spain has asserted is “ultimately controlled” by Hungarian oil company MOL.

The Spanish official said Talgo had advanced engineering — known as automatic gauge change technology — that would enable trains to move seamlessly between Ukrainian train tracks and narrower rails in neighbouring European countries.

“That point of collaboration with Ukraine is one of the most important parts of the process of reconstructing the country and integrating it into Europe,” the official said.

Ukraine’s train tracks are 1,520mm wide in line with Soviet norms, but the standard for European rails is 1,435mm, a size that originated in the UK.

Variable gauge technology was developed in Spain because the country, unusually, uses multiple track widths: the most common is a 1,668mm Iberian gauge, but there is a 1,000mm narrow gauge in the north while Spain’s high-speed trains run on standard European tracks.

According to Talgo, which produces passenger trains, its variable gauge system “enables a train to adapt its wheel gauge while running at approximately 15km/h and without having to stop”.

Due to Ukraine’s wider tracks, most passengers on trains to and from Warsaw have to endure waits of several hours while the train axles are adjusted manually. Such delays also affect wagons carrying Ukrainian exports of grain and other goods, whose weight exacerbates the problem of incompatible gauges.

Talgo pioneered the gauge change technology and is still considered a leader in the field, even though most of its key patents have expired and other trainmakers now have similar engineering.

Ganz-Mávag has already said “there are no well-founded reasons” for Spain’s veto and vowed to launch legal action against the government.

In comments to the FT, a spokesperson for the consortium disputed the idea that its interest in Talgo was driven by the variable gauge system and stressed that the technology was “not exclusive” to Talgo.

“Our interest in Talgo has always focused on increasing the production capacity of this leading company in supplying high-speed passenger trains. Gauge change technology is simply not a factor to be taken into consideration and anyone knowledgeable of the train sector would know this to be an excuse to hide behind a political decision.”

MOL, one of eastern Europe’s largest companies with a significant state ownership and which has continued to process Russian crude despite the war, did not immediately respond to a request for comment.

A lawyer familiar with Talgo said the gauge change technology “did not make sense” as a reason for Spain to veto the bid. “There is either something they are not telling us, or they just don’t want to sell to a government they are criticising every day.”

A Hungarian government spokesperson did not immediately respond to a request for comment.

György Bacsa, chief operating officer of oil group MOL’s Hungarian operations and chairman of the Ganz-Mavag Europe board, said MOL exercised no control over the train company.

FT : Goldman Sachs to earn $92mn from advising on $36bn Kellanova sale

Goldman Sachs to earn $92mn from advising on $36bn Kellanova sale
Jumbo fee comes as Wall Street hopes that long-awaited deal boom is back

Goldman Sachs is set to earn $92mn from its work advising Pringles and Pop-Tarts maker Kellanova on its $36bn sale to Mars, one of Wall Street’s biggest M&A paydays in recent years.

The fee for Goldman, disclosed in a regulatory filing on Wednesday, underscores burgeoning optimism on Wall Street that deal activity is picking up after a lacklustre two years. Lazard, which advised Kellanova’s board of directors on the deal, is set to earn $10mn. The vast majority of both fees is dependent on the deal successfully closing.

The fee is enormous, even by Wall Street standards, especially given the size of the transaction.

Mars’s $36bn deal for Kellanova is the largest US merger announced this year. But bigger deals agreed last year nevertheless yielded lower fees for the banks involved.

Goldman managed the roughly $65bn sale process for Pioneer last year, netting the bank a fee of about $46mn, and also stood to earn $80mn after Hess Corp was sold to Chevron for $60bn. Boutique investment bank Centerview Partners agreed a fee of $88mn for selling oncology-focused biotech Seagen for $43bn to Pfizer.

Sell-side fees tend to be particularly large to reward longtime advisers who will no longer have a client once the deal closes.

The lofty fee for Goldman points to the growing sense on Wall Street that dealmaking is gaining momentum after a challenging two years as markets were chilled by higher interest rates and the US government’s aggressive approach to antitrust issues.

Goldman chief executive David Solomon told CNBC on Wednesday that third-quarter earnings on Wall Street next month would show “a material improvement in investment banking activity”.

However, the recovery has taken longer to materialise than many on Wall Street were anticipating.

“I thought by this time we’d be back to 10-year averages, and we’re not quite there yet,” Solomon said. “I think there are a variety of reasons that have held it back a little bit. I think the big one is financial sponsors have been slower to move forward and engage and monetise on their portfolios because they’ve had a lot of these assets marked higher.”

Kellanova, which makes Cheez-Its, Rice Krispies Treats and Eggo waffles, was created in 2023 after Kellogg separated its breakfast cereals and snacks businesses.

The regulatory filing disclosed that the deal talks with Mars began at the end of May when the chief executives of the two companies met for lunch at the Chicago office of law firm Skadden Arps, where Mars initially bid $77 per share. Kellanova ended up securing a deal for $83.50 per share.